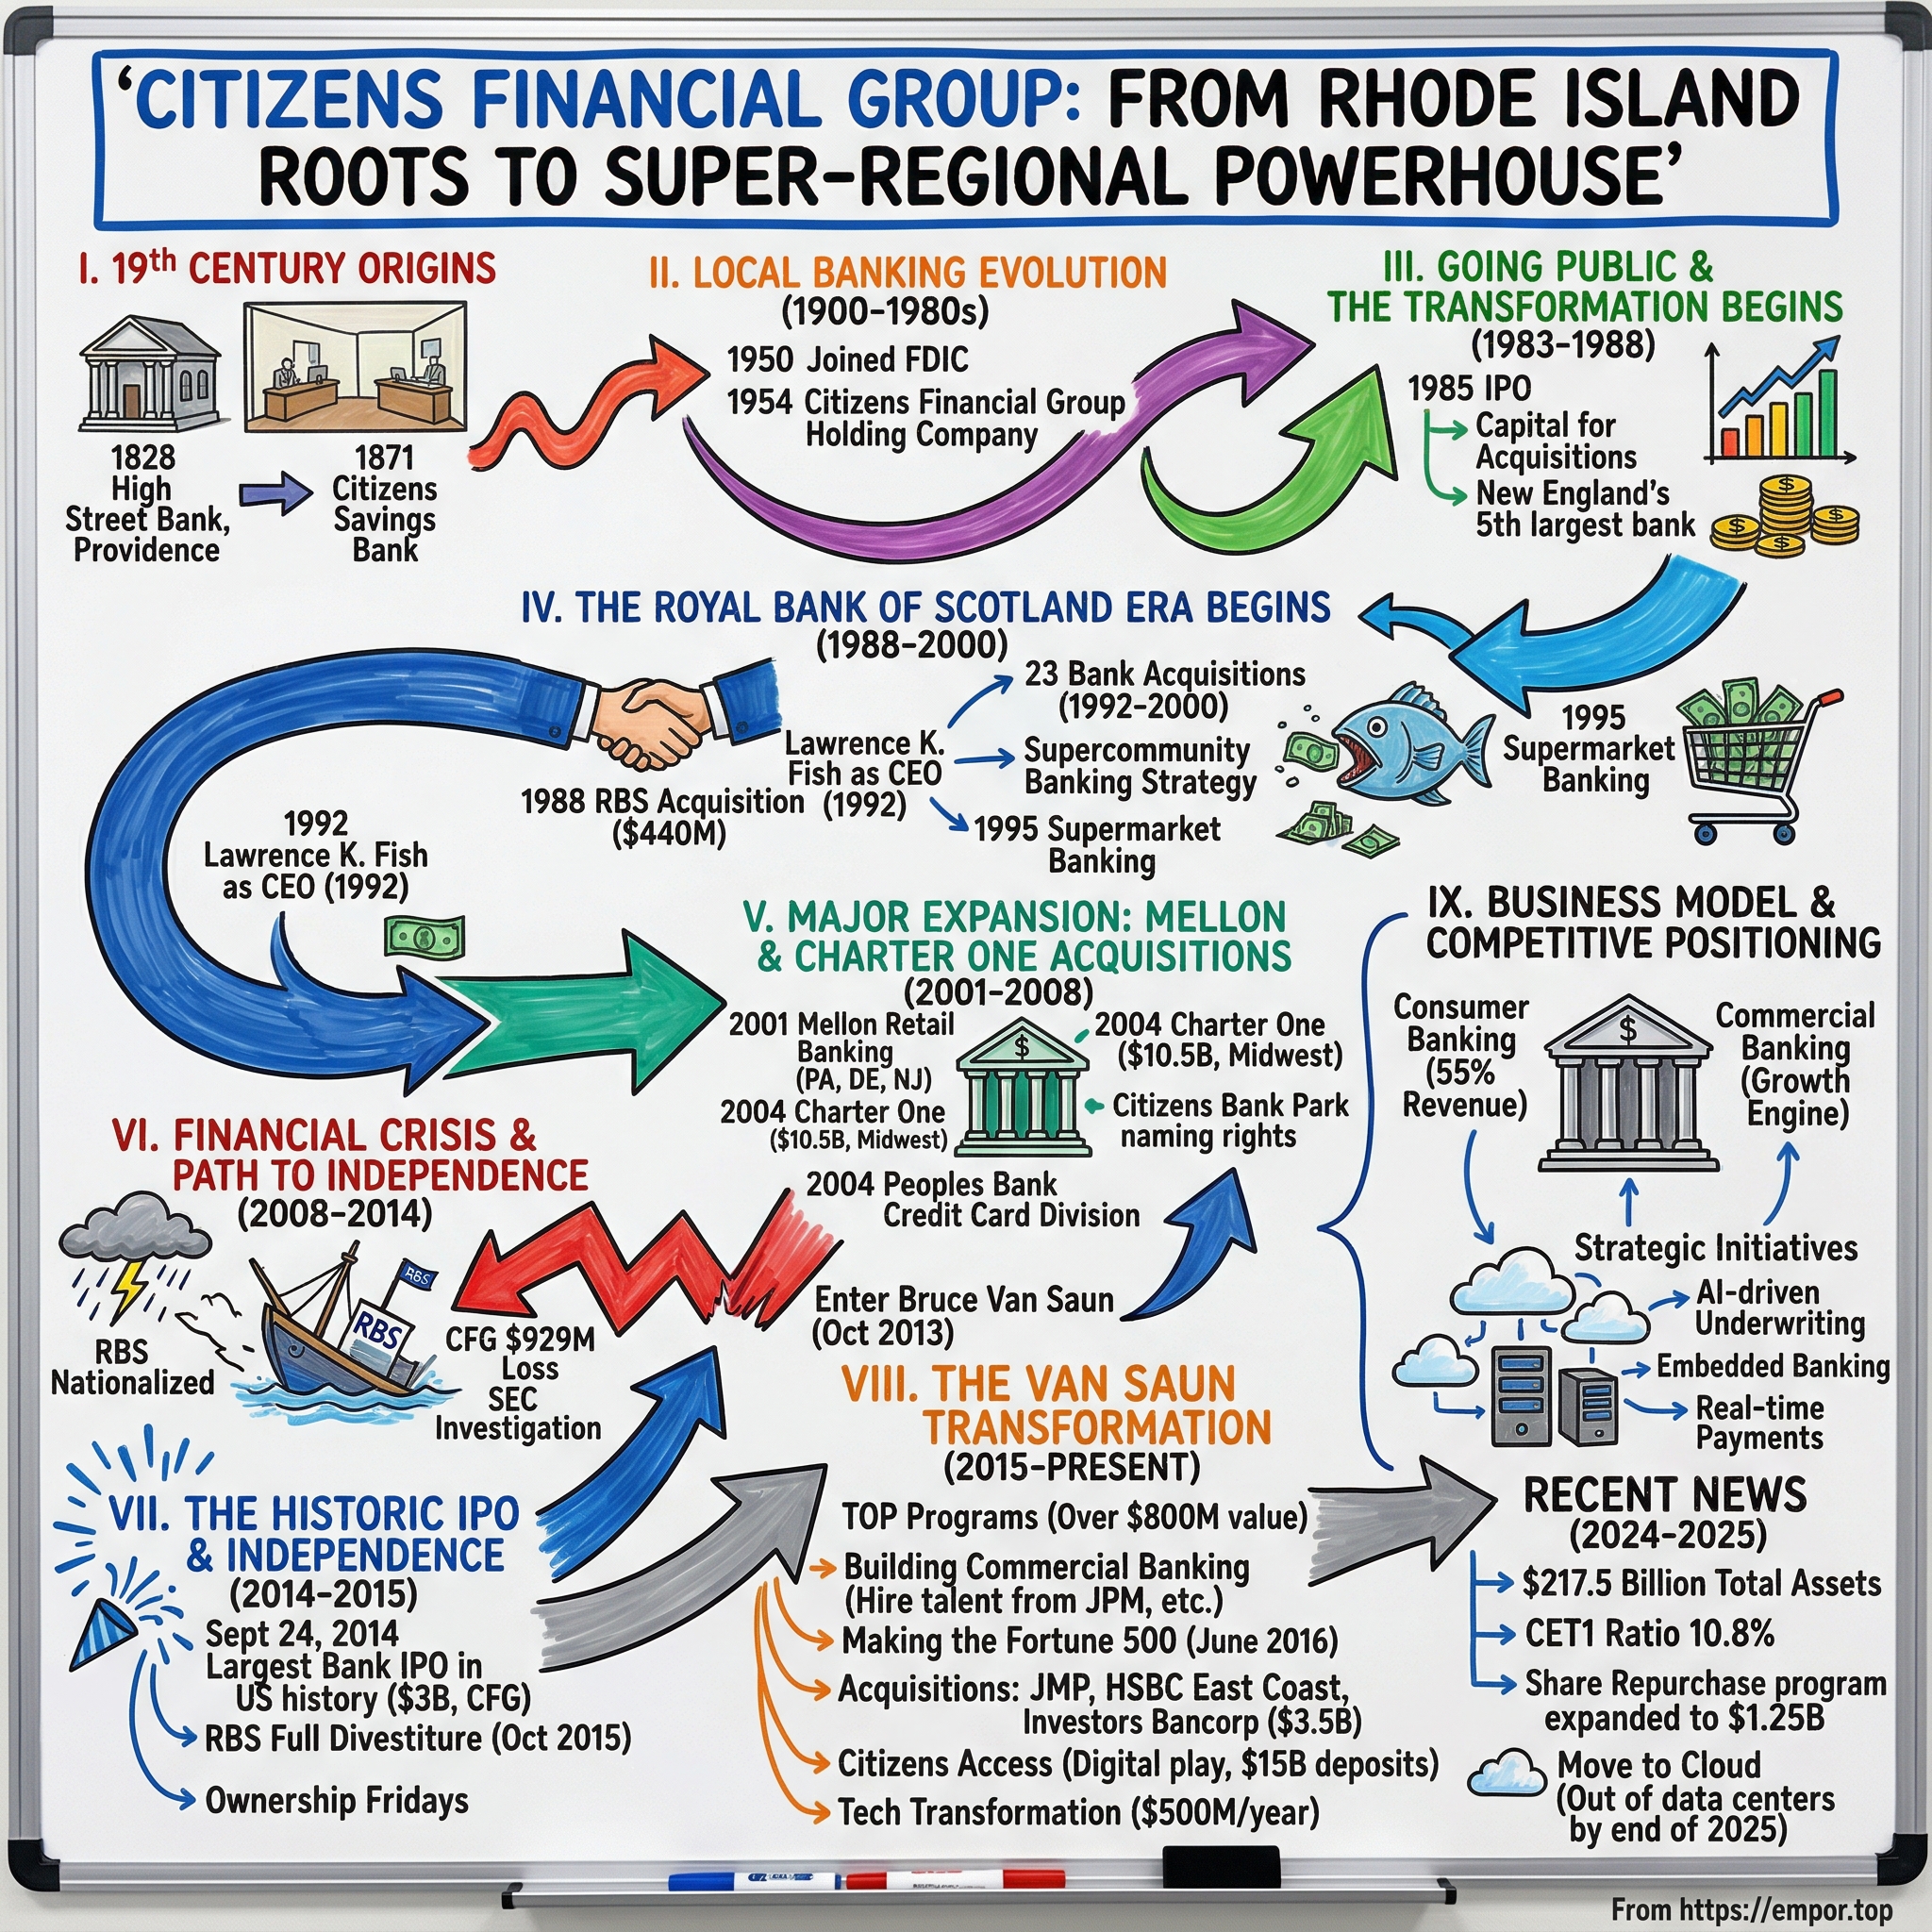
Citizens Financial Group: The Second Act — From RBS Subsidiary to Super-Regional Contender
I. Introduction & Episode Roadmap
On the morning of September 2, 2026, shares of Citizens Financial Group changed hands near $70, giving the Providence-founded, Stamford-headquartered bank a market capitalization of roughly $29.5 billion.1 The stock has traveled a long way in twelve months — the 52-week range runs from just under $48 to just over $75 — and the balance sheet underneath it now holds $233.8 billion of assets, $185.6 billion of deposits, and $147.5 billion of loans.2
Three and a half years earlier, in the frantic first weekend of May 2023, this same bank had come within a sealed FDIC envelope of becoming something else entirely. Citizens bid for First Republic Bank and lost to JPMorgan Chase.3 What happened next is the reason this story is interesting. Rather than walk away, Citizens went and hired the people. Today it is quietly operating a private bank stitched together from First Republic's alumni — a business that, by management's own accounting, threw off about 11.5% of the company's pretax income in the second quarter of 2026 at a return on equity around 25%.4
That is the good news, and it is real. Here is the number that frames everything else.
Citizens' management has committed, publicly and repeatedly, to a return on tangible common equity of 16% to 18% by the end of 2027.5 In the second quarter of 2026, actual ROTCE was 13.9%.2 That gap — a few hundred basis points, eighteen months of runway — is the entire investment debate compressed into one metric. It is also management's own scorecard, volunteered rather than extracted, which makes it the fairest instrument available for judging whether this transformation is real or rhetorical.
Some context on why 13.9% is an uncomfortable number. In the same quarter, Regions Financial posted roughly 20% adjusted ROTCE, Fifth Third about 19%, and Huntington 15.1%.678 Only KeyCorp, at 12.89%, sat below Citizens among the closest super-regional comparables.9 So the honest framing is not "worst in class" — it is "second-worst in a cohort where the leaders are five to six percentage points ahead." A bank earning 14% on tangible equity while its peer group earns 19% is, mechanically, a bank the market will value at a lower multiple of book. Management knows this. The 16–18% target is, in effect, a public admission that Citizens has been the profitability laggard of the super-regional group and intends to stop being one.
This is a company with two distinct lives. For 27 years it was the American subsidiary of The Royal Bank of Scotland — grown aggressively on someone else's capital, subjected to someone else's risk appetite, and very nearly broken when that parent detonated in 2008. For the twelve years since, it has been a standalone public company under one CEO, Bruce Van Saun, trying to prove that the second life justifies a better multiple than the first.
Three threads run through everything that follows. The first is patient capital and its limits: RBS incubated a franchise for a generation, but it took forced independence to impose discipline. The second is capability-building through talent rather than checkbooks — Citizens has not bought a bank or a branch network since 2022, choosing instead to lift out teams and buy small advisory boutiques. The third is the uncomfortable arithmetic of scale in banking, where being the eleventh-largest player in a business with enormous fixed technology costs is a structurally harder place to stand than being the fifth.
The question this episode tests is whether the second act deserves the re-rating its management is asking for.
 Subscribe on LinkedIn
II. Origins: A 200-Year Path to Providence's Biggest Bank
Start in two rooms of a residence on High Street in Providence, Rhode Island, in 1828. That was High Street Bank — a commercial bank serving a mill economy at the front edge of American industrialization. Four decades later, in 1871, the same directors obtained a second charter and opened a mutual savings bank alongside it. The first deposit into Citizens Savings Bank was made on April 19 of that year by Jessie Grant, the daughter of the bank's vice president. By December the new institution held $52,000 in deposits.10
That is the whole origin myth, and it is worth exactly the two paragraphs it gets, because the point is not the romance. The point is the character. For its first 120 years, Citizens was a conservative Rhode Island thrift. It did not begin building a branch network until 1947. High Street Bank moved into Citizens Savings' offices that same year and was renamed Citizens Trust Company in 1948. Its idea of expansion in 1954 was acquiring Greenville Trust Company — two branches and a bit over $8 million in assets.10
Compounding at that pace produces something eventually. By 1981, Citizens operated 29 branches across Rhode Island with $971 million in assets, under CEO George Graboys.10 Then came the first inflection: in 1985 the mutual structure was converted, a holding company named Citizens Financial Group was created, and the company sold 4.3 million shares of common stock at $23 per share. It entered public life with roughly $1.6 billion of assets.10
That 1985 listing is a useful bookend for what came almost thirty years later. Citizens has now been a public company twice — once as a small New England thrift holding company that lasted three years before being bought, and once as a $200-billion-plus super-regional carved out of a failed European parent. The intervening period is what turned a conservative deposit-gatherer into something with the ambition, and the problems, of a national bank.
What matters for the investment case today is the residue. The deposit franchise Citizens still leans on hardest — Rhode Island, greater Boston, the industrial Northeast — was laid down by a slow, local, relationship-driven institution over more than a century. That is the part of the balance sheet that does not churn when rates move. Everything bolted on after 1988 was bought, and bought things behave differently.
Which brings us to the buyer.
III. The RBS Century: Bought, Scaled, and Nearly Broken (1988–2008)
In December 1988, The Royal Bank of Scotland paid approximately $440 million for Citizens Financial Group.10 At the time this was an unremarkable transaction — a mid-sized Scottish bank buying a small New England thrift holding company as a beachhead. It became, over the next two decades, one of the largest foreign-owned retail banking franchises in the United States.
The man who made that happen arrived in 1992. Lawrence K. Fish was appointed chairman and CEO, and what followed was one of the more relentless acquisition campaigns in American regional banking. Citizens bought Old Colony in 1990, Plymouth Five Cents Savings in 1992, New England Savings and Boston Five Bancorp in 1993, Neworld Bancorp and Old Stone in 1994, Quincy Savings in 1995, First NH Bank in 1996, and a series of Connecticut operations after that — more than 25 bank acquisitions across two decades.1011 Fish called the strategy "supercommunity banking": run a large institution but preserve local decision-making and local brands, on the theory that customers bank with people, not logos.
The strategy worked until scale changed its nature. In 2001, Citizens bought the regional banking business of Mellon Financial for roughly $2.1 billion, vaulting the franchise out of New England and into the Mid-Atlantic — Pennsylvania, New Jersey, Delaware.12 Then in May 2004 came the deal that changed the company's weight class: Charter One Financial, a Cleveland-based thrift holding company, for $10.5 billion in cash, completed on August 31 of that year.13 Overnight, Citizens acquired the Midwest — Ohio, Michigan, Illinois, upstate New York — and became one of the ten largest commercial banking organizations in the country.13
Two things about the Charter One deal deserve attention, because they echo through everything Citizens has done since.
The first is that RBS wrote the check. Citizens did not raise the capital, did not dilute its own shareholders, did not have to defend the price to a public market. It was an internal capital allocation decision made in Edinburgh. That is what "patient capital" looks like on the way up: a subsidiary can grow far faster than its own earnings would allow, because the parent is underwriting the ambition.
The second is that integration lagged. Citizens ran a dual-brand structure for years — Citizens in the East, Charter One in the Midwest — and the operational complexity of running one bank under two names, on stitched-together systems, across a dozen states, became a chronic drag. The "supercommunity" philosophy that made sense at $10 billion of assets became a coordination problem at $130 billion. This is the recurring lesson of acquisition-led banking: the multiple you pay is knowable on day one, but the cost of integration is discovered over the following five years.
Then 2008 arrived. Citizens had not been an exotic-derivatives shop; its problem was the ordinary one of a large lender in a housing collapse. For 2008 it reported a loss of $929 million and warned it might have to write off close to $2 billion of bad loans.14 That was painful but survivable in isolation. It was not survivable in context. Its parent, RBS, posted the largest annual loss in British corporate history and required a UK government rescue that left the state owning the overwhelming majority of the group. RBS Group's American subsidiary was no longer a strategic crown jewel; it was an asset on a list of things a nationalized bank would eventually have to sell.
Here is the lesson that the current management team has internalized, and that shows up in Citizens' behavior to this day: growth financed by someone else's balance sheet, with someone else setting the risk appetite, is fragile. Citizens did not choose RBS's subprime exposures, did not choose the pace of the Charter One integration, and did not choose the timing of its own divestiture. It simply lived with the consequences.
Whether that lesson has produced genuine discipline or merely conservative habit is a question the next twenty years of Citizens' capital allocation will answer. But the immediate consequence of 2008 was straightforward: the parent had to go, and the only exit was the public market.
IV. Forced Independence: The 2014 IPO
The trigger, when it came, was not a strategy memo. It was a stress test.
In the spring of 2014, while still wholly owned by RBS, Citizens drew criticism from U.S. regulators over its capital planning and governance in the Federal Reserve's annual review.15 For a subsidiary of a nationalized British bank already under pressure to shrink, a Fed rebuke on capital and governance was not a technicality — it was a deadline. The separation that RBS had contemplated as an option became a requirement.
The man hired to execute it had arrived a year earlier. Bruce Van Saun joined Citizens in October 2013, having served from 2009 to 2013 as Group Finance Director and an executive director on the RBS board — which is to say, he had spent four years as the chief financial officer of the most spectacular banking failure in modern British history, working alongside CEO Stephen Hester to sell assets and shrink the balance sheet back to something viable.16 Before that he spent a decade at Bank of New York and then Bank of New York Mellon, including as vice chairman and chief financial officer.16 He is a Bucknell graduate with an MBA from the University of North Carolina, and earlier in his career worked at Deutsche Bank, Wasserstein Perella and Kidder Peabody.16
That résumé is the tell for what RBS was buying. They did not hire a growth banker or a retail merchant. They hired a finance executive who had personally run a bank-rescue asset-disposal program and knew, in operational detail, how to prepare a franchise for separation. Van Saun's job at Citizens was, at the outset, less about building than about making the company legible and saleable to public markets: cleaner capital, cleaner governance, standalone systems, a coherent equity story.
The market was not immediately persuaded. On September 23, 2014, Citizens priced its initial public offering of 140 million shares at $21.50 — below the $23–$25 range it had marketed — raising about $3 billion.1718 The stock began trading on the NYSE under the ticker CFG the following day and closed at $23.08, roughly 7% above the offer price.18 It was the largest U.S. bank IPO in years, and it priced at a discount, which is a fair summary of investor sentiment: interesting franchise, unproven as a standalone, still running RBS-era infrastructure and RBS-era culture, and being sold by a motivated seller.
That last point mattered enormously. RBS was not distributing Citizens because it believed the timing was optimal. It was selling because it had to. The staged exit ran through 2015 in a series of follow-on offerings and a buyback, and RBS divested its remaining stake — roughly 20.9% — in October 2015.18 Seven years after the crisis, Citizens was on its own.
Consider what that unlocked and what it exposed. On the unlocking side: every dollar of capital Citizens generated from that point forward was its own to allocate, and every strategic decision had to be defended to public shareholders rather than to a parent's group treasury. On the exposure side: a bank that had grown by acquisition for two decades now had to demonstrate it could grow organically, fund itself independently, and earn a competitive return without a parent absorbing the mistakes.
The scoreboard from that day to this is mixed in an instructive way. Citizens has closed the gap to peers on many operating measures — funding costs, fee diversification, credit discipline — while never quite closing it on the one that matters most to valuation. Twelve years on, the ROTCE gap is still there. Independence removed the excuse; it did not, by itself, deliver the result.
What Van Saun did with those twelve years is the substance of the story.
V. Building the Post-RBS Bank: TOP Programs and the 2021–2022 M&A Sprint
Every bank has a cost program. Most of them are theater. Citizens' version, launched in 2014 and given the faintly corporate name "Tapping Our Potential," ran for a decade in numbered iterations — TOP 1 through TOP 9, the last of which was completed in 2024 and delivered roughly $135 million of pre-tax run-rate benefit.19 A TOP 10 program followed in 2025.
The mechanism matters more than the branding. The premise of a self-funding efficiency program is that a bank with a structurally higher cost base than its peers cannot simply spend its way to modern technology — the earnings dilution would be unacceptable to shareholders and the operating leverage would never arrive. So instead you find recurring savings in one part of the business and redeploy them into the part you need to build. Over a decade, Citizens used TOP to pay for digital platforms, data infrastructure, and a mortgage and wealth build-out without going to the equity market for the money.
That discipline has a real limitation, and it is visible in the efficiency ratio. In the second quarter of 2026, Citizens' efficiency ratio — the share of revenue consumed by operating expense — was 61.1%, an improvement of 247 basis points from the prior quarter but still far from the mid-50s that management has set as its destination.25 Ten years of numbered cost programs produced a bank that is less inefficient, not an efficient one. That is the honest scorecard on TOP: a genuinely useful funding mechanism, not a competitive weapon.
The successor program is more ambitious and more technologically specific. "Reimagine the Bank," launched in 2025, targets roughly $100 million of pre-tax run-rate benefit by the end of 2026, $200 million-plus by the end of 2027, and $450 million-plus by the end of 2028 — built around AI-assisted software development, automated servicing, and process redesign.4 Management pointed on the first-quarter 2026 call to early evidence including materially faster software delivery and a more-than-50% increase in credit card origination.20 Two observations. First, the 2028 target is roughly three and a half times the annual benefit TOP 9 delivered, which means the company is asking investors to believe that AI-era cost takeout is a step change rather than an extension. Second, the program's costs are hitting the income statement now — outside services expense rose in the first half of 2026 specifically because of Reimagine implementation — while the benefits are back-loaded.21 Investors are being asked to fund the J-curve.
The 2021 M&A sprint, and what the prices say
Between May 2021 and June 2022, Citizens did more deal-making than in the entire preceding decade. Two transactions dominate.
Investors Bancorp was announced on July 28, 2021 — a New Jersey-and-New-York thrift-heritage institution with roughly $27 billion of assets, $20 billion of deposits, and 154 branches, about 130 of them in the New York metro area. The consideration was 0.297 CFG shares plus $1.46 in cash per Investors share, valuing the deal at approximately $3.5 billion.22 Management projected roughly $130 million of annual cost savings against about $400 million of integration costs, tangible book value dilution of around 2.6% with a 2.5-year earn-back, an internal rate of return above 20%, a return on invested capital near 13%, and about 6.4% accretion to 2023 fully diluted EPS on a standalone basis.22 The deal closed in April 2022.
Set that against the era. Bank M&A in 2021 cleared at roughly 1.4x to 1.6x tangible book value on average, and the Investors deal priced modestly below that band — appropriate, arguably, for a lower-margin thrift-heritage target. So the price reads as fair-to-good rather than brilliant. What has not been established is whether the returns landed. No primary-source retrospective confirming that the >20% IRR or ~13% ROIC were achieved has surfaced in Citizens' subsequent filings or investor materials; those figures should be read as signing-day management projections, not verified outcomes. The absence of a retrospective is itself a small governance note: banks that hit their deal models tend to say so.
The HSBC East Coast branch purchase is the better-priced of the two and gets less attention. Announced in May 2021 and completed on February 18, 2022, Citizens acquired 80 branches — 66 in the New York City metro area, nine in the Mid-Atlantic and Washington D.C., five in Southeast Florida — along with approximately $9.0 billion of deposits, $2.2 billion of loans, HSBC's national online deposit business, and more than 800,000 customer accounts. The price was a 2.0% premium on deposits.23
That number is the story. Branch deals have historically cleared in the mid-single-digit to low-double-digit percentage range on deposits. Paying 2.0% means Citizens bought $9 billion of retail funding for roughly $180 million of premium. Why so cheap? Because HSBC was not optimizing price — it was exiting U.S. mass-market retail banking entirely and needed a buyer who could absorb the whole East Coast network at once. Citizens' edge here was not analytical brilliance; it was being the right-shaped counterparty at the moment a motivated seller needed one. That is a legitimate and repeatable source of value, but it depends on someone else's distress, which is not a strategy you can schedule.
Alongside the bank deals came a set of small fee-business purchases: JMP Group, a San Francisco investment bank focused on healthcare, technology, financial services and real estate, acquired for approximately $149 million in cash at $7.50 per JMP share and completed in November 2021;24 DH Capital, a technology and internet-infrastructure advisory boutique, announced in December 2021;25 and more recently Matrix Capital Markets Group, a Richmond, Virginia firm specializing in downstream energy and convenience retail M&A, acquired in February 2026 and folded into Citizens JMP Securities.26 These are not balance-sheet deals. They are talent-and-relationship deals, funded with cash, designed to give the Commercial bank sector-specific advisory capability it could not hire one banker at a time.
The tell: silence since 2022
Here is the fact that defines Citizens' current capital allocation posture. The company has not acquired a bank or a branch network since the Investors transaction closed in April 2022. On the first-quarter 2026 call, Van Saun described the Matrix purchase as "a very small but high-quality M&A boutique" and indicated that acquisitions would continue to be "generally going to be small."20
Meanwhile the industry consolidated around it. Fifth Third completed its $10.9 billion all-stock merger with Comerica on February 2, 2026, creating the ninth-largest U.S. bank at roughly $294 billion of assets.27 PNC agreed in September 2025 to acquire Colorado's FirstBank Holding Company — 95 branches, $26.8 billion of assets — for about $4.1 billion, receiving Federal Reserve approval that December.28
Is Citizens' restraint discipline or paralysis? The bull reading is that a bank trading at a below-peer multiple should not be issuing stock to buy anything, and that management is correctly waiting to fix its own returns before spending someone else's premium. The bear reading is that in a consolidating industry with a more permissive regulatory posture, the banks that scale re-rate and the banks that don't get left with a structurally sub-scale technology budget. Both readings are consistent with the evidence to date. What would distinguish them is whether Citizens' organic returns actually converge on the peer group by the end of 2027 — because if they don't, four years of M&A abstinence will look less like discipline and more like a company that lacked the currency to participate.
The one thing Citizens did buy in that window was not a company at all. It was a roster.
VI. The First Republic Gambit: Building Citizens Private Bank
On April 30, 2023, Bruce Van Saun was having dinner in Delray Beach, Florida, waiting for a call that never came the way he wanted. Citizens had bid in the FDIC's auction for First Republic Bank. JPMorgan Chase won.3
For a bank that had spent two years telling investors it intended to build a serious wealth and private banking franchise, this looked like the end of the plan. First Republic was the single most attractive private banking client base in America — affluent coastal households, venture and private-equity relationships, deposit balances that were both large and, at least historically, sticky. There was no second First Republic to buy.
There was, however, a workforce that had just watched its employer fail.
Six weeks later, on June 9, 2023, Citizens announced it was hiring approximately 50 senior private bankers and about 100 support staff from First Republic across Boston, Florida, New York and San Francisco.3 Among that first wave was Susan deTray, First Republic's deputy chief credit officer and head of credit administration, who had overseen a loan portfolio north of $200 billion; she was named head of Citizens Private Bank in late July.29 Citizens also recruited private-banking veterans from JPMorgan for senior roles. Citizens Private Bank launched formally in October 2023, initially aimed at startups, venture investors, and the professional-services clientele that had orbited First Republic, with six offices planned across New York, Boston, Palm Beach and San Francisco.3031
Van Saun's later framing of the auction loss — that Citizens effectively won by losing — is the sharpest strategic claim in this whole story. Strip away the rhetoric and it says something specific: the valuable asset in First Republic was the people and the operating playbook, not the balance sheet. First Republic's loan book was stuffed with long-duration, low-coupon residential mortgages written when money was free and marked deeply underwater when it wasn't. Acquiring the franchise meant acquiring that. Hiring the bankers meant acquiring the origination capability and the client relationships while leaving the mark-to-market problem with someone else.
That is textbook counter-positioning: doing the thing the incumbent structurally cannot copy, because JPMorgan's win came with the obligation to digest the assets. And it cost Citizens compensation expense rather than capital.
The claim versus the record
Now the harder question, and the one that matters most for how much credit management deserves. Did the business scale the way it was sold?
In January 2024, roughly three months after launch, Citizens told the market it expected the Private Bank to reach approximately $11 billion of deposits, $9 billion of loans, and $10 billion of assets under management by the end of 2025.32
Here is what actually happened.
Deposits blew past the target and kept going — the Private Bank ended 2025 at $14.5 billion of deposits and reached $17.8 billion by the second quarter of 2026, up 7% in a single quarter.332 On deposit-gathering, the thesis was not merely validated; it was exceeded by a wide margin. That is the single strongest piece of evidence that the talent lift-out worked, because deposits are the hardest thing to move — they require a client to change where their money lives, which is a trust decision, not a price decision.
Lending is a different picture. Along the way, the company revised the 2025 loan target down — guiding to roughly $7 billion of Private Bank loans for 2025 after ending 2024 at $3.1 billion, against the original $9 billion figure.34 Private Bank loans stood at $7.7 billion at the end of the first quarter of 2026 and reached $9.7 billion in the second quarter of 2026 — landing almost precisely on the original dollar target, roughly six to twelve months after the original deadline, and only after that deadline had been formally relaxed.204 Client assets tell a similar story: total client assets were $10.1 billion at the end of the first quarter of 2026 and $11.2 billion by the second, including $9.6 billion of assets under management — again clearing the original $10 billion figure, again late.204
Management's own explanation on the second-quarter 2026 call was unusually candid: "We were held back intentionally on going really fast on growth to make sure we could demonstrate to ourselves that we could build this model effectively."5 Read that carefully. It is a reasonable risk-management posture and it is simultaneously an admission that the ramp was slower than the January 2024 framing implied. A target that is missed because you deliberately decelerated is still a missed target; the discipline is creditable, the forecast was not.
The calibrated verdict: the optionality claim is narrowed, not rejected. Citizens demonstrated it can attract high-quality private banking deposits at speed — that part exceeded plan and is now material. It has not yet demonstrated that it can scale the asset side and the fee side on the timetable it publishes. The revised claim worth holding is: Citizens has built a real, profitable private bank whose funding franchise is proven and whose lending and wealth-management scaling runs roughly a year behind management's stated schedule.
The forward tests are specific. Office count is the cleanest: ten offices were open as of the second quarter of 2026, with management targeting 15 to 16 by the end of 2027.4 Note that this itself has moved — on the first-quarter call, management framed the ambition as 11 offices by year-end 2026 and "25 to 30 within three to four years," a considerably more aggressive number than the 15–16-by-2027 figure presented a quarter later.20 Whether that is a genuine tempering or merely two different horizons being described is not disclosed, but analysts should track which number the company repeats. The second test is economics under expansion: the Private Bank has been running loans at roughly a 4% spread over its deposit costs.20 Florida is the newest major market and management has said it expects five to seven years to reach California-scale there. If that spread compresses as the business pushes into markets where Citizens has no First Republic alumni network and no incumbent relationships, the growth will be arriving at a lower return.
Sizing it honestly
At roughly 11.5% of pretax income and a 25% return on equity, the Private Bank is genuinely material today — it added fifteen cents to quarterly earnings per share in the second quarter, up from eleven cents the prior quarter.42 It is the fastest-growing profit pool Citizens owns and the clearest evidence that this management team can execute a new business build.
It is also, still, a minority of the bank. Nearly nine-tenths of pretax income comes from somewhere else. And the durability question is unresolved in a way that deserves stating plainly: the asset Citizens acquired was human beings. Bankers who left one employer for a better offer can leave again. Until this cohort has been through a full cycle and a full retention window, "cornered resource" is the wrong description. "Successfully rented capability" is closer.
Which means the answer to whether Citizens re-rates lives mostly in the other 88% of the company.
VII. The Core Business Today: Segments, Economics, and Competitive Position
Strip away the narrative and Citizens is two businesses plus a corporate center.
Consumer Banking — about 1,000 branches across 14 states and the District of Columbia, roughly 3,000 ATMs, and now the Private Bank and Private Wealth operations folded inside it — generated $804 million of net income in the first half of 2026, up from $712 million a year earlier.21 Commercial Banking generated $523 million, up from $402 million.21 The corporate "Other" segment absorbed a $223 million loss, largely the drag of legacy non-core assets and unallocated funding.21
The proportions matter because they cut against the way the company is often discussed. Consumer is the larger profit engine by a wide margin — a bit over 60% of segment net income — and it is the segment growing off the bigger base. Commercial is the faster-growing on fees: capital markets fees hit a record $153 million in the second quarter, up 46% year over year, driven by loan syndications and bond underwriting, with management flagging strengthening middle-market M&A pipelines.5 Wealth fees contributed $102 million.35
That fee engine is where the JMP and Matrix acquisitions show up. Citizens spent modest cash to buy sector-specialist advisory teams, and the resulting capital markets revenue is now a visible, cyclical, high-margin contributor. It is also, by construction, the part of the P&L most exposed to a shutdown in deal activity — a record quarter for debt capital markets is a fine thing to report and a poor thing to extrapolate.
The core banking economics
Net interest margin — the spread between what Citizens earns on assets and pays for funding, which is the fundamental profitability metric for any deposit-taking institution — reached 3.17% on a fully taxable-equivalent basis in the second quarter of 2026, up three basis points sequentially and 22 basis points year over year.2 Management guides to 3.22%–3.27% by the fourth quarter of 2026 and 3.30%–3.50% by the end of 2027.5
It is worth being precise about why that margin is expanding, because the source determines the reliability. Roughly six basis points of the sequential improvement came from terminated interest-rate swaps, and management has been explicit that the expansion is driven substantially by fixed-rate assets repricing upward as old, low-coupon loans and securities roll off — not by a bet on where the Federal Reserve goes next.520 In plain terms: Citizens wrote a lot of loans and bought a lot of bonds when rates were near zero, and every quarter a slice of that matures and gets replaced at today's rates. That is a mechanical, largely predictable tailwind, and it is the most credible single component of the path to 16–18% ROTCE.
Credit is behaving. Net charge-offs ran at 0.37% of average loans in the second quarter, nonaccrual loans at 0.97%, and the allowance for credit losses covered 1.48% of loans.2 Common equity tier 1 capital stood at 10.4%, just under the company's 10.5% internal target — and management attributed the shortfall not to credit stress but to loan growth that "accelerated during the quarter and exceeded expectations."5 Citizens repurchased $225 million of stock and paid $197 million of common dividends in the quarter.4
The uncomfortable peer table
Citizens sits mid-pack by size. At $233.8 billion of assets it is larger than KeyCorp ($191.3 billion) and Regions, and dramatically smaller than PNC, Truist and U.S. Bancorp — and now smaller than Fifth Third following the Comerica combination.2927
On profitability it sits near the bottom. The ROTCE comparison introduced at the top of this story — Regions near 20%, Fifth Third around 19%, Huntington at 15.1%, Citizens at 13.9%, KeyCorp at 12.89% — is the single most important competitive fact about this company.67829 And the peers are not standing still: Huntington has publicly targeted 18–19% ROTCE for 2027, and KeyCorp has set long-term targets of 16–19%.836 Citizens' 16–18% goal, if achieved exactly on schedule, would move it from bottom-quartile to roughly the bottom of the middle of the pack — assuming no peer improves in the meantime, which they intend to.
Efficiency tells the same story from the cost side. KeyCorp's cash-basis efficiency ratio of 61.86% is comparable to Citizens' 61.1%.9 The banks earning 19–20% on tangible equity are operating meaningfully leaner. This is the scale disadvantage made visible: a $234 billion bank and a $600 billion bank need broadly similar core technology, compliance, risk and data infrastructure, and the larger one spreads it over nearly three times the revenue.
Where the franchise is genuinely strong
There is one clear, evidence-backed advantage. In Rhode Island, Citizens held $15.62 billion of deposits as of the most recent FDIC Summary of Deposits data available — approximately 36.7% of the state's total, up from 35.0% the prior year, and by a wide margin the largest share in the state.37 It holds the number-two position in New England overall and in Pittsburgh. Those are not marketing claims; they are regulatory deposit filings, and they translate into a genuinely lower-cost, lower-churn funding base in the markets where Citizens has been the local bank for a century or more.
The problem is that this advantage does not show up in company-wide returns. Roughly a third of one small state's deposits is a durable moat around a modest amount of money. The New York metro deposits Citizens bought from HSBC and Investors are the growth markets, and in those markets Citizens is a challenger competing against JPMorgan, Bank of America and Citi on their home turf.
The NEXT program: an admission dressed as an initiative
Which brings us to the branch network. Citizens announced in 2026 a multi-year plan — internally, the network evolution program — to close approximately 100 to 120 in-store supermarket branches and open 50 to 60 nearby standalone locations staffed with wealth managers and small-business bankers, targeting mass-affluent and affluent customers. Management has suggested the transition could attract $20 billion to $30 billion of low-cost deposits over roughly a decade, and expects the total retail branch count to remain relatively stable through 2035.384
Read this for what it is. The in-store supermarket branch was a 1990s bet that convenience and foot traffic would win retail deposits. In an era when the deposit-shopping customer opens an account on a phone in four minutes and compares yields across a dozen institutions, a teller window next to the produce aisle produces transactions, not relationships. Closing 100-plus of them and reinvesting in fewer, higher-value advisory locations is a rational response to a model that has been losing.
The scale of the claim, though, deserves scrutiny. Twenty to thirty billion dollars of incremental deposits over ten years, from a network that is shrinking in unit count, is a large number resting on the assumption that advisory-led branches convert to relationships at rates the in-store model never achieved. There is no published evidence yet that they do. Treat it as a hypothesis with a decade-long testing period, and watch household growth and deposit cost, not branch counts.
Porter's Five Forces, applied to a super-regional
Rivalry is brutal and two-sided. Above Citizens sit the money-center banks with technology budgets measured in the many billions and national brands. Below and beside it sit digital-only banks and fintech deposit products with no branch cost structure at all. Citizens is squeezed from both directions on the same product.
Threat of new entrants is genuinely low — in balance-sheet banking. Chartering a bank, holding regulatory capital and managing liquidity is an enormous barrier, and that barrier is real. But the barrier protects the balance sheet, not the customer relationship. Fintechs do not need a charter to unbundle payments, lending, or brokerage from the bank that holds the deposit. The moat is around the vault, not the front door.
Buyer power is rising. Depositors can now compare rates instantly and move money in a day. The March 2023 regional-bank crisis proved that deposit flight can happen at internet speed. That single change has permanently raised deposit betas across the industry — the share of any Fed rate increase that banks must pass through to depositors.
Supplier power, in banking, is monetary policy. Citizens does not negotiate its cost of funds with a supplier; it inherits it from the Federal Reserve and the competitive market for deposits. That is why NIM guidance is the most consensus-sensitive number the company publishes.
Substitutes are eating from both ends. Money-market funds substitute for deposits; private credit funds substitute for commercial loans, increasingly at scale and increasingly for exactly the middle-market borrowers a bank like Citizens serves. This is the most underappreciated structural pressure on the regional banking model, because it attacks the asset side and the liability side simultaneously.
Seven Powers, applied honestly
Run Hamilton Helmer's framework against Citizens and most boxes come back empty.
Network economies: none. A depositor's account is not more valuable because another depositor joined. Process power: no evidence of a proprietary operating capability peers cannot replicate; the efficiency ratio argues against it. Scale economies: present in the industry, but Citizens is on the wrong side of them relative to PNC, Truist, U.S. Bancorp and now Fifth Third — the ROTCE gap is the scale disadvantage rendered in a single number. Switching costs: modest and eroding; direct deposit and bill-pay create friction, but less every year. Branding: strong locally in Rhode Island and southern New England, negligible nationally.
Cornered resource: the closest candidate is the ex-First Republic private banking team. But as established, people are rentable, not owned, and no multi-year retention record exists yet. Counter-positioning: this is the strongest claim in the portfolio — replicating a franchise through talent acquisition rather than buying its impaired balance sheet was a move the winning bidder could not make. Whether it is repeatable, or was a once-in-a-decade dislocation, is unknowable from one instance.
The sober conclusion is that Citizens does not currently possess a durable structural power in Helmer's sense. It possesses a solid regional deposit franchise, a competent management team executing a credible improvement program, and one genuinely clever strategic move. That combination can produce good outcomes. It does not, by itself, produce a premium multiple — which is precisely why the 2027 ROTCE target is the whole argument.
And a target that ambitious puts enormous weight on the people setting it.
VIII. Management, Incentives, and Capital Allocation: A Credibility Stress Test
Bruce Van Saun is 69 years old and has run Citizens for twelve and a half years.39 He has now been chief executive of this company longer than he was a finance executive anywhere else, and the transformation story is inseparable from him. On the second-quarter 2026 call, asked about his plans, he answered: "I am in no rush to go anywhere. I feel lots of energy and really have a spring in my step every day when I come to work."5
His 2025 total compensation was $12,513,920 — a $1,487,000 salary, $2,840,750 in cash bonus (half of which he deferred), $8,045,370 in stock awards, and $140,800 of other compensation. The 2024 figure was $10,630,796 and 2023 was $11.0 million.40 He beneficially owns 1,152,397 shares — less than 1% of the company, worth roughly $80 million at the current price.40 That is meaningful personal wealth tied to the stock, but as a fraction of total compensation received over a twelve-year tenure it is a moderate rather than founder-like alignment.
Succession, in real time
The succession story is where management credibility gets tested hardest, and where the record contains a genuine failure.
In June 2024, the Compensation and HR Committee granted off-cycle "Leadership Succession Awards" to three executives identified as CEO successor candidates. The values were disclosed in the 2025 proxy: Brendan Coughlin $12.0 million ($6.0 million in performance share units, $4.0 million in restricted stock units, $2.0 million restricted cash), John Woods $7.0 million ($3.5 million / $2.5 million / $1.0 million), and Elizabeth Johnson $3.0 million.41 The equity portions vest in a single installment on June 13, 2027, with the performance shares tied half to ROTCE and half to EPS over 2024–2026, plus a relative total-shareholder-return modifier.41 The committee's stated rationale was explicit: to retain a strong pool of internal CEO candidates in an extremely competitive market for executive talent. No off-cycle award was granted to Van Saun himself.41
The awards did not do what they were designed to do.
Johnson retired on March 3, 2025 and forfeited her LSAs.41 More consequentially, John Woods — the chief financial officer, a named successor candidate, and the recipient of a $7 million retention package intended to hold him through 2027 — resigned to become CFO of State Street, departing in August 2025.42 He repaid the $1 million cash portion of the award in full, as the terms required.40 Aunoy Banerjee, previously of Barclays, became CFO in October 2025.40
Two of the three executives the board paid $22 million to retain were gone within nine months. That is not a small data point. It is the clearest available evidence on a specific question — does this board's incentive design actually work? — and the answer, on this occasion, was no. Retention money buys a repayment obligation, not a person. A CFO who is offered the same title at a larger, more prestigious institution will take it, and a $7 million grant with a 2027 cliff is simply the price of the option he chose not to exercise.
The board did, on the third executive, get what it paid for and more. Brendan Coughlin, 46, was promoted to President on April 30, 2025, and on July 9, 2026 his mandate was expanded to cover essentially the entire operating company: consumer banking, private banking, wealth management, commercial banking, plus enterprise marketing, data and analytics, and the Reimagine the Bank technology program.3942 Ted Swimmer, head of commercial banking since October 2025, now reports to him, following Don McCree's retirement in March 2026.39 Van Saun has said publicly: "I'd say the obvious candidate to [take over as CEO] is Brendan."39
So where does that leave the credibility claim? Narrowed, not refuted. Citizens does have a credible, deeply experienced internal successor with a 22-year tenure and a demonstrated ability to build a new business from scratch. It does not have a resolved succession: no retirement date has been announced, no transition timeline published, and the process has already cost the company one named candidate. The confirming event to watch is simple and binary — a publicly announced transition timeline. Its continued absence, in a CEO's thirteenth year at age 69, is itself information.
The say-on-pay episode
Shareholders noticed. Support for Citizens' advisory vote on executive compensation had historically averaged over 93%. It fell to approximately 63% in 2024 and then to approximately 59% in 2025, with both Institutional Shareholder Services and Glass Lewis recommending votes against.40
The company's own diagnosis, in the 2026 proxy, is refreshingly direct: the Leadership Succession Awards were "the primary driver" of the 2025 result, and while most shareholders it spoke with understood the rationale, "many shareholders did not support our 2025 say-on-pay proposal because they do not support off-cycle awards as a matter of policy."40 The board's response was to commit that "there are no current plans to issue additional off-cycle succession awards in the future."40
That response appears to have worked. At the annual meeting on April 23, 2026, the say-on-pay proposal received 327,158,449 votes for against 30,630,016 opposed with 1,141,219 abstentions — roughly 91% of votes cast, a near-complete recovery.43 A separate shareholder proposal to adopt a majority vote standard was rejected, with about 90% voting against.43 Every director nominee was elected, though Van Saun himself received the lowest support of the twelve, at 336.7 million votes versus 357.5 million for the highest-supported director.43
The honest read: a genuine two-year governance flashpoint, tied directly to the unresolved succession, which the board addressed through engagement and a policy commitment rather than by clawing back the awards. The recovery in the vote is evidence the board is responsive. The fact that the awards failed on two of three recipients is evidence the underlying judgment was flawed.
The capital allocation record — tested against the tape
Management describes itself as a disciplined allocator. Test it against the filings.
Dividends. Citizens did not cut its dividend through COVID. It raised it in 2020, and has raised it repeatedly since, most recently declaring $0.46 per share alongside the fourth-quarter 2025 results.33 For a regional bank that had reported a $929 million loss in the previous crisis under different ownership, maintaining and growing the dividend through 2020 was a real credibility statement.
Buybacks. Here the popular narrative — that Citizens bought back stock aggressively into the 2023 regional-bank crisis — does not survive the filings. The actual annual repurchase spend runs: $1,025 million in 2018, $1,220 million in 2019, then a collapse to $270 million in 2020, $295 million in 2021 and $153 million in 2022, followed by $906 million in 2023, $1,050 million in 2024 and $600 million in 2025.44 Against shares acquired, the implied average prices work out to roughly the mid-$30s in 2018–2020, the low-to-mid $40s in 2021–2022, roughly $32 in 2023, the high $30s in 2024 and the mid-$40s in 2025.44
That record is more countercyclical than the caricature. Citizens' two largest post-crisis deployments — 2023 and 2024, nearly $2 billion combined — occurred at the lowest average prices of the entire period, in the immediate aftermath of the March 2023 dislocation. The 2021–2022 purchases were indeed made at the highest average prices of the cycle, but they totaled less than $450 million combined, because capital was being conserved for the Investors and HSBC transactions.
The genuine disconfirming data point sits earlier. The single largest buyback year in the company's public history was 2019 — $1.22 billion at roughly $36 a share — immediately before the stock fell to the mid-teens in the March 2020 crash, after which Citizens spent three years buying almost nothing while the price recovered. That is the classic pattern a skeptic should hold against any management team's "disciplined allocator" pitch: maximum deployment at the top of a cycle, minimum deployment at the bottom.
The calibrated verdict: the discipline claim survives, in a narrowed form. Citizens has demonstrated countercyclical buyback behavior once, convincingly, in 2023–2024, and procyclical behavior once, in 2019. Two observations do not establish a process. In fiscal 2025 the company returned about 80% of its earnings to shareholders and retired roughly 3% of its share count.3344 The forward test is whether that payout ratio holds if the credit cycle turns.
An activist's angle. No activist investor position in Citizens has been publicly disclosed, and the shareholder base is uncontested. What would a skeptical activist actually press on? Three things. First, the "Other" segment losing $223 million in a half-year — what exactly is in there, and how much of it is a legacy portfolio that could be sold? Second, the four-year absence from bank M&A while trading below peers on returns — either use the currency or explain why the currency is permanently impaired. Third, the pay-versus-performance question that ISS and Glass Lewis already raised: a CEO earning above $12 million while the company posts the second-lowest ROTCE in its peer group is a defensible outcome only if the trajectory delivers. That the vote recovered to 91% suggests shareholders are, for now, granting the benefit of the doubt.
The doubt has an expiry date, and several things could accelerate it.
IX. Current Risk Radar
Commercial real estate, and the honesty of a volunteered number
Citizens' commercial real estate book stood at $23.8 billion at June 30, 2026, down from $24.6 billion at year-end and representing 16% of total loans.21 Multifamily is the largest slice at $8.6 billion; office splits into $1.8 billion of credit-tenant-lease and life-sciences exposure and $2.3 billion of other general office.21 New York is the largest state concentration at $6.2 billion.21
Management has been running this book down deliberately for three years — CRE balances fell roughly 4% in the first quarter of 2026 alone and about 16% year over year — and has described its posture as biased to net shrink.205 There was a small execution wrinkle in the second quarter: several expected payoffs "got pushed out into the third quarter," slowing the intended rundown.5 That is a timing issue, not a credit event, but it is the kind of slippage worth tracking because the deleveraging pace is part of the ROTCE math.
The disclosure that deserves the most attention is one management volunteered rather than one a regulator required. Against roughly $4.1 billion of general office exposure, Citizens carries an allowance coverage ratio of 9.5% — and, combined with charge-offs already taken since early 2023, management has said the implied cumulative loss rate on that portfolio approaches roughly 20%.4
Sit with that. Reserving nearly one dollar in ten against a loan portfolio, and telling investors that cumulative losses on it will end up near one dollar in five, is not a comforting statement in isolation. Management presents it as reassurance — the argument being that the pain is largely identified and provided for, and that the remaining book is marked at a level where further deterioration is unlikely to surprise. That argument is reasonable and the reserve level is genuinely conservative relative to many peers. But it is an estimate produced by the party with the strongest interest in it being right, and office valuations are still being discovered in real time. The allowance is an accounting judgment, and it is the single most consequential one on Citizens' balance sheet.
For context on how the ACL is built: Citizens' baseline scenario assumes a start-to-trough real GDP decline of about 0.6%, but it applies a materially more severe overlay to CRE general office — peak unemployment near 9.5% and a GDP decline of roughly 4.4%.21 That is the company explicitly saying it does not trust its own base case for this portfolio.
Regulatory capital: an improvement that is not yet a requirement
In the 2026 Federal Reserve stress test, Citizens' implied stress capital buffer fell 200 basis points to 2.5% — the regulatory floor, and one of the largest improvements of any bank in the exercise.45
The catch is important and easy to misread. On February 4, 2026, the Federal Reserve Board voted to maintain existing stress-test-related capital requirements unchanged while it completes a methodology overhaul and considers public feedback, with revised rules expected to apply from the 2027 cycle.46 The practical consequence is that Citizens' binding stress capital buffer continues to be set by an earlier test, not by the 2026 result. The improvement is real as an indicator of balance-sheet resilience; it is not yet capital that management is permitted to deploy. On the first-quarter call, management indicated that any reduction in the 10.5% internal CET1 target would more likely come in 2027 than 2026, given macro uncertainty.20 If the Fed's revised framework does eventually bind at something near 2.5%, that would free meaningful capital — but that is a 2027 event contingent on a rulemaking that has not concluded.
Deposit competition and the structural squeeze
This is the mechanism running underneath both the branch program and the Private Bank. Citizens funds itself substantially with retail deposits, of which $40.9 billion — about 22% of the total — is noninterest-bearing.21 That block of free funding is the most valuable asset a bank owns and the one most exposed to erosion, because money-market funds and digital-only competitors have made the alternative to a checking account both visible and one tap away.
Analysts pressed on exactly this on the second-quarter call, questioning whether an uptick in deposit costs signals emerging competitive pressure.5 It is the right question. Every basis point of deposit beta that Citizens is forced to concede works directly against the NIM expansion that underpins the ROTCE target. The Private Bank's outperformance in deposit-gathering is, in part, an answer to this problem — high-balance private banking relationships carry a meaningfully higher share of noninterest-bearing and low-cost checking balances than the legacy retail book.
Rate and margin sensitivity
The path to 16–18% ROTCE has two load-bearing assumptions: that net interest margin reaches the guided range by the end of 2027, and that the efficiency ratio compresses from 61% into the mid-50s. Management has decomposed the ROTCE bridge as roughly two percentage points from time-based benefits (the fixed-rate repricing and non-core runoff), 150 to 200 basis points from business performance, and the remainder from credit normalization.5
The first component is the most reliable because it is mechanical. The second requires Reimagine the Bank to deliver on a back-loaded schedule while the Private Bank scales into new markets. The third requires credit not to deteriorate. Three assumptions, eighteen months, and a target the company has publicly committed to.
Execution risk in the transition itself
Finally, the risk that compounds all the others: a multi-year, undated CEO handoff at a company in the middle of a transformation. Coughlin now owns essentially every operating lever, which is sensible preparation and also concentration. A transition executed poorly — or a transition that keeps not happening while the incumbent stays energized — introduces sequencing risk into a plan that has very little schedule slack left.
X. Playbook: What This Story Teaches
Strip Citizens down to transferable lessons and five things stand out.
When the target's balance sheet is the liability, buy the people instead. The First Republic episode is the cleanest example in recent banking history of separating a franchise's valuable component from its toxic one. JPMorgan bought the whole thing and got the client base plus the underwater mortgage book. Citizens hired the origination capability and left the assets behind. The generalizable insight: in any acquisition, ask which specific asset is generating the value — the technology, the customer list, the distribution, or the team — and then ask whether it can be acquired separately. Frequently it can, and usually more cheaply. The limitation is equally clear: talent is a rental, and the deal only works when a dislocation has made an entire team available at once.
Self-funding efficiency programs let you modernize without diluting. A decade of TOP programs bought Citizens its technology stack without an equity raise. That is a genuinely repeatable discipline. But the honest scorecard on TOP is a 61% efficiency ratio after ten years — the mechanism funded the investment; it did not by itself produce competitive cost position. Investors should judge Reimagine the Bank not on the announced targets but on whether the efficiency ratio actually moves.
Retention money buys a repayment obligation, not a person. John Woods' departure for State Street, nine months after a $7 million grant explicitly designed to hold him for three years, is the case study. When a competitor offers a step up in title, institution, or scope, a vesting cliff is simply a number the recipient prices against the opportunity. Boards designing succession incentives should assume the strongest candidates are the most poachable, and that the award's real function is to buy time, not certainty.
Watch what a management team does with capital at the top of a cycle, not the bottom. Citizens' record contains both: a peak-cycle buyback in 2019 that immediately looked poor, and a trough-cycle deployment in 2023–2024 that looked good. Every management team narrates the second and omits the first. The full annual repurchase history in the 10-K is a two-minute check that cuts through a great deal of narrative.
Patient capital can incubate a franchise; only independence enforces discipline. RBS spent 27 years turning a Rhode Island thrift into a top-ten American bank — an enormous act of long-horizon capital allocation that no publicly traded American acquirer would have financed. It also produced a bank with dual brands, patchwork systems, and a risk appetite set 3,000 miles away. The separation was involuntary and, on the evidence, necessary. The corollary for investors is worth holding: a subsidiary's growth rate tells you about the parent's ambition, not the subsidiary's economics.
Which frames the question every reader of this story eventually has to answer.
XI. Analysis: Bull vs. Bear Case
The bull case
Start with the strongest version, made honestly.
Citizens is a bank whose earnings power is being repriced upward by a mechanical, largely rate-independent tailwind. Low-coupon assets originated in the zero-rate era are rolling off and being replaced at current yields, which alone accounts for roughly two points of the ROTCE bridge. That is not a forecast about Federal Reserve policy; it is an amortization schedule. Add a genuine second-quarter inflection — earnings per share of $1.30, up 41% year over year, net income of $587 million, up 35%, and a 247-basis-point sequential improvement in efficiency — and the trajectory is unambiguous.2
The Private Bank is the growth engine, and it is not speculative. It is profitable, it is running at approximately 25% return on equity, it contributes about 11.5% of pretax income, and its deposit-gathering has exceeded the original plan by a wide margin. It gives Citizens exposure to affluent household formation, venture and private-equity relationships, and fee-based wealth revenue — a genuinely better business mix than the consumer lending it is partially replacing.
The regional deposit franchise is real and measurable, not narrative: roughly 36.7% of Rhode Island's deposits and the number-two position in New England and Pittsburgh. That is durable low-cost funding.
Commercial Banking's fee engine is compounding, with record capital markets quarters driven by an advisory platform that Citizens assembled cheaply through JMP, DH Capital and Matrix. Credit is improving, not deteriorating. Capital is above the internal target's neighborhood with an improved stress-test profile behind it. And the company has spent four years refusing to overpay for bank acquisitions in a market where multiples have been rising — a restraint that costs nothing if organic returns converge.
The bear case
Now the strongest version against.
The transformation is a promise, not a result. Twelve years after independence, Citizens still earns the second-lowest return on tangible common equity among its closest super-regional peers, and the leaders are five to six points ahead. Management's own target would, if hit exactly, move the company to the bottom of the middle of the pack — against peers who have set higher targets of their own. Eighteen months remain on a clock management set for itself. A thesis that requires a specific number to land on a specific date, in a business with substantial macro sensitivity, is not a thesis with a wide margin of safety.
Succession is unresolved and has already cost something. A named internal candidate left for a rival CFO seat despite a $7 million retention grant. A second forfeited her award on retirement. The remaining candidate now runs essentially everything, with no announced timeline for the handoff and a 69-year-old incumbent who says he is in no rush. The 2025 say-on-pay result — 59% support with both major proxy advisers recommending against — was directly caused by this issue.
The competitive position lacks structural power. Run the frameworks and Citizens comes back with no network effects, no process advantage, subscale economics relative to the largest peers, modest switching costs, and a locally-strong brand that does not travel. The one genuine strategic advantage — the private banking talent lift-out — is built on employees who can leave, has never been through a retention cycle, and depended on a dislocation nobody can schedule.
The commercial real estate book is still working through losses, with management's own implied cumulative loss estimate on general office near 20%, and the deleveraging schedule already slipping by a quarter.
Capital allocation has a mixed rather than exemplary record, and the largest single buyback year in company history was followed immediately by a 60% drawdown.
And the structural pressure on regional banking is intensifying, not easing: private credit taking middle-market loans, money-market funds taking deposits, fintechs unbundling the relationship, and money-center banks out-spending everyone on technology.
Net framing
This is a "prove it" situation, and the evidence genuinely does cut both ways — which is why the calibrated conclusions matter more than the pile of facts.
On the counter-positioning claim, the record supports a narrowed version: Citizens demonstrated once, convincingly, that talent acquisition can substitute for M&A, and built a profitable business from it — but the funding side scaled and the lending and wealth sides ran roughly a year behind schedule, requiring a formal guidance reduction along the way. On the management credibility claim, the record is genuinely split: dividend resilience through COVID and countercyclical 2023–2024 buybacks on the positive side; a failed retention program, a two-year say-on-pay revolt, and an undated succession on the negative. On the scale and moat claim, the record is the least kind: there is no evidence in twelve years of independent operation that Citizens has closed the structural profitability gap to its larger peers, and the current gap is the largest single fact in the story.
The bull case does not require Citizens to become Regions Financial. It requires the ROTCE line to keep converging, quarter after quarter, toward a number management has already published — and it requires the Private Bank's asset and fee scaling to close its remaining gap to the original plan rather than continue running behind it.
XII. Epilogue & Looking Forward
Eighteen months is not long to change how a market values a bank.
Between now and the end of 2027, four things need to become visible. The return on tangible common equity must keep converging on the 16–18% band rather than plateauing in the low-to-mid teens. The Private Bank's office build-out must proceed on a schedule the company states consistently from one quarter to the next. A named CEO succession timeline must appear. And the branch reconfiguration must start producing evidence — in household growth and deposit cost, not in press releases — that advisory-led locations gather deposits the supermarket branches never did.
There is also a larger question the industry will answer for Citizens whether or not it participates. Fifth Third has absorbed Comerica; PNC has bought its way into Colorado and Arizona. If a more permissive regulatory window produces another wave of super-regional consolidation, Citizens faces a choice it has deferred since 2022: stay a disciplined non-acquirer and try to out-execute organically, or use its currency while it has one. Both paths are defensible. Continuing to avoid the choice is the option that quietly gets worse over time, because the technology cost base of the largest banks keeps rising and the revenue base to spread it over keeps growing faster than Citizens'.
For a long-term investor, three metrics carry nearly all the signal in this story, and they should be tracked directly from each quarterly release rather than taken from any summary.
First, the quarterly return on tangible common equity. This is the company's own scorecard and the single number the entire equity case rests on. The relevant question each quarter is not the absolute level but the direction and the pace — whether the convergence toward the target band is continuing, stalling, or reversing.
Second, the efficiency ratio. It is the load-bearing assumption behind the ROTCE bridge and the honest test of whether Reimagine the Bank is a genuine cost-structure change or the eleventh numbered program in a decade-long series that left the ratio in the low sixties. Improvement here is what would distinguish a structural transformation from a rate-cycle windfall.
Third, the Private Bank's client assets and office count together. Deposits have already proven the concept; the unproven half is whether Citizens can scale the fee-generating and lending side on the timetable it publishes, and the office build-out is the cleanest physical proxy for that ambition. Reading the two side by side catches the failure mode the record has already shown once — a business that gathers deposits faster than it can monetize them.
Everything else in this story — the 1828 founding, the RBS decades, the forced IPO, the auction lost on a Sunday night in Florida — is context for whether those three lines move the right way over the next six quarters.
XIII. Recent News
July 23, 2026 — Second-quarter results. Citizens reported net income of $587 million and earnings per share of $1.30, up 41% year over year, with ROTCE of 13.9%, net interest margin of 3.17%, and an efficiency ratio of 61.1%. Capital markets fees set a record at $153 million. Private Bank deposits reached $17.8 billion, loans $9.7 billion and client assets $11.2 billion, contributing 15 cents to quarterly EPS. Management reaffirmed the 16–18% ROTCE target for the end of 2027.254
July 9, 2026 — Coughlin's mandate expanded. President Brendan Coughlin, 46, assumed oversight of all primary lines of business — consumer, private bank, wealth and commercial — plus enterprise marketing, data and analytics and the Reimagine the Bank technology program. Van Saun described him publicly as "the obvious candidate" to succeed him, without announcing a timeline.39
June 2026 — Stress test results. Citizens' implied stress capital buffer under the 2026 Dodd-Frank stress test fell to 2.5%, among the largest reductions of any participating bank, though official requirements remain governed by the earlier framework pending the Federal Reserve's methodology overhaul.4546
April 23, 2026 — Annual meeting. Say-on-pay support recovered to roughly 91% of votes cast after two years of depressed results. A shareholder proposal for a majority vote standard was defeated.43
February 17, 2026 — Matrix Capital Markets acquired. Citizens purchased substantially all the assets of the Richmond, Virginia advisory firm — approximately three dozen employees specializing in downstream energy, convenience retail, automotive aftermarket and outdoor recreation M&A — folding it into Citizens JMP Securities. Terms were funded with cash; the purchase price was not disclosed.26
January 21, 2026 — Full-year 2025 results. Citizens reported net income of $1.8 billion and EPS of $3.86, returned approximately 80% of earnings to shareholders, and declared a quarterly dividend of $0.46 per share. Private Bank deposits closed the year at $14.5 billion.33
October 2025 — CFO transition completed. Aunoy Banerjee, previously of Barclays, took over as chief financial officer following John Woods' August 2025 departure for State Street.4042
References
-
Citizens Financial Group Second Quarter 2026 Earnings Release (8-K Exhibit) — SEC EDGAR, 2026-07-23 ↩↩↩↩↩↩↩↩↩↩↩
-
How Citizens turned First Republic defeat into private banking victory — Euromoney ↩↩↩
-
Citizens Financial Group Second Quarter 2026 Earnings Presentation — SEC EDGAR, 2026-07-23 ↩↩↩↩↩↩↩↩↩↩
-
Citizens Financial (CFG) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-07-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Regions Reports Earnings of $549 Million and EPS of $0.64 in 2Q 2026 — Regions Financial, 2026-07-17 ↩↩
-
Fifth Third Bancorp Reports Second Quarter 2026 Earnings — Fifth Third Bancorp, 2026-07-17 ↩↩
-
Here's How Huntington Plans to Achieve Its 18-19% ROTCE Target by 2027 — The Globe and Mail ↩↩↩
-
KeyCorp Reports Second Quarter 2026 Net Income of $472 Million — KeyCorp Investor Relations, 2026-07-21 ↩↩↩↩
-
Citizens Financial Group, Inc. — Company History — International Directory of Company Histories ↩↩↩↩↩↩
-
Citizens Financial Group, Inc. Form 10-K for fiscal year 2014 — SEC EDGAR ↩
-
Royal Bank of Scotland in $10 billion buy — NBC News, 2004-05-04 ↩
-
Citizens Financial to buy Charter One for $10.5 billion — Deseret News, 2004-05-05 ↩↩
-
Citizens loses $929m as bad loans proliferate — The Boston Globe, 2009-02-26 ↩
-
RBS's Citizens Arm Raises $3 Billion in U.S. IPO Below Range — American Banker, 2014-09-24 ↩
-
Meet Bruce Van Saun, Chairman and Chief Executive Officer — Citizens Financial Group ↩↩↩
-
Citizens Financial Group Announces Pricing of Initial Public Offering — Citizens Financial Group, 2014-09-23 ↩
-
Citizens, a public company for 10 years, looks ahead to the future — American Banker ↩↩↩
-
Citizens Financial Group Form 10-K for fiscal year 2024 — Citizens Investor Relations ↩
-
Earnings call transcript: Citizens Financial Group beats Q1 2026 expectations — Investing.com, 2026-04-16 ↩↩↩↩↩↩↩↩↩
-
Citizens Financial Group, Inc. Form 10-Q for the quarter ended June 30, 2026 — SEC EDGAR, 2026-08-03 ↩↩↩↩↩↩↩↩↩
-
Citizens Financial Group, Inc. to Acquire Investors Bancorp, Inc. — Citizens Financial Group, 2021-07-28 ↩↩
-
Citizens Financial Group Closes Acquisition of HSBC East Coast Branches and National Online Deposit Business — Citizens Financial Group, 2022-02-22 ↩
-
Citizens Financial Group Completes Previously Announced Acquisition of JMP Group — Citizens Financial Group, 2021-11-15 ↩
-
Citizens Financial Group Expands M&A Advisory Team with DH Capital Acquisition — BusinessWire, 2021-12-15 ↩
-
Citizens Financial Group Adds to Advisory Capabilities with Acquisition of Matrix Capital Markets Group — Citizens Financial Group, 2026-02-17 ↩↩
-
Fifth Third completes merger with Comerica, becomes 9th largest bank — The Detroit News, 2026-02-02 ↩↩
-
PNC Announces Agreement to Acquire FirstBank, Significantly Growing its Presence in Colorado and Arizona — The PNC Financial Services Group, 2025-09-08 ↩
-
Citizens Names Susan deTray as Head of Citizens Private Bank — Citizens Financial Group, 2023-07-24 ↩
-
Citizens Redefines Private Banking Sector With Launch of Citizens Private Bank — Citizens Financial Group, 2023-10-19 ↩
-
Armed with a team from First Republic, Citizens Bank unveils new private bank aimed at startups and the venture community — TechCrunch, 2023-09-14 ↩
-
Citizens' New Private Bank Targets $10 Billion in Assets by 2025 — BNN Bloomberg, 2024-01-18 ↩
-
Citizens Financial Group Reports Fourth Quarter and Full Year 2025 Results — Citizens Financial Group, 2026-01-21 ↩↩↩↩
-
Citizens reports fast progress in building its private bank — American Banker ↩
-
Citizens Financial Group Second Quarter 2026 Financial Supplement — SEC EDGAR, 2026-07-23 ↩
-
KeyCorp Q2 2026 slides: earnings beat, guidance raised on loan growth — Investing.com, 2026-07-21 ↩
-
FDIC market-share report shows changes among top R.I. banks — Providence Business News ↩
-
Citizens to close about 100 in-store branches for 50 retooled ones — Banking Dive ↩
-
Citizens' latest move further positions Coughlin as next CEO — American Banker, 2026-07-09 ↩↩↩↩↩
-
Citizens Financial Group, Inc. 2026 Definitive Proxy Statement (DEF 14A) — SEC EDGAR, 2026-03-09 ↩↩↩↩↩↩↩↩
-
Citizens Financial Group, Inc. 2025 Definitive Proxy Statement (DEF 14A) — SEC EDGAR, 2025-03-07 ↩↩↩↩
-
Citizens CFO departs for State Street; succession implications — Banking Dive ↩↩↩
-
Citizens Financial Group, Inc. Form 8-K reporting 2026 Annual Meeting voting results — SEC EDGAR, 2026-04-23 ↩↩↩↩
-
Citizens Financial Group, Inc. Form 10-K for fiscal year 2025 — SEC EDGAR ↩↩↩
-
Large Bank Capital Requirements, June 2026 — Board of Governors of the Federal Reserve System, 2026-06-24 ↩↩
-
Federal Reserve Board finalizes hypothetical scenarios for its annual stress test and votes to maintain the current stress test-related capital requirements until public feedback can be considered — Federal Reserve, 2026-02-04 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube