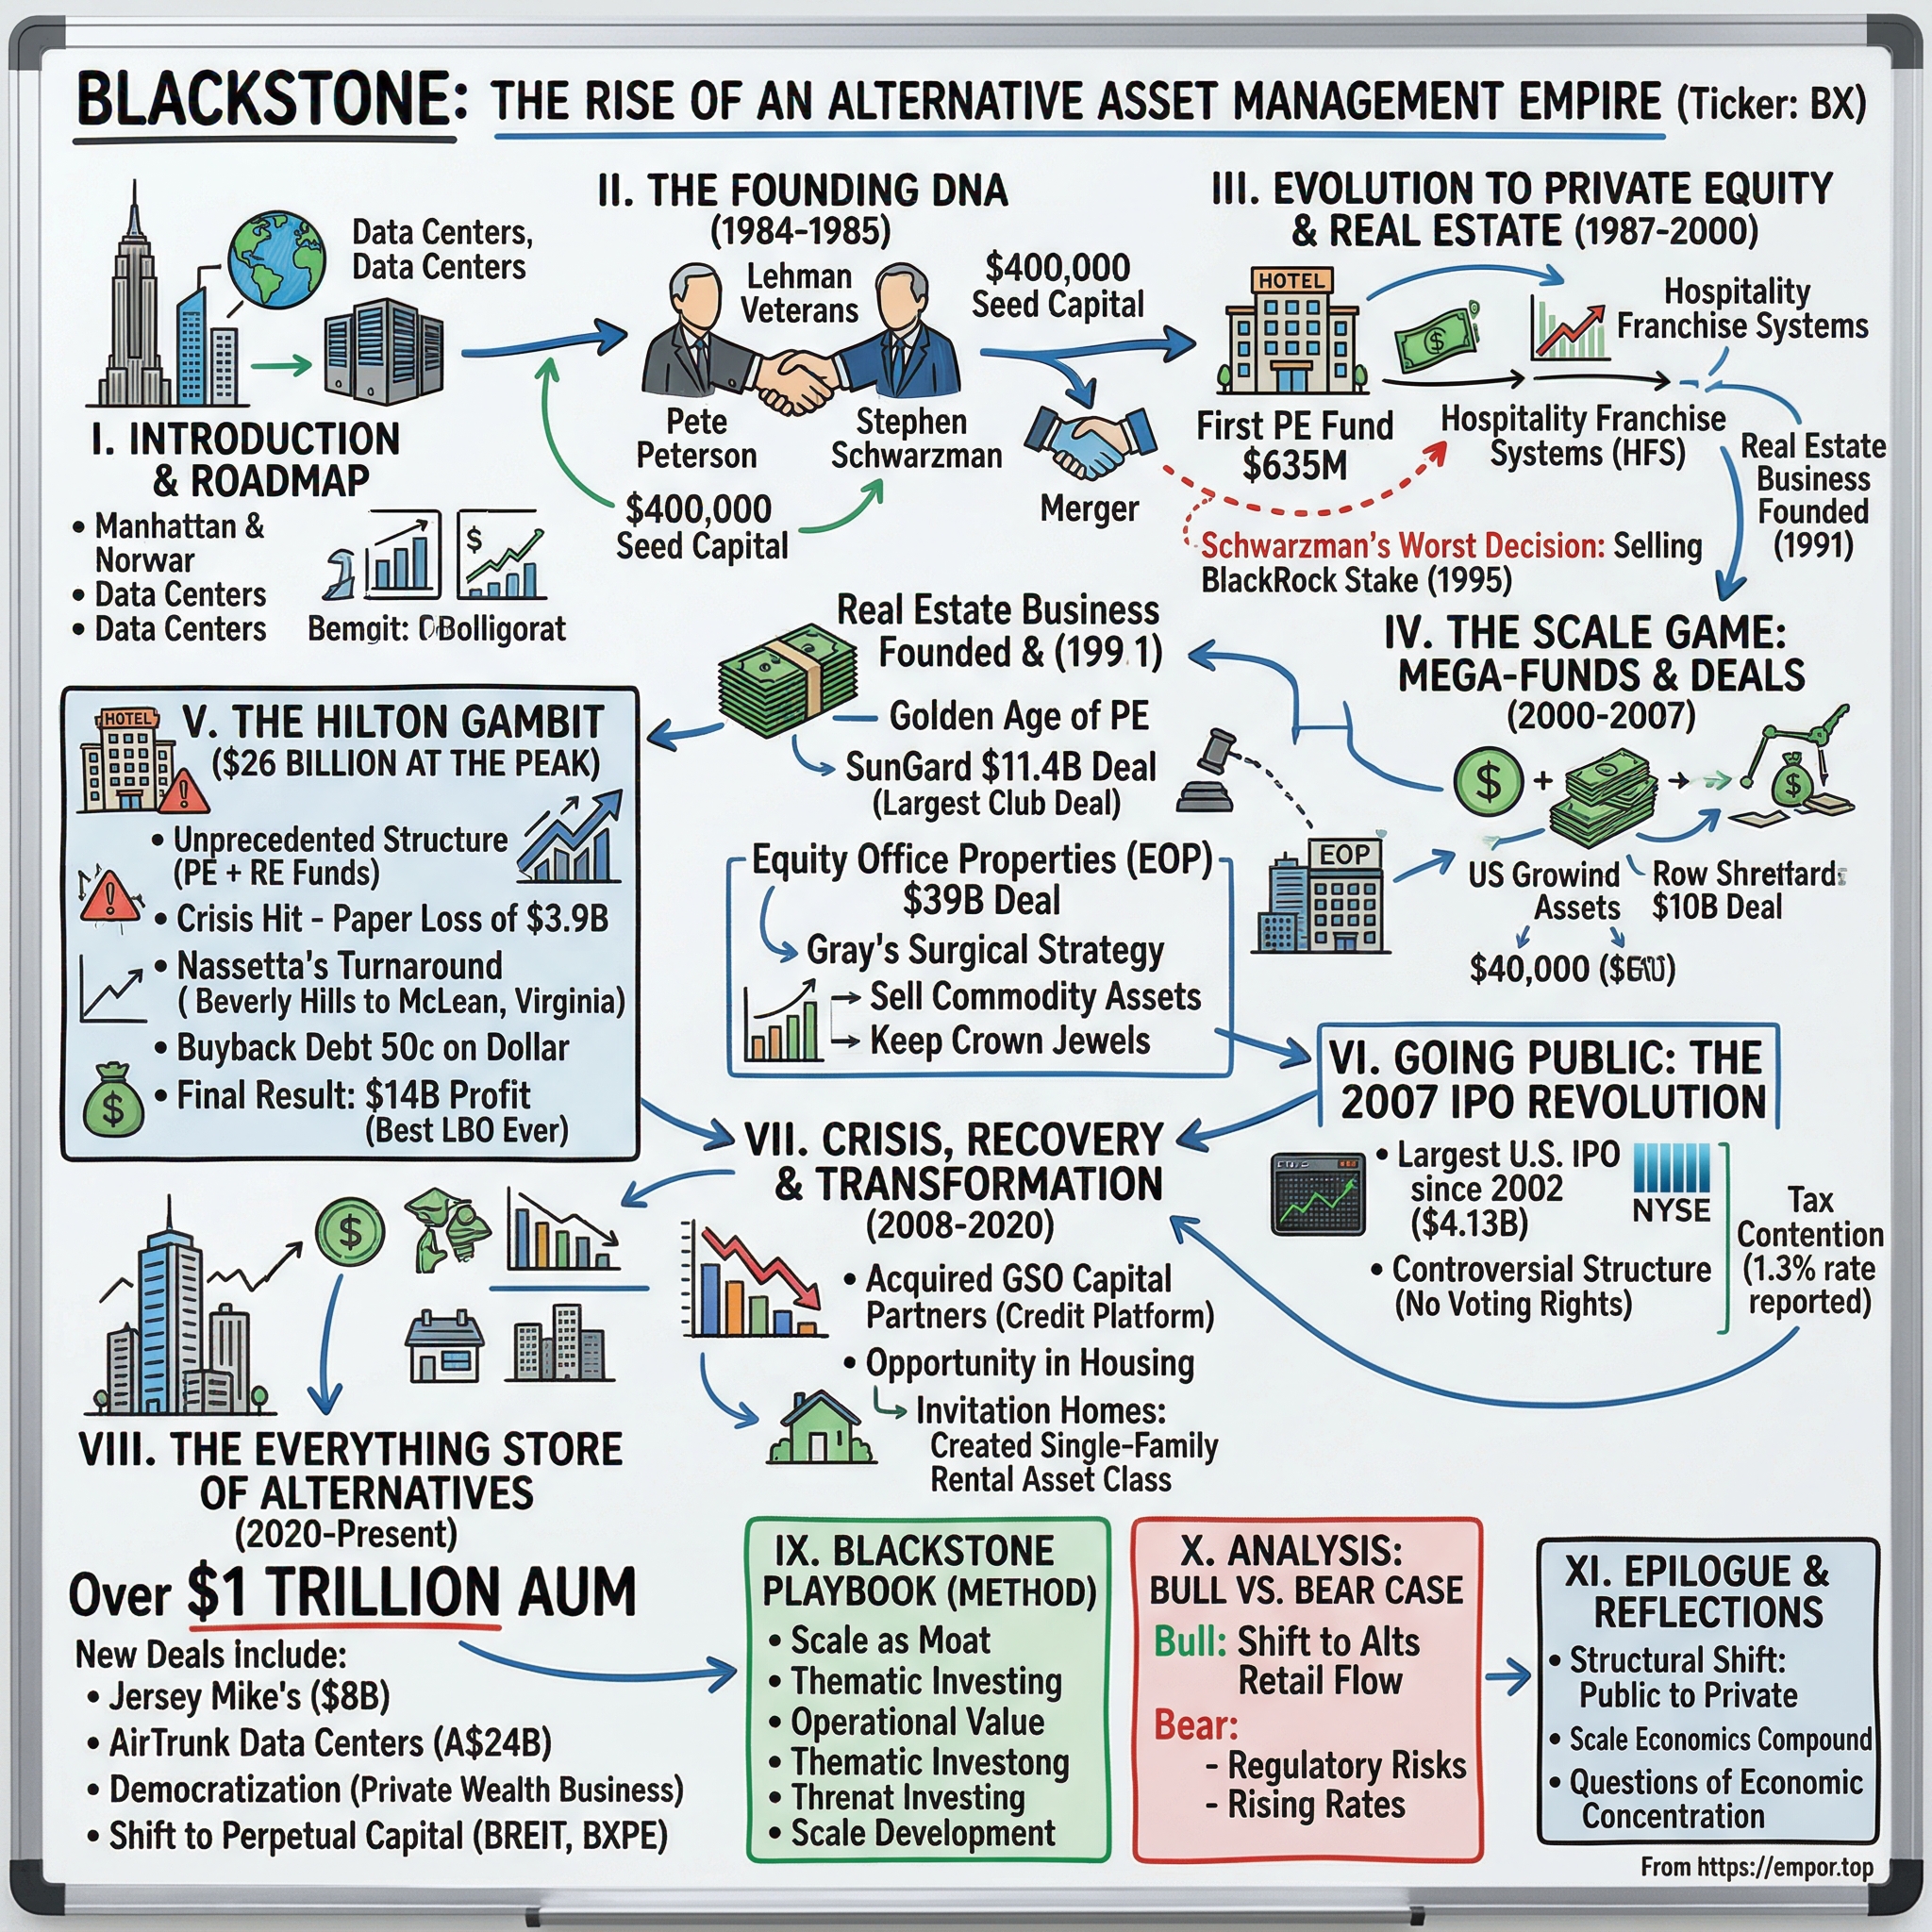
Blackstone: The Rise of Alternative Asset Management's Trillion-Dollar Empire
I. Introduction & Episode Roadmap
On the morning of July 23, 2026, Stephen Schwarzman opened Blackstone's second-quarter investor call with a statement that highlighted the firm's evolving identity: the firm had brought in roughly $70 billion of fresh capital in ninety days and had become "a trusted partner at scale to many of the key innovators" building artificial intelligence.1 A private equity firm — a category created to acquire industrial conglomerates with borrowed money — was positioning itself as primary infrastructure for a tech buildout.
Yet public markets reflected a different sentiment. That same day, Blackstone's stock traded near $122, roughly 36% below its 52-week high of $190.2
That gap between management's operational narrative and equity market valuations defines the central tension at the firm. By the end of June 2026, Blackstone managed $1.346 trillion in total assets, with $961.6 billion in fee-earning assets under management, $555.6 billion in perpetual capital, and $228.1 billion in uninvested dry powder.1 Quarterly financial performance showed the scale of the fee engine: fee-related earnings reached $1.78 billion, distributable earnings totaled $2.0 billion, and net accrued performance revenues — the balance sheet store of unrealized performance fees — stood at $7.5 billion.1 By raw scale, it represents the largest alternative asset management platform in financial history.
Inside those same disclosures, however, key growth metrics pointed to underlying friction. Base management fees — the recurring revenue intended to provide cycle-resistant stability — grew only about 4% year over year.1 In June 2026, Blackstone capped redemptions at BCRED, its flagship private credit fund for individual investors, after withdrawal requests reached 10% of shares outstanding against a 5% quarterly cap.3 Meanwhile, real estate assets under management — the segment that established Jon Gray's track record and path to the presidency — shrank 3% year over year.2
The central thesis under examination. Blackstone contends that it has converted a deal-by-deal buyout firm into a durable financial institution anchored by permanent capital, retail and insurance distribution channels, and thematic investments in data centers and digital infrastructure. The counter-question is whether an asset manager of this scale can sustain the returns required to justify its fee structure — and whether "perpetual capital" remains truly perpetual when retail investors request their money back during periods of market stress.
How the story unfolds. The narrative traces the firm's origin from two Lehman Brothers alumni starting with $400,000 in capital. It examines how a fee-for-service advisory firm shifted into asset ownership, expanding its portfolio to leverage operational data across investments. The account covers the early divestiture that formed BlackRock, the real estate strategy that built market dominance, the $39 billion Equity Office Properties buyout, and the $26 billion Hilton acquisition that tested the firm's balance sheet through the 2008 financial crisis. It details the 2007 initial public offering launched at the peak of the credit cycle, the buildout of private credit following post-crisis bank regulation, and the modern corporate architecture: four reporting segments, three investor channels, and extensive capital deployment into artificial intelligence infrastructure.
Along the way, each core thesis is evaluated against historical performance — matching prior management commitments against subsequent operational outcomes across economic cycles.
A framing note before proceeding. Public commentary on Blackstone often splits into two opposing views. One treats alternative asset managers as levered plays on asset prices deserving low valuation multiples. The other assumes Blackstone has eliminated cyclicality through perpetual capital. Disclosures in Blackstone's financial filings support neither extreme. They show a business that has structurally reduced its dependence on asset sales while remaining subject to broader market conditions — experiencing, in 2026, liquidity pressure in retail-focused credit products.
 Subscribe on LinkedIn
II. The Founding DNA: Peterson, Schwarzman & Lehman's Legacy
The origin story began with an executive departure. By 1984, Lehman Brothers was consuming itself from within. Pete Peterson — former U.S. Secretary of Commerce under President Richard Nixon and then chairman of Lehman — had been pushed out following a conflict with the firm's trading division. Stephen Schwarzman, then in his late thirties and running Lehman's mergers and acquisitions practice, watched the firm unravel and decided to build a new institution rather than fight for control of the old one.
The two founders brought contrasting backgrounds. Peterson was a Greek-American son of Nebraska diner owners and a well-connected Washington operator with ties to chief executives and cabinet secretaries. Schwarzman was a Yale and Harvard Business School graduate from suburban Philadelphia, driven, socially ambitious, and — by his own account — exceptionally averse to losing money. What they shared was an insight about 1980s Wall Street that few competitors had capitalized on: the corporate relationships that generated one-off advisory fees could also attract investment capital, and investment capital compounds in ways advisory fees cannot.
That distinction drove the economic shift of the private equity industry. An advisory firm earns a fee once when a transaction closes, resetting its revenue line to zero. A fund manager earns an annual management fee on committed capital, plus a share of profits when assets are sold. While corporate advisory is transactional, asset management provides recurring revenue alongside capital appreciation. Peterson and Schwarzman were not the first to recognize this model — Kohlberg Kravis Roberts had operated under a similar structure since 1976 — but they recognized the strategic sequencing required to build it without initial capital or a track record.
In 1985, they opened Blackstone with roughly $400,000 of their own money and a name combining their surnames — schwarz, German for black, and petros, Greek for stone. Financial advisory work was, in Blackstone's own later description, "an important business of our firm from the day we were founded."4 That sequencing was deliberate: advisory revenue covered operating expenses while the founders spent two years seeking institutional capital for a first-time fund.
The initial fundraising effort faced widespread rejection. Peterson and Schwarzman pitched hundreds of prospective limited partners, most of whom declined to commit capital to a team without an established fund track record. Schwarzman described the period as the most demoralizing of his professional life. The breakthrough came when Prudential committed $100 million, signaling institutional credibility to other investors. General Electric, Metropolitan Life, Nikko Securities, and the General Motors pension fund joined. In October 1987 — days before the stock market crash — Blackstone closed its first corporate private equity fund. The firm dates its private equity business to that year, and by the time it filed to go public two decades later, those funds had compounded at a 30.8% gross and 22.8% net annualized internal rate of return since inception.4
In practical terms, a net annualized return in the low twenties over two decades meant that limited partners roughly doubled their invested capital every three and a half years. The eight-percentage-point spread between gross and net returns represented the total fee load — comprising an annual management fee on committed capital and a 20% performance fee above a return hurdle. That spread represents the central economic tension of alternative asset management: it generates the firm's revenue while standing as the primary cost borne by investors. This dynamic shaped Blackstone's risk management philosophy. Schwarzman instituted an investment committee process focused heavily on downside protection, prioritizing the evaluation of potential loss scenarios over optimistic gain projections. This emphasis on risk avoidance helped prevent major capital losses, though it also led to missed opportunities.
Testing the claim: does Blackstone possess unmatched capital-allocation foresight?
Historical evidence, however, presents notable counterevidence.
In 1987, Blackstone entered a 50-50 partnership with the founders of what became BlackRock, backing Larry Fink and his team to build a fixed-income asset management business inside the firm.4 The business expanded rapidly, and by the early 1990s the unit was outgrowing the equity allocation Schwarzman had provided. When Fink requested additional equity to recruit and retain key talent, Schwarzman declined to dilute the existing partners. In 1994, Blackstone sold its interest.4 The buyer was PNC, and the price was approximately $240 million.
BlackRock subsequently grew into the world's largest asset manager, managing tens of trillions of dollars with a market capitalization orders of magnitude above what Blackstone received. Schwarzman later acknowledged the misstep, calling the decision a "heroic" mistake in a 2013 interview.5
The strategic lesson extends beyond typical management miscalculation. Blackstone's error was structural rather than analytical: the firm correctly identified the fixed-income opportunity and backed the right team, but lost the platform because its partnership equity structure could not accommodate a business growing faster than the core firm. This governance dynamic remains relevant today as Blackstone operates a federation of platforms — including credit, infrastructure, secondaries, and life sciences — led by executives who require competitive equity incentives. The episode demonstrates that while Blackstone has shown strong capability in identifying adjacent growth opportunities, its strategic execution has not been immune to structural limitations.
III. The Real Estate Epiphany & Early Playbook (1991–2000)
Consider American commercial real estate in 1991. The savings and loan crisis had forced the collapse of hundreds of thrifts. The Resolution Trust Corporation was liquidating the wreckage, selling office buildings, apartment complexes, and land at prices far below replacement cost. Institutional capital had fled, rendering commercial real estate uninvestable in the eyes of traditional market participants.
Blackstone hired John Schreiber, a Chicago real estate veteran, to build a business into that market vacuum. The firm launched its real estate opportunity funds in 1991, generating strong returns over the next fifteen years: a 38.2% gross and 29.2% net annualized internal rate of return from inception through the end of 2006.4 The real estate business outpaced Blackstone's corporate private equity platform by roughly six percentage points of net IRR per year, compounded, over that fifteen-year period.
The strategy relied on a straightforward playbook: acquire physical assets below replacement cost to establish a margin of safety, improve property operations, and sell into a market recovery. Blackstone avoided relying on optimistic long-term rental projections, acquiring assets at discounts deep enough to withstand adverse demand conditions.
Replacement cost served as real estate's primary structural protection. If an office building could be acquired for $80 per square foot while new construction cost $200 per square foot, developers would not construct competing supply until market rents rose sufficiently to justify the higher cost. Investors were protected by supply constraints rather than optimistic demand assumptions. Acquiring assets below the cost of new competition became a core principle in Blackstone's successful real estate funds—and its absence signaled risk in less successful investments.
In 1992, Jonathan Gray, a 22-year-old University of Pennsylvania graduate with degrees from Wharton and the College of Arts and Sciences, joined Blackstone as a junior analyst in the real estate group. While real estate was initially a small unit within the firm, Gray helped build the division into Blackstone's primary engine of growth and profitability. Within ten years he was leading the real estate business; within twenty he was directing its largest transactions; and by 2018 he became the firm's president and chief operating officer.
Another early operational lesson emerged from hospitality. Blackstone backed the consolidation of hotel franchising brands—including Ramada, Howard Johnson, Days Inn, and Super 8—under Henry Silverman's Hospitality Franchise Systems. The investment model separated brand licensing and recurring fee streams from physical real estate ownership and mortgage debt. The franchise business was capital-light and scalable, whereas property ownership was capital-intensive and leveraged. Blackstone applied this structural distinction fifteen years later on a far larger scale with Hilton.
Throughout the 1990s, the firm also operated a conventional mid-market buyout strategy focused on industrial manufacturing, packaging, and consumer services. That portfolio eventually highlighted the limitations of relying primarily on financial engineering.
Testing the claim: does financial engineering deliver reliable returns across cycles?
The classic leveraged buyout thesis posited that a disciplined manager could generate high-teens returns in any market environment by buying at modest valuations and paying down debt. Blackstone's late-1990s portfolio challenged that assumption. AMF Bowling, a bowling-center consolidation, served as a prime example: an industrial-style roll-up burdened with heavy debt in a sector whose revenues proved far more cyclical and secularly challenged than financial models anticipated. The investment resulted in severe equity impairment. The takeaway for management was clear: leverage amplifies an investment thesis, but it cannot create one. A weak business bought at a low valuation remains a weak business.
The setback prompted a strategic pivot away from generalist mid-market buyouts toward large-scale, thematic investments in sectors backed by long-term secular growth. This thematic approach became central to Blackstone's overarching investment model, shaped directly by the underperformance of its late-1990s buyout portfolio.
Institutional investors recognized the firm's strategic transition. In 1998, AIG acquired a 7% limited partnership interest in Blackstone for $150 million and separately committed roughly $1.2 billion to Blackstone funds over subsequent years.6 The capital commitments signaled that a major insurance balance sheet viewed Blackstone's returns as repeatable across market cycles. Two decades later, institutional insurance capital would become one of the firm's three core growth pillars.
By 2000, Blackstone had assembled its core foundational elements: a real estate division generating the firm's highest returns, a private equity platform focused on thematic sector trends, and an institutional investor base capable of committing substantial capital. While the firm had not yet acquired the scale to execute mega-buyouts, the structural framework for major expansion was established.
IV. The Mega-LBO Golden Era & The Hilton Masterstroke (2000–2007)
By 2006, credit markets were exceptionally loose. Collateralized loan obligations absorbed leveraged loans at a pace that made debt availability less of a constraint on transaction size, leaving deal scale limited primarily by a sponsor's willingness to commit capital.
This market expansion had been building for several years, highlighted by the 2005 acquisition of SunGard Data Systems. Seven private equity firms — Silver Lake, Bain Capital, Blackstone, Goldman Sachs Capital Partners, KKR, Providence Equity, and Texas Pacific Group — joined forces to take the financial software and services company private for $11.3 billion in August 2005.7 At the time, it was the largest technology buyout ever attempted and the second-largest leveraged buyout of a public company in history, behind only KKR's acquisition of RJR Nabisco.8
The club deal structure required for SunGard illustrated a key industry dynamic: in 2005, no single sponsor could write a check of that size alone. Within two years, however, Blackstone was executing transactions triple that size using a single fund. That rapid evolution from consortium-dependent deals to single-sponsor mega-buyouts demonstrated how dramatically credit supply had expanded.
During this same period, Blackstone was also taking profits. The firm had acquired Extended Stay America and sold the extended-stay hotel chain in 2007 for $8 billion to The Lightstone Group, exiting near the top of the hospitality cycle.9 That sale provides critical context, showing that Blackstone's real estate team was not uniformly bullish in 2007. They were divesting hotel properties while simultaneously acquiring office towers and a global hotel brand — a portfolio posture representing asset-specific decisions rather than a uniform macro market call.
The era's signature transaction began with an approach to Sam Zell, whose Equity Office Properties was the largest office owner in the United States, with more than 500 properties covering over 100 million square feet across major markets. Jonathan Gray pursued the portfolio, as did competitor Vornado. The resulting bidding war pushed Blackstone's final purchase price to roughly $39 billion including debt, closing in February 2007 as the largest leveraged buyout completed to that date — several billion dollars higher than Blackstone had originally intended.10
Rather than holding the entire portfolio at that elevated valuation, Gray immediately began dismantling it. Blackstone sold roughly $27 billion in buildings by the end of 2007 to buyers willing to pay high prices for individual assets.10 By rapidly shedding properties, the firm substantially reduced its equity capital at risk before commercial real estate markets broke. Investor estimates later placed Blackstone's net gain at approximately $7.5 billion on about $3.2 billion of invested equity.10
This outcome reflected risk structuring rather than macro market forecasting. Blackstone designed the transaction so that an overpayment at entry or a decline in office market fundamentals would not prove fatal — applying the downside-focused risk discipline established at the firm's founding, executed at unprecedented scale. Although Blackstone experienced the winner's curse by paying more than planned, its rapid asset-sale strategy turned a potentially vulnerable position into a successful exit.
The $26 billion hotel deal that should have destroyed the firm
Then came Hilton, where transaction sequencing proved critical. In July 2007, Blackstone agreed to acquire Hilton Hotels Corporation for approximately $26 billion including debt, paying $47.50 per share — a substantial premium. The deal was funded with roughly $6.5 billion in equity from Blackstone's real estate and private equity funds and more than $20 billion in debt syndicated across a lender consortium.11 The transaction closed on October 24, 2007.12
By the time the deal closed, credit markets were already tightening. Bear Stearns, a lead underwriter on the transaction, collapsed the following spring, and global travel demand fell sharply. Hilton's cash flows dropped, forcing Blackstone to write down its equity investment by roughly 71% — making Hilton one of the most widely cited examples of top-of-market overpayment during the 2008–2009 financial crisis.
Over the next six years, Blackstone executed an operational turnaround structured around four key decisions.
First, management restructuring. Blackstone appointed Christopher Nassetta as chief executive, bringing in an experienced hotel operator to overhaul commercial operations and brand strategy.
Second, balance-sheet restructuring. Capitalizing on its dual presence in equity and credit markets, Blackstone repurchased Hilton's debt at steep discounts during the financial crisis and negotiated with lenders to reduce principal balances and extend debt maturities. Buying portfolio debt below face value converted an immediate liquidity threat into manageable long-term obligations.
Third, business-model transformation. Hilton shifted away from real estate ownership toward a capital-light model focused on franchising and brand management contracts. This approach allowed Hilton to expand its global room count significantly using third-party capital while collecting recurring fee revenue — applying the franchise strategy Blackstone had used in the 1990s to a global hotel platform.
Fourth, holding period patience. Blackstone avoided a premature exit during the initial market recovery. Hilton returned to public markets in December 2013 in one of the year's largest initial public offerings, after which Blackstone gradually sold down its position over nearly five years.13 By the time it exited its remaining shares in May 2018, Blackstone had realized approximately $14 billion in profit over an eleven-year hold — making it the most profitable private equity transaction in history.14
The Hilton investment presents two contrasting interpretations. From an operational perspective, Blackstone showed that active management, balance-sheet restructuring, and long-term capital can rescue an asset acquired at a market peak. From an investment-timing perspective, the initial purchase price represented a severe entry error. An eleven-year hold to generate a three-times equity return yields an annualized rate of return below the headline figures of Blackstone's top-performing funds. The broader lesson is that Blackstone's strength lay in post-acquisition execution and operational restructuring rather than market timing.
At the same time the Hilton acquisition was being finalized in mid-2007, Blackstone was preparing a structural transformation that would reshape its corporate model: taking the asset manager itself public.
V. Going Public: The 2007 IPO Revolution & Governance Evolution
On June 21, 2007, The Blackstone Group L.P. listed on the New York Stock Exchange under the ticker BX at $31 per share, raising over $4 billion and valuing the asset manager in the tens of billions.4 The founders executed what Wall Street partnerships had resisted for a century: selling the management company itself, converting a private fee income stream into a permanent, publicly traded security. Days before the listing, China Investment Corporation — Beijing's newly established sovereign wealth fund — acquired a roughly $3 billion non-voting stake at a discount to the IPO price.
In hindsight, the timing marked the peak of the leveraged credit cycle. Schwarzman realized several hundred million dollars personally, hosting a sixtieth birthday celebration that became a public symbol of the market era's financial excess, before watching the stock embark on a multi-year decline that reshaped the firm's strategic planning.
The primary strategic logic of going public extended beyond capital raised. A firm capable of securing $20 billion in institutional fund commitments did not require $4 billion from retail equity markets. Instead, public equity provided acquisition currency to buy competing asset managers, liquid equity compensation to retain senior talent, and an established market valuation for estate planning. Listing also imposed structural discipline — quarterly disclosures, equity analyst coverage, and audited segment reporting — that accelerated the firm's institutionalization. Those structural advantages were real, even if their strategic benefits materialized a decade later than envisioned.
Testing the claim: does a public listing confer a valuation premium?
The central premise of the public listing was that equity markets would supply permanent capital, currency for expansion, and a valuation multiple reflecting Blackstone's institution. In practice, corporate structure initially undermined that narrative.
Blackstone's shares dropped from $31 at the IPO to under $4 by March 2009 — an 88% decline that exceeded the drawdowns of major investment banks. While macro financial panic drove part of the contraction, structural mechanics prolonged the valuation penalty. As a publicly traded partnership, Blackstone distributed annual K-1 tax forms rather than standard 1099s. This administrative structure excluded the stock from major stock indices, prevented institutional mutual funds from holding the shares, and created tax complexity for retail investors. The primary buyer base for large-cap financial equities remained structurally locked out.
Additionally, public markets valued Blackstone's earnings model like a hedge fund rather than an annuity. Investors applied low valuation multiples to performance revenues, viewing carried interest as volatile and unpredictable while discounting the stability of base management fees.
Blackstone spent twelve years addressing this structural discount. On July 1, 2019, the firm converted from a publicly traded partnership into a traditional C-corporation, accepting a higher corporate tax liability to eliminate K-1 tax reporting and qualify for index inclusion.15 Industry peers followed. Management made a calculated trade-off: predicting that multiple expansion from a broader investor base would exceed the permanent drag of corporate income taxes. The strategy achieved a major milestone in September 2023, when S&P Dow Jones Indices added Blackstone to the S&P 500, making it the first alternative asset manager in the index.16
The corporate conversion demonstrated a firm electing to pay permanent corporate taxes to resolve distribution limitations. While management's judgment that multiple expansion would outweigh tax costs proved effective in broadening institutional ownership, index inclusion did not eliminate share price volatility. Passive fund flows operate in both directions, and Blackstone's 2026 valuation decline of roughly 25% over twelve months occurred entirely within its S&P 500 tenure.2
The broader strategic outcome was that the decade following the IPO forced Blackstone to recognize that public markets reward earning predictability. The firm's subsequent operational strategy — building perpetual capital vehicles, prioritizing fee-related earnings as its primary financial metric, and emphasizing predictable recurring fees over volatile performance carry — emerged directly from its public equity valuation challenges. That structural pivot took shape during the global financial crisis.
VI. Crisis Turnaround, Credit Expansion & Perpetual Capital Pivot (2008–2020)
In 2008, while Blackstone's own public equity was declining sharply, the firm acquired credit manager GSO Capital Partners. Founded by leveraged finance veterans Bennett Goodman, Tripp Smith, and Doug Ostrover, GSO was acquired for up to approximately $930 million, a transaction announced in late 2007 when the firm managed roughly $21 billion in assets.17
The strategic rationale unfolded alongside regulatory shifts following the financial crisis. Regulations under Dodd-Frank and Basel III increased capital requirements for commercial banks, making middle-market corporate lending and leveraged loans more expensive for traditional balance sheets to hold. As banks pulled back, direct lending created an opening for non-bank institutional capital. GSO formed the foundation of what became Blackstone Credit & Insurance. By the end of 2025, the firm's credit platform across corporate and real estate strategies managed roughly $520 billion in assets, representing 15% year-over-year growth behind more than $140 billion in single-year capital inflows.18
Blackstone executed a second contrarian post-crisis expansion beginning in 2012, deploying roughly $10 billion to purchase tens of thousands of foreclosed single-family homes across Phoenix, Atlanta, Florida, and the American Southwest. Capital deployment reached over $100 million per week as the firm established centralized property management, leasing, and maintenance operations across geographically fragmented residential housing. Industry skeptics argued that single-family rental homes could not be operated at institutional scale. Blackstone addressed that operational challenge and took Invitation Homes public in February 2017, raising approximately $1.54 billion in the largest U.S. real estate investment trust initial public offering on record at the time.19
Both transactions highlighted a consistent operational approach: acquiring structurally disfavored assets during market dislocations and consolidating them under institutional operating platforms. This capability became a primary engine of Blackstone's post-crisis asset expansion.
However, the strategy also generated long-term reputational and political scrutiny. By acquiring residential housing at scale, Blackstone became a prominent symbol of institutional ownership in single-family housing, drawing criticism from local communities and policymakers. Although Blackstone fully exited Invitation Homes through the IPO and subsequent equity sales, the strategy established a recurring pattern of scrutiny whenever the firm invested in consumer-facing assets like housing, healthcare facilities, and student accommodation. For institutional investors, this political exposure introduces tangible regulatory risks, including potential rent caps and local ownership restrictions.
The insurance channel developed into a core growth pillar over the following decade. Rather than acquiring balance-sheet insurance liabilities directly—the strategy adopted by competitor Apollo Global Management through Athene—Blackstone established an open-architecture model managing investment portfolios for third-party insurers under long-term mandates. By the end of 2025, insurance assets under management reached $271 billion, an 18% year-over-year increase. During that year, Blackstone reported originating or placing $50 billion of credit for investment-grade insurance clients, generating approximately 180 basis points of excess spread above comparably rated liquid corporate bonds.18 The firm also completed the sale of its 6% equity stake in Resolution Life alongside that entity's acquisition by Nippon Life, while expanding its distribution partnership with the Japanese insurer.1820
This asset-light insurance model presents distinct structural trade-offs. By managing capital without underwriting insurance liabilities, Blackstone generates fee revenue while avoiding balance-sheet risk and capital requirements. However, because Blackstone does not own the underlying insurance entities, third-party capital remains subject to contract terms rather than direct corporate control. While an owned insurance subsidiary provides captive capital, third-party management mandates remain contestable if investment performance or market conditions deteriorate during a credit downturn.
The people who run it
Stephen Schwarzman remains Chairman and Chief Executive Officer as well as Blackstone's largest individual shareholder, holding an equity stake in the high-teen percentages. Over time, his leadership role has focused increasingly on high-level relationship management with sovereign wealth funds, global institutional allocators, and heads of state. During quarterly earnings calls, Schwarzman maintains an executive advocacy role; on the July 2026 call, he told investors that Blackstone stock was "on sale."20 Public remarks of that nature reflect chief executive advocacy rather than objective equity analysis.
Jonathan Gray directs day-to-day operations. Appointed President and Chief Operating Officer in February 2018 as part of an explicit corporate succession framework, Gray spent his early career building the real estate division he joined at age 22.21 His operational approach relies heavily on granular property and credit metrics, including leasing velocity, construction starts, vacancy rates, and portfolio EBITDA growth. As the primary architect of Blackstone's expansion into perpetual capital, Gray's core strategic initiatives now define the firm's operational trajectory.
Senior executive compensation combines fee-related earnings metrics with carried interest, supplemented by personal co-investment alongside fund investors. While co-investment aligns manager and investor incentives, fee-related earnings targets and performance carry can create competing operational priorities. Fee-related earnings reward asset accumulation, whereas carried interest depends on realized investment gains—an incentive split that creates structural tension during periods when disciplined capital deployment requires slowing fund growth.
This structural tension underscores a central governance question in alternative asset management: because asset managers calculate the internal net asset values that determine both fee revenues and retail redemption pricing, independent valuation integrity remains critical. Blackstone discloses its use of third-party appraisals and internal valuation frameworks across its perpetual capital vehicles. However, process disclosures differ from market-tested price discovery, making realized asset sales the definitive measurement of portfolio carrying values.
The pivot to perpetual capital
From an asset manager's perspective, traditional drawdown funds present a structural limitation: they have a finite lifespan. A ten-year closed-end fund requires the manager to liquidate assets, distribute capital to limited partners, and repeatedly launch new fundraising cycles. Perpetual vehicles address this structural churn by operating as open-ended funds that accept ongoing subscriptions and hold investments indefinitely.
By June 2026, Blackstone's perpetual capital reached $555.6 billion, representing a 15% year-over-year increase. Fee-earning perpetual capital accounted for $463.0 billion of that total—comprising 48% of the firm's overall fee-earning asset base.1 Consequently, nearly half of Blackstone's fee engine operates through funds without scheduled termination dates.
This structural transition altered Blackstone's earnings profile by securing long-term management fee streams. However, it also introduced a distinct liquidity risk: while perpetual vehicles lack scheduled fund maturity dates, they remain exposed to investor withdrawal requests during market downturns.
VII. The Modern Machine: Segment Breakdown & Financial Mechanics (2020–Present)
Blackstone operates not as a single integrated asset manager, but across four distinct business segments supported by a global distribution network. For investors, evaluating the firm requires analyzing the contrasting growth profiles and fee structures across these operating divisions.
Credit & Insurance (BXCI) represents the firm's largest segment by assets, reaching $469.3 billion as of June 30, 2026, up 15% year over year. The division encompasses direct middle-market lending, asset-based finance, infrastructure credit, and separately managed accounts for institutional insurers.2 The segment attracted $31.0 billion of capital inflows in the second quarter of 2026 alone, including $7.5 billion for insurance separate accounts.1 The unit's economic structure relies primarily on management fees tied to committed or invested capital, generating modest performance revenues. Total insurance assets under management expanded 15% to roughly $290 billion, a scale President Jonathan Gray emphasized was achieved without assuming underlying balance-sheet insurance liabilities—maintaining an operational model distinct from Apollo's owned-annuity structure.20
Private Equity managed $454.2 billion, up 17% year over year, offering the greatest operating leverage to a recovery in transaction volume.2 The segment extends beyond traditional corporate buyouts to include secondaries through Strategic Partners, infrastructure, life sciences, growth equity, tactical opportunities, and the individual-investor vehicle BXPE. Over the twelve months ending June 30, 2026, corporate private equity funds appreciated 14.4%, while infrastructure assets gained 28.6%.1
Real Estate, at $314.1 billion in assets, remains in a period of operational adjustment.2 Segment assets under management contracted 3% year over year. Over the trailing twelve months, opportunistic real estate funds depreciated 1.4%, while Core+ strategies appreciated 3.2%.1 Management and advisory fees for the division were roughly flat in the second quarter and declined slightly year-to-date, illustrating how fee growth moderates when underlying property values stabilize or contract.1
Multi-Asset Investing (BXMA), formerly hedge fund solutions, expanded 21% to $108.6 billion in assets. Over the trailing twelve months, the segment generated a 15.5% gross and 14.1% net return, outperforming the 9.7% return of the HFRX Global Hedge Fund Index.1 Historically a smaller component of the firm, the division has outpaced real estate in asset growth while contributing increasingly to year-end performance fee crystallizations.
How the money actually works
Understanding Blackstone's valuation requires distinguishing between two primary earnings metrics disclosed in its financial reporting.
Fee-Related Earnings (FRE) measures core operational profitability, combining base management fees and recurring fee-related performance revenues minus operating compensation and administrative expenses. Because FRE excludes volatile exit-dependent incentive fees, it serves as the firm's primary indicator of recurring, subscription-like earnings. For the second quarter of 2026, Blackstone generated $1.78 billion in FRE on fee-related revenues of approximately $3.04 billion—representing a 59% margin—and accumulated $6.3 billion in FRE over the trailing twelve months.1
Distributable Earnings (DE) expands on FRE by incorporating realized performance allocations and realized investment income—the net profit shares harvested when portfolio assets are sold. DE reached $2.0 billion for the quarter and $7.9 billion over the trailing twelve months. Blackstone distributes the substantial majority of DE to shareholders, declaring a dividend of $1.29 per share for the quarter and $5.23 per share over the trailing year.1
The distinction between the two metrics reflects different aspects of the business: FRE indicates structural platform scale, while DE tracks exit market conditions across economic cycles. Period-over-period expansion in FRE alongside contracting DE indicates ongoing asset accumulation during a constrained realization environment, whereas DE growth exceeding FRE suggests the firm is harvesting prior investments faster than it is building new management fee streams.
The dynamic operates much like a property manager who collects recurring rental payments while periodically selling real estate assets. Rental revenue mirrors FRE—predictable, recurring, and providing stable cash flows to support corporate operations. Asset sale profits mirror the realized performance revenues within DE—larger, lumpier, and dependent on transaction timing. A manager with expanding rental revenues can sustain earnings during periods of low property sales, whereas a manager relying primarily on asset sales to offset flat rental income is harvesting legacy investments rather than compounding core operational revenues. This structural difference explains why Blackstone spent fifteen years encouraging public equity markets to value the firm on FRE multiples rather than total distributable cash flow.
A third, increasingly influential revenue stream stems from Blackstone's internal capital markets group, which earns transaction and advisory fees by structuring and syndicating debt for internal portfolio acquisitions and third-party transactions. Management highlighted significant growth from this group in its 2026 financial outlook, supported by a near-doubling of transaction fees in the second quarter.181 While this unit allows Blackstone to monetize its internal transaction volume, transaction and advisory fees operate as investment banking revenue, which fluctuates with deal activity rather than compounding as a recurring annuity stream.
Two specialized platforms within these segments have expanded faster than their parent divisions. Strategic Partners, the firm's secondaries platform that purchases existing limited partner stakes, has expanded during the industry-wide exit slowdown as institutional investors seek liquidity in secondary markets rather than waiting for fund distributions. Blackstone secured $5.7 billion for secondary strategies in the second quarter of 2026 alone.1 Similarly, the infrastructure platform, established in 2019, has grown to approximately $90 billion while compounding at a net return of roughly 18% since inception.120 Both expansions reflect a recurring strategic pattern seen in Blackstone's entry into real estate in 1991 and credit in 2008: entering emerging asset channels before competitors institutionalize similar offerings.
This expansion highlights the underlying composition of Blackstone's recent FRE performance. Of the 22% year-over-year FRE increase reported in the June 2026 quarter, base management fees—the most recurring income source—accounted for only about four percentage points of that growth.1 Overall earnings acceleration was driven instead by transaction and advisory fees, which nearly doubled to $321 million, and fee-related performance revenues, which climbed 68% to $793 million.1 Although both items generate immediate cash earnings, neither acts as a fixed annuity: transaction fees track market activity, while fee-related performance fees require perpetual vehicles to maintain investment returns above benchmark hurdle rates.
During the July 2026 investor call, Evercore analyst Glenn Schorr questioned Chief Financial Officer Michael Chae regarding how the firm planned to accelerate base management fee growth from mid-single digits back to double-digit rates. Chae outlined several catalyst drivers: full-year fee recognition from newly activated private equity drawdown funds, broader seasoning of perpetual capital vehicles as BXPE's net asset value doubled year over year to roughly $25 billion, continued net inflows into BXMA, and the deployment of $84 billion in uninvested credit capital—nearly double 2024 deployment levels.20 Based on those factors, management projected a return to double-digit base fee growth by 2027.20
That forward projection establishes a measurable benchmark for Blackstone's operational execution. Whether the firm meets its 2027 growth target will demonstrate whether its expanding perpetual capital and private credit platforms can reaccelerate core fee growth without relying on cyclical surges in deal fees and performance revenues.
VIII. The Hidden/Future Growth Engine: Wealth Democratization & Infrastructure/AI Energy
The firm's long-term expansion strategy relies heavily on two primary growth drivers: individual wealth democratization and digital infrastructure powered by rising demand for electricity.
The wealth channel
The core economic premise driving alternative asset management into retail markets rests on asset allocation parity. Global individual wealth totals tens of trillions of dollars, yet individual investors have historically allocated low single-digit percentages to private markets, compared with 25% or more among major institutional endowments and pension funds. Rebalancing retail portfolios even partially toward institutional allocation levels represents a multi-trillion-dollar capital flow.
Blackstone established an early market lead by creating a dedicated global distribution team focused on major U.S. wirehouses and international private banks. To capture retail flows, the firm designed specialized semi-liquid vehicles for investors who cannot lock up capital for ten-year fund cycles: Blackstone Real Estate Income Trust (BREIT), Blackstone Private Credit Fund (BCRED), Blackstone Private Equity Strategies (BXPE), and Blackstone Infrastructure Strategies (BXINFRA).
The structural design of these vehicles bridges the gap between institutional asset management and retail wealth management. Traditional private equity funds operate on capital calls, long lockups, and lagged quarterly reporting, which fit poorly into individual retirement accounts. Blackstone's semi-liquid structures accept monthly subscriptions, publish monthly net asset values, pay monthly distributions, and offer quarterly redemptions capped at specific portfolio thresholds. While the fund wrapper offers periodic liquidity, the underlying loans, properties, and buyouts remain fundamentally illiquid—creating structural tension when withdrawal demands rise. Despite those liquidity constraints, private wealth assets under management reached $324 billion by June 2026, up 16% year over year, supported by $43 billion raised through the channel in 2025 alone, representing a 53% annual increase.2018 On the January 2026 earnings call, Stephen Schwarzman cited third-party research estimating that Blackstone generates roughly half of all private wealth revenue across major alternative asset managers.18
Regulatory policy has also shifted toward broader access. An August 2025 executive order directed the Department of Labor and the Securities and Exchange Commission to lower administrative barriers to introducing alternative investments into 401(k) retirement accounts. In March 2026, the Department of Labor issued a proposed rule establishing process-based safe harbors for retirement plan fiduciaries, requiring them to evaluate investment performance, fee structures, liquidity, valuation mechanisms, and structural complexity.[^22] If defined-contribution plans adopt alternative allocations at scale, Blackstone's addressable retail market could nearly double.
The firm is simultaneously moving beyond traditional qualified-purchaser wealth thresholds. During the July 2026 investor call, Jonathan Gray outlined distribution partnerships with Wellington Management and Vanguard aimed at reaching mass-affluent retail investors.20 This initiative broadens Blackstone's distribution footprint, though expanding into retail channels exposes the firm to redemption patterns driven by investors with less historical experience navigating illiquid private assets during market downturns.
Platform growth has been anchored by documented fund returns across key product lines. As of June 2026, BXPE had generated an annualized net return of approximately 19% since its 2024 inception, expanding to $25.3 billion in assets; BXINFRA had delivered an annualized net return of about 15% since launching in 2025; and BCRED had compounded at roughly 9% annually since 2021, primarily through current income distributions.1 Disclosed performance metrics reflect audited regulatory filings. However, because reported returns in perpetual vehicles rely significantly on internal valuations of unlisted portfolio holdings, the ultimate test remains whether carrying values are fully realized when assets undergo public market sales or refinancing.
The AI infrastructure bet
Blackstone's digital infrastructure expansion originated as a conventional real estate transaction. In 2021, the firm acquired data center operator QTS Realty Trust for approximately $10 billion in a joint transaction between Blackstone Infrastructure Partners and BREIT.22 The acquisition initially targeted standard enterprise data center real estate, but the subsequent rapid adoption of generative artificial intelligence and transformer model architectures dramatically altered sector demand.
By January 2026, Jonathan Gray identified QTS as the single largest contributor to investment performance across both the infrastructure and real estate divisions.18 By July 2026, Blackstone valued its total data center platform at approximately $185 billion—up from $130 billion at the beginning of the year—supported by roughly 15 gigawatts of entitled power capacity globally and an estimated $200 billion future development pipeline.20 That global presence expanded further through the 2024 acquisition of Asia-Pacific operator AirTrunk for approximately 24 billion Australian dollars.23
The firm subsequently expanded its position from physical property owner to active infrastructure counterparty. In May 2026, Blackstone partnered with Google to establish a U.S. joint venture providing integrated data center capacity, facility management, fiber networking, and compute-as-a-service utilizing Google Cloud Tensor Processing Units. Blackstone committed $5 billion in initial equity, aiming to deploy 500 megawatts of capacity by 2027.24 Concurrently, Blackstone teamed with Apollo Global Management to provide financing for a roughly $35 billion computing infrastructure expansion for Anthropic utilizing Broadcom custom silicon.25
To institutionalize retail access to the sector, Blackstone launched a dedicated public vehicle in May 2026. Blackstone Digital Infrastructure Trust (BXDC) raised approximately $1.75 billion in an initial public offering at $20 per share on the New York Stock Exchange, focusing on stabilized data center properties leased to investment-grade hyperscale technology companies.26 The vehicle contributed $2.0 billion in capital inflows to the real estate segment during the second quarter of 2026.1
This structural transition introduces distinct risk characteristics. Leasing physical building shells to hyperscale tech firms under 15-year contracts functions similarly to corporate credit secured by real estate. Providing compute-as-a-service, by contrast, exposes the manager to technological obsolescence, capacity utilization rates, and hardware pricing pressure across rapid depreciation cycles. During the July 2026 earnings call, Morgan Stanley analyst Michael Cyprys questioned whether compute services could maintain infrastructure-like investment characteristics, while Citizens analyst Devin Ryan asked whether return targets on new data center developments could match historical performance given higher asset entry prices and rising competition.20
Gray responded by highlighting supply-side barriers, arguing that grid power availability, semiconductor supply chains, and municipal site entitlements create structural bottlenecks that prevent rapid market overbuilding.20 While supply constraints have supported platform valuations to date, management's position relies on the premise that specialized infrastructure barriers will insulate the sector from traditional real estate oversupply cycles. As with Blackstone's perpetual wealth products, gains in digital infrastructure have been recognized primarily through asset revaluations rather than completed sales, leaving final performance realization dependent on future asset sales and debt refinancing cycles.
IX. Historical Falsification Pass: Testing Blackstone's Core Thesis Claims
Three core claims underpin Blackstone's valuation and strategic narrative. Evaluating the firm requires testing each assertion against its actual operational record.
Testing a firm of this scale against hypothetical scenarios—such as interest rate spikes or default surges—constitutes market forecasting rather than factual analysis. A more rigorous evaluation examines whether Blackstone has previously asserted these core thesis claims and how subsequent events unfolded across its operational history.
Claim 1: Perpetual retail capital is permanent, non-runnable capital
This claim is contradicted by historical evidence. Blackstone's record contains two distinct liquidity events where perpetual retail capital proved subject to withdrawal pressure.
The first occurred in November 2022. As the Federal Reserve raised interest rates at the fastest pace in four decades and international wealth clients faced liquidity pressures, redemption requests for Blackstone Real Estate Income Trust (BREIT) exceeded the vehicle's monthly limit of 2% and quarterly cap of 5%, forcing the firm to prorate withdrawals.27 The redemption gates remained active for over a year. To maintain liquidity, Blackstone sold major properties—including its interests in the MGM Grand and Mandalay Bay resorts—and in January 2023 secured a $4 billion commitment from the University of California's investment office under specialized terms: a guaranteed minimum 11.25% annualized net return backed by $1 billion of Blackstone's own equity as collateral.28
That collateral arrangement is telling. If perpetual retail capital were inherently stable, an asset manager would not need to pledge firm equity to guarantee returns for an anchor investor during a redemption cycle. The stabilizing measures functioned as intended: BREIT generated an 8.1% net return for its primary share class in 2025—roughly triple the performance of the public REIT index—and recorded positive net inflows in 2025 for the first time since September 2022.1829 As of June 2026, BREIT's assets under management stood at $56.6 billion, representing a 9% annualized net return since its 2017 inception.1 Nevertheless, the vehicle contracted significantly from its 2022 peak, demonstrating that operational stability was achieved by reducing overall fund scale.
A second liquidity event occurred in 2026, challenging assertions that retail capital structures had eliminated withdrawal risk. Throughout the first half of 2026, Blackstone Private Credit Fund (BCRED)—the firm's flagship private credit vehicle for individual investors—experienced rising redemption requests. In the first quarter, withdrawal demands reached 7.9% of outstanding shares. Blackstone fulfilled all requests by expanding the repurchase allocation and deploying approximately $400 million in corporate and employee capital. By the second quarter, redemption requests rose to 10.0% of shares outstanding, prompting Blackstone to enforce its 5% quarterly cap and prorate withdrawals, gating the fund for the first time in its history after closing the window on June 7, 2026.330
These two gating episodes—occurring four years apart across distinct asset classes in Blackstone's largest retail vehicles—demonstrate a structural feature of semi-liquid product design: illiquid underlying assets financed by investors holding quarterly withdrawal rights. Redemption caps function as engineered safety mechanisms to prevent forced asset fire sales, but they do not make the underlying capital permanent. Furthermore, management's decision to deploy corporate capital to fulfill first-quarter withdrawals underscores the significant reputational sensitivity surrounding fund gating.
The surviving premise is that perpetual vehicles provide sticky capital equipped with contractual friction that converts a rapid run into a controlled exit, requiring periodic asset sales or corporate balance-sheet support during market stress. That structural mechanism offers meaningful stability compared to daily-liquidity funds, but it does not constitute permanent capital.
Key metrics for ongoing verification: whether BCRED's redemption requests drop below the 5% quarterly cap without corporate capital support, and whether net capital flows across BREIT, BCRED, BXPE, and BXINFRA remain positive through sustained market volatility. During the July 2026 earnings call, President Jonathan Gray reported that redemption requests were "down materially" in early third-quarter trading and that June had marked BCRED's strongest sales month since inception, raising $1.2 billion.20 That statement reflects management's mid-year outlook; confirmation depends on official third- and fourth-quarter financial disclosures in 2026.
Claim 2: Blackstone's real estate underwriting is structurally superior
This claim holds only in a narrower form than marketing materials suggest, and a prominent counterexample in public commentary is factually misattributed.
First, the historical correction. The 2006 acquisition of Stuyvesant Town–Peter Cooper Village for $5.4 billion—which defaulted in 2010 in what was then the largest real estate default in U.S. history—was not executed by Blackstone. The transaction was led by Tishman Speyer in partnership with BlackRock, the entity Blackstone had divested in 1994.31 Blackstone entered the complex years later, acquiring the property for approximately $5.3 billion in 2015 alongside Ivanhoé Cambridge.32 Evaluating Blackstone's underwriting discipline requires focusing on transactions executed under its own management.
Blackstone's actual record contains clear evidence of cyclical vulnerability. In 2007, Blackstone acquired Extended Stay America and sold it for $8 billion to The Lightstone Group near the market peak. Under approximately $7 billion in debt, the hotel operator filed for Chapter 11 bankruptcy in June 2009. A consortium comprising Centerbridge, Paulson & Co., and Blackstone subsequently repurchased the company out of bankruptcy for nearly $4 billion in 2010.9 Although Blackstone generated profits on both the initial sale and subsequent re-acquisition, the deal structure demonstrated that capital frameworks underwritten by Blackstone at market peaks could prove unsustainable during sharp economic downturns.
Vulnerabilities also emerged in the commercial office sector following the pandemic. Shifted work patterns and elevated interest rates reduced U.S. office valuations, leading Blackstone to surrender deeds on select office properties backed by non-recourse debt rather than commit additional equity. To limit exposure, the firm reduced traditional office holdings to approximately 2% of its global real estate equity portfolio.33
A balanced assessment indicates that Blackstone's primary real estate advantage stems from sector selection and decisive capital rotation rather than flawless property-level underwriting. The firm systematically reduced office exposure while reallocating capital into logistics, residential housing, and data centers, which together represent approximately 75% of its global real estate equity holdings.18 While that sector allocation proved strategic, recent segment results highlight ongoing market pressure: opportunistic real estate funds depreciated 1.4% over the twelve months ending June 30, 2026, and Gray noted on the January 2026 earnings call that U.S. private real estate valuations remained roughly 16% below their peak at the start of the rate cycle four years earlier, compared with a 75% gain in the S&P 500.118 Gray acknowledged that while management believed the market bottom had passed two years prior, real estate value recovery "wouldn't be a straight line."18
Key metrics for ongoing verification: realized sale prices relative to carrying values on property dispositions, and the trajectory of real estate base management fee growth. Management projected near-term real estate base management fees to remain close to fourth-quarter 2025 levels, indicating that the firm's historically largest profit driver is experiencing a period of fee growth deceleration.18
Claim 3: Private credit underwriting is superior to bank lending
This claim remains unproven, with recent portfolio indicators showing emerging credit stress despite favorable long-term historical benchmarks.
The supporting historical evidence is substantial. Blackstone's non-investment-grade credit strategies have delivered net annual returns of approximately 10% over twenty years—roughly double the yield of the public leveraged loan market—while realized annual losses across its $160 billion-plus global direct lending portfolio averaged 11 basis points over the twelve months ending December 31, 2025.18
More recent disclosures, however, show increasing credit friction. BCRED's quarterly regulatory filings revealed fifteen corporate issuers across twenty-five loans on non-accrual status as of June 30, 2026, compared to nine issuers across sixteen loans at December 31, 2025—marking a notable increase in non-performing loans over six months.34 Furthermore, Blackstone's segment reporting showed private credit generating a 6.8% gross return and a 3.9% net return over the twelve months ending June 30, 2026, below BCRED's 9% annualized net return since its 2021 launch.1 Reflecting reduced net investment income, BCRED adjusted its investor payout distribution downward during 2026.
During the January 2026 earnings call, management emphasized that the core portfolio remained in "excellent shape," citing high single-digit EBITDA growth across direct lending borrowers.18 Broader portfolio health can coexist with stress in specific holdings, but recent disclosures indicate that operational discussions have expanded from maintaining zero default rates to managing non-accrual resolutions while preserving principal.
A central analytical question is whether private credit's historical performance reflects superior underwriting discipline or the absence of daily mark-to-market pricing. Unlike public bank loans that reprice continuously, private middle-market loans undergo periodic internal valuations audited against established accounting standards. While standard valuation practices are observed, quarterly appraisal models smooth reported volatility relative to public debt markets. Consequently, the true test of direct lending underwriting will depend on portfolio performance across a sustained corporate default cycle.
Key metrics for ongoing verification: the volume of non-accrual loans measured at cost and fair value in BCRED's quarterly filings, alongside realized loss rates across the direct lending portfolio.
An industry-wide factor further affects future credit returns. Direct lending expanded rapidly when commercial banks retreated and credit spreads were wide. As institutional capital flooded middle-market lending and traditional banks re-entered through manager partnerships, credit spreads compressed significantly. Gray noted that investment-grade corporate spreads reached their tightest levels since 1998.18 Narrower spreads reduce risk compensation at a time when private credit capital deployment is near record levels—creating potential return headwinds for recent fund vintages where credit stress manifests as realized principal losses rather than lower capital gains.
X. Competitive Landscape, Porter's 5 Forces & Helmer's 7 Powers
For most of the preceding decade, Blackstone operated with a scale advantage so pronounced that its leadership went largely unchallenged. The second quarter of 2026 marked a structural shift as rival asset managers closed the gap.
Apollo reported approximately $1.05 trillion in assets under management as of June 30, 2026, built on a distinct operational model: Athene, its owned annuity business, originates permanent insurance liabilities that Apollo invests primarily in investment-grade private credit.35 Brookfield crossed the $1 trillion mark during the same quarter following a record $77 billion fundraising period, operating an owner-operator platform concentrated in infrastructure, renewable power, and real assets.36 KKR reached roughly $796 billion in total assets including its insurance operations, supported by its established private equity business and an expanding balance sheet.37 Credit specialist Ares expanded its total assets by 17% to $671.3 billion, backed by record quarterly capital inflows of $36 billion.38
While Blackstone remains the market leader with $1.346 trillion in assets under management, its 11% year-over-year expansion lagged the growth rates of Ares at 17% and KKR at 16%, even as both Brookfield and Apollo joined Blackstone in the trillion-dollar club for the first time.2363738 Blackstone retains scale leadership, but its once-unassailable scale supremacy has yielded to an era of peer parity.
The 7 Powers, tested
Scale economies represent Blackstone's most formidable structural advantage. The firm maintains the capacity to commit equity checks of a magnitude that eliminates the need for co-investor syndication, converting execution speed and closing certainty into pricing leverage with sellers. Transactions such as the $18 billion take-private of Hologic and the acquisition of data center operator AirTrunk demonstrate a capital deployment capacity matched by few global peers. Scale also generates proprietary market intelligence: as Stephen Schwarzman noted on the January 2026 earnings call, managing a global portfolio spanning more than 270 companies and nearly 13,000 real estate assets provides granular operational data that allows the firm to discern macroeconomic trends ahead of public markets—an analytical capability that informed Blackstone's early thematic shifts into logistics and data infrastructure.18 The counterweight is that asset management scale eventually encounters diminishing marginal returns. Efficiently deploying $228.1 billion in uninvested dry powder while preserving historical hurdle rates presents far greater structural difficulty than deploying a fraction of that sum.
Cornered resource finds its strongest expression in Blackstone's institutionalized private wealth distribution infrastructure, backed by an estimated 50% share of private wealth revenues generated across major alternative asset managers.18 However, shelf space at major wealth management platforms represents an ongoing commercial relationship rather than an exclusive contractual monopoly. Competing asset managers are rapidly scaling parallel retail distribution networks, while Blackstone's recent partnerships with Vanguard and Wellington indicate that growth within traditional wirehouse channels may be approaching domestic saturation.
Brand functions as a tangible commercial asset. Blackstone consistently closes multi-billion-dollar flagship vehicles during tight liquidity cycles when competitors encounter fundraising headwinds, exemplified by its third Asia private equity fund closing at $13.1 billion—more than double the $6 billion raised by its predecessor.1 In institutional capital allocation, brand equity manifests as immediate access to sovereign wealth funds and shortened fundraising timelines. It also serves as a critical talent acquisition vehicle, enabling the firm to recruit senior executives and investment professionals from leading investment banks and peer asset managers.
Counter-positioning remains the single structural power Blackstone lacks. Counter-positioning requires a business model that incumbent competitors cannot replicate without impairing their existing profit streams. In alternative asset management, major peers regularly replicate successful product innovations: the launch of BREIT prompted parallel non-traded real estate investment trusts from competitors such as Starwood, the rollout of BCRED was followed by numerous non-traded business development companies, and retail wealth distribution is now actively contested across the industry. Blackstone's core advantages—scale, brand awareness, and distribution reach—represent relative operational edges rather than non-replicable structural moats.
Process power and network economies are largely absent from the platform. Alternative asset management exhibits no positive network effects; adding limited partners or expanding fund sizes does not enhance investment outcomes for existing investors. Rather, capital accumulation creates return drag, as larger pools of dry powder compete for a finite set of high-yielding investment targets and bid down asset yields. This structural dynamic explains why asset managers face return compression as assets under management expand, presenting a primary analytical hurdle to assigning sustained premium valuation multiples to public asset management equities.
Switching costs provide limited long-term protection, particularly within retail perpetual capital. While traditional ten-year drawdown funds enforce strict capital lockups, semi-liquid perpetual vehicles create administrative liquidity friction rather than permanent capital lock-in. As BCRED's 2026 redemption capping demonstrated, when retail investors face withdrawal limits during periods of market uncertainty, administrative friction prompts redemption queues rather than long-term capital retention.
A rigorous evaluation under the 7 Powers framework confirms that Blackstone commands two primary structural powers—scale economies and brand equity—alongside a contested distribution capability. The platform lacks the non-replicable structural moats that generate durable excess returns in high-barrier operating industries. This assessment is less a critique of Blackstone than a structural reality of asset management, emphasizing that the firm must be evaluated on operational execution and portfolio mix rather than on assumed competitive permanence.
Porter's five forces, briefly
Buyer power is expanding as major institutional allocators consolidate manager relationships and negotiate fee concessions, driving asset managers to seek retail channels to protect operating margins. Rivalry continues to intensify across all segments, particularly in private credit where aggressive capital deployment from Ares, Apollo, Golub Capital, HPS Investment Partners, and re-emerging commercial banks has compressed credit spreads. Substitutes present a growing headwind: with investment-grade corporate bond spreads reaching their tightest levels since 1998—a condition highlighted by Jonathan Gray—the relative yield premium for illiquid credit has narrowed, while public equity market gains of 75% over a four-year period contrast sharply with a 16% decline in private real estate values.18 Supplier power resides in key investment talent, a vulnerability demonstrated historically by the loss of the platform that became BlackRock when key executives sought greater equity participation. Barriers to entry remain formidable for multi-asset institutional platforms, even as entry barriers fall for specialized, niche credit managers.
From a corporate governance and valuation perspective, three central vulnerabilities warrant ongoing scrutiny. First is structural complexity: operating across four business segments and dozens of specialized fund vehicles creates inherent related-party dynamics. For example, data center operator QTS is jointly owned by BREIT and Blackstone Infrastructure Partners, while public vehicle BXDC purchases stabilized assets in a market where other Blackstone funds rank among the active developers.22 Although these arrangements are fully disclosed and common across alternative platforms, they place Blackstone-affiliated entities on both sides of asset valuation transactions. Second is valuation governance within perpetual capital vehicles, where internally calculated net asset values directly dictate redemption pricing for exiting retail investors and determine fee-related performance revenues for the manager. Third is key-person transition risk: while Jonathan Gray's executive succession as President and Chief Operating Officer has been clearly established, Stephen Schwarzman's eventual retirement will test whether institutional investor relationships and fundraising efficacy can be fully maintained across a leadership transition.
XI. Investor Stress Test & Bull vs. Bear Case
Why Blackstone wins from here
The strongest bull argument rests not on retail distribution alone, but on asset composition. Over the twelve months ending June 30, 2026, infrastructure holdings appreciated 28.6% while corporate private equity gained 14.4%, expanding the infrastructure platform roughly 40% to $90 billion.120 The firm's largest value driver, its data center platform, sits at the center of a major technology capital expenditure cycle. Blackstone enters this expansion with difficult-to-replicate advantages: entitled land with secured power capacity, established operating platforms in QTS and AirTrunk, and the balance-sheet scale to underwrite both equity and debt financing.
The second argument centers on the realization cycle. Blackstone holds $7.5 billion in net accrued performance revenues—unrealized profit shares earned in fund valuations but not yet collected.1 As public listing channels reopen, exemplified by the $7.2 billion Medline initial public offering in late 2025, that balance-sheet store converts to cash.18 Distributable earnings expanded 26% in the second quarter of 2026, reflecting this monetization trajectory.2
The third driver is regulatory. The Department of Labor's proposed safe harbor for alternative investments in retirement accounts opens a structural expansion in addressable capital, where Blackstone's early distribution footprint positions it to capture substantial initial flows.[^22]
A fourth, less recognized factor is the strategic value of uninvested capital. Holding $228 billion in dry powder during periods of credit tightening provides execution optionality during market dislocations—a capability demonstrated through post-2008 credit acquisitions, single-family residential investments in 2012, and deploying over $50 billion into real assets between 2023 and 2025 while competitors withdrew.18 Because many fund structures generate fees only when capital is deployed, accelerating investment pace serves directly as a primary catalyst for management's projected base fee reacceleration.
What breaks the case
Liquidity mismatch in wealth vehicles is now a demonstrated risk, not a theoretical one. Enforcing withdrawal limits twice within four years—most recently in BCRED, the flagship product management framed as its primary growth driver—exposes the structural tension of retail vehicles. A third gating event would risk lasting damage to advisor confidence. While deploying corporate capital to fulfill first-quarter 2026 redemptions preserved immediate advisor goodwill, it established an expensive precedent that cannot be scaled across a multi-hundred-billion-dollar platform.
The base fee deceleration is the number to watch. Base management fees grew approximately 4% year over year in the second quarter of 2026, with management projecting mid-single-digit growth in the third quarter before targeting a return to double-digit growth by 2027.120 Trailing 22% growth in fee-related earnings relies heavily on cyclical transaction fees and fee-related performance revenues. If base fee growth fails to reaccelerate by 2027, the thesis that Blackstone operates as a durable compounder rather than a market-sensitive asset manager becomes increasingly difficult to maintain.
Private credit is entering its first real test. A doubling of BCRED non-accrual issuers within six months, a reduced distribution payout, and narrowing spreads between gross and net returns serve as early indicators of portfolio friction.341 Direct lending at current scale has not been tested through a full corporate default cycle, nor have unlisted loan valuations faced mark-to-market pressure from forced asset sales.
Real estate recovery may lag management's projections. Management signaled a market bottom in early 2024, yet two years later, opportunistic funds depreciated 1.4% over twelve months while management guided segment management fees flat.118 Extended delays in property value recovery compound the operational drag on segment fee growth.
Tax and regulatory overhang persists. Legislative proposals to tax carried interest at ordinary income rates were reintroduced in April 2026 through the Ending the Carried Interest Loophole Act.39 While similar bills have stalled for two decades, broader political backing keeps tax reform a persistent headwind that would alter partner compensation and talent retention. Concurrently, public scrutiny from SEC leadership regarding private asset risks in 401(k) accounts underscores that retail expansion carries regulatory oversight alongside market opportunity.40
The public equity valuation reflects these operational headwinds. A 25% share price decline over twelve months to a $170 billion market capitalization indicates that public markets are pricing risks across base fee growth, credit cycles, and retail capital stability.2 While Stephen Schwarzman characterized the stock as "on sale," an alternative interpretation is that equity markets are adjusting for narrowing scale advantages and recent redemption limits in key retail products.20
A measured synthesis indicates that Blackstone maintains distinct structural advantages through its scale, established private wealth distribution network, and strategic asset positioning. However, reported earnings quality has grown more cyclical precisely as executive narrative emphasized platform durability, and its core retail innovation—semi-liquid perpetual capital—has twice demonstrated liquidity friction during periods of market stress.
XII. Epilogue & Key Investment KPIs
Four decades after its founding with $400,000 in seed capital, Blackstone's trajectory reflects a broader structural migration in high finance: credit formation shifting away from regulated, deposit-funded banks toward non-bank asset managers funded by yield-seeking investors. Blackstone did not initiate that shift, but by acquiring GSO during the 2008 financial crisis, the firm positioned itself as its primary beneficiary.
The critical question for the decade ahead is how this model performs during a major economic downturn, now that individual investors—rather than long-horizon institutional endowments—hold a substantial share of illiquid assets. The gating of BREIT in 2022 and BCRED in 2026 occurred during periods lacking a broad corporate default cycle, yet both instances required corporate balance-sheet support or specialized anchor capital to stabilize liquidity.
One interpretation holds that the semi-liquid framework is operating as intended: redemption caps prevent fire sales of illiquid holdings, protecting continuing investors during withdrawal surges, while fund performance has remained positive through gated periods. An alternative interpretation cautions that quarterly caps have succeeded because withdrawal demands have not yet tested prolonged macroeconomic stress, leaving the ultimate stability of retail perpetual capital unproven.
Evaluating which interpretation holds true depends on performance disclosures in upcoming financial filings. Three core metrics provide the clearest indication of Blackstone's operational trajectory:
1. Base management fee growth. Base management fees, disclosed quarterly in segment reporting, strip out transaction fees and volatile performance revenues to measure the growth of core recurring income. Management has projected a return to double-digit growth by 2027 from mid-single-digit levels in 2026, establishing a clear benchmark for platform durability.
2. Net flows in perpetual wealth vehicles, and the redemption ratio. While gross fundraising signals distribution reach, net flows across BREIT, BCRED, BXPE, and BXINFRA—alongside the proportion of redemption requests satisfied without prorating, corporate capital infusions, or anchor concessions—indicate whether perpetual capital remains stable under shifting market conditions.
3. Realized versus marked value. Disclosed exit prices relative to carrying values across real estate and private equity dispositions, combined with non-accrual resolution rates in private credit, demonstrate whether internal valuation marks align with public market transactions.
While total assets under management, dry powder, and sector deployment highlight platform scale, these three operational metrics will determine whether Blackstone can sustain its business model across evolving credit and market cycles.
References
-
Blackstone Reports Second Quarter 2026 Results — SEC EDGAR, Form 8-K Exhibit 99.1, 2026-07-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Blackstone Q2 2026 slides: $1.35T AUM, 26% earnings growth — Investing.com, 2026-07-23 ↩↩↩↩↩↩↩↩↩
-
Blackstone BCRED Joins Private Credit Funds Limiting Redemptions — Bloomberg, 2026-06-04 ↩↩
-
Blackstone Group L.P. Form S-1 IPO Registration Statement — SEC EDGAR, 2007-03-22 ↩↩↩↩↩↩
-
Schwarzman Says Selling BlackRock Was 'Heroic' Mistake — Bloomberg, 2013-09-30 ↩
-
AIG to Invest $1.35 Billion in The Blackstone Group and Its Funds — Blackstone, 1998 ↩
-
Consortium of Private Equity Firms Completes Acquisition of SunGard — Blackstone, 2005-08-11 ↩
-
Leveraged finance deal of the year: SunGard Data Systems $11.3 billion LBO — Euromoney ↩
-
Extended Stay Emerges From Chapter 11 After Buyout — CNBC, 2010-10-08 ↩↩
-
The $39B EOP Deal Should Have Killed Blackstone. Instead It Reaped A $7B Profit — Bisnow ↩↩↩
-
Blackstone to Buy Hilton Hotels for $26 Billion — The Wall Street Journal, 2007-07-04 ↩
-
Blackstone Completes $26 Billion Hilton Buyout — Reuters, 2007-10-24 ↩
-
Hilton IPO Marks End of Private Equity's Greatest Investment — Financial Times, 2013-12-12 ↩
-
Blackstone's overall profit from Hilton deal? A whopping $14B — The Real Deal, 2018-05-18 ↩
-
Blackstone Form 8-K C-Corporation Conversion Announcement — SEC EDGAR, 2019-07-01 ↩
-
Blackstone and Airbnb Set to Join S&P 500 — S&P Global, 2023-09-01 ↩
-
GSO Capital to Sell to Blackstone for Up to $930 Million — Reuters, 2007-11-15 ↩
-
Blackstone Fourth-Quarter and Full-Year 2025 Investor Call Transcript — Blackstone, 2026-01-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Invitation Homes goes public, raises $1.54 billion — HousingWire, 2017-02-01 ↩
-
Earnings call transcript: Blackstone tops Q2 2026 estimates on fees, AUM growth — Investing.com, 2026-07-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Blackstone Names Jon Gray as President, Setting Up Successor to Schwarzman — Bloomberg, 2018-02-13 ↩
-
QTS Realty Trust to Be Acquired by Blackstone Funds in $10 Billion Transaction — Blackstone, 2021-06-07 ↩↩
-
Blackstone Nears $16 Billion Deal for Data Center Operator AirTrunk — The Wall Street Journal, 2024-09-04 ↩
-
Blackstone to invest $5 billion in AI infrastructure venture with Google, powered by TPU chips — CNBC, 2026-05-19 ↩
-
Apollo, Blackstone back Anthropic's $35 billion capacity expansion in new Broadcom tie-up — Yahoo Finance, 2026 ↩
-
Blackstone launches IPO for data center REIT — The Real Deal, 2026-05-05 ↩
-
Blackstone Limits Redemptions From $71 Billion Real Estate Fund BREIT — Bloomberg, 2022-12-01 ↩
-
Blackstone Secures $4 Billion Investment from UC Investments for BREIT — Reuters, 2023-01-03 ↩
-
BREIT Raises $1B More Than Investors Redeem, Reversing 3-Year Outflow Trend — Bisnow ↩
-
Blackstone restricts flagship fund withdrawals as private asset fears reemerge — CNBC, 2026-06-04 ↩
-
Creditors Take Over $5.4B NYC Housing Complexes — NPR, 2010-01-25 ↩
-
Blackstone To Buy Stuy Town In $5.3 Billion Deal — Forbes, 2015-10-20 ↩
-
How Blackstone shrunk office holdings to 2 percent — The Real Deal, 2023-05-31 ↩
-
Blackstone Private Credit Fund Form 10-Q for the quarter ended June 30, 2026 — SEC EDGAR, 2026 ↩↩
-
Apollo Reports Second Quarter 2026 Results — Apollo Global Management, 2026-08 ↩
-
Brookfield Asset Management Announces Record Second Quarter Results — Brookfield Asset Management, 2026 ↩↩
-
KKR & Co. Inc. Reports Second Quarter 2026 Financial Results — SEC EDGAR, 2026-07-30 ↩↩
-
Ares Management Corporation Second Quarter 2026 Earnings Release — SEC EDGAR, Form 8-K Exhibit 99.2, 2026 ↩↩
-
Wyden, Whitehouse, King Lead Introduction of Bill Closing Carried Interest Tax Loophole — U.S. Senate Committee on Finance, 2026-04-16 ↩
-
The Diversification Deficit: Opening 401(k)s to Private Markets — U.S. Securities and Exchange Commission, 2025-11-20 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube