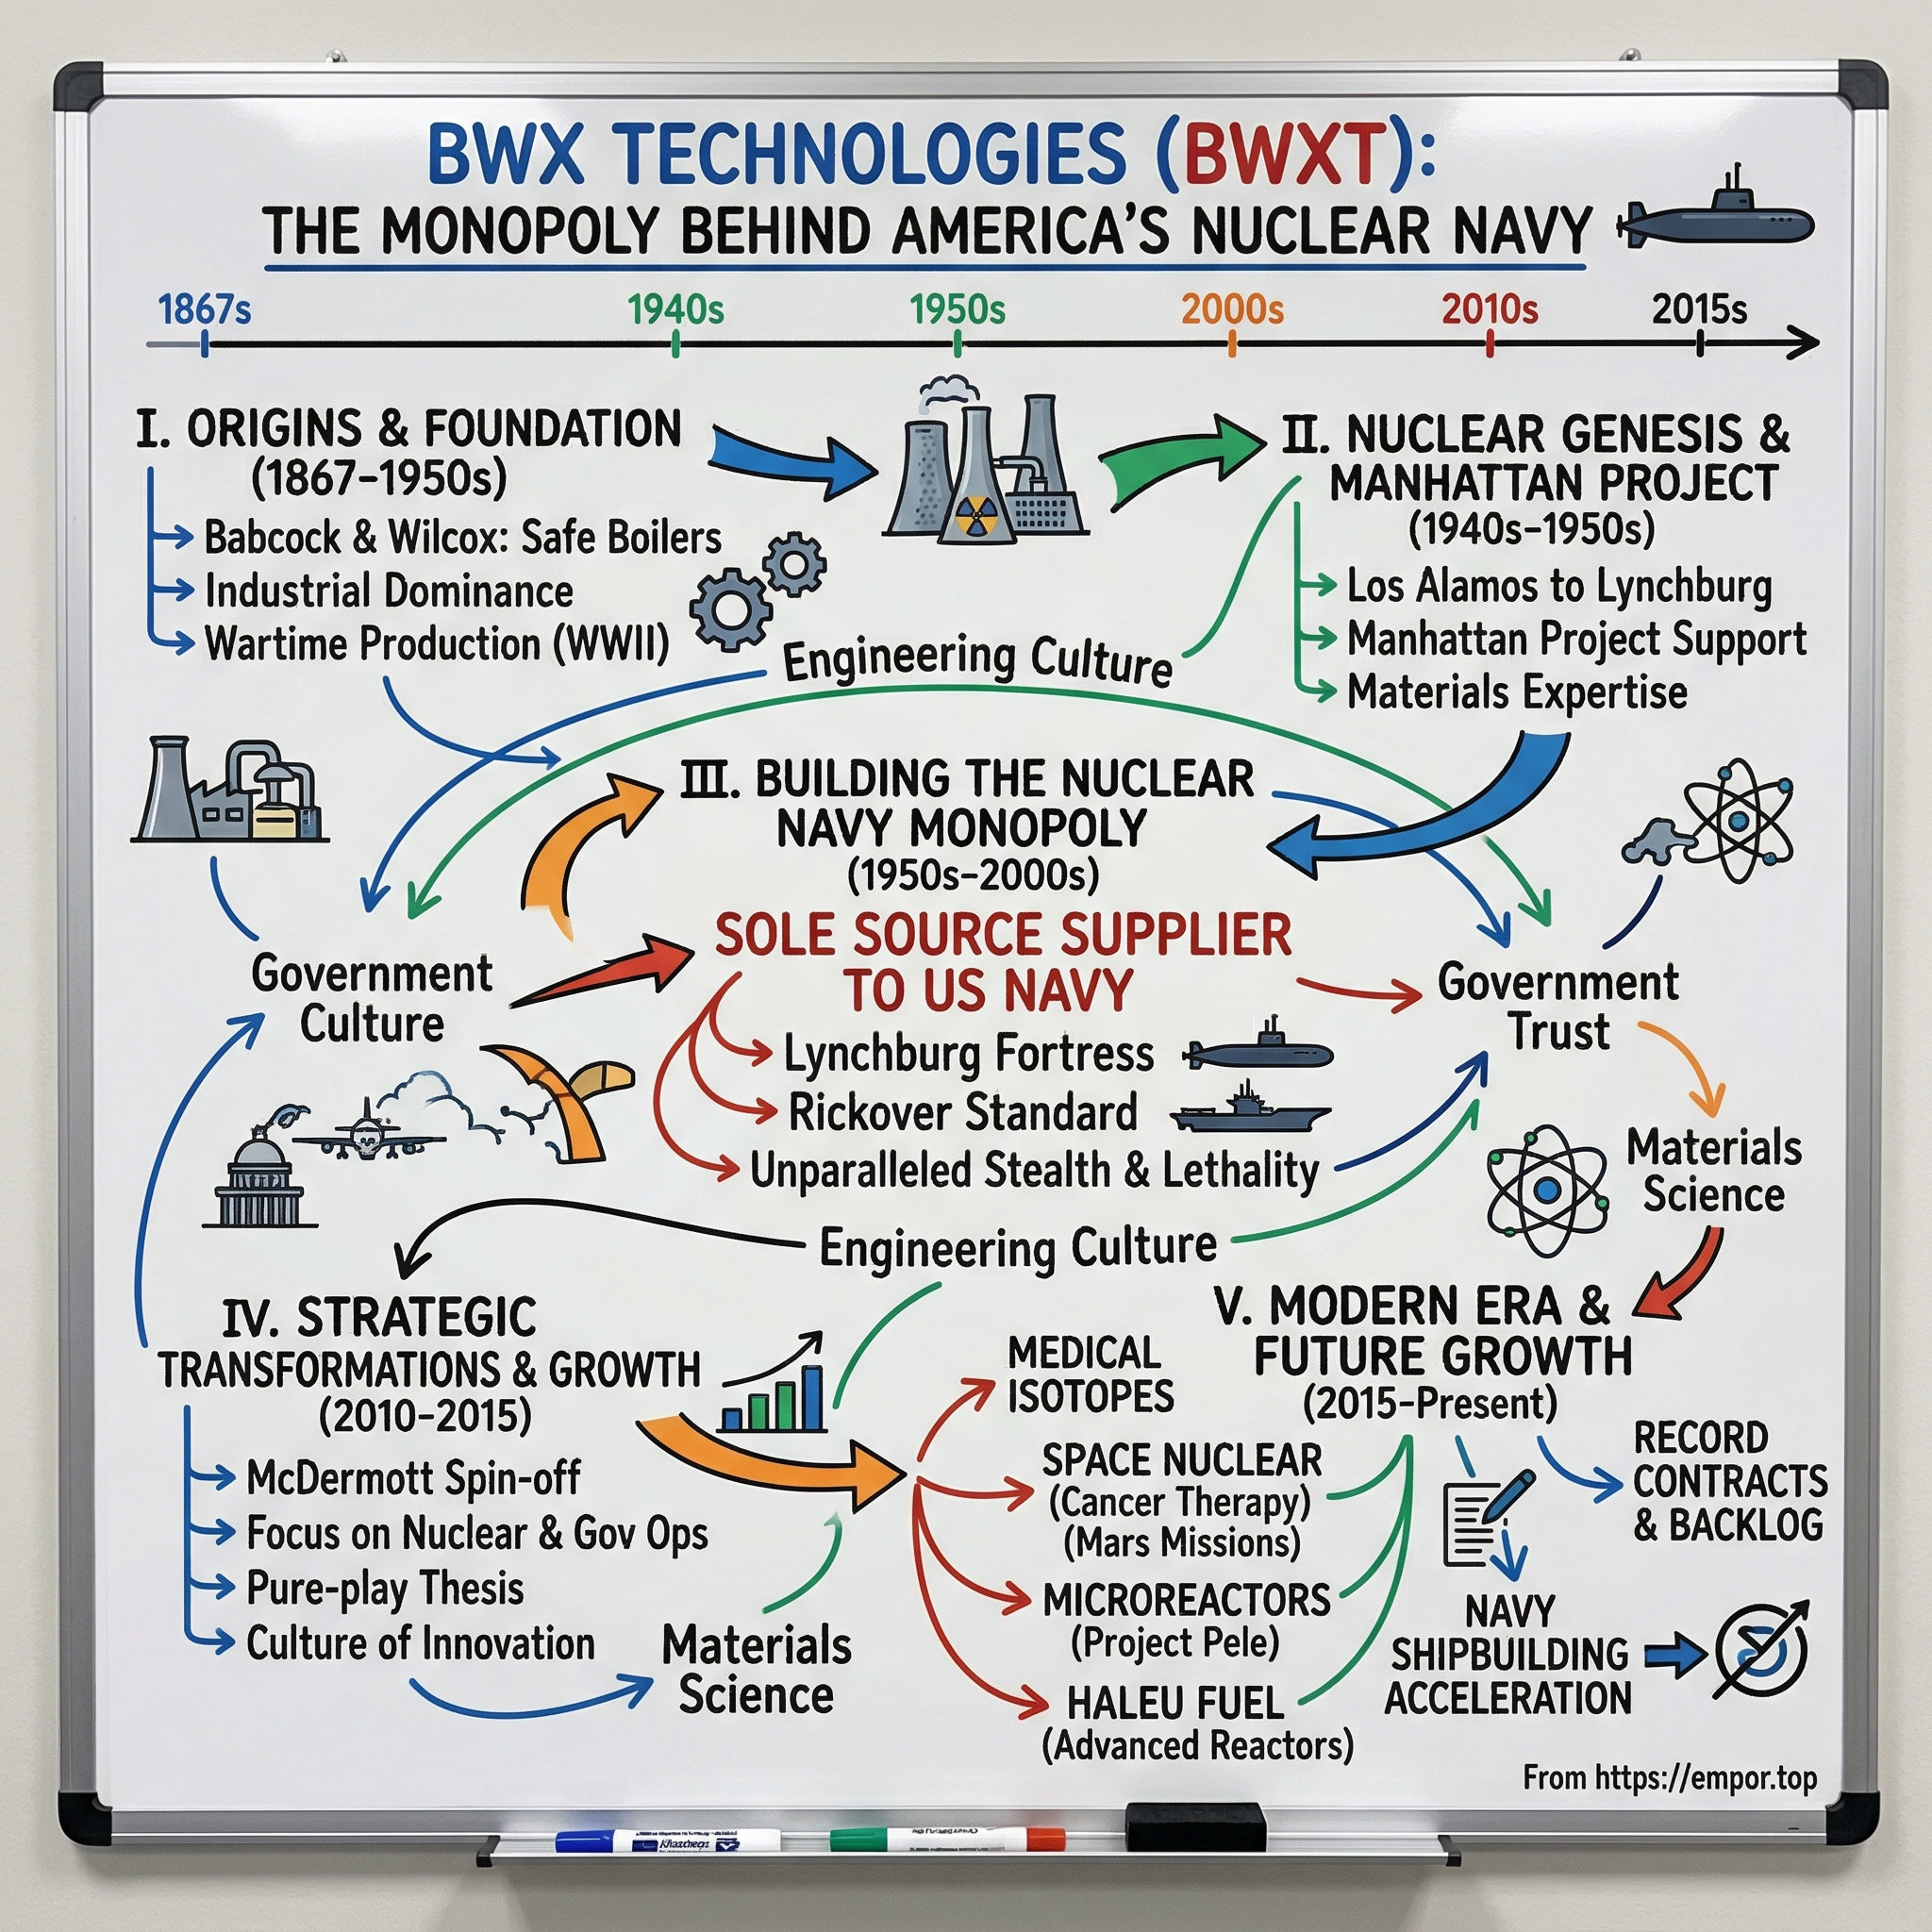
BWX Technologies: The Monopoly Behind America's Nuclear Navy
I. Introduction & Cold Open
Somewhere under the Atlantic right now, a Virginia-class attack submarine is running silent at a depth the Navy will not disclose, powered by a reactor that will not need refueling for the life of the hull. Its crew will never see the core. They will never open it. The steel pressure vessel that contains it, the fuel elements inside it, and the metallurgy that keeps neutrons doing useful work instead of destructive work were all built in a small set of guarded facilities in Virginia, Ohio, Indiana, and Tennessee.
Every one of them belongs to the same company.
That singular positioning makes BWX Technologies worth detailed examination. Every nuclear-powered vessel in the U.S. fleet—the Virginia- and Columbia-class submarines, as well as the Nimitz- and Gerald R. Ford-class aircraft carriers—runs on reactor components and nuclear fuel that trace back to BWXT. There is no second source. There is no qualified alternative sitting on a shelf. The Navy did not structure the supply chain this way out of sentiment; it reached this endpoint because every commercial competitor exited the market.
As of late August 2026, the company's financial profile presents a notable contrast. BWXT generated 2025 revenue of $3.2 billion, up 18% year over year, split between a Government Operations segment that produced $2.35 billion and a Commercial Operations segment that produced $853 million.12 The shares closed recently at $152.29, giving the company a market capitalization of roughly $14.0 billion against a 52-week range of $147.74 to $241.82—meaning the stock has surrendered nearly 37% from its high even as the operating business posted record results.3 Adding about $1.4 billion of net debt brings enterprise value near $15 billion.4
That divergence between stock performance and operating growth is the primary tension in BWXT's story, one that frames the broader analysis of the business.
The monopsony problem. A monopoly selling to a monopsony creates unusual economic dynamics. BWXT is the only seller of naval reactor cores—and the U.S. government is the only buyer, accounting for approximately 68% of consolidated 2025 revenue, down from about 76% in 2024 and 75% in 2023 as commercial work grew.4 The customer sets the volume, audits the costs, and negotiates the fee. Pricing power in the ordinary sense—raising prices to retain the difference—does not exist here. What exists instead is a durable position: the customer cannot switch suppliers because no qualified alternative exists.
The central question. How does a company founded in 1867 to sell steam boilers—a business as commoditized as heavy industry gets—survive a century and a half of technological substitution, an asbestos bankruptcy that put it under court protection for six years, ownership by an offshore oil-services conglomerate, the near-total collapse of the American nuclear industry after Three Mile Island, and the secular death of coal, to emerge in 2026 as the sole supplier to Western naval nuclear power? And having emerged, is the resulting franchise as unassailable as the narrative suggests?
The roadmap: the boiler century and why an engineering reputation is not a moat; the Manhattan Project and Admiral Rickover, who effectively wrote the company's operating manual; the slow construction of a licensing and clearance fortress between 1960 and 2009; asbestos, McDermott, and the 2015 split that created the pure-play; Rex Geveden's decade of reshaping the portfolio; the segment economics and what cost-plus accounting really does to reported growth; a hard falsification pass on the moat, the optionality, and the capital allocation record; the growth vectors, including the ones that have already failed; and finally, valuation, the KPIs worth tracking, and the bull and bear cases as a skeptical investor would frame them.
Start where the company started: with the problem of boilers that killed people.
 Subscribe on LinkedIn
II. Origins: The Babcock & Wilcox Industrial Engine (1867–1940s)
In the middle of the nineteenth century, the most dangerous machine in American industry was the steam boiler. Fire-tube designs routed hot combustion gases through tubes running inside a single large drum of water—efficient enough, but if the drum's pressure boundary failed, the entire volume of superheated water flashed to steam at once. Factory boilers took roofs off buildings. Steamboat boilers killed passengers by the hundreds. The technology that powered industrialization routinely blew it up.
Stephen Wilcox's answer, patented in 1856, inverted the geometry: put the water inside many small inclined tubes and the fire outside them.5 A useful analogy is a bundle of drinking straws versus a bathtub: puncture one straw and only a fraction of the pressurized water escapes; puncture the bathtub and everything vents at once. The water-tube boiler could therefore run hotter and at higher pressure with far lower risk of catastrophic failure. In thermodynamics, higher pressure is the essential driver that converts heat efficiently into useful work.
In 1867 Wilcox and his partner George Babcock formed Babcock, Wilcox & Company to commercialize the design.5 The commercial logic was not simply offering a better boiler, but selling one that insurers, city inspectors, and factory managers would approve at operating pressures competitors could not safely match.
The textbook as a marketing instrument
In 1879 the company published Steam: Its Generation and Use, which it describes as the longest continuously published engineering text of its kind in the world.5 This was a shrewd marketing strategy: by distributing the reference manual freely, B&W ensured an entire generation of mechanical engineers learned its vocabulary, diagrams, and operational standards. Teaching engineers on vendor-authored documentation served as an effective form of standard-setting that generated long-term commercial returns.
Commercial validation followed quickly. B&W boilers powered the first central electric station in the United States as well as Thomas Edison's Pearl Street Station in New York in 1881–1882—the facility that demonstrated distributed electricity as a viable commercial industry.5 Naval contracts followed, and by the early twentieth century B&W had established itself as a primary provider of warship propulsion. The company became a foundational supplier to American electrification and naval power.
Where the origin myth breaks
It is tempting to view that first century as the construction of an unassailable engineering moat, but the operational record does not support that narrative.
Heavy boiler manufacturing was a capital-intensive, deeply cyclical business tied to industrial capital expenditure cycles that swung sharply with economic downturns. B&W sold capital equipment rather than fuel or ongoing operating services, capturing a one-time margin on competitively bid hardware before waiting years for replacement orders. Rivals such as Combustion Engineering, Foster Wheeler, and the boiler divisions of major electrical equipment manufacturers competed for the same contracts. A strong technical reputation secured invitations to bid; it did not guarantee pricing power.
The strategic divergence became clear decades later. The descendant of that boiler business, spun out in 2015 as Babcock & Wilcox Enterprises, struggled as an independent company, while the nuclear operations continued to compound. If the original water-tube boiler franchise had constituted a true economic moat, the two segments would not have diverged so sharply after the separation. The engineering reputation was genuine, but the underlying economics were ordinary.
What did persist was not a high-margin moat or brand premium, but a specialized industrial capability: the expertise to fabricate massive, thick-walled, precisely welded pressure boundaries that hold high-temperature fluids under extreme stress without leaking, combined with the rigorous institutional practice of documenting every weld. In 1867 that capability commanded standard industrial margins. In 1943, when the U.S. government sought contractors capable of manufacturing massive nuclear pressure vessels to unprecedented engineering tolerances, that specialized manufacturing capability became far more valuable.
III. The Manhattan Project & Birth of the Nuclear Navy (1940s–1950s)
The Manhattan Engineer District faced a procurement problem that secrecy alone could not solve: the physics was unprecedented, but the hardware was not. Enriching uranium at Oak Ridge required process vessels, piping, and heavy mechanical equipment manufactured to tolerances that commercial industry had never encountered—from firms capable of building to confidential drawings without asking their ultimate purpose. Between 1943 and 1945, B&W supplied components and materials to the project.5
It was subcontract work, and it did not immediately transform the business. What it did was place Babcock & Wilcox on a very short list of trusted government fabricators.
Rickover's operating system
The individual who converted that list into an enduring industry was Admiral Hyman G. Rickover, who directed naval nuclear propulsion for three decades with absolute administrative authority. Rickover's contribution lay less in fundamental physics than in an uncompromising management framework imposed on every supplier: complete technical accountability, zero delegation of quality control, meticulous documentation, and an absolute rejection of the defense industry's traditional practice of delivering adequate hardware and patching defects in the field.
For a contractor, this environment was both onerous and clarifying. It was onerous because intense paperwork, rigorous inspection regimes, and mandatory rework made naval components far more expensive per pound than commercial hardware. It was clarifying because surviving the process yielded a rare competitive asset: a proven, audited, and government-verified process for manufacturing nuclear components correctly on the first attempt.
B&W received its first contract to research propulsion systems for the U.S. Navy in 1946 and designed and fabricated components for USS Nautilus, the world's first nuclear-powered submarine, between 1953 and 1955.5 The Nautilus project marks the true origin of the modern company. Every naval reactor component BWXT supplies to the government today descends directly from that foundation.
The commercial detour
The 1950s also produced the commercial atomic era's defining strategic error, which B&W embraced alongside its industry peers.
The company manufactured components for the Shippingport Atomic Power Station in 1956–1957, America's first full-scale peacetime nuclear plant, established the Lynchburg Research Center in 1956 as the first privately financed U.S. nuclear facility, and entered the commercial nuclear market through reactor systems for Indian Point in 1962.5 The Lynchburg site remains central to company operations today, but the commercial reactor market it helped seed quickly turned into a financial trap.
That trap stemmed from contract design. Regulated electric utilities demanded fixed-price turnkey contracts to secure predictable capital costs for their rate bases. Competing for a market expected to expand indefinitely, reactor vendors agreed to fixed pricing. Subsequent regulatory shifts repeatedly expanded safety requirements, while unforeseen corrosion, materials degradation, and field-engineering challenges in first-of-a-kind plants triggered costly redesigns. The equipment vendors absorbed the cost overruns.
For investors, the key insight from the 1950s and 1960s is not that B&W acted as an atomic pioneer, but that applying similar nuclear physics yielded radically different returns depending on contract structure and customer profile. Cost-reimbursable work for a technically sophisticated government client that specified requirements and funded their execution proved stable and profitable. Fixed-price work for commercial utilities in an evolving regulatory market proved disastrous. That structural distinction—who bears the financial risk of scope changes—remains essential to analyzing BWXT's financial results seven decades later, with direct implications for modern fixed-price-incentive contracts and commercial expansion plans.
By the mid-1970s, B&W operated two parallel businesses: a disciplined, high-margin naval supply franchise and a commercial reactor division tied to a market nearing collapse. On March 28, 1979, at four in the morning, the commercial expansion abruptly ended.
IV. Constructing the Naval Nuclear Monopoly (1960s–2000s)
Unit 2 at Three Mile Island near Middletown, Pennsylvania, was a pressurized water reactor supplied by Babcock & Wilcox. A pressure relief valve failed to close, cooling water drained out, operators misread contradictory instrumentation and shut off emergency cooling, and the core partially melted—the most severe accident in U.S. commercial nuclear operating history, though its small radioactive releases produced no detectable health effects on workers or the public.6
The physical damage was contained; the commercial damage was not. The accident hardened public opposition, triggered a sweeping tightening of Nuclear Regulatory Commission (NRC) oversight, and effectively halted new reactor orders in the United States for a generation. The next newly constructed U.S. reactor to enter commercial operation was Vogtle Unit 3—in July 2023, forty-four years later.7
For B&W, the vendor of record, the disaster brought the commercial reactor business near extinction. Its order book did not simply contract; it vanished. Yet that collapse set off a strange structural transformation: the company still retained its sole-source alignment with the U.S. Navy.
How competitors handed over the market
Naval reactor manufacturing during the Cold War was not initially a monopoly. General Electric, Westinghouse, and Combustion Engineering all held positions in the nuclear supply chain. Over the following decades, however, every one of them exited the market.
Their exit explains why BWXT's current position is structurally defensible rather than merely fortunate. For a diversified industrial conglomerate, naval nuclear manufacturing presented an unattractive operating profile:
- Low unit volumes. The Navy purchases only a few nuclear-powered hulls each year, offering no steep manufacturing scale curve comparable to commercial volume production.
- Extreme overhead. Security clearances, physical protection of special nuclear material, government-witnessed quality assurance systems, and audit regimes consume management attention disproportionate to revenue.
- Capital intensity with a single customer. Facilities require heavy capital investment while serving precisely one specialized application and one buyer.
- Regulated returns. Fees on cost-reimbursable government contracts are negotiated and audited, capping the financial upside for operational excellence.
For conglomerates with higher-return alternatives for capital, exiting was the rational strategic decision. One by one, competitors withdrew. B&W's resulting monopoly was less an aggressive conquest than a last-man-standing outcome—a posture that proved remarkably durable, as the high structural barriers that deterred incumbents continue to keep new entrants out today.
The licensing fortress
The most formidable component of the company's competitive moat is a regulatory license that cannot easily be duplicated.
Uranium enriched above 20% in the isotope U-235—highly enriched uranium (HEU), which enables submarine reactors to operate for decades without refueling—is regulated by the NRC under its most stringent Category I classification. Only two Category I fuel fabrication facilities are licensed to operate in the United States: Nuclear Fuel Services in Erwin, Tennessee, and the BWXT Nuclear Operations Group facility in Lynchburg, Virginia.89 BWXT owns both.10
That dual ownership was built through acquisition. Lynchburg was developed internally, whereas Erwin was acquired: B&W, then operating as a subsidiary of McDermott, agreed in August 2008 to acquire Nuclear Fuel Services and closed the transaction in early 2009.1112 With that purchase, a single company consolidated every commercial U.S. license to possess, process, and down-blend naval-grade HEU.
In theory, a competitor could submit an application for a Category I license. In practice, establishing a compliant site, building a physical security apparatus, implementing a nuclear material control and accounting system, navigating NRC licensing proceedings, passing environmental reviews, and securing local community consent represent a decade-long, multi-billion-dollar effort. A prospective entrant would require a client willing to underwrite that investment—and the sole customer, the U.S. government, has little incentive to fund a redundant supply chain.
The moat does not rely on vague regulatory complexity. It rests on grandfathered operating licenses tied to specific, heavily defended properties, paired with a monopsonist buyer that refuses to subsidize duplicate infrastructure.
The narrowing that followed
The pivot following Three Mile Island fundamentally transformed the company. Babcock & Wilcox transitioned from a dual commercial-and-defense fabricator into a specialized government contractor with a shrinking industrial appendage. Revenue predictability improved, as defense backlogs offer long-term visibility that commercial utility orders never matched. Yet revenue growth became tightly bound to congressional defense appropriations and Navy shipbuilding schedules—substituting political and budgetary risk for commercial market risk.
Furthermore, attached to this resilient nuclear franchise was a lingering liability from the legacy boiler business that would soon demand six years of restructuring under bankruptcy protection.
V. Corporate Turmoil: Asbestos, McDermott, and the Great 2015 Spin-off (2000–2015)
For most of the twentieth century, insulating a high-temperature boiler required asbestos. It was cheap, highly effective, and carried severe health consequences that emerged with a latency of several decades—eventually arriving on the balance sheet of a company that had long since stopped using the material, brought by claimants who had worked around equipment sold generations earlier.
On February 22, 2000, Babcock & Wilcox filed for Chapter 11 bankruptcy protection in the Eastern District of Louisiana.13 Its parent company, McDermott International—the offshore energy engineering group that had acquired B&W in 1978—spent the next six years structuring a settlement under Section 524(g) of the U.S. Bankruptcy Code. That mechanism allowed corporate defendants to channel present and future asbestos claims into an independent trust and emerge with a permanent injunction against further litigation.
B&W emerged from bankruptcy on February 22, 2006, exactly six years after filing, having funded a $1.85 billion personal injury settlement trust assembled from insurance assets, cash, equity in B&W itself, McDermott stock and notes, and tax benefits.13
What the bankruptcy actually cost
The financial settlement was only the visible cost; the subtle toll was strategic paralysis. For six years, the primary nuclear manufacturing supplier to the U.S. Navy operated inside a bankruptcy estate. Capital allocation was subordinated to a court-supervised legal process, constraining B&W's ability to invest, execute acquisitions, or reposition its portfolio. Competitors exiting naval work during this period represented an operational opportunity that B&W was poorly positioned to exploit actively at the time.
Resolving the corporate structure ultimately required two distinct separations. McDermott first spun off B&W as an independent public company in 2010.5 Five years later, the newly independent entity moved to separate its two incompatible operating models.
The 2015 split: the decision that created the modern company
On June 30, 2015, The Babcock & Wilcox Company completed the tax-free spin-off of its Power Generation business, distributing one share of the new entity for every two shares held by existing investors.14 The legacy fossil boiler and environmental equipment business retained the historic name and began trading under the ticker BW. The government nuclear operations, nuclear fuel processing facilities, and commercial nuclear service divisions were renamed BWX Technologies and began trading under the ticker BWXT on July 1, 2015.514
Strategically, the transaction separated two businesses with minimal operational synergy. The legacy unit sold heavy capital equipment into a structurally declining coal-fired power market characterized by volatile demand and execution risks. BWXT supplied high-barrier components to a single government customer operating on a predictable multi-decade procurement timetable. Combined, BWXT's high-margin economics were obscured by fossil-fuel volatility, and capital that could have expanded nuclear manufacturing capacity was instead diverted to support a shrinking legacy franchise.
The subsequent operating divergence of the two companies demonstrates that the separation uncovered pre-existing franchise value rather than creating it through financial engineering. The spin-off did not alter the fundamental quality of the nuclear business; it highlighted an established defense monopoly and removed a legacy claim on its cash flows. The separation functioned primarily as a disclosure event rather than an operational turnaround.
The mPower failure, and what it proves
The company's corporate track record includes a notable strategic failure: the same executive lineage that executed the 2015 spin-off also directed BWXT's most expensive commercial development program.
Beginning around 2008–2009, B&W developed a small modular reactor named mPower, rated at 195 megawatts electric (MWe)—a factory-built reactor designed to bypass the construction delays and cost overruns typical of gigawatt-scale nuclear plants.15 The initiative appeared aligned with the company's manufacturing capabilities, drawing on its decades of experience producing compact reactors for naval applications. Engineering firm Bechtel subsequently joined the project as a partner in a joint venture named Generation mPower.
The venture failed to establish a viable commercial path. Electric utilities declined to sign binding power purchase agreements for an unproven reactor design, and without off-take commitments, the substantial regulatory licensing costs could not be justified. B&W curtailed spending in 2014. On March 3, 2017, Bechtel formally notified BWXT that it could not secure necessary third-party funding and invoked termination provisions in the framework agreement; BWXT paid Bechtel a $30 million settlement as the sole remedy.1617
On the second-quarter 2026 earnings call, Chief Executive Officer Rex Geveden summarized the financial outcome, noting that the company spent approximately $400 million on mPower and estimated that an additional $600 million would have been required to complete Nuclear Regulatory Commission licensing before halting development because commercial demand failed to materialize.18
The analytical takeaway is clear: technical capability in defense nuclear engineering does not automatically translate into commercial utility sales. The mPower initiative failed not from manufacturing deficiencies, but from the absence of a committed customer willing to underwrite the cost of regulatory approval. That outcome provides an empirical baseline for evaluating BWXT's current commercial expansion plans in microreactors, space propulsion, and small modular reactors, and applies directly to each of those initiatives in subsequent sections of this analysis.
VI. The Pure-Play Nuclear Architecture & Rex Geveden Era (2015–Present)
Rex Geveden grew up in Mayfield, Kentucky, earned bachelor's and master's degrees in physics from Murray State, and spent 17 years at NASA, rising to associate administrator—effectively the agency's chief operating officer, responsible for a $16 billion portfolio spanning science, aeronautics, space operations, and exploration, with oversight of 10 field centers.19 He then spent eight years at Teledyne Technologies, ultimately running its digital imaging and engineered systems segments, before joining BWXT as chief operating officer in 2015 and becoming chief executive in 2017.19
That background provides relevant operational context. Managing NASA field centers requires leading technically complex organizations funded by federal appropriations, where the primary operational constraint is program execution under strict government audit. An executive with that experience is well prepared for the oversight environment of the Naval Nuclear Propulsion Program.
The leadership bench, and its recent churn
The executive team has undergone notable changes over the past two years.
Robb LeMasters, chief financial officer since 2018 and a director since 2015, stepped down in May 2025.20 Mike Fitzgerald, who joined in 2022 as chief accounting officer, served as interim CFO before his appointment as permanent CFO effective August 1, 2025.21 In June 2025, Joe Miller—previously president of BWXT Advanced Technologies—succeeded Kevin McCoy as president of Government Operations, while McCoy transitioned to chief nuclear officer to support the Navy in accelerating Columbia- and Virginia-class submarine production.22 John MacQuarrie leads Commercial Operations.23
Replacing a CFO, rotating a segment president, and creating a new chief nuclear officer role within a twelve-month span represents meaningful executive turnover for a company of this scale. The specific reasons for LeMasters' departure were not disclosed in detail. Investors should view this transition with measured scrutiny: while the succession was internal and orderly, full-year guidance has been raised rather than reduced, and financial results have not required restatement, leadership turnover in the finance function during the company's largest capital deployment cycle warrants ongoing attention.
Executive alignment is detailed in BWXT's proxy statements. Disclosed summary compensation data confirms that the chief executive's pay is structured primarily around equity and performance incentives rather than base salary, with total 2024 compensation of approximately $8.2 million against a base salary near $1.0 million.4
The two-segment machine
Government Operations remains the core business. It encompasses naval nuclear propulsion—manufacturing reactor cores and processing fuel for submarines and aircraft carriers—alongside a special materials business, technical services managing Department of Energy and National Nuclear Security Administration sites, and advanced nuclear development programs. In 2025 the segment generated $2.35 billion in revenue and $479.1 million in adjusted EBITDA, representing a 20.4% operating margin.2 It represents the primary profit center and operational foundation of the company, with growth linked directly to federal shipbuilding schedules.
Commercial Operations functions as the growth driver and primary strategic variable. In 2025 segment revenue expanded 63% to $853.1 million, producing adjusted EBITDA of $110.1 million for a 12.9% margin—profitable, but roughly two-thirds the margin of the government segment.2 The unit includes Canadian nuclear services, CANDU reactor refurbishment, heavy component manufacturing for commercial power plants, and, until recently, medical isotopes.
Management's strategic thesis is straightforward: deploy stable cash flows from a government monopoly to establish a position in commercial nuclear markets ahead of a broader sector turnaround. Whether this approach reflects disciplined capital allocation or risks repeating the capital losses of the mPower project remains the central debate for investors, with evidence supporting both perspectives.
The 2025–2026 portfolio surgery
Portfolio repositioning has accelerated through several recent transactions:
- Kinectrics, a Toronto-based nuclear services firm covering the plant lifecycle and medical isotopes, was acquired for approximately $525 million including assumed pension liabilities and debt under an agreement reached in January 2025 that closed on May 20, 2025. The transaction nearly doubled the Commercial Operations workforce.2425
- A.O.T., a smaller 2025 acquisition, expanded capabilities in depleted uranium assaying and contributed to Government Operations revenue.2
- Precision Components Group—a U.S. manufacturer of heavy-walled and heat-transfer components operating through Precision Custom Components and DC Fabricators—was acquired under an agreement signed on April 20, 2026, closing on July 1, 2026. The purchase added over 500,000 square feet of heavy manufacturing space and 450 employees across facilities in York, Pennsylvania, and Florence, New Jersey. Terms were not disclosed.2627
- BWXT Medical was sold. On August 3, 2026, BWXT reached a definitive agreement to sell its medical unit and Kinectrics' stable medical isotopes business to Nordic Capital for up to $800 million, while retaining a minority equity stake.28
The sale of the medical division provides clear insight into management's capital discipline. BWXT acquired Nordion's medical isotope business from Sotera Health in 2018 and spent eight years expanding it.5 Addressing the transaction during the second-quarter 2026 earnings call, Geveden noted that the asset was not actively marketed until Nordic Capital made an unsolicited approach, adding that medical isotopes accounted for roughly 3% of total revenue while requiring disproportionate management oversight. Summarizing the rationale, Geveden stated, "we can't shoot at everything that moves."18
A favorable interpretation views the sale as a prudent divestiture of a minor operation at an attractive valuation. A more critical assessment sees an acknowledgment that an eight-year diversification effort failed to achieve sufficient scale to justify its operational overhead—a smaller-scale parallel to the mPower experience. Both conclusions carry merit. For investors, the broader pattern indicates a leadership team willing to exit commercialization initiatives when capital demands outweigh strategic focus, offering a clear framework for evaluating the company's remaining commercial ventures.
That strategic reallocation leads directly to the financial analysis, where specialized accounting rules can make BWXT's reported top-line growth appear misleading if evaluated without adjusting for contract structures.
VII. Segment Economics & Financial Engine
The financial structure of BWX Technologies reflects a classic heavy-manufacturing business paired with a high-margin government contract model. In 2025, BWXT converted $3.2 billion of revenue into $574.3 million of adjusted EBITDA, net income of $329.9 million, GAAP diluted earnings of $3.58 per share, and non-GAAP earnings of $4.01 per share.1 Operating cash flow reached $479.8 million, yielding free cash flow of $295.3 million after $184.6 million in capital expenditures.12 Fueled by $5.4 billion in annual bookings, total backlog surged 50% to end the year at $7.3 billion.2
Free cash flow conversion stands in the mid-80% range relative to net income—a solid recovery from 2022, when an inventory build and heavy capital spending reduced free cash flow to less than $50 million.4 That prior dip highlights a key operational reality: BWXT remains a capital-intensive industrial fabricator rather than an asset-light software business, leaving annual cash conversion vulnerable to working capital swings and facility investments.
The cost-plus paradox
Analyzing BWXT requires navigating the counterintuitive accounting of government defense contracts.
During the company's second-quarter 2026 earnings call, Chief Financial Officer Mike Fitzgerald lowered full-year revenue growth guidance for Government Operations to the high single digits—down from earlier forecasts in the low teens—while simultaneously raising the segment's adjusted EBITDA margin guidance to approximately 20.5% from above 19%. As Fitzgerald explained, "Improved cost performance under our accounting rules results in lower reported revenue, but an overall favorable economic outcome."18
That divergence illustrates the mechanics of cost-reimbursable defense contracting. On cost-plus structures, recognized revenue primarily reflects total costs incurred plus an agreed fee. When manufacturing efficiency improves and costs decline, reported revenue drops even as total profit dollars remain steady or expand. Top-line revenue growth in Government Operations can therefore be a misleading indicator, blending physical volume, input inflation, and operational efficiency in ways that move inversely to economic value creation. For financial analysts, segment EBITDA dollars, operating margins, and order backlog provide far clearer signals of fundamental strength than reported revenue.
What the segments actually earn
Government Operations margins have consistently hovered between 19% and 21%. In the second quarter of 2026, the segment increased revenue by only 2% yet generated $126 million in adjusted EBITDA at a 20.9% margin, supported by strong factory execution and higher equity earnings from technical services joint ventures.18 That followed a first quarter in which segment revenue rose 4% with a 20.4% margin.29
Commercial Operations presents a contrasting financial profile. Second-quarter commercial revenue expanded 72%—including 33% organic growth—driven by ramping Canadian field services, strong aftermarket activity, and the inclusion of Kinectrics; segment adjusted EBITDA more than doubled to $36 million, yielding an 11.9% margin.18 However, this rapid top-line expansion comes with lower structural profitability and declining near-term margins. Management reduced the full-year Commercial margin outlook to roughly 13% from approximately 14%, citing front-loaded investments in U.S. manufacturing expansion and continued outlays in Canada.18
As a result, the rapid growth in Commercial Operations is temporarily diluting BWXT's consolidated profitability. The segment earns lower margins per dollar of sales and requires substantial pre-revenue capital deployment. Consequently, consolidated adjusted EBITDA margin compressed to 17.2% in the first quarter of 2026 from 19.0% a year earlier.29 Characterizing BWXT's commercial expansion as immediately margin-accretive overlooks this near-term structural reality.
Capital intensity is rising, on purpose
Capital intensity is climbing as BWXT funds its growth agenda. Capital expenditures have averaged near 6% of revenue, and Fitzgerald noted that capex could reach 7% in coming years as the business expands its commercial manufacturing footprint and develops advanced nuclear fuel capabilities.18 Applied to full-year 2026 revenue guidance of approximately $3.8 billion, that percentage represents a substantial increase in cash outlays.18
To fund its 2025 acquisitions, BWXT increased balance sheet leverage, accumulating roughly $1.4 billion in net debt—translating to a net debt-to-EBITDA ratio in the mid-2x range.4 While manageable given the company's long-term revenue visibility, the capital structure is less conservative than in 2023. Proceeds from the pending medical division sale will improve liquidity, though management has declined to commit those funds to debt paydown or share buybacks. On the second-quarter call, Fitzgerald listed internal expansion investments first, followed by bolt-on acquisitions and addressing two upcoming bond maturities, while confirming that no share repurchases are scheduled for 2026.18
That capital deployment strategy signals that management prioritizes long-term capacity expansion over immediate cash returns to shareholders. Meanwhile, the annual dividend—totaling approximately $92 million in 2025 and yielding under 1%—remains a minor component of the overall investment thesis.43
What analysts actually press on
Wall Street analyst questioning during the second-quarter 2026 earnings call highlighted key market uncertainties. When Bob Labick of CJS Securities asked about the valuation gap in the medical unit sale, Fitzgerald clarified that the agreement includes $750 million in upfront cash consideration alongside shared upside mechanisms that could reach $800 million.18 Scott Deuschle of Deutsche Bank raised a broader strategic concern, asking why no domestic electric utility had placed a firm order for Westinghouse AP1000 components despite strong federal support for nuclear power. Chief Executive Officer Rex Geveden responded that government-backed nuclear initiatives are currently being organized through special-purpose vehicles—with federal agencies sharing ownership and funding long-lead procurement—and that utilities are "rightly waiting to see how those deals come out" before committing private capital.18
That exchange provides critical context for BWXT's commercial expansion strategy. Management acknowledged that the broader commercial nuclear construction wave remains prospective rather than contractual. BWXT is committing capital to build manufacturing capacity ahead of binding utility purchase orders, anticipating demand that remains contingent on finalized government funding frameworks.
Whether that front-loaded capital deployment represents visionary positioning or premature spending depends on the durability of the company's competitive moat.
VIII. Competitive Moats & The 7 Powers Framework
Run BWXT through Hamilton Helmer's seven powers and the results are lopsided: overwhelming strength in two, real strength in one, and essentially nothing in the rest.
Cornered resource: the strongest power, precisely bounded
The two Category I HEU licenses are the closest thing to a legally enforced monopoly in American industrial manufacturing.810 Their strength should be stated precisely, though, because precision is what makes the claim survive scrutiny.
The licenses corner naval-grade highly enriched uranium fuel work in the United States. They do not corner commercial low-enriched fuel, where Westinghouse, Framatome and Global Nuclear Fuel compete. They do not corner heavy nuclear component manufacturing, where Doosan Enerbility, Japan Steel Works and others operate globally. They do not corner nuclear services. Roughly speaking, the absolute cornered resource protects the government segment; the commercial segment — the fast-growing one — competes on merit.
BWXT is also actively widening the government side. NNSA selected the company for a domestic uranium enrichment centrifuge pilot plant under the DUECE program, and the company acquired approximately 97 acres in Oak Ridge to support that mission.3031 In September 2025 it received a $1.5 billion NNSA defense fuels award, and on September 30, 2025 a separate 10-year, $1.6 billion contract to build and operate a high purity depleted uranium facility at Jonesborough, Tennessee, producing up to 300 metric tons annually — which NNSA described as the only active U.S. site capable of performing that production process for the government.323334
Note what is happening structurally: the government is paying BWXT to become the sole domestic source of additional categories of nuclear material. Each such award extends the cornered resource rather than merely adding revenue. That is the most powerful thing in the investment case, and it is happening now, not hypothetically.
Process power: real, and impossible to audit from outside
Seventy-plus years of naval reactor fabrication produce a body of tacit knowledge — welding procedures, non-destructive testing protocols, materials handling, tooling, the specific ways things go wrong and how to catch them — that exists inside people and inside a qualified quality system rather than inside patents. Approximately 11,000 employees support it, many holding clearances that take a year or more to obtain.18
Process power of this kind is genuinely durable, because it degrades slowly and cannot be bought. It is also genuinely unverifiable by an outside investor, who sees only the output: consistent 19–21% segment margins and an absence of publicly disclosed major program failures. That is evidence, but it is thin evidence, and it should be held as such.
Switching costs: extreme, but they belong to the customer
A submarine hull is designed around a specific reactor plant's dimensions, thermal output and piping architecture. Qualifying an alternative supplier would require not just building the alternative, but re-validating a design that the Navy has already accepted. In practical terms it would mean pausing the procurement of the most strategically important platform the United States builds.
The Navy will not do that. But note the asymmetry: switching costs protect BWXT's position, not its price. Under Federal Acquisition Regulation rules and Defense Contract Audit Agency oversight, cost-reimbursable fees are negotiated against audited cost bases. The customer cannot leave, and the supplier cannot gouge. The equilibrium is a stable mid-to-high-teens-to-low-20s margin with essentially no share risk — which is exactly what the reported segment margins show.
Where the powers are absent
- Scale economies: BWXT is not large. Its entire revenue base is smaller than a single General Dynamics business unit. Scale is not the mechanism.
- Network economies: none.
- Branding: irrelevant to a customer that audits rather than trusts.
- Counter-positioning: none in the Helmer sense. BWXT is not doing something incumbents cannot copy for fear of cannibalizing themselves; incumbents left because the returns were unattractive at their cost of capital, which is a different thing.
Porter's five forces, honestly scored
Threat of new entrants in naval nuclear: near zero, for the licensing and clearance reasons above. In commercial heavy components: moderate and rising, since global forging and vessel capacity exists and a genuine nuclear build cycle would attract it.
Buyer power: extremely high, and this is the force that dominates the government segment. One customer, statutory audit rights, and full visibility into the supplier's costs. BWXT's protection is not that the Navy lacks leverage; it is that the Navy's interest is a healthy, capable, reliably delivering supplier. That alignment has held for seventy years. It is not contractual.
Supplier power: moderate. Specialty forgings, nickel alloys, zirconium and — above all — qualified nuclear welders are constrained inputs. Labor scarcity in the submarine industrial base is a genuine, documented problem.
Substitutes: essentially none for naval propulsion. Meaningful in commercial power, where gas, renewables and storage compete on cost against every nuclear project.
Rivalry: minimal in government; ordinary in commercial.
The synthesis is that BWXT possesses one of the strongest defensive positions available in industrials — and that the position is defensive. It protects a stable, audited profit stream growing at the pace of federal appropriations. Every dollar of growth above that pace has to come from the commercial side, where none of these powers apply.
That is the claim worth stress-testing.
IX. Falsification Layer & The Skeptical Investor Stress Test
Three core claims carry the investment case for BWX Technologies. Each deserves rigorous stress-testing against the strongest disconfirming evidence available from the company's own operational record.
Stress test one: does the monopoly produce pricing power?
The claim. A sole-source position combined with irreplaceable regulatory licenses yields pricing power and structurally expanding operating margins.
The disconfirming evidence. Government Operations adjusted EBITDA margin reached 20.4% in 2025 and is guided to approximately 20.5% for 2026.218 Historical results show a similar pattern: a decade of monopoly positioning has generated stable margins rather than expanding ones. This reflects the mechanics of a negotiated, audited federal fee structure, where the contractor earns an agreed return on audited costs and no more.
Furthermore, this fee structure cuts both ways on fixed-price-incentive work, where BWXT absorbs cost overruns above agreed sharing thresholds. In an environment marked by defense labor inflation and tight supplies of specialized materials, that cost exposure is material. Meanwhile, demand is governed strictly by congressional appropriations and Navy procurement schedules rather than company capacity. The Navy's May 2026 30-year shipbuilding plan targets two Virginia-class submarines and one Columbia-class submarine annually, while aircraft carriers move to a four-year procurement cadence.1835 Procurement volumes are set by the customer; BWXT cannot expand its core defense market simply by trying to sell more aggressively.
Verdict. The claim is rejected in its strong form but survives in a narrower version. BWXT lacks traditional pricing power, possessing instead volume certainty and margin stability—a distinct and less dynamic economic feature, albeit a valuable one. The metric that would falsify even this narrower baseline is a durable drop in Government Operations adjusted EBITDA margin below the 19% to 20% range, which would signal either fixed-price contract losses or tighter customer fee negotiations.
Stress test two: can defense nuclear capability convert into commercial revenue?
The claim. Seven decades of naval reactor engineering give BWXT a privileged foundation to capture leadership in commercial nuclear systems and microreactors.
The disconfirming evidence. The empirical record presents clear challenges to this thesis.
First, the mPower program absorbed roughly $400 million while producing no commercial revenue, ultimately terminating with a $30 million settlement payment to a partner.1618 Second, DARPA cancelled the DRACO nuclear thermal propulsion program, for which BWXT was developing reactor hardware and high-assay low-enriched uranium (HALEU) fuel. A stop-work order was issued to the prime contractor in April 2025, NASA eliminated funding in its fiscal year 2026 budget request, and federal agencies concluded that falling launch costs and alternative technologies had superseded the concept.3637 A marquee, government-funded technology initiative ended not because of technical failure by BWXT, but because customer priorities shifted.
Third, the company spent eight years building its medical isotope business following a 2018 acquisition before agreeing to sell the unit in 2026 when it represented just 3% of revenue.51828 Notably, the New Drug Application for its Technetium-99m generator was submitted to the Food and Drug Administration in September 2022, with no public approval disclosed since.38 A four-year window from regulatory filing to divestiture without a disclosed approval highlights the commercial execution hurdles in non-core markets.
Against these setbacks, commercial conversion has occurred primarily through merchant supply contracts rather than proprietary reactor systems. Contracted work includes fabricating the reactor pressure vessel for the first BWRX-300 small modular reactor at Ontario Power Generation's Darlington station under a January 2025 GE Hitachi award, alongside manufacturing agreements supporting the Pickering plant life extension.3940 BWXT also supplied TRISO fuel and HALEU that enabled the Antares Mark-0 reactor to achieve criticality in June 2026—the first advanced reactor to reach that milestone under the federal testing executive order.18 Additionally, the company delivered the complete 40,000-compact TRISO fuel core for Project Pele to Idaho National Laboratory in November 2025.4142
Verdict. The claim requires substantial narrowing. BWXT's historical conversion of proprietary reactor designs and owned product platforms into commercial revenue is near zero across two major attempts involving roughly $400 million in outlays. Conversely, its conversion rate as a component and fuel supplier to third-party programs is demonstrably positive. Management has adjusted its approach accordingly. As Geveden outlined on the second-quarter call, BWXT explicitly declined to commercialize mPower on its own, licensing the design to Applied Atomics for terrestrial deployment while retaining intellectual property and manufacturing rights, and signing a feasibility agreement with Core Power for marine applications.18
This strategic shift reframes the investment thesis: growth depends on competing as a high-precision merchant fabricator in global commercial nuclear supply chains, where BWXT's domestic regulatory monopoly does not apply. The key indicator to monitor is firm, funded commercial equipment orders from utilities and reactor developers. Management stated on the second-quarter call that it expects at least one new commercial nuclear equipment contract by year-end.18 This provides a clear, near-term milestone to evaluate execution.
Stress test three: is the capital allocation record as disciplined as it looks?
The claim. Executive leadership systematically reinvests Government Operations cash flows into disciplined, value-accretive adjacencies.
The disconfirming evidence. BWXT has exited two major strategic initiatives—small modular reactor ownership and medical isotopes—while seeing a third government-funded program cancelled. In 2025, the company directed approximately $565 million toward acquisitions and $185 million to capital expenditures, compared to $92 million in dividends and $30 million in share repurchases, funding the deployment in part through new debt.4 Consolidated return on invested capital (ROIC), including acquisition goodwill, sits in the high single digits—below the mid-teens returns typically associated with high-moat franchises and contrary to the view that BWXT compounds capital at premium rates.4
Conversely, recent transactions show evidence of value recovery. The acquisitions are early in their integration phase, Kinectrics is contributing to a Commercial Operations segment that expanded 72% year over year, and the agreement to sell the medical unit realized up to $800 million for an asset acquired for a fraction of that sum.1828
Verdict. The thesis remains plausible but unproven. The strategic exits recovered capital rather than destroying it, representing a better outcome than a simple write-down model implies. However, the current capital deployment cycle—comprising Kinectrics, A.O.T., and Precision Components Group, alongside rising capital expenditures and a pending decision on manufacturing site expansion in Mount Vernon, Indiana or the East Coast—is substantial relative to earnings and has yet to demonstrate full returns.18 The critical performance metrics over the next three to four years are consolidated ROIC and a recovery in Commercial Operations margins toward the mid-teens as initial investments mature. Should Commercial margins remain near 13% in 2028 while capex stays near 7% of revenue, the capital discipline thesis will be invalidated.
X. Growth Vectors & Strategic Optionality
Every one of BWXT's growth vectors represents a variation on a single question: at what point does a government-funded technical milestone turn into a binding commercial purchase order? Evaluating these opportunities requires ranking them by their proximity to realized cash flow.
Naval propulsion, extended
The nearest-term growth driver is also the most direct: expansion of the core defense franchise. In February 2025 BWXT announced approximately $2.1 billion in naval nuclear reactor component contracts, followed in July 2025 by another $2.6 billion, primarily supporting Virginia- and Columbia-class submarines along with Gerald R. Ford-class aircraft carrier content, scheduled for delivery over six to eight years across facilities in Virginia, Ohio, Indiana, and Tennessee.4344 Those contract wins expanded total backlog to $8.4 billion by mid-2026, up 40% year over year, representing a trailing twelve-month book-to-bill ratio of 1.7 times—meaning the company booked $1.70 in new orders for every dollar of revenue recognized.18
An $8.4 billion backlog against roughly $3.8 billion in annual revenue provides more than two years of clear operating visibility, with the government contract portion carrying minimal cancellation risk. This remains the most predictable component of the growth case, even if it attracts less attention than higher-concept commercial initiatives.
The Navy's May 2026 shipbuilding plan introduced two incremental options: a shift to four-year procurement cadences for aircraft carriers—which management expects to stabilize manufacturing volume relative to the previous five-year cycle—and a proposed nuclear-powered battleship class of up to 15 vessels over 30 years.1835 The battleship concept requires extensive design work and congressional authorization, making it a speculative long-term possibility rather than an actionable operational plan.
AUKUS: the vector that got smaller
The consensus narrative surrounding the AUKUS security agreement requires realistic calibration.
AUKUS was initially highlighted as a structural expansion of BWXT's long-term addressable naval reactor market. By mid-2026, the near-term trajectory has proven more constrained. On May 30, 2026, the participating governments announced a revised acquisition strategy under which Australia will purchase three in-service Virginia-class submarines rather than one newly constructed boat alongside two in-service vessels—an adjustment explicitly intended to relieve pressure on U.S. shipyards struggling to meet domestic fleet schedules.45
Substituting existing hulls for new construction removes one new-build submarine reactor plant from the near-term pipeline. For a component manufacturer compensated to fabricate new reactor cores, this revision represents an immediate volume reduction rather than an expansion. Offsetting factors exist, including Australian capital injections into the U.S. submarine industrial base—highlighted by a $276 million U.S. Navy contract award to BWXT in April 2026—and prospective SSN-AUKUS submarine construction in the 2040s.46
In practice, AUKUS represents a long-dated, politically contingent option on incremental defense demand, currently undergoing U.S. policy review, whose near-term volume expectations have already been scaled back. It functions as a prospective long-term call option rather than a guaranteed high-margin annuity.
Microreactors: the closest thing to a real product
Project Pele represents the most advanced transportable microreactor program in the United States: a 1.5-megawatt high-temperature gas-cooled reactor using TRISO fuel, designed to fit inside standard shipping containers for rapid deployment to forward bases or disaster zones without relying on traditional fuel supply lines.41
TRISO fuel architecture warrants explanation because it underpins several of BWXT's advanced nuclear initiatives. Standard commercial reactors stack uranium oxide pellets inside metal alloy tubes, which serve as the primary containment structure. TRISO instead encapsulates individual fuel kernels inside micro-layers of carbon and silicon carbide, creating thousands of independent pressure vessels that allow the core to operate at substantially higher temperatures and withstand loss-of-cooling events without melting.
BWXT completed TRISO fuel fabrication for Pele's initial core and delivered 40,000 compacts to Idaho National Laboratory, where assembly and initial testing are expected by early 2027.4142 The project demonstrates tangible hardware manufacturing capability.
However, a government-funded demonstration project does not automatically establish a commercial market. While Pele validates BWXT's microreactor fabrication expertise, it does not guarantee follow-on fleet purchases. Furthermore, Government Operations revenue in both the first and second quarters of 2026 experienced headwinds from lower microreactor volume as Pele completed its primary fabrication phase.1829 Revenue from initial demonstration contracts remains inherently lumpy and finite.
Space nuclear: the vector that closed
The cancellation of DARPA's DRACO project removed a space-based nuclear propulsion vector that featured in earlier growth models.3637 The program's termination illustrates the structural risk inherent in government-funded research: technically successful hardware programs can be cancelled when broader mission architectures shift—in this case, driven by falling commercial launch costs that altered mission economics.36
Commercial nuclear: the capital being spent today
Commercial nuclear manufacturing represents management's primary capital deployment focus. The strategic objective is to operate as a merchant tier-one nuclear foundry—fabricating reactor pressure vessels, steam generators, and heat exchangers for third-party reactor designs rather than developing proprietary plant platforms.
Evidence of commercial traction includes fabricating the BWRX-300 reactor pressure vessel for Ontario Power Generation's Darlington station and securing Pickering plant refurbishment contracts in Canada;3940 partnering with TerraPower and Rolls-Royce on steam generator components for U.K. projects;18 acquiring Precision Components Group to add U.S. heavy manufacturing capacity with AP1000 heritage;27 and securing a $21 million Department of Energy award in May 2026 to support domestic manufacturing capacity expansion, with a final site selection decision pending.18
Conversely, commercial execution risks remain clear: as Chief Executive Officer Rex Geveden acknowledged on the second-quarter 2026 call, no domestic utility has yet placed a firm AP1000 component order despite federal policy support, and Canada's nuclear strategy contemplating up to ten large reactors remains a policy document rather than a binding purchase order.18 BWXT is committing capital to expand heavy manufacturing capacity—including evaluating site options requiring deepwater port access to ship massive components globally—ahead of utility orders that remain prospective.18
This capital strategy presents a distinct risk-reward profile. If utility orders materialize, BWXT will control scarce Western heavy nuclear fabrication capacity in a supply-constrained market. If contract awards slip by several years, the company will carry underutilized fixed overhead and rising depreciation expenses within its lower-margin commercial segment.
Medical: exited, and the exit is the lesson
The radiopharmaceutical expansion vector has been converted into upfront cash and a retained minority stake.28 What remains of BWXT's medical exposure is the Isogen joint venture with Framatome providing isotope irradiation services through Bruce Power, alongside specialized manufacturing services supplied to the divested unit.18 Financial models should treat the transaction as removing roughly $130 million of 2026 commercial revenue from reported sales and reclassifying future net contributions as equity income.18
Underpinning these commercial vectors is the broader narrative of growing electricity demand from artificial intelligence data centers. While data center demand is driving renewed commercial interest in nuclear power, BWXT does not sell electricity, operate utility plants, or execute power purchase agreements. The company supplies specialized heavy components to whichever reactor developers secure utility contracts. This posture offers a lower-beta, lower-ceiling approach to participating in commercial nuclear growth—a focused role that management deliberately selected following its experience with the mPower initiative.
XI. Playbook & Investment Lessons
Four transferable lessons emerge from BWXT's operational record.
Regulatory moats are the most durable moats, and the least generous. Category I nuclear fuel licenses represent as close to a legal monopoly as an industrial enterprise can hold. Yet that position delivers extraordinary stability rather than pricing power. Two decades as a sole supplier have yielded defense segment margins that fluctuate tightly within a two-percentage-point band. Investors who buy regulatory moats expecting expanding margins misinterpret the property: they are buying a low probability of profit collapse, not pricing power. Long-term returns depend on volume expansion and valuation multiples, not margin expansion.
A monopoly selling to a monopsony earns its returns through execution, not leverage. Under Federal Acquisition Regulation rules and audit oversight, cost bases are audited and contract fees remain capped. What BWXT can control is executing to schedule and beating internal cost targets. Under cost-plus accounting mechanics, operational efficiency reduces reported top-line revenue while expanding operating margin—an outcome that can look like a revenue miss to superficial analysis. Grasping that accounting inversion is an essential analytical requirement for evaluating the company.
Spin-offs reveal value; they do not create it. The 2015 separation made a high-barrier defense supplier transparent while isolating its cash flows from a declining fossil-fuel boiler division. The transaction highlighted pre-existing franchise quality rather than improving nuclear operations. Corporate spin-offs generate the greatest value when two businesses serve distinct customers, operate on different capital cycles, and address separate markets—not when executed as a substitute for operational turnarounds.
Certification is not commercialization, and this company has proved it twice. The mPower program cleared technical milestones without securing a commercial customer. The medical isotope unit submitted a New Drug Application in 2022 and was divested in 2026. The DRACO space propulsion project ended when customer priorities shifted, not from hardware failure. Technical achievements, government awards, and test milestones demonstrate engineering capability, not commercial demand. The most reliable growth vector remains the area where BWXT generates demonstrated commercial revenue: high-precision component and fuel manufacturing for third-party reactor designs.
The broader operational takeaway is that executive leadership appears to have adapted to this historical record. Licensing mPower to a third-party developer, divesting the medical isotope business, and positioning the company as a merchant equipment manufacturer rather than a plant owner reflect an explicit focus on core fabrication strengths. That strategic discipline is reflected in portfolio reallocation rather than promotional claims.
XII. Valuation, Key KPIs & Bull vs. Bear Case
What the market is paying
At $152.29 per share, BWXT trades at roughly 39 times trailing earnings and 30 times forward earnings, with a dividend yield near 0.7%.3 Based on full-year 2026 adjusted EBITDA guidance of $662 million to $672 million, its enterprise value stands at approximately 23 times.184
The valuation contrast with defense peers is sharp. Huntington Ingalls—the primary shipbuilder for U.S. nuclear submarines and aircraft carriers—trades near 17 times earnings with a market capitalization of roughly $11.5 billion, valuing the reactor supplier above the shipbuilder that integrates its hardware.47 General Dynamics, whose Electric Boat division constructs the remaining portion of the nuclear submarine fleet, trades at a similarly modest earnings multiple.4
That valuation premium reflects the market's consensus that BWXT's sole-source defense positioning offers superior earnings stability and commercial optionality compared to shipbuilders. However, that valuation multiple has compressed significantly: the stock has dropped nearly 37% from its 52-week high even as management raised full-year operating guidance twice.31829 The market is not reducing current earnings expectations; it is reassessing the valuation multiple assigned to commercial nuclear growth.
The three KPIs that matter
Three primary operational metrics frame the investment outlook:
1. Government Operations adjusted EBITDA margin. Profitability, rather than reported revenue, serves as the most reliable indicator of execution because cost-plus accounting mechanics can reduce reported top-line figures when cost efficiency improves. Investors should track the 19% to 21% operating band. Sustained performance below this threshold would indicate execution challenges on fixed-price contracts or tighter customer fee negotiations.
2. Firm commercial nuclear equipment orders. Evaluating commercial expansion requires tracking binding, fully funded contracts from utilities, small modular reactor developers, or reactor manufacturers, rather than non-binding letters of intent or policy frameworks. Management publicly projected at least one binding commercial order by the end of 2026.18 This contract milestone will determine whether capital deployed across U.S. and Canadian facilities generates adequate returns, serving as the practical test that the earlier mPower program failed to pass.
3. Consolidated free cash flow conversion. Full-year 2026 free cash flow is guided to between $345 million and $360 million against rising capital expenditures reaching 6% to 7% of revenue.18 As the company integrates acquisitions, evaluates site expansion, and allocates proceeds from the medical unit sale, cash conversion provides the primary measure of balance sheet discipline. The drop in free cash flow below $50 million in 2022 illustrates how rapidly capital outlays and working capital requirements can compress cash generation.4
The bull case
Naval propulsion demand is supported by a 30-year U.S. Navy shipbuilding plan targeting three nuclear submarines annually alongside a four-year aircraft carrier procurement cadence, backed by an $8.4 billion backlog and a book-to-bill ratio of 1.7 times.1835 Simultaneously, federal awards in enrichment pilot programs, defense fuels, and high-purity depleted uranium processing position the company to serve as the sole domestic supplier across expanded nuclear material categories, widening its regulatory moat.323334 In commercial markets, expanding electricity demand from data centers and grid modernization is driving renewed interest in nuclear power, where BWXT represents one of few Western fabricators possessing the required regulatory licenses, quality certifications, and heavy manufacturing infrastructure. Furthermore, management has transitioned to a merchant equipment supplier model, eliminating the proprietary plant design and off-take risks that led to the termination of the mPower project, while recent share price declines have reduced valuation multiples.
The bear case
Core defense growth remains tied to federal defense appropriations, leaving revenue vulnerable to budget sequestration, continuing resolutions, or shipbuilding delays. Production bottlenecks at primary shipbuilders—Electric Boat and Huntington Ingalls—can defer component delivery schedules, as demonstrated by the May 2026 AUKUS revision substituting existing hulls for new submarine construction.45 On the commercial side, rapid top-line growth is occurring in a segment earning margins roughly seven percentage points below Government Operations, with management reducing the 2026 Commercial margin outlook to approximately 13% to fund expansion outlays, making near-term revenue mix dilutive to consolidated profitability.18 Additionally, fixed-price-incentive defense contracts carry margin risk during periods of specialized labor inflation, while utility component orders remain contingent on finalized government-backed financing frameworks.18 Even after recent share price declines, the stock commands a premium valuation relative to major defense contractors.
From a critical governance perspective, three operational risks require monitoring: consolidated return on invested capital remains in the high single digits following recent acquisitions; proceeds from the medical unit sale lack a committed capital allocation plan; and the executive suite has experienced notable turnover within a twelve-month span, including the chief financial officer, Government Operations president, and chief nuclear officer during a major capital deployment cycle.4182022
Synthesis. BWXT maintains a highly defensible defense franchise growing in tandem with federal defense budgets, while deploying cash flows to establish a presence in competitive commercial nuclear supply chains. Its regulatory moat is substantial but strictly bounded to naval fuel and government material processing. Commercial expansion offers real growth potential, balanced against a historical record of commercial development challenges. At current valuation levels, the stock reflects expectations that ongoing capital investments will successfully yield long-term commercial returns.
XIII. Recent News & Developments
The last eighteen months have been the busiest stretch of BWXT's independent history, and the sequence tells its own story.
Records, then a de-rating. The company closed 2025 with record results, posting $3.2 billion in revenue—an 18% increase year over year—along with non-GAAP earnings of $4.01 per share and a 16% gain in free cash flow.1 Bookings reached $5.4 billion, expanding total backlog by 50% to $7.3 billion.2 Management initially projected 2026 adjusted EBITDA of $645 million to $660 million and non-GAAP earnings of $4.55 to $4.70 per share, before raising guidance in May and again in August.229 Full-year outlooks currently stand at roughly $3.8 billion in revenue, $662 million to $672 million in adjusted EBITDA, $4.70 to $4.80 in non-GAAP earnings per share, and $345 million to $360 million in free cash flow.18 Yet despite two consecutive guidance increases, the stock dropped to within a few dollars of its 52-week low.3
The government contract wave. Defense momentum expanded across multiple major awards, beginning with $2.1 billion in naval component contracts in February 2025, followed by another $2.6 billion in July 2025.4344 In September 2025, the company secured a $1.5 billion NNSA defense fuels award alongside a $1.6 billion contract for the Jonesborough depleted uranium facility.3233 Meanwhile, work advanced on the DUECE enrichment pilot, where management confirmed plans to deliver an operational prototype centrifuge during 2026.3018 Site preparation at Jonesborough is currently underway, with management expecting the facility to contribute meaningfully to Government Operations revenue in the second half of the year.18
Portfolio reshaping. Corporate restructuring accelerated through major acquisitions and divestitures: the acquisition of Kinectrics closed in May 2025, followed by Precision Components Group on July 1, 2026, while an agreement to sell the medical division to Nordic Capital for up to $800 million was reached on August 3, 2026.252728 That same week, BWXT executed an exclusive land-based licensing agreement for mPower with Applied Atomics—under which Applied Atomics will lead and fund design completion and NRC licensing while BWXT retains intellectual property, manufacturing rights, and royalties—alongside a feasibility study with Core Power for floating nuclear platforms.18
Advanced nuclear milestones. Technical execution yielded tangible hardware progress, marked by the delivery of the complete TRISO fuel core for Project Pele in late 2025, followed by the Antares Mark-0 reactor achieving criticality in June 2026 using BWXT-supplied fuel.4118
What to watch next. Management has scheduled an investor day for September 2026, where Chief Executive Officer Rex Geveden noted he plans to detail long-term growth prospects.18 Coming after twelve months marked by two guidance raises, a major divestiture, strategic acquisitions, licensing agreements, and a reshaped commercial strategy—all set against a stock price that has surrendered more than a third of its value—the event presents management with an opportunity to demonstrate that capital deployed into commercial capacity will generate expected returns. Beyond overall growth targets, the key test will be whether the firm commercial equipment orders predicted for the second half of the year have begun to materialize.
References
-
BWX Technologies Reports Fourth Quarter and Full Year 2025 Results, Initiates 2026 Guidance — BWX Technologies, 2026-02-23 ↩↩↩↩
-
BWX Technologies Reports Fourth Quarter and Full Year 2025 Results — StockTitan, 2026-02-23 ↩↩↩↩↩↩↩↩↩
-
BWX Technologies (BWXT) Stock Price & Overview — Stock Analysis, 2026-08-31 ↩↩↩↩↩
-
BWXT Form 10-K for Fiscal Year Ended December 31, 2025 — SEC EDGAR, 2026-02-23 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Backgrounder on the Three Mile Island Accident — U.S. Nuclear Regulatory Commission ↩
-
First new U.S. nuclear reactor since 2016 is now in operation — U.S. Energy Information Administration, 2023 ↩
-
Fuel Cycle Development for Advanced Nuclear Reactors — National Academies of Sciences, Engineering, and Medicine ↩↩
-
Nuclear Fuel Services, Erwin, Tennessee — U.S. Nuclear Regulatory Commission ↩
-
B&W to Acquire Nuclear Fuel Services — Business Wire, 2008-08-11 ↩
-
McDermott International Form 8-K, B&W Chapter 11 Emergence and Asbestos Settlement Trust — SEC EDGAR, 2006-02-22 ↩↩
-
B&W completes $1.0 billion spin-off of Power Generation business — Jones Day, 2015-07 ↩↩
-
Bechtel pulls out of SMR development — Nuclear Engineering International, 2017 ↩
-
mPower Consortium Halts Project — American Nuclear Society, 2017 ↩↩
-
Bechtel, BWXT end modular reactor project — The Chemical Engineer, 2017 ↩
-
Earnings call transcript: BWX Technologies Q2 2026 — Investing.com, 2026-08-03 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
BWXT Names Mike Fitzgerald as Chief Financial Officer — GovCon Wire, 2025 ↩
-
BWXT Announces Leadership Changes — BWX Technologies, 2025-06-16 ↩↩
-
BWXT Bolsters American Nuclear Manufacturing Capability With Strategic Acquisition — BWX Technologies, 2026 ↩
-
BWXT to acquire Kinectrics in "complementary" $525M deal — American Nuclear Society, 2025-01-08 ↩
-
BWXT Closes Acquisition of Kinectrics — BWX Technologies, 2025-05-21 ↩↩
-
BWX Technologies to acquire Precision Components Group — Investing.com, 2026-04-20 ↩
-
BWXT Completes Acquisition of Precision Components Group, Expanding U.S. Nuclear Manufacturing Capacity — BWX Technologies, 2026-07-06 ↩↩↩
-
BWXT Selling Medical Business to Nordic Capital in Transaction Valued at up to $800 Million — BWX Technologies, 2026-08-03 ↩↩↩↩↩
-
BWX Technologies Reports First Quarter 2026 Results — BWX Technologies, 2026-05-04 ↩↩↩↩↩
-
NNSA selects BWXT for DUECE Pilot Plant Award — U.S. Department of Energy, NNSA ↩↩
-
BWXT acquires Oak Ridge site as NNSA pursues unobligated enriched uranium — American Nuclear Society, 2025-04-18 ↩
-
NNSA awards BWXT $1.5B defense fuels contract — American Nuclear Society, 2025-09-17 ↩↩↩
-
BWXT Awarded Contract to Produce High Purity Depleted Uranium for National Defense Purposes — BWX Technologies, 2025-09-30 ↩↩↩
-
NNSA Issues Award for High Purity Depleted Uranium Production — U.S. Department of Energy, NNSA, 2025-09-30 ↩↩
-
New Navy Shipbuilding Plan: Trump-class Battleship Will Be Nuclear-Powered, Carrier Design Under Review — USNI News, 2026-05-11 ↩↩↩
-
DARPA says decreasing launch costs, new analysis led it to cancel DRACO nuclear propulsion project — SpaceNews, 2025 ↩↩↩
-
DRACO project cancelled — Nuclear Engineering International, 2025 ↩↩
-
BWXT Medical Submits Tc-99m Generator New Drug Application to FDA — BWX Technologies, 2022-09-13 ↩
-
GE Hitachi awards contract for BWRX-300 reactor pressure vessel to BWXT — GE Vernova, 2025-01-27 ↩↩
-
BWXT Awarded Historic Manufacturing Contracts to Support Pickering Life Extension and Darlington New Build Projects — BWX Technologies, 2025-01-27 ↩↩
-
BWXT Delivers Full Core of TRISO Nuclear Fuel for Project Pele Microreactor — BWX Technologies, 2025-12-02 ↩↩↩↩
-
INL advances Department of War's Project Pele demonstration microreactor with first TRISO fuel delivery — Idaho National Laboratory, 2025 ↩↩
-
BWXT Announces $2.1 Billion in Contracts for Naval Nuclear Reactor Components — BWX Technologies, 2025-02-19 ↩↩
-
BWXT Announces $2.6 Billion in Contracts for Naval Nuclear Reactor Components — BWX Technologies, 2025-07-17 ↩↩
-
U.S. Will Sell 3 In-service Virginia Subs to Australia Instead of 1 New, 2 In-service — USNI News, 2026-06-01 ↩↩
-
Pentagon awards $276m submarine contract in first for AUKUS pact — ABC News, 2026-04-24 ↩
-
Huntington Ingalls Industries (HII) Stock Price & Overview — Stock Analysis, 2026-08-31 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube