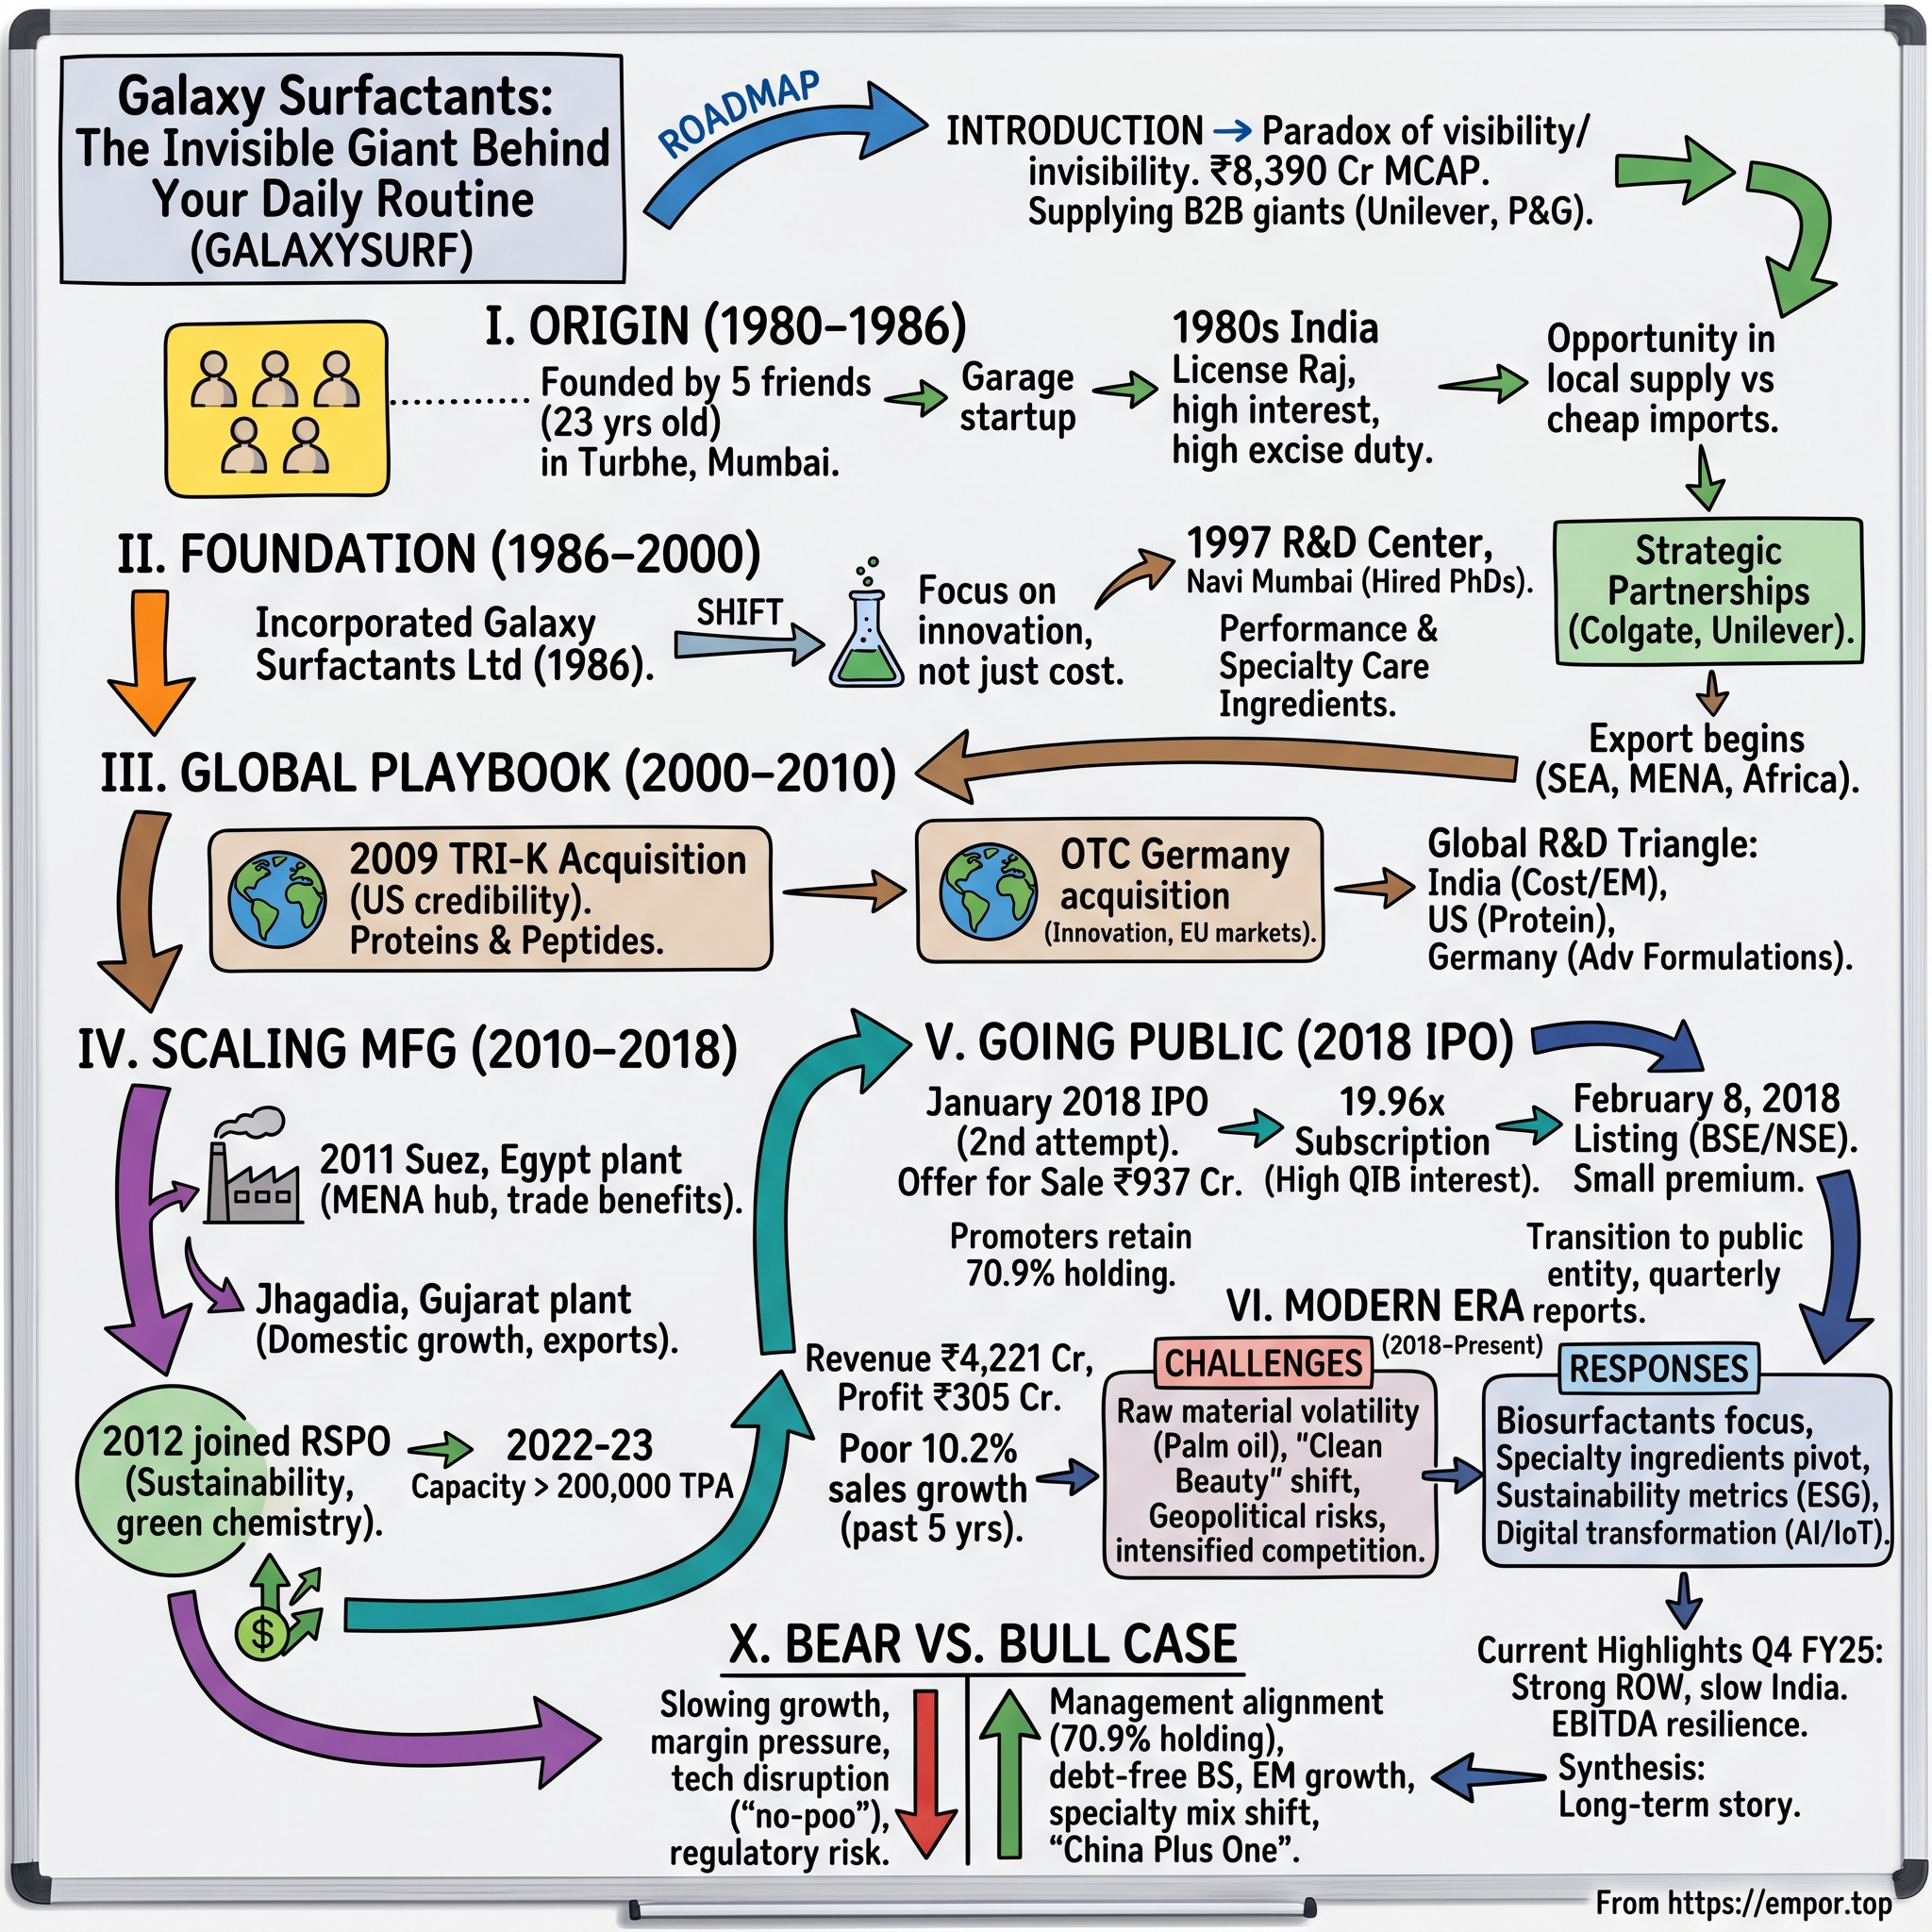
Galaxy Surfactants: The Invisible Giant Behind Your Daily Routine
I. Introduction & Episode Roadmap
The Foam Nobody Thinks About
At 6:45 a.m. in Mumbai, Cairo, São Paulo, or New Jersey, someone squeezes toothpaste onto a brush, and within seconds the paste turns into a rich white foam. A few minutes later, shampoo lathers in the shower and hand wash bubbles at the sink. Rarely does anyone stop to wonder where that lather comes from. It feels like an inherent property of the product itself, as natural as water being wet.
It is not natural. That foam is engineered, molecule by molecule, by a small group of specialty chemical producers consumers never see. One of the most critical suppliers to global home and personal care brands operates out of an unglamorous industrial belt north of Mumbai: Galaxy Surfactants (NSE: GALAXYSURF).
The Invisible Supplier
By March 2026, Galaxy offered more than 215 product grades manufactured across seven sites: five in India, one in Egypt, and one in the United States. It served more than 1,500 customers in over 95 countries.1 Its customer list reads like an index of global consumer conglomerates. CRISIL's 2011 IPO grading document named Beiersdorf, Colgate-Palmolive, Henkel, L'Oréal, Reckitt Benckiser, Unilever, P&G, Dabur, Marico, ITC and CavinKare among its buyers.2 In August 2026, Unilever described its relationship with Galaxy as a 45-year partnership.3
Yet the company's financial footprint remains modest next to the multinational brands it supplies. In FY26, total revenue was about ₹5,270 crore and EBITDA was about ₹497 crore.1 In mid-August 2026, after a record quarter, Galaxy's market value was roughly ₹8,900 crore.4 That positions it as a mid-cap intermediate processor whose ingredients end up in consumer portfolios worth hundreds of times more.
Two Businesses Under One Roof
Galaxy reports its operations across two distinct segments:
Performance Surfactants are the high-volume cleaning and foaming workhorses, primarily commodity-scale chemistries such as sodium lauryl sulfate (SLS) and sodium lauryl ether sulfate (SLES). In FY26 they made up about ₹3,341 crore of revenue across 47-plus grades.1
Specialty Care Products cover higher-complexity chemistry: mild surfactants, preservatives, UV filters, conditioning agents, and cosmetic proteins. That segment had 168-plus grades and brought in about ₹1,930 crore in FY26, or roughly 37% of revenue.1
The Central Question
The origin narrative is straightforward: in 1979, five professionals in their early twenties with no family business backing started in a borrowed laboratory. Over the ensuing decades, they built an enterprise that competes with multinational giants such as BASF, Stepan, and Clariant for mandates from Unilever and Colgate. For investors, however, the critical question is not whether Galaxy survived—it clearly did. The central question is what type of economic engine it ultimately became.
Is Galaxy a genuine specialty chemical compounder whose pricing power expands over time? Or is it an exceptionally well-run conversion processor: disciplined, trusted, and operationally sticky, but with margins structurally bounded by powerful buyers? The company's own financial record points more toward the conversion model than its admirers often acknowledge, and this story tests that record claim by claim.
Why the Story Matters Now
Galaxy looked very different at the start of September 2026 than it had a year earlier. In FY26, US tariffs, Indian tax changes, and customer reformulations left volumes flat and profit lower. Then, within about three weeks in August 2026, Galaxy reported the most profitable quarter in its history, its largest customer signed a formal growth charter with it, and BASF, one of its best-funded competitors, announced it would close its Indian sulfation plant.536 Rapid shifts like these can distort market expectations. The objective here is to separate what those catalysts reveal about the enduring business from what they reveal about one unusual operating year.
The Road Map
The investigation unfolds in seven stages. It begins with the 1979 founding and the formative partnership with Colgate. Next comes an analysis of the underlying chemistry and unit economics, explaining how a commodity-linked business can generate steady absolute returns. It then examines Galaxy's international expansion: the acquisition of TRI-K in the United States and the capital allocation behind its manufacturing hub in Egypt.
From there, the story reviews the capital-market history, comparing the aborted 2011 IPO to the successful 2018 listing. The concluding sections evaluate Galaxy's competitive positioning, test the core bull claims against historical operating data, and dissect the West Asian supply shocks of 2026 that temporarily inverted the economics of the entire surfactant industry for a single quarter.
The narrative starts at the beginning: Valentine's Day in 1979, when five young professionals decided to leave safe corporate jobs.
 Subscribe on LinkedIn
II. The Origin Story: Five 23-Year-Olds and the Colgate Crucible (1980–1995)
A Pact Over Tea
Galaxy's official corporate history traces its beginning to a precise date: five friends "united by one shared dream on 14 February 1979."7 The founders—Unnathan Shekhar, Geera (Gopalkrishnan) Ramakrishnan, Shashikant Shanbhag, C.R. Ramakrishna, and Sudhir Patil—were roughly 23 years old, came from middle-class backgrounds, and possessed little starting capital beyond their technical education.8 They gathered over cups of tea to debate what kind of enterprise they could build together.
Their professional backgrounds shaped the company's trajectory. Shekhar was a chemical engineer from Mumbai's University Department of Chemical Technology (UDCT) who held a postgraduate management diploma from IIM Calcutta and had worked at Hindustan Unilever and Lupin.2 Patil was also a UDCT-trained chemical engineer and an HUL alumnus. Ramakrishnan and Shanbhag were finance professionals who had worked at Colgate-Palmolive India.2 Together, the group understood how multinational consumer-goods companies evaluated, tested, and procured raw ingredients.
"Why Don't You Make SLES?"
The founders secured their initial opening through that corporate network. When the team visited Colgate-Palmolive India's manufacturing head, he asked why they did not produce sodium lauryl ether sulfate (SLES)—a foaming agent Colgate required—noting that setting up production would demand relatively little capital.8 A 2024 report by YES Securities offered a slightly different version of the initial spark, recounting that Colgate needed sodium lauryl sulfate (SLS) for toothpaste, Shekhar immersed himself in the chemistry, and the team's trial batch earned approval from both HUL and Colgate.9 Regardless of which surfactant led the way, the core dynamic was established: the customer defined the specification, and Galaxy engineered the process to satisfy it.
Each founder contributed ₹20,000, secured bank loans, and began manufacturing batches in an acquaintance's laboratory in Ghatkopar, Mumbai.8 Their first dedicated facility commenced operations on June 22, 1980,7 with an initial annual capacity of approximately 30 tonnes.8 For scale, CRISIL placed Galaxy's total manufacturing capacity at roughly 4.42 lakh tonnes—around 442,000 tonnes—per year by 2025.10
Building in the License Raj
Launching a chemical manufacturing business in India in 1980 without an established industrial family's backing was a formidable undertaking. Stringent industrial licensing, import restrictions, and rationed bank credit favored established domestic conglomerates. At the same time, high import tariffs on raw materials gave multinational consumer firms operating in India a compelling reason to identify local suppliers capable of matching global quality benchmarks. Galaxy positioned itself squarely in that gap, offering international brand owners a domestic manufacturing partner that operated to global standards.
The founders also established an enduring division of executive responsibility. By 2011, CRISIL noted that Shekhar served as Managing Director, Ramakrishnan and Shanbhag as whole-time directors, and Patil as a non-executive director. A sixth long-serving executive, chartered accountant Uday Krishna Kamat, served as a whole-time director and sat on the boards of Galaxy's Mauritius holding company, its Egyptian subsidiary, and TRI-K.2 Pairing chemical engineers with finance professionals proved durable for a business whose economic viability depended on converting volatile petrochemical and oleochemical feedstocks at predictable processing spreads.
Early growth was deliberate and demanding. YES Securities characterized Galaxy's initial era as one of "slow progress and modest profits."9 Between 1981 and 1986, the company entered personal-care ingredients and established a manufacturing plant at Tarapur to produce ethoxylates and sunscreen formulations.7 The present publicly traded entity was formally incorporated in 1986, as reflected in its corporate identity number.1
The Apprenticeship
Supplying institutional customers such as Colgate and Unilever imposed rigorous manufacturing discipline. For personal-care and oral-care formulations, active ingredient specifications admit virtually no batch-to-batch variation. Color, odor, trace impurities, and foaming performance must remain tightly bounded, because brand owners bear the full reputational and recall risk of a defective formulation. By 2011, CRISIL recorded that Galaxy had become a certified preferred supplier of SLS to Colgate-Palmolive India and an approved SLES supplier to Hindustan Unilever, which had recognized the company with a long-term association award.2
Subsequent capital investments reflected this focus on manufacturing scale and quality control. In 1995, the founders mobilized funds through personal networks to finance a new production site at Taloja, Maharashtra.9 By 1997–98, the Taloja complex housed an operating sulfonation plant,7 which YES Securities later described as having expanded into one of India's largest sulfation facilities.9
A Granule That Mattered
An early product refinement illustrated Galaxy's shop-floor engineering culture. SLS was traditionally supplied in either needle or fine-powder form. Needles were technically difficult to extrude efficiently, while fine powder generated airborne dust that created respiratory and handling hazards in customer factories. Galaxy engineered a technique to produce SLS as free-flowing, dust-free granules, delivering substantial processing and cost efficiencies.9 A mechanical form innovation of this type rarely commands headlines, but practical process improvements make an intermediate supplier deeply entrenched in a brand owner's manufacturing workflow.
The underlying sulfonation chemistry is inherently demanding. Sulfur trioxide gas reacts with fatty alcohol inside a thin-film reactor tube, generating an intense exothermic reaction almost instantaneously. If temperatures fluctuate or residence times vary by even seconds, the product discolors into a degraded, off-spec batch. Operating that reaction reliably at scale over decades builds genuine institutional expertise. Yet it is also a technical capability that well-capitalized global rivals can replicate, creating the underlying tension in Galaxy's business model.
Galaxy's foundational era established its defining competitive trait: it was built from inception around the strict technical and quality tolerances of the world's most demanding consumer-goods conglomerates. To see how that operational discipline generated commercial returns, the next step is examining the underlying chemistry and unit economics.
III. Chemistry & Unit Economics: Why This "Unsexy" Business Is Extraordinary (1995–2005)
A Molecule With Two Personalities
A surfactant—short for "surface active agent"—is a molecule engineered with two distinct ends that behave differently. One end is hydrophilic, naturally attracted to water. The other end is lipophilic, repelling water to bond with oil, grease, and grime. In practical terms, these molecules function like a swarm of microscopic tugboats: the oily tail anchors into a grease stain, while the water-loving head gets pulled along by the rinse stream. Foaming, dirt removal, and the effortless glide of shampoo through hair all arise from that molecular tug-of-war.
In its 2011 IPO grading report, CRISIL categorized Galaxy's portfolio into four primary functional groups: anionic surfactants for rich foaming and deep cleaning, nonionics for cosmetics and liquid detergents, cationics for fabric and hair conditioning, and amphoterics that temper formulation harshness to reduce skin irritation.2 Most consumer formulations sitting on supermarket personal-care shelves rely on an engineered combination of these four chemistry types.
The Oleochemical Chain
The vast majority of Galaxy's product line relies on oleochemicals, meaning its processes start with natural plant fats and oils rather than crude petroleum.9 Palm kernel oil or coconut oil is cracked and distilled into fatty alcohols, predominantly lauryl alcohol, a 12-to-14-carbon chain. Sulfating that alcohol with sulfur trioxide produces SLS. Inserting ethylene oxide into the chain through ethoxylation prior to sulfation yields SLES, a milder, highly versatile ingredient that serves as the workhorse cleansing base for modern shampoos.
Feedstock constitutes Galaxy's single largest operating cost, with lauryl alcohol alone representing roughly 60% of its total raw-material procurement.9 Because its supply chain begins in tropical plantations, its price moves with vegetable oils, which in turn correlate with petroleum benchmarks due to biofuel blending mandates. During an earnings call in August 2026, Managing Director K. Natarajan outlined this chain of dependencies: palm kernel oil prices dictate fatty alcohol costs, the broader palm oil market governs palm kernel oil, and crude oil benchmarks sway palm through global biodiesel mandates.5
Why Revenue Misleads
Because volatile feedstocks dominate the cost base, headline revenue offers an unreliable window into Galaxy's underlying performance. Most customer arrangements operate on formula-based pass-through pricing. YES Securities estimated that the company historically recovered roughly 80% to 90% of raw-material price swings, typically with a lag of one to two quarters.9 Supply contracts usually run three to nine months, though during the pandemic pricing windows were compressed to one or two months to track extreme feedstock swings more closely.9
This pricing structure regularly produces financial optical illusions. In the third quarter of FY26, Galaxy's revenue jumped roughly 28% year on year, even as consolidated shipping volumes remained completely flat.1112 For the full 2026 fiscal year, revenue rose 24% while EBITDA fell 2.5% and profit after tax dropped 12%.1 An investor evaluating the company solely by top-line growth would have perceived robust commercial expansion during a year when operating profits were actively contracting.
The North Star: EBITDA per Tonne
For this reason, both management and institutional analysts judge operating performance by EBITDA per metric tonne: the operating cash spread generated on each physical unit shipped. This metric effectively neutralizes raw-material swings. A metric tonne of SLES yields roughly the same processing margin whether lauryl alcohol trades at $1,500 or $3,000 per tonne. Functioning much like a toll operator collecting a fee per passing vehicle regardless of the cargo's value, the metric reveals whether Galaxy is extracting more or less economic value for its conversion work.
The arithmetic illustrates why the distinction is vital. If fatty alcohol prices double over twelve months and Galaxy passes the entire cost increase along to consumer brands, revenue per tonne climbs sharply. Reported EBITDA margins as a percentage of sales appear to collapse because the revenue denominator is inflated, even though Galaxy earns the exact same rupees on every physical tonne. Conversely, when feedstock prices drop by half, reported margin percentages artificially widen while cash generation per tonne stays flat. Tracking percentage margins can easily lead to false conclusions about operational health, whereas tracking EBITDA per tonne keeps the underlying processing spread clear.
The pass-through mechanism, however, is not completely frictionless: timing lags create quarterly volatility. On the fourth-quarter FY26 earnings call, Natarajan was candid about these limits, noting that Galaxy cannot adjust prices every week because consumer multinationals demand budget predictability, conceding, "I will have a lag effect."13 During rapid feedstock run-ups, unit spreads compress for a quarter or two until contract resets take effect. When commodity costs drop rapidly, Galaxy temporarily retains a wider spread before prices adjust downward. The toll remains resilient over a full cycle, but fluctuates from quarter to quarter.
From Recipe-Follower to Recipe-Writer
Alongside expanding plant capacity, a second structural transformation occurred in the laboratory. Galaxy established a dedicated research and development center in Navi Mumbai around 1997–98.7 According to CRISIL, the company integrated its R&D directly into the product-development cycles of its multinational buyers, evolving from an order taker into a collaborative partner that actively suggested formulation refinements; it simultaneously developed proprietary blends to sell directly to regional and local personal-care brands.2 By early 2011, Galaxy had secured 18 patents in India and 10 in the United States, with additional applications pending.2
The Pre-IPO Scorecard
Galaxy's 2011 IPO filings provide an early window into the unit-economics blueprint that would define the company for the next decade and a half. Between FY08 and FY10, consolidated revenue compounded at approximately 29.8% annually to reach ₹644 crore. CRISIL separated that growth into an underlying 18.7% compound annual volume expansion and an 11.1% contribution from higher price realization.2 Across those three fiscal years, EBITDA margins held steady in a tight corridor of 13.6%, 12.2%, and 12.6%, while return on equity remained between 26% and 32%.2 Surfactants—classified as organic surface-active agents—still generated nearly 85% of standalone revenue in FY10, while specialty care products accounted for about 10.5%.2
These early audited metrics confirmed that Galaxy's margin range was already established well before its shares listed publicly. When feedstock costs eased, percentage margins widened modestly; when foreign-exchange losses struck—as in FY09 during the global financial crisis—net earnings declined even as factory floors operated at full tilt. Galaxy grew primarily by processing and shipping more physical volume, not by extracting ever-higher processing fees per tonne.
That economic reality dictated its commercial strategy. Multinational accounts brought high production volumes and technical validation, but negotiated disciplined processing spreads. Smaller regional and local brands, lacking in-house chemistry labs, purchased Galaxy's higher-margin formulated blends. As production scale mounted, the critical strategic challenge was whether this India-tested toll-manufacturing model could succeed across international borders.
IV. The Global Expansion Playbook: TRI-K, Germany, & The Egypt Gamble (2005–2015)
A Small Deal in New Jersey
In July 2009, while the global economy was still reeling from the financial crisis, Galaxy completed its acquisition of TRI-K Industries.14 Based in New Jersey, TRI-K was a distributor and manufacturer of specialty cosmetic ingredients with more than 30 years in the industry, a protein manufacturing plant in New Hampshire, roughly 40 employees, and an affiliate named Maybrook.14 Geera Ramakrishnan, then Galaxy's director of home and personal care, remarked that the transaction "strengthens Galaxy's global presence."14
The acquisition was financially modest. CRISIL reported that Galaxy paid approximately $5 million.2 Yet the strategic assets Galaxy acquired were far more consequential than the purchase price implied: protein chemistry for hair and skin care, a distribution platform for high-end ingredients, a technical marketing team, and direct access to American formulators.2 As part of the same transaction, Galaxy acquired a majority stake in the Oberhausen Technology Center (OTC), a personal-care R&D facility in Germany, while Dr. Gerd Dahms & Associates retained a minority holding.14
What TRI-K Became
Seventeen years later, TRI-K remains modest in physical output. Its New Hampshire plant has an annual capacity of about 600 tonnes focused on specialty proteins.9 Nevertheless, the unit features prominently in management's commentary. On the Q4 FY26 earnings call, Natarajan cited the "consistent better performance of our TRI-K business," describing it as the group's premium specialty segment that supported overall margins.13 In August 2026, he noted that a new TRI-K ingredient named Everbond was "showing very significant momentum" and had begun "contributing meaningfully" to the subsidiary's revenue.5
The evidence, however, supports a narrower conclusion than a transformational acquisition. TRI-K provided a cost-effective route to acquire specialized capabilities and direct customer relationships, and the asset has endured. Yet Galaxy does not disclose TRI-K's profitability separately in its public reporting, making claims of strong margin accretion impossible to verify independently. Meanwhile, the German research center, OTC, was not discussed during the FY26 or Q1 FY27 earnings calls, leaving its commercial contribution unclear.
The Big Bet: Suez
While TRI-K cost only a few million dollars, Egypt represented a vastly larger capital commitment. In its 2011 IPO filings, Galaxy earmarked approximately ₹212 crore for capital expenditure at its Egyptian subsidiary and another ₹70 crore for a new manufacturing facility at Jhagadia in Gujarat.2 The Egyptian facility was planned across two phases—initially 50,000 tonnes followed by 40,000 tonnes—with commercial production targeted for August 2011.2 Jhagadia was slated for 77,000 tonnes, as Galaxy sought to more than double its total manufacturing capacity from roughly 155,000 tonnes to 348,000 tonnes.2
On paper, the strategic rationale was compelling. Located in a public free zone, the plant was exempt from direct and indirect taxes aside from a 1% duty on value added, according to CRISIL.2 Operating out of Suez placed Galaxy adjacent to high-growth markets across Africa, the Middle East, and Turkey (the AMET region), while shortening shipping lanes to Europe compared to sailing from Mumbai. Shifting export manufacturing to Egypt would also free up capacity at Taloja to serve expanding Indian demand.2 Today, the Egyptian subsidiary operates in the Attaqa Public Free Zone with roughly 117,500 tonnes of annual capacity and more than 400 employees.9
Jhagadia proved to be the quieter, more dependable success of that capital cycle. The Gujarat facility now possesses approximately 132,750 tonnes of capacity, sits adjacent to a dedicated source of ethylene oxide, and holds environmental clearances for future expansion.9 Because ethylene oxide is volatile and hazardous to transport, co-locating with a primary supplier confers a durable operational advantage that competitors struggle to duplicate. Capital spending continued in subsequent years, peaking at approximately ₹168 crore in FY19—when Galaxy acquired land in the United States for TRI-K and expanded Jhagadia—before moderating to an annual run rate of about ₹155 crore between FY22 and FY24.9
Testing the Egypt Thesis
The foundational thesis behind the Suez project was that it would provide Galaxy with an enduring cost and geographic advantage across the AMET region. Yet external conditions challenged the investment almost immediately. The political uprising that toppled Hosni Mubarak erupted in early 2011, precisely as the facility was under construction and Galaxy was seeking public capital to fund it.
The more enduring damage, however, stemmed from macroeconomic headwinds rather than political unrest. YES Securities highlighted what it termed "the Egypt conundrum": severe inflation, currency depreciation estimated by the brokerage at 100%, and domestic interest rates exceeding 28%.9 This macroeconomic squeeze forced Egyptian consumers toward lower-priced local brands and away from the multinational portfolios that Galaxy supplied.9 During the Q4 FY26 earnings call, an analyst from ICICI Securities pointed out that Galaxy's AMET shipping volumes had dropped from a peak of roughly 90,000 tonnes annually to around 60,000 tonnes. Natarajan attributed the decline to "local players backward integrated taking the market share," while "all the global customers who are our customers" lost ground.13
His assessment of regional dynamics was straightforward: "The better place is a local player."13 By August 2026, he ruled out any further acquisitions in the AMET region, stating, "There's no plan that we have there at all."5 Management treated the realignment in end-market share as structural and permanent: "what has changed has changed."5
Geopolitical shocks created additional operational friction. In March 2026, the Suez plant sat idle for most of the month after raw-material shipments were stranded at regional transshipment hubs.13 Supply-chain bottlenecks persisted into the following fiscal year, with the facility losing approximately seven weeks of operating time in Q1 FY27 due to similar transshipment delays.5
The Verdict on Egypt
This operating history substantially narrows the investment case for Egypt. The facility retains meaningful operational benefits: YES Securities pointed to tax exemptions projected to last another 10 to 12 years, and Galaxy redirected export volumes through Egypt in 2025 to bypass US tariffs on Indian chemical imports.915 Yet the primary strategic rationale—that Suez would serve as a self-sustaining growth engine for the broader AMET region—has not materialized. Regional shipping volumes remain roughly a third below their historical peak, a shortfall management frames as an irreversible structural shift toward local brand owners rather than a passing cyclical dip.
A dedicated regional plant helped cement supply agreements with global brand owners, but it could not insulate Galaxy when those customers lost market share on the ground. As Galaxy entered the 2010s with ambitious expansion plans and mounting capital commitments, it turned to public capital markets in May 2011 to help finance them.
V. The Seven-Year Public Market Drama: 2011 Withdrawal to 2018 Triumph
A Good Grade, an Empty Order Book
In January 2011, CRISIL assigned Galaxy's proposed initial public offering a grade of 4 out of 5, indicating "above average" fundamentals.2 The agency highlighted Galaxy's commanding presence in its domestic market, pointing to a more than 60% share in Indian personal-care performance chemicals alongside a return on equity of roughly 28%.2 At the same time, CRISIL flagged structural risks that would shadow the business for years: high customer concentration, the operational execution risk of building its first plant outside India, and an overall global market share below 1% against far larger diversified chemical rivals.2
Galaxy sought to issue 59.3 lakh new shares within a price band of ₹325 to ₹340 each, with proceeds earmarked to fund the Suez facility through Galaxy Holdings (Mauritius). Motilal Oswal and Centrum Capital served as lead managers.16 The order book never filled. The issue was subscribed just 0.30 times overall: institutional investors bid for 0.59 times their quota, while non-institutional and retail participation stalled at 0.04 times and 0.11 times, respectively.16 One day before the scheduled close, Galaxy withdrew the prospectus, citing a "lukewarm response." Market commentators attributed the failure to aggressive pricing amid fragile market conditions, making it the first IPO withdrawal of that fiscal year.16
What the Withdrawal Showed
The founders had the option to lower the price band or extend the bidding period to push the transaction through, but chose neither. That decision can be read as valuation discipline or as stubbornness, and the company's operating record provides evidence for both interpretations. More broadly, the 2011 episode illustrated how difficult intermediate industrial processors can be to sell to public investors when the narrative is complicated. A business-to-business chemical supplier whose top line swings with raw vegetable-oil costs, building a capital-intensive plant in Egypt during a political revolution, made for a tough institutional pitch.
Shut out of the public equity market, Galaxy funded its capital expenditure privately for the next seven years. Both Jhagadia and Suez were brought online without public equity, and Shekhar's IIM Calcutta citation confirmed that the Egyptian manufacturing center was commissioned in 2011.17 Galaxy would return to the primary market only when it no longer needed external capital to build factories.
The 2018 Return
In late January 2018, Galaxy returned to the capital markets with a ₹937 crore IPO priced at ₹1,480 per share—more than four times the upper end of its 2011 price band.18 Investor appetite proved radically different. The offer was subscribed 19.97 times, anchored by 25 institutional investors—including the Abu Dhabi Investment Authority, HSBC Global Investment Funds, HDFC Mutual Fund, and ICICI Prudential—who collectively absorbed ₹281 crore worth of shares.18 The stock listed on February 8, 2018, opening at ₹1,525 on the National Stock Exchange before closing the day at ₹1,730.18
The structure of the 2018 offering revealed how Galaxy's financial profile had matured. The shares on offer came entirely from the promoters, the promoter group, and long-standing private shareholders.18 Because it was structured purely as an offer for sale, the proceeds provided liquidity to early backers while the company itself raised no fresh cash. In 2011, Galaxy had sought public capital to underwrite expansion. By 2018, it sought an established public valuation and an orderly exit for early investors.
Even after that partial monetization, the founding group retained tight control. The promoters held roughly 70.9% of the equity immediately following the listing, and their stake stood virtually unchanged at 70.91% as of March 2025, with no shares pledged.19
The Investor Lens
For public shareholders, long-term returns have proved uneven. In mid-August 2026, the stock traded around ₹2,508, following a 20% single-day surge on record first-quarter earnings.4 That represented a modest 1.7-fold gain over its ₹1,480 IPO price across eight and a half years. While the stock touched a high of ₹3,370 during 2024,9 shareholder returns across the medium term had lagged: when Galaxy published its FY26 annual report in July 2026, its five-year equity return stood at approximately negative 35%.20
This divergence between stock performance and the underlying business captures the core challenge of valuing Galaxy. Operating profits have not suffered an outright collapse at any point, yet the stock's valuation multiple has repeatedly expanded and contracted as investors alternated between viewing Galaxy as a high-value specialty chemical compounder and treating it as a cyclical conversion processor. Determining which assessment reflects economic reality requires looking more closely at how its competitive advantages hold up against global rivals.
VI. Anatomy of the Business Model: Performance Surfactants vs. Specialty Care
The Workhorse Segment
A walk through the Taloja complex, one of India's largest sulfation facilities with roughly 156,700 tonnes of capacity, illustrates the operating reality of Performance Surfactants: heavy volumes, continuous manufacturing runs, and tight processing margins.9 The division's portfolio spans anionic surfactants—including fatty alcohol ether sulfates, fatty alcohol sulfates, and linear alkyl benzene sulfonic acid (LABSA)—alongside nonionic ethoxylates and amphoteric betaines.9 In FY24, the segment shipped approximately 159,400 tonnes, accounting for close to two-thirds of Galaxy's consolidated output.9
In this volume-driven category, competitive separation stems from process control and operating discipline. Ethoxylation, for example, can leave trace residues of 1,4-dioxane, an unwanted by-product subject to increasingly strict environmental limits. New York State established a ceiling of one part per million for household cleaning and personal care products effective December 31, 2023, and ended all compliance waivers after December 30, 2025.21 Processors capable of reliably stripping dioxane down to that threshold protect their positions in global brand formulas, while those unable to do so are filtered out. Meeting the standard does not command a premium price, but it acts as a regulatory hurdle that sidelines less disciplined competitors.
The Specialty Segment
Specialty Care operates on a different economic logic. The segment encompasses more than 168 commercial grades, including mild amino-acid surfactants, non-toxic preservatives, UV filters and sunscreen agents, conditioning polymers, and TRI-K's specialized cosmetic proteins.12 Physical volumes are smaller—reaching roughly 89,200 tonnes in FY24—but orders are substantially more customized.9 Because specialty formulations require multi-step synthesis and longer production cycles, Galaxy typically holds about 40 days of finished-goods inventory for the unit, compared with roughly 15 days for standard performance lines.9
Recent product rollouts reflect this push toward higher-value chemistry. In 2026, Galaxy introduced Galsoft Lumithic, a self-thickening amino-acid surfactant engineered for sensitive applications such as baby care, feminine hygiene, and anti-acne treatments.13 It also launched SimpliX, an ingredient platform designed to simplify formulation for body washes and shampoos.5 Management targeted products developed under its 2030 roadmap to generate more than 5% of group revenue by 2030.5
The Switching-Cost Argument
The core argument for Galaxy's business moat rests on customer switching costs. YES Securities noted that multinational consumer brands typically spend two to three years qualifying and validating an alternate ingredient source, and once approved, a formulation often remains in active production for six to seven years or longer.9 Because an active ingredient represents a minor portion of a shampoo bottle's retail cost but carries catastrophic recall risk if a batch fails, corporate procurement managers have little incentive to switch away from a proven, reliable supplier to capture small price concessions.
Galaxy's customer distribution reflects this tiered commercial dynamic. In FY24, global consumer conglomerates generated approximately 52% of revenue, large Indian brands like Dabur, Emami, and Himalaya contributed about 12%, and local players, niche formulators, and direct-to-consumer (D2C) startups accounted for the remaining 36%.9
This tiering directly determines pricing power. While global consumer giants possess immense bargaining leverage and multi-source every critical molecule, regional and local formulators rarely maintain specialized research teams. Instead, smaller brands turn to Galaxy for pre-formulated blends and technical application support, yielding higher realized margins for the supplier. At its June 2025 Capital Market Day, management outlined a target addressable market of roughly $30 billion across home, beauty, and personal care ingredients, about half of which was concentrated in developed markets. Management highlighted leave-on applications—such as skin care, sun care, and color cosmetics—where Tier-1 multinationals controlled only about 30% of the market, leaving the remainder to agile D2C brands and private labels.19 Expanding sales among these smaller, fragmented buyers represents Galaxy's primary avenue for curbing its dependence on multinational conglomerates, a strategic rebalancing that will show up in customer-mix disclosures over time.
Where the Switching-Cost Argument Weakened
FY26 provided an instructive stress test for this switching-cost thesis. When fatty alcohol prices remained stubbornly high, Galaxy's largest buyers did not shift orders to rival sulfators. Instead, they substituted the chemistry itself. Facing margin pressure, Tier-1 consumer companies reformulated core product lines away from palm-derived oleochemical surfactants toward cheaper petrochemical alternatives. Management estimated that this reformulation wave shaved 3,000 to 4,000 tonnes off Galaxy's shipments in the second quarter of FY26 alone.15 Over the full fiscal year, Performance Surfactant volumes contracted by a mid-single-digit percentage,1 as volume gains among non-Tier-1 customers and emerging D2C brands proved insufficient to fully bridge the shortfall.13
The episode exposed the structural boundary of Galaxy's moat. Prolonged qualification cycles protect the company against rival vendors offering the same molecule, but provide little defense when consumer giants elect to alter their master recipes. In response, Galaxy adapted its manufacturing lines to supply petrochemical derivatives, and by August 2026 Natarajan confirmed that "all approvals are in place."5 In the first quarter of FY27, the underlying economics swung back: petrochemical feedstocks surged past oleochemical alternatives, prompting consumer brands to restore original formulations and driving volumes back to Galaxy.5
Yet management acknowledged that the risk has not disappeared. If petrochemical benchmarks drop significantly while vegetable-alcohol costs stay elevated, Natarajan conceded that reformulation could return.5 Switching costs preserve Galaxy's mandate as a trusted conversion partner for an established specification; they do not lock in the chemistry itself.
Geography and Working Capital
Geographically, Galaxy's revenue footprint in FY25 remained balanced: the domestic Indian market accounted for roughly 40% of sales, the AMET region generated 24%, and the rest of the world contributed 36%.10 Supporting that worldwide distribution demands substantial working capital. CRISIL estimated Galaxy's gross current assets at 130 to 155 days of revenue, driven by inventory requirements of 65 to 75 days and trade receivables of 60 to 65 days.10 Such heavy working-capital absorption is an unavoidable requirement of the conversion model: the company must procure tropical agricultural feedstocks upfront while maintaining buffer stock to meet the demanding, just-in-time delivery schedules of multinational consumer plants. The next question is which global rivals contest Galaxy for that volume.
VII. Competitive Landscape & Structural Moats
The Battlefield
Galaxy faces competition from three distinct directions. First are global diversified chemical conglomerates; CRISIL's 2011 review identified Huntsman, Rhodia, Stepan, BASF, Croda, Dow, Clariant, and Sasol as primary international peers.2 Second are regional and domestic processors operating with lower structural overhead. Third, and least visible, are the brand-owner customers themselves, who can manufacture intermediates internally or substitute chemistries when commodity costs spike.
CRISIL's assessment in 2011 still captures the core competitive dynamic. While the multinational chemical giants possess vastly greater balance sheets, personal-care surfactants represent only a modest fraction of their consolidated revenues. According to CRISIL, that "lack of focus specifically for the end-use market of personal care works in favour of Galaxy."2 The rating agency also identified Chinese producers as a latent competitive threat due to their manufacturing scale and aggressive pricing, though Galaxy's stringent quality tolerances had historically shielded it from direct displacement.2
The Margin Scoreboard
CRISIL's peer benchmarking illuminated Galaxy's relative economic positioning. In 2009, Galaxy's operating EBITDA margin of 12.6% tracked closely with an international peer average of 13.5%, outperforming commodity-focused processors such as Stepan at 11.7% and Dow at 9.3%, while trailing higher-value specialty producers such as Croda at 16.9% and Clariant at 21.0%.2 Galaxy kept pace with high-volume conversion processors but lagged behind genuine proprietary specialty chemical compounders. Seventeen years later, the company occupies roughly that same intermediate tier.
A Signal From Dahej
A major competitive shift emerged in August 2026. On August 4, BASF India's board approved the closure of both the sulfation facility and the low-temperature reactor plant at its Dahej care chemicals site, with decommissioning targeted by the end of calendar 2026.6 Those assets had generated ₹542 crore in FY26 revenue, with BASF citing "extensive overcapacities, high costs and margin pressure" stemming from structural changes in India's competitive landscape.6
The Dahej exit sends a dual signal. On one hand, it eliminates a well-capitalized multinational competitor from the domestic sulfation market. On the Q1 FY27 earnings call, Natarajan observed that the shutdown "can result in some demand upside," though he noted that prospective customers had not yet approached Galaxy with firm volume inquiries.5 On the other hand, the departure underscores the harsh economics of domestic bulk processing: Indian surfactant capacity had become crowded enough to prompt a global chemical leader to abandon its facility. Galaxy's ability to maintain profitability where BASF retreated reflects superior conversion discipline and lean operating costs, but it also confirms that persistent industry oversupply caps the processing spreads any domestic supplier can extract.
The Domestic and Regional Challengers
Within India, Galaxy faces two domestic cohorts: backward-integrated conglomerates operating their own oleochemical refining facilities, and agile local sulfonation plants competing purely on price. Addressing whether strong quarterly results from domestic peers signaled an industry-wide resurgence in August 2026, Natarajan asserted that many regional rivals "are not into the entire range of products that we have," maintaining that among Indian suppliers Galaxy commanded "the largest portfolio and also in terms of scale and also a large customer base."5 While those statements represent management's positioning, they align with an audited catalog spanning more than 215 product grades and supply relationships spanning decades with global conglomerates.1
In Egypt, competitive pressure manifested along different lines. Domestic manufacturers integrated backward into raw-material inputs, pricing their output in local Egyptian pounds and supplying emerging regional brands that captured market share as inflation eroded consumer demand for imported labels.13 Consequently, the primary competitive headwind for Galaxy in the AMET region came not from multinational rivals, but from domestic producers insulated from foreign-currency debt who served the local formulators displacing Galaxy's core multinational clientele.
Hamilton Helmer's 7 Powers, Tested
Switching costs: real but bounded. Two-to-three-year qualification cycles and long product formulations are well documented.9 Yet FY26 demonstrated the boundary of this moat: multinational customers can bypass the friction of switching suppliers simply by reformulating their master recipes to cheaper base chemistries.
Process power: the strongest candidate. The engineering of dust-free SLS granules, precise 1,4-dioxane stripping, the operational coordination required to ship over 215 product grades reliably across seven manufacturing sites, and a 45-year supply relationship with Unilever all demonstrate deep institutional process knowledge.913 That process power, however, translates into account retention and operational reliability rather than pricing leverage. Realized EBITDA per metric tonne has not expanded steadily over time.
Scale economies: moderate. An installed capacity of approximately 4.42 lakh tonnes establishes Galaxy as a leading domestic processor in India.10 In a global context, however, its footprint remains modest: in 2011, CRISIL estimated Galaxy's share of the global personal-care ingredients market at below 1%.2 Manufacturing scale affords procurement efficiencies in feedstock sourcing and maritime freight, but it does not confer structural market pricing power.
Brand, network effects, cornered resource and counter-positioning: largely absent. Galaxy's commercial reputation among institutional procurement and formulation teams functions as an aspect of customer switching costs rather than an independent brand asset. The business exhibits no network effects and holds no exclusive access to feedstock resources. Similarly, adapting production lines to accommodate petrochemical derivatives represents an operational adaptation to peer offerings rather than strategic counter-positioning.
The counter-power: buyer concentration. The defining competitive constraint on Galaxy remains the commercial leverage of its customer base. In FY10, the company's ten largest buyers accounted for roughly 67% of standalone sales.2 Global consumer conglomerates still contributed approximately half of consolidated revenue in FY24.9 These multinational buyers qualify dual sources across key chemistries, benchmark processing fees against global competitors, and alter product formulations when spreads diverge. That institutional bargaining power explains why Galaxy's technical execution and process discipline have not translated into expanding operating margins across full market cycles.
This strategic framework credits Galaxy with meaningful operational defenses but falls short of identifying a decisive economic moat. Whether that assessment is overly conservative can be tested directly against the empirical financial record, which the next section examines across historical operating cycles.
VIII. Historical Falsification Layer: Testing the Core Thesis Claims
Stress Test 1: "Specialty Care Will Transform the Margins"
The claim. As Specialty Care expands as a proportion of total revenue, Galaxy will decouple from commodity cycles and structurally lift its operating margins per metric tonne.
The evidence. Over the decade spanning FY15 through FY24, Specialty Care remained remarkably steady, generating between 34% and 38% of total volume and between 35% and 41% of consolidated revenue.9 In FY26, the segment contributed roughly 37% of revenue, sitting squarely within that historic corridor.1 While specialty operations have expanded in absolute terms, the division has not outpaced the broader enterprise long enough to rebalance the corporate sales mix.
Executive leadership has acknowledged this structural dynamic directly. On the Q4 FY26 earnings call, Natarajan explained that the revenue split would likely continue to swing between 65–35, 60–40, or 70–30, projecting that even by 2031 the business would remain within a 60–40 to 65–35 band.13 In August 2026, he went further, stating plainly that there was no strategy to transition away from performance surfactants into pure specialty chemicals.5 Because institutional consumer brands require a complete portfolio of base cleansing and specialty formulation ingredients, Galaxy must scale both divisions in tandem.
Unit profitability tells the same story. Before the COVID-19 pandemic, Galaxy generated roughly ₹16,700 in EBITDA per metric tonne. That spread expanded to a peak of ₹25,051 in FY23, propelled by a one-off 6% export incentive in Egypt alongside a temporarily favorable product mix, before falling back to ₹20,019 in FY24.9 Cash spreads then settled at roughly ₹19,900 in FY25 and ₹19,357 in FY26.221 While Q1 FY27 yielded an extraordinary ₹35,458 per tonne—an anomaly examined in Section IX—management itself dismissed that surge as unsustainable.5
Verdict: narrowed. Galaxy is not morphing into a pure-play specialty chemical compounder. It operates as a two-segment supplier whose specialty chemistries protect returns at the perimeter without fundamentally altering underlying conversion economics. Reviving the specialty transformation thesis would require sustained unit spreads above ₹22,000 per tonne over multiple operating years without one-off subsidies. Until then, the company is best understood as a disciplined intermediate conversion processor.
Stress Test 2: "Tier-1 Relationships Guarantee Growth"
The claim. Decades-long partnerships with global consumer conglomerates like Unilever, Colgate-Palmolive, and Procter & Gamble guarantee predictable volume expansion.
The evidence. Galaxy's commercial relationships have proven durable, as demonstrated by Unilever signing a formal long-term growth charter with the company in August 2026.3 Yet customer longevity has not delivered steady shipping volumes. In FY26, consolidated volumes stayed virtually flat as Tier-1 buyers altered master formulations to cut costs, while multinational market-share losses in Egypt contributed to a one-third decline in Galaxy's regional AMET shipments.113 Management's volume forecasting record reflects this instability: YES Securities documented that actual volume growth missed guidance in FY20, FY22, and FY23, touched only the bottom of the targeted band in FY21, and reached the upper boundary only in FY24.9
Verdict: intact but not predictable. Galaxy retains its blue-chip accounts, but it cannot dictate their order volumes. When global consumer giants lose shelf share to local brands—as occurred across North Africa—Galaxy absorbs the downstream demand contraction.
Stress Test 3: Capital Allocation
The claim. Management exercises disciplined, high-return capital allocation.
The evidence. Galaxy's capital deployment reveals divergent outcomes. The acquisition of TRI-K in the United States was modest, low-risk, and operationally resilient, whereas the Suez manufacturing complex in Egypt required substantial capital, made strategic sense on paper, and ultimately lagged its original operating thesis. Recent domestic capital expenditures also face an extended payback period. On the Q4 FY26 call, an analyst highlighted roughly ₹480 crore in capex over three years; Natarajan noted that the investments were directed primarily into specialty ingredients, with a major portion commissioned only in the preceding 18 months.13 He also acknowledged that a nascent venture into wellness ingredients had stalled, conceding, "I'm not too satisfied."13
These capital outlays have visibly compressed returns. Return on capital employed fell to 15.7% in FY24 from 23.6% in FY23, according to YES Securities.9 While management's 2030 roadmap targets an average ROCE above 22%,19 direct cash distributions to shareholders have remained conservative. The FY26 dividend of ₹22 per share represented a total distribution of roughly ₹78 crore, or less than 30% of that year's ₹267 crore profit after tax.201
Verdict: disciplined in approach, uneven in outcomes. Galaxy has avoided destructive, debt-fueled acquisitions or large asset write-offs. However, chronic capacity underutilization in Egypt and heavy outlays on specialty assets that have yet to earn their cost of capital mean the capital-allocation record cannot be characterized as outstanding.
Stress Test 4: Does Management Guidance Hold Up?
A practical measure of executive credibility is tracking forward guidance against subsequent operating performance. In May 2025, leadership projected that FY26 volume growth would likely track the lower end of its 6% to 8% target range until Indian demand picked up.22 FY26 volumes ultimately ended the year flat.1 In November 2025, management insisted that volume declines from customer reformulations were not structural.15 That assessment proved accurate when brand owners reinstated oleochemical specifications in Q1 FY27, though the recovery was triggered by external geopolitical shocks that altered relative feedstock costs rather than by Galaxy's commercial leverage.5
Regional projections faced similar friction. In May 2026, Natarajan suggested that AMET volumes had probably bottomed out.13 Yet in Q1 FY27, regional shipments declined another 4% year on year, which management attributed to a seven-week shipping disruption at regional transshipment ports.5 For Q1 FY27 as a whole, leadership had guided to the upper end of 6% to 8% volume growth and an EBITDA spread of ₹19,000 to ₹21,000 per tonne.13 The actual quarter generated roughly 5% volume growth alongside an unprecedented ₹35,458 per tonne,5 missing volume targets slightly while outstripping margin expectations by more than 70%.
Verdict: candid but difficult to model. Management communicates operating challenges transparently and avoids inflating long-term margin targets. However, its volume forecasts have frequently missed the mark, and several successful calls depended on external commodity turns rather than internal execution. Investors should view management guidance as a directional aspiration rather than a precise operating forecast.
Governance Check
Galaxy's statutory auditor for FY26, Deloitte Haskins & Sells LLP, issued an unmodified audit opinion on both the standalone and consolidated financial statements, recording no qualifications or adverse remarks.20 Promoters maintain a 71% equity stake with zero pledged shares.19
One disclosure matter warrants scrutiny. Galaxy began recognizing revenue from an engineering, procurement, and construction (EPC) contract in Mexico using the percentage-of-completion accounting method. Management declined to disclose the contract's financial value during the Q1 FY27 earnings call, citing customer confidentiality, and stated that the venture was accounted for within a separate operating segment.5 While leadership characterized the contribution as immaterial, an industrial services project that external investors cannot quantify represents a disclosure blind spot in an otherwise transparent operating model.
Myth vs. Reality
Myth: Rapid revenue growth proves Galaxy is aggressively capturing market share. Reality: Top-line swings predominantly mirror raw palm-kernel oil prices. In FY26, revenue jumped 24% even as operating EBITDA contracted.1
Myth: Multi-year qualification cycles lock in volume and insulate Galaxy from competition. Reality: While qualification protects against rival suppliers of the same molecule, customers can alter their master formulas; reformulation cost Galaxy thousands of tonnes of volume in a single quarter in FY26.15
Myth: The Suez facility provides an unassailable, duty-free manufacturing conduit into the AMET market. Reality: While the free-zone tax holidays are genuine, domestic Egyptian processors integrated backward into feedstocks, causing Galaxy's regional shipping volumes to decline by approximately one-third from their historical peak.13
That empirical baseline provides the context for evaluating the extraordinary supply shocks of 2026, which upended the operating economics of the global surfactant industry for a single quarter.
IX. Modern Era: Geopolitics, The Red Sea Crisis, & Supply Chain Shocks (2020–Present)
The COVID Boom and Its Unwinding
When the pandemic arrived in early 2020, surging hygiene awareness drove unprecedented demand for hand wash, soaps, and sanitizers. Galaxy's underlying shipping volumes expanded at only a modest low-single-digit pace, but its unit processing spreads widened dramatically: EBITDA per metric tonne rose from approximately ₹16,700 before the crisis to roughly ₹25,000.9 That earnings surge proved fleeting. Russia's invasion of Ukraine in 2022 sent energy and food prices to multi-decade highs, triggering aggressive destocking across retail supply chains. By early FY24, consumer-goods conglomerates found themselves burdened with excess inventory, prompting price cuts that pulled processing spreads back toward historical baselines.9 The FY23 margin peak had also been flattered by a one-off 6% export incentive in Egypt; as that subsidy expired and channel inventories normalized, FY24 margins settled back to approximately ₹20,000 per metric tonne.9
The Red Sea Detour
In January 2024, Houthi attacks on commercial shipping in the Red Sea forced container vessels to bypass the Suez Canal and circumnavigate Africa via the Cape of Good Hope. The rerouting struck directly at the geographic rationale of Galaxy's Suez manufacturing hub. Shipping disruptions in January clipped AMET volumes by 1.5% in FY24, although regional volumes rebounded strongly across February and March as logistics networks adjusted.9 Galaxy absorbed the freight surge directly in the fourth quarter of FY24 before writing higher transportation costs into subsequent customer contracts.9 Despite the maritime disruption, full-year FY24 volumes still grew 7.7%, and EBITDA per metric tonne closed at ₹20,019, landing squarely within management's guidance band.9
Tariffs, Taxes and Reformulation (FY26)
Fiscal 2026 brought a confluence of regulatory and operational cross-currents. In late 2025, the United States imposed a 50% tariff on certain Indian chemical exports. Management estimated the cumulative financial drag at 3% to 5% of FY25 EBITDA and mitigated the penalty by shifting export production runs to its duty-free Suez facility in Egypt.15 Domestically, rationalization of Indian Goods and Services Tax (GST) rates prompted consumer brands to temporarily deplete channel inventories and relabel packaging ahead of the festive season, stalling wholesale orders.12 Concurrently, elevated palm-derived fatty alcohol costs spurred multinational buyers to reformulate their core cleansing products toward synthetic petrochemical substitutes. While the US tariff on Indian chemical shipments was later reduced to 18%,12 the trade friction disrupted commercial momentum; on the Q4 FY26 earnings call, Natarajan reported that Galaxy's specialty development pipeline in the United States had finally "been reinitiated."13
The West Asia War
The operational environment grew far more volatile in early 2026, when military escalation in West Asia disrupted maritime corridors, global energy markets, and chemical intermediate flows. Addressing analysts in May 2026, Natarajan acknowledged that what "was initially perceived as a short-term disruption extended well into and beyond quarter 4."13 Ocean freight rates more than doubled within weeks, and critical merchant supplies of sulfur and ethylene oxide grew erratic. Describing the daily uncertainty of managing hazardous chemical supply chains amid regional conflict, Natarajan observed that it was not an operating environment where "you can sleep every day presuming that things will be on a steady state."13 The disruption took an immediate toll on regional operations, with AMET shipping volumes tumbling by approximately 15% in the fourth quarter of FY26.13
Yet the same geopolitical crisis triggered the most profitable anomaly in Galaxy's operating history. As crude oil surged past $100 per barrel, petrochemical-derived surfactant feedstocks became both prohibitively expensive and physically scarce.5 For the first time in more than a year, natural oleochemical surfactants became the more economical choice. Natarajan noted that "the relative economics between oleochemical-based and petrochemical-based feedstocks reversed."5 Multinational brand owners that had reformulated away from Galaxy's plant-based chemistries reversed course and rushed back. Lauryl alcohol prices spiked from roughly $2,800 to $3,300 per metric tonne before retreating below $2,500 in late June.5 Galaxy, having secured substantial feedstock inventories well before the price surge, captured an exceptional commercial processing spread.
The Record Quarter, and How to Read It
The financial consequence was an unprecedented operating performance in the first quarter of FY27. EBITDA reached ₹252.5 crore—nearly double the ₹135.1 crore recorded in the prior-year period—delivering an extraordinary EBITDA spread of ₹35,458 per metric tonne.5 Consolidated revenue from operations rose roughly 39%, while profit after tax surged more than twofold to approximately ₹166 crore.4 Consolidated shipping volumes expanded 5%, driven by an 11% rebound in India and a 6% increase in the rest of the world, even as logistical logjams caused AMET volumes to decline 4%.5
Management moved quickly to temper market exuberance. Natarajan told investors that Galaxy anticipated unit spreads normalizing to ₹21,000–₹22,000 per metric tonne over the remainder of the fiscal year. While he raised full-year EBITDA guidance to a range of ₹24,000–₹25,000 per tonne from the earlier target of ₹19,000–₹21,000,5 he characterized the first quarter as an alignment of favorable factors: returning customer volumes, operating leverage, an improved specialty mix, and opportunistic commercial execution, cautioning that "some of it may continue, some of it may not."5 Asked repeatedly by analysts to quantify how much of the windfall came from low-cost inventory gains, management declined to provide a breakdown.5 Natarajan did concede, however, that without these temporary market distortions Galaxy would have earned "about INR 21,000 per metric ton."5
Institutional analysts pressed management on whether this margin expansion was repeatable. Jignesh Kamani of Nippon Mutual Fund observed that while fatty alcohol benchmark costs had risen only about 3% year on year, Galaxy's average realized selling price had surged roughly 30%—climbing from approximately ₹190 to ₹250 per kilogram—and questioned whether a scarcity-driven price spike would inevitably unwind.5 Natarajan attributed the realization surge to two factors: maritime export freight had more than doubled and was embedded directly in landed CIF contract pricing, and customer demand had shifted toward higher-concentration, fully active dry grades that naturally command higher realized prices.5 Arun Prasath of Avendus Spark raised a broader structural question: with gross margins holding steady at ₹52 to ₹53 per kilogram for two consecutive years while the rupee depreciated from roughly ₹88 to ₹95 against the US dollar, had the company's structural earnings baseline permanently elevated? Natarajan remained cautious, noting that management would wait "at least for one quarter" before adjusting structural guidance.5
The disciplined takeaway is that the bulk of Q1 FY27 represented a non-repeatable commodity windfall born of war and supply dislocation. The durable signal was a modest underlying expansion in normalized unit spreads—from roughly ₹19,400 per tonne in FY26 to a corridor of ₹21,000–₹22,000—and even that baseline remains contingent on natural oleochemicals retaining their cost advantage over synthetic petrochemicals.
The Feedstock Outlook
Looking across the remainder of FY27, management projected that raw-material prices would consolidate rather than collapse. Indonesia's decision to raise its mandatory biodiesel blend from 40% to 50% (the B50 mandate) had already established a floor under crude palm oil at roughly $1,100 to $1,200 per metric tonne, leading Natarajan to project fatty alcohol trading within a steady corridor of $2,600 to $2,800 per tonne.5 He also highlighted potential weather disruptions from El Niño on upcoming oil palm harvests, emphasizing that management would navigate procurement quarter by quarter amid rapid geopolitical shifts.5 On downstream demand, leadership cited steady end-market consumption, pointing to Hindustan Unilever's roughly 5% underlying volume growth in its latest quarter even as consumer companies pushed through retail price increases.5
This feedstock dynamic illustrates why intermediate conversion processors are vulnerable to volatility. Galaxy remains consistently profitable across a wide range of commodity prices. What impairs its unit economics is not high feedstock costs per se, but abrupt price swings that create contractual pass-through lags, or wide price divergences between vegetable and petroleum feedstocks that induce brand owners to alter formulations. Stable raw-material prices—even at elevated levels—allow pass-through mechanisms to work smoothly. Violent turns in either direction test the model.
Biosurfactants: Direction, Not Yet Disruption
Beyond the recurring contest between palm oil and petrochemicals lies a longer-term technological shift: biotechnology. In May 2024, German chemical producer Evonik commissioned what it described as the world's first industrial-scale manufacturing plant for rhamnolipid biosurfactants in Slovenská Ľupča, Slovakia, using sugar fermentation to replace both tropical oils and fossil feedstocks in an investment running into hundreds of millions of euros.23 Galaxy has pursued its own bio-based pathway: its Galaxy Hearth Biosurf ingredient, which pairs enzymes with specialty surfactants for concentrated laundry care, earned an industry innovation award in 2026.5 Furthermore, Unilever's long-term partnership charter with Galaxy signed in August 2026 explicitly incorporates co-development of bio-based alternatives and lower-carbon surfactant chemistries.3
Galaxy's commercial history, however, calls for measured expectations. Over four decades, the company has introduced dozens of patented molecular grades, yet Specialty Care has remained anchored at approximately one-third of total production volume. Industry awards and laboratory partnerships validate technical capability, but they do not automatically convert into high-margin commercial scale. Understanding who will steer those capital decisions and technological choices next turns the spotlight onto Galaxy's executive leadership and generational transition.
X. Current Management, Capital Allocation, & Governance
The Founder Steps Back
In February 2024, Unnathan Shekhar retired as managing director, 44 years after Galaxy's first manufacturing facility commenced operations. He remained on the board as a non-executive director.24 A 2011 citation from IIM Calcutta honoring Shekhar noted that he had started the enterprise in a borrowed laboratory and led the company "by example with a very high level of integrity and transparency."17 By roughly 2020, he was the only founder still directing day-to-day operations.8
Following Galaxy's Capital Market Day in June 2025, HDFC Securities observed that the company was "transitioning from a promoter-driven to a professionally managed organization."19 That succession carries material governance weight: the founding promoter families still held approximately 71% of the equity while stepping back from direct executive management.19
The Operator in Charge
Shekhar's successor as managing director, K. Natarajan, joined Galaxy on April 21, 1993, and spent more than three decades overseeing finance, information technology, commercial operations, global sourcing, and supply-chain logistics. A commerce graduate and qualified cost accountant who completed Harvard Business School's Advanced Management Program in 2016,24 Natarajan brings an operational and commercial background rather than a background in synthetic chemistry—a profile well suited to an enterprise whose financial performance hinges on managing raw-material procurement and contract pass-through lags.
On quarterly earnings calls, Natarajan communicates with notable candor. In August 2026, he described himself as "a very optimistic guy," but added, "I don't want to be overpromising and under delivering."5 He has corrected analysts who misquoted him and openly acknowledged when individual segments lagged behind plan, while typically attributing operating shortfalls to identifiable external shocks, including import tariffs, Indian tax recalibrations, and West Asian shipping bottlenecks. While that explanation is often credible, it can also develop into a recurring pattern of citing exogenous factors. The practical benchmark for investors remains operating delivery: in FY26, shipping volumes were flat against an internal aspiration of 6% to 8% growth.1
Senior operational leadership below Natarajan shows comparable institutional tenure. Vaijanath Kulkarni, a chemical engineer who joined in 1995 and previously led the Egyptian operating subsidiary, serves as Executive Director and Chief Operating Officer, while Abhijit Damle serves as Chief Financial Officer.24 Both top operating executives built their entire professional careers inside Galaxy across three decades. That continuity ensures an intimate understanding of shop-floor chemistry and customer specifications, but it also leaves executive leadership with limited experience of how peer chemical multinationals manage scale, navigate organizational change, or execute external corporate acquisitions—a perspective crucial to the targets set under Vision 2030.
The Board and Its Customer DNA
Galaxy's boardroom has long reflected the perspective of its institutional buyers. As of 2011, CRISIL documented that independent chairman Shekhar Ravindranath had previously served as managing director of Hindustan Unilever's foods division, while non-executive director Venkatesh Kasturirangan had led DiverseyLever in the United States and served as Executive Vice President and Chief Operating Officer of Unilever USA.2 Populating the board with former multinational executives gave Galaxy deep insight into how consumer conglomerates think, qualify suppliers, and manage procurement. At the same time, it raises a reasonable governance question: whether a board steeped in consumer-goods DNA ever sufficiently challenged management's reliance on those powerful buyers. The public record does not resolve that question either way.
Balance Sheet
Galaxy's balance sheet remains exceptionally conservative. As of March 2026, cash, bank balances, and liquid current investments comfortably exceeded total borrowings of about ₹165 crore, leaving the enterprise in a net-cash position.1 In October 2025, CRISIL reaffirmed its credit ratings of AA-/Stable for long-term borrowings and A1+ for short-term facilities, citing a minimal debt-to-equity gearing of 0.09 times and an interest-coverage ratio of roughly 26 times.10 Routine annual capital expenditures of ₹150 crore to ₹175 crore have been funded entirely through internal cash generation.10 Management projected FY27 capital spending of approximately ₹150 crore,5 with Natarajan confirming on the fourth-quarter FY26 call that no new growth commitments were planned for the year.13
Vision 2030
At its Capital Market Day on June 13, 2025, Galaxy unveiled an ambitious strategic framework for the end of the decade: roughly double consolidated shipping volumes, expand EBITDA 2.5 times—implying an annual compounding pace of about 20%—maintain an average return on capital employed above 22%, reinvest 50% to 60% of operating cash flow into organic capacity, introduce roughly 20 new commercial products, and enter adjacent beauty and wellness segments through strategic partnerships or corporate acquisitions.19 Natarajan subsequently noted that reaching the targeted EBITDA spread of approximately ₹25,000 per metric tonne would be "backloaded," with the bulk of margin expansion deferred to FY29 and FY30.13
The arithmetic behind this growth model highlights its demanding assumptions. Management's roadmap projected existing product lines growing EBITDA at 8% to 10% annually, with newly developed product portfolios adding 5 to 6 percentage points, and "emerging avenues" contributing another 3 to 4 percentage points. In effect, roughly half of all incremental EBITDA was expected to come from commercial sources that barely exist today.19 Galaxy also targeted roughly 20 product rollouts over five years, compared with 25 launches across the entire preceding decade.19 That represents an aggressive acceleration for an organization whose specialty product share has remained stationary for a decade.
Measured against historical delivery, these targets represent a significant leap. Doubling volume over five years demands sustained annual volume growth of 14% to 15%. Galaxy's actual FY26 volumes were flat, while management's ongoing baseline guidance calls for 6% to 8%. The roadmap relies heavily on acquisitions, new categories, and new product portfolios to close that arithmetic gap.19 Yet on external acquisitions, Natarajan stressed in August 2026 that Galaxy would remain disciplined, stating, "we'll not do anything just to be able to for the fear of missing out."5
What a Skeptical Activist Would Ask
An institutional investor or activist examining Galaxy's operational track record would press management on four central questions:
First, why does an enterprise holding net cash balances and earning returns on capital employed well below its 22% target distribute less than 30% of annual profits as dividends, rather than returning surplus capital to shareholders or articulating explicit hurdle rates for reinvestment?
Second, what actual return on capital is the Suez manufacturing complex generating now that domestic Egyptian processors have taken market share and AMET regional shipping volumes remain a third below their historical peak?
Third, what is the financial magnitude and risk profile of the Mexican engineering, procurement, and construction contract, which Galaxy accounts for under percentage-of-completion rules as a distinct reporting segment without disclosing its monetary value?
Fourth, how can Vision 2030 realistically deliver a 14% to 15% annual volume expansion when core operations have compounded at mid-single digits and ended FY26 completely flat?
None of these inquiries suggests operational or financial misconduct. Rather, they demarcate the exact points where management's aspirational compounding narrative diverges most sharply from Galaxy's historical financial reality.
XI. The Acquired Playbook: Core Business & Investing Lessons
1. Measure the Toll, Not the Traffic
In Galaxy's operating model, headline revenue largely reflects the price of raw vegetable oils rather than commercial expansion. The meaningful metric is EBITDA per metric tonne—the cash processing spread earned on each physical unit shipped—and the critical question for investors is whether that unit spread is expanding structurally over time. Many commodity-linked enterprises, from oil refiners and packaging converters to contract manufacturers, operate on an identical economic logic. Identifying the underlying toll rather than tracking top-line traffic prevents investors from mistaking pass-through commodity inflation for real business growth.
2. The Apprenticeship Compounds, but Only So Far
Serving an early apprenticeship with Colgate and Hindustan Unilever forced Galaxy to institutionalize manufacturing tolerances and quality controls that domestic challengers could not easily replicate. Yet the operating shocks of FY26 revealed the boundary of that competitive defense. The multinational brand owners that helped train Galaxy retain the ultimate commercial leverage: when relative input costs diverge, they can alter their master formulations to cheaper substitute chemistries. Operational reliability preserves customer qualification and long-term trust, but it cannot prevent a customer from buying less volume.
3. Location Is Not a Moat on Its Own
On paper, the Suez manufacturing hub offered compelling strategic advantages: duty-free zone status, proximity to maritime shipping corridors, and direct access to African and Middle Eastern consumer markets. Yet physical location offered no defense when regional macroeconomic crises and severe currency depreciation eroded consumer purchasing power across Egypt. When end consumers traded down to lower-priced domestic products, Galaxy's multinational buyers surrendered market share to backward-integrated local processors. An intermediate production plant positioned close to its buyers remains only as resilient as those buyers are on the supermarket shelf.
4. Small Deals Can Buy Big Capabilities
Acquiring TRI-K in 2009 cost approximately $5 million and continues to deliver access to premium specialty personal-care customers in the United States 17 years later.25 The strategic takeaway for emerging-market manufacturers is that acquiring specialized application capabilities, technical sales teams, and customer relationships at a modest price often yields far superior risk-adjusted returns than building heavy manufacturing capacity at scale. Whether executive leadership retains that acquisition discipline will become evident as Galaxy evaluates external targets across beauty and wellness under its Vision 2030 roadmap.
5. Optionality in Chemistry Is Worth Paying For
Adapting manufacturing lines to supply petrochemical derivatives alongside a predominantly oleochemical portfolio appeared purely defensive when Tier-1 customers reformulated their formulas in FY26. In the first quarter of FY27, that investment proved invaluable. When geopolitical supply shocks upended relative feedstock economics, a supplier capable of offering whichever chemistry was more cost-effective at a given time became far harder for brand owners to replace than one tethered to a single feedstock.5 Galaxy's long-term competitive durability will be determined as much by that pragmatic conversion flexibility as by new specialty product launches.
XII. Bull vs. Bear Case & The 3 Critical KPIs
Porter's Five Forces
Buyer power: high. Global consumer conglomerates account for roughly half of Galaxy's consolidated revenue, systematically qualify dual suppliers, and possess the technical capability to reformulate master recipes when processing spreads diverge.915 This institutional bargaining leverage remains the single most powerful structural constraint on Galaxy's profit margins.
Supplier power: moderate to high, and cyclical. Lauryl alcohol pricing traces back to crude palm oil benchmarks, which are anchored in turn by global energy markets and Indonesian biodiesel mandates. Indonesia's decision to raise its mandatory blend from 40% to 50% (the B50 mandate) helped establish a price floor for palm oil between $1,100 and $1,200 per metric tonne.5 Regional conflict has introduced further supply volatility, as seen during the West Asia escalation when merchant supplies of sulfur and ethylene oxide grew erratic.13 While Galaxy successfully passes feedstock inflation through to brand owners, contractual reset lags leave margins temporarily vulnerable during sharp commodity run-ups.
Threat of new entrants: moderate. Stringent customer qualification cycles spanning two to three years and tightening regulatory standards—such as New York State's one-part-per-million ceiling on 1,4-dioxane impurities—deter unproven suppliers from competing for Tier-1 corporate accounts.921 At the regional level, however, backward-integrated Egyptian chemical manufacturers demonstrated that new competitors can enter and capture domestic market share rapidly when local macroeconomic dislocation favors low-cost alternatives.13
Threat of substitutes: moderate and rising. Large consumer conglomerates switch between oleochemical and synthetic petrochemical feedstocks whenever the price spread between vegetable oils and crude oil widens. Over a longer horizon, industrial-scale fermentation processes for biosurfactants—such as rhamnolipids produced from sugar feedstocks—represent an emerging alternative that could gradually decouple detergent chemistry from agricultural land and fossil hydrocarbons.23
Rivalry: intense. The domestic surfactant sector remains crowded and burdened by surplus capacity, a structural squeeze underscored when BASF decided to decommission its Dahej sulfation facility.6
The Bull Case
Indian market expansion. Management is targeting 8% to 10% annual volume expansion in India, supported by the premiumization of personal-care routines and rising household penetration of liquid hand washes, body washes, and sunscreens. That domestic momentum was evident in the first quarter of FY27, when Indian shipping volumes expanded 11% year on year.195 Meanwhile, fast-growing direct-to-consumer personal-care brands, which rely more heavily on specialized ingredients and lack internal chemical formulation teams, continue to expand rapidly.13
Competitor consolidation and customer alignment. BASF's exit from Dahej removes roughly ₹540 crore of competitive domestic processing capacity, creating an opening for Galaxy to capture incremental Indian sulfation volume.6 Simultaneously, Unilever deepened its relationship with Galaxy by signing a long-term Partnership Growth Charter in August 2026 to co-invest in sustainable innovation, building on recent collaborative moves to establish dedicated capacity in North America closer to end consumers.325 For an intermediate supplier, this level of strategic integration is the closest an enterprise gets to a formal endorsement from its largest global account.
An elevated margin baseline. If normalized EBITDA per metric tonne stabilizes in the guided corridor of ₹21,000 to ₹22,000, Galaxy's structural earning power will settle approximately 10% above its FY26 baseline, even before accounting for incremental margin expansion from higher-value specialty product launches.5
International specialty expansion. Under Vision 2030, Galaxy projects volume growth of 10% to 12% annually across the rest of the world and the AMET region, driven predominantly by higher-margin specialty personal-care products as the company expands deeper into the United States and Europe.19 Early traction is visible in commercial rollouts such as TRI-K's Everbond hair-care active and a recovering specialty pipeline in the United States following the reduction in import tariffs.5 Outside North America, Asia-Pacific shipping volumes posted double-digit growth in the first quarter of FY27.5
Balance-sheet strength. A net-cash position, minimal debt, and an interest-coverage ratio exceeding 25 times provide Galaxy the liquidity to fund routine capital expenditure internally, sustain research and development through cyclical downturns, and pursue bolt-on corporate acquisitions without diluting equity shareholders.10
The Bear Case
Unit margins revert to historical baselines. Across three of the four fiscal years spanning FY24 through FY26, Galaxy's operating spread hovered around ₹20,000 per metric tonne.91 If the extraordinary earnings generated in the first quarter of FY27 prove to be an isolated windfall born of supply dislocations, the equity rerating sparked by that record performance could rapidly unwind.
Downstream reformulation risks resurface. Once global petrochemical intermediate supplies stabilize, consumer conglomerates could readily revive the substitution patterns seen in FY26. While management noted that relative input costs currently favor Galaxy's natural oleochemical chemistries, leadership conceded that the competitive dynamic requires a vigilant "wait and watch" approach.5
Chronic stagnation across AMET. Management has characterized the loss of regional market share to domestic competitors as an irreversible structural shift, leaving Galaxy's substantial manufacturing capacity in Suez tethered to an operating theatre that is no longer delivering robust volume growth for the group.135
Vision 2030 execution hurdles. Doubling consolidated shipping volumes by 2030 depends on commercial rollouts in unproven product categories and external corporate acquisitions that management has yet to demonstrate at scale. Nascent efforts in adjacent categories are already lagging internal expectations, as seen in the sluggish start to Galaxy's wellness ingredients initiative.1913
Consumer demand vulnerability. On the downstream demand front, executive leadership identified erratic monsoon patterns and persistent energy-driven inflation across emerging markets as primary threats that could dampen retail consumption during the second half of FY27.5
Why Galaxy Wins, and What Would Break It
Galaxy wins in commercial environments where supply reliability and strict process tolerances matter far more than securing the absolute lowest unit price. That operational sweet spot encompasses Tier-1 multinational formulations governed by exacting trace-impurity thresholds, fragmented regional and direct-to-consumer brands that depend on Galaxy for pre-formulated application expertise, and premium specialty niches in the United States served through TRI-K. The empirical evidence validates each of those pillars: customer relationships that have endured for more than four decades, the market exit of a well-capitalized global rival like BASF, and joint capital initiatives with Unilever.
The investment thesis would break if multinational consumer conglomerates leveraged their buyer power to steadily compress conversion processing spreads below sustainable levels, or if structural shifts in chemistry—whether toward synthetic petrochemicals or fermentation-based biosurfactants—eroded Galaxy's core volumes faster than its manufacturing lines could adapt. Over its four-decade operating history, Galaxy has consistently demonstrated that it can defend its market position against external shocks; what it has rarely demonstrated is the pricing power to structurally improve its commercial terms.
The 3 KPIs to Track
-
Consolidated sales volume growth (metric tonnes, year on year). This metric provides the purest measure of whether Galaxy is capturing or surrendering shelf share among brand owners, neutralizing the optical distortions of raw-material price swings and customer reformulation cycles. Management's ongoing baseline target calls for 6% to 8% annual expansion.5
-
EBITDA per metric tonne. As the defining yardstick of Galaxy's toll-conversion model, this figure isolates the cash spread generated on each physical unit shipped. The central analytical question for upcoming quarters is whether normalized spreads can hold above the ₹19,000 to ₹20,000 corridor seen between FY24 and FY26, validating management's raised baseline expectation of ₹21,000 to ₹22,000 per tonne.51
-
Specialty Care share of volume and revenue. This distribution tests whether the strategic initiatives under Vision 2030 are truly transforming the group's economic engine. Specialty Care has remained confined between 34% and 41% of consolidated revenue and volume for an entire decade; a sustained, multi-year breakout above that boundary would represent the first clear empirical evidence of a structural transformation into a higher-value specialty producer.91
XIII. Epilogue & The Next Frontier
Back to the Bathroom Sink
On an ordinary morning in late 2026, the foam in someone's toothpaste may contain SLS synthesized in Taloja. Their shampoo may rely on an amino-acid surfactant engineered in Navi Mumbai, and their conditioner may feature a protein produced in New Hampshire. Almost nobody using those products will have heard of Galaxy Surfactants—an invisibility typical for an intermediate supplier operating behind global consumer brands.
The founders' operational achievement is not in question. Five friends invested ₹20,000 each, started in a borrowed laboratory, and built an enterprise spanning seven manufacturing sites that has supplied Unilever for 45 years.83 For investors, however, the central question is what type of economic engine the business ultimately became. The financial record provides a clear answer: an operationally disciplined, highly trusted, and balance-sheet-conservative conversion processor whose margins remain structurally bounded by powerful buyers and volatile feedstocks. Its specialty ambitions are real, but over the past decade they have fortified the perimeter of the business rather than transformed its underlying unit economics.
The next chapter will turn on tests the enterprise has not previously faced. Can a company built by five founders accelerate volume growth under professional management? Can external acquisitions across beauty and wellness generate high returns without repeating the regional setbacks of Suez? And can dual-feedstock flexibility protect volumes when customer formulations next shift? The answers will not be found in headline revenue swings or one-off commodity windfalls, but in the physical tonnes Galaxy ships and the cash spread it extracts on each one.
References
-
Result Presentation, Q4 & FY26 — Galaxy Surfactants (NSE filing), 2026-05-14 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Galaxy Surfactants Limited IPO Grading Rationale — CRISIL Research, 2011-01-17 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Unilever, Galaxy Surfactants sign charter to accelerate R&D — Personal Care Magazine, 2026-08-25 ↩↩↩↩↩↩↩
-
Galaxy Surfactants shares hit 20% upper circuit on strong Q1 results — Upstox, 2026-08-14 ↩↩↩
-
Q1 FY27 Earnings Conference Call Transcript — Galaxy Surfactants (BSE filing), 2026-08-14 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
BASF India to shut two Care Chemicals plants at Dahej by end-2026 — Indian Chemical News, 2026-08-08 ↩↩↩↩↩
-
Decades of Care: Legacy and Growth — Galaxy Surfactants ↩↩↩↩↩
-
Started by five friends in the 80s, this Mumbai-based surfactant company now clocks Rs 2,563 crore annual turnover — YourStory via Dailyhunt ↩↩↩↩↩↩
-
Galaxy Surfactants Initiating Coverage: Cleansing the Path Ahead to Empiric Profitability — YES Securities, 2024-12-16 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Galaxy Surfactants Limited Rating Rationale — CRISIL Ratings, 2025-10-16 ↩↩↩↩↩↩↩
-
Galaxy Surfactants Q3 FY26 revenue up 28% to Rs. 1,334 Cr — Indian Chemical News, 2026-02-15 ↩
-
Galaxy Surfactants Q3 2026 Earnings Call Highlights — Yahoo Finance, 2026-02-16 ↩↩↩
-
Q4 and FY'26 Earnings Conference Call Transcript — Galaxy Surfactants (NSE filing), 2026-05-15 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Galaxy Surfactants Acquires TRI-K Industries — Happi, 2009-07-10 ↩↩↩↩
-
Galaxy Surfactants Q2 2026 Earnings Call Highlights — Yahoo Finance, 2025-11-13 ↩↩↩↩↩↩
-
Galaxy Surfactants withdraws IPO a day before its closing — Moneylife, 2011-05-19 ↩↩↩
-
U. Shekhar — Distinguished Alumnus Profile — IIM Calcutta ↩↩
-
Galaxy Surfactants lists at 3% premium, closes 14.74% higher over issue price — Business Today, 2018-02-08 ↩↩↩↩
-
Galaxy Surfactant Company Update: Strategic roadmap for accelerated growth — HDFC Securities, 2025-06-16 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Galaxy Surfactants files Annual Report for FY26 — ScanX, 2026-07-17 ↩↩↩
-
1,4-Dioxane Limits for Household Cleansing, Personal Care, and Cosmetic Products — New York State DEC ↩↩
-
Galaxy Surfactants Q4 2025 Earnings Call Highlights — Yahoo Finance, 2025-05-19 ↩↩
-
Evonik drives sustainable biosurfactant revolution with inauguration of new facility in Slovakia — Evonik, 2024-05-29 ↩↩
-
Galaxy Surfactants rejigs leadership team, K. Natarajan is the new MD — Indian Chemical News, 2024-03-05 ↩↩↩
-
Unilever and Galaxy to scale sustainable surfactant technology — Personal Care Insights, 2026-08-24 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube