Gabriel India: From Shock Absorbers to the ANAND Group's ₹50,000 Crore Bet
I. Introduction & Cold Open
On the morning of July 22, 2026, the board of a 64-year-old company that makes the thing that stops your motorcycle from rattling your spine sat down to approve the largest transaction in its history.
The two items on the agenda made for an odd pairing. The first was the quarter: revenue up, margins down, the EBITDA line slipping under nine percent as commodity costs ran ahead of the price increases the company had negotiated with its customers. The second was a proposal to spend ₹2,231 crore buying a 28.99% stake in HL Mando Anand India — a steering and braking joint venture — from Asia Investments Private Limited, the promoter entity that already controlled Gabriel India itself.4
The market's verdict arrived within hours. Gabriel India's shares fell close to 7%, the sharpest single-day drawdown the stock had seen in months, as investors digested a related-party purchase roughly a tenth the size of the company's own market capitalisation announced on the same day as a margin miss.2
To understand why that reaction was both reasonable and incomplete, you need to hold two facts in mind simultaneously.
The first is that Gabriel India has been, on the operating numbers, one of the better compounding stories in Indian auto components. Consolidated revenue rose from roughly ₹1,681 crore in FY21 to about ₹4,667 crore in FY26 — a near-tripling in five years. Net income moved from roughly ₹60 crore to about ₹252 crore over the same stretch, with earnings per share climbing from ₹4.20 to ₹17.55.3 None of that required a single acquisition. It came from shock absorbers, struts, front forks and a replacement-parts network that reaches into small-town India.
The second is that this company — market capitalisation around ₹21,000 crore, a stock that has round-tripped between roughly ₹796 and ₹1,600 over the past twelve months3 — is in the middle of being structurally rewritten. Over fourteen months spanning 2025 and 2026, Gabriel India has absorbed or agreed to absorb stakes in at least six businesses, almost all of them purchased from its own promoter, financed partly with newly issued shares to that same promoter, and backed by a ₹1,000 crore non-convertible debenture programme that will take a historically debt-light balance sheet toward roughly one-to-one leverage.811
So here is the question this story tries to answer honestly: is Gabriel India becoming the ANAND Group's disciplined consolidation platform — the listed vehicle through which a family-controlled industrial group assembles a diversified mobility business with access to global joint-venture technology it could never have built alone? Or is it a listed shell absorbing promoter-owned assets on promoter-determined terms, with minority shareholders along for a ride they did not choose?
The uncomfortable answer, which the rest of this piece will earn rather than assert, is that both can be true at once — and that the evidence needed to separate them has not yet been disclosed.
The path runs through four things. First, the origins: a 27-year-old engineer, a licence from an American company, and a plant in Mulund. Second, the ride-control franchise that still pays every bill — and the genuinely different competitive games Gabriel plays in two-wheelers, passenger cars, and commercial vehicles. Third, the 2025-26 restructuring, which is where the investment case actually changed. Fourth, what a long-term holder should watch to know, two or three years from now, which version of this story turned out to be real.
 Subscribe on LinkedIn
II. Origins: Deep C. Anand and a 1961 Bet on Shock Absorbers
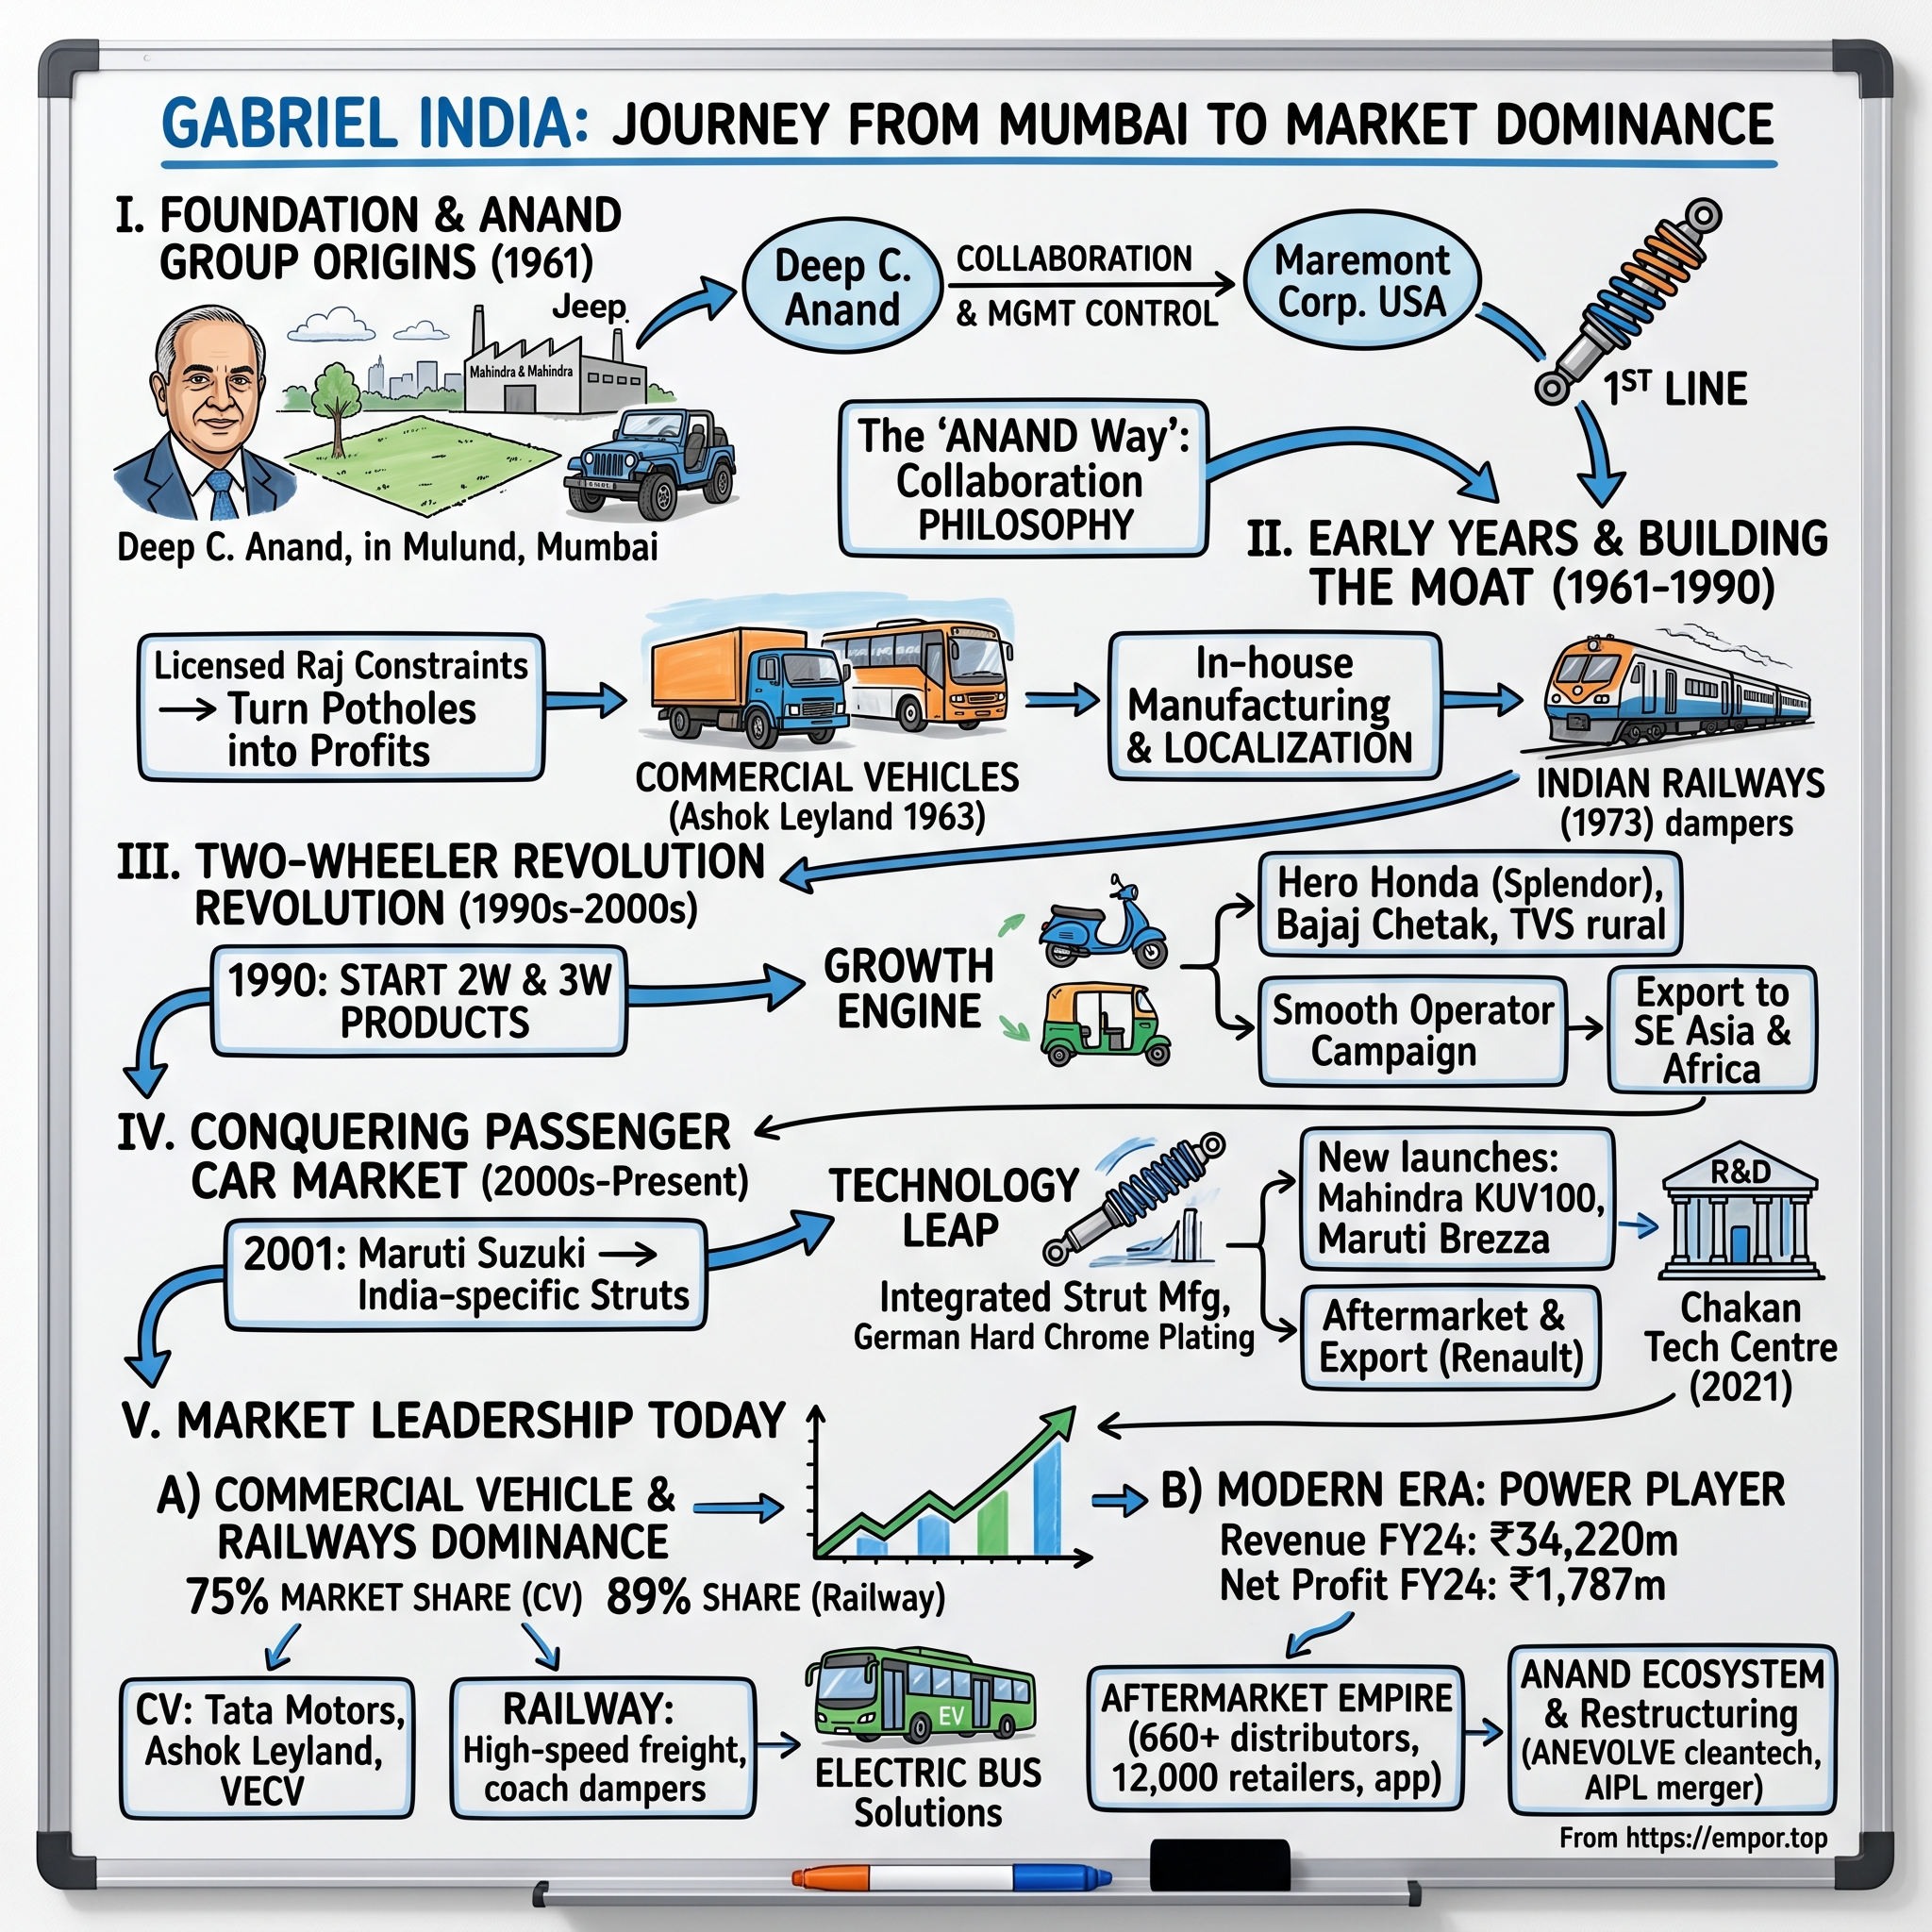
In 1961, a mechanical engineer named Deep C. Anand left a steady job as Plant Manager at Mahindra & Mahindra to start a company making a part that almost nobody in India manufactured and almost everybody assumed you imported. He was 27.
The part was the shock absorber — the hydraulic damper that sits between a vehicle's wheel and its body and turns the violence of a pothole into a manageable compression. In a country whose roads in 1961 were, to put it gently, a rigorous test environment, this was not a trivial product. It was also not a product Indian industry knew how to make to any reliable standard.
Anand's solution set the template for everything that followed. Rather than attempt to invent the technology, he licensed it — striking a technical collaboration with the Maremont Corporation of the United States, whose Gabriel brand of shock absorbers was already established in American automotive markets. The Indian company took the Gabriel name, the Gabriel designs, and the discipline of manufacturing to an American specification, and set about building them in Mulund, on the northern edge of Mumbai.5
It is worth pausing on how unusual this was in 1961. India's industrial policy of the period was built around import substitution and licensed capacity, a regime that rewarded whoever could secure a manufacturing licence and then protected them from competition. Most entrepreneurs treated foreign technology as a one-time input: buy the drawings, make the part, keep the margin. Anand treated the foreign partner as a permanent structural relationship — a source of continuously refreshed engineering rather than a static blueprint.
That distinction compounded over six decades. The company Anand built around Gabriel India — what became the ANAND Group — grew into a portfolio of joint ventures with an almost improbable roster of global component majors: Dana of the United States in axles and driveshafts, Henkel of Germany in adhesives and sealants, Mahle in filtration and thermal systems, HL Mando of Korea in steering and braking, Valeo in friction materials, SKF in bearings.19 Each followed roughly the same shape: the global partner brought the technology and the quality system; ANAND brought Indian manufacturing, local supply chains, and the relationships with Indian OEMs that a foreign entrant could not replicate quickly.
For most of those sixty years, this structure had a peculiar consequence for public-market investors. Gabriel India was listed. The joint ventures, for the most part, were not — they sat inside Asia Investments and other promoter-held entities. A shareholder buying Gabriel India bought shock absorbers. The rest of the empire was visible but unreachable, a shape glimpsed through frosted glass.
That is the single most important thing to carry forward from the origin story. The history matters here not as nostalgia but as mechanism: the partnership playbook Deep C. Anand invented in 1961 is precisely the playbook the group is now executing at conglomerate scale — except that in 2025-26, the thing being assembled is not a new joint venture but the existing ones, and the assembly point is the listed company.
Before we get to that, though, the listed company had to become worth using as a platform. That took the better part of forty years.
III. Building the Franchise: License Raj to the Two-Wheeler Boom
For its first three decades, Gabriel India was a one-product company in a market that did not reward variety.
The License Raj economy of the 1960s through the 1980s produced a specific kind of supplier relationship: OEM demand was capped by licensed production quotas, model cycles ran for decades rather than years, and the incentive to engineer a better damper was muted by the fact that the customer could not build more vehicles anyway. Gabriel sold shock absorbers to a small, slow-moving set of Indian vehicle makers, and the business grew roughly at the pace those customers were permitted to grow.
The 1991 liberalisation changed the denominator. But the change that actually made Gabriel India what it is today was narrower and, at the time, less obvious: India's two-wheeler boom.
Through the 1990s and 2000s, motorcycle and scooter volumes in India went from a middle-class aspiration to the default form of household mobility. Hero, Bajaj and TVS scaled into some of the highest-volume two-wheeler manufacturers on earth. Every one of those vehicles needed a front fork and a rear shock absorber. Unlike passenger cars — where global suspension majors could and did follow their OEM customers into India — the two-wheeler segment was won on cost, on volume, and on being physically close to assembly lines that ran enormous throughput at thin unit economics.
Gabriel leaned into it hard, and that decision still defines the company's revenue mix. Two- and three-wheeler ride control has remained the largest single slice of the business ever since.5
The second structural move was product breadth. A company that made one damper design in 1961 now manufactures a catalogue of roughly 500 products spanning shock absorbers, struts, front forks, cabin dampers and specialised suspension for rail applications, supported by a patent portfolio that the company puts at more than 75 filings.56 The passenger-vehicle entry, when it came, was a genuine extension rather than a pivot: the underlying physics of hydraulic damping transfers, but the tolerances, the NVH expectations and the OEM qualification burden all step up considerably.
What did all this add up to strategically? Two things worth naming plainly.
First, Gabriel converted a licensed foreign technology into a domestically engineered capability. That is not a small achievement, and it is the reason the company can now credibly talk about backward integration into front-fork casting rather than simply assembling imported components.
Second — and this cuts the other way — the breadth is horizontal, not vertical. Five hundred products across three vehicle categories is evidence of engineering capability and customer coverage. It is not, by itself, evidence of pricing power. A supplier can hold a wide catalogue and still be a price-taker if the buyers are few and large, which, as the next section shows, they mostly are.
By the early 2020s, then, Gabriel India was a good business with a specific shape: a durable, unglamorous, volume-driven ride-control franchise with real share in the segments that matter to Indian mobility, modest margins, almost no debt, and a growth rate that quietly outran most of its listed peers. The question the restructuring poses is whether that shape was the ceiling or the foundation. To answer it, you have to understand what the core business actually is.
IV. The Core Business Today: Industry Structure, Competitors, Economics
Walk the aisles of an Indian auto-component trade show and the suspension stands all look roughly alike: cutaway dampers, polished tubes, a video loop of a wheel absorbing a kerb. What you cannot see from the booth is that the companies behind those near-identical products are playing three entirely different competitive games — and Gabriel India plays all three at once.
Three businesses wearing one uniform
Start with the FY26 revenue map, because it is the frame for everything that follows.
Two- and three-wheeler ride control accounted for roughly 57% of revenue and grew about 15% over the year. Passenger vehicles contributed roughly 23%, growing faster at about 24%, on the back of a suspension share management puts at around a quarter of the Indian PV market. Commercial vehicles and railways together made up around 20% — the smallest slice, and by some distance the fastest-growing, with commercial vehicles up roughly 34% and railways up about 40%.71
Now the competitive reality behind each of those numbers.
In two- and three-wheelers, Gabriel is not the leader. Endurance Technologies is, with something in the region of 40% of the category, and Endurance is materially the larger company — a market capitalisation in the ₹37,000–42,000 crore range against Gabriel's roughly ₹21,000 crore, trading at a price-to-earnings multiple in the mid-forties, roughly double Gabriel's on a scale-adjusted basis.183 Behind those two sit Munjal Showa, carrying the Hero-Showa lineage with roughly 17% of two- and three-wheeler suspension and a low-single-digit presence in passenger vehicles, and the Toyota-linked KYB operations at around 6%.5 This is a real fight among well-capitalised incumbents, each with entrenched OEM relationships, and it is where more than half of Gabriel's revenue sits.
In passenger vehicles, the game changes. Here Gabriel competes against global suspension majors — Tenneco with its Monroe brand, ZF, and the premium end where international OEMs bring their home-market supplier preferences to India. The contest is one of scale economics and engineering-change cost: once a damper is tuned into a specific vehicle platform's ride-and-handling signature and validated through the OEM's durability cycle, swapping it out mid-cycle is expensive and slow. Switching costs here are real but time-limited; they reset at every model changeover.
In commercial vehicles and railways, the game changes again, and dramatically. Gabriel's share in this segment runs around 88-89%, with limited named domestic competition.57 On its face, that is the most attractive position in the entire portfolio: near-monopoly share in the fastest-growing segment.
The moat, tested rather than asserted
What is the evidence that this franchise defends itself?
The capability evidence is substantial and worth laying out. Gabriel operates eight manufacturing plants with a ninth planned in South India that will include backward-integrated front-fork casting — a move that pulls a bought-in component in-house and, if it works, removes a cost and a supply dependency simultaneously.1 The aftermarket network spans more than 800 dealers, nine carrying-and-forwarding agents and over 30,000 retail outlets, supporting a replacement-market share the company puts above 40%.5 Add the roughly 500-product catalogue and the 75-plus patents, and you have a supplier that is genuinely hard to replicate from a standing start.
But capability is not the same as pricing power, and this distinction deserves to be made sharply rather than glossed.
Patents and plant counts tell you a competitor would need years and capital to match Gabriel's footprint. They tell you nothing about whether Gabriel can raise prices. The actual test of pricing power is the margin trend — and through FY26 into FY27, Gabriel's EBITDA margin has been compressing, not expanding.1 A business with genuine pricing power passes commodity inflation through promptly. A business without it absorbs the gap and explains the lag on the earnings call. Gabriel, on the Q1 FY27 call, did the latter.
The structural reason sits in the channel mix: roughly 88% of revenue comes through OEM channels, with only about 12% through the replacement market.5 That is the wrong way around for margin durability. The replacement market is fragmented, brand-sensitive and higher-margin — it is where the 30,000 retail outlets actually earn their keep. The OEM channel is concentrated, annually renegotiated, and structurally favours the buyer. When nine-tenths of your revenue sits with a handful of large customers who run competitive sourcing processes and settle commodity pass-throughs on their own timetable, bargaining power lives on their side of the table.
The concentration problem hiding inside the best segment
Which brings us to the most interesting analytical wrinkle in the core business: the CV and railways franchise, the one with 88-89% share, is also the one with the most concentrated and most politically exposed customer base.
Railways in India means Indian Railways — a state-owned buyer that procures through tenders, periodically restructures its vendor base, pursues explicit indigenisation and vendor-diversification policies, and can change technical specifications in ways that reopen a settled supply position. Commercial-vehicle and bus demand skews toward state transport undertakings and PSU-adjacent fleet buyers with similar procurement dynamics.
This matters because a near-monopoly share held against a single dominant buyer class is not the same asset as a near-monopoly share held across thousands of independent customers. In the first case, the supplier's share is, at least partly, the buyer's choice — and the buyer can revisit it. A dominant position in front of a monopsony buyer with an explicit policy interest in cultivating alternative vendors should be assessed as a strong but conditional franchise, not a cornered resource.
The honest calibration, then: Gabriel's moat is real but narrower than the headline share numbers imply. It rests on OEM incumbency, engineering-change costs within model cycles, and genuine distribution reach in the replacement market. It does not currently manifest as pricing power, and the segment where share looks most dominant is the segment where the customer has the most structural leverage to reduce it.
What would change that assessment? A sustained period of margin expansion through a commodity up-cycle — the single cleanest proof that Gabriel is setting prices rather than accepting them. That has not happened yet.
Which makes the growth vectors matter more. And the loudest of those is electrification.
V. The EV Pivot: Front Forks, E2W Share, and a Powertrain-Agnostic Bet
There is a quietly reassuring fact about suspension in an age of powertrain disruption: an electron-powered motorcycle still has to absorb a pothole.
This is the structural comfort at the heart of Gabriel's electric-vehicle story, and it is genuine. Companies that make fuel-injection systems, exhausts, clutches and gearboxes face an existential question as internal combustion gives way. Companies that make dampers and forks face a product-engineering question instead. Electric two-wheelers are typically heavier than their petrol equivalents, carry their mass lower and differently because of battery placement, and deliver torque in a way that changes how the front end loads under acceleration. That means the suspension has to be redesigned — but it still has to exist, and the company that redesigns it first gets designed into the platform.
Gabriel claims to have won that race. Management puts the company's share of India's electric two-wheeler suspension market at around 60%, supplying Ola Electric, Ather, TVS, Ampere and Ultraviolette.57
What the number is, and what it isn't
Take the claim seriously — and then bound it properly.
The affirmative evidence goes beyond the share percentage. The single-source win on the inverted front fork for the Piaggio RS 457 is a specific, verifiable proof point: an inverted fork is a premium, technically demanding architecture, and a single-source award on a globally sold motorcycle platform is a different quality of validation than a domestic volume contract.5 The decision to backward-integrate front-fork casting at the planned South India facility is a second, more commercial signal — you do not fund casting capacity for a product line you expect to stay small.1
Now the bounding, which matters just as much.
Electric two-wheelers remain a minority of a two- and three-wheeler segment that is itself around 57% of revenue. Sixty percent of a small thing is a small thing. More importantly, Gabriel has not disclosed E2W-specific revenue or margin — there is no line item that tells an investor what this franchise earns, whether its contribution per vehicle exceeds the ICE equivalent, or whether the share is being held on price.
And there is a falsification test that belongs right here, next to the claim rather than buried in a risks list: India's electric two-wheeler penetration has repeatedly run behind consensus forecasts over the past decade. Adoption curves projected in the late 2010s and again in the early 2020s have been revised down more often than up, on a combination of subsidy-policy volatility, charging infrastructure, battery costs and the simple durability of a very cheap, very well-understood petrol alternative. A supplier's share of a market is only worth what the market's volume turns out to be.
The calibrated conclusion: the E2W position is a real competitive win, evidenced by more than management assertion, but it is unproven at economic scale. It should be held as a credible forward option rather than counted as a current earnings driver. The event that would confirm it is segment-level disclosure — E2W revenue and contribution margin broken out. The event that would falsify it is a repeat of the last decade's pattern, in which the penetration curve slips right again and 60% of a delayed market stays a press-release number.
The smaller bets, sized honestly
Two other diversification moves deserve a mention proportional to their economic weight, which is currently small.
The first is a joint venture with SK Enmove — Gabriel holding 49% to SK Enmove's 51% — targeting India's lubricants and EV-fluids market.7 Thermal-management fluids for electric drivetrains are a genuinely growing category and the partner brings real formulation capability. But Gabriel is the minority holder in a business with no disclosed India revenue.
The second is a push into e-bike and bicycle components for export.16 Interesting as a use of existing fork and damper engineering, early in every respect.
Both belong in the story. Neither belongs in a forecast. The pattern worth noticing is that Gabriel's management has a habit of announcing optionality with confidence and disclosing it with reticence — a combination that requires investors to discount the announcements until the disclosure catches up.
That same tension — big strategic claims, thin segment-level disclosure — runs directly into the two transactions that have rewritten this company's identity.
VI. The 2025-26 Reinvention: Project Rise, Project Jupiter, and the ANAND Group Roll-Up
On June 30, 2025, Gabriel India filed a corporate announcement describing a Composite Scheme of Arrangement.10 The next trading day, the stock soared.17
That initial enthusiasm is worth remembering, because it frames the puzzle of the fourteen months that followed. The market's first instinct was that a shock-absorber company gaining access to the ANAND Group's joint-venture portfolio was straightforwardly good news. Its instinct thirteen months later, when the second and larger transaction arrived, was a 7% decline. Between those two reactions lies everything an investor needs to think carefully about.
Project Rise: the portfolio arrives
The first transaction — internally branded Project Rise — moved Asia Investments Private Limited's automotive business into Gabriel India.13 It received NCLT approval and became effective on May 22, 2026.
What came across was four assets of very different character.
Anchemco India transferred as a wholly owned subsidiary — a chemicals business making brake fluid, coolants, diesel exhaust fluid and adhesives. This is the one that looks least like Gabriel and, arguably, fits best: consumable automotive chemicals sold partly through the same replacement channels Gabriel already serves, with a demand profile tied to the vehicle parc rather than new-vehicle production.
Dana Anand came across as a 25.1% stake — axles, driveshafts and electric-vehicle transmission products, built on the partnership with Dana Incorporated. By size and profitability, this is the most significant of the four, and it is a minority holding, which matters for a reason we will return to.
Henkel Anand arrived at 49% — sealants, adhesives and noise-vibration-harshness materials with Henkel KGaA. Anand CY Myutec came across at 76% — synchroniser rings and transmission electronics with Korea's CY Myutec.
The strategic logic is coherent on its face. Gabriel's content per vehicle in a suspension-only world is bounded by physics. A company that also supplies driveline components, transmission parts, adhesives and fluids sells several times more value into the same vehicle, to the same purchasing department, through the same relationship. That is the standard component-consolidator argument, and it is not wrong.
But the ownership structure complicates it. Gabriel consolidates Anchemco fully and Anand CY Myutec at 76%. Dana Anand at 25.1% and Henkel Anand at 49% are associate stakes — they contribute to profit via equity accounting but not to revenue, and critically, Gabriel does not control them. An investor should be careful about the language of "platform" and "integration" when applied to holdings where the listed company cannot direct capital allocation, set pricing, or force operational synergy. Owning a quarter of a good business is a financial position. It is not a platform.
The vote nobody quite published
Here the governance thread begins, and it deserves precision rather than outrage.
The scheme was approved at an NCLT-convened shareholder meeting on March 18, 2026, with 99.99% of votes cast in favour.13 That is the headline number, and it is accurate.
It is also, on its own, close to uninformative. The promoter group held roughly 55% of Gabriel India before the scheme.3 In a vote where the promoter is the counterparty — Asia Investments was selling these assets to Gabriel — the meaningful statistic is not the aggregate tally but the separate count of public, non-related shareholders. SEBI's related-party framework exists precisely to isolate that number, because a transaction in which the seller votes its own controlling block is not a shareholder endorsement of anything.
Public reporting does not clearly disclose the separate majority-of-minority tally for this scheme. That is not an allegation of impropriety; NCLT-convened scheme meetings operate under a different procedural regime from ordinary related-party resolutions, and the requirement may have been satisfied without being separately reported. But it does mean that the 99.99% figure cannot be used as evidence that minority shareholders approved this deal. It is evidence that a vote happened.
For context on what Gabriel's minority base actually does when it has reservations: the company's shareholders approved the re-appointment of independent director Pallavi Joshi Bakhru with 91.88% of votes in favour — a number well short of unanimous, which tells you this shareholder register is capable of registering dissent when it wants to.12 That makes the absence of a disclosed minority tally on the far more consequential scheme vote more conspicuous, not less.
Project Jupiter: the big one
Thirteen months later came the transaction that moved the stock the other way.
Project Jupiter, announced alongside the Q1 FY27 results, comprised two purchases totalling roughly ₹3,166 crore. The larger was a 28.99% stake in HL Mando Anand India — the steering, braking and suspension joint venture with Korea's HL Mando — acquired from Asia Investments for ₹2,231 crore. HL Mando Anand posted FY26 turnover of roughly ₹5,886 crore and profit of about ₹358 crore.4 The smaller was a roughly 30% stake in HL Klemove India, the advanced-driver-assistance and autonomous-driving joint venture, for $98.44 million.4
Take HL Klemove first, because it should be sized the way every optionality bet in this story gets sized: at its economic weight, not its press-release prominence. ADAS localisation in India is a genuine technology capability — radar, camera and sensor-fusion systems that let a vehicle see and react. It is also, in the Indian market as of today, a capability without disclosed revenue. Gabriel has not published standalone HL Klemove financials. This is roughly a quarter of the Jupiter outlay deployed into a certification-and-technology story rather than a commercialisation one, and it should be held as speculative until the numbers appear.
The valuation question, benchmarked
Now the part that a skeptical investor should sit with.
A 28.99% stake priced at ₹2,231 crore implies a full-company valuation for HL Mando Anand of roughly ₹7,700 crore. Against FY26 profit of about ₹358 crore, that is a trailing price-to-earnings multiple in the region of 21-22 times.4
Is that fair? The transaction was priced via an independent joint valuation conducted by KPMG Valuation Services LLP and BDO Valuation Advisory LLP, and management has characterised it as arm's length.4 That process is a meaningful procedural safeguard and should be credited as such. But "an independent valuer produced a number" and "the number is favourable to minority shareholders" are different claims, and only the first is verified.
The benchmarks cut in two directions, which is why the honest answer is genuinely mixed. Twenty-one times trailing earnings is well below Endurance Technologies' mid-forties multiple.18 It is broadly in the neighbourhood of Gabriel's own trading multiple. For a business with near ₹5,900 crore of revenue growing in a segment — steering and braking — with higher technology content and arguably better structural economics than ride control, that is not a prima facie fleecing.
Against that: Gabriel is buying a minority stake, and minority stakes conventionally trade at a discount to control, not at parity. There is no competitive process here — no auction, no second bidder, no market test of whether ₹7,700 crore is what an unrelated buyer would pay. And the promoter sits on both sides.
The calibrated read: the price is defensible on multiples but unproven on process. It is not evidence of expropriation. It is also not evidence of a bargain, and investors who want to treat management's "fair value" characterisation as settled should note that the only thing genuinely settled is that two valuation firms were engaged.
The financing mechanism is the governance story
The structure of how Gabriel pays for Jupiter is, analytically, the most important detail of the entire transaction — and the easiest to skim past.
Gabriel funds the ₹2,231 crore HL Mando Anand purchase with ₹350 crore in cash and ₹1,881 crore in preferential shares issued to Asia Investments at ₹1,305.89 per share.4
Read that carefully. The promoter sells an asset to the listed company and is paid, for roughly five-sixths of the consideration, in newly issued shares of that same listed company. The transaction therefore simultaneously transfers the asset in and pushes promoter ownership up. Promoter shareholding had already risen from roughly 55% to about 63.5% through Project Rise.3 On completion of Jupiter, it moves toward roughly 66.3%.
So within about fourteen months, a set of promoter-to-company transactions will have taken the controlling family's stake up by more than eleven percentage points while diluting every public shareholder proportionally — and the vehicle for that increase is the consideration for assets the same family sold in. Whether the assets are good and whether the price is fair are separate questions from whether this mechanism is one minority holders would have chosen. It is not buried detail; it is the design.
No track record to lean on
There is one more thing to say, and it is the most important constraint on how much benefit of the doubt anyone should extend.
Gabriel India has no prior large-scale M&A record. This roll-up is, by a very wide margin, the largest capital deployment in the company's 64-year history. There is no earlier acquisition to point at and say: they did this before, it worked, they were disciplined about price, they integrated it on schedule.
That absence cuts against management, not for it. The standard investor move — "they've earned the benefit of the doubt" — requires a doubt that was previously resolved favourably. Here there is nothing to resolve it against. The closest available comparison is the ANAND Group's broader joint-venture history, which genuinely is long and genuinely is successful: a partnership model running from Maremont in 1961 through Dana, Henkel, Mahle, HL Mando and Valeo.19 But building joint ventures over sixty years and executing a ₹5,000-crore-plus consolidation inside a listed company in twenty-four months test different muscles. The first is patient relationship-building. The second is integration, capital discipline and minority-shareholder stewardship under quarterly scrutiny.
All of this sits inside a stated strategic frame: Chairperson Anjali Singh's articulated ambition of ₹50,000 crore in group revenue by 2030, from an estimated base somewhere in the ₹15,000-20,000 crore range today. That is management's framing of why the roll-up is happening, and it should be read as exactly that — a stated ambition, not a verified target, and one that implies further transactions of this kind.
Which makes the people setting that direction the next thing to examine.
VII. Current Management: Ownership, Incentives, and Credibility
If you wanted to design a leadership structure that maximises the tension between conglomerate-building and minority-shareholder stewardship, you would have a hard time improving on Gabriel India's as of mid-2026.
Anjali Anand Singh: the second generation, building outward
Anjali Anand Singh chairs both Gabriel India and the ANAND Group — the second generation of the founding family, and the architect of the consolidation strategy.19
Her strategic thesis is consistent and, on its own terms, logical. Indian auto components is fragmenting into two futures: a commodity tier squeezed between OEM purchasing power and Chinese cost, and a technology tier where content per vehicle rises with electrification, safety regulation and ADAS mandates. A group holding minority and majority positions across a dozen technology joint ventures, scattered across unlisted entities, cannot easily raise capital against them or present a coherent story to investors. Consolidating them into a listed platform solves both problems at once.
The question is not whether the thesis is coherent. It is whether the execution serves all shareholders or primarily the controlling family. And the appropriate discipline here is the one this piece has applied throughout: assess public statements against the concrete deal terms rather than repeating them. Those terms — promoter as seller, preferential shares as currency, ownership rising past two-thirds, minority tally undisclosed — are facts that exist independently of anyone's stated intent.
Mahendra K. Goyal: the bandwidth problem
In July 2026, Gabriel India appointed Mahendra K. Goyal as Executive Director, Group CEO and Managing Director for a five-year term.14
His credentials are, in a narrow sense, close to ideal for what the company is attempting. Goyal is a chartered accountant, a company secretary and a cost accountant — three qualifications that map almost exactly onto the demands of a multi-entity consolidation involving different accounting treatments, transfer-pricing exposure and statutory complexity. He holds an Advanced Management Programme credential from Oxford. And he has been inside the ANAND Group since 1995, meaning three decades of relationships with the joint-venture partners whose businesses Gabriel is now buying into.14
That last point is where the credibility question turns, and it should be stated plainly rather than softened.
Goyal simultaneously chairs or serves on the boards of Dana Anand, HL Mando Anand, Mahle Anand Filter Systems, Mahle Anand Thermal Systems and Valeo Friction Materials — while running Gabriel India.14
Two distinct problems follow. The first is bandwidth: five board positions plus an executive mandate to integrate four-to-six newly consolidated entities and run a ₹4,667 crore operating business is an extraordinary allocation of one person's attention, at precisely the moment when integration failures are most likely and most costly.
The second is structural conflict, and it is sharper. Gabriel is buying stakes in Dana Anand and HL Mando Anand from the promoter. Goyal sits on the boards of both. He is, in effect, positioned on the buy side, the sell side and the asset side of transactions that transfer over ₹5,000 crore of value between related entities. Indian corporate law and SEBI's framework provide for interested-director recusal, and the presumption should be that formal procedure was followed. But recusal on a specific resolution does not neutralise the information and relationship asymmetry that comes from occupying every seat at the table. This is not a one-time disclosure item to be checked off; it is a standing structural feature of how the ANAND Group is organised, and it will persist through every future transaction in the ₹50,000 crore plan.
Atul Jaggi and the separated mandate
There is a genuine mitigant in the structure, and it deserves credit.
Atul Jaggi serves as Managing Director of the Ride Control business — the legacy core — having taken over from Manoj Kolhatkar.15 The split is meaningful: a Group CEO facing outward toward conglomerate strategy and transaction execution, and a separate managing director whose entire mandate is the shock absorbers, forks and struts that generate essentially all of today's cash.
That design suggests the board recognised the risk that a transformative M&A programme would starve the operating business of senior attention. Whether it works is an empirical question, and there is one early data point that is not encouraging: margins compressed in the quarter that Jupiter was announced. One quarter proves nothing about causation. But the whole purpose of separating the mandates was to prevent exactly that coincidence from becoming a pattern.
What can actually be tested today
On capital allocation, the honest position is that there is almost nothing to test. No meaningful prior M&A. No history of write-offs or marked-down investments to examine. No pattern of announced-then-abandoned ventures. The roll-up is the first real examination, and its results are years away.
But one thing is testable right now, and it is a genuine strategy change rather than routine financing.
Gabriel India ran a near-debt-free balance sheet for essentially its entire modern history, with leverage that sat comfortably below 0.2 times equity. The company is now establishing a ₹1,000 crore non-convertible debenture programme, with debt-to-equity projected toward roughly one-to-one.118
That is not incremental. A company whose conservatism was a defining characteristic — one of the reasons a certain kind of investor owned it at all — is deliberately becoming a moderately levered acquisition vehicle. Management is entitled to make that choice. But it should be described as what it is: a change in the fundamental risk profile of the equity, made by a management team with no demonstrated track record of deploying leverage, at a moment when operating margins are contracting.
The numbers tell that story more precisely.
VIII. The Numbers: Growth, Margins, and the New Balance Sheet
Strip away the transactions for a moment and look at what Gabriel India did operationally over five years, because it is genuinely impressive and it happened without any of this.
The compounding that came first
Consolidated revenue went from roughly ₹1,681 crore in FY21 to about ₹4,667 crore in FY26. Net income rose from roughly ₹60 crore to about ₹252 crore. Earnings per share climbed from ₹4.20 to ₹17.55.3
Translated: revenue compounded at roughly 23% a year and net income at roughly 33%. Earnings growing meaningfully faster than revenue means margins expanded over the period — the company converted scale into profitability rather than simply buying volume.
That matters for two reasons. First, it establishes that the operating business was working before the restructuring, which pre-empts the most cynical reading of the roll-up (that management needed acquisitions to manufacture growth). Second, it sets a bar. Gabriel is now deploying the largest capital commitment in its history into assets that will have to earn returns comparable to what the base business was already generating organically. Acquisition-driven growth that dilutes the return profile of a 33%-compounding earnings base is not progress, however much revenue it adds.
The margin problem, and how management explains it
Then the trend turned.
In the first quarter of FY27, EBITDA margin came in around 8.4% on a standalone basis and roughly 8.7% consolidated, against approximately 9.3% a year earlier.1 Roughly 90 basis points of compression.
On the Q1 FY27 call, management attributed this to commodity inflation combined with a timing lag between input-cost movements and the price-recovery settlements negotiated with OEM customers.1 The implication conveyed was that this resolves over a quarter or two as recoveries catch up.
That mechanism is real and standard across the auto-component industry. OEM contracts typically index raw-material pass-through to agreed formulas settled quarterly or half-yearly, so a sharp input move shows up in supplier margins before it shows up in supplier pricing. The explanation is not evasive, and management gave a specific mechanism rather than a vague one — which, on the credibility scale that matters, counts for something.
But there are two reasons to treat it as a claim to be tracked rather than a fact to be accepted.
The first is definitional. If the lag is genuinely a timing issue, margins recover within two to three quarters and the FY27 dip becomes a footnote. If margins stay at or below 8.5% through FY27 and into FY28, then what management described as a lag was actually a structural repricing — Gabriel absorbing cost that it lacks the market power to pass on. The two explanations look identical for one quarter and completely different for four. This is the same pricing-power question raised earlier, now with a live test running.
The second is that the company is getting more exposed to this mechanism, not less. Every newly consolidated entity — Anchemco's chemicals, Anand CY Myutec's transmission components, and eventually the associate-accounted stakes — carries its own OEM-linked commodity exposure with its own pass-through lag. A larger, more complex group has more places for this effect to originate and less transparency into where.
The balance sheet becomes a different instrument
In August 2026, CRISIL affirmed and assigned a Crisil AA+/Stable rating on the new ₹1,000 crore NCD programme.118
AA+ is a strong rating — it signals a credit view that this company can comfortably service the debt it is taking on, and it is not the kind of assessment a rating agency issues casually to a business it thinks is overextending. That should be weighed properly on the positive side of the ledger.
But the more revealing fact sits alongside the rating rather than in it: the debt-to-equity trajectory is projected toward roughly one-to-one, against a history that ran below 0.2 times.8 Compare this against the pre-transaction baseline — CRISIL's July 2025 rationale reflected a fundamentally different leverage profile, one appropriate to a conservatively financed industrial compounder.9
This is the single clearest, most concrete piece of evidence that the financial character of Gabriel India has changed. Not a forecast, not a strategic intention — a rated, documented instrument.
What does leverage of that order actually do? It amplifies. A business earning high-single-digit EBITDA margins with roughly one-to-one debt-to-equity has meaningfully less room to absorb a demand shock, a commodity spike, or an integration that takes longer than planned. In a good scenario, the borrowed capital buys assets that earn above the cost of debt and equity holders capture the spread. In a poor one, fixed interest obligations meet compressing margins, and the equity absorbs the difference. Neither outcome is predictable today. What is knowable is that the range of outcomes has widened — which is the actual meaning of a risk-profile change.
The three things that matter
Out of everything in Gabriel India's reporting, three indicators carry most of the informational weight going forward.
EBITDA margin trajectory is the first and most important. It simultaneously tests the pricing-power question, the integration question, and management's credibility on the timing-lag explanation. A single metric that adjudicates three separate theses is rare, and this one does.
The divergence between standalone and consolidated growth is the second. Standalone tells you what the ride-control business is doing on its own. Consolidated tells you what the roll-up is contributing. The gap between them is the cleanest available read on whether the acquired assets are adding value or merely adding size.
Debt-to-equity against the CRISIL rating is the third — the measure of whether the financing plan is tracking to the agency's assumptions or drifting past them.
Two further items are worth watching without elevating to headline status: any standalone disclosure on E2W or HL Klemove revenue, and progress toward management's stated target of lifting export share from low single digits toward 15-20% by 2030.16 The export target in particular is a useful management-credibility instrument — it is specific, time-bound, and publicly stated, which means it can be scored.
IX. Powers & Moat, Applied Segment by Segment
The most common analytical error with a company like Gabriel India is to average it. A single moat rating, a single Porter score, a single verdict. The trouble is that averaging a near-monopoly, a competitive scale fight and a technology-partner business produces a number that describes none of them.
So take them separately.
Porter, three times over
Commercial vehicles and railways looks, structurally, like the strongest position — and contains the sharpest paradox. Barriers to entry are high: rail and heavy-vehicle suspension carries qualification burdens, safety certification and durability validation that take years. Rivalry is low, with limited named domestic competition against Gabriel's 88-89% share. Substitution risk is minimal.
And buyer power is the highest in the entire portfolio. A concentrated base of state-linked customers with tender-based procurement, explicit vendor-diversification policy and the ability to rewrite specifications is not a buyer set that lets a supplier extract monopoly economics. The right description is a cornered position in front of a buyer with the structural power to un-corner it — which is why this segment's share number should not be read as a durable rent.
Passenger vehicles is a scale-and-switching-cost game. Moderate supplier power, moderate rivalry against larger global incumbents, and switching costs that are genuine within a vehicle platform's life but reset at every model changeover. Gabriel's roughly 25% PV suspension share and 24% growth rate suggest it is winning platform awards at a respectable clip. This is a good business, not a fortress.
Two- and three-wheelers is the most competitive of the three and the largest by revenue — an uncomfortable combination. Endurance is bigger, better-margined and commands roughly 40% of the category against Gabriel's position, with Munjal Showa and KYB holding meaningful share below.518 Buyer power is high, with a handful of enormous OEMs. Rivalry is intense. The 57% of revenue that funds everything else sits in the segment with the least favourable structure.
Through the 7 Powers lens
Applying Hamilton Helmer's framework separates what Gabriel actually has from what it is asserted to have.
Scale economies exist in manufacturing, but are shared with Endurance at greater scale — so they are table stakes rather than advantage.
Process power and the distribution network are, in this analysis, Gabriel's most defensible genuine advantage. The combination of nine CFAs and 30,000-plus retail outlets reaching into fragmented small-town replacement demand is expensive, slow and relationship-dependent to build.5 A competitor can match a plant in eighteen months. Matching a distribution network that took decades to assemble is a different problem. The irony is that this strongest power operates in the channel that generates only about 12% of revenue.
Switching costs are real but bounded to model cycles.
Cornered resource is the claim most often implied by the CV/railways share number and, for the reasons above, the one that survives scrutiny least well.
Branding matters modestly in the aftermarket and essentially not at all in OEM sales.
Counter-positioning is where the roll-up thesis actually lives — and it is worth stating precisely, because it is subtler than "Gabriel is buying good businesses." The bet is that Gabriel becomes the default listed consolidation platform for global auto-component joint ventures in India: the entity a Dana or an HL Mando or a Henkel looks to when it wants scaled Indian manufacturing, local supply chains and public-market capital access, all through one counterparty. If that position establishes itself, it is hard for a rival to copy, because it requires both the sixty-year relationship history and the listed vehicle.
But notice what the moat in those consolidated businesses actually consists of. In Dana Anand, HL Mando Anand and HL Klemove, the technology belongs to the global partner. Gabriel's contribution is manufacturing, localisation and market access. That is a real and valuable contribution — but it is not proprietary technology, and the terms on which it is rewarded depend on the partner's continued willingness to route Indian ambition through ANAND rather than through a wholly owned subsidiary.
So the counter-positioning claim should be recorded as what it is: plausible, strategically coherent, and entirely unproven. No Indian listed company has successfully established itself as the default consolidation platform for global component JVs. Gabriel may be first. First is not the same as proven.
That is the structural picture. What follows is what happens when you argue both sides of it properly.
X. Bull Case vs. Bear Case
The bull case
Start with what already worked. Before a single rupee of acquisition capital was committed, Gabriel India compounded revenue at roughly 23% and net income at roughly 33% over five years — a rate that outpaced most listed Indian auto-component peers, achieved organically, from a debt-light balance sheet.3 Whatever one concludes about the roll-up, the operating company underneath it has demonstrated it can grow and improve profitability at the same time. That is the foundation, and it is genuine.
The CV and railways franchise is a real asset even after discounting for buyer concentration. An 88-89% share in the fastest-growing part of the portfolio, built on qualification barriers that take years to clear, generates cash and strategic option value that a fragmented supplier cannot.
The E2W position is evidenced, not merely asserted. The Piaggio inverted-fork single-source award and the decision to fund front-fork casting capacity are commitments of capital and engineering, not press releases. If Indian electric two-wheeler adoption arrives on anything resembling the currently projected curve, Gabriel is positioned in front of it.
The roll-up, if it works, solves a real ceiling problem. A suspension-only supplier's content per vehicle is capped. A group that also supplies driveline, transmission components, adhesives, fluids, steering, braking and eventually ADAS sells multiples of that value into the same vehicle. Crucially, Gabriel could not have built these capabilities organically at any reasonable cost or timeline — ADAS sensor fusion and EV transmission engineering are not adjacent extensions of damper design. Access through joint ventures with established global partners is genuinely the only realistic path.
And the price is not obviously wrong. At roughly 21-22 times trailing earnings for HL Mando Anand, against Endurance Technologies in the mid-forties, Gabriel is not paying a bubble multiple for a business with more technology content than its own core.418
The bear case
The mechanism of the deal is the governance risk. This is the argument that deserves the most weight, because it does not depend on predicting anything. The promoter sold assets to the listed company; the listed company paid for them substantially in newly issued shares to that same promoter; promoter ownership rises from roughly 55% toward approximately 66.3% across the two transactions; and the shareholder vote that approved the first scheme was reported as a 99.99% aggregate with no clearly disclosed majority-of-minority breakdown.34 No forecast is required to observe that this is a structure in which the controlling family sets price, receives equity, and increases control, and the minority holder's consent is difficult to verify.
Margin compression and rising leverage are arriving together. Individually, 90 basis points of EBITDA compression is a manageable industry-standard event, and a move toward one-to-one debt-to-equity is a strategic choice a rating agency has endorsed at AA+.1811 Arriving simultaneously, they compound: more fixed obligations meeting a thinner operating cushion, during the exact period when management attention is most divided.
The valuation is defensible but untested by any market process. There was no auction, no competing bid, no unrelated buyer. Two valuation firms produced a number; that is a procedural safeguard, not a price discovery mechanism. The HL Klemove stake — roughly a quarter of the Jupiter outlay into a business with no disclosed India revenue — is on current disclosure a capability purchase, not an earnings purchase.
The conflict structure is permanent, not transitional. A Group CEO holding board positions at Dana Anand, HL Mando Anand and three other related entities while Gabriel transacts with them is a standing feature of the organisation. And the ₹50,000 crore 2030 ambition implies more such transactions, each requiring the same scrutiny.
Finally: there is no track record to fall back on. The absence of prior large M&A means that when integration gets difficult — and integrating four-to-six entities with different partners, cultures and reporting standards is reliably difficult — investors have no basis in Gabriel's own history for estimating how well this management handles it.
The weighing
Placing these side by side and walking away would be a failure of analysis, so here is the calibrated read.
The bear case's governance argument is the strongest single element on either side, because it rests entirely on disclosed facts rather than forecasts. It does not establish that value was transferred away from minority shareholders — the valuation multiple argues against the most aggressive version of that claim. What it establishes is that minority shareholders bore a structural risk they could not effectively vote on, and that the same structure will recur.
The bull case's operating argument is also strong, and it is not cancelled by the governance concern. A 33% earnings compounder with a defensible replacement-market distribution position and a credible electrification hedge is a real business regardless of who sits on which board.
The synthesis: Gabriel India is a genuinely good operating company that has attached itself to a capital-allocation programme of unknown quality, executed by a management team with no prior record in it, financed by a mechanism that systematically increases promoter control. The operating quality is proven. The capital allocation is unproven and structurally conflicted. Those are separate facts and they do not net out against each other — they have to be held simultaneously, and they resolve on different timelines.
XI. Risk Radar
Not every risk deserves equal airtime, and a list that treats them as equivalent is worse than no list. Ordered by how much they should actually move an investor's thinking:
Execution risk in the integration ranks first. Gabriel has committed to folding four-to-six entities — with different joint-venture partners, different corporate cultures, different reporting standards and, in several cases, no controlling stake for Gabriel — into one listed structure over the next twelve to twenty-four months. This is where the largest, most probable value destruction would originate, and it is the risk with the least available historical evidence to calibrate against. The associate-stake structure makes it harder, not easier: influencing a business you own 25.1% of requires persuasion where control would allow direction.
Related-party and governance risk is second, and it is ongoing rather than resolved. The ₹50,000 crore ambition implies further promoter-to-company transactions. Each one deserves the identical treatment applied to Jupiter: what is the implied multiple, who valued it, was there any market test, how is the consideration paid, and is the minority vote separately disclosed?
Leverage and refinancing risk is third. The shift from sub-0.2x to roughly 1:1 debt-to-equity is new and has never been tested through a full automotive down-cycle.8 Indian auto demand is cyclical; the two-wheeler segment in particular has experienced multi-year volume declines within living memory. A company carrying that leverage into such a period faces choices — asset sales, equity raises, capex deferral — that a debt-free company does not.
Commodity and input-cost risk is fourth, and it is no longer theoretical: it is the demonstrated cause of the FY27 margin compression.1 The mechanism — rubber, steel and other inputs moving ahead of contractually lagged OEM price recoveries — is now an observed feature of this business rather than a hypothetical.
Customer-concentration risk is fifth and is really two risks wearing one label. The 88% OEM channel mix concentrates bargaining power with a small number of vehicle makers. Separately, the CV and railways franchise depends on a narrow, partly state-linked buyer base subject to procurement policy shifts.
Competitive risk from Chinese entrants belongs on the radar as a watch item and nothing more. The evidenced competitive set today is domestic and Japanese/Korean-linked — Endurance, Munjal Showa, KYB, Tenneco.5 Chinese suspension suppliers scaling into India is a plausible future pressure, particularly in price-sensitive two-wheeler segments. But there is no specific current evidence of it displacing Gabriel, and inventing a threat because it sounds plausible is exactly the analytical error this piece has tried to avoid elsewhere.
One second-layer note worth recording: CRISIL's AA+/Stable assignment on the NCD programme is a meaningful external credit signal from an agency with access to management projections.11 It is not an endorsement of the strategy or the governance structure — rating agencies assess debt-service capacity, not minority-shareholder treatment — but on the narrow question of whether Gabriel can carry this debt, an independent professional assessment says yes.
XII. Playbook: Lessons on Family-Business Consolidation and Capital Allocation
Step back from Gabriel India specifically, because the pattern here is one investors in Indian markets will encounter repeatedly.
The first lesson is about the durability of a good playbook — and its limits. Deep C. Anand's 1961 insight was that a developing-market manufacturer could rent world-class technology and own the local execution. Sixty-five years later, his daughter is applying the identical logic one level up: rather than partnering with global technology holders one joint venture at a time, consolidate the accumulated portfolio into a single listed platform and partner at the portfolio level.
That is a genuinely elegant extension. But the two versions carry different risk. Building a joint venture is incremental — each one is a separate bet, failures are contained, and success compounds slowly. Consolidating them is a single large bet made all at once, with leverage, inside a public company on a quarterly reporting cycle. The playbook that worked patiently over decades is being run at a tempo it has never been run at before.
The second lesson is the structural tension at the heart of every promoter-driven roll-up. A listed company can be a vehicle for consolidating founder-family assets, or it can be run purely for all shareholders. Most of the time these coincide. When they diverge — over price, over timing, over how consideration is paid — the controlling family decides, and the minority discovers that its vote was arithmetically irrelevant.
The generalisable diagnostic is not "avoid promoter-driven roll-ups." Many of them create substantial value; a family with sixty years of industrial relationships genuinely can assemble things a professional management team cannot. The diagnostic is to watch the mechanism rather than the rhetoric. Specifically: Is consideration paid in cash or in shares to the seller? Is the minority vote separately disclosed? Was there any price discovery beyond a commissioned valuation? Does promoter ownership rise as a consequence of the transaction? Those four questions separate roll-ups that treat the listed vehicle as a growth platform from those that treat it as a liquidity venue.
Gabriel answers the first question with "mostly shares to the seller," the second with "not clearly," the third with "no," and the fourth with "yes, by more than eleven percentage points across two deals." That combination does not prove bad intent. It does describe a structure where minority interests depend on management restraint rather than on alignment.
The third lesson is about the epistemics of judging capital allocation. The hardest moment to assess a management team's discipline is precisely the moment they make their first truly large bet — because the evidence that would let you judge it does not exist yet, and the temptation is to substitute a proxy. The available proxies here are seductive and misleading in both directions: the ANAND Group's sixty-year partnership record argues for competence, while the conflict structure argues for suspicion, and neither actually tells you whether ₹2,231 crore for 28.99% of a steering business will earn its cost of capital.
The disciplined response is not a verdict. It is a set of pre-committed tests and the patience to wait for them — margin trajectory, standalone-versus-consolidated divergence, disclosure quality on the next transaction. Investors who reach a conclusion before those data arrive are not analysing; they are guessing with extra steps.
XIII. What to Watch Next
Five things, in rough order of how much information each carries.
Whether EBITDA margins recover within the next two to three quarters. This is the highest-information single observable in the entire story. Management's explanation on the Q1 FY27 call was a timing lag between commodity moves and OEM price recoveries.1 If margins return toward and above the roughly 9.3% level of the prior year within that window, the explanation is validated and management's credibility on operational diagnosis strengthens meaningfully. If they persist at or below the current level through FY27, then the "lag" was a structural repricing, and both the pricing-power thesis and management's explanatory reliability take a real hit. One metric, three theses.
Whether standalone disclosure appears for E2W and HL Klemove revenue. The distinction between a technology capability and a commercial business is revenue, and Gabriel currently discloses neither. Segment-level disclosure would convert two speculative claims into measurable ones. Continued silence, particularly past the point where these businesses are material, should itself be read as information — companies generally disclose numbers that flatter them.
The debt-to-equity trajectory against the CRISIL AA+ rating as the NCD programme draws down.118 The specific thing to watch is not the absolute leverage number but whether it tracks the agency's projected path or overshoots it — and whether any subsequent rating action signals a changed view.
How the next related-party transaction is structured and disclosed. Given the stated 2030 ambition, more deals are likely. The single most informative detail will be whether the majority-of-minority vote is separately and clearly published. A company that discloses that number is signalling it believes it can win it. A company that reports only an aggregate tally is signalling something else. This is the cheapest available test of whether management has heard the governance criticism.
Progress toward the stated export-share target of 15-20% by 2030, from a current low-single-digit base.16 This is worth tracking less for the exports themselves than as a management-credibility instrument: it is specific, time-bound, publicly stated and therefore scoreable. Companies that hit publicly stated multi-year targets earn the right to be believed on the next one. Companies that quietly stop mentioning them tell you something too.
A shock-absorber company exists to make violent inputs come out smooth on the other side. Over the next eight quarters, Gabriel India gets to find out whether that principle applies to balance sheets.
References
-
Gabriel India Limited Q1 FY27 Earnings Conference Call Transcript — ANAND Group, 2026-07-22 ↩↩↩↩↩↩↩↩↩
-
Gabriel India Shares Fall 7% After ₹2,231 Cr Promoter Stake Deal, Margin Pressure — BW Businessworld ↩
-
Gabriel India Ltd — Financials and Shareholding Pattern — Screener.in ↩↩↩↩↩↩↩↩
-
Gabriel India to Buy 28.99% Stake in HL Mando Anand for ₹2,231 Cr — Autocar Professional ↩↩↩↩↩↩↩↩
-
62nd Annual Report FY2023-24 — Gabriel India / NSE Archives ↩
-
Gabriel India Limited Q4 FY26 Earnings Conference Call Transcript — ANAND Group, 2026-06 ↩↩↩↩
-
CRISIL Rating Rationale — Gabriel India Limited, 2026-07-29 ↩↩↩↩↩↩↩
-
CRISIL Rating Rationale — Gabriel India Limited, 2025-07-09 ↩
-
BSE Corporate Filing — Composite Scheme of Arrangement announcement, 2025-06-30 ↩
-
BSE Corporate Filing — Finance Committee / NCD approval, 2026-08-27 ↩↩↩↩↩↩
-
Gabriel India shareholders approve re-appointment of Mrs Pallavi Joshi Bakhru as Independent Director with 91.88% votes in favour — ScanX ↩
-
ANAND Group's Gabriel India to Acquire Asia Investments Pvt Ltd's Automotive Business — Autocar Professional ↩↩
-
Gabriel India Names Mahendra Goyal Group CEO in Executive Leadership Realignment — Autocar Professional ↩↩↩
-
Manoj Kolhatkar steps down as MD of Gabriel India, Atul Jaggi to take over — Autocar Professional ↩
-
Gabriel Targets Fivefold Jump in Export Share to 15-20% by 2030 — Autocar Professional ↩↩↩
-
Gabriel India soars after announcing strategic business restructuring scheme — Business Standard, 2025-07-01 ↩
-
Endurance Technologies Ltd — Financials for Peer Benchmarking — Screener.in ↩↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube