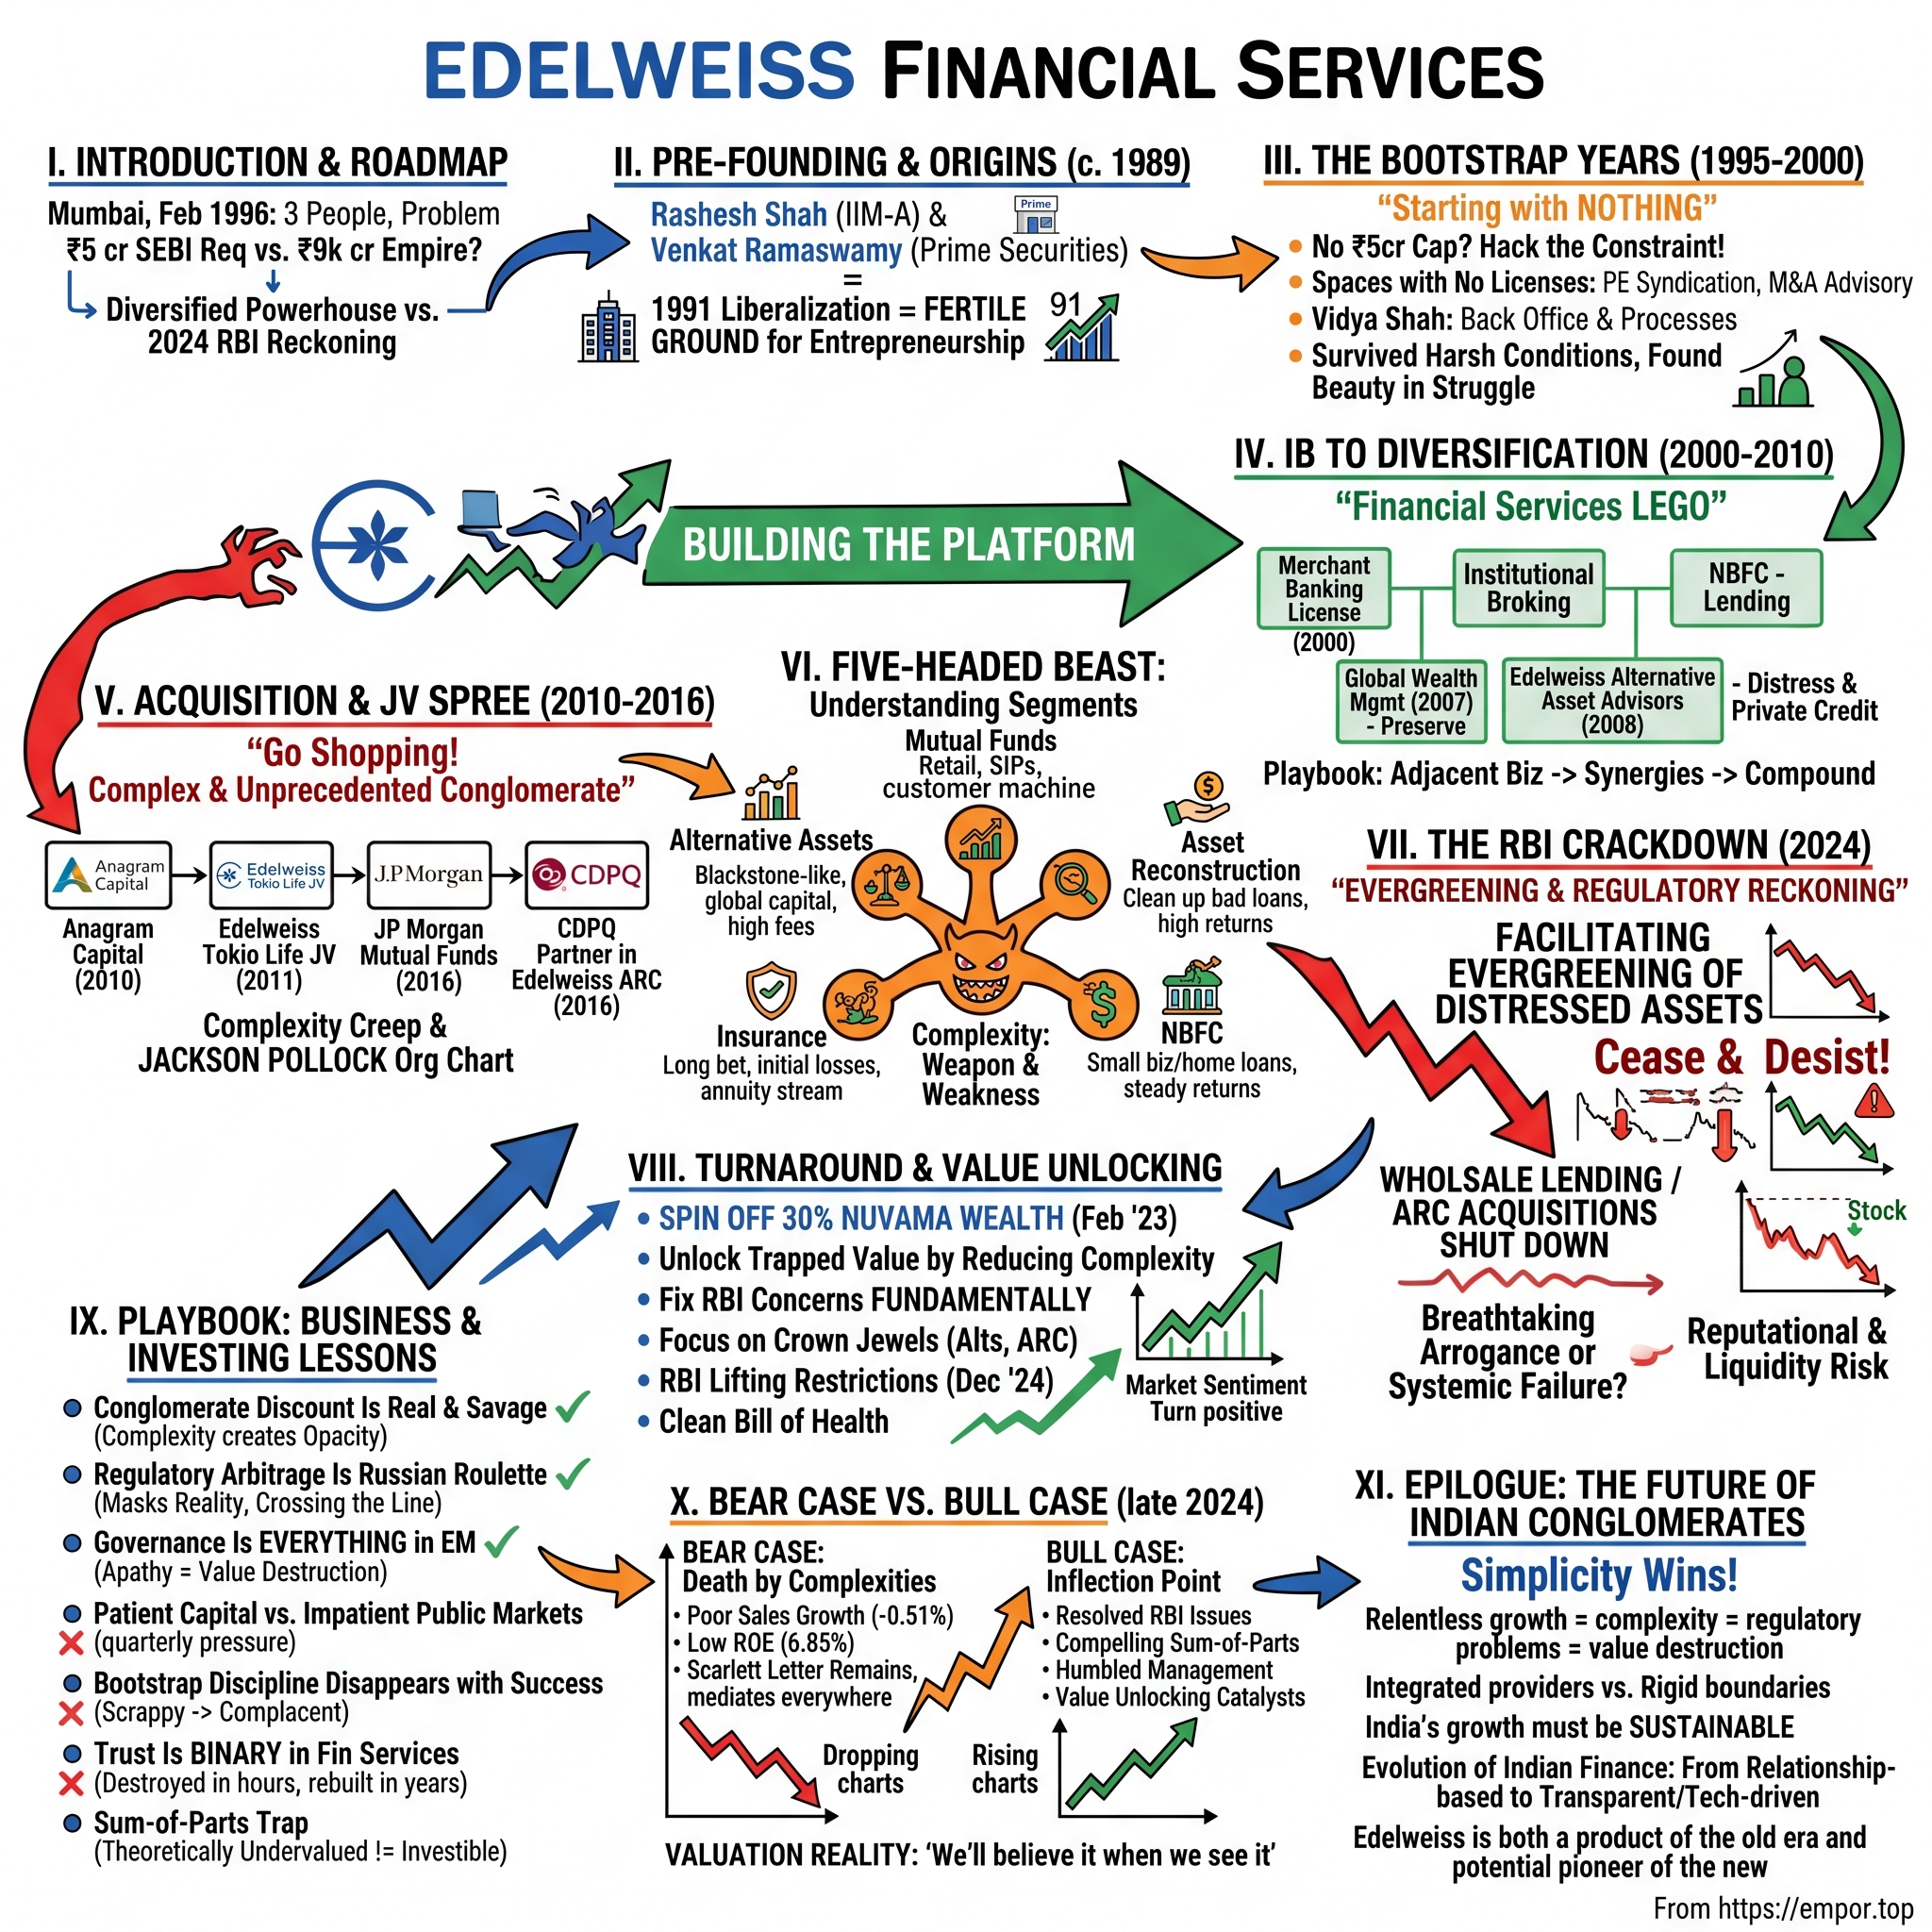
Edelweiss Financial Services: The Conglomerate That Kept Getting Caught
I. Introduction & Episode Roadmap
On the morning of May 29, 2024, the Reserve Bank of India published a press release that ran barely a page and a half. It was addressed to two companies inside one corporate group: ECL Finance Limited, a non-bank lender, and Edelweiss Asset Reconstruction Company Limited, India's largest buyer of distressed loans. The language was unusually direct for a central bank. The RBI barred ECL Finance from undertaking any structured transactions on its wholesale exposures, and barred the asset reconstruction company from acquiring any new financial assets or reorganising its existing security receipts — both "with immediate effect."1
The reason given was the part that mattered. The regulator wrote that the entities had been "acting in concert," running "a series of structured transactions for evergreening stressed exposures of ECL, using the platform of EARCL and connected AIFs." In plain English: the group's lending arm had been parking bad loans with the group's own distressed-debt arm, and the RBI had decided the arrangement was a laundering of losses rather than a genuine sale.
The market's reaction was immediate. Edelweiss Financial Services stock fell as much as 17% intraday on May 30 — the kind of single-session move that only happens when investors conclude the regulator has found something structural rather than clerical.2
Twenty-seven months later, the picture looks very different. As of early September 2026, Edelweiss Financial Services trades around ₹134 a share, giving the holding company a market capitalisation of roughly ₹12,760 crore — near the top of its 52-week range, and roughly 37% above its 52-week low.3 The group has spent 2025 and 2026 selling minority stakes in its best businesses to some of the most discriminating buyers in the market: WestBridge Capital into the mutual fund, Carlyle into the housing finance arm, and its own limited partners into the alternatives platform ahead of a filed IPO.
Here is the first thing worth getting right, because the recovery narrative is often told carelessly. The stock is not at an all-time high. Its all-time high was ₹180, and it was set on May 29, 2018 — exactly six years to the day before the RBI order.3 Eight years after that peak, and with a group that has been through two separate near-death experiences in the interim, the equity is still around a quarter below where it stood before any of this began. That gap is not a rounding error. It is the accumulated cost of the story we are about to tell.
Edelweiss Financial Services today is a holding company — although, as we will see, its chairman objects to that word — sitting atop six operating businesses of wildly different quality: an asset reconstruction company that is the most profitable thing in the group, an alternative asset manager heading for a public listing, a mutual fund growing fast off a small base, a deliberately shrunken NBFC, a housing finance business being handed to Carlyle, and a life-and-general insurance pair that has lost money for fifteen years. It spun off its wealth management arm, Nuvama, in 2023.
The tension this episode holds together is simple to state and hard to resolve. Edelweiss is simultaneously two true things. It is a genuine three-decade compounding story — three people in a small office in Mumbai's Fountain district in 1996 who built India's largest private distressed-asset platform.4 And it is a group that has now been through two separate regulatory-and-liquidity near-death episodes in six years, where the mechanism behind both looks uncomfortably similar: aggressive intra-group structuring that the regulator eventually caught up with.
The structure from here: the origins and the platform build through 2018; the IL&FS-era collapse of the wholesale book and the four rounds of rescue capital that followed; the Nuvama demerger and the "do an HDFC" framing management uses to describe its strategy; the segment economics of what is actually left today; the 2024 RBI action as a rhyme with 2019 rather than a bolt from the blue; the credibility record of the people running it; and finally the bull and bear cases for the pieces that remain. The through-line is a question worth asking of any Indian financial conglomerate: when a group tells you it is unlocking value, is it choosing to, or being made to?
 Subscribe on LinkedIn
II. Origins: Liberalization's Children (1991–1995)
Rashesh Shah did not want to join the family business. That is the detail that explains a lot of what follows.
Shah grew up in a Gujarati business family in Mumbai, took a B.Sc. in statistics from KC College, spent a year at the Indian Institute of Foreign Trade, and then went to the Indian Institute of Management Ahmedabad, graduating in 1989. The choice of an MBA at IIM-A was, by his own account, partly a deliberate escape hatch — a credential that would let him build something of his own rather than inherit something already built. For a certain generation of Indian professionals, IIM-A in the late 1980s was the closest thing available to a passport out of the family firm and into the newly forming world of institutional finance.
The timing turned out to be extraordinary. In July 1991, with India's foreign exchange reserves down to a few weeks of imports, Finance Minister Manmohan Singh delivered the budget that dismantled the licence raj, opened the capital account partially, and — critically for anyone in Shah's position — began the construction of a modern securities market. The Securities and Exchange Board of India got statutory powers in 1992. Foreign institutional investors were allowed in the same year. The National Stock Exchange began trading in 1994. Within thirty-six months, India went from a market where equity capital was allocated by a government controller to one where it was allocated by underwriters and analysts.
Shah's own framing of this window, repeated in interviews across three decades, is that "the 1991–96 period was a very fertile period for entrepreneurship."35 That is not nostalgia; it is an accurate description of an unusual structural moment. Shah has continued to speak publicly about the structural gaps in India's credit markets — the shortage of long-term domestic capital, the dominance of bank balance sheets, the slow development of a corporate bond market — in terms that have stayed remarkably consistent since the 1990s.34 New markets had been created but not yet staffed. The institutions that would eventually dominate them — the private banks, the foreign brokerages, the domestic asset managers — were being assembled in real time, mostly by people in their early thirties.
Shah was working at Prime Securities, an early-generation Indian merchant bank, when he decided to leave. His co-founder was Venkat Ramaswamy, and the vehicle they registered in November 1995 was Edelweiss Capital. Operations began in February 1996.4 The name — a high-altitude alpine flower that grows in hostile conditions — was chosen for exactly the metaphor you would expect, and has aged into something between charming and ironic depending on which chapter of the company's history you are reading.
That is the whole of the scene-setting, and it deserves to be brief, because the origin story is not the investment story. What matters analytically is that Edelweiss was founded by people with no capital, no balance sheet, and no franchise, in a market that was being invented around them. Both halves of that sentence — the resourcefulness and the chronic shortage of permanent capital — recur for the next thirty years.
III. The Bootstrap and the First Pivot (1996–2000)
The first thing that happened to Edelweiss was a regulatory rejection, and it set the template.
Shah and Ramaswamy intended to be merchant bankers. SEBI's rules for a full Category-1 merchant banking licence required ₹5 crore of net worth. Edelweiss started with roughly ₹1 crore of equity capital — about $250,000 at the exchange rates of the day.4 They were, by a factor of five, too small to do the thing they had set out to do.
So they did something else. Rather than raise capital they could not raise, or wait for a market that might not wait for them, the two founders rewrote the business plan around activities that did not require a licence they could not afford: private equity syndication, mergers and acquisitions advisory, and placing funds with institutional investors.4 They were, in effect, forced into the agency business because the principal business was closed to them.
It is worth pausing on why this matters beyond biography. Advisory and syndication are capital-light: you earn a fee for arranging a transaction, you carry no balance-sheet risk, and your only real assets are relationships and analytical credibility. It is a business that scales with reputation rather than equity. For a firm with ₹1 crore, it was the only viable choice — and because it worked, it became formative. The instinct that Edelweiss carried forward from these years was: when you lack balance-sheet capital, sell judgment instead.
The early scale was tiny. Three employees, a small office in Mumbai's Fountain area — the old colonial-era financial district near the Bombay Stock Exchange — and roughly ₹20 lakh of revenue in the first year, around $27,000 at then-prevailing rates. In an industry where the fee on a single mid-size transaction can exceed that, this was a firm operating at the threshold of viability.
Four years later, the arithmetic had changed. By 2000, Edelweiss had ten employees, had crossed the ₹5 crore capital threshold, and had obtained the Category-1 merchant banking licence it had originally been denied.4 That is the first genuine proof point in the story: a model that generated enough retained earnings from fee income to fund the licence that unlocked the next tier of business. Not spectacular growth — a doubling of headcount and a fivefold increase in capital over four years — but organic, self-funded, and directionally correct.
One other person joined in these years who matters to the later narrative. Vidya Shah, an IIM Ahmedabad batchmate who later married Rashesh Shah, came in as an early operating partner and eventually served as chief financial officer through the formative period. Her arc is one of the more unusual in Indian finance: from CFO of a scaling securities firm to, from 2008 onward, the full-time head of the group's philanthropic foundation. We will return to her in Section X, primarily to be precise about what she does and does not do today, because she is frequently and incorrectly described as part of current operating management.
By 2000, then, Edelweiss had the licence, the team, and the credibility. What it did next — putting its own balance sheet at risk — is where the story stops being purely about resourcefulness and starts being about risk appetite.
IV. Building the Platform: From Advisory Shop to Diversified Financial Firm (2000–2010)
There is a moment in the life of every advisory firm when the founders look at the transactions they are arranging for other people and think: we should be taking this risk ourselves.
For Edelweiss, that moment arrived across the 2000s, and it changed the nature of the company permanently. Through the decade, the firm added institutional equity broking — a natural extension of the research and relationships it already had — and then, more consequentially, an NBFC lending business. This was the first time Edelweiss put real balance-sheet risk on its own books rather than arranging it for others.
The logic was sound and the timing was good. India's 2003–2008 bull market produced enormous demand for structured credit: promoters wanting to borrow against their own shares, real estate developers needing capital that banks would not extend, mid-market corporates that were too small or too complicated for the priority queue at a public sector bank. A firm with Edelweiss's deal flow could see these opportunities before anyone else and, with an NBFC licence, could fund them itself and capture the spread rather than a fee.
But the change in business model was more profound than it looked. An advisory firm that makes a bad call loses a client. A lender that makes a bad call loses capital. Once you own the loan, the quality of your underwriting — not the quality of your pitch — determines whether you survive. Everything that goes right for Edelweiss over the next fifteen years and everything that goes wrong traces back to that switch.
The decade added three other pieces, each of which becomes a full character later:
2007 — Edelweiss Global Wealth Management. A business built around wealth structuring, asset protection, and investment banking for high-net-worth individuals. In a country where private wealth was compounding faster than the institutions to manage it, this was an obvious and well-timed franchise. It is also the business whose eventual fate — majority sale to a foreign private equity fund, then demerger and separate listing as Nuvama — is one of the two largest structural events in the company's history. Hold that thought until Section VII.
2008 — EdelGive Foundation. The group's philanthropic arm, focused on education and livelihoods, and Vidya Shah's project from inception to the present day.
Mid-2008 — Edelweiss Alternative Asset Advisors. Launched into the teeth of the global financial crisis, this business raised institutional and HNI capital for private credit, real estate, and infrastructure yield strategies. Founded in 2008, it is now the entity called EAAA India Alternatives, and it is the one heading for a public listing.5 Eighteen years is a long incubation, and it is the strongest single piece of evidence that this group can build something durable when it is patient.
By 2010, Edelweiss had assembled the shape it would keep for the next fifteen years: an advisory and agency core, wrapped in a growing set of balance-sheet-heavy businesses — lending, insurance, and soon asset reconstruction. The agency businesses generated fees and required little capital. The balance-sheet businesses generated spread income, required a great deal of capital, and carried the risk.
For an investor, this is the structural fact about Edelweiss that never changes: the group's earnings quality depends entirely on which half is driving results in any given year, and the half that requires capital is also the half that attracts regulators. In 2010 that looked like prudent diversification. It looked considerably less prudent nine years later.
V. The Acquisition and JV Spree — and Whether It Was Worth the Price (2010–2018)
Between 2010 and 2018, Edelweiss went shopping. The list is long enough that it is worth asking whether this was a strategy or an accumulation.
The opening move was Anagram Capital, a Gujarat-rooted retail broking and distribution franchise, acquired for ₹164 crore in a deal announced in January 2010 and completed that July.67 The rationale was straightforward: Edelweiss was strong with institutions and weak with retail; Anagram brought branches, sub-brokers, and a distribution footprint that would have taken years to build organically. Buying distribution rather than building it is a recurring Edelweiss instinct, and on the whole a defensible one — distribution is the scarcest asset in Indian financial services and the slowest to compound from scratch.
The most consequential deal of the period was not an acquisition but a joint venture. In 2011, Edelweiss partnered with the Japanese insurer 東京海上 Tokio Marine to form Edelweiss Tokio Life Insurance, with Edelweiss holding 74% and Tokio Marine the balance; the business received its IRDA registration in May 2011 and commenced operations that July.8
This deserves more scrutiny than it usually gets. Indian life insurance is a business with a brutal capital profile: you write policies, book the acquisition cost immediately, and recognise the profit over decades. New entrants typically lose money for seven to ten years. Edelweiss knew this going in. What it appears not to have modelled correctly is how long the losses would run without the distribution muscle of a large bank behind it — the private life insurers that reached profitability fastest were almost all attached to a bank branch network. Fifteen years later, the insurance segment is still losing money, and management's breakeven guidance has been reset more than once, currently landing on FY27.9 We take that promise apart in Sections VIII and X. For now, note the plant: this was a long-duration, capital-intensive bet made by a group that would shortly discover it did not have spare capital to spare.
The mid-decade run of purchases was more opportunistic:
- 2014 — Forefront Capital Management, a Mumbai-based asset manager, acquired to add quantitative and alternative strategies.10
- 2016 — the fund schemes of JPMorgan Asset Management India, transferred to Edelweiss AMC. This was a classic trade of the era: a global asset manager concluding that sub-scale Indian mutual fund operations were not worth the management attention, and a local player buying the AUM and the unitholder relationships at a price that reflected the seller's urgency.
- 2016 — Ambit Alpha Fund, a hedge fund acquired from Ambit Investment Advisors.
The pattern is consistent: Edelweiss was buying assets under management and licences at a time when foreign firms were retreating from India, and paying prices that reflected a buyer's market. L&T's acquisition of Fidelity's India schemes and the various HSBC AMC transactions of the same period tell the same story from the other side. Judged narrowly on capital discipline, this was reasonable behaviour — small cheques, real assets, no goodwill-destroying mega-deal.
The most significant validation of the period came in 2016, when the Canadian pension manager CDPQ — Caisse de dépôt et placement du Québec — took a 20% stake in Edelweiss Asset Reconstruction Company. For the first time, a marquee global institution was underwriting a specific Edelweiss franchise rather than the group as a whole, and it chose the distressed-asset business. That was a meaningful signal: CDPQ has an unusually deep bench in credit and infrastructure, and its diligence is not casual. It is also the beginning of a relationship that becomes distinctly uncomfortable five years later, when a whistleblower complaint puts the CDPQ–ARC structure at the centre of a regulatory inspection.
So: was the spree worth the price? On the evidence, the acquisitions themselves were not the problem. They were individually small, bolt-on rather than transformational, and bought at cyclically attractive moments. Edelweiss AMC — the vehicle that absorbed the JPMorgan schemes — went from 36th to 13th in the Indian mutual fund rankings over the following decade, which is the sort of outcome that retrospectively justifies a lot of small acquisitions.11
The far larger capital allocation decision of this era was not any of these deals. It was the quiet, continuous, unannounced expansion of the wholesale lending book — structured credit to real estate developers and mid-market corporates, funded increasingly with short-term wholesale borrowing. No press release accompanied that decision. It nearly ended the company.
VI. The Reckoning: The IL&FS Crisis, the Wholesale Book Blowup, and the PE Rescue (2018–2021)
On September 21, 2018, Infrastructure Leasing & Financial Services — a systemically important infrastructure financier that had been rated AAA weeks earlier — defaulted on commercial paper. Within days, India's mutual funds, which were the primary buyers of NBFC short-term paper, stopped rolling anything they did not have to. The wholesale funding market that every non-bank lender in India depended on simply closed.
For a lender that had funded long-dated developer loans with short-dated market borrowings, this was the specific nightmare the business model was exposed to. Edelweiss was exactly that lender.
The mechanism
Understand what the wholesale book actually was. Through the mid-2010s, Edelweiss had built a portfolio of structured credit — loans to real estate developers secured against project cash flows and land, and loans to corporates secured against promoter shareholdings. These are not bad instruments in themselves. They are, however, instruments whose value depends entirely on the borrower's ability to refinance. A developer loan is repaid out of apartment sales or, far more often, out of a new loan from the next lender. When the refinancing market closes, the underlying collateral does not save you, because everyone is trying to sell the same collateral into the same absent bid.
At the peak of the stress, roughly 40 out of 100 developer loans in the book were reported to have turned non-performing. Even years into the workout, gross Stage 3 loans stood at ₹945 crore, equivalent to about 21% of net worth — a level at which the loss-absorbing buffer of the enterprise is genuinely in question.
The scale of the retrenchment tells you how bad it was. Edelweiss shrank the wholesale book from roughly ₹19,100 crore at the end of FY19 to about ₹10,000 crore by March 2020 — nearly halving a loan portfolio in twelve months. You cannot do that through ordinary repayment. You do it by selling.
And here is the detail that becomes the hinge of this entire episode: a material part of that reduction was achieved by selling stressed wholesale loans to Edelweiss's own asset reconstruction company. The group's lending arm transferred problem assets to the group's distressed-debt arm. On a consolidated basis nothing left the building; on an entity basis, ECL Finance's books looked dramatically cleaner.
That is the same self-referential transfer mechanism that, four years later, the RBI would formally find had been used to circumvent the rules governing what an ARC is permitted to buy. We will get to the 2024 order in Section IX. The point to fix here is chronological: the practice predates the enforcement action by years, and it was visible in the group's own disclosures at the time.
The ratings cascade
Credit rating agencies are slow, but they are not blind. ICRA cut EFSL's non-convertible debentures from AA to AA- in June 2019 with a negative outlook. CRISIL cut the group's long-term rating a notch in October 2019 — the stock fell 7% the same day. ICRA downgraded eight group entities in May 2020, in the middle of the Covid liquidity freeze. And the group reported a pre-tax loss of ₹2,819 crore in the March 2020 quarter, as it took provisions against the wholesale book.
Now apply the falsification test that matters most to any current bull case, which is the claim that "the crisis is behind them."
EFSL's long-term credit rating has never recovered to its pre-2019 level. It did not merely stall — it was cut again, in December 2023, from AA- to A+, with CRISIL explicitly citing "lower-than-expected revival in core profitability."12 That downgrade came four and a half years after IL&FS, in a period when the group was supposedly repaired. And as of the most recent reaffirmation on January 9, 2026, the rating still sits at Crisil A+/Stable.13
Read the January 2026 rationale and the reason for the stall is not mysterious. CRISIL described the group's profitability as "subdued," noting a FY25 profit after tax of ₹536 crore on a return on assets of just 1.3% — a level the agency characterised as lower than other large financial groups. It flagged a monitorable portfolio of ₹7,089 crore, against which 45% provisions had been taken, leaving ₹3,892 crore of net exposure. Gross Stage 3 assets stood at 8.0% of loans as of September 2025. Group gearing was 3.4 times, with net debt of ₹11,334 crore.13
That is a rating agency saying, in January 2026, that the balance sheet still carries the residue of 2018. A stock price can round-trip in eighteen months. A credit rating reflects the cost of the group's funding, which is the raw material of every lending business it owns, and it has not round-tripped in eight years.
The rescue sequence
What Edelweiss actually did between March 2019 and March 2021 was raise external capital four times, in rapid succession, from four different sources.
March 2019: CDPQ committed approximately ₹1,800 crore into ECL Finance. The stock jumped 12% on the announcement — a reaction that says more about how badly the market wanted evidence of solvency than about the terms.14
August 2019: Kora Management, a US-based investment firm, committed up to $125 million — roughly ₹875 crore — across the group, including into the wealth management arm.
July 2020: The board approved raising up to ₹1,500 crore through rights issue, qualified institutional placement, or preferential allotment. This is the classic all-options-open resolution of a company that needs money and does not yet know who will provide it.
August 2020: PAG, the Hong Kong–based private equity firm, agreed to acquire a controlling stake of between 51% and 61.5% in Edelweiss Wealth Management for $300 million, about ₹2,366 crore.15 PAG followed with a further ₹2,366 crore in March 2021.
Look carefully at what the PAG transaction actually did. It did not only buy shares from Edelweiss. It also bought out the positions that Kora Management and Sanaka Capital had taken in the wealth business barely a year earlier. The emergency capital of 2019 was being cashed out in 2020. That is not the ownership profile of a stable business attracting long-term partners; it is the profile of a distressed capital structure being passed between hands, with each holder taking a turn and exiting.
What the record says about capital allocation
Management's preferred framing of the last decade — which we will examine directly in the next section — is that Edelweiss has been deliberately unlocking value by building separately fundable businesses. Test that against this sequence.
The record shows a group that needed four rounds of outside capital in under two years to stabilise; that ceded majority control of its single best franchise to a foreign private equity fund at the bottom of a liquidity crisis; and that managed to buy back only a 5.3% sliver from PAG in December 2021 once conditions improved. CRISIL's own tally, in the 2026 rationale, is that the group has raised roughly ₹6,000 crore of capital since 2016 — against a net worth of ₹5,918 crore as of March 2025.13 Put bluntly: essentially the entire equity base of the group as it stands today was raised from outside, much of it under duress.
The honest verdict is not that management is incompetent — a group that survives a funding freeze with its franchises intact has done something right, and many Indian NBFCs of that vintage did not survive at all. The honest verdict is narrower and more useful: the 2019–2021 capital raising was crisis response, not strategy, and any narrative that presents it as a deliberate value-unlocking programme is retrofitting intent onto necessity.
Regulatory friction, running in parallel
Two other things happened in this window that matter for the pattern.
In January 2020, the Enforcement Directorate summoned Rashesh Shah twice in connection with a ₹2,000 crore foreign exchange fraud allegation linked to an entity called Capstone Forex. The company denied any relationship with the entity. No public resolution of the matter has been identified.
In March 2021, a whistleblower complaint — reportedly from a former Additional Solicitor General — alleged that Edelweiss ARC and CDPQ had diverted at least ₹1,800 crore from the ARC in violation of investment norms, and the Ministry of Corporate Affairs ordered an inspection of the books.16 This too has no clear public resolution.
Neither episode produced a finding against the company that we can point to. That is worth stating plainly rather than implying guilt by summons. But both establish something that matters for the analysis: regulatory and enforcement attention specifically directed at the ARC's structuring practices predates the 2024 RBI action by three years. When we get to 2024, the relevant question is not whether the group had warning. It is why the warnings did not change the behaviour.
By the end of 2021, the group had survived. It had also lost control of its best business, taken a permanent step down in credit quality, and acquired a regulatory file. What it did next was attempt to turn the loss of the wealth business into a strategy.
VII. Splitting the Conglomerate: The Nuvama Demerger and "Doing an HDFC" (2021–2023)
On September 26, 2023, a company called Nuvama Wealth Management began trading on the BSE and NSE. It was, in every operational sense, the Edelweiss wealth management franchise that had been launched in 2007 and sold to PAG in 2020 — renamed, restructured, demerged from the parent, and handed to shareholders as a separate listed security. Post-listing, PAG held roughly 56% and Edelweiss Financial Services retained a residual stake of about 14%, which it has since monetised down further, including a sale of roughly ₹3,200 crore worth during FY25.17
By the metric management uses, this was a success. On the Q1 FY27 earnings call in August 2026, Rashesh Shah pointed to Nuvama as the proof of concept, noting that the value distributed to Edelweiss shareholders through the demerger now exceeds $1 billion.18 That is a real number and a fair claim. Shareholders who held through the demerger received a security that has compounded well.
The framing Shah has attached to this for years is that Edelweiss intends to "do an HDFC" — build individually strong operating businesses, list them separately, and run a family of listed companies rather than one undifferentiated conglomerate. On the August 2026 call he sharpened it further: "we are not a holding company, we are an investment company."18
That distinction is doing a lot of work, and it deserves to be examined rather than accepted.
Testing the HDFC analogy
The HDFC comparison is flattering and structurally inexact. HDFC Ltd listed HDFC Bank, HDFC Asset Management, and HDFC Life — and retained control of each, sequencing the listings from a position of strength, at valuations it chose, on a timetable it set. The parent never lost the operating businesses; it monetised a minority of each while keeping the consolidated economics.
Edelweiss's path was different in the way that matters. The wealth business did not become a separately listed company because Edelweiss decided the time was right. It became one because PAG bought control of it during a liquidity crisis, and the demerger was the mechanism by which the residual value was returned to Edelweiss shareholders afterward. The destination — a separately listed wealth franchise, Edelweiss shareholders holding paper worth over a billion dollars — is genuinely close to what the HDFC playbook would have produced. The path there ran through forced dilution at the bottom of a cycle.
This is not a semantic quibble. The difference between "we chose to sell 56% of our best business" and "we had to sell 56% of our best business" is the entire question of whether management's capital allocation should be trusted going forward. On the historical record, the answer for 2020 is clearly the latter.
Which brings us to the more interesting question: has that changed?
The playbook run three more times
Since 2025, Edelweiss has applied the same formula — sell a minority or control stake to a sophisticated institutional buyer, then consider a listing — three more times in rapid succession:
- WestBridge Capital into Edelweiss Asset Management (August 2025)
- Carlyle into Nido Home Finance (February 2026)
- A pre-IPO placement of EAAA to existing limited partners (March 2026), ahead of a filed IPO
The material difference is the starting condition. In 2020, Edelweiss was selling because it needed the money to survive. In 2025 and 2026, the group is profitable, the RBI restrictions are lifted, and the buyers are competing for allocation rather than negotiating against a distressed seller. On the March 2026 EAAA placement, the company reported that it had planned to sell about 4% and expanded slightly to 4.4% because demand exceeded the offer — while still deliberately capping the placement below what the market wanted.19 That is the behaviour of a seller with pricing power, and it is a genuinely different posture from 2020.
The correct conclusion is calibrated, not celebratory. The "do an HDFC" claim, tested against the full record, does not survive as a description of what management has historically done — it survives, at most, as a description of what management is currently doing, and that current behaviour is roughly eighteen months old. Eighteen months is not a track record. It is a promising start that has not yet been tested by a down cycle.
The KPI that would confirm the revised claim is specific and near-term: whether the EAAA IPO prices at or above the ₹8,500 crore valuation implied by the March 2026 placement, in an open market rather than a private negotiation with friendly LPs. That is the first time this management team will have sold a business to strangers, from strength, at a price set by the market. Everything before it was either a distressed sale or a club deal.
Before that, though, we need to understand what is actually inside the company.
VIII. Understanding Today's Edelweiss: The Business Segments and Where the Value Actually Sits
If you read only the consolidated headline for FY26, you would conclude Edelweiss is a modestly profitable, slow-growing financial group. Total income of ₹10,865 crore, consolidated profit after tax before minority interest of ₹680 crore, up 27% year on year, profit attributable to owners of ₹546.63 crore, up 37%, net worth of ₹5,944 crore, and a recommended dividend of ₹1.50 per share.20
The consolidated number is close to meaningless. Break it into segments and you find not one business but five, of radically different quality — one that prints money, one that is genuinely growing, two being sold, and one that has never made a rupee.
Asset Reconstruction: the profit engine nobody talks about
Start with the segment that matters most and gets discussed least.
In FY26, the asset reconstruction business generated segment revenue of ₹930.03 crore — up 5.4% year on year, which is unremarkable — and profit before tax of ₹469.87 crore.21 Sit with that ratio for a moment. Slightly more than half of every rupee of revenue in this business converted into pre-tax profit. It is not the largest segment by revenue. It is comfortably the most profitable thing Edelweiss owns.
What an ARC actually does. Indian banks accumulate loans that have gone bad. Working them out — chasing promoters through courts, taking possession of collateral, running an insolvency process — is slow, specialised, reputationally awkward work that banks are structurally bad at. An asset reconstruction company buys those loans at a discount, usually paying partly in cash and partly in "security receipts" that pay out only if recoveries materialise. The ARC then does the unglamorous work of recovery and keeps the spread between what it paid and what it collects, plus a management fee on the security receipts.
Two features make this economically attractive. First, the raw material — bad loans — is countercyclical: it is most abundant precisely when everything else in financial services is struggling. Second, and more importantly for the moat question, regulation restricts who ARCs can buy from. Only banks and financial institutions can sell financial assets to an ARC. That rule is a genuine structural barrier: you cannot start an ARC in a garage and buy a portfolio from a hedge fund. You need a licence, capital, and a relationship with a small, concentrated set of bank sellers.
But notice that the same rule cuts both ways, and this is the part the bull case usually omits. If your only permitted suppliers are banks, then banks hold the bargaining power. When public sector banks were drowning in bad loans in 2016–2019, ARCs had abundant supply and could bid selectively. When bank asset quality is strong — as it broadly has been in India in the mid-2020s — the supply of assets shrinks and pricing tightens. And the regulator sets both the rules of engagement and, through supervisory posture, the effective size of the market. An industry whose addressable volume is determined by the RBI's mood is not a fortress. It is a licensed utility with cyclical raw material.
The competitive set. Edelweiss ARC is the largest private ARC in India by AUM. Its nearest comparables tell you something about the industry's difficulty. JM Financial ARC is smaller and has had a rockier book, swinging from a loss of ₹942 crore in FY24 to a much reduced loss of about ₹30 crore in FY25 — a business recovering rather than compounding. Phoenix ARC, backed by Kotak, is smaller still at around ₹13,300 crore of AUM but carries the sector's highest credit rating at CRISIL AA — a reminder that in this industry, balance-sheet quality and scale are not the same thing. ARCIL, the oldest ARC in India, received SEBI clearance for an IPO in October 2025, which means it — not Edelweiss ARC — is likely to be the first Indian ARC to actually list. That is a quietly interesting fact: Edelweiss owns the largest ARC in the country and is choosing to take a different subsidiary public first.
The falsification test on the ARC moat. The claim is that Edelweiss ARC has a durable, defensible franchise. The strongest disconfirming evidence comes from the business's own recent record: when the RBI froze acquisitions in 2024, the AUM went from ₹31,591.72 crore in March 2024 to ₹14,716.63 crore in March 2025 — a decline of roughly 53% in twelve months, as new acquisitions collapsed from ₹13,187 crore to ₹757.56 crore.22
A franchise that halves when the regulator says stop is not a moat in the Buffett sense. It is a licence. The distinction matters enormously for how you underwrite the segment: the profitability is real and the scale is real, but the durability is contingent on a relationship with a supervisor that has already been ruptured once.
The revised claim that survives: Edelweiss ARC is the scale leader in a regulated, structurally protected, but regulator-dependent industry, earning genuinely high margins on a shrinking asset base that it must now rebuild. The KPI that confirms or falsifies it is the quarterly acquisition run-rate. In Q1 FY27, the business acquired ₹300 crore of retail assets and recovered ₹304 crore, delivering a 13% annualised return on equity against management's stated target of 14–15%.18 Against the ₹13,187 crore of acquisitions in FY24, ₹300 crore a quarter is a fundamentally smaller business. That gap is the single cleanest measure of what the RBI episode actually cost.
Alternative Asset Management: the real growth story
EAAA is the one place in the group where the growth is genuine, the economics are attractive, and the optionality is not speculative.
The FY26 segment numbers: revenue of ₹963.76 crore, up 22.5% year on year, and profit before tax of ₹338.63 crore.21 The Q1 FY27 detail is better still — fee-paying AUM of ₹48,623 crore, up 27%, quarterly profit of ₹81 crore, up 45%, return on equity of 29%, and a revenue yield of 2.89% on fee-paying assets.18
That yield figure is the one to understand. Charging 2.89% on fee-paying assets is an alternatives-manager fee level, not a mutual-fund fee level — Indian equity mutual funds charge a fraction of that. It tells you EAAA is genuinely selling private credit and real assets to institutions that will pay for scarcity, not commoditised beta. Combined with a 29% return on equity, this is a capital-light, high-margin fee business — structurally the most attractive economic model in the entire group.
The IPO mechanics: EAAA India Alternatives filed its draft red herring prospectus with SEBI in January 2026 — a resubmission, after an earlier draft filed in December 2024 was returned — for an offer of approximately ₹1,500 crore.519 The critical structural detail is that the offer is entirely an offer for sale. Not a rupee of primary proceeds goes to EAAA. Edelweiss Financial Services is the sole selling shareholder.5
Be clear about what that means. This is not a growth financing. It is the parent selling down its stake and taking the cash — which management has said explicitly will go toward reducing corporate debt.18 For an investor in EFSL, that is arguably the right use of proceeds. For an investor considering EAAA itself, it means the company gets a listing, a currency, and public-market scrutiny, but no new capital to deploy.
On scale, keep the ambition honest. EAAA's total platform AUM was reported at roughly ₹68,175 crore as of December 2025, with fee-paying AUM of about ₹41,920 crore at that date, split roughly 46% private credit and 52% real assets.19 That makes it a real, scaling platform — but smaller than Kotak's alternatives business at around $18.5 billion, and roughly in the neighbourhood of ChrysCapital at about $8.5 billion, a firm that closed a $2.2 billion fund in November 2025. EAAA is a credible mid-tier player in Indian alternatives with a strong niche in private credit and real assets. It is not the sector leader that IPO marketing will imply.
On the August 2026 call, EAAA chief executive Amit Agarwal made the moat argument explicitly, pointing to a 60-person operating asset team with deep domain experience — people who have spent "20 years of work only on building renewable energy."18 That is a real differentiator in infrastructure yield strategies, where the ability to actually operate an asset separates the managers who can underwrite construction risk from those who can only buy stabilised cash flows. It is also unverifiable from outside and untested through a credit down-cycle in Indian private credit, which has not yet happened at scale.
Mutual Fund: a small business at a big multiple
In August 2025, WestBridge Capital agreed to acquire 15% of Edelweiss Asset Management for ₹450 crore, valuing the asset manager at approximately ₹3,000 crore — about 57 times its FY25 profit after tax of ₹53 crore.11
Fifty-seven times earnings for an Indian asset manager is a full price by any standard, and it tells you the buyer is underwriting the growth rate rather than the current earnings. The growth rate justifies some of it: Edelweiss Mutual Fund managed ₹1,52,200 crore of AUM as of June 30, 2025, compounding at 44% a year over the prior five years, and climbed from 36th to 13th in the industry rankings over a decade.11 By Q1 FY27, equity AUM alone had crossed ₹1,00,000 crore, with management describing annual net new money additions of roughly ₹18,000–20,000 crore.18
Under chief executive Radhika Gupta, the fund house has built something genuinely distinctive: a retail brand in a category where distribution normally decides everything, driven substantially by direct communication with investors rather than by a captive bank channel. That is a rare achievement in Indian asset management and probably the honest explanation for the multiple.
The analytical caveat is one of proportion. A ₹53 crore profit pool, even growing quickly, is small against a ₹680 crore consolidated result. WestBridge's price is a statement about the option, not the current contribution. Investors should size it accordingly.
NBFC: deliberately shrunk to near-irrelevance
ECL Finance — the entity at the centre of the 2019 blowup and the 2024 RBI order — is now a shadow of itself. AUM of ₹3,704 crore, quarterly profit of ₹4.79 crore in Q1 FY26, and gross non-performing assets that rose from 2.66% to 3.35% over two quarters. That last movement deserves a note: asset quality deteriorating even in the small, supposedly de-risked residual book is not what a clean wind-down looks like.
For scale, Bajaj Finance's AUM is on the order of a hundred times larger. Cholamandalam and L&T Finance are each many multiples of ECL. Edelweiss shrank this business on purpose after 2019 and there is no evidence it is being rebuilt as a growth vector — the retail arm was folded in via the Edelweiss Retail Finance amalgamation, simplifying what remains. Management did signal on the August 2026 call a target of ₹2,000 crore of MSME disbursements for FY27, against a historical run-rate of ₹300–500 crore.18 That is a meaningful percentage increase off a tiny base and does not change the segment's irrelevance to consolidated economics for at least several years.
Housing Finance: exiting a chronic underperformer
Nido Home Finance, formerly Edelweiss Housing Finance, has underperformed for most of its life — gross NPAs climbed from 1.82% in FY19 to 3.8% by the first nine months of FY22, a period during which competitors in affordable housing were generally compounding cleanly.
In February 2026, Edelweiss agreed to bring in Carlyle as strategic majority investor. Carlyle Asia Partners funds committed ₹2,100 crore, approximately $230 million, comprising a 45% secondary purchase from Edelweiss plus a primary infusion of ₹1,500 crore into Nido. Aditya Puri, the former HDFC Bank chief executive and now a senior adviser to Carlyle in Asia, joined as a co-investor.2324 Nido manages roughly ₹4,804 crore of AUM across more than 800 talukas, focused on first-time and self-employed borrowers in rural and semi-urban India.24
On the August 2026 call, management provided the mechanics: Carlyle's ₹1,500 crore of primary comes in two tranches of ₹750 crore, eighteen months apart; Edelweiss receives ₹630 crore for its secondary sale; and after the second tranche Carlyle holds 74% with Edelweiss retaining 26%. All agreements were signed, with final RBI and National Housing Bank approvals pending and closing expected "within the next three to four weeks" from early August 2026.18 As of this writing in early September 2026, no confirmation of completion has been identified in public disclosure.
Read this transaction for what it is. Edelweiss is not fixing the housing finance business; it is selling control of it to someone who thinks they can, at a price. That is a defensible decision — recognising that you are not the best owner of an asset is a real capital allocation skill, and one this group did not display in 2020. It also means the consolidated entity gets smaller.
One second-order detail from the same call is worth noting for anyone underwriting Nido's growth: management flagged that new RBI co-lending rules requiring a 180-day hold before sell-down had affected profitability, and that the business was recalibrating its expansion strategy around Carlyle's capital.18 Regulatory change is a live input to this business, not a background condition.
Insurance: fifteen years, no profit
The insurance segment — Edelweiss Life (formerly Edelweiss Tokio) and Zuno General Insurance — produced FY26 segment revenue of ₹3,482.30 crore, down 4.3% year on year, and a segment loss of ₹216.31 crore.21
Declining revenue and a continuing loss is the worst combination available. Note the proportion: this is the group's largest segment by revenue and its only structurally loss-making one.
There are signs of life at the margins. Zuno's gross written premium rose 58% in the June 2026 quarter to ₹287 crore, with management pointing to motor insurance, telematics, and OEM partnerships. Edelweiss Life's embedded value reached ₹2,306 crore.18 On the same call, Rashesh Shah stated that the business is "on path to break even" for the full year FY27 — not merely in the fourth quarter, which is the easier claim.189
Take that guidance seriously but not at face value, and here is why: breakeven has been promised and deferred repeatedly across more than a decade. The joint venture began operations in 2011.8 Fifteen years is longer than the seven-to-ten-year gestation that Indian private life insurance typically requires, and considerably longer than management's own earlier projections. The historical record does not falsify the FY27 target — it is a specific, checkable claim, and the embedded value trajectory is not inconsistent with it — but it does establish that this management team's insurance timelines have a systematic optimistic bias. The confirming event is unambiguous and arrives within twelve months: a full-year FY27 segment result at or above zero. Anything else, and the pattern extends to sixteen years.
What the segment picture actually says
Assemble it. The asset reconstruction business is the profit engine and the most defensible franchise, but it is regulator-dependent and currently operating at roughly half its former scale. EAAA is the highest-quality economic model in the group and the one credible growth vector, though smaller than its listing narrative will suggest. The mutual fund and housing finance businesses are being monetised to outside capital at prices that flatter the group's stated book value. The NBFC has been deliberately reduced to a rounding error. Insurance is a fifteen-year unresolved drag.
Any sum-of-the-parts case for EFSL has to reckon with a structural awkwardness: the two segments worth the most — ARC and EAAA — are also the two most exposed to the regulatory risk this group has repeatedly demonstrated it attracts. That is not a theoretical concern. It is what happened in 2024.
IX. The 2024 RBI Reckoning: Evergreening, Again
Return to that May morning in 2024, and look at what the RBI actually found — because the detail is more damning than the headline.
The findings
The supervisory action rested on a set of specific determinations. The core finding was that the group entities were "acting in concert" and had run "a series of structured transactions for evergreening stressed exposures of ECL, using the platform of EARCL and connected AIFs."1
The mechanism, unpacked: ECL Finance was taking over loans from non-lender group entities — companies within Edelweiss that were not licensed lenders — for the ultimate purpose of selling them to the group's own asset reconstruction company. Why route them through ECL? Because an ARC is permitted to buy financial assets only from banks and financial institutions. Loans sitting inside a non-lending group entity are not eligible. Pass them through a licensed NBFC first, and on paper they become eligible. The regulator's view was that this was a workaround, not a transaction.
"Evergreening" is the word that carries the weight, and it is worth defining precisely because it is the central accusation. Evergreening means keeping a bad loan alive so it never has to be recognised as bad — refinancing it, restructuring it, or moving it somewhere it will not be counted. It is the financial equivalent of moving a pile of debris from one room to another before an inspection. Nothing has been cleaned. The room being inspected merely looks clean.
The order listed additional findings beyond the central one: incorrect valuation of security receipts; incorrect reporting of eligible book debts for computing drawing power on borrowings; non-compliance with loan-to-value norms on lending against shares; incorrect reporting to CRILC, the RBI's central repository of large credit information; and know-your-customer lapses. Specific to the ARC, the regulator found that a prior inspection letter from the 2021–22 supervisory cycle had not been placed before the ARC's own board.1
That last item is the governance finding, and it is arguably the worst on the list. A regulator wrote to the company. The company did not tell its own directors. The Wire raised precisely this question in its coverage of the action, asking why the firm's directors had not acted when it mattered.25 For a board whose primary function is to be the internal check on management, being kept unaware of a supervisor's concerns is a failure of the control architecture, not a filing error.
The pattern, stated plainly
Here is the callback that belongs in this section rather than buried in a risk list.
The mechanism the RBI described in 2024 — routing group loans into the group's own ARC — is structurally the same mechanism Edelweiss used in 2019 and 2020 to shrink its wholesale book from ₹19,100 crore to ₹10,000 crore. It is also the same subject matter as the March 2021 whistleblower complaint alleging diversion of funds from the ARC in violation of investment norms, which triggered an MCA books inspection.16
Three episodes. Six years. One recurring practice.
That sequence should carry real weight against the claim that 2024 was an isolated lapse by a group that otherwise runs clean. The most charitable reading available on the evidence is that Edelweiss operated for years in a grey zone of intra-group asset transfers that it believed was defensible, received warning signals in 2021, and did not change the practice until the regulator forced it to in 2024. The less charitable reading is that it knew.
Context and consequences
On the same day as the action, RBI Deputy Governor Swaminathan J told an ARC industry conference that "some" Indian ARCs were being used as conduits for evergreening. Much of the media coverage framed this as presaging the Edelweiss action. Be careful with that inference: no source confirms Edelweiss was named in the speech, and the more defensible reading is that the RBI was signalling a sector-wide concern and chose the same day to make an example. That distinction matters — it suggests the supervisor was addressing an industry practice, not conducting a vendetta.
The personnel consequence came quickly. In June 2024, the RBI rejected the reappointment of Raj Kumar Bansal as managing director and chief executive of Edelweiss ARC.26 A central bank refusing to approve a senior appointment is among the sharpest tools it has short of licence action, and it is a direct statement about accountability.
The economic consequence was the AUM collapse already described: from ₹31,591.72 crore to ₹14,716.63 crore in twelve months, with acquisitions falling to ₹757.56 crore.22 The freeze hit the group's single most profitable segment, and the damage compounds — an ARC that stops buying today has less to recover from in three years.
The restrictions were lifted on December 17, 2024, with the RBI citing satisfactory remedial measures.27 The stock rose about 3% on the day. Seven months from order to lifting is fast by supervisory standards and is a genuine point in management's favour: the group did what was asked, quickly. No monetary penalty has been identified in public reporting. The precise remedial steps taken are, however, thinly documented publicly — we know the regulator was satisfied, but not what specifically satisfied it.
Is the fix durable?
Two data points bear on that question, pulling in opposite directions.
The first is that by the Q1 FY27 earnings call in August 2026, the episode did not come up at all — not in prepared remarks, not in analyst questions.18 Two years on, the market has filed it as resolved. That is either evidence of genuine resolution or evidence of short memories; the honest answer is that a quiet agenda is weak evidence either way.
The second is more concrete and cuts the other way. On September 30, 2025 — nine months after the RBI restrictions were lifted — two Edelweiss alternative investment fund entities, the Edelweiss Stressed and Troubled Assets Revival Fund Trust and EAAA itself, settled a SEBI adjudication proceeding for ₹61.42 lakh, with a twelve-month bar on named officers. The underlying allegations concerned failure to act in investors' interest and inadequate conflict-of-interest controls.28
The amount is trivial. The subject matter is not. Conflict-of-interest controls in a group whose defining regulatory problem has been intra-group transactions is precisely the area where you would want a clean record. And the entity involved was EAAA — the business now going public.
The forward KPI to watch is the one identified earlier: Edelweiss ARC's new-acquisition run-rate over the next several quarters. Having the restriction lifted on paper is not the same as having banks willing to sell you portfolios again. Reputational damage with a concentrated set of institutional sellers is slow to repair and does not show up in a press release. ₹300 crore of retail acquisitions in the June 2026 quarter, against ₹13,187 crore in all of FY24, suggests the origination engine has not yet recovered.
That gap between the regulatory clean slate and the operational reality is the most important unresolved fact in the current investment case — and it leads directly to the question of who is making the decisions.
X. Current Management: Incentives, Ownership, and the Capital-Allocation Record
Rashesh Shah has run Edelweiss for thirty-one years. That is longer than most Indian financial institutions have existed. It means the assessment of management here is not an assessment of a team; it is an assessment of one person's judgment across three cycles.
Ownership and alignment
Shah held approximately 15.39% of Edelweiss Financial Services in his personal capacity as of the June 2025 shareholding filing, with the promoter group in aggregate holding roughly 32%. Venkat Ramaswamy, the co-founder, held about 6.3%; Vidya Shah about 3.73%; the remainder sits with other family holders.
A 32% promoter holding in an Indian financial services company is meaningful skin in the game — enough that the founders' personal wealth is dominated by this one security, which is the alignment investors generally want. It is also not a controlling stake in the legal sense, which means the group is theoretically contestable, though no contest has ever materialised.
On pledges, precision matters. Edelweiss disclosed to the exchanges on April 9, 2026, under Regulation 31(4) of SEBI's takeover regulations, that the promoters had created no new encumbrance on their shares during FY26.29 That is a genuine positive — promoter pledging is one of the most reliable early warning signals in Indian mid-caps, and its absence during a year of active dealmaking is worth noting. But read the disclosure precisely: it confirms no new pledges beyond those already disclosed. It is not a statement that total pledges are zero. A clean current aggregate pledge figure could not be confirmed from public sources for this piece, and investors should pull it from the latest SAST filing rather than infer it.
The group's chief financial officer is Ananya Suneja, appointed effective March 1, 2022, previously finance controller for India at Deutsche Bank and a vice president at JPMorgan Chase. She has appeared as a listed participant on the company's earnings calls, including the Q2 FY25 call held during the RBI restriction period.3031
Vidya Shah's current role should be stated accurately because it is often misreported. She runs EdelGive Foundation and serves on several external non-profit boards. She holds no confirmed current executive or operating role at Edelweiss Financial Services. Her arc — from chief financial officer in the founding years to full-time philanthropy leader — is genuinely interesting, but she is not part of the management team whose credibility is being tested here.
The capital allocation record, stated in full
Cherry-picking is easy in a thirty-year history, so here is the complete ledger of major capital actions at the holding company level.
On the raising side: one meaningful equity raise in normal conditions — a ₹1,528 crore qualified institutional placement in November 2017 — followed by the four rescue rounds of 2019 to 2021 and the PAG buyout of the wealth business. On the returning side: one small buyback in April 2014, for up to ₹135 crore, and none since. Dividends have been modest; the FY26 recommendation was ₹1.50 per share.20
The pattern that emerges is unflattering: this is a group that has been a persistent net issuer of equity, that has raised most of its permanent capital from outside investors, and that has returned very little. CRISIL's tally of roughly ₹6,000 crore raised since 2016 against a March 2025 net worth of ₹5,918 crore is the cleanest single statement of this.13 Whatever else Edelweiss has been, it has not been a compounder of internally generated capital.
Against that, the 2025–2026 transactions genuinely represent something new. The WestBridge stake sale at 57 times earnings, the Carlyle transaction at a price that reflects Carlyle's confidence rather than Edelweiss's desperation, and an EAAA placement that was oversubscribed and deliberately capped — these are the first proactive, non-distressed capital allocation decisions of the past decade. Management has also attached a checkable target to them: reducing corporate debt from ₹5,700 crore to below ₹4,000 crore by the end of FY27, funded by the EAAA IPO, the Nido proceeds, investment sales, and dividend income from subsidiaries that management estimates at ₹600–800 crore annually.18
That is a specific, dated, verifiable promise. It is exactly the kind of commitment that will tell you, within eighteen months, whether the change in posture is real.
Guidance discipline: the clearest credibility test
Which brings us to the pattern that should most temper confidence in any Edelweiss forward target.
Take the wholesale book wind-down. The original commitment was to exit by 2022. That was missed. It was reset to a ₹5,900 crore target in 2021. That was missed. It was reset again to ₹2,900 crore in 2022. The residual book reached roughly ₹2,400 crore only by the first half of FY26.
Three successive downward rebasings of the same promise over about six years. Note what this is and is not. It is not a single miss with a clear explanation — those happen to everyone, and a management team that explains one honestly deserves credit. It is a repeated pattern of setting a timeline, missing it, and setting a new one, on the group's single most important balance sheet clean-up. The insurance breakeven story follows the same shape over an even longer horizon.
The analytical conclusion: Edelweiss management has a demonstrated systematic bias toward optimistic timelines on multi-year commitments. This does not mean the FY27 insurance breakeven or the sub-₹4,000 crore debt target are wrong. It means the base rate for this specific team hitting a multi-year target on the first stated date is poor, and forward guidance from this group should be discounted accordingly — particularly any growth guidance offered around the EAAA listing, where the incentive to be optimistic is at its highest.
Where the pressure has come from
An activist-style stress test of Edelweiss would find plenty of material: a holding structure that makes valuation genuinely hard; segments that have destroyed capital for over a decade; related-party asset transfers that a central bank characterised as evergreening; a board that was not shown a regulator's inspection letter; and a founder-chairman who has occupied the top role for three decades without meaningful succession disclosure.
And yet organised shareholder activism has been essentially absent. No proxy advisory firm — IiAS, InGovern, or SES — has been identified as issuing an adverse vote recommendation specifically tied to the RBI-action years. Dissent on the postal ballot approving the WestBridge transaction was negligible, at roughly 0.02% against. The pressure on this management has come almost entirely from outside the shareholder base: from the RBI, from SEBI, from the Ministry of Corporate Affairs, and from litigation.
On litigation, one matter deserves careful and sober mention. In August 2023, the art director Nitin Desai was found dead at his studio near Karjat. His company, ND's Art World, had borrowed ₹185 crore from ECL Finance across loans taken in 2016 and 2018, with repayment problems beginning in January 2020, and his total debts reportedly exceeded ₹250 crore. An FIR was registered under sections 306 and 34 of the Indian Penal Code — abetment of suicide and common intention — on a complaint by his widow alleging repeated mental harassment in connection with the loans.32 Edelweiss ARC's response was that it had followed all legal processes as mandated by the RBI and had not acted outside the legal framework.33 Rashesh Shah and Raj Kumar Bansal subsequently approached the Bombay High Court seeking to quash the FIR against them.32
No finding has been made against them, and it would be wrong to treat an FIR as a verdict. It is included here because recovery conduct is a genuine operational risk in the distressed-debt business — reputationally, legally, and politically — and because it is part of the record an investor in this specific franchise is buying into.
That a company's only effective governance check has been its regulators, rather than its owners, is itself the finding. It suggests that if the RBI had not acted in 2024, nothing internal to Edelweiss would have stopped the practice.
XI. Playbook: Business & Investing Lessons
Five things this thirty-year history teaches that generalise beyond one Indian financial conglomerate.
Regulatory arbitrage is a recurring temptation, not a one-time mistake. In structured and distressed finance, the gap between what the rules say and what a clever structurer can achieve is where a great deal of reported profit lives. The Edelweiss record shows the same intra-group transfer mechanism appearing in 2019, drawing a complaint in 2021, and drawing an enforcement action in 2024. Once a firm builds an internal capability for this kind of structuring — the people, the systems, the institutional habit — it does not disappear because a regulator objects once. Investors should treat a first enforcement action in this domain as a base rate, not an outlier.
Judge conglomerate value-unlock stories by whether the seller chose the moment. "We sold a stake in our subsidiary to a marquee investor and are considering a listing" is the same sentence whether it is uttered from strength or from a liquidity crisis. The economics are opposite. Edelweiss ran that playbook in 2020 under duress and lost majority control of its best asset; it is running the same playbook in 2025–2026 with pricing power and oversubscribed placements. The correct test is not what management says about the strategy — it is what the buyer's alternatives were.
One dominant, profitable business can mask years of capital destruction elsewhere. The asset reconstruction segment converted more than half its revenue to pre-tax profit in FY26 while the insurance segment lost money on declining revenue. Consolidated, they net to a respectable-looking result. Sum-of-the-parts analysis is only useful if every part is sized honestly, including the parts with negative value — and a segment that has consumed capital for fifteen years without earning a return has negative value regardless of its embedded value disclosure.
Guidance slippage compounds differently from operational misses. A company that misses a target once and explains why retains credibility. A company that rebases the same target downward three times over six years has taught the market that its numbers are aspirations. The second pattern is much harder to reverse, because the only cure is a multi-year record of hitting stated targets — which by construction takes multiple years to establish.
In regulated finance, check "the crisis is over" against credit ratings, not stock prices. Equity is a call option on the future and reprices on sentiment. A credit rating is a considered judgment about the durability of a balance sheet, and it directly determines the cost of the raw material — funding — in every lending business the group owns. Edelweiss's equity has recovered substantially from its 2024 low. Its long-term rating sits at A+, several notches below where it stood before September 2018, and was cut again in December 2023.1213 When those two signals diverge for years, the rating is usually the one to weight.
XII. Risk Radar
Regulatory and political risk. This is the single most material risk to this specific case, and it is not generic. The group has a demonstrated, documented history — a 2021 whistleblower complaint and MCA inspection, a 2024 RBI enforcement action, a 2025 SEBI settlement — of intra-group structuring practices attracting scrutiny. The two segments carrying the most value, the ARC and EAAA, are the two most exposed to a repeat. A second RBI action against the ARC would not merely pause acquisitions; it would call into question whether banks should transact with the franchise at all.
Execution risk in the monetisation programme. The entire current bull case rests on three transactions completing at or near announced terms. The Nido transaction awaits RBI and NHB approval; the EAAA IPO awaits SEBI clearance and a receptive market window that management has indicated it hopes to hit around October 2026.18 Any of these can slip. An IPO in particular is hostage to conditions no management team controls — and because the EAAA offer is entirely secondary, a weak window means Edelweiss either accepts a lower price for its own stake or waits, delaying the debt reduction the whole plan is built around.
Refinancing and cost-of-capital risk. With a Crisil A+ rating, group gearing of 3.4 times, and net debt of ₹11,334 crore as of September 2025, Edelweiss borrows at a structurally higher cost than better-rated peers.13 In a spread business, funding cost is not a line item — it is the competitive position. Every lending business the group retains competes at a permanent handicap until the rating improves, and rating improvement requires exactly the sustained profitability that CRISIL described as subdued.
Insurance segment drag. A fifteen-year-old, still-loss-making bet with a repeatedly deferred breakeven. A further slip beyond FY27 would be a double hit: directly to consolidated profit, and simultaneously to the credibility of every other forward target management offers. Note also that segment revenue declined in FY26 — breakeven achieved through cost reduction on a shrinking book is a materially lower-quality outcome than breakeven achieved through growth.
Holding company discount and the residual-claim problem. This is the structural risk that receives the least attention. As Edelweiss sells down stakes in its best businesses — 15% of the AMC, up to 74% of Nido, an IPO tranche of EAAA — the listed EFSL entity progressively becomes a claim on whatever has not yet been monetised, plus cash, minus corporate debt. Shah's insistence that "we are not a holding company, we are an investment company" is a real distinction in intent, but the market does not price intent.18 Indian holding companies routinely trade at 40–60% discounts to the sum of their stakes, and the discount tends to widen, not narrow, as the operating control weakens. Owning a minority stake in a good business through a listed vehicle is worth measurably less than owning the business.
XIII. Bear vs. Bull Case & Valuation
Bear Case
The top line has gone essentially nowhere. Five-year revenue growth for the consolidated group has been close to flat on screener-level data, and the FY26 profit improvement was driven by margin and mix — the alternatives and capital markets segments doing better — rather than by underlying volume growth across the group. A financial conglomerate that is not growing its revenue base is, over time, a business shrinking in real terms.
The credit rating remains below its pre-2019 level more than seven years after IL&FS, and CRISIL's own language in January 2026 attributes this to profitability that has not revived as expected, alongside a monitorable portfolio still measured in thousands of crores.13 That is a rating agency declining to endorse the recovery narrative.
The regulatory pattern is the bear case's strongest card, and it is not a single event. Three related episodes across six years, all concerning how assets move between entities inside this group, is a frequency that no peer of comparable size matches. The remediation was fast, but remediation after the third instance is different from remediation after the first.
The guidance record undermines confidence in the forward plan. Three downward rebasings of the wholesale exit target and more than a decade of deferred insurance breakeven mean the FY27 targets — insurance profitability, sub-₹4,000 crore corporate debt — carry a discount that management has earned.
And the structure itself is hard to underwrite. Six businesses, several partially owned, one heading for a separate listing, one being handed to Carlyle, one loss-making — and a stated corporate strategy of continuing to sell down the best pieces.
Bull Case
Edelweiss ARC remains the scale leader in an industry with a real regulatory barrier to entry, and the FY26 margin — more than half of segment revenue converting to pre-tax profit — demonstrates the economics are genuine, not accounting.21
EAAA is a legitimately fast-growing platform with attractive economics: 27% fee-paying AUM growth, a 2.89% revenue yield, and a 29% return on equity in the June 2026 quarter, with a near-term listing catalyst.18 Alternatives fee streams are contractual, long-duration, and capital-light — the best business model in the group by a wide margin.
The 2025–2026 transactions were struck at prices that sophisticated buyers had to justify to their own investment committees. WestBridge paid 57 times earnings for the AMC.11 Carlyle committed ₹2,100 crore to a housing finance business with under ₹5,000 crore of AUM and brought Aditya Puri alongside.2324 The EAAA placement at a ₹8,500 crore valuation was oversubscribed.19 Against a consolidated market capitalisation of roughly ₹12,760 crore, these marks imply the parts are worth more than the whole.3
The governance signals have improved at the margin: no new promoter encumbrances in FY26, and institutional buying through 2025 from Carnelian Asset Management in May and Abakkus in August.29
And management resolved a serious RBI enforcement action in seven months rather than years — evidence of an organisation that can execute remediation under pressure.27
Porter's Five Forces on the businesses that matter
Threat of new entrants — low in ARC, moderate in alternatives. Running an ARC requires an RBI licence, minimum net owned funds, and credibility with a small set of bank counterparties. That is a real barrier. Alternatives is different: raising a private credit fund in India requires an AIF registration, a track record, and relationships, but the number of credible platforms has multiplied over the past five years, and global managers are entering.
Bargaining power of suppliers — high, and this is the ARC's underappreciated weakness. The suppliers of raw material are banks, and by regulation they are the only legal sellers. When bank asset quality is good, supply contracts. When a bank chooses not to deal with a particular ARC — for reputational reasons, say — that ARC has no alternative source. Supplier concentration this extreme is not usually compatible with a durable moat.
Bargaining power of buyers — moderate. In alternatives, the buyers are institutional LPs and family offices who can and do compare fee terms across managers. The 2.89% yield holds only as long as the strategies are genuinely differentiated. In the mutual fund business, buyer power is high and rising as the industry moves toward direct plans and passive products.
Threat of substitutes — real and growing in distressed assets. ARCs are no longer the only route for a bank to clean its balance sheet. The Insolvency and Bankruptcy Code lets banks pursue resolution directly; the National Asset Reconstruction Company was created as a state-backed alternative; and direct sales to funds and to the National Company Law Tribunal process compete for the same assets. Every one of these reduces the necessity of an ARC.
Rivalry — intense and price-based in the segments that grow. In mutual funds and alternatives, competition is on fees and performance, both of which compress. In distressed assets, rivalry shows up in auction pricing, where an aggressive bidder like Omkara ARC can compress returns for everyone.
Seven Powers
Applying Hamilton Helmer's framework as a discipline rather than a decoration, Edelweiss's position is thinner than the narrative suggests.
Scale economies: partially present in the ARC, where fixed recovery infrastructure spreads over a larger book — but the book just halved, which is exactly how scale economies unwind.
Network economies: absent. There is no mechanism by which one more Edelweiss client makes the platform more valuable to the next.
Counter-positioning: absent today. The one genuine instance in the group's history was Edelweiss Mutual Fund's direct-to-investor brand building under Radhika Gupta, which incumbents dependent on bank distribution found awkward to copy — but that is a small business.
Switching costs: low in alternatives, where LPs re-underwrite at every fund vintage; low in mutual funds; moderate in the ARC, where a bank that has sold you a portfolio has an interest in your recovery success but no lock-in on the next sale.
Branding: mixed, and the honest reading is negative at the group level. The Edelweiss brand carries the 2019 and 2024 episodes with it. Notably, the wealth business was renamed Nuvama on separation, and the housing finance business was renamed Nido — two occasions on which a business leaving the group's direct control shed the group's name.
Cornered resource: the strongest candidate is EAAA's operating asset team in renewables and infrastructure, which Amit Agarwal identified as the platform's differentiator.18 Sixty specialists with two decades of sector operating experience is genuinely hard to assemble quickly. But people are a cornered resource only while they stay, and asset management teams are portable.
Process power: not evident. The most process-intensive activity in the group — distressed recovery — has produced a return on equity of 13% against a 14–15% target, which is competent rather than exceptional.18
The synthesis: Edelweiss's real advantages are a regulatory licence in a protected industry, three decades of relationships, and a genuinely good alternatives team. Those are worth something. They are not the kind of compounding advantages that justify paying up for permanence, and the group's own history is the evidence — this is a franchise that has twice been brought to the edge by its own risk-taking, which is not what a durable moat produces.
The KPIs that actually matter
Three, and no more. Everything else is noise.
One: Edelweiss ARC's quarterly new-asset acquisition run-rate. This is the direct measure of whether the most profitable franchise in the group has recovered its origination engine after the RBI freeze, and whether banks are willing to transact with it again. The comparison base is FY24's ₹13,187 crore of acquisitions.22
Two: EAAA's fee-paying AUM and blended revenue yield, tracked together. AUM growth alone can be bought by cutting fees. The combination tells you whether the platform is winning mandates on differentiation or on price, and it is the single best read on the quality of the group's one genuine growth engine.
Three: the insurance segment's path to breakeven, and specifically whether it comes with growing or shrinking revenue. This is simultaneously the cleanest test of a fifteen-year capital allocation decision and the cleanest test of whether this management team's stated timelines can be relied upon.
XIV. Epilogue: What Would Change the Verdict
There is a version of the next three years in which this story resolves cleanly. The EAAA IPO completes at or above the ₹8,500 crore mark implied by the March 2026 placement, validating that the group can sell an asset to public markets from strength rather than accepting a discount from a distressed position. The Carlyle money closes into Nido and the housing book becomes someone else's problem to fix. Corporate debt falls below ₹4,000 crore on schedule. Insurance breaks even in FY27, as promised, with revenue growing rather than shrinking. And Edelweiss ARC's acquisition run-rate climbs back toward pre-2024 levels, proving that the banks never really stopped trusting it.
If all five happen, the reasonable conclusion would be that the 2024 episode was expensive but survivable, that management genuinely changed its posture on capital allocation in 2025, and that what remains is a smaller, cleaner group with two good businesses and a lot fewer distractions.
There is also a version in which it does not. The IPO slips or prices below the placement mark. The ARC's acquisitions stay at a fraction of former levels, revealing that lifting a restriction and restoring a franchise are different things. Insurance breakeven moves to FY28 for the fourth time. And the group ends up as a listed holding vehicle with minority stakes in businesses it no longer controls, trading at the discount that structure attracts.
The single most important signal, and it is available quarterly, is the ARC acquisition number. Everything else in the bull case can be explained by market conditions. That number cannot — it is a direct measure of whether the institutions that supply this business with its raw material still want to do business with it.
The second is the EAAA listing outcome, because it is the first genuine market test of the value-unlock thesis, and because a company selling 100% secondary shares into a public offering is telling you something about where it thinks the value is.
The third is whether insurance actually breaks even in FY27. It is a small number in the scheme of consolidated profit. It is a very large number in the scheme of whether an investor can take this management's forward statements at face value.
And there is a fourth signal, which is not a number but an absence. The pattern in this story — 2019, 2021, 2024 — is of a group that kept finding its way back to the same structural practice, and kept being caught doing it. If a fourth related-party or intra-group structuring episode surfaces, it would falsify, more directly than any financial metric could, the claim that Edelweiss has become a clean, disciplined, well-governed conglomerate. If several years pass without one, that is the strongest evidence available that something inside the organisation actually changed after May 29, 2024.
The company has told the market it has changed. The record says it has changed before, and then changed back. The next three years are when we find out which pattern holds.
References
-
RBI press release imposing business restrictions on ECL Finance Limited and Edelweiss Asset Reconstruction Company Limited — Reserve Bank of India (FIDC mirror), 2024-05-29 ↩↩↩
-
Edelweiss tanks 17% as RBI imposes business restrictions on EARCL, ECL Finance — Business Standard, 2024-05-30 ↩
-
Edelweiss Financial Services Ltd share price, market capitalisation and all-time high — Business Standard Markets ↩↩↩
-
Upcoming IPO: EAAA India Alternatives files DRHP with SEBI for ₹1,500 crore public offer — Upstox, 2026 ↩↩↩
-
Edelweiss to acquire Anagram Capital for Rs 164 cr — Business Standard, 2010-01-27 ↩
-
Edelweiss Capital units complete acquisition of Anagram Capital — Moneylife, 2010 ↩
-
Commencement of Business by Edelweiss Tokio Life Insurance Company Limited — Tokio Marine Holdings, 2011-06-14 ↩↩
-
Edelweiss Life targets double-digit growth and FY27 breakeven — Insurance Business Asia ↩↩
-
Edelweiss Fin Services acquires Forefront Capital Management — Business Standard, 2014-05-01 ↩
-
WestBridge picks up 15% stake in Edelweiss AMC for Rs 450 crore — Business Standard, 2025-08-22 ↩↩↩↩
-
CRISIL downgrades Edelweiss Financial Ltd's long-term rating — Business Standard, 2023-12-18 ↩↩
-
Edelweiss Financial Services Limited — Rating Rationale, CRISIL Ratings, 2026-01-09 ↩↩↩↩↩↩↩
-
Edelweiss Financial surges 12% as CDPQ to invest Rs 1,800 crore in NBFC arm — Business Standard, 2019-03-06 ↩
-
PAG buys $300 million majority stake in Edelweiss wealth unit — Bloomberg, 2020-08-27 ↩
-
Edelweiss ARC lands in the middle of whistleblower allegations, shareholder tiff — Hemindra Hazari, 2021-03-19 ↩↩
-
Edelweiss founders divest stake in Nuvama Wealth Management after demerger — Business Standard, 2024-08-22 ↩
-
Edelweiss Financial Services Limited Q1 FY2027 Earnings Call Transcript — AlphaStreet, 2026-08-06 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Edelweiss Financial Services sells 4.4% stake in EAAA India Alternatives — Business Standard, 2026-03-09 ↩↩↩↩
-
Investor Presentation Q4 FY26 — Edelweiss Financial Services, 2026-04 ↩↩
-
Edelweiss Financial Services: FY26 segment results and annual report for FY2025-26 — InvestyWise, 2026 ↩↩↩↩
-
Edelweiss ARC eyes ₹6,000 cr in recoveries in FY26; to invest ₹1,000 cr to acquire NPAs — Business Standard, 2025-06-23 ↩↩↩
-
Edelweiss to bring in Carlyle as strategic majority investor for its housing finance business — The Carlyle Group ↩↩
-
Carlyle to acquire majority stake in Edelweiss's Nido Home Finance for ₹2,100 crore — Business Standard, 2026-02-10 ↩↩↩
-
RBI restrictions on Edelweiss: why did the firm's directors sleep when it mattered — The Wire, 2024 ↩
-
RBI rejects Raj Kumar Bansal's reappointment as Edelweiss ARC MD/CEO — Business Standard, 2024-06-11 ↩
-
RBI lifts restrictions on ECL Finance, Edelweiss ARC after compliance — Business Standard, 2024-12-17 ↩↩
-
Settlement order in the matter of examination of SCORES complaints against Edelweiss Stressed and Troubled Assets Revival Fund Trust — SEBI, 2025-09-30 ↩
-
Edelweiss Financial Services confirms no encumbrance on promoter shares in FY26 — ScanX, 2026-04-09 ↩↩
-
Q2 FY2025 Edelweiss Financial Services Ltd earnings call transcript — GuruFocus, 2024-10-29 ↩
-
Ms. Ananya Suneja, Chief Financial Officer, Edelweiss Financial Services Ltd — Trendlyne ↩
-
Nitin Desai suicide case: insolvency professionals urge PM, MCA, IBBI; Edelweiss' Shah, Bansal approach High Court — Moneylife ↩↩
-
Nitin Desai suicide: 'Did not act outside legal framework,' says Edelweiss ARC — Free Press Journal ↩
-
Edelweiss chairman Rashesh Shah on what's holding back India's credit market evolution — The Core, 2025 ↩
-
India (and Edelweiss)'s long-term opportunity is bright but the short term can be messy — Forbes India ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube