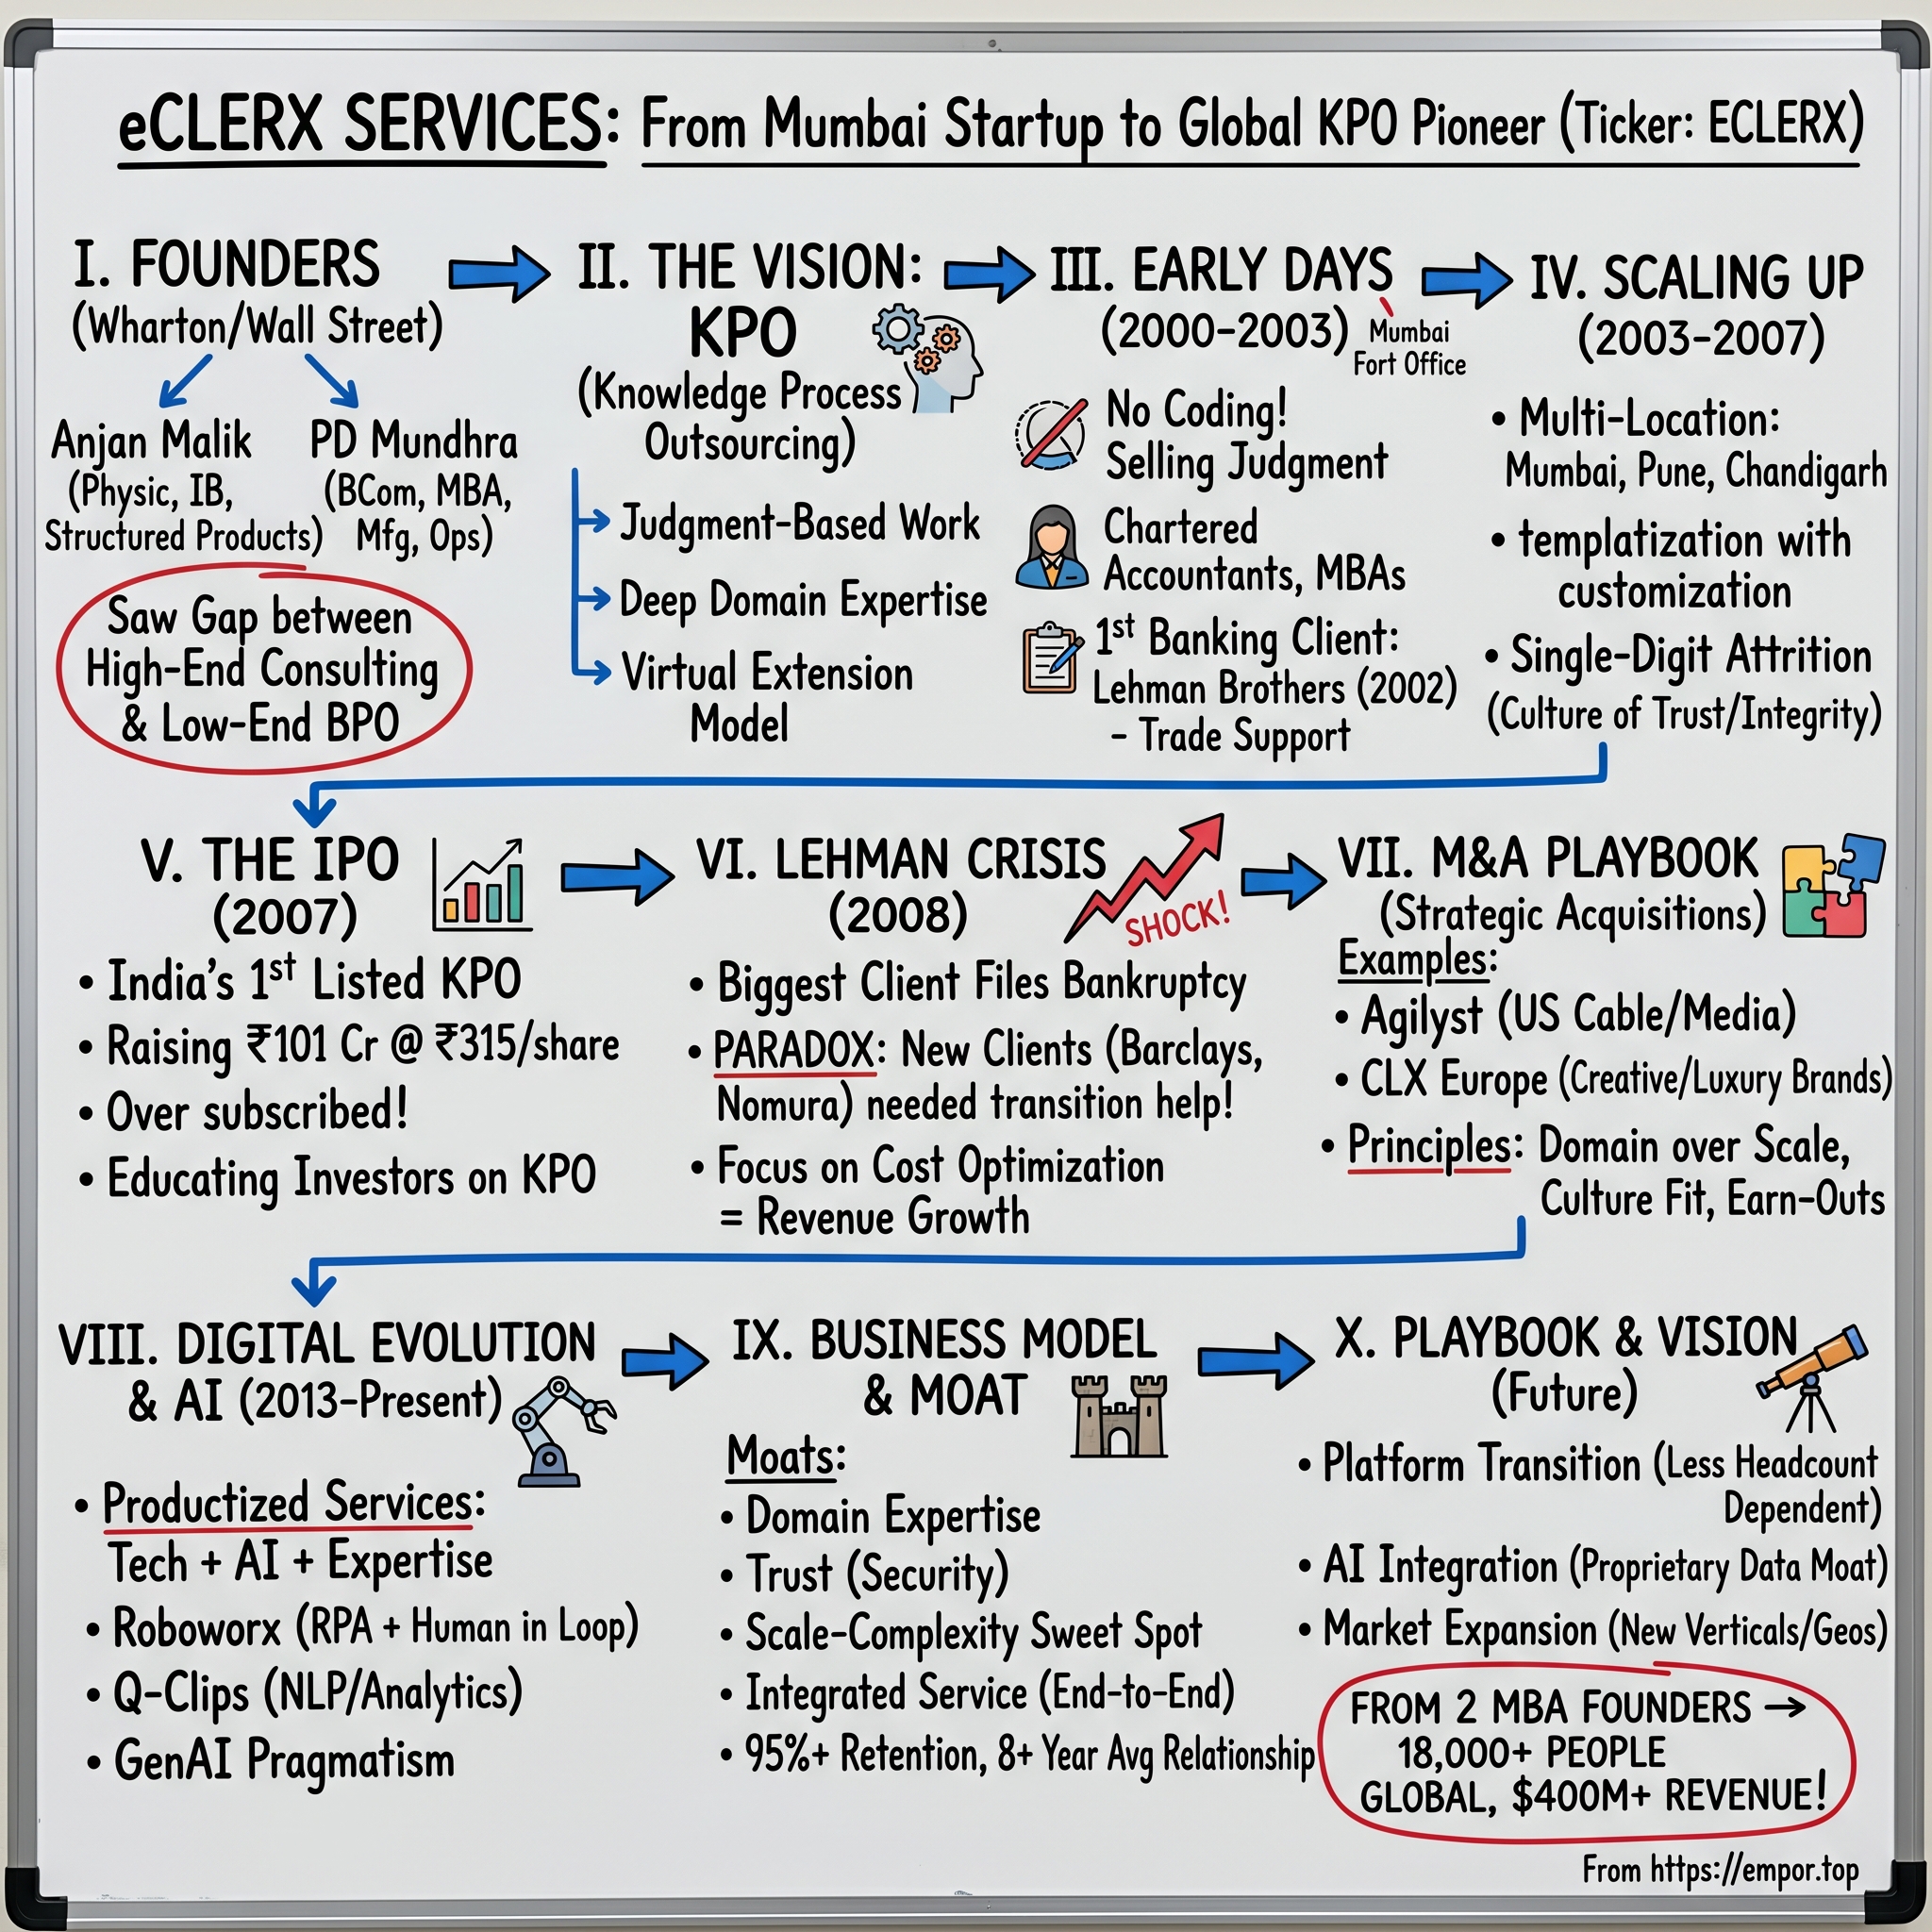
eClerx Services: The Boutique KPO That Chose to Stay Small
I. Introduction & Episode Setup
On the morning of September 2, 2026, in a room full of Mumbai analysts who had spent three years watching this company quietly outgrow its own reputation, eClerx Services put a slide on the screen with eight words on it and nothing else.
"We are poised to be a $1 billion enterprise."1
No date. No bridge. No revenue build. Just the assertion, sitting alone on a white background, from a company that had crossed a $500 million annualized revenue run rate only four weeks earlier and announced it as a milestone.2 The room had just been walked through a growth blueprint covering the years FY2024 to FY2029, three strategic pillars, a portfolio of AI toolkits with names like Mortgage360 and FinOps, and a finance section that compared eClerx's profitability favourably against a peer group of India-listed IT and ITES companies. And then: a billion dollars.
It is a genuinely interesting moment to catch this business. eClerx sits at roughly ₹17,760 crore of market capitalisation — call it $1.9 billion — with the stock around ₹1,889 a share, some 24% below its 52-week high of ₹2,497.50.3 It employs about 22,400 people across 17 countries.2 It earned ₹706 crore of net profit in the fiscal year that ended March 31, 2026, up 30.5%, on revenue that grew 22.6% to ₹4,217 crore.4 Those are, by any measure, excellent numbers.
And yet the same company is roughly one-tenth the size of Genpact, which reported $5.08 billion of 2025 revenue.5 It is a fifth the size of EXL, at $2.09 billion.6 Its third obvious comparable, WNS, no longer exists as an independent company at all — Capgemini completed a $3.3 billion cash acquisition of it on October 17, 2025, and immediately described the combination as "a global leader in Agentic AI-powered Intelligent Operations."7
So here is the tension that runs through this entire story. eClerx was built by two ex-Lehman Brothers bankers who decided, in 2000, that the interesting money in outsourcing was not in doing more work more cheaply but in doing harder work — the judgment-heavy stuff that generic call-centre scripts could not touch. That bet made them India's first listed knowledge process outsourcing company. Twenty-six years later, the bet has produced a business with genuinely superior margins and returns, a professional CEO running it for the first time in its history, and a set of unresolved problems that management itself names out loud every quarter.
The largest of those problems is arithmetic. In the quarter ended June 30, 2026, eClerx's top ten clients still accounted for 60% of revenue — a number that had been 63% a year earlier, ticked down to 59% at the end of March, and then went straight back up.8 On the October 2025 call, when an analyst asked whether the faster growth outside the top ten was finally broadening the base, CEO Kapil Jain answered without spin: "the concentration has only improved by 0.5% point despite showing a good growth in non-top 10 and emerging."9 That is not a company hiding a problem. It is a company telling you the problem is harder than it looks.
The second unresolved question is AI, and it cuts closer to the bone here than at almost any other listed services business, because the work eClerx defined itself around — nuanced, rules-based, requires-a-human-who-understands-the-domain — is precisely the work that large language models are being sold to automate. Management's answer is that AI is an opportunity. The evidence for and against that claim, including management's own guidance about when its flagship agentic deal will actually produce revenue, is the most important thing in this story.
Over the next several sections: what a KPO actually sells and why it was different; what the founders built and what happened in the half-decade when the model stopped working; the full record of three acquisitions and what the FY2026 subsidiary accounts reveal about how each one turned out; the economics of the core engine and the industry structure it sits inside; the handover from founders to a professional CEO and what the pay arrangements and buyback behaviour say about incentives; and finally, the AI question, tested against the company's own numbers rather than its own adjectives.
 Subscribe on LinkedIn
II. What a KPO Actually Sells, and Who Built It
Two Indians met at the Wharton School in the mid-1990s and graduated in 1996 with finance MBAs and, by their own later account, an understanding that they would one day build something together.
Priyadarshan Mundhra — universally "PD" — had come from a Commerce degree at St. Xavier's College in Kolkata, and after Wharton went to Citibank in Mumbai and Lehman Brothers in New York. He also spent three years running a capital goods manufacturing business, an unglamorous detail that matters more than it sounds: he had actually managed an operation with a shop floor.10 Anjan Malik had read Physics at Imperial College in London, spent three years at Accenture in Europe, and then more than seven years at Lehman Brothers in New York and London, where he helped build a global structured products business.10
Structured products is a useful clue to what came next. It is a business in which the money is made not on the trade itself but on getting the plumbing right — the term sheets, the reference data, the confirmations, the reconciliations. Malik had spent years inside a bank watching how much expensive human attention got consumed by work that was neither strategic nor mechanical. It was in between. It required someone who understood what a corporate action was, but not someone who needed to be paid like a trader.
That gap is the entire company. eClerx Services Private Limited was incorporated on March 24, 2000.10 The founding image is deliberately unromantic: five people and five computers in Mumbai.
What "knowledge process outsourcing" actually means
Strip away the acronym and the proposition is simple. A traditional BPO takes a process that has already been written down as a script — answer the phone, ask these six questions, route the ticket — and executes it somewhere cheaper. The value is arbitrage on labour cost, and because the script is the product, the work is fundamentally commoditised: anyone with a building and a headset can bid.
A KPO takes a process that cannot be fully written down. Consider a bank's trade reference data. Every derivative contract, every corporate bond, every equity swap has dozens of attributes that must match across systems, counterparties and regulators. When they do not match — and they constantly do not match — someone has to look at the exception and decide what actually happened. Was the coupon reset misapplied, or did the issuer change the terms? Is this a genuine break or a timing artefact? There is no script. There is a person who has seen ten thousand of these and knows which of the four plausible explanations is usually right.
The analogy that gets closest is the difference between a copy-editor and a translator. A copy-editor applies rules. A translator has to understand what the sentence means before deciding how to render it, and two competent translators will produce different output. eClerx sold translators. The pitch was that this work was too nuanced to script, too repetitive and too expensive to keep in New York or London, and too consequential to hand to a generalist. That last word — consequential — is the load-bearing one. A settlement break at a Tier-1 bank has a direct P&L and reputational cost, which is why, as the company put it at its 2026 investor day, clients buy from a provider whose delivery is resilient rather than merely cheap.1
The founders split the company geographically from the first year: Malik ran client origination out of London and New York, Mundhra built delivery in Mumbai. This is now such a standard template for Indian services businesses that it is easy to forget it was a real design choice, and it produced a durable cultural artefact — eClerx has always been run as much from the client side as from the delivery side.
December 2007, and the year that followed
On December 4, 2007, eClerx opened its initial public offering with a price band of ₹270 to ₹315 per share. It closed on December 7, priced at the top of the band, raised ₹101 crore, and listed on both the BSE and NSE on December 31, 2007.1110 It was India's first publicly listed KPO — a genuine category first, and the company used the label in its own boilerplate for the next decade.12
The timing looks, in retrospect, close to catastrophic. eClerx listed roughly nine months before Lehman Brothers — the firm both founders had worked for — collapsed, taking with it a large part of the sell-side ecosystem that was eClerx's core client base.
What happened instead is the single most important structural fact about this business, and it is counter-intuitive. The crisis was good for eClerx. When banks are growing, they buy discretionary projects. When banks are in trauma, they buy cost reduction and regulatory compliance — and both of those are eClerx's product. Post-2008 financial regulation created an enormous, mandatory, non-discretionary volume of client onboarding, know-your-customer refreshes, transaction monitoring and trade reporting. Somebody had to do all of it, and nobody wanted to do it in Manhattan.
The company scaled through the 2010s on that tailwind, adding delivery centres in Pune and Chandigarh and growing from hundreds of employees to thousands. By March 2018 the delivery headcount was 9,351.12
The half-decade that falsifies the easy story
Here is where a promotional version of this article would move briskly to the present. It should not, because the period from roughly FY2016 to FY2021 is the strongest disconfirming evidence available against the claim that vertical specialisation is a durable, self-sustaining moat — and it comes from eClerx's own investor day deck.
On slide 69 of the September 2026 presentation, the company showed its dollar revenue growth against a peer set of India-listed IT/ITES companies plus offshore-heavy foreign-listed peers, over ten years. The FY2016 to FY2021 line reads: eClerx compound annual growth of 1%, peers 9%.1 For five years, a specialist that told investors its domain depth made it different grew at roughly a ninth the rate of the generalists it claimed to be differentiated from.
The texture is worse than the CAGR. In fiscal 2018, operating revenue rose 2% in dollar terms to $198.6 million, and net profit fell 18% to ₹290 crore.12 Three years later, in fiscal 2021, revenue had crawled to just over $210 million and net profit was ₹283 crore — still below the FY2018 figure.13 The business went sideways on revenue and backwards on profit for half a decade.
The reasons were mundane and instructive. Concentration cut both ways: when a large cable and telecom client rationalised its outsourced footprint, there was no long tail to absorb it. Pricing on mature, well-understood processes ground lower every renewal cycle, because the second and third vendor into an account can always quote below the incumbent for work whose scope is now documented. And the "digital" diversification bought in 2015 — which the next section examines in detail — did not scale as promised.
What does that record actually establish? Not that eClerx has no advantage; the margin evidence in Section IV says otherwise. It establishes something more specific and more useful: eClerx's advantage is account-level, not market-level. It is very hard to displace inside a workflow it already runs. It has never demonstrated an ability to compound reliably by winning new accounts fast enough to offset the natural erosion of old ones. Every claim made later in this story — about AI optionality, about the $1 billion ambition, about the new delivery geographies — has to survive that distinction.
Which brings us to the three occasions when management tried to buy its way out of it.
III. The M&A Record: What Actually Got Bought, and How It Played Out
Turn to page 163 of eClerx's FY2026 annual report — deep in the standalone financial statements, in the note on non-current investments — and you will find a single line that no press release ever celebrated.
Against an investment of ₹605.67 million in preference shares of a subsidiary called eClerx Investments Limited, the company carries a provision for diminution in value of ₹605.67 million.14 A hundred percent. The asset is on the balance sheet at zero, and it has been carried at zero for at least two years.
eClerx Investments Limited is the overseas subsidiary through which, on April 12, 2012, eClerx announced the acquisition of Agilyst Inc.15
That is the right place to begin an honest audit of this company's acquisition record, because the question that matters is not whether each deal was announced with a strategic rationale — they all were — but whether each one earned back its purchase price. Three deals in fourteen years. One clear success, one clear disappointment, and one whose acquisition vehicle now sits fully written down. Let us take them in order.
Agilyst, 2012: the capability tuck-in
Agilyst was small. Founded in 2007 by Mahesh Dhillon, it was a back-office operations and analytics business serving the North American media industry — critical error identification, customer experience analysis, end-user support — with roughly 1,000 employees, mostly in India, and revenue expected to come in just under $10 million for fiscal 2012.15 The consideration was all cash with what the announcement called a substantial earn-out based on future performance; the headline price was not disclosed by the company.1516
Strategically it did what it was supposed to do. It gave eClerx a real position in cable and telecom operations for large US media clients — a vertical that today generates about a quarter of group revenue.8 Agilyst was amalgamated into the parent structure and the brand disappeared.
But the full provision against the holding entity is a fact that deserves to sit next to the strategic rationale rather than in a footnote. It does not prove the Agilyst deal destroyed value — an intermediate holding company can be written down for reasons ranging from restructuring to intra-group transfers of the underlying business, and eClerx Investments Limited does not appear in the FY2026 list of subsidiaries where control exists, suggesting it is no longer an operating vehicle.14 What it does establish is that the capital originally routed through that entity is not recoverable at that level, and that the annual report has never explained why in narrative form. For a company whose investor day slide reads "Prudent M&A," that is a gap in the disclosure rather than a scandal.
CLX Europe, 2015: the one to interrogate hardest
In April 2015, eClerx agreed to buy CLX Europe S.p.A., an Italian creative-content business, for €25 million, from two Italian private equity firms, Progressio sgr and Opera sgr, which had owned it since 2008.17 CLX created, managed and delivered creative assets — product photography, catalogue content, digital asset management — for luxury brands, major retailers and publishers, with delivery centres spanning Italy, Germany, the UK and Thailand. In calendar 2014 it had revenue of €19.4 million and EBITDA of €4.5 million.17 The acquisition closed on April 22, 2015.14
The thesis was explicit and, on paper, sensible: move up the value chain out of pure process work into creative and "digital lifecycle" services, and cross-sell a European luxury client base that eClerx did not otherwise reach.
Eleven years of evidence is now available, and it is not favourable.
Start with the seller's own numbers. Progressio and Opera bought CLX in 2008, when it had revenue of €30.8 million and EBITDA of €12.8 million.17 By the time eClerx bought it, revenue had fallen by more than a third and EBITDA by nearly two-thirds. eClerx paid roughly 5.6 times trailing EBITDA for a business whose earnings had collapsed by 65% over the prior seven years. That multiple looks cheap — until you ask whether the decline had stopped, and the answer, as it turned out, was no.
Now turn to the FY2026 subsidiary schedule. CLX Europe S.p.A. reported turnover of ₹2,410.09 million for the year — roughly €22 million, meaning the top line is essentially where it was at acquisition, in nominal terms, after eleven years inside eClerx. Profit before tax was ₹58.71 million. Tax was ₹52.04 million. Profit after tax: ₹6.67 million.18 The entity's reserves and surplus stood at negative ₹376.64 million — accumulated losses.18 Two associated entities did modestly better, with CLX's German subsidiary contributing ₹326.30 million of revenue and ₹17.44 million of profit, and a 49%-held Thai company adding ₹449.94 million of revenue and ₹5.05 million of profit.18
Put plainly: the acquisition that was supposed to move eClerx up the value chain has, on the most recent full year of disclosure, generated a net margin near zero in its principal operating entity, while the group as a whole earned a 17% net margin.
The vertical it feeds tells the same story from the other direction. Fashion, Luxury and Retail contributed 8.2% of group revenue in the June 2026 quarter, down from 10.3% two years earlier.8 On the August 2026 call, CFO Srinivasan Nadadhur guided the full-year outlook for the CLX business at "probably around 0% to 2%," adding only that "we should be able to do a little better this year."19 Management has been consistent about the cause — a genuine multi-year downturn in high-end fashion, which is real and not eClerx's fault. Kapil Jain told analysts in October 2025 that luxury was the one segment he was watching closely and that clients believed the industry was near a bottom.9 A year later, that recovery had still not clearly arrived.
There is also a disclosure pattern worth naming. CLX is not reported as a standalone segment with its own growth and margin. It is visible only through the subsidiary schedule in the annual report and through a blended "Fashion & Luxury and Retail" vertical percentage. An investor who wanted to test the 2015 deal thesis directly has to reconstruct it from AOC-1 filings. That is legal and common, but it is not the same as accountability.
The calibrated conclusion: CLX has not been a write-off, and it did buy eClerx a European client roster and a creative capability it now packages as an AI-enabled platform. But it has not delivered the value-chain elevation it was bought for, and on the evidence of eleven years, the version of the claim that survives is much smaller than the one that was sold — a modest, low-margin European appendage whose principal current use is as a distribution channel for other eClerx services rather than as a profit engine in its own right.
Personiv, 2020: the one that worked
On December 24, 2020, eClerx announced it had acquired Eclipse Global Holdings LLC, trading as Personiv — an Austin, Texas-headquartered outsourcing business with more than 35 years of history in outsourced accounting, customer experience and back-office services across the US, India and the Philippines. The deal added over 2,000 employees and three delivery centres, and was funded entirely with cash on hand.20 Enterprise value was reported at approximately $34 million with earn-outs tied to two calendar years of revenue and profitability targets.21 It closed on December 23, 2020.18
At its 2026 investor day, eClerx claimed the acquisition "has been successful," citing a doubling of revenue run rate, a 60% increase in employee count, and cross-sell of customer experience, client life cycle and digital services out of Manila and Coimbatore.1
Unusually for a management self-assessment, the subsidiary accounts broadly support it. eClerx Philippines Inc., the largest Personiv-lineage entity, reported FY2026 turnover of ₹2,833.26 million and profit after tax of ₹260.14 million — a 9.2% net margin, below group level but respectable for a delivery entity. AG Resources (India) added ₹416.35 million of revenue and ₹68.53 million of profit.18 The finance-and-accounting capability Personiv brought has been the single fastest-growing part of eClerx: the Emerging vertical went from 4.7% of revenue in the June 2025 quarter to 11.7% in the June 2026 quarter, and management has attributed that repeatedly, on four consecutive calls, to F&A wins.819
The group also simplified the structure during FY2026, merging ASEC Group LLC into Personiv Eclipse Inc. effective October 1, 2025, and Eclipse Global Holdings into the same entity effective November 3, 2025.18 Tidying up acquisition vehicles five years after the fact is a small but genuine sign of administrative discipline.
What the pattern actually says
Three deals, none transformative, none funded with meaningful debt, none requiring equity issuance. Total disclosed consideration across fourteen years is under €25 million plus roughly $34 million plus an undisclosed Agilyst price — against a company that now generates over ₹750 crore of annual free cash flow.22
Is that capital discipline or an absence of ambition? The honest answer is that it has been both, and which one it was depended on the decade. Through the FY2016-FY2021 stagnation, small bolt-ons were the right posture for a company that had not proven it could grow. But the pattern also has a cost that management named itself. Asked in October 2025 what shape future M&A would take, Kapil Jain described a target profile — a capability eClerx is strong in, taken into a vertical where it has white space, or vice versa — that is by construction another bolt-on: "it needs to strengthen our capability and ideally in an industry segment where we are not present."9
That is where the arithmetic gets uncomfortable. Moving from a $500 million run rate to $1 billion requires either sustained mid-to-high-teens organic growth for roughly five years — which the company has delivered for three and never for five — or a change in M&A appetite that has no precedent in its history. Management has not said which. Until it does, the $1 billion slide is an aspiration with no stated mechanism, and the fair way to hold it is as a statement of ambition rather than a plan.
The core business, meanwhile, has been doing something rather more interesting than any of the acquisitions.
IV. The Core Engine: Analytics, Automation and Process Management
Four months after eClerx opened a delivery centre in Cairo, the operation was already in the top quartile of performance among the vendors it competes with for the same services at the same clients. Kapil Jain mentioned it three times on the October 2025 call, once unprompted and twice in answer to entirely different questions.9
The repetition was not vanity. It was the CEO making the one argument he thinks actually holds: that eClerx's edge is not a technology or a patent or a price point, but the ability to take a complex, high-consequence process and get it running at standard in a new location with new people faster than anyone else. If that is true, it is a real thing. If it is not, this is a labour-arbitrage business with a good sales story.
Let us test it properly.
Where eClerx sits in the food chain
The industry structure is stark. Genpact — the original General Electric captive, spun out and listed — reported net revenues of $5.08 billion for 2025, up 6.6%, with its "Data-Tech-AI" line at $2.44 billion, or 48% of the total, and an adjusted operating margin of 17.5%.5 EXL reported $2.09 billion for 2025, up 13.6%, and by July 2026 had raised its full-year 2026 guidance to $2.39-2.415 billion, implying 14-16% growth.6 WNS, the third historical comparable, was absorbed into Capgemini for $3.3 billion at $76.50 per share.7
eClerx, at $468.9 million of FY2026 operating revenue, is the smallest independent name in its own peer set by a wide margin.4
Two things follow. First, eClerx has no scale economies in the Hamilton Helmer sense — it cannot outspend anyone on sales, on AI research, or on the enterprise-wide platform investments that Capgemini can now fund out of a €22 billion revenue base. Second, and more subtly, the WNS transaction changed the competitive question from "can eClerx win against WNS" to "does a sub-$500 million independent specialist have a reason to exist once the platforms bulk up." That is a strategic question, not a quarterly one, and it cuts in both directions: it raises the risk of standalone irrelevance and simultaneously makes eClerx one of a shrinking number of scaled, profitable, clean-balance-sheet assets in the category.
How eClerx says it wins, and what the data supports
The company's own answer is vertical depth over horizontal scale. The investor day framed it as an asset built out of three ingredients: proprietary data, codified operating knowledge, and domain judgment — summarised in the deck's own phrase, "two decades of encoded 'how this actually gets done.'"1
The affirmative evidence is real and worth taking seriously. eClerx serves 8 of the world's 10 Tier-1 banks, 4 of the top fashion and luxury brands, 8 of the largest manufacturing and distribution organisations, 3 of the world's top PC makers and 4 Tier-1 cable providers. It has relationships of more than ten years with 20 of its million-dollar-plus clients. Half of group revenue comes from Fortune 100 companies and 70% from the Fortune 500.1 Those are not the client rosters of a vendor that is easily swapped out.
The client-count progression is the strongest single data series. In FY2016 eClerx had 23 clients generating more than $1 million a year and 7 generating more than $5 million. By FY2021 that was 33 and 7 — the million-dollar count grew, the five-million-dollar count did not move at all in five years. By FY2026 it was 51 and 16.1 That inflection, from a decade of stalled account deepening to genuine mining of existing relationships, is the most concrete evidence that something changed under the current management regime.
Now the counter-evidence, which belongs in the same breath.
The first is concentration, already introduced, and it has not resolved. It sat at 62-64% through FY2025, reached 59% in the March 2026 quarter, and rebounded to 60% by June.8 The chairman's FY2026 letter cited a full-year top-ten share of 61%, moderating from 64%.22 The direction is right; the pace is glacial. A company that gets three-fifths of revenue from ten buyers, each of them a Fortune 500 with a procurement function, does not have pricing power in any meaningful sense. It has renewal risk.
The second is roll-off, and it is the least-discussed number in this story. Asked in August 2026 whether roll-off trends had changed, the CFO said that over a four-quarter window it "is generally between 15% and 20% of revenues for the year," and that he expected that to hold.19 Read that again. Between a sixth and a fifth of eClerx's revenue base disappears every year as projects end, scopes complete and clients insource. To grow 15%, the company must win roughly 30-35% of its revenue base in new work annually. That is why the annual contract value figure — $82.4 million in FY2023, rising to $91.0 million, then $137.4 million, then $169.9 million in FY2026 — is arguably the truest measure of the business.8
It also reframes the switching-cost argument. eClerx is sticky within a workflow. It is not sticky at the client level in the way a software vendor is, because the unit of stickiness is the individual process, and processes end.
The economics, and what they actually prove
eClerx earned a 27% EBITDA margin in FY2026, at the upper end of its guided 24-28% band, with net profit up 30.5% and return on equity of 27% per the chairman's letter.22 Free cash flow was ₹7,543 million against net operating cash flow of ₹8,735 million, with EBITDA-to-cash conversion around 76%, the best in five years.22 The balance sheet carries no debt.
The peer comparison in the investor day deck is more informative than any absolute figure. Over FY2017-FY2021 — the stagnant years — eClerx averaged a 19% net margin against 11% for peers, on a 21% return on equity against 19%. Over FY2022-FY2026, eClerx averaged 17% against 12%, on a 26% return on equity against 21%.1 Two conclusions follow. eClerx has consistently earned better returns than its peer set, including through a period when it barely grew, which is genuine evidence of a structural cost or mix advantage rather than a cyclical one. But the net margin premium narrowed, from eight points to five, even as growth accelerated. Something in the mix is diluting profitability as the company scales.
That something is visible in the geography. eClerx opened Lima in October 2024 and Cairo in February 2025, expanded Manila, and started operations in Coimbatore during FY2027.1819 The CFO was direct about the consequence: "these locations operate at a lower gross margin than India, and the change in revenue mix will have some downside on margin."19 The subsidiary accounts show the cost of the build phase — eClerx Egypt lost ₹100.65 million in FY2026 and eClerx Peru SAC lost ₹70.86 million.18
The June 2026 quarter is where this became visible in the group numbers. Operating EBITDA margin fell 264 basis points sequentially to 23.0% — below the bottom of the guided band — while profit after tax grew 16.0% against revenue growth of 23.3%.28 Management attributed 210 of those basis points to annual wage increments effective April 1 and 40 to computer and network infrastructure spending, and reaffirmed the 24-28% full-year range.19 But when an analyst pressed on where within the range, the CFO gave a notably specific steer: "the midpoint is what you should pick because higher than that is going to be a little bit difficult."19 That is management telling investors, in advance, that FY2026's 27% was a high-water mark helped by currency, and not to extrapolate it.
Utilisation offers a further ceiling. Asked why eClerx runs at around 75% when IT services companies run at 80-85%, the CFO rejected the comparison outright: in operations, a bench is structurally necessary, and over 12-15 quarters the company has operated in a 73-78% range.9 There is, in other words, no large hidden margin lever sitting in utilisation.
The five forces, applied concretely
Buyer power is high and it is the defining feature of the business. Ten Fortune 500 procurement organisations control 60% of revenue, and the annual roll-off cycle gives them a scheduled, recurring opportunity to renegotiate. Kapil Jain acknowledged pricing pressure in August 2026 — "yes, there are pressures that we are seeing, but nothing untoward" — while arguing that total cost of ownership, not headline price, drives the decision.19 That is a reasonable defence, and it is also exactly what an incumbent says before a repricing.
Supplier power is low. The input is Indian, Filipino, Egyptian and Peruvian graduate labour. Attrition ran at 21% in the June 2026 quarter, roughly flat sequentially and below historical levels.19 Wage inflation is real but industry-wide and passed through in pricing over time.
Threat of new entrants is moderate. Domain expertise in trade lifecycle operations or financial crime compliance takes years to build and cannot be bought off a shelf. But it is not patented, not regulated, and not exclusive. A determined competitor with capital and patience can replicate it, which is precisely what the larger platforms are now attempting with AI-enabled offerings.
Rivalry is intensifying and consolidating. Sandeep Shah of Equirus put the sharpest version of this to management in August 2026: Accenture had signalled it wanted to move into small and medium deals, the exact segment where a $500 million specialist lives.19
Substitution is the force that matters, and it gets its own section.
The net assessment: eClerx has what Helmer would call process power — an advantage embedded in how work gets done, built slowly, hard to copy quickly, and invisible on a balance sheet. That is a real power and the margin record supports it. It is also, of the seven, the one most vulnerable to a technology shift that changes what "the work" is.
Which is a question about people as much as technology, and eClerx changed the people at the top three years ago.
V. Leadership Transition: From Founder-Operators to Professional CEO
On the evening of May 26, 2023, four men joined an earnings call: the two co-founders, the chief financial officer, and a man who had been in the building for three weeks.
Srinivasan Nadadhur delivered the FY2023 results — $332.7 million of revenue, up 17%, net profit of ₹4,888 million, also up 17% — and then, almost as an afterthought at the end of prepared remarks, announced that Kapil Jain had been appointed Managing Director and Group CEO, describing him as "an Infosys veteran" with two decades of experience scaling businesses.23
An analyst named Hitesh Arora asked the question everyone wanted answered: was this a UK role, or the whole thing?
PD Mundhra took it himself. "Kapil is Group CEO for the entire Group," he said, adding that Jain had also been appointed Managing Director of the listed Indian entity, subject to shareholder approval, and that he was based in London because that is where he lives.23
Later in the same call, Shradha Agrawal of AMSEC asked the founders directly what would be left for them. Anjan Malik answered first, and the phrasing was careful: "over the next few months, what PD and I are doing, I think we're taking on a broader strategy role."23 Mundhra was blunter when Sandeep Shah returned to it: "He will own executive and operational responsibilities for the Group. And our role will become, I would say, more involved in strategy setting and more involved at the Board level. So yes, there will be a change. It will take a few months to accomplish, but there will be a change."23
It is the single most consequential governance event in eClerx's history, and it was handled with unusual clarity.
Who Kapil Jain is
Jain had spent 22 to 23 years at Infosys, most recently as Executive Vice President and Global Head of Sales and Enterprise Capability for its business process management arm, with a background spanning delivery, sales, transitions, marketing, alliances and M&A. He was appointed CEO of eClerx Limited, the UK subsidiary, effective May 1, 2023, and joined the board of the listed Indian company on May 25, 2023.2425
Asked on that first call what had attracted him, his answer was revealing about how he read the asset. He said clients described eClerx as a company where "a lot of the revenue comes through referenceability" — and then made a striking admission for a man who had spent two decades at India's most famous IT services firm: "in the last 22, 23 years that I had spent with Infosys, I have not come across eClerx because I think it's a very differentiated set of offerings and space eClerx operates in."23
That is a useful data point about the moat and a warning at the same time. eClerx was so specialised that a senior executive at a company thirty times its size had never competed with it. That is protection from a giant — and also a description of a very small pond.
His operating style, three years of transcripts later, is consistent: heavy on process discipline (a "One eClerx" cross-sell architecture, a dedicated large-deals team, unified pre-sales and deal governance), heavy on external validation (analyst-relations investment, Everest Group and Gartner and Chartis rankings cited in almost every opening statement), and notably unwilling to give a revenue number. His stated target is to be "in the top quartile of the segment that we operate in, in terms of growth."9
That target deserves a hard look, because it is close to unfalsifiable. When an investor asked in August 2026 what top-quartile growth actually was for the June quarter, the CFO's answer was to suggest the questioner look at "the top 20-odd companies that are listed in India with a similar market cap" and work it out, noting some had not reported yet — after which Jain said, "We think even in Q1, we have delivered top-quartile growth."19 A target defined against an unnamed peer set, assessed by management after the fact, is not guidance. It is a posture. Investors should treat it as such.
The credibility ledger
Against that, the record on the things that are checkable is better than most.
The 24-28% EBITDA band has been reaffirmed across every quarter since it was introduced, including in quarters when the actual number was above it and quarters when it was below.92619 Management has not moved the goalposts after a miss.
On the January 2026 call, management warned that seasonality was inherent to the business and "may result in Q4 being softer than the first 3 quarters."27 The March quarter then delivered 0.6% sequential dollar growth, and when asked in May whether it had been a surprise, Jain said it was in line with what had been communicated in advance.26 Pre-announcing a weak quarter and then delivering exactly the weak quarter you pre-announced is a small thing that tells you a lot.
And on the largest open problem, management states the shortfall in its own words rather than reframing it — the concentration line quoted earlier, and Jain's explicit acknowledgement in August 2026 that the top five accounts had been soft partly because "the overall regulatory environment for financial services in the U.S. is slightly less onerous than it used to be, let's say, two or three years back."19 That is an unflattering admission: a meaningful part of eClerx's largest vertical is levered to the intensity of American financial regulation, and that intensity has eased.
The offsetting concern is that BFSI has now been flat-to-negative for three consecutive quarters — down 2.8% sequentially in March, down 0.1% in June, with the vertical's share of revenue falling from 43.3% in FY2025 to 37.6% by June 2026.819 Girish Pai of BOB Capital put the challenge directly on the August call: peers large and small were reporting strong BFSI growth while eClerx was not.19 Jain's answer — that the gradient was improving and the turn would come "from H2FY27 onwards" — is a specific, dated, falsifiable commitment. It is the single clearest test of this management team's forecasting credibility available in the next two quarters.
Ownership, incentives, and who is paid by whom
The promoter group's behaviour is genuinely unusual and, read carefully, tells a different story than the summary version.
At the time of the December 2022 buyback, promoters held 53.38%. The public announcement disclosed that all promoters and promoter group members except Pawan Malik, Vijay Kumar Mundhra and Shweta Mundhra had expressed their intent to participate and tender up to their full entitlement — meaning the two founders themselves tendered.28 By March 31, 2025, promoter holding was 53.81%. By March 31, 2026, it was 54.53%, with PD Mundhra at 27.21% and Anjan Malik at 27.20%.14
The step-up came because in the buyback announced in October 2025 — 625,000 shares at ₹4,800, for ₹300 crore, later completed with a settlement date of January 2, 2026 — the promoters and promoter group did not participate at all.192914 Public shareholders tendered, promoters did not, and the promoter stake mechanically rose.
What does that mean? Less than a bullish reading would like. The honest answer is that it is consistent with confidence in the current trajectory and equally consistent with tax and liquidity planning by founders who no longer need cash. The company has not explained it. What can be said without over-reading is narrower and still useful: two founders 26 years past founding, who have handed operational control to an outsider, have not used a liquidity event to reduce their exposure — and in 2022, under the prior structure, they did.
The capital return machine, and its limits
eClerx has bought back stock in five of the last six fiscal years: 2,093,815 shares in FY2021, 1,063,157 in FY2022, 1,714,285 in FY2023, 1,375,000 in FY2025 and 625,000 in FY2026.14 The FY2025 tranche was priced at ₹2,800 for approximately ₹385 crore.30 The FY2026 buyback price was raised from an announced floor of ₹4,500 to ₹4,800 in December 2025.31 There have also been two 1:1 bonus issues, in FY2023 and FY2026.14
The CFO's stated policy is to return roughly 50% of cash to shareholders over any 12-18 month window if it is not required by the business, and his defence of buybacks over dividends is thoughtful: a buyback gives the individual investor a choice about whether to participate, allows capital-loss set-off, and improves earnings per share.9 Meanwhile the dividend has been ₹1 per share every single year from FY2019 through FY2026 — under 1.2% of profit after tax in every one of those years.22 The dividend is a formality; the buyback is the entire return.
Here is the tension an activist would press. The company's own investor day disclosed that shareholder return as a percentage of net profit fell from 65% in FY2017-FY2021 to 49% in FY2022-FY2026.1 So in the period of stronger profits, eClerx returned a smaller share of them — while cash and equivalents built to ₹12,589 million by June 2026.8 The CFO's explanation is mechanical and legitimate: buyback capacity is constrained by the standalone entity's cash and net worth under Indian regulations.9 But the effect is a growing cash pile at a company with no announced use for it and a $1 billion aspiration with no stated funding mechanism.
Two more items belong in the governance file, stated as facts rather than accusations. First, Kapil Jain receives no remuneration from the listed Indian company; he was paid ₹256.90 million in FY2026 by eClerx Limited, the UK subsidiary, on a basic salary of £750,000 plus a board-approved FY2026 performance bonus of £946,500, with transfer-pricing arrangements between the entities.14 Because of this structure, he is excluded from the listed company's director-to-median-employee remuneration ratio, which is disclosed as 39 times for the executive director — a figure that therefore reflects PD Mundhra's ₹16.64 million salary, not the CEO's pay, which is roughly fifteen times larger.14 Second, Anjan Malik received no remuneration from the parent but was paid ₹18.47 million during FY2026 by CLX Thai Limited, a 49%-held subsidiary.14 None of this is improper and all of it is disclosed. But an investor comparing eClerx's headline pay ratios to peers without reading the footnotes would materially understate what the top of this house costs.
The board itself is conventionally structured: six non-executive independent directors, an independent chairperson in Shailesh Kekre, and attendance of 100% at all five FY2026 board meetings for every director except one, at 80%.14 Contingent liabilities are small and bounded — ₹268.49 million of income tax demands spanning assessment years 2011-12 through 2021-22, plus ₹55.02 million of indirect tax demands, all under appeal.18 There is no material litigation disclosed in the FY2026 accounts.
The one accounting judgment worth flagging is goodwill. The consolidated balance sheet carried ₹4,492.94 million of goodwill at March 31, 2026 — 12.15% of total group assets — arising from the foreign acquisitions. The statutory auditors designated its impairment assessment a key audit matter, noting that management allocated it to a cash-generating unit and tested it using a discounted cash flow model with an independent valuation expert, concluding no impairment was necessary.18 Given what the CLX subsidiary accounts show, the assumptions inside that DCF are worth watching in future annual reports.
All of which sets up the question that decides whether any of this compounds from here.
VI. The AI Question: Opportunity, Threat, or Both — Tested Against Management's Own Numbers
On the May 2026 earnings call, an analyst asked a question that management could have answered in any number of comfortable ways, and Kapil Jain instead answered it honestly.
Sandeep Shah had noticed something in the prepared remarks: eClerx had won its first large-scale agentic AI deal in the fourth quarter of FY2026. "You believe revenue ramp-up may start from Q4 FY '27," he said. "Is it the right way of looking at it?"
Jain: "I think that is the right way."26
Hold onto that exchange, because everything else in this section has to be weighed against it.
First, what these words actually mean
"Generative AI" is a system that produces new content — a paragraph, an image, a summary — by predicting what should come next based on patterns learned from enormous quantities of text. It is a very good junior analyst who has read everything and understood some of it.
"Agentic AI" is the step beyond. Instead of producing an answer for a human to act on, an agent is given a goal, a set of tools, and permission to take actions in sequence: look up the record, compare it against the policy, flag the mismatch, draft the correction, route it for approval. Think of generative AI as an assistant who writes you a memo, and agentic AI as an assistant who goes and does the errands the memo describes.
Now recall what eClerx sells. Trade exceptions. KYC refreshes. Reconciliations. Invoice-to-cash. Order management. Every single one of those is a bounded, rules-and-judgment workflow with a defined goal, a set of systems to touch, and a decision at the end. If you were designing a demonstration of what agentic AI is for, you would design something that looks very much like eClerx's revenue base.
That is the bear case in one paragraph, and it is not hypothetical.
The affirmative evidence, taken at its proper weight
eClerx has moved earlier and harder on this than most Indian mid-caps.
On February 5, 2025, the company announced ISO/IEC 42001:2023 certification for AI management systems, awarded by Intertek, describing itself as among the first five companies globally to achieve it.32 It has built proprietary products: Compliance Manager for KYC and client life cycle management, Market360 for market intelligence, QA360 for quality assurance, FLUiiD4 for marketing communications and digital asset management, and DocIntel for document processing.1 It launched an agentic data-sourcing platform and put an AI-native orchestrator for KYC case management live across multiple client systems.26 Internally, roughly 8,000 employees have been trained on generative AI in partnership with the Technical University of Munich, against a stated ambition of 10,000, and more than 3,000 have been trained specifically on agentic AI and "vibe coding."2226 In May 2026 the company consolidated its AI efforts under a single organisation led by John Flowers, previously head of BFSI, working with CTO Dr. Sanjay Kukreja.33
Certification is not commercialisation, and a Forrester mention is not a purchase order. These items matter as credibility signals inside an RFP — a bank's procurement and risk functions genuinely do ask whether a vendor has an AI governance framework — but none of them is revenue, and the honest way to weigh them is as reduced friction in sales conversations rather than as evidence of a monetised pivot.
The revenue evidence, which is what matters, sits in one line: Analytics and Automation. Management describes it as the surrogate for the technology-led part of the business. It reached a $90 million book in FY2026 and crossed a $100 million annualised run rate in the June 2026 quarter, at which point it represented roughly 20% of firm revenue and was growing at 7% sequentially, well ahead of the company average.119
That is genuinely material. It is not a pilot. A fifth of revenue in technology-led services, growing faster than the base, is the strongest single argument for the opportunity case.
But the series has a hole in it, and the investor day deck published it: Analytics and Automation revenue was $65.3 million in FY2023, then fell to $61.9 million in FY2024, before recovering to $73.2 million in FY2025 and $89.5 million in FY2026.1 A 5% decline in the productised, technology-led line in FY2024 — the first full year under the new CEO — is a reminder that this book is not a smooth compounding annuity. It is project-shaped, and projects roll off.
The disconfirming evidence, in management's own words
Now put the pieces of the agentic story together in the order management delivered them.
The first large-scale agentic AI win came in the fourth quarter of FY2026, in the hi-tech, manufacturing and retail cluster, with deployments planned from the first quarter of FY2027 onward.26 The commercial structure is not outcome-linked; Jain was explicit that "for this Agentic AI deployment, that specific project that I called out, it is not linked to outcome or positive or negative influence."26 And the revenue ramp, per the exchange that opened this section, is expected to begin in the fourth quarter of FY2027 — roughly two years after the deal was won.26
Three months later, asked whether the technology-led share could go from 15-20% of revenue to 25-30% within twelve to eighteen months, Jain declined to forecast it and offered instead the most useful sentence any executive has said about AI economics in this sector: "the deal sizes in AI are relatively small. You see what I'm saying. So, what is happening is that it's like icing on the cake."19
And on the industry as a whole, describing why clients are outsourcing more rather than less: "clients are investing a massive amount of money that's going in AI. And there is a lag between when the investments are happening and when the benefits will start showing up the ROI. And the investors, the CFOs, are asking where is the ROI?" His conclusion was unusually candid for a vendor selling into that spend: "the ROI is still yet to be seen. So, there's a lot of promise in terms of commitments that are being given."19
Weighing it
Set the claim against the evidence and the verdict is narrower than either the bull or bear caricature.
The claim "AI is an opportunity for eClerx, not a threat" is not rejected, but it is materially narrowed. What the evidence supports is that eClerx has converted AI into a real, growing, technology-led services line worth about a fifth of revenue, whose content is largely data preparation, exploratory analysis, document digitisation, KYC screening and workflow automation — the plumbing that clients need before they can deploy agents. Jain described exactly this in August 2026: strong demand for "data preparation and exploratory data analysis, which is the foundation for implementing AI," and "these are often the first steps before clients move to larger agentic AI programs."19
What the evidence does not support is the stronger claim that eClerx has a scaled, differentiated agentic business today. Management itself has bounded that claim in three separate ways: the flagship deal will not ramp until Q4 FY2027, AI deal sizes are small, and client ROI on AI has not yet been demonstrated. Any investor who hears "AI-powered analytics" in the corporate boilerplate2 and infers a monetised transformation is running ahead of what the company is saying about itself.
The bear mechanism is specific and testable, and it runs through the roll-off number established earlier. eClerx does not need to lose a client to be disrupted. It needs its clients, or its clients' other vendors, to automate faster than eClerx can re-win the work — and 15-20% of the revenue base comes up for that test every year. Every renewal is now a conversation in which the client's own AI investment is a bargaining chip. Jain has said he will not resist it: asked why the top five accounts were soft, he said that if clients are implementing technology and AI, "we are not going to shy away from it."19 That is the right posture and it is also an acknowledgement that the cannibalisation is already inside the largest accounts.
Scale is the aggravating factor. Capgemini can fund an agentic operations platform across a 350,000-person base and amortise it over thousands of clients. Genpact is deploying against a $2.44 billion Data-Tech-AI book. eClerx is investing roughly 1% of revenue in strengthening capabilities including AI, 1% in sales, and 1.5% in geographic expansion.1 That is disciplined relative to its size. It is also, in absolute rupees, a rounding error against what the platforms are spending.
The falsification test is clean and it arrives on a known schedule. If the Analytics and Automation run rate keeps compounding through FY2027 and the Q4 FY2027 agentic ramp lands and total annual contract value exceeds the $169.9 million booked in FY2026, then the opportunity case is confirmed and the disruption case weakens. If the technology line stalls the way it did in FY2024, or the agentic ramp slips, while the traditional base faces renewal pressure, then the mechanism described above starts showing up as decelerating organic growth. The company has told investors when to check. There is no ambiguity about the date.
One further observation on sell-side sentiment, stated with the confidence the evidence supports: the analysts who cover this stock have been pressing on precisely these points on the calls — Kotak Securities' Vamshi Krishna asked directly in October 2025 whether eClerx's strong communications, media and telecom performance was at risk from AI adoption in those services, and in August 2026 pushed on the margin trajectory given the geographic mix shift.919 The stock's position roughly a quarter below its 52-week high suggests the market has not fully resolved the question either.3
VII. Bull vs. Bear: The Investment Case, Stated Without Advocacy
Every investment case is a war game. So let us play both sides properly, with the pieces on the board rather than the adjectives.
The bull case, with the evidence attached
Leg one: the margin structure is genuinely superior and has survived a full cycle. The peer comparison holds across two five-year windows, including one in which eClerx barely grew, and it holds on both net margin and return on equity.1 That is not a cyclical artefact. The mechanism is mix — a portfolio weighted toward complex, high-consequence processes where the buyer's alternative is expensive onshore labour rather than a cheaper offshore vendor. In Helmer's vocabulary this is process power, and the accumulated operating knowledge behind it is the closest thing eClerx has to a cornered resource. The caveat established earlier stands: the premium has narrowed from eight points to five as the delivery footprint diversified into lower-margin geographies.
Leg two: account deepening has genuinely inflected. The five-million-dollar client count sat at 7 for the entire FY2016-FY2021 stretch and has since more than doubled to 16, while million-dollar clients went from 33 to 51.1 Cross-sell wins grew 2.5x, 82% of the top 50 clients deepened into new service areas, and large deals accelerated 2x per the company's own disclosure.1 The first cross-sell of customer experience services into a banking client, won in the June 2026 quarter for the Fayetteville centre, is a concrete instance of a capability crossing a vertical boundary.19 This is the most direct evidence that the current management regime changed something operational rather than merely narrative.
Leg three: the technology-led line is real and material. Discussed above; the honest framing is a fifth of revenue growing faster than the base, with the agentic layer still ahead.
Leg four: capital returns are consistent, non-dilutive and shareholder-aligned. Five buybacks in six years, no equity issuance, no debt, and founders who chose not to reduce their stake into the most recent one. Free cash flow conversion at 76% of EBITDA.22
Leg five: management states problems out loud. Concentration, luxury weakness, BFSI softness, the regulatory tailwind that faded, the margin cap — all disclosed by management before analysts forced the issue. That is a genuine and undervalued asset in an Indian mid-cap.
The bear case, with the evidence attached
Leg one: concentration is structural, not transitional. Nine consecutive quarters of disclosure show a band of 59-64% with no durable break below.8 For a company of this size, the loss or repricing of a single top-five relationship is a material event. Kapil Jain identified this as the primary internal risk when asked in October 2025 what could break the growth journey.9
Leg two: the M&A record does not support the $1 billion ambition. Fourteen years, three bolt-ons, one clear success, one eleven-year disappointment now earning a near-zero net margin, one acquisition vehicle fully provided against. There is no evidence in the record that this team — or its predecessors — can integrate a scale-changing acquisition, and no disclosed plan for how the target is reached organically.
Leg three: AI risk sits closer to the core business definition than at any peer. The mechanism, timing and falsification test are set out above.
Leg four: consolidation has thinned the field of comparable independents. After the WNS transaction, eClerx is one of very few remaining scaled, independent, profitable specialists. That is optionality and vulnerability in the same fact: it makes the company a plausible target and simultaneously raises the question of whether standalone scale is sufficient for the next platform cycle.
Leg five: the reporting has soft edges an activist would probe. CEO compensation routed through a UK subsidiary and consequently excluded from the listed entity's remuneration ratio. A co-founder's fee paid by a 49%-held Thai subsidiary. A fully provided ₹605.67 million investment with no narrative explanation. ₹4,492.94 million of goodwill at 12.15% of assets, tested by DCF and flagged as a key audit matter, sitting partly against a business whose principal operating entity carries negative reserves. A growth target defined against an unnamed peer group and assessed retrospectively by management. And a payout ratio that fell as profits rose. Individually each is defensible. Collectively they describe a company that discloses what it must, clearly, and not much more.
The current risk radar, where it is material
The risks that actually transmit to this P&L are narrower than a generic list.
Currency is the largest short-term swing factor and it cuts both ways. Rupee depreciation contributed roughly 200 basis points of the margin expansion in the September 2025 quarter, and management flagged in advance that the following quarter would not repeat it.9 The hedge book stood at $273.6 million at an average of ₹93.41 to the dollar, all forwards, running out to the first quarter of FY2029 at rates rising to ₹100.85.8 Hedging smooths the P&L; it also caps the benefit of further depreciation.
Regulatory and political risk is specific rather than abstract. Management has been monitoring a proposed US rulemaking on offshore call restrictions and maintaining contingency dialogue with clients, though it reported no change in either direction as of August 2026.2619 Separately, the softening of US financial-services regulatory intensity has already shown up as reduced client-refresh volumes in the largest accounts.
Geopolitical and demand risk is running through manufacturing, distribution and retail, where management cited supply chain challenges from the prolonged Middle East conflict producing longer decision cycles and delayed discretionary projects.19
Execution risk in the geographic build-out is live and quantified: five new or expanded delivery locations, roughly 1,600 seats being added across Indian centres over three to four months, capital expenditure guided at ₹130-150 crore for the year, and two new-country subsidiaries still loss-making.1918
The one to two things worth tracking
Reduce all of the above and three metrics carry the case.
Top-ten client concentration. It is the single number that determines whether eClerx is a specialist with a diversified franchise or a supplier to ten companies. Management publishes it quarterly. A durable break below the mid-50s would validate the broadening thesis; a return toward the mid-60s would falsify it.
Annual contract value of new deal wins, read against the 15-20% roll-off. This is the true growth engine, because it measures whether the company is winning enough new work to replace what expires and still grow. Management has committed to exceeding the $169.9 million booked in FY2026.
Analytics and Automation revenue run rate as a share of the total. The cleanest available proxy for whether the technology-led pivot is compounding or stalling — and the FY2024 dip in that line is the reason to watch it every quarter rather than every year.
VIII. Durable Lessons for Builders and Investors
Strip away the tickers and there are four transferable ideas in this story.
Specialisation is a margin strategy, not a growth strategy, and the two are not the same thing. eClerx chose depth over breadth for 26 years and it shows up exactly where you would expect: in a persistent net margin and return-on-equity premium over a peer set that is five to ten times its size.1 It also shows up where a promotional telling would omit it — in the five years when depth did not produce growth at all. The lesson is not that specialisation fails. It is that a specialist's addressable market is bounded by definition, which means growth has to come from mining the accounts you have rather than from a rising tide, and that is a much harder operational discipline than it sounds. The client-count series is the receipt for whether a company has actually learned it.
The founder-to-professional-CEO handoff has a specific, replicable shape here. Hire an operator from a much larger peer rather than promoting internally — Jain came from a business process arm at a company thirty times eClerx's size, bringing a sales-and-governance machine the founders had never built. Keep the founders in the company but move them out of the operating line, into strategy and the board, rather than pushing them out entirely. Say so publicly, on a call, with a timeline, and let analysts ask uncomfortable questions about who does what. Three years later, the operational evidence — cross-sell architecture, large-deal team, analyst relations, an annual contract value figure that roughly doubled between FY2023 and FY20268 — suggests the structure worked. What it has not yet produced is a solution to the problem the founders left behind.
Buyback-plus-bonus-issue is the default Indian promoter-heavy capital return playbook, and it signals less than it appears to. A token dividend, a near-annual buyback, and periodic bonus issues that change nothing economically but broaden the shareholder base and reduce the headline share price. The mechanics are genuinely efficient for a company where founders own more than half the equity. But the signal content is limited: promoters tendering into one buyback and abstaining from the next, three years apart, with no disclosed reason, admits multiple readings, and the payout ratio falling as profits rose complicates any simple story about discipline. The general lesson is to read Indian capital return as an artefact of tax structure and regulatory constraint first, and as a confidence signal only second — and only when management explains the change.
Serial small bolt-on M&A is a discipline with a hard ceiling. eClerx never bet the company, never diluted shareholders, never levered up. Across three deals it also never re-platformed. Each acquisition bought a capability or a geography at the margin — media operations in 2012, creative content in 2015, finance and accounting in 2020 — and the strategic pivots that resulted took years to show up in the mix, when they showed up at all. That is a defensible way to run a business through a difficult decade. It is a much less obvious way to fund a doubling of revenue in an industry where a competitor just spent $3.3 billion in a single transaction to acquire a capability.7 Discipline and ambition are not opposites, but a company that has only ever demonstrated one owes its investors an explanation of how it intends to demonstrate the other.
IX. What to Watch Next
The useful thing about eClerx is that management has, mostly inadvertently, given investors a dated checklist. Five items, each with a specific window.
Whether BFSI turns in the second half of FY2027. Kapil Jain committed to it twice on the August 2026 call, with a named timeframe, after three quarters of flat-to-negative performance in a vertical that still represents 37.6% of revenue and was 43.3% a year and a half ago.198 This is the nearest-term, cleanest test of management's forecasting credibility. If the turn arrives on schedule, the softness was cyclical and regulatory. If it does not, the question shifts to whether the largest vertical is structurally losing volume to client automation.
Whether the agentic AI ramp lands in the fourth quarter of FY2027. Management named the quarter. The deal was won in the March 2026 quarter, deployments began in the June 2026 quarter, and the revenue is expected roughly a year out.26 Watch also whether the Analytics and Automation run rate keeps compounding past the $100 million mark and whether the QA360 engagement that went live in the September 2026 quarter, auditing about half a million client interactions a month, scales as described.119
Whether top-ten concentration breaks the band. Nine quarters of data show 59-64%. Sustained sub-55% would be genuine structural change. A drift back toward the mid-60s would confirm that the long tail grows faster in percentage terms without ever mattering in absolute terms.
Whether anything happens on M&A, and how it is financed. The $1 billion slide implies a mechanism that has not been disclosed. A larger, capability-focused acquisition — Jain has described the target profile without naming a size — funded from the growing cash pile would be the first real test of whether this team's capital allocation extends beyond bolt-ons and buybacks. Equally informative would be another year in which nothing happens and the cash simply accumulates.
Whether margins settle at the midpoint the CFO pointed to, and whether promoter behaviour repeats. FY2026's 27% was flattered by currency; the June 2026 quarter printed 23.0% and management guided investors toward the middle of the 24-28% band rather than the top.19 A full year at or near the midpoint would confirm that the geographic diversification carries a permanent margin cost, which is a fair trade for growth but should be priced as such. And when the next buyback comes, whether the promoters tender — as they did in 2022 — or abstain again, as they did in 2025, will be the cheapest available read on how two founders who no longer run the company assess the man who does.
References
-
Presentation for eClerx Investor Day 2026 — eClerx Services Limited (BSE/NSE filing), 2026-09-01 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
eClerx's Q1 FY27 revenue at INR 1,170.2 crore, up by 23.8% — eClerx Services Ltd press release, 2026-08-05 ↩↩↩↩
-
eClerx Services Limited (ECLERX.NS) real-time quote — Financial Modeling Prep, 2026-09-06 ↩↩
-
eClerx's FY26 revenue at INR 4,217.4 crore, up by 22.6% — eClerx Services Ltd press release, 2026-05-13 ↩↩
-
Genpact Reports Fourth Quarter and Full Year 2025 Results — PR Newswire, 2026-02-05 ↩↩
-
EXL Reports 2025 Fourth Quarter and Year-End Results; Issues 2026 Guidance — ExlService Holdings, 2026-02-24 ↩↩
-
Capgemini completes the acquisition of WNS and creates a global leader in Agentic AI-powered Intelligent Operations — Capgemini, 2025-10-17 ↩↩↩
-
eClerx Investor Presentation — Financial Performance Q1 FY27, 2026-08-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
eClerx Services Limited Q2 FY26 Earnings Conference Call transcript, 2025-10-27 ↩↩↩↩↩↩↩↩↩↩↩↩
-
eClerx IPO — Date, Price, Review, Analysis & Details — Chittorgarh ↩
-
eClerx's FY18 revenue stands at INR 1,404.9 crore and net profit down by 18% at INR 290 crore — eClerx Services Ltd earnings release, 2018-05-23 ↩↩↩
-
eClerx Services Limited Q4 FY21 Earnings Conference Call transcript, 2021-06-10 ↩
-
eClerx Services Limited: Announcement regarding acquisition of Agilyst Inc. by eClerx — MarketScreener, 2012-04-12 ↩↩↩
-
eClerx Acquires Mahesh-Founded Agilyst — SiliconIndia, 2012-04-16 ↩
-
Mumbai's eClerx buys Italy's global media content company CLX Europe — BeBeez International, 2015-04-07 ↩↩↩
-
eClerx Services Limited Annual Report 2025-26 — Form AOC-1, consolidated financial statements and auditors' report ↩↩↩↩↩↩↩↩↩↩↩
-
eClerx Services Limited Q1 FY27 Earnings Conference Call transcript, 2026-08-06 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Business Process Management Leader, eClerx, Acquires Texas-Based Personiv — PR Newswire, 2020-12-24 ↩
-
eClerx Services acquires Texas-based outsourcing firm Personiv — Business Standard, 2020-12-24 ↩
-
eClerx Services Limited Annual Report 2025-26 — Chairman's Message and Management Discussion & Analysis ↩↩↩↩↩↩↩
-
eClerx Services Limited Q4 FY23 Earnings Conference Call transcript, 2023-05-26 ↩↩↩↩↩
-
eClerx Limited Appoints Kapil Jain as CEO — PR Newswire, 2023-04-18 ↩
-
eClerx Marks 25 Years of Innovation, Growth, and Client Impact — BusinessWire, 2025-08-21 ↩
-
eClerx Services Limited Q4 FY26 Earnings Conference Call transcript, 2026-05-14 ↩↩↩↩↩↩↩↩↩↩
-
eClerx Services Limited Q3 FY26 Earnings Conference Call transcript, 2026-01-29 ↩
-
eClerx Services Limited — Buyback Public Announcement, December 2022 — SEBI ↩
-
eClerx Services Limited — Buyback Public Announcement, December 2025 — SEBI ↩
-
eClerx Services shares drop as IT firm announces share buyback, Q4 show — Business Standard, 2024-05-17 ↩
-
eClerx Services shares rise on increasing buyback price to Rs 4,800 — Business Standard, 2025-12-17 ↩
-
eClerx achieves ISO 42001:2023 Certification for Artificial Intelligence Management Systems (AIMS) — PR Newswire, 2025-02-05 ↩
-
eClerx Unifies AI Leadership to Deliver Outcome-Driven Results at Enterprise Scale — eClerx, 2026-05-20 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube