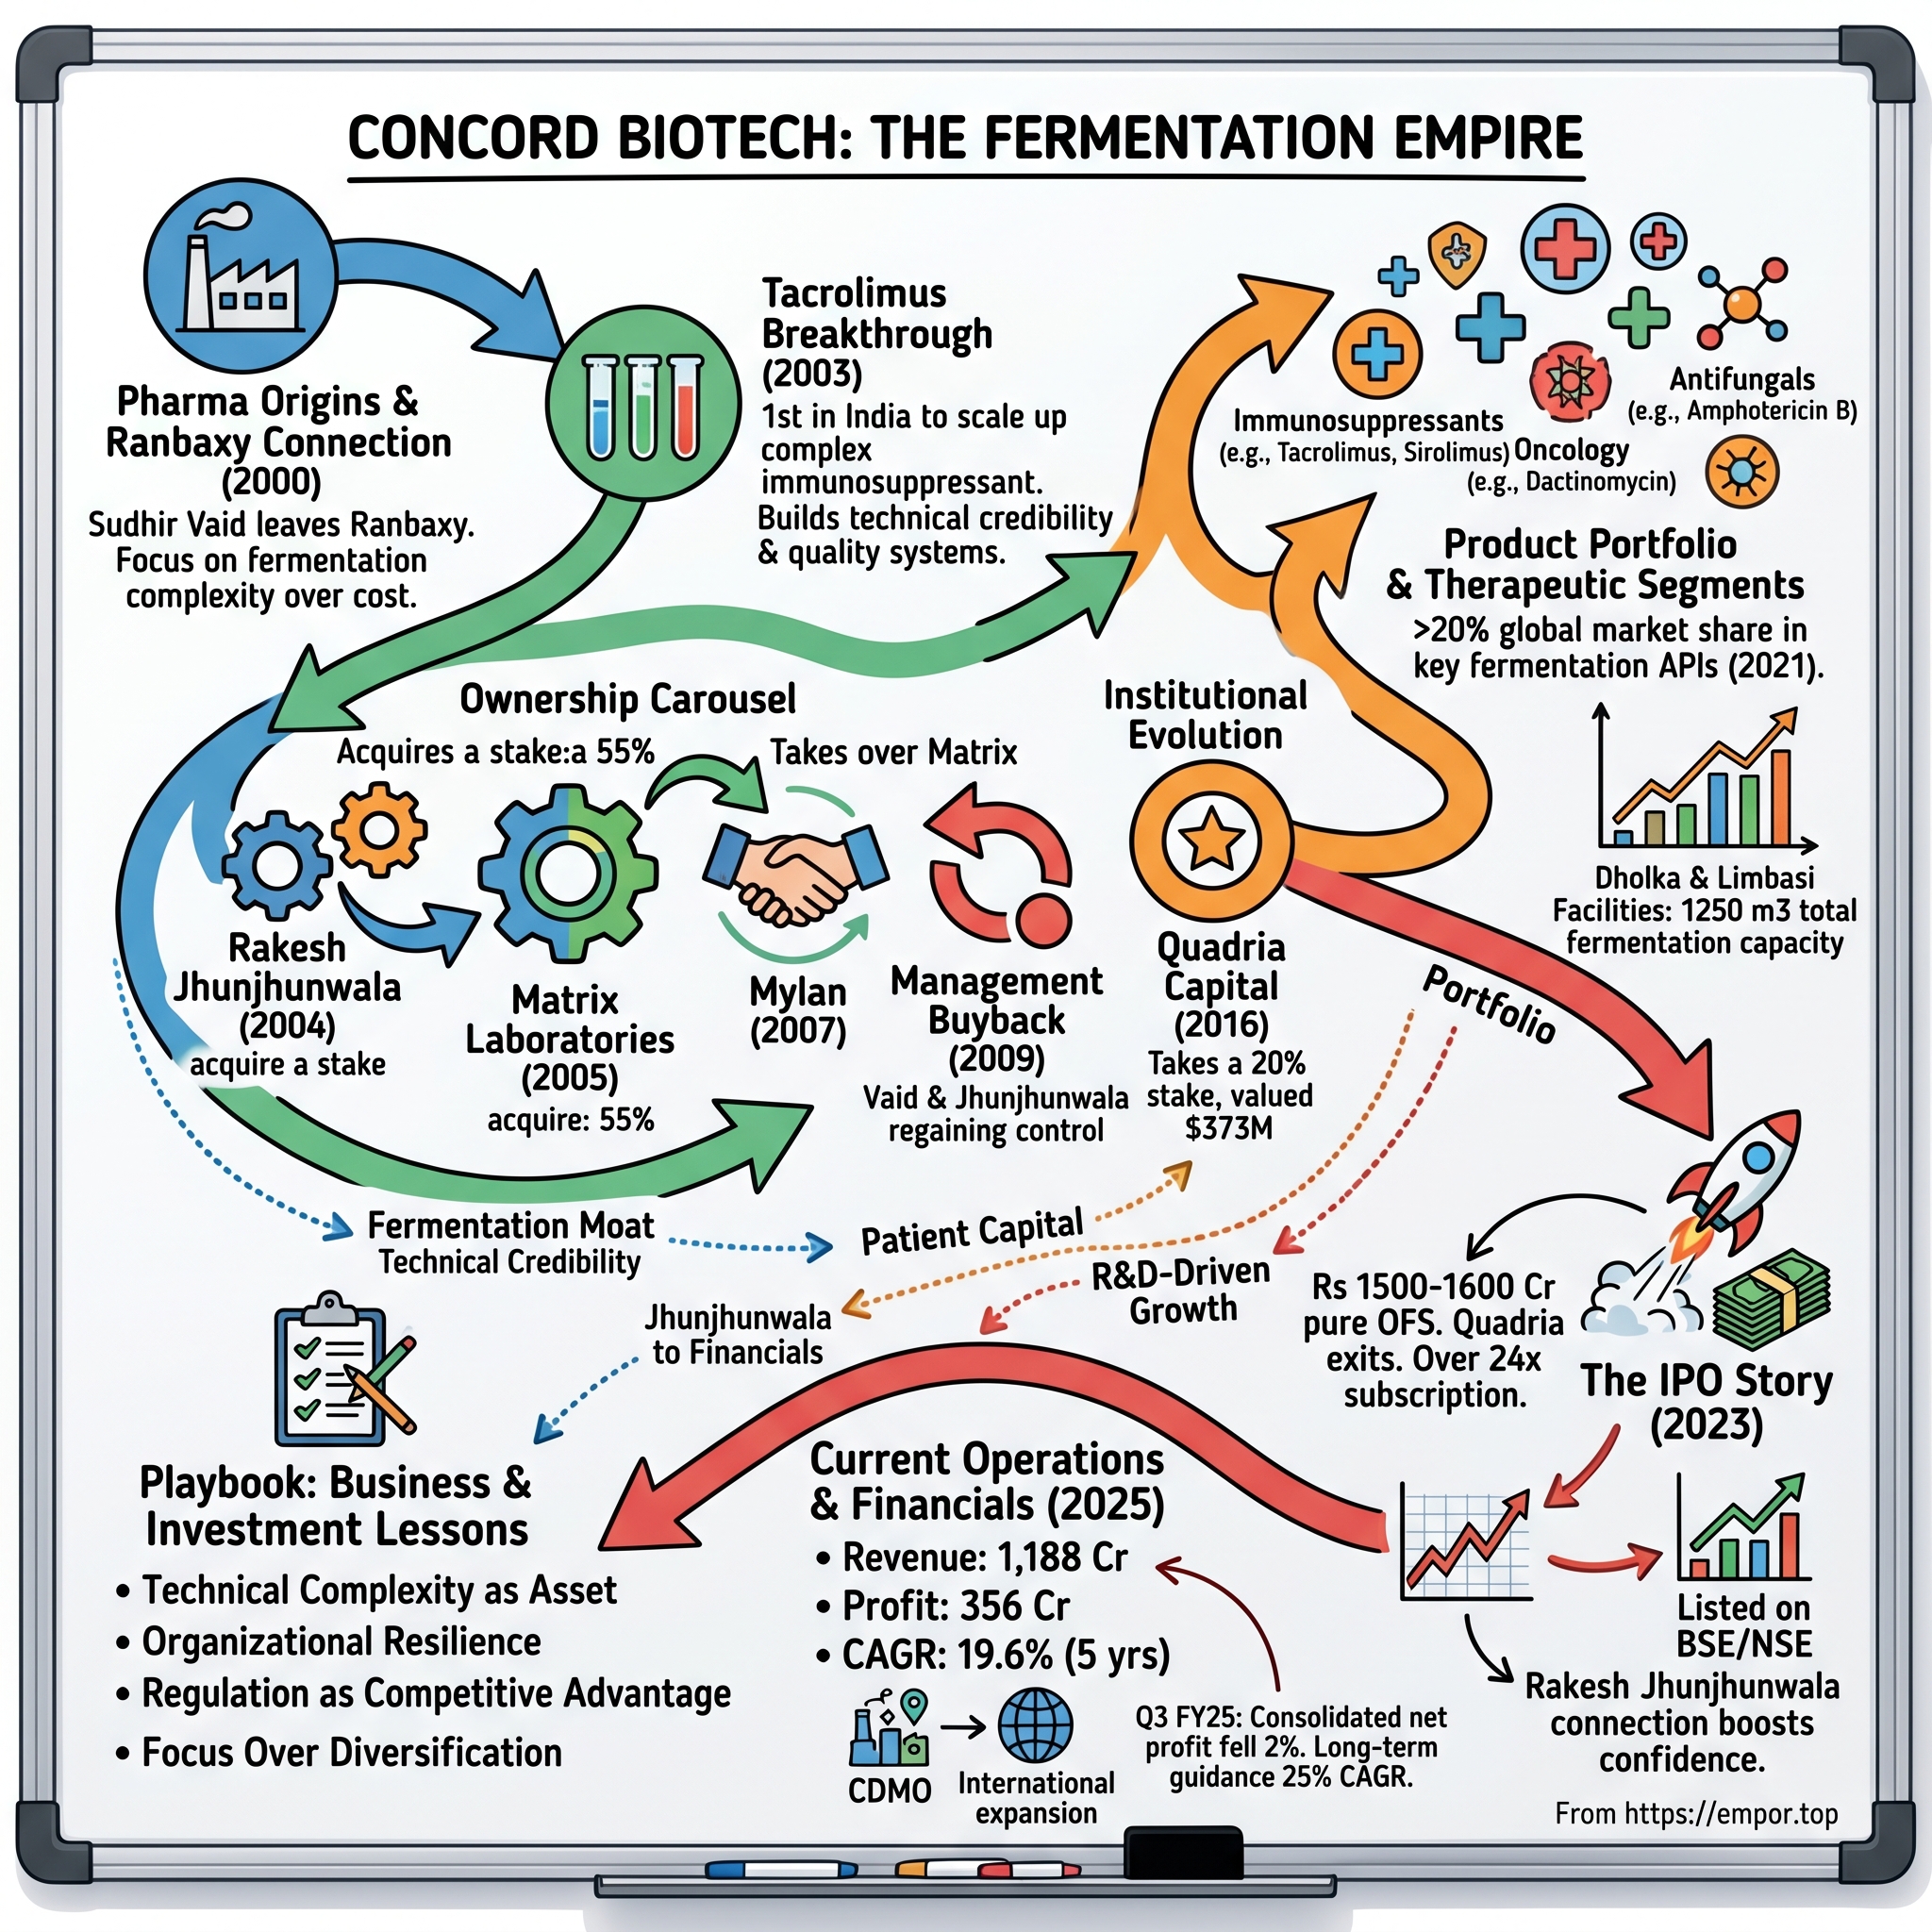
Concord Biotech: The Fermentation Empire
I. Introduction & Episode Roadmap
There is a room in Dholka, an hour's drive southwest of Ahmedabad, where the most valuable asset in the entire company sits inside a freezer. Not a machine. Not a patent. A collection of vials holding frozen microorganisms — descendants of soil bacteria that have been coaxed, mutated, starved, selected, and re-selected across two decades until they reliably produce a molecule that keeps transplanted kidneys alive inside human bodies. Lose the freezer and you do not lose a production line. You lose the company.
That is the distinct reality of Concord Biotech Limited. In an Indian pharmaceutical industry built on chemistry — on reactions that behave the same way on Tuesday as they did on Monday — Concord bet its existence on biology, which does not. That bet succeeded to the point that by 2022, the company held over 20% global volume share across a basket of fermentation-based active pharmaceutical ingredients including tacrolimus, cyclosporine, sirolimus, mycophenolate sodium, and mupirocin.1 Today, its portfolio spans more than 30 fermentation APIs, over 150 Drug Master Files filed globally, and a base of more than 300 customers across 70-plus countries.2
The market took notice. As of August 31, 2026, Concord traded around ₹1,446 a share on the NSE, giving it a market capitalization of roughly ₹15,145 crore against a trailing price-to-earnings ratio of about 54.5.3 That is a premium multiple for a company whose revenue fell 12% in the fiscal year ended March 2026, and whose profit after tax declined 30%.4
That valuation frames the central question of Concord's investment thesis. The company's technical achievements are established — the strain libraries, regulatory approvals, and global market shares are well documented. The real question is whether that technical foundation translates into durable pricing power, compounding returns on capital, and a viable second act beyond immunosuppressant APIs. On those three dimensions, the evidence is far more mixed than the prevailing narrative suggests. Return on capital employed has fallen from roughly 36% in FY2017 to about 17% today.35 Management informed analysts in June 2026 that the API business experienced no price growth during FY2026 alongside declining volumes.4 Furthermore, when the CEO was asked in August 2026 what drove the company's wallet-share gains, the explanation was neither switching costs nor scientific superiority, but price.6
Here is how the story unfolds. First, why fermentation presents a fundamentally different industrial challenge than synthetic chemistry, and how a closed factory in Gujarat became the platform to tackle it. Next, the tacrolimus breakthrough that established Concord's scale, followed by the regulatory architecture that locked in customers. Then, the ownership carousel — Rakesh Jhunjhunwala's early bet, Matrix Laboratories' control stake, Mylan's entry and exit, and the founder's repurchase of the firm. That sets up the private-equity decade, the 2023 public listing, and the subsequent operating record. Along the way, the analysis tests the moat against the hardest available counterevidence: customer behavior, price realization, the nine-year record of the formulations business, and the performance of every corporate adjacency. Finally, the report examines the competitive structure, the bull and bear cases, and the key operating metrics that will determine whether the thesis holds.
Start with the science, because everything else follows from it.
 Subscribe on LinkedIn
II. The Fermentation Paradox & Post-Liberalization Origins
Imagine two factories. In the first, pour Chemical A into Chemical B under specified heat and pressure, and Compound C emerges. Run it a thousand times and get a thousand identical outcomes. If the yield disappoints, adjust the temperature or catalyst. The process is written down, transferable, and — critically — copyable by any competent engineer who reads the patent.
In the second factory, feed a living organism. Give a strain of bacteria a broth of corn steep liquor, starch, and dextrose, hold it at precise temperature and oxygen levels for 30 to 50 days, and hope it excretes the molecule wanted.7 It might. It might also mutate, drift, get contaminated, or simply decide — for reasons process engineers will spend months failing to identify — to produce 30% less than last quarter. Nothing is written down that fully captures why one company's strain out-produces another's, because the knowledge lives partly in the organism itself.
This is the fermentation paradox, and it is the foundation of Concord's business. Fermentation is worse than synthetic chemistry in almost every way a manufacturing manager cares about: slower, less predictable, more capital-hungry per kilogram of output, harder to scale, and harder to troubleshoot. Concord's investor materials list the barriers as complex technical expertise, capital-intensive infrastructure, large-scale fermenter requirements, and long gestation periods.2 That list reads like a warning label. Read as a competitive statement, it is the pitch: everything that makes fermentation miserable to operate also makes it miserable to enter.
Consider the arithmetic of imitation. To copy a synthetic API, a company needs a chemist and a reactor. To copy a fermentation API, it needs a productive strain — which takes years of mutation and selection — plus fermenters, tacit process knowledge to run them at economic yields, and regulatory approval for the resulting molecule. During the decade in which India's generic industry exploded after the 1991 liberalization, most Indian firms went where returns arrived fastest. Fermentation was the road nobody wanted.
Sudhir Vaid took it, starting from an unusual vantage point: he had already spent eight years as Director of Fermentation at Ranbaxy Laboratories, then India's most ambitious pharmaceutical company, before consulting for other pharma firms.5 Credit rating agencies later described him as a technocrat-turned-entrepreneur — someone who understood that the technical frustrations of fermentation were precisely what competitors could not replicate.
The vehicle he chose was, by any conventional standard, a wreck. The corporate entity dated to November 1984, originally established as Servomed Pharmaceuticals in Ahmedabad, and had passed through a succession of owners before shutting down.58 In May 2000, Vaid acquired the shell for roughly ₹3.6 crore — a business carrying accumulated losses of close to ₹4 crore.8 The company was renamed Concord Biotech in 2001 and initially operated with a single manufacturing block producing amidase enzyme.5
It is worth pausing on how modest that beginning was. One block. One enzyme. A balance sheet that had already destroyed capital for its previous owners. The strategic insight — that chemical synthesis APIs were heading toward commoditization against low-cost Chinese capacity while fermentation would remain difficult — was sound, but in 2000, it remained unproven and unfunded. What Vaid actually bought was time: a facility cheap enough that he could afford years of trial and error in strain development before achieving commercial viability.
That origin highlights a key structural pattern. Concord's beginning was not a sudden technological breakthrough followed by rapid scale-up. It was the purchase of optionality at distressed prices, followed by a long, expensive, and unglamorous grind through biology — a grind with a specific destination in mind.
III. The Tacrolimus Breakthrough & Technical Moat Construction
To understand why tacrolimus mattered, consider what it does. When a surgeon transplants a kidney, liver, or heart into a patient, the recipient's immune system naturally attacks the foreign tissue. Immunosuppressants halt that response. They are neither optional nor short-course; transplant recipients typically require them for life. In pharmaceutical terms, this represents chronic, non-discretionary demand that cannot be deferred. Management has pointed to this characteristic when explaining why disrupted supply eventually recovers, arguing that supply interruptions in chronic therapies cannot persist indefinitely.4
Tacrolimus is produced by a soil bacterium, Streptomyces tsukubaensis, discovered by Japanese researchers. The original commercial process belonged to Fujisawa Pharmaceutical, later part of Astellas Pharma. The molecule is a macrolide of immense structural complexity, making synthetic, atom-by-atom reactor synthesis economically unfeasible. It must be grown. Because wild microbial strains excrete tiny quantities, commercial viability depends entirely on pushing the organism's yield far beyond natural limits.
That yield optimization is where technical expertise resides. Concord's R&D capabilities center on strain isolation, mutation, and passive selection, alongside iterative strain improvement processes supported by fermenters and a pilot plant that scale laboratory output to commercial volumes.2 Beneath the corporate phrasing lies accelerated biological selection: exposing organisms to mutagens, screening thousands of surviving variants, retaining those with higher output, and repeating the cycle for years. Each incremental gain in titre — the concentration of product per liter of broth — directly reduces unit costs, because fermenter operations, utilities, and labor remain fixed regardless of cellular productivity.
Concord became one of the first Indian manufacturers to produce tacrolimus commercially via fermentation.8 The resulting head start shaped the global market structure. On tacrolimus, Concord holds an estimated 40% global volume share and remains among a small group of suppliers — including Teva Pharmaceutical Industries — holding Drug Master Files across all major regulated markets.8 In cyclosporine, it is India's largest supplier with roughly 30% global volume share, while holding approximately 22% in mycophenolate sodium and about 15% in mycophenolate mofetil, where Concord and Teva are again the only suppliers with active DMFs across all three highly regulated regions.8
This technical capability translates into commercial durability through regulatory lock-in. A Drug Master File is a confidential dossier submitted to regulatory authorities detailing an API's manufacturing process. When a generic drug manufacturer files an Abbreviated New Drug Application to market a finished dose, it references its API supplier's DMF. That reference creates a binding regulatory dependency rather than a routine purchase order. Switching API vendors requires re-validating the finished formulation, generating new stability data, and securing regulatory approval — a process that consumes significant capital and time while keeping the finished product off the market.
By June 2023, Concord had filed 128 DMFs globally, including 20 in the United States, 65 in Europe, and four in Japan, a total that has since surpassed 150.12 The primary evidence of switching costs lies in customer retention rather than dossier counts: at the time of its public listing, Concord's relationships with its top ten customers averaged eight years.1
The distribution of these regulatory filings provides further context on cost competitiveness. Concord has registered dossiers for tacrolimus, mycophenolate mofetil, cyclosporine, and mupirocin not only in the United States, Europe, Canada, and Japan, but also in China.2 Selling fermentation products directly into China — a market often viewed as a dominant low-cost threat to Indian API makers — indicates that Concord's advantage stems from scarce process engineering and biological yield management rather than basic wage arbitrage.
A second commercial driver is portfolio breadth across therapeutic categories. Concord offers a complete suite of immunosuppressants — including tacrolimus, both mycophenolates, cyclosporine, sirolimus, pimecrolimus, voclosporin, and everolimus premixes — alongside oncology therapies such as temsirolimus, romidepsin, and midostaurin, plus an anti-infective portfolio containing mupirocin, teicoplanin, vancomycin, fidaxomicin, and echinocandin antifungals.2 For generic formulators focused on transplantation, this comprehensive range positions Concord as a single-source category provider. Management describes this dynamic as becoming a customer's primary fermentation partner, while noting that portfolio breadth is a supporting relationship factor rather than the sole driver of contracts won.6
However, customer retention demonstrates that buyers do not switch vendors casually; it does not guarantee pricing power. High switching costs and price realization are distinct dynamics, a separation that becomes crucial when evaluating Concord's long-term financial performance. Before examining that financial record, the company's evolution requires examining its shifting ownership structure.
IV. The Ownership Carousel: Rakesh Jhunjhunwala, Matrix & The Mylan Buyback
By 2004, Concord had the beginnings of a viable business alongside the balance sheet of a small enterprise. Fermentation capacity must be built well ahead of revenue — fermenters, utilities, effluent treatment, and containment — while strain development programmes consume cash for years before a single kilogram of commercial product ships. Vaid needed capital, and when traditional banks hesitated to finance an unproven biological venture, he sold equity.
Around 2004, he parted with roughly 30% of the company, selling about 18% to Rakesh Jhunjhunwala's RARE Enterprises and roughly 12% to a Canadian investor.8 Jhunjhunwala was then building the reputation that made him India's most prominent public-market investor, and Concord represented the kind of opportunity that defined his portfolio: private, illiquid, technically obscure, and held for the long term. That investment provided Concord with more than cash; it brought institutional credibility at a time when the company had little else to showcase.
The company's trajectory soon shifted. In 2005, Hyderabad-based Matrix Laboratories acquired a controlling stake of roughly 55%, buying down the holdings of both Vaid and Jhunjhunwala.8 The industrial logic appeared sound for both sides: Matrix was a major synthetic-chemistry API house seeking fermentation capabilities it lacked, while Concord gained access to international distribution channels and corporate governance infrastructure.
Neither party anticipated the corporate restructuring that followed. In 2007, Mylan acquired Matrix Laboratories, turning Concord — a specialized, capital-hungry fermentation niche player — into a third-tier asset inside a global generics conglomerate focused on branded and retail finished doses. Concord fell outside that strategic core. In 2009, Mylan sold its stake back to Sudhir Vaid and RARE Enterprises, a transaction that materially increased Jhunjhunwala's ownership.8
This shift corrects a common misconception surrounding Concord's history. The prevailing narrative suggests Rakesh Jhunjhunwala bought shares in 2004 and passively held them for two decades while the technology matured. The actual record shows a more active strategy: he entered around 2004, trimmed his stake during the Matrix transaction a year later, and expanded his position in 2009 when Mylan sought an exit — leaving his entity with a larger holding than before.8 Rather than passive holding, the move reflected disciplined capital allocation: selling to a strategic buyer at a premium and reinvesting when a parent firm sought liquidity.
This distinction offers a clearer lesson for investors. Concord did not benefit merely from a buy-and-hold backer, but from an engaged shareholder willing to provide liquidity across multiple ownership transitions and capital when independence became achievable. That willingness to step in at a pivotal moment proved far more decisive than static ownership.
The repurchase itself warrants objective assessment. A founder reclaiming control from a multinational owner represents a clear operational advantage, as parent companies rarely fund long-term capital investments in non-core assets. Regaining independence allowed Concord to allocate capital toward multi-year fermentation projects without competing against a global conglomerate's internal priorities. The company's subsequent facility expansions would have been difficult to execute under conglomerate ownership.
Two important caveats temper this transition. First, the buyback was not purely an act of founder conviction; it required an institutional co-investor willing to finance the transaction, with the precise financial terms remaining undisclosed. Second, ties with Mylan extended beyond equity ownership: as late as FY2018, Intas Pharmaceuticals and Mylan together accounted for roughly 40% of Concord's total revenues.5 The former parent remained a primary revenue source, illustrating how fluid the boundaries between owner, customer, and partner often remain in the API sector.
With its independence restored, Concord faced the same requirement it had in 2004: substantial growth capital paired with patient long-term backing.
V. The Quadria Capital Era & Institutional Scale-Up
The investor that arrived in 2016 was not a generalist. Quadria Capital, a healthcare-focused private equity firm operating across Asia, invested through a Singapore special purpose vehicle, Helix Investment Holdings Pte Ltd, acquiring a 20% stake.95 The precise consideration was not disclosed in the primary regulatory filings.
What that capital and decade-long partnership yielded is clearer in the operating figures. Quadria reported that Concord's sales roughly tripled during its holding period, driven by organic expansion, geographic diversification, and a strategic move into finished formulations.9 Credit rating agency ICRA corroborated this trajectory: by FY2025, revenue reached ₹1,220.6 crore, representing a 19% compound annual growth rate over five fiscal years, while operating margins held between 42% and 44% over the prior four years.7
The physical build-out during this era established the production ceiling for the subsequent decade. Concord operates four units, all located in Gujarat. Unit I at Dholka, the original API facility operational since FY2000, provides 450 cubic metres of installed fermentation capacity. Unit III at Limbasi, commissioned in FY2021, added 800 cubic metres, bringing total fermentation capacity to 1,250 cubic metres — a substantial volume for generic fermentation, though lower than speculative secondary estimates.2 Meanwhile, Unit II at Valthera, operational since FY2016, produces oral solid formulations with an annual capacity of 869 million units, while Unit IV at the same site handles injectables, having commenced operations in FY2025.2
Regulatory approvals expanded alongside capacity. Concord's API plants hold certifications from the US Food and Drug Administration, EU-GMP, Japan's Foreign Manufacturer Registration, South Korea's Ministry of Food and Drug Safety (식품의약품안전처), and Indian GMP, while the formulation plant holds EU-GMP and USFDA approvals.7 Each certification expands addressable market access, but also creates a permanent compliance obligation subject to periodic re-inspection.
A precise accounting of the private equity transaction clarifies its actual financial role. The investment was predominantly a secondary purchase to provide exit liquidity for existing shareholders, rather than a massive primary infusion. ICRA recorded a direct equity injection into the business of ₹76.30 crore in FY2017, relative to a net worth that reached ₹594.36 crore by March 2018.5 The investment primarily reshaped ownership rather than rescuing balance-sheet solvency.
The company's balance sheet already reflected self-sustaining cash generation prior to institutional expansion. By FY2018, Concord maintained an interest coverage ratio of roughly 126 times, a debt service coverage ratio above 12 times, and an average working capital line utilization of just 2%.5 The private equity partnership did not rehabilitate a distressed asset; it added institutional governance and capital allocation discipline to a business that was already generating strong cash flow.
The expansion at Limbasi highlights a recurring capital deployment pattern. The facility required roughly ₹224.75 crore in capital expenditure, funded through internal accruals and term debt at a planned debt-to-equity ratio of 0.5 times, with commercial production initially targeted for June 2020.5 Although commercial operations slipped into FY2021, the associated debt was fully retired, leaving Concord with virtually no debt today.3 However, the investment underscores Concord's tendency to build large-scale capacity well ahead of market demand: five years after commissioning, Limbasi operated at approximately 55% capacity utilization.6
The broader ownership structure remained stable throughout the pre-IPO period. Rakesh Jhunjhunwala's entity maintained approximately a 24% stake alongside Helix's 20% holding.5 Following Jhunjhunwala's passing in 2022, the equity transferred to family trusts, which retain the position. The combination of a founder-operator alongside two major long-term institutional shareholders provided an unusually stable governance backbone for an Indian mid-cap, establishing the platform for a pure offer-for-sale initial public offering.
Before evaluating that public listing, the underlying operating model requires closer inspection, as recent fiscal performance has tested the investment thesis more rigorously than any period since the Mylan buyback.
VI. Core Business Deep Dive: Economics, Segments & Competitive Structure
On June 1, 2026, Ankur Vaid opened Concord's fourth-quarter earnings call with a sentence that no CEO enjoys delivering. FY26, he said, had been a challenging year, with industry headwinds compounded by geopolitical headwinds and supply chain disruptions.4 The numbers behind that sentence were stark. Full-year revenue declined 12% to approximately ₹1,036 crore on management's measure — ₹1,055 crore on a consolidated reported basis — and profit after tax fell 30% to ₹260 crore.43 The fourth quarter alone shrank 24%, with revenue of ₹326.1 crore against ₹429.9 crore a year earlier, net profit down 36.8% to ₹88.8 crore, and EBITDA margin compressing from 44.3% to 36.4%.10
To feel how sharp a break that was, hold it against what came before. Consolidated revenue had climbed from ₹713 crore in FY22 to ₹853 crore in FY23, ₹1,017 crore in FY24 and ₹1,200 crore in FY25, with operating margins running between 38% and 42% and net profit compounding from ₹175 crore to ₹372 crore across those four years.3 Then FY26 reversed roughly two years of progress in twelve months.
What the segments actually are
The business splits roughly 80:20. In FY26 the API segment produced about ₹829 crore, or 79% of revenue, and formulations about ₹226 crore, or 21%.2 Both declined — APIs by 12%, formulations by 13%.4 Domestic revenue fell 15% and exports fell 9%, leaving the geographic mix at 53:47 domestic to export for the year.4
The API portfolio is genuinely broader than the immunosuppressant label suggests: tacrolimus, mycophenolate mofetil and sodium, cyclosporine, sirolimus, pimecrolimus and voclosporin in immunosuppressants; temsirolimus, everolimus, romidepsin, mitomycin, dactinomycin and midostaurin in oncology; mupirocin, polymyxin B, teicoplanin, vancomycin and fidaxomicin in antibacterials; anidulafungin, caspofungin, micafungin, amphotericin B and nystatin in antifungals.2 But breadth of catalogue is not breadth of revenue. ICRA's July 2025 assessment put immunosuppressants at over 74% of API revenues, with APIs at roughly 77% of company revenue overall — meaning a single therapeutic class drove something close to three-fifths of the whole business.7
Testing Claim One: does fermentation complexity confer pricing power?
This is the load-bearing claim in the entire investment case, and Concord's own management has answered it more clearly than any outside analyst could.
On the Q4 FY26 call, Kotak's analyst asked for the split between volume and price growth in the API business for the full year. Ankur Vaid's answer: there had been no price growth; growth had been primarily volume-based. Pressed on whether that meant volumes had declined for the full year, he confirmed it.4 He went on to characterise pricing more fully — newly launched products like nystatin and fusidic acid face no pricing pressure because Concord enters them aggressively as a second source, while on more mature products there is always a little bit of price erosion with certain customers, offset by entering new regions. He framed this as part and parcel of the game rather than a structural threat.4
That is a considerably narrower claim than "pricing power". It describes a business that holds price roughly flat on mature molecules, wins new volume by undercutting incumbents, and relies on R&D to keep refreshing the portfolio ahead of erosion. It is a good business. It is not a business that raises prices.
The Q1 FY27 call, in August 2026, made the mechanism explicit. Jefferies asked directly what drove the wallet-share gains Concord had been advertising — was it pricing, or a competitor's disruption? Vaid's answer was unambiguous: it was primarily driven by pricing, because the scale of the 1,250 cubic metre fermentation base gives Concord a good grip on cost, and that price benefit had been shared with customers. Even by offering competitive pricing against rivals, he said, the company still maintains healthy margins. He added that softer relationship factors play a part but that the primary reason for the change is price, and that these were mostly existing products rather than new launches.6
Read carefully, that is a cost advantage being converted into share, not a differentiation advantage being converted into margin. It is a real and defensible edge — low-cost position in a capital-intensive niche is exactly the kind of thing that compounds — but it is the economics of a scale manufacturer, not of a monopolist. The distinction matters enormously for how much multiple the business deserves.
Two further pieces of evidence bound the claim in opposite directions. Working against it: ICRA's standing constraint on the rating is high concentration in a single therapeutic segment, which heightens vulnerability to segment-specific regulatory or market disruptions.7 Working in Concord's favour: customer concentration has genuinely improved. The top ten customers accounted for 47.7% of revenue in FY22, 44.3% in FY23, 42.0% in FY24, 37.8% in FY25 and 37.6% in FY26.2 That is a decade-long trend in the right direction and it contradicts the common claim that Concord remains dangerously dependent on a handful of buyers. Compare it with FY2018, when the top two customers alone were around 40% of revenue and the top three products around 60%.5 The business is meaningfully more diversified than it was.
Verdict on Claim One: the history does not reject the moat, but it narrows it decisively. Concord's advantage is demonstrated in cost position and customer retention, not in price realisation. The falsification test going forward is simple — if the moat were a pricing moat, gross margin would expand as mix shifts toward niche molecules. Gross margin was 78.9% in Q1 FY27, up 100 basis points year on year, and management guided it to stay broadly in line with historical levels rather than climb.64 Watch whether that number moves. So far it mostly has not.
Testing Claim Two: does pure-play fermentation scale insulate the company?
FY26 answered this one empirically, and the answer is no.
Management's account of the year is specific and, importantly, disaggregated. US customers slowed procurement in the first half amid uncertainty over tariff measures, with prospective customers declining to alter existing supply chains. Delays in obtaining written confirmation approvals from India's CDSCO restricted supplies to Europe for nearly three months — roughly a third of the fiscal year. A major Middle East tender went into abeyance amid the regional war, costing about ₹25 crore, with total company exposure to the region around ₹50 crore. The US Veterans Affairs tender was not finalised, costing roughly another ₹25 crore. And customers shifted from bulk purchasing to staggered quarter-on-quarter procurement.4
Management's framing is that these were largely beyond the company's control, not related to lower demand, loss of market share or pricing pressure, and that while similar situations had occurred individually before, this year multiple challenges coincided.4 That explanation is plausible and was offered with unusual specificity — one participant on the call remarked that the quality of communication had been consistently strong.4
But plausible is not the same as reassuring. The analytical content of FY26 is that a business with 1,250 cubic metres of the hardest-to-replicate fermentation capacity in India was still knocked down 12% by a regulatory paperwork delay, a government tender that did not clear, and customers changing their purchasing rhythm. Scale in fermentation protects you from competitors. It does not protect you from buyers — particularly buyers who are governments, tender authorities and large generic formulators with the ability to time their orders.
The balance-sheet consequences were visible. Inventory rose from ₹240 crore to ₹326 crore, with inventory days climbing from 286 to 480, as goods manufactured for Q4 shipment were pushed into later quarters.4 Operating cash flow of ₹267 crore converted at 73% of EBITDA, respectable for a year like that.4 Working capital intensity in this business runs structurally at 45–55%, driven by 115–120 day credit terms to key customers and the long fermentation cycle, and management expects it to stay in line with history.74 That is simply the cost of the business model, and investors should price it as permanent rather than fixable.
Verdict on Claim Two: rejected as stated. Fermentation scale does not insulate Concord from industry and geopolitical cycles; FY26 demonstrated it directly. The narrower surviving claim is that Concord's margins are more resilient than its revenue — adjusted for the roughly ₹75 crore of unabsorbed operating expenses from the injectables facility and the US subsidiary, EBITDA margin held near 39% for FY26 despite a 12% revenue decline.4 Cost structure held; volume did not.
One more feature of FY26 deserves attention because it complicates the "timing, not demand" account. The damage was not confined to the quarters where revenue fell. In the December 2025 quarter, net sales actually rose about 14% year on year to ₹277.8 crore — and consolidated net profit still fell roughly 15% to ₹64.5 crore.11 A quarter with double-digit revenue growth and a double-digit profit decline is telling you that something structural was happening on the cost side, not merely that shipments moved between periods. The new facilities were absorbing overhead regardless of what the top line did, and that drag was independent of the tender delays and regulatory paperwork management emphasised.
The number nobody puts on a slide
There is one metric that captures the tension in this business better than any other, and it does not appear in the investor presentation. Return on capital employed was 36.4% in FY2017 and 25.0% in FY2018.5 Today it stands at roughly 17.1%, with return on equity of 12.5%.3
That decline is not evidence of a deteriorating business — it is the arithmetic of a company that has built a great deal of capacity, funded it conservatively, and is still waiting for volume to arrive. Reserves of ₹2,007 crore against borrowings of ₹2 crore, ₹414 crore of cash at March 2026 rising to ₹442 crore by June, and a fortress balance sheet come at a price, and the price is returns diluted by idle assets and accumulating cash.346
Which is exactly why the next two questions — who is allocating that capital, and what are they doing with it — matter more than any discussion of strain libraries.
VII. Management Assessment, Governance & Capital Allocation Track Record
Concord is run by a father and a son, and the division of labour between them is unusually legible.
Sudhir Vaid, Chairman and Managing Director, is the fermentation man. ICRA describes him as a technocrat-turned-entrepreneur with nearly four decades of experience in biotechnology, formed by those years running fermentation at Ranbaxy.7 The company's own materials claim fifty years of expertise.12 He is the reason the strain libraries exist, and he is the reason a shuttered enzyme plant in Dholka became a global tacrolimus supplier.
Ankur Vaid, Joint Managing Director and CEO, is the commercial and capital-markets face of the business — a chemical engineer with an MBA and, at the time of listing, over eighteen years in the industry.8 He runs the earnings calls, and the way he runs them is itself evidence. Across the FY26 and Q1 FY27 calls he quantified the injectables drag at roughly ₹10 crore per quarter and ₹38–39 crore for the year, named the Middle East exposure at ₹50 crore, disclosed unit-by-unit capacity utilisation without being pushed, and when asked at what utilisation the injectables plant breaks even, simply said he did not have the number and would come back.46 That last answer is worth more than a confident guess.
There is also a notable piece of self-limiting disclosure. Asked in August 2026 whether the 26% top-line growth reflected real demand or currency, the CFO acknowledged the rupee had moved roughly 10–12% against the dollar year on year, and after accounting for input-cost effects, put the net currency contribution flowing through to EBITDA at 3% to 5%.6 Management volunteering that a meaningful slice of a headline growth number is foreign exchange, on a call where nobody would have caught it otherwise, is a genuine credibility marker.
Where the credibility is thinner
Two areas deserve scrutiny.
The first is guidance discipline around new ventures. On the Q1 FY27 call, management was asked whether the injectables ramp was in line with initial expectations. The answer: last year's expectations got delayed by a couple of quarters, largely because of inspection and approval timelines and facility qualification taking longer than wanted.6 That is honest, but it is also the second time this company has told shareholders that a formulations facility would take longer than planned — the first was nearly a decade earlier, which we come to shortly. Slippage of one to two quarters on a facility ramp is unremarkable; slippage as a repeated pattern across two separate facilities is a fact about how this management forecasts.
The second is related-party structure. Two of the three new-venture vehicles were acquisitions of entities that qualified as related-party transactions: the 75% interest in Stellon Biotech in July 2025, and the 100% acquisition of Celliimune Biotech in April 2026.1314 Both were disclosed, both were stated to be at arm's length, and both involved trivial sums. But the pattern — newly incorporated shell entities, pre-revenue or nil-turnover, acquired by the listed company as related-party transactions — is one that deserves ongoing attention from shareholders rather than a shrug, particularly given how small the disclosed consideration was relative to the operating expense the parent then absorbed.
On remuneration, aggregate promoter compensation in FY25 — salaries, perquisites, rent and professional charges combined — has been calculated at approximately ₹16.7 crore, or about 4.5% of consolidated profit after tax, with Ankur Vaid's own compensation at roughly ₹3.3 crore, around 122 times median employee pay.8 By the standards of Indian promoter-run mid-caps that is not egregious, but the inclusion of rent and professional charges in the promoter payment stream is worth watching, and shareholders should read the related-party disclosures rather than the salary line alone.
Capital allocation: the actual record
Here the evidence is genuinely good in one dimension and genuinely untested in another.
The good: Concord funded its entire capacity build without leaning on shareholders. It has never raised fresh equity from public markets — the 2023 listing was a pure secondary sale, which we will come to. Borrowings sit at ₹2 crore.3 FY26 capex was ₹65 crore against ₹267 crore of operating cash flow, and management guided FY27 maintenance capex to ₹20–30 crore, with any larger spend deferred until Limbasi utilisation reaches 80–85%.4 A dividend of ₹7.55 per share was recommended for FY26 with a record date of July 24, 2026, maintained despite the profit decline.10 Average dividend payout has run around 28%.3
The untested: what happens to the cash. By June 2026 Concord held ₹442 crore and rising, with a stated peak revenue potential of ₹3,000 crore from existing assets and essentially no capex requirement for years.64 Asked about capital allocation, management said dividends, organic growth and inorganic growth in fermentation adjacencies were all on the table, and separately identified peptides and veterinary products as areas that might warrant dedicated capacity.6 That is a company approaching a genuine capital allocation decision with no track record of large acquisitions to judge it by.
The small deployments so far have been modest and, on the evidence available, more optionality than strategy. A $1 million investment in compulsorily convertible notes of US-listed Palvella Therapeutics in December 2024, converting to roughly 71,446 shares, intended to underpin a manufacturing and commercialisation partnership for Palvella's rare skin disease candidate.15 A 26% stake in CleanMax Everglades, a special purpose vehicle for a 6.6 MW wind and 3.3 MW solar captive project at Dholka — the initial equity subscription was ₹2.6 lakh for 26,000 shares, part of a total investment reported at ₹6.09 crore.16 The CleanMax structure is a standard group-captive arrangement and management expects it to add 1% to 1.5% to EBITDA margin, though it noted that higher LPG and furnace oil costs are partially eating that benefit — power and fuel run around 20% of costs, roughly half of it LPG or furnace oil based.4
So: disciplined, small, mostly sensible, and not yet a test of anything. The real capital allocation question arrives when the cash pile forces a decision, and nothing in the record yet tells us how this management behaves when writing a large cheque.
Which brings us to the three bets they have already placed.
VIII. Optionality Bets: The Valthera Injectables Plant & US Expansion
In March 2025, after a construction programme costing roughly ₹240 crore, Concord's injectables unit at Valthera began commercial operations.7 Designed to manufacture sterile products — liquid vials, dry powder filling, and bulk sterile lyophilised material — the facility added installed capacity of 13 million liquid vials, 12 million dry powder units, and 2,200 kilograms of bulk sterile lyophilised product.2
Sterile injectables represent the most technically demanding segment in generic manufacturing. Every component touching the product requires sterilization, the facility must maintain strictly validated environmental controls, and regulators inspect sterile lines far more stringently than oral tablet lines. Qualifying a plant for commercial supply is measured in years rather than months.
Management's strategic case for the investment is coherent and integrated. Joint Managing Director and CEO Ankur Vaid told analysts in August 2026 that the facility can generate close to ₹600 crore in peak top-line revenue, arguing that Concord is the only manufacturer in India integrated from fermentation API all the way through to finished injectable products — providing what he termed a competitive right to win.6 For molecules such as anidulafungin or micafungin, where Concord already supplies the API, capturing the finished-dose margin represents logical vertical integration rather than speculative diversification.
However, execution must be evaluated against the historical record.
Testing the optionality claim against Concord's own history
The investment thesis assumes that formulations and injectables will scale meaningfully and lift overall margins. The primary counter-evidence is not theoretical; it is Concord's earlier attempt to execute the exact same transition.
Concord's first formulation unit began commercial production in March 2017. By FY2018, the plant had failed to stabilize, posting an operating loss of ₹23.47 crore and a net loss of ₹29.54 crore. Rating agency ICRA noted at the time that the unit faced intense competition from established organized players, domestic price caps, and dependence on timely export market approvals, concluding that the company's ability to gain market share, scale operations, and achieve breakeven remained to be seen.5
Nine years later, the historical record provides a clear answer. Formulations generated ₹226 crore in FY26 — roughly 21% of total revenue — before declining 13% during the year.24 In the first quarter of FY27, formulation revenue fell another 23% year-over-year to ₹38.6 crore, even as the core API business grew 42%.2 Meanwhile, Unit II, the oral solids facility, operated at approximately 25% capacity utilization during that same quarter.6
Management attributes this weakness partly to portfolio optimization and partly to market shifts. The CFO explained that Concord optimizes across its entire business: where an opportunity can be captured via API supply, the company prefers that route, reserving formulation capacity for markets where direct API sales are unavailable — causing segment mix to fluctuate quarter to quarter.6 Ankur Vaid cited a concrete example: Middle East customers who previously purchased finished formulations shifted back to buying API, seeking longer product shelf life and cash-flow flexibility amid regional currency and funding constraints.46 Excluding the Middle East impact, management noted that both domestic formulation divisions achieved double-digit growth.6
While credible, that explanation reveals an underlying vulnerability. A meaningful portion of formulation revenue depended on a single geopolitically exposed tender market where buyers proved indifferent between purchasing Concord's API or its finished product. Where buyers remain indifferent, forward integration does not capture a competitive moat; it merely captures a temporary margin until customer preferences shift.
Historically, Concord required nine years to convert formulation capacity into one-fifth of overall revenue, with the segment contracting in recent reporting periods and oral solids running at a quarter of capacity. That track record indicates a slow commercial conversion rate.
What that implies for the injectables ramp
Applying that historical base rate to Unit IV indicates an extended ramp period, a timeline consistent with management's own disclosures. The injectables plant operated at approximately 5% capacity utilization in the first quarter of FY27.6 The unit generated roughly ₹38 crore to ₹39 crore in unabsorbed operating expenses during FY26, running at about ₹10 crore per quarter.4 Emerging market regulatory filings remain in the documentation stage, prioritizing Southeast Asia and Africa, with approval timelines estimated at 12 to 15 months — deferring export sales until the following fiscal year.46 In the interim, management plans to fill capacity domestically through Concord's own branded generics and contract manufacturing for larger Indian pharma firms, with audit-stage discussions expected to yield commercialization in the second half of FY27.6
Management acknowledged in June 2026 that reaching full breakeven would likely take until the following financial year.4 Although the facility secured WHO-GMP certification and completed commercial validation batches — necessary technical milestones — regulatory certification does not automatically guarantee commercial adoption.4
Stellon Biotech and the US front end
Concord's US commercial vehicle requires similar analytical precision. In July 2025, Concord acquired a 75% stake in Stellon Biotech Inc., a Delaware entity incorporated in December 2024 with no prior revenue, created specifically to market and commercialize Concord's products in the United States. The transaction was structured at USD 1,500 for 15 million shares at USD 0.0001 per share.13
The transaction represents the incorporation of a subsidiary rather than an asset acquisition. The primary financial commitment lies in ongoing operating expenditure, which, combined with the injectables plant, resulted in approximately ₹75 crore of unabsorbed operating drag in FY26.4 Stellon initiated commercial operations and sales in the June 2026 quarter, with management framing it as a nascent platform that will also in-license third-party products for US distribution rather than solely selling Concord's own products.6
The strategic rationale — moving from a bulk API supplier to a front-end distributor in the United States — aligns with ANDA approvals received in the first quarter of FY27 for mycophenolate mofetil and tofacitinib tablets.2 However, establishing a front-end presence in US generics requires competing in a highly price-eroded market dominated by established distributors. Given Concord's lack of distribution history in the region, Stellon represents an early-stage experiment with capped downside exposure rather than a mature strategic asset.
The third bet, and the newest
Contract Development and Manufacturing Organization (CDMO) services — producing fermentation molecules using customer-owned intellectual property — represents Concord's third expansion vector. Management explicitly distinguishes CDMO work, which involves third-party IP, from custom manufacturing using Concord's own IP.4 Under that definition, CDMO accounted for just 1% to 2% of sales in the first quarter of FY27, anchored by a single animal health contract generating a couple of million dollars, alongside long-term goals to expand CDMO into a double-digit revenue contributor over time.6 Management reported two additional opportunities at advanced discussion stages, expecting at least one to convert during FY27.6
Concord also acquired 100% of Celliimune Biotech in April 2026 for ₹66 lakh, purchasing a January 2025 shell company with zero turnover focused on cell and gene therapy and DNA engineering for cancer.14 Cell and gene therapy represents a complete departure from fermentation-based small molecules. While the acquisition price is trivial, entering an unrelated therapeutic modality raises capital allocation questions for a company currently working to utilize newly built capacity.
In summary, Concord's optionality bets remain unproven. While each initiative possesses a logical rationale, none has established material revenue scale. The historical record indicates a multi-year lag between facility commissioning and commercial realization. The immediate milestone for investors will be whether contract manufacturing agreements for the injectables plant materialize in the second half of FY27. Securing those contracts and raising Unit IV utilization above 5% would validate the strategy; continued near-breakeven operations through FY28 would confirm the historical base rate.
IX. The 2023 IPO & Public Market Reception
By early 2023, Concord faced a situation most companies would envy: it generated enough cash to fund its own growth and carried almost no debt. However, its private equity backer, Quadria Capital — investing through Helix Investment Holdings — was seven years into its holding period and required an exit strategy. With no need for primary expansion capital, the company had every reason to create public market liquidity for existing shareholders without raising fresh equity.
The resulting transaction was rare for an Indian pharmaceutical listing: a 100% offer for sale. Helix Investment Holdings offered up to 20.93 million shares — its entire 20% stake — in a price band of ₹705 to ₹741 per share, with bidding open from August 4 to August 8, 2023, following anchor investor allocation the day before.17 Priced at the top of the band, the offering raised ₹1,551 crore, valuing Concord at ₹7,752 crore.1718 Crucially, not a rupee went to the company's balance sheet.
That secondary structure carries meaningful analytical signal. A pure offer for sale demonstrated that internal accruals were sufficient to fund growth without diluting equity — a premise Concord's subsequent operating record borne out, as the firm continued to fund capital expenditure from operating cash flows without returning to equity markets in the three years since. The absence of a fresh issue also eliminated a common post-listing risk: cash sitting idle on the balance sheet ahead of physical deployment.
Institutional demand was strong. Qualified institutional buyers subscribed to their allocated portion 67.67 times, non-institutional investors 16.99 times, and retail investors 3.78 times, driving an overall subscription rate of 24.87 times.18 On August 18, 2023, the shares listed on both the BSE and NSE at ₹900.05, representing a 21.46% premium over the issue price.18
Quadria characterized the transaction as a successful exit and one of the largest Indian pharmaceutical public offerings of the preceding two years.9 Because Quadria did not disclose its realized return multiple and primary sources did not confirm the entry valuation, claims regarding precise private equity returns require caution.
Over the three years following its public debut, the stock roughly doubled from its issue price, trading near ₹1,448 per share by the end of August 2026.3 However, that performance was non-linear. The stock underwent a valuation de-rating during the operational decline in fiscal 2026, followed by a recovery as first-quarter results in fiscal 2027 suggested the slowdown was a temporary interruption rather than a structural shift.
Three years after listing, the thesis implicit in the pure secondary structure has held up. Concord funded every post-listing expansion — the injectables facility, a softgel line commercialized during fiscal 2026, and a small topical facility planned for fiscal 2027 — entirely out of operating cash flow, carrying ₹79.3 crore of capital work-in-progress as of March 2026 against a balance sheet with essentially no borrowings.43 Management attributed the higher-than-maintenance capex in fiscal 2026 partly to the softgel build and partly to plant modifications required for a larger-volume project with an innovator client.4 Delivering three years of capital expansion without returning to equity markets fulfilled the commitment made at listing.
What the pure offer-for-sale structure did not provide was a primary cash war chest. Every rupee Concord deploys toward acquisitions or new capacity must be earned through operations. That structural constraint imposes capital discipline that bullish expectations can overlook when projecting simultaneous expansions across injectables, contract manufacturing, and US distribution.
The resulting shareholding structure remains unusually concentrated. Promoters hold 44.08%. The Jhunjhunwala family trusts — Aryavir, Aryaman, and Nishtha, each holding 8.03% — collectively hold 24.09%, representing roughly 2.52 crore shares worth around ₹3,703 crore as of August 2026.319 Foreign institutional investors hold 7.53% and domestic institutions hold 9.37%, across a base of roughly 83,000 shareholders on the register.3
With approximately 68% of the equity held by the founding family and a long-horizon family office, ownership stability cuts both ways for investors. Concentrated voting control insulates management from short-term public market pressures, supporting multi-year facility qualifications and long fermentation production cycles. Conversely, minority shareholders possess minimal governance mechanisms to influence capital allocation decisions if corporate strategy falters. In a company building cash reserves without immediate capital expenditure requirements, capital deployment oversight remains a central consideration.
The market's current valuation — a price-to-earnings multiple in the mid-fifties on trailing earnings that fell 30% in fiscal 2026 — represents a bet that fiscal 2026 was an anomaly and the pre-2026 growth trajectory will resume.3 Whether that valuation premium holds depends on the competitive structure of the underlying business.
X. Competitive Strategy: Helmer's 7 Powers & Porter's 5 Forces Framework
Strip away the narrative and ask the war-game question: if a well-capitalized competitor decided tomorrow to take Concord's tacrolimus business, what exactly would stop them?
Hamilton Helmer's 7 Powers, applied honestly
Process Power — the primary source, and it is real. Helmer defines process power as embedded organizational capability that competitors cannot replicate even with full knowledge of what the company does, because it accrues only through prolonged practice. Concord's strain libraries and fermentation know-how fit this definition better than almost any other Indian pharmaceutical asset. The company's R&D operation — 187 employees working on strain isolation, mutation, and passive selection, with pilot-scale fermenters to bridge laboratory output to the factory floor — functions as the machinery that maintains it.2 The critical qualification is that this power expresses itself as low unit cost, which management confirmed is how Concord wins share, rather than as premium pricing.6
There is one uncomfortable data point: R&D spending stood at ₹29 crore in fiscal 2026, or 2.8% of sales, having ranged between 2.2% and 3.6% over the preceding five years.2 For a company whose investment thesis hinges on scientific capability, that allocation is modest — closer to a process-optimization budget than a discovery budget. It aligns with Concord's strategy of incremental yield improvement and second-source entry into established molecules, rather than the loftier framing of an R&D-driven innovator.
Switching Costs — real, and the best-evidenced power in the portfolio. The Drug Master File referencing mechanism creates genuine regulatory friction, with eight-year average relationships across the top ten customers providing empirical proof.1 Yet switching costs make Concord hard to displace, not expensive to replace on the margin. Generic formulators routinely multi-source. The Middle East episode demonstrated that customers shift between Concord's API and finished formulations based on shelf-life requirements and currency convenience, showing that even loyal buyers retain control over order timing and format.
Scale Economies — secondary but strengthening. The 1,250 cubic meter fermentation base spreads fixed costs across higher output than domestic peers can manage, and management explicitly attributes its pricing flexibility to that scale.6 The limitation is that scale economies materialize only when fermenters run near capacity. With Limbasi operating at 55% utilization, Unit II at 25%, and Unit IV at 5%, a substantial portion of the asset base currently dilutes returns on capital rather than driving structural advantage.6
Counter-Positioning — historical, and now spent. Choosing fermentation while Indian peers focused on synthetic chemistry represented genuine counter-positioning in 2000, as incumbents could not follow without cannibalizing their existing business models. That window has closed. Commercial fermentation capacity exists in China, Teva holds competing DMFs across core immunosuppressants, and Concord's position must now be defended on cost efficiency and regulatory compliance rather than competitors' reluctance to enter.
What Concord lacks is equally instructive: no network economies, as additional customers do not enhance the product for existing buyers; no API-level branding power, where generic formulators evaluate pure specification and price; and no cornered resource beyond its strain libraries, which fall under process power.
Porter's Five Forces
Threat of new entrants: genuinely low. The entry barriers Concord highlights — technical complexity, capital intensity, large-scale fermenters, and long gestation periods — are validated by market structure, where only two or three suppliers hold DMFs across all major regulated regions for core molecules.28 A new entrant must navigate strain development, physical build-out, and regulatory approvals sequentially rather than concurrently.
Bargaining power of buyers: moderate to high. This represents the primary vulnerability in Concord's moat. Buyers include major generic formulators that multi-source by policy, along with government tender authorities in the Middle East and the US Department of Veterans Affairs. Concord extends credit terms of 115 to 120 days.7 Buyers dictated the transition from bulk purchasing to staggered orders that disrupted fiscal 2026 operations.4 Furthermore, Concord gains market share by offering competitive pricing rather than commanding premium realization.6 When a supplier finances customer working capital, absorbs delayed purchasing schedules, and competes on price, bargaining power sits squarely with the buyer.
Bargaining power of suppliers: low. Fermentation raw materials are commoditized agricultural products, and Concord is backward integrated to the key starting material level.2 The primary input exposure is energy: power and fuel account for roughly 20% of operating costs, with about half tied to LPG or furnace oil, and management noted that industry-wide fuel restrictions and higher charges in April 2026 forced plant operations at elevated cost because biological fermentation cannot be abruptly halted.4 A continuous biological process cannot simply pause to wait out transient input cost spikes.
Threat of substitutes: low. Total chemical synthesis of complex macrolide immunosuppressants remains economically unfeasible, preserving the role of biological fermentation. Long-term substitution risks are therapeutic rather than chemical: if organ transplant immunosuppression eventually shifts toward tolerance induction or cellular therapies, substitution will occur at the treatment level rather than the API manufacturing level — a multi-decade horizon rather than an immediate operational threat.
Competitive rivalry: moderate. Teva remains the principal peer across core molecules.8 Chinese fermentation capacity presents a persistent cost benchmark. Domestic Indian peers compete selectively rather than across the full portfolio. Rivalry manifests not as acute market-share loss, but as the steady, low-grade price erosion on mature molecules that management characterized as a standard operational condition.4
The strategic synthesis is clear: Concord occupies a defensible, structurally attractive niche with high barriers to entry, yet faces a customer base capable of capping returns. It is a durable business bounded by a structural ceiling — a reality reflected directly in its financial performance.
XI. Bull vs. Bear Case & Stress-Test Risk Radar
Every investment case eventually reduces to a disagreement about one thing. For Concord, that thing is whether FY26 was weather or climate.
The bull case
The China+1 argument. The most-cited reason to own Concord is that global pharmaceutical buyers are structurally reducing dependence on Chinese API supply, and Concord is among the very few non-Chinese suppliers with the fermentation capability, the regulatory approvals and the spare capacity to absorb that shift. Management has made the claim directly: with greater clarity emerging on the tariff situation, customers are focused on derisking supply chains and shifting business toward Concord, supported by its capabilities, capacities, global approvals and customer references.4
What is the evidence? Genuinely supportive: export revenue grew 46% year on year in the June 2026 quarter, described as broad-based across geographies with rising enquiries from regulated and semi-regulated markets, and Concord commenced API supplies to two innovator companies during FY26 — a customer category that historically did not buy from Indian suppliers at all.64 Genuinely complicating: the CFO conceded that the rupee moved roughly 10–12% against the dollar over that period, with a net 3% to 5% flowing through to EBITDA after input-cost effects, and the CEO attributed the wallet-share gains primarily to price rather than to scarcity of alternatives.6 A supplier who is winning because customers have nowhere else to go does not need to discount. So the China+1 shift is real but is currently being purchased rather than harvested. The falsifying observation would be gross margin rising toward the mid-eighties as scarcity replaces price competition. It has not happened.
Operating leverage from the new assets. This is the most mechanically credible bull point, because the costs are already sunk. Management stated plainly that the full expense of the injectables unit and the US subsidiary was booked in FY26, so anything from here should be positive for EBITDA.4 Add roughly 100 to 150 basis points from the captive renewable project and perhaps another 50 from the ventures, and management has sketched a path of 200 basis points or more of margin improvement.4 It has also been explicit about the timeline: the 40% EBITDA margin mark requires the injectables plant and Stellon to ramp fully, and is more likely an FY28 event than an FY27 one.6 Note the discipline in that answer — an executive with an incentive to promise a nearer date did not.
Capacity without capital. The existing asset base can support roughly ₹3,000 crore of revenue against about ₹1,055 crore delivered in FY26, with maintenance capex guided at ₹20–30 crore and no material addition expected for four to five years beyond debottlenecking.43 If revenue does compound, the incremental returns are excellent because the capital is already spent.
The bear case
Regulatory concentration risk is the fastest-acting danger. Concord's US business depends on facility clearances that can be withdrawn. The most recent test went well: the USFDA inspected the Dholka API facility from April 28 to May 2, 2025 and issued a Form 483 with four observations, which the company characterised as procedural with none relating to data integrity.20 An Establishment Inspection Report followed, closing the inspection.21 That is a clean outcome and a meaningful data point on compliance culture. It is not insurance. A future warning letter or import alert at Dholka or Limbasi would not dent revenue — it would sever a channel, and it would do so faster than any competitive threat in this analysis.
The reverse operating leverage of a high gross margin. Here is the uncomfortable arithmetic that the bull case tends to skip. Concord's gross margin runs near 79%, meaning direct cost of goods is only about a fifth of revenue.6 That is wonderful when volumes rise. It also means a price cut passes almost entirely into profit: cut price 15% on a product and you do not lose 15% of the margin on it, you lose something close to the full 15 points. FY26 demonstrated the same asymmetry through volume — a 12% revenue decline drove a 30% profit decline.4 Any thesis that treats Concord's margin structure as defensive has it backwards. High gross margin plus high fixed costs is a leveraged structure in both directions.
Working capital is a permanent tax, not a fixable inefficiency. The 480-day inventory position at March 2026 was an anomaly management expects to unwind, but the underlying 45–55% working capital intensity is not going away, because it derives from the fermentation cycle itself and from the credit terms customers extract.74 Every rupee of growth requires roughly half a rupee of incremental working capital before it becomes cash. That is the structural reason ROCE sits where it does.
Input costs the company cannot hedge or pause. In April 2026 government restrictions on industrial fuel use and higher charges hit the sector, and because fermentation cannot be stopped mid-batch, Concord ran at elevated fuel prices rather than curtailing output.4 With power and fuel around 20% of costs and roughly half of that LPG or furnace-oil based, this is a live exposure that partially offsets the renewable-energy benefit.4
Tariff risk, imperfectly answered. Asked in August 2026 about reports of prospective 100% tariffs on generics within two years, management said only that it had not heard any concerns from customers.6 That may be accurate reporting of customer sentiment. It is not an analysis of exposure, and given that US-bound volume travels largely indirectly through Indian formulators, the company may have less visibility into its own end-market exposure than the answer implies.
The activist stress test
Imagine a skeptical investor with a large position. What do they attack?
Not the balance sheet — there is nothing to attack. They attack the returns. Here is a company earning roughly 17% on capital employed and 12.5% on equity, sitting on ₹442 crore of cash that is growing, with management stating no material capex requirement for years, a dividend payout around 28%, and an explicit statement that inorganic growth in adjacencies such as peptides and veterinary products is under consideration.36 The activist's case writes itself: the cash is diluting returns, the stated adjacencies are unproven, the company has no track record of large acquisitions to justify trust with the balance sheet, and two of the three recent venture vehicles were related-party acquisitions of newly incorporated shells. Return the cash, or explain precisely why not.
The counter-argument is structural: with promoters at 44.08% and the Jhunjhunwala trusts at 24.09%, roughly two-thirds of the register is immovable.317 No activist campaign succeeds against that. Minority shareholders here are passengers, and should price the governance accordingly — favourably in that management can take genuinely long views, unfavourably in that there is no corrective mechanism if those views prove wrong.
Now run the operating scenario the bears actually fear. Suppose Concord's largest customers qualify a Chinese second source on tacrolimus and demand a 15% price reduction. Management's implicit answer is that Concord's scale-derived cost position lets it match almost any price while preserving healthy margins — the same mechanism it used to take share.6 The evidence supports the first half: FY26 held adjusted EBITDA near 39% through a 12% revenue collapse, which is a real demonstration of cost resilience.4 But the margin arithmetic above means the price cut lands nearly intact on profit. Concord would very likely keep the volume. It would keep considerably less of the earnings. That is the honest shape of the downside: this is a business far more likely to suffer margin compression than share loss.
Weighing it
The bull and bear cases are not symmetric, and they are not really in conflict. Concord almost certainly keeps its niche — the entry barriers are real, the compliance record is clean, the customer relationships are long, and the cost position is the best evidence in the whole file. What is genuinely unresolved is whether the returns on the capital already deployed rise back toward historical levels or settle permanently lower. FY26 is one data point for the pessimists; Q1 FY27 is one for the optimists. Neither is enough. Which is why what to watch matters more than what to conclude.
XII. Key Investment KPIs & Earnings Call Roadmap
Most commentary on Concord focuses on output metrics — quarterly revenue growth, headline margins, or the stock's 52-week range. Those numbers reflect past conditions. Three specific operational inputs determine whether the investment thesis ultimately holds, and management discloses all three directly on quarterly earnings calls without requiring complex adjustments.
One: Unit III capacity utilization at Limbasi. This metric offers the clearest picture of core operational health. Limbasi accounts for 800 of Concord's 1,250 cubic meters of fermentation capacity. Management reported utilization at roughly 53% for fiscal 2026 and around 55% for the June 2026 quarter.246 The bull case depends directly on this figure expanding: it underpins the company's ambition to reach ₹2,200 crore to ₹2,300 crore in API revenue, drives operating leverage, and fuels any recovery in return on capital. Management has noted a key operational nuance: some Limbasi capacity produces key starting materials that could otherwise be purchased externally, while oncology products made in smaller fermenters generate far more revenue per cubic meter than antibacterials, meaning utilization and revenue do not move in lockstep.6 Investors should track trend direction rather than minor quarterly fluctuations. The key benchmark: management has stated it will evaluate new capacity expansions only when Limbasi utilization reaches 80% to 85%.6
Two: the gap between reported and adjusted EBITDA margins. Concord reports both figures — actual operating margin alongside an adjusted margin excluding unabsorbed overhead from the injectables plant and the US commercial subsidiary. In fiscal 2026, that spread stood at four percentage points, with a reported margin of 35% against an adjusted 39%. In the June 2026 quarter, the gap widened to five points, reporting 32% against an adjusted 37%.46 That spread quantifies the drag from expansion initiatives, turning a qualitative narrative into a measurable metric. If these growth initiatives succeed, the margin gap should narrow as new facilities absorb overhead. If a spread of four to five percentage points persists through fiscal 2028 — the year management targeted for reaching a 40% margin — the injectables and US distribution bets will have failed to convert, regardless of qualitative updates.6
Three: inventory days. Working capital absorbs a substantial portion of Concord's cash, with inventory serving as the primary swing factor. Inventory days climbed from 286 days in March 2025 to 480 days in March 2026, which management attributed to customers shifting toward staggered procurement and higher upfront fermentation production, predicting a moderation across the first half of fiscal 2027.4 This represents management's most testable operational commitment. Elevated inventory will either convert into customer shipments in subsequent quarters, validating the explanation that fiscal 2026 reflected purchasing timing rather than structural demand destruction, or it will not. When asked on the fiscal 2026 earnings call where this timing recovery would manifest first, management confirmed that inventory reserves should convert into revenue during the first half of fiscal 2027.4
Reading the calls
Concord publishes full earnings call transcripts on its investor relations site, offering critical context where prepared comments and analyst Q&A diverge.22
Post-listing calls established the company's core baseline: historical top-line growth of roughly 18%, an 80-to-20 revenue split between APIs and finished formulations, and operating margins in the low forties. Management maintained consistent messaging across these parameters, even during operational downturns.
The June 1, 2026 call covering fiscal 2026 remains essential for evaluating management's communication during a down period. Prepared remarks disaggregated the performance shortfall into specific, verifiable drivers rather than generic macroeconomic headwinds. The subsequent Q&A contained a pivotal disclosure: full-year API performance was driven entirely by volume changes without pricing expansion, with total volumes contracting for the year.4 Management provided granular figures when pressed on Middle East tender values, injectables drag, capacity utilization, and working capital expansion.
The August 3, 2026 call covering the June quarter serves as a key counterweight, notable primarily for the analytical scope of investor questioning. Asked directly what drove wallet-share gains, management cited price. Questioned on how API revenue could more than double when primary unit utilization already hovered near 80%, management detailed operational adjustments. Finally, when asked which expansion initiative had earned priority management focus and what evidence would prompt a strategy correction, management stated that no market condition would trigger a retreat from any of the three new ventures — an assertion worth noting when evaluating capital allocation discipline.6
In future reporting periods, three core questions require monitoring: whether commercial contract manufacturing clients have formally signed for the injectables plant; whether any CDMO discussion has converted into commercial supply to support management's goal of scaling CDMO into a double-digit revenue contributor from its current 1% to 2% share; and how management deploys its expanding cash balance.6
III. Epilogue & Playbook Lessons
Return, finally, to the freezer in Dholka.
What Sudhir Vaid understood in 2000, and what most of his contemporaries missed, is that operational difficulty becomes an asset if a company can survive it. Indian pharma spent the two decades following 1991 liberalization racing into synthetic chemistry, where the science was tractable, capital requirements were modest, and returns were immediate. That race was won, and then lost, as low-cost Chinese capacity arrived and margins compressed toward commodity levels. Vaid acquired a shuttered enzyme plant carrying accumulated losses and directed it toward the one manufacturing process unpredictable enough to deter competitors.
Complexity as a moat has a specific mechanism and a clear limit. The mechanism is that tacit process knowledge — embedded in living organisms and held by teams with two decades of operating practice — cannot be bought off the shelf. That explains why only a handful of global suppliers maintain Drug Master Files across major regulated markets for these molecules, and why Concord commands double-digit global volume shares. The limit is that technical complexity protects a manufacturer solely from supply-side competition. It does not constrain buyers. Concord's customers — large generic formulators and government tender authorities — retain control over purchasing timing, volumes, and contract terms. Any investor assuming that operational complexity automatically yields pricing power need only examine the fiscal 2026 financial record.
Patient capital is a critical input, and it is rarer than it sounds. Concord's ownership sequence — a 2004 minority sale, a 2005 change of control, a 2007 parent acquisition, a 2009 management buyback, a 2016 private equity entry, and a 2023 public listing — shows a firm that shifted corporate structure repeatedly while its core biological project ran uninterrupted. That multi-decade strain development depended on an anchor shareholder willing to remain engaged with a private, illiquid, technically complex business across three separate ownership regimes. Few companies pursuing difficult fermentation models find such backing, making that patient capital structure less of a repeatable playbook than an alignment of rare circumstances.
Reclaiming control matters when a parent company's strategic agenda diverges. The buyback from Mylan proved advantageous not because multinational parents are inherently flawed owners, but because Concord's capital requirements were multi-year commitments while its revenue was immaterial to a global conglomerate. A niche business requiring years of upfront capital deployment before generating returns rarely thrives as a non-core unit inside a large income statement. The broader lesson lies in aligning asset duration with owner horizon, rather than celebrating founder conviction.
And what of the company today? Concord in 2026 is not the story it was in 2016. It is no longer a founder proving that fermentation can work in India — that thesis is established. It is now a mid-scale, cash-generative, low-debt manufacturer operating with roughly half its capacity idle, three early-stage expansion initiatives absorbing capital, a return profile below its historical highs, and a market valuation that prices in a prompt operational recovery. The engineering challenge has been solved. The remaining tests are commercial and financial: whether fermentation capacity utilization recovers, whether the injectables plant converts regulatory clearances into commercial contracts, and how management deploys an expanding cash reserve given its limited track record with large-scale capital allocation.
Those operational questions carry observable metrics, tracked quarterly by a management team that has consistently disclosed adverse performance details alongside positive developments. For a company built on biological processes that defy simple documentation, that reporting transparency remains its most dependable asset.
References
-
Concord Biotech Ltd – IPO Note, Equity Research Desk — FundsIndia, 2023-08 ↩↩↩↩
-
Concord Biotech Limited Investor Presentation – Q1 FY27 — Concord Biotech, 2026-08-01 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Concord Biotech Ltd — Consolidated Financials, Ratios and Shareholding — Screener.in ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Transcript of Q4 & FY26 Earnings Call held on June 01, 2026 — Concord Biotech, 2026-06-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Concord Biotech Limited — Rating Rationale — ICRA, 2019-01-25 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Transcript of Q1 FY27 Earnings Call held on August 03, 2026 — Concord Biotech, 2026-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Concord Biotech Limited: Ratings reaffirmed — ICRA, 2025-07-23 ↩↩↩↩↩↩↩↩↩↩
-
Concord Biotech Ltd Share Analysis — Congruence Advisers ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Quadria Capital completes successful exit of Concord Biotech through IPO — Quadria Capital, 2023-08 ↩↩↩
-
Concord Biotech Q4 Profit Falls 37% As Revenue And Margins Weaken, Board Recommends ₹7.55 Dividend For FY26 — The Free Press Journal, 2026-05 ↩↩
-
Concord Biotech Q3 FY26: Margin Pressure Persists Despite Revenue Recovery — MarketsMojo, 2026-02 ↩
-
Concord Biotech acquires 75% stake in Stellon Biotech — Capital Market, 2025-07-02 ↩↩
-
Concord Biotech acquires Celliimune to accelerate DNA-engineered cancer therapies — Indian Pharma Post, 2026-04 ↩↩
-
Concord Biotech invests USD 10 lakh in Palvella Therapeutics — The Week, 2024-12-12 ↩
-
Concord Biotech to Procure Wind-Solar Power from CleanMax's Project — Mercom India, 2025-01-17 ↩
-
Concord Biotech sets IPO price band at Rs 705-741 — Business Today, 2023-07-31 ↩↩↩
-
Concord Biotech IPO Makes Solid Debut, Lists At Rs 900 Per Share On BSE — Outlook Business, 2023-08-18 ↩↩↩
-
Concord Biotech shares: Jhunjhunwala-backed stock — Business Today, 2026-08-04 ↩
-
Intimation about completion of inspection by USFDA of API facility at Dholka — Concord Biotech, 2025-05-02 ↩
-
Concord Biotech Limited receives EIR from USFDA for API facility at Dholka — EquityBulls, 2025-06 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube