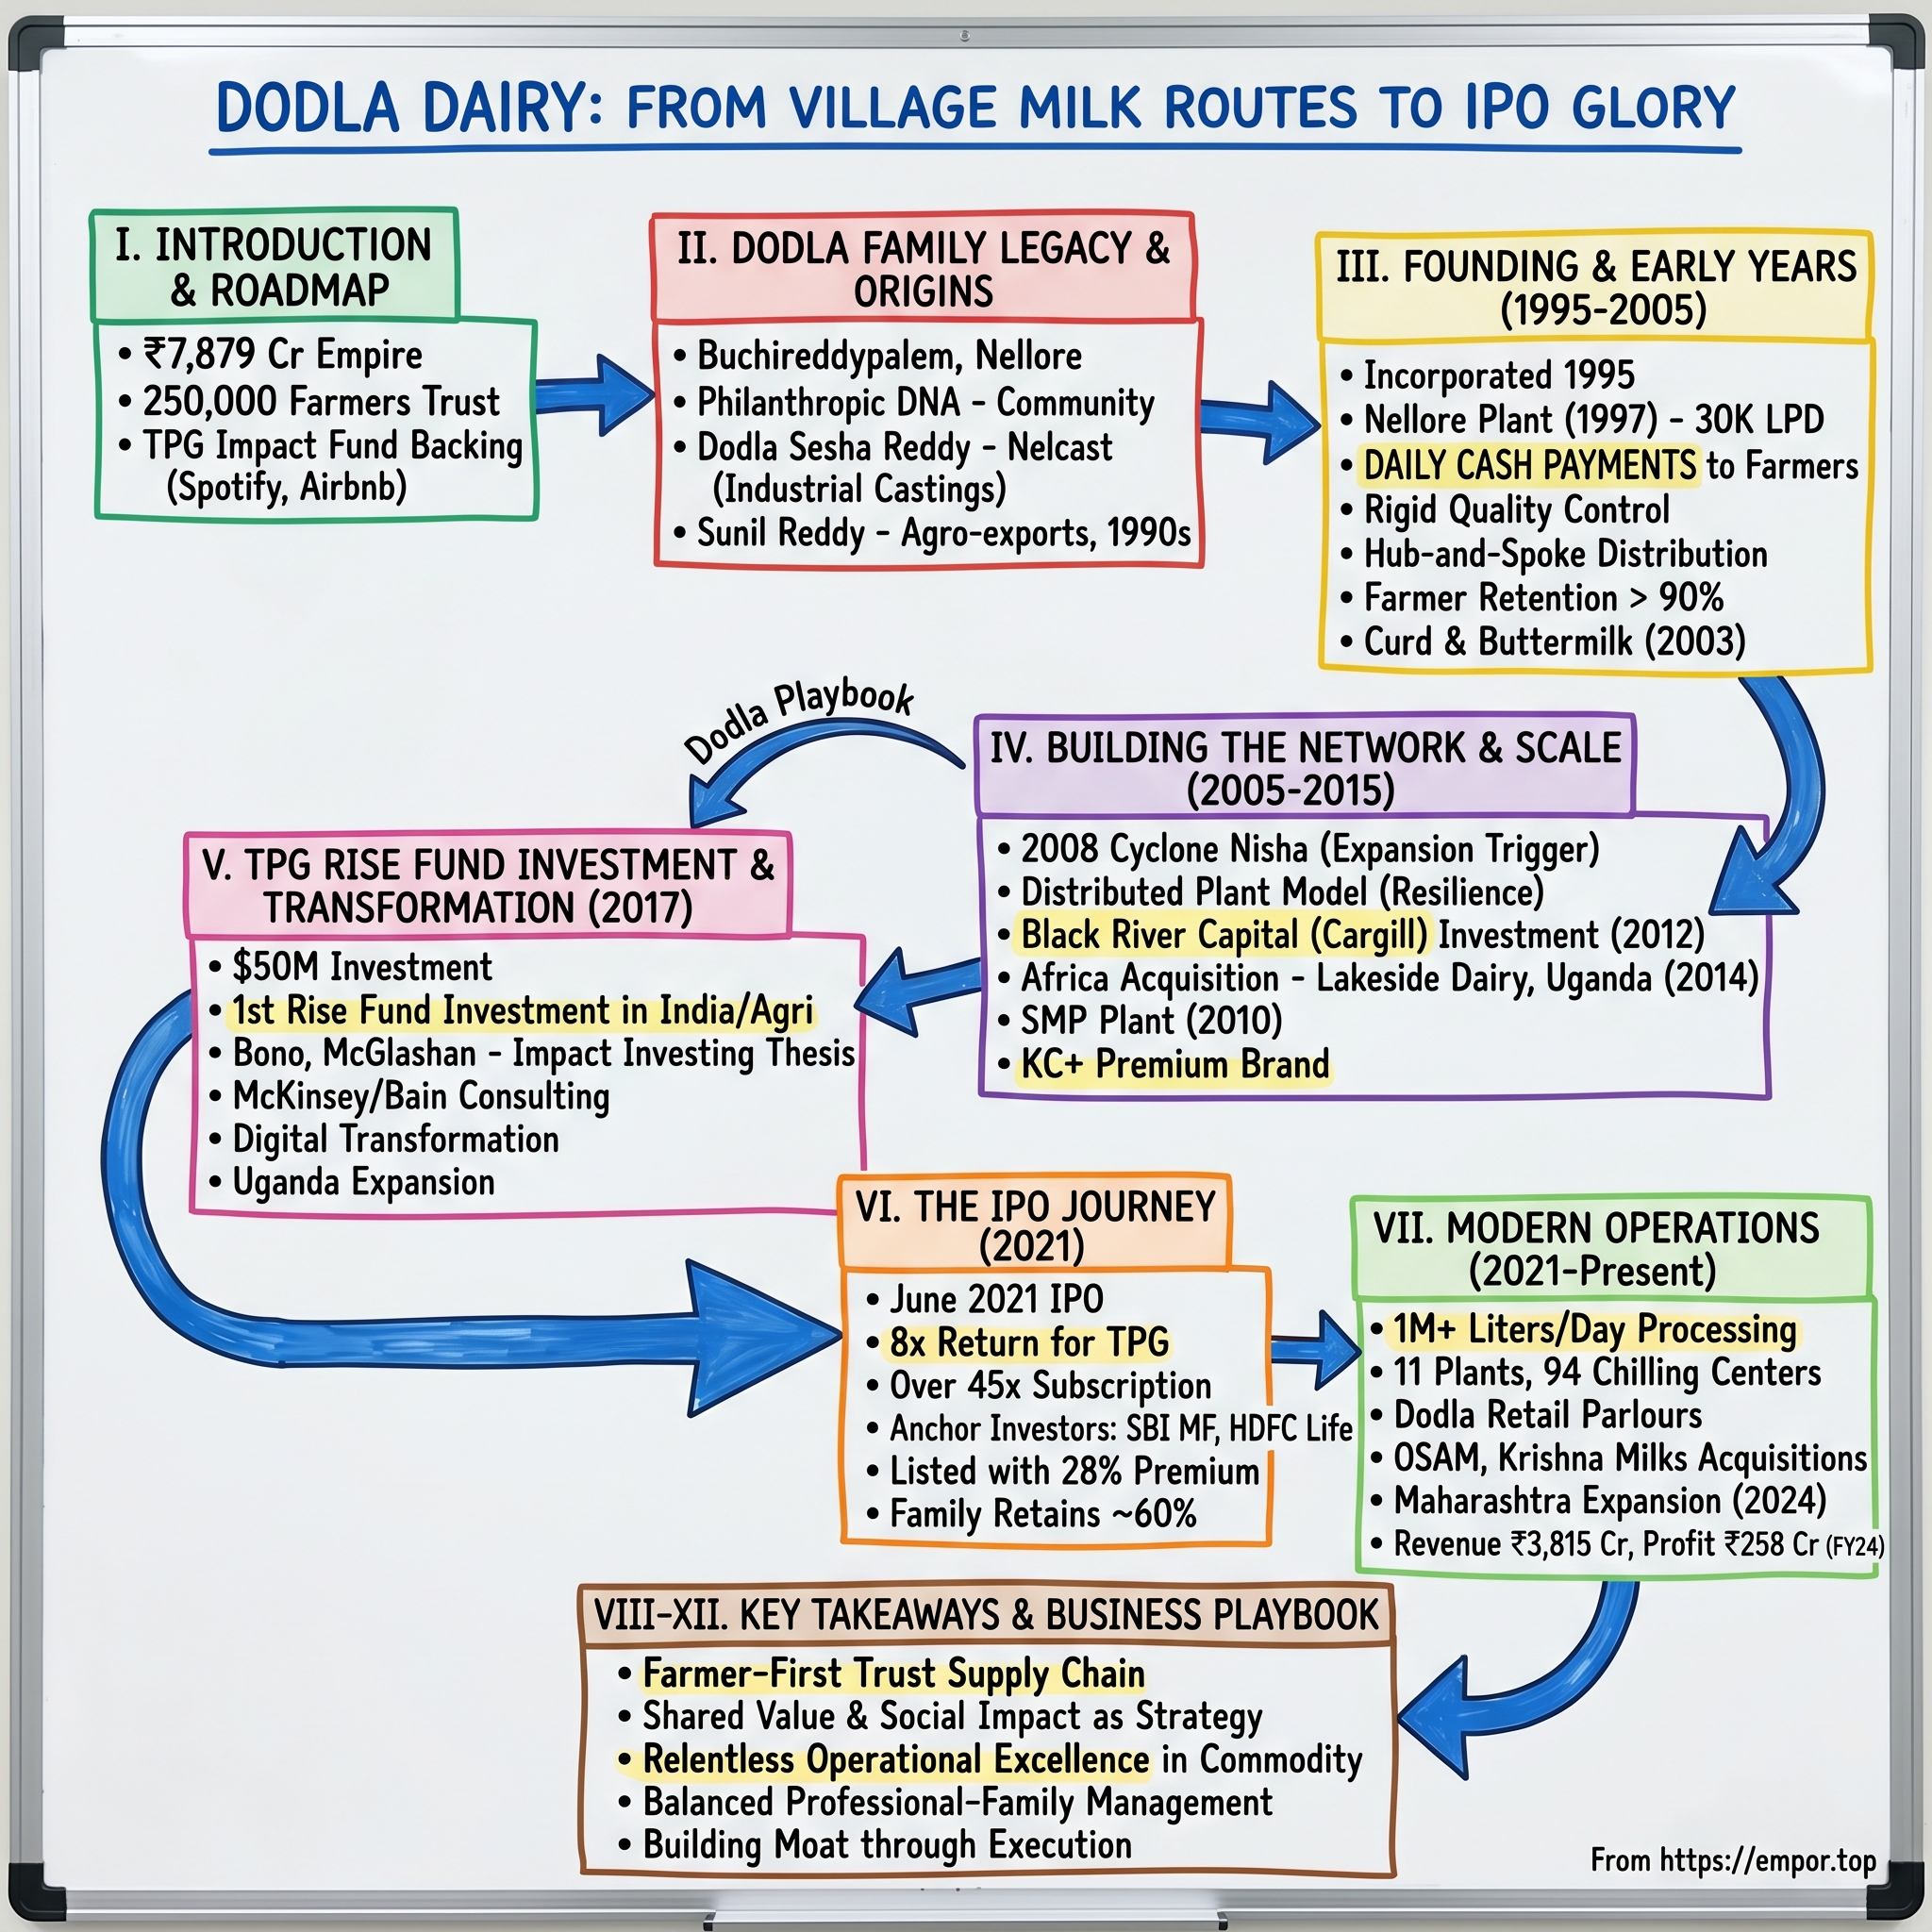
Dodla Dairy: From Village Milk Routes to Public Market Glory — The South Indian Dairy Revolution
I. Introduction & Episode Roadmap
On the morning of July 27, 2026, Dodla Sunil Reddy opened his company's quarterly earnings call with quarterly results three decades in the making. Revenue for the June quarter reached ₹1,198 crore—the highest in company history. Milk procurement hit a record 21.1 lakh litres per day, while value-added products reached a quarterly peak of ₹415 crore. Every headline operating metric reached an all-time high.[^1]
Yet the stock fell.
The reason appeared two lines further down in the same press release. EBITDA margin collapsed to 5.4% from 8.2% a year earlier. Net profit stood at ₹41 crore—down roughly 42% year on year, even as revenue grew 19%.[^1] CEO B.V.K. Reddy stated the underlying arithmetic plainly: Dodla was selling milk at ₹59.4 per litre while procuring it at ₹41.3 per litre, leaving a spread of ₹18.1 per litre compared to ₹19.8 twelve months earlier.[^2] Nearly the entire quarterly margin contraction stemmed from that ₹1.70 reduction in spread.
That single spread metric offers a candid introduction to the business. Dodla Dairy is an integrated dairy processor operating across eight Indian states and two East African countries, with 18 processing plants, approximately 1.4 lakh farmers supplying it directly in India, and consolidated revenue of ₹4,125 crore in the financial year ended March 2026.[^1][^3] It is net-debt-free, has compounded revenue at roughly 16% annually over four years, and completed three acquisitions over four years without borrowing.[^3] However, its annual profitability remains highly sensitive to monsoon timing and raw-milk price adjustments by state-subsidized cooperatives.
The core thesis worth examining over the following sections is whether Dodla has established a durable structural advantage in procurement rather than consumer branding, and whether it can convert that procurement strength into shareholder returns through a mix shift toward higher-margin value-added products, disciplined balance-sheet management, and expansion into East Africa and Eastern India.
Each part of that thesis requires separate scrutiny. The procurement capability is supported by thirty-one years of operating history, whereas the margin-expansion strategy has been disrupted twice by internal results within four years.
The narrative traces this trajectory from its origins. It begins in Buchireddypalem, a Nellore town settled by the founder's ancestors, where his father established an iron-casting business that introduced industrial discipline to the family. It moves to 1995 and the founding of Dodla Dairy by a 27-year-old engineer whose first three business ventures had failed. It examines the step-by-step construction of the cold chain through coastal Andhra Pradesh, the influx of private-equity capital—first Cargill's Black River fund in 2012, followed by TPG's Rise Fund in 2017—and how institutional ownership reshaped operations. It details the June 2021 initial public offering, oversubscribed 45.6 times, and clarifies the timing of TPG's eventual exit.
Before examining that history, three common misconceptions about the company require correction:
Myth: Dodla sources from more than 250,000 farmers. This figure appears frequently in older secondary coverage. However, the company's July 2026 disclosures confirm direct Indian procurement from approximately 1.4 lakh farmers across more than 8,700 villages.[^1] The verified lower figure indicates a higher milk yield per farmer relationship than the legacy estimate implied.
Myth: The 2021 IPO marked TPG's complete exit. The listing was a partial sell-down. TPG retained a near-10% stake a full year after listing and continued executing block sales through 2022 and 2023.9 Any model of post-listing share price performance must account for this persistent supply overhang.
Myth: Dodla's acquisition playbook is asset-light and easily repeatable. Three of its four historical acquisitions were small, local, and low-cost. The fourth deal was five times larger, located 1,700 kilometers away, and currently generates roughly one-third of the group's profit margin.[^3] The playbook's track record at meaningful scale rests on a single data point.
From there, the analysis turns to the modern operating record: the transition into value-added products and its actual financial impact. It examines the acquisition strategy, ranging from a ₹50 crore slump purchase in Karnataka to a ₹271 crore expansion into Bihar and Jharkhand—a transaction that generated ₹131.6 crore of goodwill on the balance sheet and prompted auditors to highlight two key audit matters in FY26.[^4] The business is evaluated through Hamilton Helmer's 7 Powers and Porter's Five Forces, stress-testing the investment thesis against filings evidence—including the fact that margin contractions in FY23 and FY26–27 stemmed from identical underlying cost pressures three years apart.
Finally, the section outlines the specific operational metrics investors should track and the key risk factors that could undermine the core investment thesis.
 Subscribe on LinkedIn
II. Family Origins & The Nellore Roots
There is a temple town about twenty kilometres from Nellore, in coastal Andhra Pradesh, called Buchireddypalem. It was settled in the eighteenth century by the ancestors of the Dodla family, who came as farmers and stayed as landowners and, eventually, as the local philanthropic establishment. Sunil Reddy's grandparents built the first women's college in Nellore, along with schools and hospitals.1 In a region where a family's reputation travels faster than any advertisement, that history mattered — not sentimentally, but commercially. When a Dodla later showed up in a village asking farmers to hand over their milk on the promise of payment in ten days, the name was already collateral.
The industrial precedent came from Sunil Reddy's father. Dodla Sesha Reddy founded Nelcast Limited, a manufacturer of ductile and grey iron castings — cylinder blocks, housings, rear hubs, brackets, exhaust manifolds — supplying India's commercial-vehicle industry from a plant in Gudur, an hour down the coast.2 Castings are an unglamorous business with punishing tolerances: a foundry must hit exact metallurgical specifications on every run or lose the client. It was a useful environment for a son to observe, because dairy shares that uncompromising operational character. Milk is either chilled within hours at the correct fat and solids-not-fat percentages, or it spoils.
Sunil Reddy earned an industrial engineering degree from Manipal Institute of Technology in 1990.1 What happened next is the part of the founding story that usually gets edited out of investor presentations, yet it remains the most revealing.
He tried mushroom cultivation. It failed. He tried exporting mangoes to Singapore. It failed. He tried to set up a textile manufacturing unit and could not raise the money.1 He spent time in the family's civil construction business and disliked it.
By 1995, he was 27 years old with an engineering degree, an established family name, and a track record of three commercial failures. The idea that finally worked did not come from him. It came from his father-in-law, M.S. Reddy, a dairy scientist, who suggested the sector.1
That detail matters when evaluating the founder. Dodla Dairy was not the product of a visionary who foresaw the future of Indian protein consumption. It was the fourth attempt by a persistent operator who was pointed toward a promising industry by a technical expert, and who subsequently executed within it for three decades without diversifying away.
Serial early failure is often framed as evidence of grit. A more analytical reading is narrower: mushrooms, mangoes, and textiles were all businesses where Reddy possessed no structural advantage. Dairy in coastal Andhra Pradesh was a business where his family's name, his father's industrial credibility, and his father-in-law's technical expertise all converged. The lesson is about aligning a venture with institutional and network advantages, rather than sheer persistence.
The company's investor materials describe its edge in unglamorous terms: "All dairy processors have access to the same raw material and equipment; what distinguishes us is our dedicated employees and our strong relationship with farmers."[^1] That is not a moat statement; it is an execution statement — and whether execution alone constitutes a durable advantage remains central to evaluating the business.
The choice of geography represented genuine strategic insight. Coastal Andhra Pradesh in the mid-1990s combined two factors: abundant milk-producing households scattered across dense agricultural villages, and urban centres reliant on informal middlemen with no accountability for quality or adulteration.
That gap formed the market opportunity. Urban consumers paid for milk of unknown provenance and dilution, while rural producers depended on traders who dictated both price and quality assessments. A processor capable of honest measurement at procurement and reliable distribution at retail could capture margin from middlemen at both ends simultaneously.
Dodla Dairy Limited was incorporated in 1995 with roughly ₹9 crore assembled from Sunil Reddy's father, IDBI Bank, and venture capital firm Ventureast — a capital structure that, from inception, combined family equity with institutional backing.1
Ventureast founder Sarath Naru later attributed the outcome to "smart operations and backing the right people," with a "watertight supply chain" as the operating result.1
The company was launched out of Chennai, before moving its headquarters to Hyderabad in 2006.1 Its initial processing facility, however, was built back home in Andhra Pradesh.
III. Founding Dodla Dairy & Early Infrastructure (1995–2005)
Dodla commissioned its primary processing plant in Nellore in 1997.[^1] In its first full year of operations, the plant sold approximately 30,000 litres of milk per day.1 To put that initial volume in perspective, the modern business procures roughly seventy times that daily volume across its network.
The central challenge the plant addressed was time rather than manufacturing capacity.
Raw milk degrades within hours of milking, and rural Andhra Pradesh in the late 1990s suffered from an unreliable power grid. Operating in that environment required managing cold-chain logistics under severe infrastructure constraints. The operational model Dodla developed over the following decade answered a single practical question: how to move milk from smallholders owning two or three cows or buffaloes, in villages without continuous electricity, into chilled storage before spoilage occurred.
The solution was a hub-and-spoke model: village-level collection centers feeding regional chilling centers, which in turn supplied central processing plants. In this system, the collection radius served as the critical operational variable. Rapid chilling preserved milk quality, whereas delays resulted in discarded product.
Each chilling center reduced the effective collection radius within its catchment area. Shorter transport distances brought additional villages within economic reach, expanding the farmer supplier base and increasing processing capacity utilization. Managing Director Sunil Reddy's operational target has remained constant: processing and delivering milk to retail markets within 24 to 36 hours of collection.1
Establishing mutual trust was the second operational requirement. Historically, unorganized traders controlled rural dairy procurement, frequently undercounting fat content to lower payouts to farmers while diluting liquid milk before selling to urban consumers.
Dodla replaced discretionary quality assessments with automated measurement. It equipped village collection centers with digital scales and electronic analyzers to test fat and solids-not-fat (SNF) content, establishing formulaic payouts based on objective metrics.[^1]
Fat and SNF represent the core pricing components of commercial dairy. Because dilution reduces both metrics, displaying automated scanner readings directly to farmers on printed slips removed quality disputes at the point of collection.
That procurement network has expanded to 7,691 village-level collection centers. The company reports that raw milk undergoes digital testing across 100% of its collection centers and plants, supplemented by an automated scanner at its Hyderabad facility capable of running 26 adulterant checks.[^1] Milk entering chilling centers and processing plants undergoes secondary testing for chemical contaminants and neutralizers.[^1]
Direct settlement terms reinforced the procurement architecture. Payouts deposited directly into bank accounts on a 10- to 15-day cycle provided essential liquidity for agricultural households. Management continues to monitor payment digitization closely: direct bank transfers covered approximately 93% of total farmer payouts in the quarter ended March 2026,[^1] while Sunil Reddy noted on the first-quarter FY27 earnings call that direct payments reached nearly 100% after accounting for minor technical exceptions.[^2] The small variance between overall payment volume and total participating farmers indicates that bank-transfer integration is widespread, though not fully universal.
Dodla's growth during the early 2000s combined greenfield construction with opportunistic asset purchases. The most instructive transaction of this period occurred in 2001, when the company acquired a subscale facility in Chittoor for ₹40 lakh. That plant generated approximately ₹1.5 crore in cash flow over the following two years, enabling the company to retire its early debt.1
The rapid payback reflected broader market conditions across southern India, where underutilized dairy facilities were available at distressed valuations due to a lack of integrated procurement networks. Once connected to Dodla's established collection infrastructure, the facility achieved immediate volume utilization.
This transaction established an acquisition template the company repeated in later years: acquiring distressed or underutilized regional assets at low valuations rather than absorbing the gestation costs of greenfield builds. This playbook subsequently guided the acquisitions of KC Dairy, Sri Krishna Milks, and OSAM.
By 2007, Dodla added processing facilities in Badvel and Sattenapally, followed in 2009 by a milk powder and skimmed milk powder (SMP) plant in Nellore.[^1]
The SMP facility addressed the structural seasonality of Indian dairy procurement. Milk production peaks during the winter "flush" months and declines during the summer "lean" season. A processor lacking powder conversion capacity must either turn away surplus milk during peak months—damaging farmer relationships—or accept excess volume without a commercial outlet.
Converting surplus liquid milk into powder created a shelf-stable product for storage, trade, or later reconstitution. While providing an operational buffer for the procurement network, SMP also represented a low-margin bulk commodity line that Dodla would later work to minimize as it shifted focus toward higher-margin consumer products.
Alongside physical infrastructure, executive continuity proved central to operational execution. B.V.K. Reddy, who led commercial operations, and Krishna Reddy, who managed procurement, both joined the business near its founding and remained in senior leadership for three decades.1 In a business dependent on field relationships across thousands of villages, stability within the procurement organization served as a stabilizing factor.
By the mid-2000s, Dodla had built a functional regional procurement and distribution network. Expanding further required institutional capital, geographic diversification, and formal corporate governance.
IV. Scaling the Cold Chain & International Optionality (2005–2016)
Between 2005 and 2016, Dodla Dairy transitioned from a regional family business into an institutional processor—a decade also marked by an unconventional expansion into Uganda.
Operational expansion during this period followed a consistent path: expanding village collection networks, chilling capacity, and processing facilities across Andhra Pradesh, Telangana, Karnataka, and Tamil Nadu, including plants at Gundrampally, Hyderabad, Chendurthi in East Godavari, and Rajahmundry.[^1]
The company also pursued selective acquisitions, purchasing two processing plants from KC Dairy Products and launching Orgafeed—a cattle-feed venture built around an acquired feed-mixing plant—to support farmer integration and secure raw milk procurement.[^1]
By the end of this period, Dodla had established a strong regional footprint without achieving national scale. As of 2018, it ranked as the largest private dairy in Karnataka, third in Tamil Nadu behind Heritage and Thirumala, and fourth in Andhra Pradesh behind Hatsun Agro, Thirumala, and Heritage—competing against private peers as well as state cooperatives Nandini, Aavin, and Vijaya.1 This market ranking illustrates that Dodla was not the leading private dairy in most of its core home markets.
Institutional capital arrived in 2012 when Black River Capital Partners (Food) Fund Holding, the private equity arm associated with Cargill, invested approximately ₹110 crore for a 23.66% stake.1[^1] Dodla’s disclosures note that Black River was subsequently renamed Proterra after spinning out from Cargill.[^1]
Management noted that much of the raised capital remained undeployed, with the primary benefit residing in governance: "They helped us professionalise the company," Sunil Reddy later observed.1 For a family-managed business, institutional investment introduced formal audit standards, board oversight, and structured accountability.
In 2014, Dodla made an unexpected international move by acquiring Lakeside Dairy in Mbarara, Uganda, for approximately ₹14.5 crore and establishing an adjacent large-scale dairy farm.[^1]1
A mid-sized Indian dairy processor with no prior international experience, local management bench, or East African distribution network bought an overseas processing plant for less than the cost of a domestic greenfield facility. By FY18, four years after the acquisition, the African operations contributed roughly ₹32 crore to consolidated revenue of ₹1,597 crore—remaining a minor component of total operations for several years.1
The strategic rationale rested on regional fundamentals: East Africa offered extensive grazing land, substantial cattle herds, low-cost raw milk, and minimal organized processing capacity. Dodla's investor disclosures emphasized the margin potential, noting that African dairy margins ran higher "due to limited competition and constrained supply of processed milk."[^1]
The company introduced brands including Dairy Top, Dodla +, and Pride of Cows, later expanding into Kenya through Dodla Dairy Kenya and Country Delight Dairy alongside a new Kenyan processing facility.[^1] Sunil Reddy framed the initiative expansively, stating, "wherever there is a viable opportunity, we will go there," and declaring that "the world is our oyster."1
Evaluating the Africa expansion against operational results shows a multi-year gestation period. Sunil Reddy characterized it on the May 2026 earnings call as a twelve-year effort: "The decision that we took 12 years ago to extend our footprint in Africa has now become an important engine for long-term growth of the company."[^3] Financial disclosures confirm this trajectory. Africa generated ₹504 crore in revenue in FY26, up 33% year on year, with EBITDA reaching ₹57.2 crore and an EBITDA margin of 11.3%—exceeding the consolidated company's 7.5% margin.3[^3] In the June 2026 quarter, African operations reported record quarterly revenue of ₹154 crore, up 45.6%, and EBITDA of ₹24 crore, up 74%.[^1]
This performance trajectory clarifies several aspects of the segment. The expansion operated subscale for nearly a decade before generating substantial returns. Furthermore, recent growth has been driven primarily by Kenya rather than Uganda. Ugandan procurement remained flat at 1.45 to 1.50 lakh litres per day across FY25 and FY26, with volume gains originating in Kenya.[^3] Management holds an estimated 50% market share in Uganda's long-life milk and yogurt categories—a leading position in a smaller market—compared to a 2% to 3% share in Kenya, which represents the larger addressable market.[^2]
Africa has transitioned from a speculative venture into a profitable segment generating approximately 10% of total revenue, with continued growth potential in Kenya. However, management disclosures reflect varying projections regarding its ultimate share of business. Asked about the three-year outlook, Sunil Reddy stated Africa would "continue to be in the same trajectory of 10%" of revenue due to simultaneous growth in India, after having suggested a 15% to 18% contribution by FY28 on an earlier call.[^2][^3] Operational progress depends on processing capacity utilization; by mid-2026, Kenyan procurement reached approximately 80% of its 1.5 lakh litre daily capacity.[^2]
With institutional backing, an established East African operational base, and expanded regional procurement in India, the stage was set for subsequent institutional investors to accelerate growth.
V. The TPG Rise Fund Investment & Transformation (2017–2020)
In May 2017, TPG announced that its newly launched global impact vehicle, The Rise Fund—managed by TPG Growth—had agreed to invest $50 million in Dodla Dairy.4 The transaction structure was significant: this was secondary capital rather than fresh equity injected directly into operations. TPG Dodla Dairy Holdings acquired the entire 23.66% stake held by Black River,5 allowing Proterra to fully exit its investment.[^1] Consequently, the capital influx provided liquidity to an outgoing private equity backer rather than funding new chilling centers or processing capacity directly.
The Rise Fund's core thesis viewed Dodla's direct smallholder procurement network as a rural livelihoods platform as much as a commercial dairy business. This perspective aligned commercial priorities with impact objectives: expanding direct procurement, improving payout reliability, and deepening supply relationships served both the impact mandate of raising smallholder incomes and the commercial goal of securing raw milk supply. Unlike traditional impact investments that require trade-offs between social goals and financial returns, Dodla's operational agenda focused heavily on strengthening procurement infrastructure without generating strategic friction between management and institutional investors.
The operational changes during the TPG tenure centered on managerial structure and procurement technology.
First, leadership responsibilities were formally divided. B.V.K. Reddy, a long-serving executive with the company since near its inception, was installed as Chief Executive Officer alongside Managing Director Sunil Reddy—establishing a leadership partnership that has directed operations for nearly a decade.1[^2]
Second, Dodla upgraded its field infrastructure. The company deployed GPRS-enabled electronic milk analyzers at village collection points, established veterinary support networks for herd health, and facilitated bank loans for farmers to purchase cattle.[^1]
Third, Dodla expanded its integrated cattle-feed subsidiary, Orgafeed. The business scaled into a two-plant operation producing 480 tonnes per day, selling directly to Dodla's supplier network with the cost adjusted against the value of the milk delivered.[^1]
By financial year 2018, the expanded operational footprint supported a daily processing capacity of 10.2 lakh litres. The network collected milk from approximately two lakh farmers across four southern states through 66 chilling stations feeding 11 processing plants, generating ₹54.3 crore in net profit on ₹1,597 crore in revenue.1 The resulting net margin of roughly 3.4% underscored the financial reality of liquid milk processing at the time: operating volume alone provided modest profitability, leaving future margin expansion dependent on shifting the product mix toward higher-margin items.
The feed-deduction mechanism created a reinforcing operational loop. Farmers obtained quality feed without upfront cash outlay, while Dodla secured higher supply volumes and improved supplier retention. On its July 2026 earnings call, management disclosed that farmers using Dodla cattle feed averaged approximately 14 litres of milk per day, compared to roughly 11 litres for non-Dodla-feed suppliers.[^2] While this management-reported metric is not an audited study and may reflect self-selection among more commercially oriented farmers, it illustrates how integrated input supply can strengthen procurement loyalty against competing cooperatives.
Simultaneously, Dodla began prioritizing value-added products to alter its unit economics. Liquid milk functions essentially as a pass-through commodity where gross margin depends entirely on the spread between raw milk procurement costs and retail realizations—two variables heavily influenced by external market forces. Processing raw milk into curd, paneer, ghee, flavored milk, lassi, or ice cream allows the company to capture higher manufacturing margins and build consumer brand equity.
By FY22, the first full financial year following its public listing, value-added products represented a substantial share of total sales, subsequently compounding at approximately 20% annually over the FY22–FY26 period.[^1] This consistent volume growth in value-added offerings has served as a primary driver of structural revenue expansion.
TPG's ownership approach was notably conservative in scope. The firm did not alter promoter control, launch expensive national branding campaigns, or attempt to reposition Dodla into premium urban retail channels. Instead, institutional capital reinforced the existing business model—improving operating discipline, digitalizing procurement, and expanding capacity.
By 2020, Dodla operated 11 processing plants with a clean balance sheet and an institutional investor holding nearly a quarter of its equity seeking an exit route.
VI. The 2021 IPO & Public Market Debut
The Dodla Dairy initial public offering opened for bidding on June 16, 2021, and closed on June 18—a period when Indian equity markets were experiencing an unprecedented primary-issuance boom, driven by record retail participation following the second wave of COVID-19.
The transaction structure clearly reflected the offering's primary purpose. Of the total ₹520 crore issue, fresh equity capital accounted for just ₹50 crore, or roughly 11.68 lakh (1,168,224) shares, while the remaining ₹470 crore comprised an offer for sale by existing investors.6
The stated allocation of the fresh proceeds was modest and targeted: approximately ₹32.26 crore for repayment or prepayment of bank borrowings from ICICI Bank, HSBC, and HDFC Bank, about ₹7.15 crore for capital expenditure, and the balance for general corporate purposes.6[^11] For a company generating nearly ₹300 crore in annual operating cash flow within five years, allocating roughly ₹32 crore to debt retirement represented balance-sheet housekeeping rather than growth financing. Dodla did not list to fund physical expansion; it went public to provide liquidity for its private-equity sponsor and to establish a publicly traded stock currency for future acquisitions.
Despite the modest primary raise, public demand was overwhelming. The issue was subscribed 45.61 times on its final day, generating bids for 38.80 crore shares against 85.07 lakh shares on offer.7 After fixing the issue price at ₹428, the stock debuted on June 28, 2021, listing at ₹550 on the National Stock Exchange—a 28% premium—opening at ₹528 on the Bombay Stock Exchange, and reaching an intraday high of ₹588.95, roughly 38% above the issue price.8
That high subscription multiple reflected market liquidity rather than company-specific conviction. Similar oversubscriptions occurred across diverse issuers during that market cycle, where the modest ₹520 crore issue size allowed even modest institutional capital flows to produce dramatic subscription multiples.
Contrary to secondary accounts framing the IPO as a complete private-equity exit, TPG retained a substantial stake following the listing, holding 9.80% at the end of the June 2022 quarter. In September 2022, TPG Dodla Dairy Holdings sold approximately ₹193 crore worth of shares through open-market transactions at an average price of around ₹509 per share. A further 6.7% block was placed at ₹509 per share with institutional buyers, including Steinberg India Emerging Opportunities Fund, White Oak Capital, and Plutus Wealth Management.9
This secondary trajectory carries two key implications. First, it demonstrates that a persistent supply overhang weighed on the stock throughout 2022, while confirming that the block buyers were long-only institutional investors rather than short-term traders. Second, TPG’s secondary sale price of around ₹509—modestly above the ₹428 issue price and well below the initial listing peak—indicated that early market enthusiasm was not sustained by underlying performance in the eighteen months post-listing, a period that coincided with the margin contraction of FY23.
A notable institutional legacy of the TPG era persists on Dodla's board. Akshay Tanna, initially appointed to the board on July 21, 2017, as the investor’s nominee, continues to serve as a Non-Executive Non-Independent Director, even after transitioning to head KKR's India private equity business following more than thirteen years at TPG.[^4] While retaining a director originally nominated by a legacy private-equity shareholder is compliant with governance rules, it highlights a structural board arrangement where the specific shareholder constituency represented is no longer active in the capital structure.
Following its listing, Dodla entered the public market debt-light, cash-generative, and fully valued—faced for the first time with quarterly public disclosures and reporting scrutiny.
VII. Modern Operations, Segment Data, & The VAP Pivot (2021–Present)
Behind the narrative, Dodla Dairy in September 2026 operates as a precise physical system. Dissecting its actual operational footprint is essential, as widely circulated figures often lag behind current disclosures.
In its core standalone domestic market, Dodla procures raw milk directly from approximately 1.4 lakh farmers across more than 8,700 villages via 7,691 collection centres. The milk moves through 905 primary vehicles to 240 chilling centres, before reaching 14 processing plants across southern India. These plants offer a combined capacity of 22.0 lakh litres per day and operate at 65.8% utilisation. Distribution relies on 46 sales offices, over 1,850 distributors, more than 2,950 agents, 138 modern trade accounts, and 1,020 company-owned retail parlours.[^1]
In Eastern India, the acquired HR Food Processing entity—operating as OSAM—contributes approximately 1.2 lakh litres per day in procurement across 101 villages and 1,100 dairy farms. Supported by 20 chilling centres, OSAM feeds two processing facilities in Bihar and Jharkhand, which have a combined daily capacity of 2.2 lakh litres running at 64.0% utilisation, distributed across 42 districts through more than 640 distributors.[^1] Internationally, the African division processes 2.6 lakh litres per day sourced across 60 villages and 840 dairy farms, backed by 13 chilling centres and two processing plants with 4.5 lakh litres of daily capacity at 57.1% utilisation.[^1]
Three operational observations emerge from this footprint. First, processing capacity utilisation across all regions sits between 57% and 66%, indicating that physical infrastructure can absorb several years of volume expansion without requiring immediate, heavy capital expenditure. Second, the network demonstrates clear operating leverage: while the number of village collection centres remained flat over five years—moving from 7,837 in FY22 to 7,691 in FY26—procurement volume expanded from 12.2 lakh to 18.8 lakh litres per day.[^1] Generating higher volumes through an established collection footprint provides concrete evidence of density-driven efficiency in procurement.
The financial results, however, present a far more volatile picture than the physical infrastructure suggests.
Consolidated revenue expanded from ₹2,243 crore in FY22 to ₹4,125 crore in FY26, representing a compound annual growth rate of roughly 16%.[^1] Profitability, however, experienced notable fluctuations. EBITDA margins swung from 9.4% in FY22 down to 6.8% in FY23, before recovering to 9.2% and 10.2%, and then compressing to 7.5% in FY26. Net profit tracked a similar path, moving from ₹133 crore to ₹122 crore, rising to ₹167 crore and ₹260 crore, and reaching a headline ₹267 crore in FY26.[^1] While top-line growth followed a steady upward slope, net earnings behaved more like a rollercoaster. That divergence was driven primarily by gross margin volatility, which fluctuated between 27.5%, 23.9%, 27.4%, and 25.6% over the five-year span.[^1]
The reported FY26 net profit includes a substantial non-operational adjustment. Of the ₹267 crore reported net profit, approximately ₹70 crore stemmed from one-off tax benefits, comprising ₹58.7 crore in prior-year tax credits following a favourable Income Tax Appellate Tribunal ruling and around ₹10 crore in associated interest income. Chief Financial Officer Murali Mohan Raju quantified the underlying operational result on an earnings call: "Adjusted FY '26 PAT is therefore approximately INR215 crores with an adjusted PAT margin of around 5.2%. This is the clean baseline against which FY '27 should be evaluated."[^3]
Volunteering an adjusted baseline provides helpful transparency, but it also underscores the extent of operational earnings pressure. On an adjusted basis, net profit fell by approximately 17% year on year in FY26, even as revenue grew 10.9%.
The transition toward value-added products (VAP) has delivered growth, though headline mix percentages require careful interpretation. Value-added revenues reached ₹414.7 crore in the June 2026 quarter, accounting for 34.6% of total sales compared to 35.0% in the prior-year period.[^1] While the total share appears unchanged, the prior-year comparative included ₹57.7 crore in commodity bulk sales of skimmed milk powder and butter. Excluding bulk commodity trades, consumer value-added products expanded their share of revenue from 29.3% to 34.6%—representing a 40.6% like-for-like revenue increase.[^1][^2] Volume expansion was led by curd and curd-based items, which grew 41.4% year on year to reach a record 642.6 metric tonnes per day.[^2]
Exiting the bulk commodity business represents a central operational shift. Annual bulk sales dropped from ₹313 crore in FY25 to ₹86 crore in FY26 as Dodla redirected liquid milk into branded consumer lines rather than commodity conversion.[^1] However, this portfolio shift was shaped by supply limitations as well as commercial choice. Managing Director Sunil Reddy acknowledged on the May 2026 earnings call that lower milk yield across the industry constrained surplus processing: "we don't have the extra butter that we produce," adding that the firm had temporarily become a net purchaser of skimmed milk powder.[^3] The reduction in bulk sales thus reflects both a strategic pivot toward consumer branding and raw-milk availability constraints during low-yield cycles.
Management has established a target range of 32% to 34% for value-added products as a share of total revenue.[^3] With the current mix already sitting at 34.6%, further margin expansion cannot rely solely on portfolio rebalancing. Instead, sustained margin improvement remains tied to the normalization of raw milk procurement costs—a factor largely governed by external market conditions and agricultural cycles.
Two supplementary initiatives illustrate management's operational priorities. The cattle-feed subsidiary, Orgafeed, expanded revenue by 23.2% in FY26 and 25.9% in the June 2026 quarter, maintaining EBITDA margins near 10.5%. However, management absorbed rising raw-material input costs rather than passing price increases to farmers, choosing "to sustain long-term relationship" with its procurement base.[^2][^3] Absorbing inflation within feed operations serves as an indirect cost of maintaining farmer retention. Additionally, in July 2026, the board authorized an ₹11.65 crore primary investment for an approximate 2% equity stake in Sids Farm, a premium direct-to-consumer dairy brand. Sunil Reddy described the stake as an observational entry to "keep a closer watch on how the modern high-value the D2C products behave."[^2] Given Dodla's cash balance of ₹689 crore, the ₹11.65 crore allocation functions as an exploratory market monitoring investment rather than a strategic expansion.[^2]
Overall, Dodla has built an efficient procurement and processing infrastructure across its markets. Yet its financial productivity remains vulnerable to raw-milk cost volatility and agricultural supply dynamics that lie beyond immediate operational control.
VIII. The M&A Playbook: Benchmarking Strategic Acquisitions
Dodla's acquisition strategy was historically modest and localized until 2025, when the company executed a transaction nearly five times larger than any previous deal—entering a market 1,700 kilometres from its core South Indian footprint and drawing specific scrutiny from statutory auditors.
The foundation for Dodla's expansion template was established through smaller regional transactions. In March 2022, Dodla signed a business transfer agreement with Sri Krishna Milks Private Limited to acquire the business as a going concern on a slump-purchase basis for ₹50 crore in cash.10 Sri Krishna, incorporated in 1989, had operated as Karnataka's first private-sector dairy processor, recording a turnover of ₹67.27 crore in FY21—valuing the acquisition at roughly 0.74 times sales.10 The strategic value was geographic: securing an established brand and procurement footprint in northern Karnataka and adjacent markets without incurring the two-to-three-year gestation period of a greenfield entry. Equity markets responded favorably, sending the stock up 19% following the announcement.
That transaction, along with earlier plant purchases from KC Dairy, generated goodwill that remains on the balance sheet. In testing for impairment as of March 31, 2026, management concluded no write-downs were required for either asset.[^4] Across its pre-2025 dairy acquisitions carrying goodwill, Dodla has maintained a clean record without recognizing impairment losses through FY26.
That baseline was tested on July 11, 2025, when the board approved the 100% acquisition of HR Food Processing Private Limited for ₹271 crore—comprising an enterprise value of ₹247.2 crore plus net cash of ₹23.8 crore—with no regulatory approvals required.11 Founded in 2010 and backed by impact investors, HR Food recorded turnover of ₹282.6 crore in FY25 while operating the OSAM brand across Bihar, Jharkhand, and West Bengal.12 The transaction closed with effect from August 1, 2025.[^1]
The strategic ambition was clear: transition from a South Indian regional operator into a multi-regional player by acquiring an established brand and collection network rather than building from scratch in an unfamiliar milk shed. At roughly 0.96 times trailing sales, the purchase price exceeded the Sri Krishna multiple but remained reasonable for a business with strong brand equity and a distribution network spanning 42 districts.
The financial composition of the transaction highlights where operational risk resides. Dodla accounted for the acquisition under Ind AS 103, recognizing goodwill of ₹131.63 crore on total consideration of ₹271.0 crore.[^4] On the July 2026 earnings call, management clarified that intangible assets comprised approximately ₹100 crore in goodwill and roughly ₹150 crore in brand value. Because reported profitability reflects purchase price allocation effects such as brand amortization, management noted that "the underlying profitability runs ahead of the reported figures."[^2] Total consolidated goodwill stood at ₹183.2 crore as of March 31, 2026.[^4]
Dodla's statutory auditors, S.R. Batliboi & Associates LLP, identified two Key Audit Matters in the consolidated FY26 financial statements: the impairment assessment of goodwill and the business combination accounting for OSAM. On the acquisition accounting, the auditors noted that the exercise "is complex and judgmental due to the use of subjective assumptions in the valuation model used by management when determining their estimated fair value," with fair value estimates for tangible and intangible assets "sensitive to changes in assumptions for projected revenue growth rates and discount rate."[^4] While the audit opinion was unqualified and no fraud was reported under Section 143(12), the key audit matters emphasize that roughly ₹250 crore of the consolidated balance sheet remains dependent on OSAM's projected cash flows.[^4]
Evaluating whether this acquisition playbook transplants cleanly requires examining early operational results. During the eight consolidated months of FY26, OSAM contributed ₹214.7 crore in revenue and ₹4.8 crore in EBITDA—a margin of about 2.2%, compared to the group's 7.5% consolidated margin. In the March 2026 quarter, OSAM recorded revenue of ₹81.9 crore and EBITDA of ₹2.7 crore.[^3] Gross margin at OSAM hovered near 21% against roughly 25.6% for the consolidated group, with Sunil Reddy stating it "will move up to the 25% soon."[^3][^1] Asked about the timeline for margin convergence, management initially projected six to twelve months for existing operations to reach group-level margins.[^3]
Ten weeks later, the June 2026 quarter delivered ₹91 crore in OSAM revenue, while management's language shifted from a fixed convergence window to a gradual integration process, stating that integration "continues to progress well," with profitability improving "gradually."[^2] Management did not disclose a specific quarterly margin figure.
Procurement adjustments in Bihar offer further context on the integration pace. CEO B.V.K. Reddy noted that Dodla is converting OSAM to its direct farmer payment structure, stating: "We are going for farmer payment model. That's why things are going very slow."[^2] Procurement volume growth at OSAM remained minimal during the quarter because the company deliberately unwound the acquired business's reliance on powder and butter sales to rebuild supplier relationships from the ground up.
This restructuring demonstrates that OSAM is not a plug-and-play asset; it requires rebuilding procurement architecture in a milk shed dominated by the state cooperative COMFED and informal traders, using field practices developed over thirty years in Andhra Pradesh. Management also adjusted its capital allocation plan mid-stream. After conducting due diligence on a 7-acre land parcel allotted by the Bihar Industrial Area Development Authority for about ₹4.4 crore, management began reconsidering whether to deploy capital toward that land or toward expanding capacity at its existing Chandil facility, aiming to expand "in a more capital-effective manner."[^3][^2]
While reassessing land commitments reflects capital discipline, the aggregate picture—a margin convergence timeline that widened within a single quarter, procurement growth described as "very slow," and ₹250 crore in balance-sheet intangibles resting on the outcome—indicates that Dodla's acquisition playbook remains unproven at this scale. The small-deal record is clean, whereas the large-deal record consists of a single 13-month-old transaction operating below group margins. The critical milestone to monitor will be OSAM's quarterly EBITDA margin reaching group levels, an objective management now targets between mid-FY27 and subsequent quarters.
IX. The Business Model: Helmer's 7 Powers & Porter's 5 Forces Analysis
Strategic frameworks are most instructive when they deliver a selective verdict. Evaluating Dodla Dairy through Hamilton Helmer's 7 Powers and Michael Porter's Five Forces reveals a business with a distinct operational defense, but few structural mechanisms to protect pricing or profit margins.
Cornered Resource — partial, and localized. Dodla's investor materials do not claim a proprietary asset or patent; instead, management emphasizes dedicated staff and supplier relationships—attributes closer to Process Power than a true Cornered Resource. The genuinely cornered element is the installed density of its procurement network within economically viable chilling radii: 7,691 collection centres and 240 chilling centres built over three decades, feeding processing plants that operate at 65.8% utilization.[^1] A new entrant cannot easily replicate this physical infrastructure without running plants at loss-making utilization rates for years while attempting to induce farmers to switch. The operational proof of this density lies in Dodla’s rising procurement per collection point, extracting significantly higher daily milk volumes from a stable touchpoint count over five years.
However, a true cornered resource should generate durable excess returns. Dodla's return on capital employed stood at 16.0% as of March 31, 2026—a solid figure, but modest for a company claiming an unassailable moat.[^1] The company's structural advantage is real at the level of raw-milk sourcing costs and supply reliability, but it does not extend to consumer pricing power.
Scale Economies — modest and regionally capped. While Dodla is a major regional processor, raw milk is highly perishable and milk sheds are inherently hyper-local, capping the geographic radius over which scale benefits can be shared. Its domestic processing capacity of 22.0 lakh litres per day represents substantial regional scale, yet industry leader Hatsun Agro generated roughly ₹9,972 crore in FY26 revenue—more than double Dodla's top line—without converting that superior scale into fundamentally different liquid milk economics.13 In dairy, scale secures regional procurement leverage and efficient plant utilization, but it fails to deliver national pricing power in a market fragmented by state boundaries.
Counter-Positioning versus cooperatives — a constrained dynamic. A conventional thesis suggests that private dairies counter-position against state cooperatives because cooperatives prioritize farmer payouts over shareholder returns. In practice, the dynamic limits Dodla's pricing flexibility. In July 2026, Sunil Reddy noted that Dodla's retail prices sit "more than INR10" per litre above state cooperative prices in Tamil Nadu and ₹6 to ₹7 higher in Karnataka.[^2] Rather than undercutting cooperatives, Dodla operates at a premium, ceding the price-sensitive mass market to protect its gross margins.
Management acknowledged that this price differential constrains domestic volume expansion. Sunil Reddy explained that in core markets "we don't want to keep pushing it further and that is why we do more of geographical expansion," adding that the price gap means Dodla "will not get block more entry into the HoReCa or the local shops."[^2] While delayed cooperative payouts to farmers create potential long-term pricing pressure on cooperatives, relying on competitors to raise prices represents an external market expectation rather than a structural power held by Dodla.
Brand, Switching Costs, Network Effects, and Process Power: These advantages remain largely absent or unproven on the consumer side. A consumer incurs zero switching cost when choosing an alternative brand of curd or milk, and no demand-side network effects exist. The primary switching cost resides on the supply side through integrated cattle-feed financing and veterinary support, confirming that Dodla's operational moat resides in farmer procurement rather than consumer brand equity.
A complementary analysis using Porter's Five Forces illuminates the broader industry structure:
Threat of new entrants: low. High capital intensity, perishable inventory risks, and established farmer networks make greenfield entry into mature milk sheds economically unfeasible. Entry occurs primarily through acquisitions—the exact path Dodla pursued in Eastern India.
Supplier power: medium and rising. Farmers retain the ability to divert milk to state cooperatives when private procurement prices lag behind inflation. In the June 2026 quarter, Dodla's raw milk procurement cost rose 10.4% year on year, whereas its retail realization increased by only 3.9%.[^1] That spread compression highlights how supplier cost pressures are absorbed by the processor rather than fully passed to consumers.
Buyer power: high and binding. Individual retail shoppers lack formal bargaining power, but consumer price expectations are anchored by state-subsidized cooperatives operating under political constraints against price hikes. This price ceiling limits Dodla's ability to pass on cost increases without sacrificing market share.
Threat of substitutes: low. Plant-based milk alternatives remain commercially insignificant across Dodla's target demographics.
Competitive rivalry: high and intensifying. Dodla faces intense competition from regional private processors, state cooperatives, and specialized value-added players. In August 2026, pure-play value-added dairy processor Milky Mist completed an initial public offering, raising ₹1,553 crore—including ₹1,428 crore in fresh primary capital—in an issue subscribed 56 times.1415 Milky Mist reported total income of ₹3,145 crore in FY26 with net profit of ₹127 crore, operating a pure value-added model with EBITDA margins in the 13–14% range against Dodla's 7.5%.1413 A well-capitalized competitor focused exclusively on value-added products represents a formidable challenge to a processor whose margin recovery strategy depends on value-added growth.
The strategic verdict is clear: Dodla possesses a genuine operational power in procurement density that protects its raw material sourcing and supply continuity, but lacks structural mechanisms to command premium pricing. The business operates with a secure operational floor alongside a structurally capped margin ceiling—a reality reflected in its five-year financial performance.
X. Management Credibility, Capital Allocation & Financial Analysis
Evaluating a management team requires comparing prior guidance against subsequent operational reality. Dodla's earnings call transcripts from mid-2026 offer a clear window into this dynamic, as analysts revisited core strategy and margin targets across consecutive quarters.
The division of labor among executive leadership is clearly defined. Managing Director Dodla Sunil Reddy, who received ₹4.62 crore in remuneration in FY26, focuses on long-term strategy, industry cycles, and external cost drivers such as fuel and weather patterns.[^4] Chief Executive Officer B.V.K. Reddy manages granular operations, providing precise per-litre procurement and realization figures. Chief Financial Officer Murali Mohan Raju addresses balance-sheet accounting, having proactively disclosed the company's adjusted earnings baseline on the May 2026 call.
Proactively separating one-off tax credits from core operational earnings before analyst questioning represents a transparent disclosure practice. Disclosing an adjusted operational profit figure rather than relying on headline numbers provides analysts with a clear baseline for evaluation.
The promoter group held 35.5 million of the company's 60.3 million shares—a 58.92% controlling stake—as of the July 2026 annual general meeting, with zero shares pledged.[^21] Founder chairman Dodla Sesha Reddy serves as a Non-Executive Director and drew no remuneration in FY26.[^4] In May 2026, the board appointed Dodla Silpa Reddy as senior management personnel for strategy and transformation, with Sunil Reddy stating she had "spent considerable time understanding the business across verticals" before assuming operational responsibilities.[^3] While management disclosed the appointment directly during earnings commentary, the addition underscores that strategic leadership remains centered within the promoter family.
Guidance discipline: mixed, with optimism regarding margin recovery timelines. In May 2026, Sunil Reddy projected FY27 revenue growth in the "low to mid-teens" alongside a gross margin expansion of 50 to 100 basis points.[^3] By July 2026, management refined its revenue target to 10% volume growth and 15% top-line expansion.[^2] However, margin expectations faced delays. Management initially anticipated raw milk procurement costs would decline with seasonal monsoon rainfall, but acknowledged by July that procurement prices remained firm: "we were assuming that with the onset of monsoons, the procurement prices will taper down, but now seeming to be that there's not much of an increase in procurement in terms of the price what we normally expect."[^2]
Management attributed the price persistence to industry-wide inventory rebuilding following a low-yield period. To offset elevated raw material costs, Dodla implemented price increases of ₹2 per litre on liquid milk and ₹3 to ₹4 per litre on value-added products in mid-July 2026, while contemplating an additional 2.0% to 2.5% price adjustment.[^2] Evaluating whether these price adjustments can restore margins without suppressing retail volume remains a key test for upcoming quarters.
Consistency across calls: aligned on operational facts, but firming on margin expectations despite near-term pressure. When questioned in May 2026 regarding whether baseline margins had structural headwinds, Sunil Reddy cited input cost volatility—including fuel, packaging materials, and weather patterns—describing FY27 as "a year in transition."[^3] By July, when asked if margin targets required downward revision, management maintained a firmer stance: "It is not a reset of the margins, but more a seasonal correction that has been happening."[^2] Management reaffirmed its medium-term EBITDA margin target of 7% to 8%, relying on mid-quarter price hikes to counter short-term spread compression.
Capital allocation: conservative execution facing expanding deployment commitments. On the May 2026 earnings call, Sunil Reddy outlined capital deployment priorities: funding organic expansion first, maintaining regular dividend distributions second, and pursuing selective bolt-on acquisitions with operational synergies third.[^3]
Historical execution matches this policy framework. Capital expenditure in FY26 totaled approximately ₹430 crore, comprising ₹271 crore for the OSAM acquisition, ₹86 crore for the Maharashtra facility, and ₹73 crore in routine maintenance—funded entirely through internal cash generation.[^3] Balance-sheet leverage remained low with a debt-to-equity ratio of 0.03, while cash and liquid investments grew from ₹649 crore at year-end FY26 to approximately ₹689 crore by June 2026, covering a planned ₹590 crore multi-year capital expenditure outlay.[^3][^2] Management recommended a final dividend of ₹5 per share for FY26, while ICRA reaffirmed the company's long-term credit rating at AA with a stable outlook and short-term rating at A1+.163
Executing a ₹271 crore acquisition alongside major greenfield construction without debt or equity dilution demonstrates capital discipline. However, maintaining balance-sheet strength is distinct from achieving high returns on invested capital; long-term allocation efficiency will depend on the operational yield of these new assets.
The greenfield processing plant in Solapur, Maharashtra, represents Dodla's largest organic capital commitment: a ₹280 crore facility designed to add 10 lakh litres per day of processing capacity, with ₹106 crore deployed cumulatively across FY25 and FY26 and the remaining ₹180 crore scheduled for FY27 to support commercial operations by the end of the financial year.[^3]3 Sunil Reddy highlighted the plant's operational role, noting that Maharashtra serves "predominantly [as] our milk balancing procurement operation," with local market sales projected at roughly 2 lakh litres per day.[^2] Rather than serving primarily as a retail market expansion, the facility functions as a procurement balancing hub, diversifying raw-milk sourcing across a milk shed with seasonal production cycles distinct from Southern India. By May 2026, procurement in Maharashtra reached approximately 3 lakh litres per day, with management targeting a peak seasonal volume of at least 5 lakh litres.[^3]
Governance: clean audit reports, with minor institutional dissent on related-party terms. S.R. Batliboi & Associates LLP serve as statutory auditors, KPMG Assurance and Consulting Services LLP act as internal auditors, and MNM & Associates serve as secretarial auditors, with the FY26 Board's Report recording no qualifications or adverse remarks across statutory or secretarial audit filings.[^4]
At the annual general meeting in July 2026, five of six voting resolutions passed with institutional opposition below 0.1%. The remaining item—a special resolution approving consultancy fee payments to non-executive director Dodla Sesha Reddy in excess of standard non-executive compensation limits—drew 2.54% institutional votes against, representing approximately 4.7 lakh shares.[^21] The resolution established an upper payment cap of ₹10 lakh per month, with management proposing an active payout of ₹5 lakh per month.[^4] While the financial amount is modest and the resolution passed, the vote reflected institutional sensitivity regarding related-party compensation structures within promoter-led boards.
Evaluating corporate governance and risk factors. An analysis of potential governance and structural vulnerabilities highlights three primary areas of scrutiny:
First, board composition includes a legacy non-executive director originally appointed by a private equity shareholder that has since exited, who remains on the board nine years after initial appointment while working at a major private equity firm.[^4] Second, executive oversight remains concentrated within the promoter family across board leadership and operational management. Third, the balance sheet carries approximately ₹250 crore in OSAM-related intangible assets and goodwill, which statutory auditors designated as a key audit matter due to the subjective assumptions governing carrying-value evaluations.
Conversely, the company maintains zero pledged promoter shares, negligible debt, transparent subsidiary accounting, and a history free of equity dilution. With financial engineering risks largely absent, operational performance, procurement cost control, and M&A integration remain the primary determinants of business valuation.
XI. Historical Falsification Layer & Stress Testing
This is where the thesis gets pressure-tested against Dodla's own history rather than against management's framing of it.
Stress Test 1 — Does Dodla have pricing power? The record says no, twice.
The claim under test: brand equity and regional distribution density give Dodla the ability to pass input cost inflation through to consumers, making margin compression temporary.
The first falsification occurred in FY23, when raw-milk procurement costs surged across South India following a lumpy skin disease outbreak among cattle and widespread input inflation. Despite a 25% surge in revenue, Dodla could not pass along cost increases fast enough: gross margin fell from 27.5% to 23.9%, EBITDA margin dropped from 9.4% to 6.8%, and net profit declined from ₹133 crore to ₹122 crore.[^1] Margins subsequently recovered over FY24 and FY25 as procurement costs normalized, elevating EBITDA margin to a five-year peak of 10.2% in FY25.[^1]
At that juncture, investors might have viewed FY23 as an isolated biological shock.
The second falsification emerged in FY26 and persisted into FY27. Raw-milk procurement costs rose from ₹37.4 per litre in the March 2025 quarter to ₹41.0 in March 2026 and ₹41.3 in June 2026, whereas retail realizations increased only from ₹57.2 to ₹59.4 per litre.[^1][^3] Consequently, consolidated EBITDA margin contracted to 7.5% for FY26, dropping to 5.0% in the March quarter and 5.4% in June.[^3][^1] CEO B.V.K. Reddy stated plainly that Dodla "did not entirely pass on this increase in cost to the consumers," while Sunil Reddy clarified that price increases were muted "to maintain the market share."[^3]
That admission directly challenges the pricing-power thesis. Dodla's retail pricing remains bounded from below by state cooperative price anchors and from above by its existing ₹6 to ₹10 per litre price premium. Management prioritized market share over short-term profitability—a defensible operational choice, but one that demonstrates a clear lack of pricing power.
The calibrated verdict: The pricing-power thesis is invalidated for liquid milk and must be narrowed. Dodla possesses a procurement cost advantage paired with a price premium it can sustain but cannot easily expand. The value-added portfolio displays stronger pricing dynamics—management implemented ₹3 to ₹4 per litre price increases in value-added products compared to ₹2 per litre in liquid milk, noting that ghee and allied items absorbed "substantially larger" price adjustments.[^2] While genuine, this pricing flexibility applies to roughly one-third of total revenue.
The metrics for evaluation are specific and near-term: if consolidated EBITDA margin recovers to the 7% to 8% range within two to three quarters as targeted by management, the "cyclical fluctuation" narrative holds. If FY27 EBITDA margin finishes below 7% while procurement costs stabilize, the cyclical explanation breaks down, indicating a business with a lower baseline structural margin than its FY25 peak implied.
Stress Test 2 — Is the FY25 peak the right anchor?
Examining baseline metrics is essential, as the choice of anchor changes how recent margin compression is interpreted. FY25's peak EBITDA margin of 10.2% was supported by ₹313 crore in bulk skimmed milk powder and butter sales, while that year's nearly 20% revenue growth benefited from highly favorable raw-milk procurement conditions.[^1][^3] Sunil Reddy cautioned against relying on single-year benchmarks, noting: "To better understand the trends of the dairy industry, one should look at the three to four-year cycle. On that basis, our four-year CAGR stands at a healthy level of 16%."[^3]
That multi-year perspective provides a balanced framework. Across FY22 through FY26, Dodla's average EBITDA margin stood at approximately 8.6%, spanning a range from 6.8% to 10.2%. Anchoring expectations on either extreme misrepresents the operating model. The analytical reality is that Dodla operates as a high-single-digit EBITDA margin business with roughly ±200 basis points of cyclical volatility tied to the procurement-realization spread, placing the burden of proof on assertions that its baseline margin is structurally shifting upward.
Stress Test 3 — Does the acquisition record support the ₹271 crore bet?
The affirmative case rests on precedent: two earlier dairy acquisitions carrying goodwill were evaluated for impairment as of March 31, 2026, with neither requiring a write-down.[^4] Management has ruled out impairment provisions for OSAM, with Sunil Reddy stating no write-offs will occur and CFO Murali Mohan Raju describing the intangible amortization as "a standard fair value of amortization. There is no any surprises of reduction in the fair value."[^2]
The counter-evidence, however, remains substantial: thirteen months post-acquisition, OSAM operates at approximately one-third of consolidated group EBITDA margins; management's margin-convergence timeline shifted from a fixed window in May to an unquantified "gradual improvement" by July; procurement growth remains "very slow" while direct farmer payment structures are rebuilt; and capital plans for a Bihar land allotment were re-evaluated.[^3][^2] Furthermore, statutory auditors flagged valuation assumptions for OSAM as complex and judgmental, noting high sensitivity to projected revenue growth rates and discount factors.[^4]
The calibrated verdict: The capital allocation framework holds regarding financing discipline—the acquisition was funded entirely through internal cash flows while maintaining a debt-to-equity ratio of 0.03—but remains unproven regarding value creation outside its core geography. Successful integration of two minor regional assets provides a narrow historical baseline for executing an out-of-region transaction five times larger. The key confirming metric will be OSAM's standalone EBITDA margin trajectory in quarterly disclosures, whereas a goodwill write-down or unexplained delay in margin convergence would invalidate the expansion thesis.
Stress Test 4 — Governance and accounting.
Statutory and secretarial audit filings for FY26 were unqualified with zero adverse remarks or fraud reported under Section 143(12), while the promoter equity stake remains entirely unpledged.[^4][^21] Receivables risk is structurally low, with management reporting average days sales outstanding of 1.5 to 2 days—reflecting the cash-and-carry nature of consumer staples distribution.[^2] Working capital requirements remain exceptionally low.
Two accounting areas warrant ongoing observation: the valuation of OSAM's goodwill and brand intangibles, which depend on subjective discounted cash flow modeling noted by auditors, and the non-recurring FY26 tax credits. Management confirmed that the Income Tax Appellate Tribunal credit "represents the final portion and accordingly no further impact shall be reflected from the next quarter onwards," projecting an effective tax rate of 25% to 27% for FY27.[^3] Consequently, financial models built on headline FY26 net profit rather than the ₹215 crore adjusted operational baseline will overestimate forward earnings by roughly one-third.
XII. Current Risk Radar, Bull vs. Bear Case & Key KPIs
Evaluating Dodla's forward outlook requires ranking key risk factors by their potential impact on operating profitability.
Raw milk procurement cost represents the single largest earnings sensitivity. Cost of goods sold, including packaging materials, accounted for 74.4% of consolidated revenue in FY26, with raw milk representing roughly 71 percentage points and packaging taking 3.5 points.[^3] An unabsorbed 5% increase in procurement costs reduces EBITDA margin by roughly 350 basis points—potentially eliminating half of operating profit. Procurement costs are driven by weather patterns, cattle health, fodder prices, and industry inventory cycles, none of which management can directly control.
Non-milk input inflation has become a material cost driver. Packaging material costs rose 48% year-on-year in the June 2026 quarter to 5.6% of revenue, up from 4.4%, with Sunil Reddy attributing a roughly 30% rise to plastic pricing that management expects to remain elevated.[^2][^3]
Transportation expenses represent another significant cost factor, accounting for 7.3% of revenue across four distribution legs—village to chilling center, chilling center to processing plant, plant to sales office, and sales office to retail customer—alongside loading and contract labor, leaving operations unusually sensitive to diesel prices.[^3] Management estimated that a ₹3 per litre diesel price hike reduces margins by 0.25 to 0.5 percentage points, noting that transport contractors absorb price adjustments during the initial two weeks.[^3]
By contrast, plant power and fuel represent only about 1.5% of revenue.[^3] Solar energy installations across chilling centers and plants provide operational efficiencies, but operate on too small a base to serve as a primary margin driver.
Cooperative pricing behavior functions as a policy risk framed by competitive market dynamics. Industry peers Amul and Mother Dairy implemented ₹2 per litre price increases in 2026 following Dodla's price adjustment in mid-March.[^3] However, major state-subsidized cooperatives in southern India, such as Nandini and Aavin, had not adjusted retail prices as of July 2026.
Because state cooperatives operate under political pricing constraints, their price levels set an effective cap on private processors' realizations. Sunil Reddy noted that regional cooperatives face financial pressure, exhibiting delayed farmer payouts and withdrawing unprofitable product lines—factors management anticipates will eventually force cooperative price adjustments.[^2] However, relying on competitors' policy adjustments represents an external market dependency rather than an operational lever.
OSAM execution represents the primary operational integration risk.
African currency and geopolitical risk remains a structural factor, though offset recently by operational revenue growth. In the first quarter of FY27, realizations in local currency terms converted favorably into rupees, with Ugandan realizations rising from ₹59.36 to ₹65.31 per litre and Kenyan realizations increasing from approximately ₹58 to ₹65.[^2] Historically, cross-border trade restrictions between Uganda and Kenya presented greater operational friction than currency fluctuations, prompting the build-out of localized processing capacity in Kenya.[^3] Because recent growth has coincided with favorable pricing cycles, a substantial devaluation of East African currencies against the Indian rupee would negatively impact consolidated financial results independent of underlying operational performance.
The Bull Case
Dodla enters FY27 with processing capacity already in place across its three geographic segments, allowing volume expansion to generate operating leverage. The company maintains a net-debt-free balance sheet with ₹689 crore in liquidity against a planned ₹590 crore capital expenditure program, supporting organic expansion without requiring equity dilution or debt financing.[^2] The value-added portfolio continues to compound at approximately 20% annually, led by curd product growth exceeding 40% year-on-year. African operations have established a profitable footprint with expanding scale in Kenya, while the Solapur facility in Maharashtra provides a geographically diversified milk shed to mitigate procurement volatility. If raw milk costs normalize and recent price adjustments hold, margin recovery follows a defined operating path: management estimates that a combined ₹0.60 to ₹1.50 per litre improvement across procurement, operational efficiency, and realization expands EBITDA margins by 100 basis points.[^3]
The Bear Case
Two major margin compressions within four years highlight vulnerability to raw material cycles, suggesting that FY25 profitability reflected favorable industry conditions rather than a permanent structural baseline. Dodla's price premium over state cooperatives limits further pricing flexibility in core markets, with management acknowledging that additional retail price hikes risk losing market share among commercial and retail channels.[^2] Standalone domestic volume growth in core southern markets remains modest at approximately 3%, leaving consolidated growth dependent on international markets and recent acquisitions.[^2] Balance-sheet quality remains exposed to roughly ₹250 crore in intangible assets tied to OSAM, an acquired entity operating below group-level profitability. Meanwhile, specialized competitors such as Milky Mist, operating at EBITDA margins above 13%, present intensified competition in value-added categories. Finally, a return on capital employed of 16.0% reflects moderate capital efficiency for a cyclical processor lacking consumer pricing power.[^1]
Key Performance Indicators
First, the procurement-realization spread per litre. The net spread between raw milk procurement costs and retail realizations serves as the primary metric explaining quarterly EBITDA margin fluctuations. Progress should be benchmarked against historical spreads of ₹19.8 per litre in mid-2025 and ₹18.1 per litre in mid-2026.
Second, value-added products as a percentage of revenue, excluding bulk sales. Because bulk commodity liquidations fluctuate seasonally, tracking value-added revenues excluding bulk commodity sales provides an accurate measure of structural mix shifts. Like-for-like value-added revenue share expanded to 34.6% in the June 2026 quarter, compared to 29.3% in the prior-year period.[^1]
Third, OSAM's standalone EBITDA margin. OSAM's margin trajectory serves as the decisive metric evaluating the success of the ₹271 crore acquisition, indicating whether the Eastern India expansion can achieve group-level profitability.
XIII. Lessons & Takeaways for Founders & Investors
Stripping away thirty-one years of processing plants, chilling centers, and quarterly earnings calls leaves a set of lessons that generalize well beyond the dairy sector. Dodla's trajectory illustrates what happens when a company builds a genuine operational advantage in the upstream half of its value chain while remaining exposed to downstream pricing constraints.
In commodity perishables, the moat lives upstream — but so does the volatility.
Dodla's primary competitive strength lies in three decades of village-level procurement density that a competitor cannot quickly purchase or easily replicate. That physical infrastructure protects raw-material supply reliability and baseline procurement costs.
What an upstream moat does not provide is selling-price protection. In commodity processing, an upstream moat offers structural durability, but it also imports raw-material volatility. A processor cannot own a procurement network without absorbing the agricultural procurement cycle; the two represent sides of the same operational asset. Any investment thesis asserting a durable procurement advantage while treating raw-milk cost volatility as an anomaly remains internally inconsistent.
Private equity institutionalises; it rarely transforms.
The investment periods under Black River and TPG introduced audit discipline, a professional chief executive, upgraded field instrumentation, and formal board oversight—aligning with management's observation that institutional investors helped professionalize operations. However, private-equity ownership did not alter the core business model, establish a national consumer brand, or permanently elevate returns on capital.
This outcome reflects structural industry constraints rather than managerial execution. Institutional ownership provided governance and operational discipline, serving as a reminder that private-equity backing improves operating rigor rather than fundamentally altering business economics.
Balance-sheet conservatism is a strategy, not a virtue signal — and it is testable.
Dodla funded the OSAM acquisition, greenfield plant construction in Solapur, and routine capital expenditures entirely through internal cash flows while maintaining a near-zero debt-to-equity ratio. In an industry where operating profits compress in two out of five years, minimal balance-sheet leverage ensures survival during lean cycles while preserving liquidity for opportunistic expansion.
For cyclical commodity processors, maintaining low financial leverage is necessary because operational risk is already elevated. The evaluation of this conservative capital structure depends on acquisition execution and asset yields, making the long-term integration of Eastern India operations a key test of capital allocation.
Farmer welfare is supply chain security with better public relations.
Direct bank settlements on a fixed 10- to 15-day cycle, veterinary support, integrated cattle-feed financing, and bank loan assistance represent strategic supply-chain retention tools rather than corporate philanthropy. Management deliberately absorbed rising raw-material costs in its cattle-feed operations rather than passing price increases to farmers, choosing to protect supplier retention over short-term segment margins.
These initiatives function as operational investments to maintain procurement density. When evaluating smallholder support programs in agriculture, the key test is whether management sustains them during margin downturns; continuing to fund these programs during tight cycles confirms that supplier retention forms part of the operational moat.
Growth that comes only from new geographies is a specific kind of signal.
Management's disclosures regarding core southern markets highlight a key strategic transition: retail price differentials relative to state cooperatives have widened to the point where further price increases would jeopardize distribution volume, shifting home-market priorities toward defending existing market share.[^2] Consequently, incremental top-line growth relies primarily on expansion into East Africa, Maharashtra, and Eastern India.
While geographic expansion represents a valid growth vector, it alters the investment profile. Expanding within core markets compounds an established operational advantage, whereas expanding outside core territories requires establishing or acquiring new procurement networks—exposing capital to region-specific execution risks.
Finally: when the same failure repeats, believe the second one.
A key analytical takeaway from Dodla's public operating record is that recurring margin contractions require evaluating underlying structural constraints rather than treating individual down-cycles as isolated events. The margin compression of FY26 occurred through the same spread-narrowing mechanism as FY23. While management attributes the squeeze to temporary input cost inflation, repeated occurrences place the burden of proof on sustained margin recovery.
Mid-2026 price increases across liquid milk and value-added categories aim to restore operating profitability. However, whether Dodla can normalize EBITDA margins toward its target 7% to 8% range will be determined by the quarterly procurement-realization spread—a metric disclosed directly in quarterly reporting.
References
-
Dodla Dairy: Greener grass on the udder side — Forbes India, 2018 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Dodla Dairy Reports Record FY26 Revenue, Expands into Eastern India Through OSAM Acquisition — AgriMoon, 2026 ↩↩↩
-
The Rise Fund Invests in Dodla Dairy Limited — TPG / Business Wire, 2017-05-03 ↩
-
TPG to invest $50m in India's Dodla Dairy, Proterra to exit — AVCJ, 2017 ↩
-
Dodla Dairy IPO — Date, Price, Details and Objects of the Issue — Chittorgarh, 2021 ↩↩
-
Dodla Dairy IPO ends with bumper subscription — Business Standard, 2021-06-19 ↩
-
Dodla Dairy share lists at over 28% premium to issue price — Business Today, 2021-06-28 ↩
-
Avendus Capital and Spark Capital close TPG Rise Fund's stake sale of 6.7% in Dodla Dairy — Avendus ↩↩
-
Dodla Dairy to acquire Sri Krishna Milks for Rs 50 cr — Business Standard, 2022-03-19 ↩↩
-
Dodla Dairy's board nod to acquire 100% stake in HR Food Processing — Business Standard, 2025-07-11 ↩
-
Dodla Dairy to buy peer HR Food Processing — Just Food, 2025-07 ↩
-
Why dairy stocks aren't easy to milk — PrimeInvestor, 2026 ↩↩
-
Milky Mist IPO: Dairy Company Fixes Offer Size At Rs 1,553 Cr Ahead of Public Issue — Outlook Money, 2026-08 ↩↩
-
Milky Mist Dairy Food IPO Subscribed 56.06x — Kotak Neo, 2026-08 ↩
-
Dodla Dairy's Q4 PAT rises 3% YoY to Rs 70 cr — Business Standard, 2026-05-18 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube