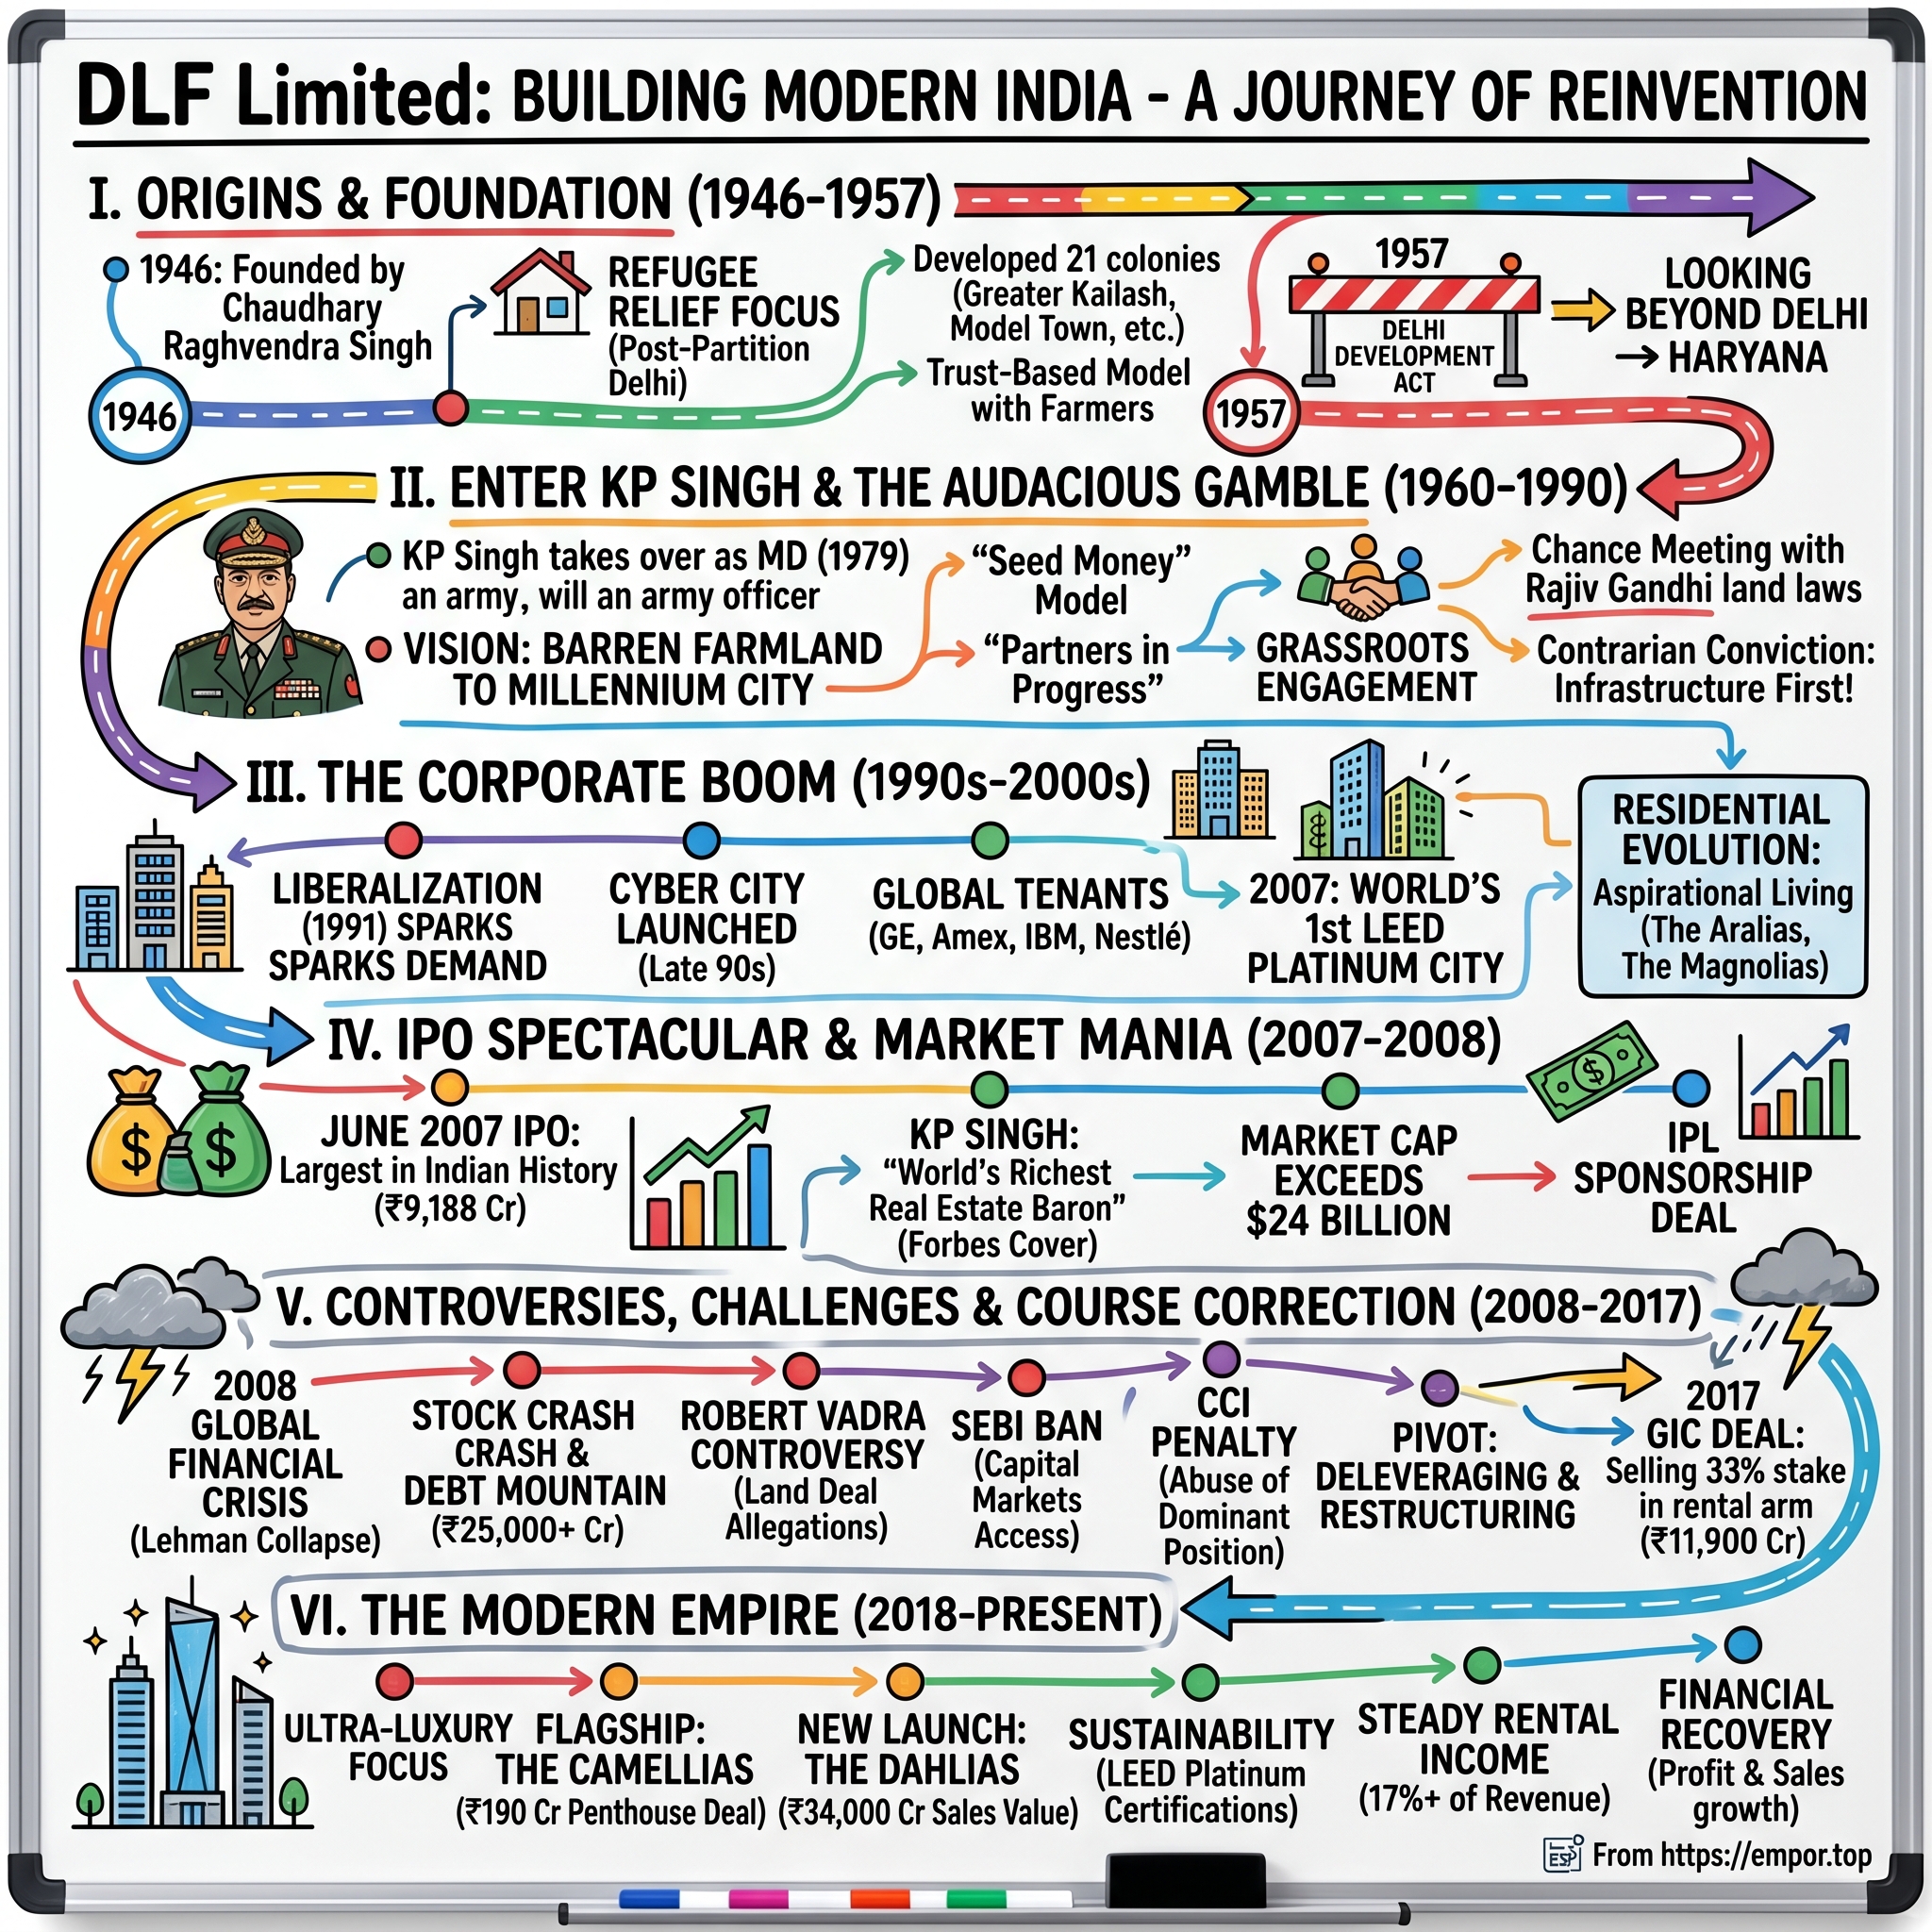
DLF Limited: The Building of Modern India's Real Estate Empire
I. Introduction & Episode Roadmap
In August 2026, a single penthouse apartment in Gurugram sold for ₹271 crore. Located inside The Dahlias—a 17-acre enclave in DLF Phase 5—the 17,200-square-foot residence fetched roughly ₹1.58 lakh per square foot on super area, or about ₹2.58 lakh per square foot based on usable carpet area. Purchased by entrepreneur Manav Sardana, the sale surpassed the previous national record set within the same development: a ₹120.7 crore penthouse acquired by investor Madhusudan Kela.1
Twenty months earlier, in December 2024, a 16,290-square-foot penthouse at the neighbouring DLF project, The Camellias, sold for ₹190 crore to Info-x Software Tech, led by Rishi Parti. That deal marked the highest price ever recorded for a high-rise condominium in the National Capital Region at the time.2 In less than two years, DLF surpassed its own regional benchmark by more than 40% in a micro-market it had originally developed from agricultural farmland.
This price trajectory mirrors DLF's broader corporate evolution. Founded in 1946 as Delhi Land & Finance, the company built its early business developing residential layouts for displaced families following Partition, creating 22 urban colonies across Delhi.3 Eight decades later, DLF stands as India's largest listed real estate developer, with a market capitalisation of approximately ₹1.69 lakh crore and a share price trading near ₹673 in early September 2026.4 The expansion from middle-income housing developments like Krishna Nagar to luxury penthouses selling for ₹271 crore reflects the broader structural transformation of urban Indian real estate.
Beyond individual luxury sales, DLF operates through two distinct business units with contrasting financial profiles.
The first engine is the wholly owned development business, often referred to as DevCo. Operating on a pre-sales model, DevCo receives customer payments in construction-linked instalments before completing projects. In fiscal year 2026, the unit recorded ₹20,143 crore in new sales, collected ₹13,517 crore in cash, and ended the year with a net cash surplus of ₹14,155 crore.5 This customer-funded structure has enabled DLF to fund residential construction with minimal balance-sheet debt.
The second engine is the commercial rental business housed within DLF Cyber City Developers Limited (DCCDL), a joint venture owned 66.66% by DLF and 33.34% by Singapore's sovereign wealth fund, GIC. In fiscal 2026, DCCDL's rental income increased 16% to ₹5,525 crore—comprising ₹4,550 crore from office space, up 17%, and ₹975 crore from retail, up 11%. Consolidated revenue reached ₹7,393 crore with EBITDA of ₹5,718 crore, while net profit grew 38% to ₹2,726 crore.6 This recurring revenue platform holds AAA credit ratings from CRISIL and ICRA.7
Three central questions define the company's trajectory:
First: how did a developer restricted from building in its original market expand into neighbouring Gurugram? DLF navigated three distinct regulatory eras: Partition-era Delhi, the licence-permit period that municipalised development in the capital, and post-1991 liberalisation that attracted foreign corporate tenants. The company's expansion into Gurugram relied as much on land acquisition strategies and regulatory positioning as on construction execution.
Second: how did India's largest initial public offering lead to severe financial distress? DLF raised ₹9,187.5 crore in 2007 but accumulated over ₹22,000 crore in net debt within five years.89 The subsequent restructuring—a 2017 transaction with GIC that injected capital back into the listed parent—represents a crucial case study in capital allocation and debt reduction.
Third: what is the appropriate framework for evaluating DLF's business model today? Investors must evaluate whether DLF operates primarily as an asset-light luxury residential developer, an annuity-style rental platform suited for a REIT structure, or a cyclical land bank reliant on momentum in key micro-markets. Each perspective carries distinct valuation implications.
This analysis examines DLF's history through several key phases: its origins in post-Partition housing, its land acquisition in Gurugram, the development of Cyber City during the IT outsourcing expansion, its public listing and subsequent debt challenge, the GIC joint venture restructuring, and the post-2020 luxury residential cycle.
 Subscribe on LinkedIn
II. Foundations: Partition, Land Banking, & Forced Exit from Delhi (1946–1979)
In the winter of 1947, Delhi faced a sudden humanitarian crisis. The city's population swelled as refugees from West Punjab arrived by train, on foot, and in bullock carts. Temporary camps at Kingsway and Purana Qila held tens of thousands, while municipal infrastructure and housing stock were virtually non-existent. Into that vacuum stepped a private company founded a year earlier by Chaudhary Raghvendra Singh, carrying a name that read like a balance sheet: Delhi Land & Finance.3
The early DLF business was straightforward. It acquired agricultural land at the edge of the built-up city, laid out residential plots, installed basic utility connections, and sold them. Areas such as Model Town, Rajouri Garden, South Extension, and Greater Kailash—now established South and East Delhi neighborhoods—began as farmland marked with survey pegs. By the company's own account, DLF developed 22 urban colonies in Delhi during this period.3 The early strategy relied on securing land ahead of municipal expansion, performing basic civic development, and benefiting from subsequent urban growth.
That model ended when the regulatory framework changed.
The Delhi Development Act of 1957 created the Delhi Development Authority, placing urban planning and land development in the capital under state control. Private developers were effectively excluded from Delhi. For DLF, this was not merely a market headwind but an existential disruption; its core model of assembling and subdividing land inside the capital was restricted overnight. Through the 1960s and 1970s, DLF drifted as its land holdings within the Union Territory faced constraints under urban land ceiling legislation and its cash reserves eroded.
The leadership transition occurred in 1979. Kushal Pal (KP) Singh—who trained as an aeronautical engineer, graduated from the Indian Military Academy, and served as an officer in the Deccan Horse cavalry regiment—had left the armed forces to join American Universal Electric, an electric motor manufacturer. He married Indira, the daughter of Raghvendra Singh. When American Universal merged with DLF in 1979, KP Singh assumed control of a company whose principal asset was a business model that no longer existed.10
KP Singh brought a different background to real estate development. As a former military officer and industrial equipment salesman who had spent years negotiating commercial contracts, his primary skill was direct negotiation rather than construction management. Over the subsequent three decades, pivotal moments in DLF's expansion frequently depended on regulatory negotiations and personal relationships rather than pure project engineering.
By the late 1970s, the company's strategic assessment was clear: residential land development inside Delhi remained permanently restricted. To expand, DLF needed territory outside the jurisdiction of the Delhi Development Act that could still serve as a residential suburb for the capital.
South-west of Delhi, across the Haryana state border and beyond the Aravalli ridge, lay Gurgaon—a rural district of scrub, quarries, and farming communities with a population of a few tens of thousands.
Developing the area presented structural hurdles. Haryana's land regulations were complex, and the land was fragmented into small parcels held by thousands of individual farming families. Assembling contiguous tracts required extensive land-assembly negotiations, regulatory approvals, and local trust—factors that extended far beyond standard construction timelines.
DLF's primary competitive advantage was not structural engineering, but long-term regulatory arbitrage: identifying adjacent jurisdictions where development was permissible, and acquiring land before urban expansion revalued the asset class. That land assembly strategy established the foundation for DLF's modern land bank, while also creating ongoing exposure to state regulatory decisions.
III. The Gurugram Gamble: Car Breakdowns, Farmers, & Infrastructure First (1980–1990s)
The origin story of modern Gurugram features an overheated engine on a rural road—an anecdote that captures both the serendipity and political dynamics of Indian real estate.
In his memoir Whatever the Odds, KP Singh describes a hot afternoon in the early 1980s on a deserted stretch of Haryana beyond the Qutub Minar, where he was negotiating land purchases with local villagers. A jeep pulled up, and its driver asked for water after the engine overheated. The driver was Rajiv Gandhi, who had recently left his career as an Indian Airlines pilot following the death of his brother Sanjay. According to Singh, the two men conversed for ninety minutes, during which Singh detailed his plan to develop a new city of residences and offices while outlining the state regulatory hurdles blocking the project. Singh recounted that Gandhi subsequently asked for a formal presentation and intervened to help ease Haryana's regulatory restrictions on urban development.10
While the encounter is often retold as a fortunate coincidence, it underscores how regulatory access served as a critical catalyst for DLF's business model.
The legal framework proved even more decisive than political relationships. Haryana's Development and Regulation of Urban Areas Act established a licensing mechanism allowing private developers to convert agricultural land for urban colonies. This policy legitimised private township development while turning development licences into scarce, state-allocated assets. In discretionary licensing regimes, commercial value accrues to entities capable of securing permits at scale, making regulatory navigation a core element of corporate strategy. Gurgaon's land licensing framework, administered through successive Haryana state administrations, remained a subject of ongoing scrutiny over the next four decades.
The execution of land assembly presented a distinct operational challenge. Rather than relying on state-sponsored compulsory acquisition—the traditional mechanism that frequently triggered prolonged agrarian resistance across India—DLF purchased land directly from thousands of individual owners. Singh adopted a direct negotiation model: providing upfront cash, offering prices above agricultural baseline values, promising employment opportunities to local villagers, and maintaining a continuous local presence.
Assembling 3,000 contiguous acres from thousands of smallholders created a significant holdout risk, as remaining sellers could demand steep premiums once project momentum was established. Standard industry practices relied on covert acquisitions via shell companies or government expropriation. DLF instead built local credibility by ensuring prompt payment and honouring land commitments. Although slower, this direct purchasing strategy secured large, unbroken land tracts without the litigation standard in public land acquisitions.
Contiguity was central to the economic model. Developing 3,000 contiguous acres permitted single-entity control over arterial road networks, sector layouts, commercial corridors, and long-term land valuation. DLF City, built in phases throughout the 1980s and 1990s, represented the physical manifestation of this master-planning approach. DLF formally entered Gurugram in 1985.3
Initial sales proved challenging. When DLF began marketing plots in Gurgaon, the location lacked basic municipal infrastructure, including reliable power, water supply, sewage systems, and adequate road connections to Delhi. To address these deficits, DLF funded and constructed internal roads, private water networks, electrical substations, and security infrastructure. This capital-intensive development yielded low short-term financial returns, while middle-class Delhi buyers initially resisted purchasing plots in what was widely viewed as remote farmland.
DLF survived this extended cash-gestation period primarily because its low original land cost minimized holding expenses. Developers acquiring land at prevailing market rates would have faced severe liquidity pressures, forcing early asset sales at lower valuations. The strategy positioned the company to capture the land value appreciation generated by its infrastructure investments once commercial demand materialised.
By the late 1990s, DLF held an assembled, master-planned land bank equipped with private infrastructure—preparing the company for an emerging corporate tenant base that required large, modern office floor plates in the National Capital Region.
IV. Cyber City & the IT/BPO Revolution: Building India's First Corporate Metropolis (1990s–2006)
In 1991, India's balance of payments crisis forced the dismantling of the licence-permit system, opening the economy to foreign investment. Almost simultaneously, two global trends converged: a sharp decline in international telecommunications costs and the realization by Western multinationals that back-office operations could be performed offshore at significantly lower cost.
For those multinationals, the primary hurdle was physical infrastructure. A company seeking to operate a thousand-seat business process outsourcing facility in North India in the mid-1990s required large, contiguous floor plates—a real estate format virtually absent from established commercial centers. Delhi's traditional business districts, including Connaught Place, Nehru Place, and Bhikaji Cama Place, offered small, subdivided units across buildings with fragmented ownership structure. Multiple ownership posed a major operational barrier: a tenant could not easily install uniform power, cooling, and data backbones across floor space split among dozens of individual landlords.
DLF held a distinct structural advantage: single ownership of a large, contiguous, pre-licensed land tract 20 kilometres from Delhi, unencumbered by legacy building stock.
The company's pivotal commercial relationship was with General Electric. Under Chief Executive Officer Jack Welch, GE expanded its Indian back-office operations, establishing GE Capital International Services—the precursor to Genpact—led by Pramod Bhasin. Corporate tenants required customized floor plates and uninterruptible power. Because India's public grid suffered frequent, prolonged outages during the 1990s, DLF constructed captive, industrial-scale power infrastructure to guarantee operational continuity. Over the following decade, the tenant roster expanded across major multinationals, including American Express, British Airways, IBM, and Nestlé.
Rather than merely leasing office space, DLF was effectively providing operational risk mitigation. For a multinational shifting core business processes offshore, downtime and landlord friction represented major operational risks. DLF addressed these concerns by serving as a single counterparty offering long-term lease control, integrated infrastructure, and guaranteed power uptime.
This strategy culminated in DLF Cyber City, an integrated commercial district of Grade-A office towers featuring captive power generation and structured data networks. To improve connectivity, DLF collaborated with Infrastructure Leasing & Financial Services (IL&FS) to develop the Gurgaon Rapid Metro, a private transit loop connecting the campus to the Delhi Metro network.11 The campus also incorporated Cyber Hub, a central dining and retail precinct designed to serve office workers and drive evening foot traffic.
The Rapid Metro highlighted the complexities of private transit infrastructure. Opening in 2013, the line suffered from overoptimistic ridership projections that were later exposed during the insolvency and unwinding of IL&FS.11 While DLF successfully delivered transit infrastructure that public authorities had delayed, the project's financial structure proved unsustainable. For investors, the initiative demonstrated both DLF's master-planning capability and the risks inherent in private infrastructure financing.
Cyber City established a self-reinforcing commercial flywheel. The concentration of corporate campuses attracted high-earning professionals, driving demand for nearby modern housing, retail, and dining. Because DLF owned the surrounding land bank across all three segments, pre-sales from residential developments and rental income from retail properties funded subsequent phases of office construction. This integrated model enabled DLF to capture value across multiple property asset classes.
By 2006, Gurugram had emerged as North India's primary corporate hub, with DLF as its dominant commercial landlord. The transformation relied on long-term capital deployment and patient execution: land acquired in the 1980s was developed with private infrastructure in the early 1990s, occupied by corporate tenants in the late 1990s, and monetised through high-margin residential and commercial development in the 2000s.
This multi-decade cycle set the stage for DLF's next corporate phase. Following the financial success of its Gurugram master plan, management sought to replicate the model across new asset classes and geographic regions, relying increasingly on debt financing.
V. The $2.24B IPO Spectacular, Hubris, & The Great Debt Trap (2007–2016)
DLF's initial public offering in June 2007 marked a major milestone in Indian capital markets. Opening on 11 June and closing on 14 June, the offering comprised 175 million equity shares of ₹2 face value at ₹525 per share, raising ₹9,187.5 crore—approximately $2.24 billion at contemporary exchange rates. It stood as the largest public issue in Indian corporate history at the time, and when trading commenced on 5 July 2007, the stock listed at ₹573.60.8
Following the listing, DLF's market capitalization surpassed ₹2 lakh crore in late 2007 and early 2008, placing founder KP Singh among the world's wealthiest individuals on global ranking lists. To project its brand nationally, the company acquired the title sponsorship for the inaugural season of the Indian Premier League in 2008. Less than three decades after regulatory changes effectively barred DLF from developing land inside Delhi, the developer had reached the apex of corporate visibility.
However, the company subsequently embarked on a widespread expansion strategy that tested its capital allocation discipline.
First, DLF pursued aggressive geographic expansion. Attempting to replicate its Gurugram master-planning model nationwide, the company acquired high-cost land parcels at peak-cycle valuations in Mumbai, Hyderabad, Chennai, Kolkata, Kochi, Bengaluru, and several tier-2 cities. A prominent example was the acquisition of the National Textile Corporation mill land in Lower Parel, Mumbai—a high-priced transaction premised on uninterrupted real estate appreciation.
Second, the company expanded into non-core sectors. In 2007, DLF paid approximately $400 million to acquire a controlling stake in the ultra-luxury hotel chain Amanresorts.12 Simultaneously, management invested in wind power assets across Gujarat, Rajasthan, and Tamil Nadu, while pursuing hotel joint ventures, retail malls, Special Economic Zones (SEZs), and infrastructure projects.
While each venture offered an individual strategic rationale—hospitality promised exposure to expanding luxury travel, wind energy provided tax benefits and policy support, and SEZs aligned with government growth initiatives—collectively they departed from DLF's core competitive advantage. Unlike its Gurugram developments, which relied on low-cost, contiguous land assembled over decades, these capital-intensive projects offered no structural synergies. Rather than leveraging historic land bank arbitrage, they operated as balance-sheet extensions funded by IPO proceeds and bank debt.
When the 2008 global financial crisis struck, credit markets tightened and Indian residential demand slowed sharply. The newly acquired land parcels in regional markets generated little immediate cash flow while accumulating substantial holding costs. By the second quarter of fiscal year 2012, DLF's net debt escalated to ₹22,519 crore.9 Relative to the company's operational scale—evidenced by annual sales bookings of ₹4,070 crore in fiscal 2014—this debt burden posed severe liquidity risks.13
To stabilize its balance sheet, management launched a multi-year asset monetization program during a broader market downturn. In February 2013, DLF announced a target to reduce net debt by half, aiming for ₹10,000 crore to ₹11,000 crore within three years through non-core asset sales, equity issuance, and operational cash flows.14 In fiscal 2014 alone, the company generated ₹5,930 crore through divestments.13 On 10 February 2014, DLF sold its 97% stake in Amanresorts for $358 million to an investment vehicle involving founder Adrian Zecha and Peak Hotels & Resorts—realizing a loss relative to its $400 million purchase price and subsequent capital injections.12 The company also divested its wind energy assets and liquidated various regional land holdings. These included a four-acre parcel in Kochi sold for ₹111 crore in 2015, undeveloped land in Bengaluru and Chennai divided with a former joint venture partner in 2016,15 and eventually the Kolkata SEZ along with an adjoining 17.75-acre parcel sold to Srijan Group entities for ₹710.23 crore.16
This divestment sequence highlighted the financial cost of peak-cycle diversification. By acquiring illiquid, non-core assets with leverage at the height of the market, DLF was forced to liquidate them during a downturn when its balance-sheet pressures were public knowledge. The resulting value erosion demonstrated the structural risks of departing from its core Gurugram land bank model—a period of capital misallocation that remains a central reference point for assessing management discipline.
Regulatory and legal challenges further compounded DLF's financial strain. In May 2014, the Competition Appellate Tribunal upheld a ₹630 crore penalty imposed by the Competition Commission of India for abuse of dominant position regarding buyer agreements in the Belaire and Park Place residential projects.18 Five months later, in October 2014, the Securities and Exchange Board of India (SEBI) prohibited DLF, founder KP Singh, and five company executives from accessing securities markets for three years, citing deliberate suppression of material facts regarding subsidiary litigation in the 2007 IPO prospectus.17 As equity prices declined to record lows, a February 2015 business press assessment noted that the company was beset by multiple operational and financial challenges.19
By 2016, DLF retained its core land bank in Gurugram, but nine years of non-core expansion, heavy leverage, and regulatory penalties had severely damaged its balance sheet and market reputation. Resolving this leverage crisis required a structural recapitalization unprecedented in Indian real estate.
VI. The GIC Transformation & Debt Deleveraging (2017–2020)
By 2016, DLF faced a major balance-sheet hurdle: eliminating roughly ₹20,000 crore in net debt. Conventional restructuring options presented severe trade-offs. Issuing large volumes of new equity at depressed market valuations would dilute existing shareholders and risk promoter control. Selling the Gurugram commercial rental portfolio outright would surrender the group's primary source of recurring annuity income. Liquidating additional residential land holdings would shrink its future development pipeline. Meanwhile, relying solely on operating cash flows was insufficient, as mid-2010s residential pre-sales remained far below the level needed to service the debt load.
In August 2017, DLF announced a structural recapitalization that monetized unlisted promoter assets to fund corporate debt reduction. The promoter family, led by KP Singh, personally held a 40% stake in DLF Cyber City Developers Limited (DCCDL), the group's commercial rental subsidiary, outside the listed entity. Under the deal structure, Singapore sovereign wealth fund GIC acquired a 33.34% stake in DCCDL from the promoters for ₹8,900 crore—valuing the commercial rental arm at approximately ₹35,617 crore—while DCCDL repurchased the remaining 6.66% promoter holding for roughly ₹3,000 crore, generating total consideration of ₹11,900 crore for the family.20[^21]
Following transaction closure in December 2017, the promoters reinvested the proceeds into the listed parent company. The family infused ₹9,000 crore into DLF Limited through compulsorily convertible debentures, along with warrants requiring an additional ₹2,250 crore, which was fully paid in June 2019.2122 This mechanism transferred capital into the listed entity, allowing the promoters to convert a private, unlisted asset into listed equity while providing DLF with the funds required to pay down its leverage. GIC acquired a one-third stake in North India's premier commercial rental portfolio, and DLF significantly reduced its debt burden.
The transaction also carried structural implications for public investors. Because minority shareholders of DLF Limited did not own the private 40% stake in DCCDL, they received no direct cash proceeds from the ₹11,900 crore transaction. Instead, public equity holders traded equity dilution for balance-sheet recapitalization. The ultimate value of this trade depended on the subscription price of the new DLF shares relative to the company's intrinsic value. This recapitalization also consolidated promoter ownership in DLF Limited to approximately 74%, near the regulatory ceiling.23
Beyond deleveraging, the restructuring established a clear operational division between two distinct business models.
The development business, operating as DevCo within DLF Limited, functioned as a pure residential developer. DevCo manages the legacy land bank, launches housing projects, collects construction-linked milestone payments from buyers, and recognizes revenue upon project completion. Supported by customer funding for construction, DevCo operates with low structural capital intensity, though its financial results remain tied to residential launch cycles.
The commercial rental business, operating through DCCDL as RentCo, was structured as a ring-fenced annuity platform holding Grade-A office parks and shopping malls. Serviced by long-term corporate leases, DCCDL relies on asset-level, long-tenor debt that generates predictable cash flows flowing up to DLF Limited as dividends. Secured by prime commercial assets, DCCDL accesses lower borrowing costs than traditional real estate developers. On its Q1 FY27 earnings call, management reported an average borrowing cost of approximately 7.14% for the platform.24 CRISIL rates DCCDL's non-convertible debentures AAA/Stable, while ICRA maintains an equivalent AAA rating.7
The balance-sheet cleanup proceeded over several years, accompanied by accounting distortions and timeline shifts. In the third quarter of fiscal 2018, DLF reported a net profit of ₹4,091 crore, driven primarily by an accounting deemed gain from the GIC transaction rather than core operations—underscoring that headline net income frequently served as an unreliable guide to underlying performance.25 DLF also carried an inter-company payable of roughly ₹8,500 crore to the joint venture, targeted for settlement by 2020.26 In March 2019, the company raised ₹3,173 crore through a qualified institutional placement to prepay debt.27 By November 2019, DLF's net debt had risen 31% to ₹4,461 crore, even as management publicly targeted becoming debt-free within a year.28 Deleveraging gained traction thereafter, with net debt reduced by 54% over five quarters to ₹2,259 crore by the June 2022 quarter.29
This multi-year sequence demonstrated a persistent pattern in management guidance: while the company achieved its ultimate goal of eliminating gross debt in the development business, the actual timeline lagged initial public forecasts by several years. For investors, this history illustrates a propensity for optimistic scheduling when setting balance-sheet targets.
The restructuring concluded with a leadership transition. In June 2020, KP Singh stepped down after more than four decades at the helm, assuming the role of Chairman Emeritus at age 88. His son, Rajiv Singh, was named Executive Chairman, while professional managers Ashok Kumar Tyagi and Devinder Singh were appointed Managing Directors and joint chief executives. This transition shifted DLF from a founder-managed enterprise toward a professionally led corporate structure.
This reorganized framework was immediately tested by an external shock: the COVID-19 pandemic, which reshaped urban housing demand across India.
VII. The Modern Luxury Empire & Current Business Breakdown (2020–Present)
Following the COVID-19 pandemic, the Indian luxury housing market experienced an unexpected structural shift: rather than softening, demand accelerated dramatically.
Extended lockdowns reshaped residential preferences toward larger living spaces, modern amenities, and integrated community developments. Concurrently, rising equity markets, technology liquidity events, and expanding executive compensation created an affluent buyer base for whom multi-crore residences represented wealth allocation rather than financial stretch. Holding premium land parcels across the country's densest concentration of high earners in Gurugram, DLF was uniquely positioned to capture this demand cycle.
The development business. In fiscal 2025, DLF booked new sales of ₹21,223 crore—a 44% year-on-year increase—generating consolidated revenue of ₹8,996 crore, EBITDA of ₹3,111 crore, and a net profit of ₹4,357 crore.30 The primary catalyst was The Dahlias, launched in October 2024, which alone generated ₹13,744 crore in sales bookings during that fiscal year.30
Performance remained robust in fiscal 2026, though new sales bookings moderated slightly to ₹20,143 crore. Cash collections reached ₹13,517 crore, net profit before exceptional items rose 16% to ₹4,256 crore, and the year-end net cash surplus stood at ₹14,155 crore. Operational cash flow reached a record net cash surplus of ₹7,746 crore during the year—up 25%—prompting a dividend declaration of ₹8 per share, representing a 33% increase and a 400% payout on the ₹2 face value.531 The primary driver of FY26 bookings was DLF Privana North, where all 1,164 units across six 50-storey towers sold out in one week in June 2025 for approximately ₹11,000 crore, averaging ₹9.5 crore per unit, with non-resident Indians purchasing 27% of the total inventory.3233
Two underlying dynamics in the fiscal 2026 results warrant closer scrutiny. First, gross margins compressed materially year-on-year, a shift highlighted by financial commentators at the time.31 Record bookings accompanied by margin contraction indicate rising construction costs or a shift toward lower-margin product mix. Second, quarterly revenue and profit metrics offer limited analytical utility because DLF recognizes development revenue only upon project completion. The first quarter of fiscal 2027 illustrated this disconnect: revenue from operations declined sharply year-on-year to approximately ₹1,280 crore, while net profit rose 4% to ₹794 crore, supported by operating cash flows of ₹1,317 crore on collections of ₹2,406 crore.243435 On the earnings call, management noted that fiscal 2028 would mark "an inflection point from a reporting perspective, wherein all our large products, starting from The Arbour, will start to contribute to the P&L."24 Consequently, DLF's reported income statement acts as a lagging accounting indicator, whereas cash flows and pre-sales bookings provide the real-time measure of operational trajectory.
The first quarter of fiscal 2027 also highlighted quarterly sales volatility. New bookings for the quarter dropped to ₹657 crore—a fraction of the annual ₹20,000 crore target—because DLF introduced no new project launches during the period.3435 Management reaffirmed its full-year guidance despite the slow start, attributing the lower bookings entirely to project launch schedules.36 This claim remains subject to verification against execution over subsequent quarters.
The rental business. Operating through DCCDL, the commercial rental portfolio provided the group's stable earnings base. By the first quarter of fiscal 2027, the operational office portfolio expanded to 44.6 million square feet with 95% occupancy, while the retail portfolio reached approximately 5 million square feet at 97% occupancy. Together, these operational assets carried a gross asset value of ₹91,810 crore, with weighted-average monthly rents of ₹109 per square foot for office space and ₹218 per square foot for retail.34 On the Q1 FY27 earnings call, management reported that the office portfolio had surpassed 50 million square feet when including projects under construction, maintaining portfolio occupancy above 95% by area and 97% by rental value, with recently completed assets—including Cyber Park, Atrium Place, Downtown Gurgaon, and Downtown Chennai—nearing full occupancy.2437
The retail portfolio is anchored by prime regional properties, including DLF Mall of India in Noida, along with DLF Promenade, DLF Emporio, and The Chanakya in New Delhi.3 Retail rental yields running at double office rates underscore a structural reality of urban Indian commerce: high-end luxury retail space remains severely supply-constrained compared to commercial office inventory.
Management targets a group rental exit run-rate of ₹7,300 crore to ₹7,500 crore for fiscal 2027, alongside a medium-term objective of ₹10,000 crore in annual rental income.24 Achieving these milestones will require timely completion of ongoing developments and sustained high occupancy across commercial assets.
Optionality. Outside its core residential and commercial businesses, DLF holds three strategic initiatives:
Mumbai. DLF re-entered the Mumbai real estate market in July 2025 with The Westpark in Andheri West, developed in partnership with Trident Realty under a 10-acre Slum Rehabilitation Authority scheme. Phase 1—comprising four 37-storey towers across 5.18 acres and 416 units—sold out in under a week for approximately ₹2,300 crore against a planned outlay of roughly ₹900 crore.3839 The full project encompasses eight towers across 2 million square feet, with projected total sales exceeding ₹10,000 crore.38 Structurally, this entry relies on an asset-light joint development model rather than the capital-intensive land purchases that characterized DLF's 2007 Mumbai expansion.
Data centers. DLF has committed capital toward a data center and IT campus development at Noida Sector 143, involving a planned investment of approximately ₹3,400 crore, supported by an anchor client agreement for roughly 370,000 square feet of space.4041 On the Q1 FY27 earnings call, management clarified the scope of the project, emphasizing that DLF will act strictly as a commercial developer and facility landlord rather than an operational data center operator.24 This approach bounds operational execution risk, while positioning DLF primarily as a real estate provider to the technology sector rather than a direct operator.
Goa. In North Goa, DLF is planning 60 to 65 ultra-luxury villas across 38 hilltop acres at Reis Magos, priced between ₹40 crore and ₹60 crore per unit. Management stated that regulatory approvals are secured but confirmed that sales bookings have been paused pending resolution of a public interest litigation. The project accounts for approximately ₹2,000 crore, or roughly 10%, of management's fiscal 2027 sales booking guidance.3642
Underpinning these initiatives is a launch pipeline of 37 million square feet with an estimated gross development value of ₹1,14,500 crore. Having launched 13 million square feet valued at ₹54,285 crore, DLF retains 25 million square feet of upcoming projects representing ₹60,215 crore in remaining development value.34
For investors, DLF's corporate structure operates through two distinct economic models: a development arm that monetizes strategic land reserves into lump-sum cash flows aligned with project launches, and a rental arm that generates long-term, inflation-linked commercial revenues backed by AAA-rated financing. Ultimately, evaluating DLF depends on determining how much of its current performance stems from a durable competitive moat in key micro-markets versus exposure to a favorable luxury real estate cycle.
VIII. Helmer's 7 Powers & Porter's 5 Forces: The DLF Moat Analysis
Stripping away the narrative raises a strategic question: if a competitor were backed with ₹50,000 crore to challenge DLF's position in Gurugram, could it succeed?
Cornered resource. This is DLF's strongest competitive power and approaches an absolute advantage within its specific geography. The land underlying DLF City, Golf Course Road, Cyber City, and the Southern Peripheral Road was assembled during the 1980s and 1990s at agricultural prices from a fragmented ownership base that no longer exists in that format. A competitor today cannot purchase contiguous acreage on Golf Course Road at any price, because no such land is available for sale nor is there a mechanism to assemble it. This advantage translates directly into unit economics: DLF can price luxury apartments at levels competitors cannot match on margin because its land cost is a historical artifact rather than a current market expense. The evidence for this power is not management assertion, but the empirical market outcome: when DLF launches projects on legacy land, the entire inventory clears within days and cash conversion follows.
The structural limitation is that this power represents a finite cornered resource, not an replicable operational capability. It expires when the legacy land reserve is exhausted. The 25 million square feet of remaining pipeline is finite, forcing DLF to resume land purchases—deploying ₹545 crore on land acquisitions across two quarters, primarily through strategic parcels and municipal auctions in Gurgaon and the broader region.24 Land acquired at 2026 auction valuations necessarily carries 2026 margin structures rather than 1985 development margins.
Scale economies and ecosystem lock-in. Cyber City operates as a self-contained commercial ecosystem, integrating captive power infrastructure, transit connectivity, retail dining precincts, and a dense concentration of corporate employers. For a multinational evaluating a Global Capability Centre location in North India, the district's agglomeration is itself the core product: the talent pool consists of neighboring corporate employees working next door. An overall occupancy rate above 95% across a 44.6 million square foot commercial portfolio provides operational proof of this dynamic.34 However, this advantage remains strictly location-bound rather than enterprise-wide, as DLF's commercial properties in Chennai and Hyderabad do not share in Gurgaon's local network density.
Brand and pricing power. In Indian residential development, buyers pay the majority of the purchase price before construction is completed. Brand equity functions not as conventional marketing, but as a credit substitute for execution risk. Buyers pay a premium to a developer they trust to complete the project, and DLF's ability to sell ₹11,000 crore of unbuilt residential units within a single week reflects the market's financial pricing of that credibility.32 The Dahlias achieving sales realizations above ₹1 lakh per square foot represents the same mechanism at the ultra-luxury level.24 The strategic caveat is that this buyer trust was earned recently and was visibly absent a decade ago during the company's financial restructuring.
Counter-positioning. Weak. The separation between development and commercial rental entities is a logical capital structure rather than a counter-positioning moat. Competitors such as Godrej Properties, Prestige Estates, Embassy Group, and Brookfield-backed entities can adopt identical organizational split models, and several already operate through listed real estate investment trusts. DLF possesses an established execution of a common structure rather than a model that competitors are structurally unable to copy.
Process power, switching costs, network economies. Not present in a material capacity. Construction management relies on standard industry practices rather than proprietary processes. Homebuyers incur no structural switching costs between developers. While office tenants sign multi-year leases with financial lock-ins, these represent contractual obligations rather than self-reinforcing network effects.
Analyzing the broader industry structure through Porter's framework:
Buyer power is low in the super-luxury residential segment. A buyer paying ₹271 crore for a penthouse is purchasing address scarcity rather than optimizing on a price-per-square-foot basis.1 Buyer power is noticeably higher in commercial office leasing, where corporate tenants maintain negotiating leverage and evaluate alternative locations across the National Capital Region.
Supplier power is moderate and bifurcated. Land costs are fixed for the legacy land bank, providing a permanent cost advantage on historical inventory. Conversely, construction inputs remain exposed to market inflation; rising prices for steel, cement, and labor flow directly into project costs, as evidenced by the gross margin compression observed in fiscal 2026.31
Threat of new entrants is low within DLF's core micro-markets but moderate elsewhere. The primary barrier is not capital availability, but the scarcity of contiguous licensed land in prime locations alongside the complex regulatory and administrative navigation required in Haryana.
Threat of substitutes remains low for Grade-A office campuses in the short term, as prime business districts with established talent pools cannot be readily substituted by cheaper buildings in peripheral locations. However, this dynamic remains exposed to structural changes, including hybrid work adoption, AI-driven hiring adjustments among IT and business process outsourcing tenants, and potential shifts in corporate expansion velocity. Management acknowledged on its Q1 FY27 earnings call that office leasing experienced temporary softness due to corporate AI hiring assessments and geopolitical uncertainty, before reporting initial recovery indicators in subsequent weeks.24 This statement illustrates management explicitly acknowledging substitution and demand-flexibility risks.
Competitive rivalry is intense across mid-market and premium housing in the National Capital Region, where developers including Godrej Properties, M3M, Signature Global, and Smart World compete aggressively. In contrast, rivalry remains limited in the super-luxury corridor along Golf Course Road, where DLF's primary competition consists of its own secondary resale market.
Synthesizing these dynamics for investors: DLF commands one dominant advantage in its cornered land resource, one strong location-bound agglomeration effect, one recently restored brand premium acting as a credit substitute, and no structural process, network, or counter-positioning advantages. While this constitutes a tangible business moat, it is geographically narrower than the headline status of "India's largest developer" implies, as its core earnings power remains anchored to a single district in Gurugram. This raises a fundamental historical question: how has this business model performed when tested by major economic downturns?
IX. Historical Falsification Layer: Testing Moats, Capital Allocation, & Governance Claims
Claim 1: The legacy land bank plus execution capability constitutes an unassailable moat.
The mechanism capable of invalidating this claim is not competitive substitution—no rival developer can recreate Golf Course Road. Rather, it is an execution failure severe enough to erode the brand premium that converts land into upfront pre-sales cash.
Substantial evidence challenges this assumption. Buyer associations at two Gurugram developments—The Belaire and Park Place—appealed to the Competition Commission of India, which ruled in 2011 that DLF had abused its market dominance by imposing one-sided buyer agreements, altering building plans unilaterally, and delaying project handovers without meaningful compensation. The Competition Appellate Tribunal upheld a ₹630 crore penalty—representing roughly 7% of DLF's annual turnover—in May 2014. Three months later, the Supreme Court directed DLF to deposit the full penalty amount into an interest-bearing account pending appeal, requiring ₹50 crore within three weeks and the remaining balance within three months.1843 These proceedings coincided with widespread, multi-year handover delays across DLF's residential portfolio throughout the 2010s.
This evidence narrows the claim rather than invalidating it entirely. While land ownership sustained a permanent cost advantage, it provided no protection against execution flaws or customer friction. The revised proposition is that DLF commands a cornered land resource paired with an operational capability rebuilt since 2020, which remains untested through an economic downturn. Buyer confidence has clearly recovered, as demonstrated by rapid sellouts at Privana North and Westpark, but these launches occurred during a buoyant market. The true test will be a softer market cycle: a major project launch that fails to clear, or delivery delays on flagship developments like The Arbour or Privana that trigger consumer disputes or regulatory filings.
Claim 2: Management and governance meet institutional standards.
The mechanism that breaks this claim is a history of disclosure lapses or political entanglements, where the historical record remains complex regardless of ultimate legal outcomes.
In October 2014, the Securities and Exchange Board of India (SEBI) barred DLF, KP Singh, Rajiv Singh, Pia Singh, and other senior officials from securities markets for three years, citing alleged suppression of material facts in the 2007 IPO prospectus.17 In March 2015, the Securities Appellate Tribunal quashed the prohibition by a majority decision, though the presiding officer dissented and recommended a six-month ban.4417 SEBI appealed to the Supreme Court, which issued notice in April 2015 before the appeals were eventually disposed of as withdrawn.45 SEBI separately imposed a financial penalty on DLF in February 2015.46
Separately, land licensing in Haryana generated sustained political scrutiny. In February 2008, Skylight Hospitality—an entity associated with Robert Vadra—acquired 3.53 acres in Shikohpur for ₹7.5 crore and subsequently agreed to sell the parcel to DLF for ₹58 crore by June 2008. Senior administrator Ashok Khemka cancelled the land mutation in October 2012, citing procedural irregularities.4748 A state-appointed inquiry panel subsequently cleared both parties and criticized the cancellation, and in April 2023 the Haryana government submitted an affidavit to the Punjab and Haryana High Court confirming that revenue officials found no statutory violations in the transfer.48
While the judicial record contains no findings of criminal wrongdoing by DLF, evaluating governance standards requires assessing institutional risk rather than strictly legal liability. Prior to 2017, DLF operated as a founder-centric enterprise navigating a discretionary state licensing framework, featuring a prolonged regulatory challenge over IPO disclosures that ended in a split tribunal ruling rather than definitive exoneration. Governance structure improved following the 2017 GIC transaction, which introduced a major institutional investor with board representation into DCCDL, while the 2020 appointment of professional joint chief executives separated daily operations from promoter family ownership. However, the promoter family continues to hold approximately 74% of the listed entity—near the statutory ceiling of 75%.23 Consequently, public shareholders remain minor partners. Key metrics to monitor include institutional voting patterns on related-party transactions and executive remuneration, alongside auditor notes in annual filings.
Claim 3: Capital allocation is disciplined.
The historical record from 2007 to 2016 refutes this claim for that era. Capital deployed into Amanresorts, wind power, peak-cycle land acquisitions across six metropolitan areas, and concurrent commercial real estate projects was financed through equity capital and bank borrowing, only to be liquidated under financial strain during a market downturn.121315 The Amanresorts acquisition highlights this pattern: acquired for roughly $400 million and divested seven years later for $358 million—excluding interim capital injections and debt servicing costs.12 Furthermore, balance-sheet deleveraging targets announced in 2013 missed initial schedules, and net debt was still expanding as late as November 2019 despite public commitments to eliminate debt within twelve months.1428
Subsequent management decisions reflect greater capital discipline. Re-entering Mumbai through a joint development partnership on a Slum Rehabilitation Authority project avoids the capital-intensive land purchases that failed during the 2007 expansion.38 Similarly, the data center venture is structured strictly as a core real estate development rather than an operating infrastructure platform.24 Recent land acquisitions have remained measured and focused primarily on Gurugram.24 Furthermore, higher dividend payouts and a substantial net cash balance in fiscal 2026 indicate a cautious approach to capital deployment.
A balanced assessment supports a more constrained claim: capital allocation under current leadership has remained conservative and core-focused for roughly six years. While significant, this track record is shorter than the preceding decade of balance-sheet expansion and has occurred entirely during a supportive property cycle. The primary development that would invalidate this revised view is a large, debt-financed acquisition outside Gurugram, mirroring the 2007 strategy. Management noted during the Q1 FY27 earnings call that it is actively exploring further expansion opportunities in Mumbai, marking the market segment where capital discipline will be tested.24
Claim 4: Geographic expansion is a reliable growth vector.
DLF's track record outside its home market demonstrates the limits of geographic expansion. After acquiring sites in Hyderabad, Chennai, Kolkata, Kochi, and Bengaluru during the mid-2000s real estate boom, the company spent the subsequent decade liquidating or restructuring those holdings: selling its Kochi land parcel in 2015, dividing out Bengaluru and Chennai holdings in 2016, and divesting the Kolkata Special Economic Zone along with adjacent land to Srijan Group entities for ₹710.23 crore.1516 None of these regional projects replicated Gurugram's pricing power or operating margins, primarily because DLF lacked the master-planned scale and land-bank dominance it held in its flagship market.
Historical performance refutes the assertion that national expansion represents a proven growth engine. A more defensible thesis is that DLF can execute asset-light joint ventures in external markets where local partners manage land acquisition and municipal approvals. Currently, this model relies on a single milestone: the initial sellout of Westpark Phase 1 in Mumbai.38 One successful launch does not establish an operational track record. Key indicators to monitor include sales velocity and pricing across subsequent phases of Westpark, execution of the slum rehabilitation requirements without legal or administrative delays, and resolution of the public interest litigation in Goa required to proceed with launches included in fiscal 2027 guidance.3642
Taken together, this empirical examination supports a nuanced conclusion. DLF commands a genuine competitive moat, but one that is geographically concentrated in Gurugram and finite in duration. Corporate governance has strengthened through institutional involvement but remains centered on promoter control. Capital allocation practices have been restored but remain untested in a prolonged market downturn. Finally, the company's ability to replicate its core success in new geographic markets remains unproven.
X. Current Management, Governance, & Transcripts Analysis
Whereas founder KP Singh expanded DLF primarily through land assembly and regulatory negotiation, Executive Chairman Rajiv Singh—an MIT-trained mechanical engineer—has focused on product design and positioning. As the principal architect of DLF's modern strategy, he moved the developer up-market, establishing new regional price ceilings through ultra-luxury developments such as The Camellias, The Dahlias, and DLF Privana. He was also directly involved in negotiating the 2017 partnership with GIC and instituting the capital discipline that followed.
The operating layer below the chairman consists of professional executives with clear domain separation. Joint Managing Director and Chief Executive Officer Ashok Kumar Tyagi oversees finance, balance-sheet strategy, investor relations, and financial guidance. Joint Managing Director and Chief Executive Officer Devinder Singh directs design, construction, and project delivery. On earnings calls, the leadership team routinely includes Sriram Khattar for the rental portfolio, Aakash Ohri for sales and marketing, and Badal Bagri as Chief Financial Officer.37 This distributed executive structure contrasts with the founder-centric governance model of earlier decades, allowing domain specialists to address operational details directly with analysts.
Ownership structure defines another critical dimension of corporate governance. Promoter equity stands at approximately 74%, near the regulatory ceiling.23 While high insider ownership aligns family wealth directly with share performance, it leaves public shareholders holding roughly a quarter of the equity register, rendering minority votes non-contestable and limiting public shareholder influence to institutional advocacy. In contrast, GIC's 33.34% holding in DCCDL functions as a direct governance control, providing the sovereign wealth fund with explicit contractual rights as a joint venture partner rather than a minority public investor.20
Earnings call transcripts provide empirical evidence for evaluating management execution and strategic priorities.
On guidance discipline. Recent financial reporting demonstrates conservative target-setting followed by consistent delivery. DLF achieved ₹21,223 crore in new sales bookings for fiscal 2025 against guidance in the high teens, and recorded ₹20,143 crore in fiscal 2026, aligning with its target range.305 This performance marks a clear departure from the 2013–2019 period, when balance-sheet deleveraging repeatedly missed management's public schedules.
On quarterly volatility. The first quarter of fiscal 2027 highlighted how launch timing creates reporting swings. Management explained that pre-sales bookings fell to ₹657 crore because the company introduced no major project launches during the quarter, while maintaining its full-year sales guidance of ₹20,000 crore.36 Executives emphasized that operational priority remains focused on cash flow generation and embedded profit margins rather than headline booking totals.37 A quarterly operating cash flow of ₹1,317 crore against ₹657 crore in pre-sales bookings supports that operational focus,34 though meeting the full-year ₹20,000 crore guidance will require generating nearly the entire annual pre-sales target across the remaining three quarters.
On luxury sales velocity. Analysts raised questions during the Q1 FY27 earnings call regarding slower absorption at The Dahlias, where 34 units were booked during the quarter. Management stated that the pace reflected a deliberate pricing strategy, with entry-level residences priced above ₹100 crore and realisations exceeding ₹1 lakh per square foot, while pointing to an experience centre opening after Diwali as a future sales catalyst.24 This exchange illustrates a persistent strategic tension: whether to accelerate land bank monetization at peak market prices or restrict volume to maximize price realisations and long-term land values. If realization rates per square foot remain firm or expand as sales volume moderates, management's pricing thesis remains intact; if pricing softens alongside lower volumes, it would signal demand deceleration.
On capital deployment. DLF ended the first quarter of fiscal 2027 with a net cash position of ₹15,200 crore, of which approximately ₹11,305 crore was held in RERA-mandated 70% escrow accounts and was therefore not immediately available for corporate use.34 Management has maintained a consistent capital allocation framework: maintaining a debt-free development balance sheet, increasing dividend payouts, and pursuing selective land acquisitions and partnership opportunities in external markets. The ₹545 crore committed to land purchases across two quarters represents a conservative deployment relative to total reserves.24 Critics argue that holding large cash balances at modest yields while distributing modest dividends depresses return on equity; conversely, management maintains that maintaining substantial liquidity provides essential protection for a developer operating in a cyclical property market.
On commercial office leasing. Management offered a candid assessment of commercial office demand during the Q1 FY27 earnings call, attributing the quarter's softness to corporate uncertainty surrounding AI-driven hiring adjustments and global macroeconomic conditions, before noting a recovery in enquiries from Global Capability Centres and multinational tenants in subsequent weeks with stronger momentum expected in the second and third quarters.24 This acknowledgment highlights an external operational risk for the commercial rental business, underscoring that reaching management's medium-term rental target of ₹10,000 crore depends on sustained growth in corporate office absorption.
In summary, current management has established operational credibility by meeting guidance targets and providing specific explanations for quarterly fluctuations rather than relying on macroeconomic generalization. However, this track record has been built entirely during an extended real estate upswing, leaving executive execution untested through a major market downturn.
XI. Strategic Position, Risk Radar, & Bull vs. Bear Case
The risk radar, evaluated by strategic severity:
Geographic concentration remains DLF's primary structural risk. The vast majority of the company's net asset value is concentrated in Gurugram and the wider National Capital Region, where its land reserves and development pipeline are heavily weighted.49 An adverse shift in Haryana's land licensing posture, a restrictive judicial ruling on Aravalli eco-sensitive zone boundaries, infrastructure bottlenecks in Gurugram, or a broader downturn in the regional luxury housing market would simultaneously impact both the development and commercial rental divisions. Without internal geographic diversification, this concentration serves as both the foundation of DLF's competitive moat and its primary point of vulnerability.
Cyclicality in luxury absorption represents a key demand risk. Indian residential real estate historically operates in prolonged, pronounced cycles, and the post-2020 luxury expansion has been exceptionally rapid. The buyer profile for residences priced above ₹10 crore overlaps significantly with individuals whose wealth is tied to equity markets and startup liquidity. A market drawdown or a sharp rise in borrowing costs could trigger a non-linear contraction in discretionary luxury demand. The decline in first-quarter fiscal 2027 sales bookings to ₹657 crore illustrates how rapidly booking figures adjust when project launches pause, highlighting the potential volatility if end-user demand slows.34
Commercial demand and corporate automation poses a long-term structural risk. DLF Cyber City Developers Limited (DCCDL) relies heavily on technology services firms, business process outsourcing operators, and global capability centers—sectors where artificial intelligence may compress the relationship between revenue growth and office headcount. Because commercial landlords receive rent based on leased desk space rather than tenant revenue, hiring slowdowns directly affect office space absorption. Management cited corporate assessments of AI-driven workforce needs as a contributing factor to softer leasing activity in the first quarter of fiscal 2027.24 While portfolio occupancy exceeding 95% and high pre-leasing in newly completed towers provide strong operational stability,34 upcoming lease renewals make corporate headcount trends a key variable over a multi-year horizon.
Execution risk in expansion markets remains format-specific. Developing under Mumbai's Slum Rehabilitation Authority framework requires rehousing existing residents, securing regulatory clearances, and managing complex administrative and legal processes. Consequently, the rapid initial sales success at Westpark Phase 1 does not guarantee the project's long-term rehabilitation timeline.38 Similarly, the ultra-luxury villa project in North Goa remains paused pending the resolution of public interest litigation.42
Regulatory and political exposure remains embedded in the core business model, given that land development licenses in Haryana depend on state-administered discretionary frameworks and considering the company's historical record of regulatory scrutiny.48
Accounting revenue recognition dynamics. The completed-contract accounting method provides conservative financial reporting, but it creates temporary divergences between reported net income and real-time operational performance. Headline earnings can spike during quarters with major project handovers or non-operational accounting adjustments, as occurred with the deemed gain from the GIC transaction in the third quarter of fiscal 2018,25 while lagging behind periods of strong pre-sales bookings and cash collections from newly launched developments.24 Evaluating the business strictly on income statement metrics can distort underlying performance.
The bull case. The positive investment thesis rests on four pillars: - Historical land cost advantage: The low acquisition cost of legacy land holdings provides a durable margin advantage that competitors acquiring land at current market prices cannot replicate. - Deleveraged development balance sheet: The development business carries zero gross debt alongside a substantial net cash balance, eliminating refinancing risk and marking a complete reversal from the company's heavy debt load a decade earlier.534 - Contracted rental cash flow: DCCDL's commercial portfolio generates predictable annuity income backed by AAA credit ratings, establishing a stable cash floor that insulates corporate solvency during residential downcycles—a protective buffer absent during the 2008 downturn.67 - Empirical pricing power: Rapid sellouts of major developments, including the ₹11,000 crore sellout of DLF Privana North within a single week, demonstrate strong brand credibility and buyer demand in its core market.32
The bear case. Counterarguments offset each element of the positive thesis: - Finite legacy land pipeline: The margin advantage diminishes as legacy holdings are developed and replacement acreage is acquired at market prices; the 25 million square feet of remaining pipeline represents a finite asset stock rather than an expandable supply.34 - Restricted cash balances: A significant portion of the reported net cash position remains restricted in RERA escrow accounts, while unallocated capital weighs on overall return on equity.34 - Commercial tenant concentration: The recurring rental cash flow relies on corporate office demand from technology and outsourcing tenants navigating structural shifts in workforce requirements. - Cyclical peak pricing: Pricing power demonstrated at the height of a luxury real estate upswing may not endure across a full economic cycle, as annual sales bookings moderated from ₹21,223 crore to ₹20,143 crore alongside gross margin compression in fiscal 2026.3031 - Capital reallocation risks: Given historical challenges with non-core expansion, strategic decisions regarding capital deployment outside the core Gurugram market carry heightened execution risk.
Key performance indicators. Three primary metrics provide the clearest signal of operational performance:
First, new sales bookings relative to project launches, evaluated alongside cash collections. Sales bookings in isolation are sensitive to launch timing, whereas cash collections lag sales announcements. Evaluated together, they indicate real market demand and actual liquidity inflows. Throughout fiscal 2027, the critical benchmark is whether DLF achieves its ₹20,000 crore annual pre-sales target across the final three quarters while maintaining average price realizations. Stable realizations alongside lower sales volume would support management's strategy of protecting price levels, whereas falling realizations combined with lower volume would signal softening demand.
Second, DCCDL rental income growth paired with same-portfolio occupancy and net absorption. Headline rental revenue can increase through new building completions even if underlying occupancy declines in mature properties. With baseline occupancy standing above 95% by area and 97% by rental value, tracking occupancy stability across existing properties provides a more reliable gauge of corporate office demand than headline rental figures alone.2434
Third, net operating cash flow relative to capital expenditure and land acquisition outlay. This metric serves as the primary indicator of balance-sheet discipline. DLF generated a record net cash surplus of ₹7,746 crore in fiscal 2026 while maintaining modest capital outlay for new land.524 A sustained shift toward heavy land acquisition spending relative to operational cash generation—particularly in markets outside the National Capital Region—would signal a return to the capital allocation risks observed during the 2007 expansion phase.
XII. Playbook: Key Business & Investing Lessons
Build the city, not the building. DLF's most durable strategic insight was that a developer controlling contiguous land determines the broader pattern of value creation around it—shaping where offices, retail, and premium residential properties are located, and consequently capturing the resulting value uplift. Cyber City functions effectively not merely because of individual tower design, but because the offices, transit networks, power infrastructure, dining, and housing were planned as an integrated system by a single master developer. The principle extends beyond real estate: in industries with strong local agglomeration effects, controlling the underlying platform provides a greater long-term advantage than owning an isolated asset within it.
Buy the input decades before the market needs it—and maintain the capacity to hold it. Legacy land assembly represents the purest cornered resource in DLF's corporate history, but the strategy depended on two distinct factors: acquiring land early and maintaining a cost basis low enough to endure long periods without end-user demand. The second requirement is where most corporate strategies fail. An acquisition that appears strategically sound but relies on debt requiring near-term cash flow is not a long-term strategic posture; it is a leveraged trade dependent on market timing.
Euphoric capital poses severe downside risk. DLF raised ₹9,187.5 crore at the peak of a market cycle and deployed the capital into hospitality, wind energy, and regional land acquisitions in unfamiliar markets, before liquidating those assets during a subsequent market downturn.812 The underlying vulnerability was not simply the individual projects—several appeared plausible in isolation—but that none leveraged the developer's core competitive advantage. A key discipline test for capital deployment is whether an investment generates returns because of a unique operational capability or merely because capital is accessible.
Separate the cyclical engine from the annuity platform. Bifurcating volatile pre-sales residential development from contracted commercial rental income achieves two strategic objectives: it allows each business to maintain an appropriate capital structure, and it provides the broader group with a resilient cash floor during downturns. DLF Cyber City Developers Limited (DCCDL) secures AAA credit ratings against contracted rental revenue precisely because it is insulated from residential development risk.7 However, as the strategic moat analysis indicates, this organizational split represents a standard structural design rather than a proprietary moat—it can be, and has been, replicated by industry peers.
A sophisticated co-investor serves as a governance asset alongside providing capital. GIC's entry accomplished more than balance-sheet deleveraging. It established a sophisticated, contractually protected institutional partner inside the group's core commercial asset. For an enterprise with a history of founder-centric management and regulatory scrutiny, that partnership provides a structural oversight mechanism that independent board appointments rarely match. Investors evaluating family-controlled firms should look beyond public statements regarding governance improvements to determine whether a counterparty holding genuine economic leverage and contractual rights participates directly in corporate governance.
Prioritize cash flow metrics over reported income statements. DLF's completed-contract accounting methodology means reported quarterly revenue and profit figures can diverge significantly from real-time operational performance.24 This reflects a broader financial principle: when revenue recognition rules decouple reported earnings from current business activity, analytical focus must shift to metrics that reflect operational reality. For DLF, those fundamental indicators remain sales bookings, cash collections, and net operating cash flow generation.
XIII. Epilogue & Forward Outlook
One perspective on the DLF story presents a classic narrative of corporate transformation: a former cavalry officer takes over a constrained firm, negotiates with landowners across a rural district beyond Delhi, and builds North India's primary corporate hub from farmland. The trajectory spans eight decades, expanding from post-Partition housing layouts to an individual penthouse selling for ₹271 crore.1 That narrative highlights a significant arc in modern Indian business history.
A more analytical reading reveals a more complex reality. DLF expanded through regulatory arbitrage and strategic positioning. After securing a land asset of extraordinary scale, the company spent nearly a decade illustrating that controlling a cornered resource does not guarantee operational discipline. Management diversified into hospitality and wind energy using bank debt, accumulating more than ₹22,000 crore in net debt,9 while incurring regulatory penalties from the competition authority over buyer contract terms.18 Corporate recapitalization relied not on core operational cash flows, but on a structural transaction that monetized a private promoter asset and reinvested the capital into the listed entity alongside Singapore's sovereign wealth fund.2021 Over the subsequent six years, management has operated with a degree of capital discipline absent during the prior decade.
Both narratives describe the same enterprise. Which version an investor prioritizes depends on whether current management discipline reflects a permanent operational shift or an alignment with an unprecedented luxury real estate upswing.
The near-term trajectory remains straightforward. The remaining legacy land pipeline—encompassing 25 million square feet with ₹60,215 crore in estimated development value—represents a finite harvest.34 The commercial rental platform functions as the primary compounding asset, targeting an exit rental run-rate of ₹7,300 crore to ₹7,500 crore for fiscal 2027 against a medium-term goal of ₹10,000 crore, with an eventual REIT listing providing strategic optionality.24 Meanwhile, projects in Mumbai, Goa, and the Noida data center campus serve as controlled operational tests, structured to limit balance-sheet exposure through asset-light structures and joint developments.243842
The central analytical question remains unchanged. DLF's core competitive advantage is substantial, but geographically concentrated. Previous attempts to replicate that advantage across other metropolitan markets proved unviable. The developer is tested once again, employing an asset-light model in complex regional environments—Mumbai, where development depends on partner land and administrative approvals, and Goa, where launches remain paused by public interest litigation. If this joint development approach succeeds, DLF will demonstrate a repeatable, national execution model. If it fails, the company will remain what it has historically been: a highly lucrative enterprise anchored to a single prime district in Gurugram, generating substantial cash flow until its legacy land reserves are exhausted.
That regional concentration remains a formidable operational position. However, it represents a distinct investment profile from a national developer platform—a distinction that accounts for a substantial valuation premium in equity markets.
References
-
₹271 crore for one penthouse: DLF's The Dahlias sets new luxury benchmark — Business Standard, 2026-08-10 ↩↩↩
-
Gurgaon: Penthouse in DLF Camellias sold for Rs 190 crore to Rishi Parti — Business Standard, 2024-12-09 ↩
-
About DLF — Corporate History and Portfolio — DLF Limited ↩↩↩↩↩
-
DLF Limited Share Price, Market Capitalisation — Bajaj Finserv ↩
-
DLF Limited Reports Strong Growth and Record Collections for FY26 — Q4 FY26 Earnings Call Transcript Summary, InvestyWise, 2026-05 ↩↩↩↩↩
-
DLF-GIC JV's Rental Income Climbs 16% To ₹5,525 Crore, Strong Office Demand Boosts FY26 Profit By 38% — Free Press Journal, 2026 ↩↩
-
DLF Cyber City Developers Limited — Rating Rationale — CRISIL Ratings, 2025-03-26 ↩↩↩↩
-
DLF IPO — Dates, Price, Issue Size and Listing Details — Chittorgarh ↩↩↩
-
DLF's Q2 net debt up Rs 1,000 cr to Rs 22,519 cr — Business Standard, 2011-11-11 ↩↩↩
-
A Family Enterprise — KP Singh and "Whatever the Odds: The Incredible Story Behind DLF" — The Weekend Leader ↩↩
-
IL&FS Scam: Gurgaon's Rapid Metro Was Based on Entirely Fraudulent Numbers — Moneylife ↩↩
-
Amanresorts Sold by India's DLF for $358m — CoStar News, 2014-02 ↩↩↩↩↩
-
DLF sales bookings up 7% in FY14 to Rs 4,070 cr; debt falls — Business Standard, 2014-05-30 ↩↩↩
-
DLF targets to halve debt in 3 yrs to Rs 11,000 crore — Business Standard, 2013-02-18 ↩↩
-
DLF sells land parcel in Kochi for Rs 111 cr — Business Standard, 2015-08-18 ↩↩↩
-
DLF completes INR 710 crore sale of Kolkata SEZ asset and land parcel to Srijan Group — PropNewsTime ↩↩
-
SAT quashes SEBI ban on DLF with 'majority order' — The Tribune, 2015-03 ↩↩↩
-
DLF told to pay Rs 630-cr fine — Business Standard, 2014-05-19 ↩↩↩
-
DLF beset by multiple issues — Business Standard, 2015-02-27 ↩
-
DLF sells 33% of rental arm to GIC for Rs 11,900 crore — Business Standard, 2017-08-26 ↩↩↩
-
Promoters infuse Rs 9,000 cr in DLF to reduce debt post closure of GIC deal — Business Standard, 2017-12-29 ↩↩
-
Promoters infuse Rs 2,250 crore in DLF against issuance of new equity shares — Business Standard, 2019-06-27 ↩
-
DLF Ltd — Shareholding Pattern and Key Financials — Screener.in ↩↩↩
-
Earnings call transcript: DLF Q1 FY2027 — Investing.com, 2026-08-04 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
DLF Q3 profit soars to Rs 4,091 cr on deemed gain from GIC deal — Business Standard, 2018-02-13 ↩↩
-
DLF to settle Rs 8,500 cr payable to JV with GIC by 2020 — Business Standard, 2018-08-21 ↩
-
DLF raises Rs 3,173 cr via QIP; to prepay debt — Business Standard, 2019-03-29 ↩
-
DLF's net debt rises 31 pc to Rs 4,461 cr; to become debt-free in next one year — Business Standard, 2019-11-08 ↩↩
-
DLF cuts net debt 54% in five quarters to Rs 2,259 crore in Q1 FY23 — Business Today, 2022-07-29 ↩
-
DLF Profit Rises 39% in Q4; Sales Bookings Up 44% to Record Rs 21,223 Crore in FY25 — Outlook Business, 2025-05 ↩↩↩↩
-
DLF FY26: ₹20,143 Cr Bookings, ₹4,408 Cr Profit — Margin Dip Sparks Concern — Whalesbook, 2026-05 ↩↩↩↩
-
DLF sells 1,164 luxury units for ₹11,000 cr in Gurugram's Privana North — Business Standard, 2025-06-18 ↩↩↩
-
DLF's Privana Legacy Continues: North Phase Sells Out — DLF Limited Press Release, 2025-06-18 ↩
-
DLF Q1 FY2027 slides: strong cash flow masks accounting-driven miss — Investing.com, 2026-08-04 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
DLF Ltd Q1 profit rises 4% to Rs 794 crore — Business Standard, 2026-08-03 ↩↩
-
DLF confident of meeting ₹20,000 cr FY27 pre-sales target despite weak Q1 — Business Standard, 2026-08-04 ↩↩↩↩
-
DLF Q1 FY27 Earnings Call: Reaffirms Rs. 20,000 Cr Sales Guidance, Office Portfolio Crosses 50 Mn Sq Ft — Cofacto, 2026-08 ↩↩↩
-
DLF's Mumbai Comeback: 'The Westpark' Sees ₹2,300 Crore Sell-Out in Just One Week — Outlook Business, 2025-07 ↩↩↩↩↩↩
-
DLF re-enters Mumbai market with premium residential project The Westpark — Business Standard, 2025-07-17 ↩
-
India's DLF to invest $408.4m in Noida data center and IT park — Data Center Dynamics ↩
-
DLF Plans to Invest Rs 3,400 Crore for IT Block and Data Centre Facility in Noida — EquityPandit ↩
-
DLF sticks to ₹20,000 crore target despite weak Q1, Goa launch awaits — Business Today, 2026-08-05 ↩↩↩↩
-
Supreme Court tells DLF to pay Rs 630 cr fine — Business Standard, 2014-08-27 ↩
-
Tribunal reverses capital markets ban for developer DLF — Reuters via Business Standard, 2015-03-13 ↩
-
SEBI moves Supreme Court against DLF — Business Standard, 2015-04-20 ↩
-
SEBI imposes $8.4 million penalty on property firm DLF — Reuters via Business Standard, 2015-02-26 ↩
-
Vadra firm's land mutation cancelled, DLF stock drops — Business Standard, 2012-10-17 ↩
-
Explainer: Why the Vadra-DLF land deal is under scanner — The Tribune ↩↩↩
-
Strong launch pipeline factored into realty major DLF's valuations — Business Standard, 2024-01-30 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube