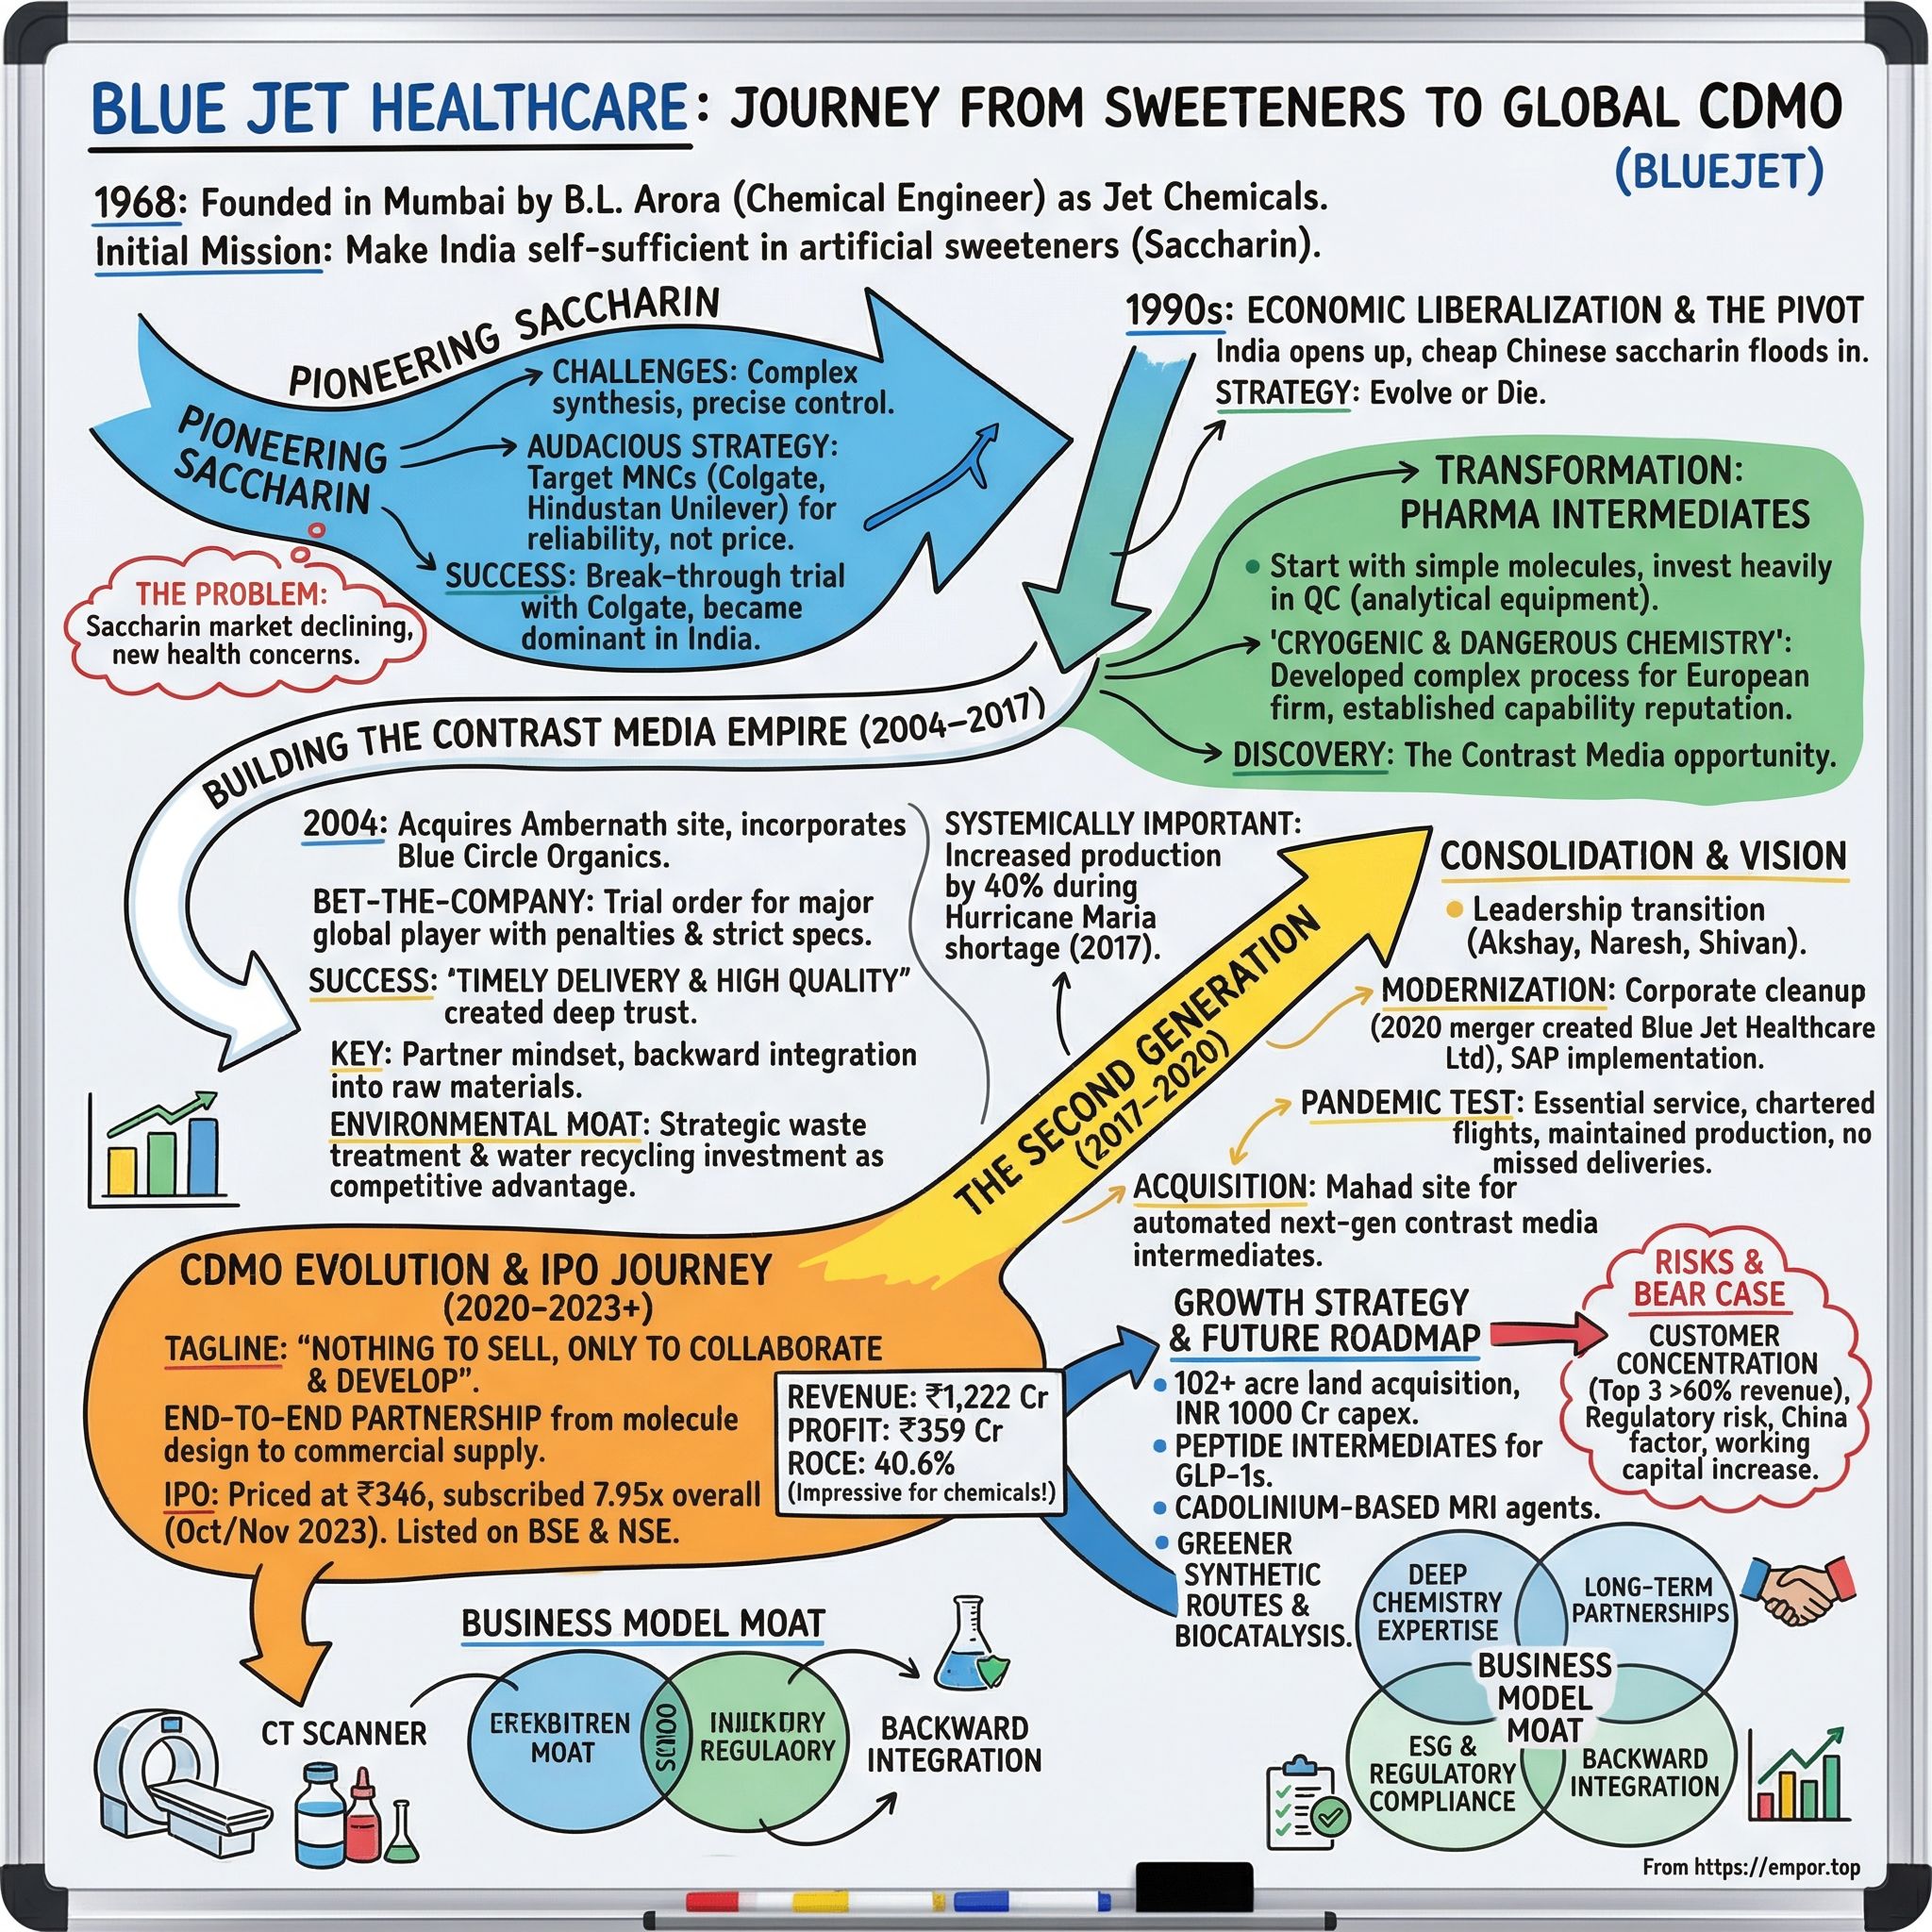
Blue Jet Healthcare: The Intermediate Man
I. Introduction & Episode Setup
Somewhere in a hospital in Ohio or Osaka or Oslo, a patient lies inside the bore of a CT scanner while a nurse pushes a syringe of clear liquid into a vein. The liquid is iohexol — an iodinated contrast agent sold by GE HealthCare under the brand name Omnipaque. Within seconds it floods the vasculature, and organs that were grey smudges resolve into sharp, readable anatomy. The patient will never know the brand. The radiologist barely thinks about it. And almost nobody in the chain — not the hospital, not the insurer, not the shareholder in GE HealthCare — has any idea that a meaningful share of the chemistry that made that molecule possible was manufactured in a plant in Maharashtra by a company that started life in 1968 making artificial sweetener.
That company is Blue Jet Healthcare. It has no consumer brand, no drug of its own, no salesforce calling on physicians. What it has is a position: it sells the molecule two or three synthetic steps before the finished drug, to a handful of customers who cannot easily replace it, in categories where switching suppliers means re-filing paperwork with regulators across dozens of countries.
That raises the framing question this story keeps circling back to: what does it actually mean to own an un-ownable step in someone else's supply chain? Not the branded product, not the API, but the advanced intermediate — the thing that has no market of its own, only a customer. It is a genuinely interesting economic position. It can be extraordinarily profitable. Blue Jet earned a return on capital employed of 40.35% in FY2025, on an EBITDA margin just shy of 38%.1 Those are numbers that usually belong to software companies, not to chemical plants in Raigad district.
But there is a second question, and by 2026 it has become the more urgent one. In FY2025 Blue Jet's revenue grew 44.7% and its profit after tax grew 86.4%.12 In FY2026 — the year that ended in March 2026 — revenue fell roughly 8% and profit after tax fell 18.8%.3 The June 2026 quarter continued the slide, with revenue down 17.4% year-on-year and net profit down 14.2%.4 Something that looked like a growth business one year looked like a cyclical one the next.
The company's explanation is destocking: a single innovator customer that had built inventory during a product launch stopped ordering while it worked the stockpile down. That is a specific, testable claim. The alternative reading is that FY2025 was a peak — that a business with two customers accounting for three-quarters of revenue and one molecule accounting for nearly half of it will always look like this, and the market simply hadn't been shown the downside yet.21
This is the story of how a saccharin maker became a critical node in the global diagnostic-imaging supply chain, why the contrast-media franchise it built over two decades is more defensible than most Indian chemical businesses, and why the thing currently driving its numbers is not that franchise at all. The route runs through origins, the contrast-media bet, a 2023 IPO that returned nothing to the company, the business as it exists today, the FY2026 reversal, the management and ownership record, and finally the first genuinely large capital-allocation decision this company has ever made — a greenfield plant in Andhra Pradesh that will cost more than the company earned in revenue last year.
 Subscribe on LinkedIn
II. Origins: Building India's Saccharin Franchise (1968–2004)
India in 1968 was a country that had decided, as a matter of policy, that it should make things itself. The licence raj was in full flower, imports were rationed, foreign exchange was hoarded, and an entrepreneur who could domestically manufacture something India otherwise had to buy abroad occupied a privileged position. It was into this world that B.L. Arora founded Jet Chemicals Pvt. Ltd., and chose an unglamorous target: saccharin sodium.
Saccharin is the oldest artificial sweetener in commercial use — about 300 times sweeter than sugar, discovered accidentally in a Johns Hopkins lab in 1879, and by the mid-twentieth century a workhorse ingredient in toothpaste, soft drinks, pharmaceutical syrups, animal feed, and, oddly, nickel electroplating baths. Making it well is not trivial. Making it to pharmaceutical grade — USP and BP standards, batch-consistent, with a documented impurity profile — is a different discipline again. Jet Chemicals became the first Indian manufacturer of saccharin and its salts,1 and that first-mover position gave it something more durable than a cost advantage: it gave it multinational customers.
This is the part of the story that matters for everything that follows. Selling a food and oral-care ingredient to companies like Colgate and Unilever means submitting to their audits, their documentation standards, their supplier-qualification regimes.5 A small Indian chemical firm in the 1970s and 1980s that could satisfy a multinational's quality function was learning, without quite knowing it, the exact skill set that would later be required to supply a global pharmaceutical innovator. The muscle memory of regulatory compliance — the paperwork, the change-control discipline, the willingness to be inspected — was built decades before it was monetised.
There is a second, quieter thing worth noting about the choice of saccharin. It is a molecule with an unusually promiscuous set of end markets. The same compound goes into toothpaste, into diet soft drinks, into animal feed premixes, into cough syrups as a taste-masking excipient, and into electroplating baths as a nickel brightener — an industrial application that has nothing whatever to do with sweetness.6
A manufacturer serving that spread learns to run a plant that switches grades and specifications constantly, and to maintain parallel quality regimes for food, pharmaceutical, and industrial customers simultaneously. That flexibility — modular blocks, fast changeovers, multiple specifications from shared assets — is precisely the operating model the company runs today across contrast media, sweeteners, and pharmaceutical intermediates.2 The capability was acquired for one reason and used for another, which is how most durable industrial advantages actually form.
The other formative lesson came from pain. In the late 1980s, Chinese producers flooded the sweetener market and prices collapsed.5 Akshay Arora, B.L. Arora's son and an organic chemist by training, responded not by fighting on price but by going upmarket: he took a saccharin by-product molecule to European customers and built a contract-manufacturing niche around it.5 Two principles hardened out of that episode and, by the family's own account, have governed the business ever since: prefer science-based products over generic ones where the only lever is cost, and stay inside a defined niche rather than chase scale for its own sake.5
That decision — go where the chemistry is harder rather than where the price is lower — sounds like something every management team says. What makes it credible in this case is that it was made under duress, by a chemist, at a moment when the alternative was available and cheaper to pursue. Cutting cost to defend a commodity position is the reflexive response; walking away from the commodity and finding a customer who values a harder molecule is not. The second-order effect was that the company acquired the habit of asking what a customer's problem actually was rather than what the customer's purchase order said — which is the entire premise of contract development and manufacturing, arrived at some three decades before the industry gave it an acronym.
It is worth being precise about what the saccharin business is today, because it is easy to over-read the origin story. Artificial sweeteners contributed ₹133.5 crore in FY2025 — about 13% of product revenue, down from roughly 18% the year before.2 The global high-intensity sweetener market is worth about US$2.9–3 billion, with annual demand of 37–40 thousand tonnes; Blue Jet's capacity sits at roughly 3.7 thousand tonnes, against a single Chinese producer with over 7 thousand tonnes.6 The company serves over 300 sweetener customers globally.6
It is a real business with real customers. It is not the investment case.
What it is, instead, is the control experiment. Because this is the one segment where Blue Jet unambiguously dominates its Indian niche — and it is also the one segment that has already been mauled by a competitor operating at a scale Blue Jet cannot match. That story arrives in Section VII, and it is the single most useful piece of disconfirming evidence available for anyone trying to assess how much the word "moat" is worth in this company's other segments. First, though, the pivot that made the moat question worth asking at all.
III. The Pivot: Pharma Intermediates and the Contrast Media Bet (1990s–2011)
Liberalization arrived in India in 1991 and it arrived, for the chemicals sector, as a threat dressed as an opportunity. Tariff walls came down. The comfortable arithmetic of import substitution — where being the only domestic producer was itself the business model — stopped working. A generation of Indian chemical companies discovered simultaneously that their protected margins were an artefact of policy rather than capability, and that the only durable escape was to sell to the world rather than to a captive home market.
Blue Jet's answer, arrived at over the back half of the 1990s, was to move from sweeteners into pharmaceutical intermediates. And in 1999 it made the specific bet that defines it: contrast media.5
It is worth explaining what contrast media actually is, because the economics follow from the chemistry. When a radiologist takes a CT scan, they are measuring how much X-radiation different tissues absorb. Soft tissue and blood absorb almost identically, which means blood vessels and many organs are effectively invisible. Contrast agents solve this by loading the bloodstream with an element that absorbs X-rays intensely — iodine. An iodinated contrast agent is essentially a molecular cage designed to carry three iodine atoms safely through the body, deliver a few minutes of radiographic visibility, and then be excreted by the kidneys without doing harm. MRI uses a different physical principle and a different element: gadolinium, a rare-earth metal whose magnetic properties change how nearby water protons relax, brightening the tissue around it.
Both are, in the end, exercises in careful organic chemistry. The finished agents — GE HealthCare's Omnipaque and Visipaque, Bracco's Isovue, Bayer's Ultravist, Guerbet's Dotarem — are branded pharmaceutical products sold into hospitals. But before you get to those, you need building blocks. Blue Jet commercialized 5-nitro isophthalic acid, its foundational contrast-media building block, in the year 2000, and spent the following two decades climbing the synthetic ladder from that starting material toward the more advanced, higher-value intermediates just below the finished API.6
It helps to picture the synthesis as an assembly line running backwards. At the end of the line sits the finished drug — a sterile, injectable solution in a bottle with a brand name and a marketing authorisation. One step before that is the active pharmaceutical ingredient, the pure molecule itself. One or two steps before that sit the advanced intermediates: compounds that already contain most of the finished molecule's skeleton but are missing the final, hardest transformations. Industry shorthand calls these positions n-1, n-2, and so on, counting backwards from the API. Blue Jet has spent two decades walking up that line — starting at 5-nitro isophthalic acid, a relatively simple building block many steps removed, and progressively taking on the more complex intermediates closer to the finished product.6
Each step up that ladder is worth more per kilogram, because each step embeds more of the chemistry the customer would otherwise have to do itself. It is also riskier, because the closer you get to the API, the more the customer's regulatory filing depends on exactly how you run your process — and the more painful it becomes for either party to change anything.
The strategic logic of stopping short of the finished product deserves to be stated plainly, because it is the heart of the business model. Making the branded contrast agent means owning the physician relationship, the marketing spend, the pharmacovigilance obligation, the product liability, and the full weight of drug regulation in every market you sell into. Making the advanced intermediate means none of that. What you carry instead is chemistry risk and environmental risk: multi-step syntheses at scale, hydrogenation, solvent recovery, and effluent that has to be treated rather than discharged.
Those are real barriers, and Blue Jet has treated them as such. The company invested in wastewater treatment capability as part of building the position, and its manufacturing blocks carry the accreditations — ISO, WHO-GMP, SMETA, FSSAI — that a global innovator's audit team looks for.1 Framing that spending as an ESG line item misreads it. In a business where a customer's decision to qualify you takes years and their decision to stop buying takes one failed inspection, compliance infrastructure is the price of the relationship, not a virtue signal.
By around 2011, the pitch had crystallised into something the company could sell repeatedly: reliable, on-time delivery of high-quality contrast media intermediates to customers who could not tolerate a supply interruption. That is a boring sentence. It also happens to be the entire product. Contrast agents are consumed in enormous volume — roughly 65 million gadolinium-enhanced procedures are performed globally each year, and iodinated procedures dwarf that.7 The innovators who sell them run continuous manufacturing operations and cannot afford a gap in feedstock. A supplier who has never missed becomes progressively harder to replace, not because of affection but because the cost of finding out whether the alternative is equally reliable is asymmetric: the upside is a small price saving, the downside is a stockout in a product that hospitals schedule procedures around.
Consider what a purchasing manager at a global contrast-media manufacturer is actually optimising for. The intermediate is a small fraction of the cost of the finished agent — the expensive inputs are iodine and the manufacturing and regulatory overhead of a sterile injectable. Saving 10% on an intermediate barely moves the finished product's economics. Interrupting supply of that intermediate, however, halts a production line for a drug that hospitals schedule CT and MRI capacity around, and potentially triggers a shortage that makes the trade press. The 2022 global iodinated-contrast shortage, which forced hospitals worldwide to ration scans, is the sector's living memory of what that looks like.
Against that backdrop, a supplier with a twenty-year record of never missing is not competing on price. They are competing on the absence of a reason to think about them at all.
That asymmetry is the closest thing Blue Jet has to a structural advantage, and by the early 2010s it had translated into direct relationships with three of the four companies that dominate the global category.6 What it had not yet translated into was a corporate structure anyone could invest in.
IV. Second-Generation Leadership and Consolidation (2017–2020)
Family businesses in India tend to fail at one of two moments: the handover, or the institutionalisation. The handover is the easier problem — sons and daughters can be trained. Institutionalisation is harder, because it requires the founding generation to accept processes that constrain them, and because the relationships that built the business often live in one person's head.
Blue Jet approached this through the back half of the 2010s. Akshay Arora — who brings, by CARE Ratings' description, over four decades of expertise in organic chemistry and who personally steered the shift into contrast media and high-value pharma intermediates — moved into the Executive Chairman role.1 His son Shiven Arora, who had joined the board in December 2015, took the Managing Director seat with responsibility for finance and strategic initiatives.12 Naresh Shah joined as an Executive Director. The arrangement is exactly what it looks like: a founder-chemist retaining technical and customer authority, a next-generation family member owning the capital-markets-facing functions, and a professional executive layer beneath.
The trickiest part of any such transition in a relationship-driven business is not the org chart — it is the transfer of credibility. When a customer's supply-chain director has spent fifteen years dealing with one man about batch schedules and specification changes, that relationship does not automatically transfer to his son. What appears to have worked here is that the founder did not step away from the technical side at all. Akshay Arora retained the chemistry and the customers; Shiven took finance, strategy, and the capital-markets-facing work. The division splits along a natural fault line — the things that require decades of accumulated credibility stayed with the person who accumulated it, and the things that require a different skill set entirely moved to someone trained for them.
It is a less dramatic arrangement than a clean handover, and probably a more durable one.
The corporate plumbing followed. The Ambernath site had been acquired in 2004, and Blue Circle Organics had been incorporated to build API and intermediate capability alongside the legacy Jet Chemicals sweetener business. Running two entities made sense when they were two businesses. It made no sense at all if the intention was ever to raise outside capital or be valued as a single franchise. In 2020, Blue Circle Organics merged into Jet Chemicals and the combined entity was renamed Blue Jet Healthcare Pvt. Ltd. A new site at Mahad was added.
Today that footprint consists of three operating units in Maharashtra — Shahad (Unit I, 200.60 KL of installed capacity), Ambernath (Unit II, 833.60 KL), and Mahad (Unit III, 141.40 KL) — plus a solvent-storage facility at Morivali, Ambernath.2 Across two operating sites and eight manufacturing blocks, the company exports to more than 50 countries and serves a base of over 400 clients.1 Roughly 87% of FY2025 sales went overseas.2
One detail in that footprint is worth pausing on, because it recurs later. Blue Jet's capacity is measured in kilolitres of reactor volume, not tonnes of output — the standard unit for a multi-product fine-chemicals plant where the same vessels make different molecules in campaigns. That measure is what makes the flexibility real: a block designed for pharmaceutical intermediates can, with cleaning and changeover, run a contrast-media campaign instead. It is also what makes capacity utilisation a slippery number to interpret from the outside, since a plant can be fully utilised on low-value work or partly utilised on high-value work and report similar physical throughput.
None of this is a story in itself. Mergers of commonly-controlled entities and site acquisitions are administrative events. What matters is what they enabled: a single, auditable, professionally-governed company with a clean segment structure, five decades of operating history, and a customer list that included some of the most demanding buyers in the pharmaceutical world. That is an investable object. In 2023, the Aroras took it to market — and the structure of how they did it tells you more about their intentions than any strategy slide.
V. The IPO: A Pure Promoter Exit, Not a Growth Raise
The book build ran from October 25 to October 27, 2023, in a price band of ₹329 to ₹346 per share. It priced at the top. The offer comprised 2,42,85,160 shares aggregating ₹840.27 crore, and the stock listed on November 1, 2023, opening at roughly a 10% premium to the issue price.8
By the standards of Indian IPO drama, that is an unremarkable outcome — a decent debut, no fireworks, no disaster. What made it structurally significant is a detail that gets flattened out in most summaries: the entire offer was a secondary sale. Not a rupee of the ₹840 crore went to Blue Jet Healthcare. Every rupee went to the selling promoters, Akshay Arora and Shiven Arora.8 There was no fresh issue, no primary proceeds, no stated use of funds for capacity expansion, debt repayment, or working capital.
This is not a criticism. A 100% offer-for-sale is a completely legitimate structure, and for a debt-free, cash-generative family business it is arguably the honest one: the company did not need money, so the company did not take money. Capital was not raised because capital was not the constraint. But an investor reading incentives should register what the transaction was rather than what an IPO usually is. It was a liquidity event for a founding family that had built a business over fifty-five years and chose to convert part of it into cash and a public market price. Everything the family has done in the capital markets since — and there have been two further transactions — should be read as continuous with that decision rather than as a series of unrelated events.
There is also worth noting, on the sourcing side, what is not in the record. The selling-shareholder list contained the promoters. Public reporting on the offer identifies Akshay Bansarilal Arora, Shiven Akshay Arora, and Archana & Akshay Arora as the promoters of the company.8 Claims occasionally surface that a private-equity sponsor exited through this IPO; nothing in the offer documents or listing-period reporting reviewed here supports that. This was a family monetisation.
And then there is the part of the IPO week that does not appear in any of the celebratory listing coverage.
On November 3, 2023 — six days after the book build closed, two days after the shares began trading — a fire tore through Blue Jet's factory in the Mahad MIDC industrial area of Raigad district, Maharashtra. Eleven workers were killed. Seven more were injured.9 The district administration, acting on a recommendation from the Maharashtra Pollution Control Board's Raigad unit, ordered the company to halt production and to remove inflammable chemical goods from the premises within 72 hours.9 Blue Jet filed an intimation of the fire with the exchanges the same day.10
There is no way to write around this. Eleven people died at a plant belonging to a company whose shares had begun trading forty-eight hours earlier. The listing proceeded on schedule because the listing had already happened; the sequencing is coincidence, not concealment.
But the incident is a genuine data point about operating risk in a business that runs hydrogenation and multi-step organic synthesis at commercial scale, and it belongs in the narrative of how this company came public rather than in a risk appendix.
The remediation record is also part of the picture: Unit III has since operated, and the company's disclosed expansion programme at Mahad has proceeded under regulatory consent. What the episode establishes is that safety and environmental compliance at Blue Jet is not only a moat — a barrier that keeps competitors out — but also a hazard that can shut the company itself down.
It also raises a question the market did not much ask in late 2023 and probably should have. A company that lists without raising money is telling you it does not need money — which is a statement about the past, not the future. Blue Jet at listing was funding modest incremental expansions from cash flow, and that was genuinely sufficient for the business it then was. Less than three years later it would return to the market and raise a sum comparable to the entire IPO from institutional investors — a transaction taken up in Section IX. Nothing about that is dishonest; circumstances changed and the company's ambitions grew with them. But it does mean the "we don't need external capital" framing had a shorter shelf life than the IPO structure implied, and investors reading a debt-free balance sheet as evidence of permanent capital self-sufficiency were reading too much into it.
For readers building a view on management incentives, the IPO leaves one clear residue. The founders took ₹840 crore off the table at ₹346 a share in a transaction that gave the business nothing. That is the baseline against which the September 2025 offer for sale and the July 2026 institutional placement should be measured. First, though, what exactly the market was buying.
VI. The Business Today: Three Segments, One Dominant Customer
If you had read Blue Jet's IPO prospectus in late 2023 and then fallen asleep for eighteen months, you would not recognise the company on waking. The headline description in every piece of 2023-vintage coverage was of a contrast-media intermediates business — 67.7% of FY2024 revenue came from that segment.2 By FY2025 that was no longer true, and it was not true because contrast media had merely been outgrown. It was true because contrast media had actually shrunk.
Here is the primary data, from the disaggregated revenue note in the FY2025 annual report. Contrast media intermediates fell from ₹479.9 crore in FY2024 to ₹403.9 crore in FY2025 — a decline of about 16%.2 Artificial sweeteners rose marginally, from ₹128.2 crore to ₹133.5 crore.2 And pharmaceutical intermediates and APIs went from ₹94.8 crore to ₹462.2 crore — growth of 387.75% in a single year.2 Total product and services revenue reached ₹1,024.7 crore against ₹708.4 crore.2
So the FY2025 mix was roughly 45% pharma intermediates and API, 39% contrast media, 13% sweeteners.2 That is not a modest rebalancing. It is a company whose identity changed in twelve months, driven almost entirely by one product line — and it happened while the segment everyone associated with Blue Jet was going backwards.
(A note on sourcing: the Business Responsibility and Sustainability Report inside the same annual report shows a product mix of 68% contrast media, 18% sweeteners, 14% pharma intermediates — figures that align with FY2024, not FY2025, under a different classification basis.2 Anyone pulling segment data for this company should take it from the disaggregation note in the financial statements, not the BRSR table.)
What drove the pharma intermediates explosion was a single molecule with an unlovely name: TosMIC, or tosylmethyl isocyanide, an advanced intermediate in the synthesis of bempedoic acid.6 Bempedoic acid is a cholesterol-lowering drug developed by Esperion Therapeutics and sold as Nexletol and Nexlizet. It matters clinically because it lowers LDL cholesterol through a different mechanism than statins and is therefore an option for patients who cannot tolerate them. It matters to Blue Jet because in FY2025, the bempedoic acid intermediate alone accounted for roughly 45% of total operating income.1
Read that again.
Just under half of a company's revenue, from one intermediate, for one drug, from one innovator.
Blue Jet's mitigation is elegant and worth understanding. Rather than supplying a single API manufacturer, it supplies multiple — including Neuland Laboratories and Fareva — who each make bempedoic acid API for the same innovator.11 The company describes this as being the arms dealer rather than the combatant: whichever API maker wins the volume, Blue Jet ships the intermediate.11
That genuinely de-risks the relationship layer. It does absolutely nothing about the demand layer. If the end customer stops ordering, having two API-maker customers instead of one means two customers who have both stopped ordering. FY2026 proved this in the most literal way possible, and Section VIII is where that plays out.
The concentration shows up in the audited numbers with unusual clarity. In FY2024, one customer accounted for approximately 56.71% of revenue from the sale of products. In FY2025, two customers accounted for approximately 41.44% and 34.05% respectively — three-quarters of product revenue between them.2 CARE Ratings puts the top five customers at roughly 79% of FY2025 revenue.1 Going further back, GE Healthcare alone represented about 64% of FY2023 revenue.6
Most companies describing themselves as diversified CDMOs would find those numbers difficult to explain. Blue Jet's management does not really try to; it frames depth as the point. The stated philosophy is that the company has "nothing to sell but only to collaborate and develop" — that it does not push a catalogue at customers but embeds itself in their process chemistry. There is evidence for this. Around 70% of contracts are backed by long-term supply agreements.6 The company manages parts of the supply chain for GE Healthcare directly, which makes it materially harder to swap out.6 It has been positioning itself at what the industry calls "n-2" — two synthetic steps before the final API — which is deliberately upstream of where a more integrated peer like Divi's Laboratories or Neuland competes.
The honest assessment is that "collaborate, don't sell" is a real description of how a niche intermediates supplier behaves, and also a description that conveniently reframes customer concentration as customer intimacy. Both readings are supported by the same facts. What separates them is not rhetoric but observed behaviour under stress, and until FY2026 there was no stress to observe.
It is also worth being clear about what "n-2 positioning" buys and what it costs, because management uses the phrase as a differentiator and it deserves testing. The benefit is that Blue Jet avoids the regulatory and liability burden of being an API manufacturer while capturing much of the chemistry value — a genuinely attractive trade in a category where API-level compliance is expensive and unforgiving. The cost is that it sits one commercial layer further from the end demand signal, with less visibility into the innovator's inventory position than the API maker has, and no direct contractual relationship with the party whose ordering behaviour actually determines its revenue. In a smooth year that distance is invisible. In a destocking year it is precisely why a supplier gets whipsawed harder than the parties closer to the end market. FY2026 was the demonstration.
For context on how narrow the FY2025 base really was: revenue of ₹1,048.29 crore of total operating income was measured against ₹721.53 crore the prior year; profit after tax of ₹305.20 crore against ₹163.75 crore.1 EBITDA margin expanded from 33.34% to 37.78%, and ROCE from 28.62% to 40.35%.1 Those are spectacular numbers. They were also, in substantial part, one product ramping into a launch stockpile. The gap between those two sentences is the entire debate about this company.
VII. The Contrast Media Franchise: Testing the Moat
Strip away the pharma-intermediates story and look at what Blue Jet built over twenty-five years, because it is the part of the business with the strongest claim to genuine defensibility — and the part where that claim can actually be tested.
The market structure is unusually favourable to a supplier. Global contrast-media formulations were valued at about US$5.9 billion, growing at 7–8% annually, split roughly 74% iodinated agents for X-ray and CT, 24% gadolinium agents for MRI, and 2% microbubble agents for ultrasound.6 The top four players — GE HealthCare, Bracco, Bayer, and Guerbet — controlled about 75% of the market in CY2024, with the leader alone at 27%.6 Within iodinated agents, GE's Omnipaque holds 31–33% share and its Visipaque another 12–14%; Bracco's Isovue 15–17%; Bayer's Ultravist and Guerbet's Optiray around 10–12% each.6
An oligopoly downstream is normally bad news for a supplier — concentrated buyers have bargaining power. What makes this one different is that the buyers are not price-optimising commodity purchasers. They are pharmaceutical companies whose contrast agents are registered products with defined manufacturing routes filed with regulators in every market they sell into. Changing an intermediate supplier is a regulatory event, not a procurement decision. That is what creates switching costs here — not loyalty, not relationships in the sentimental sense, but requalification cost and the risk of a filing amendment.
The concrete evidence that this has translated into position is reasonably strong. Blue Jet contributes more than 75% of India's exports of ABA-HCl — 5-amino-N,N'-bis(2,3-dihydroxypropyl) isophthalamide hydrochloride, the key advanced intermediate for iohexol and iodixanol.6 That single product accounts for around 59% of contrast-media segment revenue.6 The company has commercialised roughly twenty contrast-media molecules spanning MRI, CT, and X-ray diagnostics,1 and its customer relationships in the segment run from four to twenty-six years.1 It is not a marginal supplier; it is embedded.
The demand backdrop right now is also, on the evidence, a tailwind rather than a headwind — which is worth stating because it cuts against a lazy bear framing. GE HealthCare's own 2026 disclosures describe global contrast-media demand as close to outpacing total market supply, with the Pharmaceutical Diagnostics segment delivering organic revenue growth of 14.6% on strong volume and pricing, and management expecting the market to roughly double over the next decade.1213 That is the largest player in the category, on the record, saying the constraint is supply. Whatever went wrong at Blue Jet in FY2026 — and plenty did — a maturing contrast-media end market is not the explanation.
Now the falsification test, and it does not come from contrast media.
Sodium saccharin is the segment where Blue Jet is closest to unambiguously dominant. It was India's first producer. It holds the country's only dedicated pharma-grade saccharin capability meeting USP and BP standards. It supplies over 300 global customers across oral care, beverages, pharmaceuticals, and agrochemicals.6 By any conventional reading, that is a moat.
In FY2024, that segment's revenue fell 27% year-on-year, because Chinese producers intensified competition and priced aggressively into the market.6 The largest China-based saccharin manufacturer operates capacity of over 7 thousand tonnes per annum against Blue Jet's 3.7 thousand tonnes.6 Blue Jet retained its long-term contracts with the major FMCG accounts — the relationships held — but the spot market repriced around it, and the segment has not recovered its old growth trajectory since. FY2025 sweetener revenue rose just 4.10%,2 and pricing pressure in artificial sweeteners was named by the company as one of two drivers of the FY2026 revenue decline.3
So what does this tell us about the contrast-media moat? Weighing it properly: the saccharin precedent is highly relevant — same company, same management regime, same customer-relationship playbook, and a recent, economically material outcome. But the mechanism is not identical. Saccharin is a large-volume commodity chemical where capacity is the weapon and Chinese producers hold a decisive scale advantage. Contrast-media intermediates are lower-volume, regulatorily entangled products where the customer's own filings create friction that price alone cannot overcome.
The calibrated conclusion is that the moat claim survives, but in a narrower form than the headline suggests. It is not "Blue Jet has durable pricing power because it has deep customer relationships." The saccharin experience refutes that general version outright: deep relationships preserved volume there and did not preserve price. The version that survives is narrower and mechanism-specific — Blue Jet holds a defensible position in products where a customer's regulatory filings name its process, and that defensibility is a function of requalification cost, not of trust. The KPI that would falsify even the narrow version is realised pricing and volume share in ABA-HCl specifically. If Chinese capacity ever qualifies into GE's or Bracco's filings at scale and Blue Jet's contrast-media revenue per kilogram starts compressing the way saccharin's did, the narrow claim breaks too.
One further risk deserves flagging honestly rather than dramatised. In April 2026, GE HealthCare announced the first patient dosed in the Phase 2/3 LUMINA trial of mangaciclanol, a manganese-based MRI contrast agent carrying FDA Fast Track designation, positioned as an alternative to gadolinium-based agents on retention, supply-security, and environmental grounds.7 This is not a near-term commercial threat — it is a mid-stage clinical asset. But it is a reminder that Blue Jet sits downstream of chemistry choices made by companies it supplies rather than controls. A category-level substitution in gadolinium chemistry would eventually reach the intermediates that feed it, and Blue Jet would have no vote in the matter.
That is the long horizon. The short horizon turned out to be considerably more eventful.
VIII. The FY26 Reversal: Destocking or Structural Reset?
The first quarter of FY2026 was, on the face of it, magnificent. Revenue of ₹354.8 crore, up 118% year-on-year. Profit of ₹91.2 crore.414 Analysts covering the stock had a target price of ₹865 on it from Motilal Oswal's April 2025 initiation, which modelled a 27% revenue CAGR and a 24% EBITDA CAGR over FY2025–27, with average EBITDA margins of 35.1%.6 The story was working.
Then the orders stopped.
Second-quarter revenue came in at ₹165.5 crore — down 20.5% year-on-year and down 53% sequentially.15 The mechanism was not subtle. Pharma intermediates and API revenue fell 80% quarter-on-quarter, from roughly ₹212 crore to ₹42 crore.15 The innovator customer behind bempedoic acid had built substantial inventory during the drug's launch into regulated markets and spent the year working it down.
Blue Jet was not selling less because prescriptions had fallen. It was selling less because its customer already had the material sitting in a warehouse.
The third quarter was worse in year-on-year terms: revenue of ₹192.4 crore, down 39.6%, with EBITDA down 62% and profit after tax down 39%.16 The stock fell about 19% over two days in February 2026, trading near a 52-week low of ₹358 — within a rounding error of its ₹346 IPO price, two and a quarter years on.1617 ICICI Securities cut FY2026–28 EPS estimates by 12–22% and its target price from ₹750 to ₹500 while maintaining a Buy; Emkay cut earnings roughly 25% and its target from ₹600 to ₹400; JPMorgan and Emkay carried Sell ratings citing execution risk.16
Sequentially, the recovery began. Q3 was up 16% on Q2, Q4 was up 22% on Q3 at ₹234.67 crore, and Q1 FY2027 was up 24.9% on Q4 at ₹293.1 crore.161819 But the year as a whole was unambiguous: FY2026 revenue of ₹947.3 crore against ₹1,030 crore, down about 8%; profit after tax of ₹247.8 crore against ₹305.2 crore, down 18.8%; EBITDA margin compressed from 37.78% to 31%.31 The company attributed the decline to customer inventory destocking in pharma intermediates and pricing pressure in artificial sweeteners.3 Pharma intermediates revenue for the full year came in around ₹298 crore, down roughly 35%.15
And the June 2026 quarter, the most recent reported period, still showed revenue down 17.4% and profit down 14.2% against the prior year, even as sequential momentum improved.419 Contrast media revenue in that quarter fell about 40% sequentially — but on transit timing rather than demand, with roughly ₹30 crore of goods sitting in transit at the period end.18
So: air pocket, or peak?
The bull reading has real support. Management's position on the Q1 FY2027 call was that the pharma intermediates segment rebounded strongly as destocking normalised, that there is clear secular growth at the front end with consistent consumption and strong monthly growth, and that the company has good visibility for at least the next three to four quarters.18 Prescriptions for the underlying drug never stopped; a destocking cycle by definition ends when the stockpile clears. And the sequential recovery through Q3, Q4, and Q1 is consistent with that story rather than against it.
The bear reading has equally real support, and it is not primarily about whether orders come back. It is about what the episode revealed regarding the shape of the earnings stream. A single product line moved from ₹212 crore to ₹42 crore in one quarter.
Whatever else is true, that establishes the amplitude of this business's swing factor, and it establishes it in the company's own audited record rather than as a hypothetical. Nothing about a demand recovery makes that amplitude smaller; it just points it upward for a while.
Sell-side commentary through the downturn also raised a more specific concern — that the innovator has been shifting some European manufacturing arrangements, introducing uncertainty about Blue Jet's long-run share of that molecule.20 That claim has not been confirmed by the company and should be held at the confidence its evidence supports, which is: an analyst concern, not an established fact.
The calibrated position, on the evidence available on 1 September 2026, is this. Destocking is well-supported as the proximate cause: the mechanism is specific, the timing fits, the sequential recovery is consistent with it, and the end-market demand signal never turned negative.
What is not established is that FY2025's intensity repeats. FY2025 included a launch-phase inventory build, and launch builds happen once. A business can have both a genuine multi-year demand vector and a FY2025 revenue level that was inflated by a non-recurring stocking event — those propositions are compatible, and the market appears to be pricing only the first.
Which brings up the valuation tension, stated plainly and without adjudication. As of this writing the stock trades on a trailing P/E of roughly 47, against about ₹11,100 crore of market capitalisation, with ROCE at 26.1% and ROE at 19.4%.21 Those return figures have compressed materially from FY2025's 40.35% ROCE.1 A multiple that expands while trailing earnings fall and returns on capital compress is a market expressing confidence in a recovery it has not yet seen in the numbers.
That may prove correct. It is nonetheless a tension worth naming rather than narrating away.
The working-capital picture deserves the same treatment, and here the primary source is unambiguous. Gross current asset days, excluding cash and investments, stood at approximately 333 in FY2025 against 277 in FY2024.1 Export receivables ran around 92 days, inventory around 114 days including goods in transit, with credit terms extended to the largest contrast-media customer running up to roughly 190 days, against creditor days of just 39 — producing an operating cycle of about 167 days.1
The consequence showed up exactly where it should: operating cash flow collapsed to ₹39.08 crore in FY2025 from ₹232.84 crore in FY2024, purely on higher year-end receivables and inventory.1
A company earning ₹305 crore of accounting profit converted ₹39 crore of it into operating cash.
That is not fraud and it is not even unusual for an exporter with a 190-day-terms anchor customer. But it is the mechanism that matters most for what comes next, because a business whose growth consumes cash is about to embark on the largest fixed-asset programme in its history. Before that, the people making the decision.
IX. Current Management: Incentives, Ownership, and the Capital Allocation Test
The leadership structure is straightforward and, in the Indian mid-cap context, unremarkable: Akshay Arora as Executive Chairman, his son Shiven Arora as Managing Director, Naresh Shah as Executive Director, with an independent board that met five times in FY2025 and includes Girish Vanvari, Divya Momaya, Preeti Mehta, and Priyanka Yadav as non-executive independent directors.2 The father-son relationship is disclosed; no other directors are related.2
Compensation is modest relative to profitability and disclosed in full in the annual report, which is worth saying because the outline for this piece flagged the figures as low-confidence. They are not. For FY2025, Akshay Arora received ₹2.40 crore in basic pay plus ₹1.20 crore in allowances; Shiven Arora ₹3.06 crore basic plus ₹2.16 crore in allowances; Naresh Shah ₹1.69 crore basic, a ₹25 lakh bonus, and ₹2.06 crore in allowances.2 Against ₹305 crore of profit after tax, aggregate executive-director pay of roughly ₹13 crore is not a governance flashpoint.
Ownership is a more interesting story, and it has moved a long way in eighteen months.
At March 31, 2025, Akshay Arora held 11.97 crore shares or 68.99% and Shiven Arora 1.90 crore shares or 10.96%, with the total promoter group at approximately 86%.2 On September 10 and 11, 2025, Akshay Arora sold 1,07,34,529 shares — 6.19% of issued equity — through an offer for sale at a floor price of ₹675, a roughly 7.6% discount to the prevailing market price, in a base ₹400 crore offer with a matching greenshoe.2223 Promoter holding fell to 79.81%.3 Then, on July 6–9, 2026, the company itself raised ₹800 crore through a qualified institutional placement of 1,58,10,276 shares at ₹506 each, with Shamyak Investment and ICICI Prudential Mutual Fund together taking roughly 68% of the book.24 That dilution took promoter holding to approximately 73%.21
The OFS has a straightforward regulatory explanation. SEBI requires listed companies to reach 25% public shareholding within three years of listing, and with a November 2023 listing Blue Jet's clock runs out in late 2026. The sale was explicitly conducted to move toward minimum public shareholding compliance.23 That is genuine context and it should not be waved away.
Neither, however, should the transaction itself. A promoter sold roughly ₹725 crore of stock at ₹675 a share at a point when the stock had run substantially above its ₹346 IPO price, in the fiscal year immediately following the one blowout earnings year the company has had, and roughly twelve months before the earnings reversal became visible.
Whether that sequencing reflects foresight or coincidence is unknowable and not worth speculating about. What is knowable is the pattern: across the IPO and the OFS, the founding family has converted a substantial quantum of equity into cash, and has done so at prices well above where the stock trades today. That is a fact about incentives, and investors are entitled to weigh it without needing to allege anything.
On the positive side of the governance ledger, the promoter group has declared zero encumbrance — no pledged shares — as of the FY2026 year-end.3 For an Indian promoter family with a large concentrated holding, an unpledged position is a meaningful and underrated signal. It means the family is not financing anything against the stock, which removes an entire class of forced-selling risk.
There is one disclosed internal-controls issue that should be surfaced rather than buried, and it is in the primary document. The independent auditor's report in the FY2025 annual report states that the company's inventory records "are maintained manually in a spreadsheet and hence does not have a feature of recording audit trail (edit log)."2 The same report notes that the audit-trail facility on the main accounting software was not enabled until July 13, 2024, and that the auditors were unable to comment on whether audit-trail logging was enabled at the database level for a third-party software used to maintain employee master data.2
Weighing this properly matters. These are audit-trail disclosures under the Companies (Accounts) Rules, not qualifications on the financial statements, and a great many Indian listed companies carried similar language in the first years the requirement applied. The auditors, KKC & Associates LLP, also recorded that where audit trails were enabled they found no instance of tampering.2
So this is not evidence of manipulation. It is evidence of a specific control gap in a specific area — inventory — at a company where inventory runs at roughly 114 days and where the working-capital cycle is the single most important operational variable. That is exactly the wrong place to have spreadsheet-based records without an edit log. It is a legitimate diligence item, remediation of which investors should want to see confirmed in the FY2026 audit report.
Finally, capital allocation. And here the honest answer is that there is very little track record to assess. Since the 2020 consolidation, Blue Jet has not made acquisitions, has not written off major investments, and has not shuttered ventures — a review of the disclosed record in the FY2025 annual report and the December 2025 CARE rating rationale surfaces no impairments or abandoned projects.12 But absence of failure over a five-year period in which the company deployed capital only incrementally is not the same as demonstrated capital-allocation skill. The company has never before spent at the scale it is about to spend. Which makes the next section not a retrospective but a live test.
X. Capital Deployment: The Vizag Bet and Whether It's Sized Right
On February 28, 2026, on 102.48 acres of industrial land in the Rambilli Cluster Phase 2 at Anakapalli district, Andhra Pradesh, Blue Jet Healthcare broke ground on the largest project in its history. Nara Lokesh, the state's minister for IT, electronics and communications and HRD, attended alongside senior officials.25
The land, allotted by the Andhra Pradesh Industrial Infrastructure Corporation, cost ₹43.5 crore.3
The numbers on the facility itself are what make this consequential. Phase 1 carries board approval for ₹1,000 crore of investment, targeting roughly 1,000 KL of capacity dedicated to complex pharmaceutical intermediates and APIs, with multi-phase development potential disclosed at up to ₹2,300 crore.252 CARE Ratings frames the broader programme as approximately ₹1,300 crore over three to four years across capacity expansion, product development, backward integration, and an R&D centre.1
Put that against the base. FY2025 revenue was roughly ₹1,048 crore.1 Phase 1 alone is a capital commitment approximately equal to one year of revenue at the company's best-ever level. The full disclosed plan is more than double it. Blue Jet's existing installed capacity across three units totals under 1,200 KL;2 Phase 1 at Vizag adds roughly 1,000 KL on its own.
This is not an incremental debottlenecking. It is close to doubling the company.
The funding is conservative, which is the strongest thing to say for it. The ₹800 crore QIP covers most of Phase 1, supplemented by internal accruals from a balance sheet that carried overall gearing of 0.02x at March 31, 2025 against net worth of ₹1,132.88 crore, and just ₹44 crore of borrowings at March 2026.121 The company held liquid investments of ₹269.81 crore at FY2025-end including ₹98.12 crore of cash and ₹171.69 crore of debt mutual funds.1 It has demonstrated it will take working-capital debt when it needs to — it borrowed around ₹265 crore in June 2025 for peak export-shipment requirements and repaid it by September 2025 — but it has not funded fixed assets with leverage.1 CARE explicitly flags debt-funded capex pushing gearing above 0.25x as a negative rating trigger.1
Now the execution evidence, which is the part that actually matters and which is considerably less clean.
The FY2025 annual report, published in August 2025, told shareholders that the built-to-suit backward-integration unit at Mahad — a smaller, nearer-term project for a key contrast-media raw material currently imported — had its effluent treatment plant commissioned and ready for trial runs, with remaining infrastructure nearing completion, and that "commercial operations are expected by the end of FY2026."2 On the Q3 FY2026 call, the guidance had moved to validations expected in Q1 FY2027.26 On the Q1 FY2027 call in August 2026, management stated that ₹210 crore had been invested with ₹40 crore remaining and that commercial contribution was expected in H2 FY2027, while characterising the project as slightly ahead of schedule against its then-current plan.18
That is a roughly one-year slip from the guidance published in the annual report, on a project that is a fraction of Vizag's size and complexity.
Management's framing of "slightly ahead of schedule" is accurate against the revised timeline and misleading against the original one — which is a small but telling illustration of how guidance discipline works at this company. Nothing was concealed; each disclosure was accurate at the time. But an investor tracking only the latest statement would never know the project was originally due a year earlier.
The same pattern is visible on Vizag, and this is the more important instance. The FY2025 annual report stated that Phase 1 was "envisaged to create a capacity of 1,000 KL during 1st Phase to be commissioned by FY2028."2 On the Q1 FY2027 call, management guided to commercialisation at end-FY2029 to FY2030, with full ramp-up by FY2031–32.18 That is a two-year-plus extension on a project that broke ground six months ago, disclosed within a year of the original guidance.
The analytical conclusion is not that Vizag will fail. Greenfield chemical plants slip; anyone modelling otherwise is naive. It is narrower and more useful: Blue Jet's stated project timelines have moved out materially on both of its two current capital projects, within twelve months of first publication, and investors should discount future commissioning guidance accordingly rather than treating it as a schedule. FY2027 capex guidance of roughly ₹250 crore against a ₹1,000 crore Phase 1 is itself consistent with a long build.18
There is no acquisition comparison to make here — this is greenfield construction, not M&A, so there is no "did they overpay" question. The test is entirely about return on incremental capital once the asset exists. The existing asset base has generated ROCE between roughly 26% and 40% across recent years.121 Vizag's Phase 1 will add roughly ₹1,000 crore of capital employed to a base whose net worth was ₹1,133 crore at FY2025-end.1
For the blended return not to fall, the new plant needs to earn something close to the old economics — which means it needs contracted volumes at intermediate-like margins, not spot API work. That, in turn, means the capital-allocation question and the customer-concentration question are the same question wearing different clothes.
On R&D, proportionality demands restraint. Blue Jet opened a research centre in Hyderabad, operational as of August 2026, focused on peptide chemistry, biocatalysis, and GLP-1 intermediates.183
The pipeline framing has moved. On the Q3 FY2026 call management described approximately 20 active RFPs including six high-conviction Phase 3 programmes; by the Q1 FY2027 call the language was four high-conviction NCE programmes, two of which should fructify within FY2027–28.2618 That shift from six to four within two quarters is itself the relevant data point. Blue Jet has no disclosed track record of converting early-stage pipeline claims into commercial revenue at scale — the one molecule that did convert, bempedoic acid, arrived through a supply relationship rather than a discovery pipeline. Until a Hyderabad-originated programme produces revenue, this is technical capability and speculative optionality, not a growth pillar.
XI. Competitive Landscape: CDMO Peers and the Unverifiable Ranking Claim
Drop Blue Jet into a screen of Indian CDMO and pharmaceutical-intermediates companies and it lands among Divi's Laboratories, Laurus Labs, Neuland Laboratories, Suven Pharma, Syngene International, Aarti Pharmalabs, and Cohance Lifesciences. In February 2025, Macquarie initiated coverage of the Indian CRDMO sector with an Outperform stance grouping Blue Jet alongside Divi's, Suven, and Syngene — a useful marker of how the institutional market frames the competitive set, whatever one thinks of the call.27
But the peer comparison is less informative than it looks, because Blue Jet is not really running the same business as most of that list. Divi's is a scale generic-API and custom-synthesis manufacturer with capital employed an order of magnitude larger. Syngene is a research-services organisation selling scientist hours. Laurus is an integrated API-to-formulation player. Blue Jet sits deliberately upstream at n-2 in a narrow set of chemistries, with a customer count in the hundreds but a revenue concentration in the single digits of accounts. Its comparables on economics are not its comparables on business model.
At roughly ₹11,100 crore of market capitalisation the company sits below the peer median in size, and until FY2026 it sat above most of them on returns — ROCE of 40.35% and EBITDA margins near 38% in FY2025 are top-quartile numbers for the sector.121 The "smaller but more profitable" framing was accurate. It now requires the FY2026 caveat attached at all times: ROCE at 26.1%, ROE at 19.4%, EBITDA margin at 31%.213 Those are still respectable. They are no longer exceptional.
There is a further structural point about where Blue Jet sits that the peer screen obscures entirely. Most Indian CDMOs compete for programmes — they pitch, they win or lose a molecule, and their growth is a function of business-development throughput. Blue Jet largely does not. Its growth comes from two sources: existing customers moving more of their value chain onto it through forward and backward integration, and new molecules arriving through customers it already serves.2 That is a materially different growth engine, and it has a ceiling built into it. You cannot win share from a customer you do not have, and Blue Jet's customer count in the segments that matter is small by design.
This is why the Vizag decision is more strategically loaded than it first appears. A ₹1,000 crore multi-purpose API and intermediates plant is not the sort of thing you build to serve existing customers incrementally. It is the sort of thing you build when you intend to change the growth engine — to compete for programmes rather than only to deepen relationships. Whether Blue Jet has the business-development apparatus for that, having never needed one, is an open question the company has not been asked directly on any call reviewed here.
A note on sourcing discipline, because it bears on how one reads any claim about this company. A figure circulates in secondary coverage that Blue Jet "ranks 4th among 145 active competitors." That claim could not be traced to the DRHP, the RHP, any Frost & Sullivan or CRISIL industry section, or any company disclosure reviewed for this piece. It should not be repeated. It is the kind of number that acquires authority purely through repetition, and there is no basis in the primary record for it.
What can be evidenced is narrower and more useful. Blue Jet contributes more than 75% of India's ABA-HCl exports.6 It is the first and, per its own disclosure, the only Indian producer with dedicated pharma-grade saccharin capability. It holds direct, multi-year supply relationships with three of the four global contrast-media majors, running from four to twenty-six years.16 It has around twenty commercialised contrast-media molecules and roughly 70% of contracts backed by long-term supply agreements.16
Those are the real competitive facts, and they describe a specific kind of company: not a broad CDMO winning share across a market, but a specialist that has cornered a handful of molecules and holds them through regulatory entanglement.
That position is genuinely hard to attack from the outside. It is also, by construction, hard to grow beyond — which is precisely why the Vizag capacity and the NCE pipeline matter, and precisely why both remain unproven.
XII. Risks and the Bear Case
Most risk sections in most articles are checklists. This one can be shorter than usual, because the principal risks in this business are not hypothetical — they have already happened, and they have been described where they occurred.
The dominant risk is concentration, and FY2026 was its realisation rather than its warning. Two customers at 41.44% and 34.05% of product revenue, one molecule at roughly 45% of total operating income, one segment line falling 80% in a quarter.2115 Everything else on this list is second-order.
Competitive and pricing pressure from Chinese manufacturers is the second, and it too has a realised precedent rather than a theoretical one. Saccharin was contested and repriced.6 The open question is whether that ever reaches contrast-media intermediates, where the regulatory friction is higher. Blue Jet's own backward integration into 3-amino-1,2-propanediol at Mahad is partly a de-risking move against Chinese feedstock supply — an acknowledgement by the company that this exposure is real.62
Execution risk on Vizag has been discussed with its evidence attached. The relevant fact is the timeline movement on both current projects, not a generic caution about capex.218
The working-capital-plus-capex combination deserves a sentence of its own because the interaction is what matters. Gross current assets at 333 days and operating cash flow of ₹39 crore against ₹305 crore of profit in FY2025 describe a business where growth absorbs cash.1 Layering a ₹1,000 crore fixed-asset programme on top of that is precisely the combination that has historically stressed working-capital-heavy Indian chemical companies. The QIP substantially de-risks it — that is the point of raising equity rather than debt — but the cash-conversion trend remains the number to watch, not the headline margin.
Safety and environmental regulation is not merely a moat. The 2023 Mahad fire killed eleven people and drew a production-halt order.9 Multi-step organic synthesis with solvent recovery and hydrogenation is inherently hazardous, the company operates eight manufacturing blocks, and a serious incident at a site supplying a sole-source intermediate would hit revenue and customer confidence simultaneously.
Two overlays worth a line each. On credit: CARE assigned CARE A+ (Stable) / CARE A1+ ratings to ₹275 crore of bank facilities in December 2025 — an assignment, not an upgrade, and it explicitly named non-renewal or changed terms on long-term client contracts causing total operating income to fall below ₹800 crore as a negative trigger.1 Given FY2026 came in at ₹947 crore, that threshold is closer than it looks. On accounting: the inventory audit-trail gap discussed above sits directly on the balance-sheet line that matters most here.
Valuation risk closes the list. A trailing P/E near 47 on declining earnings, with returns on capital roughly a third lower than the prior year, prices a recovery in bempedoic acid volumes and an eventual payoff from Vizag.21 Neither has appeared in reported results yet.
XIII. Bull vs. Bear: The Investment Thesis, Stress-Tested
Run Blue Jet through Porter's five forces and the picture is genuinely unusual — strong on some axes, structurally exposed on the one that matters most.
Threat of new entrants: low. Building an advanced contrast-media intermediates capability requires multi-step chemistry expertise, effluent infrastructure, global regulatory accreditations, and — the binding constraint — years of qualification with a customer who has no incentive to qualify a second supplier unless the first one fails. Twenty-plus years of relationship history is not a moat you can buy.16
Supplier power: moderate. Iodine is the critical input and it is geographically concentrated; Blue Jet's backward integration at Mahad exists to reduce a specific import dependency.2 Manageable, and actively being managed.
Substitutes: low near-term, non-zero long-term. Contrast agents have no substitute for the imaging modalities they serve. But the chemistry within a modality can substitute — mangaciclanol is the live example, and Blue Jet has no seat at that table.7
Rivalry: low within its molecules, brutal outside them. Where Blue Jet holds a qualified position it faces little contest. Where it does not — saccharin spot markets — it faces Chinese producers with twice its capacity.6
Buyer power: very high, and this is the whole ballgame. Two customers, three-quarters of revenue. Credit terms extended to 190 days for the largest one, against 39 days of creditor support — the customer is being financed by the supplier.12 That is what buyer power looks like on a balance sheet.
Through Hamilton Helmer's 7 Powers, only two hold up under scrutiny. Switching costs are real, mechanism-specific, and evidenced: requalification and filing amendments, not preference. Cornered resource applies narrowly — the incumbent qualified position in ABA-HCl, where Blue Jet supplies over 75% of India's exports, functions as one.6 Process power is arguable at best; the company has genuine chemistry capability but no demonstrated cost or yield advantage that has been disclosed. Scale economies, network effects, branding, and counter-positioning do not apply. Two of seven, both narrow, is a real but bounded position — and it is worth noting that the powers Blue Jet has are the ones that protect existing revenue rather than the ones that generate new revenue.
The bull case, stated at its strongest. This is a company with an evidenced, mechanism-backed position in an oligopolistic end market whose largest participant says demand is close to outrunning supply and expects the category to double over a decade.1213 It has a debt-free balance sheet that funded a ₹1,000 crore expansion with equity rather than leverage, and a controlling family whose interests remain overwhelmingly in the stock. The FY2026 reversal has a specific, non-demand mechanism, and sequential revenue has now improved for three consecutive quarters. If bempedoic acid volumes normalise, three contrast-media launches land in FY2027 as guided, and Vizag ramps at anything near historical returns, the current earnings base understates the business.18
The bear case, stated at its strongest. FY2026 is not a warning about concentration risk — it is the proof. One molecule moved the consolidated P&L by double digits in both directions within eighteen months, and no amount of supplying two API makers changes that.
The saccharin record demonstrates that this management's relationship-based moat preserved volume but not price when a scale competitor arrived, so the moat should be underwritten narrowly rather than generally. Both current capital projects have slipped materially against published guidance within a year, and Vizag is roughly seven times the size of the one that slipped.218 The founders have monetised meaningfully twice — ₹840 crore at IPO and roughly ₹725 crore in the 2025 OFS — at prices above where the stock trades now.823 And an inventory control gap sits precisely on the line item that drives the cash conversion problem.2
The activist question, which nobody has yet asked publicly and which someone eventually will: why is a company with 190-day terms to its anchor customer and a 167-day operating cycle not disclosing segment-level receivables, and why did a business earning ₹305 crore of profit convert only ₹39 crore into operating cash without that being the headline of the FY2025 investor communication rather than a line in the rating rationale?1
The answer is probably benign — export timing, a large year-end shipment, the mechanics of a launch ramp. But the disclosure asymmetry between the growth narrative and the cash narrative is real, and it is the sort of thing that gets repriced when someone points at it rather than when it first appears.
The unresolved question, left open deliberately: is bempedoic acid a multi-year demand vector that hit an inventory air pocket, or was FY2025 a launch-stocking peak that will not repeat at that intensity? Management says the former with specificity and reasonable evidence.18 The record does not yet contain enough post-destocking quarters to confirm it.
The thing that resolves this is not commentary — it is two or three more quarters of pharma-intermediates revenue measured against the innovator's own prescription trends.
XIV. Playbook: Lessons for Founders and Investors
Owning the unglamorous step can beat owning the brand — but only where requalification is expensive. Blue Jet's contrast-media position is defensible because a customer's regulatory filing names its process, and changing that is costly. The same company's dominant position in saccharin proved worth very little when a competitor with twice the capacity decided to compete on price. The lesson is not "own the intermediate." It is "own the intermediate where the customer is regulatorily entangled with you," and to check for that entanglement rather than assume it travels with the business model.
Family-to-professional transitions can preserve customer trust — but watch the shares, not the statements. Blue Jet's second generation kept the founder-era relationships intact through the corporate consolidation, the IPO, and the scale-up. That is a genuine achievement and it is rarer than it sounds. It is also entirely compatible with a founding family selling ₹1,500 crore-plus of stock across two transactions. Both things are true, and only one of them appears in the investor presentation.
A 100%-OFS IPO is legitimate, and it is a different signal than a primary raise. The company did not need capital, so the company did not take capital — that is discipline. But it also means the listing was a monetisation, and the subsequent offer for sale and QIP read as continuations of that arc rather than as separate strategic events. Investors should read a promoter's capital-markets history as one continuous sequence, because that is how the promoter experiences it.
Concentration that reads as reliability in good years is the same concentration that produces volatility in bad ones. They are not separable properties. The very depth that let Blue Jet grow pharma intermediates 388% in one year is what let it fall 35% the next. A supplier cannot have the upside of being embedded in one customer's ramp without the downside of being embedded in that customer's destocking. Any framework that describes the first as a moat and the second as a temporary blip is describing the same fact twice with different adjectives.
Cash conversion is a strategy disclosure, not an accounting detail. Blue Jet's decision to extend 190-day credit to its largest contrast-media customer against 39 days from its own suppliers is not a treasury oversight — it is the price of the relationship, and therefore part of the moat's cost structure.1 Any business that describes itself as having deep, sticky customer relationships should be checked for exactly this: who is financing whom. Stickiness is often paid for in working capital, and the payment shows up in the cash flow statement long before it shows up in the narrative.
And guidance ages. Two projects, two published timelines, two material extensions within twelve months — each disclosed accurately, none flagged as a change.218 Reading only the latest statement produces a systematically optimistic picture. Keeping a dated log of what management said and when is unglamorous work that pays for itself.
XV. Epilogue: What to Watch
Blue Jet Healthcare enters the back half of 2026 as a company with a genuinely well-evidenced niche position in one segment and growth numbers driven almost entirely by a different, far more concentrated bet. That is the tension, and nothing in the next few quarters will fully resolve it.
Three KPIs are worth tracking above all others, and they should be read rather than calculated:
Pharma intermediates and API segment revenue, quarter by quarter, against the innovator's own prescription trends. This is the single number that adjudicates the destocking-versus-peak debate. Management has guided to good visibility for three to four quarters.18 Whether the segment stabilises meaningfully above its FY2026 run-rate, or merely returns to it, is the difference between two very different businesses.
Contrast-media intermediate revenue and realisation. This segment declined 16% in FY2025 while the end market grew and the category leader described supply as tight.212 That divergence has not been fully explained. Three launches are guided for FY2027, plus the Mahad backward-integration contribution in H2.18 Watch whether the segment reclaims growth, and watch for any sign of pricing compression of the kind saccharin experienced.
Cash conversion — operating cash flow against EBITDA. Gross current asset days rose from 277 to 333 in a single year, and operating cash flow fell to ₹39 crore on ₹305 crore of profit.1 With ₹1,000 crore of fixed-asset spending ahead, this is the metric that determines whether growth is self-funding or requires the equity market again.
Beyond those, the medium-term markers are straightforward: Vizag milestones against the now-extended FY2029–30 commercialisation guidance, whether the incremental capital earns returns anywhere near the 26–40% ROCE the existing asset base has produced, and whether the FY2026 audit report shows the inventory audit-trail gap remediated.
The 1968 saccharin business is still there, still selling to companies whose consumers have never heard of it, still absorbing whatever Chinese capacity decides to do. It is the smallest segment now and the most instructive one.
It is what a moat looks like after someone larger has tested it — smaller, still profitable, no longer growing. Whether the contrast-media franchise ends up in the same place, or whether regulatory entanglement really is a different order of protection than customer relationships, is the question that will define the next decade of this company. The answer will not arrive in a press release. It will arrive slowly, one quarter of realised pricing at a time.
References
-
Blue Jet Healthcare Limited — Rating Rationale, CARE Ratings, 2025-12-16 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Annual Report FY2024-25 — Blue Jet Healthcare Limited ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Blue Jet Healthcare FY26: Revenue falls 8% to ₹9,473 million — ScanX, 2026 ↩↩↩↩↩↩↩↩↩
-
Blue Jet Healthcare standalone net profit declines 14.16% in the June 2026 quarter — Business Standard, 2026-08-03 ↩↩↩
-
From CT scans to MRIs: How Blue Jet Healthcare made it big with contrast media — Forbes India ↩↩↩↩↩
-
Blue Jet Healthcare — Initiating Coverage, Motilal Oswal Financial Services, 2025-04-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
GE HealthCare Announces First Patient Dosed in Phase 2/3 LUMINA Trial for Manganese-Based MRI Contrast Agent — BioSpace, 2026-04-23 ↩↩↩
-
Blue Jet Healthcare makes decent debut, up 10% premium over its issue price — Business Standard, 2023-11-01 ↩↩↩↩
-
Blue Jet Healthcare asked to stop production after death of 11 workers in fire at its Raigad plant — Medical Dialogues, 2023-11 ↩↩↩
-
Intimation of fire — Blue Jet Healthcare Limited exchange filing, 2023-11-03 ↩
-
Blue Jet Healthcare: A Temporary Glitch or a Structural Reset? — Manthan Rastogi ↩↩
-
GE HealthCare Reports First Quarter 2026 Financial Results — GE HealthCare Investor Relations ↩↩↩
-
GE HealthCare (GEHC) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026 ↩↩
-
Blue Jet Healthcare Q1 FY26: Revenue jumps 118% YoY — Multibagg ↩
-
Blue Jet Healthcare Reports Mixed Q2FY26 Results with 53% Revenue Decline but Strong Half-Year Growth — ScanX ↩↩↩↩
-
Blue Jet Healthcare: Margin Woes vs. Growth Bets Post-Q3 — Whalesbook, 2026-02 ↩↩↩↩
-
Blue Jet Healthcare stock tanks 19% in 2 days; nears issue price; here's why — Business Standard, 2026-02-16 ↩
-
Blue Jet Healthcare Ltd (NSE:BLUEJET) Q1 2027 Earnings Call Highlights — GuruFocus via Yahoo Finance, 2026-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Blue Jet Healthcare Reports Q1 FY27 Results: Net Profit ₹78.26 Crore; Revenue Up 24.9% QoQ — EquityBulls, 2026-08 ↩↩
-
Blue Jet Healthcare Downgraded: Execution Woes Spark Valuation Fears — Whalesbook, 2026-02 ↩
-
Blue Jet Healthcare Ltd — financials, ratios and shareholding pattern, Screener.in ↩↩↩↩↩↩↩
-
Blue Jet Healthcare down 4% as promoter launches OFS at ₹675 — Business Standard, 2025-09-10 ↩
-
Blue Jet Healthcare Promoter Sells 6.19% Stake via OFS — Moneycontrol via TradingView, 2025-09 ↩↩↩
-
Blue Jet Healthcare share price jumps over 8% as firm raises ₹800 crore via QIP — Upstox, 2026-07 ↩
-
Blue Jet Healthcare Breaks Ground on ₹1,000 Cr Vizag Plant; ₹2,300 Cr Future Potential — Whalesbook, 2026-02-28 ↩↩
-
Blue Jet Healthcare Q3 FY26 Earnings Call Transcript Highlights — InvestyWise, 2026-02 ↩↩
-
Macquarie bullish on Suven Pharma, Divi's, BlueJet, Syngene; shares rise — Business Standard, 2025-02-19 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube