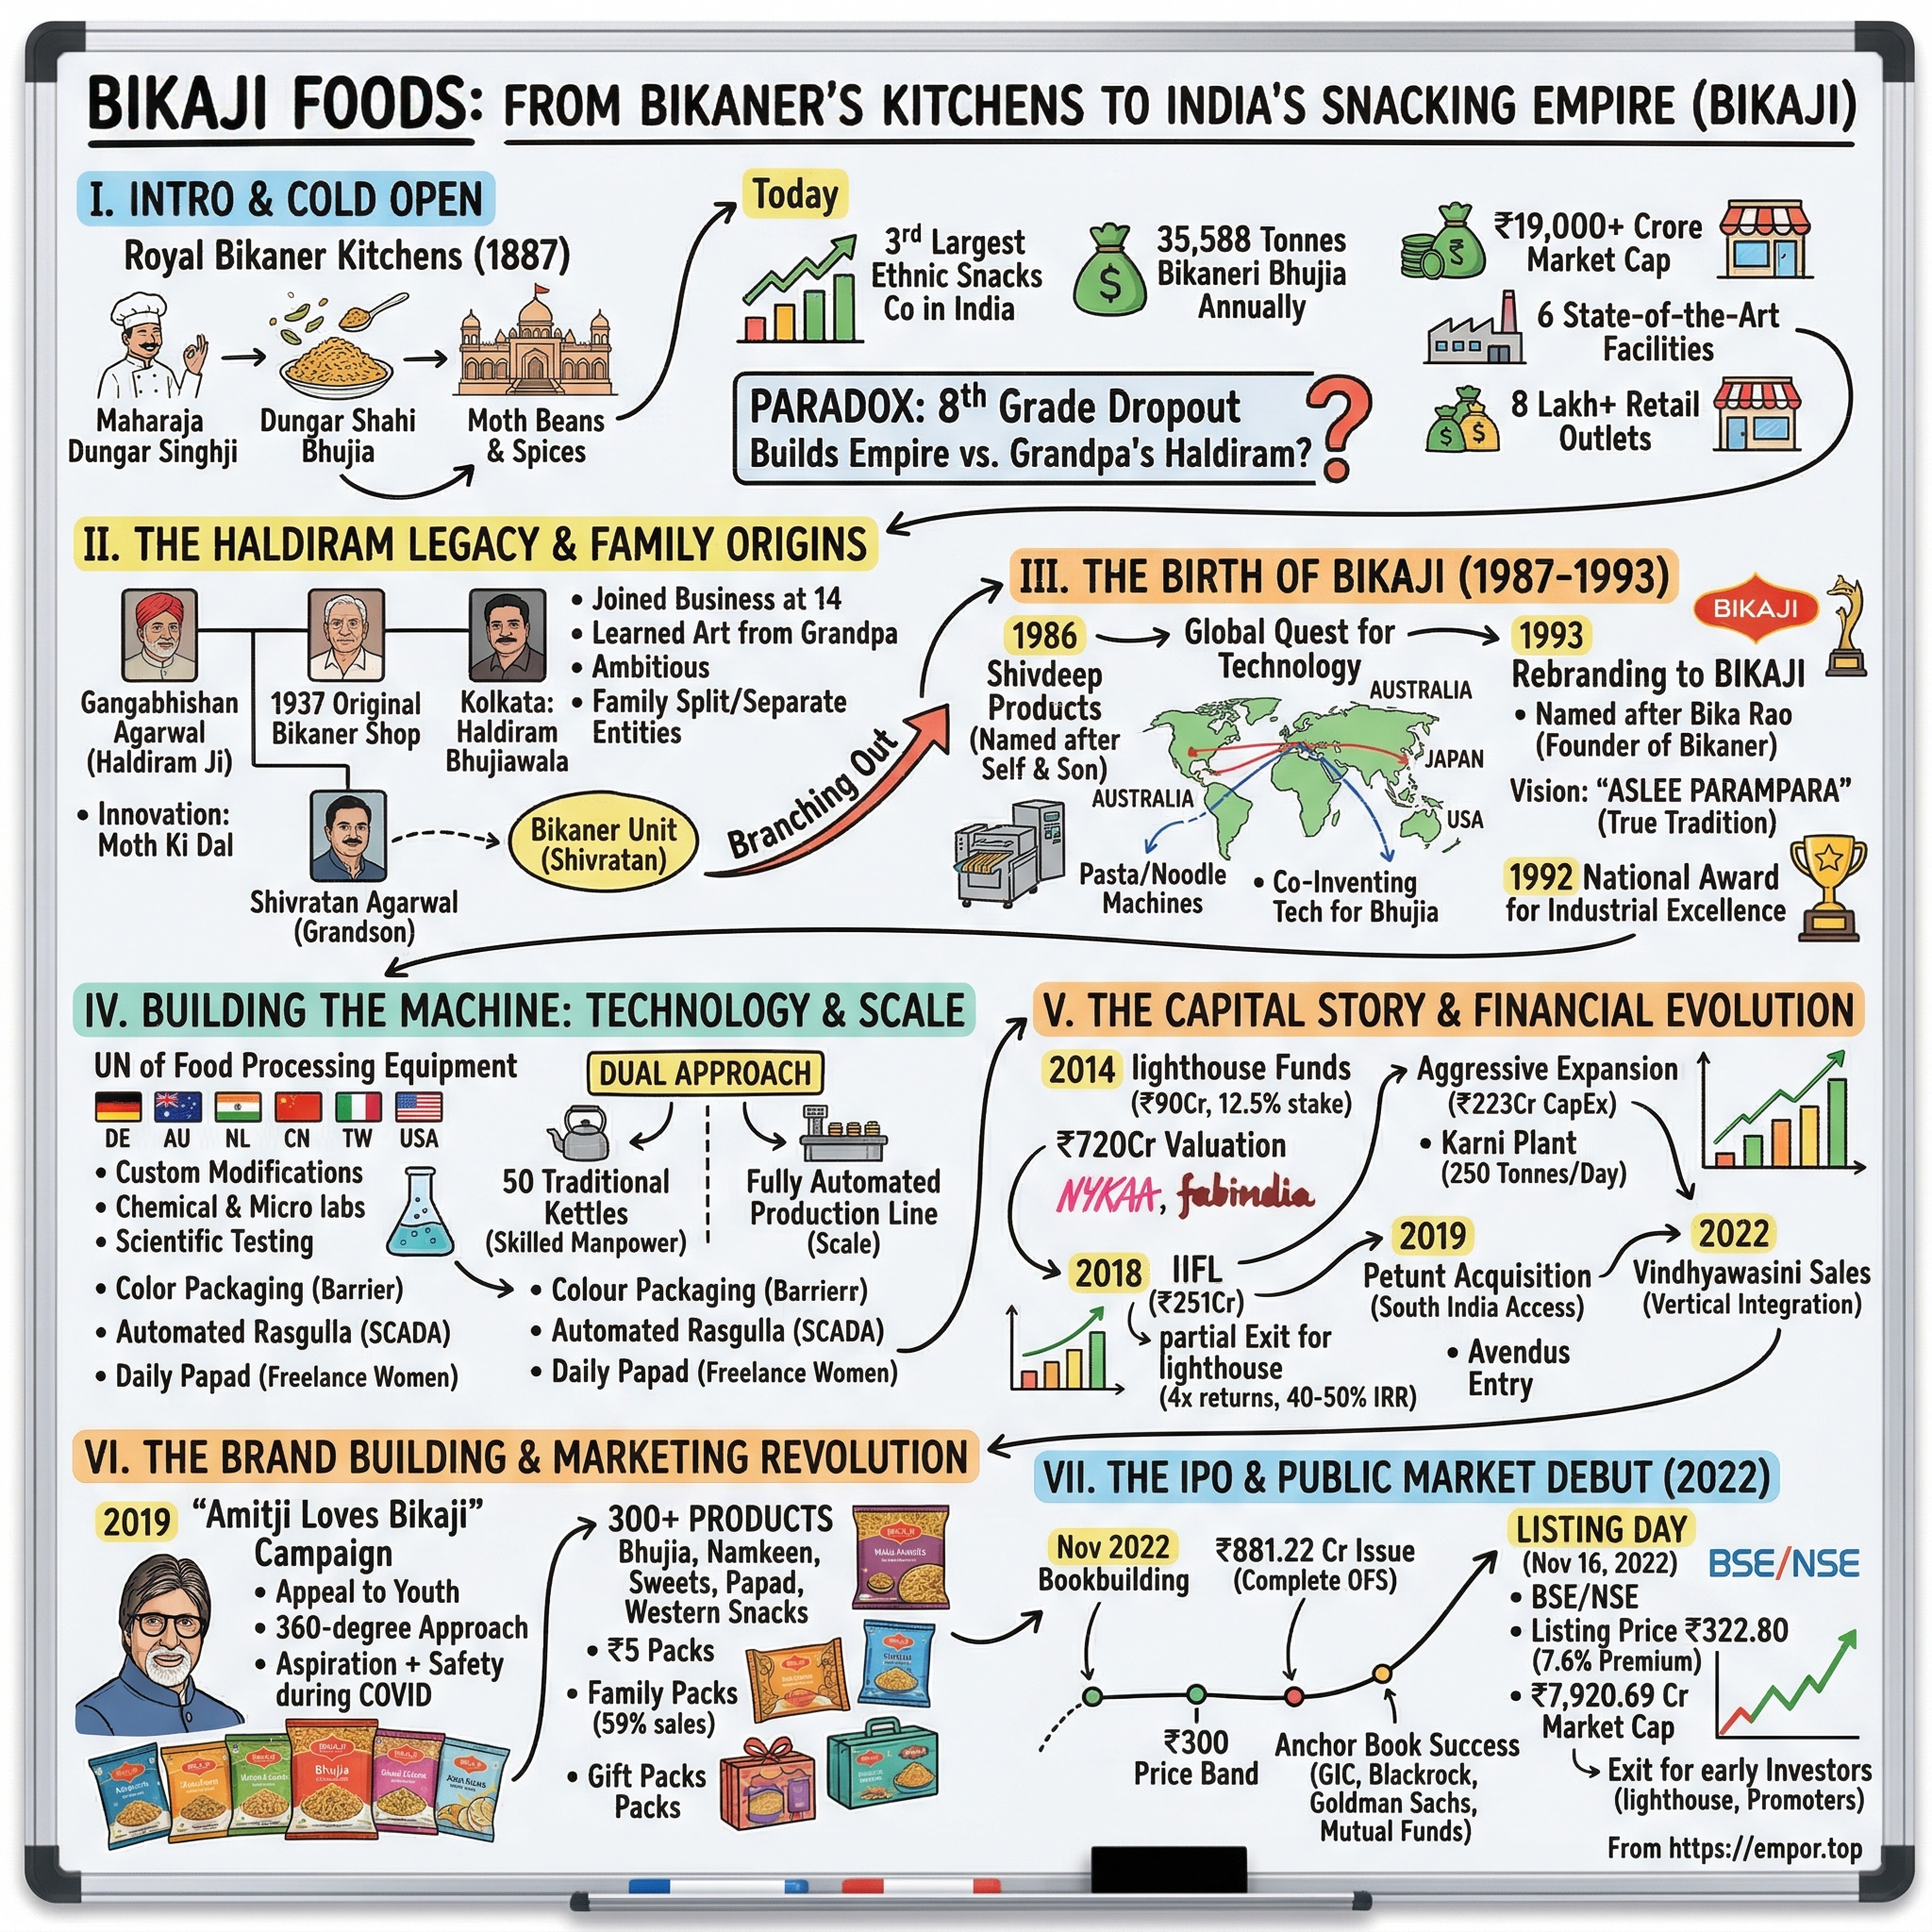
Bikaji Foods: From Bikaner's Royal Kitchens to India's Snacking Empire
I. Cold Open & Episode Roadmap
Bikaner sits at the edge of the Thar Desert, a city built on caravan money and camel routes, where the summer air is so dry that food behaves differently than it does anywhere else in India. Local tradition dates the invention of the city's signature snack to 1877, during the reign of Maharaja Dungar Singh, when the royal kitchens produced a crisp, fiery, thread-thin fried noodle made not from wheat or chickpea flour but from moth bean — a hardy desert legume that grows in sandy soil on rain-fed fields and brackish well water.1 The snack was called bhujia. It was, for decades, a court delicacy and then a cottage industry: dough pressed by hand through a perforated ladle into a vat of hot oil, fried in small batches, sold loose from tin containers, and eaten within a fortnight before the oil turned.
What makes bhujia interesting as a business object rather than a food is that it is almost perfectly resistant to industrialisation. The dough has no gluten, so it does not hold together the way wheat does. It is sticky, so it clogs machinery. It fries in seconds, so temperature control is unforgiving. And once fried, it begins to oxidise immediately. For roughly a century after its invention, every attempt to make bhujia at scale ran into the same wall: you could make more of it, but you could not make it the same, and you could not move it very far. That constraint is the reason India's snack industry stayed regional for so long — and dissolving it is, in one sentence, what this company did.
Bikaji Today
A century and a half later, that same recipe is the operating core of a listed company with a market capitalisation of roughly ₹15,000 crore. Bikaji Foods International reported revenue from operations of ₹2,994 crore in the financial year ended March 2026, up 14.4%, with EBITDA of ₹411 crore at a 13.7% margin and profit after tax of ₹254 crore.2 The company describes itself — on the authority of a commissioned Frost & Sullivan study — as India's third-largest ethnic snacks company, selling into 28 states and seven union territories and exporting to 43 countries.2 It is, by the same study, the largest single manufacturer of Bikaneri bhujia in the world, producing 26,690 tonnes of it in fiscal 2021 alone against an installed bhujia capacity that has since risen to 57,600 tonnes a year.34
The Central Paradox
Here is the paradox that makes the story interesting. The man who built this — Shiv Ratan Agarwal, who died on April 23, 2026 — was born into the family that invented the modern bhujia business.5 His grandfather's brand was Haldiram's, today the dominant force in Indian packaged snacks and a company valued in the billions of dollars. Agarwal walked away from that name. He started again in the late 1980s under a brand nobody had heard of, in a category where the name on the packet was the product, and spent the next three decades trying to prove that manufacturing capability could substitute for inherited brand equity. The evidence on whether he succeeded is genuinely mixed, and the mixedness is the point: Bikaji holds roughly 8.7% of India's ethnic snacks market against Haldiram's 36.6%.6 It is a large, competent, third-place operator in a category where the leader is nearly four times its size.
The Roadmap
That framing sets up everything that follows. Over the next sections: the family schism and the founding of Shivdeep Products in 1987, rebranded to Bikaji in 1993; the industrialisation of a fundamentally artisanal food, which required co-engineering machinery that did not exist; the private-equity capital that professionalised the company between 2014 and 2018 and the November 2022 IPO in which — and this matters more than it sounds — not one rupee of new money entered the business; the leadership transition after the founder's death and what the succession reveals about governance in a 73.88% promoter-owned company;7 the segment economics of bhujia versus sweets versus western snacks; the acquisition spree into frozen food, digital-first snacking and premium café retail, all of which lost money in FY26; and the war for shelf space against Haldiram, Balaji Wafers, PepsiCo and, increasingly, a quick-commerce channel that changes the economics of an impulse purchase.
There is also a market backdrop worth setting down at the start, because it disciplines everything that follows. Bikaji's shares traded at ₹598.30 at the beginning of September 2026, against a 52-week range of ₹592 to ₹818.70 — which is to say, at the very bottom of the year's band.17 On FY26 earnings that is a trailing multiple in the high fifties.12 Multiples of that order are not descriptions of the present; they are commitments about the future. They embed years of mid-to-high-teens growth, margin expansion, and successful geographic diversification. So the analytical job is not to decide whether Bikaji is a good company — it plainly is a competent one — but to work out which of those embedded commitments the evidence actually supports.
A second discipline is worth naming: this is a business whose reported profitability contains a government subsidy that is about to expire. Bikaji recognised ₹51.36 crore of Production Linked Incentive income in FY26 and ₹59.84 crore in FY25.7 Management has told investors that PLI is worth roughly 150 basis points of EBITDA margin and that FY27 is its last year.10 Any statement about Bikaji's margins that does not net that out is a statement about accounting, not economics — and this article will keep the distinction visible throughout.
The through-line question for an investor is simple to state and hard to answer: is Bikaji a low-cost manufacturing machine with a long distribution runway, or a regionally concentrated brand whose margins are hostage to the price of palm oil and whose management has started buying things it does not know how to run?
 Subscribe on LinkedIn
II. The Haldiram Legacy & Family Origins (1930s–1980s)
The Patriarch's Blueprint
To understand what Shiv Ratan Agarwal gave up, you have to understand what his grandfather built. Ganga Bishen Agarwal — known universally by his childhood nickname, Haldiram — opened a sweet and snack shop in Bikaner in the 1930s. His commercial insight was a formulation change: grinding moth bean flour finer and altering the spice profile, producing a bhujia that was lighter, crisper and more consistent than the coarse local version. It converted a court delicacy into a commodity snack that ordinary households bought weekly. The Bikaneri bhujia of today — the one with a Geographical Indication tag granted in 2010, restricting the name to producers within Bikaner district — is essentially his recipe scaled.3
Why Bikaner, and Not Anywhere Else
Two things made Bikaner rather than, say, Jaipur the home of this product, and both are still economically live. The first is the crop. Vigna aconitifolia, the moth bean, is an arid-zone legume grown across western Rajasthan under rain-fed conditions and irrigated, where irrigated at all, with saline water drawn from deep wells.1 A manufacturer sitting inside that agricultural belt buys its principal raw material at the farm gate without freight. The second is the GI itself: the tag covers all nine tehsils of Bikaner district, which means the appellation is a regional public good rather than a company asset. Any registered producer inside the district may call its product Bikaneri bhujia. This is a crucial and frequently misread point — the GI protects Bikaner, not Bikaji.
There is a third factor that rarely gets mentioned and is arguably the most durable: the labour pool. A century of bhujia production created in Bikaner a workforce that knows how to handle moth-bean dough — how it behaves at different humidities, how it should look coming off a line, what a correctly fried strand sounds like. Culinary clusters of this kind function much as industrial clusters do in Italy or Germany: the tacit knowledge sits in the town rather than in any one firm, which lowers the cost of scaling for everyone inside it and raises the cost of entry for everyone outside. It is also, as the events of April 2026 would eventually demonstrate, a concentration risk — a town-level workforce is a town-level single point of failure.
The Founder Who Left the Name Behind
Into that ecosystem Shiv Ratan Agarwal was born, and inside it he grew up. The family enterprise was, by the 1970s and 1980s, no longer a single shop but a set of regional operations, and the Haldiram name was in the process of fragmenting along geographic lines among the founder's grandsons — Nagpur and the west, Delhi and the north, Kolkata and the east. The details of the division have been litigated for decades and remain contested; what is not contested is that by the late 1980s the name belonged to a collective, not to any one operator. Details of Agarwal's schooling have circulated widely in profiles and are frequently repeated, but the company has never disclosed them in a filing, and this article will not treat them as established. What the record does establish is his disposition: the Frost & Sullivan industry study commissioned for Bikaji's own offer documents describes him as "one of the pioneers in the Indian snack industry" with more than three decades of experience,3 and every account of his career — including the company's own communication on his death — centres on the same obsession, which was not retail and not brand but process: making the same product, at the same taste, ten thousand times a day.5
In 1987 he left. He started a separate business, initially under the name Shivdeep — a portmanteau of his own name and his son Deepak's — with no rights to the family brand and no access to the family's distributor relationships. This is where the most common thesis about Indian family businesses deserves a hard test.
Disconfirming Evidence: The Dynastic Moat That Was Not There
The intuitive thesis is that a spinoff from a legendary food dynasty inherits a halo: suppliers extend credit, distributors take the stock, consumers assume quality. The record does not support it. The brand equity in Bikaner bhujia belonged to the word Haldiram, and Agarwal did not own that word. He had to build distribution from a standing start in a category where the retailer's shelf decision is made on brand pull, and where an unknown packet earns shelf space only by paying for it — in margin, in credit terms, or in the humiliation of selling unbranded bulk. It took six years before the business had a brand identity worth defending: the rebrand to "Bikaji" came only in 1993, and the company itself dates its brand launch to that year, not to 1987.2 Six years is a long time to operate as a nameless supplier in a branded category.
It is worth being precise about what the first six years actually required, because the popular version of this story compresses it into a montage. A manufacturer without a brand in a branded category has exactly three currencies with which to buy shelf space: a lower price to the retailer, longer credit, or a willingness to sell unbranded. Each of those is a direct transfer of economics from the manufacturer to the channel, and each of them compounds — a business that funds its own distribution through extended credit is a business whose growth consumes rather than generates cash. That is the specific, unglamorous cost of walking away from a famous name, and it is paid up front, in working capital, years before any brand asset exists to show for it.
The revealing detail is that the family relationship never fully severed — it commercialised. Bikaji's FY26 related-party disclosures list Haldiram Snacks Food Private Limited (into which Haldiram Ethnic Foods, Haldi Ram Products, Haldiram Snacks and Haldiram Foods International were merged) as an entity under the control of relatives of Bikaji's key managerial personnel, with recorded transactions in both directions: Bikaji purchased ₹10.28 crore of goods from a Haldiram entity in FY25 and ₹1.05 crore in FY26, and sold goods to Haldiram entities in both years.7 Nearly forty years after the split, the cousins still trade with each other across the ledger. The dynastic moat was never a moat; it was a network, and networks can be rented but not inherited.
So the founding lesson is not romantic. Agarwal did not leave with an advantage. He left with a constraint, and the only way around a brand constraint in a commodity food is to become structurally cheaper or structurally better than everyone else making the same thing.
It is worth pausing on how unusual that choice was in context. The 1980s and 1990s in Indian consumer goods were a period in which brand names were the scarcest asset in the system — distribution was fragmented, advertising reach was limited to Doordarshan, and a retailer's shelf decision was made almost entirely on recognition. Choosing to compete on manufacturing capability in that environment was choosing the hardest possible route. The pay-off, if it came at all, would arrive a decade later, and only if the cost differential grew large enough to buy shelf space that the name could not.
That is what he set out to do next, and it required machines that nobody had built.
III. Industrializing Tradition: Automation & Packaging Breakthroughs (1987–2000s)
The Bottleneck
Picture the traditional process, because the physics explain the business. A worker holds a jhara — a wide perforated ladle — over an open vat of oil and presses moth-bean dough through it by hand. The strands drop, fry, and are skimmed. Batch size is limited by the worker's forearm and by how fast the oil recovers temperature. Consistency depends on the individual. And the finished product has a hard biological limit: fried in open oil, packed in a single-layer pouch or a tin, exposed to oxygen, it goes rancid in roughly two to three weeks.
That shelf-life ceiling is the entire strategic problem of regional Indian food. A product that lasts three weeks cannot be freighted a thousand kilometres, cannot sit in a distributor's godown through a slow month, and cannot be exported at all. It confines the producer to a radius. This is precisely why India's snack market fragmented into hundreds of regional champions rather than consolidating into two or three national ones — and why, on the Q4 FY26 earnings call in May 2026, management could still observe that the local players genuinely under pressure are those "with geographies under 150 km."8 The 150-kilometre business is a shelf-life business.
Agarwal's response had two parts, and neither was available off the shelf.
Part One: Machines That Did Not Exist
Non-gluten legume dough is sticky, low in structural integrity, and behaves nothing like the wheat and potato feedstocks that European and Japanese snack machinery was designed around. There was no extruder built for moth besan. The accounts of his career converge on the same episode: rather than buy equipment, he travelled to machinery manufacturers abroad and co-developed customised continuous extrusion and frying lines with them.5 The distinction between buying and co-developing is not a detail. Off-the-shelf equipment gives you parity with anyone else who writes the cheque. Co-developed equipment, tuned over years to one specific dough at one specific throughput, gives you a process advantage that a competitor has to re-derive rather than purchase. Bikaji's own investor materials still describe the Bikaneri bhujia line as "largely automated," with automation framed as the mechanism that delivers consistency of taste at scale rather than merely lower labour cost.3
There is a quieter benefit to continuous processing that is easy to miss and that matters enormously in food: variance reduction. A hand-fried batch is a distribution of outcomes — some strands thicker, some oil hotter, some batches slightly bitter. A continuous line is a single outcome repeated. For a company trying to sell the same product in Bikaner and Guwahati, sameness is the product. A consumer who has been disappointed once by an unbranded packet learns to pay a premium for predictability, and predictability is manufactured, not advertised. This is the real reason the automation investment produced a brand rather than merely a cost saving.
Part Two: The Packet
This is the underrated half. Bikaji was among the first in the Indian ethnic snacks industry to move bhujia from single-layer pouches to multi-layer laminated packaging, then to gas-flushed formats.3 The mechanism is simple to explain: fried snacks go stale because oxygen oxidises the frying oil. Replace the oxygen inside the packet with nitrogen and seal it inside a multi-layer laminate that oxygen cannot cross, and the clock effectively stops. Shelf life extends from weeks to months without adding a single synthetic preservative.
Combine the two and the company's addressable geography changes shape. A six-month shelf life means a truck from Bikaner can reach Guwahati; it means a distributor can hold inventory; it means a container can cross an ocean. Everything Bikaji later became — the eastern India stronghold, the export business, the pan-India ambition — is downstream of a packaging decision made in the 1990s.
Turning Shelf Life into Geography
The commercial expression of this was a distribution strategy aimed deliberately at the map's white space. Rather than fight PepsiCo and the national FMCG majors in metropolitan western India, Bikaji pushed into Assam, Bihar and West Bengal — markets with weak organised coverage, high ethnic-snack consumption, and few branded competitors with the shelf life to serve them. Those states, alongside home-market Rajasthan, remain what the company calls its "core" today, and they still generated 72.4% of revenue in the June 2026 quarter.9 The choice that built the company is also the concentration that now defines its risk.
The choice of eastern India also carried a subtler commercial logic. Assam and Bihar are markets where ethnic savoury consumption per capita is high, where organised retail penetration was — and largely remains — thin, and where the super-stockist model works well: one large intermediary carries the working-capital burden of a wide territory, which lets a mid-sized manufacturer achieve reach without financing it. National FMCG companies with metro-first strategies were not competing there in the 1990s. Bikaji built a franchise in the gaps of somebody else's map, which is the standard playbook for a challenger with a cost advantage and no brand budget.
So What This Buys, and What It Does Not
Process power of this kind is real but bounded. It is real because it took three decades to accumulate and cannot be bought as a unit. It is bounded because it protects the cost and consistency of making bhujia, not the price Bikaji can charge for it — and, as later sections show, the two came apart badly in FY25. It is also bounded because packaging technology, unlike a proprietary recipe, diffuses: nitrogen flushing and multi-layer laminates are now standard across the organised industry. The first mover advantage in a technology that everyone eventually adopts is a head start, not a wall. What Bikaji converted its head start into was a distribution footprint — and by the 2010s that footprint was large enough to attract outside capital, which brought a very different kind of scrutiny into a family firm.
IV. Modern Management, Ownership & Governance: The Leadership Transition
On April 23, 2026, Shiv Ratan Agarwal died. Bikaji's plants stopped. On the Q1 FY27 call in August, management disclosed the operational consequence with unusual plainness: a factory closure of roughly two and a half days, which combined with labour disruption around the West Bengal elections cost approximately four to four and a half days of production, and which — because most Bikaneri bhujia output is concentrated in Bikaner and worked substantially by Bengali migrant labour — depressed dispatches through the first 45 days of the quarter.810 Reported quarterly volume growth fell to 7.7% against value growth of 12.5%.11 A single death, in a single family, cost a ₹15,000 crore listed company most of a quarter's momentum. That is what key-person concentration looks like in numbers.
The succession itself was orderly and, notably, pre-loaded. Deepak Agarwal — the "deep" in Shivdeep, running operations for years — became Chairman and Managing Director; Shweta Agarwal continues as Whole-Time Director.7 Nothing about the transition was improvised. But orderly is not the same as arm's length, and the governance picture that emerges from the FY26 annual report is worth walking through carefully, because it is the sort of thing that a skeptical investor — an activist, or a short — would go to first.
There is a management-continuity point worth making before the governance audit, because it cuts the other way. Bikaji's senior team is not a family monoculture. Chief Operating Officer Manoj Verma and Chief Financial Officer Rishabh Jain have been the primary voices on earnings calls for years, and it is Verma and Jain — not the promoter — who field analyst questions on category growth, distribution economics and margin bridges.810 For a company where the founder was the single most important operating asset, having a professional layer already fronting investor communication before his death materially reduced the transition risk. The market may have priced the succession as a shock; the disclosure record suggests it had been de-risked well in advance.
Ownership and the Thin Float
The promoter and promoter group held 18,52,39,398 shares, or 73.88% of a 25.07 crore share capital, as at March 31, 2026.7 That is high alignment and a thin float. It also means every governance question resolves, in practice, to whether the independent directors are willing to be difficult. The board includes five independent directors — Siraj Azmat Chaudhry, Nikhil Vora, Pulkit Bachhawat, Richa Goyal and Sunil Sethi — alongside a non-executive nominee, Sachin Kumar Bhartiya, who has waived his right to remuneration.7
Pay Versus Performance
Here the record is uncomfortable. In FY26, Deepak Agarwal's remuneration rose 20%, and the late founder's by 10%, against a 3.76% increase in the median employee's pay; the Chairman and Managing Director's remuneration stood at 344.47 times the median employee's.7 Managerial remuneration across the company rose 14.01% while non-managerial salaries rose 8.96%.7 FY26 was a good year, so a 20% increase is defensible on its own. The problem is the year before it. FY25 was the year consolidated PAT fell to ₹194 crore from ₹263 crore — a 26% decline — and EBITDA margin compressed from 16.8% to 12.5%.4 A remuneration structure that rises smartly in the recovery year without visibly absorbing the shortfall year is a structure with limited variable content, and it is exactly the item an activist would put on the first slide.
The mitigating context is that Bikaji employs 3,040 permanent staff and grew median pay 3.76% in a year when it grew earnings sharply, which is a modest pass-through by any standard.7 The company's stated justification is scope of role, achievement of milestones and industry benchmarking, approved through the nomination and remuneration committee.7 That is the standard formulation. What an investor cannot verify from the disclosure is the counterfactual: what the CMD's pay would have been had FY26 gone the way FY25 did. Until a bad year is followed by a visible pay reduction, the variable component of promoter compensation remains an assertion rather than a demonstrated fact.
Related-Party Flows
Bikaji is not unusual among Indian promoter-controlled companies here, but the amounts are not trivial and they are two-directional. On the purchase side in FY26, the standalone entity bought ₹23.74 crore of goods and services from Vedapremium Agro Private Limited (an entity under the control of relatives of KMPs) and ₹2.65 crore from S.M. Foods Engineering Private Limited (under significant influence of relatives), plus ₹0.34 crore of plant and equipment from the same engineering entity; total related-party purchases were ₹56.11 crore, down from ₹80.09 crore in FY25.7 On the sale side, ₹33.05 crore of goods went to members of the Thadiram Shiv Dayal HUF, and total related-party sales came to ₹84.84 crore.7 Against ₹2,994 crore of revenue these are small percentages. But the disclosure quality matters more than the size: the transactions are named, quantified, put through the audit committee under a stated materiality policy, and the counterparties are identified down to the HUF. That is the minimum standard, and Bikaji meets it. It does not, however, tell an outside investor whether the pricing is keen — only that it was approved.
Auditor Signals and Legal Overhangs
Two items deserve flagging. First, the statutory auditors identified impairment of goodwill and loans as a key audit matter for the consolidated FY26 statements: the group carried goodwill of ₹30.38 crore relating to subsidiaries and outstanding loans receivable of ₹51.19 crore to others, with recoverable value determined by discounted cash flow models whose assumptions the auditors singled out as judgement-heavy.7 That is a standard KAM formulation, but it is pointed at exactly the part of the business — the acquisitions — that this article will show is currently loss-making. Second, a live tax dispute: in FY25 the GST authorities issued a show-cause notice alleging that extruded savoury products including Bikaji Kurram, Ring Tomato Cheese and Corn Puff were misclassified under a 12% namkeen head rather than an 18% head, and passed a demand of ₹5.54 crore plus interest and penalty in January 2025 despite an interim stay; Bikaji has an amended writ petition before the Karnataka High Court and a further stay from April 2025.7 The rupee amount is immaterial. The precedent is not — an adverse ruling would reset the tax rate on a growing category, and the western snacks portfolio is precisely where management wants growth.
A third item sits in the "others" column of the same note and is worth a sentence: Bikaji imported machinery for its Tumkur bakery project under the MOOWR warehousing scheme, deferring integrated GST and customs duty of ₹10.76 crore as at March 2026, against ₹9.51 crore a year earlier.7 The liability is contingent — exempted if the capital goods are ultimately exported, payable if they are cleared domestically. It is not large, but it is an example of the sort of judgement that accumulates when a company runs several simultaneous new-format projects, and it belongs on a diligence list alongside the goodwill assumptions.
Capital Allocation, as Management Frames It
Management's own framing is that operating cash flow funds automated capacity: roughly ₹100 crore of capex guided for FY27, principally a new sweets factory in Bikaner and warehousing that lifts finished-goods storage from about two days to six to eight.8 Set against that discipline is the record of what was bought outside the core, which Section VI takes apart. Borrowings stood at ₹299 crore against reserves of ₹1,582 crore at March 2026 — a lightly levered balance sheet with no refinancing question worth asking.12
The honest summary: governance is compliant, disclosure is above average for a promoter-controlled Indian mid-cap, and the specific vulnerabilities are pay discipline and the judgement calls sitting inside the acquisition carrying values. Which brings us to what is actually being sold, and how the money is made.
V. Core Business Architecture: Segment Economics, Moats & Supply Chain
Walk the floor of the Karni Extension complex in Bikaner and the thing that strikes you is how little of it looks like cooking. Dough moves through enclosed extruders, drops into oil at a controlled temperature, travels on a belt, gets seasoned by a rotating drum, and arrives at a filling machine that flushes nitrogen into a laminate pouch and seals it, all without a human hand touching the product. What began as a court delicacy pressed through a ladle is now, functionally, a continuous chemical process with a taste specification. Strip away the corporate structure and Bikaji is four such processes of very unequal importance sharing one distribution system.
Ethnic Snacks: The Company
In FY26 the category grew 11.2% and contributed approximately 68.9% of revenue; in the June 2026 quarter it grew 11.4% to ₹515 crore and represented 75.7% of the categorised revenue mix.29 Within it, bhujia and namkeen together dominated: in fiscal 2021, namkeen and bhujia alone were 37% and 36% of sales respectively.3 This is the cash engine, it is where the automation advantage lives, and it is the category in which Bikaji is a genuine leader rather than a challenger.
The economics of this category explain why the whole company is shaped the way it is. Bhujia and namkeen are dense, cheap, non-perishable and consumed habitually rather than occasionally. That combination produces high asset turns, predictable repeat demand and low obsolescence risk — the closest thing in Indian FMCG to an annuity. It also produces a brutal ceiling on price: the consumer knows exactly what a packet should cost, and a ₹5 sachet is a psychological unit, not a price point that can be nudged.
Packaged Sweets: A Seasonality Problem, Not a Demand Problem
Rasgulla, gulab jamun and soan papdi grew 8.9% in FY26 and was about 5.8% of the June-quarter mix.29 The strategic problem here is not demand but shape of demand. On the FY26 call, COO Manoj Verma explained the constraint precisely: sweets capacity runs above 100% utilisation during the festive season and sits underused the rest of the year, which caps how large the base can get.8 The company is answering with a dedicated new sweets factory and all-season ₹5 and ₹10 packs designed to smooth the seasonal curve. Whether that works is a real, checkable question — sweets have compounded at roughly 6% over the past two years against an 11–12% aspiration.8
The sweets business also carries a quieter advantage that the market rarely credits: it is one of the few categories where the unorganised competitor is structurally disadvantaged. The Indian sweets market is overwhelmingly informal — the offer-document industry study put the unorganised share of Indian sweets at close to 90% of a ₹589 billion market — and loose sweets sold from a halwai's counter face milk-price volatility, no shelf life and no food-safety documentation.3 A packaged rasgulla in a sealed can is a fundamentally different product. If formalisation happens anywhere, it happens here first.
Western Snacks: Growth Optics and Margin Reality
Extruded pellets, rings and chips form the growth-optics category and the margin-pressure category simultaneously. It grew 6.8% in FY26 and then 21.3% in the June 2026 quarter.29 Management's argument for why it should keep growing fast is disarmingly honest: Bikaji has roughly 1.1% share of the western snacks market, so even indifferent execution can produce a high growth rate off a small base.8 That is a fair point and also an admission — in this category Bikaji is a price-taker facing Balaji Wafers and PepsiCo, both of which have deeper pockets and better scale in potato and corn.
Papad and the Rest
Papad and ready-to-eat is small — around 4.5% of the June-quarter mix, down 6.5% year on year on early monsoon — but structurally interesting.9 It is low-capital, partly produced through decentralised women's manufacturing networks, and it competes against a segment that is overwhelmingly unorganised.
The Footprint: Why a Snack Company Is Really a Freight Company
The manufacturing footprint is built to minimise the one cost that dominates snack economics: freight on a product that is mostly air. Total installed capacity was 325,320 tonnes as of March 2025 — 141,540 tonnes of namkeen, 62,280 of packaged sweets, 57,600 of bhujia, 39,300 of western snacks, 11,400 of papad — spread across the Bikaner cluster plus units and contract facilities positioned at Guwahati and Muzaffarpur for the east, Kanpur and Patna for the north-east corridor, Kolkata, Raipur, and Tumkur for the south.49 Bikaner is where cost advantage lives, because that is where the moth bean is; everything else exists because a truck of bhujia crossing India is a truck of packaging.
It is worth making the freight point concrete, because it is the most important physical fact about this industry and the least intuitive. A pouch of bhujia is mostly volume and very little weight. A truck fills up long before it reaches its weight limit, which means the cost of moving a rupee of snack revenue is several times what it is for, say, a rupee of soap or biscuit revenue. Every kilometre between a factory and a retailer is therefore a direct subtraction from margin, and the only defence is to put production near consumption. Bikaji's plant map is not a diversification story; it is a freight-arbitrage map. It also explains why the company can defend its home markets so effectively and why penetrating the south and west is genuinely hard — the incumbent there enjoys exactly the same local-freight advantage that Bikaji enjoys in Rajasthan and Assam.
Seven Powers, Applied Honestly
Scale economies are real inside bhujia specifically — the Bikaner complex converts moth besan into packed product at a per-kilogram cost that a 150-kilometre regional fryer cannot match, and that is the single most defensible thing about the company. Process power is real, accumulated over thirty years of tuning continuous lines to a difficult dough, and management is now deliberately decentralising bhujia production to a second plant to remove a single-point failure — an admission that the concentration which creates the cost advantage also creates operational fragility.11 Brand power is medium: strong enough in core states to command shelf, not strong enough to pass through cost inflation at ₹5 and ₹10 price points, which is the only test that counts. Cornered resource is weak and often overstated — the GI belongs to Bikaner district, not to Bikaji, and proximity to the moth bean belt is shared with every other Bikaner producer including the Haldiram branches. Counter-positioning runs against the company: a general-trade distribution machine built over three decades is an asset in a general-trade world and a legacy cost structure in a quick-commerce one.
Porter, Applied to the Same Facts
Substitutes are the dominant force: roughly 43.4% of India's packaged savoury snacks market was unorganised at the time of the company's offer-document industry study,3 which means the marginal competitor is a local fryer with no brand, no tax drag and no advertising budget. Buyer power splits by channel: a traditional kirana retailer takes a standard trade margin and has no leverage, but the quick-commerce platforms — where Bikaji's sales grew more than 100% year on year off a base that took e-commerce from 2% to 3% of the business — extract materially richer terms.89 That growth rate is genuinely impressive and genuinely dilutive at the same time, which is the tension the next few years will resolve. Supplier power is moderate-to-high and entirely commodity-driven: edible oil, pulses and flours, laminates, corrugate. Rivalry is intense at the top and infinite at the bottom — Haldiram at 36.6%, Balaji at 9.6%, Bikaji at 8.7%, Bikanervala at 5.9%, then PepsiCo, ITC, Prataap and a 28.3% tail.6
One more force deserves naming because it is changing fastest: the threat of new entrants has fallen, not risen, in this category over the past five years — but only at the top end. Contract manufacturing, third-party logistics and quick-commerce distribution mean a well-funded D2C brand can now exist without owning a fryer, which is precisely the threat Bikaji hedged by buying into Bhujialalji. What has not fallen is the barrier to becoming a national ethnic snacks player at scale, because that still requires the freight network, the capacity and the working capital to service hundreds of thousands of outlets. The new entrants are real but small; the incumbents are the competition that matters.
So What
The investable core of Bikaji is a low-cost, high-consistency ethnic snacks manufacturer with a distribution system built into markets national players under-serve. Everything outside ethnic snacks is either seasonal (sweets), sub-scale (western snacks, papad) or unproven (frozen, café retail). An investor should size the thesis accordingly: this is a bet on bhujia and namkeen volumes, executed through a distribution engine, exposed to a commodity input. The rest is optionality — and optionality, as the next section shows, has been bought at prices worth examining.
VI. Capital Allocation & The M&A Playbook: PE to IPO
In April 2014, a mid-market private equity firm called Lighthouse Funds paid ₹90 crore for 12.5% of a Bikaner snack company, valuing it at roughly ₹720 crore.13 It was, in retrospect, one of the better mid-market cheques written in Indian consumer that decade. Four years later, in 2018, Lighthouse sold a 2.5–3% slice to IIFL Special Opportunities Fund for about ₹100 crore — more than four times its money on that portion, an IRR in the 40–50% range — and still held roughly 10%.13 IIFL's total commitment into the company was ₹251 crore.
What the private equity phase actually bought Bikaji was not capital. It was infrastructure of a different kind: an institutional board, ERP systems, reporting discipline, and the audit-and-forecast machinery that a family firm needs before it can face public markets. That is the standard justification for taking PE money into a profitable family business, and in Bikaji's case the sequencing supports it — the company listed four years after IIFL came in.
There is a second, less flattering way to read the private equity era, and it is worth holding alongside the first. A family business that takes institutional money and lists four years later has, in effect, spent a decade optimising for an exit event rather than for the operating business. The tell is what the exit looked like.
The IPO, and the Thing Everyone Glosses Over
Bikaji went public in November 2022. The issue was 2,93,73,984 equity shares at ₹300, aggregating ₹881.22 crore, and it listed on November 16, 2022.14 It was 100% an offer for sale. Lighthouse, IIFL, Intensive Softshare and promoter entities sold down; the company received nothing. Zero rupees of primary capital entered the balance sheet.
This deserves to be stated neutrally rather than as an accusation, because both readings are defensible. The generous reading: Bikaji was already cash-generative and did not need equity, so an all-OFS structure avoided dilution and let early backers exit at a fair price — a sign of financial health, not weakness. The skeptical reading: a company that told the market it had a long runway of pan-India expansion, greenfield capacity and category entries chose not to raise a rupee for any of it, which means every subsequent growth initiative had to be funded from operating cash flow or debt. Both readings are true. The consequence is what matters — and the consequence is that the acquisition programme which followed was funded out of the same cash flow that funds capacity, dividends and working capital.
The market's initial verdict was measured rather than euphoric: the stock listed at ₹322.80 on the NSE, a 7.6% premium to the ₹300 issue price.14 Nearly four years later the shares trade near ₹598, which is roughly a doubling from the issue price — a good outcome for IPO subscribers, and a reminder that the OFS structure did not, in itself, damage anyone. What it did was set the funding constraint for everything that came next.
The M&A Playbook, Deal by Deal
Bhujialalji, July 2023. Bikaji took 49% of Bhujialalji Private Limited, a Bikaner-based digital-first ethnic snacks venture.[^15] The FY26 annual report puts the carried investment at ₹4.90 crore for 9,608 shares, with an additional ₹2 crore of optionally convertible debentures subscribed in FY25.7 It is small, it is strategically sensible as a listening post in D2C and quick commerce, and it is the only one of the three acquisitions that contributed positive profit to consolidation in FY26 — ₹45.4 lakh — although its net worth attributable to Bikaji's shareholding was negative ₹98.5 lakh.7 Call it a cheap option that has not yet cost anything.
Ariba Foods, August–September 2024. Bikaji acquired 55% of Ujjain-based Ariba Foods, which makes frozen Indian snacks under the InDine brand and exports roughly half its output, for ₹60.49 crore.157 The logic is the cleanest of the three: Bikaji had frozen demand from export markets and no dedicated frozen capacity, and Ariba came with a plant, an export customer base and existing certifications. On the FY26 call, management framed it exactly that way — "Ariba is largely manufacturing facility" — and said the frozen business was running well below its 55% target utilisation while contributing to export growth of 50–60%.8 The FY26 outcome: turnover of ₹57.31 crore and a loss after tax of ₹2.74 crore.7
The Hazelnut Factory, October 2024. This is the one that requires a hard look. Bikaji Foods Retail Limited, a wholly owned subsidiary, agreed to invest up to ₹131.01 crore for 53.02% of Hazelnut Factory Food Products Private Limited — a Lucknow-based café-cum-artisanal-sweets chain incorporated in December 2019, with stores in Lucknow, Kanpur and Delhi — structured as ₹61 crore for an initial 40.40% through primary subscription and secondary purchase, then a further ₹70.01 crore of primary infusion in tranches over two years.16[^18] THF's disclosed financials at the time: turnover of ₹44.85 crore and profit after tax of ₹2.46 crore in FY24, against ₹39.31 crore and ₹0.83 crore in FY23.16 The stated object was to "develop and expand our Quick Service Restaurant (QSR) business vertical through a comprehensive House of Brand strategy."16
Historical Falsification: Is This a Disciplined Allocator?
The thesis under examination is that Bikaji is a disciplined allocator that reinvests behind its core competence. Three pieces of the company's own record bear directly on it.
First, the price. ₹131.01 crore for 53.02% implies a valuation around ₹247 crore for a business earning ₹2.46 crore — roughly 100 times trailing earnings and 5.5 times sales — for a nine-store café chain. Much of the money is primary growth capital rather than payment to sellers, which materially softens the multiple as a price, but it does not soften it as a commitment: Bikaji is putting more than a fifth of a year's operating profit into a business model where the unit of production is a store lease, not a fryer line.
Second, the operating fit. Bikaji's core competence is running automated lines at high throughput and pushing packets through 3.71 lakh direct outlets.9 A café is a real-estate business with fresh-food wastage, table economics and hospitality labour. These are not adjacent skill sets. Management's own targets acknowledge the difference: each store is underwritten at ₹6–8 crore of annual sales and 25%-plus EBITDA margins, with 35 stores targeted by the end of FY27 and 50 within two and a half to three years.10
Third — and this is the part that a promotional write-up would omit — the FY26 scorecard for the entire non-core portfolio is red. Per the FY26 statement of subsidiary financials: Ariba Foods lost ₹2.74 crore; Bikaji Foods Retail Limited lost ₹2.15 crore; Bikaji Bakes lost ₹0.62 crore; Petunt Food Processors lost ₹5.42 crore; Bikaji Foods International USA Corp lost ₹4.71 crore, and the parent recognised an impairment of ₹5.54 crore against its equity investment in the US entity.7 THF, held at 48.99% as an associate through Bikaji Foods Retail with ₹100.99 crore invested, contributed a negative ₹0.84 crore to consolidation.7 Two further structural moves happened quietly in the same period: Bikaji Mega Food Park was divested with effect from May 15, 2025, Vindhyawasini Sales was amalgamated from June 30, 2025, and THF Retail Private Limited — a step-down subsidiary acquired in October 2024 — ceased to be a related party on March 31, 2025 "on account of its sale to a third party," within roughly five months of the acquisition.7
A fourth data point arrived outside the listed entity entirely and is worth a brief aside for what it signals about the family's appetite. In May 2026, the Bikaji Foods family office led a ₹72 crore round in Dil Foods, a Bengaluru-based cloud-kitchen and food-brand platform.18 That investment sits with the promoter family, not with shareholders, and it does not consume company capital. But it tells you where the second generation's attention is pointed — toward food-service and brand aggregation rather than toward tonnes per line — and an investor is entitled to ask whether the listed company's QSR ambitions and the family office's food-service bets are describing the same enthusiasm from two different balance sheets.
The Verdict
The history does not reject the disciplined-allocator claim outright — the core capex programme is conservative, the balance sheet is clean, and Bhujialalji and Ariba are small, logical and cheap. But it narrows the claim substantially. On the evidence of one full year, Bikaji's diversification portfolio consumes cash, has already produced one write-down in the US entity, and has already involved selling a piece of an acquired structure within months of buying it. The specific, falsifiable test to watch is this: THF's store count against the 35-by-FY27 and 50-by-FY29 targets, and whether Bikaji Foods Retail crosses into profitability by FY28. If store count stalls in the twenties while the ₹70 crore of committed further infusion goes in, the goodwill and investment carrying values that the auditors already flagged as a key audit matter become the story.
VII. Brand Revolution & Distribution Engineering
The Bachchan Catalyst
In October 2019, Amitabh Bachchan started eating bhujia on Indian television. The campaign line was "Amitji Loves Bikaji," and it ran alongside a positioning built on the phrase Aslee Bikaneri — authentically Bikaneri.3 The strategic reading is straightforward: a regional manufacturer with a cost advantage and no national brand borrowed the most trusted face in India to buy recognition it could not build organically at the speed it needed. Frost & Sullivan's assessment at the time noted that Bikaji's advertising expense as a percentage of sales was the highest among Indian traditional snacks companies.3 For a company that had spent three decades competing on process, that was a deliberate change of weapon.
The mechanics of why a celebrity endorsement works in this specific category are worth spelling out, because they are not the same as in, say, apparel. An ethnic snack is a trust purchase made at a low price point: the consumer is not aspiring to be the celebrity, they are outsourcing a food-safety judgement. In a category where nearly half the competition is unbranded product fried in unknown oil, a nationally trusted face functions less as glamour and more as a quality guarantee. That is why the format has persisted across seven years and three campaigns rather than being cycled out after a season.
Seven years on, the campaign architecture has become more granular and, arguably, smarter. FY26 featured two national-scale efforts — "Bhujia Ho To Bikaji," reinforcing the flagship category association, and "Kya Baat Hai Ji," the company's first regional campaign, targeted specifically at Uttar Pradesh and fronted by Pankaj Tripathi.2 The UP campaign is the tell. Uttar Pradesh is the single largest prize in Bikaji's focus-market expansion — management noted on the Q1 FY27 call that UP's addressable market roughly equals the other five focus states combined, and that it grew about 37% in the quarter.10 Spending national-quality creative on one state, with a regionally resonant face rather than a universal one, is what a company does when it has decided that geographic expansion is the growth algorithm.
The Distribution Machine
The numbers here are the ones an investor should actually track, because they are the mechanism by which advertising converts to revenue. Direct outlet coverage grew from 71,884 outlets in March 2022 to 3,11,331 in March 2025 — a more than fourfold expansion in three years — reached 3.54 lakh by March 2026 after adding about 9,638 in the fourth quarter alone, and stood at 3,70,893 by June 30, 2026, up 13.6% year on year.429 Total reach, including outlets served indirectly through wholesalers, was 14.46 lakh at the end of June 2026, up from 12.08 lakh in March 2025.49 Management has guided to roughly 50,000 new direct outlets a year, weighted toward focus markets.8
Why direct coverage rather than total reach is the number that matters: a directly serviced outlet is one where Bikaji's salesperson controls the assortment, the planogram and the replenishment cycle. An indirectly served outlet buys whatever the wholesaler happens to have. Converting reach into direct coverage is how a snack company turns distribution breadth into shelf-share depth — and it is expensive, which is why it shows up in the cost line before it shows up in the revenue line.
Geography, and the Concentration Problem
The company splits India into "core" (Rajasthan, Assam, Bihar and adjacent), "focus" (Uttar Pradesh, Delhi and others) and "other." In FY25, core was 69.7% of revenue and focus 15.2%; by the June 2026 quarter, core was 72.4% growing 10.8% and focus 14.3% growing 18.9%.49 Of about 3.5 lakh direct outlets, roughly 1,20,000 sit in the four core states and 1.7 lakh in the focus states.8 Management guides core to 13–15% growth and focus to more than 20–30% in FY27.89 The maths of that guidance is the whole bull case for the next three years — but note that core's share rose rather than fell over the past year, which means the focus states are not yet growing fast enough to change the mix. That is the honest reading, and it is not the reading the guidance implies.
There is an important asymmetry hidden inside the core-versus-focus framing that management has been candid about. Focus markets are not homogeneous. Uttar Pradesh is delivering; Delhi has underperformed and has received limited investment, by management's own account.8 That is a rational triage — put the money where the addressable market is largest and the competitive intensity lowest — but it also means the "focus market" growth number is carried disproportionately by one state. A single-state dependency inside the diversification strategy is a narrower proposition than the headline suggests, and it should be read that way.
Pack Architecture and the ₹5 Ceiling
Bikaji sells roughly 58–60% of its revenue through impulse packs — the ₹5 and ₹10 sachets — and about 40% through family packs.49 The impulse pack is a customer-acquisition instrument: it puts the brand into a rural consumer's hand at a price point where the purchase decision is trivial. It is also the company's single greatest margin vulnerability, because a ₹5 pack cannot become a ₹5.50 pack. When input costs rise, the only levers are grammage reduction or eating the cost — which is precisely what happened in FY25, and what the next section examines.
The counterweight is the family pack, which grew 11.2% to ₹399 crore in the June 2026 quarter against impulse packs at 10.5%.9 Family packs are bought in modern trade, e-commerce and larger kirana formats, carry better realisation per kilogram, and are far less price-sensitive because the consumer is buying for a household rather than reaching for change at a counter. If Bikaji's premiumisation narrative is going to show up anywhere in the numbers, it is in a rising family-pack share — and over the past two years that share has moved only marginally.49
Market Position, Stated Precisely
Bikaji is the largest manufacturer of Bikaneri bhujia and the third-largest player in Indian ethnic snacks, with roughly 8.7% share against Haldiram's 36.6% and Balaji's 9.6%.36 Those two facts sit oddly together and should: Bikaji dominates a product and is a distant third in the category that product belongs to. The company's growth thesis is essentially that its bhujia leadership can be levered across a wider geography and a wider basket. The distribution numbers say it is executing that. The mix numbers say it is not yet winning it.
VIII. Earnings Transcript Analysis & Historical Falsification
The most useful thing a long-term investor can do with Bikaji is read two consecutive years of earnings calls side by side, because FY25 and FY26 form a natural experiment in what happens to this business when input costs move against it and then move back.
FY25: The Year the Margin Broke
The sequence is visible quarter by quarter in the company's own charts. EBITDA margin ran 13.6%, 14.4%, 12.0% and 16.0% through FY24, then 14.8%, 12.1% (as reported for the second quarter's comparative period), 7.8% in Q3 FY25 and 12.1% in Q4 FY25.4 The third quarter is the one that matters: revenue grew 14.5% year on year to ₹714.9 crore while EBITDA margin collapsed to 7.8% and gross margin fell to 29.0%.4 For the full year, on the adjusted basis excluding a one-time PLI income adjustment, revenue from operations rose 14.6% to ₹2,562 crore with 10.3% underlying volume growth, but EBITDA fell 10.0% and PAT fell 22.1%.4 On the reported basis including PLI, revenue was ₹2,622 crore, EBITDA margin 12.5% against 16.8% the prior year, and PAT ₹194.3 crore against ₹263.5 crore — a 26.2% decline.4
Management's explanation, in its own words in the FY25 presentation, was that "the sharp and unanticipated increase in input prices particularly in edible oil put temporary pressure on profitability."4 The company's own sensitivity chart tells the story better than the prose: indexed to a base of 1.00, edible oil prices had fallen as low as 0.57 before rising back to 0.85; laminates and corrugated boxes moved similarly.4 In other words, Bikaji had been enjoying a deflationary tailwind and had priced its packs into it. When the tailwind reversed, there was no room left.
It is worth pausing on the mechanics of why an edible-oil move hits this business so hard, because the arithmetic is not obvious. Fried snacks absorb oil during frying — a meaningful fraction of the finished packet's weight is the oil. Palm oil is therefore not a minor input; it is close to a co-ingredient. When its price doubles off a low base, the cost of goods for the entire portfolio moves at once, across every SKU, with no product-mix escape route. There is no equivalent of a manufacturer swapping to a cheaper grade of packaging or trimming an advertising line. The company either raises price, cuts grammage, or takes it in the margin — and in FY25 it took most of it in the margin.
Historical Falsification: The Pricing-Power Claim
The claim under examination is that Bikaji's brand equity and GI-linked leadership in Bikaneri bhujia confer pricing power. FY25 falsifies the strong version of that claim decisively. Revenue grew double digits, volumes grew double digits, and net profit margin fell from 11.3% to 7.4% — a 390 basis point compression — because the company could not raise prices fast enough at the ₹5 and ₹10 price points that carry the majority of its volume.4 A business with genuine pricing power in an inflationary input year does not lose 430 basis points of EBITDA margin while growing volume 10%. What Bikaji demonstrated instead is volume power — the ability to keep selling more units through a cost shock — which is a real and valuable thing, but a different thing.
The mechanism by which it eventually adjusted is instructive and was disclosed rather than hidden. On the FY26 call, CFO Rishabh Jain described a price rise "close to 3%" taken in April 2026, and the company confirmed the approach it uses at the low end: reduce grammage in impulse packs while holding family-pack pricing.8 By the Q1 FY27 call in August 2026, management said it had taken two MRP increases in four months and did not plan further increases in the following 30 days unless costs turned "catastrophic," and framed the medium-term ambition as 50 to 75 basis points of annual margin improvement through pricing and gross-margin gains, targeting a 15% EBITDA margin by FY29–30.10 Grammage reduction is a real pricing lever. It is also a slow one that shows up as a gap between volume growth and value growth — which is why that gap is one of the few metrics worth tracking mechanically.
FY26: The Recovery, and What It Proves
With input costs benign, the model snapped back exactly as the operating leverage would predict. FY26 revenue rose 14.4% to ₹2,994 crore with 9.5% volume growth; gross margin rose 290 basis points to 35.1%; EBITDA margin recovered to 13.7%; PAT rose to ₹254.4 crore.2 The fourth quarter was stronger still — revenue up 18.0% to ₹720.9 crore on 16.1% volume growth, PAT up 39.8% to ₹56.0 crore.2
The disconfirming detail sits inside that recovery, and management put it there itself. Bikaji's reported margins include Production Linked Incentive income: ₹51.36 crore in FY26 and ₹59.84 crore in FY25.7 On the Q1 FY27 call, management confirmed the FY27 margin guidance of 13–13.5% is inclusive of PLI, that PLI contributes roughly 150 basis points of EBITDA, that FY27 is the last year of the subsidy — approximately ₹50 crore expected, ₹12.5 crore received in the first quarter — and that restoring margin after the subsidy sunsets "will take approximately two years."1011 This is the juxtaposition that matters: the same management guiding to 15% EBITDA margins by FY29–30 has also told investors that roughly 150 basis points of today's margin disappears when the government stops paying. Any margin-expansion thesis for Bikaji has to clear that hurdle before it starts.
What the Analysts Pushed On
The Q&A is where the narrative gets stress-tested, and the questions were pointed. On the Q1 FY27 call, Nuvama's Abneesh Roy questioned the Bengal labour disruption directly, noting that other FMCG companies had not reported similar issues; management's answer was specific rather than evasive — bhujia production is concentrated in Bikaner and worked substantially by Bengali labour, and the mitigation is dual-plant manufacturing.10 IIFL's Percy Panthaki challenged whether a five-day shutdown could plausibly move a full quarter given supply-chain buffers; management conceded the labour shortage extended into mid-May and that inventory restoration took time, and fell back on "the numbers speak louder" as June and July momentum accelerated.10 On the FY26 call, Motilal Oswal's Shirish Pardeshi pressed on whether GST rationalisation had actually shifted share from unorganised to organised players; Verma declined to claim victory, saying the impact "would be seen over two to four quarters."8 An analyst questioned why western snacks grew only 8.5% in Q4 FY26 against a historical 20%-plus; management acknowledged the underperformance and attributed it to a category-wide slowdown.8
Two things are worth saying about the tone. First, the answers are largely concrete and quantified — production days lost, price increases in percentage terms, outlet counts by state cluster — which is a positive credibility signal relative to the Indian mid-cap average. Second, when asked about healthy snacking, Verma gave the least promotional answer available — there is no such thing as healthy snacks, only "less unhealthy snacking" — and put meaningful scale five to six years out.10 Management that declines to oversell an obvious narrative hook is management worth listening to on the things it does claim.
There is one narrative inconsistency worth flagging, because it is the kind of thing that separates a credible operator from a promotional one. Across FY26 and Q1 FY27, management has simultaneously guided to holding gross margin flat in percentage terms, expanding EBITDA margin through operating leverage, holding advertising at roughly 2% of sales, absorbing the loss of a 150 basis point subsidy, and reaching 15% EBITDA margins by FY29–30.810 Each statement is individually plausible. Together they require nearly everything to break the right way for four consecutive years, in a business that has demonstrated it cannot protect margin through a single adverse commodity year. That is not evidence of dishonesty; it is evidence that the guidance describes a good scenario rather than a base case, and it should be read with that discount applied.
The Calibrated Conclusion
Bikaji's moat is a cost-and-consistency moat, not a pricing moat. FY25 rejected the pricing-power claim in its strong form; FY26 showed that the cost structure is genuinely operating-leveraged when inputs behave. The revised, defensible claim is narrower: Bikaji can grow volume through a cost cycle and recover margin on the other side, but it cannot protect margin during one. The KPI that confirms or falsifies the revised claim is the spread between value growth and volume growth over a full cycle, read alongside EBITDA margin excluding PLI.
IX. Optionality Bets: Frozen Foods, Exports & Premium QSR
In a Lucknow shopping district, a café sells specialty coffee, artisanal chocolate and patisserie under a brand called The Hazelnut Factory. In Ujjain, a plant freezes samosas for shipment to Canada. In Kathmandu, a joint-venture factory is under construction with a partner best known for instant noodles. None of these look like a bhujia line in Bikaner, and that is exactly the point — and exactly the risk.
Every Indian consumer company eventually tells an optionality story, and the discipline an investor needs is to size it before believing it. In Bikaji's case, the sizing is unambiguous: exports were 4.3% of revenue in the June 2026 quarter and declined 2.2% year on year; THF is an equity-accounted associate contributing a small negative; frozen is a sub-scale plant running below target utilisation.97 Together, the non-core ventures are a low-to-mid single-digit share of revenue and a negative contributor to profit. They are not the thesis. They are a call option with a visible premium.
Frozen Food and Exports
The rationale is the most coherent of the three bets. Indian diaspora demand for frozen samosas, parathas and ethnic meals is real, is served in hard currency, and carries better gross margins than domestic impulse packs. Ariba's Ujjain plant gave Bikaji owned frozen capacity and an export customer base overnight rather than through a three-year greenfield build, and management said the acquisition drove export growth of 50–60% and that exports crossed ₹100 crore for the first time in FY26.815 The Q1 FY27 targets are specific: the US business to grow threefold over two years, and international revenue to reach 5.5–6% of the total within three to four years.10
The mechanism by which exports would improve group margins is worth spelling out, since it is often asserted rather than explained. A packet sold in New Jersey or Dubai carries the same manufacturing cost as one sold in Patna but a materially higher realisation, because the diaspora consumer is buying a nostalgia good in a high-income market rather than an impulse snack at a fixed price point. There is no ₹5 ceiling abroad. Export revenue is also denominated in hard currency, which means a weakening rupee helps rather than hurts — a natural hedge against the imported edible oil that damages the domestic business. That is a genuinely attractive structural argument. It is also, so far, an argument about a business that was 4.3% of revenue and shrinking in the most recent quarter.9
The disconfirming evidence is equally specific and equally recent. Exports fell 2.2% in the June 2026 quarter, which management attributed to tariff uncertainty and freight costs that had tripled.910 More pointedly, Bikaji Foods International USA Corp — the entity through which the American ambition runs — lost ₹4.71 crore in FY26, and the parent took a ₹5.54 crore impairment against its equity investment in it, having put a further ₹4.88 crore in during the year.7 That is the historical rate at which this company has so far converted an export ambition into export profit: negative. The claim is not rejected — the frozen capacity is new and the utilisation ramp is genuinely early — but it is unproven, and it has already produced one write-down. The falsifying test is whether exports resume double-digit growth and whether the US subsidiary reaches breakeven before the next impairment review.
Nepal: A Template Test, Not a Revenue Story
On July 23, 2025, the board approved a joint venture and shareholders' agreement with Nepal's Chaudhary Group for a 50:50 venture, including co-investment in a local manufacturing facility.7 Management put the commitment at roughly ₹15 crore from each side with local production expected within eight to nine months of the Q1 FY27 call.10 The partner choice is the interesting part. Chaudhary Group is the closest thing Nepal has to a national FMCG institution, and it built that position on an instant-noodle brand that dominates the domestic market. Pairing an Indian manufacturer's product capability with a local incumbent's route-to-market is the standard emerging-market entry structure precisely because it addresses the two things a foreign entrant cannot buy quickly: shelf access and regulatory familiarity. The logic is tariff arbitrage plus partner distribution: manufacturing inside Nepal removes import duty and shortens the freshness cycle, and CG brings the route to market. At ₹15 crore, this is not a capital allocation question; it is a template test. If a 50:50 JV with a strong local partner works in Nepal, the same structure is repeatable across South Asia and the Gulf. That is the reason to watch it, not the revenue.
Café Retail and the House of Brands
This is the bet with real execution risk, and the company's own numbers frame it honestly. The store network went from 15 to 28 stores year on year by June 2026, with retail revenue up 71.8% to ₹36.4 crore in the quarter; the target is 35 stores by the end of FY27 and 50 within two and a half to three years, focused on tier-two cities, with each store underwritten at ₹6–8 crore of sales and 25%-plus store EBITDA.910 On the FY26 call, management said the retail business had crossed ₹100 crore of revenue for the first time, expected 50–60% annual growth for two to three years, and characterised it as EBITDA positive and "not dilutive."8
Hold that characterisation against the audited record: Bikaji Foods Retail Limited, the wholly owned holding entity, lost ₹2.15 crore in FY26 on turnover of ₹2.03 crore, and the THF associate contributed negative ₹0.84 crore to consolidated profit.7 Store-level EBITDA positive and consolidated-entity loss-making are not contradictory statements — pre-opening costs, corporate overhead and amortisation sit above store contribution — but an investor should be clear which one management is describing. The gap between "EBITDA positive at the store" and "profitable for shareholders" is exactly where retail expansions go wrong, because it is bridged only by store count, and store count is bridged only by capital and site selection.
The comparison an investor should hold in mind is what a café chain requires that a snack factory does not. A fryer line, once installed, produces the same output whether the economy is strong or weak, and its utilisation is a function of demand aggregated across three lakh outlets. A café's utilisation is a function of one street corner. Site selection errors are not recoverable; a badly chosen lease burns cash for its full term. Fresh bakery carries daily wastage that a sealed pouch does not. And hospitality labour turns over at rates that packaged-goods manufacturing does not experience. None of this makes the strategy wrong — premium sweets and gifting is a genuinely attractive Indian category, and Bikaji's brand is credible in it. It does mean the failure modes are unfamiliar to this management team, and unfamiliar failure modes are the expensive kind.
Sizing It Correctly
The correct posture on all three bets is neither dismissal nor enthusiasm. Together they are a small share of revenue, a negative share of profit, and roughly ₹190 crore of committed capital across Ariba and THF. If they work, they add a growth vector and a margin mix benefit in the back half of the decade. If they do not, the downside is bounded by the carrying values the auditors have already flagged — meaningful to a year's earnings, not to the enterprise. What they should not do is obscure the fact that 96% of this company is still bhujia, namkeen, sweets and papad moving through 3.71 lakh outlets.
X. Strategic Frameworks & Bull vs. Bear Case
Set the two cases against each other with the same facts.
The Bull Case
Start with formalisation, because it is the largest single force. Roughly 43.4% of India's packaged savoury snacks market was unorganised at the time of Bikaji's offer-document study.3 Every increment of food-safety enforcement, GST formalisation and packaging standardisation moves volume from a local fryer to a branded manufacturer, and a company with 325,320 tonnes of installed capacity and automated lines captures that shift structurally rather than by winning share from a peer.4 Management is appropriately cautious here rather than promotional — on the FY26 call it declined to claim GST rationalisation had delivered yet, saying the effect "would be seen over two to four quarters" — but the direction is not in dispute.8
Second, the cost position. The Bikaner complex, sitting inside the moth bean belt with three decades of process tuning behind it, converts raw legume into packed bhujia at a per-kilogram cost that a sub-scale regional competitor cannot match. This is the durable part of the moat and it is the reason the company can afford ₹5 packs at all.
There is a supporting argument the company rarely makes explicitly but which the numbers support: the incremental economics of distribution expansion improve with density. Once a salesperson's route exists in a district, adding outlets along it costs very little and adds revenue at close to full contribution. The expensive part of geographic expansion is the first thousand outlets in a new state; the profitable part is the next twenty thousand. If Bikaji's focus markets are past the first phase — and the outlet counts suggest Uttar Pradesh is — the operating leverage from here should be better than the leverage that got the company to this point.
Third, the distribution runway. Direct coverage roughly quintupled between March 2022 and June 2026, and the company is adding around 50,000 direct outlets a year with the weight going to focus markets where it is under-penetrated.498 Focus markets grew 18.9% in the June quarter against core at 10.8%, and UP — the largest single prize — grew around 37%.910 If focus markets sustain 20%-plus while core delivers low-teens, the blended algorithm produces mid-to-high-teens growth without needing a new category.
Fourth, operating leverage. FY26 proved the model: with benign inputs, gross margin expanded 290 basis points and EBITDA margin recovered 120 basis points, and PAT grew far faster than revenue.2
The Bear Case
First, concentration. Core markets were 72.4% of revenue in the June 2026 quarter, and that share rose over the prior year.9 A company whose growth thesis is geographic diversification but whose mix is becoming more concentrated has not yet demonstrated the thesis. In western and southern India, incumbents like Balaji and a thicket of strong regional chip brands hold the shelf, and Bikaji's own admission of 1.1% share in western snacks tells you where it stands outside its home category.8
Second, margin fragility. FY25 established what happens when edible oil moves against the company: 430 basis points of EBITDA margin and 26.2% of net profit disappeared in a year of double-digit volume growth.4 Layer on the PLI sunset — roughly 150 basis points of current EBITDA, with management guiding to a two-year restoration period — and the FY29–30 target of 15% requires both a benign commodity cycle and successful pricing simultaneously.10
Third, capital allocation. Zero primary capital was raised at the IPO, and the diversification portfolio — Ariba, THF, Bikaji Bakes, the US entity, Petunt — collectively lost money in FY26 with one impairment already taken.147
Fourth, valuation. At ₹598.30 a share the market capitalisation is about ₹15,000 crore against FY26 net profit of ₹254 crore — a trailing multiple in the high fifties.1217 The stock's 52-week range runs from ₹592 to ₹818.70, and it is currently at the bottom of it.17 A multiple of that order embeds years of mid-to-high-teens compounding and margin expansion. It leaves no room for a repeat of FY25.
Fifth — and this is the item that gets least attention — channel mix. Quick commerce is growing faster than anything else in Bikaji's portfolio and is structurally more expensive to serve than a kirana store, because the platform captures a share of the transaction that a traditional retailer does not. Today the exposure is small: e-commerce moved from 2% to 3% of the business in FY26.8 But the growth rate is above 100%, and a channel growing at that pace becomes material within a few years.910 The unresolved question is whether the incremental volume arrives at acceptable contribution, or whether Bikaji ends up funding platform economics out of a margin structure built for general trade. Management has not disclosed channel-level profitability, and until it does, this remains an open exposure rather than a quantified risk.
The Frameworks, Reconciled
Under Helmer's lens, the two powers Bikaji genuinely holds — scale economies in bhujia and process power in continuous frying — are cost powers, not price powers, and cost powers protect returns only as long as the cost differential exceeds the brand differential your competitor enjoys. Under Porter's, the binding constraints are substitute intensity from an unorganised sector nearly half the market's size and supplier power vested in globally traded edible oil. The strategic implication is that Bikaji's returns are a function of two variables it does not control — palm oil and the pace of formalisation — and one it does: how fast it converts reach into direct coverage in states where it is currently small.
Myth Versus Reality
Three consensus statements about Bikaji deserve correcting. Myth: the GI tag on Bikaneri bhujia is a competitive moat for Bikaji. Reality: the tag is a regional appellation covering all of Bikaner district and available to any registered producer inside it, including the Haldiram branches that started there.3 It protects the category from imitation elsewhere; it does not protect Bikaji from anyone. Myth: Bikaji is a national brand. Reality: nearly three-quarters of revenue comes from core states, and that share has been rising rather than falling.9 Myth: the company's margins are recovering structurally. Reality: FY26's recovery was substantially a commodity-cycle recovery, and reported margins include roughly 150 basis points of a subsidy that management has said ends in FY27.10 Each myth is a plausible reading of a headline; none survives contact with the filings.
The Activist's Slide
A skeptical investor would open with three items: a 20% managerial pay increase against 3.76% median employee growth in a company where the CMD earns 344 times the median;7 ₹190-odd crore committed to café retail and frozen food by a company that has never operated either at scale, with every acquired entity loss-making in FY26 and a US impairment already booked;7 and reported margins that flatter the underlying business by roughly 150 basis points of soon-to-expire government subsidy.10 None of these is fatal. All three are legitimate.
The KPIs That Actually Matter
Three, and only three. First, the spread between value growth and underlying volume growth — it reveals whether growth is real demand or grammage-and-price arithmetic. Second, EBITDA margin excluding PLI income — the only honest read on whether the structural margin story is working as the subsidy rolls off. Third, focus-market revenue growth alongside net direct-outlet additions — the single mechanism by which the geographic diversification thesis either becomes true or does not.
XI. Epilogue: Business & Investing Lessons
Lesson One: Leaving a Dynasty Means Giving Up the Shortcut
Shiv Ratan Agarwal's decision in 1987 was not a clever brand play. It was a decision to trade the fastest available path — a famous name — for the slowest one, which was building a manufacturing capability that would take decades to compound. Six years passed before the business even had a brand identity worth the name. The generalisable point for investors looking at family-business spinoffs is that the family halo is almost never transferable; the operating asset is. When a spinoff's pitch rests on lineage rather than on a specific capability, the lineage is decoration.
Lesson Two: Industrialising Authenticity Is an Equipment Problem First
Bikaji did not scale bhujia by advertising it. It scaled bhujia by co-developing continuous fryers for a dough nobody had built machinery for, and by switching to laminated, gas-flushed packaging that turned a three-week product into a six-month one.35 The packaging change, not the frying line, is what made national distribution and export physically possible. In consumer businesses rooted in a place, the binding constraint is usually logistical chemistry, and the company that solves it first gets a decade of geography that its competitors cannot reach. The corollary is the caution: process advantages that depend on widely available technology decay, and Bikaji's does not protect the price it can charge — only the cost at which it can make.
Lesson Three: Interrogate Distribution Powerhouses Hardest When They Buy Storefronts
Bikaji's core skill is throughput — tonnes per line, cases per truck, outlets per salesperson. A café chain is a different sport played with different equipment: leases, wastage, footfall, hospitality labour. The company has committed real capital to that sport, and the FY26 record shows every acquired entity in the red, one impairment taken against the US business, and a step-down retail subsidiary sold within months of being acquired.7 None of that proves the strategy is wrong; the retail base is small and the ramp is early. It does mean the burden of proof sits with management, and that the proof is countable: store openings against the stated 35-and-50 targets, and whether Bikaji Foods Retail turns profitable before the remaining committed infusion is spent.
Lesson Four: Subsidised Margins Are Borrowed Margins
There is a fourth lesson that Bikaji illustrates cleanly and that generalises well beyond snacks. Government incentive schemes — production-linked, state-level, export-linked — flatter reported profitability for a defined window and then stop. A company that reports margins inclusive of such incentives, guides on the same basis, and sets long-term targets from that base is compounding an accounting convenience into a strategic assumption. Bikaji has been transparent about the mechanics, disclosing the PLI amounts in the notes and the basis point impact on calls.710 The discipline sits with the reader: build the model on the ex-subsidy number, and treat the incentive as what it is — a temporary transfer, not an earned margin.
The Founder's Actual Legacy
There is a final observation about Shiv Ratan Agarwal worth recording, because it is the least sentimental and the most useful. His achievement was not the brand, which took six years to acquire a name and twenty-six to acquire a national celebrity. It was not the family break, which was a constraint rather than a strategy. It was that he identified, correctly and early, that the binding constraint on his industry was technological rather than commercial — that whoever solved continuous frying and oxygen-barrier packaging for legume dough would inherit a geography, and that this was a solvable problem if you were willing to spend a decade abroad co-developing machinery instead of a decade at home buying advertising. Most founders in most industries misidentify their binding constraint. He did not.
What his successor inherits is a solved problem and an unsolved one. The manufacturing question — can this company make bhujia cheaper and more consistently than anyone else — was answered in the affirmative decades ago and is not seriously in dispute. The commercial question — can a third-place brand convert a manufacturing advantage into national share against a leader four times its size, while defending margin through commodity cycles and funding a diversification programme out of operating cash flow — is entirely open. The FY25 and FY26 results are two data points in a series that will take another five years to read.
The broader synthesis is this. Bikaji is a genuinely good manufacturing business with a genuinely long distribution runway, priced as though both the runway and a margin expansion are already delivered. Its recent history contains one clean demonstration of resilience — FY26's recovery — and one clean demonstration of fragility — FY25's collapse. The founder who solved the hardest problem the company ever faced is gone, and the successor was in the chair before he left, which is the best version of that transition available. What remains unresolved is whether the third-largest player in a category dominated by a name that Bikaji's own founder walked away from can convert cost leadership into national share, in a market where nearly half the competition still has no name at all.
References
-
Bikaneri Bhujia — Geographical Indications of Goods (documentation), oriGIn ↩↩
-
Press Release — Financial Results for Q4 & FY26, Bikaji Foods International Limited, 2026-05-21 ↩↩↩↩↩↩↩↩↩↩↩
-
Industry Report on Savouries, Sweets and Papad in India — Frost & Sullivan (commissioned by Bikaji Foods), 2022-02-15 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q4 & FY25 Earnings Presentation — Bikaji Foods International Limited, 2025-05-15 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Shiv Ratan Agarwal, Founder of Bikaji Foods International, Passes Away — Open The Magazine, 2026-04-23 ↩↩↩↩
-
Annual Report 2025-26 — Bikaji Foods International Limited ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Bikaji Foods International Ltd (BIKAJI) Q4 FY26 Earnings Call Transcript — AlphaStreet, 2026-05-22 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Bikaji Foods Q1 FY27 slides: growth rebounds amid cost pressures — Investing.com, 2026-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Earnings call transcript: Bikaji Foods Q1 FY27 — Investing.com, 2026-08-06 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Bikaji Foods targets 13-13.5% EBITDA margin for FY27 after Q1 supply disruptions — ScanX, 2026-08 ↩↩↩
-
Bikaji Foods International Ltd — Consolidated Financials, Screener.in ↩↩↩
-
Lighthouse churns out high returns by partially exiting snacks maker Bikaji — Lighthouse Funds ↩↩
-
Bikaji Foods International IPO — Prospectus and Offer Details, Moneycontrol ↩↩↩
-
Bikaji Foods acquires 55% stake in Ariba Foods for Rs 60.5 crore — Business Standard, 2024-08-24 ↩↩
-
Announcement under Regulation 30 — Acquisition of Hazelnut Factory Food Products Private Limited by Bikaji Foods Retail Limited, 2024-10-16 ↩↩↩
-
Bikaji Foods International Limited (BIKAJI) — Stock Quote, NSE India ↩↩↩
-
Bikaji Foods Family Office leads Rs 72 crore round in Dil Foods — VCCircle, 2026-05-14 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube