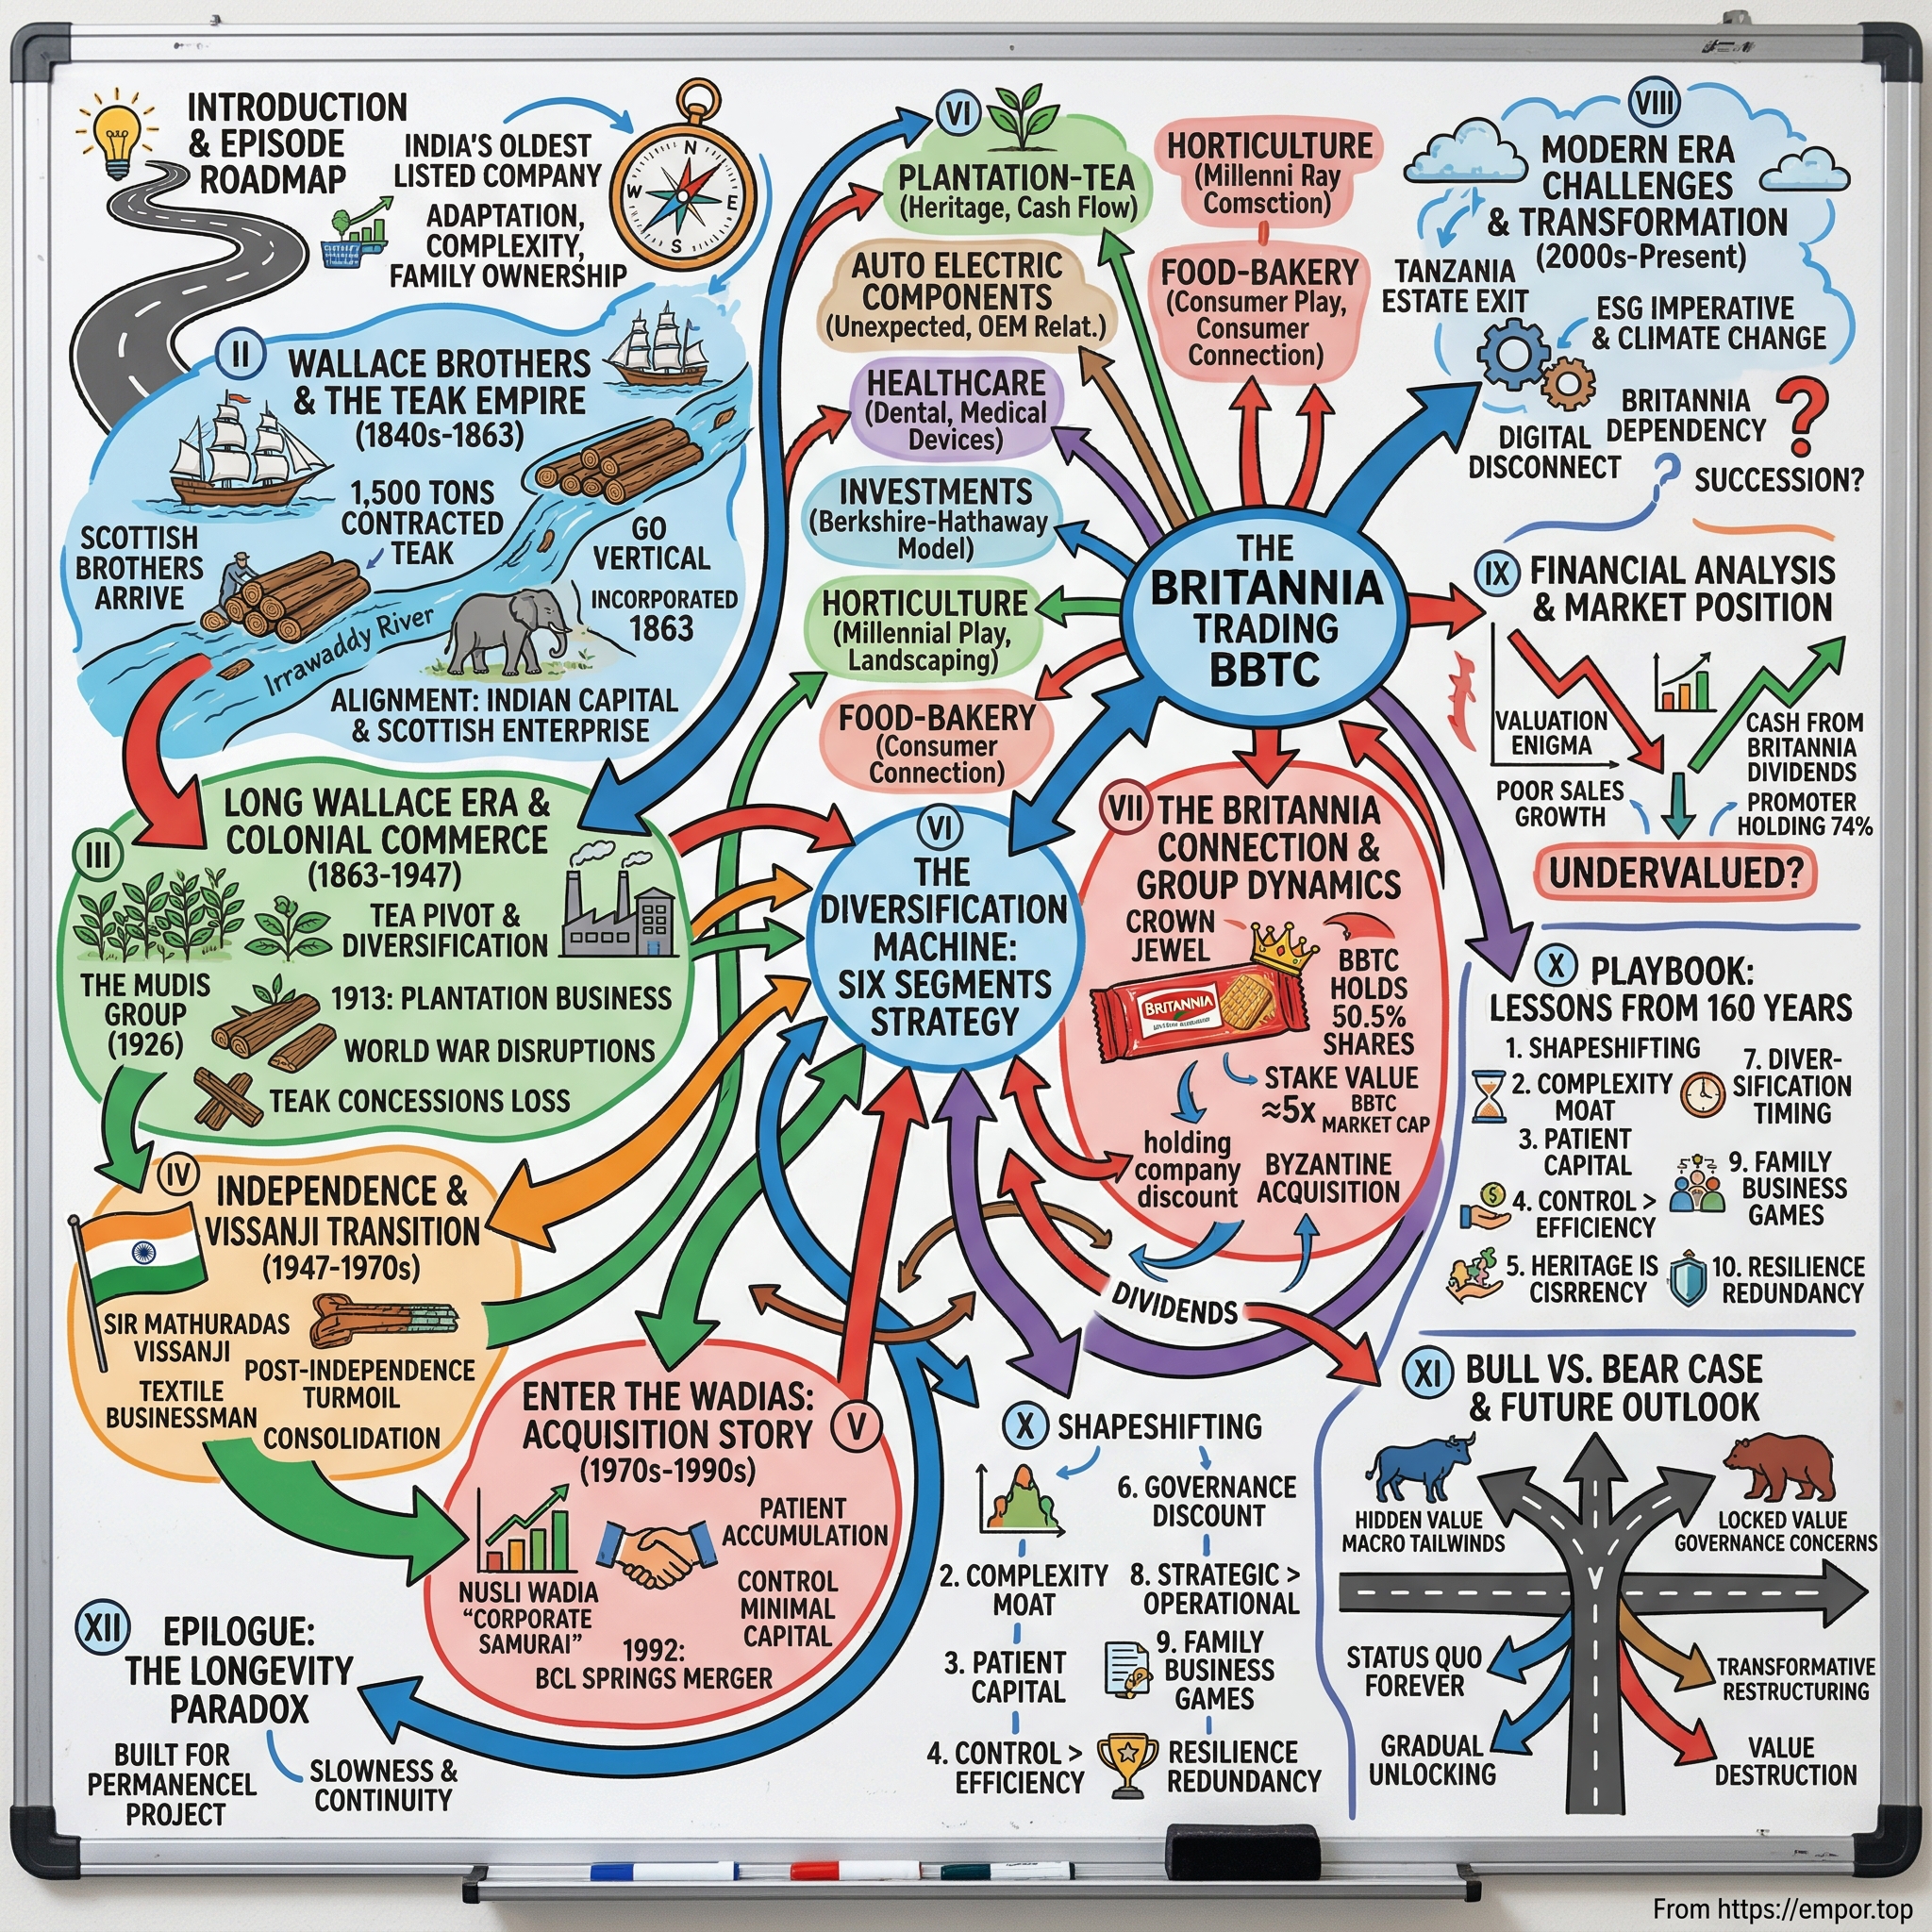
Bombay Burmah Trading Corporation: From Colonial Teak to FMCG Powerhouse & The Holdco Puzzle
I. Introduction & Episode Roadmap
On the morning of August 27, 2026, traders watching the National Stock Exchange saw something unusual happen to a stock that most of the market treats as a sleepy relic. Shares of the Bombay Burmah Trading Corporation — a company incorporated in 1863, when the American Civil War was still being fought and the Suez Canal had not yet opened — jumped nearly 13% in a single session, touching ₹1,605.1 Nothing had changed about the tea it sells, the solenoids it manufactures, or the dental points it exports. What changed was a sentence in a court file.
Three months earlier, in an order dated May 29, 2026, the Supreme Court of India had reproduced an observation drawn from a Central Empowered Committee report: that lease rent of roughly ₹4,655.24 crore remained recoverable from the company in respect of the Singampatti tea estate in Tamil Nadu, computed from 1958 through August 2025.2 For a company whose entire market capitalisation sat near ₹10,500 crore, a number of that size was not an accounting footnote. It was an existential arithmetic problem.3 The company filed an interlocutory application arguing that the figure had never been the subject of a formal notice and had never been adjudicated after hearing its side.4 On August 19, 2026, the Court recalled the observation.1 The stock responded as equities typically do when a tail risk is removed from valuation models.
That episode is a near-perfect miniature of the entire Bombay Burmah story. On one side is an operating business — tea, coffee, auto-electric components, dental products, and horticulture — generating roughly ₹300 crore of standalone revenue in a good year.5
On the other side are consolidated accounts that reported revenue of ₹19,539 crore and consolidated profit after tax of ₹2,499 crore in the financial year ended March 2026.6 The gap between those two numbers is not an accounting quirk. It is the defining feature of the company.
The core paradox. Bombay Burmah, through a chain of step-down subsidiaries, is the controlling shareholder of Britannia Industries, holding roughly 50.55% of the consumer franchise.7 Britannia reported FY26 consolidated revenue of ₹19,152 crore and profit of about ₹2,537 crore, on a return on capital employed of roughly 56%.78 Strip Britannia out of Bombay Burmah's consolidated accounts and what remains is a modest plantation-and-engineering operation with the earnings power of a mid-sized firm. Bombay Burmah is not primarily an operational conglomerate; it functions as a holding vehicle dressed in conglomerate operations.
The episode thesis. This case study illustrates what Indian investors call the holding company trap. A single major consumer asset sits inside a legacy corporate structure controlled by a promoter family; the structure cannot be unwound without tax leakage; there is no realistic activist mechanism to force a restructuring; and the market consequently prices the wrapper at a fraction of its underlying assets. As of late August 2026, Bombay Burmah's market capitalisation of roughly ₹10,486 crore compared with a Britannia stake worth on the order of ₹64,000 crore at Britannia's own market valuation of about ₹1.26 lakh crore.37 That reflects a holding company discount near 80% — wider than the 40%–60% range historically observed in Indian markets.9
It is worth clarifying how holding companies function in Indian markets. Think of the structure as a locked vault holding shares of a cash-generating business. The vault itself trades under its own ticker, which in theory should track the net asset value of its contents minus administrative overhead. In practice, the ticker tracks market expectations of how much cash flow will ultimately accrue to minority equity holders. If controlling shareholders exercise absolute control, maintain the structure indefinitely, or deploy capital into unrelated ventures, the holding entity trades at a deep discount — reflecting a diminished effective claim on underlying assets rather than a lower intrinsic value of those assets.
That structure explains why Bombay Burmah operates on two distinct timelines. The first is Britannia's operational clock, driven by quarterly volume growth, palm oil commodity cycles, and market share dynamics against peers like Parle and ITC. The second is the structural clock, governed by corporate decisions, capital allocation, tax treatment, and judicial rulings — factors that have historically exerted a far greater influence on Bombay Burmah shareholder returns than biscuit manufacturing operations. Investors monitoring only operational metrics risk being repeatedly misaligned with structural realities.
The central question is why this valuation gap persists. The explanation is twofold: structural friction common to holding companies, combined with specific corporate capital allocation decisions — most notably the multi-decade funding of an airline that ultimately entered liquidation, resulting in a single-year provision of ₹1,865.66 crore.10
What this story examines. How a Scottish timber house transformed into an Indian holding company; how the controlling Britannia stake was assembled through a corporate battle with a French food multinational; what the standalone operations earn; and whether land bank optionality assumptions hold up against Singampatti legal disclosures.
The analysis further evaluates the implications of the Go First insolvency for group capital allocation, whether financial contagion risks have subsided, and how institutional investors have responded — including a March 2026 vote where public institutions cast 55.33% of votes against Britannia's chief executive appointment.11 Finally, it outlines the key catalysts required to assess structural change.
A note on scope: Britannia's standalone operational trajectory — brand strategy, distribution scale, and rural execution — is covered only where it impacts Bombay Burmah shareholders' indirect equity claim. The analytical focus remains on the corporate structure filtering those earnings.
A note on perspective: This analysis focuses on the structural disconnect between owning an operating franchise directly versus holding equity in a controlling investment entity — a distinction that has represented a multi-billion-dollar valuation gap for over a decade.
 Subscribe on LinkedIn
II. Colonial Foundations & The Teak Empire (1840s–1947)
Picture the Rangoon waterfront in the 1850s. Teak logs, some of them two centuries old, float down the Irrawaddy River in rafts lashed together by men who have worked the river for generations. Elephants drag timber out of unmapped forests. On the bund, a Scottish merchant house counts its inventory.
The Wallace family arrived in Bombay in the 1840s and built the trading firm that eventually provided Bombay Burmah with its capital, charter, and founding asset base. The corporation itself was formed in 1863 as a public company for a specific purpose: to take over William Wallace's assets and rights in Burma and develop the teak business on a scale larger than a private partnership could sustain.12 That structure established the company's core character. From birth, Bombay Burmah was a corporate wrapper created to hold and monetise operating assets created by others — a role it has maintained ever since.
The timing of the flotation was not accidental. Bombay in 1863 was awash in capital. The American Civil War had choked off the supply of American cotton to Lancashire's mills, and Indian cotton rushed into the gap. The resulting speculative boom turned the city's merchants — Parsi, Gujarati, Bania, Jewish, and British alike — into a deep pool of risk capital hunting for ventures. A joint-stock company formed to work Burmese teak concessions was tailored for that environment: British merchant expertise and concession access on one side, Indian merchant capital on the other, wrapped in a listed structure that allowed both to participate without either holding absolute control. That hybrid ownership structure helped the corporation survive the eventual departure of its British sponsors; the shareholder register was never purely colonial.
The economics of the mid-Victorian teak trade were driven by the material properties of teak itself. Teak is dense, oily, and dimensionally stable; it resists rot, marine borers, and tropical humidity. In the era before steel hulls, it was the premier material for shipbuilding. Even after steel gained dominance, teak remained the material of choice for decks, railway carriages, and imperial infrastructure.
Burma's forests held the world's finest supply. The British annexation of Lower Burma in 1852 opened those forests to concessionaires capable of deploying capital, organising elephant-based extraction, and transporting logs to sawmills.
Bombay Burmah operated this business at scale across British Burma and into Siam. The model was not manufacturing in a modern sense, but a lease-and-extract operation: secure long-dated forest concessions from colonial or princely authorities, invest in extraction logistics, and harvest a natural resource. That business model generates substantial cash flow while leases remain active, but yields nothing once they expire. Its primary risk was not commercial competition but political authority — counterparties were governments, and governments change.
Much of the company's early advantage derived from political relationships rather than proprietary technology. Floating logs downriver involved no patentable process or consumer brand. The competitive edge rested on privileged concession access, multi-year working capital, and an international shipping and agency network. When the granting authority disappeared — as occurred in Burma in 1942, and recurred in a different context at Singampatti eight decades later — the advantage evaporated regardless of operational capability.
Management recognised part of this exposure early. Around 1913, acknowledging that timber leases were finite, Bombay Burmah turned to tea, purchasing plantation land in South India.12 Swapping a depleting timber resource for a renewable agricultural asset reduced Burmese political exposure. It gave the corporation a second pillar — estates in the Nilgiris and the Western Ghats that remained on its books over a century later. Yet it also introduced a long-term liability: plantation land in India was frequently held under long-term state leases, creating obligations that could outlast the commercial logic of the original business.
The plantation pivot did not fully insulate the enterprise from twentieth-century shocks. The First World War disrupted shipping lines and commodity trade. The Great Depression depressed timber and tea prices simultaneously. In 1942, the Japanese invasion of Burma eliminated the company's founding operations entirely. Sawmills, timber stocks, extraction infrastructure, and concession agreements were wiped out.
The enterprise that emerged from the Second World War was effectively a new entity under a legacy title: a South Indian plantation business operating with a Burmese name and a Bombay listing.
By 2026, virtually none of that original operational enterprise survived in physical form. The forests belong to another nation; the sawmills, ships, and Rangoon offices have long since vanished. What persisted was the corporate charter: an entity established in 1863 with an unbroken chain of annual general meetings running to its 161st.5 In a commercial landscape where most nineteenth-century enterprises dissolved, that structural continuity proved durable, providing a listed vehicle that the Wadia group would later repurpose.
For investors, the underlying pattern is clear: Bombay Burmah's longevity has depended on holding assets developed elsewhere and reallocating capital into new fields — moving from timber rights to plantation acreage, and eventually into consumer goods. The corporate form has remained durable while the underlying operating businesses have been serially replaced.
By 1947, as British capital prepared to exit India, the central question turned to who would acquire control of the listed wrapper.
III. Post-Independence, Vissanji Era, & Wadia Group Entry (1947–1990s)
The years immediately following Independence produced one of the major wealth transfers in Indian business history. British managing agencies and merchant houses, facing a new regulatory environment, exchange controls, and the loss of imperial trade preferences, sold their Indian operations to domestic buyers with available capital. Indian trading families who had operated for decades as junior partners in the colonial economy acquired full control of these legacy enterprises.
Bombay Burmah passed to the Vissanji family during this period. For the next two decades, the corporation operated as a mid-sized plantation and trading business — profitable during favorable tea cycles, but largely overlooked by the broader market. It functioned as a stable asset base with unexploited corporate potential.
The economic environment of the era reinforced that posture. Between the mid-1950s and 1991, industrial licensing, import restrictions, and stringent capital controls meant that corporate expansion depended heavily on regulatory permissions. A plantation company could not easily transition into manufacturing, an industrial firm faced strict capacity caps, and foreign capital was tightly restricted. In that environment, the prevailing strategy for family-controlled listed entities was to preserve capital, maintain compliance, and hold existing assets. Bombay Burmah adopted that conservative posture, developing operational habits of patience that over time resembled corporate inertia.
Then came the Wadia family.
Understanding this transition requires examining the Wadia family's deep business lineage. The family's commercial history dates back to 1736, when Lovji Nusserwanjee Wadia secured the contract to build ships for the East India Company at the Bombay dockyard — an enterprise that produced vessels including HMS Trincomalee. From shipbuilding, the family expanded into textiles, making Bombay Dyeing the group's twentieth-century flagship.13 By the late 1960s, leadership of the group transitioned to Nusli Wadia, born in February 1944, who became a prominent figure in Indian corporate history over the subsequent half-century.
Nusli Wadia's strategic approach focused heavily on corporate control rather than direct operational management — accumulating equity stakes, utilizing governance mechanisms and litigation, and maintaining long investment horizons. His career included a prolonged rivalry with Reliance Industries over polyester licensing in the 1980s, a contested acquisition of Britannia Industries across the 1990s and 2000s, and a high-profile governance dispute with the Tata Group in 2016 that resulted in his removal from several Tata company boards where he had served as an independent director for decades. Forbes has estimated his fortune in the multi-billion-dollar range, ranking him among India's wealthiest industrialists.13
The acquisition of Bombay Burmah proceeded gradually. Wadia entities built a stake through the 1970s and 1980s until the corporation became the structural apex of the group's holdings — the corporate wrapper sitting above its most valuable assets. This structure was strategically advantageous: Bombay Burmah was long-established, publicly listed, and thinly followed, providing an efficient vehicle for holding control positions without attracting the public scrutiny of a newly created holding company.
Consequently, public shareholders in the historical plantation enterprise became minority investors in the group's broader capital allocation strategy.
This shift fundamentally altered the equity investment thesis. Investors who bought Bombay Burmah shares in the 1970s acquired an agricultural operating business. Over the subsequent decades, without a single corporate restructuring vote, the nature of the underlying asset transformed through decisions made at the controlling family level. While such structural evolution is common among family-promoted conglomerates in India, the scale of the disconnect at Bombay Burmah was unusual, as the acquired asset eventually dwarfed the parent entity in value.
The relationship between Bombay Burmah and Bombay Dyeing also shifted. Bombay Dyeing served as the group's public face for most of the twentieth century, associated with consumer textiles, advertising, and valuable Mumbai real estate, while Bombay Burmah remained the quieter holding entity for key equity investments. Over time, their relative economic weight inverted: by FY26, Bombay Dyeing's revenue had fallen to ₹1,460.33 crore with profit of ₹26.66 crore, while Bombay Burmah's consolidated accounts carried a biscuit business more than ten times that size.146 For investors, this demonstrated that group-level capital requirements and financial reputation were shared across both entities.
During the 1990s, Bombay Burmah pursued operational diversification across several small manufacturing sectors. It entered auto-electrical components — manufacturing solenoids, switches, slip rings, and precision springs for automotive original equipment manufacturers — an operation continuing today under the Electromags banner, which generated turnover of ₹191.77 crore in FY26.5 It created a healthcare and dental division producing gutta-percha points, paper points, and endodontic consumables, which turned over ₹37.71 crore in FY26.5 It also established horticulture and nursery operations.
This expansion reflected the post-1991 economic environment. As economic liberalisation dismantled industrial licensing, listed plantation companies with surplus cash gained the flexibility to enter manufacturing. Many domestic business groups expanded into new lines during this period, though long-term commercial success required allocating sufficient capital and management focus to achieve operational scale.
Three decades later, the financial impact of these standalone manufacturing divisions remains limited. Combined, these operating units generate revenue equivalent to roughly one and a half percent of consolidated group turnover.65 While requiring management oversight, board review, and working capital, they contribute minimally to overall equity valuation, highlighting a long-standing reluctance to either scale or divest legacy operating units.
As the corporation assembled these small industrial units, the Wadia group simultaneously engaged in a far larger corporate contest across Kolkata, London, and Paris to secure control of a biscuit manufacturer established in 1892.
IV. The Britannia Crown Jewel: Genesis of an FMCG Titan (1990s–Present)
The fight for Britannia is the single most consequential event in the history of Bombay Burmah, yet almost none of it occurred on Bombay Burmah’s own balance sheet.
In the early 1990s, Britannia Industries was a well-regarded but understated biscuit manufacturer whose foreign equity block — roughly 38% — was held by a UK entity, Associated Biscuits International Limited. Control of Britannia consequently ran not through the Indian operating company's direct register, but through the shareholding of this overseas holding vehicle. In 1993, Nusli Wadia acquired control of Britannia from its then-chairman Rajan Pillai, partnering with the French food multinational Danone.15 The Wadia group acquired a stake in Associated Biscuits International, becoming an equal partner alongside Danone in the holding company sitting above the Indian business.16
What followed was one of the longest and most bitter joint-venture corporate battles in Indian business history. The two partners clashed over brand ownership, Danone’s registration of the Tiger biscuit trademark in international markets, non-compete clauses, and the strategic expansion of the Indian enterprise. Wadia filed suit against Danone for non-compete violations, sparking a decade-long dispute across boardrooms, courts, and global financial media. The impasse finally resolved in April 2009, when Danone agreed to sell its stake to Wadia entities, granting the family full control of Britannia for the first time.1617
The resulting structure explains why Bombay Burmah remains an object of intense market scrutiny. Bombay Burmah does not own its Britannia equity directly. Instead, it holds the stake through a network of step-down subsidiaries, several incorporated offshore, which together hold approximately 50.55% of Britannia’s share capital.7 Britannia’s regulatory disclosures record promoter ownership at that 50.55% level, with foreign institutional investors holding about 13.4% and domestic institutions holding nearly 21%.7 These layered entities reflect the legacy of the original Associated Biscuits vehicle and the offshore restructurings of the Danone era — a structural complexity that accounts for much of the persistent holding company discount.
What the crown jewel actually is. Britannia is not merely a large food company; it is one of the highest-return consumer franchises in India. In FY26, it generated consolidated revenue of ₹19,152 crore and a profit after tax of ₹2,537 crore, producing a return on capital employed near 56% and a return on equity exceeding 53%.78 The company recommended a final dividend of ₹90.50 per share for the financial year, representing a payout ratio of roughly 86%.78 These metrics illustrate an asset-light business with minimal incremental capital requirements — an established manufacturing footprint, a fully built distribution network, and mature brands requiring maintenance rather than foundational capital expenditure.
The core economic flywheel operates through three reinforcing elements. First, its flagship consumer brands — Good Day, Marie Gold, NutriChoice, Tiger, and Treat — are household staples across India, giving retailers high inventory turnover with minimal stock risk. Second, strong consumer pull allows Britannia to command premium retail footprint; direct distribution expanded to roughly 2.79 million outlets by FY24, backed by an estimated 30,000 rural distributors.18 Third, ubiquitous shelf placement functions as perpetual brand reinforcement: high retail visibility drives consumer adoption, which in turn secures grocer shelf space. Each cycle through this flywheel lowers the marginal cost of customer acquisition.
To complement this core business as biscuit volume growth matures, management has executed a systematic premiumisation strategy. Britannia has expanded into adjacent categories — including cakes, wafers, croissants, and rusks — characterized by higher price points, lower unorganized competition, and superior gross margin profiles. Management reported that adjacency categories significantly outpaced overall corporate growth in FY26, with recent product innovations such as the Treat Triple Choco Croissant expanding by over 30% in the June 2026 quarter.819 The commercial logic relies on leveraging an existing biscuit distribution infrastructure to launch higher-margin products at negligible incremental distribution cost.
However, category adjacencies present lower competitive barriers to entry. While a new market entrant cannot economically replicate a three-million-outlet biscuit distribution network, it can launch competing premium wafer brands across modern trade and quick-commerce channels with modest capital. Consequently, the channel shifts that alter traditional retail distribution also lower entry barriers in the premium categories targeted for margin expansion.
Britannia's international division represents a smaller, higher-variance segment. During FY26, international operations faced vessel shortages and logistics disruptions stemming from the West Asia conflict, which weighed on export volumes and margins; in response, the company shifted North American manufacturing from Oman to Mundra to maintain supply continuity.819 Performance remained uneven, with strong growth in Kenya offsetting headwinds in the Middle East during the June 2026 quarter.20 For investors, the international segment functions primarily as a source of earnings variance rather than a core growth driver, leaving the investment case dependent on Indian domestic execution.
The broader market structure surrounding Britannia remains highly consolidated. Privately held Parle Products maintains market volume leadership through Parle-G — a value-tier glucose biscuit whose unit economics depend almost entirely on production scale. ITC’s Sunfeast holds a stable third position, backed by ITC’s extensive distribution infrastructure. The remainder of the market consists of regional and unorganized bakeries competing on price within localized markets. This decade-long three-player oligopoly confirms the height of structural entry barriers in mass consumer foods.
Now the falsification. Evaluating the durability of this competitive moat requires testing it against four potential disruption vectors: product substitution, input cost pass-through, channel shift, and leadership continuity.
On input cost pass-through, during the June 2026 quarter, management highlighted palm oil prices near 140 following a price surge of over 20%, noting that selective price increases and operational efficiencies offset approximately half of total cost inflation, with the company absorbing the remaining margin impact.19 This highlights the boundaries of Britannia's pricing power. While substantial, pricing power in mass consumer goods remains constrained; full cost pass-through risks alienating price-sensitive consumers and losing market share to value competitors like Parle. The moat primarily protects volume share rather than absolute gross margin.
On channel shift, e-commerce expanded to approximately 6% of total sales in FY26, with quick-commerce platforms representing nearly 70% of that digital volume.20 Quick commerce operates under fundamentally different economics than traditional distribution, characterized by concentrated platform power, real-time demand data, and aggressive private-label expansion. A physical distribution moat established across millions of small retail outlets provides diminished defensibility when urban consumer demand migrates to centralized digital platforms.
On management continuity, the leadership structure experienced a major shift. Varun Berry, who led Britannia for nearly a decade and oversaw its distribution expansion and margin enhancement, resigned with immediate effect; the board waived his notice period and relieved him of duties on November 10, 2025.21 Rakshit Hargave — former chief executive of Birla Opus with prior executive experience at Beiersdorf and Jubilant FoodWorks — assumed the roles of managing director and chief executive officer effective December 15, 2025.11 An unexpected exit by a long-serving chief executive represents a critical transition for an operating company whose financial performance underpins the valuation of its parent holding entity.
Initial operational performance under Hargave has shown resilience. For the June 2026 quarter, Britannia reported consolidated revenue of approximately ₹4,964 crore, representing a 9.5% year-over-year increase, driven by 9% volume growth and low-to-mid-teens net profit expansion; management reported market share gains despite elevated freight and fuel costs linked to West Asia trade disruptions.2019 While two quarters of financial results do not establish a long-term trajectory, volume expansion in a mature category indicates operational continuity under new executive leadership.
Myth versus reality. Three persistent market assumptions regarding the parent-subsidiary relationship require objective examination.
Myth: Bombay Burmah actively manages Britannia's daily operations. Reality: It does not. Britannia is an independently listed entity with a dedicated board of directors, executive management team, and institutional shareholder base controlling roughly 34% of its equity between foreign and domestic institutions.7 Bombay Burmah functions strictly as a controlling shareholder — exercising board representation and strategic oversight, while operational execution driving Britannia’s 56% return on capital remains under professional management. Consequently, Bombay Burmah equity holders depend on the performance of an executive team over which they hold no direct oversight.
Myth: The 50.55% Britannia stake is a simple, direct equity holding. Reality: The ownership structure is complex and multi-layered. The controlling interest is held across a chain of step-down subsidiaries, including offshore entities established during the Associated Biscuits and Danone eras.16 While disclosures reflect a 50.55% beneficial ownership, cash flow from Britannia dividends must flow through multiple corporate entities and tax jurisdictions before reaching Bombay Burmah shareholders.
Myth: Britannia is an immune, defensive consumer holding. Reality: Britannia remains an operating consumer goods manufacturer exposed to raw material volatility in palm oil, wheat, sugar, and ocean freight, with pricing flexibility bounded by low-cost value competitors. The June 2026 quarter — where management absorbed half of input inflation internally — reflects the ongoing operational reality of mass-market consumer packaged goods.19
Britannia’s competitive moat remains robust, having weathered commodity inflation and executive transition. However, it functions primarily as a share-defending mechanism rather than an unconstrained price-setting monopoly, faces emerging distribution shifts from digital channels, and operates within a multi-tiered corporate structure that insulates management from minority public shareholder intervention. That structural disconnect leads directly to the other side of Bombay Burmah's balance sheet — the operating businesses it manages directly.
V. The Operating Business Reality: Segment Breakdown & Financial Disconnect
A four-hour drive south-west from Coimbatore into the Anamalai hills leads to the Mudis estates, where Bombay Burmah has cultivated tea for over a century. Plucking remains a manual task, and the factory continues to wither, roll, oxidise, and fire leaf using essentially the same principles established in 1913. It is an aesthetically compelling enterprise, but a commercially difficult one to operate.
The division's financial results demonstrate these operational challenges. In FY26, the tea business produced 30.16 lakh kilograms, down from 36.06 lakh kilograms the prior year, even as average selling prices rose to ₹172 per kilogram from ₹161.5 Combining these two movements illustrates the core economics of Indian tea plantations: a 16% drop in output outweighed a 7% price gain, sending top-line revenue lower. Meanwhile, operating costs — dominated by statutory labor and estate upkeep — remained fixed. As a price-taker with a rigid cost structure and weather-dependent revenue, the division remains structurally constrained from generating attractive returns across economic cycles.
A secondary structural challenge rarely highlighted in financial reports involves long-term estate liabilities. South Indian tea plantations carry statutory welfare obligations to resident worker communities — including housing, education, healthcare, and provident funds — that remain fixed regardless of harvest yields. Because an estate operates as a permanent settlement rather than an easily idled manufacturing facility, plantation owners across India have spent two decades exiting estates rather than attempting operational restructurings. Consequently, buyers for marginal estates are typically local planters seeking modest yields rather than strategic acquirers paying valuation multiples. Unpredictable climate patterns exacerbate these risks; the FY26 production decline of roughly six lakh kilograms reflects typical weather-driven volatility that cannot be reliably forecast.5
By contrast, the auto-electrical components division, Electromags, presents a stronger operational profile. Turnover expanded to ₹191.77 crore in FY26 from ₹174.52 crore, driven by approximately 23% growth in plastic assembled parts and slip rings.5 The unit manufactures solenoids, switches, valves, and precision electromechanical components for original equipment manufacturers. These parts — which engage starter motors or route alternator currents — are specified into vehicle platforms years in advance, providing sticky, recurring revenue once designed into OEM platforms.
However, the division faces a long-term technological transition. A significant portion of its product line remains tied to internal combustion engine (ICE) powertrains. Because battery electric vehicles eliminate starter motors and alternators, supplier content per vehicle declines as India's passenger vehicle market electrifies, unless the business successfully transitions to electric vehicle architectures. While Bombay Burmah highlights growth in platform-agnostic product lines like plastic assembled parts and slip rings, management does not disclose the proportion of Electromags revenue derived from non-ICE applications.5 The absence of this breakdown leaves investors unable to evaluate the division's long-term terminal value amid automotive electrification.
The healthcare division, operating as Dental Products of India, recorded turnover of ₹37.71 crore in FY26, representing an 8.51% increase.5 Although it occupies a stable niche with established export markets and healthy margins, the unit accounts for approximately two-tenths of one percent of consolidated group revenue, rendering it immaterial to overall enterprise performance.
Combined with horticulture, Bombay Burmah's standalone operating units generate between ₹270 crore and ₹300 crore in annual revenue. In the June 2026 quarter, standalone revenue from operations totaled ₹67.54 crore, yielding a standalone profit after tax of ₹7.86 crore — though even that modest profit included an exceptional gain of ₹14.87 crore from selling property, plant, and equipment across tea plantations in the Nilgiris and Tanzania.22 Excluding that asset sale, standalone operating activities operated at a net loss for the quarter.
Rationalisation, and what it reveals. Management has actively pursued asset rationalisation. The company divested three tea estates in the Usambara mountains of Tanzania, removing a persistent cash drag.23 In January 2025, the corporation sold 13.91 acres at Aralvaimozhi in Kanyakumari for ₹13.05 crore.24 During FY26, it completed the sale of the Dunsandle estate in the Nilgiris for ₹120 crore — an estate that had contributed ₹5.65 crore of turnover (about 2.05% of divisional turnover) and held a net worth of ₹7.10 crore — to members of the Rangasamy family and Poomex Clothing Company, third-party buyers unrelated to the promoter group.255 The transaction generated an exceptional gain of ₹87.70 crore in the March 2026 quarter, enabling the company to prepay ₹73.44 crore in term loans during the year.65
This divestment strategy exhibits sound corporate finance practices: monetising non-core holdings, reducing debt obligations, and executing arm's-length sales with independent counterparties.
However, these transactions must be viewed in proportion to the overall balance sheet. While a ₹120 crore asset sale and a ₹73 crore debt prepayment improve standalone metrics, they remain marginal relative to a ₹10,500 crore equity valuation and consolidated debt of ₹1,590 crore as of March 2026.3 The rationalisation program streamlines standalone operations, but does not materially alter the holding company's core investment thesis.
What the segment reporting actually shows. Bombay Burmah's consolidated segment reporting for FY26 highlights its operational realities in two primary lines: food, bakery, and dairy products at ₹19,162.78 crore, and investments at ₹1,320.46 crore.6 Every physical manufacturing and agricultural operation — tea plantations, auto components, dental products, and nurseries — sits outside these main categories within residual disclosures, illustrating the extent to which subsidiary assets dominate consolidated performance.
Horticulture and real estate activities are also contained within that residual segment. Horticulture operates as a small-scale landscaping unit, while real estate activities reflect opportunistic land disposals rather than an active development division. Legacy surplus parcels attached to plantation holdings are sold periodically when buyers emerge, as demonstrated by the Kanyakumari transaction in January 2025 and the Dunsandle sale in FY26.2425 Market commentary occasionally characterizes these holdings as a strategic land bank awaiting commercial development. However, disclosures indicate a more fragmented collection of legacy assets with varying legal title clarity — some of which yield cash sales, while others, such as the Singampatti estate, lead to legal surrenders and contested financial claims.
The disconnect, stated plainly. Consolidated profit after tax of ₹2,499 crore for FY26 appears to reflect the earnings power of a diversified conglomerate.6 However, that headline figure includes the minority interest share of Britannia's earnings owned by external public shareholders (49.45%). The net profit attributable to Bombay Burmah's equity holders represents approximately half that amount. This accounting distinction explains why, against a market capitalisation of roughly ₹10,486 crore, the company trades at an effective price-to-earnings multiple near 8.5 rather than the unadjusted headline ratio of 4.3 Similarly, in the June 2026 quarter, consolidated profit after tax reached ₹582.67 crore, but profit attributable to Bombay Burmah's owners totaled approximately ₹290 crore, compared with ₹240 crore in the prior-year period.2226
Evaluating these disclosures confirms the underlying economic reality: attributable corporate earnings consist almost entirely of Bombay Burmah's 50.55% share of Britannia's profits, modified only slightly by standalone operational results. The tea estates, auto components, dental division, and nurseries function collectively as minor accessories attached to a major consumer goods stake.
That structural arrangement might offer straightforward holding-company exposure if the entity simply gathered subsidiary dividends and distributed them to shareholders. However, capital allocation decisions over the past two decades followed a far more complex trajectory.
VI. Capital Allocation Catastrophe: The Go First Aviation Drag
A long-term investor in Bombay Burmah must confront a central thesis: that the company functions as a patient, stable steward of capital — a 160-year-old institution designed to preserve and compound wealth. The primary test of that claim lies not in its operational moats, but in its capital allocation choices, demonstrated by the fate of the largest discretionary investment management ever executed.
The Wadia group launched the airline in 2005 as GoAir under Jehangir Wadia, Nusli Wadia's younger son. The strategic logic at the time appeared defensible in the abstract: Indian civil aviation was deregulating, passenger incomes were expanding, and IndiGo had not yet established market dominance. A disciplined low-cost carrier operating a unified fleet type on a patient balance sheet could plausibly capture sustainable market share.
That strategy failed to materialise. Over the following eighteen years, IndiGo built dominant scale, superior on-time performance, and tight cost control, while GoAir remained trapped in a middle tier — large enough to incur substantial losses, but never reaching the scale economics essential for low-cost aviation. The airline rebranded as Go First in 2021 ahead of a proposed initial public offering that was ultimately abandoned. Jehangir Wadia stepped down as managing director in March 2021, and family succession around the airline became a subject of public reporting ahead of the failed listing.27
Despite mounting losses, group entities continued capital injections. Bombay Burmah held an approximate 33% stake in Go Airlines (India) Limited, with unlisted Wadia group holding companies holding the remainder.10 Capital flowed through equity infusions, corporate advances, and financial guarantees. In behavioral finance, this sequence illustrates an escalation of commitment, where subsequent capital deployments are justified by past sunk costs, deferring a decision to stop because halting crystallises the loss.
The funding ended in May 2023 when Go First filed for voluntary insolvency under the Insolvency and Bankruptcy Code, citing persistent Pratt & Whitney engine failures that had grounded much of its operational fleet. Bombay Burmah recorded provisions of ₹1,865.66 crore against its total GoAir exposure in FY23, writing off the investment entirely.10 For an entity whose standalone operating units generate only tens of crores in annual profit, a loss of this magnitude could not be offset by tea, solenoids, or dental consumables. Consequently, Bombay Burmah's consolidated accounts registered a net loss of roughly ₹534 crore in FY23 before recovering to a profit of ₹1,689 crore in FY24.3
The corporate insolvency resolution process failed to produce a viable buyer. Restructuring proposals from EaseMyTrip and SpiceJet-linked entities were deemed inadequate, leading the committee of creditors to vote unanimously for liquidation by August 2024.28 On January 20, 2025, the National Company Law Tribunal ordered liquidation, concluding a twenty-month insolvency process and appointing Dinkar T. Venkatasubramanian as liquidator.29 At liquidation, the airline owed financial lenders approximately ₹6,200 crore — including admitted claims of ₹1,934 crore to Central Bank of India and ₹1,744 crore to Bank of Baroda — with total obligations estimated at roughly ₹110 billion.2930 Listed among unsecured creditors were group entity Leila Lands Limited at ₹1,330 crore and Bombay Burmah itself at ₹90.88 crore, leaving the holding company ranking behind secured banking institutions for recovery of loans extended to its own subsidiary.29
Weighing the evidence. Evaluating how severely this episode undermines the management stewardship thesis requires weighing opposing arguments.
Several factors argue for a significant valuation discount: - Management continuity: The capital deployment occurred under the current executive management regime. - Duration: Sustained funding over eighteen years reflects a structural capital allocation strategy rather than an isolated operational misstep. - Scale of loss: A ₹1,866 crore provision exceeded more than a decade of cumulative standalone operating profits. - Entity exposure: The venture was financed in part through a publicly listed company whose minority investors sought exposure to consumer goods and agricultural assets.
Conversely, counter-arguments suggest bounded forward risk: - Full provisioning: The financial exposure has been fully written off on the balance sheet. - Process status: The airline is in formal liquidation rather than undergoing open-ended operational restructuring. - Promoter commitments: Management has not requested public shareholders to fund additional aviation ventures, and Bombay Burmah confirmed zero encumbrance on promoter shareholding in FY26.31
This evidence contradicts the premise that group capital has been deployed with consistent discipline. What remains defensible is a narrower observation: since 2023, Bombay Burmah has ceased funding its main loss-making entity and initiated non-core asset sales. However, this shift represents a three-year operational track record rather than a multi-decade corporate pattern, requiring further observation to confirm long-term durability.
Residual financial liabilities also remain unresolved. Lenders to Go First have sought recovery through collateral pledged by the promoter group, including real estate assets in Thane valued between ₹1,600 crore and ₹1,900 crore — representing an estimated 25% to 30% recovery rate against admitted bank exposure; as of early 2025, lenders anticipated realisations during the first half of FY26 while asset monetisation due diligence continued.3233 A formal liquidation order does not instantly conclude corporate liability. Guarantee obligations and inter-creditor litigation can persist for years, and existing disclosures regarding group-level contingent liabilities remain insufficient for public shareholders to quantify potential residual risks.
This episode underscores broader governance implications for minority shareholders in holding companies. In 2018, a public investor reviewing Bombay Burmah's disclosures could verify an equity interest in an aviation venture, but could not determine the cumulative scale of capital, advances, and financial guarantees extended across group entities, nor the criteria governing further capital support. This structural opacity meant that inter-corporate exposure became fully visible to public markets only when recorded as a write-off rather than an active allocation choice. Consequently, inter-corporate loans and financial guarantees represent primary risk factors requiring rigorous evaluation in promoter-controlled investment entities.
The opportunity cost of this capital deployment remains substantial. The total funds written off represented a meaningful fraction of Bombay Burmah's market capitalisation, allocated into an industry with a historical record of capital destruction across economic cycles. Alternative capital uses — such as share repurchases while trading at a discount to underlying net asset value, debt reduction, or direct dividend distributions from Britannia cash flows — were available and execution-ready. While the initial investment in 2005 reflected a plausible market entry, sustaining capital support for eighteen years presents a clear friction with minority shareholder value creation.
This track record leads directly to the core governance question: what visibility public minority shareholders retain, and what mechanisms exist to influence capital allocation moving forward.
VII. Corporate Governance, Promoters, & The Legal Battleground
On December 18, 2024, promoters and affiliated entities remitted ₹2.13 crore to the Securities and Exchange Board of India to settle regulatory proceedings. The settlement comprised ₹1.46 crore from the promoters and affiliated entities, ₹34.70 lakh from Wallace Brothers Trading & Industrial, and ₹31 lakh from Bombay Burmah Trading Corporation.34 A SEBI panel of whole-time members had approved the settlement on November 8, 2024. The underlying allegations concerned lapses in disclosures relating to shareholding changes and related-party transactions — specifically that an 8.11% stake held through Wallace Brothers, acquired indirectly by Wadia interests in December 2014, had been classified as public shareholding rather than part of the promoter group.34 The parties settled without admitting or denying the findings, with the regulator retaining the right to act if further violations emerged.34
While the monetary penalty was modest, its informational weight was substantial. Misclassifying promoter equity directly impacts the primary disclosure that informs minority investors of the controlling family's true equity ownership. As of June 2026, promoters held 74.04% of Bombay Burmah, while foreign institutions held 9.46%, domestic institutions 1.04%, and public shareholders 15.46%, distributed across roughly 48,630 shareholders.3
That concentration carries decisive mechanical implications. At 74%, the promoter group can pass any ordinary or special resolution without requiring a single vote from public shareholders. Consequently, minority investors lack a realistic mechanism to compel a demerger, alter dividend policy, or enforce board changes. In Bombay Burmah's corporate structure, minority shareholders can register disapproval, but cannot dictate outcomes.
The people. Leadership remains concentrated within the promoter family. Nusli Wadia, 82, serves as chairman.13 His son Ness Wadia serves as managing director; shareholders approved his reappointment for a five-year term from April 1, 2026 to March 31, 2031, with the special resolution carrying roughly 96% of votes cast. The approved package includes a basic salary of up to ₹46.5 lakh per month within an overall annual limit of ₹8.37 crore, compared to total FY25 compensation of about ₹7.7 crore.3536 The FY26 annual report also recorded the appointment of Rukhshana Jina Mistry as an independent director as of August 26, 2025, alongside the reappointment of Dr. Minnie Bodhanwala as a non-executive director, bringing female representation on the board to 25%.5
Evaluating this executive remuneration against the underlying business model highlights a structural contradiction. Managing director compensation of roughly ₹7.7 crore represents a negligible fraction of the company's ₹1,200-odd crore in attributable consolidated profit. However, it stands out as a substantial sum against the standalone operating business, which operated at a net loss before non-recurring asset-sale gains in the June 2026 quarter.22 Determining the appropriate benchmark is debatable: managing a holding company that oversees a ₹64,000 crore investment involves a different scope than running an operating business. Nevertheless, executive compensation remains tied to the scale of inherited holdings rather than operational value creation.
What institutions are actually saying. The most compelling governance signal emerges not from regulatory orders, but from voting records at the operating company level.
When Britannia submitted Rakshit Hargave's appointment as managing director and chief executive to a postal ballot, the resolution passed with 79.58% approval on an 80.21% turnout. However, the voting breakdown highlighted a sharp institutional divide: while the promoter group voted 100% in favor and public non-institutional shareholders voted 98.26% in favor, public institutional investors voted 55.33% against.11 A majority of voting institutional capital opposed the chief executive appointment for India's premier biscuit company, with results declared on March 15, 2026 following an e-voting period from February 13 to March 14.11
Similarly, at Britannia's 107th annual general meeting on August 7, 2026, the reappointment of Ness Wadia as a non-executive non-independent director passed with 89.59% total support, yet public institutions cast 27.59% of their votes against him — even as those same institutions supported the financial statements and dividend payouts with virtually no dissent.37 Institutional shareholders were not expressing broad dissatisfaction with Britannia's financial performance, but registering specific opposition to promoter-linked board and management appointments.
This voting behavior represents the closest equivalent to an activist signal available in family-controlled Indian corporate structures. While such dissent cannot alter ballot outcomes against a majority promoter block, it demonstrates that institutional investors who scrutinize the enterprise maintain specific concerns regarding executive appointments and governance oversight.
The litigation overhang. The legal proceedings surrounding the Singampatti tea estate require precise evaluation. The estate sits in the Manjolai hills of Tirunelveli district within the Kalakkad-Mundanthurai Tiger Reserve, where Bombay Burmah held approximately 8,373.57 acres under a 99-year lease granted in 1929 by the Singampatti zamindar.2 Following the application of forest protection laws over the Agasthyamalai landscape, the Supreme Court directed the Central Empowered Committee to investigate encroachment and statutory compliance.38
The physical exit is now complete. Bombay Burmah handed over more than 8,152 acres to the Tamil Nadu State Forest Department in May 2025, and transferred the remaining 221.44 acres on July 11, 2026, following factory demolition and machinery removal.39 The CEC's report to the Court recorded an internal computation indicating that ₹4,655.24 crore in lease rentals remained recoverable by the state government, a figure reproduced in the Court's May 29, 2026 order.24 Bombay Burmah filed an interlocutory application to recall and expunge the observation, arguing that no formal notice had been issued and no determination made after hearing its defense; the Court allowed the application on August 19, 2026.14
The legal implication of this ruling is specific and narrow. The recall removed a judicial observation, but did not resolve whether lease rent is legally owed nor adjudicate any final amount. Bombay Burmah has surrendered the land and relinquished the estate without securing a formal determination that no liabilities remain payable. Investors must treat this as an unquantified contingent risk rather than a closed matter, noting that the stock's 13% relief rally priced the development as significantly more conclusive than the judicial order specifies.1
Accounting judgments worth flagging. Three critical areas of Bombay Burmah's financial statements depend on estimation rather than direct measurement. First is the carrying value and impairment history of investments in group ventures, underscored by the ₹1,865.66 crore GoAir provision in FY23, where the timing of loss recognition represented a judgment call made under external pressure.10 Second is the contingent liability disclosure surrounding Singampatti, which remains uncertain because state authorities have not issued a formal notice or adjudicated an amount; the recall of the Supreme Court's observation removed a judicial statement but not the underlying financial risk.14 Third is the accounting treatment of asset-sale gains: the ₹87.70 crore exceptional gain on the Dunsandle estate in the March 2026 quarter and the ₹14.87 crore gain in the June 2026 quarter represent cash-backed items, but are non-recurring by construction.622 Any analysis assessing standalone operational health without stripping out these property sales will overstate core business performance.
Finally, portfolio complexity adds to holding company risk. Bombay Burmah's controlling interest in Britannia is held through offshore step-down subsidiaries, while sister entity Bombay Dyeing has faced financial pressure: FY26 revenue declined to ₹1,460.33 crore from ₹1,605.43 crore, and profit after tax fell to ₹26.66 crore from ₹489.83 crore, the prior-year result having been elevated by exceptional gains from selling a 22-acre Worli land parcel to Japan's Sumitomo for about ₹5,200 crore.1440 Additionally, Bombay Dyeing's real estate segment posted a loss of ₹7.09 crore in FY26.14 A cautious investor evaluating Bombay Burmah must consider not only what the holding entity owns, but also whether other group entities could require capital support — and whether the vehicle holding the Britannia stake might be called upon to provide it.
VIII. Strategic Spine: Moat Analysis (7 Powers & 5 Forces) & The Holdco Discount
Evaluating a holding company requires a dual framework: examining the operating enterprise it controls alongside the corporate vehicle that holds it. These two perspectives yield contrasting conclusions, and the divergence between them measures the holding company discount.
Britannia through Hamilton Helmer's 7 Powers. Three of the seven powers are clearly evident. Branding represents the primary asset: Good Day and Marie Gold command deep consumer loyalty, evidenced by retailers stocking them without demanding concessionary terms because the inventory carries minimal turnover risk. Scale economies manifest through a nationwide manufacturing and logistics network sized for a market leader, distributing fixed costs across massive volumes in a market where freight constitutes a substantial portion of delivered unit cost, alongside national advertising expenditure that yields low costs per unit. Cornered resource applies to distribution infrastructure: multi-decade distributor relationships across roughly 2.79 million directly served outlets and about 30,000 rural distributors cannot be replicated swiftly by capital alone.18
Two powers are only partially present. Process power appears in input hedging — with management describing commodity procurement below prevailing market prices — and manufacturing cost controls, though neither constitutes a proprietary advantage.19 Switching costs are virtually absent for packaged biscuits, meaning the competitive moat protects retail distribution channels rather than individual consumer decisions. The remaining two powers are absent: there is no counter-positioning against Parle or ITC, which operate under comparable business models, and no network economies exist in mass food manufacturing.
Bombay Burmah standalone through the same lens. Standalone operations possess virtually no structural moat. Tea remains a price-taking soft commodity where FY26 disclosures recorded production volume declining faster than average selling prices rose.5 Auto-electrical components offer modest platform design-in stickiness but face concentrated original equipment manufacturer buying power and an ongoing powertrain electrification shift that reduces content per vehicle. Dental consumables constitute a defensible niche, yet remain financially immaterial to overall enterprise performance. None of these standalone operating segments commands branding power, scale economies, or a cornered resource.
Porter's five forces, applied honestly. For Britannia, buyer power is moderate and expanding as modern trade and quick-commerce platforms consolidate consumer purchasing that was historically dispersed across millions of traditional grocers. Supplier power remains significant for key agricultural inputs — wheat, sugar, and particularly palm oil are globally traded commodities beyond corporate control, as demonstrated by a palm oil price surge of roughly 20% during the June 2026 quarter.19 Threat of new entrants remains low in mass-market biscuits but higher in premium adjacencies such as cakes, wafers, and croissants, which have attracted well-funded competitors; Britannia's own adjacency portfolio grew over 30%, signaling both category opportunity and incoming competition.20 Substitution poses an underappreciated risk, as biscuits compete against namkeen, chocolates, and alternative impulse snacks with zero consumer switching friction. Industry rivalry remains intense but stable, structured around three primary players.
For Bombay Burmah as a holding vehicle, the five forces framework offers limited applicability because investment entities have neither traditional operational customers nor commercial suppliers. Its intrinsic equity value depends entirely on the cash flows generated by underlying assets and the capital allocation choices made by controlling promoters.
Anatomy of the discount. As of late August 2026, Britannia's market capitalisation stood at roughly ₹1.26 lakh crore (₹1,26,456 crore).7 The 50.55% controlling stake was therefore valued at approximately ₹63,900 crore at market prices. By contrast, Bombay Burmah's market capitalisation sat at about ₹10,486 crore, against consolidated debt of ₹1,590 crore and reserves of ₹7,028 crore as of March 2026.37 Even before assigning value to tea estates, component manufacturing, surplus land, or equity holdings in Bombay Dyeing, the public equity market valued the parent wrapper at approximately one-sixth the market value of its primary asset.
Historically, Indian holding company discounts have clustered in the 40% to 60% range, yet Bombay Burmah's discount has expanded as wide as 82%.9 This persistent divergence indicates that the valuation gap reflects specific corporate attributes rather than generic holding company dynamics.
Three primary structural mechanisms explain this valuation gap:
Capital allocation risk. This factor represents the largest discount driver. The ₹1,866 crore Go First write-off demonstrated that cash generated within the corporate structure could be deployed into high-risk, non-core ventures, dwarfing the earnings of standalone operations.10 When public markets observe capital deployed outside core operating strengths, valuation models discount cash flows over which minority shareholders exercise no control.
Tax and structural friction. The controlling Britannia equity is held through layered step-down subsidiaries, including offshore entities inherited from Associated Biscuits and Danone-era joint ventures.16 Direct asset monetisation would trigger substantial corporate-level capital gains tax, while distributing proceeds to Bombay Burmah equity holders would invite secondary dividend tax leakage. Consequently, net capital recoverable by public shareholders in a liquidation scenario is materially less than gross asset value — an eventuality neither controlling promoters nor corporate tax structures are incentivized to trigger.
Absence of a catalyst. With promoter shareholding at 74.04%, external investors cannot build a blocking stake, succeed in proxy contests, or mount hostile acquisitions.3 Institutional shareholders can register formal opposition to executive appointments — as occurred during Britannia votes in March and August 2026 — yet management resolutions pass comfortably.1137 A valuation discount that cannot be arbitraged through market mechanisms functions as a permanent structural price adjustment rather than a temporary market inefficiency.
A fourth mechanism involves the operational complexity of the parent entity itself. Bombay Burmah is not a pure pass-through vehicle holding cash and a single equity line. It directly operates tea plantations exposed to weather and statutory labor costs, auto component units navigating automotive electrification, an unadjudicated lease-rent legal contingency in Tamil Nadu, and equity positions in group entities whose operational segments remain loss-making.514 Each element introduces analytical variance without offering upside proportionate to that uncertainty, resulting in a valuation penalty for operational complexity.
Narrowing this valuation gap requires specific corporate catalysts rather than operational earnings growth at Britannia, which elevates both holding value and parent market capitalization proportionally. Mechanisms that compress holding company discounts globally include committing received dividends through formal distribution policies, executing share repurchases to reduce equity count against underlying holdings, implementing demergers that grant direct equity access to underlying assets, or executing control changes. Three of these avenues require promoter initiation, while the fourth is precluded by a 74.04% promoter block.3 Investing in the holding company discount represents an unhedged exposure to future promoter capital allocation decisions.
The valuation discount reflects both rational structural friction and punitive market pricing. Rational discount components stem from permanent tax friction and governance constraints. The punitive component reflects market expectations of unconstrained capital deployment. If post-2023 corporate behavior — including non-core asset sales, debt reduction, and the FY26 interim dividend of ₹17 per share on ₹2 face value — proves consistent over extended periods, the punitive discount may contract.65 However, the underlying structural discount will persist as long as the multi-layered holding architecture remains in place.
IX. Playbook: Lessons from a 160-Year-Old Enterprise
1. Corporate longevity is a survival record, not a compounding record. Bombay Burmah has existed continuously since 1863, surviving the loss of its Burmese timber empire, the departure of British capital, three changes of controlling family, and the near-total replacement of its operating businesses.12 While that endurance is notable, investors must be precise about what longevity proves. It demonstrates that the corporate shell adapts, not that a rupee invested in the entity compounds. The shell's owners have repeatedly used it to hold assets rather than to build them — and used it to fund an aviation venture that destroyed nearly ₹1,900 crore.10 Corporate age is evidence of resilience, not capital discipline.
2. When the investment outgrows the enterprise, management must define its model. In FY26, Britannia contributed segment revenue of ₹19,162.78 crore compared with ₹1,320.46 crore from the investments segment and a modest standalone operation.6 At that ratio, Bombay Burmah functions primarily as an investment vault carrying minor legacy operations. A company in this position has two coherent paths available: become a disciplined holding vehicle that distributes subsidiary dividends directly to shareholders, or operate as an industrial conglomerate that reinvests capital into scalable businesses. Bombay Burmah has maintained an ambiguous stance for three decades. The persistent valuation discount represents the market's ongoing price penalty for that structural ambiguity.
3. Recognise impairment before external events force the disclosure. The Go First provision of ₹1,865.66 crore was recorded in FY23, eighteen years after the airline launched and only after an insolvency filing made further deferral impossible.10 Capital was destroyed gradually over nearly two decades, even though accounting statements recognized the loss all at once. For analysts evaluating promoter-controlled groups, tracking real-time cash flows toward troubled affiliates provides a clearer risk picture than relying on official impairment dates, which mark when management admits a loss rather than when economic damage occurs.
4. Legacy land is not automatically a valuable asset. Bombay Burmah's 2026 disclosures provided a clear case study that challenges typical land-bank investment assumptions. The company held 8,373.57 acres at Singampatti under a lease dating back to 1929. Rather than generating a monetisation event, the holding resulted in a physical surrender to the Tamil Nadu State Forest Department, completed on July 11, 2026, followed by a Central Empowered Committee report computing ₹4,655.24 crore in unrecovered lease rent.239 By contrast, the sale of the Dunsandle estate for ₹120 crore to unrelated buyers generated actual cash backed by clean freehold title.255 The defining factor is title clarity rather than raw acreage. Any land-bank thesis that fails to distinguish unencumbered freehold property from ecologically protected state leases risks mistaking contingent liabilities for assets.
5. Divest decaying assets before margin compression deepens. The Tanzanian tea estates and the Dunsandle estate were sold only after years of constrained economics.2325 Bombay Burmah's FY26 tea disclosures illustrate the risk of delayed exit: a 16% year-on-year drop in output offset a 7% average price gain, reflecting a business in structural decline masked temporarily by favorable commodity pricing.5 Operational signals to divest emerge well before accounting losses force a sale.
6. A listed legacy shell provides strategic flexibility — and minority governance risk. The Wadia group positioned its primary holdings above a listed nineteenth-century plantation company rather than creating a new holding entity. An established listing avoids promoter lock-in constraints, attracts minimal analytical scrutiny while operating legacy agricultural lines, and maintains public market access without the setup requirements of a purpose-built investment vehicle. While efficient for controlling shareholders, public investors who bought into a plantation enterprise find their capital tied to group-level capital allocation decisions. Evaluating long-standing listed entities requires verifying the shell's current function rather than relying on historical corporate titles.
7. Evaluate holding-company accounts on a look-through basis. Consolidated profit figures for holding entities that control but do not wholly own primary assets are frequently misinterpreted. Standard consolidated reporting includes 100% of subsidiary revenue and profit, whereas parent shareholders are entitled only to their proportionate economic interest, with external ownership deducted as minority interest. For Bombay Burmah, headline consolidated figures exceed attributable profit by roughly a factor of two.626 A reliable valuation approach requires determining the holding entity's net economic claim on underlying earnings, deducting parent net debt and operating overhead, and treating residual disclosures with caution until verified.
Together, these playbook lessons point to a clear conclusion: much of the progress at Bombay Burmah over the past three years reflects the unwinding of capital allocation choices from the prior two decades. Resolving legacy issues marks necessary operational progress, but does not yet constitute a forward-looking growth strategy.
X. Bull vs. Bear Case & Forward-Looking KPIs
The bull case, stated at its strongest. Buying Bombay Burmah offers indirect ownership of Britannia Industries at a substantial discount. The core valuation gap is straightforward: Bombay Burmah holds a controlling stake in Britannia worth roughly ₹63,900 crore at market prices, while its own total equity market capitalisation sits near ₹10,486 crore, backed by ₹7,028 crore in reserves and ₹1,590 crore in debt.37 For investors viewing Britannia as a durable compounder — supported by a return on capital employed of 56%, 9% volume growth in the June 2026 quarter, and an 86% dividend payout ratio — acquiring this asset through an approximate 80% holding company discount offers a structurally lower entry cost. Under this premise, the holding company discount does not need to narrow for shareholders to participate in Britannia's underlying earnings growth.720
The second bull case argument centers on capital discipline: the primary cash drain has ceased. Go First entered formal liquidation with its financial exposure fully written off, and the promoter group has sought no further capital for aviation operations.1029 Meanwhile, management has monetised non-core assets, reduced outstanding term loans, and distributed an interim dividend of ₹17 per share on a ₹2 face value in FY26 — representing an 850% payout on face value, though it opted against declaring a final dividend.65
The third argument relies on structural optionality: potential value realisations from unencumbered surplus land parcels, corporate simplification under future executive leadership, and market pressure generated by an expanding valuation gap between the parent holding company and its underlying consumer franchise.
The bear case, stated at its strongest. The valuation discount reflects structural friction rather than a transient arbitrage opportunity. With promoters controlling 74.04% of equity, minority shareholders lack the voting power to force corporate restructurings, dividend policy changes, or board realignments.3 Institutional voting patterns illustrate these governance limits: public institutions cast 55.33% of their votes against Britannia's chief executive appointment and 27.59% against Ness Wadia's non-executive board reappointment, yet both management resolutions passed.1137 The holding company discount has persisted throughout the post-2009 period despite Britannia's valuation expanding significantly, because no external market mechanism exists to force structural change.
The second pillar emphasizes that standalone operations remain a persistent low-return drag on capital. Tea production volumes fell 16% in FY26, the Electromags component division carries undisclosed exposure to internal combustion engine platforms, and the healthcare unit remains financially immaterial to overall enterprise results.5 Excluding exceptional asset-sale gains, standalone operations generated a net loss in the June 2026 quarter.22
The third bear case pillar rests on capital allocation and governance track records. Group management funded an aviation venture into liquidation over an eighteen-year period, settled regulatory proceedings with SEBI in December 2024 regarding promoter-classification disclosure lapses, and oversees sister entity Bombay Dyeing, where FY26 profit dropped to ₹26.66 crore from ₹489.83 crore while its real estate division operated at a loss.341014 Consequently, the core investment question is not the quality of Britannia's consumer franchise, but whether cash flows generated by that franchise remain protected within the investment structure.
The activist stress test. Institutional analysts assessing structural risks evaluate four primary friction points. First is disclosure depth: management provides no breakdown of non-ICE revenue for Electromags and publishes no formal public reconciliation tracking Britannia dividends received against Bombay Burmah dividends distributed to shareholders.5 Second is ownership architecture: the controlling interest in Britannia is held through a multi-tiered offshore step-down structure created during legacy joint-venture restructurings, introducing tax and regulatory opacity for public equity holders.16 Third is inter-corporate exposure: affiliate entities have historically required capital support, while disclosures regarding group-level financial guarantees remain limited. Fourth is executive accountability: reappointing executive leadership for a five-year term at compensation up to ₹8.37 crore annually — three years following a ₹1,866 crore impairment on a group aviation venture — represents an allocation decision that has not been publicly reconciled against standalone operational performance.1036
A thorough due diligence process highlights three secondary operational factors: the Singampatti lease-rent claim remains unadjudicated despite the Supreme Court's August 2026 recall of its judicial observation, consolidated debt of ₹1,590 crore as of March 2026 sits above a parent company with minimal standalone operating cash flow, and a significant portion of standalone earnings in FY26 and the June 2026 quarter derived from non-recurring asset sales rather than ongoing operations.3622
Why this wins from here, and what breaks it. The thesis for holding company value appreciation rests on specific execution criteria: Britannia maintaining mid-to-high single-digit volume expansion under new executive leadership, combined with a sustained post-2023 pattern of non-core asset sales, debt reduction, and regular dividend distributions. Conversely, the thesis breaks under three conditions: operational deterioration at Britannia following executive transition, fresh capital deployment into non-core group affiliates, or an unadjudicated Singampatti financial settlement that proves material relative to Bombay Burmah's ₹10,500 crore market capitalisation.
The risk radar, restricted to what is mechanically relevant. Key operating and structural risks focus on specific transmission channels:
- Input-cost inflation: Fluctuations in palm oil, wheat, sugar, and ocean freight impact Britannia's gross margins, with disclosures from the June 2026 quarter demonstrating that management absorbed roughly half of cost inflation internally.19
- Geopolitical supply disruption: Trade conflicts in West Asia increased freight rates and disrupted international shipments, prompting management to relocate North American product manufacturing from Oman to Mundra.2019
- Channel shift and digital disruption: Emerging retail channels — specifically quick-commerce platforms and platform private labels — alter traditional distribution advantages in urban markets.
- Regulatory and legal exposure: Legal risk centers on the unadjudicated Singampatti lease-rent claim and broader statutory compliance across legacy plantation estates.238
- Refinancing risk: Debt obligations remain manageable, with consolidated debt of ₹1,590 crore supported by reserves of ₹7,028 crore as of March 2026.3
Enterprise performance remains governed primarily by consumer biscuit volumes, judicial decisions on legacy land leases, and group capital allocation decisions.
The KPIs that actually matter. Three core metrics determine future trajectory:
First, Britannia's volume growth and market share. Operating performance depends on underlying unit volume growth rather than pricing adjustments. Britannia reported approximately 9% volume expansion in the June 2026 quarter alongside market share gains; monitoring requires verifying whether this trajectory continues over a multi-quarter period under new management.2019
Second, dividend cash pass-through. Evaluating governance requires comparing dividends received by Bombay Burmah from Britannia against cash deployed for debt reduction and parent shareholder dividends, versus capital retained or redirected. Britannia's 86% dividend payout ratio ensures steady cash inflow to holding entities.7 The allocation of those inflows represents the primary signal of promoter governance.
Third, standalone net debt and inter-corporate capital flows. Term loan prepayments of ₹73.44 crore in FY26 signal operational debt reduction.5 Conversely, any future financial disclosures revealing new capital advances, equity investments, or corporate guarantees extended to non-Britannia group entities would contradict the assumption of sustained capital discipline.
XI. Epilogue: The Longevity & Liquidation Paradox
In 1863, when the Bombay Burmah Trading Corporation was incorporated to acquire William Wallace's Burmese teak rights, the dominant technologies of the age were the steamship and the telegraph, the American Civil War was in its third year, and the idea that a public company might one day trade for less than the value of its equity holdings in another listed enterprise would have struck its founders as arithmetic nonsense.12
One hundred and sixty-three years later, that valuation disconnect defines Bombay Burmah. The company convened its 161st annual general meeting on August 13, 2026.5 Consolidated accounts remain dominated by a biscuit manufacturer; the most consequential internal corporate development of the preceding five years was the liquidation of an airline; the primary legal challenge of the past year concerned a 1929 princely lease over land that evolved into a tiger reserve; and public shares continue to trade at a deep discount to the market value of the single operating asset that underpins the entity.
This structure presents a fundamental corporate paradox. The institutional attributes that enabled the enterprise to survive across generations — multi-decade investment horizons, capital preservation habits, indifference to quarterly market sentiment, and stable family control — are the exact characteristics that generate the holding company discount.
An enterprise structured to hold assets indefinitely can also sustain a loss-making airline across eighteen years. A controlling promoter block that cannot be unseated cannot be compelled to distribute subsidiary capital. In this corporate framework, structural durability and executive accountability operate in direct tension.
The three years leading into 2026 reflect a distinct operational posture. Go First exposure has been fully written off as the entity entered liquidation; tea estates in Tanzania, the Dunsandle estate, and secondary land parcels were monetised; term loans were prepaid; an interim dividend was distributed; and a century-old lease that became an environmental and legal liability was surrendered alongside the recall of the related judicial observation. Viewed individually, these steps represent incremental adjustments. Taken together, they indicate an enterprise focused on balance sheet cleanup rather than speculative expansion — an appropriate operational posture for a holding company whose primary historical missteps stemmed from unconstrained capital allocation.
Evaluating whether this turnaround persists requires tracking clear empirical signals. If Britannia dividends flow directly toward parent debt reduction and shareholder distributions; if remaining agricultural and manufacturing units are systematically scaled or divested; if Singampatti liabilities are settled within manageable financial limits; and if capital remains protected from unrelated group ventures — then the holding company trap thesis will prove overly pessimistic, and the valuation gap will have represented an entry opportunity rather than a permanent discount. Each criterion can be verified directly from regulatory filings without relying on executive commentary.
What distinguishes Bombay Burmah's position is that opposing investment arguments draw from the same management record within the same decade. The eighteen-year aviation commitment and the post-2023 restructuring are not isolated events from separate eras; they overlap. The Go First impairment landed in FY23, and asset sales, debt prepayment, and estate surrenders followed within three years. Empirical evidence supports two distinct interpretations: either management learned an expensive lesson in capital discipline, or the group exhausted available capital deployment avenues. Disclosed records as of September 2026 cannot definitively confirm which interpretation will prevail.
Whether this transition marks a permanent strategic shift or a temporary operational pause remains an open question that historical financial data alone cannot resolve. The outcome will depend on how management deploys subsequent Britannia dividend inflows. If that cash is directed toward balance sheet strengthening and shareholder payouts, public markets will eventually re-rate the stock and contract the punitive component of the discount. If capital is redirected into new group ventures, the valuation penalty will prove justified, and recent restructuring will register as an intermission.
A key counterfactual clarifies the boundary between structural friction and managerial choice. Consider a hypothetical scenario where Bombay Burmah acquired the identical Britannia stake through the same offshore subsidiary chain during the same period, but pursued no secondary ventures — avoiding aviation funding, thirty years of sub-scale manufacturing operations, and legacy land disputes. That entity would still trade at a discount because tax leakage on structural unwinding and the absence of shareholder activist mechanisms are inherent to the holding structure. However, the discount would likely have tracked the historical Indian holding company average of 40% to 60% rather than expanding near 80%.9 The gap between those two valuation discount levels represents the penalty earned through capital allocation choices, marking the specific portion of value that management can plausibly recover.
The history of the Bombay Burmah Trading Corporation ultimately illustrates the fundamental purpose of listed corporate entities. Navigating 163 years through colonial empire, global conflicts, independence, and airline liquidation demonstrates exceptional institutional survival. Yet institutional survival and capital stewardship represent separate achievements, and public shareholders invest in the latter. The Burmese timber operations, sawmills, and airline have vanished; the consumer biscuit franchise remains; and the core question of how underlying asset value will ultimately accrue to minority equity holders remains unresolved.
References
-
Bombay Burmah zooms 14% as SC recalls ₹4,655 cr lease liability observation — Business Standard, 2026-08-27 ↩↩↩↩↩
-
Bombay Burmah Trading surges after SC recalls Rs 4,655 crore lease rent observation — Business Standard Capital Market News, 2026-08-27 ↩↩↩↩↩
-
The Bombay Burmah Trading Corporation Ltd — Consolidated financials, shareholding and key ratios, Screener.in (accessed 2026-08-31) ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Bombay Burmah Trading Asks Supreme Court to Overturn ₹4,655 Crore Lease Rent Views on Singampatti Tea Estate — ScanX ↩↩↩↩
-
Bombay Burmah Trading Annual Report FY26 and Notice of 161st AGM on Aug 13, 2026 — ScanX ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
The Bombay Burmah Trading Corporation Limited Q4 & Annual FY 2025-26 Financial Results — InvestyWise ↩↩↩↩↩↩↩↩↩↩↩↩
-
Britannia Industries Ltd — Consolidated financials, shareholding and key ratios, Screener.in (accessed 2026-08-31) ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Britannia Industries FY26 Results: Revenue ₹19,151 Cr, PAT ₹2,533 Cr; ₹90.50 Dividend Declared — Whalesbook ↩↩↩↩↩
-
Bombay Burmah makes Rs 1,866 cr provisions for GoAir investment — Business Standard, 2023-05-28 ↩↩↩↩↩↩↩↩↩↩
-
Britannia Industries Announces Official Postal Ballot Results for CEO Appointment — ScanX, 2026-03-15 ↩↩↩↩↩↩
-
Company Profile — The Bombay Burmah Trading Corporation, Limited ↩↩↩↩
-
Bombay Dyeing FY26 profit drops sharply as revenue slips 9 per cent — Indiantelevision.com ↩↩↩↩↩
-
40 years ago... and now: Britannia has crowned many as 'biscuit king' — Business Standard, 2014-10-30 ↩
-
Tiger issue tamed, Wadias get Britannia from Danone — Business Standard, 2009-04-15 ↩↩↩↩↩
-
Britannia Targets 50% Rural Sales Share in 3–4 Years — FoodInfoTech ↩↩
-
Q1 2027 Britannia Industries Ltd Earnings Call Transcript — GuruFocus, 2026-08-07 ↩↩↩↩↩↩↩↩↩↩
-
Britannia Industries Q1 FY27 results: Net profit jumps 13%; revenue increases to ₹5,000 crore YoY — Upstox, 2026-08-06 ↩↩↩↩↩↩↩
-
Britannia MD and CEO Varun Berry resigns; Rakshit Hargave to take charge — Business Standard, 2025-11-10 ↩
-
Bombay Burmah Trading Corp: Q1 FY27 Results — Standalone PAT ₹7.86 Cr, Consolidated PAT ₹582.67 Cr — InvestyWise ↩↩↩↩↩↩
-
Tanzania Tea Estate — The Bombay Burmah Trading Corporation, Limited ↩↩
-
Bombay Burmah Trading sells land parcel in Tamil Nadu for Rs 13 cr — Business Standard, 2025-01-10 ↩↩
-
Bombay Burmah to Sell Nilgiris Dunsandle Tea Estate in Non-Core Asset Move — TipRanks ↩↩↩↩
-
The Bombay Burmah Reports Q1 Consolidated Net Profit Of ₹290 Crore Vs ₹240 Crore YoY — Sahi ↩↩
-
What's brewing at the Wadia Group ahead of GoAir's IPO? — The Week, 2021-09-14 ↩
-
Go First heads towards liquidation after failed EaseMyTrip, SpiceJet bids — Business Standard, 2024-07-17 ↩
-
NCLT allows liquidation of Go First Airways — SCC Times, 2025-01-21 ↩↩↩↩
-
Tribunal orders liquidation of India's Go First — ch-aviation ↩
-
Bombay Burmah Trading promoters confirm no share encumbrance in FY26 — ScanX ↩
-
Go First lenders likely to recover Rs 1,600-1,900 cr through Thane land — Business Standard, 2023-11-08 ↩
-
Lenders to Go Air expect recovery in H1FY26, collateral assessment underway — Business Standard, 2025-01-22 ↩
-
Wadia Family, Bombay Burmah Trading and 13 Others Pay Rs 2.13 Crore To Settle Disclosure Violation Case with SEBI — Moneylife ↩↩↩↩
-
Bombay Burmah Shareholders Back Five-Year Reappointment of MD Ness Wadia — TipRanks ↩
-
Bombay Burmah Trading Corporation seeks shareholder approval for Managing Director re-appointment — ScanX ↩↩
-
Britannia approves FY26 dividend, reappoints Ness N. Wadia amid institutional dissent — ScanX, 2026-08-07 ↩↩↩
-
SC Orders CEC to Investigate Encroachments and Forest Law Breaches in Agasthyamalai Ecosystem — Courtbook ↩↩
-
Bombay Burmah Moves Supreme Court To Remove Lease Rent Observations In Singampatti Tea Estate Case — StudyCafe ↩↩
-
Bombay Dyeing to sell 22-acre plot for Rs 5,200 cr to Japan's Sumitomo — Business Standard, 2023-09-13 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube