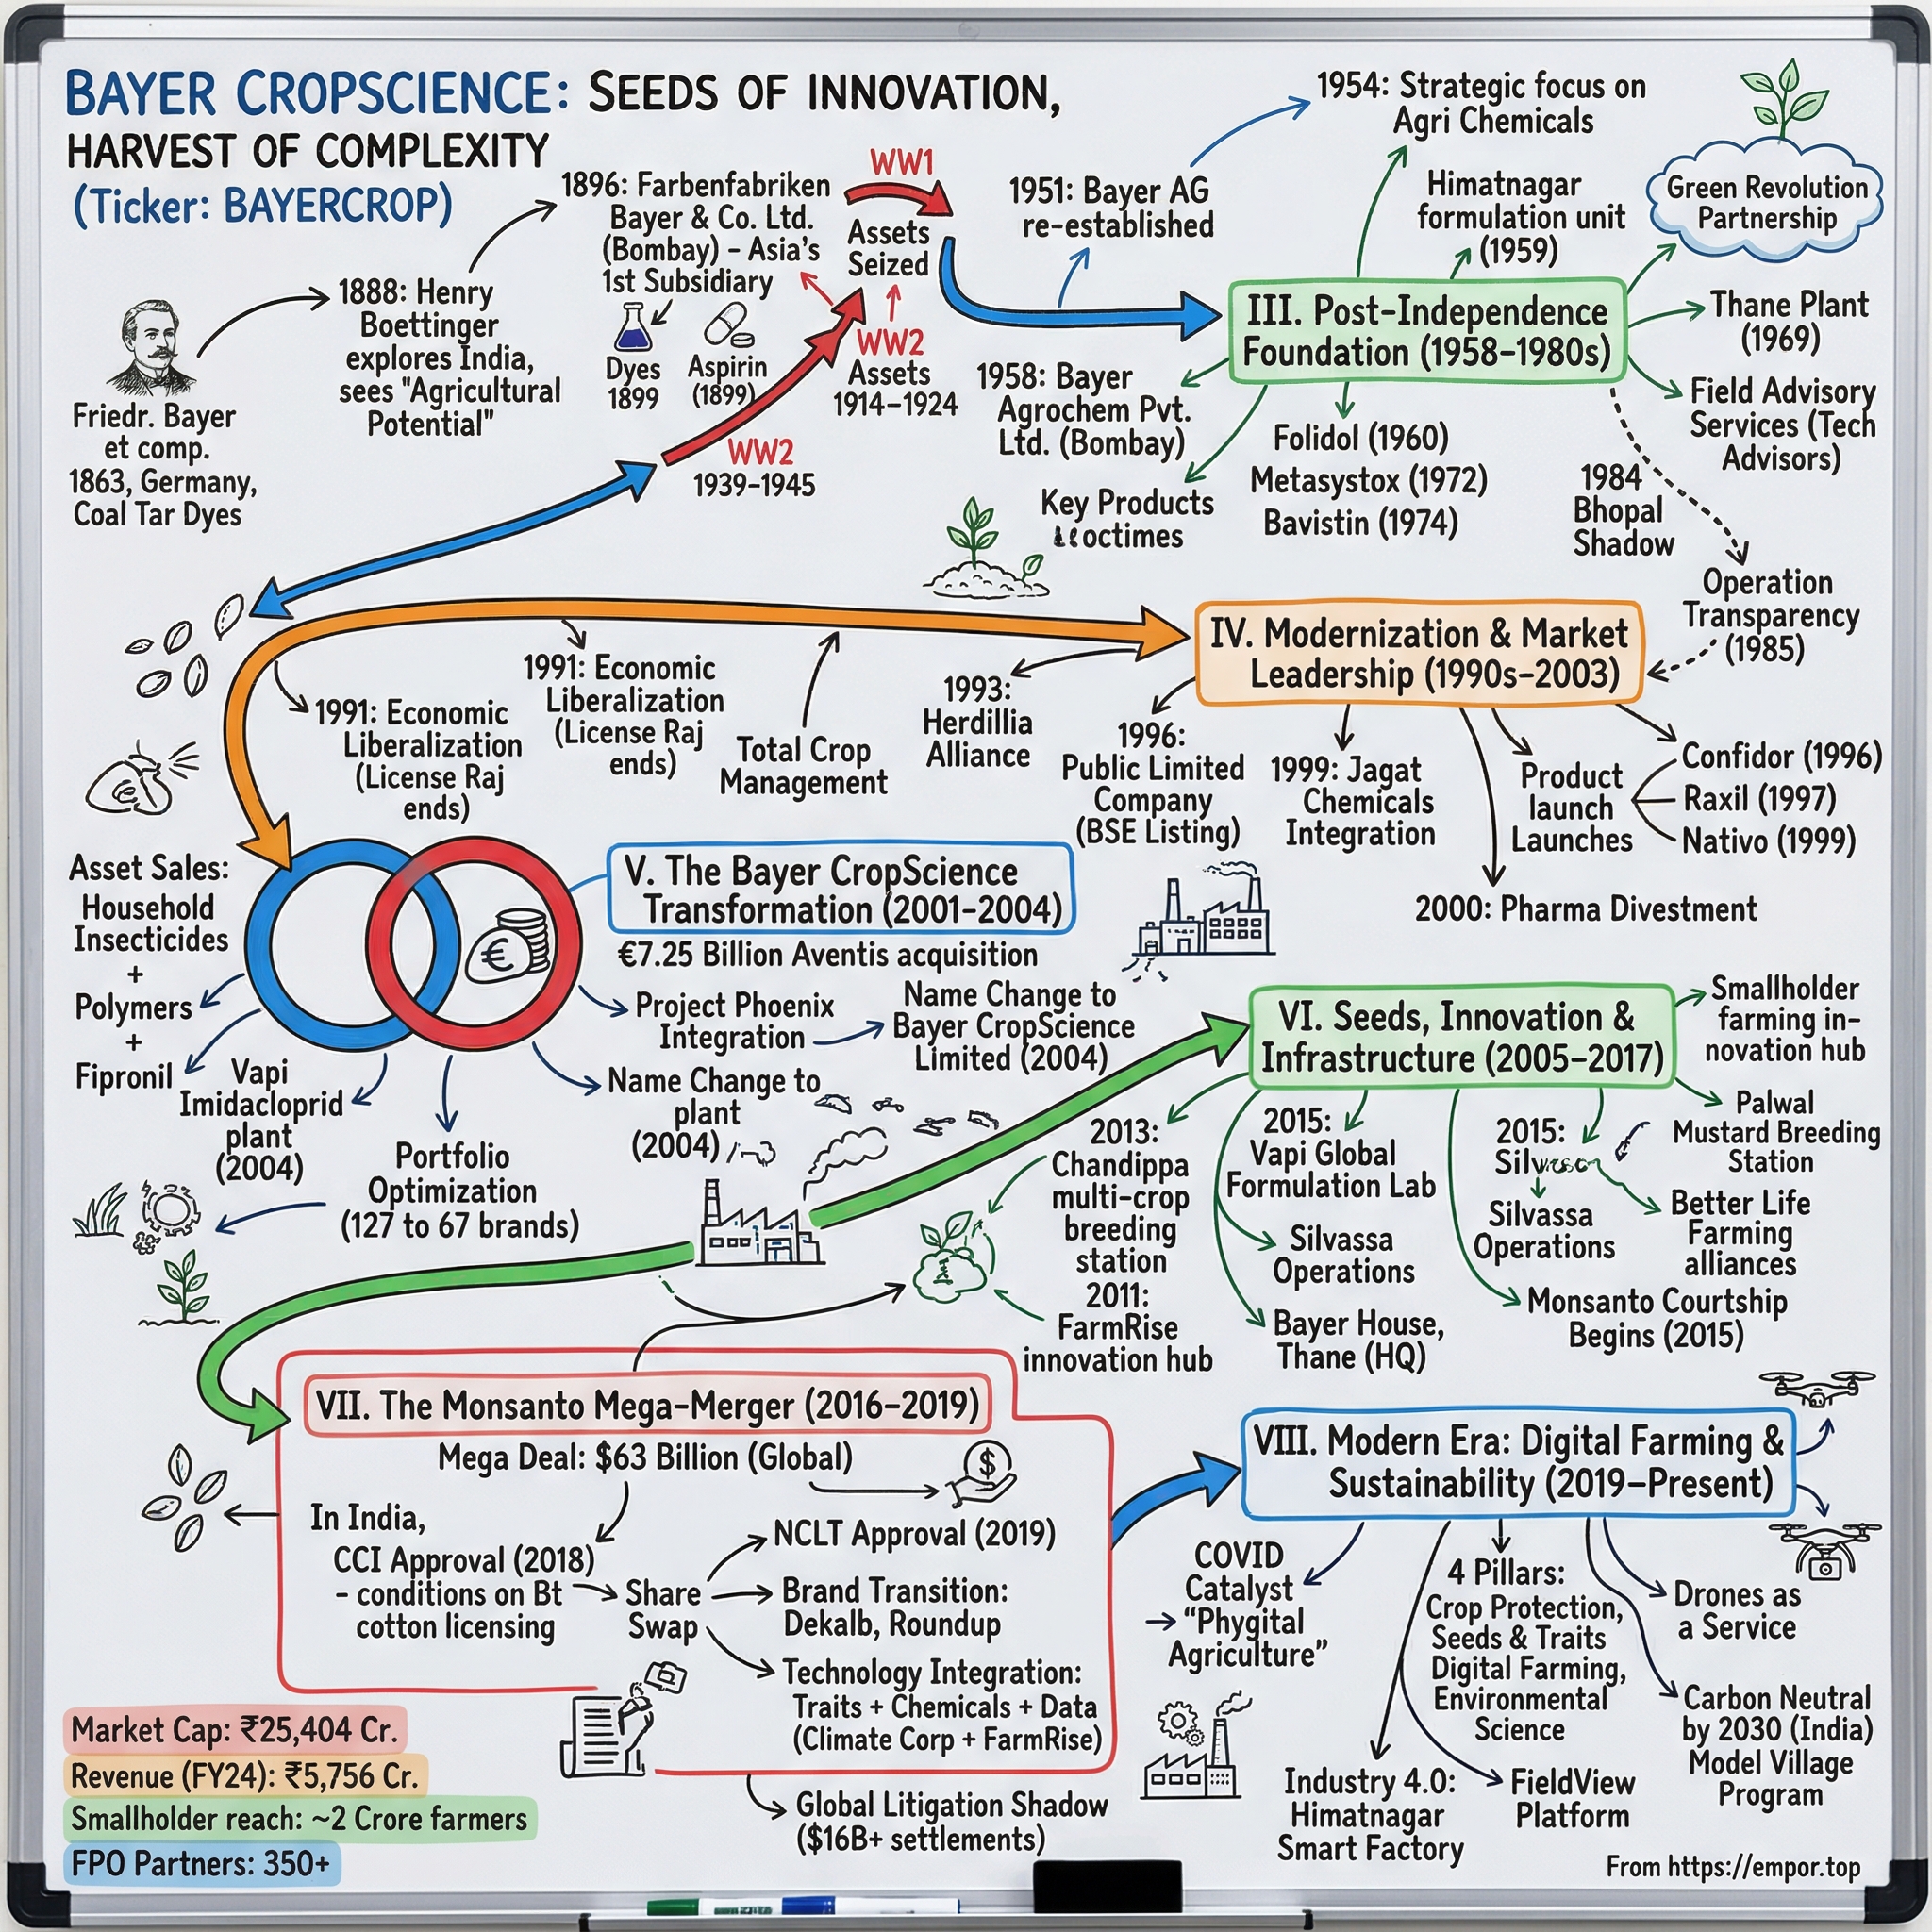
Bayer CropScience: Seeds of Innovation, Harvest of Complexity
I. Introduction & Episode Roadmap
Along the Gujarat coast, just north of the Maharashtra border, the chemical estates of Vapi stretch for kilometres in every direction — a landscape of pipe racks, flare stacks, and tanker queues that looks nothing like traditional agriculture. Yet inside one of those compounds, Bayer manufactures active ingredients destined for sprayer tanks on two-hectare paddy plots in Bihar, as well as shipping containers bound for Brazil, Japan, and the United States. That single facility serves as a fitting metaphor for the company at the centre of this story: an enterprise operating simultaneously in global industrial chemistry and Indian smallholder farming, with economics dictated by the collision between the two.
Bayer CropScience Limited — NSE ticker BAYERCROP — is the listed Indian subsidiary of German group Bayer AG. It is modest in size relative to India's major listed compounders. As of late August 2026, the company's market capitalisation stood at roughly ₹17,850 crore, with its share price trading near ₹3,971.1 For fiscal year 2025-26, which ended on March 31, 2026, the company reported revenue from operations of ₹56,750 million — approximately ₹5,675 crore — up from ₹54,734 million in the prior year, while profit before tax grew to ₹8,549 million from ₹7,074 million.2 Bayer AG and its affiliates hold a 71.44% equity stake; domestic institutional investors hold roughly 11.6%, foreign institutional investors hold under 4%, and the genuine public float is slightly over 13%.1
That ownership structure is the primary consideration for an investor, as it dictates the company's operational boundaries. Bayer CropScience's research pipeline is determined in Monheim and St. Louis, its key seed traits originated from a $63 billion global transaction executed without local input, its largest single supplier is its own parent group, and its minority shareholders own a thin slice of a business managed for a controlling parent based half a world away.
The central question of this episode is therefore not whether Indian agriculture presents an attractive market — an input industry valued in the tens of thousands of crores serving a farm population feeding 1.4 billion people provides a clear macro context. The crucial issue is narrower: how much of the value created in Indian crop science actually accrues to the minority shareholders of BAYERCROP, and what does the historical record reveal about the durability of the advantages that are supposed to protect it?
Three core tensions shape the business model.
The first is the M&A inheritance. Bayer's Indian franchise was assembled through two major global transactions — the acquisition of Aventis CropScience in the early 2000s and Monsanto in 2018 — both of which landed in India as mergers the local entity absorbed rather than authored.
The second is the discovery-versus-distribution gap. Bayer AG operates one of the world's largest agricultural R&D engines. However, molecules developed for 500-hectare corn farms in Iowa must be commercialised in small margin increments to Indian farmers operating an average landholding of barely one hectare. The unit economics of this translation — field force overhead, dealer credit lines, and seasonal monsoon dependence — dictate where profits are actually won or lost.
The third is extraction versus reinvestment. A 71.44% foreign parent extracts value through royalties, service charges, and dividends. The Indian entity maintains essentially no borrowings and a very high payout ratio.1 Whether this capital allocation represents prudent discipline or a structural cap on growth remains a live debate, tested against the historical record rather than asserted upfront.
The story also evaluates how trait pricing functions when the government sets rates by decree, why a patented molecule moat can become a wasting asset, the operational impact when Indian regulators paused approvals for genetically modified crops, and the specific metrics that indicate whether this business is compounding or coasting.
The narrative begins with the company's historical origins in industrial dyes.
 Subscribe on LinkedIn
II. Colonial Roots & India's Chemical Genesis (1863–1958)
In 1863, in Barmen — now part of Wuppertal — dye salesman Friedrich Bayer and master dyer Johann Friedrich Weskott formed a partnership to manufacture synthetic coal-tar dyestuffs. Nothing about that origin suggested agriculture. Synthetic dyes were the semiconductors of the nineteenth century: a new chemistry that rendered previously scarce colours affordable while enriching the firms that mastered it. What the dye business ultimately created, however, was more durable than any individual pigment. It built core capabilities in industrial organic synthesis, alongside a distribution challenge — because the world's largest market for cotton dyes was not in Germany.
It was in India.
That commercial logic drove Bayer east. In 1896, the group established what it describes as its first wholly owned Asian subsidiary, Farbenfabriken Bayer and Co. Ltd., in Bombay. By 1904, it was posting commercial and technical staff to India to expand operations. The product lineup focused on textile dyes for the mills of Bombay and Ahmedabad, alongside a growing pharmaceutical portfolio following the introduction of Aspirin in 1899.
Investors should be careful about how much weight this pre-independence chapter carries. It provides useful context that Bayer was not a post-liberalisation arrival; it maintained a physical presence in Indian commerce for more than half a century before selling a single pesticide. But the modern investment thesis does not rest on colonial-era dye sales. What survived from that period was narrower and more specific: a registered corporate presence, a brand recognized by Indian traders, and — critically — an established habit of routing German chemical output through Indian distributors.
That operational pattern forms a direct through-line to the present. A modern Bayer field officer visiting a village retailer in Maharashtra performs a contemporary version of what a dye agent did in 1910: selling a technically differentiated German product into a fragmented distribution network where retailer trust drives volume. In an industry where farmers cannot chemically verify bottle contents and counterfeit products present a recurring hazard, a brand with a century of local history retains tangible commercial value — a legacy Bayer's marketing has drawn upon for decades.
The boundaries of that inheritance are equally distinct. Brand trust built on dyes and aspirin does not automatically grant pricing power to a fungicide, nor does it defend profit margins once a patent expires and domestic formulators offer the same active ingredient at a 40% discount. Ultimately, the segments of Bayer's Indian operation that sustain pricing power are those where the product remains differentiated, not those relying solely on the label.
The strategic shift from dyes to crop chemistry occurred in Germany, not India. Bayer's insecticide development accelerated in the mid-twentieth century, producing a portfolio of organophosphate and carbamate compounds by the 1950s. These products offered high utility for tropical agriculture just as newly independent India was launching a state-directed agricultural modernization drive.
That alignment led an industrial dyestuffs company to incorporate its Indian agrochemical subsidiary in the autumn of 1958.
III. License Raj to Liberalization: Building the Ag-Chem Backbone (1958–2000)
Picture the paperwork. In 1958, as India entered its Second Five-Year Plan, a German multinational sought to manufacture pesticides in a country where the state decided who could produce what, in what quantity, and with how much imported input. Every expansion required a licence. Every rupee of foreign exchange required justification. And the primary customer — the Indian farmer — was largely subsistence-oriented with minimal cash for chemical inputs.
The entity that would become BAYERCROP was incorporated in 1958 as Bayer Agrochem Private Limited, renamed Bayer (India) Limited in 1963, and listed on Indian exchanges shortly afterwards.34 Its early manufacturing footprint was modest: a formulation facility in Bombay, followed by a larger production unit at Thane in 1969.
The strategic insight of that era was that the License Raj rewarded local manufacturing. Import substitution was policy, not merely a preference. Bayer responded by progressively transferring formulation and synthesis technology into India, securing industrial licences through the 1980s for active ingredients including cypermethrin and methyl parathion.4 The Foreign Exchange Regulation Act compelled multinationals to dilute foreign ownership, while price controls capped realisations. In that environment, a business survived by offering products farmers genuinely needed and building a domestic manufacturing base the state would tolerate.
That demand was real. The Green Revolution of the late 1960s and 1970s did not merely introduce high-yielding wheat and rice varieties; it created monocultures of genetically uniform, densely planted, heavily fertilised crops — an ideal environment for insects and fungi. Chemical crop protection was not an optional upgrade to the Green Revolution package; it was load-bearing. Selling German organophosphate chemistry in 1970s India meant supplying demand the company did not need to generate.
That dynamic shaped Bayer's institutional character in India. For roughly three decades, the primary operational constraint was supply and regulatory permission rather than demand and commercial competition. Companies forged in such conditions typically build strong technical and regulatory capabilities alongside less aggressive commercial instincts. Bayer's subsequent challenges in defending market share against agile domestic formulators become clearer when viewed through this lens: the company spent its formative Indian decades in a market where the state, rather than the customer, was the binding constraint.
Economic liberalisation in 1991 altered those terms. Licensing was dismantled, import tariffs fell, and Indian formulators gained access to cheap technical-grade active ingredients, particularly from China. Bayer's Indian entity converted to a public limited company on December 28, 1996, and set about reshaping its portfolio for a competitive market.34
Two restructurings from that decade stand out. First, the amalgamation of Jagat Chemicals, effective January 1, 1999, folded in additional agrochemical capability.4 Second, and far more consequential, was the decision in 2000 to move the pharmaceutical business into a separate entity, leaving the listed company focused on crop science.4
That demerger represented a defining strategic choice. On one hand, sharpening focus made operational sense: crop protection and human pharmaceuticals shared chemical roots but differed in regulatory frameworks, distribution channels, sales cycles, and capital intensity. Running both inside one listed vehicle risked creating a conglomerate discount and dividing management attention.
On the other hand, minority shareholders of the listed entity ended up excluded from the more lucrative pharmaceutical business. Bayer's Indian pharmaceutical operations were placed outside the listed company, leaving public investors with no ticker access to that franchise. This established a recurring pattern: when the global parent restructured, Indian minority shareholders inherited whatever remained in the domestic corporate vehicle without being consulted.
That structural arrangement would soon face an even larger test in the next global restructuring.
IV. The Aventis Leap & Molecule Moats: Re-Architecting Crop Protection (2001–2015)
In the late 1990s, the global agrochemical sector underwent widespread consolidation. Novartis and AstraZeneca combined their agricultural units to create Syngenta, while Hoechst and Rhône-Poulenc merged to form Aventis. That transaction created a massive crop science division that was ultimately non-core to Aventis's pharmaceutical focus. Bayer, holding a strong insecticide portfolio but lacking overall global scale, acquired the business.
Completed in the early 2000s at a headline value of roughly €7.25 billion, the Aventis CropScience acquisition doubled Bayer's global agricultural scale and added crucial product breadth in herbicides and seed treatments. In India, the transaction triggered a local amalgamation as Aventis CropScience India merged into the domestic entity. On February 24, 2004, the listed company formally adopted its current name, Bayer CropScience Limited.34
The commercial impact extended beyond top-line revenue. The acquisition provided a portfolio broad enough for a field officer to present retailers with a full-season protection program — spanning seed treatments, insecticides, fungicides, and herbicides — rather than a single product for a narrow window. In a fragmented market where village retailers act as gatekeepers and shelf space remains scarce, portfolio breadth functions as a powerful distribution lever. A supplier capable of addressing the entire cropping cycle commands priority shelf space.
The company's manufacturing network expanded alongside its portfolio. Bayer's Indian footprint includes agrochemical production at Himatnagar in Gujarat and Silvassa, seed processing facilities near Hyderabad, and breeding stations in Bengaluru and Udaipur, in addition to the major complex at Vapi.3 The Vapi facility is strategically distinct because it operates beyond the domestic market, manufacturing active ingredients exported into Bayer's global supply chain. This embeds the Indian entity into the parent group's global cost structure rather than leaving it as a purely domestic sales outlet.
Integrating into global production also means the Indian listed entity absorbs domestic industrial risks on behalf of the group. That vulnerability became evident in December 2022, when operations at the Himatnagar crop protection formulations plant were temporarily suspended following directives from the Gujarat Pollution Control Board under Section 33-A of the Water (Prevention and Control of Pollution) Act. The company stated that it complied with the board's requirements and sought revocation, and no monetary penalty was reported.5 Although the disruption was brief and contained, it highlighted that domestic manufacturing facilities carry real environmental compliance risks and operational shutdown vulnerabilities alongside seasonal monsoon dependence and pricing pressures.
The second pillar developed during this era was seeds. Rather than acquiring immediate scale, Bayer built its initial Indian seed presence organically, establishing breeding capabilities across multiple crops to construct a hybrid platform in corn, rice, and vegetables. Developing commercial hybrids requires years of cross-breeding, field trials, and regional adaptation before earning farmer trust. When successful, hybrid seed platforms build higher customer retention than crop protection chemicals.
That durability stems from a fundamental operational difference. A farmer purchasing an insecticide seeks a simple chemical outcome; if a lower-cost alternative delivers equivalent pest control, switching barriers remain low, bounded only by brand trust. Conversely, a farmer choosing a hybrid corn seed buys a predictable yield profile based on multi-season performance under specific local soil and rainfall conditions. Because performance cannot be verified from a price tag, customer switching costs in seeds are behavioral rather than contractual, creating a durable competitive moat that set the stage for Bayer's subsequent acquisition of Monsanto.
Financially, the decade following the Aventis integration established BAYERCROP's profile as a capital-efficient compounder. The business maintained a conservative balance sheet, operating virtually debt-free with borrowings of ₹82 crore against reserves of ₹2,921 crore as of fiscal 2026, while generating a return on capital employed of 29.1% and a return on equity of 23.7%.1 These returns reflect an asset-light operational model focused on formulation and seed processing rather than capital-intensive primary chemical synthesis.
However, generating high returns on a modest capital base reveals a structural constraint. When a business earns nearly 30% on capital but lacks opportunities to reinvest retained earnings at comparable rates, excess cash is returned to shareholders rather than driving expansion. This dynamic is evident in the combination of a 3.8% dividend yield and a ten-year annual sales growth rate of roughly 7%.1 Exceptional capital efficiency and modest top-line growth reflect the same underlying reality: high profitability within a mature, capital-disciplined operating model.
That dynamic would soon be tested by the largest agricultural transaction in history.
V. The $63 Billion Catalyst: Monsanto, Trait Fee Battles, & The NCLT Saga (2016–2019)
There is a version of the Monsanto story that gets told from Leverkusen, and a version that gets told from a cotton field in Yavatmal, and the remarkable thing is how little the two have to do with each other.
The Leverkusen version: in 2016 Bayer AG under CEO Werner Baumann pursued Monsanto Company, the world's dominant seed and trait business, and closed the acquisition in June 2018 for approximately $63 billion.6 The logic was clean on a slide. Bayer possessed crop chemistry; Monsanto possessed germplasm and genetic traits. Modern agriculture was converging on integrated systems where the seed, trait, and crop protection chemicals were designed together — most famously, a herbicide-tolerant seed that allowed a farmer to spray a broad-spectrum herbicide over a growing crop without destroying it. Owning both halves was supposed to yield far higher value than operating either in isolation.
The Yavatmal version: by the time Bayer closed the transaction, the Indian government had already begun dismantling the commercial foundation of the most lucrative asset Monsanto owned in India.
Examining these developments in sequence demonstrates why the Indian regulatory environment dictated the actual outcome for investors.
The CCI's price of admission
The Competition Commission of India approved the acquisition on June 14, 2018, but attached one of the most intrusive remedy packages it has ever imposed. Bayer was required to divest its glufosinate-ammonium herbicide business alongside its cotton and corn crop traits, as well as its hybrid vegetable seeds business; Monsanto was required to sell its 26% stake in Maharashtra Hybrid Seed Company. For seven years, the merged entity was obliged to license its GM and non-GM traits broadly and non-exclusively on fair, reasonable, and non-discriminatory terms, license non-selective herbicides on the same basis, make agro-climatic data and digital farming platforms available to Indian users on subscription, provide such data free to Indian state institutions, and refrain from bundling products or enforcing exclusivity on sales channels. If it offered superior terms to a new licensee, it was required to extend them to existing licensees within 60 days.7
Viewed from an investment perspective, the CCI did not merely trim the deal; it preemptively neutralized the key mechanisms through which an integrated seed-trait-chemical company converts market power into pricing leverage. Bundling was banned, channel exclusivity was prohibited, compulsory FRAND licensing was mandated for flagship traits, and most-favored-nation treatment was guaranteed for existing licensees. In effect, regulatory authorities permitted Bayer to hold the technology while prohibiting monopolistic pricing or tied selling.
The seven-year duration of those commitments began at deal completion, setting their expiration for around 2025. While that marks a genuine structural shift in the operating environment, its practical impact remained limited because another branch of the Indian government had taken even more decisive action against the business model.
The trait fee war
Understanding that outcome requires examining how trait licensing functioned. Monsanto generally did not sell cotton seed directly in India. Instead, it licensed a genetic trait — Bollgard, and later Bollgard II, which introduced bacterial genes producing proteins toxic to bollworm larvae — to roughly 45 Indian seed companies. Those licensees bred the trait into locally adapted hybrids, distributed the seed, and paid Monsanto a per-packet fee. The technology provider captured a portion of the economic value while seed companies retained the remainder.
The commercial model generated substantial returns before encountering severe friction. Under a 2004 agreement, Nuziveedu Seeds paid an upfront sum plus a trait fee that reached as high as ₹1,200 per 450-gram packet in early contracts, eventually stabilizing around ₹163 to ₹168 per packet before regulatory intervention.8
Government intervention subsequently restructured the market. The Cotton Seeds Price (Control) Order of December 2015 empowered the central government to fix both the maximum retail price of Bt cotton seed and the licensing fee payable to the technology provider. The initial administrative order reduced the trait value by roughly 70%. Further reductions followed: the trait fee was lowered to ₹39 per packet in 2018, ₹20 in 2019, and set to zero in 2020.8
This shift represented the administrative elimination of a high-margin revenue stream over a five-year period on technology that had been contractually licensed.
Concurrently, commercial licensing dissolved into litigation. Monsanto and Nuziveedu disputed unpaid fees and questioned whether Monsanto's patent on the Bt trait was valid under domestic law. The legal debate centered on Section 3(j) of the Indian Patents Act, which excludes plants and biological processes from patentability, contrasting with the Protection of Plant Varieties and Farmers' Rights Act, which provides a distinct framework for breeder rights. The Delhi High Court invalidated the patent in April 2018; the Supreme Court set aside that ruling in January 2019, restoring the patent and remanding the underlying dispute for trial.8
Consequently, Bayer sustained the intellectual property right while losing the associated cash flows, as the state capped license realisations at nil. This sequence serves as a critical case study in the company's domestic operational history and remains a critical reference point when evaluating the company's economic moat.
Bringing Monsanto India inside
Domestic corporate integration followed the global transaction. The Mumbai bench of the National Company Law Tribunal approved the scheme of amalgamation of Monsanto India Limited into Bayer CropScience Limited on September 13, 2019 — marking the final regulatory step in the Indian integration following Competition Commission clearance and shareholder approval earlier that year.6 Under the tribunal-approved exchange ratio, Monsanto India shareholders received two Bayer CropScience shares of ₹10 face value for every three shares held.[^9]3
The assets brought into the entity extended beyond cotton traits. Monsanto India contributed the DeKalb hybrid corn franchise and the Roundup herbicide portfolio, both of which demonstrated greater commercial durability in India than Bt cotton. Roundup continued as a primary revenue contributor; management attributed a portion of the 17% top-line growth in the first quarter of fiscal year 2025-26 specifically to expanded volumes of corn seeds and Roundup, supported by an early monsoon.9
This dynamic created a sharp geographic divergence. In India, Roundup remained an operational product line; in the United States, it developed into a major legal liability for the parent group. The Indian listed entity carried no direct balance sheet exposure to the American mass-tort litigation that impacted the parent — Bayer AG faced approximately 65,000 pending Roundup lawsuits, incurred litigation expenses exceeding $10 billion, and saw more than $60 billion in market value erased after the 2018 transaction.10
The parent group's legal standing shifted in mid-2026. On June 29, 2026, the U.S. Supreme Court ruled in the Durnell case that federal law preempted failure-to-warn claims against the Roundup label — a key legal development, though legal analysts emphasized that plaintiffs could still pursue design-defect and negligence claims. Legal scholar Carl Tobias noted, "This is not the silver bullet Bayer was looking for."10 Previously, in February 2026, Bayer proposed a $7.25 billion class settlement to address the majority of outstanding claims.10 On July 2, 2026, the group consolidated its U.S. glyphosate operations under a dedicated subsidiary, Ruveon LLC, based in St. Louis — a corporate restructuring interpreted by market analysts as facilitating a potential future separation of the unit. Berenberg analyst Sebastian Bray noted that the reorganization "may prompt investor speculation of an eventual separation of some agriculture activities from Bayer," after which Bayer shares rose as much as 5.7% to their highest level since August 2023.11
For minority shareholders in BAYERCROP, these parent-level developments created indirect operational effects. A global parent managing significant debt and legal liabilities operates under different capital constraints than an unencumbered parent, generally prioritizing debt reduction and cash extraction over discretionary subsidiary reinvestment. At its April 2026 annual general meeting, Bayer AG management under CEO Bill Anderson outlined a five-year operational framework focused strictly on execution and core product lines. Shareholders approved only the minimum statutory dividend to preserve cash for debt paydown, while institutional investors highlighted a decade of relative underperformance against the DAX index, prompting Anderson to acknowledge that "the work isn't complete."12
The net impact of the Monsanto integration for BAYERCROP minority investors reflects two contrasting outcomes. The merger added core operating assets — specifically DeKalb corn hybrids and Roundup — at an independently evaluated swap ratio, while consolidating the group's listed domestic presence. However, it did not deliver the trait-royalty stream anticipated in the original global thesis, as domestic price controls eliminated cotton trait fees. Furthermore, it aligned the Indian entity's capital allocation framework with a parent group focused through 2026 on litigation management, debt reduction, and portfolio simplification.
This sets up the examination of the core operating engine: what the company sells, to whom, and at what margin.
VI. Inside the Engine Room: Segments, Economics, & Competitor Benchmarking
Every business has a rhythm. While software companies generate steady quarterly revenue, Bayer CropScience operates on a financial trajectory that resembles an electrocardiogram.
Consider the financial trajectory across fiscal year 2025-26. During the June 2025 quarter — the kharif sowing window when monsoon rains trigger peak demand for seeds and crop protection — revenue reached ₹19,146 million, representing a 17% year-on-year increase.9 By contrast, in the off-season December 2025 quarter, net sales fell to ₹1,106 crore, marking a 28.8% sequential decline from the September quarter's ₹1,553 crore. Net profit dropped 37% sequentially during that same quarter, even as it rose 180% against a depressed year-earlier comparison base.13 Full-year revenue reached ₹56,750 million.2
This pronounced seasonality is inherent to supplying inputs into a monsoon-dependent agricultural calendar. However, it introduces two operational realities that market observers frequently overlook.
First, single-quarter financial results provide limited analytical value. A one-week shift in monsoon arrival can reallocate substantial revenue between reporting periods. Management acknowledged this dynamic when attributing the first-quarter fiscal 2025-26 growth surge in corn seeds and Roundup volumes to "the early onset of the monsoon."9 Consequently, a strong opening quarter does not demonstrate a multi-year turnaround, nor does an off-season decline signal market share erosion. Evaluating the underlying business requires analyzing trailing twelve-month metrics and season-over-season comparisons.
Second, negative operating leverage impairs off-season margins. Because field personnel, manufacturing facilities, and distribution networks represent largely fixed costs, seasonal sales contractions compress profitability. In the December 2025 quarter, the operating margin recovered to 10.6% from 1.9% a year earlier, yet remained 263 basis points below the preceding quarter's 13.2%.13 Management attributed this contraction to volume deleverage during an off-season period. When an enterprise generates the vast majority of its annual earnings across two key quarters, the remaining periods test operational cost containment rather than underlying market demand.
What the two segments actually are
Crop protection represents the larger operational division, spanning insecticides, fungicides, herbicides, and seed treatments. Official corporate reporting categorizes the business into crop protection, seeds and traits, digital farming, and an agri-care operations segment encompassing the manufacture, sale, and distribution of agrochemicals and corn seeds.3 Bayer CropScience does not publish a granular revenue breakdown between crop protection and seeds in its quarterly filings, leaving financial analysts dependent on secondary estimates rather than primary disclosures.
Within crop protection, segment economics split into two distinct product categories that are blended in reported consolidated margins. The proprietary portfolio — comprising patented molecules and proprietary co-formulations combining active ingredients into specialized suspensions — commands premium pricing due to limited direct substitution. Conversely, the post-patent portfolio trades at market prices dictated by generic competition and Chinese technical-grade active ingredient supply. Consolidated gross margins obscure this division; a margin contraction may reflect generic price competition, or simply a temporary product mix shift toward off-patent formulations while newer launches scale.
Seeds and traits constitutes the higher-margin division, centered on hybrid corn under the DeKalb brand alongside hybrid rice and vegetable seeds. Hybrid corn represents the primary growth vector for the segment. However, it also presents near-term challenges: for the fourth quarter of fiscal 2025-26, management reported softer corn seed sales, though product diversification sustained overall revenue growth at approximately 5%.2 Given that the segment's investment thesis relies heavily on DeKalb's market position, demand softness in hybrid corn directly impacts overall seed profitability.
Distribution: the part that is hard to copy and hard to verify
Bayer's commercial route to market operates through wholesale distributors, retail dealers, and village-level stockists, backed by a technical field force conducting agronomic demonstrations. Because the company does not disclose dealer headcount or sales force size in its financial statements, third-party network estimates lack verification.
Documented commercial initiatives focus on expanded channel touchpoints and digital ecosystem platforms. Bayer operates 1,500 Better Life Farming centers across India, reporting reach to 30 million smallholder farmers with seeds, micro-credit linkages, and custom drone spraying services, alongside training 10,000 women as drone operators under the "Drone Didis" initiative.14 Concurrently, its FarmRise digital advisory platform has registered over five million farmers, while the FarmRise One marketplace connects more than 500 Farmer Producer Organizations and 200,000 agricultural producers to input sales, institutional credit, and market access.
Working capital patterns reflect these distribution dynamics directly on the balance sheet. Pre-season stocking for the kharif period requires extending trade credit to distributors until post-harvest settlement, causing trade receivables and inventory levels to expand significantly ahead of monsoon demand. Management attributed full-year fiscal 2026 performance to monsoon disruptions and a "strategic emphasis on disciplined channel management over aggressive volume-driven growth," with Chief Financial Officer Vinit Jindal highlighting cost controls, cash flow management, and balance sheet flexibility.2
While channel discipline presents a prudent operational posture, management claims regarding volume restraint require empirical verification against trade credit trends. Investors can evaluate this strategic assertion by tracking whether trade receivables and dealer inventory levels decline relative to total sales. A simultaneous drop in channel inventory and receivables accompanied by stable revenue indicates genuine inventory normalization, whereas falling sales alongside inventory write-downs suggests broader demand weakness.
The competitive set, honestly assessed
Bayer's competitive landscape spans three distinct peer groups, each operating under fundamentally different business models.
PI Industries is often cited as an industry growth benchmark, though its core business differs structurally from Bayer CropScience. PI operates primarily as a custom synthesis and manufacturing exporter for global life science innovators, producing active ingredients for patented international molecules. This export model achieved higher historical compounding rates than domestic retail distribution, generating a return on capital employed of approximately 27.8% against a five-year average of 27.7%. However, the contract manufacturing model demonstrated greater cyclical vulnerability during recent global destocking: PI's September 2025 quarter revenue declined 15.7% year-on-year while net profit fell 19.5%, followed by a steeper revenue contraction in the December 2025 quarter.15 The global destocking cycle that began in late 2022 disproportionately impacted export suppliers, rendering Bayer's domestic retail focus relatively more defensive through this downturn, even if long-term structural growth remains lower.
UPL Limited operates as a global generic producer, competing on manufacturing scale, broad distribution, and price rather than proprietary innovation. UPL maintains higher debt leverage, resulting in returns on capital substantially lower than Bayer's. Bayer retains competitive advantages over UPL through proprietary product pricing power and a conservative balance sheet free of debt refinancing pressures. Conversely, UPL's global sourcing flexibility enables it to price generic crop protection chemicals at levels Bayer's cost structure cannot match.
Sumitomo Chemical India represents the closest structural comparable as a foreign multinational subsidiary leveraging a parent R&D pipeline alongside a strong Indian distribution network. While Sumitomo has sustained elevated returns on capital, its top-line expansion has similarly moderated, with revenue increasing by 0.64% year-on-year in the March 2026 quarter.15 The concurrent slowdown across both multinational subsidiaries highlights structural constraints inherent in commercializing foreign parent pipelines in the Indian smallholder market, rather than company-specific execution failures.
Beyond these primary peers, unlisted multinational competitors — including Syngenta India and Corteva Agriscience — compete directly in premium corn hybrids and specialized fungicides. Simultaneously, domestic formulators such as Dhanuka Agritech, Rallis India, and Coromandel International utilize rapid commercialization of off-patent active ingredients and lower-cost co-formulations to capture market share. This domestic cohort exerts continuous margin pressure on Bayer's post-patent portfolio as molecules age past exclusivity.
Evaluating these competitive dynamics reveals a business subject to multi-directional pressure rather than direct market share loss to a single rival. Bayer's market position is effectively compressed: premium market share is contested at the top by multinational peers, volume share at the lower end is undercut by domestic formulators relying on Chinese active ingredient imports, and mature portfolio molecules face steady margin erosion over time. While this structure supports high return metrics on existing capital, it constrains top-line compounding velocity.
This competitive dynamic leads directly to the core analytical question: how durable is Bayer CropScience's economic moat?
VII. The Falsification Pass: Testing Bayer's Moat, Capital Allocation, & GM Optionality
Most investment analyses of Bayer CropScience assert three core claims: a proprietary R&D moat, a post-Monsanto seed and trait franchise, and disciplined, independent capital allocation. Each thesis is plausible, and each can be tested against decades of operational evidence in India by evaluating the specific mechanisms that would break each claim.
Claim 1: "Bayer possesses an impenetrable proprietary molecule moat"
The mechanism that breaks a proprietary molecule moat is substitution — specifically, price and volume erosion following patent expiry, combined with regulatory restrictions on commercial distribution.
The historical record highlights this vulnerability. Bayer's major Indian insecticide successes of the 2000s, imidacloprid and fipronil, both lost patent protection and are now manufactured at scale by generic producers in China and India. The dynamic is structural: an innovator maintains premium pricing during exclusivity, but faces price compression once off-patent technical-grade active ingredients flood the market. Bayer's domestic brand equity moderated volume loss, but it could not defend historical pricing levels.
Regulatory policy presents an additional constraint specific to the Indian market. On May 14, 2020, the Ministry of Agriculture issued a draft order proposing to ban the import, manufacture, distribution, and use of 27 agricultural pesticides — including acephate, atrazine, carbendazim, chlorpyrifos, 2,4-D, deltamethrin, dimethoate, malathion, mancozeb, monocrotophos, pendimethalin, and quinalphos. These target molecules accounted for roughly 10% to 15% of India's agrochemical exports and nearly 20% of total industry revenue, with mancozeb alone representing an annual domestic production capacity of about 82,000 tonnes in 2018.16 The draft followed an expert committee review of 66 pesticides, 18 of which had already been banned in 2018.16
Although the 2020 draft order was not fully implemented and only a subset of molecules was ultimately banned, the episode demonstrated that one-fifth of the industry's revenue base could be placed under administrative threat. Furthermore, on October 21, 2022, the government restricted glyphosate application strictly to authorized pest control operators — a requirement that industry observers noted is difficult to enforce given the scarcity of licensed operators in rural areas.17 This regulatory restriction remains an active commercial constraint on a core product in Bayer's domestic lineup.
Verdict: narrowed, materially. The assertion of an impenetrable molecule moat is unsupported by the historical evidence. What survives is a narrower, defensible advantage: Bayer maintains a renewable edge that relies on launching new differentiated products — including proprietary co-formulations, novel modes of action, and seed-applied technologies — faster than older molecules commoditize. This business model functions as a product treadmill rather than a permanent barrier. Demonstrating its execution requires a consistent commercial launch cadence; for instance, management highlighted the nationwide launch of BICOTA for stem borer management in paddy as evidence of ongoing portfolio renewal.9 Evaluating the durability of this revised advantage requires tracking the revenue share generated by products introduced within the preceding three to five years — a key metric that remains unquantified in corporate disclosures.
Claim 2: "The Monsanto merger created an unstoppable seed trait monopoly in India"
The mechanism that breaks a seed trait monopoly operates across three vectors: regulatory price controls, biological pest adaptation, and unauthorized channel leakage. In the Indian market, all three materialized.
Administrative price regulation severely impacted licensing economics. Statutory decrees reduced trait fees from roughly ₹163 to ₹168 per packet prior to government intervention down to ₹39 in 2018, ₹20 in 2019, and finally zero in 2020.8 Consequently, the high-margin royalty stream that formed the primary economic rationale for trait licensing was eliminated. Furthermore, retail seed prices declined only modestly, shifting from ₹740 to ₹730 per packet before stabilizing — indicating that the economic value created by fee reductions accrued primarily to domestic seed formulators rather than smallholder farmers.8
Biological adaptation represented the second structural challenge. Bollgard II technology relies on expressing two bacterial proteins within the cotton plant to target bollworm pests. However, pink bollworm populations developed resistance over time. Resistance to single-gene traits emerged in Gujarat in 2009, followed by documented resistance to dual-gene Bollgard II by 2014. Field efficacy failures spread across central and southern cotton belts during 2016 and 2017, reaching northern growing zones by 2018 and worsening through 2023. Major agricultural states — including Gujarat, Madhya Pradesh, Maharashtra, Karnataka, Andhra Pradesh, and Telangana — reported crop yield losses of up to 30% as the pest transformed from a late-season hazard into a mid-season threat.18 As biological resistance reduces pest control efficacy, farmer willingness to pay premium pricing diminishes accordingly.
The third factor involved market leakage stemming from regulatory delays in approving next-generation traits. In the absence of formal clearance for herbicide-tolerant Bt cotton, an unauthorized seed market expanded to meet farmer demand. Industry estimates indicate that unapproved cotton varieties cover approximately 20% of India's cotton acreage — representing roughly 24 lakh hectares out of 120 lakh total hectares. Annual sales of unapproved seed reach around 75 lakh packets, priced at approximately ₹1,500 per packet compared to ₹760 for authorized hybrids, capturing roughly ₹500 crore in annual farmer expenditure outside legal commercial channels.19 This unmonetized volume competes directly against official product lines without generating royalty income or corporate margin.
Verdict: rejected for cotton traits; intact but unproven for hybrid corn. In cotton traits, the monopoly thesis is negated by the combination of zero-fee price caps, biological resistance, and extensive unauthorized market leakage. Conversely, the hybrid corn business under the DeKalb brand operates under different economics: Bayer sells proprietary seed directly rather than licensing traits to third parties, insulating it from cotton price control orders while benefiting from behavioral switching costs. However, management's report of softer hybrid corn sales during the March 2026 quarter demonstrates that the segment remains subject to cyclical demand fluctuations.2 Confirming the strength of the corn franchise requires tracking DeKalb volume and realizations across an entire agricultural cycle rather than relying on single-season performance surges.
The argument that next-generation biotechnology represents embedded upside option value warrants equal scrutiny. India's Genetic Engineering Appraisal Committee has not approved a new genetically modified food or fiber crop for commercial cultivation in over a decade, while field trials have faced persistent local opposition and physical disruptions.5 An asset option contingent on regulatory approvals that have been stalled for more than ten years carries limited economic value until formal clearances are granted.
Claim 3: "Bayer CropScience India is a disciplined, independent capital compounder"
Evaluating the assertion that Bayer CropScience India represents a disciplined, independent capital compounder requires testing two core concepts: top-line compounding performance and strategic independence.
Regarding compounding capability, multi-year top-line growth metrics display a decelerating trend: ten-year compound annual sales growth stands at roughly 7%, five-year growth at 6%, and three-year growth at 3%, lagging broader market expansion.1 Ten-year annual profit growth of approximately 8% reflects modest expansion rather than high-rate compounding.1 The company maintains a high payout policy, offering a dividend yield near 3.8%; for fiscal year 2025-26, the board recommended a final dividend of ₹60 per share, distributing roughly ₹2,697 million across 44.94 million shares out of a net profit after tax of ₹6,892 million.2 Although profit after tax grew 21% in fiscal 2025-26, revenue increased by less than 4%, indicating that earnings expansion was driven by margin recovery and cost controls rather than broad-based volume growth.2
Subsequent quarterly results underscore this distinction. In the June 2026 quarter, revenue from operations declined 4.2% year-on-year to ₹1,835 crore, while profit after tax expanded 15.4% to ₹321.6 crore. Total expenses decreased 4.8%, while other income rose to ₹88.9 crore from ₹18.7 crore in the prior-year period — driven by a ₹63.9 crore one-time gain from divesting marketing rights for specific formulated products, alongside a ₹74.3 crore inventory reversal benefit compared to a ₹68 crore provision in the previous year.20 Adjusting for the one-time asset sale and inventory adjustments reveals an underlying quarter defined by operational cost reduction rather than organic demand expansion. Management described the performance as a "resilient start to FY2026-27," attributing results to "disciplined execution amid challenging weather and evolving market conditions."20 While operational discipline supported net earnings, the results reflect asset monetization and cost management rather than top-line momentum.
Regarding independence, the Indian entity relies on its parent group for product R&D, active ingredient sourcing, and intellectual property licensing. Bayer AG's corporate priorities through 2026 have centered on litigation resolution, debt reduction, and portfolio simplification — as reflected in the minimal dividend payout approved at its April 2026 annual meeting and the structural reorganization of its U.S. glyphosate business under Ruveon LLC.1211 Consequently, a domestic subsidiary dependent on technology transfers from a parent group prioritizing balance sheet restructuring operates under strategic boundaries that constrain autonomous growth.
Verdict: narrowed. The empirical evidence supports characterizing Bayer CropScience India as a high-return, cash-generative, conservatively financed, and well-governed business. However, the data does not support the label of an independent compounder. Instead, the entity functions as a mature, high-payout cash generator within a global group structure, as evidenced by decelerating multi-year revenue growth. This structure represents a low-risk, income-producing asset rather than a high-growth compounder. Revising this assessment upward would require sustained double-digit revenue growth driven by new product commercialization and expanding gross margins, rather than seasonal monsoon recoveries.
VIII. Current Management, Parent Governance, & Capital Allocation
Executive succession at a multinational subsidiary is frequently routine, but at Bayer CropScience, the transition in late 2023 marked a major leadership shift.
D. Narain retired at the end of November 2023 after leading Bayer's Indian crop science business for more than 25 years.21 In an industry where commercial relationships with distributors, state agriculture departments, and seed licensees accumulate over decades, Narain's departure represented the exit of substantial institutional memory. He had guided the entity through the Monsanto integration, the collapse of cotton trait licensing revenue, and the disruption of the COVID-19 pandemic. The company announced his successor on August 30, 2023.
Simon-Thorsten Wiebusch assumed the roles of President of Bayer South Asia and Vice Chairman, Managing Director, and CEO of Bayer CropScience Limited on November 1, 2023, while retaining his position as country division head for India, Bangladesh, and Sri Lanka.21 His background reflects the parent group's strategic priorities.
Wiebusch is a career Bayer executive who joined the group in 1998, serving across Germany, Eastern Europe, and Asia in sales support, operations, tender management, controlling, and strategy. He moved to India in December 2018 as chief operating officer for the South Asia cluster before becoming country division head in early 2022.21 He holds a bachelor's degree in economics from a university of applied sciences in Essen and an MBA from the University of Bradford.21
Wiebusch's background in financial controlling, operations, and tender management characterizes an executive focused on systems and operational discipline rather than aggressive commercial expansion. By appointing a former chief operating officer who spent five years in the domestic business, Bayer prioritized institutional continuity and financial control precisely as global agrochemicals entered a destocking downcycle and domestic top-line growth decelerated. Subsequent corporate strategy aligned with this operational orientation, prioritizing channel discipline, cost containment, and cash generation over volume growth or market share expansion.
Executive Director and Chief Financial Officer Vinit Jindal reinforced this orientation, emphasizing disciplined cost management, cash flow generation, and balance sheet flexibility in the fiscal 2026 financial commentary.2 For two consecutive financial cycles, executive leadership focused public commentary on cost structures and working capital management rather than top-line demand generation.
What governance actually looks like here
With Bayer AG holding a 71.44% equity stake, governance for minority shareholders centers less on abstract board independence and more on identifying where minority interests diverge from parent priorities.
Three operational areas present potential structural divergence:
Related-party pricing: The Indian subsidiary purchases active chemical ingredients and licenses technology from foreign parent affiliates, leaving the internal margin split determined within the global corporate structure. While the company maintains a formal related-party transaction policy and Indian regulatory frameworks require non-promoter shareholder approval for material related-party transactions, transfer pricing remains challenging to evaluate externally. The company held its 68th annual general meeting on August 19, 2026, to consider the fiscal 2026 accounts and approve a final dividend of ₹60 per share, with the record date set for August 5, 2026, and payment scheduled on or after September 3, 2026.23
Capital deployment: Major domestic capital expenditure proposals must compete for allocation within a parent group that prioritized litigation settlements and debt reduction throughout 2026.12
Portfolio scope: Commercialization timelines for new active ingredients and seed traits remain subject to global parent pipeline prioritization.
These structural arrangements reflect typical multinational subsidiary governance rather than regulatory impropriety. However, value transfer through intra-group pricing and technology royalties represents an opaque mechanism for public investors. Evaluating true minority value capture would require granular historical disclosures breaking down royalty payments, service fees, and raw material purchase prices paid to parent entities as a percentage of total revenue.
The capital allocation record, without adjectives
Bayer CropScience's capital allocation history demonstrates consistent conservatism. The enterprise operates virtually debt-free, funds working capital from internal accruals, and avoids debt-financed acquisitions. Capital expenditure focuses primarily on formulation plants and seed processing facilities rather than capital-intensive active ingredient synthesis, supporting elevated returns on capital employed.1
However, capital efficiency has come at the expense of aggressive reinvestment. The business has not pursued large domestic acquisitions, major greenfield manufacturing expansions for global exports, or diversification into adjacent market segments. Instead, earnings are predominantly distributed as dividends. This dynamic reflects both parent-level capital constraints and a domestic agrochemical market offering limited acquisition targets capable of matching the subsidiary's historical return on capital.
A transaction during the June 2026 quarter illustrated this optimization strategy: the company divested marketing rights for specific formulated products, generating a one-time gain.20 Asset monetization of product rights represents portfolio rationalization rather than expansion, consistent with executive focus on return optimization over top-line scale.
For minority investors, Bayer CropScience operates as a capital-efficient, conservatively managed enterprise operating within defined strategic boundaries. Executive management prioritizes cash generation, return metrics, and balance sheet protection rather than broad volume growth, making non-promoter shareholder voting on related-party transactions the primary minority governance mechanism. Shifting this investment trajectory toward higher compounding would require substantial capital reinvestment—such as major domestic manufacturing expansion or strategic acquisitions—signaling a transition from cash distribution to business expansion.
That requirement focuses attention on potential future growth catalysts across the business.
IX. Dark Horses & Optionality: Better Life Farming, Digital Agronomy, & Biologicals
Every agri-input company in India eventually encounters the same structural barrier: the last mile. India features over a hundred million operational holdings, overwhelmingly small, distributed across districts with underdeveloped infrastructure, limited extension services, and village retailers who serve simultaneously as vendor, credit provider, and default agronomist. A sales force cannot directly cover this fragmented base; access depends on local retailers whose brand loyalty remains tied to commercial margin structures.
Better Life Farming represents Bayer's effort to construct a distribution channel over which it exercises partial control. Operated alongside development-finance and input partners, the model establishes village-level centers managed by local entrepreneurs, farmer producer organizations, or agriculture graduates who supply inputs, advisory support, and services to surrounding farms. Globally, the alliance surpassed one million smallholders across multiple jurisdictions by mid-2023.
The strategic rationale extends beyond simple channel expansion. While a conventional retailer stocks products based on immediate turnover, a Better Life Farming operator follows Bayer agronomic protocols and leverages the brand's technical credibility. If executed successfully, this model converts transactional sales into advisory relationships, creating a more favorable environment for commercializing premium products.
However, commercial evidence confirming this transition remains limited. Reach metrics—such as centers launched, farmers engaged, or application downloads—reflect activity rather than monetized revenue. Bayer does not disclose the proportion of domestic revenue routed through these centers, the incremental margins generated, or whether participating farmers purchase higher volumes of proprietary products relative to traditional channels. Until such granular data is provided, investors must evaluate the initiative as an emerging distribution concept rather than a verified competitive advantage. Historically, Indian agri-input firms have frequently launched village engagement programs without achieving durable market share gains, as underlying dealer economics continue to dominate last-mile distribution.
The digital agronomy strategy displays similar characteristics. A digital advisory platform registering over five million users provides a direct information conduit to farmers that bypasses traditional retail channels, while the FarmRise One marketplace expands this framework to encompass input sales, credit access, and market linkages.14 Nevertheless, India's agricultural technology landscape includes numerous platforms with substantial user bases that have struggled to generate meaningful monetization. The critical analytical test is not registration volume, but whether digital engagement alters purchasing behavior.
Drone application services represent a more immediate operational development, driven by rising rural labor costs, the physical demands of manual spraying, and the speed and uniform coverage offered by aerial technology. Rather than selling hardware, Bayer's model focuses on training service operators—including a cohort of female drone operators.14 This approach aligns commercial incentives with high-margin chemical delivery rather than equipment manufacturing, though the business segment remains modest relative to total operating revenue.
Direct-seeded rice represents a significant agronomic shift within the portfolio. Traditional paddy cultivation relies on raising seedlings in nurseries before manual transplantation into flooded fields. While flooding suppresses weed growth, it requires substantial water, generates methane under anaerobic soil conditions, and depends heavily on seasonal labor.
Direct-seeded rice eliminates standing water by planting seeds directly into unflooded soil, reducing water consumption, labor requirements, and methane emissions. However, unflooded fields allow weed populations to expand rapidly, requiring effective herbicide protocols paired with compatible seed genetics—the specific combination Bayer commercializes. Under its DirectAcres initiative, Bayer targeted expanding direct-seeded rice across one million hectares in India by 2030 to support over two million smallholders, citing potential reductions of up to 40% in water usage and up to 45% in greenhouse gas emissions.22 The company reported that 99% of participating farmers established viable crops, with 75% achieving higher returns on investment compared to traditional transplantation. Direct-seeded techniques accounted for approximately 11% of Indian rice cultivation at the program's launch.22
This initiative aligns agronomic sustainability with commercial incentives: expanding direct-seeded rice acreage creates recurring demand for specialized seed and companion herbicide programs on India's largest crop by cultivated area. If adopted at scale, it provides a recurring revenue stream tied directly to crop establishment.
Nevertheless, multi-year adoption targets announced years in advance represent strategic goals rather than guaranteed financial outcomes. Bayer's domestic history includes regulatory suspensions of herbicide-tolerant cotton and subsequent price control decrees that eliminated trait fees. While direct-seeded rice operates outside genetically modified regulatory constraints, its long-term value capture depends on maintaining premium realizations for proprietary chemistry before generic alternatives enter the market.
Biological inputs—comprising microbials and naturally derived crop protection compounds—further expand the company's optionality. These products face lower regulatory hurdles and align with residue limits required for agricultural exports. However, biologicals currently represent a fragmented domestic market characterized by low entry barriers, intense competition, and an absence of established brand pricing power.
Collectively, these dark horse initiatives offer plausible growth mechanisms but lack verified revenue conversion. Until Bayer discloses segmented financial performance demonstrating that direct-seeded rice or digital channels drive accelerated top-line growth, valuation models should treat these platforms as unpriced optionality rather than core compounding drivers.
This sets up the formal evaluation of the company's competitive position.
X. Helmer's 7 Powers & Porter's 5 Forces Analysis
Strategic frameworks are useful only when applied with unvarnished rigor, including low scores where warranted. Applied to Bayer CropScience Limited, the striking takeaway is how few of the classic power sources are robust, and how heavily the business relies on just two of them.
Hamilton Helmer's 7 Powers
Cornered Resource — moderate, and rented rather than owned. Bayer CropScience's access to its parent's global discovery pipeline is a genuine asset that no domestic competitor can replicate: designing a novel mode of action requires a decade of development and a research budget far beyond what Indian peers can contemplate. However, the Indian listed entity does not own this resource; it merely licenses it. Furthermore, its ultimate value depends on the global parent continuing to fund discovery at scale — which, under a strategy of fewer but stronger bets alongside an explicit deleveraging priority, remains an active question rather than a guaranteed assumption.12 A cornered resource licensed from a controlling shareholder is fundamentally weaker than one owned outright.
Process Power — moderate. Formulation is far more technical than simple mixing. Converting an active ingredient into a stable suspension that survives two seasons in a hot warehouse, mixes cleanly in hard water, and adheres to a leaf requires genuine chemical engineering. This process capability explains why a Bayer formulation and a generic containing the identical active ingredient often perform differently in the field. Bayer's domestic manufacturing footprint supports both Indian sales and internal group exports.3 The caveat is that formulation expertise diffuses over time — domestic formulators have steadily closed the gap — and manufacturing assets carry local regulatory vulnerabilities, as the Himatnagar operational suspension demonstrated.5
Branding — high, and the most durable power in the portfolio. In an input market where farmers cannot chemically verify bottle contents and counterfeit products present a constant hazard, a century-old brand endorsed by local retailers commands a consistent price premium. This power has proven the most resilient across the company's operating history. Its limitation, however, is clear: while brand equity protects a premium over unbranded generics, it cannot prevent generic competitors from taking volume at lower price points, nor did it shield trait licensing fees from administrative elimination.
Scale Economies — moderate. A dense field force and extensive distribution footprint amortize marketing and agronomic demonstration costs across a larger revenue base than subscale competitors can match. Yet agrochemical distribution in India lacks the self-reinforcing returns of true scale economies, as expanding into a hundredth district carries roughly the same incremental cost as entering the tenth.
Switching Costs — low in crop chemistry, moderate in hybrid seeds. This structural asymmetry represents a critical operational distinction within the business model. It indicates that the seeds division possesses a higher-quality economic moat than the crop protection portfolio.
Network Economies — essentially absent. A farmer's purchase decision gains little direct value from other growers adopting the same product, outside of local village word-of-mouth. While digital platforms could theoretically generate a data network effect among participating farmers, disclosed metrics provide no evidence that this capability exists at commercial scale.
Counter-Positioning — absent, operating instead in reverse. Counter-positioning occurs when an entrant adopts a business model that incumbents cannot copy without damaging their existing profits. Here, Bayer is the established incumbent, while low-cost domestic formulators act as counter-positioned challengers. These domestic players operate with overhead structures and margin expectations that Bayer cannot match without compromising its own economic model.
In summary, the enterprise holds two strong powers in brand equity and seed switching costs, two moderate and rented or diffusing powers in its cornered resource and process capabilities, and three powers that are absent or structurally adverse. This combination defines a defensible franchise rather than an unassailable moat.
Porter's Five Forces
Buyer power — high, and structurally anchored. The end buyer is not merely the farmer, but the state acting on behalf of the agricultural sector. The administrative reduction of cotton trait fees to zero demonstrated that regulatory authorities will cap input pricing by statutory decree when deemed necessary. Commercial positioning provides little leverage against a buyer with legislative authority.
Threat of substitutes — high. Post-patent generic products from domestic and Chinese manufacturers offer direct chemical substitutes across the majority of the crop protection portfolio. Additionally, biological alternatives introduce a secondary substitution path over time.
Supplier power — low, subject to transfer-pricing governance. Sourcing key active ingredients from foreign parent affiliates eliminates conventional third-party supplier leverage. However, low supplier power and dependence on a controlling parent represent the same reality: transfer prices are established internally, requiring minority shareholders to rely on regulatory governance frameworks rather than open-market competition.
Competitive rivalry — intense across two distinct fronts. Premium market share is contested by multinational peers, while volume at lower price points is undercut by domestic formulators. Sharp revenue contractions among top-performing peers during the recent destocking cycle demonstrate that industry rivalry is being fought aggressively on price.15
Threat of new entrants — low for innovators, unprotective against generic formulators. Registering a novel active ingredient in India requires extensive field trials, data submissions, and years of regulatory processing through the Central Insecticides Board and Registration Committee. While this creates a substantial barrier against new life-science innovators, it does not impede generic formulators from commercializing existing off-patent molecules. Consequently, the regulatory barrier blocks potential innovators while leaving the company exposed to generic competition.
This structural analysis reinforces the historical record: Bayer CropScience Limited is a high-return enterprise possessing genuine but bounded advantages, operating in an industry where customers, state regulators, and patent expiration continuously erode pricing power. The business model generates strong returns on existing capital while growing at a measured pace.
The narrative next examines the specific operational risks facing the enterprise and how management has addressed them.
XI. Current Risk Radar & Earnings Call Q&A Stress Test
Every June, the Indian agri-input sector hinges on the India Meteorological Department’s monsoon onset forecast, which shapes the sowing decisions of a hundred million farmers within days. An early, evenly distributed monsoon drives robust kharif demand, while a delayed onset or an ill-timed mid-season dry spell compresses both cultivated acreage and application windows.
For Bayer CropScience, weather is not a secondary variable but the principal driver of annual performance. Management explicitly acknowledged this dependency, attributing the strong June 2025 quarter partly to an early monsoon onset and the full-year fiscal 2026 results to kharif season disruptions.92
The risks that actually matter
Weather and climate. Beyond annual monsoon variance, increasing rainfall volatility presents a structural challenge. Heavy downpours concentrated over fewer days followed by extended dry spells shorten the viable window for crop protection applications. This operational constraint mechanically reduces volume demand regardless of underlying pest pressure, eroding the company's addressable application window over time.
Chinese oversupply and price erosion. The global inventory correction that began in late 2022 remains a major industry headwind, driven by excess active ingredient capacity in China and channel destocking worldwide.15 This overcapacity exerts direct pricing pressure on Bayer's post-patent portfolio, forcing a choice between margin compression and market share loss. Although management cited stabilizing input costs during fiscal 2026, lower raw material prices also enable generic competitors to undercut finished product pricing across the retail network.
Regulatory action on molecules. Sudden regulatory intervention represents an unhedgeable tail risk for Indian agrochemicals. State authorities have demonstrated a willingness to restrict key active ingredients via administrative notification—evidenced by the restriction of glyphosate applications strictly to licensed pest control operators17—and have previously drafted proposals for broad product bans across the industry.16
Genetically modified regulatory constraints. The long-standing freeze on new genetically modified crop approvals limits the expansion of integrated seed, trait, and chemical product packages. As a result, the domestic subsidiary remains unable to commercialize the parent group's full international product pipeline.
Related-party and transfer-pricing dynamics. Sourcing active ingredients and intellectual property from parent affiliates creates ongoing disclosure and value-allocation risks. Because internal pricing determines profit sharing between the parent group and the listed domestic entity, adjustments to intra-group transfer rates can alter local earnings independently of domestic market demand.
Site-level environmental compliance. Operational disruptions at chemical manufacturing facilities represent an active compliance risk. As demonstrated by the temporary shutdown order at the Himatnagar formulation plant, state pollution control boards maintain statutory authority to halt operations immediately.5
Stress-testing the narrative across consecutive disclosures
Evaluating management credibility requires analyzing corporate disclosures sequentially to test whether operational messaging remains consistent across reporting periods. The company publishes quarterly financial releases and investor presentations through its official relations channels, with quarterly earnings transcripts tracked by market data services.2425 Comparing four consecutive reporting cycles reveals how management's performance narrative evolved as top-line momentum moderated.
In August 2025, reporting a 17% revenue increase for the June 2025 quarter, management emphasized volume expansion driven by higher corn seed and Roundup sales, supported by an early monsoon and new product introductions.9 In February 2026, following a third-quarter profit recovery from a low comparison base, the commentary shifted toward favorable product mix, lower input costs, and working capital discipline as key drivers of operational resilience.13 By May 2026, after reporting full-year revenue growth under 4% alongside a 21% rise in pre-tax profit, management attributed performance to strategic channel management and cost discipline over volume expansion, while acknowledging softness in hybrid corn seeds.2 In August 2026, reporting a 4.2% top-line decline alongside a 15.4% increase in net profit for the June 2026 quarter, management again cited execution discipline and adverse weather conditions.20
A sequential evaluation of these disclosures highlights three key analytical findings:
First, management's growth narrative transitioned from volume expansion to channel discipline and cost management as top-line growth decelerated. While prioritizing channel health over aggressive discounting is a rational strategy, attributing top-line weakness to deliberate volume restraint becomes difficult to verify unless channel inventory and trade receivables decline proportionally while market share holds steady.
Second, weather conditions were cited to explain both outperformance and underperformance. Management pointed to an early monsoon to explain strong quarterly growth and subsequently cited adverse weather patterns to account for revenue contractions. Although agrochemical demand is inherently weather-dependent, relying on climate variance as a primary explanation provides limited insight into underlying market share trends.
Third, recent profit expansion relied primarily on margin discipline and non-operating factors rather than top-line revenue growth. The disconnect between flat full-year revenue and expanding pre-tax profit in fiscal 2026—further underscored by the June 2026 quarter, where net profit rose despite falling sales due to a one-time product rights divestment gain and an inventory provision reversal—indicates that recent earnings growth reflected cost controls and balance sheet adjustments.220 While operational efficiency improves near-term profitability, it does not demonstrate a recovery in underlying customer demand.
From an investor perspective, addressing these analytical uncertainties requires expanded disclosures across four key areas: segment-level revenue and margin breakdowns for crop protection versus seeds, multi-year trends in parent royalty and service fees, channel inventory levels alongside working capital metrics, and strategic plans for deploying the company's unleveraged balance sheet in a consolidating domestic market. Granular reporting on these operational parameters would allow market participants to evaluate Bayer CropScience's competitive trajectory on empirical data rather than executive narrative.
This sets up the two competing readings of the underlying enterprise.
XII. Bull vs. Bear Case
Two investors can examine this identical set of facts and reach opposite conclusions without either side misrepresenting the evidence. Here is the strongest, most objective version of each argument.
The bull case
Start with what is undisputed. Bayer CropScience earns nearly 30% on capital employed with virtually no debt, generating sufficient cash to distribute a substantial dividend within a resilient end market.1 Indian agriculture must continuously raise yields on a fixed and fragmenting land base, making chemical crop protection load-bearing infrastructure.
The bull case centers on operational resilience and operating leverage. Fiscal year 2025–26 demonstrated that the company can expand profitability sharply even during a sluggish top-line environment, with pre-tax profit rising 21% on top-line growth of under 4%, followed by further profit expansion in the subsequent quarter despite falling sales.220 This demonstrates a flexible cost structure and a management team willing to prioritize returns over unprofitable volume growth. When global destocking concludes and the agrochemical cycle turns, that operating leverage works in reverse, converting modest revenue gains into rapid profit growth.
Second, product mix is improving even where top-line volume remains steady. DeKalb hybrid corn carries genuine switching costs, the direct-seeded rice platform attaches recurring branded chemistry to India's largest crop by area if it achieves its 2030 adoption target,22 and the co-formulation pipeline provides a mechanism to outrun generic commoditisation. In a market where product quality cannot be verified visually, brand equity remains the most durable asset in Indian farm inputs—one that domestic generic formulators cannot replicate.
Third, an unleveraged balance sheet is a strategic weapon during an industry downturn. Peers carrying debt—particularly export-oriented players whose revenues contracted sharply during the destocking cycle15—possess far less financial maneuverability. Bayer CropScience can absorb cyclical troughs without taking on balance-sheet risk.
Fourth, parent-level overhang has receded. The U.S. Supreme Court's June 2026 preemption ruling, the proposed class settlement, and the Ruveon reorganization together mark the first period since 2018 in which global litigation risks have moved in Bayer AG's favour.1011 A parent group no longer managing acute crisis is better positioned to support growth markets, and executive leadership has publicly designated India as a priority market by 2030.14
The bear case
The bear case does not dispute the return metrics; it questions the underlying growth engine to which those returns are attached.
The core challenge is top-line deceleration across every major time horizon, with annual sales growth slowing from roughly 7% over ten years to about 6% over five years and 3% over three years.1 This is not merely a cyclical dip, but a multi-year structural trend. Earning high returns on a stagnant capital base converts an equity investment into a fixed-income-like yield instrument with equity-market downside.
Second, the economic moat has been breached before in a defining way. The cotton trait franchise—the premier technology asset the group brought to India—saw its licensing fee reduced from over ₹160 per packet to zero by administrative decree, while target pests developed resistance and 20% of cultivated acreage shifted to unapproved seed.81819 Any investment thesis assuming Indian regulators will preserve the unit economics of foreign proprietary technology runs directly counter to historical precedent.
Third, recent earnings expansion is of lower quality than headlining numbers suggest. Cost containment, temporary product mix shifts, inventory reversals, and a one-time gain from divesting marketing rights do not constitute repeatable growth drivers.20 Adjusting for these non-recurring elements reveals a fundamentally flat operating trajectory.
Fourth, structural value extraction remains unresolved. Regardless of local transfer-pricing policies, a controlling parent supplies the underlying technology and primary active ingredients, sets internal commercial terms, and captures nearly three-quarters of every dividend distribution. Minority shareholders hold a residual claim with zero influence over transfer pricing or capital reinvestment decisions.
Fifth, maintaining a debt-free balance sheet while distributing the majority of earnings during an era of industry consolidation signals that management either sees few attractive domestic reinvestment opportunities or lacks the mandate to execute them. Neither interpretation supports characterizing the company as an independent compounder.
Reconciling them
Applying the analytical frameworks of economic powers and competitive forces reconciles these opposing viewpoints. Where Bayer's competitive advantages are structural and locally defensible—specifically brand equity and hybrid seed switching costs—the bull case holds. Where advantages are rented or externally controlled—such as parent pipeline access and formulation know-how—the outcome depends entirely on decisions made in Leverkusen. Where forces are hostile—such as administrative buyer power, generic substitution, and low-cost domestic competition—the bear case dominates, backed by historical evidence.
The resolution is not that the truth lies in the middle, but that both arguments describe different facets of the same underlying asset: a capital-efficient, cash-generative, low-risk franchise bound by a capped top-line growth rate and persistent regulatory policy risks. The divergence between bull and bear is ultimately a debate over valuation rather than business reality.
XIII. Epilogue & The 2030 Horizon
Standing in a field in Punjab in June, an observer can see the entire strategic argument playing out at once. The water table has fallen for decades, labor for transplanting is scarce and expensive, and stubble burning fills the sky each autumn. The state demands reduced water consumption and lower emissions, while farmers require profitable yields. Operating at the intersection of these competing pressures is a business selling a seed and herbicide package designed to cultivate rice without flooding fields.
That dynamic captures the realistic 2030 outlook for Bayer CropScience in India. The narrative is not about German chemistry dominating a market, but whether a global input provider can commercialize integrated systems within an agricultural sector forced to adapt to water scarcity, rising labor costs, and climate volatility—all while operating under a regulatory framework that has previously eliminated key technology royalties.
India's broader agricultural trajectory supports the demand side of this equation. Policy priorities have shifted from basic calorie security toward farm income growth, higher-value crops, export competitiveness, water efficiency, and strict residue compliance for international markets. Each of these structural trends favors technically differentiated inputs over commodity formulations—presenting, in principle, an advantageous environment for Bayer's business model.
Whether the company successfully translates this environment into sustained financial performance remains a question with verifiable parameters. The DirectAcres goal of reaching one million hectares by 2030 establishes a specific, dated target against which execution can be measured.22 Expanding the Better Life Farming footprint offers a similarly trackable distribution metric. Conversely, what remains unquantified in public disclosures is whether these initiatives generate meaningful revenue expansion. The company does not break out segment-level revenue and margins, sales linked to direct-seeded rice programs, or the share of revenue directed to parent royalty and service fees. Until such disclosures are provided, investors are left evaluating strategic ambitions without full financial visibility.
Consequently, assessing the company's long-term trajectory depends on monitoring a concise set of key metrics:
Full-year revenue growth alongside gross margin direction. Evaluating multi-year revenue alongside gross margin stability provides a clearer signal than quarterly sales—which fluctuate with monsoon timing—or net profit growth, which can be temporarily boosted through cost reductions or one-time gains. Revenue growth paired with stable or expanding gross margins indicates that new, differentiated products are driving performance. Conversely, top-line growth accompanied by margin compression suggests volume is being incentivized through lower pricing, while profit expansion on flat revenue—the pattern seen in fiscal 2026—reflects cost discipline that cannot compound indefinitely.
The corn seed franchise. The DeKalb business accounts for the primary switching costs within the portfolio, representing the principal remaining value from the Monsanto acquisition following the administrative elimination of cotton trait licensing fees. Management flagged softer corn seed sales during the March 2026 quarter.2 Whether the corn segment returns to sustained growth serves as a direct test of the broader seed investment thesis.
Working capital days and channel inventory. Tracking working capital trends provides an empirical test of management's stated emphasis on channel discipline over volume growth. If the company is actively restraining channel stocking, trade receivables and inventory levels should decline relative to stable revenue. Elevated working capital alongside contracting sales would indicate underlying demand weakness rather than intentional channel management.
Over the next five years, two distinct trajectories remain plausible. In one scenario, global destocking completes, the direct-seeded rice platform scales, hybrid corn demand recovers, and a parent group past its primary litigation hurdles reinvests in its Indian division. In the alternative scenario, top-line growth remains in the low single digits, regulatory authorities intervene on additional active ingredients, and the enterprise continues its historical trajectory: operating as a capital-efficient, cash-generative, slowly growing business controlled by a foreign parent.
While historical performance cannot guarantee future outcomes, the empirical record of the past decade demonstrates that the second scenario represents the baseline the company has consistently delivered. Underwriting the expansion scenario requires tracking concrete performance indicators rather than relying on strategic narrative alone.
References
-
Bayer CropScience Ltd — Financial ratios, growth and shareholding — Screener.in ↩↩↩↩↩↩↩↩↩↩
-
Bayer CropScience India FY26 Revenue Rises to ₹56,750 Million; Profit Before Tax Grows 21% — Global Agriculture, 2026-05-27 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Bayer CropScience Ltd — Company Summary and Profile — IIFL Capital / India Infoline ↩↩↩↩↩↩↩
-
Controversies: Bayer 2024 — ChemScore / ChemSec, 2024-10 ↩↩↩↩
-
NCLT okays merger of Monsanto India with Bayer CropScience — The Asian Age, 2019-09-14 ↩↩
-
CCI Approves Conditional Acquisition Of Monsanto By Bayer — Mondaq, 2018 ↩
-
End of the Road for Bt Licensing Royalties in India — SpicyIP, 2020-04 ↩↩↩↩↩↩
-
Bayer CropScience India Reports 17% Growth in Q1 FY 2025-26 Revenue — Global Agriculture, 2025-08-08 ↩↩↩↩↩↩
-
Bayer's Supreme Court Win in Roundup Case No 'Silver Bullet' — Claims Journal, 2026-06-29 ↩↩↩↩
-
Bayer Fuels Break-Up Talk as Roundup Business Put Into Separate Unit — Insurance Journal, 2026-07-02 ↩↩↩
-
Bayer promises 'first-to-the-farm' innovation as shareholders push back — AgNavigator, 2026-04-24 ↩↩↩↩
-
Bayer CropScience Q3 FY26 result analysis — MarketsMojo, 2026-02 ↩↩↩
-
P I Industries Q2 FY26: Profit Decline Continues Amid Agrochemical Headwinds — MarketsMojo, 2025-11 ↩↩↩↩↩
-
India Proposes a Ban on 27 Agricultural Pesticides — ChemLinked, 2020-05 ↩↩↩
-
Centre restricts use of common weedicide glyphosate citing health hazards — Down To Earth, 2022-10 ↩↩
-
Resistance development in pink bollworm against Bt cotton and its establishment as mid-season pest in India — PMC / National Library of Medicine ↩↩
-
Illegal HtBt cotton acreage continues to rise — Telangana Today ↩↩
-
Bayer CropScience Q1 FY27 Results: Net Profit Up 15% to ₹321 Cr Despite Revenue Dip — Trade Brains, 2026-08-06 ↩↩↩↩↩↩↩
-
Bayer Announces Key Leadership Changes — PR Newswire India, 2023-08-30 ↩↩↩↩
-
Bayer aims to bring sustainable rice cultivation to 2M farmers in India — Agriculture Dive ↩↩↩↩
-
Bayer CropScience declares ₹60 final dividend for FY26; 68th AGM on August 19 — ScanX, 2026 ↩
-
Bayer CropScience Limited — Investor Relations — Bayer India ↩
-
Bayer CropScience Ltd — shareholding and transcript tracker — Trendlyne ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube