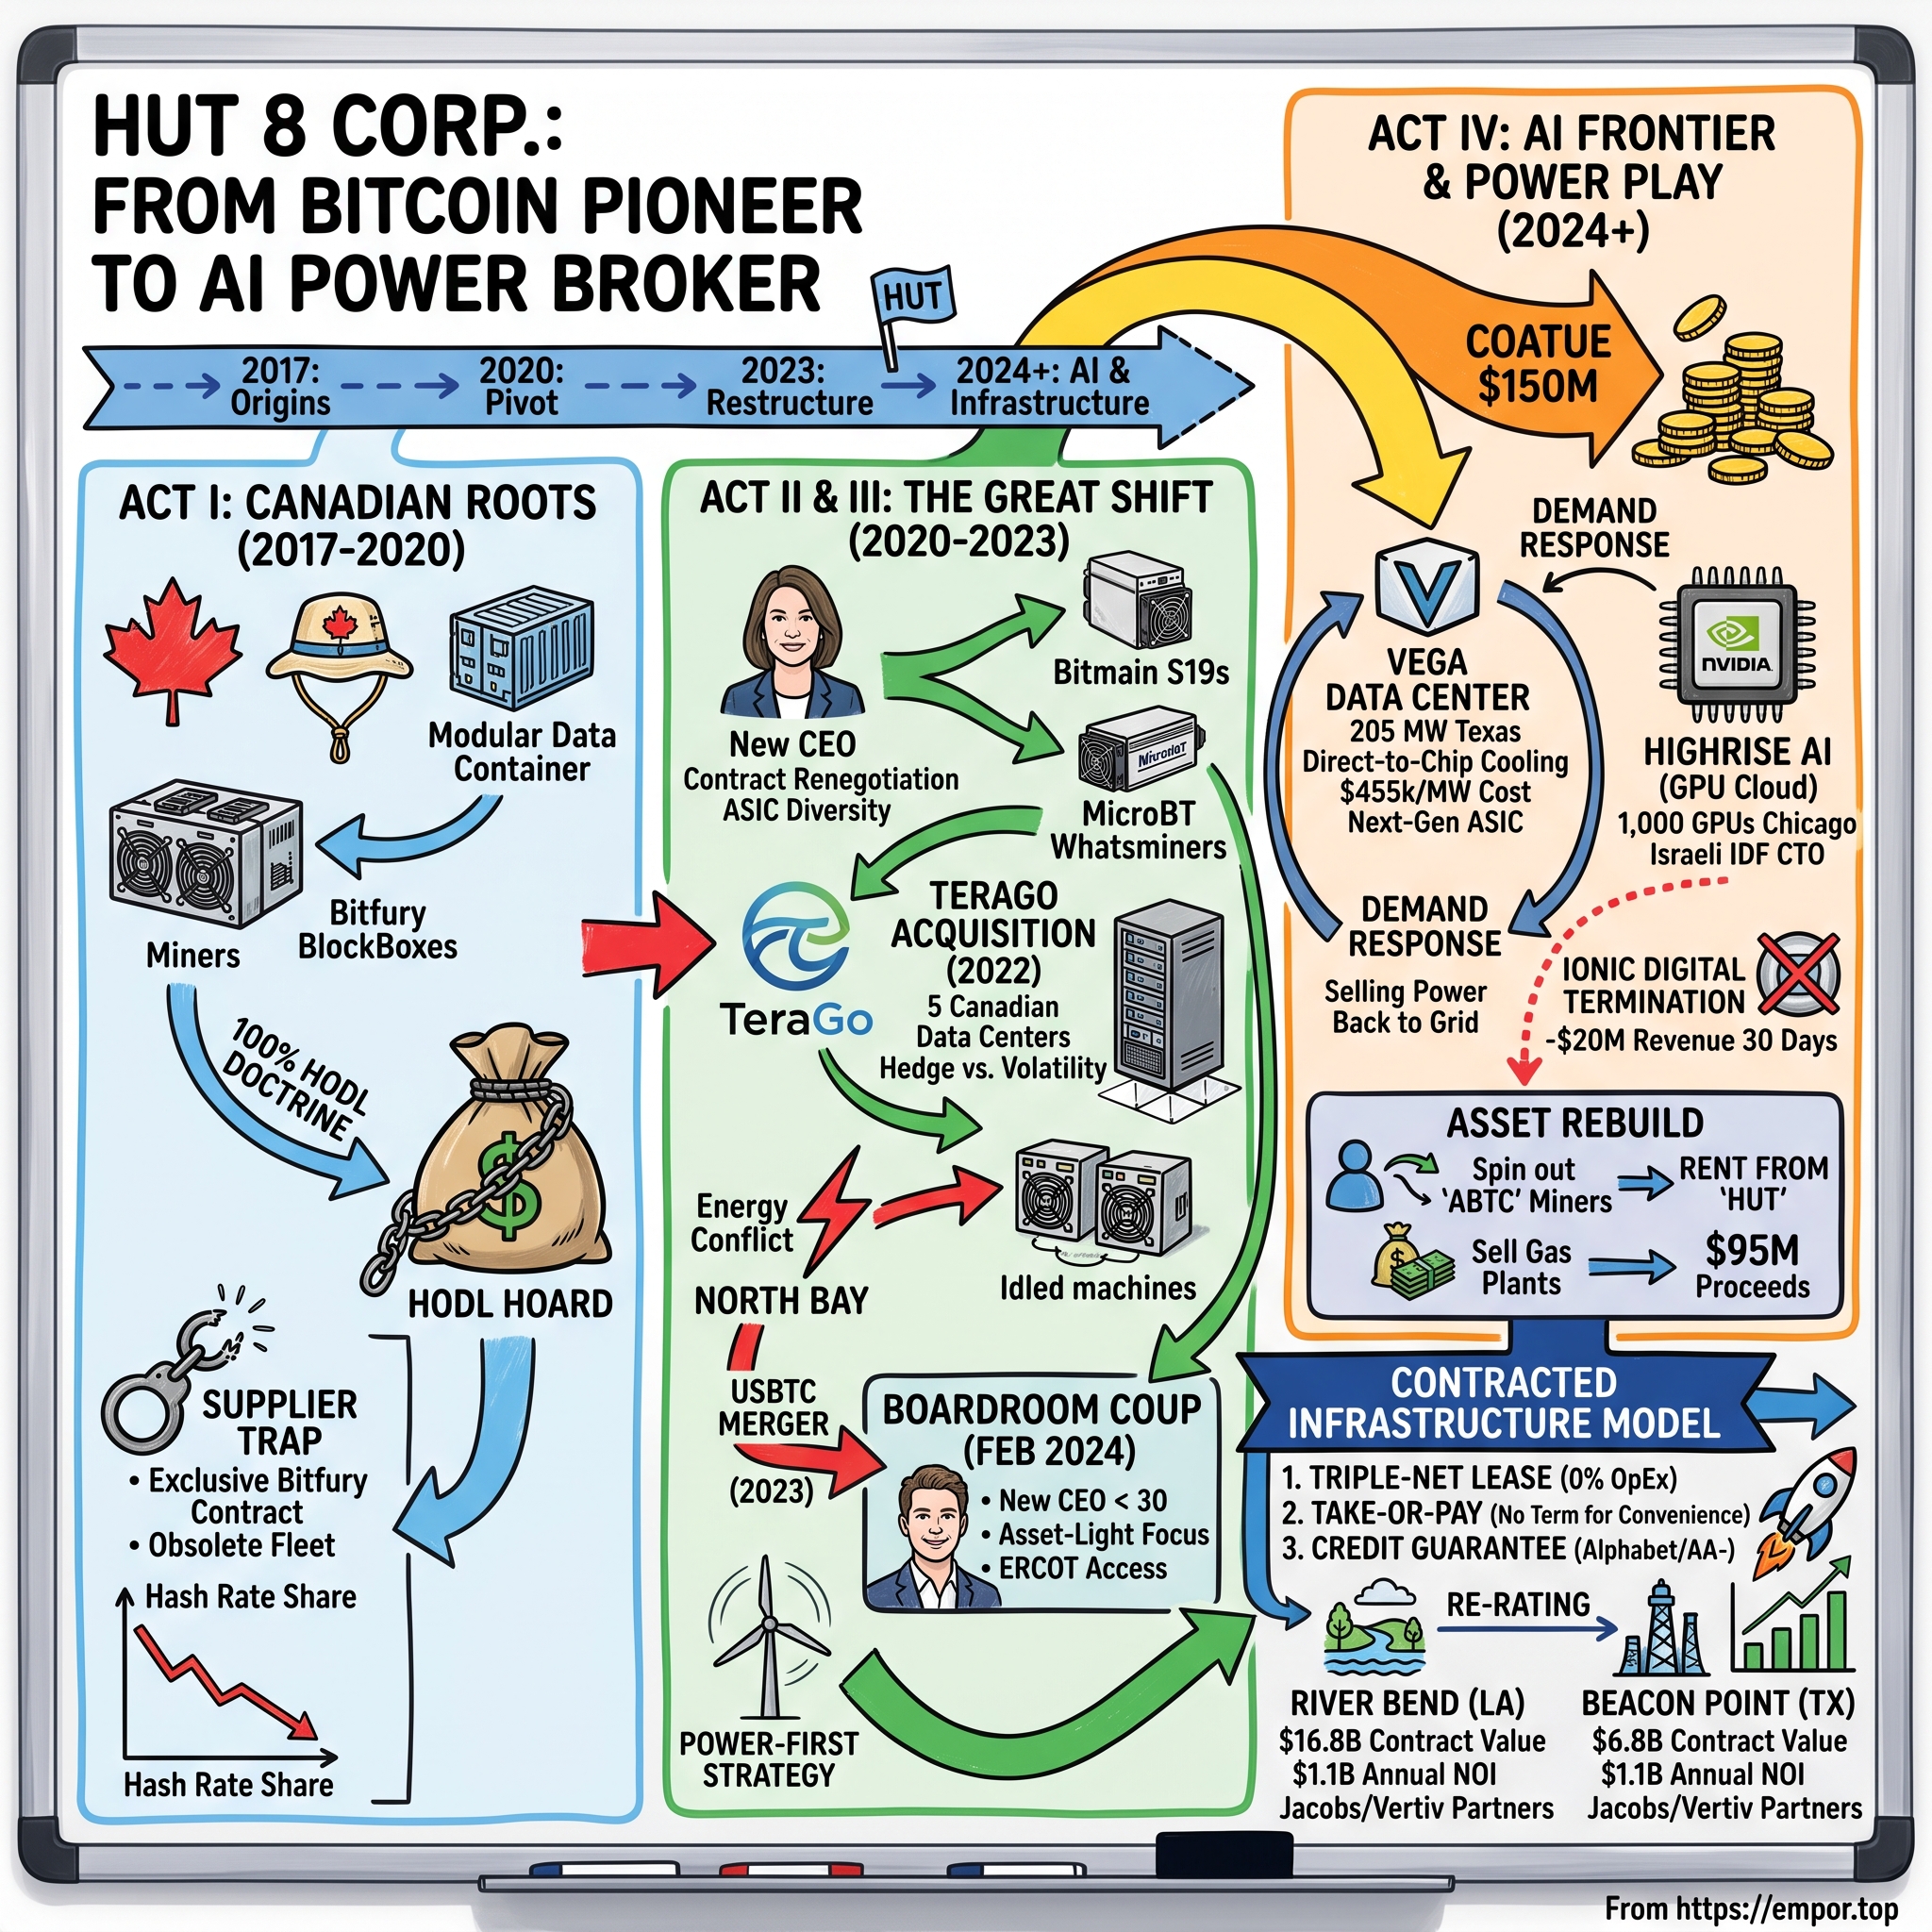
Hut 8 Corp. (HUT): The Great Infrastructure Transformation
I. Introduction & Episode Roadmap
On the morning of December 17, 2025, a company that most institutional investors still filed under "Bitcoin miner" announced a fifteen-year lease worth $7.0 billion. The tenant was Fluidstack, an AI cloud company few outside the GPU-brokerage world could describe. The site was a campus in Louisiana called River Bend. And the entity standing behind the rent payments — the credit that made the whole structure financeable — was Google.1
The stock rose roughly 25% that day.2 Six months later, in the spring of 2026, the same company announced a second lease, this one for 352 megawatts of IT capacity with a base contract value of $9.8 billion, and the stock jumped again — this time more than 30%.3 Somewhere in that stretch, Hut 8 Corp. stopped being priced like a Bitcoin miner and started being priced like something else entirely.
The question is whether it is something else entirely.
The Hook
Consider the path. A Canadian Bitcoin miner founded in 2017 on a partnership with Bitfury, running warehouses full of machines in Drumheller and Medicine Hat, Alberta. A rigid corporate philosophy of holding every satoshi it mined. A brutal crypto winter that turned that philosophy into a liquidity problem. A merger of equals with a scrappy American operator. A short-seller report that erased nearly a quarter of the market capitalization in a single session.4 A CEO change three weeks later.5 A $150 million convertible note from Coatue Management.6 The purchase of four bankrupt Ontario gas plants and their resale, two years on, to a Canadian utility.7 The spin-out of the entire self-mining fleet into a separate Nasdaq-listed company co-founded by Eric Trump.8 And now a multi-gigawatt AI data center development pipeline financed with investment-grade project bonds.
That is an enormous amount of corporate motion for roughly eight years of existence. The generous reading is that a management team correctly identified that its actual asset was never Bitcoin — it was electricity, land, and permits — and restructured relentlessly around that insight. The skeptical reading is that this is a company that has changed its business model roughly once every eighteen months, and that each new model has been announced with the same confidence as the one it replaced.
Both readings deserve a hearing.
The Core Paradox
Here is the structural tension that has defined Hut 8 for its entire life as a public company, and it is worth stating plainly because everything downstream flows from it.
Bitcoin mining and AI data centers consume the same fundamental input — cheap, abundant, interconnected electrical power — but the capital markets value them on completely different logic. A Bitcoin miner is valued on hashrate, on the spot price of Bitcoin, and on the market's mood about crypto. Its revenue is a lottery ticket denominated in a volatile asset, redrawn every ten minutes. Nobody assigns a mining company a long-duration multiple, because nobody can underwrite what Bitcoin will trade at in 2032.
An AI data center landlord is valued on entirely different terms: contracted revenue, tenant credit quality, lease duration, and the spread between the cost of capital and the yield on invested capital. It is, in financial substance, closer to a triple-net REIT or a toll road than to a technology company. If a tenant with a AA+ credit rating standing behind it commits to fifteen years of escalating rent, that stream can be modeled, rated, and levered.
Same electron. Radically different multiple.
Hut 8's entire strategy since early 2024 has been an attempt to arbitrage that gap — to take power capacity that was earning mining economics and re-point it at contracted infrastructure economics, while retaining exposure to the mining upside through an equity stake rather than an operating business. Whether that arbitrage is a durable competitive advantage or simply a well-timed ride on the largest capital expenditure boom in modern computing history is the central investment question, and it is not yet settled.
Episode Roadmap
The story breaks into five acts. The legacy era from 2017 to 2022, when Hut 8 was a Canadian miner with a HODL religion and a first, tentative step into traditional data centers. The rise of U.S. Bitcoin Corp, an asset-light operator with a very different philosophy about who should own power plants. The convergence and crisis of late 2023 into early 2024 — the merger, the short report, the leadership change. The Genoot era of restructuring: distressed power assets, Coatue's capital, and a GPU business. And finally the structural separation of mining from infrastructure, and the emergence of Hut 8 as a developer of AI campuses at a scale that would have seemed absurd to describe in 2022.
We will end where every honest analysis of a transformation story has to end: with the specific things that would have to be true for this to work, and the specific things that would falsify it.
 Subscribe on LinkedIn
II. Legacy Hut 8 & The HODL Philosophy (2017–2022)
In December 2017, Bitcoin was in the final, feverish weeks of a parabolic run toward $20,000. Retail brokerages were crashing under signup volume. And in Canada, a partnership was announced that would, in its founders' framing, "recentralize" Bitcoin mining away from China and toward North America.9 Hut 8 Mining Corp. was born out of a deal with Bitfury, the Amsterdam-headquartered mining hardware and infrastructure group, which supplied rigs and took a substantial equity position — at one point owning roughly 47.6% of the company.10
The logic was elegant for its moment. Alberta had two things Bitcoin mining wanted: stranded, inexpensive power in a deregulated market, and a climate cold enough that ambient air did most of the cooling work for free. Hut 8 built at Drumheller, a badlands town best known for dinosaur fossils, and at Medicine Hat, a city that had run its own municipal gas utility for over a century. The two Alberta sites together represented more than 100 megawatts of capacity — 67 MW at Medicine Hat and 42 MW at Drumheller.10 For 2018, that was genuinely industrial scale.
The Religion of HODL
What distinguished Hut 8 from its peers was not its engineering. It was its treasury policy.
Most miners of that era sold a portion of production each month to cover electricity, payroll, and debt service. Hut 8, particularly under CEO Jaime Leverton, who took over in 2020, made a doctrinal commitment to the opposite: mine Bitcoin and keep it. Fund operations from equity issuance, debt, and credit facilities rather than from selling production. Let the balance sheet accumulate coins.
During a bull market, this was a superb trade — and, more importantly, a superb product. Hut 8 became a leveraged, high-beta proxy for Bitcoin itself, wrapped in a listed equity that pension funds and retail brokerage accounts could actually buy at a time when spot Bitcoin ETFs did not exist in North America. Investors who wanted crypto exposure inside a conventional account could buy HUT and get more than one-for-one participation in Bitcoin's move. The stock ran hard through 2021, and the company added a Nasdaq listing in June 2021 alongside its Toronto listing, opening the register to American institutional capital.
It is worth pausing on why this worked, because the mechanism matters for understanding what broke.
A HODL miner is running an implicit carry trade. It is short cash — it must pay for power and labor in dollars every single month — and long an extremely volatile asset it refuses to sell. As long as the asset appreciates and capital markets stay open, the trade compounds beautifully: coins accumulate, the equity re-rates, the company issues stock at the higher price to fund more machines, and the cycle repeats.
The trade breaks the moment either leg fails.
When Winter Came
Both legs failed in 2022. Bitcoin fell from roughly $69,000 in November 2021 to under $16,000 by year-end 2022. Simultaneously, energy prices spiked globally following the invasion of Ukraine, raising the single largest line item in a miner's cost structure. And crypto capital markets slammed shut after the collapses of Terra, Three Arrows, Celsius, and finally FTX.
So Hut 8 entered the worst possible configuration: rising cash costs, collapsing revenue per unit of hashrate, a treasury full of an asset that had lost three-quarters of its value, and no ability to issue equity at a price management could stomach. The coins on the balance sheet were still there — that was the point of the strategy — but selling them into a bear market to fund opex was precisely the outcome the whole doctrine existed to avoid.
The analytical lesson is not that HODL was stupid. It is that HODL is a financing decision disguised as a conviction statement. A company that refuses to sell its output has chosen to fund itself entirely from external capital markets, which means it has accepted maximum sensitivity to the exact conditions that fail together in a crypto bear market. Legacy Hut 8 had no meaningful hedging program, no long-dated power purchase agreements locking in its input cost, and no revenue stream uncorrelated to the coin. It had conviction where it needed diversification.
The First Pivot: TeraGo
Management was not blind to this. In January 2022 — before the worst of the drawdown — Hut 8 agreed to acquire the cloud and colocation data center business of TeraGo for approximately $30 million, picking up five data centers spanning Toronto to Vancouver with more than 36,000 square feet of space.1112
Read in isolation, this looks like a modest tuck-in. Read against what came later, it is the first appearance of the idea that would eventually reorganize the entire company: that Hut 8's competence might be in operating digital infrastructure generally, not in mining specifically, and that revenue from customers who sign contracts is worth more than revenue from a protocol that pays in lottery tickets.
But it was badly sub-scale. Thirty-six thousand square feet of legacy enterprise colocation is a rounding error against a hundred-plus megawatts of mining load. It generated real but small revenue, and it did nothing to fix the fundamental asymmetry: the company's energy footprint was enormous and its contracted footprint was tiny. Solving that mismatch would require a partner with a completely different theory of what a mining company should own — and one was already assembling itself across the border.
III. US Bitcoin Corp (USBTC) & The Rise of the Operators (2020–2023)
While Hut 8 was building its identity around what it held, a small group in the United States was building a business around what it could run.
U.S. Bitcoin Corp was co-founded by Asher Genoot and Mike Ho at the tail end of 2020, into a market that was about to go vertical.5 Genoot's background was not utilities or heavy industry; he came out of entrepreneurship, and by the time he became a public-company CEO he was among the youngest people running a Nasdaq-listed business of Hut 8's scale. What he and Ho brought was a specific and, in retrospect, contrarian thesis about where the money in Bitcoin mining actually sat.
The Asset-Light Heresy
The consensus miner playbook of 2021 was straightforward and capital-intensive: raise money, buy ASICs, build or buy a site, plug in, mine. Every additional exahash required proportional capital. The industry's growth was therefore a function of how much equity and debt it could absorb, and the entire sector was in a race to spend.
USBTC took a different view. The scarce resource, they argued, was not machines — Bitmain and MicroBT would happily sell machines to anyone with a wire transfer. The scarce resources were energized, interconnected sites and the operational competence to run them well. Machines are a commodity. Megawatts with a signed interconnection agreement are not, because getting one takes years of utility queue time, permitting, and substation construction.
So USBTC built a business around operating infrastructure it did not necessarily own:
Third-party site management. Running facilities on behalf of owners who had the capital but not the operational capability. This converted a capital-intensive business into a fee business.
Distressed and bankruptcy mandates. When the 2022 winter killed a generation of overleveraged miners and hosting providers, someone had to keep the machines running and the estates solvent. USBTC positioned itself as that operator, including work associated with Compute North's collapse and management of mining assets tied to the Celsius Network bankruptcy estate. This was, quietly, one of the best positions in the industry: counter-cyclical revenue earned precisely when everyone else's revenue was collapsing.
Energy arbitrage and curtailment. In deregulated markets — ERCOT in Texas above all — power prices swing violently, sometimes going negative when wind output overwhelms demand and spiking to thousands of dollars per megawatt-hour during scarcity. A Bitcoin miner is the most flexible large load ever invented: it can shut down in seconds and lose nothing but foregone revenue. USBTC leaned into software that decided, in real time, whether a given megawatt was worth more turned into hashes or sold back into the grid. Explained simply: the mining rig becomes a battery that stores value in the form of deferred consumption, and the operator gets paid by the grid for the privilege of being interruptible.
The Asset Base
By 2023, USBTC had assembled operations across Texas, Nebraska, and New York. The crown jewel — and later the flashpoint — was a 50% interest in the King Mountain joint venture in West Texas, a roughly 280 MW site acquired in the wreckage of Compute North.13
The comparison with legacy Hut 8 is instructive. Hut 8 had a pristine treasury and a Canadian footprint but no fee revenue, no U.S. grid diversity, and no proprietary operating software. USBTC had operating capability, U.S. sites, and management contracts but a thin balance sheet and no meaningful Bitcoin holdings. Each company had exactly what the other lacked, which is the textbook setup for a merger — and also, as it turned out, the textbook setup for a culture clash.
IV. The Merger of Equals & The J Capital Short Storm (Late 2023 – Early 2024)
In February 2023, with the crypto sector still in the rubble of FTX, the two companies announced an all-stock combination they described as a merger of equals. It would create a Delaware corporation named Hut 8 Corp., headquartered in Miami, listed on Nasdaq. The transaction closed on November 30, 2023.
The Stated Logic
The pitch was a balance-sheet-plus-operator story. Legacy Hut 8 contributed a treasury of self-mined Bitcoin — the accumulated output of six years of refusing to sell — along with Canadian sites and the TeraGo data centers. USBTC contributed U.S. grid access, the managed services revenue line, curtailment software, and a management team that had spent the winter running other people's assets.
Governance was split in the way merger-of-equals transactions typically are, which is to say ambiguously. Jaime Leverton remained CEO. Asher Genoot became President and joined the board.5
Anyone who has watched corporate combinations knows that a "merger of equals" with two strong-willed philosophies rarely stays equal for long. One theory of the business wins. The only question is how quickly, and how messily.
January 18, 2024
The answer arrived seven weeks after closing.
J Capital Research — a short-selling research firm with a long history of aggressive, forensic work on companies it believes are misrepresenting themselves — published a report titled "The Coming HUT Pump and Dump."4 The document was not a polite disagreement about valuation. It alleged that management was obscuring stock ownership through an undisclosed related party, that USBTC's promoters were tied to a network that included figures the SEC had previously accused of running "classic pump and dump" schemes, and that the company's assets were substantially less valuable than represented.
The most operationally specific allegation concerned King Mountain: J Capital claimed the West Texas site — the core asset USBTC had acquired from the Compute North estate — suffered from persistent shortfalls in the energy and internet connectivity required to actually mine at the capacity implied.4
The stock fell more than 23% that day.4
Hut 8 responded publicly the following day, disputing the report and characterizing it as the work of a short seller with a financial interest in the decline.[^14] That is the standard playbook, and it is not evidence of anything either way. What matters analytically is what happened next, over the following two and a half years.
What the Record Actually Shows
This is where an independent posture earns its keep, because the outcome was neither vindication nor conviction.
The promoter and related-party allegations — the most inflammatory claims in the report — did not produce a regulatory enforcement action against the company. But the King Mountain disclosure question did survive into litigation. A securities class action proceeded on Securities Act claims that Hut 8's merger materials failed to adequately disclose energy and internet-related risks at King Mountain, the Texas joint venture in which USBTC held its 50% stake before the deal closed.14
In June 2026, Hut 8 agreed to settle for $2.35 million, following a mediator's proposal accepted by both sides on May 13, 2026. The company denied wrongdoing or liability, and the settlement required court approval from U.S. District Judge Victor Marrero.1415 Reporting at the time noted the figure represented roughly 19.6% of an estimated maximum recoverable damages figure of about $12.08 million.14
How should an investor read this? Carefully. A $2.35 million settlement is immaterial to a company with over a billion dollars of parent-level liquidity — it is a rounding error, and settling avoids years of discovery and distraction. That is a rational business decision that implies nothing about guilt. But the fact that a court let the King Mountain disclosure claims survive to a settlement posture is a real data point about how the merger was communicated. The specific operational criticism at the heart of the short report was, at minimum, a legitimate enough question that it did not get dismissed.
The more durable lesson is about what short reports do to companies rather than what they prove. J Capital did not force any of the changes that followed. But it collapsed the board's tolerance for ambiguity at precisely the moment when the merger's unresolved governance question needed an answer — and the answer arrived three weeks later.
V. The Genoot Restoration & Asset Restructuring (2024)
On February 7, 2024 — twenty days after the short report — Hut 8 announced that Jaime Leverton had departed as CEO, effective immediately, and that Asher Genoot, then President and a director, would succeed her.16 The company's framing was that following the completion of the merger of equals, the board had determined the time was right to set a new strategic direction.16 Shares slid on the news.17
Strip away the corporate language and the substance is clear: the USBTC theory of the business had won, and the legacy Hut 8 theory had lost. The company that had defined itself by what it held would now be run by someone who had built his career on what he could operate.
Genoot's mandate was not subtle. Stop being a passive accumulator of a volatile asset. Become an energy-first infrastructure developer that happens to monetize power through compute. And do it while the market was still valuing the company as a Bitcoin miner in a post-halving margin squeeze.
The Stalking Horse
The first significant move came almost immediately, and it was not what anyone expected from a Bitcoin miner.
In partnership with Macquarie Equipment Finance, Hut 8 pursued the bankrupt natural gas generation portfolio of Validus Power Corp. in Ontario — four gas-fired plants totaling 310 megawatts: Kingston at 110 MW, Iroquois Falls at 120 MW, and 40 MW each at Kapuskasing and North Bay.7 The joint venture vehicle, Far North Power Corp., was structured with Hut 8 holding the large majority and Macquarie the balance. The assets were acquired out of bankruptcy in late 2023 and the work of stabilizing them ran through 2024 and 2025.18
Why would a compute company buy power plants? Two reasons, and they point in different directions.
The defensive reason is that a miner's existential vulnerability is its power cost. Owning generation converts a variable input cost into a fixed asset. The offensive reason — the one that turned out to matter — is that distressed power assets in a world entering a compute-driven electricity shortage were mispriced. Bankruptcy sellers were pricing four Ontario gas plants as tired thermal generation in a decarbonizing province. Genoot was pricing them as scarce, permitted, dispatchable megawatts.
The Flip
The execution vindicated the second view. Far North secured five-year capacity contracts covering the entire 310 MW portfolio through Ontario's IESO Medium-Term 2 auction, converting the plants from short-duration seasonal arrangements into long-dated revenue backed by an investment-grade counterparty.7 That is the single most value-creating action available to an owner of a merchant power asset: you are not changing the physical plant at all, you are changing the quality and duration of its cash flow, which is what determines the multiple a buyer will pay.
Then, on November 17, 2025, Hut 8 announced it was selling the entire portfolio to TransAlta Corporation. TransAlta disclosed a purchase price of $95 million, subject to working capital and other adjustments.719
Hut 8 framed the sale as consistent with a power-first capital allocation strategy that prioritizes large-scale compute over owning standalone generation.7 Translated: Hut 8 does not want to be a utility. It wants to be the party that buys distressed or under-optimized power capacity, does the unglamorous work of stabilizing and contracting it, and then either deploys it for high-margin compute or sells it to someone whose cost of capital is better suited to owning a gas plant forever.
There is an honest caveat here that the company's framing glosses over. The company did not disclose a full return calculation on the Far North investment, and the headline $95 million sale price is not by itself evidence of a spectacular outcome — it is a price, not a return. Judging the trade properly would require the acquisition cost, two years of stabilization capital expenditure, the operating cash flow generated in the interim, and Macquarie's share. Investors should treat the Validus-to-TransAlta sequence as evidence of a repeatable capability — buy distressed, contract it, sell to a strategic — rather than as a quantified win, because the quantification is not public.
What the sequence does establish, credibly, is that this management team can execute a complex distressed acquisition in a regulated foreign power market, win a competitive capacity auction, and exit to an investment-grade strategic buyer inside two years. That is a genuinely unusual skill set for a company that started as a Bitcoin miner, and it is the skill set the next chapter would require at ten times the scale.
VI. The AI Pivot, Coatue's $150M Bet, & Highrise AI (June 2024 – 2025)
April 2024 delivered the event every Bitcoin miner had been dreading and modeling for four years: the halving. The block subsidy cut in half. Overnight, the same machines consuming the same electricity produced half the Bitcoin. For an industry whose marginal operators were already thin, this was a brutal compression.
And at almost exactly the same moment, an entirely different industry discovered it had a problem that Bitcoin miners were uniquely positioned to solve.
Why AI Needed the Miners
The generative AI buildout of 2023–2024 ran into a physical constraint that surprised almost everyone: not chips, not capital, but power and the buildings to put it in. Training and serving large models requires racks drawing an order of magnitude more electricity than traditional enterprise IT. A conventional data center hall designed for 5 to 10 kilowatts per rack simply cannot host modern AI hardware — the power density and the heat rejection requirements are in a different regime.
Meanwhile, utility interconnection queues in most American markets stretched to five, six, seven years. You could have unlimited capital and a signed order from NVIDIA and still be unable to plug anything in.
Bitcoin miners, it turned out, were sitting on exactly the scarce thing: large, already-energized interconnections at industrial scale, in deregulated markets, with land, substations, and utility relationships already in place. They had spent years acquiring the one asset the AI industry could not buy quickly at any price.
The catch — and this is where most of the miner-to-AI conversion stories oversimplify — is that a Bitcoin mining shed and an AI data center are not the same building. Mining tolerates dust, heat, humidity, and downtime; if a rig goes offline for an hour you lose an hour of revenue and nothing else. AI training clusters demand redundant power, precision cooling, high-reliability networking, and uptime guarantees written into contracts with financial penalties. Converting one into the other is not a retrofit. It is usually a demolition and a rebuild on the same interconnection. What transfers is the power, the land, and the permits. Almost nothing else does.
Coatue's Validation
On June 24, 2024, Hut 8 announced a $150 million investment from a fund managed by Coatue Management, structured as a convertible note.6 The terms are worth understanding because they reveal how each side saw the risk.
The note carried an 8.00% coupon compounded quarterly, an initial five-year term extendable at the company's option for up to three additional one-year periods, and an initial conversion price of $16.395 per share — approximately a 45% premium to the ten-day volume-weighted average price through June 20, 2024.620
Decode that structure. Coatue took downside protection in the form of a debt instrument paying a high single-digit coupon, while purchasing equity upside at a price 45% above where the stock was trading. That is not a bet that Hut 8 was cheap. It is a bet that Hut 8 was about to become a fundamentally different company — one whose equity would need to appreciate substantially before Coatue's conversion made sense.
Coatue's identity mattered as much as its money. The firm was an early backer of CoreWeave, the GPU cloud company that became the defining success story of the AI infrastructure trade. When the investor with the best pattern-recognition on "which companies convert power into AI revenue" writes a check to a Bitcoin miner, the market updates. And the company gained something scarcer than $150 million: a credible signal to counterparties that it belonged in AI infrastructure conversations at all.
Highrise AI: The Small Experiment
Hut 8's first operational move into AI was deliberately modest. In September 2024, it launched a GPU-as-a-Service vertical under the Highrise AI brand, commissioning a cluster of 1,000 NVIDIA H100 GPUs under a five-year agreement with an AI cloud developer.21 The hardware sat in a tier-three data center in the Chicago area.22
One thousand H100s is, in the context of the AI buildout, tiny. Frontier training runs of that era involved tens of thousands of accelerators. This was not an attempt to compete with hyperscalers. It was a pilot: proof that the company could procure scarce silicon, deploy it in a high-reliability facility, sign a multi-year enterprise contract, and collect predictable revenue instead of mining rewards.
And it is worth naming the risk the company took on, because it is the same risk every GPU-as-a-Service provider carries. When you own the GPUs, you own the depreciation. NVIDIA's product cadence — Hopper to Blackwell and beyond — compresses the useful economic life of any given generation. If you have signed a five-year contract against hardware whose competitive half-life is closer to three, you are exposed on the back end.
That exposure helps explain the strategic direction Hut 8 ultimately chose. The company's largest commitments today are not GPU ownership deals. They are leases in which Hut 8 builds and owns the building and the power and the tenant brings the silicon — a structure that keeps the long-lived asset with Hut 8 and the fast-depreciating asset with the customer. Highrise AI proved capability. The lease model is what got financed.
But none of that could scale while the mining fleet and the infrastructure business shared a balance sheet and an equity story.
VII. The Spinoff Masterstroke: American Bitcoin Corp (ABTC) & Eric Trump (2025–2026)
Imagine pitching two businesses to an investor inside one ticker.
The first: an AI infrastructure developer with long-dated contracted revenue, investment-grade counterparties, and project-financeable assets. Value it on cash flow yield and cost of capital.
The second: a Bitcoin miner whose revenue is a function of a volatile commodity, requiring perpetual reinvestment in depreciating ASICs, with earnings that swing hundreds of millions of dollars per quarter on mark-to-market accounting.
An investor who wants the first cannot own it without the second. An investor who wants the second is diluted by the first. The result is that neither shareholder base is satisfied, and the stock trades at a discount to the sum of its parts — a conglomerate discount, in a company far too small to justify being a conglomerate.
The Structural Fix
On March 31, 2025, Hut 8 launched American Bitcoin Corp. The mechanism: Hut 8 contributed substantially all of its ASIC miners to American Data Centers, Inc. — an entity formed by a group of investors including Eric Trump and Donald Trump Jr. — in exchange for an 80% interest in the resulting company.8
The initial leadership was announced as Mike Ho, Genoot's USBTC co-founder, as Executive Chairman; Matt Prusak as Chief Executive Officer; and Eric Trump as Chief Strategy Officer.8
Then came the listing. Rather than pursue a conventional IPO, American Bitcoin merged into Gryphon Digital Mining, an already-listed Nasdaq company, in a stock-for-stock transaction announced in May 2025 and completed on September 3, 2025, with the combined entity trading as ABTC.23 A reverse split effective September 2, 2025 reduced Gryphon's outstanding share count from approximately 82.8 million to 16.6 million ahead of the exchange.23
Using a listed shell was a speed decision. It avoided the IPO underwriting process and got the entity trading during a favorable window. It also, characteristically for this management team, prioritized transaction velocity over process conventionality.
The Ownership Question — Read the Share Classes
Here is where the popular framing of this deal and the actual capital structure diverge, and it matters for anyone valuing Hut 8 on a sum-of-the-parts basis.
The widely repeated figure is that Hut 8 owns 80% of American Bitcoin. That is accurate as a statement about control. As of April 10, 2026, Hut 8 held 585,779,924 Class B shares representing approximately 80% of total voting power.24
Economic ownership is a different number. The listing itself was dilutive, and ABTC subsequently issued equity to fund Bitcoin purchases — by March 2026 the company's holdings had grown to roughly 6,889 BTC, a stack large enough to place it among the larger corporate holders.25 Reporting around the Gryphon merger indicated Hut 8's post-transaction economic stake at roughly 64%, materially below the 80% voting figure.24
An investor building a sum-of-the-parts model on "80% of ABTC's market cap" would therefore overstate the value of that stake by a meaningful margin. This is not an accusation of misrepresentation — dual-class structures are disclosed and legal, and the 80% voting figure is true on its own terms. It is a reminder that in structures like this, control percentages and economic percentages drift apart over time, and the drift always runs the same direction: every subsequent ABTC equity raise dilutes Hut 8's economics while leaving its voting control intact.
What Hut 8 Actually Kept
The elegance of the structure is what remained on the Hut 8 side. Hut 8 continues to serve as the operator and infrastructure provider to ABTC — supplying sites, hosting, facility management, and energy procurement — and collects fees for doing so.8
This converts the mining relationship from a capital-consuming operating business into a customer. Hut 8 no longer funds ASIC purchases out of its own balance sheet; ABTC does, using its own currency. Hut 8 books service revenue with contracted economics, retains a large equity stake in the mining upside, and removes the fleet's capital expenditure treadmill from its own cash flow statement.
That said, an activist would push back on the obvious governance question: Hut 8 controls ABTC's votes and is ABTC's largest vendor. Every hosting rate, every energy procurement fee, every site allocation between the two entities is a related-party transaction negotiated between a parent and a subsidiary it controls. Minority ABTC shareholders are relying on independent directors and disclosure to ensure those terms are arm's-length. Hut 8 shareholders, conversely, benefit from favorable pricing to the parent. This is not a hypothetical concern — it is the structural reality of every controlled-subsidiary vendor relationship, and it is a permanent item on the diligence list.
The Eric Trump Question
The Trump involvement is the part of this story that generates the most heat and the least analysis, so it is worth handling directly and without either cheerleading or squeamishness.
The bull framing is that the association delivers extraordinary visibility with retail investors and crypto-native capital, plus perceived alignment with an administration favorable to domestic Bitcoin mining and energy development — useful when your business depends on permits, interconnections, and regulatory posture.
The bear framing is that political brand equity is the least durable asset a company can hold. It is tied to an electoral cycle, it can invert with a change in administration, and it introduces headline and governance risk that certain institutional allocators are mandated to avoid entirely. A pension fund with political-exposure screens may simply be unable to own ABTC regardless of the operating merits — which shrinks the buyer base for the very asset Hut 8 needs to hold value.
The honest assessment is that the Trump association is a marketing and access asset, not an operating one, and that the operating control rests with the USBTC lineage — Ho and Prusak — who ran the mining business before the Trumps were involved.8 Investors should underwrite ABTC on its fleet efficiency, its power cost, and its Bitcoin per share, not on the name recognition of its Chief Strategy Officer. The volatility in ABTC's shares following its listing and lock-up expiry suggests the market has been learning that lesson in real time.
VIII. Financial Breakdown & Operating Economics (FY 2025)
There is a specific kind of income statement that appears when a company is mid-transformation: the revenue line tells you about the future and the earnings line tells you about the past. Hut 8's fiscal 2025 is a textbook example, and reading it correctly requires separating three completely different things that are jumbled together.
The Top Line
Revenue for the twelve months ended December 31, 2025 was $235.1 million, up from $162.4 million the prior year — roughly 45% growth.26 The segment split:26
Compute — ASIC compute, AI cloud, and traditional cloud — generated $202.3 million, about 86% of the total. This is the engine.
Power — energy sales and grid participation — contributed $23.2 million, about 10%.
Digital Infrastructure — colocation and managed hosting — produced $9.6 million, roughly 4%.
That Digital Infrastructure line deserves attention precisely because it is so small. It is the segment that will house the AI data center leases, and at $9.6 million it is currently a rounding error against a company that has signed contracts with a combined base value in the tens of billions of dollars. Management has indicated that Digital Infrastructure becomes the primary growth driver from the second quarter of 2027, when the first River Bend data hall is scheduled for delivery.27
This is the single most important framing for anyone evaluating Hut 8 today: the business the market is valuing has essentially not started generating revenue yet. Everything currently in the income statement is the old company. Everything in the equity story is the new one. The gap between those two facts is roughly a year and a half of construction risk.
The $248 Million Question
Net loss for 2025 was $248.0 million, against net income of $331.4 million in 2024.2628 That is a $579 million swing, and it would look catastrophic if you did not know what caused it.
The answer is almost entirely accounting for Bitcoin. The 2025 loss included $220.0 million of primarily unrealized losses on digital assets. The 2024 profit included $509.3 million of primarily unrealized gains.26
Under current fair-value accounting rules, companies holding Bitcoin mark it to market through the income statement every period. A company that holds a large Bitcoin position therefore reports earnings that are substantially a function of where Bitcoin closed on the last day of the quarter — regardless of whether a single coin changed hands. Adjusted EBITDA of negative $135.4 million for 2025 versus positive $555.7 million in 2024 reflects the same distortion.26
The practical instruction for investors is that Hut 8's GAAP net income is close to uninformative about operating performance. It is a Bitcoin price chart with a company attached. The metrics that carry information are segment revenue, segment margin, contracted backlog, and the cost and structure of the capital funding construction.
The Q4 2025 figures illustrate how violent this can be: quarterly revenue of $88.5 million against a quarterly net loss of $301.8 million.26 No operating business generates that ratio. Bitcoin marks do.
Balance Sheet and Pipeline
At year-end 2025, combined cash and Bitcoin reserves totaled approximately $1.4 billion, of which $899.3 million was attributable to Hut 8 and $472.6 million to American Bitcoin.26 The disaggregation matters — the ABTC-attributable portion sits inside a majority-owned subsidiary with its own minority shareholders and its own capital needs, and is not freely available to the parent.
The development pipeline stood at approximately 8,500 MW, staged by maturity: 1,020 MW under management, 330 MW under construction, 1,230 MW under development, 1,755 MW under exclusivity, and 5,185 MW under diligence.26
That staging disclosure deserves credit — it is more honest than a single headline gigawatt number, because it tells you that roughly 61% of the pipeline is at the "diligence" stage, which is a long way from an energized megawatt. A skeptical investor should mentally apply a steep probability discount to everything below "under development." A generous one should note that the company disclosed the breakdown at all rather than advertising "8.5 GW" without qualification.
On the operating side, the Vega facility — 205 MW of behind-the-meter capacity that commenced operations in mid-2025, using a proprietary liquid cooling system supporting deployments up to 180 kW per rack — represents the company's demonstrated capability at high-density construction.2627 That 180 kW figure is the relevant proof point: it is roughly twenty times the density of a traditional enterprise data center hall, and it is the physical evidence behind the claim that Hut 8 can build for AI-class hardware rather than just for ASICs.
Q1 2026: The Transition in Miniature
The first quarter of 2026 showed both halves of the story at once. Revenue reached $96.7 million, up 226% year over year, with gross margin expanding to 64% from 14%.27 Compute revenue roughly quadrupled to about $66 million with margins at 67% versus 16%.27 Power revenue declined to $3.7 million from $4.4 million, a direct consequence of the Far North sale.27 Digital Infrastructure was flat at $1.3 million.27
And yet: net loss of $253.1 million, driven again by Bitcoin marks, and revenue that missed consensus expectations by roughly 9%.27
A margin expansion from 14% to 64% in twelve months is the most genuinely encouraging operating number in this entire story, and it deserves to be stated plainly: it suggests the restructuring changed the underlying economics rather than merely rearranging the org chart. But one quarter of margin, on a revenue base still dominated by mining-adjacent compute, is not proof of a durable infrastructure business. That proof arrives in 2027 or not at all.
IX. Strategic Moats: Porter's 5 Forces & Hamilton Helmer's 7 Powers
Every infrastructure company claims a moat. The useful exercise is to ask what specifically would prevent a well-capitalized competitor from replicating the position, and whether that barrier is strengthening or eroding.
Helmer's Powers, Tested
Cornered Resource — the strongest claim, and a real one. Helmer's cornered resource requires preferential access to a valuable asset on terms unavailable to others. Energized, permitted, large-scale grid interconnections in the 2024–2027 window qualify. Utility interconnection queues run multiple years; the transmission and generation capacity to serve gigawatt-scale loads does not exist in most markets; and no amount of capital compresses a regulatory timeline. Hut 8 accumulated these positions when they were priced as mining sites rather than as AI real estate.
But this power has a shelf life, and honesty requires naming it. Interconnection scarcity is a cyclical condition created by a demand shock, not a permanent structural feature. Utilities are responding: new generation is being permitted, transmission is being planned, and every miner in North America is now marketing the same conversion story. The cornered resource is real today. Whether it is cornered in 2032 depends on whether AI compute demand outruns grid buildout for another decade — which is an assumption, not a fact, and it is the load-bearing assumption in the entire bull case.
Counter-Positioning — underappreciated and arguably the sharper power. Hut 8's structure lets it do something incumbent data center REITs largely cannot: acquire distressed or unconventional power assets, tolerate crypto-adjacent revenue during the development gap, and operate at power densities traditional operators were not built for. A conventional REIT would find it difficult to explain a Bitcoin mining subsidiary to its shareholders. Hut 8's willingness to live in both worlds is not a compromise — it is precisely what lets it monetize a site during the years between acquisition and lease commencement.
Process Power — plausible, partially evidenced. The Validus stabilization and capacity-auction win, the Vega liquid-cooling build at 180 kW per rack, and the ability to underwrite and close complex distressed transactions in multiple jurisdictions constitute an accumulating operational capability. On the Q1 2026 call, management argued explicitly that the scarcity of developers capable of meeting hyperscaler standards is a widening moat — "the supply of developers who can meet that bar is limited, and it's getting smaller."27 That is a self-serving claim from an interested party, but it is also broadly consistent with what tenants have signed.
Scale Economies — weak, and management largely does not claim otherwise. Hut 8 is not the largest buyer of ASICs, GPUs, or power in its sector. Its procurement leverage is real but not differentiating.
Switching Costs — weaker than the standard story suggests. For a fifteen-year triple-net lease on a purpose-built campus, the tenant's switching cost is enormous — but that is a function of the contract, not of any proprietary Hut 8 technology. Once the lease is signed, the lock-in is legal and physical. Before it is signed, Hut 8 has essentially no switching-cost advantage at all. This power operates only after the win, which means it does nothing to help win the next deal.
Branding and Network Economies — not applicable. No serious case exists for either in industrial data center development.
Porter's Five Forces
Rivalry: high and intensifying. Every publicly traded Bitcoin miner with meaningful power capacity has announced some version of an AI pivot. Core Scientific pursued high-density AI colocation aggressively after emerging from bankruptcy. MARA Holdings and CleanSpark operate substantially larger self-mining fleets than ABTC. On the infrastructure side, Hut 8 competes against established data center developers with lower costs of capital and decades of hyperscaler relationships. The company's differentiator is not that it is the only one trying — it is that it has actually signed and financed contracts, which most peers have not.
Supplier power: high, and structurally so. NVIDIA controls accelerator allocation. Bitmain and MicroBT control ASIC supply. Utilities control interconnection timing. Critically, the utility is the supplier that matters most now — analysts pressed management on the Q1 2026 call about whether Entergy's power availability would constrain Louisiana growth, and the answer involved behind-the-meter generation and independent power producers, which is a sensible mitigation but also an admission that the constraint is real.27
Buyer power: mixed, and less favorable than the narrative implies. The scarcity of AI-ready capacity gives developers pricing power today. But look at who the counterparties are: Google backstopping the River Bend lease, a high-investment-grade tenant at Beacon Point, NVIDIA as a design partner.127 These are among the most sophisticated and powerful buyers in the world economy. They are not price-takers. They are extracting fifteen-year commitments to specifications they define, from a developer whose entire financing structure depends on their credit. Hut 8 has excellent customers; it does not have weak ones.
Threat of substitutes: moderate and underdiscussed. The substitute is not another data center — it is better algorithmic efficiency. If model architectures, inference optimization, or specialized silicon materially reduce the electricity required per unit of useful AI output, the demand curve for gigawatts flattens. This is the risk that would invalidate the entire sector thesis simultaneously, and no individual company's execution protects against it.
Threat of new entrants: low in the near term. Gigawatt-scale development requires hundreds of millions in equity, project financing relationships, utility standing, and construction capability. The barrier is genuine — though it is worth noting that private capital, sovereign funds, and hyperscalers themselves are entering, and they do not face the same cost-of-capital disadvantage Hut 8 does.
X. Playbook: Key Lessons for Founders and Investors
1. Identify the actual scarce asset, not the fashionable application. Hut 8's entire recovery rests on a reframing: the company never really sold Bitcoin mining, it sold the conversion of electricity into computation. Bitcoin was the application that happened to be the highest bidder for a megawatt in 2018. AI is the application that happens to be the highest bidder in 2026. The asset — an energized, permitted interconnection with land around it — did not change. Companies that define themselves by the application must reinvent themselves each cycle. Companies that define themselves by the asset can simply re-point it. The corollary is uncomfortable: if the asset is truly the moat, then the company is a landlord, and landlords earn landlord returns.
2. Structural separation can be worth more than operational improvement. The ABTC spin-out changed almost nothing about how many Bitcoin get mined or how efficiently. What it changed was who funds the ASICs, which shareholders bear which risk, and how the market prices each stream. Sometimes the highest-return corporate action available is not making the business better but making it legible — separating streams that require different capital, different holding periods, and different investors. The caution attached: separation creates related-party complexity, and complexity is where value quietly leaks.
3. Buy distressed, contract the cash flow, sell to the natural owner. The Validus-to-TransAlta sequence is a repeatable pattern. Acquire an asset whose cash flows are short-dated and therefore cheap, do the operational and regulatory work to convert those cash flows into long-dated contracted revenue, and then sell to a buyer whose cost of capital makes long-dated contracted revenue worth more than it is worth to you. The value creation happens in the contracting, not in the buying or the selling. And recycling capital this way funds growth without dilution — which matters enormously for a company that spent its early life issuing equity to survive.
4. When a short seller lands, the question is what it exposes internally. J Capital did not force the CEO change. But it removed the board's ability to defer an unresolved governance question from the merger. The pattern worth learning is that short reports are rarely decisive on their merits and frequently decisive on their timing — they arrive when a company is already carrying an unresolved internal tension and they make deferral impossible. Boards that have already resolved their tensions survive short reports comfortably. Boards that have not, change management.
5. Underwrite management on the gap between promise and delivery, over time. Genoot's team has now made a series of specific, falsifiable commitments: stabilize and monetize Validus (delivered), launch a GPU vertical (delivered, small), separate the mining fleet (delivered), sign anchor AI leases (delivered), finance them without recourse to the parent (delivered, via the River Bend bond). That is a genuinely strong record of doing what was announced. The commitments now outstanding are far larger and far harder — deliver a data hall in the second quarter of 2027, then repeat it. Past execution earns the benefit of the doubt. It does not substitute for the next delivery.
XI. The Bull vs. Bear Case & Risk Radar
The Bull Case
The contracts are signed, rated, and financed. This is what separates Hut 8 from the dozen other miners announcing AI ambitions. The River Bend lease with Fluidstack covers 245 MW of IT capacity over a fifteen-year base term with a $7.0 billion contract value, a 3.0% annual rent escalator, three optional five-year renewals, and lease obligations financially backstopped by Google — an AA+/Aa2 credit.1 The expected cumulative net operating income over the base term was disclosed at approximately $6.9 billion, or roughly $454 million annually.1 Beacon Point followed: 352 MW of IT capacity within a one-gigawatt campus, a fifteen-year triple-net lease with a high-investment-grade tenant, $9.8 billion of base contract value with 3% escalators, and NVIDIA as a design and technology partner.27
The financing validates the contracts independently. Anyone can announce a contract. What is harder to fake is the debt market's verdict. Hut 8 closed $3.25 billion of senior secured bonds against River Bend — 16.5-year fully amortizing structure at a 6.192% coupon, rated BBB- by both S&P and Fitch — and recovered $184 million of equity at closing.27 That structure is the whole thesis in one instrument: non-recourse project debt, investment-grade rated, amortizing over the lease term, sized so the contracted rent services it. It means third-party rating agencies and institutional bond buyers underwrote the same cash flows management is describing. That is a meaningfully higher evidentiary bar than a press release.
Balance sheet discipline that is actually observable. Management stated on the Q1 2026 call that it had eliminated parent-level recourse debt other than the Coatue convertible note, with approximately $1.3 billion of parent-level liquidity in cash and Bitcoin.27 The Coatue note was described as deeply in the money with a potential mandatory redemption.27 A convertible converting is dilutive, but it is dilution at $16.395 into a substantially higher share price — which is to say, it was cheap capital in retrospect.
Optionality that costs nothing to hold. Hut 8 retains a controlling stake in a listed Bitcoin miner, a development pipeline it can lease or sell, and demonstrated ability to monetize power assets to strategics. Several separate paths to value exist rather than one.
The Bear Case
The revenue does not exist yet. This is the central bear point and it cannot be argued away. Digital Infrastructure — the segment that will house these leases — generated $9.6 million in all of 2025 and $1.3 million in the first quarter of 2026.2627 First delivery is targeted for the second quarter of 2027.27 Every dollar of the tens of billions in announced contract value is contingent on construction that has not been completed. The market is capitalizing a promise with roughly six quarters of execution risk in front of it.
Construction and schedule risk is the binding constraint. Analysts pressed this directly on the Q1 2026 call, and management's response — investment-grade construction bond validation, partners including Jacobs and Vernova, conservative timelines with buffer, and a prior track record of delivering gigawatt-scale infrastructure — was substantive but is, necessarily, forward-looking.271 Large data center projects slip. Transformers, switchgear, and turbines have multi-year lead times. A triple-net lease with delivery obligations creates penalty exposure if the developer is late.
Counterparty quality is more layered than the headlines suggest. The River Bend tenant is Fluidstack, a company with nothing resembling Google's balance sheet; the credit comes from Google's backstop of the base-term lease payments.1 A backstop is a contractual obligation with defined scope, and investors should understand its precise terms rather than mentally substituting "Google is the tenant." Reporting also linked the arrangement to Anthropic.2 The chain from an AI lab's compute commitment, through a neocloud intermediary, to a landlord's rent has more links in it than a direct hyperscaler lease. When an analyst asked whether Beacon Point represented genuinely new demand or an extension of the existing Google/Fluidstack/Anthropic relationship, Genoot said it was net new growth and emphasized credit diversification.27 That the question was asked at all reflects a real concentration concern.
Related-party and structural complexity. An activist would look at this company and see: a controlled public subsidiary that is also the parent's largest customer, a Chief Strategy Officer whose value proposition is political access, a joint-venture history in a foreign power market, a convertible note held by a single sophisticated investor, and project debt at multiple non-recourse entities. None of these is improper. Collectively they mean valuing Hut 8 requires consolidating and de-consolidating several structures correctly, and complexity of that kind reliably attracts a valuation discount.
Cost of capital versus incumbents. A BBB- project bond at 6.192% is a strong outcome for Hut 8. It is not a strong outcome relative to what an established data center REIT or a hyperscaler funding on its own balance sheet would pay. In a business where returns are the spread between yield on cost and cost of capital, a structural funding disadvantage compresses margins permanently.
Current Risk Radar
AI capital expenditure cyclicality. The dominant risk. If hyperscaler and AI-lab capex growth decelerates, the scarcity premium on power-ready capacity compresses and the pipeline behind the signed leases loses value. Signed contracts are protected; the 8.5 GW pipeline is not.
Efficiency-driven demand destruction. Improvements in model efficiency or inference-optimized silicon could reduce electricity demand per unit of AI output faster than expected. This is the substitute risk, and it would hit the entire sector at once.
Bitcoin price and ABTC value. Hut 8's stake in ABTC and its own Bitcoin holdings mean a sustained crypto drawdown damages both reported earnings and the parent's liquidity position — the same reflexivity that broke the 2022 balance sheet, now held at one remove rather than eliminated.
ERCOT and grid regulation. Extreme weather events in Texas have historically triggered regulatory and political scrutiny of large flexible loads. Curtailment mandates would reduce mining output at ABTC-served sites.
GPU obsolescence at Highrise AI. The owned H100 fleet faces the depreciation risk inherent to any GPU-as-a-Service model as newer architectures ship. This is a small exposure in the context of the whole, but it is the clearest illustration of why the lease model was chosen over the ownership model for the large deals.
Concentration. A small number of very large contracts now drive the entire equity story. That is the nature of gigawatt-scale infrastructure development, but it means the company's fortunes turn on a handful of counterparty relationships rather than a diversified revenue base.
XII. Epilogue & Key KPIs to Watch
In roughly two and a half years, Asher Genoot took a company that had been publicly accused of being a pump-and-dump, whose CEO had just been removed, whose core business had been halved by protocol design, and whose treasury strategy had proven procyclical — and rebuilt it into a developer signing fifteen-year leases financed with investment-grade bonds and designed to NVIDIA specifications.
That is, on any reasonable assessment, an unusual corporate turnaround.
It is also, at this moment in July 2026, substantially unproven where it matters most. Every operating number in Hut 8's financial statements still reflects the old business. Every number driving the equity story reflects buildings that do not yet exist. The company has moved the risk from strategic — will they find a business model? — to executional: can they build what they promised, on time, at cost, and repeat it?
Those are very different risks, and the second is the better one to have. But it is not a small one. The gap between a signed lease and a delivered data hall is where infrastructure companies most reliably disappoint, and Hut 8 has never delivered a project of River Bend's complexity before.
There is also a philosophical shift worth naming for long-term holders. The company that once offered investors a levered claim on Bitcoin now offers something closer to a contracted-cash-flow developer with a Bitcoin option attached. Those attract different shareholders. Some portion of the register that bought HUT for crypto beta is being replaced by investors who want infrastructure yield — and transitions in shareholder base are frequently accompanied by volatility that has nothing to do with the underlying business.
The Three KPIs That Matter
Given how much of the reported financials is noise, the tracking discipline should be narrow. Three metrics carry nearly all the signal.
1. Digital Infrastructure segment revenue. This is the cleanest available test of whether the transformation is real. It sat at $9.6 million for full-year 2025 and $1.3 million in the first quarter of 2026, with management pointing to the second quarter of 2027 for meaningful contribution.2627 If this line inflects on schedule, the thesis is working. If delivery slips and this line stays flat into late 2027, the market's valuation of announced contract value will need to be revisited. Nothing else in the income statement answers this question.
2. Contracted capacity converted from pipeline — megawatts under construction and under development. The company's staged pipeline disclosure makes this trackable: watch the migration of megawatts from "under diligence" and "under exclusivity" into "under development" and "under construction," and watch how much of that carries a signed lease.26 Announced pipeline is an aspiration. Contracted, under-construction megawatts are a balance sheet. The ratio between them is the truest measure of whether the power-first strategy compounds or stalls after the first two campuses.
3. Realized yield on invested capital at delivered projects, versus project-level cost of debt. This is the only metric that ultimately determines whether the model creates value. River Bend's disclosed annual net operating income of roughly $454 million against $3.25 billion of project debt at a 6.192% coupon establishes the benchmark.127 As subsequent projects are financed and delivered, the question is whether that spread holds, compresses as competition for tenants increases, or widens as the company's credit improves. A developer that maintains its spread across multiple projects has a business. One whose spread narrows with each deal has a moment.
Everything else — quarterly net income, Bitcoin marks, headline pipeline gigawatts, the ticker's correlation to crypto on any given day — is noise around those three signals.
References
-
Hut 8 Signs 15-Year, 245 MW AI Data Center Lease at River Bend Campus with Total Contract Value of $7.0 Billion — Hut 8 Corp. / PR Newswire, 2025-12-17 ↩↩↩↩↩↩↩
-
Hut 8 shares surge 25% as bitcoin miner seals AI deal with Anthropic and Fluidstack, signs $7 billion data center lease — The Block, 2025-12-17 ↩↩
-
Hut 8 shares soar over 30% after scoring $9.8 billion AI data center deal set to NVIDIA specs — The Block, 2026 ↩
-
The Coming HUT Pump and Dump — J Capital Research, 2024-01-18 ↩↩↩↩
-
Bitcoin miner Hut 8 appoints Asher Genoot as new CEO — The Block, 2024-02-07 ↩↩↩
-
Hut 8 Announces $150 Million Strategic Investment from Coatue to Partner in Building Next Generation AI Infrastructure Platform — Hut 8 Corp. / GlobeNewswire, 2024-06-24 ↩↩↩
-
Hut 8 Announces Sale of 310 MW Power Portfolio to TransAlta Following Successful Optimization and Long-Term Contract Wins — Hut 8 Corp. / PR Newswire, 2025-11-17 ↩↩↩↩↩
-
Hut 8 and Eric Trump Launch American Bitcoin to Set a New Standard in Bitcoin Mining — Hut 8 Corp. / GlobeNewswire, 2025-03-31 ↩↩↩↩↩
-
Hut 8 and Bitfury Team Up to Recentralize Bitcoin Mining to Canada — Techvibes, 2017-12-06 ↩
-
Hut 8 Mining On Sustainability, Expansion And Surviving Crypto Winter — Bitcoin Magazine ↩↩
-
Crypto mining firm Hut 8 acquires TeraGo's data center business — Data Center Dynamics, 2022-01 ↩
-
Hut 8 Announces Closing of the Acquisition of TeraGo's Data Center Business — Hut 8 Mining Corp. / Newswire.ca, 2022 ↩
-
Description of the Business of American Bitcoin Corp — SEC EDGAR, 2025 ↩
-
Hut 8 agrees to $2.35 million settlement in investor suit tied to US Bitcoin merger — The Block, 2026-06 ↩↩↩
-
AI miner Hut 8 to pay $2.35 million to settle investor claims tied to 2023 USBTC merger — CoinDesk, 2026-06-23 ↩
-
Hut 8 Announces Leadership Transition — Hut 8 Corp. / GlobeNewswire, 2024-02-07 ↩↩
-
Bitcoin Miner Hut 8 Shares Slide as CEO Departs Weeks After Short-Seller Report — CoinDesk, 2024-02-07 ↩
-
Cryptomining firm Hut 8 sells 310MW Canadian natural gas portfolio to TransAlta — Data Center Dynamics, 2025-11 ↩
-
TransAlta to Acquire 310 MW Contracted Ontario Gas Portfolio for $95 million — TransAlta Corporation, 2025-11-17 ↩
-
Hut 8 Corp. Form 8-K, Exhibit 99.1 — Coatue Convertible Note — SEC EDGAR, 2024-06-21 ↩
-
Hut 8 GPU-as-a-Service Vertical Goes Live with Inaugural Deployment — Hut 8 Corp. / GlobeNewswire, 2024-09-26 ↩
-
Hut 8 rolls out GPU cloud cluster in Chicago, Highrise AI arm — Structure Research, 2024-10-28 ↩
-
Gryphon Digital Mining Completes Merger to Form American Bitcoin Corp — TipRanks, 2025-09-03 ↩↩
-
American Bitcoin Corp. Definitive Proxy Statement (DEF 14A) — SEC filing summary, 2026 ↩↩
-
Trump-linked American Bitcoin overtakes Galaxy Digital in bitcoin rankings — CoinDesk, 2026-03-18 ↩
-
Hut 8 Reports Fourth Quarter and Full Year 2025 Results — Hut 8 Corp. / PR Newswire, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Earnings call transcript: Hut 8 Q1 2026 — Investing.com, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Hut 8 posts $248 million net loss for 2025 as AI pivot takes shape — The Block, 2026 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube