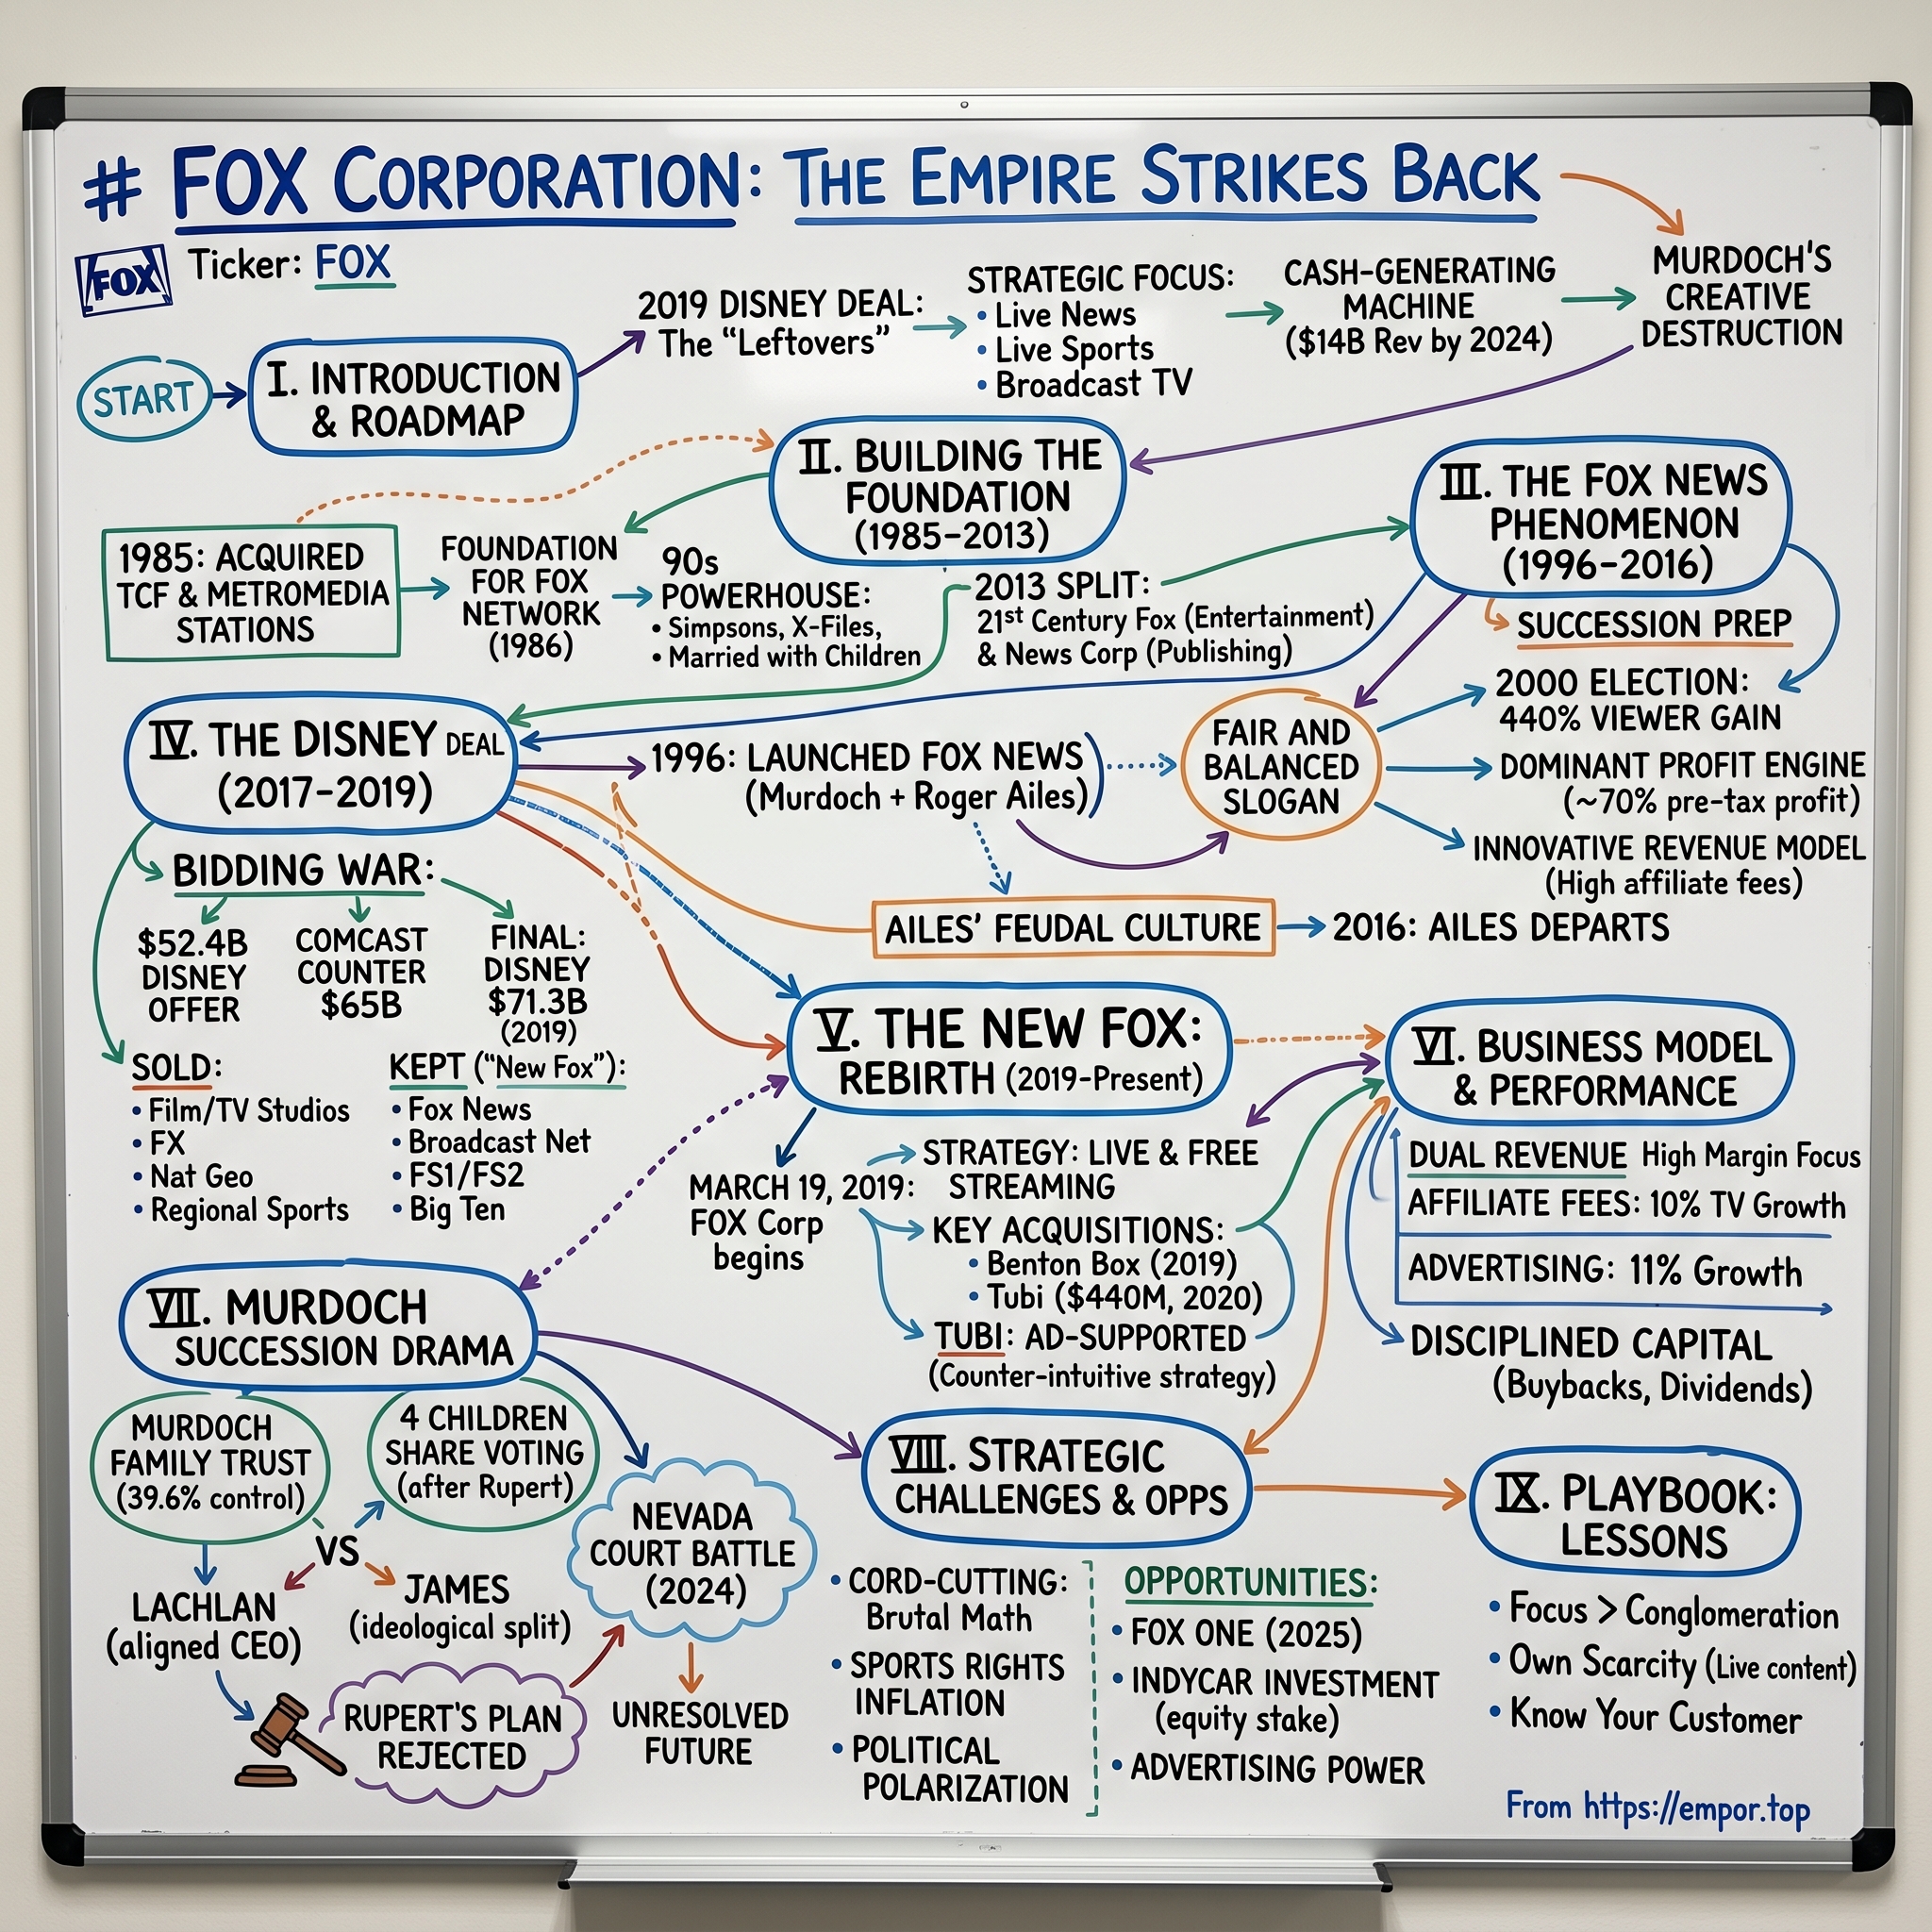
Fox Corporation: The Empire Strikes Back
I. Introduction & Episode Roadmap
On the morning of March 19, 2019, a company that had technically existed for less than a year began trading on the NASDAQ under two ticker symbols, FOX and FOXA. There was no IPO roadshow, no bell-ringing founder in a hoodie, and no venture capitalists counting paper gains. Instead, the debut was the result of a corporate divestiture. Rupert Murdoch had sold the entertainment and international assets built over half a century — including the film studio behind Avatar, the cable network behind The Americans, National Geographic magazine, a third of Hulu, and satellite operations spanning London to Mumbai — to Disney, led by Robert Iger, for roughly $71 billion.2 What remained was a focused portfolio: a broadcast network, a news channel, two sports channels, twenty-eight local television stations, and a studio lot in Century City.
Wall Street initially viewed this remainder with skepticism. The assets Murdoch retained were linear, advertising-dependent, politically sensitive, and exposed to cord-cutting. Yet the strategy for the newly formed Fox Corporation was intentionally contrarian. While rival legacy media companies committed billions of dollars to build subscription streaming platforms to compete with Netflix, Fox chose not to build a costly subscription app. Instead, it focused on monetizing live news and live sports twice — first through distributor retransmission fees, and second through advertising revenue — while returning cash to shareholders.
Seven years later, the financial results of that choice are clear. In the fiscal year ended June 30, 2025, Fox generated $16.30 billion in revenue, yielding $2.29 billion in net income and $3.62 billion in adjusted EBITDA.[^12] The company maintained modest leverage while peers such as Warner Bros. Discovery and Paramount restructured balance sheets weighed down by streaming investments. Meanwhile, Fox had acquired Tubi for less than half a billion dollars in cash, growing it into the largest free ad-supported streaming service in the United States.3
That backdrop makes Fox's subsequent move notable. On June 15, 2026, Fox Corporation signed a definitive agreement to acquire Roku, Inc. for approximately $22 billion.7 The company that had avoided building a subscription streaming app and emphasized capital discipline committed the largest sum in its history to buy a connected-television operating system and hardware business — a transaction currently facing antitrust scrutiny from the Department of Justice.[^9]
Consequently, the central strategic question is not merely whether the anti-streaming playbook succeeded in the short term. The core issue is sharper: was Fox's performance driven by a durable structural moat, or was it a well-timed harvest of a mature legacy asset — and does the Roku acquisition represent a natural evolution of the strategy, or a fundamental pivot away from it?
The story unfolds across eleven sections. The analysis begins with the corporate split that created the company and the valuation of its assets. It examines segment economics to explain revenue sources and margin drivers. It evaluates the Tubi acquisition, analyzing its performance and strategic role within modern media. It subjects the capital allocation record to a falsification test, reviewing both successes and failed ventures. It addresses legal and governance challenges, including Dominion, Smartmatic, and a confidential probate dispute in Reno, Nevada, over future control of the Murdoch family trust. It then analyzes the Roku transaction, applies strategic frameworks (Helmer and Porter), presents bull and bear cases, outlines three key performance indicators, details strategic takeaways, conducts a management credibility test, and evaluates upcoming catalysts.
Three core themes underpin the analysis: focus versus conglomeration, examining whether Fox's narrow scope reflected strategic conviction or constrained options; live content pricing power versus cord-cutting dynamics, which represents the primary operating tension; and capital discipline versus platform ambition, a trade-off highlighted by the Roku acquisition.
 Subscribe on LinkedIn
II. The Murdoch Empire & The $71 Billion Cash-Out (1985–2019)
Understanding Rupert Murdoch’s decision to sell requires examining four decades of asset accumulation — and why, at age eighty-six, he concluded that his entertainment empire was on the wrong side of media history.
The early history directly explains the portfolio Fox retained. In 1985, Murdoch acquired 20th Century Fox and became a naturalized U.S. citizen to satisfy federal restrictions on foreign ownership of broadcast stations. In 1986, he combined those stations to form the FOX Broadcasting Company, establishing a fourth broadcast network by serving audiences overlooked by ABC, CBS, and NBC. In 1994, Fox secured the National Football Conference broadcast package from CBS, spending aggressively to reset sports rights economics and cement the network's national distribution. In 1996, Murdoch hired Roger Ailes to launch the Fox News Channel, entering a cable news market CNN had dominated for sixteen years.
That launch established the financial engine of the modern company. Fox News built its audience by targeting underserved conservative viewers with consistent programming and brand discipline. Commercially, it became the most-watched cable news network in the United States, maintaining that position for more than two decades and generating industry-leading viewer engagement measured in hours per day rather than minutes.
The 2013 corporate reorganization split News Corporation into two publicly traded entities: publishing assets (The Wall Street Journal, British print titles, and HarperCollins) were spun into a new News Corp, while film and television assets were grouped under 21st Century Fox. This division established the structural blueprint for future transactions: isolating businesses with distinct cost-of-capital profiles and growth narratives to optimize market valuations, while maintaining family control through dual-class shares anchored by the Murdoch Family Trust.
The auction nobody expected to be an auction
By 2017, Murdoch recognized a structural shift that rival executives were slower to accept. Netflix was spending more on content annually than 21st Century Fox generated in total profit, supported by capital markets that prioritized subscriber acquisition over short-term returns. Meanwhile, tech giants Amazon and Apple were expanding into video streaming with balance sheets that made immediate content returns on investment optional. To compete in global direct-to-consumer streaming, Fox faced the prospect of investing billions of dollars annually without guaranteed scale, even as cord-cutting began threatening legacy cable cash flows.
Concluding that general entertainment streaming was a scale battle Fox could not win, Murdoch opted to sell into peak market demand. In December 2017, The Walt Disney Company agreed to acquire 21st Century Fox's entertainment and international assets for approximately $52.4 billion in stock.
The transaction structure escalated in June 2018 when Comcast Chairman and CEO Brian Roberts submitted an all-cash offer of roughly $65 billion. Disney responded by raising its offer to approximately $71.3 billion in cash and stock, prompting Comcast to withdraw and redirect its capital toward acquiring European broadcaster Sky.2 The sale to Disney closed on March 20, 2019.2
The bidding contest highlights both strategic discipline and favorable market timing. Murdoch extracted a substantial premium from two motivated buyers during a period of intense competitive anxiety across legacy media. While the transaction did not guarantee foresight into broader streaming unit economics, Fox divested its general entertainment assets immediately before rising production costs and subscriber churn compressed industry margins. Whether the outcome reflected deliberate strategic foresight or the advantageous result of a bidding war remains an open analytical question.
What went, and what stayed
Under the transaction terms, Disney acquired the 20th Century Fox film and television studios, FX Networks, National Geographic, a 30% interest in Hulu, and international assets including Star India. Fox Corporation retained the FOX News Channel, FOX Business Network, the FOX broadcast network, twenty-eight owned-and-operated local television stations, FS1, FS2, FOX Deportes, and the Century City studio lot in Los Angeles.
The divestiture revealed a clear strategic boundary: Fox kept everything that is watched live and discarded everything that is watched later. Scripted drama can be binged and unbundled, placing it in direct competition with global streaming libraries. Live news and sports, by contrast, depend on real-time viewership. A sporting event or election night broadcast loses most of its commercial value once the outcome is known. This time-sensitivity preserves advertising pricing power because viewers rarely skip commercials during live events, while providing programmers crucial leverage in retransmission fee negotiations with pay-TV distributors.
Fox Corporation began trading on March 19, 2019, as an intentionally focused enterprise with modest net debt, a singular content strategy, and dual revenue streams—retransmission fees and advertising—across its primary assets.[^1] Wall Street's initial reaction was cautious, reflecting the risks inherent in concentration. Relying strictly on live news and sports left Fox exposed to two key industry headwinds: accelerated pay-TV cord-cutting and escalating sports rights fees. Both pressures were already evident in 2019 and define the company's operating environment.
III. Business Model & Segment Financial Engine
A helpful mental model for Fox Corporation rests on a structure that operates more like a toll road than a traditional media company.
Fox does not own the vehicles or the final destination. Instead, it controls a stretch of infrastructure that, at specific hours on select days, serves as the only available route—and it collects revenue twice from every traveler. First, it charges the transport provider that must include the route in its consumer package; second, it collects from billboard advertisers along the roadside. While overall traffic volume declines each year, the toll collected per vehicle rises. The core investment thesis hinges on the race between those two opposing lines.
The two-stream architecture
Every Fox asset monetizes through two distinct revenue streams. Affiliate fees in cable and retransmission consent fees in broadcast represent per-subscriber payments made by cable, satellite, and virtual distributors for channel carriage rights. These contractual payments are recurring, negotiated in multi-year cycles, and collected regardless of actual viewership. Advertising forms the second stream, priced against audience delivery and inherently volatile: it surges during even-numbered election years, spikes during Super Bowl broadcasts, and contracts during economic downturns.
In fiscal year 2025, both streams aligned to produce record results. Revenue reached $16.30 billion, up 17% year over year, propelled by three simultaneous tailwinds: a record political advertising cycle, the broadcast of Super Bowl LIX, and continued growth at Tubi.[^12] Net income rose to $2.29 billion from $1.55 billion, and Adjusted EBITDA increased roughly 26% to $3.62 billion.[^12]
Financial analysts should evaluate these results carefully before extrapolating future performance. Two of the three tailwinds stem from cyclical calendar artifacts. Super Bowl broadcasts rotate among major networks, while political advertising surges biennially. A fiscal year containing both represents Fox's structural maximum output rather than a baseline run rate. Analyzing fiscal year 2025 as the peak of a cycle makes comparisons against the prior peak cycle, rather than the immediately preceding fiscal year, the proper gauge of underlying organic growth.
Cable Network Programming
Cable Network Programming serves as the company's primary earnings engine. The segment houses FOX News Channel, FOX Business, FS1, FS2 and FOX Deportes, generating well over $6 billion annually at EBITDA margins in the mid-to-high forties.[^12] These high margins stem from a low-cost production model: studio space, control rooms, fixed anchors, and a regular rotation of on-air contributors, amortized across twenty-four hours a day, three hundred and sixty-five days a year. The segment avoids costly scripted dramas that carry tens of millions of dollars in per-episode production expense.
Carriage dynamics within this segment explain its pricing power. FOX News commands the highest per-subscriber affiliate rate in cable news, reported in the range of $2.50 per subscriber per month. Distributors pay this premium because channel removal triggers subscriber cancellations. In carriage negotiations, subscriber retention outweighs total audience size. FOX News maintains an audience concentrated among older, highly engaged viewers who consistently switch pay-TV providers if the channel is dropped. This viewer behavior provides Fox with negotiating leverage, allowing it to extract higher rates per subscriber than networks with similar or larger total audiences.
Yet this mechanism contains structural vulnerability. Pricing leverage depends on an aging demographic and a contracting pay-TV subscriber base. Negotiating power is highest among the cohort least likely to maintain traditional video subscriptions over the next decade—a challenge rooted in subscriber demographics rather than hypothetical risk.
Television
The Television segment—comprising the broadcast network, twenty-eight owned-and-operated local stations, and Tubi—generates larger overall revenue but lower profit margins than cable. It generated roughly $7.9 billion in FY2024 and stepped up materially in FY2025 on the Super Bowl and political cycle.[^12]
Segment economics reflect a hybrid distribution structure. Retransmission consent fees flow from distributors to local station groups, which remit a substantial portion back to the network as reverse compensation. This circular capital flow converted broadcast television over the 2010s from a pure advertising medium into a dual-revenue subscription model, preserving the economic viability of local broadcast assets.
Operating costs are dominated by long-term live sports rights, including packages for the NFL, Major League Baseball, college football's Big Ten, and NASCAR. These contractual commitments escalate over time regardless of overall distribution trends. Segment profitability therefore operates as a financial spread: retransmission consent fees plus sports advertising revenue minus escalating sports rights bills. When Fox renewed its NFL package, it secured long-term audience reach while locking in higher fixed costs. The ultimate return depends on whether combined distribution and advertising revenues outpace rising rights fees over the contract lifecycle.
The rest
Credible Labs, a consumer finance marketplace, and the Century City studio lot rental operation comprise the remainder of segment reporting. Both represent minor revenue contributions. Credible will be re-examined in the capital allocation falsification analysis, as its corporate history illustrates management's investment criteria more clearly than its current earnings impact.
So what
Fox's competitive position rests on a clear structural dynamic: live programming remains the primary driver retaining household pay-TV subscriptions, granting Fox negotiating leverage in affiliate carriage deals that library-content owners have lost. This pricing power is demonstrated in realized affiliate rates. However, because this leverage relies on increasing rates across a contracting subscriber base, the model faces long-term structural limits. Evaluating how management deployed cash flow generated during this window forms the focus of the subsequent analysis.
IV. The Anti-Streaming Playbook & The Tubi Triumph
During 2019 and 2020, major legacy media companies launched subscription direct-to-consumer services. Disney+ added ten million subscribers on its first day, WarnerMedia unveiled HBO Max, and NBCUniversal introduced Peacock. On quarterly earnings calls across the industry, executives focused heavily on subscriber growth metrics, and leadership teams faced constant pressure to articulate their direct-to-consumer subscription plans.
Fox took a different path.
Executive Chairman Lachlan Murdoch and Chief Financial Officer Steve Tomsic stated repeatedly that Fox would not launch a general-entertainment subscription service, spend heavily to acquire subscribers at negative unit economics, or introduce another paid streaming app into a crowded market. In 2020, that posture appeared to rationalize the divestiture of the content library required to compete in subscription video on demand (SVOD).
Yet the underlying rationale proved sound: subscription streaming is a scale business with a brutal content treadmill, and the second-tier players in a scale business do not earn a return. Streaming economics require amortizing content expenditures across a massive global subscriber base. Having sold its film and television studios, Fox lacked the scale to compete on those terms. Rather than incurring sustained operating losses to build a paid subscriber base, Fox chose not to participate in the subscription streaming race.
The $440 million footnote that became the business
In March 2020, Fox acquired Tubi for approximately $440 million net of cash.3 Announced as global economic activity slowed during the onset of the COVID-19 pandemic, the transaction initially received modest attention relative to Fox's multi-billion-dollar core revenue base.
Tubi operates as a free, ad-supported streaming service requiring no subscription, login, or expensive original programming. Instead, it licenses catalog and mid-tier film and television content—assets that rights holders were not actively monetizing—and generates revenue through advertising. In economic terms, Tubi functions like a digital syndication outlet: aggregating non-exclusive content at low cost and monetizing viewer attention rather than subscription commitments.
The operating model relies on low marginal overhead. The cost of a viewer-hour consists primarily of content licensing fees and streaming bandwidth, while revenue is generated per advertising impression. The service incurs no subscriber acquisition costs and suffers no subscriber churn. Furthermore, licensing costs remained low because Tubi acquired content that major subscription platforms did not prioritize.
Tubi scaled rapidly following the acquisition. The platform surpassed 110 million monthly active users and delivered more than 13 billion total viewing hours, with annual revenue surpassing a $1 billion run-rate while growing at roughly 23% year over year in recent quarters and achieving standalone profitability.[^12][^1] Approximately 95% of consumption occurs on-demand rather than through linear FAST channels. Moreover, Tubi's audience skews younger and more multicultural—demographically distinct from Fox News and largely composed of households without traditional cable subscriptions.
This demographic profile provides Fox with a structural hedge. The company operates both a top-rated linear news network serving an older demographic and a large free streaming service reaching younger viewers, with minimal audience overlap between the two platforms.
Where the Tubi story gets tested
Three strategic caveats counterbalance Tubi's growth narrative:
First, AVOD revenue per hour is a fraction of SVOD revenue per subscriber. While Tubi generates substantial viewing hours, its annual revenue of roughly $1 billion remains a modest fraction of Fox's total business. Engagement volume does not automatically translate into monetized yield, making Tubi's eventual contribution to consolidated net profit the key financial variable.
Second, Tubi's content advantage is a function of other people's strategy. The service relies on cheap catalog licensing because rival studios treat older titles as secondary inventory. If SVOD platforms retain rights for their own ad-supported tiers—a shift already underway across several major media companies—Tubi's content acquisition costs could rise. Fox management has not disclosed a long-term content cost trajectory, leaving current operating margins exposed to potential tightening in the licensing market.
Third, Tubi does not own its distribution. The service operates as a third-party application on external operating systems, leaving it subject to platform placement policies, revenue-sharing agreements, and distribution data restrictions. This structural dependency represents a key strategic vulnerability—one that Fox subsequently sought to address through its proposed acquisition of Roku.
The Venu interruption
The limitations of Fox's distribution position were highlighted in 2024 when Fox, Disney, and Warner Bros. Discovery announced Venu Sports, a joint venture designed to bundle their respective sports networks into a single direct-to-consumer streaming service. Independent distributor FuboTV filed an antitrust lawsuit, alleging that combining major sports rights into a joint platform constituted anti-competitive coordination. In August 2024, a federal judge issued a preliminary injunction blocking the service's launch,9 and the partners subsequently abandoned the venture.
The Venu outcome demonstrated a broader strategic constraint: in attempting to reach streaming consumers directly at scale, Fox faced either third-party platform tolls or regulatory intervention. Content ownership alone did not provide direct control over distribution access.
That constraint—operating as a content provider without owning the underlying distribution network—bridges the company's anti-streaming period to its subsequent strategic moves. Before evaluating the Roku transaction, however, Fox's capital allocation track record requires detailed examination.
V. Capital Allocation, Sports Gambling & Historical Falsification
Fox's reputation among investors rests substantially on a single word: discipline. The company sold its entertainment assets near the top of the market, resisted burning cash on subscription streaming, acquired Tubi at a modest valuation, and returned capital aggressively—repurchasing roughly $5.85 billion of Class A and Class B stock through the 2024–2025 period while maintaining an investment-grade balance sheet with limited near-term maturity pressure.[^12][^1]
That buyback volume represents a substantial share of the company's market capitalization, and the pace has been sustained rather than opportunistic. Management has framed share repurchases across earnings calls as the default deployment of free cash flow in the absence of superior reinvestment options, delivering on those commitment disclosures.
Yet a reputation for disciplined capital allocation warrants rigorous evaluation against the complete operating record rather than a curated list of successes. Examining the three primary claims supporting the Fox investment thesis against historical disconfirming evidence reveals a more nuanced trajectory.
Claim 1: The affiliate fee moat holds against cord-cutting
The claim: Fox's live programming provides sufficient bargaining leverage to raise per-subscriber carriage fees faster than the pay-TV subscriber base contracts.
The disconfirming evidence: The underlying subscriber base is shrinking rapidly. American linear pay-TV households fell from roughly 100 million in 2014 to approximately 50 to 55 million by 2025—cutting the addressable distribution universe in half over a decade. Meanwhile, Fox's financial disclosures show cable affiliate fee growth moderating to roughly 3% in FY2025.[^12] In a year of record consolidated revenue, the company's highest-margin recurring revenue stream grew at approximately the rate of inflation.
The underlying mechanics illustrate the constraint. Affiliate revenue is the product of per-subscriber rates and total subscriber volume. If subscribers drop 7% annually while carriage rates increase 10%, affiliate revenue grows by 2.3%. However, if subscriber losses accelerate to 9% while rate increases remain capped at 10%, affiliate revenue contracts. Growth depends entirely on distributor tolerance for price increases. The 2023 carriage dispute between Charter Communications and Disney—which temporarily blacked out ESPN and led Charter to declare the traditional cable bundle model broken—demonstrated that major distributors will risk channel blackouts rather than accept escalating rate cards.
Verdict: Historical evidence does not invalidate the claim, but it constrains its scope. The distribution moat remains functional—Fox continues to raise prices on a declining subscriber base—yet the thesis must be refined from permanent pricing power to conditional leverage that offsets volume declines only at current decay rates. The falsification threshold is clear and measurable: if annual pay-TV subscriber declines accelerate beyond roughly 8% while rate increases stay in the high single digits, affiliate revenue turns negative, causing Fox's highest-margin business unit to contract in absolute dollar terms.
Claim 2: Management allocates capital with discipline and resists diworsification
The claim: Fox avoids empire-building initiatives that eroded capital at peer media conglomerates.
The disconfirming evidence: Fox's own transactional history reveals several underperforming adjacency bets.
FOX Bet. In 2019 and 2020, Fox entered the U.S. sports betting market through a joint venture with Flutter Entertainment, launching FOX Bet on the premise that Fox Sports' broadcast audience could be converted into active gamblers at a lower customer acquisition cost than rivals DraftKings and FanDuel were incurring. That conversion thesis proved flawed. FOX Bet failed to gain meaningful market share, leading Flutter and Fox to shutter the platform in August 2023.4 Broadcast reach and sports-wagering customer acquisition proved to be distinct operational assets, with incumbent product platforms outperforming media cross-promotion.
Credible Labs. In 2019, Fox acquired a 67% stake in the consumer lending marketplace Credible Labs for approximately $265 million, valuing the business at roughly $397 million. The acquisition was premised on cross-selling mortgage and student loan refinancing to FOX Business viewers. Synergy benefits failed to materialize at scale, leaving the refinancing-focused platform vulnerable to macroeconomic shifts. When interest rates rose sharply beginning in 2022, consumer refinancing activity contracted, putting pressure on the asset's carrying value.1 Acquiring a rate-sensitive loan marketplace near the end of a multi-year low-interest-rate environment represented a notable timing miscalculation.
Bento Box Entertainment. Fox acquired the animation studio Bento Box Entertainment for roughly $50 million in 2019 to bring production capabilities in-house following the studio divestiture to Disney. While financially modest, the transaction fits a broader pattern of small, adjacent acquisition bets.
Verdict: The investment claim requires revision. Management has demonstrated discipline on major structural transactions—divesting general entertainment assets, abstaining from subscription streaming losses, and returning cash to shareholders—while exhibiting less rigor on smaller adjacent ventures funded on cross-sell assumptions. The operating record shows strong execution on portfolio-defining decisions alongside underperformance in venture-style adjacencies. This pattern is directly relevant when evaluating large-scale M&A justified by revenue synergy projections, warranting a conservative haircut to forward integration targets.
Claim 3: The FanDuel option is hidden optionality
The claim: Fox holds a valuable, underappreciated call option on the leading U.S. sports betting operator.
The record: Fox holds an equity stake in Flutter Entertainment alongside a ten-year option to acquire an 18.6% interest in FanDuel, exercisable through December 2030. Following a contested arbitration resolved in 2022, the exercise price was established based on a $20 billion FanDuel enterprise valuation that escalates by 5% annually.8 Exercising the option would require capital of approximately $4.5 billion, compounding each year the option remains unexercised.
Verdict: The option remains intact, but carries significant financial conditions. The agreement is not cost-free optionality; it represents a fixed purchase right with a substantial compounding strike price that requires significant cash funding. Furthermore, Fox's single attempt to operate a sports betting service directly was unsuccessful, making the FanDuel option a pure financial holding rather than an operational asset. The holding creates economic value if FanDuel's enterprise valuation expands faster than 5% per year, but it offers no direct operating synergies to Fox's core broadcasting business and competes for capital against other corporate deployments.
So what
Evaluating Fox's capital allocation history yields a more balanced assessment than standard bull or bear narratives suggest. The company's core distribution moat remains operational but mathematically bounded by subscriber decay. Capital allocation has proven effective at the macro level while producing mixed results across smaller adjacencies. Meanwhile, key financial assets represent valuable but capital-intensive holdings.
Beyond strategic and financial execution, however, lies an additional category of operational risk—one stemming not from capital deployment decisions, but from liability created on air.
VI. Legal Liabilities, Political Risk & The Murdoch Succession Trial
In the spring of 2023, a Delaware courtroom prepared for a major media trial. Dominion Voting Systems had sued Fox News for defamation over broadcasts alleging its voting machines rigged the 2020 presidential election. Pre-trial discovery produced a comprehensive public record of private communications between Fox hosts and executives during those broadcasts. However, on April 18, 2023, as opening statements were set to begin, Fox agreed to pay Dominion $787.5 million in cash — the largest publicly known defamation settlement in United States history.5
What the settlement actually means for a business analyst
From a corporate analysis perspective, the settlement established three key operational points:
First, the financial impact was manageable. Fox paid the $787.5 million settlement directly from cash reserves while continuing its share repurchase program. For a company generating billions of dollars in annual EBITDA, the settlement represented a substantial one-time expense rather than a structural threat to the balance sheet.
Second, the litigation exposed a fundamental tension in the business model. The commercial strength of Fox News rests on strong audience engagement and brand loyalty. Discovery disclosures revealed that host and executive decisions were heavily influenced by viewer retention concerns. Consequently, the mechanism that drives Fox's pricing power also generates a recurring legal liability. The distribution moat and the litigation exposure stem from the same audience dynamics, making legal risk an inherent operating factor rather than an isolated event.
Third, the settlement did not eliminate ongoing legal exposure. Smartmatic's $2.7 billion defamation lawsuit remains pending, continuing to generate discovery obligations and litigation risk.1 Because the ultimate outcome remains uncertain, financial models should treat potential future liabilities as an ongoing variable rather than assuming the Dominion settlement established a maximum liability cap.
The Dominion litigation also prompted operational changes, including stricter editorial oversight and the April 2023 departure of Tucker Carlson, then the network's prime-time ratings leader. Viewership recovered following his departure, with Fox News maintaining its position as the most-watched cable news network. This resilience demonstrated that brand equity resides primarily in the network brand and channel positioning rather than in individual on-air talent.
Reno
The second major legal issue centers on corporate governance and voting control.
The Murdoch Family Trust holds roughly 40% of the Class B voting shares of Fox Corporation, which — combined with the dual-class structure — gives the family effective control with far less than 40% of the economics.1 The trust was originally established as an irrevocable vehicle, distributing equal voting rights among Rupert Murdoch's four eldest children — Lachlan, James, Elisabeth, and Prudence — upon his death.
In 2024, reporting revealed that Rupert Murdoch had filed a sealed petition in probate court in Reno, Nevada, seeking to amend the irrevocable trust to grant Lachlan sole voting control after his death.6 Conducted outside public view, the filing aimed to override the equal-voting structure to preserve concentrated management and strategic direction.
For public shareholders, this ongoing trust dispute carries two distinct governance implications:
On one hand, the petition addresses a potential operational conflict. James Murdoch has publicly diverged from the editorial direction of Fox News. An equal-voting trust structure split among four siblings with differing strategic views could lead to boardroom deadlock or pressure to sell corporate assets.
On the other hand, the legal effort highlights the inherent limitations of dual-class ownership. A controlling shareholder litigating in sealed court proceedings to alter a public company's ultimate control vehicle underscores that public holders of Class A common stock (FOXA) have virtually no ability to influence corporate governance or succession outcomes.
While the Reno probate proceedings continue through judicial review, the strategic takeaway remains clear: the single largest discontinuity risk facing Fox Corporation is not cord-cutting or escalating sports rights fees, but an actuarial transition triggering a family control dispute. This succession risk exists entirely outside the influence of management, the board of directors, or public shareholders — a critical factor as the company evaluates major strategic commitments.
VII. The $22 Billion Roku Acquisition: The Connected TV Platform Bet
On June 15, 2026, Fox Corporation announced a definitive agreement to acquire Roku, Inc. for approximately $22 billion — $160.00 per Roku share, consisting of $96.00 in cash and $64.00 in FOXA stock.7
Set against the company's prior operating history, the transaction creates immediate strategic tension. Having established its market identity on capital discipline and avoiding costly streaming infrastructure, Fox committed a purchase price exceeding any prior transaction in its history—and larger than its entire cumulative stock buyback program. The deal transforms an asset-light, cash-generative broadcaster into a leveraged platform operator carrying a consumer hardware division.
The strategic logic, stated fairly
At its core, Roku produces the operating system powering tens of millions of television sets—the software gatekeeper that loads before a viewer selects a streaming application. The platform reaches well over 100 million streaming households.7 Rather than relying on low-margin hardware sales, Roku derives most of its revenue from platform economics: home-screen advertising, revenue-sharing agreements with hosted applications, and its own ad-supported channel.
In industry terms, Roku controls the interface where viewer decisions occur. The operating system owner dictates home-screen positioning, content promotion, viewer data collection, and advertising inventory splits.
Fox's strategic rationale follows directly from that.7 First, distribution ownership: after decades of relying on traditional pay-TV distributors whose subscriber bases are rapidly contracting, acquiring a leading connected-TV operating system replaces a shrinking distribution channel with an expanding platform. Second, Tubi integration: rather than operating as a third-party tenant paying revenue shares on Roku's home screen, Tubi becomes an integrated first-party service with preferred positioning and direct access to viewer data. Third, advertising technology: pairing Roku's targeted digital ad stack with Fox's live sports and news inventory allows the combined entity to sell premium live broadcasts with advanced digital measurement.
This logic reflects the operational lesson of the blocked Venu joint venture: content providers without direct control over distribution remain subject to platform gatekeepers.
The case against, stated equally fairly
It contradicts the established strategy. For seven years, management assured investors that Fox's competitive edge lay in avoiding the capital-intensive streaming cycle. The Roku transaction represents a massive investment in streaming infrastructure precisely as connected-television platforms face intense competition. While strategic shifts can be justified, the transaction eliminates the capital-discipline narrative that attracted investors seeking low-leverage, cash-generative media exposure.
It inherits a hardware business. Roku's device segment operates at or near breakeven by design. Fox has no experience in consumer electronics, supply chains, or component sourcing, creating operational complexity and exposing the company to global tariff and supply-chain risks.
The synergy thesis rhymes with prior failures. Fox's previous adjacent acquisitions—such as FOX Bet and Credible Labs—relied on converting broadcasting audiences into transactional customers, an approach that failed to deliver expected synergies. While the Roku acquisition involves an established platform with structural synergies rather than purely behavioral cross-selling, management's integration projections should be evaluated cautiously in light of that historical track record.
The balance sheet changes character. Funding the cash portion requires significant debt issuance, while the equity component dilutes existing shareholders. Combining higher financial leverage with a linear broadcasting segment subject to subscriber contraction creates a fundamentally different credit profile than the conservative balance sheet established in 2019.
The regulatory path is not clear. In September 2026 the Department of Justice issued a Second Request — the formal demand for extensive additional information that signals an in-depth antitrust investigation.[^9] Regulators are examining potential vertical competition concerns: specifically, whether a major content owner acquiring the distribution platform on which rival content owners depend would have the ability and incentive to favor its own service while disadvantaging competitors on the home screen. The preliminary injunction blocking the Venu joint venture demonstrates that courts have recently been receptive to exactly this kind of argument about Fox and its peers.9 Fox and Roku shareholders are scheduled to vote at special meetings on October 14, 2026.7
So what
The Roku acquisition transforms the investment thesis rather than merely extending it. Prior to the announcement, Fox operated as a low-leverage, cash-generative broadcaster harvesting legacy assets while benefiting from Tubi's upside. If completed, the acquisition redefines Fox as a leveraged connected-television platform operator whose success depends on integration execution, ad-tech competition against tech giants such as Amazon and Google, and navigating regulatory oversight. These demands require distinct operational capabilities and carry a different risk profile. Consequently, past performance under the anti-streaming playbook provides limited evidence of management's ability to execute a platform integration of this scale.
VIII. Strategic Moat & Framework Analysis
Strip away the narrative and ask the structural question: what, precisely, prevents a competitor from earning Fox's profits?
Hamilton Helmer's 7 Powers
Cornered Resource — High, but rented. Fox controls long-term rights to NFL, Major League Baseball, Big Ten, and NASCAR programming, alongside the FOX News brand. A cornered resource requires preferential access to a coveted asset on attractive terms. Sports rights satisfy the access criteria but fail on terms: they are leased, finite, and re-auctioned to the highest bidder. Every renewal cycle presents the risk of losing the asset or retaining it at a price that compresses returns. The brand equity of FOX News represents a far more genuine cornered resource — it cannot be bid away in an auction, it survived the departure of its top-rated host, and no competitor has replicated its audience relationship across three decades. It remains the more durable of the two.
Scale Economies — Moderate to High. Fixed costs across news gathering, broadcast infrastructure, and sports production are amortized over a major station group, national cable networks, and Tubi's advertising stack. These scale advantages are real but localized rather than absolute. Fox's total operational scale remains smaller than Comcast's or Disney's, while its advertising technology footprint is an order of magnitude smaller than those of Amazon and Google.
Counter-Positioning — High, but temporary. Tubi serves as a clear example of counter-positioning. Its free, ad-supported, catalog-driven model proved difficult for legacy subscription video-on-demand (SVOD) operators to match initially, as adopting a free model threatened to cannibalize the recurring subscription revenue underpinning their corporate strategies. Incumbents hesitated to imitate out of economic self-interest rather than operational oversight. However, this advantage narrows as SVOD platforms introduce ad-supported subscription tiers. Counter-positioning is structurally temporary; its primary value lies in buying time to establish alternative competitive powers.
Switching Costs — Low. Viewers face minimal switching costs, as changing a channel or closing an application requires no financial or operational friction. Viewer habit provides behavioral persistence, but habit differs from structural lock-in. Acquiring Roku would introduce modest switching costs, given that consumers replace television hardware infrequently and connected-TV operating systems are deeply embedded in the hardware interface.
Network Economies — Absent in core broadcasting; potentially present post-Roku. Linear broadcasting displays no network effects: FOX News does not improve for an existing viewer as additional viewers tune in. By contrast, a connected-TV operating system can generate two-sided network dynamics between content publishers seeking distribution and viewers seeking content choices. Establishing network effects represents the primary structural power the Roku transaction could add to Fox's portfolio.
Process Power and Branding — Branding is strong for FOX News, modest elsewhere. Process power is not evident.
Porter's Five Forces
Bargaining power of buyers (distributors) — High and rising. Pay-TV distributors represent a concentrated, consolidating buyer base facing ongoing subscriber contraction. Charter's willingness to accept a temporary channel blackout during its 2023 Disney negotiations established that distributors will risk carriage disputes rather than accept rising fee structures. Vertically, Fox's proposed Roku acquisition represents an attempt to alter this dynamic by controlling a primary distribution platform itself.
Bargaining power of suppliers (sports leagues) — Extremely high. Major sports leagues, led by the NFL as the single provider of premier live audience reach in the United States, sell rights to a bidding pool that now includes capital-rich technology platforms such as Amazon, Google, and Netflix. Because these buyers operate without traditional linear pay-TV margin constraints, rights fees escalate across renewal cycles. Consequently, the sports leagues capture the majority of the economic surplus created by live events, while networks compete for carriage rights. Treating sports rights as an exclusive moat rather than a high-cost supplier constraint misinterprets the primary direction of pricing power.
Threat of substitutes — High. YouTube commands the largest single share of U.S. television screen viewing time, while digital platforms, gaming, and social video compete directly for consumer attention. For news consumption specifically, audience substitution reflects a multi-year demographic shift away from linear broadcasts.
Threat of new entrants — Moderate, and asymmetric. Barriers remain high against launching a traditional broadcast network. However, technology firms have entered live sports broadcasting directly by deploying substantial balance sheets to acquire rights rather than building legacy broadcast networks. Fox faces low entry barriers in consumer attention markets alongside competitors with far greater capital resources.
Rivalry — High. Competition spans legacy media networks — including Disney and ESPN, NBCUniversal, Paramount, and Warner Bros. Discovery — as well as tech platforms. Rivalry concentrates most intensely at rights auctions, reinforcing the pricing power of sports leagues.
So what
Applying these frameworks reveals a defensible yet structurally constrained business model. Fox maintains strong brand equity in news and a temporary counter-positioning advantage in free streaming, set against high supplier power from sports leagues, rising buyer power among distributors, and broad consumer substitution. This structure allows the company to generate substantial cash flow from its existing asset base, even as its addressable linear audience contracts. However, the core competitive position does not expand organically — providing the underlying rationale for management's decision to pursue a major distribution platform acquisition.
IX. Bull vs. Bear Case & 3 Critical KPIs
The bull case
One: high cash conversion from live programming. FY2025's results demonstrated that when favorable cyclical tailwinds align, Fox converts viewership into operational profit efficiently.[^12] The critical distinction is between reported top-line growth and free cash conversion: Fox's Adjusted EBITDA yields strong free cash flow with minimal capital intensity because the company avoids maintaining an expensive production studio pipeline or heavy satellite infrastructure.
Two: Tubi's scale and Roku's distribution potential. Fox acquired the leading free ad-supported streaming service for $440 million net, expanded it past 110 million monthly active users, and reached standalone profitability.[^12] If the proposed Roku integration achieves management's target—featuring Tubi natively on a dominant connected-television operating system with unified advertising sales across live and on-demand inventory—Fox would combine premium live content with owned direct distribution at an industry-leading scale.7
Three: embedded optionality in FanDuel. At an exercise price based on a $20 billion valuation from 2022 compounding at 5% annually, an 18.6% stake in a platform expanding faster than that rate represents significant embedded equity value.8
Four: consistent capital return discipline. Repurchasing roughly $5.85 billion in shares across fiscal years 2024 and 2025 significantly reduced outstanding share count, reflecting a sustained return of capital rather than opportunistic announcements.[^12]
The bear case
One: contracting distribution volume offsets fee increases. High-single-digit carriage fee increases offset by near-equal subscriber losses yield minimal top-line expansion. Cable affiliate fee growth of approximately 3% in FY2025 serves as a leading indicator of this structural deceleration.[^12]
Two: escalating sports rights fees squeeze margins. Sports leagues maintain significant bargaining power during rights renewals, capturing a growing share of broadcast revenue. As technology platforms with non-traditional media economics bid aggressively for live events, future renewal cycles threaten to compress Television segment profitability further.
Three: legal exposures and governance structures create tail risk. Smartmatic's $2.7 billion defamation lawsuit remains pending, preserving substantial potential liability.1 Concurrently, the sealed Reno probate proceeding leaves future voting control tied to an unpredictable succession outcome.6
Four: the Roku transaction fundamentally alters the investment risk profile. Acquiring Roku introduces higher debt leverage, share dilution, operational exposure to a low-margin consumer hardware business, ongoing Department of Justice antitrust scrutiny via a Second Request, and reliance on revenue synergy assumptions similar to those that unraveled in previous adjacent ventures.[^9]4
The activist's stress test
A rigorous stress test of Fox's strategy highlights four operational and disclosure vulnerabilities:
Disclosure: Tubi's standalone financial metrics—including content amortization schedules, contribution margins, and monetization per viewing hour—are not fully broken out in public filings, making independent verification of its operating profitability difficult.
Governance: Dual-class share capital structures, sealed probate proceedings over voting control, and limited influence for public shareholders warrant a persistent governance discount.
Capital allocation: Management's request for investor confidence on the $22 billion Roku transaction comes after closing FOX Bet and writing down carrying values at Credible Labs.
Portfolio coherence: Operating a consumer lending marketplace within a national broadcasting network lacks a clear strategic fit with core media operations.
A balanced synthesis reveals that Fox is neither an unblemished compounder nor a terminal legacy asset. Rather, it operates a highly cash-generative broadcasting business facing structural linear decline, which has deployed capital to acquire a costly, high-risk option on digital platform distribution. Whether that $22 billion transformation creates long-term value depends entirely on operational integration rather than strategic projection.
The three KPIs that matter
Evaluating Fox's forward trajectory requires monitoring three critical metrics:
1. The spread between carriage fee rate increases and pay-TV subscriber losses. This relationship represents the fundamental determinant of legacy segment health. Comparing reported affiliate and retransmission fee growth against overall pay-TV subscriber attrition reveals whether pricing power offsets volume decline. As long as this spread remains positive, cash generation continues; if it turns negative, high-margin subscription revenue contracts in absolute terms.
2. Tubi advertising revenue growth relative to monthly active user growth. Audience expansion demonstrates engagement but does not guarantee profitability. The key operational metric is whether advertising revenue expands faster than user count—signifying improving advertising yields and higher revenue per viewing hour—or lags user growth, indicating under-monetized audience consumption.
3. Television segment operating margins net of sports rights commitments through renewal cycles. Top-line revenue expansion in broadcast is uninformative without analyzing associated rights costs. The key metric is whether Fox maintains segment margins following sports contract renewals. If operating margins decline permanently after renewal cycles, sports leagues are absorbing the economic surplus created by live broadcasts.
X. Strategic Playbook & Key Business Lessons
1. Sell when buyers prioritize strategic necessity over return metrics. The 21st Century Fox sale extracted $71.3 billion from two strategic bidders for assets whose underlying economics faced impending structural pressure.2 The transferable insight is not predicting the precise peak of a market cycle, but recognizing when industry competitors begin bidding out of strategic necessity rather than projected investment returns. A key caveat remains: because the transaction price was driven by an escalating auction between Disney and Comcast, the final valuation reflected rival urgency as much as seller timing.
2. Not competing is a deliberate strategy that requires enduring short-term narrative costs. Declining to build a general-entertainment subscription service exposed management to persistent market skepticism. Strategic discipline lay less in the economic analysis—which rival media executives privately shared—than in enduring the reputational penalty of standing outside industry consensus.
3. Free models can outperform paid platforms when consumer attention is the primary constraint. Tubi demonstrated that a broad consumer segment would accept advertising to avoid managing additional subscription fees, while the catalog content required to engage that audience could be licensed at low cost as secondary studio inventory.3 Value was created by capturing the market gap between costly subscription video-on-demand services and baseline viewer preferences.
4. Content perishability preserves distribution bundles. Live sports and breaking news maintain pricing power because their commercial value depends on real-time consumption. Once streaming made entertainment libraries on-demand and infinite, non-perishable programming categories became unbundled and substitutable.
5. Content ownership does not guarantee distribution control. The regulatory injunction blocking Venu Sports and the proposed acquisition of Roku illustrate complementary facets of the same operational constraint.97 Operating as a content provider on third-party platforms leaves a media company dependent on distribution gatekeepers—a position Fox sought to alter through a $22 billion platform transaction. While the long-term return on that acquisition remains an open question, the underlying structural diagnosis highlights the limits of relying solely on content ownership without controlling distribution.
XI. Management Credibility & Governance Stress Test
Executive Chairman and Chief Executive Officer Lachlan Murdoch returned to the family business in 2014 after a period away during the 2000s, assuming top leadership at Fox Corporation upon its formation in 2019. His employment contract extends through 2030, with total compensation reported at approximately $31 million for fiscal year 2026, weighted primarily toward performance-based equity.1 He leads an executive team that includes President and Chief Operating Officer John Nallen—a former CFO of 21st Century Fox with extensive transaction experience—and Chief Financial Officer Steve Tomsic, who has maintained direct, plain-spoken public disclosures relative to industry peers.
Assessing credibility through behaviour, not rhetoric
Narrative consistency: strong until 2026. From the company's 2019 formation through its fiscal year 2025 financial results, management presented a remarkably consistent operational narrative across earnings calls and investor presentations: focus on live content, rely on dual revenue streams, avoid subscription streaming, and return excess capital to shareholders.[^1][^12] Leadership resisted shifting this framework during periods when direct-to-consumer streaming was heavily favored by Wall Street, nor did the company launch a subscription service under a different moniker. In a sector where corporate strategy was frequently revised, that multi-year consistency established genuine credibility with public markets.
Execution against stated plans: strong at the macro level. Share repurchases were executed steadily in line with guidance.[^12] Tubi scaled into a profitable platform without incurring the multi-billion-dollar content liabilities that burdened competing media companies, while balance sheet leverage remained disciplined within stated target ranges.
Willingness to explain misses: mixed. Management publicly recognized the operational shortcomings of FOX Bet and shut down the platform rather than continuing to commit capital to an underperforming venture.4 By contrast, the underperformance of Credible Labs received limited detailed commentary, and the long-term strategic rationale for retaining a consumer loan marketplace alongside core broadcast assets has not been clearly articulated to investors.
The 2026 discontinuity. The proposed Roku acquisition represents a major departure from seven years of capital discipline, placing the onus on management to explain why the conditions justifying prior restraint no longer hold. The company's rationale—that direct control over distribution has become the primary operational constraint—is structurally logical and aligns with the regulatory blocking of the Venu joint venture.9 However, the transaction marks the first time this management team has asked shareholders to endorse a large, highly leveraged, integration-dependent acquisition. Because their historical record consists primarily of asset sales and capital discipline, prior success at abstaining from major acquisitions does not establish platform integration capability.
Governance: the weakest link, and structurally so. Dual-class voting concentrates effective control in a family trust whose future voting structure was litigated in a sealed Nevada probate proceeding that public shareholders discovered through media reports.6 Furthermore, executive compensation and board governance operate under controlled-company exemptions. Regardless of management's strategic track record, public Class A shareholders possess virtually no mechanism to influence board decisions or corporate direction. This structural arrangement justifies a permanent governance discount, amplifying the execution risks of major transactions where public shareholders lack formal checks on management.
Net assessment. Fox Corporation features a management team with a strong record on macro portfolio decisions, a weaker track record on minor adjacent ventures, high narrative consistency up to a major strategic shift in 2026, and governance arrangements that leave public investors entirely reliant on the controlling family's judgment. The pending Roku acquisition represents the first critical test of whether management's high-level strategic discipline translates into complex platform integration—an operational domain in which the team has no prior corporate track record.
XII. Recent News & Catalyst Watch
Four upcoming catalysts across regulatory, judicial, and corporate governance channels will shape Fox Corporation's trajectory over the next eighteen months.
The October 14, 2026 shareholder votes. Special meetings of Fox and Roku shareholders are scheduled to vote on the merger.7 For Fox, the dual-class share structure renders the official vote outcome largely predetermined, as the controlling Murdoch Family Trust commands effective voting power. Consequently, the primary analytical signal lies in the non-binding Class A shareholder vote: a high level of dissent among Class A holders would provide the clearest indicator that public investors view the company's platform pivot as a departure from its historical capital discipline.
The DOJ antitrust review. Following the Department of Justice's September 2026 Second Request, the regulatory review timeline will extend well beyond the shareholder vote.[^9] A Second Request typically entails months of document production, legal discovery, and negotiations. Regulators face three main paths: unconditional clearance, conditional approval tied to behavioral commitments—such as non-discriminatory home-screen placement and app-store terms for competing services—or a formal lawsuit to block the transaction. The preliminary injunction blocking the Venu Sports joint venture demonstrated that courts have recently shown a willingness to intervene against structural consolidation in video distribution.9 Analysts should monitor whether regulatory inquiries focus primarily on vertical foreclosure theories, which are often resolved through behavioral remedies, or broader competitive concerns.
The Reno probate ruling. A final judicial determination remains pending on Rupert Murdoch's petition in Nevada probate court to amend the family trust.6 If the court approves the amendment, Lachlan Murdoch's voting control will be locked in, ensuring strategic continuity through the proposed Roku integration. If the petition is denied, the original equal-voting structure remains intact upon Rupert Murdoch's passing, creating an immediate post-succession control dispute among four siblings with contrasting strategic visions. Because no financial metric can capture this outcome, the probate ruling represents a binary, unhedgeable variable with significant implications for future governance.
Smartmatic. Smartmatic's $2.7 billion defamation lawsuit continues to proceed through litigation, with a negotiated settlement representing a plausible path given the precedent set by the Dominion Voting Systems case.51 Although a potential payout represents a material cash outflow, the Dominion precedent indicates that such litigation is unlikely to threaten balance sheet solvency. The more significant operational risk stems from the evidentiary discovery process, which can expose internal communications that impair brand equity and viewer trust.
Beyond these discrete events, the company's quarterly operating metrics carry the primary underlying signal. Upcoming financial releases will track affiliate fee growth against subscriber attrition, Tubi's advertising monetization efficiency relative to audience expansion, and net Television segment margins following sports rights renewals—the three core indicators that will show whether the focused enterprise Murdoch created in 2019 can successfully execute a platform expansion or remain a maturing cash-harvest business.
References
-
Fox Corporation SEC Filings (Form 10-K & 10-Q) — SEC EDGAR ↩↩↩↩↩↩
-
Disney Completes Acquisition of 21st Century Fox Assets — Reuters, 2019-03-20 ↩↩↩↩
-
Fox Corporation Completes Acquisition of Tubi — Fox Corporation IR, 2020-04-20 ↩↩↩
-
Flutter and Fox Agree to Close FOX Bet Platform — Reuters, 2023-07-31 ↩↩↩
-
Dominion Reaches $787.5M Settlement With Fox News — Reuters, 2023-04-18 ↩↩
-
Rupert Murdoch Secret Family Trust Succession Battle in Nevada — The New York Times, 2024-09-02 ↩↩↩↩
-
Fox Corporation to Acquire Roku in $22 Billion Transaction — Fox Corporation IR, 2026-06-15 ↩↩↩↩↩↩↩↩
-
Flutter Arbitration Decision Regarding Fox FanDuel Option Valuation — Flutter Entertainment IR, 2022-11-04 ↩↩
-
Judge Issues Preliminary Injunction Blocking Venu Sports Launch — Wall Street Journal, 2024-08-16 ↩↩↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube