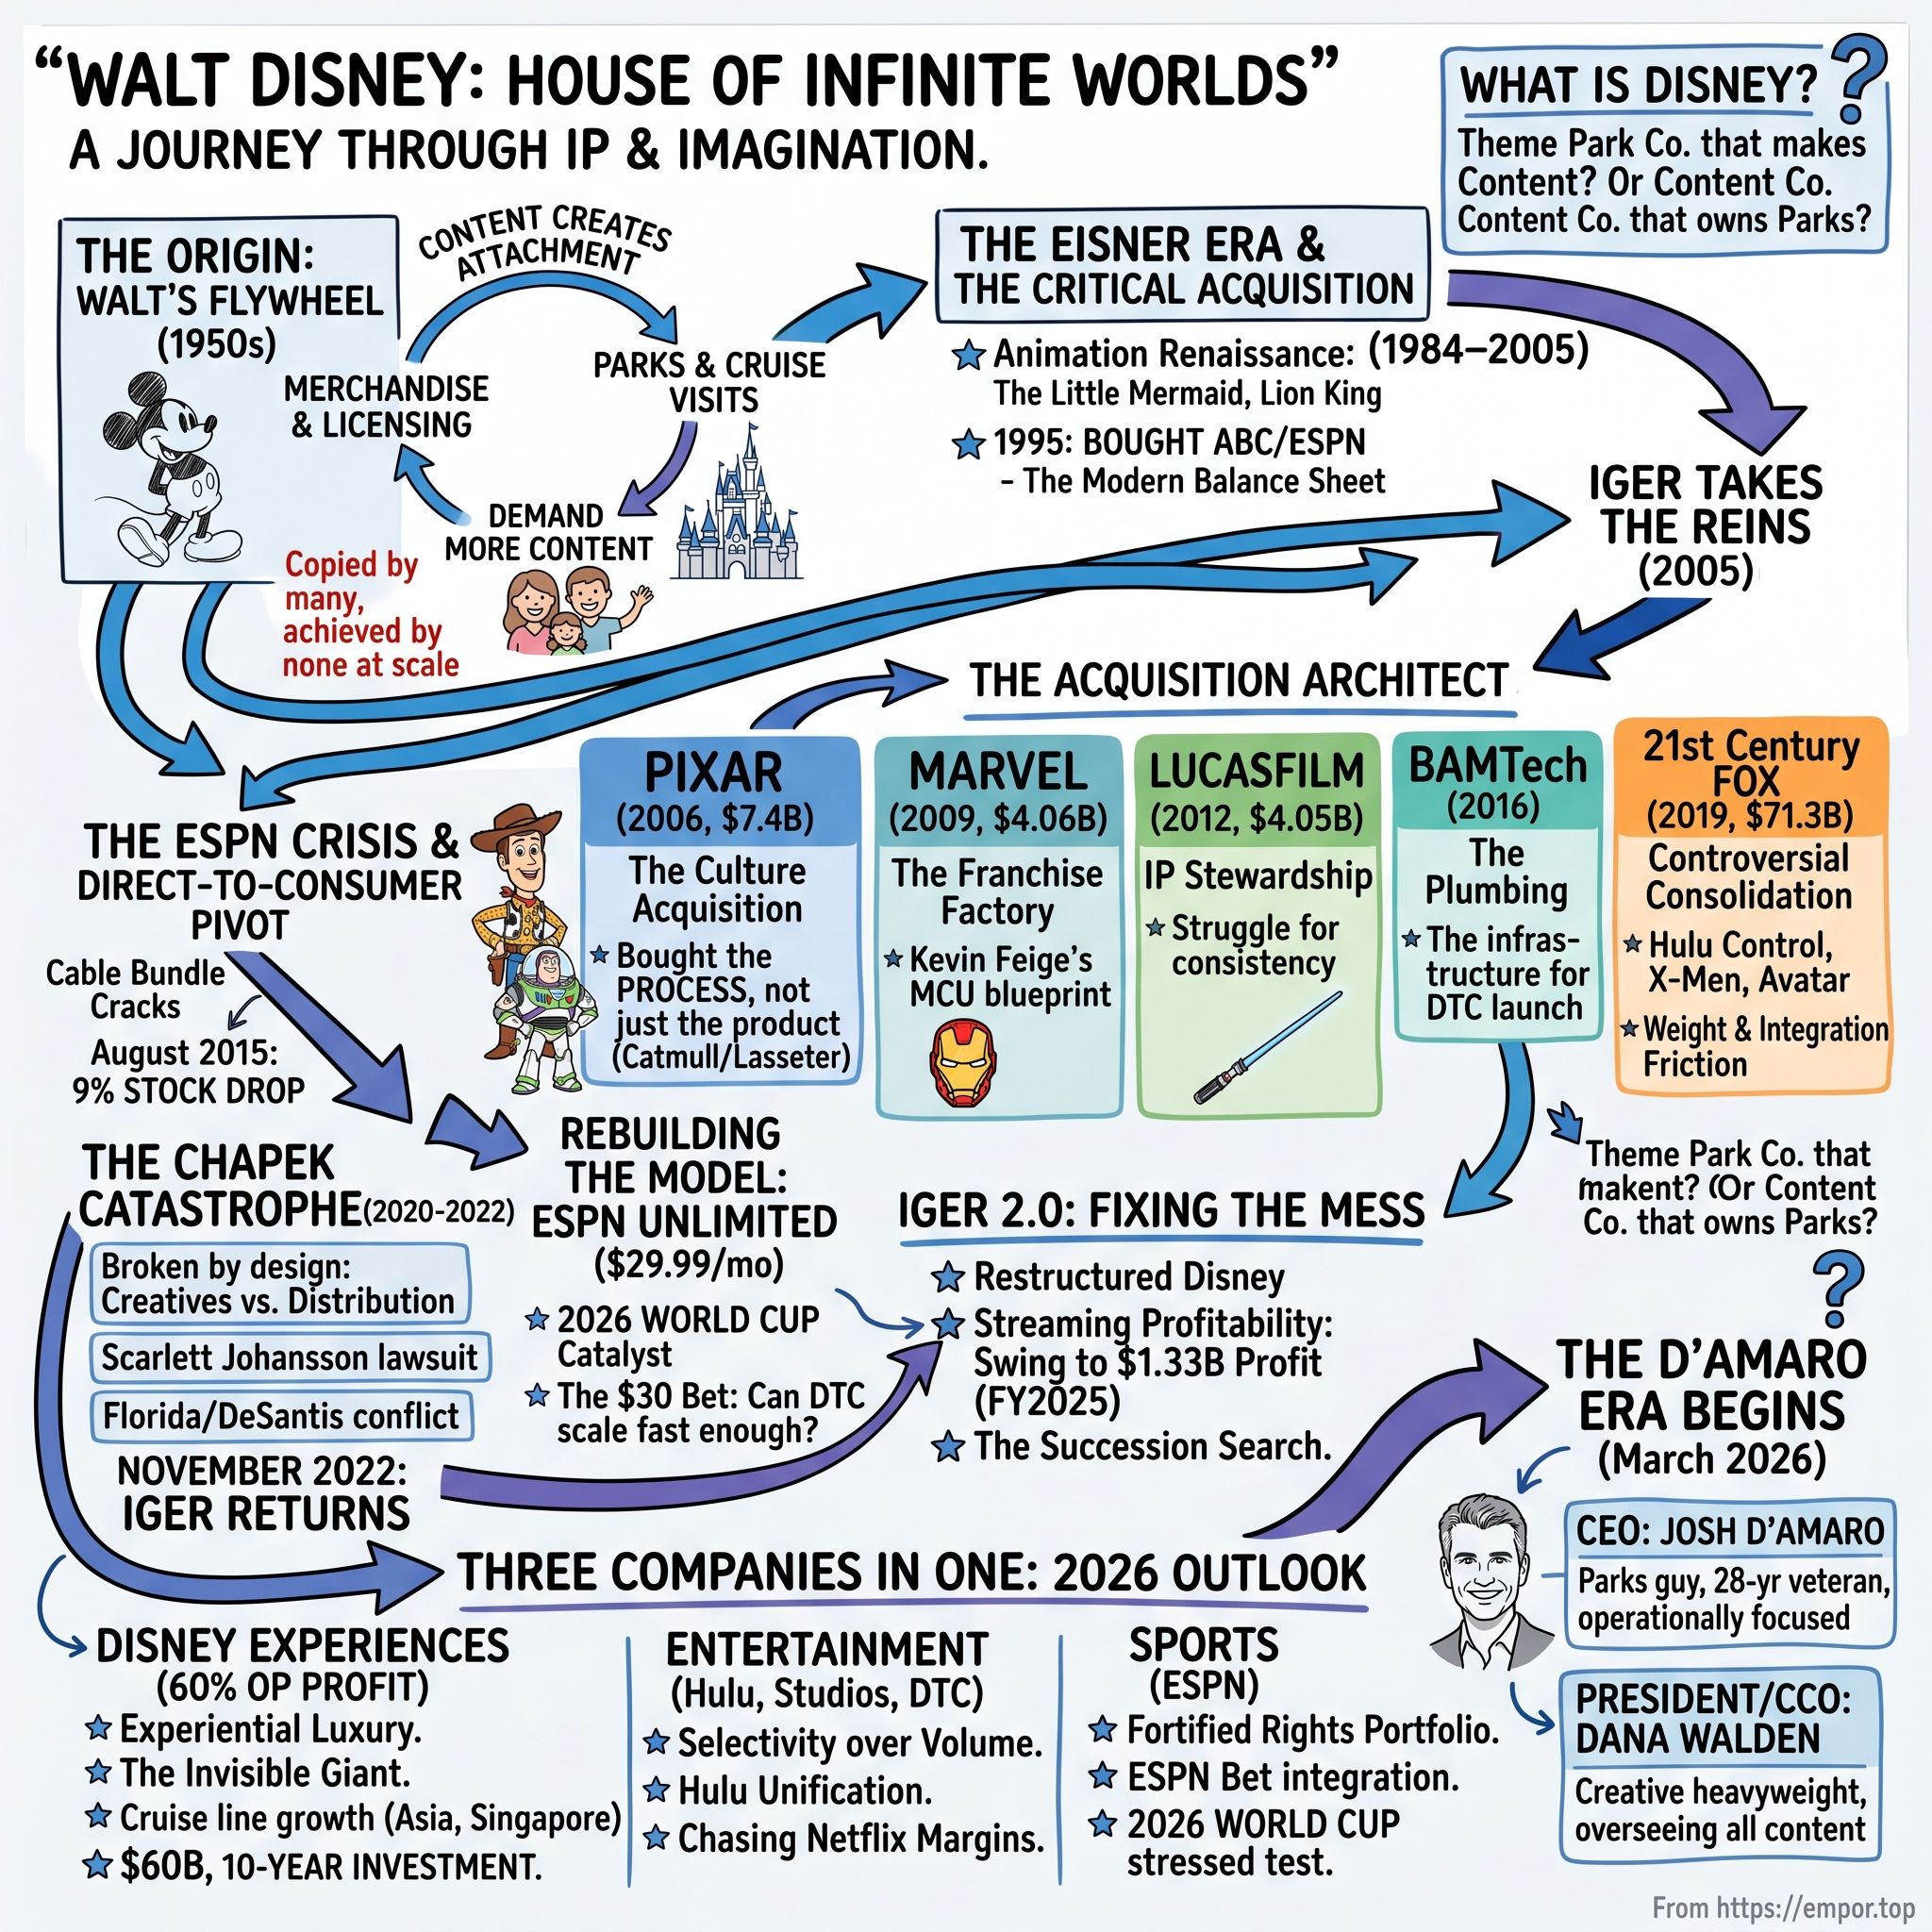
The Walt Disney Company: From Mickey Mouse to a Three-Segment Media Machine
I. Introduction & Episode Roadmap
Start with a sound. A tin whistle, played badly, by a mouse standing at the wheel of a steamboat. It is November 1928, the whistle is synchronized to the frame, and an audience in New York is watching a cartoon character make noise on cue for the first time in a way that actually works. That whistle is the foundation stone of everything that follows.
Now cut, hard, ninety-eight years forward. It is August 2026, and Josh D'Amaro is on a conference call with roughly thirty sell-side analysts, holding his first set of results as chief executive of The Walt Disney Company. The numbers are good. Total revenue rose 7% to $25.2 billion in the quarter, and total segment operating income climbed 21% to $5.56 billion, ahead of the company's own prior guidance.1 Disney Experiences — the theme parks, cruise ships, and consumer products business D'Amaro himself ran until earlier that year — posted record fiscal-third-quarter revenue of $10.0 billion and record segment operating income of $3.02 billion, up 20%.1 Streaming, which spent the better part of five years as one of the largest sustained cash-burn projects in the history of American media, threw off $712 million of operating income in the quarter, more than double the prior year.1
And yet.
On the day this article is written, Disney shares trade at roughly $105, giving the company a market capitalization of about $181 billion.2 Five years earlier, on September 8, 2021, the stock closed at $185.15. That is a decline of roughly 43% over a stretch in which the S&P 500 gained roughly 70%. An investor who bought Disney at the peak of the streaming enthusiasm and held has lost close to half their money in nominal terms while the broad market nearly doubled. That is the single most important fact about Disney as a stock, and no amount of record park income makes it go away.
So the question this piece is built around is not "is Disney a great company." Disney is obviously a great company by any measure of brand, catalogue, or cultural footprint. The question is narrower and harder: why has a business that has demonstrably improved — streaming from billion-dollar losses to double-digit margins, parks to record profit, a new sports app, a cleaner succession — been valued as though it has not?
There are three plausible answers, and they are not mutually exclusive. The first is that the market is wrong and is late. The second is that the improvements are real but are being offset, roughly dollar for dollar, by the melting of the linear television business Disney bought at enormous cost. The third is that the improvements are real but low quality — pricing power substituting for volume in the parks, subscription price increases substituting for creative hits in streaming — and the market is discounting the durability, not the level.
The roadmap: a fast pass through the founding decades, because the lessons matter more than the chronology; the Bob Iger acquisition era and what it actually cost; the Bob Chapek interregnum and why it broke; Iger's return and the most expensive proxy fight ever run; then the three segments in order of what actually generates profit rather than what generates headlines; the handoff to D'Amaro; and a bull and bear case with the mechanisms named rather than asserted.
We begin where the company began, with a young man in Kansas City losing control of a rabbit.
 Subscribe on LinkedIn
II. Origins in Brief: From Mickey to the Magic Kingdom (1901–1966)
In February 1928, Walt Disney rode a train from Los Angeles to New York with what he thought was a strong hand. He had a hit character — Oswald the Lucky Rabbit — and he was going to ask his distributor, Charles Mintz at Universal, for more money per short. Mintz's counteroffer was that Disney should take less money. And by the way, Mintz mentioned, he had already quietly hired away most of Disney's animators. And by the way, Universal owned Oswald outright.
Disney had built a business on an asset he did not own, staffed by people who could be bought. He rode the train back to California having lost both. The story is told inside Disney as a founding parable, and it deserves its status, because the lesson — own the intellectual property your economics depend on — is the single most durable thread running through the next century of the company's decisions. It is also a lesson the company has had to relearn expensively, more than once, including in living memory.
What Walt did in response was to invent something he owned. Mickey Mouse arrived that year, and the third Mickey short, Steamboat Willie, premiered in November 1928 with synchronized sound — a technical bet that turned a commodity product into an event. The strategic pattern established there repeats forever: take a technology the industry regards as a gimmick, spend more on it than seems rational, and use it to make your character indispensable.
Nine years later Disney did it again, at far greater risk. Snow White and the Seven Dwarfs was known around Hollywood as "Disney's Folly" — nobody believed audiences would sit for a feature-length cartoon, and Walt mortgaged his house to finish it. It became one of the highest-grossing films of its era and proved that animated features were a business rather than a stunt. What matters analytically is less the box office than what it created: a library. A film that could be re-released every seven years to a new generation of children was, in modern language, an annuity with a very long duration and almost no maintenance capex. Disney was building recurring revenue decades before anyone used the phrase.
The third move is the one most relevant to Disney today, and it is the least understood. In the 1950s Walt wanted to build a theme park and could not fund it. Television was the new medium, and the studios treated it as an enemy. Disney treated it as a marketing channel: he made a deal with ABC that gave him airtime and capital, and used the weekly television show — literally titled to promote the park — to sell America on Disneyland before a single guest walked through the gate. Disneyland opened in July 1955.
Read that carefully, because it is the same argument Disney is having with itself in 2026. Walt did not ask whether the television show was profitable on a standalone basis. He asked whether it drove the thing that was profitable. Seventy years later the company is running the identical calculation in reverse — whether a streaming service and a sports app are standalone profit centers or funnels that feed the parks, the merchandise, and the brand. The flywheel was never an abstraction. It was a financing structure.
Walt died in December 1966, of lung cancer, at 65, with Walt Disney World still a set of drawings. What followed was roughly fifteen years of a company asking "what would Walt do" and getting no answer. The parks kept running. The animation atrophied. By the early 1980s Disney was a takeover target with a magnificent library it had stopped adding to — which is exactly the condition that invites a boardroom fight.
III. Empire in Transition: Eisner, Stagnation, and the Groundwork for Iger (1966–2005)
The 1984 crisis is worth thirty seconds. Corporate raiders circled, the family split, and the board ended up installing Michael Eisner from Paramount as chief executive with Frank Wells as president. What followed was one of the great turnarounds in American corporate history: The Little Mermaid, Beauty and the Beast, Aladdin, The Lion King — a decade in which Disney Animation went from moribund to a machine that reliably produced billion-dollar franchises across film, merchandise, and Broadway.
The move that matters most for understanding Disney's 2026 income statement, though, was not creative. It was the roughly $19 billion acquisition of Capital Cities/ABC in 1995. Disney bought a broadcast network. What it actually bought, in hindsight, was ESPN — which came along inside Capital Cities and which, for the following twenty-five years, was arguably the most profitable single asset in American media. Cable operators paid ESPN more per subscriber than any other network, and they paid it for every household, including the ones that never watched a game. That is not a media business; that is a tax.
The ESPN cash machine funded a great deal, and it also hid a great deal. It hid the fact that Eisner's late tenure went badly: Frank Wells died in a helicopter crash in 1994; the Michael Ovitz hire lasted fourteen months and cost well over $100 million to unwind; the relationship with Steve Jobs and Pixar — which by then was making the animated films Disney could no longer make itself — deteriorated to the point of public rupture; and Roy E. Disney, Walt's nephew, ran a "Save Disney" campaign that culminated in a 43% withhold vote against Eisner at the 2004 annual meeting. The board stripped him of the chairmanship. He was gone by 2005.
Two patterns are worth carrying forward, because both recur.
First, Disney's most expensive strategic errors have consistently been errors of dependency — relying on creative capability or IP it did not own. Oswald in 1928. Pixar in 2004, when the company's animation pipeline had become a distribution deal with a partner that was about to walk. The company's answer, when it finally gets one, is always the same: buy the thing you depend on.
Second, Disney's governance failures are not random. They cluster around succession. Eisner's inability to build a bench, the Ovitz disaster, and later the Chapek reversal are three instances of the same institutional weakness, and any assessment of the 2026 handoff has to be made against that base rate rather than against a generic corporate average.
The man who succeeded Eisner had been quietly running ABC when Disney bought it. He was not the obvious pick. He was, by his own account, nearly passed over. And his diagnosis of Disney's problem was blunt enough to structure the next fifteen years.
IV. Act One of Iger: Building the IP Fortress (2005–2019)
Bob Iger's first board presentation as a CEO candidate reportedly rested on three priorities, and the first was that Disney's own creative pipeline had stopped working. This was an unusual thing for an internal candidate to say out loud. His conclusion was more unusual still: rather than spend a decade trying to rebuild Disney Animation from the inside, buy the studio that had already beaten it.
Pixar, $7.4 billion, January 2006. An all-stock deal that made Steve Jobs Disney's largest individual shareholder and, critically, installed John Lasseter and Ed Catmull at the head of Disney's own animation studio rather than quarantining them at Pixar. The financial return is well documented across Toy Story, Up, Inside Out, and Coco. The less-quantified return was the restart of Walt Disney Animation Studios itself — Tangled, Frozen, Moana, Zootopia. Buying Pixar bought the capability, not just the catalogue, and the capability compounded. This is the deal against which every subsequent Disney acquisition is measured, and by the standards of large-cap media M&A it looks conspicuously underpriced relative to what it generated across film, parks, and merchandising over the following two decades.
Marvel, $4 billion, 2009. Iger bought Marvel when it was, in operational terms, a licensing company with a modest film slate and a balance sheet that had emerged from bankruptcy a decade earlier. Disney did not buy a functioning studio; it bought roughly five thousand characters and a man named Kevin Feige. The Marvel Cinematic Universe that followed has grossed something on the order of $30 billion at the global box office cumulatively — an outcome that makes the purchase price look like a rounding error, and which also, more subtly, gave Disney's parks a new source of attraction IP for the first time in a generation.
Lucasfilm, $4.05 billion, 2012. Here the record is more mixed, and it is worth saying so plainly because it complicates the tidy narrative of the first two deals. The asset value was extraordinary and remains so — Star Wars merchandise, the Star Wars: Galaxy's Edge lands at both domestic resorts, and The Mandalorian as a streaming anchor. The execution on new Star Wars filmmaking has been uneven: a sequel trilogy that split the fanbase, a spin-off (Solo) that underperformed, a multi-year gap in theatrical releases, and a 2026 theatrical return that did not meet expectations. The honest reading is that Disney bought a great asset and has managed the creative output of that asset less well than it managed Marvel's. "IP acquisitions always pay off" is not the lesson; "IP acquisitions pay off when you also inherit or install a functioning creative leadership structure" is closer.
The Fox deal, and what it actually cost
Then there is the outlier.
In 2017 and 2018, Disney and Comcast fought a genuine bidding war for the entertainment assets of Twenty-First Century Fox. Comcast pushed an all-cash counteroffer to roughly $65 billion before withdrawing. Disney won at $71.3 billion and closed in March 2019.3 It was, by a wide margin, the largest acquisition in the company's history and a bet-the-company move by a CEO who had made his reputation on smaller, surgical purchases.
The stated logic was scale: X-Men and Deadpool returning to Marvel, the Avatar franchise, National Geographic, FX, the Fox film and television libraries, and — the piece that mattered most strategically — Fox's 30% stake in Hulu, which took Disney to a controlling position in the only general-entertainment streaming platform it could build a two-brand bundle around. This was to be the ammunition for the streaming war Disney was about to enter.
Seven years on, the deal has to be split in two, because the two halves have performed very differently.
The content half worked. Hulu became the adult-skewing complement to Disney+ that the bundle strategy required. Disney completed the buyout of Comcast's remaining stake at a total cost of roughly $9.0 billion — an initial $8.61 billion agreed in 2023, plus a further $438.7 million determined by a contractual appraisal process that concluded in June 2025 and closed the following month.4 That final number matters: NBCUniversal's own appraiser had argued for a substantially higher valuation, and Disney at one point warned it might owe up to $5 billion more. It did not. On this piece of the Fox transaction, Disney paid less than the counterparty wanted, which is a reasonable data point on negotiating discipline.
The distribution half has not worked, and Disney's own filings say so. In fiscal 2024 the company recorded non-cash impairment charges of approximately $1.5 billion in connection with the Star India transaction — the Indian business that came with Fox, contributed into a joint venture with Reliance's Viacom18 — alongside goodwill impairment losses of roughly $1.29 billion at the entertainment linear networks reporting unit, recognised in two tranches during the year.56 These are not abstractions. They are the accounting system marking down assets Disney acquired directly in the Fox deal, in the same segment, within five years of buying them.
Management's own behaviour is the strongest evidence available. Iger has publicly floated that ABC, FX, National Geographic, and Freeform may not be core to Disney's future — which is a tacit concession that a meaningful slice of what $71.3 billion bought is a business the company would like to shrink or exit rather than integrate. And in August 2026 Disney sold its 50% stake in A+E Global Media, home of A&E, History, and Lifetime, to Hearst for $1.2 billion in cash.7
Weighing it. The claim that Disney's M&A record demonstrates "transformative, disciplined dealmaking" survives for Pixar and Marvel, is narrowed for Lucasfilm, and does not survive intact for Fox. The accurate version is: Disney paid a control premium in a live auction, won content IP that has real ongoing value, and simultaneously acquired a large pile of linear television assets whose economics deteriorated faster than the purchase price assumed. Roughly $2.8 billion of impairments across fiscal 2024 is the company's own quantification of part of that error. The falsifiable follow-up is straightforward: watch whether the entertainment linear networks reporting unit takes further write-downs, and at what price the remaining non-core networks are eventually sold, if they are sold at all.
One further caveat on the M&A record, offered as an honest limitation rather than a conclusion: a rigorous verdict on Fox would benchmark $71.3 billion against comparable transactions — Amazon–MGM at $8.5 billion in 2022, or the WarnerMedia–Discovery combination — on a per-subscriber or EV/EBITDA basis. Directly comparable sell-side multiple analysis was not located in the research for this piece, and it would be worse than useless to invent one. The impairments stand on their own.
Whatever the price, the assets were in the building by March 2019. Eight months later Disney used them.
V. The Streaming Gambit, COVID, and the Chapek Stumble (2019–2022)
Disney+ launched on November 12, 2019, and promptly fell over. Demand overwhelmed the servers on day one — a problem every product manager would trade almost anything for. Into the new service went the entire fifteen-year accumulation: Pixar, Marvel, Star Wars, the Fox library, National Geographic. The whole acquisition era, in one app, for $6.99 a month.
Four months later the world shut down.
COVID-19 hit Disney harder than almost any company of its size because it hit every segment at once and in the same direction. The parks — then as now the profit engine — closed entirely. Cruise ships docked. Theatrical distribution, the front end of the whole flywheel, ceased to exist as a business for over a year. And the one thing that worked, spectacularly, was the streaming service, which added subscribers at a pace nobody had modelled because several hundred million people were sitting at home.
This produced the single most consequential misreading in Disney's recent history, and it was a misreading the entire market participated in. Subscriber growth was treated as the metric. Wall Street rewarded it. Disney's stock hit an all-time high in March 2021 on the strength of a business that was losing billions of dollars a year. Content spending escalated to chase the number. Direct-to-consumer losses ran into the multiple billions annually. The company was, in effect, buying subscribers at a price it had never underwritten because the market was applying a subscriber multiple rather than a profit multiple.
Presiding over this was Bob Chapek, who became CEO in February 2020 — announced abruptly, with Iger moving to executive chairman. Chapek had run the parks and had a reputation as a disciplined operator, and in fairness he ran a genuinely difficult reopening competently. But his tenure produced a series of trust failures that had nothing to do with operating metrics.
The first was Scarlett Johansson. Disney released Black Widow simultaneously in theatres and on Disney+ Premier Access in July 2021. Johansson sued, alleging the day-and-date release breached her contract and gutted her box-office-linked compensation. Disney's response was not a legal argument but a personal one — a public statement noting her salary and suggesting callousness toward the pandemic. The suit settled, but the message to every A-list talent representative in Hollywood had been delivered: this management will attack you publicly over an accounting dispute. For a company whose supply chain is creative talent, that was an unforced error with a long tail.
The second was Florida. In 2022 the state passed the Parental Rights in Education act. Chapek initially declined to comment, then reversed under internal pressure and opposed it, which satisfied nobody and antagonised the governor. Governor Ron DeSantis moved to dissolve the Reedy Creek Improvement District — the special self-governing tax district that had let Disney manage its own infrastructure, permitting, and services at Walt Disney World since 1967 — replacing it with a state-appointed oversight board. The litigation ran for two years and settled in March 2024.8
The settlement resolved the legal dispute. It is less clear that it resolved the operating consequence. Disney has not announced a fifth theme park gate at Walt Disney World, and reporting has linked that restraint to the political relationship. That is the analytically interesting part: a governance fight cost Disney not a fine but an option — the ability to deploy capital into its most valuable land bank without political risk. Regulatory overhang for a park operator does not look like a penalty; it looks like a project that never gets announced.
By November 2022 the board had seen enough. Earnings had missed badly, streaming losses had widened, and on November 20, 2022, the board removed Chapek and reinstated Iger with a two-year contract.9
It is worth being precise about what that decision was. It was not a strategic pivot. It was the board admitting that its own succession process, executed less than three years earlier, had failed — and reaching backward for the person it had just replaced. That is the most damning available evidence on Disney's governance, and it sets the bar the 2026 succession has to clear.
VI. The Return: Iger's Turnaround and the Trian War (2022–2025)
Iger came back to a company with a cost structure built for a subscriber-growth thesis nobody believed anymore.
The response was fast. In February 2023 he announced a restructuring targeting $5.5 billion of cost savings and roughly 7,000 job cuts, split across content spend and non-content operating expenses. By November 2023 the target had been raised to $7.5 billion. Content budgets were cut, marketing was rationalised, and — most importantly for the streaming economics — Disney stopped treating subscriber additions as the objective function and started raising prices, cracking down on password sharing, and building an advertising tier.
Then the activist arrived. Twice, in fact.
The Trian fight
Nelson Peltz's Trian Partners first pushed for a Disney board seat in late 2022, stood down when Iger returned, and came back harder in late 2023 with a stake reported at up to roughly $3.5 billion — much of it economic exposure supplied by Isaac Perlmutter, the former Marvel chairman whom Disney had fired earlier that year, which gave the campaign an unmistakable personal edge. Trian nominated Peltz and Jay Rasulo, Disney's own former chief financial officer, to the board.
The complaints were: streaming losses with no credible path to profit, capital allocation that had produced the Fox impairments, and — the sharpest one — a succession process that had already failed once and showed no sign of having been fixed.
Here is the uncomfortable thing about that list: it was largely correct, and it was largely the same list Iger was already working through. The cost programme, the shift to streaming profitability, the reinstated dividend, and the formal succession committee were all responses to exactly the problems Trian named. Whether they were caused by the activist pressure or merely coincident with it is unknowable from outside, but the direction of travel is not in dispute.
What followed was, by widely cited estimates, the most expensive proxy fight in corporate history — combined spending on the order of $600 million across advertising, solicitation, and advisory fees. Disney mobilised everything: George Lucas, Jamie Dimon, Laurene Powell Jobs, and Abigail Disney all publicly backed the board. Retail shareholders, who own an unusually large slice of Disney because so many of them received shares as gifts, broke heavily for management.
The outcome at the April 3, 2024 annual meeting was not close.10 Iger was re-elected with roughly 94% support. Peltz drew roughly 31% of the votes cast against incumbent director Maria Elena Lagomasino — a loss of about two to one. Rasulo lost by a wider margin still, roughly five to one.11 Peltz sold Trian's entire Disney position the following month, reportedly realising around $1 billion of gains on the way out.12
Two readings of that result deserve equal weight. The generous one: shareholders assessed a specific turnaround plan against a specific critique and endorsed the incumbents, and the subsequent arrival of streaming profitability suggests they read it correctly. The sceptical one: Disney spent a fortune, deployed celebrity endorsements, and leaned on a retail base structurally inclined to vote with management. A 94% vote purchased at that cost is a weaker signal than a 94% vote obtained cheaply.
The tiebreaker is what happened next, and it favours the generous reading. Streaming reached operating profitability on roughly the timeline management had promised. That is the relevant test of credibility — not the vote, but whether the thing they said would happen, happened, on the schedule they said.
The other activist
The contrast case is instructive and gets far less attention. ValueAct Capital built a Disney position and, in January 2024, signed an information-sharing agreement with the company and publicly backed the board's slate. Same industry, same company, same set of problems, opposite method: engagement rather than confrontation. It is a useful reminder that "activist involvement" is not a single phenomenon, and that a company being targeted by an activist tells you much less than which activist and on what terms.
Capital returns resume
The financial punctuation mark came in December 2023, when Disney reinstated a dividend for the first time since the pandemic suspension — a small one, deliberately, at 30 cents per share semi-annually. It has been raised twice since. Buybacks restarted and have accelerated: $3 billion in fiscal 2025, guided to $7 billion for fiscal 2026 and subsequently raised in-year to at least $9 billion.113
The dividend reinstatement is worth reading as a signal rather than a payout. A company that suspends its dividend is telling you it is not sure about its cash flows. A company that reinstates one at a deliberately modest level, then raises it twice, is telling you it now is — and building credibility incrementally rather than making a promise it might have to break. After the Chapek era, incremental credibility was the scarce commodity.
Which brings us to where the money actually comes from — and it is not where most people assume.
VII. Disney Experiences: The Profit Engine
Walk into the Magic Kingdom on a Tuesday in July and the thing you notice, if you are looking at it as an investor rather than a parent, is the number of transactions. Not the rides. The transactions. A family of four has already paid for tickets, parking, a hotel room on property, a Lightning Lane multi-pass to skip queues, breakfast with a character, a Mickey pretzel, two sets of light-up ears, and a photo package. Disney's genius in this segment is not that it built a park. It is that it built a place where a family voluntarily makes fifteen purchasing decisions a day and describes the experience as magical.
The numbers say this is the company. In fiscal 2025, Experiences generated $36.2 billion of revenue — less than the Entertainment segment's $42.5 billion — but produced $10.0 billion of segment operating income against Entertainment's $4.7 billion.13 That is roughly 57% of Disney's total segment profit from a business most people think of as the marketing department for the movies. Fiscal 2025 was a record year for the segment, and the momentum carried into the new CEO's first quarters: record fiscal-third-quarter revenue of $10.0 billion, up 10%, and record segment operating income of $3.02 billion, up 20%.1
Anyone building a mental model of Disney should invert the popular one. This is a capital-intensive, high-margin, real-asset hospitality and consumer-products business that owns a film studio, rather than a film studio that happens to own some parks.
The pricing-power question, weighed honestly
Now the part that requires care, because it is the crux of the moat argument.
Disney's fiscal 2025 disclosures showed domestic park attendance down 1% for the year, following a 1% increase in fiscal 2024. Over two years, in other words, domestic attendance went nowhere. Over the same two years, domestic per-capita guest spending rose 3% and then 5%, driven by higher prices on tickets, parking, food, and merchandise.14 That combination — flat bodies, rising spend per body — is what produced a record $10.0 billion of operating income.
What does this mean? It means the pricing power is real and demonstrated. Disney raised prices materially, across a broad basket, in a period of consumer stress, and guests paid. Very few businesses can do that. It is genuine evidence of a cornered resource: there is no substitute for the Disney characters, and a family that has decided to take its children to see them has limited ability to shop the purchase elsewhere.
But it also means the pricing power has been substituting for volume growth rather than adding to it. Those are different businesses with different durations. A park that grows attendance and price is compounding. A park that holds attendance flat and raises price is harvesting, and harvesting has a terminal point — the price at which the marginal family decides the week at Disney World is not worth it and books something else. Nobody knows where that point is. Disney does not know where it is. What we know is that the company has been walking toward it for two years.
There was a genuine improvement in the most recent quarter: on the fiscal Q3 2026 call, management reported global guest growth of 4%, domestic attendance up 3%, and per-capita spending up 4% — the first stretch in a while where the volume line contributed alongside price.15 One quarter does not resolve a two-year trend, and the year-ago comparison was soft, but it is the right variable to watch and it moved the right way.
Enter the competition
For fifty years Orlando was effectively a Disney monopoly with a smaller neighbour. That changed on May 22, 2025, when Comcast opened Epic Universe — a full-scale fourth Universal Orlando park reportedly costing well over $10 billion, the first genuinely new large-scale theme park competitor in that market in a generation.16
The pre-opening analysis was cautious for Disney. Post-opening, the picture is more nuanced than either side's talking points. Third-party projections from MoffettNathanson had Walt Disney World attendance holding roughly flat at around 55 million guests through 2026 while Epic Universe drew several million visitors of its own — which is the signature of a market that expanded rather than one that got divided.16 Comcast executives have separately characterised the impact on their own legacy Orlando parks as minimal, which points the same way. A destination with more to do supports longer trips, and longer trips can lift everyone's attendance.
The intellectually honest position is that the jury is out. Epic Universe's first year is its novelty year, when it draws the enthusiasts who were always going to come. Year two and year three are the real test — and they arrive precisely when Disney needs its own pricing to keep working. The competitive question is not whether Epic Universe steals Disney's guests. It is whether the existence of a credible alternative constrains Disney's ability to keep raising prices 4-5% a year. That is the mechanism through which this competitor actually damages Disney, and it will show up in the per-capita spending line long before it shows up in attendance.
Where the capital is going
Disney's answer to all of this is to spend. In September 2023 the board approved a plan to roughly double capital investment in the Experiences segment over ten years, to approximately $60 billion.17 The money is going into new lands at the Magic Kingdom and Disneyland, expansions at Shanghai and Hong Kong, and a near-doubling of Disney Cruise Line's capacity, including the Singapore-homeported Disney Adventure. Capital expenditure guidance for fiscal 2026 was set at approximately $9 billion.13
Cruise is the most interesting piece of that allocation and the least discussed. It is the Disney model at its most concentrated: a captive guest for seven days, no competing attractions, all spending on-ship, and the ability to add capacity by ordering a hull rather than buying land. If per-capita spend is the metric that matters, a cruise ship is a theme park where nobody can leave.
Then there is the asset-light bet. On May 7, 2025, Disney and Miral announced Disneyland Abu Dhabi on Yas Island — Disney's seventh theme park resort and its first in the Middle East. The structure is what makes it notable: Miral fully develops, builds, and will operate the resort, while Disney provides creative design and operational oversight through Imagineering.18 Disney's own framing is that this expands the portfolio without Disney capital; the specific royalty and licensing economics were not disclosed.
That is a genuine option, and it is sized appropriately here as a sub-point rather than a headline. The park is under construction, contributes no near-term revenue, and its financial contribution has not been quantified publicly. What it demonstrates is a learned discipline: Disney now operates across a full spectrum of capital exposure, from wholly-owned Anaheim and Orlando, through the joint ventures and licensing arrangements at Tokyo, Paris, Hong Kong, and Shanghai, to a structure in Abu Dhabi where it puts in creative work and takes out fees. Given that Euro Disney's early years were a near-catastrophic capital sink requiring multiple restructurings, the evolution toward letting someone else own the concrete is not an accident.
The man who ran this segment through all of it — the capex plan, the Epic Universe response, the Abu Dhabi deal — took the top job in 2026. But before we get to him, we need to look at the two segments that generate the headlines and rather less of the profit.
VIII. Entertainment & Streaming: From Cash Furnace to Profit Center
There is a specific quarter that deserves a marker. In fiscal Q2 2024 — the three months ended March 2024, in the middle of the Trian proxy fight — Disney's combined direct-to-consumer streaming operations turned an operating profit for the first time. It was a small number. It followed years of quarterly losses measured in the high hundreds of millions. And it arrived roughly when management had said it would, which is the part that mattered.
The trajectory since has been steep. DTC operating income went from $143 million in fiscal 2024 to $1.327 billion in fiscal 2025, on revenue of $24.6 billion.13 By fiscal Q3 2026, Entertainment SVOD operating margin reached 12.9%, and management reaffirmed guidance for a double-digit full-year margin in fiscal 2026.115 Disney+ ended fiscal 2025 with approximately 132 million paid subscribers and Hulu with approximately 64 million.14
How did they do it? Not primarily through subscriber growth. Through price increases, an advertising tier, password-sharing enforcement, and cutting content spend — the classic mature-subscription playbook. The FY2025 disclosures attribute the improvement to "higher effective rates, reflecting increases in pricing" alongside subscriber increases, partially offset by higher programming and marketing costs.13 This is a margin story built on monetising an installed base, which works well and is also, by construction, finite.
The strategic question, asked on the record
On the fiscal Q3 2026 call, Wells Fargo's Steven Cahall put the sharpest available question to the new chief executive: given how difficult and expensive owning a streaming platform has been, should Disney go back to being an arms dealer — licensing its content to Netflix and others and collecting the cheque?
D'Amaro's answer was a direct defence of the platform. He argued that Netflix had proven streaming can be a highly attractive business with recurring and predictable revenue, noted that Disney's current margins at comparable revenue scale are similar to where Netflix stood at the same point in its own trajectory, and made the data argument: a large global user base is strategic, providing a first-party dataset that enables personalisation. Exiting DTC for pure licensing, he concluded, "would likely lead to both inferior strategic and financial positions."15
That is the correct argument to make, and it is also a claim that needs testing rather than acceptance. The Netflix-at-similar-scale comparison is management's chosen framing, and it flatters Disney by aligning on revenue rather than on time or competitive context — Netflix built its margin structure in a market it largely had to itself, whereas Disney is building its in one with five well-capitalised competitors. Netflix's absolute profit pool remains in a different league. The bull case here does not require Disney to catch Netflix; it requires Disney's margin to keep climbing toward the high teens without a step-up in content spending. That is the falsifiable version, and the KPI is the SVOD operating margin line, quarter by quarter.
What management conceded
The most revealing exchange on the same call came from Barclays' Kannan Venkateshwar, who pressed on how much of Disney's reaffirmed earnings growth actually depends on theatrical and content performance, given that recent releases had underperformed.
CFO Hugh Johnston's answer was notably candid. He described the film business as "a portfolio game," said Disney's diversified business "helps us basically cover the volatility that comes out of the film business," and stated plainly that "growth drivers for the company right now are Experiences and Streaming," with theatrical representing "just one data point" in a broader IP monetisation strategy.15
Sit with that for a moment, because it is a structural admission dressed as a routine answer. For a hundred years, Disney's flywheel started with a theatrical hit. The film made the character famous; the character sold merchandise; the merchandise funded the park attraction; the park attraction sold the next film. The CFO of Disney has now said, on the record, that the growth drivers are the parks and the subscription business, and that the movies are a portfolio to be managed for volatility.
Both things can be true — the same quarter included Toy Story 5 crossing $1 billion at the global box office, which D'Amaro attributed directly to the flywheel.15 But the honest reading is that Disney's earnings now depend less on the creative engine than at any point in its history, and more on capacity, pricing, and subscription mechanics. Whether that is a strength (diversification) or a weakness (the moat's source has become the smallest contributor) is genuinely arguable. It is not arguable that it is a change.
The linear problem, and the industry's verdict on it
Underneath the streaming improvement sits a business melting at speed. Entertainment's Linear Networks generated $9.364 billion of revenue in fiscal 2025, down 12%, with operating income of $2.955 billion, down 14% — declines amplified by the Star India deconsolidation but negative on the underlying trend as well.13 Still nearly $3 billion of operating income, and still shrinking every year.
The useful thing about this decline is that Disney's competitors have independently confirmed it with their own capital structures. Comcast completed the spin-off of most of its cable networks into a separate public company, Versant Media Group, with the separation effective January 2, 2026 and trading beginning January 5 — a portfolio containing CNBC, USA Network, E!, Syfy, and Golf Channel, deliberately cut loose from the streaming and studio assets Comcast kept.19 Versant shares fell sharply on debut, which is roughly what you would expect when a market prices a pure-play linear asset with no growth story attached.
Warner Bros. Discovery's version of the same problem went further and is still unresolved. Having announced its own split into streaming/studio and global networks companies, WBD instead became the subject of a bidding contest. Netflix's proposed acquisition of the studio and streaming assets drew a Department of Justice second request, a Senate Judiciary antitrust hearing, and bipartisan congressional opposition before Netflix withdrew. Paramount Skydance then agreed to acquire all of WBD at $31.00 per share in cash. That transaction has cleared the DOJ, the European Commission, and the UK authority, but has been held up by litigation from a group of state attorneys general; in July 2026 Paramount agreed to extend the outside date to as late as June 2027, with shareholders receiving a quarterly ticking fee if the deal has not closed by September 30, 2026.20
Two things follow for Disney. First, the structural decline of linear television is not a Disney-specific narrative or an excuse — it is the organising fact of the industry, and two rivals have restructured their entire corporate form around it. Second, the competitive landscape Disney will operate in from 2027 is unsettled in a way it has not been since the Fox auction. A Paramount that owns Warner Bros., HBO, CNN, and the DC library is a materially different competitor than either company alone, and Disney has no vote in how that resolves.
Which leaves the third segment, and the one with the most to prove.
IX. ESPN's Existential Pivot: Sports in the Streaming Era
For twenty-five years ESPN had the best business model in media, and it was almost embarrassing to explain. Cable operators paid ESPN roughly ten dollars per subscriber per month — more than any other network by a wide margin — and they paid it for every household on the system. A retired couple in Ohio who had never watched a football game in their lives funded ESPN's rights deals. Roughly 100 million households, paying whether or not they watched, was the closest thing to a private tax in American business.
That model has been unwinding for a decade, and ESPN's entire strategy since is best understood as an attempt to land the plane before the fuel runs out.
The segment as it stands: Sports generated $17.7 billion of revenue and $2.9 billion of operating income in fiscal 2025, with operating income up 20% — a figure flattered by the Star India deconsolidation, which removed a loss-making operation from the consolidated results.13 Then in fiscal Q3 2026, Sports operating income fell 17% year over year to $858 million, on revenue up 4%.1 The proximate cause was mundane: the NBA playoffs ran shorter than in the prior year, and a renewed NBA contract shifted costs into the quarter.15
That volatility is not noise to be looked through — it is a permanent feature of the asset. ESPN's costs are contractually fixed years in advance through rights deals, while its revenue depends on how many games a playoff series actually goes and where the calendar falls. Investors accustomed to the smooth annuity of the affiliate-fee era should recalibrate: sports rights ownership is a lumpy, calendar-dependent business, and the smoothness of the old model was a property of the distribution arrangement, not the content.
The big swing
On August 21, 2025, ESPN launched its standalone direct-to-consumer service — the move it had deferred for a decade because launching it meant admitting the cable bundle was ending. ESPN Unlimited priced at $29.99 per month and includes all the ESPN linear networks, ESPN on ABC, ESPN+, and roughly 47,000 live events a year; a cheaper Select tier sits below it; and a Trio Bundle packages ESPN Unlimited with Disney+ and Hulu, offered at $29.99 per month for the first twelve months.21 ESPN chairman Jimmy Pitaro framed it as a redefinition of the business.
Now size the traction honestly. Research firm Antenna estimated approximately 2.1 million sign-ups from launch through September 30, 2025.22 By the November 2025 earnings call, Iger said 80% of new ESPN subscribers were also taking Disney+ and Hulu, and described the launch as working "in almost every way you look at it."23
Two million-plus sign-ups in six weeks is a solid product launch. It is not, yet, a business that replaces roughly $9 billion of linear network revenue. Against Disney's combined base of approaching 200 million Disney+ and Hulu subscriptions, it is a small number. And the bundle statistic cuts both ways: 80% attach to the Trio Bundle means the product is an effective upsell mechanism and that relatively few consumers are buying ESPN as a standalone destination at $29.99.
Management's own framing, tested
Wolfe Research's Peter Supino asked exactly the right question on the fiscal Q3 2026 call: when will ESPN DTC subscriber scale become large enough to meaningfully drive Disney+ traffic?
Johnston did not defend ESPN DTC as a standalone growth engine. He reframed around consumer segmentation — the Trio Bundle and ESPN Unlimited "are the best options for big sports fans" — and described the strategy as bringing additional sports content to Disney+ users in order to drive upsell.15
That is an honest answer, and it is also a smaller claim than the "redefine our business" language at launch. The current state of the evidence: ESPN DTC is functioning as a bundle-retention and upsell mechanism, not as an independent subscriber acquisition engine. It may become the latter. It is not yet.
The narrative inconsistency worth naming
The most analytically interesting thing about ESPN's recent history is not the product. It is how inconsistently Disney's own leadership has described the underlying asset, on the record, within eighteen months.
In August 2023, Iger said linear television "remains highly profitable" but that "the trends fueled by cord-cutting are unmistakable," and confirmed Disney was exploring "a variety of strategic options" — language widely read as putting ABC in play. In May 2024, he said Disney would "pretty dramatically" reduce its investment in linear television.24 Then in February 2025, he reversed the framing entirely: the linear cable networks "are not a burden at all, they're actually an asset" — while still not ruling out selling smaller ones.25
The financials did not reverse. Linear revenue and operating income declined right through the period of the rhetorical turn, and continued declining afterward. So what changed?
The most parsimonious explanation is that the reframing tracked a change in negotiating and strategic posture rather than a change in economics. Once Disney concluded it was not going to sell ABC — and once ESPN's future depended on carriage negotiations and rights deals in which describing your own networks as a dying business is a poor bargaining position — "asset" became the useful word. That is a rational thing for a CEO to do. It is also exactly the kind of unexplained narrative shift that investors should mark down rather than launder into "management pivoted strategically." When the words move and the numbers do not, believe the numbers.
The A+E sale in August 2026 is consistent with the earlier framing, not the later one — Disney took $1.2 billion in cash for its half of a cable networks joint venture rather than holding an "asset."7 Actions have been more informative than adjectives.
X. New Leadership: The Josh D'Amaro Era Begins (2026–)
The most important thing Disney's board did in this decade may have been a personnel decision that had nothing to do with the CEO job.
In August 2024, the board named James Gorman — the former Morgan Stanley chief executive, and himself a widely studied case in orderly succession, having handed his own firm to Ted Pick after a multi-year, publicly-managed process — as chair of a formal Succession Planning Committee. Gorman became Disney's board chairman in January 2025, with the committee targeting a decision in early 2026.
Compare that to 2020: an abrupt announcement, an outgoing CEO who stayed on as executive chairman, ambiguity about who actually had authority, and a reversal within three years. The 2024-2026 process was structured, time-bound, and run by someone with a track record in exactly this task.
It delivered on February 3, 2026, when the board named Josh D'Amaro as Iger's successor, effective at the March 18, 2026 annual meeting.26 D'Amaro is a 28-year Disney veteran who worked his way up through the parks — Disneyland Resort president, then Walt Disney World president, then chairman of Disney Experiences from 2020. Dana Walden, who ran the entertainment side and was the other finalist, became President and Chief Creative Officer reporting to D'Amaro. Iger remained as a senior advisor and board member through the end of 2026.27
Two observations, one favourable and one restraining.
The favourable one: the process was, by the standards of this company's history, remarkably drama-free — no leaked briefing wars, no departing executives, no reversal.27 Given the Ovitz episode and the Chapek reversal, that is a real governance improvement and should be credited as such. Retaining Walden in an elevated role rather than losing her to a competitor is a specific, non-trivial part of that.
The restraining one: what underwrites D'Amaro's credibility today is his operating record running Experiences — the segment that delivered record profit through a difficult consumer period and absorbed a well-funded new competitor without visible damage. That is a strong record. It is not a record as a chief executive, and the skills differ. Running the best business in the portfolio is a different job from allocating capital across a good business, a shrinking business, and a business in transition — which is precisely Disney's problem.
The first data points
Two early moves under D'Amaro deserve to be read together, because they point in opposite directions.
The first was the A+E divestiture: $1.2 billion in cash for a 50% stake in a cable networks joint venture that had been a fixture of Disney's portfolio since 1984, announced in early August 2026 and closing in September.7 This reads as disciplined portfolio pruning — continuing the late-Iger logic of shedding non-core linear assets, at a real price, in cash, into a market that is not eager for such assets. It also funds buybacks.
The second was the OpenAI investment, and it went badly enough to be genuinely instructive. Disney agreed to invest $1 billion of equity in OpenAI, take warrants for more, and become the first major content licensing partner on Sora, OpenAI's short-form generative video platform — a three-year deal covering more than 200 characters from Disney, Marvel, Pixar, and Star Wars, with curated Sora-generated videos to appear on Disney+, alongside a broader commitment to use OpenAI's APIs across the business.28 It was announced as a landmark, and Disney's stock rose on it.
On March 24, 2026, OpenAI announced it was shutting down the standalone Sora app and exiting video generation. Disney pulled out of the $1 billion investment, with the company noting only that "as the nascent AI field advances rapidly, we respect OpenAI's decision to exit the video generation business and to shift its priorities elsewhere."29
The financial damage appears limited — Disney does not appear to have deployed the capital. But the process signal is not limited. Disney announced a billion-dollar equity investment tied to a specific product from a partner who discontinued that product within months. The commercial rationale evaporated before the ink dried. That is not a story about AI risk; it is a story about how much diligence went into the commercial durability of the counterparty's product line before a billion dollars was publicly committed.
Set against the A+E sale, the pairing is the fairest available summary of D'Amaro's capital allocation record to date: disciplined when selling assets he understands deeply, and not yet demonstrably rigorous when buying into things outside the company's competence. It is two data points. It is not a verdict. But investors evaluating Disney's forward-looking optionality bets — AI, new formats, new platforms — now have one completed example, and it did not de-risk cleanly.
The first guidance cycle
For fiscal 2026, Disney has guided to adjusted EPS growth of approximately 12% excluding the effect of a 53rd week, or approximately 16% including it; operating cash flow of about $19 billion; capital expenditure of roughly $9 billion; and share repurchases raised to at least $9 billion, up from an initial $7 billion target.113 Nine-month free cash flow ran at $5.74 billion against $7.52 billion a year earlier, with the decline attributed to higher tax payments partially offsetting improved operating cash flow in Experiences and Entertainment.1
That last item is the sort of detail worth tracking rather than dismissing. A buyback raised mid-year to at least $9 billion while free cash flow is running below the prior year is a defensible choice — the cash flow gap is tax-timing rather than operational — but it is a choice, and it is the first one D'Amaro has made that trades balance-sheet flexibility for per-share optics. Whether that becomes a pattern is a fair thing to watch.
XI. Business Model, Flywheel & Competitive Moat
The flywheel is the most-cited diagram in business strategy and it deserves a re-examination against Disney's actual 2026 income statement rather than its 1957 version.
The mechanism, plainly stated: a film creates a character; the character generates emotional attachment in a child; the attachment converts into merchandise purchases, park visits, and streaming subscriptions; the park visit and the subscription reinforce the attachment; and the attachment transfers to the next generation, because parents take children to see the things they loved. That last step is the actual moat. Disney is one of very few companies whose customer acquisition is performed, unpaid, by its previous customers, out of nostalgia.
The flywheel still turns. But the torque now comes from a different place. The content engine — the part that historically started the whole cycle — is, in the CFO's own characterisation, a portfolio managed for volatility, while the growth drivers are Experiences and streaming.15 The wheel has become a system where the monetisation layer is doing the work and the ignition layer is coasting on a catalogue built between 1937 and 2019. That is sustainable for a long time, because the catalogue is deep. It is not sustainable forever, and the strongest single piece of evidence for it working is Toy Story 5 — a fifth instalment in a franchise that began in 1995.
Five Forces, segment by segment
Experiences. Barriers to entry are as high as anywhere in the consumer economy: land, capital, and the decade Comcast spent building Epic Universe. Supplier power is low. Buyer power is the interesting one — individually negligible, collectively meaningful, and rising as a genuine alternative opens forty minutes away. Substitutes are the real threat and are chronically under-modelled: the competitor for a $7,000 family week at Walt Disney World is not only Universal, but a European cruise, a national parks trip, or nothing at all. Rivalry has just increased for the first time in a generation.
Entertainment/streaming. The worst structure of the three. Rivalry is intense and getting more so, with Netflix, Amazon, Apple, and a potentially combined Paramount-Warner all competing for the same content and the same hours. Switching costs are close to zero — cancellation is two clicks. Supplier power, in the form of talent and production cost inflation, is a persistent margin risk. Buyer power is high. Disney's margin gains here have come from operational discipline rather than structural advantage, and disciplines can be competed away in a way that structures cannot.
Sports. A distinctive shape. ESPN's power comes from exclusive live rights and brand primacy, but supplier power — the leagues — is extraordinarily high and rising, because there are very few leagues and many bidders, now including Amazon, Netflix, and YouTube. Every rights renewal transfers value from network to league. ESPN's counter is that it is the only distributor offering a comprehensive sports destination, which has real value to a subset of consumers. That subset's willingness to pay $29.99 a month is the whole thesis, and the current evidence sizes it in the low millions.
Seven Powers
Applying Hamilton Helmer's framework, the honest scoring is uneven.
Cornered resource is Disney's clearest and most durable power, and it is enormous: Mickey, the princesses, Marvel, Star Wars, Pixar. These cannot be replicated at any price. Their strength is best measured not by box office but by the fact that guests accepted 5% annual price increases in a soft consumer year.
Scale economies are real in Experiences. A park network with Disney's density spreads Imagineering, technology, and marketing costs across a base no entrant can match quickly; Comcast needed most of a decade and over $10 billion for one park.
Branding is genuine and quantifiable, in exactly the pricing evidence above.
Switching costs are weak. The streaming bundle creates some friction and the 80% Trio attach rate shows it works at the margin, but nothing here resembles enterprise software lock-in.
Network economies are largely absent. Disney+ does not get better for a user because other users joined. This is the power Netflix partially has and Disney mostly does not.
Counter-positioning and process power are not meaningfully present. Disney is the incumbent, not the disruptor.
The composite: one exceptional power, two solid ones, and three weak-to-absent — concentrated in the segment that generates the profit. That is a real moat, appropriately located, and narrower than the brand's cultural stature implies.
The capital-exposure spectrum
One structural point worth naming, because it is a learned behaviour rather than an accident. Disney operates parks under at least four different ownership structures: wholly owned (Anaheim, Orlando), majority-owned joint venture (Shanghai, Paris), licensed with royalty (Tokyo, operated by Oriental Land Company), and now fully asset-light (Abu Dhabi). The trend over forty years has been decisively toward less Disney capital per new resort. Given that Euro Disney's opening years produced losses severe enough to require multiple financial restructurings, that trend looks like an institution that learned an expensive lesson and encoded it.
XII. Playbook: Durable Lessons from the House of Mouse
Own the IP you depend on — and notice that the lesson keeps needing to be relearned. Oswald in 1928. Pixar in 2004. But the modern version has a twist: Fox demonstrated that owning IP and owning distribution are different bets with different returns. Disney bought both and only one worked. The generalisable lesson is that "content is king" is a claim about content, not about the pipes it travels through, and the two should be underwritten separately.
Buy the capability, not just the catalogue. The distinguishing feature of Pixar and Marvel versus Lucasfilm is not the quality of the IP but whether Disney inherited a functioning creative leadership structure and left it alone. Lasseter and Catmull ran animation; Feige ran Marvel. Lucasfilm's post-acquisition creative direction was managed more centrally and has been more erratic. Integration discipline in creative businesses looks like restraint.
Competitive dynamics, not DCF, set the price in contested auctions. Fox is best understood as a transaction where a large part of the premium bought the denial of those assets to Comcast. That is a legitimate strategic objective — but it should be priced and disclosed as such, because a defensive premium and an accretion assumption are different things, and only one of them shows up in the impairment testing later.
Self-disruption at this company has been reactive, not proactive. Disney let streaming losses run for years and moved decisively toward profitability only when the board, the market, and an activist made the status quo untenable. Similarly, ESPN's standalone app arrived roughly a decade after cord-cutting became undeniable. This is not unique to Disney — incumbents rarely cannibalise willingly — but it is a specific, repeated behavioural pattern, and it argues for scepticism when management describes any current transition as being ahead of the curve.
Governance process compounds. The delta between 2020 and 2026 is not luck. It is the difference between an informal handoff and a chaired committee with a timeline and an accountable director. It cost the board a reversal, a proxy war, and roughly $300 million of its own money to learn.
XIII. Bear vs. Bull Case
The bear case
Start with the market's verdict, because it is the strongest single bear argument and it is not an opinion. Over five years the stock has lost roughly 43% while the S&P 500 gained roughly 70%.2 Everything a bull cites — record park profit, streaming profitability, a clean succession — happened during that period. The market has had the information and has not re-rated the shares. Either it is wrong, or the improvements are being offset by something.
The most likely offset is arithmetic. Linear Networks contributed nearly $3 billion of Entertainment operating income in fiscal 2025 and shrank 14%; the Sports segment carries its own linear exposure.13 Streaming added roughly $1.2 billion of operating income year over year. Those magnitudes are uncomfortably similar. The bear reading of the last three years is not that Disney failed — it is that Disney ran hard to stay in place, converting a melting high-margin asset into a growing lower-margin one at roughly break-even in aggregate profit terms.
Second: the pricing-power ceiling. Two years of flat-to-down domestic attendance offset by 3% and 5% per-capita spending increases is harvesting, and a well-funded competitor has just opened in the most important market. The mechanism by which Epic Universe hurts Disney is not attendance theft — it is constraint on future price increases.
Third: ESPN DTC's scale is modest at approximately 2.1 million early sign-ups, and management's own framing on the most recent call positioned it as a bundle and upsell mechanism rather than a standalone growth engine.2215 The gap between "this will redefine our business" and "the best option for big sports fans" is where the bear case lives.
Fourth: the content engine. When a CFO says the growth drivers are Experiences and streaming and that film is a portfolio game, he is describing a company whose creative output has become an input to be managed rather than the source of growth.15 For a business whose entire moat derives from characters people love, a weakened character-creation engine is a slow-acting but serious problem.
Fifth: management. D'Amaro is unproven as a CEO, and his two visible capital allocation decisions split one-for-one. The OpenAI episode is small in dollars and meaningful in what it suggests about diligence on non-core bets.29
Sixth: the Fox precedent. Roughly $2.8 billion of impairments across fiscal 2024 on assets acquired in the largest deal in company history is a live reminder that Disney's M&A record includes a very expensive error, not just three famous wins.56
An activist looking at Disney today would press on exactly this: a conglomerate holding a declining linear business, a competitively contested streaming business, and a world-class parks business inside one holding company with one multiple. The sum-of-the-parts argument — that Experiences alone, as an independent capital-intensive consumer asset with $10 billion of operating income, might command a valuation approaching the current whole-company market capitalisation — is the trade any concentrated fund would model first. Trian never made that argument explicitly. The next activist might.
The bull case
The bull case does not require heroics. It requires the current trajectory to be durable and the market to eventually price it.
Experiences is the anchor: $10.0 billion of record fiscal 2025 operating income, roughly 57% of segment profit, growing 20% in the most recent quarter, with demonstrated price realisation and — encouragingly — attendance growth returning alongside price in fiscal Q3 2026.13115 Behind it sits a roughly $60 billion decade-long capital programme aimed squarely at capacity, which is the binding constraint on a business that has been selling scarcity.17 Add a capital-free international expansion option in Abu Dhabi.18
Streaming has crossed from multi-billion-dollar annual losses to a 12.9% quarterly operating margin in about two years, on the timeline management set.115 That is a completed promise, and completed promises are the currency of management credibility. It also validates the platform strategy against the alternative — licensing out — that D'Amaro explicitly rejected on the record.15
The Trian episode ended with the incumbent positions vindicated by subsequent results and a clean activist exit.12 Succession was handled without drama for the first time in a generation, promoting an internal operator with a genuine track record in the company's largest profit pool.27
The IP portfolio remains close to unmatched in breadth and monetises simultaneously across film, streaming, merchandise, cruise, and park attractions — the only asset in media that does all five.
And the balance sheet has room. Buybacks raised to at least $9 billion for fiscal 2026, a dividend growing since its 2023 reinstatement, and roughly $19 billion of guided operating cash flow against $9 billion of capital expenditure leaves genuine flexibility.113 A company generating that much cash while investing heavily in its highest-return segment does not need a re-rating to compound; it just needs to keep going.
The reconciliation
Both cases rest on the same facts. The difference is what you believe about duration.
The bull believes the streaming margin keeps climbing toward the high teens while linear stabilises at a smaller base, so the arithmetic that has cancelled out for three years starts working in Disney's favour around fiscal 2027-2028. The bear believes streaming margin plateaus in the low teens under competitive pressure while linear keeps declining and park pricing hits its ceiling, so the cancellation continues indefinitely.
That is a genuinely open question, and the evidence to settle it will arrive in the next two to three years of reported results rather than in any argument made here.
XIV. Epilogue: What to Watch
Three metrics carry most of the information about whether Disney's improvement is durable. Everything else is commentary.
One: Entertainment SVOD operating margin. It reached 12.9% in fiscal Q3 2026 against a double-digit full-year guide.115 The question is not whether Disney reaches Netflix's margin — it almost certainly will not — but whether the line keeps climbing without a step-up in content spending. If margin expansion stalls in the low teens, the streaming turnaround was a one-time repricing of an installed base rather than the emergence of a structurally profitable platform. This is the single number that decides which of those it was.
Two: the Experiences attendance-versus-per-capita-spend mix. Not operating income, which can be produced either way, but the composition. Two years of flat attendance with rising spend told one story; fiscal Q3 2026's 3% domestic attendance growth alongside 4% per-capita growth told a better one.15 Watch whether that persists as Epic Universe moves past its opening-year novelty. If attendance softens again while per-capita spend keeps rising, Disney is harvesting and the ceiling is approaching. If both grow together, the moat is intact and the $60 billion capital programme is being deployed into genuine demand.
Three: ESPN DTC net additions and bundle mix. Approximately 2.1 million early sign-ups with 80% attaching to the Trio Bundle is a defensive hedge that works.2223 Sustained standalone growth would be something else entirely — evidence that ESPN can survive the death of the cable bundle as a direct consumer relationship rather than merely retard the decline. Disney has not consistently disclosed this number; whether it starts to is itself informative.
Beyond the metrics, a short list of events. Fiscal 2026 full-year results in November 2026 will be the first complete year under D'Amaro and the first clean read on whether the guided 12-16% adjusted EPS growth was delivered. The A+E transaction should complete. Epic Universe's second full year of attendance data arrives during 2027 and is the real test of the Orlando market's expansion thesis. The Paramount-Warner Bros. Discovery litigation resolves — one way or another — into a materially different competitive set. Construction milestones at Disneyland Abu Dhabi will indicate whether the asset-light model actually produces a park on schedule. And it is worth watching whether the new chief executive holds a formal investor day, because a new CEO who lays out multi-year targets in public is creating a scoreboard, and scoreboards are how credibility gets built or lost.
The question the story leaves open is the one it opened with. Disney has stopped losing money on streaming, has a record profit engine in its parks, and has handed the company to an operator in the most orderly transition of the modern era. And the shares are worth roughly what they were worth in 2014.
The market's five-year verdict is that the wins have been offset — that a company converting a melting monopoly into a competitive subscription business, while raising prices at parks whose attendance is not growing, has been running to stand still. That verdict is not obviously wrong. It is also not obviously permanent. It rests on an extrapolation, and extrapolations are exactly what the three metrics above are for.
D'Amaro inherits a company whose founder learned in 1928 that owning your characters is everything. Disney owns more of them than anyone. What it has not yet proven, to the people who set the price of its shares, is that owning them is still enough.
References
-
The Walt Disney Company Reports Third Quarter and Nine Months Earnings for Fiscal 2026 — SEC EDGAR, 2026-08-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Walt Disney Company (DIS) Stock Price and Market Data — Stock Analysis, 2026-09-08 ↩↩
-
The Walt Disney Company / Twenty-First Century Fox acquisition completion press release — SEC EDGAR, 2019 ↩
-
Disney Closes Hulu Deal With Comcast, Paying Billions Less Than NBCU Was Seeking — Variety, 2025-07 ↩
-
The Walt Disney Company Form 10-K for Fiscal Year Ended September 28, 2024 — SEC EDGAR ↩↩
-
Disney faces charges of up to $2.4 billion due to Star India's removal — Business Standard, 2024-03-01 ↩↩
-
Disney Closes $1.2 Billion Deal, Sells A+E Global Media Stake To Hearst — Deadline, 2026-08 ↩↩↩
-
Disney and Florida settle lawsuits over DeSantis special district fight — CNBC, 2024-03-27 ↩
-
Bob Iger named Disney CEO, effective immediately — CNBC, 2022-11-21 ↩
-
Disney wins proxy fight against Nelson Peltz — CNBC, 2024-04-03 ↩
-
Final Disney Proxy Vote Tally: Win for Bob Iger, Defeat for Nelson Peltz — The Hollywood Reporter, 2024-04 ↩
-
Nelson Peltz sells entire Disney stake — CNBC, 2024-05-29 ↩↩
-
The Walt Disney Company Reports Fourth Quarter and Full Year Earnings for Fiscal 2025 — thewaltdisneycompany.com, 2025-11-13 ↩↩↩↩↩↩↩↩↩↩↩
-
The Walt Disney Company Form 10-K for Fiscal Year Ended September 27, 2025 — SEC EDGAR, 2025-11-13 ↩↩
-
Disney (DIS) Q3 2026 Earnings Call Transcript — The Motley Fool, 2026-08-12 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
The battle for Orlando: How Epic Universe could impact Disney World theme park attendance — Fast Company, 2025 ↩↩
-
The Walt Disney Company Form 8-K announcing approximately $60 billion, 10-year Experiences investment plan — SEC EDGAR, 2023-09-19 ↩↩
-
Disney Announces Plans for New Theme Park and Resort with Miral in Abu Dhabi — thewaltdisneycompany.com, 2025-05-07 ↩↩
-
Comcast spinoff Versant starts trading on Nasdaq in rare media debut — CNBC, 2026-01-05 ↩
-
Paramount agrees to delay WBD acquisition to as late as June 2027 amid legal challenge — CNBC, 2026-07-24 ↩
-
ESPN's Direct-to-Consumer Service and Enhanced App Launching August 21 — thewaltdisneycompany.com, 2025 ↩
-
ESPN app cracks 2 million subscribers in first month — Awful Announcing, 2025 ↩↩↩
-
ESPN Streaming Step-Up Going "Extremely Well," With 80% Of Subscribers Also Taking Disney+ & Hulu, Bob Iger Says — Deadline, 2025-11 ↩↩
-
Bob Iger: Disney Will "Pretty Dramatically" Reduce Linear TV Investment — Deadline, 2024-05 ↩
-
Disney CEO Bob Iger On Linear Cable Networks: "Not A Burden At All" — Deadline, 2025-02 ↩
-
Disney names Josh D'Amaro as CEO, successor to Bob Iger — CNBC, 2026-02-03 ↩
-
Disney's CEO Succession Was Drama-Free — Deadline, 2026-03 ↩↩↩
-
The Walt Disney Company and OpenAI Reach Agreement to Bring Disney Characters to Sora — thewaltdisneycompany.com ↩
-
Disney Pulls Out Of $1B OpenAI Deal As Sora Shuts Down — Yahoo Finance, 2026-03-25 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube