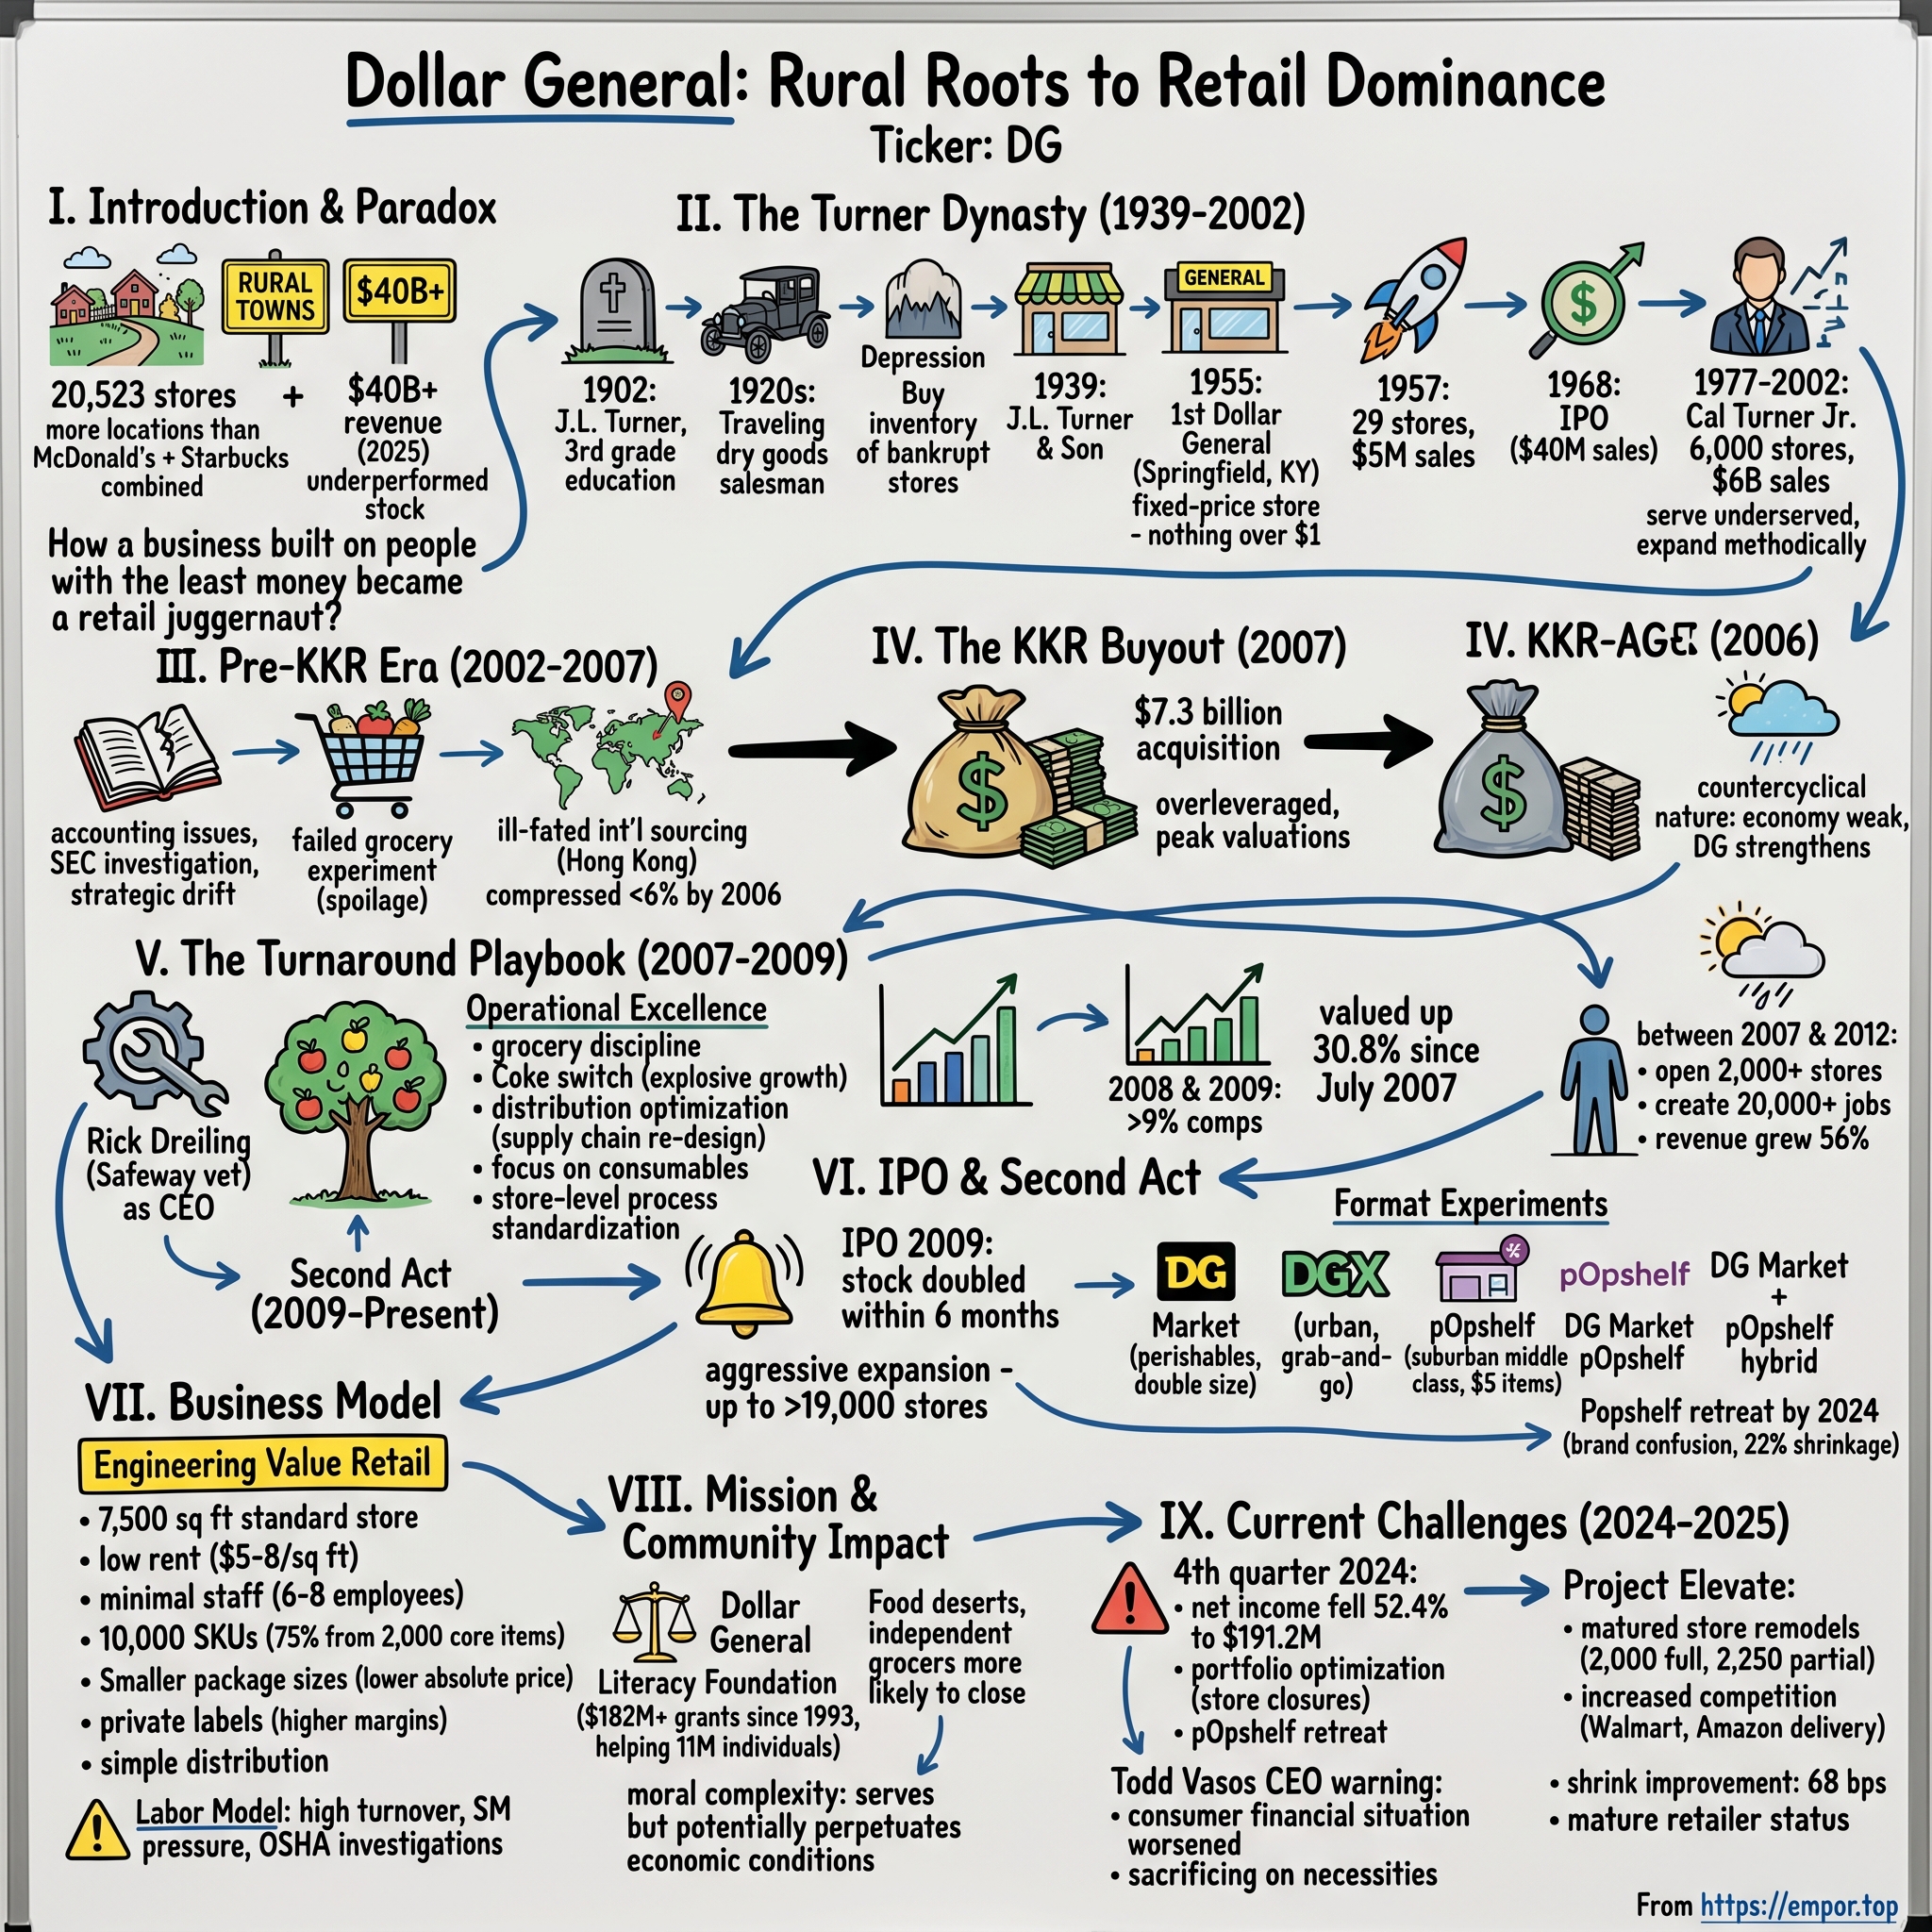
Dollar General: One Turn Away From The Edge
I. Introduction & The Central Puzzle
On the morning of August 29, 2024, a company that sells laundry detergent and canned corn to small-town America did something that almost never happens to a retailer of its size: it lost roughly a third of its market value between the opening and closing bell.1
The trigger was not fraud, not a lawsuit, not a failed acquisition. It was a quarter. Dollar General reported diluted earnings per share of $1.70 for its fiscal second quarter — a miss against a consensus in the high $1.70s — and then took a hatchet to its own full-year outlook, cutting expected EPS from a range of $6.80 to $7.55 down to $5.50 to $6.20.2 For a business whose entire pitch to investors was metronomic predictability across thousands of tiny, nearly identical boxes, that was less a guidance revision than a confession. The stock fell about 32% that day and finished calendar 2024 down 44%.3
The explanation management offered was, on its face, sympathetic. Dollar General's core shopper — the household earning under $35,000 a year, living in a town of a few thousand people, without a Walmart within a reasonable drive — was, in the company's own framing, "financially constrained."2 Two years of accumulated inflation had eaten the discretionary dollar. The customer wasn't leaving; the customer simply had less.
That story has the great virtue of being partly true and the great convenience of being nobody's fault.
Zoom out and the picture gets more interesting. Revenue never actually stopped growing. Sales climbed from $37.8 billion in fiscal 2022 to $40.6 billion in fiscal 2024 and $42.7 billion in fiscal 2025, the year ended January 30, 2026. But net income over that same stretch went from $2.42 billion down to $1.13 billion before recovering to $1.51 billion. Diluted EPS traced the same arc: $10.68, then $5.11, then $6.85. The company kept selling more and earning dramatically less. That is not a demand problem. A demand problem shows up in the top line. This showed up entirely between the top line and the bottom line — in gross margin, in shrink, in markdowns, in damaged inventory, in the cost of running the stores.
That gap is the puzzle this story is about.
Dollar General Corporation, listed on the New York Stock Exchange under the ticker DG, is the largest small-box retailer in the United States by store count, operating 21,148 locations as of July 31, 2026 across 48 states and Mexico, plus a separate pOpshelf banner.4 Roughly 80% of those stores sit in towns of 20,000 people or fewer, and about 75% of the U.S. population lives within five miles of one.5 It employs around 194,000 people.5 It is, by physical footprint, one of the most ubiquitous consumer brands in the country — more locations than McDonald's and Starbucks in the U.S. combined.
And in 2024 it very nearly convinced the market that ubiquity was worth less than everyone thought.
The specific question worth resolving is this: how does a company with genuinely unmatched physical distribution in markets nobody else can profitably serve let its own execution — not the consumer, not the format, not a competitor — become the biggest single risk to its earnings? And did the emergency return of former CEO Todd Vasos in October 2023 actually repair the underlying machine, or did it simply stop the bleeding while a stabilizing macro backdrop did the rest?
Two years on, the scoreboard looks much better. In the quarter ended July 31, 2026, reported on August 27, net sales rose 5.2% to $11.3 billion, same-store sales rose 3.5%, operating profit jumped 29.2% to $769.2 million, and diluted EPS climbed 33.3% to $2.48. Management raised full-year EPS guidance to a range of $7.80 to $8.00 and announced it would resume share repurchases in the third quarter after a four-year pause.4
But the most consequential piece of news for anyone underwriting this business did not come from an earnings release at all. On March 24, 2026, Dollar General announced that Vasos would hand the CEO job to Jerry W. "JJ" Fleeman Jr. — a 35-year grocery operator most recently running Ahold Delhaize USA — effective January 1, 2027.6 Which means the recovery narrative and the person who authored it are about to be separated, deliberately and on a published timetable.
Here is the roadmap. First, the origin story, compressed — because the useful part of Dollar General's Depression-era history is not nostalgia but a recurring failure pattern. Then the KKR buyout and the operational turnaround that made the modern company. Then the growth machine of the 2010s and the ceiling it hit. Then the 2023–2024 collapse in detail, because that is where the real evidence lives. Then the recovery, tested rather than accepted. Then the economics of the small box and the question of who actually competes with Dollar General. Then management, incentives, and whether trust has genuinely been rebuilt. Then capital, risk, the bull and bear cases, and what to watch.
It starts, as these things often do, with a family, a small town, and a very specific idea about what a poor customer is worth.
 Subscribe on LinkedIn
II. Origins: A Depression-Era Discount Idea That Outlived Three Generations of Turners (1939–2007)
Scottsville, Kentucky in 1939 was a county seat of a few thousand people in the tobacco country north of the Tennessee line, in the tail end of a decade that had taught rural America a permanent lesson about price. J.L. Turner had spent that decade in the retail equivalent of scavenging — buying the inventory of failed general stores and liquidating it. He and his son, Cal Turner Sr., each put up $5,000 and formalized the operation as J.L. Turner and Son.
The business was not, initially, an idea about format. It was an idea about supply: distressed goods bought below wholesale could be sold below retail and still leave a margin. What turned it into a franchise came sixteen years later, when Cal Turner Sr. converted a store in Springfield, Kentucky into something with a rule attached — nothing in the store cost more than a dollar. The rule was the product. It removed the entire cognitive burden of price comparison for a shopper who had no slack in the household budget, and it created a merchandising discipline for the buyer, who now had to work backward from a price point to a cost.
Simplicity scaled. The Dollar General format spread across the mid-South through the 1950s and 1960s, and the company went public in 1968.
The generation that made it big also nearly broke it. Cal Turner Jr. — the founder's grandson — ran the company from 1977 to 2002 and took it from a regional chain to roughly 6,000 stores and around $6 billion in annual sales. He was, by every account, a genuine merchant, and the store count he built became the foundation of everything that followed.
Then, in 2001, the accounting came apart.
The Securities and Exchange Commission ultimately charged Dollar General and five individuals with accounting fraud spanning fiscal 1998 through 2001. The specifics are almost quaint in their crudeness: roughly $10 million of import freight costs underreported in 1999, an $11 million "sham sale" of obsolete Omron cash registers booked in the fourth quarter of 2000, and a "rainy day" reserve account used to smooth earnings.7 The January 2002 restatement cut previously reported pre-tax income by approximately $143 million.7 Turner paid a $1 million civil penalty and the company paid $10 million to the SEC; separately, Dollar General settled the consolidated shareholder class action for $162 million.7
It is tempting to file this under ancient history. Do not.
The reason it matters is the shape of the failure, not the amount. Dollar General had built roughly 6,000 stores — an enormous number of small, geographically dispersed, thinly staffed physical nodes — on top of a financial control infrastructure built for a much smaller company. Freight costs that nobody was reconciling. Inventory whose real value nobody could verify. A reserve account that existed precisely because the underlying numbers were too noisy to report straight. The store count outran the systems.
That is the throughline. Hold onto it, because the 2024 problem — inventory sitting in back rooms nobody could get onto shelves, shrink nobody could measure in real time, damages nobody was catching — is the same failure wearing different clothes.
The KKR Chapter
By the mid-2000s, Dollar General was a company with a great franchise and mediocre operations: in-stock rates were poor, stores were cluttered, and the merchandising was generic in a way that ignored what its own customers actually bought.
That is precisely the profile private equity is built to attack. On July 6, 2007, an investor group led by Kohlberg Kravis Roberts, with GS Capital Partners and Citi Private Equity alongside, completed the acquisition of Dollar General at $22.00 per share — an enterprise value of approximately $7.3 billion covering more than 8,000 stores.8 The equity check was roughly $2.8 billion, with about $4.5 billion of borrowed money doing the rest.
The timing was, in retrospect, almost comically dangerous. The deal closed weeks before the credit markets seized. A highly levered retailer walking into the worst consumer recession since the 1930s is a standard-issue private-equity obituary.
Except that this particular retailer sold cheap consumables to poor people, and the Great Recession produced tens of millions of new poor people. The macro that should have killed the deal instead handed it the strongest tailwind in the format's history.
KKR did not simply ride it. It installed Rick Dreiling, a career operator who had run Duane Reade, and Dreiling did unglamorous, high-return work: fixing in-stock rates so shelves actually had product, imposing category management so assortment reflected local demand rather than a national planogram. The most-cited example — stocking Coca-Cola more heavily in the parts of the South where people drink Coke, rather than a uniform mix — sounds trivial. It is not. In a store with 8,500 square feet and no room for error, every facing you get wrong is a sale you cannot make and inventory you will eventually mark down. Dreiling also slowed and disciplined store growth, which is the hardest thing to do at a company whose entire cultural reflex is to open more stores.
Dollar General returned to public markets via an IPO in November 2009, and KKR exited gradually through secondary offerings over the following years.
Now the falsification. The KKR-era story is almost always told as an unambiguous private-equity triumph, and on returns it is one — Dollar General compounded enormously from its 2007 buyout while a good many 2007-vintage mega-LBOs did not. But the claim frequently smuggled in alongside the returns — that Dollar General became an operationally excellent company — does not survive contact with the record.
Within roughly a decade of the IPO, Dollar General became the first retailer added to OSHA's Severe Violator Enforcement Program, in 2023, for hazards that read like a catalog of the same disease that caused the 2001 restatement: blocked emergency exits, blocked electrical panels, blocked fire extinguishers, unsafe storage.9 Between January 2017 and July 2024, OSHA proposed more than $26 million in penalties against the company.10 Those citations are, mechanically, a store-conditions problem — too much inventory, too few labor hours, nobody with the time to put it away.
The honest reading of the Dreiling era is therefore narrower than the legend: operational excellence was real while it was actively managed, and it did not survive as a durable institutional trait across leadership changes. That is not a small distinction for an investor. It means the quality of this business is a function of who is running it and how hard, rather than something baked into the model — which is exactly the question the company faces again with a new CEO arriving in 2027.
III. The Public Company, Growth Machine Era — and Its Ceiling (2009–2022)
For most of the 2010s, Dollar General was one of the most reliable compounding machines in American retail, and the mechanism was gloriously simple: build more boxes.
Each new store was small, cheap to fit out, leased rather than owned, and could be sited in a trade area of a few thousand people that no other national retailer wanted. The unit economics worked at a population density where a Walmart Supercenter would starve. So the company built, and built, and built — well over two thousand net new stores in the first five post-IPO years alone, marching toward roughly 18,000 locations by 2022. Investors got a growth rate without a technology risk, and they paid a premium multiple for it.
Todd Vasos took over as CEO in June 2015. He was, and is, a merchant by training and temperament — a career retail operator rather than a strategist parachuted in from consulting. Over his first tenure he added roughly 7,000 stores and grew annual revenue by more than 80%.11 He also began hedging the core bet, because he could see the arithmetic: at some point the country runs out of towns.
So Dollar General launched formats. DG Market, a larger box with a deeper grocery offer. DGX, a compact urban convenience concept. And, most prominently, pOpshelf — a higher-margin, discretionary-goods banner aimed at suburban households with more money, explicitly designed to solve the structural margin problem that the core business was walking into.
That structural problem deserves a plain-English explanation, because it governs everything downstream. Dollar General's sales mix has been steadily shifting toward consumables — food, paper goods, cleaning supplies, health and beauty — which now account for 82.0% of net sales, against roughly three-quarters a decade earlier.5 Consumables are the traffic driver: they bring people in weekly. But they carry the thinnest margins in the store. Every point of mix that moves from a seasonal decoration or a T-shirt into a box of cereal is a point of blended gross margin the company has to earn back somewhere else. It is a slow, grinding, largely one-directional headwind, and it is why the discretionary-format experiments were not a vanity project — they were an attempt to buy back margin.
The Peak That Wasn't Quite What It Looked Like
Fiscal 2022, ended February 3, 2023, is conventionally described as the best year in Dollar General's history: $37.8 billion of revenue, $2.42 billion of net income, diluted EPS of $10.68.
The numbers are real. The framing deserves a second look.
Net income actually peaked two years earlier. In fiscal 2020 — the pandemic year ended January 29, 2021 — Dollar General earned $2.66 billion on $33.7 billion of revenue. By fiscal 2022, net income was about 9% below that peak. What made fiscal 2022 look like a record on a per-share basis was that the weighted average diluted share count had fallen from roughly 250 million to 226 million over those two years. Buybacks, not operating performance, carried EPS across the line.
That matters for a specific reason. Fiscal 2020 and 2021 were an extraordinary environment for this format: stimulus checks in the hands of exactly Dollar General's customer, a pandemic that made a nearby small store more attractive than a distant large one, and a trade-down cycle that pulled in shoppers who normally would not have walked in. Those were tailwinds, not achievements. Reading the 2020–2022 stretch as proof of durable operating outperformance overstates the case; the more defensible reading is that a good format caught an exceptional macro wave, and the wave was already receding when the results were being celebrated.
Which is roughly when Vasos handed over the keys. He stepped down as CEO in November 2022, staying on as a board member, and Jeff Owen — a long-tenured internal operator — took over.
The timing could hardly have been worse. Owen inherited the company at the precise moment the stimulus was gone, inflation had compounded into a real reduction in his customer's purchasing power, and the store base was large enough that any slippage in execution would compound across roughly 19,000 locations at once.
He would last less than a year.
IV. The Reset: Jeff Owen's Ouster and the 2023–2024 Free-Fall (2022–2024)
Corporate press releases are written to say as little as possible. Occasionally one says too much.
On October 12, 2023, Dollar General announced that Jeff Owen was out, effective immediately, and that Todd Vasos was returning as CEO. Board chairman Michael Calbert's explanation was unusually direct: "The Board has determined that a change in leadership is necessary to restore stability and confidence in the Company moving forward," adding that the board sought to "refocus the Company's strategic direction and priorities to stabilize the business."11
Boards do not use the words "restore stability and confidence" about a company that is stable and inspiring confidence. In under eleven months, the succession the board had planned and executed had been publicly reversed. That is a governance data point in its own right — not primarily about Owen, who was handed an impossible macro handoff, but about a board that had apparently misjudged both the difficulty of the moment and the readiness of its own bench.12
Vasos returned saying he would work to "return to a position of operational excellence."11 The phrasing is worth noting: return to. Even the incoming CEO was conceding the company had left it.
What Actually Broke
The 2024 deterioration was not one thing. It was four things compounding, and each of them was, to a meaningful degree, self-inflicted.
Inventory sat in the wrong place. Stores carried too much of it relative to the labor hours available to put it on shelves. Product piled up in back rooms and aisles. That simultaneously depressed sales — a customer cannot buy what is in a box behind a door — and generated damages, since merchandise handled repeatedly and stored badly gets destroyed.
Shrink rose. "Shrink" is retail's term for inventory that leaves without being paid for: theft, damage, error. In a business with the margin profile of consumables retail, shrink is close to a pure hit to gross profit. A hundred basis points of shrink at Dollar General's scale is hundreds of millions of dollars of gross profit that simply evaporates.
Self-checkout made shrink worse. Dollar General had rolled self-checkout out aggressively for one reason: labor cost. In a store staffed by a handful of people, a self-checkout kiosk substitutes for hours you otherwise have to pay for. The problem is that self-checkout in a small, lightly staffed store with limited sightlines is an invitation. By March 2024 the company had removed self-checkout entirely from about 300 stores, converted roughly 9,000 locations from self-checkout to assisted checkout, and restricted the remaining kiosks to baskets of five items or fewer.13 The company had, in other words, spent capital installing a system, absorbed the shrink it caused, and then spent more capital taking it out.
Markdowns rose. Discretionary goods bought for a customer who no longer had discretionary money had to be cleared at a loss.
Put together, the second-quarter fiscal 2024 gross margin fell from 31.1% to 30.0%, driven by higher markdowns and damages, while SG&A rose from 24.0% to 24.6% of sales. Operating income dropped from $692.3 million to $550.0 million.3 In a business that converts roughly six cents of every sales dollar into operating profit in a good year, a single point of gross margin is not a rounding error. It is the year.
Stress-Testing "It's the Consumer"
On the August 29, 2024 call, management leaned hard on the constrained-customer explanation.2 It is worth taking seriously — the low-income consumer genuinely was under pressure, and every retailer serving that demographic said so.
But an explanation should be judged against what else was happening in the same window. In the twelve months surrounding that call, Dollar General was designated a severe violator by OSHA for store-condition hazards, agreed in July 2024 to pay $12 million in penalties and commit to a corporate-wide safety overhaul including hiring additional safety managers and — tellingly — reducing inventory levels and improving stocking efficiency,9 and reversed a self-checkout program it had itself rolled out.
Read that OSHA settlement term again. A federal safety regulator required Dollar General to carry less inventory and stock it better. That is not a consumer problem. That is a regulator diagnosing the same operational disease that was showing up in the gross margin line, and writing the remedy into a legally binding agreement.
The analytical conclusion is not that management lied. It is that a macro explanation offered simultaneously with a documented pattern of controllable operational failure should reduce, not increase, an investor's confidence in that explanation. When a company attributes a miss to conditions outside its control while a regulator is compelling it to fix conditions inside its control, the burden of proof shifts.
Shareholders noticed. At the 2024 annual meeting, the advisory vote on executive compensation drew 72.8% support — a weak number for a say-on-pay vote, where anything below the high 80s signals genuine institutional discontent, and a countable, contemporaneous signal that the market's largest owners were not treating 2024 as purely a weather event.14
The Retreat
The formal admission arrived with fourth-quarter fiscal 2024 results in March 2025. Dollar General announced it would close 96 Dollar General stores and 45 pOpshelf locations, convert six pOpshelf stores to the Dollar General banner, and take related charges. The pOpshelf fleet shrank by about 22%, to roughly 180 stores.15 Vasos explained that the closing Dollar General locations were predominantly urban and had "become increasingly challenging to operate."15
The charges were not trivial. Fourth-quarter operating profit absorbed $232 million tied to the closures and pOpshelf impairment — roughly $0.81 per share — which drove quarterly operating profit down 49.2% to $294.2 million and quarterly EPS down 52.5% to $0.87.16 Writing down a format is the most honest disclosure a retailer makes, because it converts a strategic hope into a number. For the full year, net sales still rose 5.0% to $40.6 billion on a 1.4% same-store gain, while gross margin fell 70 basis points on markdowns and inventory damages.16
Strip the language away and this was a retreat from the two places the company had gone looking for growth beyond its rural core: cities, and higher-margin discretionary retail. pOpshelf had been presented only a few years earlier as a genuine growth vector. It was now a 180-store experiment held roughly flat.
Which raises the question that governs the rest of this story: was the fix that followed a real rebuild, or a cost program running with the wind at its back?
V. Back to Basics: The Vasos 2.0 Playbook and the FY2025–FY2026 Recovery
"Back to Basics" is the least ambitious-sounding strategy a large public company has announced in years, and that was the point.
There was no new format, no digital transformation, no adjacency. The program was a list of things a well-run retailer is supposed to do already: get inventory out of the back room and onto the shelf, reduce the number of SKUs so employees can actually manage the assortment, fix the supply chain so trucks arrive when they are supposed to, and stop losing product to theft. Vasos's framing to investors was essentially that the company had broken its own machine and needed to repair it before doing anything else.
The unglamorousness is itself informative. A CEO returning to a company he ran for seven years, choosing to attack blocking and tackling rather than announce a bold new direction, is implicitly confirming that the 2024 problem was executional. You do not fix a demand problem with better stocking.
The Remodel Engine
The offensive half of the plan is a remodel program running at genuinely industrial scale.
Project Renovate is the full remodel: it touches 100% of a store, adds or replaces refrigerated coolers, and upgrades the layout to the current format, targeted at locations seven or more years past their last touch. Project Elevate, introduced in 2025, is a lighter, cheaper intervention aimed at stores that are performing but not yet old enough to justify a full remodel — refreshing merchandising, improving adjacencies, and adding cooler capacity without gutting the box.
For fiscal 2026 the company planned approximately 4,730 real estate projects: about 450 new U.S. stores, about 10 in Mexico, roughly 2,000 Renovate remodels, roughly 2,250 Elevate remodels, and about 20 relocations.17 Roughly nine out of ten projects are improvements to stores that already exist.
That ratio is the single clearest signal of what Dollar General has become. Compare it with fiscal 2025, when the plan called for about 575 new U.S. stores and up to 15 in Mexico,18 and with the actual fiscal 2025 outcome of 589 openings against 290 closings — a net addition of 299 stores, versus net additions of 608 in fiscal 2024 and 882 in fiscal 2023.5 New-unit growth has decelerated sharply and deliberately over three years.
This is a real strategic shift, and investors should be clear-eyed about which direction it cuts. Positively, capital is moving from a lower-return use (marginal new stores in increasingly marginal trade areas) to a higher-return one (fixing productive stores that are underperforming their potential). On the Q2 fiscal 2026 call, Vasos said the company continues "to target annualized comp sales lift of approximately 6% in Project Renovate stores and approximately 3% in Project Elevate stores."19 Against remodel capital in the low-to-mid six figures per store, those are attractive returns if they hold.
Negatively, it is an admission that the runway for new units is shorter than the growth story of the 2010s implied. Remodels are a one-time lift per store, not a compounding engine — you can only renovate a given box once. A company that adds 300 net stores a year on a base of 21,000 is growing units at under 1.5%. The long-term algorithm now depends far more on same-store productivity than on unit count, and that is a materially different business to underwrite.
The Shrink Reversal
The defensive half worked faster and more visibly. Having pulled self-checkout out of thousands of stores and layered in analytics to flag mis-scans and probable theft patterns, the company got shrink moving in the right direction — and it shows up exactly where it should, in gross margin.
In the second quarter of fiscal 2025, gross margin expanded 137 basis points to 31.3%, driven primarily by lower shrink, higher markups, and lower damages.18 In the first quarter of fiscal 2026 it expanded another 65 basis points to 31.62%, with management noting that shrink had "significantly improved from elevated levels in recent years" and that damages, while still elevated, had improved for five consecutive quarters.20 In the second quarter of fiscal 2026 it expanded a further 127 basis points to 32.6%.4 CFO Donny Lau told analysts the company continues to expect shrink and damages to contribute about 50 basis points of incremental gross margin expansion.19
The Scoreboard, and How Much of It to Credit
The recent operating results are unambiguous on their face. In the July 2026 quarter, comps of 3.5% came alongside continued traffic growth, and every merchandise category posted positive comps. Vasos noted that non-consumable categories were in their sixth consecutive quarter of momentum and said share gains "accelerate[d] in the quarter."19 Guidance moved up: net sales growth of approximately 4.0% to 4.3%, comps of 2.5% to 2.9%, EPS of $7.80 to $8.00.4
Now the skeptical read, which is where this section has to land.
Trace where the earnings growth actually came from. In the July 2026 quarter, sales rose 5.2% while operating profit rose 29.2%. That enormous gap is margin recovery, and margin recovery is overwhelmingly a shrink-and-damages story — reclaiming profit the company was previously losing to its own operational failures. That is genuine, high-quality earnings. It is also, by definition, non-repeatable. Once shrink normalizes, the tailwind stops, and growth has to come from comps.
The comps themselves deserve scrutiny too. A 3.5% comp with traffic growth is a good number for this format. But part of the traffic is trade-down: Vasos explicitly attributed incremental gains to "the $100,000 and above crowd" trading into Dollar General.19 Trade-down is a macro gift, not a competitive victory, and it reverses. The 2020–2022 sequence is the cautionary case — the company took credit for a trade-down cycle, and when it reversed the earnings went with it.
So: is the turnaround real? The evidence supports a bounded version. Dollar General has demonstrably fixed a set of self-inflicted operational problems, and the gross margin recovery is measurable, sustained across at least six quarters, and traceable to specific, identifiable actions the company took. That is more than management rhetoric. What the evidence does not yet establish is new pricing power, a structurally better cost position, or share gains that survive a macro in which higher-income shoppers stop trading down. The claim that Dollar General is now a better business than it was in 2019 remains unproven. The claim that it is a better-run business than it was in 2024 is supported.
The KPI that would settle it: comp sales growth sustained at or above roughly 3% in a quarter where shrink is no longer contributing to gross margin. That would separate the operating improvement from the loss-recovery.
Tariffs: A Structural Advantage That Is Real But Narrow
One structural claim does check out cleanly. Dollar General directly imported approximately 4% of its purchases at cost in fiscal 2025, with a substantial portion of that from China.5 Compared with general-merchandise-heavy discounters whose direct import exposure runs many times higher, that is a meaningfully smaller direct tariff surface.
The important caveat is in the company's own disclosure: many of its domestic vendors import, and those costs arrive indirectly through the cost of goods.5 Direct import exposure of 4% understates true tariff sensitivity. It is a real advantage, but it is a partial hedge, not immunity — and the company has acknowledged tariffs feeding into prices.21
The Optionality Graveyard
Two entries belong in the record before anyone underwrites a future adjacency.
Dollar General announced in 2021 an ambition to become a "health destination." The most concrete expression was a mobile-clinic partnership with DocGo under the DG Wellbeing banner. It ran as a pilot at three stores in Tennessee and was discontinued on May 31, 2024, after roughly eighteen months, by mutual agreement.22 Three stores is a small experiment, and it should be described as one rather than inflated into a strategic failure — but it is also the entirety of what a stated ambition to become a health destination produced.
pOpshelf is the larger entry: a format promoted as a genuine growth vector, then cut by roughly a fifth and held near 180 stores.15
The pattern that matters is not that either bet failed — most retail adjacencies fail. It is the conversion rate from announced ambition to standalone profitability, which so far is zero across two attempts. Any future pitch involving retail media, delivery, financial services, or another adjacency should therefore be treated as unproven until it discloses standalone economics, regardless of how large the addressable market sounds. This company's demonstrated competence is running small boxes in small towns. The evidence that it can build something else is currently absent.
Which brings us to the thing it demonstrably can do.
VI. The Core Business: Small-Box Economics and Who Actually Competes With Dollar General
Picture a town of 3,000 people somewhere in southern Missouri. There is a gas station, a church, a school, maybe a diner. The nearest Walmart Supercenter is twenty-six minutes away. The nearest full-service grocery store closed in 2011 when the family that ran it retired.
There is a Dollar General.
That store is roughly 8,500 square feet, staffed by a handful of people, leased rather than owned, stocked with about 12,000 SKUs weighted heavily toward the things a household buys every week. It is not the cheapest place in America to buy detergent — a Walmart run would beat it on price, sometimes substantially. But a Walmart run costs fifty-two minutes of driving plus fuel. For a household buying one item, or four, the Dollar General is not competing on price. It is competing on total cost including time, and on that basis it wins by a wide margin.
This is the actual moat, and it is worth stating precisely because it is often stated loosely.
The Mechanism
The advantage is not brand, and it is not scale purchasing power — Walmart's is vastly larger. It is that Dollar General's cost structure allows a store to be profitable in a trade area too small to support anyone else's format. A small leased box with low fit-out cost, minimal staffing, a consumables-weighted assortment with high turns, and a distribution network built to serve thousands of tiny stores efficiently produces a breakeven volume so low that a few thousand nearby people are enough.
In Hamilton Helmer's 7 Powers vocabulary, this is closest to a cornered resource combined with scale economies — but the cornered resource is geographic, not proprietary. Dollar General does not own the towns. It owns the first-mover position in them, and the relevant barrier is that a second small-box entrant in a town of 3,000 would split a market too small for either to earn its cost of capital. That is a real deterrent, and it is why the format has stayed remarkably uncontested in its smallest markets.
But notice the boundary condition. The advantage is a function of trade-area size, and it decays continuously as that size increases. In a town of 3,000, Dollar General is effectively unchallenged. In a town of 15,000, an Aldi becomes viable. In a town of 40,000, a Walmart Neighborhood Market or Supercenter is viable and Dollar General is one option among several — competing, at that point, mostly on convenience and losing on price and assortment. The 2025 closure of 96 predominantly urban stores was that boundary condition asserting itself.15
So the correct statement of the moat is: strong and defensible in the smallest trade areas, weakening monotonically as trade-area population rises, and essentially absent in cities. That is a genuine competitive advantage. It is not a general one.
Who Is Actually Coming
Walmart is the one that matters most, and the evidence here is genuinely favorable to Dollar General. Placer.ai's foot-traffic analysis found Walmart's share of visits among the top five retailers fell from 55.9% in 2019 to under 50% by 2025, while Dollar General rose from 12.1% of combined visits in 2019 to overtake Target between January and July 2025.23 Target had held 15.9% of those visits in 2019.
That is a checkable, third-party-measured share gain, and it is one of the strongest affirmative data points in the bull case. Two caveats keep it honest: visit share is not dollar share, and Dollar General's average ticket is a fraction of Walmart's or Target's, so a visit-share crossover does not imply a revenue-share crossover. And Walmart has both the balance sheet and the demonstrated willingness to invest in price when it wants share back. A rural price war would be existential for one participant and merely annoying for the other.
Aldi is the more insidious threat, because it attacks the specific thing Dollar General has become. Aldi is a hard discounter with a small, private-label-heavy assortment and a genuinely lower price on groceries. It plans more than 180 new stores in 2026 across 31 states, bringing it to nearly 2,800 locations, with a target of 3,200 by the end of 2028, backed by roughly $9 billion of investment and three new distribution centers. It is entering Maine as its 40th state, adding 50-plus stores in Colorado, and converting nearly 80 Southeastern Grocers locations in 2026 alone, part of more than 200 planned conversions by end-2027.24 Aldi says one in three U.S. households shopped its stores in the past year.24
Here is why that matters more than the raw store count suggests. Dollar General now derives 82% of sales from consumables. Aldi sells consumables cheaper. Aldi's format needs a larger population than Dollar General's, so it cannot follow into the smallest towns — but as it densifies across the Southeast and Midwest, it progressively takes the larger end of Dollar General's trade-area distribution. The mix shift into consumables that pressured Dollar General's margins also moved it directly into the crosshairs of the most disciplined grocery discounter in the world. Those two facts are usually discussed separately. They should not be.
Dollar Tree is increasingly a different business rather than a direct rival, and its own numbers show it. Its multi-price strategy — moving beyond the founding $1.25 point into higher tiers — drove a 5% fourth-quarter comp, but the composition was the opposite of Dollar General's: average ticket rose 6.3% while traffic fell 1.2%, with discretionary comps up 6.2% against consumables up 3.6%.25 That is a company earning more per visit from fewer visits, tilting discretionary and suburban. Dollar General's recent comps have been traffic-led and consumables-weighted. The overlap between the two is thinner than the shared word "dollar" implies, and it has been getting thinner.
Five Below overlaps least and is growing fastest: net sales up 22.9% to $1.26 billion in the quarter ended August 1, 2026, comps up 14.1%, 52 net new stores in the quarter to reach 2,022 locations, and full-year guidance raised to $5.63–$5.71 billion with comps of 10% to 12%.26 It targets teens and young families with treasure-hunt discretionary merchandise in suburban centers. It is not taking Dollar General's detergent customer. It is relevant mainly as evidence that discretionary small-box retail can grow at rates Dollar General's discretionary experiments never approached — which reflects poorly on pOpshelf's execution rather than on the core.
E-commerce, including Temu and Amazon, is the long-horizon question. Same-day and next-day delivery economics remain poor in a town of 3,000, which is the same reason Walmart does not build there. But the general-merchandise portion of Dollar General's basket — the 18% that is seasonal, home, and apparel — is precisely the portion most exposed to cheap direct-from-China e-commerce over a decade. That is where the pressure lands first, and it is the higher-margin part of the mix.
Porter, Briefly
Running the five forces without the jargon: rivalry is low in the smallest towns and intensifying everywhere else; buyer power is individually nil but collectively acute, because this customer is the most price-elastic in America and demonstrated in 2024 exactly how fast spending contracts; supplier power is moderate and asymmetric — Dollar General's scale gives it leverage with most vendors, but the large consumer packaged goods companies whose brands drive traffic hold real pricing power; substitutes are the genuine long-term concern, since Aldi substitutes on price and e-commerce substitutes on assortment; and barriers to entry are high in small towns and low everywhere else.
Why It Wins From Here, and What Breaks It
It wins if two things hold simultaneously: remodel-driven comps deliver something close to the 6% and 3% lifts management has targeted, and the shrink gains prove durable rather than a one-time recovery. In that scenario, a low-single-digit comp on a slowly growing store base with recovering margins compounds respectably.
It breaks if Walmart invests in price and Aldi keeps densifying faster than Back to Basics savings can offset — squeezing the consumables business that is now 82% of sales from two directions at once. It also breaks, more quietly, if the 2024 pattern repeats: execution drifting while management attributes the result to the customer. In a business earning roughly six cents of operating profit per sales dollar, there is no margin of error to absorb a second episode.
The judgment: the real-estate advantage is genuine and evidenced, but it is narrower than the company's ubiquity suggests, and it is a defensive asset — it protects the existing store base far better than it generates growth. Growth now depends on remodel execution and on management, which is precisely where the picture is about to change.
VII. Current Management: Track Record, Incentives, and Whether Trust Has Actually Been Rebuilt
Todd Vasos has now been CEO of Dollar General twice — from June 2015 to November 2022, and from October 2023 to the present — for about ten years in total. The second stint has a defined end date. On March 24, 2026, the company announced that Jerry W. "JJ" Fleeman Jr. would become CEO effective January 1, 2027, with Vasos serving as senior advisor through April 2, 2027 and remaining on the board thereafter.6
Fleeman is not a dollar-store operator. He spent about 35 years across Ahold Delhaize's businesses, ran Peapod Digital Labs from May 2018 to April 2023 — the group's e-commerce and digital platform arm — and has served as CEO of Ahold Delhaize USA since April 2023, overseeing Food Lion, Giant Food, Hannaford and Stop & Shop.6 Chairman David Rowland cited his "proven CEO track record."6
The hire is a legible strategic statement. Dollar General is now overwhelmingly a food-and-consumables retailer that has publicly identified cooler capacity and fresh-adjacent assortment as central to its remodel programs, and it has just hired a grocery executive with a digital background to run it. Whether that reads as sensible — matching the leader to what the business has actually become — or as risk depends on a question that will take years to answer: whether small-box rural consumables retailing is close enough to supermarket operating to transfer. Food Lion and Dollar General serve overlapping customers in overlapping geographies, which helps. A 40,000-square-foot supermarket with a perishables department and a 8,500-square-foot leased box with three employees on shift are different operating problems, which does not.
There is also a plain succession-risk observation to make. This board has already had one CEO transition fail publicly and expensively, in under a year. It is now attempting another, this time with an external hire who has never run this format, at a company whose recovery is credited substantially to the person departing. Vasos remaining on the board provides continuity. It also creates the classic awkwardness of a predecessor watching over a successor's shoulder — the exact configuration that existed in 2022 and 2023.
The rest of the leadership team was largely rebuilt around Vasos: Emily Taylor became COO in November 2024, and Donny Lau returned as CFO in October 2025.27 The general counsel role has been in transition. That is a lot of newness in the senior ranks arriving simultaneously with a new CEO.
Compensation and the Shareholder Signal
The say-on-pay sequence tells a specific and bounded story.
After the 2024 rebuke, the response was unusually energetic. In the autumn of 2024 the company conducted outreach to holders of roughly 66% of outstanding shares, with holders of about 56% agreeing to engage and the chairman personally sitting in on meetings with investors representing 31% of shares outstanding.14 Shareholder concern focused substantially on a perceived pay-for-performance imbalance created by the one-time option award granted to Vasos when he returned in October 2023, and on certain structural features of the program.14 Changes followed, addressing overlap between short- and long-term incentive metrics and maximum payout levels, and support recovered to 93.5% at the 2025 meeting.27
Then it slipped again. At the May 28, 2026 annual meeting, say-on-pay drew 160,040,421 votes for against 21,835,901 opposed — about 87.3% support.28
Three observations. First, this is evidence of a board that responds to shareholder pressure, which is genuinely worth something. Second, 87.3% is materially below 93.5%, and the direction is the wrong one in a year when operating results were good — which suggests the underlying pay structure, rather than performance, is what a slice of the shareholder base objects to. Third, and most important: engagement that changes the presentation and the metric overlap is not the same as engagement that changes the quantum or the structure. The proxy describes the committee taking input into account on equity award type, mix, metrics, and performance periods.27 It does not describe a fundamental redesign. "Responsive" is supported by the evidence; "fixed" is not.
The Labor and Safety Record
This is where the credibility question gets genuinely uncomfortable, and where it deserves to be confronted directly rather than deferred to a risk list.
The July 2024 OSHA settlement required Dollar General to pay $12 million, hire additional safety managers, reduce inventory and improve stocking efficiency, provide safety and health training to all employees, and establish a safety and health committee with employee participation.9 It resolved contested and open federal inspections involving blocked exits, blocked electrical panels, blocked fire extinguishers and unsafe storage.10 Cumulatively, OSHA proposed more than $26 million in penalties against the company between January 2017 and July 2024.10
That record spans Vasos's first tenure, Owen's tenure, and Vasos's second tenure. It predates and postdates the turnaround. It is therefore not attributable to any single leadership regime, which is precisely what makes it a structural rather than a situational observation: the store-conditions problem is a function of the operating model — very high store count, very low labor hours per store, high inventory intensity — not of who occupies the corner office.
The 2026 shareholder proposal made the argument explicitly. Filed by a coalition including Mercy Investment Services, Presbyterian Life & Witness, the Sisters of St. Joseph of Peace, Portico Benefit Services and Schroder Unit Trust, it asked the board to report on the feasibility of adopting a comprehensive human rights policy aligned with international standards.29 The supporting statement cited National Labor Relations Board findings of "blatant hallmark unfair labor practices," eight unfair labor practice cases still pending as of April 2026, the OSHA record, 79 shootings at Dollar General locations between 2022 and 2024, a median employee wage of $18,876 against CEO compensation of $8.16 million — a ratio of 432 to 1 — and 92% of workers earning below $15 an hour. It contrasted Dollar General with Dollar Tree, Target, Walmart and Costco, each of which has adopted comprehensive human rights policies explicitly referencing UN and ILO standards.29
The proposal failed on May 28, 2026, receiving 53,033,609 votes for against 128,843,194 opposed — roughly 29% support.28 Two other shareholder proposals also failed: a director resignation policy at about 14.8%, and a lower special-meeting threshold at about 41.8%.28
An investor should read the 29% carefully in both directions. It is a clear defeat, and it means the proposal is not an imminent governance forcing event. But roughly three in ten shares voted against the board's recommendation on a labor and human rights question, which for a proposal of this type is a substantial minority rather than a fringe — and the special-meeting proposal at 41.8% suggests a broader appetite for shareholder rights than the headline results imply.
The Net Read
Management's operational credibility has improved on evidence, not assertion: six quarters of gross margin expansion traceable to specific interventions, guidance raised repeatedly rather than cut, and a strategy described in consistent terms across calls rather than reinvented each quarter. That is a real change from 2024, when a large guidance cut arrived with an explanation that pointed outward.
But "credibility rebuilt" should be qualified in two ways. The labor and safety pattern was never addressed head-on within the turnaround narrative — it is treated in filings and settlements, not in the strategy the company presents to investors, even though the OSHA remedy and the Back to Basics inventory work are describing the same underlying problem. And the executive who earned the operational credibility is leaving in under four months. Credibility that attaches to a person rather than an institution transfers poorly, and the 2001 restatement and the 2024 collapse both suggest this particular institution has a recurring tendency to let discipline slip when nobody is actively enforcing it.
VIII. Capital Deployment, M&A (or the Absence of It), and the Debt Legacy
Here is a fact that is easy to miss and genuinely unusual: Dollar General has done no material acquisitions since the 2007 take-private. Nineteen years, roughly 13,000 additional stores, and essentially all of it organic.
The natural benchmark is sitting right next door. Dollar Tree acquired Family Dollar in 2015 and spent the better part of a decade wrestling with the integration and impairments that followed. Dollar General, facing similar pressure to consolidate, simply kept building its own stores.
The instinct is to call this capital discipline, and there is something to it. Building a store at a known cost with known unit economics in a trade area you have mapped is a far more reliable use of capital than paying a control premium for someone else's stores and hoping the cultures merge. Dollar General's balance sheet carries $4.34 billion of goodwill,5 essentially all of it inherited from the 2007 LBO accounting — and no post-2007 acquisition write-downs, because there were no post-2007 acquisitions.
But the characterization should be bounded honestly. Avoiding M&A is not automatically discipline; it can equally be an absence of opportunity, or an absence of ambition, or a management team that knew it lacked the integration capability. And the same company that made no bad acquisitions also converted zero of its internally developed adjacencies into a profitable business — pOpshelf cut by a fifth, the health initiative shut down. Capital discipline on the M&A axis coexists with a poor record of organic diversification. The defensible statement is narrow: Dollar General avoided the specific, large, value-destroying acquisition risk that hit its closest peer. That is worth something. It is not evidence of general capital-allocation excellence.
The Leverage Question, Corrected
The commonly repeated framing is that Dollar General remains constrained by leverage inherited from the 2007 buyout, cited at something like 4.5x. That framing needs to be taken apart, because it is misleading in a way that matters.
The actual funded debt is modest. At May 1, 2026, long-term obligations totaled $4.563 billion, consisting of seven tranches of senior notes at coupons between 3.5% and 5.5%, maturing between 2028 and 2052.20 Against fiscal 2025 EBITDA of roughly $3.2 billion, that is well under 1.5x on a funded-debt basis. This is an investment-grade balance sheet with a long, laddered maturity profile and no near-term refinancing wall.
What produces the higher number is leases. Operating lease liabilities at May 1, 2026 were $11.22 billion — $1.55 billion current and $9.67 billion long-term — bringing total balance-sheet obligations to roughly $15.8 billion.20 Once leases are capitalized and the ratio is computed on an EBITDAR basis, the leverage multiple rises accordingly.
That is not an LBO hangover. It is arithmetic. A company that leases 21,000 stores has enormous lease liabilities by construction, and would have them if it had never been bought by KKR. Dollar General's own stated framework targets adjusted debt to adjusted EBITDAR below 3x, in support of middle-BBB ratings from S&P and Moody's — a lease-inclusive target, on a lease-heavy model.
What is true is that the company chose to protect its rating rather than buy stock. It repurchased no shares in fiscal 2025 and none in the first quarter of fiscal 2026, stating in filings that it had not repurchased since 2022 "to preserve our investment grade credit rating."20 The dividend was maintained throughout, most recently at $0.59 per share quarterly.28
And on August 27, 2026, that changed. Lau told analysts the company "now intend[s] to resume our share repurchase program in the third quarter," with up to $700 million of stock in the second half, citing cash position, liquidity, progress toward the long-term financial framework, and confidence in the business.19 Remaining authorization stood at $1.4 billion.4
An activist would press hard on the timing, and the objection is fair. Dollar General bought no stock through the 2024 trough, when the shares were at their cheapest in six years, and is resuming after a substantial recovery. Judged purely on execution, that is buying high relative to the opportunity that existed. The counterargument is real too — a downgrade during an operational crisis would have raised the cost of capital on $4.5 billion of debt at precisely the wrong moment, and management chose the conservative path. Both are defensible; what is not defensible is describing the sequence as opportunistic capital allocation. It was defensive, and the resumption should be read as a signal about management's confidence in forward cash flow rather than as a valuation judgment.
Meanwhile the capital that has been deployed went where the strategy said: new stores, the two remodel programs, distribution capacity, and Mexico. Capital expenditure guidance for fiscal 2026 is $1.4 billion to $1.5 billion.4 Against roughly $42 billion of revenue and 21,000 stores, that is a maintenance-plus-modest-growth budget — appropriate for a company that has shifted from building to fixing, and a further confirmation that the growth algorithm has changed.
IX. Risk Radar
The risks worth carrying are the ones with a mechanism attached to this specific business.
Remodel execution. The entire growth case now rests on Renovate and Elevate delivering roughly 6% and 3% annualized comp lifts across thousands of stores a year. These are company-reported targets, and the individual store results are not independently verifiable from outside. If actual lifts come in materially below target, the arithmetic breaks quickly: with unit growth under 1.5% and shrink recovery finite, there is no other engine. Watch total company comps as the aggregate check, since remodels are large enough relative to the base that a shortfall cannot hide.
The two-sided squeeze on consumables. With 82% of sales in the lowest-margin category, Dollar General is maximally exposed to exactly the arena Walmart and Aldi are contesting most aggressively. Walmart has the balance sheet to invest in price; Aldi has a structurally lower-cost grocery model and is adding 180-plus stores a year. Neither reaches the smallest towns, but both progressively take the larger end of Dollar General's trade-area range.
Labor and regulatory exposure. Eight NLRB unfair labor practice cases remained pending as of April 2026.29 The OSHA settlement commitments carry ongoing compliance obligations, and the severe-violator framework exposes the company to elevated per-violation penalties on repeat findings. The financial magnitude is manageable against $42 billion of revenue; the more relevant concern is that the underlying cause — inventory intensity against thin store labor — is the same variable the earnings model depends on. Cutting store hours to protect margin is the lever most likely to re-create the problem.
Consumer demand sensitivity. This was demonstrated, not theorized, in 2024. Dollar General's customer has the least financial slack of any major retailer's, and the trade-down that is currently helping comps runs in both directions.
Shrink durability. The margin recovery of the last six quarters is substantially a shrink-and-damages reversal. Sustaining it requires continued investment in store labor, loss prevention, and analytics. If cost pressure returns and the company reaches for the labor lever, the historical record suggests what happens next.
Refinancing and rates. Genuinely modest. Senior notes are laddered from 2028 to 2052 with no concentration, and the funded-debt ratio is low.20 The lease obligations are the larger economic commitment, but they are operationally flexible over time — leases expire, and the company has demonstrated it will close stores at expiry.
Tariffs and supply chain. Bounded by the 4% direct import figure, but not eliminated, since domestic vendors pass through import costs.5
Leadership transition. Added by the March 2026 announcement, and arguably the largest single unquantifiable risk on this list, given that the last transition failed within eleven months.
X. Bear vs. Bull
The bear case starts with what 2024 proved rather than what it feared. A business converting roughly six cents of every sales dollar into operating profit has essentially no tolerance for operational drift, and this company demonstrated within a single year that it can lose more than half its net income without losing a single point of revenue growth. The mix shift into consumables is a genuine, measurable, largely one-directional margin headwind — and it has walked the company into direct competition with the world's most efficient hard discounter at exactly the moment that discounter is adding 180 stores a year. New unit growth has decelerated from 882 net additions to 299 in two years, which means the multiple has to be justified by same-store productivity rather than expansion. The recurring OSHA and NLRB pattern spans three leadership regimes and points at the operating model itself, not at any individual. Two organic growth ventures were tried and neither reached standalone profitability. And the CEO who is credited with the recovery leaves on January 1, 2027, replaced by a supermarket executive who has never run this format, at a board that got its last succession badly wrong.
The sharpest activist question is a simple one: if the last two years of earnings growth came substantially from reclaiming profit the company had previously lost to itself, what is the growth rate once that recovery is complete?
The bull case rests on evidence rather than narrative, which is its main strength. Six consecutive quarters of gross margin expansion tied to identifiable actions. Five consecutive quarters of traffic growth into the July 2026 quarter, with comps of 3.5% and every category positive.19 Guidance raised repeatedly rather than cut. A third-party foot-traffic dataset showing genuine share gains against both Walmart and Target through 2025.23 Direct import exposure of roughly 4%, a real if partial insulation against the tariff pressure hitting general-merchandise peers.5 A balance sheet whose funded leverage is low enough that management has now chosen to put up to $700 million into buybacks.19 And a real-estate position — 80% of stores in towns of 20,000 or fewer, with 75% of Americans within five miles — that is genuinely difficult to replicate, because the economics of replicating it are bad for the second entrant.5
Weighing them. The two cases are not symmetric, and it is worth saying how they resolve rather than leaving them side by side.
The moat claim survives, narrowed. Dollar General does have a defensible position, but it is geographically contingent — strong below roughly 10,000 population, contested above it, absent in cities — and it is defensive rather than growth-generating. The falsifying test is whether comps in the smallest-town cohort hold up as Aldi densifies; the company does not disclose that cohort separately, which is itself a disclosure gap worth noting.
The operational-turnaround claim survives, bounded. It is supported by six quarters of margin data traceable to specific actions, which is more than rhetoric. It is not yet supported as evidence of a structurally better business, because the improvement is loss-recovery plus a trade-down cycle, neither of which is repeatable.
The management-quality claim is the one the history most clearly narrows. Across 2001, 2015–2022, 2023, and 2024, the recurring pattern is discipline that erodes when it is not being actively enforced. Vasos's return demonstrably re-imposed it. Nothing in the record establishes that it has become institutional, and the record specifically includes a failed succession in 2023 and a labor and safety pattern that persisted across every regime. That is the claim most exposed by a CEO transition, and it is the reason the January 2027 handover is the single most consequential scheduled event in this story.
The optionality claim is rejected on the evidence. Two attempts, zero conversions to standalone profitability. Any new adjacency should be underwritten at approximately zero until it discloses its own economics.
XI. Playbook: What Dollar General Teaches About Retail, Leverage, and Leadership Continuity
Distinguish balance-sheet leverage from lease leverage before concluding a company is constrained. The "still burdened by the 2007 LBO" story about Dollar General is largely wrong. Funded debt is modest and laddered; the large number comes from capitalizing thousands of store leases, which is a structural feature of leased-footprint retail rather than a private-equity scar. Getting this distinction wrong leads to the wrong conclusion about capital-return capacity — as the resumption of buybacks in 2026 demonstrated.
An emergency CEO reversion can restore operating metrics quickly and still leave the underlying institution unchanged. Vasos's return produced a measurable operational recovery within about six quarters. It did not resolve a labor and safety pattern that has now spanned three leadership regimes and roughly a decade of regulatory findings. Operating metrics respond to attention; institutional culture responds to structure. Investors should not read the first as evidence of the second.
In low-margin, high-unit-count retail, execution failures compound faster than management concedes in real time. Dollar General's revenue never declined. Its earnings halved. The entire loss occurred in the space between the top and bottom line, distributed across thousands of stores in increments too small to notice individually. By the time it was legible in the reported numbers, it was already a full-year guidance cut. The lesson is to weight gross margin trend and store-condition evidence — including regulatory findings, which are unusually good high-frequency data on store conditions — over the narrative framing offered on the call.
Organic-only growth genuinely avoids acquisition risk, and genuinely does not prove capital-allocation skill. Dollar General sidestepped the write-down its closest peer took on Family Dollar. It also failed to build anything profitable outside its core in two attempts. The absence of a bad acquisition is a real, checkable benefit; it should not be inflated into a general claim about discipline.
Trade-down is a loan, not income. Both the 2020–2022 peak and the 2025–2026 recovery drew meaningfully on higher-income shoppers moving down. Both times, the company had every incentive to describe it as share gain. It is worth separating the two in real time, because the reversal is what produced August 29, 2024.
XII. Recent News & What To Watch
The last twelve months have been the best stretch of operating results Dollar General has posted since the pandemic, and the most consequential news has been about who will inherit them.
The July 2026 quarter delivered the strongest set of numbers of the recovery — a 5.2% sales increase, a 3.5% comp, a 29.2% jump in operating profit, and a 33.3% rise in diluted EPS — alongside raised full-year guidance and a capital-return signal in the form of resumed buybacks.419 The shareholder votes at the May 28, 2026 annual meeting resolved the human rights proposal, which failed at roughly 29% support, while say-on-pay slipped from 93.5% to 87.3%.28
Five things now carry the story forward.
The Fleeman transition on January 1, 2027. The most important item on this list by a wide margin. Watch for whether the Back to Basics program and the remodel cadence are sustained without modification through the first several quarters, and whether Fleeman's grocery and digital background produces a strategic shift — particularly around fresh, cooler capacity, or delivery. Any new adjacency announcement should be measured against the pOpshelf and DG Wellbeing record before it is credited.
Remodel comp-lift disclosure. The 6% Renovate and 3% Elevate targets are the growth algorithm. The company reports them as targets rather than achieved results at the cohort level; the practical check is whether total-company comps hold in the 2.5%-plus range as remodel volume accumulates.
Shrink durability. Damages remain elevated even after five consecutive quarters of improvement.20 The relevant question is what happens to both once the year-over-year recovery comparison is exhausted, and whether store labor investment is sustained if margin pressure returns.
Buyback execution. Up to $700 million in the second half, against $1.4 billion of authorization.4 Whether the company actually deploys it, and at what pace, is a live test of how confident management is in forward cash flow.
The NLRB docket and the labor question. Eight unfair labor practice cases were pending as of April 2026.29 The 29% vote for the human rights proposal removed the immediate governance pressure but did not remove the underlying operating issue, and a new CEO arriving from a heavily unionized supermarket background may approach it differently.
XIII. Key KPIs
Three metrics carry the weight here, and everything else is commentary.
Same-store sales growth, with the traffic-versus-ticket split. This is the master KPI now that unit growth has decelerated below 1.5%. The split matters as much as the headline: traffic growth means the format is winning customers, while ticket growth alone can simply be inflation passing through. Recent quarters have shown traffic leading, which is the higher-quality version.
Gross margin, and specifically the shrink-and-damages contribution within it. This is where the entire 2024 collapse and the entire 2025–2026 recovery played out. The critical thing to watch is the composition: margin expansion driven by shrink recovery is finite loss-reclamation, while margin held or expanded after shrink normalizes would be genuine evidence of a structurally better business. Set against it is the permanent drag from the consumables mix, which management has not claimed will reverse.
Adjusted debt to adjusted EBITDAR, against the company's stated sub-3x target, alongside buyback pace. This is the honest leverage measure for a lease-heavy retailer, and it is the constraint management itself has cited for four years. The pace of actual repurchases against the $700 million second-half plan is the cleanest available read on how much financial flexibility the company believes it has genuinely recovered.
References
-
Dollar General shares crater as retailer cuts outlook, blaming 'financially constrained' customers — CNBC, 2024-08-29 ↩
-
Dollar General (DG) Q2 2024 Earnings Call Transcript — The Motley Fool, 2024-08-29 ↩↩↩
-
Why Dollar General Stock Fell 44% in 2024 — The Motley Fool, 2025-01-14 ↩↩
-
Dollar General Corporation Reports Second Quarter 2026 Results (Form 8-K, Exhibit 99) — SEC, 2026-08-27 ↩↩↩↩↩↩↩↩
-
Dollar General Corporation Form 10-K, fiscal year ended 2026-01-30 — SEC, filed 2026-03-20 ↩↩↩↩↩↩↩↩↩↩
-
Dollar General Announces CEO Succession and Leadership Transition (Form 8-K, Exhibit 99) — SEC, 2026-03-24 ↩↩↩↩
-
SEC v. Dollar General Corporation, Hurley Calister Turner Jr., Brian M. Burr, Randy C. Sanderson, and Bobby R. Carpenter — SEC Litigation Release No. 19174, 2005-04-07 ↩↩↩
-
KKR Completes Acquisition of Dollar General Corporation — KKR, 2007-07-06 ↩
-
Department of Labor announces settlement with Dollar General requiring corporate-wide safety investments in stores nationwide — OSHA, 2024-07-11 ↩↩↩
-
Dollar General settles with Labor Department over workplace safety violations — CNBC, 2024-07-11 ↩↩↩
-
Dollar General Corporation Announces Leadership Transition (Form 8-K, Exhibit 99.2) — SEC, 2023-10-12 ↩↩↩
-
Dollar General brings back former CEO Todd Vasos — CNN Business, 2023-10-12 ↩
-
Dollar General curtails self-checkout given theft — Retail Customer Experience, 2024-03-28 ↩
-
Dollar General Corporation DEF 14A Proxy Statement — SEC, filed 2025-03-27 ↩↩↩
-
Dollar General to close 96 stores, 45 pOpshelf locations — Retail Dive, 2025-03-13 ↩↩↩↩
-
Dollar General Corporation Reports Fourth Quarter and Fiscal Year 2024 Results (Form 8-K, Exhibit 99) — SEC, 2025-03-13 ↩↩
-
Dollar General Corporation Plans to Execute Approximately 4,730 Real Estate Projects in Fiscal 2026 — MarketScreener ↩
-
Dollar General Corporation Reports Second Quarter 2025 Results (Form 8-K, Exhibit 99) — SEC, 2025-08-28 ↩↩
-
Dollar General (DG) Q2 Fiscal 2026 Earnings Call Transcript — The Motley Fool, 2026-08-27 ↩↩↩↩↩↩↩↩
-
Dollar General Corporation Form 10-Q, quarter ended 2026-05-01 — SEC, filed 2026-06-02 ↩↩↩↩↩↩
-
Dollar General revenue grows, but tariffs begin impacting prices — Retail Dive ↩
-
Dollar General shuts down mobile clinics, becoming latest retailer to abandon primary care — Healthcare Brew, 2024-06-03 ↩
-
A New Era for Retail Giants: Who's Winning in 2025? — Placer.ai ↩↩
-
ALDI US Doubles Down on Growth in 2026 — ALDI US Newsroom ↩↩
-
Multi-price strategy drives Dollar Tree sales gains — Supermarket News ↩
-
Five Below, Inc. Announces Second Quarter Fiscal 2026 Financial Results — GlobeNewswire, 2026-09-02 ↩
-
Dollar General Corporation DEF 14A Proxy Statement — SEC, filed 2026-04-07 ↩↩↩
-
Dollar General Corporation Form 8-K — 2026 Annual Meeting Voting Results, SEC, filed 2026-06-02 ↩↩↩↩↩
-
Notice of Exempt Solicitation (PX14A6G) — Dollar General human rights policy proposal, SEC, filed 2026-05-21 ↩↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube