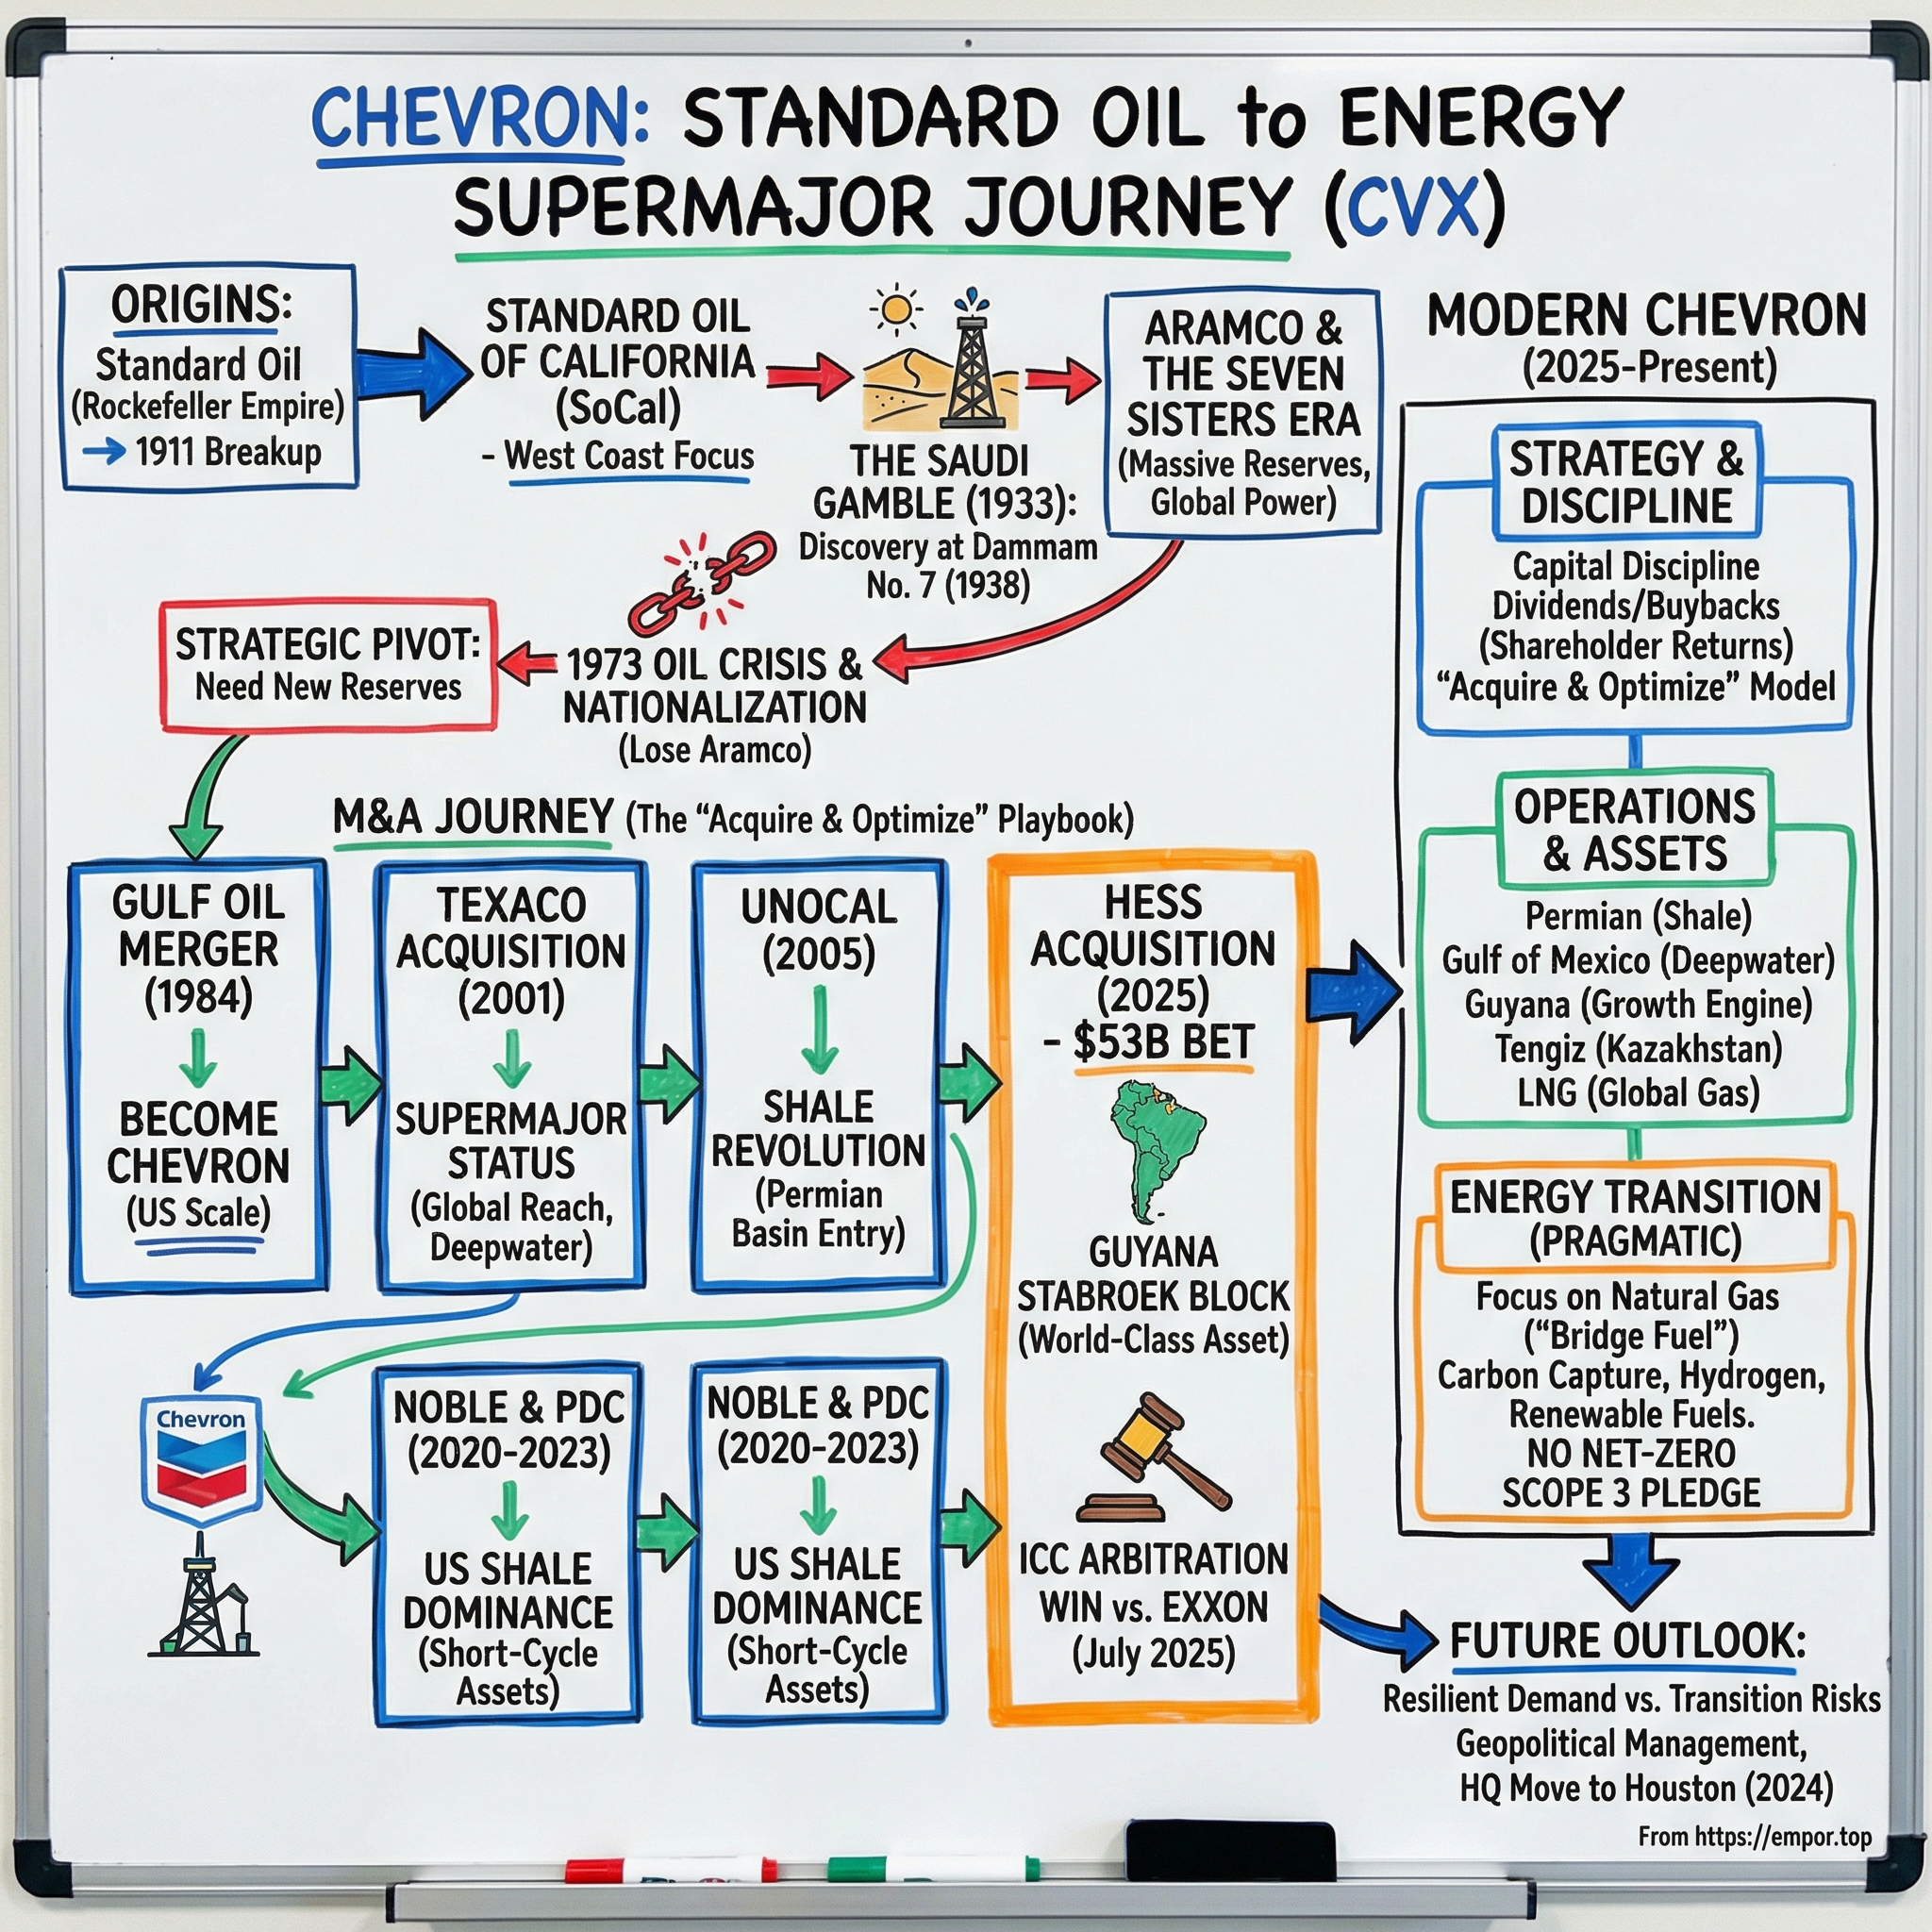
Chevron: The Capital Discipline Supermajor
I. Cold Open & The Big Picture
In a conference room far from any oil field, three arbitrators appointed under the rules of the International Chamber of Commerce spent the better part of 2025 deciding the fate of the largest energy transaction of the decade. The question in front of them was almost comically technical: does a right of first refusal buried inside a joint operating agreement for an offshore block in Guyana get triggered when someone buys the parent company of one of the partners? On July 18, 2025, they said no. Within hours, Chevron closed its acquisition of Hess Corporation, and ExxonMobil — which had spent sixteen months arguing the opposite — issued a statement saying it disagreed with the panel's interpretation but respected the process.1
That is how the modern oil business settles its biggest fights: not with wildcatters and derricks, but with lawyers arguing over contract clauses drafted a decade earlier by people who never imagined this scenario. The stakes were the difference between Chevron owning a 30% stake in the most economically attractive oil discovery of the 21st century and Chevron owning a very expensive lawsuit.
Chevron won. And then something happened that no arbitration panel could have scripted.
A price shock changes the frame. On February 28, 2026, military action in the Middle East led to the de facto closure of the Strait of Hormuz. Brent crude, which had opened the year at $61 a barrel amid near-universal forecasts of oversupply, finished the first quarter at $118 — the largest quarterly increase, on an inflation-adjusted basis, in data going back to 1988.2 As of early September 2026, the strait has still not reopened, and Brent trades in the mid-$90s.3 Chevron shares set an all-time closing high of $211.78 on September 2, 2026, and the company carries a market capitalization north of $410 billion.4
Which means the honest starting point for any analysis of Chevron today is this: the company is generating the best financial results in its modern history, and it does not control the variable that produced most of them. In the first quarter of 2026, Chevron earned $2.2 billion.5 In the second quarter — same assets, same people, same drilling plan — it earned $12.1 billion, the highest quarterly profit in six years.6 Nothing operational changed by a factor of five in ninety days. The oil price did.
That is not a criticism of the company. It is the defining condition of the industry, and it dictates how the rest of this story has to be read. For an oil producer, the only questions worth asking are the ones the commodity price does not answer: what does it cost to get a barrel out of the ground, how long can it keep doing that, what does it do with the cash, and who can take the assets away. Everything else is weather.
The Wirth paradigm, and what it actually claims. Chairman and CEO Mike Wirth has spent eight years building a reputation as Wall Street's benchmark for capital discipline. The evidence usually cited: in 2019, Chevron declined to raise its bid for Anadarko Petroleum when Occidental Petroleum went over the top, collected a $1 billion breakup fee, and walked.[^7] Since then, Chevron has bought Noble Energy at the bottom of the COVID crash, bolted on PDC Energy, and absorbed Hess — while holding annual organic capital spending in a band that would have been considered starvation rations in the shale boom.
The more interesting test of that reputation came in 2026. With Brent at $118 and every incentive to spend, CFO Eimear Bonner told analysts on the first-quarter call: "we are not changing any of our capital allocation framework. We are not changing any of our ranges."7 That is a behavioral data point, not a slogan — and it is the single strongest piece of evidence for the discipline thesis in this article. Whether it survives four consecutive quarters of windfall cash is the thing to watch.
The company itself. Chevron is the direct corporate descendant of Standard Oil of California, the West Coast entity spun out of John D. Rockefeller's trust in the 1911 antitrust breakup, and today it is the only oil and gas producer left in the Dow Jones Industrial Average. In the second quarter of 2026 it produced 4.07 million barrels of oil equivalent per day worldwide — up 20% year over year, with U.S. output at a record 2.08 million barrels per day.6 It is the second-largest Western supermajor by production and market value, behind ExxonMobil.
The portfolio behind those barrels is unusually spread out for a company that markets itself on focus. Chevron operates refineries in California, Mississippi and elsewhere, holds half of the CPChem petrochemical joint venture alongside Phillips 66, runs two of the largest LNG plants in Australia, produces in Kazakhstan, Israel, Angola, Nigeria, Argentina, Thailand and Venezuela, and has signed heads of agreement to return to Iraq. Simplicity is not the word for it.
The roadmap. What follows traces how a California wildcatting outfit founded on a canyon seep in 1876 became the operator of the world's largest single-field oil expansion in Kazakhstan, a 30% owner of Guyana's Stabroek Block, the biggest royalty-advantaged landholder in the Permian Basin, and — as of 2026 — a would-be power utility for artificial intelligence data centers. Along the way, this analysis will test the claims that matter to an investor: that the Permian is an inexhaustible high-margin engine, that Chevron executes mega-projects well, that its M&A record is disciplined, and that its low-carbon spending is optionality rather than value destruction. Some of those claims survive the test in narrowed form. One of them does not survive at all.
Three claims carry the investment case, and each gets tested against Chevron's own record rather than against management's description of it. First, that the company owns resources rivals cannot replicate. Second, that it executes large capital projects well. Third, that it allocates capital with a discipline its peers lack. The first is mostly true and narrower than advertised. The second is contradicted by the company's largest recent project. The third is true in one domain and demonstrably false in another.
There is also a question of identity running underneath all of it. Chevron is simultaneously a cyclical commodity producer whose earnings swing violently and a Dow Jones dividend stalwart owned by income funds and retirement accounts that want none of that volatility. Almost every capital-allocation choice the company makes — the flat capital ranges, the preference for stock over debt in acquisitions, the uninterrupted dividend increases through four downturns — is an attempt to serve the second constituency while running the first kind of business. That tension explains more of Chevron's behavior than any strategy document.
It starts, as most American oil stories do, with a man walking up a canyon looking for a seep.
 Subscribe on LinkedIn
II. Roots & Foundational Inflections: SoCal to Saudi Arabia (1876–1948)
In September 1876, in Pico Canyon north of Los Angeles, a well named Pico No. 4 struck oil. Drilled by Star Oil Works, it was California's first commercially successful oil well. Three years later, the operation was reorganized as Pacific Coast Oil Company — the corporate predecessor from which every subsequent form of Chevron descends. That founding date explains why Chevron's dividend announcements still cite roots stretching back nearly 150 years.
Rockefeller arrives, and then leaves. In 1900, Standard Oil purchased Pacific Coast Oil, integrating it into a trust that had been systematically absorbing regional refiners and marketers for two decades. For eleven years, California crude flowed inside the Rockefeller organization. Then, in 1911, the Supreme Court ordered the dissolution of Standard Oil under the Sherman Antitrust Act. The West Coast business emerged as an independent corporation: Standard Oil Company (California), known internally and publicly as SoCal.8
That breakup highlights a recurring theme in Chevron's history: government action has repeatedly shaped its trajectory, creating foundational opportunities rather than merely imposing constraints. Antitrust policy established the independent company, American diplomacy in the Persian Gulf later underwrote its overseas expansion, and federal sanctions policy continues to influence its operating footprint today.
Building the coast. Through the 1910s and 1920s, SoCal constructed the downstream spine of its West Coast business, including the Richmond refinery on San Francisco Bay and the El Segundo refinery south of Los Angeles. Recognizing that the rapid adoption of automobiles required a dedicated retail distribution system, SoCal opened what company histories document as one of the world's first purpose-built drive-in service stations, in Seattle in 1907. In 1926, its acquisition of Pacific Oil Company added substantial crude production and pipeline reach, extending its logistics network from California toward Texas.8
By the early 1930s, SoCal faced a structural imbalance familiar to modern energy executives: ample downstream refining capacity paired with insufficient low-cost crude supply.
The prospect of expanding into Saudi Arabia offered little immediate promise from a boardroom perspective. The geology was unmapped, the political counterparty was a kingdom unified only a year earlier, and the region lacked industrial ports, roads, or domestic demand. Any discovered oil would have to be shipped to overseas buyers already supplied by Texas, Venezuela, and Persia. The financial strain of the Great Depression added further reason for caution.
The gamble that made the company. On May 29, 1933, SoCal attorney Lloyd Hamilton signed a concession agreement with Saudi Arabia's finance minister, Abdullah Suleiman, securing exploration rights across the kingdom's eastern province. The upfront payment was a loan funded in gold — a modest sum relative to the eventual value of the acreage, but a significant speculative commitment during a depression. SoCal's initial geologists arrived at Jubail on September 23, 1933.9 To direct field operations, the company created a subsidiary, California Arabian Standard Oil Company, known as Casoc.10
Five years of costly, unsuccessful drilling followed. By 1936, with no proven reserves in Saudi Arabia and no distribution network east of Suez, SoCal sought a partner. It sold Texaco a 50% interest in the Saudi concession in exchange for cash and access to Texaco's retail networks across Asia and Africa. The joint marketing enterprise, Caltex, created a commercial partnership that endured until the two companies merged in 2001.
That 1936 transaction stands as one of the most consequential capital allocation decisions in Chevron's history. To fund exploration and secure distribution, SoCal surrendered half of what became the largest conventional oil resource on earth to a competitor. While logical as a risk-sharing measure during the Depression, it represented a massive transfer of long-term value. This tendency to trade away upside to mitigate near-term risk recurs throughout Chevron's history, from the Caltex deal to its 2019 decision to walk away from Anadarko Petroleum rather than match Occidental's higher bid.
Dammam No. 7. The Arabian venture achieved its breakthrough under field geologist Max Steineke, who argued that six disappointing wells at the Dammam dome had failed because they were not drilled deep enough into the Arab Zone. On March 3, 1938, Dammam No. 7 — drilled more than 600 meters deeper than earlier tests — struck commercial oil, quickly reaching production of thousands of barrels per day.11 Steineke's subsequent field mapping established the structural framework of the eastern province, establishing his reputation as one of the era's most influential petroleum geologists.11
Aramco and Ghawar. Casoc was renamed Arabian American Oil Company — Aramco — in 1944.10 Four years later came the discovery of Ghawar, which remains the largest conventional oil field ever found. Standard Oil of New Jersey and Socony-Vacuum subsequently bought into the partnership, establishing SoCal among the international supermajors known as the Seven Sisters.
The scale of Ghawar redefined global energy logistics: a single field that ultimately produced more oil than most petroleum-producing nations have in their entire histories. For roughly three decades, SoCal held a 25% stake in the operating consortium on terms negotiated when the kingdom had little bargaining leverage. No asset in Chevron's modern portfolio — including its positions in Kazakhstan's Tengiz field or Guyana's Stabroek Block — offers comparable economic returns.
The physical footprint established during this era remains on Chevron's balance sheet today. The Richmond and El Segundo refineries, built a century ago to process California crude, continue to serve as core refining hubs. Infrastructure assets with multi-decade operating lifespans encourage a long-term planning horizon, serving as a distinct advantage when managing multi-billion-dollar capital projects, but potentially delaying strategic pivots when market conditions change.
What this history means for an investor today. Two primary themes carry forward into modern analysis. First, Chevron's defining resource advantages have rarely come from superior drilling technology alone; they have stemmed from securing early entry into world-class basins and maintaining asset control through long periods of political uncertainty — a playbook visible today in Kazakhstan, Venezuela, and Guyana. Second, its greatest historical asset position was eventually nationalized, creating a loss of low-cost equity reserves that shaped its subsequent approach to project selection and capital discipline.
III. Strategic Consolidation: Aramco Loss, Gulf, Texaco & Unocal (1948–2005)
The loss of the crown jewel of SoCal's portfolio—the lowest-cost, largest, and most profitable oil concession on earth—unfolded in slow motion through the 1970s. Saudi Arabia acquired participating interests throughout the decade and completed its takeover of Aramco by 1980, ending the era of Western supermajors owning Middle Eastern reserves outright.
Decades later, it is easy to view that shift as an inevitable wave of post-colonial resource nationalism. To the international oil companies that had financed five dry years of exploration and built the infrastructure under binding contracts, the outcome was a stark lesson in political risk: a concession is only as durable as a host government's willingness to honor it, and that willingness fluctuates with oil prices and domestic politics. That historical lesson applies directly to Chevron's operations in Kazakhstan, Venezuela, and Iraq today.
The scramble for non-OPEC barrels. What followed across the energy sector was a two-decade hunt for reserves in jurisdictions less prone to expropriation: the North Sea, the deepwater Gulf of Mexico, Alaska, and West Africa. For SoCal, the operational arithmetic was challenging. The company maintained extensive refining capacity and retail marketing networks, but faced a shrinking equity reserve base to supply them. When organic exploration fell short of replacing depleted reserves, corporate acquisition became the primary tool to fill the gap.
Gulf Oil, 1984. SoCal paid roughly $13.2 billion for Gulf Oil, at the time the largest corporate merger in history.8 Gulf, a fellow Seven Sister, had become vulnerable during a takeover attempt led by corporate raider T. Boone Pickens. SoCal stepped in as a white knight, doubling its oil production and reserves in a single transaction while acquiring an extensive refining and retail network. Following the deal, the combined entity adopted Chevron—previously one of SoCal's retail brands—as its corporate identity.
The circumstances of the deal underscored a key industry dynamic. Gulf had been forced into a sale process, allowing SoCal to acquire major assets from a target with limited alternatives. The 1980s consolidation wave demonstrated that an undervalued reserve base invited takeover bids rather than providing protection. Mergers and acquisitions became the industry's default response to weak organic returns, establishing a playbook Chevron would repeat in subsequent decades.
The underlying strategic rationale has remained consistent: when exploration fails to replace reserves at acceptable costs, capital allocation shifts to acquisitions. Chevron has relied primarily on corporate transactions rather than organic discoveries to rebuild its resource base throughout its modern history.
This pattern reframes the conventional narrative around the company's capital discipline. While market commentary often equates capital discipline with restrained capital expenditure, relying on acquisitions means allocating capital in large, periodic outlays at market-determined prices rather than through incremental drilling costs. The discipline of this approach depends entirely on execution and purchase price.
Texaco, 2001. Sixty-five years after selling Texaco a half-interest in its Saudi concession, Chevron acquired Texaco for approximately $45 billion. The transaction unified the long-standing Caltex joint marketing venture under a single corporate umbrella, briefly named ChevronTexaco before reverting to Chevron in 2005.8 The acquisition expanded Chevron's deepwater Gulf of Mexico footprint, international natural gas assets, and downstream refining integration.
Legacy liabilities. The Texaco transaction also brought legacy environmental and legal liabilities that persisted for decades. In Ecuador, a $9.5 billion judgment concerning environmental contamination from Texaco's historical Amazon operations led to multi-jurisdictional litigation. Federal courts in the United States ruled in 2014 that the judgment was obtained through fraud and racketeering—a decision upheld on appeal in 2016—and an international tribunal seated at The Hague reached the same conclusion in 2018.12 Although Chevron successfully defended its position, the dispute absorbed significant management attention and financial resources over two decades.
In Louisiana, legacy legal exposure remains active. In April 2025, a Plaquemines Parish jury found Chevron liable for coastal wetland damage stemming from historical dredging and wastewater practices by Texaco, awarding more than $740 million.13 With more than 40 similar parish lawsuits pending across the industry, the central jurisdictional questions reached the U.S. Supreme Court, which heard argument in January 2026.14 For investors, the key takeaway extends beyond immediate financial penalties: acquiring legacy energy assets can generate ongoing operational and legal liabilities decades after a transaction closes.
Unocal, 2005. Chevron's acquisition of Union Oil Company of California for approximately $18 billion triggered significant geopolitical scrutiny. In June 2005, state-owned CNOOC (China National Offshore Oil Corporation) submitted a competing all-cash bid at a higher valuation. The resulting political reaction included congressional hearings and national security reviews, ultimately leading CNOOC to withdraw its offer. Chevron completed the acquisition in August 2005, adding Asian natural gas, Thai deepwater, and Gulf of Mexico acreage.15
The contest highlighted the strategic value of political alignment in cross-border energy transactions. Chevron secured Unocal as the politically viable domestic buyer rather than the highest bidder—an advantage tied to its corporate domicile. That status continues to provide regulatory and geopolitical access in select international markets.
Long-term competitive dynamics. CNOOC subsequently emerged as a 25% joint venture partner in Guyana's Stabroek Block. In 2024, CNOOC joined ExxonMobil in filing arbitration claims challenging Chevron's proposed acquisition of Hess Corporation's stake in the block—demonstrating how historic competitive rivalries can resurface across major international assets.
By 2005, Chevron's modern structure was largely established: a major producer built through sequential corporate consolidations, managing long-life international positions alongside a substantial domestic upstream and downstream footprint. However, the company had not yet developed the high-margin onshore engine that would define the next era of U.S. energy production.
IV. Core Upstream Engine & Segment Economics
Stand on a well pad in the Midland Basin at three in the morning, and the operation looks less like oil exploration and more like advanced manufacturing: rows of identical wellheads on a single pad, pressure pumps running on automated schedules, sand and water moving through integrated logistics, and a central control room in Midland monitoring pressure data from hundreds of wells simultaneously. The geology is established; the variable being optimized is cost per foot and barrels per dollar of invested capital. This is the onshore model Chevron spent a decade industrializing—and it represents only one of the company's three primary upstream engines.
How the money is actually made. The conventional description of Chevron posits that upstream exploration and production generates nearly all corporate earnings while downstream refining and marketing provides a stabilizing counter-cyclical buffer. Across a full commodity cycle that model holds roughly true, but the volatile market of 2026 demonstrated how dramatically the relationship can break. In the first quarter, as crude prices surged nearly 100% inside ninety days, downstream reported an $817 million loss—with international refining down more than $1 billion—driven by roughly $3 billion in unfavorable timing effects across inventory valuations and derivative positions.57 Just one quarter later, with middle distillate margins tightening severely, downstream produced $4.9 billion in profits across domestic and international operations alongside $8.1 billion from upstream.6
The structural takeaway: downstream refining is not a reliable hedge that smoothly balances upstream volatility. It is a secondary cyclical business governed by its own independent drivers—refining crack spreads, product inventories, and mark-to-market accounting timing—that can either offset upstream swings or compound them. Investors relying on refining earnings for ballast risk being surprised in both directions.
The Permian: a factory with a fence around it
Chevron's Permian Basin position carries a distinct structural advantage rooted in corporate history. In 1962, Texaco acquired two million acres of the historical Texas & Pacific Railway land grant. When Chevron purchased Texaco in 2001, those mineral rights came with it. As a result, Chevron pays low or zero royalties on a substantial portion of its two-million-acre Permian footprint, with royalty-free barrels accounting for roughly 15% of its total basin output.16
In practical terms, while most shale producers lease acreage and surrender 20% to 25% of top-line revenue to landowners before paying operating expenses, Chevron functions as the landowner across much of its footprint. At $70 oil, that royalty advantage yields approximately $15 per barrel in structural margin that peers cannot replicate. It represents the closest equivalent to a cornered asset in U.S. onshore energy—a legacy benefit that cannot be duplicated on the open market.
Testing the growth thesis. Wall Street long framed this royalty-advantaged acreage as an inexhaustible high-margin growth engine. However, operational realities contradict the strongest version of that thesis. As the Delaware and Midland basins matured, operators across the industry—including Chevron—encountered parent-child well interference, where newer infill wells cannibalize pressure from established producers and yield lower production than initial type curves projected. High-quality Tier-1 acreage is finite. In 2023, Chevron paid $7.6 billion in enterprise value to acquire PDC Energy, a transaction designed to bolster inventory in Colorado's DJ Basin and the Permian.[^18] Purchasing inventory reflects an underlying need to replenish core reserves.
Furthermore, management deliberately halted production growth in the basin. Chevron capped Permian output at a plateau of approximately 1 million barrels of oil equivalent per day, guiding 2026 Permian capital expenditure below $3.5 billion—reflecting a roughly 25% improvement in capital efficiency per barrel.17 On the second-quarter 2026 earnings call, management fielded questions regarding the growth cap, stating that the plateau decision was finalized in 2025, that production was beginning to drift higher, and that advanced chemistry alongside AI-driven subsurface modeling could eventually recover a portion of the 90% of hydrocarbons left in place by current completion methods.17
An objective evaluation. A production plateau represents capped growth regardless of narrative framing. The thesis of an endlessly expanding Permian footprint is refuted by Chevron's own capital allocation strategy. What survives is a narrower, highly valuable asset: a long-life, low-royalty resource capable of generating substantial free cash flow at a steady production rate with declining capital intensity. Meanwhile, enhanced recovery via subsurface AI remains an early-stage research initiative without commercial proof points. The critical performance indicator: sustained Permian free cash flow generation at a flat production volume, and whether capital intensity per barrel continues to decline after initial efficiency gains are realized.
Tengiz: the mega-project that tested the execution thesis
Tengizchevroil (TCO)—a 50-50 joint venture between Chevron and Kazakhstan's state oil producer KazMunayGas—operates the giant Tengiz and Korolev fields in western Kazakhstan.18 The underlying reservoir represents a world-class resource: deep, highly pressurized, sour, and expansive. The execution of its multi-billion-dollar expansion, however, proved deeply flawed.
Cost overruns and schedule delays. Sanctioned in 2016 with an initial budget of $36.8 billion, the Future Growth Project and Wellhead Pressure Management Project saw cost estimates surge to roughly $48.5 billion by March 2024, with full start-up delayed years beyond the original mid-2022 target due to pandemic logistics failures, module fabrication breakdowns, and engineering complexities.1920 First oil from the Future Growth Project was finally achieved in January 2025.21
Falsifying execution excellence. The claim that Chevron maintains superior mega-project execution capabilities is directly contradicted by the record at Tengiz. A $12 billion cost overrun and a multi-year delay on a core operated asset represent a budget escalation of nearly one-third. While industry-wide inflation created broad headwinds, the scale of cost expansion at Tengiz placed Chevron at the severe end of peer underperformance.
The durable asset base. The exceptional quality of the underlying resource ultimately absorbed the execution failures. Tengiz now produces above its nameplate capacity of 1 million barrels per day, with debottlenecking expanding Wellhead Pressure Management Project train capacity from 260,000 to 320,000 barrels per day. Consequently, Chevron guided to approximately $6 billion in 2026 free cash flow from TCO at $70 Brent—delivered via affiliate loan repayments and dividends, with cash distributions transitioning to a monthly cadence.717 The revised investment premise is straightforward: Chevron completes its major commitments, and its top-tier asset quality can withstand substantial capital missteps. That reality reflects resilient geology rather than management operational excellence. The critical performance indicator: actual cash distributions collected from TCO relative to the $6 billion target.
Geopolitical transit vulnerabilities. Tengiz production reaches global markets primarily through the Caspian Pipeline Consortium, a 1,500-kilometer pipeline crossing southern Russia to the Black Sea terminal at Novorossiysk, carrying over 80% of Kazakh crude exports—equal to roughly 1% of global oil supply. Throughout 2025 and 2026, the Black Sea terminal faced repeated military strikes. In July 2026, drone attacks struck four crude tankers over four days, forcing temporary suspensions of export loadings, including a vessel handling Tengiz crude.2223 On the second-quarter earnings call, management confirmed that two single-point mooring buoys remained operational with a third returning to service, citing alternative transit options via Caspian shipping, rail, and storage.17 However, when asked by analysts to quantify backup evacuation capacity, executives declined to provide specific figures.
Assessing the risk profile. Chevron's single largest source of incremental growth cash flow relies on a pipeline terminal operating in an active Black Sea conflict zone, supported by alternative evacuation capacity management refuses to disclose. This transit exposure is not a distant geopolitical tail risk; it represents a primary vulnerability directly affecting Tengiz cash flow projections.
Deepwater and LNG: the ballast
The third upstream pillar is less volatile and demonstrably better executed. In the deepwater Gulf of Mexico, Chevron achieved first production at Anchor in 2024—the industry's first ultra-high-pressure development operating at up to 20,000 pounds per square inch at reservoir depths reaching 34,000 feet.24 The Ballymore development followed in 2025, optimized as a subsea tieback to the existing Blind Faith platform rather than requiring standalone host infrastructure.25 Together, these deepwater assets support Chevron's regional production target of 300,000 net barrels of oil equivalent per day.26
The commercial significance of 20,000-psi technology is substantial. High-pressure deepwater reservoirs trapped beneath thick salt layers historically exceeded the operational limits of subsea hardware, stranding significant reserves. Engineering blowout preventers, risers, and trees capable of withstanding 20,000 psi unlocked a major asset class—demonstrating technical capability that, while milestone-setting, remains replicable by deepwater peers.
In Asia-Pacific, the Gorgon and Wheatstone liquefied natural gas developments in Australia provide commercial stability, selling the majority of their output under long-term contracts to Asian utilities. Management confirmed on the second-quarter 2026 call that while Australian LNG is contracted into Asia, West African cargoes serve European spot markets, alongside roughly 4 million tonnes per annum of off-take capacity from North American LNG projects.17 LNG long-term contracts offer lower upside during price spikes but deliver reliable cash flow during market downturns, serving as effective corporate ballast.
That operational foundation sets the stage for the asset Chevron did not discover, did not construct, and spent sixteen months in arbitration to acquire.
V. The $53B Hess Acquisition & The Guyana Arbitration Showdown (2023–2025)
October 2023 marked the moment the U.S. oil sector signaled that the era of independent shale operators was coming to a close. On October 11, ExxonMobil announced its $59.5 billion acquisition of Pioneer Natural Resources, instantly positioning itself as the dominant player in the Permian Basin. Twelve days later, Chevron responded — but chose not to match Exxon's strategy directly. Instead, Chevron agreed to acquire Hess Corporation in an all-stock transaction valued at approximately $53 billion, offering 1.025 Chevron shares for each Hess share — representing an equity value of roughly $171 per share and an enterprise value of $60 billion including debt.2728
What stands out is what Chevron chose not to buy. Hess owned no Permian acreage whatsoever. Where Exxon doubled down on short-cycle U.S. shale, Chevron paid up for long-life offshore barrels in a South American nation that had barely registered on energy investors' radar a decade prior.
The prize. Hess held a 30% non-operated working interest in the Stabroek Block offshore Guyana — a 6.6-million-acre concession operated by ExxonMobil containing over 11 billion barrels of oil equivalent in discovered recoverable resources.28 The asset boasts some of the strongest economics in the non-OPEC world: thick, stacked, highly permeable reservoirs; daily production per well measured in tens of thousands of barrels; and development via floating production, storage, and offloading (FPSO) vessels — specialized ships that process subsea crude, store it, and offload directly to tankers.
The FPSO model carries structural advantages. Because processing facilities are built in shipyards rather than assembled offshore, Guyana developments offer far greater schedule predictability than traditional fixed platforms — a stark contrast to Chevron's multi-year delays in Kazakhstan. The Stabroek joint venture surpassed 900,000 barrels per day of gross production in November 2025 and reached a final investment decision on the $6.8 billion Hammerhead project, targeted for 2029 start-up with a capacity of roughly 150,000 barrels per day.2930
Chevron captures these barrels without operating the asset. That structure offers clear benefits — zero operating overhead, no schedule risk, and an operating partner with a proven record of delivering FPSOs ahead of schedule — alongside a clear constraint: Chevron cannot dictate the pace, costs, or capital calls for its primary growth engine. It remains a non-operating partner in an exceptionally high-margin field.
The deal also brought 465,000 net acres in the Bakken shale, delivering steady cash flow by extending Chevron's standard U.S. manufacturing playbook across another domestic basin.27
Sixteen months of trench warfare
In March 2024, ExxonMobil and CNOOC filed arbitration claims under the Stabroek joint operating agreement, contending that the change of control at Hess triggered their right of first refusal over the 30% stake — a claim that, if upheld, would have allowed them to purchase the Guyana interest directly at the deal-implied valuation.1
The conflict turned on a multi-billion-dollar legal distinction: whether selling the parent company holding an asset constitutes selling the asset itself. Chevron maintained that standard corporate mergers do not trigger asset-level pre-emption rights. Exxon argued that the economic substance of the transaction was a transfer of the underlying Guyana interest regardless of corporate structure.
Concurrently, regulatory hurdles emerged in Washington. The Federal Trade Commission cleared the merger in September 2024 subject to a condition barring John Hess from joining Chevron's board, citing concerns that his past interactions with OPEC officials could influence Chevron's commercial strategy.31 That order was finalized in January 2025. However, in July 2025, a reconstituted Commission reopened and vacated its own order, ruling that the original complaint failed to allege a violation of Section 7 of the Clayton Act, made no showing of anticompetitive harm, and identified no material increase in market concentration.32
This regulatory reversal warrants scrutiny. An antitrust restriction accepted by the company was set aside ten months later by the same agency on the grounds that it lacked statutory backing. Beyond the immediate legal outcome, it demonstrates how regulatory risk in the energy sector often hinges on administrative composition rather than static statutory standards.
The arbitration panel ruled decisively in Chevron's favor. Chevron closed the acquisition on July 18, 2025, issuing approximately 301 million shares as transaction consideration, and John Hess joined the board of directors.33 CEO Mike Wirth characterized the combination as uniting two leading energy producers while extending Chevron's growth profile well into the next decade.33
The integration, so far
Chevron initially pledged to achieve $1 billion in annual run-rate cost synergies within twelve months of closing. By the second quarter of 2025, management projected hitting that target six months ahead of schedule.34 By the second quarter of 2026, Chevron reported $1.5 billion in annual run-rate synergies — achieved within a year of close and 50% above its original target.617
Evaluating execution. Rapidly exceeding self-imposed synergy targets demonstrates integration efficiency on controllable corporate overhead. However, administrative cost reduction represents only the baseline test. The broader investment question — whether paying $53 billion in equity secured long-term value — will take years of commodity cycles to evaluate. Utilizing equity rather than cash shared downside commodity risk with Hess shareholders, while subsequent strength in Chevron's share price lowered the effective long-term cost of the issued stock.
The key operational test lies in capital allocation across Chevron's unified U.S. onshore platform. Managing the Permian, DJ, and Bakken as a single organization producing roughly 1.7 million barrels of oil equivalent per day, Chevron reported operational gains, including Bakken wells drilled with 28% longer laterals that delivered equivalent production with one fewer rig.17 Whether the Bakken successfully competes for capital against Permian opportunities will determine whether the asset expands returns or merely absorbs reinvestment.
This brings the analysis to its central strategic question: does Chevron's performance reflect genuine capital allocation discipline, or has it primarily benefited from favorable oil price cycles?
VI. Capital Allocation, M&A Benchmarking & Management Credibility
In April 2019, Chevron had a signed agreement to acquire Anadarko Petroleum. When Occidental Petroleum submitted a higher bid backed by Warren Buffett's preferred equity, conventional corporate strategy called for raising the offer. Chevron declined. It terminated the agreement, collected a $1 billion breakup fee, and Chairman and CEO Mike Wirth issued a statement noting that winning in any environment does not mean winning at any cost — a principle cited frequently by energy investors since.[^7]
That single decision established the reputation for capital discipline that this analysis tests.
The leadership profile. Mike Wirth's background is unusual for a supermajor chief executive: he is a chemical engineer who spent most of his career in refining, marketing, and supply — downstream operations where margins are thin, products are commodities, and the main advantage comes from low operating costs and disciplined working capital. Since taking over as chairman and CEO in 2018, his approach has treated cost reduction as a continuous priority, capital as a scarce resource, and production volume as an outcome rather than a primary goal.
The upstream M&A record. Chevron acquired Noble Energy in October 2020 during a deep slump in energy demand, completing an all-stock transaction valued at approximately $13 billion in enterprise value that added Eastern Mediterranean natural gas assets — including the Leviathan and Tamar fields offshore Israel — alongside Permian and DJ Basin acreage.[^37] PDC Energy followed in August 2023 for $7.6 billion in enterprise value.[^18] The Hess acquisition completed the sequence. By paying for three of the four major acquisitions with equity, Chevron demonstrated a consistent approach, refusing to take on heavy debt to acquire reserves.
Where the discipline thesis breaks. The claim that Chevron's acquisition record is uniformly disciplined is contradicted by its downstream expansion into renewable fuels. In June 2022, near the peak of industry enthusiasm for alternative fuels, Chevron bought Renewable Energy Group for $3.15 billion in cash, aiming to reach 100,000 barrels per day of renewable fuels capacity by 2030.[^38] Less than two years later, in March 2024, the company indefinitely idled biodiesel facilities in Ralston, Iowa, and DeForest, Wisconsin — both of which had been offline since December 2023 — citing weak demand under federal Renewable Fuel Standard mandates and expanding renewable diesel capacity.35
Evaluating the capital impact. While Renewable Energy Group represented only about 6% of the Hess transaction value, the deal highlights a structural vulnerability. Chevron purchased the business near a market peak in a sector dependent on annual regulatory mandates, and the investment thesis faltered within twenty-four months when policy volumes fell short of industry expectations. The same management team that walked away from Anadarko over acquisition price paid a top-of-cycle valuation for a policy-dependent asset.
A narrowed assessment. Chevron's capital discipline is genuine and demonstrated where it buys oil and gas reserves — a core asset class management has evaluated for a century and where its willingness to walk away is documented. That discipline has not reliably extended to adjacent businesses whose economics rest on government subsidies. This distinction provides the framework for assessing the company's emerging power and low-carbon initiatives.
Long-term legacy risks. Furthermore, historical transactions demonstrate that the full cost of an acquisition includes long-dated legal and environmental liabilities that surface decades later on timelines outside management's control.
The activist's file
A skeptical investor evaluating Chevron's management record would highlight four key areas of scrutiny.
Governance and board structure. Wirth holds both the chairman and CEO roles. At the 2026 annual meeting, a shareholder proposal to mandate an independent board chair received 14.5% support, reflecting the modest traction typical for governance votes at major U.S. corporations. Shareholders approved executive compensation with 97% support, ratified PricewaterhouseCoopers as auditor with 96%, elected director John Hess with 99.3% of votes cast, and defeated proposals seeking reports on Indigenous rights and human rights processes, which drew 9.0% and 8.9% respectively.36 While showing strong institutional support, the voting results indicate limited independent shareholder pushback on corporate governance.
Returns relative to targets. Chevron targets a return on capital employed (ROCE) in the low-to-mid teens across commodity cycles. For full-year 2025, the company reported an ROCE of 6.6%, or 10.5% on an adjusted basis.37 This gap stems partly from timing: $53 billion of Hess capital landed on the balance sheet in July 2025 while contributing only partial-year earnings during a period of moderate oil prices. However, a single-digit reported return on capital during a stable price environment presents a legitimate line of attack, illustrating that strong cash flow does not guarantee high returns on invested capital.
Capital return pacing. Chevron repurchased $12.1 billion of its stock in 2025 and distributed $12.8 billion in dividends.37 In the first half of 2026, buybacks slowed to $2.5 billion in the first quarter and $3.1 billion in the second quarter, while Chevron directed $8.4 billion toward debt reduction in the second quarter alone, reducing its net debt ratio to 13.1%.56 Management's long-term framework calls for $10 billion to $20 billion in annual share repurchases at Brent crude prices between $60 and $80 through 2030.38 Reducing share buybacks during periods of record commodity prices highlights a tension between maintaining fixed repurchase targets and prioritizing balance sheet deleveraging after major acquisitions.
Cost reduction execution. In February 2025, Chevron announced plans to reduce its global workforce by 15% to 20% — approximately 9,000 positions — targeting $2 billion to $3 billion in structural cost reductions by year-end 2026.39 By the second quarter of 2026, management reported reaching $3 billion in annual run-rate structural savings six months ahead of schedule, attributing the progress to efficiency gains and organizational restructuring, while raising its investor-day savings target to $3 billion to $4 billion.61738 Asked whether the savings were durable, Chief Financial Officer Eimear Bonner cited centralized engineering, predictive maintenance in shale operations, and turnaround optimization, adding: "costs always matter, never satisfied, never done."17
Evaluating management execution. Chevron's operational performance presents a legible track record: management establishes explicit targets and reports progress publicly. While project overruns such as Tengiz were disclosed incrementally over time, the company's refusal to expand capital budgets during commodity price spikes serves as a meaningful test of capital discipline, provided that restraint persists through extended windfalls.
This brings the analysis to portfolio areas where discipline is hardest to verify, as initial investments have not yet produced material earnings.
VII. The Energy Transition Paradox & Chevron New Energies
In West Texas, on land Chevron already owns near natural gas it already produces, a subsidiary called Energy Forge One is preparing to build a power plant that will sell no electricity to the public grid. Every megawatt is contracted to a single customer under a twenty-year agreement: Microsoft, for a data center dedicated to artificial intelligence workloads. Sized at roughly 2.67 gigawatts — enough electricity to power approximately two million homes — the Kilby project will be constructed in phases using heavy-duty gas turbines from GE Vernova alongside additional capacity from Caterpillar's Solar Turbines unit.4041
This arrangement reflects what Chevron's energy transition strategy looks like in 2026, marking a distinct evolution from its initial framework five years earlier.
The original construction. Chevron New Energies was established in 2021 under Vice President Jeff Gustavson to commercialize hydrogen, carbon capture and storage, renewable fuels, and emerging technologies such as geothermal energy and carbon offsets. Management framed the unit defensively rather than transformationally: as a modest hedge on a lower-carbon future, structured so it would not dilute the returns of the core hydrocarbon business. In the 2026 capital budget, roughly $1 billion of an $18 billion to $19 billion capital allocation — under 6% — was dedicated to lowering operational carbon intensity and expanding new energies.42 Today, the segment generates a negligible share of corporate earnings.
Sizing it honestly is the whole point. Assessing the division accurately requires framing its economic weight correctly. Chevron New Energies is neither a central growth driver nor a major contributor to operating income; it represents a minor capital line item. An objective analysis requires evaluating whether these outlays generate returns above the company's cost of capital or serve primarily narrative purposes.
Evaluating Chevron's climate disclosures requires distinguishing between operational intensity and total emissions. The company's targets focus on carbon intensity — measuring emissions per unit of energy produced — rather than absolute volume reductions, and cover operational emissions from production rather than scope 3 emissions from end-user fuel combustion. These metrics reflect engineering goals for field operations rather than a reduction in total carbon released by the company's refined products. Conflating operational intensity with absolute emissions misrepresents actual performance, leading supporters to overstate progress and critics to dismiss meaningful operational efficiency work.
The European contrast — and what it actually proves. European supermajors such as BP and Shell spent the late 2010s and early 2020s committing substantial capital to utility-scale renewable power and setting production decline targets, only to dial back those commitments as returns lagged and investors objected. Chevron avoided that approach, maintaining that oil and gas demand would remain robust for decades and that cash returns to shareholders surpassed unsubsidized renewable projects. Over the past five years, that strategy delivered superior financial returns relative to European peers.
However, claims of avoiding competitor missteps are weaker than they appear. While Chevron avoided utility-scale renewable power projects, its acquisition of Renewable Energy Group demonstrated that smaller investments in policy-dependent fuels carry similar risks. The primary distinction was position size — a form of capital restraint, but not proof of superior strategic insight.
The policy dependency has not gone away. Renewable diesel economics turn heavily on California Low Carbon Fuel Standard credits and federal blending mandates. Carbon capture relies on federal 45Q tax credits, while hydrogen projects depend on 45V incentives. Because each mechanism remains subject to legislative and regulatory revision, the key test for long-term viability is unsubsidized project-level profitability — metrics Chevron has not publicly disclosed.
Carbon capture technology warrants precise definition. In industrial applications, the process involves separating carbon dioxide from gas streams at power plants, processing facilities, or refineries, compressing the gas, and injecting it into underground geological formations. Chevron possesses operational experience with the technology, including at its Gorgon LNG facility in Australia, where carbon injection has operated below original design capacity. While the underlying engineering is established, project economics generally rely on tax credits or government subsidies rather than market-driven demand.
Hydrogen presents a similar dynamic. Chevron currently produces and consumes hydrogen within its refining network. The new energies strategy seeks to manufacture low-emissions hydrogen for transportation and industrial markets that remain undeveloped at commercial scale. While this offers optionality on future demand, asset values tied to congressional tax credits differ fundamentally from low-cost crude reserves.
Which makes Kilby the interesting case. The power initiative represents the first new-energies-adjacent venture with a direct line to commercial returns, leveraging three existing corporate assets — natural gas supply, land ownership, and heavy industrial project management — for a customer seeking firm power generation. Gustavson told analysts that the model is repeatable, confirming discussions for additional projects with existing and new counterparties, describing it as the company's largest opportunity set in years while maintaining a focus on return thresholds. Management has projected mid-teens expected returns for the venture.17
The underlying commercial logic differs from traditional environmental initiatives. Artificial intelligence data centers require reliable, dispatchable power on timelines that public utility grids cannot accommodate, where regional transmission queues often span several years. By generating power behind the meter on owned land adjacent to gas production, Chevron can bypass grid interconnection delays. This structure functions as an integrated natural gas monetization project supported by a creditworthy off-taker rather than a renewable energy venture.
Now apply the record. A signed twenty-year power purchase agreement represents a commercial contract rather than an operating, cash-generating facility. Final investment decision on Kilby is expected by the end of 2026, with first power targeted for 2028.40 Chevron has previously announced ambitious targets in adjacent sectors — such as its goal of 100,000 barrels per day of renewable fuel production — before idling assets as policy conditions shifted. The key distinction at Kilby lies in contracted corporate revenue rather than government subsidy schedules. However, the project requires managing a commercial structure with distinct capital costs, customer profiles, and competitive dynamics compared to core exploration and production.
The calibrated conclusion: treat Chevron New Energies as an unproven corporate option backed by limited capital risk rather than an established growth engine. Transforming that status requires Kilby reaching final investment decision on schedule, delivering projected returns, and securing secondary contracts on comparable commercial terms to demonstrate a repeatable business model.
That distinction — between a capability that compounds and a one-time transaction — represents the critical benchmark for evaluating operational execution across the broader corporation.
VIII. Structural Analysis: Porter's 5 Forces & Hamilton Helmer's 7 Powers
Consider a war-game scenario: place five industry analysts in a room, assign each a primary competitor—ExxonMobil, Shell, TotalEnergies, Saudi Aramco, and a well-capitalized private operator—and ask how they would extract value from Chevron over the coming decade. The exercise is clarifying because it illustrates how few of Chevron's advantages are structural company-wide capabilities, and how many simply derive from owning premier geological assets.
What Chevron actually has, in Helmer's terms
Cornered resource—the strongest claim, and it is asset-specific rather than company-wide. Hamilton Helmer's framework defines a cornered resource as preferential access to a valuable asset on terms rivals cannot replicate. Chevron holds three genuine examples. Its railroad-derived Permian Basin mineral position cannot be duplicated at any price, stemming from a single 19th-century land grant. Its 50% stake in Tengiz sits atop a massive Kazakh reservoir with no equivalent in Western portfolios. Finally, its 30% interest in the Stabroek Block provides access to premier non-OPEC deepwater economics discovered this century—though Chevron acquired that position by writing a major equity check rather than securing early preferential terms, and ExxonMobil operates the field.
Scale economies—real, but bounded and shared. Spreading seismic processing, global procurement, deepwater rig contracting, and trading infrastructure over more than four million barrels per day of production genuinely lowers unit operating costs. However, for the investment case, scale provides bounded advantages: ExxonMobil enjoys the same benefits at a larger volume, state-owned oil companies operate with a lower cost of capital, and U.S. shale marginal cost curves flatten rapidly—a producer outputting 300,000 barrels per day faces little structural cost disadvantage per well compared to a one-million-barrel operator. In this industry, scale buys corporate resilience rather than pricing power.
The peer comparison sharpens this limitation. ExxonMobil produces more crude, refines more products, and holds the deepest concentrated U.S. shale inventory following its Pioneer acquisition. Shell dominates global liquefied natural gas trading. TotalEnergies maintains the broadest low-carbon energy platform among the majors. Saudi Aramco operates at an ultra-low cost per barrel that no Western peer can approach while answering to a sovereign owner rather than public markets. Chevron does not lead any of those operational categories outright. Instead, it maintains a selective portfolio with fewer underperforming legacy assets—a defensible strategy built on portfolio curation rather than a structural moat competitors are barred from copying.
Process power—moderate, and partially observable. Chevron's 20,000-psi deepwater capabilities, its standardized shale development framework deployed across three domestic basins, and the predictive maintenance and turnaround optimization supporting its structural cost program represent real operational strengths built over years. However, Helmer's test for process power requires that competitors cannot replicate an operating capability even when observing it directly. Deepwater pressure technology diffuses across shared oilfield service providers, while shale efficiency techniques spread through engineer mobility. Chevron's advantage here represents an operational lead time rather than an unassailable barrier.
Counter-positioning—a generous analytical rating that fails to hold up. The argument for counter-positioning holds that Chevron's refusal to adopt aggressive production decline targets while European peers pivoted away from fossil fuels created a structural advantage. It does not qualify, because true counter-positioning requires that incumbent rivals cannot match a strategy without damaging their legacy businesses. BP and Shell demonstrated they could pivot back to oil and gas simply by shifting strategic priorities when low-carbon returns lagged. A strategy rivals can replicate at will by altering capital allocation represents a well-timed management decision rather than structural power.
And the powers Chevron lacks entirely. Chevron possesses no network economies and no customer switching costs; a refiner purchasing crude evaluates assay specifications and spot prices rather than vendor loyalty. Nor does it hold meaningful branding power in Helmer's economic sense: while the Chevron logo supports retail marketing margins at the pump, wholesale buyers pay no premium for a Chevron-produced crude barrel. Recognizing these structural limits explains why the company's financial returns remain closely tied to global oil price cycles regardless of operational discipline.
Porter, applied where it bites
Buyers: weak individually, but politically influential in sovereign markets. Crude oil and liquefied natural gas trade against transparent global pricing benchmarks, preventing individual buyers from dictating commercial terms. The notable exception involves Chevron's exposure to counterparties that operate simultaneously as commercial partners, customers, and sovereign authorities—such as PDVSA in Venezuela or the Iraqi state in the West Qurna 2 and Nasiriyah discussions noted by management on the second-quarter 2026 call.17 In those jurisdictions, contract terms are negotiated and revised through political processes rather than pure market dynamics.
Suppliers: moderate leverage, rising sharply during commodity upcycles. Oilfield service providers and offshore drilling rig operators regain pricing power when sector activity accelerates, coinciding with the periods when producers seek to expand capital programs. While Chevron's multi-basin procurement scale mitigates these cost pressures, a distinct supply constraint emerged in 2026 around heavy gas turbines. The company's data center power initiative relies on power generation hardware from a supply chain constrained by hyper-scaler demand, making equipment delivery schedules a key bottleneck for expanding behind-the-meter power generation.
Substitutes: low in the near term, high and unquantifiable over the long term. Electric vehicle adoption is reducing gasoline demand growth at the margin in developed economies, but aviation, maritime shipping, heavy freight, and petrochemical manufacturing lack economic alternatives to liquid hydrocarbons at commercial scale today. The strategic reality is that the timing of global peak oil demand remains uncertain, and Chevron's explicit corporate planning framework extends through 2030. Beyond that horizon, the investment case relies on the premise that low production breakevens and high asset quality will keep its barrels profitable as global demand plateaus.
Rivalry: intense, shifting from field acreage to corporate consolidation. Recent industry competition has centered on corporate M&A rather than exploratory acreage auctions. ExxonMobil and Chevron each committed between $55 billion and $60 billion in equity within a twelve-day span in October 2023 to execute contrasting strategic acquisitions. Simultaneously, state-owned oil companies compete for international concessions with lower cost-of-capital requirements and diplomatic support that investor-owned supermajors cannot match.
The core investment synthesis: Chevron's durable competitive advantages are embedded in specific, high-quality assets—a royalty-advantaged Permian land grant, a giant Kazakh reservoir, and a top-tier Guyanese offshore block—rather than in a compounding, company-wide structural capability. That distinction is fundamental to evaluating an international oil company. It indicates that long-term investment performance depends on sustaining capital discipline and field execution across a curated asset base rather than relying on a widening corporate moat.
IX. Investment Thesis: The Bull vs. Bear Stress Test
Two investors look at the same second-quarter 2026 results. One sees a company that generated $22.6 billion of operating cash flow in ninety days, cut net debt by $8.4 billion, returned $6.6 billion to shareholders, and reached two publicly stated targets ahead of schedule.6 The other sees a company that earned $2.2 billion just one quarter earlier with identical assets, concluding that those financial results primarily reflect oil price swings rather than operational changes. Both perspectives draw from the exact same financial reporting.
The bull case, stated at its strongest
A portfolio of low-breakeven barrels arriving simultaneously. The company's three primary growth engines reached operational inflections within an eighteen-month window: Tengiz reached and then exceeded nameplate capacity, Guyana continued adding production vessels, and deepwater projects in the Gulf of Mexico came online. Chevron management informed investors that it expects to maintain a capital-expenditure-plus-dividend breakeven below $50 Brent through 2030, alongside annual production growth of 2% to 3%, average adjusted free cash flow growth above 10% per year, and more than three percentage points of return on capital employed improvement — all assuming a flat crude price of $70 Brent, well below 2026 market levels.3817 While these targets represent management projections rather than historical results, they establish specific, measurable benchmarks.
A dividend record that is genuinely rare. In January 2026, Chevron raised its quarterly dividend by 4% to $1.78 per share, extending its record of annual payout increases to 39 consecutive years.4337 That streak survived the 1998 oil price collapse, the 2008 financial crisis, the 2014–2016 market downturn, and the 2020 pandemic demand shock — periods when the company relied on debt rather than reducing shareholder distributions. For income-focused investors, this historical performance across four full commodity cycles offers a concrete track record of capital priority.
Cost delivery that has been checked. Management met two self-imposed commitments — Hess acquisition cost synergies and structural operating cost reductions — ahead of schedule and above initial guidance. Because corporate overhead reductions and synergy targets represent measurable internal milestones, early completion provides empirical support for management's operational execution.
Capital restraint under maximum temptation. The single most persuasive item supporting the capital discipline thesis remains behavioral. With Brent crude spiking to $118 per barrel and chief executive Mike Wirth describing the situation as "clearly a very significant disruption to the global energy system," Chevron kept its capital expenditure range unchanged and declined to accelerate activity. Wirth told analysts that the company would not "make rash or immediate changes to a system that is running at a high degree of capital and operating efficiency."7 Historically, industry upcycles have often ended when producers expanded capital budgets during peak commodity prices.
The bear case, stated at its strongest
The cash flow has a geography problem, and it is getting worse rather than better. Kazakh barrels exit through a Russian Black Sea terminal exposed to repeated military strikes. In Venezuela, operating conditions depend on a U.S. licensing regime that was tightened in 2025 — cutting exports by half — before being loosened following the removal of Nicolás Maduro in January 2026. In September 2026, Chevron announced it had been assigned additional Orinoco Belt acreage and planned to invest over $7 billion through its joint ventures to nearly double production to roughly 600,000 barrels per day within five years, in a signing ceremony attended by the U.S. Energy Secretary in Caracas.44 Chevron has also signed preliminary agreements for field development in Iraq and reported a discovery offshore Angola in August 2026 with over 600 meters of hydrocarbon column in Block 0.1745
Read that portfolio as a skeptic would. Each of those positions represents high-quality geology located in jurisdictions where operating rights remain politically sensitive. Rather than diversifying away from geopolitical exposure, Chevron is concentrating production in high-risk regions at a time when U.S. energy policy functions as an explicit instrument of foreign relations. Venezuela currently accounts for approximately 1% to 2% of operating cash flow while Chevron recovers roughly $1.5 billion in outstanding receivables — an immaterial share of current earnings, but an exposure that will grow under a $7 billion capital program and remain vulnerable to policy shifts in Washington.717
The Permian is at plateau by the company's own plan, and the post-2030 story is unspecified. With Permian Basin production capped under company plans, maintaining growth beyond 2030 depends either on unproven enhanced recovery technologies or on additional corporate acquisitions. Because three of Chevron's four largest recent capital deployments involved corporate acquisitions to replace reserves, sustaining long-term output relies heavily on periodic M&A.
Returns on capital have not yet justified the capital. A reported single-digit return on capital employed of 6.6% in 2025, compared with management's low-to-mid-teens target, provides key evidence for the bear case. While management attributes lower returns to the mid-year timing of the Hess acquisition before full asset integration, that explanation remains subject to verification in full-year 2026 and 2027 financial reporting.
Litigation and regulation are live, not historical. Legal liabilities remain active across multiple venues. A $740 million verdict regarding Louisiana coastal wetland damage is under appeal while the U.S. Supreme Court reviews underlying jurisdictional questions, and dozens of parish lawsuits remain pending. Concurrently, municipal and state climate litigation continues across several jurisdictions. While individual cases do not threaten solvency, they collectively represent unquantified claims against future cash flows.
And the largest bear point is the one no company can answer. Chevron's five-year financial plan relies on an assumed oil price of $70 per barrel Brent. In early 2026, market forecasts anticipated an oversupply before geopolitical events drove crude to $118 per barrel; prices could shift downward if transit routes stabilize and spare capacity returns to market. A lower-cost asset base positions Chevron to remain profitable at $50 Brent, but equity valuations reaching record highs on peak commodity earnings may leave little margin for price drops.
Where this leaves the thesis. The evidence supports a narrowed version of the bull case: Chevron holds a high-quality asset base, has demonstrated cost discipline and capital restraint during commodity price spikes, and maintains a dividend record tested across multiple downturns. The evidence does not support the broader assertion that Chevron possesses an expanding structural moat, superior mega-project execution capabilities, or immunity from geopolitical risk. Instead, the company has managed operational risks by reallocating exposure into politically sensitive jurisdictions, leaving investors reliant on current cash returns.
X. Earnings Call & Transcript Playbook for Analysts
The most useful hour an investor can spend evaluating Chevron is not reading a broker note, but studying an earnings transcript — specifically the Q&A session rather than the prepared remarks. Prepared remarks outline how management prefers to be measured, whereas the Q&A reveals where analysts attempt to hold the company accountable.
The documents that matter most. For the transaction itself, the fourth-quarter 2023 and first-quarter 2024 calls provide the primary record of how management framed the Hess acquisition rationale before arbitration risk was resolved, serving as the benchmark to evaluate whether current justifications match initial claims. For the forward operational plan, the November 12, 2025 investor day remains the foundational document for 2030 targets, capital expenditure ranges, breakeven commitments, and the share repurchase framework.38 For integration progress, the second-quarter 2025 call — held two weeks after closing — marks the point where management accelerated the original synergy timeline.34 Finally, the two 2026 earnings calls provide a live test of whether capital discipline holds during a commodity price shock.
What analysts actually push on, based on the 2026 calls. Four recurring themes emerge, mapping directly onto the central analytical tests of this report.
Kazakh cash conversion and the pipeline. Morgan Stanley's Devin McDermott opened the second-quarter 2026 call by questioning Tengiz operational performance and Caspian Pipeline disruptions. CEO Mike Wirth affirmed approximately $3 billion in quarterly affiliate distributions alongside full-year guidance, but described mooring status and alternative routing options without quantifying backup evacuation capacity.17 The pattern across both 2026 calls remains consistent: management provides precise figures on cash received, but remains qualitative on export route resilience.
Shale inventory depth. Neil Mehta of Goldman Sachs and Doug Leggate of Wolfe Research pressed from complementary angles — Mehta on how the unified 1.7-million-barrel shale organization transfers operational learnings, and Leggate directly on Permian Basin inventory longevity after 2030. Management offered a candid assessment regarding the production plateau, but remained speculative on technologies required to reverse it.17
The durability of cost savings. Evercore's Steve Richardson questioned whether structural cost reductions were permanent or cyclical — a critical distinction, given that headcount reductions temporarily lower expenses until operational activity resumes.
New businesses and new jurisdictions. Piper Sandler's John Royall inquired about the long-term potential of the behind-the-meter power business; JPMorgan's Arun Jayaram focused on expansion opportunities in Iraq; TD Cowen's Jason Gabelman asked about operating parameters in Venezuela; and BMO's Phillip Jungwirth examined Argentina's Vaca Muerta, where CFO Eimear Bonner outlined a fiscal framework offering 30-year stability and an ambition to triple production by 2035.17
What analysts omit from their questioning is equally revealing. In neither 2026 call did the Q&A focus on the CPChem joint venture, retail marketing, or long-term domestic refined product demand — areas where structural demand shifts would manifest earliest. Wall Street coverage concentrates where near-term earnings variance is highest, leaving slow-moving operational risks unexamined until they materialize.
On management's tone, and what to listen for. Wirth and Bonner consistently frame responses around cash flow and capital efficiency rather than raw production volumes, declining to offer volume targets detached from capital returns. While this reflects a disciplined communications strategy, investors must distinguish between quantitative disclosures and narrative framing. Across both 2026 calls, questions on controllable variables — such as cost synergies, unit capital metrics, and affiliate cash distributions — yielded specific data. Conversely, questions regarding uncontrollable risks — such as pipeline contingency capacity, Permian inventory beyond 2030, and unsubsidized new-energy returns — produced qualitative frameworks. This asymmetry in detail serves as a disclosure in its own right.
A valuable longitudinal exercise is tracking management's framing of the Hess acquisition across three distinct phases: the initial announcement when arbitration was unresolved; the deal close after securing legal victory; and the 2026 earnings calls with assets fully in operation. If the primary justification migrates — shifting from deepwater resource quality to corporate cost synergies, or from Guyana growth to Bakken cash flows — that narrative shift signals which component of the original transaction thesis is actually driving performance.
Two financial disclosures warrant careful inspection. The quarterly results exhibit filed with each Form 8-K details segment performance and price realization tables, clarifying whether earnings movements reflect commodity price fluctuations or underlying operational changes — allowing this analysis to isolate the driver of 2026 quarterly results.65 Additionally, the annual results release discloses the reserve replacement ratio, which reached 158% in 2025.37 This metric provides information absent from quarterly calls: whether the company is acquiring and discovering resources faster than it depletes them.
However, reserve replacement metrics require contextual interpretation. A ratio above 100% can result from organic exploration, corporate acquisitions, or upward revisions of existing reserves driven by higher oil prices. In a year marked by a $53 billion acquisition and rising crude prices, an elevated replacement ratio confirms resource addition via M&A and accounting adjustments rather than superior exploration efficiency.
One consistency check worth running each quarter. Compare current call commentary on capital allocation against the January 2026 dividend release, the December 2025 capital budget, and the investor-day framework.4238 If capital spending ranges begin shifting upward during an extended price boom, Chevron's central behavioral claim of strict capital discipline will have quietly changed.
XI. Epilogue: Key Investor KPIs & The Supermajor Endgame
There is a narrative that ends with Chevron as the victor: the company that refused to overpay, refused to chase volume, refused to apologize for producing hydrocarbons, and was rewarded when global markets re-emphasized commodity supply. There is another narrative in which a company whose quarterly profits swung by a factor of five within ninety days remains a leveraged claim on an unforecastable oil price, wrapped in the rhetoric of discipline.
The way to tell which story is unfolding is to track three key metrics while discarding most of the remaining noise.
Free cash flow per share. Not just aggregate free cash flow, but free cash flow per share. This metric isolates whether the growth engines are converting capital into cash, whether share buybacks are shrinking the share count after issuing roughly 301 million shares for Hess, and whether dividends are being funded from operational cash flow rather than balance sheet leverage. Within this figure, affiliate cash distributions represent the single most informative line item, as they determine whether the Kazakh mega-project generates acceptable returns on more than $48 billion in gross investment.
Cash breakeven, in dollars of Brent. Management committed to covering capital expenditures and the dividend at crude prices below $50 per barrel Brent through 2030. That threshold determines whether Chevron's 39-year streak of dividend increases can survive the next downturn without taking on debt, making it the primary financial boundary to monitor.
Return on capital employed, measured across the cycle rather than in a windfall year. This metric provides the ultimate test of the Hess acquisition. While free cash flow demonstrates whether assets are producing cash, return on capital employed reveals whether they were worth the acquisition price. A company generating single-digit reported returns in a baseline market while targeting low-to-mid-teens performance has yet to prove that its capital outlays cleared their return hurdles.
There is good reason to focus strictly on these three figures. Chevron discloses dozens of operational metrics, but most fluctuate directly with commodity prices, adding noise rather than analytical clarity. These three metrics isolate variables within management's direct control: the conversion of capital into cash, the structural cost floor, and the discipline of past capital allocation. If all three improve during a period of declining crude prices, the capital discipline thesis is confirmed by empirical evidence. If free cash flow per share holds up solely due to high oil prices, no strategic progress has been demonstrated.
The endgame. The consolidation wave of recent years has reshaped the industry structure. Independent operators that previously drove U.S. shale growth have largely been acquired. European supermajors have scaled back aggressive renewable targets to focus on core operations. National oil companies are expanding into refining and petrochemicals rather than competing for Western equity assets. What remains in the investable Western universe increasingly resembles a duopoly: one competitor holding the deepest Permian inventory, and Chevron holding premier deepwater acreage alongside the sector's most contested arbitration victory.
A duopoly does not guarantee attractive returns for equity holders. In an industry where global prices are dictated by cartel decisions, low-cost state producers, and geopolitical shocks, being one of two surviving Western supermajors provides operational scale and capital access, but no pricing power. The central competitive test is not whether Chevron outperforms ExxonMobil, but whether either company can generate returns above its cost of capital across a full commodity cycle as national oil companies expand low-cost supply and long-term demand growth moderates.
A structural downturn could also re-rate Chevron's valuation without operational missteps by management. If the Strait of Hormuz reopens, if OPEC+ reinstates spare capacity into a market previously facing oversupply forecasts, and if physical supply balances normalize, a valuation built on record cash generation would adjust to lower baseline earnings — with the same asset base, execution, and strategy. No management framework protects a commodity producer from underlying market cycles.
Whether this market position proves rewarding depends on a variable beyond any supermajor's control: global hydrocarbon demand duration and pricing. Chevron's response is to maintain profitability at $50 Brent, return excess cash to shareholders during upcycles, and preserve targeted optionality in emerging power opportunities. That framework represents a coherent operational strategy rather than an unassailable economic moat — and the company's explicit planning horizon of 2030 underscores the inherent limits of long-term forecasting in the sector.
The summary of Chevron in September 2026 is that of a disciplined operator in an industry where operational execution dictates only a portion of financial outcomes. Corporate history contains repeated examples of this dynamic: a Saudi concession secured for gold that built the enterprise, a nationalization that removed a third of its reserve base, an M&A wave that restructured its footprint, and an arbitration decision that secured its Guyanese assets. At each inflection, the decisive catalyst originated outside corporate headquarters. Management's primary control lies in ensuring the balance sheet remains solvent, the dividend remains funded, and capital remains available when the next market inflection occurs — and on that specific standard, the empirical record stands.
References
-
Chevron completes Hess acquisition after defeating Exxon in dispute over Guyana oil assets — CNBC, 2025-07-18 ↩↩
-
Crude oil and petroleum product prices increased sharply in the first quarter of 2026 — U.S. Energy Information Administration, 2026 ↩
-
Oil prices today: Uncertainty over U.S.-Iran Strait of Hormuz deal — CNBC, 2026-08-10 ↩
-
Chevron Reports First Quarter 2026 Results (Form 8-K, Exhibit 99.1) — Chevron Corporation / SEC EDGAR, 2026-05-01 ↩↩↩↩
-
Chevron Reports Second Quarter 2026 Results (Form 8-K, Exhibit 99.1) — Chevron Corporation / SEC EDGAR, 2026-07-31 ↩↩↩↩↩↩↩↩
-
Chevron (CVX) Q1 2026 Earnings Call Transcript — The Motley Fool, 2026-05-01 ↩↩↩↩↩
-
Benchmarks: September 23, 1933: The U.S. oil industry arrives in Saudi Arabia — EARTH Magazine ↩
-
International Tribunal Rules for Chevron in Ecuador Case — Chevron Corporation ↩
-
Louisiana jury rules Chevron must pay $740 million for coastal damages — Louisiana Illuminator, 2025-04-04 ↩
-
Supreme Court's Plaquemines Parish Case Deserves More Attention — Harvard Journal of Law & Public Policy ↩
-
Chevron Corporation Form 8-K, Exhibit 99.1 (Unocal acquisition completion) — SEC EDGAR, 2005 ↩
-
Built on legacy, driven by discipline: Chevron's Permian advantage explained — Chevron Corporation, 2025 ↩
-
Chevron (CVX) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-08-03 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Tengizchevroil Joint Venture Official Portal — Tengizchevroil ↩
-
Chevron hikes Tengiz project cost to $45.2 billion — Oil & Gas Journal ↩
-
Chevron's Huge Kazakh Oil Project to Cost $48.5 Billion — Bloomberg, 2024-03-14 ↩
-
Chevron achieves first oil at Future Growth Project in Kazakhstan — Chevron Corporation, 2025-01 ↩
-
Four drone strikes in four days hit tankers carrying Kazakhstan's oil — Euronews, 2026-07-21 ↩
-
Caspian Pipeline Consortium Halts Loadings on Drone Strike — Bloomberg, 2026-07-19 ↩
-
Chevron starts production at Anchor with industry-first deepwater technology — Chevron Corporation, 2024 ↩
-
Chevron starts oil production from Ballymore project in Gulf of America — Chevron Corporation, 2025 ↩
-
Chevron Announces Agreement to Acquire Hess — Chevron Corporation, 2023-10-23 ↩↩
-
Chevron will acquire Hess for $53 billion in new oil megadeal days after Exxon announces buy of shale giant Pioneer — Fortune, 2023-10-23 ↩↩
-
Daily oil production hits 900,000 barrels in Guyana's Stabroek block — ExxonMobil Guyana, 2025-11-12 ↩
-
ExxonMobil Reaches FID on $6.8 Billion Hammerhead Field Offshore Guyana — Journal of Petroleum Technology (SPE) ↩
-
FTC Order Bans Hess CEO from Chevron Board in Chevron-Hess Deal — Federal Trade Commission, 2024-09-30 ↩
-
FTC Reopens and Sets Aside Chevron-Hess Final Order — Federal Trade Commission, 2025-07 ↩
-
Chevron Completes Acquisition of Hess Corporation — Chevron Corporation, 2025-07-18 ↩↩
-
Chevron to shutter two US biodiesel plants — Oil & Gas Journal, 2024-03 ↩
-
Chevron Corporation Form 8-K, Item 5.07 — 2026 Annual Meeting voting results — SEC EDGAR, 2026-05-29 ↩
-
Chevron Reports Fourth Quarter 2025 Results (Form 8-K, Exhibit 99.1) — Chevron Corporation / SEC EDGAR, 2026-01-30 ↩↩↩↩
-
Chevron Outlines Plan for Sustained Cash Flow Growth at Investor Day — BOE Report, 2025-11-12 ↩↩↩↩↩
-
Chevron will slash up to 20% of its workforce as part of cost-cutting plan — CNBC, 2025-02-12 ↩
-
Chevron Signs 20-Year Power Agreement with Microsoft for West Texas Data Center — Chevron Corporation, 2026-06 ↩↩
-
Chevron to fuel massive Microsoft data center in Texas using natural gas — CNBC, 2026-06-22 ↩
-
Chevron Announces 2026 Capex Budget of $18 to $19 Billion — Chevron Corporation, 2025-12-03 ↩↩
-
Chevron boosts dividend 4% as 147-year oil streak continues — TheStreet, 2026 ↩
-
US oil giant Chevron to expand Venezuela operations — Al Jazeera, 2026-09-02 ↩
-
Chevron advances its strategic exploration program with discovery in Angola's Block 0 — Chevron Corporation, 2026-08-17 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube