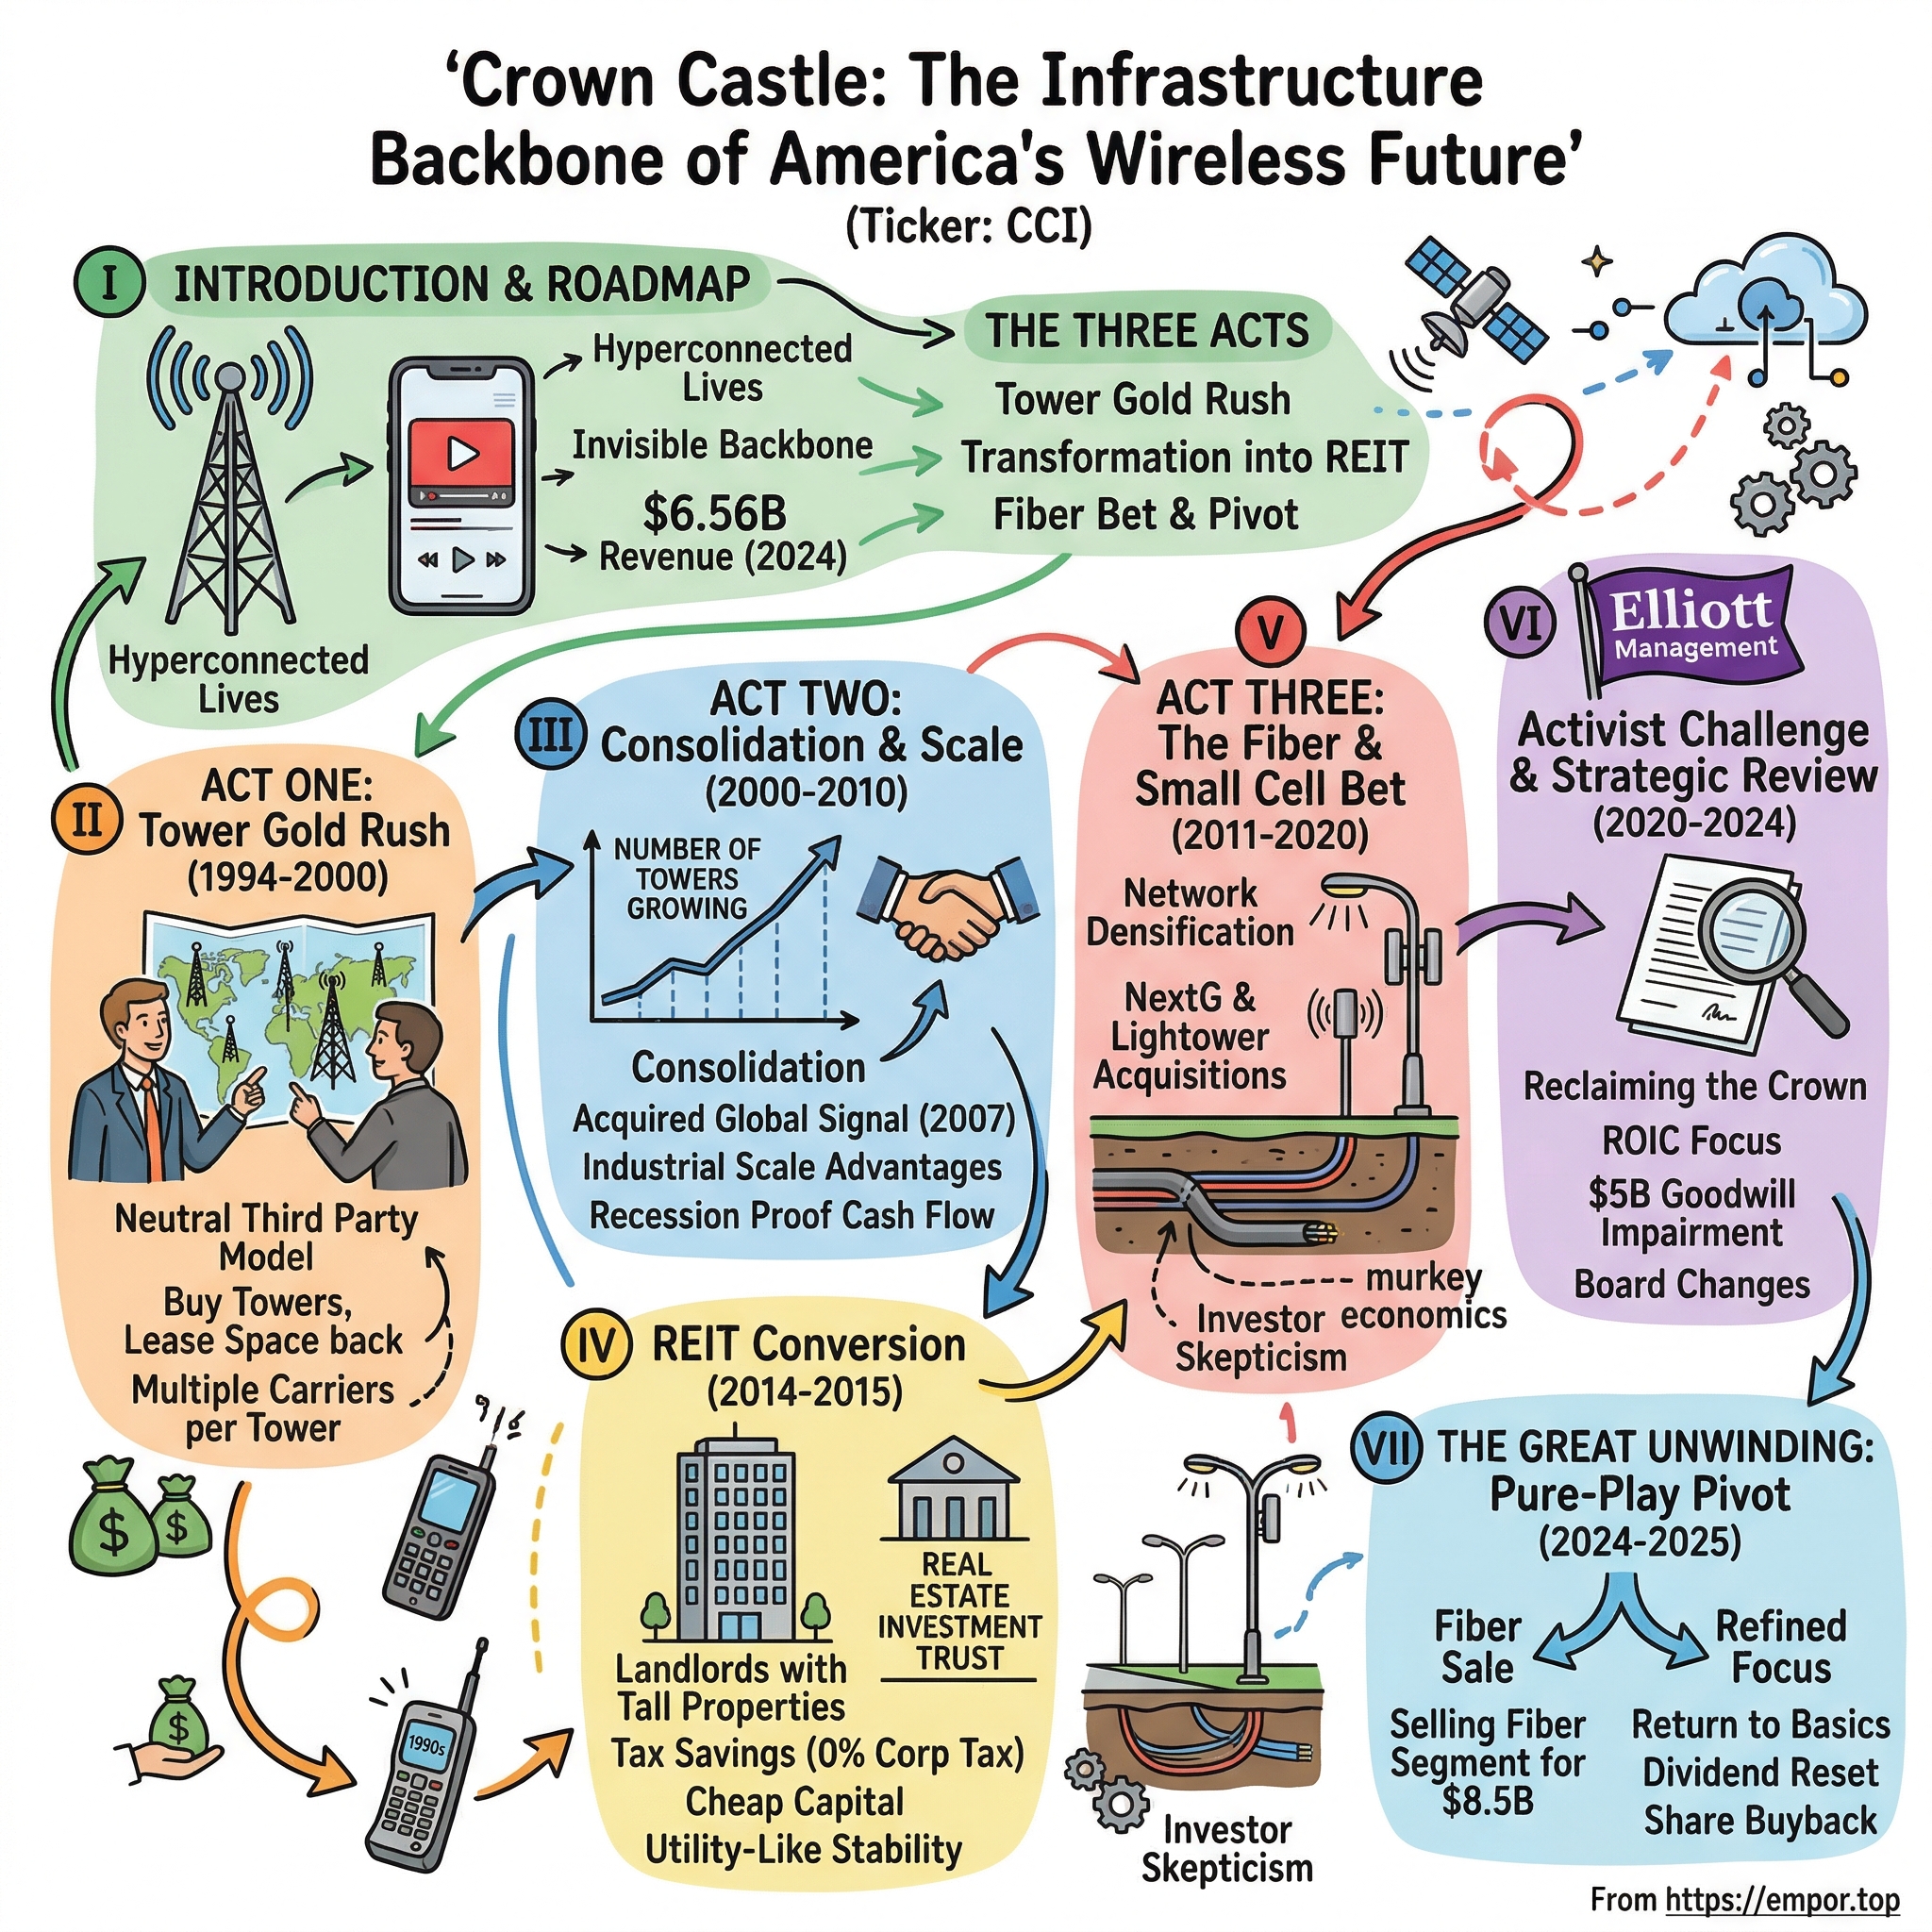
Crown Castle: The Infrastructure Backbone of America's Wireless Future
I. Introduction & Episode Roadmap
On the morning of May 1, 2026, roughly $8.4 billion in net cash landed on Crown Castle's balance sheet.1 It was the largest single financial event in the company's thirty-two-year history, and it was not a triumph. It was a retreat.
The money came from selling the fiber and small cell businesses that Crown Castle had spent fifteen years and roughly $16 billion assembling. Sold in two transactions—the fiber solutions business to Zayo Group Holdings and the small cell business to EQT Active Core Infrastructure fund's Arium Networks—the assets fetched a combined enterprise value of $8.5 billion.1 Within weeks, Crown Castle directed more than $7 billion of that cash to bondholders and used $1 billion to buy back stock.2
That is the paradox at the center of this story. Crown Castle owns one of the most defensible physical asset bases in corporate America: roughly 40,000 steel structures bolted into the ground, mostly in locations where a competitor legally cannot build a second one.3 The unit economics of those structures are exceptionally high-margin—once a tower is built, adding a second tenant costs very little. Yet over a decade and a half, the company managed to underperform its two closest peers so severely that an activist hedge fund could credibly claim tens of billions of dollars in foregone shareholder value.4
Crown Castle Inc. (NYSE: CCI) today is fundamentally different from what it was eighteen months ago. It is a single-segment, U.S.-only tower company. Its continuing operations generated $4.05 billion in site rental revenue in 2025 and are guided to roughly $3.86 billion in 2026—down from the headline $6.5 billion figure in older investor presentations because that previous number included the divested fiber business and because a major tenant stopped paying its bills.56
The thirty-two-year saga breaks into four acts.
Act One (1994–2000): A Houston startup with 133 towers rides telecom deregulation and the initial cellular buildout to a Nasdaq listing.3
Act Two (2000–2014): Crown Castle sells its UK business, consolidates the U.S. market, executes two major carrier sale-leasebacks that more than double its footprint, and converts to a REIT.
Act Three (2011–2023): Management bets that 5G will require hundreds of thousands of street-level small cells anchored by fiber, spending heavily to build the network. The anticipated returns never materialize.
Act Four (2023–2026): Elliott Investment Management launches an activist campaign, a co-founder initiates a proxy fight, the board writes off $5.0 billion in goodwill, three CEOs cycle through in two years, the dividend is cut, and the fiber business is sold at a loss of roughly $1.6 billion against its carrying value.5
The core themes worth watching include: a business with local monopoly characteristics selling to a concentrated group of three carrier customers; operating leverage that compounds powerfully in both directions; a real estate investment trust (REIT) structure that incentivizes capital distribution over retention; and whether an activist-driven return to core towers can restore compounding growth or merely halt the erosion.
That question remains unresolved. Crown Castle is now a simplified, highly levered tower company generating organic billings growth in the low-to-mid single digits, with one of its three main customers facing a major renewal cliff three years out and a bankrupt fourth customer owing it $3.5 billion.76 Whether that setup represents a coiled spring or a value trap is the central debate for investors.
To understand how Crown Castle reached this point, the story begins in Houston in 1994, when mobile phones were still installed in cars and towers were viewed as cost centers.
 Subscribe on LinkedIn
II. Origins & The Tower Gold Rush (1994–2000)
Picture the American wireless map in 1994. Cellular service was a patchwork of regional licenses, and coverage was measured by whether a call stayed connected along an interstate highway. Every carrier seeking to sell airtime had to build its own physical infrastructure: buying land, securing zoning approvals, pouring concrete foundations, erecting steel towers, and only then hanging the radios that actually generated revenue.
Crown Castle was founded in Houston in 1994 around a simple observation: the steel structures were the most capital-intensive and least differentiated link in that value chain. The company began with a portfolio of 133 cell towers.3 According to filings from a 2024 proxy campaign, co-founder Ted B. Miller led Crown Castle as chief executive officer from 1994 to 2002 and served as chairman from 1999 to 2002.8
Miller's insight was financial rather than technological. A carrier's scarce capital belonged in spectrum licenses and network electronics, not tied up in concrete and steel. If an independent owner held the tower and leased vertical space to multiple competing carriers simultaneously, the tower company captured steady, utility-like rental income while the carriers freed up billions of dollars in capital.
The regulatory unlock. The Telecommunications Act of 1996 accelerated this model. By deregulating the industry, the law multiplied the number of licensed wireless carriers competing in each market. Because those carriers needed antennas in virtually the same locations—along key highway interchanges, ridgelines, and urban rooftops—the shared-infrastructure model moved rapidly from theoretical concept to practical necessity.
The shared-infrastructure paradigm. Crown Castle's model was to buy or build a tower once and lease vertical space on it to competing carriers under long-term contracts. As an independent infrastructure operator, the company remained neutral in the retail wireless war, functioning as a tollbooth for network traffic rather than a provider of consumer service. This structural positioning helped insulate tower site rental revenue from subscriber churn among individual carriers.
The 1998 listing. Crown Castle went public on Nasdaq in 1998 with roughly 1,400 towers—a tenfold expansion in four years, achieved almost entirely through acquisition.3 Tapping public equity markets at the onset of the late-1990s telecom investment boom provided the capital required to scale rapidly.
Access to capital served as a primary competitive tool. By 2000, Crown Castle's portfolio exceeded 10,000 towers across the continental U.S., Hawaii, and Puerto Rico.3
The three-way race. Crown Castle was not alone in executing this strategy. Competitors American Tower and SBA Communications pursued the same consolidation playbook against the same regional seller base, competing to acquire portfolios before carrier capital expenditure and site expansion decelerated. This race established an enduring operating pattern for Crown Castle: acquiring scale rapidly, frequently funded with debt.
In fixed-cost infrastructure, scale delivers operational leverage. Key operating expenses—such as ground leases, insurance, property taxes, and structural maintenance—remain largely fixed regardless of how many tenant antennas are installed on a tower. Reaching a national footprint allowed an operator to spread fixed corporate overhead across a broader asset base while offering wireless carriers nationwide master lease agreements instead of site-by-site negotiations.
However, this acquisition-driven expansion carried long-term implications for capital returns. In an industry where three primary buyers bid on regional tower portfolios using debt financing, marginal asset purchases were unlikely to yield outsized returns over time. Exceptional returns were concentrated in early-stage acquisitions completed before tower real estate was widely recognized and priced as a mature asset class.
Crown Castle's disclosures illustrate this divergence in asset performance. As of June 30, 2026, the 11,153 towers the company acquired or built in 2006 and earlier were generating a 19% cash yield on invested capital. By comparison, the 28,588 towers acquired or built from 2007 onward were generating a 9% cash yield.7
The initial cohort reflects the high-return early expansion phase, while the subsequent cohort—more than twice as large—represents assets acquired under higher market valuations and competitive pricing.
For investors, this early history establishes a baseline for evaluating capital deployment. While the initial asset buildout achieved strong economics, subsequent large-scale capital deployment failed to replicate those early return metrics. The first major test of that strategy's limits emerged shortly thereafter across the Atlantic.
III. Building Scale & The Strategic US Pivot (2000–2010)
In April 2001, Crown Castle moved its listing from Nasdaq to the New York Stock Exchange under the ticker CCI.3 The move signaled a strategic repositioning from a high-growth telecom startup toward a mature real estate infrastructure company.
A more consequential strategic shift occurred three years later.
The UK divestiture. On June 28, 2004, Crown Castle agreed to sell its United Kingdom subsidiary to National Grid Transco plc for $2.035 billion in cash.9 The transaction closed on August 31, 2004, with approximately $1.3 billion of the proceeds applied immediately to repay the operating company's credit facility.10 The UK operations encompassed roughly 3,600 tower sites, providing the company with a substantial footprint in a second national market.
Management's rationale, articulated by then-chief executive John Kelly, was that the U.S. market offered greater scale, lower penetration, and an earlier-stage 3G deployment cycle, making concentrated domestic investment more financially flexible and growth-oriented.10
This pure-play domestic strategy remained Crown Castle's core thesis for more than two decades.
What it cost. In contrast, peers such as American Tower expanded into Latin America, Africa, India, and Europe, while SBA Communications built out footprints across Central and South America. By avoiding international expansion, Crown Castle left itself entirely dependent on domestic market conditions. When U.S. carrier capital expenditure decelerated, the company lacked alternative geographic markets to offset the slowdown, making the domestic focus both a driver of high operating margins and a cap on long-term growth.
The long-term merits of the 2004 divestiture remain a subject of debate. European tower economics historically trailed those in the U.S. Crown Castle's current chief executive—who previously led Vantage Towers—noted on the company's July 2026 earnings call that European average revenue per user remains a fraction of U.S. levels and that the operator-to-towerco balance in markets such as Spain remains structurally challenged.11 While the UK exit avoided weaker European returns, it permanently eliminated geographic optionality available to peers.
Scale via Global Signal. Reinvesting capital domestically, Crown Castle agreed on October 6, 2006, to acquire Global Signal Inc. The transaction closed on January 12, 2007, for approximately $5.8 billion, including roughly $1.8 billion of assumed debt.1213
The acquisition expanded the combined portfolio to more than 24,000 wireless sites, including 16,240 towers in the top 100 basic trading areas—giving Crown Castle the largest urban concentration among independent tower operators at the time.13 Notably, 6,553 of Global Signal's towers originated from a prior sale-leaseback transaction with Sprint.13
Rather than owning those structures outright, Crown Castle inherited long-term leasehold interests paired with purchase options. Under the Sprint agreements, approximately 16% of Crown Castle's tower portfolio operated under master leases running 32 years through May 2037, backed by an option to buy the assets in 2037 for approximately $2.3 billion.14
This structure introduced a significant long-term financial feature: a substantial portion of Crown Castle's portfolio relied on long-term leaseholds rather than fee-simple land ownership, deferring major capital commitments into future decades.
Surviving the crisis. During the 2008–2009 financial crisis, Crown Castle demonstrated operational stability. Because site rental revenues were secured under long-term contracts with investment-grade carriers maintaining critical network coverage, tower cash flows remained steady even as commercial real estate values declined sharply.
That resilience reinforced the cash-flow predictability underlying tower infrastructure valuations. However, it also reinforced a reliance on elevated financial leverage—a practice that would define Crown Castle's balance sheet strategy in the decade that followed.
IV. Tower Economics & The Carrier Sale-Leasebacks (2010–2014)
By 2012, major U.S. wireless carriers faced an infrastructure bottleneck reminiscent of the mid-1990s, but at a vastly larger scale. The nationwide deployment of 4G LTE required substantial capital alongside expensive spectrum auctions, even as carriers continued to maintain thousands of non-differentiating cell towers.
Crown Castle, led by W. Benjamin Moreland—who became president and chief executive officer effective July 1, 2008—offered carriers the same arrangement its founders had structured: hand over the steel infrastructure to an independent operator and retain the cash.15
The T-Mobile transaction (2012). Crown Castle acquired rights to approximately 7,200 T-Mobile towers for $2.4 billion, under master prepaid lease arrangements with a weighted-average initial term of roughly 28 years.14 Crown Castle holds options to purchase those towers at the end of the terms for aggregate option payments of approximately $2.0 billion, payable between 2035 and 2049.14
The AT&T transaction (2013). The following year, Crown Castle secured rights to approximately 9,700 AT&T towers for $4.85 billion—again on a weighted-average initial term of about 28 years, with purchase options aggregating approximately $4.2 billion due between 2032 and 2048.14
Together, these two transactions added roughly 17,000 sites, expanding Crown Castle's footprint to approximately 40,000 towers. The deals also cemented AT&T and T-Mobile as long-term anchor tenants on their former physical assets.
How it was paid for. To partially fund the AT&T transaction, Crown Castle issued 41.4 million shares of common stock in October 2013 for net proceeds of $3.0 billion, alongside approximately 9.8 million shares of convertible preferred stock for net proceeds of $950.9 million.14
That represented nearly $4 billion in equity issued in a single month. The transaction demonstrated that Crown Castle has periodically returned to public equity markets when large-scale strategic ambitions exceeded internally generated cash flow.
The unit economics. Tower operators feature powerful incremental economics. A cell tower operates much like an apartment building where the underlying structure is already built, essential operating expenses—such as ground rent, insurance, and structural inspections—are largely fixed, and adding an additional tenant requires minimal incremental investment.
Roughly 75% of Crown Castle's site rental cost of operations is ground lease expense, and those costs escalate broadly with inflation regardless of tenancy.5 Sustaining capital expenditure—the reinvestment required to maintain asset safety and structural integrity—has historically run at less than 1% of net revenues.5
When a second or third carrier installs antennas on an existing tower, the vast majority of that incremental rental revenue flows directly to gross profit. This operating leverage explains why tower real estate commands premium valuation multiples.
But the leverage runs both ways. Because tower operating costs are fixed, revenue losses pass directly through to bottom-line earnings. Crown Castle experienced this dynamic in 2025: site rental revenues fell $219 million, or 5%, year over year, of which $204 million resulted from non-renewals following the T-Mobile and Sprint network consolidation.5 Adjusted EBITDA fell $172 million over the same period, demonstrating how top-line churn compresses operating profit.5
Tenancy is the scoreboard. As of December 31, 2025, the average number of tenants per tower was approximately 2.4.5 By June 30, 2026—following the DISH contract termination—the disclosed figure stood at 2.0.7 Vintage performance illustrates a stark split: the pre-2006 cohort averages 2.5 tenants per tower and generates about $130,000 of annualized cash site rental revenue per tower, whereas the 2007-and-later cohort averages 1.9 tenants and generates about $80,000.7
The tower portfolios acquired from carriers were, on average, less densely tenanted and less profitable than those built or acquired during the initial expansion phase. Acquiring anchor-tenanted portfolios at prevailing market prices meant Crown Castle paid for the existing tenant, leaving co-location lease-up as the primary variable to drive incremental returns.
The concentration problem. Crown Castle's three largest tenants—T-Mobile, AT&T, and Verizon Wireless—collectively accounted for approximately 90% of 2025 site rental revenues.5 As of June 30, 2026, the tenant revenue split was T-Mobile 42%, AT&T 28%, Verizon 23%, and all others combined 7%.7
Generating 90% of revenue from three counterparties provides high credit quality—given that investment-grade carriers must maintain network connectivity—but it also creates substantial customer concentration. Master lease agreements are negotiated centrally on a recurring basis by carrier procurement teams aware of their structural bargaining power.
The impact of this counterparty concentration is reflected in the contract renewal schedule. As of mid-2026, AT&T's weighted-average remaining lease term across Crown Castle's portfolio was three years, compared with six years for T-Mobile and five years for Verizon.7 Furthermore, $774 million of annualized rental cash payments from AT&T reach their renewal date in calendar year 2028 alone—versus $27 million from T-Mobile and $32 million from Verizon that year.7
This concentration makes the upcoming 2028 AT&T lease renewal the single most critical commercial event on Crown Castle's near-term horizon.
V. REIT Transformation & Capital Structure (2014–2015)
On January 6, 2014, Crown Castle announced that it had commenced operating as a Real Estate Investment Trust (REIT) effective January 1, 2014, following tax opinions delivered on December 31, 2013, by Skadden, Arps, Slate, Meagher & Flom and Cravath, Swaine & Moore confirming its qualification.16
On paper, converting to a REIT was a tax election. In practice, it rewired how the company managed and distributed its capital.
What the structure does. As a REIT, Crown Castle is generally entitled to a corporate tax deduction for dividends paid, eliminating U.S. federal income tax on distributed net income provided it annually distributes at least 90% of its REIT taxable income.5 The practical impact is evident on the income statement: Crown Castle recorded a tax provision of just $16 million in 2025 and $18 million in 2024, despite generating income from continuing operations exceeding $1.1 billion.5
Eliminating a 21%-plus corporate tax drag on a stable cash-flow annuity provided a permanent improvement in after-tax returns, while broadening the shareholder base to income-focused institutional investors seeking predictable yield.
The contract machine. The REIT wrapper monetized a highly predictable contractual framework. Wireless tenant contracts typically feature initial terms of five to 15 years, multiple five-year renewal options exercisable by the tenant, limited termination rights, and contractual rent escalators.5 Tenant retention has historically averaged between 98% and 99% annually.5
As of December 31, 2025, the weighted-average remaining term on tenant contracts stood at approximately six years, representing roughly $23.7 billion in expected future cash inflows, excluding contracted amounts owed by DISH.5
The escalator, honestly measured. Crown Castle's rent escalators are frequently cited as a flat 3% annual increase, but realized figures run lower. Escalators contributed $96 million, or 2.5% of prior-period site rental billings, in full-year 2025, while the 2026 outlook projects approximately $100 million, or 2.7%.62
That distinction is material. Realized escalators of 2.5% to 2.7% provide a modest inflation hedge. However, when ground lease expenses escalate alongside inflation, that revenue growth functions more like a treadmill than an economic moat. Fixed escalators serve as a liability during high-inflation regimes and an asset in low-inflation environments—the inverse of how they are often marketed.
The zoning moat. The company's most defensible asset is regulatory permission. Municipal zoning ordinances, setback rules, height restrictions, and local opposition make constructing a second tower within close proximity to an existing site slow, costly, and frequently impossible. That regulatory barrier, rather than the physical steel, forms the core of an incumbent's moat.
Crown Castle's disclosures underscore that structural position: approximately 56% of its towers sit within the 50 largest U.S. basic trading areas, 71% reside in the top 100, and underlying land contracts carry an average total remaining life of roughly 35 years, including company-held renewal options.5
But permission is not the same as pricing power. A local monopoly on tower siting prevents carriers from easily bypassing an existing structure, but it does not dictate pricing. Wireless carriers can decommission redundant sites after corporate mergers, consolidate equipment onto fewer structures, or leverage bulk volume commitments to secure rate concessions during master lease negotiations. Crown Castle has experienced all three headwinds.
The land question. As of June 30, 2026, approximately 57% of Crown Castle's site rental gross margin was derived from towers on leased land, while 43% came from land the company owns outright.7 Ground rent represents the largest operating expense in the tower business, meaning land acquisitions convert an escalating operating expense into an owned asset.
Management has made acquiring underlying land an explicit operational priority. Land capital expenditures drove a $20 million quarterly increase in capital spending in the second quarter of 2026.2 Chief Financial Officer Sunit Patel described the effort during an earnings call as a multi-year initiative executed "in a very financially disciplined manner," targeting returns "well above our cost of capital."11
That land-buyback effort represented an unglamorous, high-confidence deployment of capital—a sharp contrast to the strategic path the company chose next.
VI. The $16B Fiber & Small Cell Strategic Gamble (2011–2020)
The strategic argument for small cells was straightforward.
Every generation of mobile technology relies on higher-frequency spectrum to deliver greater data capacity. However, high-frequency signals face physical limitations: while carrying more data, they travel shorter distances and are easily attenuated by walls, foliage, and precipitation. A low-band signal from a macro tower can cover several miles, whereas a high-band 5G signal reaches only a few city blocks.
Under this model, dense urban capacity cannot rely on macro towers alone. It requires hundreds of thousands of street-level radio nodes mounted on utility poles and streetlights—each linked by fiber optic cable back to the core network.
Crown Castle management concluded that owning urban fiber would yield the same high-margin, shared-infrastructure economics in small cells that it enjoyed in macro towers. The company launched a multi-year acquisition campaign to secure municipal fiber networks across major metropolitan markets.
December 2011 — NextG Networks, approximately $1.0 billion in cash. NextG was the largest provider of outdoor distributed antenna systems, operating over 7,000 active nodes with 1,500 under construction and holding rights to more than 4,600 miles of fiber.17 Then-CEO W. Benjamin Moreland framed the transaction as a strategic extension: "Increasingly, we believe that small-cell architecture, such as DAS, will be an important complement to traditional macro tower installations."17
April 2015 — Sunesys, approximately $1.0 billion in cash. Crown Castle agreed to acquire Sunesys from Quanta Services, closing the deal in August 2015 and adding nearly 10,000 miles of fiber across Los Angeles, Philadelphia, Chicago, Atlanta, Silicon Valley, and northern New Jersey.1814
November 2016 — FPL FiberNet, approximately $1.5 billion in cash. The company agreed to acquire FPL FiberNet from NextEra Energy, closing in January 2017 and incorporating approximately 11,500 route miles of fiber across Florida and Texas.19
April 2017 — Wilcon, approximately $600 million. The acquisition added roughly 1,900 route miles concentrated in Los Angeles and San Diego.20
July 2017 — Lightower, approximately $7.1 billion in cash. Crown Castle agreed to acquire Lightower in July and closed the transaction in November 2017, adding approximately 32,000 route miles focused in Boston, New York, and Philadelphia.19
Funding for the Lightower acquisition relied heavily on equity issuance. To finance the purchase, Crown Castle issued 40.15 million common shares in July 2017 to raise approximately $3.8 billion, alongside 1.65 million shares of 6.875% convertible preferred stock for net proceeds of approximately $1.6 billion.19 In total, roughly $5.4 billion in newly issued equity funded the single largest acquisition of the expansion strategy.
By the end of the consolidation phase, Crown Castle owned roughly 90,000 route miles of fiber and had approximately 105,000 small cell nodes either operational or under contract.5 The cumulative capital committed—combining acquisitions and ongoing network construction—reached the $16 billion headline estimate later highlighted by Elliott Investment Management, a figure Elliott subsequently revised upward to $19 billion by 2023.421
Why the thesis broke. Three structural factors undermined the strategy's economic returns.
First, municipal permitting. Unlike a macro tower, which requires a single negotiation with one landowner, small cell deployment involved thousands of separate agreements with local municipalities, electric utilities, and pole owners. Variable local regulations and approval timelines extended deployment cycles across multiple years, tying up capital in ongoing construction while debt service costs accumulated.
Second, limited tenancy. Shared infrastructure relies on co-location—leasing an existing asset to multiple tenants to maximize incremental profit. While macro towers achieved high tenant ratios, small cell nodes were deployed to solve coverage gaps for specific carriers operating on dedicated frequencies. Consequently, most nodes served only a single tenant, turning a shared asset model into custom carrier construction financed at Crown Castle's cost of capital.
Third, market competition. Enterprise fiber solutions—selling dark and lit fiber to corporate customers—lacked the high barriers to entry characteristic of macro towers. Crown Castle competed in a price-sensitive market against incumbent telecommunications carriers, cable operators, and regional fiber providers.
The returns, in the company's own eventual accounting. Activist investor Elliott Management reported in 2020 that Crown Castle's fiber return on investment was roughly 3%, "well below the cost of capital," and calculated that $4.6 billion of capital investment had produced only $135 million in organic EBITDA growth.4 By November 2023, Elliott updated its estimate to a 6% return on invested capital across $19 billion of deployment—a return below both the company's cost of capital and prevailing U.S. Treasury yields at the time.21
Management defended the segment's growth potential for years, but accounting disclosures eventually reflected the valuation shortfall. In the fourth quarter of 2024, Crown Castle's annual goodwill impairment test determined that the carrying value of its Fiber reporting unit exceeded its fair value, resulting in a goodwill impairment charge of approximately $5.0 billion that fully eliminated the unit's remaining goodwill.22
That single non-cash charge resulted in a full-year 2024 net loss of $3.9 billion, compared with net income of $1.5 billion in 2023.22
The opportunity cost. Beyond the direct balance-sheet write-down lay significant opportunity costs. Capital directed to fiber expansion was unavailable to purchase land beneath existing macro towers, reduce leverage ahead of rising interest rates, or return capital to shareholders.
Crown Castle applied the narrative of its core tower business—shared infrastructure, co-location, and high incremental margins—to an asset class without equivalent competitive protections.
By 2020, that widening gap between capital deployment and financial returns attracted activist investors with substantial capital.
VII. Historical Falsification Pass: Testing Thesis Claims
Every investment case for Crown Castle rests on a small number of load-bearing claims. Testing each claim against the longest span of the company's own record—evaluating disclosed outcomes rather than executive assertions—reveals where the thesis holds up and where it collapses.
Claim 1: "Adjacent digital infrastructure is a natural, high-return extension of the tower franchise."
The corporate record rejects this claim outright. Between 2011 and 2020, Crown Castle invested roughly $16 billion in fiber and small cells, a commitment that grew to around $19 billion by 2023 while generating an estimated 6% return on invested capital.421 The financial outcome was decisive: a $5.0 billion goodwill impairment in 2024, an additional loss on disposal of approximately $1.6 billion in 2025 when the asset was classified as held for sale, and an ultimate sale price of $8.5 billion.2251
Verdict: Rejected. The evidence of failure comes directly from the company's own reporting across the same asset base over a multi-year period, proving economically terminal.
What would change the assessment: Nothing regarding the fiber venture itself. However, the underlying premise has reemerged in a new form: management is trialing edge data center deployments at tower sites. That initiative must be evaluated against this historical record rather than treated as a fresh opportunity.
Claim 2: "Macro tower tenancy expands naturally toward 3.0x as carriers densify."
This claim has been severely narrowed. Rather than compounding upward, average tenancy per tower declined from approximately 2.4 tenants at year-end 2025 to 2.0 by mid-2026.57
Two developments caused the contraction. The T-Mobile–Sprint merger in April 2020 triggered years of network consolidation, resulting in $204 million of non-renewals for Crown Castle in 2025 alone and an anticipated $20 million drag in 2026.26 Concurrently, DISH Network—the fourth carrier expected to drive new tenancy—defaulted on its obligations.
Vintage asset performance reinforces the structural limit: the newer, larger cohort of towers averages 1.9 tenants per structure and has failed to converge toward the older cohort's 2.5 tenants despite nearly two decades of 4G and 5G network rollouts.7
Surviving version of the claim: Tenancy on individual, well-situated towers can still increase, and amendment revenue from existing tenants remains a reliable income stream. However, portfolio-average tenancy reflects broader industry structure, and the U.S. wireless market has consolidated rather than expanded over the past fifteen years.
Falsifiable test: Whether average tenancy per tower rises above 2.0 across any four-quarter period without portfolio acquisitions. If new spectrum allocations genuinely drive network densification, the trend will manifest in that metric.
Claim 3: "The REIT structure delivers low-volatility, growing dividends."
Rejected in its strongest form. Crown Castle targeted 7% to 8% annual dividend growth for years. However, after paying $1.565 per share in the first quarter of 2025, the company reduced its quarterly payout to $1.0625 for the remainder of the year—a 32% annualized reduction that established a $4.25 per share baseline.5
Management attributed the reduction to an updated capital allocation framework designed "to focus more on free cash flow generation and financial flexibility."5 In practice, debt accumulated during the fiber expansion, combined with a higher-rate refinancing environment, rendered the previous dividend payout unsustainable.
Surviving version: The dividend is now pegged to cash flow rather than a fixed growth mandate, targeting 75% to 80% of adjusted funds from operations (AFFO) excluding the amortization of prepaid rent.22 Management has committed to maintaining the $4.25 per share payout until that target payout ratio is achieved.6 While this represents a more durable capital policy, it abandons the original growth promise.
Claim 4: "Management allocates capital with discipline."
This remains an open question, with disclosed evidence pointing in conflicting directions.
The historical record highlights notable missteps. Beyond the fiber strategy, Crown Castle repeatedly issued equity to finance large-scale expansion at peak valuations. The company raised nearly $4 billion in common and preferred equity in October 2013 to fund the AT&T transaction, followed by approximately $5.4 billion in 2017 to acquire Lightower.1419 Capital return commitments have also shifted: when announcing the fiber sale in March 2025, management outlined plans for an approximate $3.0 billion share repurchase program post-closing.22 The executed authorization was ultimately scaled back to $1.0 billion.2
That reduction had a practical rationale. DISH's default removed roughly $280 million in expected AFFO over the twelve months following the deal's close, prompting management to allocate $7 billion toward debt repayment instead of the planned $6 billion to maintain target leverage metrics.6 Even so, the adjustment highlights a pattern of setting aggressive initial targets that were later scaled back as market conditions shifted.
Conversely, recent actions reflect greater discipline. The ground lease buyout program offers high-confidence returns, discretionary capital expenditures dropped to $149 million in 2025 with $150 million to $250 million guided for 2026—a fraction of the fiber-era investment rate—and executive compensation has been restructured around return on invested capital and AFFO per share.56
Verdict: Narrowed to "capital allocation is now governed by a strict financial framework and a smaller set of investment opportunities." Whether this framework maintains discipline when presented with major acquisition opportunities remains untested.
Claim 5: "The balance sheet is repaired."
Partially true, but frequently overstated. Crown Castle repaid more than $7 billion in debt during the second quarter of 2026, resized its credit facility from $7 billion to $4.5 billion, converted all outstanding debt to fixed rates, and extended its weighted-average debt maturity to approximately seven years.117
Nevertheless, net debt stood at $17.1 billion as of June 30, 2026, representing a net leverage ratio of 6.3 times annualized Adjusted EBITDA—nearing its 7.0x covenant ceiling—alongside a total equity deficit of $3.27 billion.7
Furthermore, management raised its target net leverage range to 6.0 to 6.5 times Adjusted EBITDA, up from its historical target of roughly 5.0 times. Moody's highlighted this shift on March 17, 2025, affirming Crown Castle's Baa3 rating while revising its outlook to negative due to the higher leverage target and limited net debt reduction from the fiber transaction.23
For comparison, peer American Tower reported net leverage of 4.9 times as of June 30, 2026, maintaining a policy target of 5.0 times or below.24
Verdict: Crown Castle resolved its immediate refinancing risks, but its underlying leverage remains elevated. The company deliberately chose to operate with higher leverage than its primary peer to fund share repurchases and dividend distributions.
VIII. The Activist Siege & Strategic Review (2020–2024)
On July 6, 2020, Elliott Management published a letter and presentation under a title built for headlines: Reclaiming the Crown. The firm disclosed a $1 billion economic interest in Crown Castle and presented an argument grounded less in strategic philosophy than in stark arithmetic.4
The relative figures were stark. Over a ten-year horizon, Crown Castle had underperformed American Tower by 125% and SBA Communications by 313% in total return. Over fifteen years, those performance gaps widened to 415% and 1,074%. On profitability, American Tower and SBA were generating 65% and 55% more profit per dollar of invested capital, respectively, while Crown Castle's five-year AFFO per share growth trailed American Tower by 41% and SBA by 21%.4
Elliott identified a single root cause: the fiber strategy. Its remedies included establishing a 40% minimum return hurdle on fiber capital expenditures, tying executive compensation directly to return on invested capital, refreshing the board, and committing to a substantially larger dividend.4
Crown Castle's board engaged with the activist and appointed several new directors, but ultimately continued building out fiber while the stock continued to lag. Chief Executive Officer Jay Brown—who had advanced from Vice President and Treasurer to Chief Financial Officer in July 2008 before succeeding Ben Moreland as President and CEO in June 2016—remained at the helm.1525
The second campaign. On November 27, 2023, Elliott returned with an expanded stake of approximately $2 billion, shifting its tone from advisory critique to outright prosecution.21
The firm asserted that under the incumbent executive team, Crown Castle had underperformed its direct peers by an average of 85% in total return, wiping out roughly $26 billion in relative shareholder value. The letter reiterated the poor return profile of the fiber strategy—pointing to $19 billion invested at a 6% return on invested capital, with incremental outlays since 2020 yielding just 4%. Elliott outlined four demands: replace the CEO and refresh the board, initiate a strategic review of fiber ownership, adopt ROIC-based compensation metrics, and repeal shareholder-unfriendly bylaw amendments enacted in 2021. If engagement failed, Elliott pledged to nominate a majority director slate at the May 2024 annual meeting.21
Ten days later, on December 7, 2023, Crown Castle announced that Jay Brown would retire as President, CEO, and director effective January 16, 2024. Board member Anthony Melone—formerly Executive Vice President and Chief Technology Officer at Verizon Communications from December 2010 to April 2015—was appointed interim CEO.26
The board simultaneously formed a Fiber Review Committee to evaluate strategic and operational alternatives for the small cell and fiber solutions businesses.22 That committee served as the direct precursor to the 2026 divestiture. In substance, Elliott had prevailed.
The founder's counterattack. In February 2024, the narrative took an unexpected turn when co-founder Ted Miller—who had stepped down from the board two decades earlier—launched a proxy contest through Boots Capital Management. Miller proposed a four-director slate, claiming his team could execute a more efficient, tax-advantaged resolution for the fiber assets than the sitting board.
Crown Castle responded aggressively, characterizing the proxy challenge as a vehicle for Miller to re-establish himself as de facto chief executive while securing board seats for his son-in-law and two associates.27
Shareholders settled the dispute at the annual meeting on May 22, 2024, re-electing all twelve corporate nominees and rejecting Miller's entire slate.27 The board retained control, and the co-founder's bid failed.
Reading the outcome correctly. While this result might appear to vindicate the board over both the activists and the founder, the underlying dynamics suggest otherwise. Crown Castle's shareholder base proved willing to enforce capital discipline through the existing board while rejecting a management takeover by a returning founder with a personal slate. In effect, shareholders adopted Elliott's strategic mandate almost completely while turning down Miller's governance bid.
The financial toll of the proxy fight left clear marks in the financial statements: selling, general, and administrative expenses fell $52 million, or 12%, between 2024 and 2025, a drop management attributed in part to reduced legal and advisory fees "primarily related to our recent proxy contest in 2024."5
The activist stress test that remains. With the fiber business sold, investors face a different set of governance and operational questions than Elliott raised in 2020. Key unresolved issues include: why the company targets net leverage of 6.0 to 6.5 times Adjusted EBITDA—well above its primary peer's sub-5.0x target—despite Moody's maintaining a negative outlook; why the annual incentive plan paid out at 139.16% of target for 2025 during a year when site rental revenues dropped 5% and total shareholder returns were negative; and what explicit criteria will prevent future edge-infrastructure initiatives from repeating past capital allocation errors.
These questions are not academic; they will determine whether Crown Castle's renewed focus on core towers restores sustainable compounding or repeats historical missteps.
IX. Executive Leadership & Current Governance
Between December 2023 and September 2025, Crown Castle had five individuals occupy the chief executive’s office—a sequence reflecting intense board and governance instability as the company navigated activist pressure and the unwinding of its fiber strategy.
Jay Brown was the insider—the treasurer who became chief financial officer and then chief executive, promoted from within at each step.1525 As the principal architect and defender of the fiber strategy, he departed in January 2024 within days of Elliott Investment Management launching its second activist campaign.26
Anthony Melone served as the interim caretaker with technical credibility—a former Verizon chief technology officer who provided carrier-side operating experience while the board conducted a search.26
Steven Moskowitz arrived as the outsider hire, appointed President and CEO effective April 11, 2024.28 His background fit the company's asset footprint precisely: twelve years at American Tower, including seven leading its U.S. tower business; CEO of NextG Networks from 2010 to 2012—the small cell company Crown Castle acquired; and CEO of Centennial Towers from 2014 to 2023, building tower platforms in Brazil, Colombia, and Mexico.28
Moskowitz executed the transaction. The March 13, 2025 announcement of the $8.5 billion fiber sale included his statement concluding the strategic review.22 Eleven days later, on March 24, 2025, Crown Castle announced his termination.
The company stated that the termination was without cause, was not the result of policy or financial disagreements, and was unrelated to compliance concerns, framing the decision around a board determination that new leadership was required to complete the divestiture and transform the company into a pure-play tower business.29 His employment ended effective March 23, 2025, a qualifying termination that triggered severance under his agreement.30
Replacing a CEO eleven days after closing the largest strategic sale in company history—while explicitly disclaiming performance as the cause—highlighted an unusual governance dynamic, suggesting the board shifted its leadership criteria between deal execution and ongoing pure-play operations.
Dan Schlanger, the long-serving CFO, served as interim CEO starting in March 2025 and was subsequently appointed Chief Transformation Officer to shepherd the divestiture through closing.29
Sunit Patel joined as Executive Vice President and CFO in 2025, bringing extensive experience in capital-intensive telecom finance.7 His public communication focused on operational detail—itemizing cost savings line by line, naming the components of organic growth, and evaluating balance sheet leverage in debt covenant terms.
Christian H. Hillabrant assumed the roles of President and CEO effective September 15, 2025.31 At age 60, he had been with the company for less than a year as of mid-2026.7 His background is operational rather than financial, including senior executive roles at T-Mobile, Ericsson, and Samsung, service as chief operating officer of Tillman Infrastructure, and most recently chief executive officer and management board chairman at Vantage Towers, which manages more than 86,000 wireless sites across ten countries.31
Compensation incentives. Crown Castle's executive incentive framework underwent three consecutive annual revisions, aligning closely with activist recommendations. In 2024, the board replaced absolute total shareholder return as a long-term performance metric with three-year average return on invested capital (ROIC). In 2025, it introduced three-year cumulative AFFO per share while converting relative total shareholder return into a modifier of plus or minus 15%. In 2026, the board raised cumulative AFFO per share to 40% of the long-term incentive mix and reduced average ROIC to 20%, citing reduced capital intensity following the fiber divestiture.30
Lowering the weight on return on invested capital immediately after divesting an asset class that generated substandard returns represents a notable structural adjustment, shifting focus toward cash flow generation on the remaining tower base.
Short-term payouts versus market outcomes. For 2025, the annual incentive plan paid out at 139.16% of target. That payout was driven by Adjusted EBITDA reaching $4.044 billion against a $3.968 billion target—weighted at 70%—and organic revenue growth reaching $285 million against a $251 million target—weighted at 30%.30 Over the same three-year performance period ending December 31, 2025, total shareholder return was negative, trailing the S&P 500, and performance-based restricted stock units granted in 2023 paid out at zero.30
This divergence reflects a split structure: short-term cash bonuses rewarded internal budget targets, while long-term equity grants reflected market performance. Shareholders have consistently endorsed this structure, approving the say-on-pay proposal with approximately 93% of votes cast at the 2025 annual meeting and maintaining a 95% five-year average.30
Retention economics. In March 2025, the compensation committee authorized a one-time grant of "Transformation RSUs" vesting upon the successful closing of the fiber transaction to retain key executives through the asset sale.30 Hillabrant’s executive package includes a target annual long-term incentive of $10.5 million, an $800,000 make-whole cash bonus subject to recoupment, and time-vesting make-whole RSUs valued at approximately $7 million to offset forfeited awards from his previous employer.30
The resulting executive team is operationally focused and new to the company, tasked with managing a simplified tower portfolio under strict capital allocation constraints. Its mandate is clear: optimize operating returns across 40,000 domestic towers.
X. The Great Unwinding: Pure-Play Pivot (2024–2026)
The unwinding took fourteen months from signature to cash, and the delay itself became part of the story.
The definitive agreement was signed on March 13, 2025: the entire Fiber segment, together with certain supporting assets and personnel, sold for $8.5 billion in aggregate—Zayo taking fiber solutions and EQT's fund taking small cells, with each business valued equally.225 Because the transaction represented a material strategic shift, the Fiber business was reclassified as discontinued operations and prior periods were recast, causing Crown Castle's headline revenue line to shrink by roughly a third overnight.5
Accounting recognition of the loss occurred immediately. Upon classification as held for sale in the first quarter of 2025, Crown Castle recognized a loss from disposal of discontinued operations of approximately $1.6 billion, inclusive of estimated transaction fees, representing the excess of the Fiber business's carrying value over the purchase price less estimated costs to sell.5
The closing. The transaction completed on May 1, 2026, generating approximately $8.4 billion in net cash after $124 million of preliminary purchase price adjustments still subject to a post-closing settlement process.7 Regulatory clearance proved to be the primary gating item; while the Department of Justice closed its Hart-Scott-Rodino review without taking action, the deal required multiple state and federal approvals, with California singled out by management as the sensitive jurisdiction.6
Where the money went. Crown Castle directed approximately $7.2 billion of the proceeds to debt repayment. This included roughly $5 billion in floating-rate obligations across its commercial paper program, revolving credit facility, and term loan, $500 million in open-market debt repurchases, and two unsecured note maturities totaling $1.75 billion.11 To match a smaller operating footprint, the revolving credit facility was resized downward from $7 billion to $4.5 billion.11
The company executed its $1 billion share buyback during the second quarter of 2026 at an average price of $88.66 per share, retiring more than 11 million shares and reducing its annual dividend obligation by $47 million.11 Total outstanding shares fell from 435 million to 426 million.7
The organizational surgery. Roughly 60% of the consolidated workforce transferred with the sale.6 What remained underwent further cuts: in February 2026, ahead of the closing, Crown Castle announced a restructuring that reduced continuing operations' tower and corporate headcount by approximately 20%, leaving about 1,250 full-time employees. The downsizing targeted $65 million in annualized run-rate cost savings against roughly $30 million in restructuring charges.65
Management acknowledged that this headcount reduction was accelerated and expanded specifically because of the DISH default—staffing had been scaled for network deployment activity that would never arrive.6
Why the buyback shrank. The strategic framework announced in March 2025 originally contemplated approximately $3.0 billion in share repurchases.22 However, DISH's contract termination removed roughly $280 million in expected AFFO over the twelve months following the closing, lowering post-closing AFFO guidance by $240 million to $2.1 billion.6 With less EBITDA to lever against, staying inside a 6.0–6.5x net leverage target required prioritizing debt reduction over equity retirement.
When asked about the shift in capital deployment, CFO Sunit Patel was straightforward: "we thought it made sense to pay down more debt than stay within the range because as we said previously, the key for us is to be investment grade."6
Patel's explanation highlights an important distinction: share repurchases functioned as a residual use of cash rather than a fixed commitment—a critical detail given management's presentation of buybacks as a central pillar of its capital framework.
The dividend, restated. Management reset the quarterly payout to an annualized baseline of $4.25 per share in the second quarter of 2025 and has maintained it since, committing to hold the payout until the distribution ratio reaches 75% to 80% of AFFO excluding prepaid rent amortization, after which dividend growth is slated to track AFFO expansion.56 CEO Christian Hillabrant has called the dividend "sacrosanct" in the capital allocation stack, funded ahead of capital expenditure and share repurchases.11
What the pure-play company actually looks like. For full-year 2026, midpoint guidance projects site rental revenues of about $3.86 billion, Adjusted EBITDA of roughly $2.69 billion, and AFFO of approximately $1.98 billion, or $4.59 per share—representing AFFO growth of roughly 5% per share on a revenue decline of 5%.2
That divergence captures the core post-divestiture equation: top-line revenue is contracting because non-renewals from DISH and the Sprint network consolidation exceed new carrier leasing, yet cash flow per share is rising because interest expense fell by roughly $160 million and the share count shrank.111
This outcome reflects balance-sheet arithmetic rather than commercial growth. Lower interest costs and a reduced share count produce a discrete boost in cash flow per share, but that benefit is finite. Sustainable value creation going forward will depend on whether the underlying tower leasing business can reaccelerate—the central question that subsequent sections examine.
XI. Business Model Deep Dive & Competitive Powers
Strip away thirty-two years of corporate evolution, and Crown Castle is once again simple to describe: one reportable segment, one country, and one core product.5
Site rental revenues generated 95% of net revenues in 2025, with the remaining 5% derived from ancillary pre-construction site development services—including site acquisition, architectural and engineering work, zoning, and permitting—that the company handles opportunistically rather than as a primary growth driver.5 The underlying core remains highly profitable: Adjusted Site Rental Gross Margin reached $3.08 billion on $4.05 billion of site rental revenue in 2025, representing a gross margin of roughly 76%.5
Applying Hamilton Helmer's 7 Powers.
Scale Economies — real but bounded. A national footprint enables Crown Castle to spread corporate overhead, legal, and network operations across 40,000 sites while negotiating nationwide master lease agreements. However, tower scale economies plateau: the industry's third-largest operator and its largest operate at comparable site-level cost structures. The clearest evidence that scale alone is not decisive is that Crown Castle remains the scaled domestic incumbent yet has consistently trailed both primary peers on capital returns.
Switching Costs — the strongest power. Relocating a carrier's antennas, radios, cabling, and backhaul from one structure to another requires costly truck rolls, crane rentals, re-permitting, radio network re-optimization, and potential service degradation. Carriers rarely undertake such moves voluntarily, a stability demonstrated by Crown Castle's historical tenant retention rate of 98% to 99% annually.5
Cornered Resource — moderate and misunderstood. Zoning and siting rights are genuinely difficult to replicate. Yet Crown Castle does not own outright a major share of what it operates: large tranches of its portfolio sit under long-dated master leases with multi-billion-dollar purchase options, and 57% of gross margin is derived from towers on leased land.714 A cornered resource that is leased rather than owned represents a diluted form of competitive power.
Counter-Positioning — attempted and failed. The small cell initiative was an attempt to occupy a street-level infrastructure position that carriers could not easily replicate, but the strategy failed to deliver anticipated returns for the structural reasons detailed previously.
Process Power, Branding, Network Economies — largely absent. Management's stated operational priorities focus on process improvements, such as faster deployment cycle times, automated administrative systems, and upgraded asset data.6 While operational efficiency is necessary, these efforts represent catch-up execution rather than a durable structural power.
Applying Porter's Five Forces.
Buyer power — high and expanding. Three primary carriers generate approximately 90% of revenue, negotiate centrally through master lease agreements, and hold the structural leverage to consolidate redundant sites following industry mergers. Customer concentration is more pronounced at Crown Castle than at its peers because the company lacks international or non-carrier operations to dilute its exposure.
Supplier power — moderate and persistent. The primary supplier is the landowner. Ground lease expense represents the company's largest single operating cost, and landowners retain pricing leverage when negotiating lease renewals. This dynamic underscores the strategic logic of Crown Castle's land buyout program, which seeks to convert recurring supplier expense into an owned asset base.
Threat of new entrants — low. Erecting a competing macro tower network remains constrained by municipal zoning rules rather than capital availability, and regulatory approvals do not scale linearly.
Threat of substitutes — manageable today, but evolving. Satellite direct-to-device technology represents the primary emerging substitute, warranting clear-eyed analysis.
The satellite question, explained. A satellite in low Earth orbit operates hundreds of miles above the planet, whereas a cell tower operates within a mile or two of the device. Because signal strength degrades rapidly over distance, a direct-to-device satellite signal reaches a handset at a fraction of a terrestrial signal's strength. Management noted on the July 2026 earnings call that satellite signals are roughly 10,000 times weaker, requiring mobile phones to transmit at higher power levels and accelerating battery drain.11
Two additional technical constraints limit satellite capacity. Direct-to-device satellite networks generally operate on tens of megahertz of spectrum, whereas each major U.S. wireless carrier controls hundreds.11 Furthermore, a satellite beam covers 100 to 600 square miles compared to 3 to 20 square miles for a terrestrial cell site, forcing far more users to share the same available bandwidth.11
Management's assertion that terrestrial cell sites support roughly thirty times more users per megahertz reflects an interested party's perspective.11 Nonetheless, the underlying engineering reality is widely accepted: satellite is primarily a coverage solution for remote areas where towers are uneconomic, rather than a capacity solution for dense markets where network demand is highest. Furthermore, roughly 90% of mobile data usage occurs indoors or inside vehicles, where satellite signal penetration is weakest.11
The secondary risk is strategic rather than direct. If a well-capitalized satellite operator chooses to construct a hybrid terrestrial network, it will still require tower infrastructure—a development that could benefit Crown Castle's urban-dense portfolio. When asked about that possibility on the earnings call, CEO Christian Hillabrant noted it was too early to speculate, though he emphasized that the company maintains available "space, power and backhaul" across its tower sites.11
The peer comparison that matters. Compared to American Tower, Crown Castle presents a more concentrated customer base, higher balance-sheet leverage, and lower capital returns. Crown Castle generated a consolidated return on invested capital of 9.9% as of mid-2026—down from 10.4% a year earlier—while operating at a net leverage ratio of 6.3 times Adjusted EBITDA, compared with American Tower's 4.9 times.724 For full-year 2026, Crown Castle projects organic billings growth of approximately 3.4%—or 3.6% when adjusting prior-year billings for the DISH contract loss—compared to American Tower's global organic growth guidance of roughly 4% excluding DISH.224
A pure-play domestic structure provides operational simplicity, but it has yet to prove that a single-country focus translates into superior shareholder returns.
XII. Strategic Position: Why Win / Why Not
The bull and bear cases for Crown Castle do not disagree about the assets. They disagree about whether a very good asset base in a maturing market, owned by a company that must service $17 billion of net debt, compounds or merely persists.
The case that Crown Castle wins from here.
The simplification is genuinely valuable. Complexity destroyed value at this company for a decade — not only through the capital misallocation but through the analytical fog that let a low-return segment hide inside a high-return one. A single-segment company cannot cross-subsidize. Every dollar of capital is now visible.
Cash conversion has structurally improved. Discretionary capital expenditure guidance of $150–250 million for 2026, against Adjusted EBITDA near $2.69 billion, means the business converts the large majority of EBITDA into distributable cash.26 Sustaining capital requirements remain under 1% of revenue.5 This was never true during the fiber years, when construction absorbed the tower business's output.
Demand drivers are real, even if the timing is not underwritable. Management cites Ericsson's projection that U.S. smartphone data consumption more than doubles over five years, from roughly 25 to 52 gigabytes per month, with a projected threefold increase in uplink traffic as devices push video and sensor data upward.11 The FCC has outlined a pipeline of at least 800 megahertz of additional commercial spectrum, with auctions signalled from 2027, and the upper C-band decision extends usable mid-band spectrum.11
The physics argument is straightforward: higher-frequency spectrum requires denser deployment for consistent coverage, and denser deployment on macro networks means more amendments and more sites.
Management has said 2026 is the trough. Both Hillabrant and Patel stated on consecutive calls that 2026 marks the low point for organic growth, citing contracted visibility through master lease agreements, AT&T's newly acquired 600 MHz spectrum requiring new radios and antennas rather than software unlocks, and the spectrum pipeline.611
Contracted visibility is improving within the year. More than 90% of 2026 organic growth excluding Sprint and DISH effects was contracted by the end of the second quarter, up from about 80% at the start of the year.2
The case that it does not.
Core leasing activity has weakened, and the guidance masks it. This is the most important number in the story and it is easy to miss. In full-year 2025, core leasing activity contributed $118 million, or 3.0% of prior-period billings. The 2026 outlook implies $65 million, or 1.8%.62 Escalators — which require no customer decision at all — now contribute more growth than new leasing does.
Part of that decline is the removal of DISH, whose roughly $50 million contribution to 2025 organic growth Patel described as "all contractual, not really activity driven."6 But that is the point: a meaningful share of what looked like leasing demand was a contractual ramp from a customer that has since gone bankrupt.
Carrier behavior is softening, by management's own description. Services revenue guidance was cut $20 million in July 2026, and Hillabrant attributed the pullback across all three mobile network operators to "leadership and strategy changes" at those companies and a broader focus on cost reduction.11 He also noted the industry is late in a decade-long 5G coverage deployment cycle.6
The AT&T renewal is a scheduled negotiation with real stakes. The concentration of AT&T's contract expiries in 2028, against a three-year weighted-average remaining term, gives Crown Castle's largest-by-renewal customer a defined moment of leverage.7 Nothing in the disclosure suggests distress; everything in it suggests a negotiation the company cannot avoid.
Leverage is a choice that constrains everything else. Operating at 6.3x with a negative outlook from Moody's means the company's excess cash has a claim on it before shareholders do.723 It also means Crown Castle enters any future downturn, or any adverse renewal, with less cushion than its principal peer.
The DISH receivable is an accounting and legal overhang, not an asset. Crown Castle asserts DISH owes in excess of $3.5 billion under the terminated master lease agreement.5 It has been appointed to the unsecured creditors' committee following DISH's Chapter 11 filing at the end of June 2026, and is pursuing both a court claim and a share of the $2.4 billion escrow the FCC required as a condition of the EchoStar spectrum sales to AT&T and SpaceX.1132
The complications are material and management has acknowledged them. DISH is arguing that the bankruptcy code's cap on lease rejection damages applies to Crown Castle's claim; Crown Castle disputes this.11 The escrow prioritizes smaller vendor claims before tower companies. The number of competing claimants is unknown, and Hillabrant declined to estimate recovery, saying it was "a little premature."11 Meanwhile DISH's abandoned equipment sits on Crown Castle's towers, with ownership unresolved and removal not performed.11
No revenue from DISH is in the 2026 outlook.5 Any recovery would be a windfall of uncertain size and timing. Treating it as a valuation input would be a mistake.
The edge data center story deserves scepticism proportional to the fiber record. Management describes trials with edge providers, targeting deployments below roughly 0.2 megawatts, monetizing existing power, space and backhaul without new capital.11 Patel emphasized that available site power runs from tens to low hundreds of kilowatts and that not all sites even have shelters.11
If it works, it is incremental revenue on a sunk asset — genuinely attractive. But this is a trial, not a business. Crown Castle's record of converting a plausible infrastructure adjacency into returns is the fiber record, and the appropriate posture is to require revenue disclosure before assigning value. Certification of an opportunity is not commercialization of one.
No international optionality, by choice. The 2004 decision still binds. Where peers can redeploy capital toward higher-growth geographies, Crown Castle's only levers are U.S. leasing, cost reduction, land purchases, buybacks and debt repayment.
Where the balance sits. The strongest bull argument is not growth; it is that a simplified, cash-generative asset with 98–99% retention throws off a large and predictable amount of cash, and that the market's price already reflects considerable pessimism — the shares closed the second quarter of 2026 at $75.73, down from $98.02 a year earlier, with market capitalization of $32.2 billion.7
The strongest bear argument is that the fixed-cost structure that produces high incremental margins also produces high incremental losses, that the customer base has structurally fewer members than it did five years ago, and that management is asking investors to underwrite an acceleration that has not yet appeared in core leasing.
XIII. Playbook: Lessons from Crown Castle
1. An adjacency is not a moat extension unless the moat's mechanism travels with it. Crown Castle's tower advantage stemmed from a specific combination: scarce municipal zoning approvals, high switching costs for installed tenant equipment, and shared infrastructure across competing carriers. Small cells shared the label of telecom infrastructure, but possessed none of those three structural advantages. Before allocating capital to an adjacent market, the critical test is whether the underlying economic protections of the core business actually apply to the new asset.
2. Operating leverage is a symmetric instrument. The same fixed-cost structure that allows a third tenant's rent to flow almost entirely to operating profit ensures that a departing tenant takes nearly all of its revenue straight out of earnings. Crown Castle's 2025 results—where nearly the entire top-line site rental decline passed directly into reduced Adjusted EBITDA—provide a clear demonstration. Any business valued for high incremental margins must also be stress-tested for how those margins perform during a revenue downturn.
3. Activists are most effective when the primary issue is capital allocation rather than operations. Elliott Management's core contribution was not operational instruction, but demanding a return-on-invested-capital standard, tying executive compensation to that benchmark, and replacing executive storytelling with rigorous arithmetic. When a management team relies on a long-term strategic narrative to justify substandard returns, an outside shareholder with a significant financial stake provides an essential governance check.
4. Distribution policy is capital allocation policy. A real estate investment trust that treats dividend growth as an obligation rather than an output will eventually fund that commitment with leverage. Crown Castle increased its dividend throughout the fiber expansion, only to cut the payout by roughly a third when higher interest rates and weaker cash flows forced a balance-sheet reset. The takeaway is not that dividend payouts are inherently risky, but that a distribution tied to organic cash flow generation is durable, whereas a fixed growth target is a forecast dressed up as a commitment.
5. Evaluate the tenant renewal schedule rather than the average contract term. A weighted-average remaining lease term of five to six years appears reassuring on paper. However, the distribution beneath that average—where a single major carrier accounts for the vast majority of near-term contract expirations—is where commercial risk actually resides. Portfolio-wide averages frequently hide significant contract renewal cliffs.
6. When a board replaces an executive immediately after closing a deal, the timing serves as critical governance data. The decision to terminate Steven Moskowitz shortly after announcing the fiber divestiture demonstrates that corporate boards rarely state their internal strategic shifts explicitly. The timing and context of executive changes reveal board priorities far more clearly than formal press releases.
XIV. 1–3 Primary KPIs That Matter
Three key metrics contain nearly all the signal regarding whether Crown Castle's underlying business is improving; all other operational data points are downstream.
1. Core leasing activity within Organic Contribution to Site Rental Billings. Not headline organic growth, but the core leasing line specifically. Headline organic growth blends three distinct drivers: contractual escalators that require no customer action, lumpy non-recurring billings, and core leasing activity—the sole component measuring whether carriers are actively adding and amending equipment on Crown Castle's towers.
Crown Castle discloses this component explicitly each quarter, both as a dollar amount and as a percentage of prior-period billings.2 The deceleration from 3.0% in 2025 to a guided 1.8% in 2026 represents the clearest indicator of current carrier demand.62 If management's assertion that 2026 marks the operational trough is correct, this metric must inflect first. If core leasing fails to recover while escalators keep headline growth respectable, the turnaround thesis falls apart.
2. Average tenants per tower. This metric serves as the purest expression of operating leverage in the tower business, determining whether returns on the 2007-and-later asset cohort ever converge toward the performance of older legacy sites.7
Disclosed in quarterly supplements and annual filings, average tenancy per tower has recently trended downward. Tracking this metric on an organic basis—excluding portfolio acquisitions—reveals whether the yield gap between pre-2006 and post-2006 tower vintages is narrowing.
3. AFFO per share. Adjusted funds from operations (AFFO) per share is the REIT benchmark for cash available to fund dividends, debt reduction, and share buybacks, and it is a metric Crown Castle has elevated to 40% of its long-term executive incentive mix.30
However, AFFO per share can grow through three distinct mechanisms: operational expansion, interest expense reduction, and share count reduction. In 2026, growth is driven overwhelmingly by the latter two balance-sheet adjustments.11 The key question for future years is whether the core business can drive per-share cash flow once balance-sheet arithmetic is exhausted.
A useful analytical discipline is to evaluate AFFO per share alongside core leasing activity. When both metrics expand together, the core operating business is strengthening. If AFFO per share rises while core leasing declines, growth reflects debt refinancing and stock repurchases—a constructive financial move, but fundamentally distinct from commercial expansion.
XV. Recent News & Catalyst Watch
As of September 1, 2026, five primary catalysts will determine Crown Castle's trajectory over the next several quarters.
The DISH bankruptcy process. This represents the largest discrete swing factor. Escrow funding remains tied to the closing of EchoStar's spectrum sale to AT&T, and the bankruptcy claims hierarchy places smaller vendors ahead of infrastructure providers.11 Crown Castle believes that it and American Tower represent the two largest claimants.11 Key factors to monitor include court rulings on the applicability of the statutory lease damages cap, the final size of the claimant pool, and potential settlement terms. Management has cautioned that resolving these claims could take a year or longer.6
Whether core leasing inflects. On its July 2026 earnings call, management outlined a three-horizon recovery: near-term visibility secured through contracted master lease agreements, medium-term network expansion driven by AT&T's 600 MHz spectrum deployment, and longer-term capacity needs tied to the FCC's proposed 800 megahertz auction pipeline.11 Near-term visibility is already reflected in financial guidance. The medium-term driver—deploying 600 MHz spectrum via physical low-band antennas and radios rather than software upgrades—represents the first verifiable test of carrier demand.6
Edge infrastructure trials. Management has stated it will share additional updates as trials progress, framing the primary operational constraint around site power delivery rather than capital availability.11 The key disclosure metric to track is whether edge revenue begins appearing inside core leasing activity, as Chief Financial Officer Sunit Patel indicated it would.11 Until it generates measurable contribution in reported billings, edge infrastructure remains a narrative rather than a financial driver.
Capital allocation after the buyback. Crown Castle fully exhausted its $1 billion share repurchase authorization during the second quarter of 2026.11 With net leverage hovering in the upper half of its target range and a negative rating outlook from Moody's outstanding, any future share buybacks will compete directly with debt reduction. Investors should watch whether the board authorizes a new repurchase program and what leverage thresholds it establishes.
Cost execution. The 2026 restructuring program targets $65 million in annualized run-rate savings, while management has guided to approximately 200 basis points of Adjusted EBITDA margin expansion over the next year, driven by ground lease buyouts and systems streamlining.116 This represents the most controllable element of the corporate strategy and serves as a direct test of the new executive team's operational execution. Delivering that level of margin expansion on a contracting revenue base would demonstrate structural progress, whereas falling short in the absence of external shocks would undermine credibility.
A final operational item warrants monitoring: the economic return of the ground lease buyout program. Management has committed to increasing land purchase outlays over the coming years at returns "well above our cost of capital," while acknowledging the company should be able to "do better than what the company has done in the past" in acquiring underlying site real estate.11 That statement acknowledges that a high-confidence, low-risk capital deployment initiative was previously underutilized—a commitment that investors should verify against reported cash yields rather than executive assertions.
XVI. Outro & Key Takeaways
Crown Castle's arc is not a story about tower infrastructure failing. The core towers worked. An annual retention rate of 98% to 99%, contractual rent escalators, and site rental gross margins in the mid-70% range fulfilled what the founders envisioned in 1994, with the pre-2006 tower cohort still generating a 19% cash yield more than two decades later.57
Instead, the arc demonstrates what happens when a company attempts to force growth onto a mature core business. For roughly a decade, Crown Castle bought adjacent infrastructure and labeled it strategy. The financial cost of that effort is measurable with unusual clarity: a $5.0 billion goodwill impairment, a $1.6 billion loss on disposal, a 32% dividend reduction, five leadership transitions in less than two years, and an asset portfolio sold for $8.5 billion after absorbing an estimated $16 billion to $19 billion in capital.22521
The business that emerged on May 1, 2026, is smaller, simpler, and more transparent. Crown Castle now operates roughly 40,000 towers in the world's most lucrative wireless market, with no international operations to manage, no secondary segment to absorb losses, and executive compensation tied directly to cash flow per share and return on invested capital.
Yet it remains a company burdened by $17.1 billion in net debt against a $32 billion market capitalization, reliant on three carrier customers for 90% of its revenue, facing a deceleration in its primary organic growth driver, and pursuing a $3.5 billion claim in bankruptcy court against DISH Network.75
Both realities exist simultaneously. The tension between them defines the investment case, which will be determined not by executive messaging but by two disclosed metrics: whether core leasing activity reaccelerates and whether average tenancy per tower stabilizes.
The founders' original premise was that physical tower real estate was valuable precisely because carriers needed the coverage but avoided owning the steel. Thirty-two years later, Crown Castle's multi-billion-dollar fiber detour proved that this economic moat does not automatically extend to adjacent digital assets. Whether a simplified pure-play operator can now generate sustainable compounding from its core tower footprint remains the final unresolved chapter.
References
-
Crown Castle Announces Closing of Sale of Fiber and Small Cell Businesses and Updates Full Year 2026 Outlook — Form 8-K Exhibit 99.1, SEC EDGAR, 2026-05-01 ↩↩↩↩
-
Crown Castle Reports Second Quarter 2026 Results and Updates Outlook for Full Year 2026 — Form 8-K Exhibit 99.1, SEC EDGAR, 2026-07-22 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Elliott Management Recommends Changes at Crown Castle ("Reclaiming the Crown") — Elliott Investment Management via PR Newswire, 2020-07-06 ↩↩↩↩↩↩↩
-
Crown Castle Inc. Annual Report on Form 10-K for the year ended December 31, 2025 — SEC EDGAR, 2026-02-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Crown Castle Reports Fourth Quarter and Full Year 2025 Results and Provides Outlook for Full Year 2026 — Form 8-K Exhibit 99.1, SEC EDGAR, 2026-02-04 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Crown Castle Inc. Second Quarter 2026 Supplemental Information Package — Form 8-K Exhibit 99.2, SEC EDGAR, 2026-07-22 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Crown Castle Inc. Founder Ted B. Miller Leads Slate of Four Highly Qualified Directors for Board of Crown Castle Inc. — Boots Capital Management via PR Newswire, 2024-02 ↩
-
Crown Castle International Announces Sale of UK Subsidiary for $2.0 Billion — Form 8-K Exhibit 99.1, SEC EDGAR, 2004-06-28 ↩
-
Crown Castle International Completes Sale of UK Subsidiary — Form 8-K Exhibit 99.2, SEC EDGAR, 2004-08-31 ↩↩
-
Crown Castle Q2 2026 Earnings Call Transcript — Investing.com, 2026-07-22 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Crown Castle International to Acquire Global Signal; Creates Premier Tower Company — Form 8-K Exhibit 99.1, SEC EDGAR, 2006-10-06 ↩
-
Crown Castle International Completes Acquisition of Global Signal — Form 8-K Exhibit 99.1, SEC EDGAR, 2007-01-12 ↩↩↩
-
Crown Castle International Corp. Annual Report on Form 10-K for the year ended December 31, 2015 — SEC EDGAR, 2016 ↩↩↩↩↩↩↩↩
-
Crown Castle International Announces First Quarter 2008 Results and CEO and CFO Succession Plan — Form 8-K Exhibit 99.1, SEC EDGAR, 2008-04-23 ↩↩↩
-
Crown Castle Commences Operating as a REIT Effective January 1, 2014 — GlobeNewswire, 2014-01-06 ↩
-
Crown Castle Announces Agreement to Acquire NextG Networks — Form 8-K Exhibit 99.1, SEC EDGAR, 2011-12-16 ↩↩
-
Crown Castle Announces Agreement to Acquire Sunesys — Form 8-K Exhibit 99.1, SEC EDGAR, 2015-04-30 ↩
-
Crown Castle International Corp. Annual Report on Form 10-K for the year ended December 31, 2017 — SEC EDGAR, 2018 ↩↩↩↩
-
Crown Castle Announces Agreement to Acquire Wilcon — Form 8-K Exhibit 99.1, SEC EDGAR, 2017-04-17 ↩
-
Elliott Sends Letter to the Board of Crown Castle Inc. — Elliott Investment Management via PR Newswire, 2023-11-27 ↩↩↩↩↩↩
-
Crown Castle Announces Agreement to Sell Fiber Segment to EQT and Zayo, Reports Fourth Quarter and Full Year 2024 Results, and Provides Outlook for Full Year 2025 — Form 8-K Exhibit 99.1, SEC EDGAR, 2025-03-13 ↩↩↩↩↩↩↩↩↩↩
-
Moody's changes Crown Castle's outlook to negative, affirms Baa3 ratings — Investing.com, 2025-03-17 ↩↩
-
American Tower Q2 2026 slides: data centers drive guidance raise — Investing.com, 2026-07-28 ↩↩↩
-
Crown Castle Appoints New Chief Financial Officer — Form 8-K Exhibit 99.1, SEC EDGAR, 2016-03-09 ↩↩
-
Crown Castle Announces CEO Transition — Form 8-K Exhibit 99.1, SEC EDGAR, 2023-12-07 ↩↩↩
-
Crown Castle Wins Proxy Contest With Boots Capital — Paul, Weiss, Rifkind, Wharton & Garrison LLP, 2024 ↩↩
-
Crown Castle Appoints Tower Industry Veteran Steven J. Moskowitz as President and Chief Executive Officer — Form 8-K, SEC EDGAR, 2024-04-10 ↩↩
-
Crown Castle Announces CEO Transition (Termination of Steven Moskowitz; Dan Schlanger Named Interim CEO) — Form 8-K Exhibit 99.1, SEC EDGAR, 2025-03-24 ↩↩
-
Crown Castle Inc. Definitive Proxy Statement on Schedule 14A — SEC EDGAR, 2026-04-06 ↩↩↩↩↩↩↩↩
-
Crown Castle Appoints Christian Hillabrant as President and Chief Executive Officer — Form 8-K Exhibit 99.1, SEC EDGAR, 2025-08-04 ↩↩
-
EchoStar's satellite TV and wireless subsidiaries file for bankruptcy — SpaceNews, 2026-07-01 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube