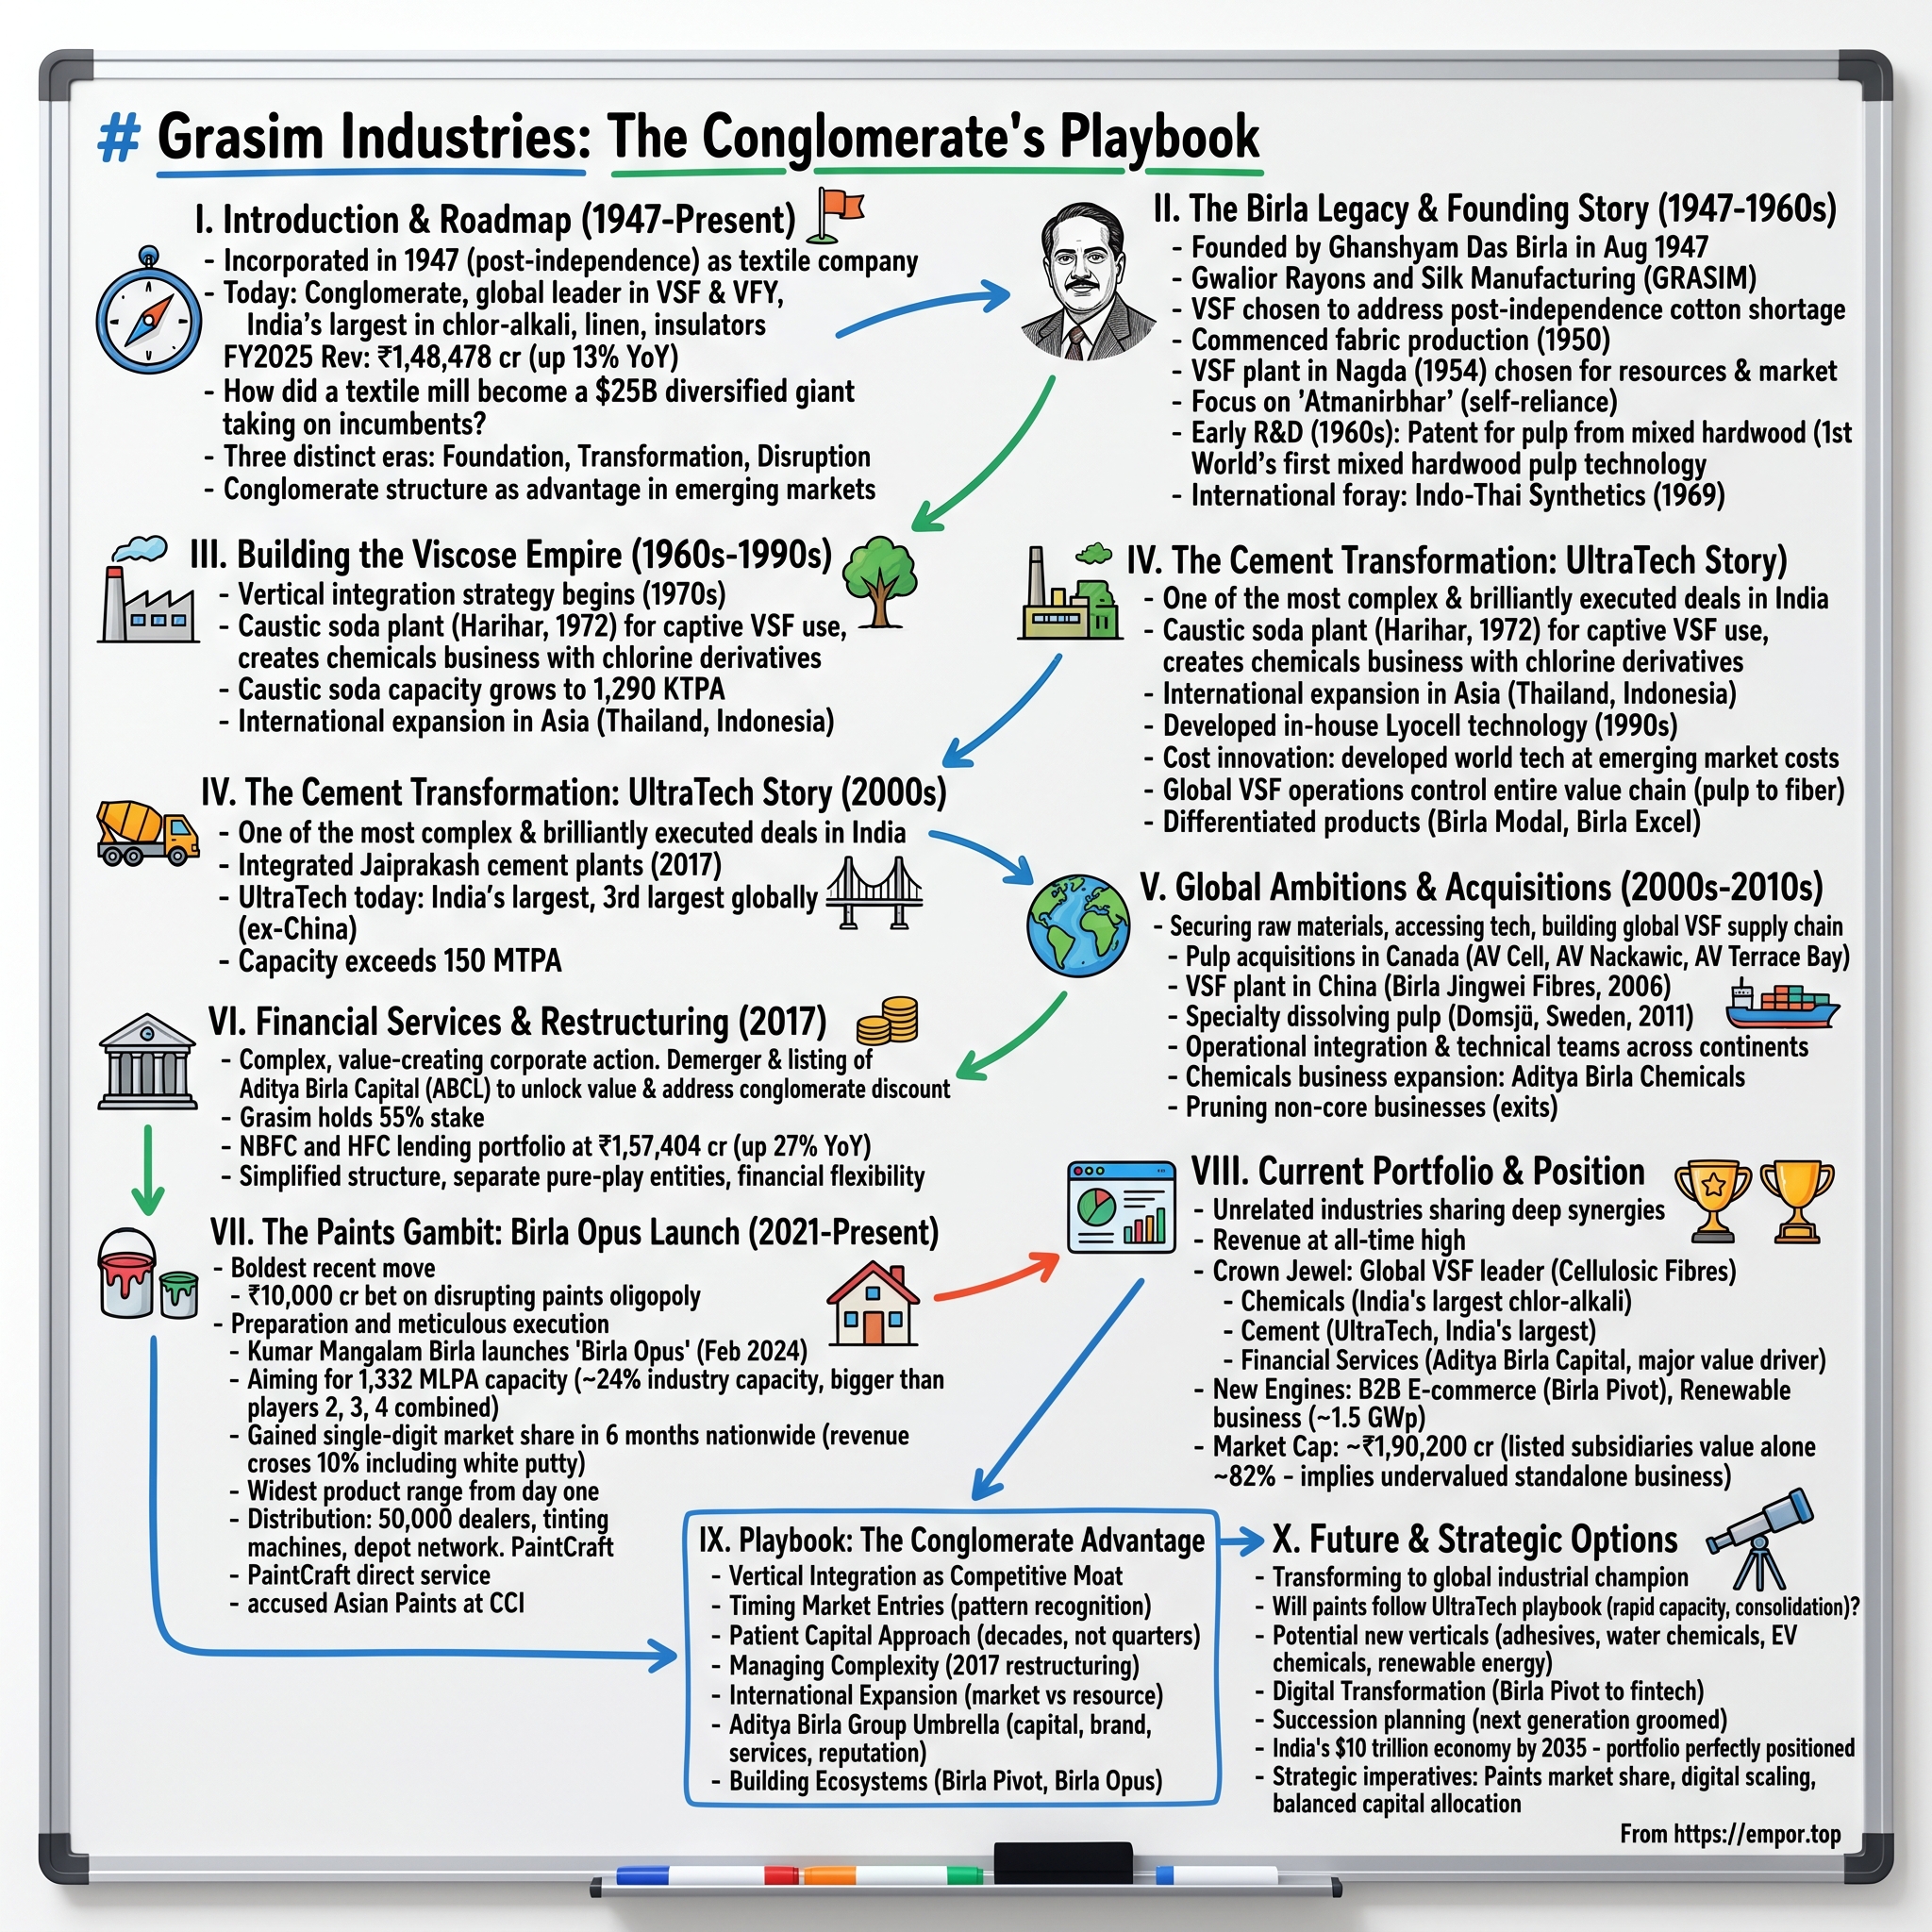
Grasim Industries: The Conglomerate's Playbook
I. Introduction & Episode Roadmap
On the morning of February 22, 2024, Kumar Mangalam Birla stood on a stage in New Delhi and launched an aggressive, direct challenge against an incumbent consumer franchise that had dominated the market for half a century. "No paints company has ever started with factories, operations, products and services at this scale," he said, as the Aditya Birla Group unveiled Birla Opus.1 Three manufacturing plants were commissioned that day, three more were underway, and the company announced plans to add roughly 40% to the installed capacity of India's organised decorative paints industry in a single stroke.2
The entity funding that expansion was not a dedicated paints maker. It was Grasim Industries, a company incorporated on August 25, 1947, ten days after Indian independence, as Gwalior Rayon Silk Manufacturing (Weaving) Company.3 For decades, Grasim operated primarily as a commodity processor, producing viscose staple fibre from wood pulp and caustic soda from salt. Over time, it also became the controlling shareholder of India's largest cement producer and a major financial services conglomerate. Today, it operates businesses directly while functioning as an investment holding company, and that dual identity sits at the heart of the story.
Consider what a single share of Grasim represents in September 2026. It provides exposure to roughly 56% of UltraTech Cement, a producer that crossed 200 million tonnes per annum of grey cement capacity in April 2026.[^4]4 It provides exposure to a little over half of Aditya Birla Capital, which Grasim topped up with ₹2,880 crore in FY26 specifically to maintain its stake above 50%.5 And it provides exposure to the standalone operating businesses: cellulosic fibres, chlor-alkali chemicals, textiles, insulators, renewables, the Birla Pivot B2B e-commerce platform, and Birla Opus.6
The stock closed at about ₹3,150 on September 24, 2026.7 With roughly 68 crore shares outstanding—implied by the ₹681 crore total outlay for its ₹10-per-share FY26 dividend—Grasim carries a market capitalization of a little over ₹2.1 lakh crore, or roughly $25 billion.8 An analysis published in January 2026 estimated that listed investments accounted for about 84% of Grasim's enterprise value, leaving the stock trading at roughly a 44% discount to the net asset value of its parts.9 In practice, public markets value Grasim primarily as a vehicle for cement, attributing modest value to its standalone operations.
That disparity creates the central tension of the story. Grasim's leadership views the company as an active capital allocator, recycling cash flow from mature commodity assets into emerging growth sectors. Public equity markets, by contrast, treat it as a holding company prone to capital misallocation. Both interpretations find support in the historical record. UltraTech stands as one of the most successful capital allocation cases in modern Indian corporate history. Vodafone Idea, which Grasim absorbed through a contentious 2017 merger, remains one of the costliest.
The paints venture sits squarely between those two precedents. If Birla Opus achieves scale and sustained profitability, it will demonstrate that an industrial commodity conglomerate can build an insurgent consumer brand from scratch. If it falls short, it will reinforce the governance and allocation concerns that justify a persistent holding company discount.
The narrative unfolds in twelve subsequent parts. Part one traces the swadeshi founding and the early viscose breakthroughs that established Grasim's technical foundation. Part two covers the contested takeover of Larsen & Toubro's cement division and the formation of UltraTech. Part three evaluates the standalone cash generators—viscose fibre and chlor-alkali—alongside the mixed record of Grasim's overseas pulp investments. Part four details the 2016–2017 Aditya Birla Nuvo merger and the institutional investor opposition that accompanied it. Part five analyzes the operational offensive in decorative paints. Subsequent sections examine Birla Pivot, corporate financial architecture, governance, structural risks, strategic takeaways, and the core bull and bear cases.
To understand why Grasim believes it can build at this scale, the story begins where it first learned to manufacture: in a small town in central India, without foreign technology licences, in a newly independent nation that had just lost its primary cotton-growing regions.
 Subscribe on LinkedIn
II. The Swadeshi Roots & The Viscose Foundation (1947–1980s)
A country without its cotton
Partition in 1947 did more than redraw political boundaries. It split the subcontinent's textile economy, leaving much of the premier cotton-growing acreage in what became Pakistan while the spinning and weaving mills remained in India. For a newly independent nation trying to clothe several hundred million people, raw fibre was an urgent strategic challenge, not merely a commercial one.
Ghanshyam Das Birla, an associate of Mahatma Gandhi and a central figure in India's early industrial expansion, saw an answer in viscose staple fibre, or VSF. Viscose is regenerated cellulose, sharing the same molecular base as cotton but extracted from wood pulp. The process dissolves purified wood pulp using caustic soda and carbon disulphide, extrudes the resulting viscous solution through spinnerets into an acid bath, and regenerates it into solid filaments. The resulting staple can be blended, spun, and woven much like cotton. For a country short on domestic cotton acreage but endowed with forests, developing viscose represented import substitution grounded in direct strategic need.
The operating footprint began modestly. Grasim's initial weaving unit started producing fabric in Gwalior in 1950.3 The Maharaja of Gwalior allocated land at Nagda, along the Chambal river in Madhya Pradesh, in 1951.10 By 1954, Grasim had commissioned a VSF facility there with a capacity of 15 tonnes per day.3 Against today's global viscose industry, that output is negligible. For India in the 1950s, however, it demonstrated that domestic industry could manufacture commercial textile fibres without relying on imported cotton.
Building what nobody would sell
Securing feedstock proved to be the more complex hurdle. Viscose manufacturing requires dissolving-grade pulp, a highly purified cellulose that was then produced almost exclusively from softwood forests in temperate climates. India had bamboo and mixed tropical hardwoods, which international suppliers and chemical engineers generally regarded as unsuitable for rayon-grade pulp.
Grasim chose to engineer its own solution. It commissioned a one-tonne-per-day pulp pilot plant at Nagda in 1956 and established the Birla Research Institute for Applied Sciences there in 1965.310 In 1963, its Mavoor facility in Kerala began producing what the group describes as the world's first bamboo-based rayon-grade pulp.3 In 1972, the company commissioned what it calls the world's first mixed hardwood pulp plant at Harihar in Karnataka, using process technology developed and patented by its own research institute.3
That technological self-reliance shaped Grasim's corporate identity. Operating in a foreign-exchange-constrained economy, the company developed its own chemical processing techniques because global intellectual property was either inaccessible or incompatible with domestic raw materials. That technical capability established an in-house engineering culture that resurfaced decades later when Grasim initiated proprietary research into lyocell fibres in 1993.10
Caustic soda: the first integration move
The year the Harihar pulp unit opened, Grasim built an on-site caustic soda plant with an annual capacity of 33,000 tonnes to secure its own chemical requirements.3 The rationale was operational continuity. Viscose production consumes substantial volumes of caustic soda, and depending on erratic third-party merchant supply in 1970s India frequently exposed chemical plants to costly shutdowns.
That captive unit established an operating playbook Grasim would follow for the next half-century: manufacture a critical input to insulate the core business, expand production until it achieves standalone scale and a cost advantage, and then sell the surplus into the open merchant market. The chemicals business that originated from that captive plant now generates more than ₹2,600 crore in quarterly revenue.6 What started as a defensive backward-integration measure evolved into an independent profit engine.
Going abroad before India opened up
Grasim also initiated international operations decades ahead of its domestic peers. Thai Rayon was incorporated in Bangkok in 1974, which the group describes as the first foreign manufacturing facility established by an Indian company, and commenced commercial VSF production in 1976.3 Under Aditya Vikram Birla, G.D. Birla's grandson, the wider group constructed a network of fibre and spinning assets across Southeast Asia well before India dismantled industrial licensing and eased capital controls in 1991.
That early cross-border exposure proved consequential for Grasim's long-term capital allocation. It provided management with practical operating experience across international commodity cycles and established a willingness to commit balance-sheet capital abroad—an appetite that later drove dissolving-pulp acquisitions in Canada and Sweden. As section IV explores, however, deploying capital into overseas resource assets yielded an uneven operating record.
What the origin story says about today
Grasim's founding decades instilled two enduring institutional habits. The first is a conviction that vertical integration and large-scale manufacturing capacity provide the most reliable defence against cyclical volatility. The second is an established practice of using the cash flow from mature, steady industrial assets to finance the next capital-intensive venture. Viscose cash funded caustic soda. Viscose and caustic soda cash funded cement. Cement subsequently expanded into UltraTech. Today, cement dividends and chemical cash flows are underwriting the rollout of Birla Opus paints.
For equity investors, Grasim's industrial history provides essential context. It illuminates why corporate leadership routinely pursues integrated scale and operational control when entering a new vertical, and why public markets price in a holding-company discount whenever an established cash generator begins committing substantial capital to an unproven enterprise. The first time that conglomerate playbook created an industry titan was in cement, and it originated with an unsolicited corporate raid that initially had nothing to do with Grasim.
III. The Masterstroke: Carving Out UltraTech Cement (2001–2010s)
A modest cement business
Grasim entered the cement sector in 1985 with Vikram Cement at Jawad in Madhya Pradesh, commissioning a plant with an initial capacity of just 0.5 million tonnes per annum.3 Cement offered a logical deployment channel for the cash flows generated by the viscose business: it required heavy capital, rewarded operational discipline, and served an economy embarking on decades of infrastructure, commercial, and residential building.
By the late 1990s, Grasim had built a meaningful presence in cement through plant expansions and regional acquisitions, yet India's wider industry remained highly fragmented. In cement, scale and geographic reach dictate unit economics. Because the material carries a low value-to-weight ratio, it rarely travels economically more than a few hundred kilometres by road. A producer needed regionally distributed kilns and dense logistics networks to compete on a national level. Whichever manufacturer could assemble a nationwide manufacturing footprint stood to capture an enduring cost advantage.
The L&T gambit
In 2001, Reliance Industries accumulated a stake of roughly 10% in Larsen & Toubro, India's flagship engineering company, which also housed one of the country's premier cement businesses. L&T's management, led by A.M. Naik, opposed an unsolicited takeover. Then, on November 18, 2001, Reliance abruptly sold its entire 10.05% stake to Grasim for about ₹766 crore, securing a price well above prevailing market levels.11
The transaction altered the corporate landscape. Grasim had no strategic ambition in engineering or infrastructure construction. Kumar Mangalam Birla wanted L&T's cement division, and acquiring equity in the parent company offered the only available entry point. Grasim subsequently increased its holding to around 15%, and in October 2002 announced an open offer for an additional 20% at ₹190 per share, which the securities regulator directed it to put on hold while reviewing the transaction.12
L&T's leadership and its employees' welfare trust mounted sustained resistance. An unsolicited takeover of the country's leading engineering enterprise by an industrial family group carried substantial political and reputational friction. The resulting standoff lasted more than a year.
The settlement that created UltraTech
The resolution, agreed in 2003 and executed in 2004, delivered a structured compromise. L&T demerged its cement operations into a newly created entity, UltraTech CemCo. L&T shareholders received four CemCo shares for every ten L&T shares they held.13 Under the agreement, Grasim acquired an 8.5% stake directly from L&T, launched an open offer for another 30% of UltraTech at ₹342.60 per share, and transferred its holding in the residual L&T engineering business to the L&T Employees Welfare Foundation.1213
The open offer closed in June 2004 to what UltraTech described as an overwhelming response.14 UltraTech CemCo entered the market with roughly 17 million tonnes of annual capacity—representing about 10.5% of the Indian cement industry—anchored by major manufacturing plants at Pipavav, Chandrapur, Tadipatri, and Hirmi.13
The transaction satisfied the core strategic goals of both sides. L&T retained its independence and concentrated on engineering and construction, an operational focus that generated substantial shareholder value over the following two decades. Grasim secured an established nationwide cement network without engaging in a costly bidding war. Both parties achieved their primary objective through a negotiated separation that stands as one of the most consequential corporate settlements in modern Indian business history.
Folding everything into one vehicle
For several years after the deal, Grasim ran two parallel cement operations: its legacy in-house division and UltraTech. In November 2009, Grasim moved to unify them. It announced that its standalone cement assets, carved out into a subsidiary called Samruddhi Cement, would merge into UltraTech at a swap ratio of four UltraTech shares for every seven Samruddhi shares, with the amalgamation taking effect on July 1, 2010.15
The combined company commanded 48.8 million tonnes of grey cement capacity across 22 manufacturing facilities, controlling roughly 20% of the domestic market. The consolidation established UltraTech as India's largest cement producer and, by its own account, the tenth largest in the world.15 Grasim emerged with a 60.3% controlling stake in the expanded entity.15 From that point forward, Grasim held its cement business entirely through an equity stake in a listed subsidiary, cementing its identity as part operating company and part holding company.
Rolling up the kilns
The next fifteen years brought a continuous consolidation campaign. In June 2017, UltraTech completed the acquisition of Jaiprakash Associates' cement assets for ₹16,189 crore, absorbing roughly 21.2 million tonnes of capacity from an infrastructure conglomerate under financial strain.[^17] In October 2019, it integrated Century Textiles' cement business through a court-approved arrangement where Century shareholders received one UltraTech share for every eight Century shares held.16
The pace of consolidation accelerated after 2023. In November 2023, UltraTech agreed to acquire Kesoram Industries' cement business—adding 10.75 million tonnes of capacity across Sedam in Karnataka and Basantnagar in Telangana—in exchange for one UltraTech share for every 52 Kesoram shares.17 That transfer became effective on March 1, 2025.18 In July 2024, UltraTech agreed to purchase a 32.72% promoter stake in India Cements, a long-established southern competitor, a transaction that culminated in operating control.19
Through those roll-ups and ongoing organic expansions, UltraTech's grey cement capacity reached 205.5 million tonnes per annum by the end of FY26, alongside a corporate roadmap targeting more than 240 million tonnes by March 2028.8 Volume growth remained steady: in the first quarter of FY27, UltraTech sold 41.3 million tonnes of cement, up 12% from the prior year.6
Did the roll-up destroy or create value?
The constructive case for UltraTech's roll-up strategy argues that the company acquired kilns at valuations well below greenfield replacement costs, using national volume to become the industry's low-cost producer. Operating results support that premise. UltraTech's operating EBITDA per tonne reached a record ₹1,253 in the fourth quarter of FY26, which management cited as evidence that logistics optimization, procurement scale, and an expanding share of renewable power were lowering unit costs.8 In a commodity market where competitors manufacture a standardized grey powder, sustained unit-margin leadership provides the clearest evidence of an operational cost advantage.
Countervailing evidence exists alongside those gains. Several assets were purchased from distressed sellers and required years of turnaround capital. The Jaiprakash plants, for example, required extensive equipment refurbishments, logistics redesigns, and dealer-network restorations before their output generated returns comparable to UltraTech's legacy operations. In addition, cement remains inherently cyclical, with swings in fuel costs from imported thermal coal and petcoke capable of compressing operating margins from quarter to quarter.
The industry's most significant structural change arrived in September 2022, when the Adani Group completed its acquisition of Holcim's controlling stakes in Ambuja Cements and ACC for approximately $6.5 billion including open offers, immediately becoming India's second-largest cement manufacturer.20 That acquisition converted a fragmented landscape into an aggressive two-player race for national scale. When two well-capitalized groups simultaneously add supply, returns on new capacity can compress for extended periods. In that context, some of UltraTech's recent transactions, including the acquisition of India Cements, functioned partly as defensive moves to block rival consolidation in regional markets.
The structure also affects who captures the financial reward. Direct shareholders in UltraTech participate fully in its operating cash flows and margin resilience. Grasim's shareholders, by contrast, capture that performance indirectly, filtered through the dividend distribution set by UltraTech's board and discounted by public equity markets. Every major asset UltraTech adds expands Grasim's underlying value, but it also increases Grasim's reliance on listed investments, reinforcing the conglomerate discount applied to the parent stock.
The measured conclusion is that UltraTech possesses a durable cost moat rather than pricing power. Scale protects its operating margins relative to peers, but it cannot protect the wider market from supply additions that outpace construction demand. The decisive operational metric testing that moat will be UltraTech's EBITDA per tonne relative to the Adani platforms across future capacity cycles.
For Grasim's investors, UltraTech remains both the primary asset on the balance sheet and the core source of the holding-company puzzle. It provides the dividend stream that underwrites corporate expansions, including a ₹3,970 crore payout in the fourth quarter of FY26 according to one report.21 Before examining how Grasim deploys that cash into new growth verticals, the story turns to the legacy manufacturing divisions that continue to operate directly inside the standalone balance sheet.
IV. The Core Cash Engines: Viscose (VSF) & Chlor-Alkali Duopoly (1990s–Present)
Inside a fibre plant
A visit to a viscose plant begins with an unmistakable sensory impression: the sharp, sulphurous tang of carbon disulphide. Then comes the industrial scale: bales of white dissolving-grade pulp feeding into vats of caustic soda, temperature-controlled aging rooms where cellulose gradually transforms, and spinning machines extruding thousands of delicate filaments into an acid bath. While the underlying chemistry is more than a century old, the commercial economics governing the process remain complex and volatile.
Cellulosic fibres: dominant at home, a price-taker abroad
Grasim's cellulosic fibres division encompasses viscose staple fibre and cellulosic fashion yarn. Anchored by major manufacturing complexes at Nagda, Harihar, Kharach, and Vilayat, it operates as the dominant domestic producer of VSF in India while competing globally against established producers such as Austria's Lenzing and large-scale Chinese manufacturers.[^4]
Yet domestic dominance does not confer pricing power. Viscose competes directly against natural cotton on one side and synthetic polyester on the other. When bumper cotton harvests depress agricultural prices, spinning mills substitute away from viscose. When crude oil drops, synthetic polyester becomes cheaper to manufacture. At the same time, Chinese producers, who control the majority of global viscose capacity, effectively establish world market prices through their export flows. As a consequence, Grasim's domestic selling prices largely track an import-parity benchmark.
That dynamic injects sharp cyclicality into the business. In the first quarter of FY27, cellulosic staple fibre realizations rose to $1.81 per kilogram, up 19% from a year earlier. That recovery lifted segment revenue to ₹4,530 crore and nearly doubled operating EBITDA to ₹632 crore.6 Sales volumes, however, contracted 4% to 202,000 tonnes, dampened by scheduled plant maintenance and subdued downstream domestic demand.622 On the quarterly earnings call, management acknowledged this inherent cyclicality, noting that the sustainability of operating margins would depend on input costs and downstream demand.22
Grasim's strategic countermeasure has been an ongoing migration up the value chain. Specialty fibres—encompassing the consumer-facing Liva brand, lyocell (a cellulose fibre manufactured through a closed-loop solvent spinning process), and dyed and flame-retardant variants—rose to 27% of the product mix in the first quarter of FY27, compared with 21% a year earlier.23 To expand that capacity, Grasim is constructing a commercial lyocell facility with an initial phase of 55,000 tonnes per annum targeted for commissioning in mid-2027, alongside a second phase designed to double that output that remains under environmental review.423
Corporate history provides a cautionary benchmark for that transition. Grasim initiated in-house lyocell research in 1993 and commissioned a pilot plant at Nagda in 1999.103 More than twenty-five years later, commercial-scale lyocell remains an upcoming capital project rather than an established earnings driver. That extended timeline demonstrates that technical capability does not convert swiftly into commercial scale, and investors should view management's specialty-mix targets as operational milestones to be verified each quarter rather than as a structural fait accompli.
Chlor-alkali: the business of making two products at once
The chemicals business rests on an unbending electrochemical equation. Passing an electrical current through a purified brine solution splits salt water into caustic soda, chlorine, and hydrogen in a fixed ratio: every tonne of caustic soda produced simultaneously generates roughly 0.89 tonnes of chlorine. Because production is co-dependent, the industry evaluates unit economics through an electrochemical unit, or ECU, which bundles the net realizations of both co-products.
The operational friction arises because the two substances inhabit entirely different commercial markets. Liquid caustic soda is stable, easy to transport, and widely consumed across alumina refining, textiles, soaps, and paper manufacturing. Chlorine, by contrast, is hazardous, difficult to store in large quantities, and costly to transport over long distances. If a chemical manufacturer cannot consume or sell its chlorine output, it must either sell the gas at steep discounts or curtail caustic soda production entirely. In practice, the logistics of the hazardous byproduct can dictate the profitability of the primary chemical.
As India's largest chlor-alkali producer,[^4] Grasim addresses this structural constraint by consuming a growing share of chlorine internally. It converts the byproduct into higher-value downstream derivatives, including epoxy resins, chlorinated polyvinyl chloride (CPVC) for water piping, and epichlorohydrin (ECH), a key raw material for epoxy. A 50,000-tonne CPVC plant was commissioned in August 2026, while an adjacent 50,000-tonne ECH facility reached mechanical completion ahead of its scheduled startup in the second quarter of FY27. Through these downstream additions, management expects captive chlorine integration to reach approximately 68% by the end of FY27.2322
In the first quarter of FY27, the chemicals division generated ₹491 crore of EBITDA on ₹2,640 crore of revenue, supported by an ECU realization of ₹37,955 per tonne.6 Yet those headline returns reflect a delicate balance. In the fourth quarter of FY26, international caustic soda prices declined to $446 per tonne from $525 a year earlier, while specialty margins came under pressure from elevated ECH input costs.4 On the Q1 FY27 earnings call, management cautioned that second-quarter margins would face headwinds from higher-cost legacy inventory, feedstock price volatility stemming from conflict in the Persian Gulf, and new domestic caustic capacity entering the market.22
The analytical takeaway is that chlor-alkali is an operationally disciplined business, but not an insulated one. Grasim's manufacturing scale and on-site integration establish it as one of India's lowest-cost producers. Even so, expanding into downstream derivatives resolves the chlorine bottleneck without removing underlying exposure to industrial power costs or cyclical domestic supply additions by competitors.
The overseas pulp bet: when integration becomes a burden
A revealing chapter in Grasim's industrial evolution lies in an overseas resource strategy that corporate presentations rarely emphasize. Beginning in the late 1990s, the group acquired international pulp mills to secure dedicated feedstock for its viscose operations. It acquired the AV Cell pulp mill in Canada in 1998 and took a significant equity stake in Sweden's Domsjö Fabriker in 2011.10 In 2012, operating through AV Terrace Bay, Grasim agreed to acquire the Terrace Bay pulp mill in Ontario out of creditor protection for a modest cash payment and assumed liabilities, with plans to convert the facility to produce rayon-grade pulp for captive consumption.24
The rationale followed classic conglomerate doctrine: control the raw-material supply to insulate the core manufacturing engine. The operating reality proved considerably more difficult. On January 2, 2024, AV Terrace Bay placed its operations into what it termed a 'warm idle' due to adverse market conditions, halting production at a facility with 320,000 tonnes of annual northern bleached softwood kraft pulp capacity and affecting approximately 400 workers.[^27] More than two and a half years later, the mill remains offline, with prospective buyers reportedly evaluating the asset.
Further strain emerged in September 2026, when AV Group NB—the group's New Brunswick joint venture in which Grasim holds a 45% stake—announced that it would temporarily idle its Nackawic dissolving pulp mill from late October 2026.2526 The facility, which commands roughly 190,000 tonnes of annual dissolving pulp capacity and employs about 350 workers, cited persistent challenges stemming from weak market conditions and broader macroeconomic pressures.25
These operational halts provide significant disconfirming evidence against the universal benefits of vertical integration. When global pulp supplies are plentiful and market prices decline, operating high-cost captive assets in high-wage jurisdictions with extended rail logistics turns an intended supply moat into a heavy fixed-cost burden. The decisions to idle these plants indicate that group management itself concluded that purchasing pulp on the open merchant market was more economical than maintaining captive operations at those sites.
The calibrated verdict is that Grasim's vertical integration playbook succeeds when raw materials are scarce, geographically adjacent, and manufactured at low unit cost—as with captive chlor-alkali production supporting viscose at Nagda. It falters when the input is a globally traded commodity that specialized competitors produce more cheaply elsewhere. That distinction is directly relevant to Grasim's current trajectory, because the paints expansion is fundamentally an integrated play designed to link cement distribution networks, wall putty, and architectural coatings under a single corporate umbrella.
While these standalone industrial divisions generate dependable operating cash flow, they have rarely been the primary reason investors hold Grasim's shares. That interest centers on the corporate holding structure—an architecture that assumed its controversial modern form in a 2016 merger that institutional shareholders contested vigorously.
V. The Conglomerate Re-Engineering & The Holding Company Paradox (2016–2018)
An August announcement
On August 11, 2016, the boards of Aditya Birla Nuvo and Grasim approved a two-step corporate restructuring. Under the proposal, Aditya Birla Nuvo—a diversified holding entity with interests spanning telecommunications, financial services, fashion retail, and textiles—would first merge into Grasim. Subsequently, the financial services division would be demerged and listed separately as Aditya Birla Capital.27 Under the agreed swap ratio, Nuvo shareholders would receive three Grasim shares for every ten Nuvo shares held.27
The stated corporate rationale was structural simplification. Nuvo had long operated as a sprawling conglomerate trading at a steep holding-company discount, and management argued that combining the two balance sheets would create a larger, more resilient entity. Concurrently, the financial services arm would secure its own public listing and independent access to growth capital.
The proxy advisers push back
Institutional and minority shareholders saw the transaction in a very different light. Institutional Investor Advisory Services argued that the merger would dilute Grasim's minority shareholders by about 29% while helping the promoter family reach its target of holding 40%.28 The proxy advisory firm questioned why Grasim's shareholders should absorb direct exposure to financial services and telecom—sectors it characterized as capital-intensive and likely to remain cash-hungry—and recommended voting against the merger.2928
The central grievance centered on cross-subsidization. Grasim was a cash-generative industrial manufacturer supported by stable viscose and chlor-alkali earnings and a controlling stake in UltraTech. Nuvo, by contrast, brought a substantial equity holding in Idea Cellular just as the domestic telecom sector was entering the most punishing price war in its history following Reliance Jio's commercial launch in September 2016. Critics asked why Grasim's balance sheet should absorb that risk, and why the financial services division could not be demerged directly to Nuvo's own shareholders without routing the transaction through Grasim.30
Despite institutional objections, the merger was approved and became effective in 2017, with Aditya Birla Capital listing as a standalone company later that year.31 Yet the contested vote left an enduring impression, exposing a persistent gap in trust between the promoter group and public minority investors over corporate capital allocation.
The Idea problem becomes a Grasim problem
Those investor concerns were rapidly borne out by events. Idea Cellular merged with Vodafone India in 2018 to form Vodafone Idea, but the combined carrier quickly buckled as operating losses mounted under intense tariff competition. In the quarter ended September 2018, Grasim reported a consolidated net loss of ₹1,299.86 crore after recognizing an exceptional charge of ₹2,003 crore for the difference between the book value and fair value of its Vodafone Idea investment.32 Further balance-sheet support followed when Grasim participated in a 2019 Vodafone Idea rights issue.33
By September 2020, Business Standard reported that small Grasim shareholders were wary of any further investment in Vodafone Idea.33 The sentiment was unambiguous: minority investors did not want Grasim's balance sheet deployed as a financial rescue vehicle for group-level telecom ventures.
The episode stands as the most critical historical test of the proposition that Grasim allocates capital with consistent discipline. Where the UltraTech acquisition demonstrated that conglomerate resources could assemble a low-cost industry leader, the Nuvo-Idea transaction showed the vulnerabilities of the model. A balanced reading of the record suggests that the group excels at consolidating heavy industrial manufacturing sectors it already understands and at purchasing distressed operational assets at attractive valuations. Its record is markedly more troubled, however, when the conglomerate architecture is enlisted to support capital-draining ventures that are strategically vital to the group rather than accretive to Grasim itself.
How the market prices the structure
Since 2017, public equity markets have evaluated Grasim almost exclusively through a sum-of-the-parts framework: taking the market value of its listed holdings in UltraTech and Aditya Birla Capital, adding an estimated valuation for the standalone manufacturing businesses, and subtracting a holding-company discount. That discount has remained stubbornly wide, persisting at roughly 40% to 44% in recent estimates.921
Management has offered a consistent defense of the structure: the standalone chemical and fibre operations generate reliable cash flow, the UltraTech stake secures strategic control over India's premier building-materials platform, and Aditya Birla Capital provides exposure to long-term financial deepening. Grasim reinforced that posture in FY26 by investing ₹2,880 crore to maintain its stake in Aditya Birla Capital above 50%, with management reaffirming its intent to keep more than 50% in both UltraTech and Aditya Birla Capital.5
For equity investors, the trade-off is clear. Every rupee of parent cash flow committed to maintaining control of a listed subsidiary is a rupee not returned directly to Grasim's own shareholders, and the persistent holding-company discount reflects market skepticism that those capital commitments generate adequate standalone returns. In corporate finance, holding-company discounts typically narrow only when a parent entity credibly commits to pass-through dividend policies or corporate simplification. Grasim has chosen neither path. Instead, in 2021 it opted to do the reverse: committing balance-sheet capital to build an entirely new consumer business from the ground up.
VI. The ₹10,000 Crore Gambit: Birla Opus & The Decorative Paints War (2021–Present)
Why paints
Walk into a paint shop in any Indian town and the most important piece of equipment is not a can of paint. It is the tinting machine: a computerised dispenser that mixes base paint with colourants to produce thousands of shades on demand. Whoever controls the tinting machines on dealers' counters controls what the painter recommends and what the homeowner buys.
For decades, that counter belonged to Asian Paints. The incumbent built an entrenched distribution supply chain that delivered to retail dealers multiple times a day, used store-level data to forecast localized demand, and reinforced channel loyalty through credit terms, volume rebates, and dealer incentives including international travel. Berger Paints, Kansai Nerolac, and Akzo Nobel's Indian business followed behind. The industry expanded reliably while sustaining high operating margins—the kind of financial profile that prompts an industrial conglomerate with substantial balance-sheet capacity to seek entry.
Grasim announced its entry into decorative paints in 2021.10 At the February 2024 launch, it committed an upfront capital outlay of ₹10,000 crore, targeted ₹10,000 crore in annual revenue within three years, and characterized the addressable market as an ₹80,000 crore industry.2
Building with overwhelming force
The launch strategy rejected the conventional model of a regional pilot. Birla Opus constructed six fully automated manufacturing plants at Panipat in Haryana, Ludhiana in Punjab, Cheyyar in Tamil Nadu, Chamarajanagar in Karnataka, Mahad in Maharashtra, and Kharagpur in West Bengal, assembling a total commercial capacity of 1,332 million litres per annum.2 The first three facilities were commissioned at launch, with the remaining units coming on stream during FY25.2
The product rollout was equally broad: more than 145 products across 1,200 SKUs, over 2,300 tintable shades, first-time warranties on enamels and wood finishes, a 150-depot logistics network promising four-hour replenishment, and an in-house direct painting service.2 Kumar Mangalam Birla framed the venture as "a scale start-up incubated by the Aditya Birla Group."2
Why the incumbents looked unbeatable
The defensive strength of the incumbents in 2021 was formidable. Decorative paint is a low-ticket, high-frequency stock item for dealers, but an infrequent, high-anxiety expenditure for homeowners. Most households repaint only once every five to seven years and defer heavily to a professional painter's recommendation. That dynamic makes the painter and the retail dealer the true decision-makers, and incumbent brands had spent decades solidifying loyalty programmes, vocational training, and informal credit lines around them.
Paint is also a working-capital challenge. A retailer carrying thousands of shades cannot afford to tie up working capital in slow-moving inventory; the supplier that replenishes stock fastest and tints reliably on demand commands the counter. Incumbents' regional depot networks and daily delivery cycles allowed dealers to operate lean inventory buffers. Any prospective challenger had to duplicate that logistics infrastructure before competing on price or formulation, which explains why Birla Opus built manufacturing capacity and distribution depots concurrently rather than progressively.
Finally, the category has historically favored established consumer brands. Homeowners unfamiliar with resin chemistry default to names that have advertised on national television for half a century. A new entrant's immediate hurdle is establishing credibility rather than parity in formulation, which explains why Birla Opus led with multi-year warranties, direct painting services, and a comprehensive product catalogue from day one.2
Attacking the channel
The insurgent weapon was the commercial offer extended to the retail channel. Birla Opus installed more than 45,000 tinting machines within twelve months, placing them with dealers free of charge where established competitors typically charged ₹1.5 lakh to ₹2 lakh, and engineered the units to occupy roughly 40% less floor space so they could fit into compact neighbourhood stores.1 The company offered 10% additional paint volume at parity pricing, dealer margins of 12% to 16% compared with an estimated 4% at Asian Paints, and extended payment cycles.1
In strategic terms, this was classic counter-positioning: offering dealers unit economics that the market leader could not match across its established national base without severely eroding its operating margins. For Asian Paints, matching those dealer terms nationally would have meant diluting profitability on an enterprise generating several times Birla Opus's sales volume. For Birla Opus, which had no legacy profit pool to defend, the margin sacrifice represented direct customer acquisition spend.
Early results
The early commercial ramp outpaced general industry expectations. Birla Opus generated gross revenue of about ₹2,600 crore to ₹2,700 crore in its first full year and ascended to the rank of third-largest decorative paints brand within roughly six months, according to reporting on subsequent antitrust filings.34 By March 2026, the brand had reached roughly a 10% revenue market share, supported by a 52% year-over-year revenue increase in the fourth quarter of FY26.54
In the first quarter of FY27, paints revenue reached ₹1,661 crore—up 64% from the prior year and 17% sequentially—expanding market share by an additional 30 basis points.6 The distribution footprint expanded to 12,100 towns, covering more than 55,000 retail dealers and over 1,450 exclusive franchise stores.6 Group management stated that brand awareness had reached approximately 90%, placing the brand second in unaided consumer recall.22
Incumbent manufacturers felt the competitive pressure directly. Outlook Business reported that Asian Paints' market share fell from roughly 51% to approximately 47%, that the company expanded advertising and promotional outlays by 15% to 20%, and that its revenue declined 4.5% alongside a 32% contraction in net profit over the evaluated period.1 The same report noted that Akzo Nobel exited the Indian decorative market by selling its holding to JSW Paints, another conglomerate challenger.1 Rather than absorbing an incremental entrant, the sector began consolidating and restructuring around the shock.
The antitrust fight
The commercial contest quickly extended to the regulatory arena. Grasim filed an abuse-of-dominance complaint against Asian Paints before the Competition Commission of India. On July 1, 2025, the antitrust regulator determined that a prima facie case existed and instructed its Director General to open a formal investigation.34 The complaint alleged that Asian Paints coerced dealers into refusing Birla Opus inventory by threatening to revoke credit facilities and seasonal incentives, pushed retailers to return newly installed tinting dispensers, hindered access to key raw-material vendors, and tied commercial perks such as foreign travel to exclusive dealing.34
Asian Paints contested the investigation through the courts. The Bombay High Court dismissed its petition on September 11, 2025, and Asian Paints subsequently withdrew its appeal before the Supreme Court on October 13, 2025, leaving the High Court order intact.35 As of September 2026, a final regulatory ruling on whether Asian Paints abused its dominant market position remains pending. Under Indian competition law, an adverse finding carries potential financial penalties of up to 10% of turnover alongside mandatory behavioural remedies.34
For equity analysts, the antitrust inquiry matters less for the size of any ultimate penalty than for its effect on channel dynamics. If the competition regulator restricts exclusivity-linked rebates, Birla Opus's customer acquisition cost at the dealer counter falls significantly. If proceedings drag out without clear enforcement, the legal dispute recedes into background noise while the contest for shelf space is decided purely on commercial economics.
Testing the distribution thesis
The founding bull case for Birla Opus held that UltraTech Cement's vast retail footprint would provide an immediate, captive distribution highway. That premise required practical qualification. Grey cement is a heavy, low-margin bulk building material purchased by masons, civil engineers, and contractors. Decorative paint is a tinted, consumer-facing aesthetic finish chosen by homeowners upon the guidance of professional painters and specialist paint retailers. While the two customer groups overlap in rural building-material outlets, they operate largely as distinct retail ecosystems.
The operational record indicates that the cement footprint provided assistance primarily at the margin, notably through UltraTech Building Solutions outlets and in institutional B2B sales, which expanded 85% year over year in the first quarter of FY27.6 The vast majority of Birla Opus's market penetration, however, required independent channel development: establishing a dedicated dealer base, distributing free tinting machines, building an active contractor network of 4.5 lakh registered painters by FY26, and underwriting aggressive consumer marketing campaigns.8 Conglomerate adjacency delivered corporate credibility and initial institutional access, but Grasim ultimately had to finance its retail shelf space directly.
The profitability question
The primary vulnerability in the operational narrative is profitability. Grasim does not disclose segment-level EBITDA for Birla Opus separately, but corporate updates have consistently characterized the division as loss-making during its initial investment phase. A briefing on the fourth-quarter FY26 earnings call noted quarterly pre-tax losses of approximately ₹300 crore, with management projecting that drag to narrow over time.5 On the first-quarter FY27 earnings call, managing director Himanshu Kapania tied corporate breakeven to crossing ₹10,000 crore in annual revenue and reaffirmed FY28 as the target date for that threshold.22
That timeline reflects a subtle postponement from original launch commitments. At the February 2024 launch, management framed the ₹10,000 crore revenue target as achievable within three years, pointing toward roughly FY27.2 By FY26, executives recast that objective as applying to the third full year of commercial operations, and in August 2026 confirmed FY28 as the operating benchmark.422 While that adjustment represents a minor operational drift given the scale of the initial capacity deployment, it defers corporate profitability and extends the period of balance-sheet cash burn.
Operating results in mid-2026 introduced further margin friction. Management cited an "unprecedented raw material cost shock" that compelled cumulative price increases of 8.8% during the first quarter of FY27, narrowing Birla Opus's pricing discount relative to incumbent peers.22 A portion of the quarter's revenue expansion stemmed from channel stocking ahead of those announced price hikes—a seasonal benefit management confirmed would not recur—while underlying sequential volume growth tracked closer to overall industry rates.22 First-quarter revenue annualized to approximately ₹6,600 crore; scaling to ₹10,000 crore by FY28 will require sales growth to outpace the broader market even as introductory discounts and dealer subsidies moderate toward commercial norms.
The calibrated verdict is that Birla Opus has demonstrated an ability to win market share faster than industrial incumbents anticipated. It has yet to prove that this acquired volume is profitable once introductory margins and discounted dealer terms normalize. The decisive operational test will be whether customer demand and dealer loyalty hold as the price spread between Birla Opus and the market leaders closes.
The paints venture represents only one half of Grasim's modern growth offensive, sharing both its building-materials strategic rationale and its initial cash-burn profile with an adjoining digital platform.
VII. Emerging Material Optionality: Birla Pivot (B2B E-Commerce)
A contractor in a tier-two town constructing an apartment block requires steel, cement, pipes, tiles, plywood, and chemicals—typically sourced from half a dozen independent suppliers, each with separate pricing, credit arrangements, and delivery timetables. Birla Pivot, announced in 2022 as a business-to-business e-commerce platform for building materials, represents Grasim's bid to become the single procurement counter for that contractor.10
Top-line expansion has been rapid. In the first quarter of FY27, Birla Pivot generated ₹2,548 crore in revenue, up 75% year over year, lifting its annualized run rate above ₹10,000 crore.6 By March 2026, the marketplace catalogued more than 50,000 SKUs from over 1,000 brands across more than 5,000 pin codes.4
Gross revenue, however, is an incomplete yardstick for a platform that predominantly buys and resells physical goods. In building-materials commerce, gross trading margins are thin, working-capital requirements run high, and the temptation to capture market share through loose payment terms risks turning an e-commerce platform into an unrated lender. Management initially targeted EBITDA breakeven by the exit of FY27.4 On the first-quarter FY27 earnings call, however, leadership acknowledged a slight timeline shift resulting from front-loaded investments in technology and personnel, while citing delayed customer purchases as buyers trimmed inventory amid Middle East geopolitical tensions.22
The calibrated conclusion is that Birla Pivot remains an operational call option rather than an established earnings engine. The decisive test is not gross turnover, but whether segment breakeven arrives without an unsustainable buildup in working capital or receivables. If it delivers, Pivot establishes an integrated digital distribution channel for the group's wider building-material portfolio. If it falters, it adds another cash-absorbing commitment to the standalone balance sheet, reinforcing the market's conglomerate discount.
Both capital-intensive ventures depend on the same corporate funding pool, making a rigorous examination of Grasim's financial architecture essential.
VIII. Financial Architecture, Capital Allocation & Management Credibility
In January 2024, a month before the public unveiling of Birla Opus, Grasim's shareholders received an offer document rather than a dividend cheque. The company, which had recently operated with a net cash position on its standalone balance sheet, turned to equity investors to raise ₹4,000 crore. To understand why that cash call became necessary, an investor must separate the headline figures Grasim reports on a consolidated basis from the cash flows and obligations that sit directly inside the parent entity.
The consolidated picture
Consolidated results present an expansive profile because they incorporate both UltraTech Cement and Aditya Birla Capital. In FY26, consolidated revenue reached ₹1,75,431 crore and EBITDA rose to ₹25,872 crore, up 18% and 29% respectively.8 Consolidated net debt excluding the financial services business stood at ₹36,915 crore as of March 31, 2026, representing 1.43 times EBITDA, an improvement from 1.77 times a year earlier.4 Operational scale continued into the first quarter of FY27, with consolidated revenue reaching ₹48,716 crore and EBITDA coming in at ₹8,077 crore.6
The standalone accounts, however, reflect the direct consequences of Grasim's capital allocation choices. In FY26, standalone revenue was ₹41,039 crore and standalone EBITDA stood at ₹3,558 crore.8 Standalone top-line growth of 30% was driven heavily by Birla Opus and Birla Pivot—ventures that add commercial sales far faster than operating profit. In the first quarter of FY27, standalone EBITDA more than doubled year over year to ₹1,094 crore, bolstered by the cyclical rebound in cellulosic fibre prices.6
From net cash to net debt
The financial toll of incubating new ventures is visible on the standalone balance sheet. In February 2022, following the divestment of its fertiliser business, Grasim reported that it had become net-debt-free at the standalone level.36 By June 2026, standalone net debt had expanded to approximately ₹9,900 crore; management attributed part of the sequential increase to the timing of its capital deployment into Aditya Birla Capital ahead of incoming UltraTech dividend receipts, while stating that it expected to keep standalone leverage below two times EBITDA.2223
Within four years, Grasim transitioned from a net cash position to nearly ₹10,000 crore of standalone net debt. That balance-sheet shift funded the ₹10,000 crore outlay for Birla Opus, parallel capacity additions in chlor-alkali chemicals and specialty fibres, and equity infusions to retain control of Aditya Birla Capital. Management stated that peak capital expenditure was behind it, establishing a standalone capex budget of ₹3,157 crore for FY27.56 While that moderating budget is plausible, it leaves parent-level cash flow dependent on volatile commodity earnings from viscose and chemicals, as well as dividend flows from UltraTech, while Birla Opus continues to generate operating losses.
The rights issue
The clearest signal that internal cash generation could not fully fund these concurrent expansions arrived in January 2024. Grasim priced a ₹4,000 crore rights issue at ₹1,812 per share—representing a discount of approximately 12% to prevailing market prices—offering six rights shares for every 179 shares held.37 The issue was structured on a partly paid basis, requiring ₹453 per share on application with the balance of ₹1,359 due in calls through March 2026.37 The promoter group held 42.75% of the equity prior to the transaction, which entailed an overall equity dilution of roughly 3.3%.37
The offering was fully subscribed and did not dilute shareholders who took up their entitlements. Yet the structural signal was unmistakable. An industrial conglomerate that had long promoted the self-funding strength of its manufacturing engines turned to equity markets within three years of launching a new consumer venture. Spreading the cash calls over a two-year timeline offered financial flexibility, but it confirmed to public markets that building a consumer paints platform concurrently with heavy chemical capex exceeded the standalone entity's organic free cash flow.
A new royalty
A smaller but consequential governance development surfaced in 2026. On the first-quarter FY27 earnings call, management confirmed that starting in June 2026, Grasim would begin paying a brand royalty of 0.25% of standalone revenue to the group's parent brand-holding entity.22 While the absolute payout appears manageable relative to Grasim's scale, introducing an ongoing royalty payment from a listed operating company to a promoter-affiliated entity is precisely the type of related-party transaction that attracts scrutiny from proxy advisory firms and institutional investors. The obligation warrants close monitoring because the fee is levied on top-line revenue rather than net earnings, compounding as rapid commercial growth in Birla Opus and Birla Pivot expands the standalone revenue base.
The people
Kumar Mangalam Birla assumed the chairmanship of the Aditya Birla Group in 1995 at the age of 28, following the sudden passing of his father, Aditya Vikram Birla.38 Born in Calcutta in 1967, he trained as a chartered accountant and completed an MBA at London Business School in 1992, only three years before inheriting leadership of the group.38 Under his tenure, the conglomerate's annual turnover grew from roughly $2 billion in 1995 to a reported $70 billion.38 His track record established him as an aggressive, counter-cyclical capital allocator, underscored by landmark transactions such as the acquisition and consolidation of UltraTech and Hindalco's takeover of Novelis.
His public executive persona is patient and understated, frequently framing commercial investments around broader national economic development goals, as evidenced by references to "Viksit Bharat" in Grasim's earnings materials.8 Yet his corporate architecture remains unmistakably promoter-centric. Major strategic choices—from the contested entry into Larsen & Toubro's cement business to the absorption of Aditya Birla Nuvo and the aggressive funding of paints—were conceived as group-level ambitions executed through Grasim's corporate vehicle. Minority shareholders have repeatedly had to weigh whether group priorities aligned with standalone shareholder value. That history is decidedly mixed: while the industrial roll-up in cement generated enormous enterprise value, the conglomerate's commitment to Idea Cellular and subsequent support of Vodafone Idea destroyed a large amount of capital, much of it borne by Grasim and its shareholders.3233
Operational leadership within Grasim has undergone a significant transition. Hari Krishna Agarwal, a chartered accountant who joined the group as a management trainee in 1982 and spent decades directing operations across cement, chemicals, and pulp and fibre, became managing director on December 1, 2021.39 Following his early retirement, he was succeeded on April 1, 2025, by Himanshu Kapania, for a term running to April 2028.40 Kapania, previously managing director of Idea Cellular, had been business director of Birla Opus, an appointment indicating that the decorative paints venture had become the central operational priority for the company as a whole.40
Leadership within the consumer division has also seen movement. Birla Opus's first chief executive, Rakshit Hargave—an IIT and Faculty of Management Studies graduate who had spent 11 years at Nivea's parent Beiersdorf, including tenure as managing director of Nivea India—resigned effective November 1, 2025, and joined Britannia as chief executive from December 15, 2025.4142 Kapania was given oversight of the paints business until a new chief executive is appointed.41 The departure of the consumer-marketing executive recruited to build the venture, occurring less than two years after commercial launch, represented an operational disruption, even as Birla Opus continued to post market share gains. By the first quarter of FY27, Hemant Kadel was addressing investors on quarterly calls as chief financial officer.22
Credibility scorecard
Assessed by behaviour over time, management has delivered on capacity and distribution promises in decorative paints: six automated manufacturing plants, a national retail network, and a double-digit revenue share materialized broadly within the operational timeframes promised at launch. Management has proven less definitive on financial returns, with the revenue target that anchors commercial breakeven gradually moving from "within three years" to FY28. On leverage, while consolidated debt ratios have remained moderate, Grasim surrendered the standalone net cash position that was once a core element of the parent company's investment case.
The decisive question for capital allocators is whether this aggressive deployment establishes an enduring consumer moat, or simply demonstrates the raw financial power of a conglomerate balance sheet.
IX. The Strategic Moat: 7 Powers & Porter's Five Forces Analysis
A war-game frame
To evaluate whether Grasim commands genuine competitive moats, consider three distinct planning rooms across the group. In the first, UltraTech's strategists track Adani's capacity additions and evaluate where to locate the next kilns. In the second, Grasim's cellulosic team monitors Chinese export prices to determine operating rates at Nagda. In the third, the Birla Opus sales force maps dealer counters across a district to identify which retailers still rely exclusively on an Asian Paints dispenser. Each vertical confronts a different competitive dynamic, and each relies on an entirely different source of strategic advantage.
Hamilton Helmer's 7 Powers
Scale economies represent the most durable power across the corporate portfolio. UltraTech's nationwide manufacturing footprint and logistics network lower freight and fixed costs per tonne, an operational advantage reflected in its record operating EBITDA per tonne.8 In chlor-alkali, Grasim's position as India's largest merchant producer underpins structurally lower unit processing costs.[^4] In viscose staple fibre, domestic manufacturing scale confers operational efficiency but does not insulate the business from global commodity price cycles.
Cornered resources reside almost exclusively in cement. Long-dated limestone mining leases and legacy plant sites secured decades ago cannot be replicated at historical cost, particularly under India's modern competitive mineral auction regime. That resource moat, however, accrues entirely to UltraTech's equity holders rather than directly to Grasim's standalone balance sheet.
Switching costs represent the primary barrier Grasim is attempting to dismantle in decorative paints. Independent paint retailers are tied to incumbent manufacturers through proprietary tinting systems, informal working-capital credit lines, and retrospective annual volume rebates. Birla Opus's commercial offensive—deploying free tinting machines and funding elevated dealer margins—amounts to subsidizing retail partners to absorb the friction of switching suppliers.1
Counter-positioning is the structural power Birla Opus aims to establish. The strategic logic posits that established leaders cannot match Birla Opus's aggressive dealer margins and volume discounts across their mature national sales bases without incurring severe profit dilution. Early commercial data supports that premise: Asian Paints surrendered market share and experienced a sharp earnings contraction as competitive pressure mounted.1 Yet counter-positioning proves durable only when an entrant's operating architecture differs structurally from the incumbent's. Birla Opus operates a capital-intensive manufacturing and dealer-led distribution model identical to that of legacy leaders, simply operated on narrower introductory margins. As promotional discounts normalize—reflected in the cumulative 8.8% price increases implemented during the first quarter of FY27—that counter-positioning advantage begins to erode.22
Brand power is an advantage Grasim has yet to secure in consumer paints. Widespread consumer awareness is a necessary precursor, but brand power in economic terms requires the pricing power to charge a premium for comparable goods. To date, Birla Opus's volume gains have stemmed from aggressive channel subsidies and favorable pricing terms rather than customer-driven brand premiums.
Network effects remain largely absent across the portfolio, limited to a modest two-sided marketplace dynamic within the nascent Birla Pivot B2B platform. Process power exists across the chemical and fibre complexes, where proprietary engineering and decades of domestic process adaptation have reduced unit consumption norms, but those refinements yield incremental cost efficiencies rather than an unassailable technical moat.
The strategic verdict across Helmer's framework is unequivocal: Grasim's most durable economic powers reside inside UltraTech, an asset public markets price independently as a listed subsidiary. The standalone company commands meaningful but cyclical process and scale advantages in chemicals and fibre, while its competitive position in decorative paints remains an unproven hypothesis funded by balance-sheet capital.
Porter's Five Forces
The threat of new entrants is structurally low in cement and chlor-alkali due to intense capital expenditure requirements, lengthy environmental permitting processes, and captive raw-material constraints. Domestic viscose staple fibre exhibits similar barriers to entry. In decorative paints, however, the threat of entry has proved surprisingly high for well-capitalized industrial groups, as both Birla Opus and JSW Paints have illustrated. That reality cuts both ways: while Grasim successfully breached the category, the retail channel remains vulnerable to future balance-sheet-backed entrants seeking high-margin consumer diversification.
Supplier power exerts substantial leverage across several operating divisions. Viscose manufacturing remains exposed to globally priced dissolving-grade pulp, chlor-alkali requires substantial electrical power and raw salt, and decorative paints depend heavily on crude-oil derivatives, titanium dioxide, and packaging materials. The raw-material cost shock experienced in the first quarter of FY27 demonstrated how rapidly upstream commodity inflation can compress an insurgent's retail price advantage.22
Buyer power varies significantly across verticals. In cellulosic fibres, downstream spinning mills exercise moderate bargaining power because they can substitute cotton or polyester when synthetic or agricultural prices diverge. In paints, individual retail consumers are highly fragmented, but retail dealers have accumulated substantial commercial leverage as competing manufacturers bid aggressively for limited shelf space and counter display.
The threat of substitutes is material in textile fibres, where viscose competes directly on price and availability against cotton, polyester, and alternative blends. Conversely, substitution risk is negligible in industrial chlor-alkali, where caustic soda and chlorine serve as irreplaceable chemical feedstocks across alumina, textile, and PVC production.
Competitive rivalry is exceptionally intense in decorative paints, where four well-capitalized corporate groups are actively contesting retail shelf space. In cement, rivalry is defined by a two-player capacity expansion race between UltraTech and the Adani Group. In domestic viscose, Grasim faces minimal local manufacturing competition but remains fully exposed to import parity set by Chinese export flows.
Peer comparison
Against Asian Paints, Birla Opus commands substantial modern manufacturing capacity but generates only a fraction of the incumbent's sales turnover, lacks decades of accumulated brand affinity, and has yet to achieve operational breakeven. Against Berger Paints and Kansai Nerolac, Birla Opus reached a comparable revenue market share within roughly two years of launch, based on reported industry estimates.14 Against JSW Paints, recently strengthened by its acquisition of Akzo Nobel's Indian operations, Grasim confronts a fellow industrial conglomerate prepared to commit patient balance-sheet capital to win distribution share.1
In cement, UltraTech's primary competitive benchmark is the Adani Group's combined platform of Ambuja Cements and ACC. While UltraTech maintains a decisive lead in installed capacity and operating efficiency, Adani's entry transformed the industry from a fragmented field led by a single national player into an aggressive duopolistic contest for regional dominance.20
In cellulosic fibres, Grasim benchmarks against global leaders including Austria's Lenzing and major Chinese manufacturers. Grasim benefits from deep domestic distribution relationships and integrated caustic soda supply, but it remains a structural price-taker against global benchmark pricing established in East Asia.
Both strategic frameworks lead to an identical analytical conclusion: Grasim's most defensible economic moats reside in its mature, cash-generative industrial businesses, while its weakest competitive advantages inhabit the consumer vertical absorbing the vast majority of its growth capital. That structural imbalance frames the operational and financial risks confronting the enterprise.
X. The Risk Radar & Skeptical-Investor Stress Test
In late October 2026, the digesters at Nackawic in New Brunswick are scheduled to go quiet, leaving roughly 350 workers waiting to learn whether the shutdown is temporary.25 In Grasim's consolidated accounts, it is a minor line item. Yet it serves as an instructive reminder that risks in a conglomerate rarely surface first in the marquee divisions. Instead, they emerge along the operational periphery: in an overseas pulp mill, an unexpected raw-material bill, channel-stocking patterns at retail dealerships, or a newly instituted related-party royalty.
Risk one: paints becomes a long-term drain
The transmission mechanism is straightforward. If incumbent paint manufacturers continue to defend their distribution moats with elevated promotional spending, dealer incentives, and advertising, industry margins will remain suppressed. To protect its hard-won market share, Birla Opus would be forced to maintain discounted pricing and enriched dealer commissions indefinitely. Under that scenario, top-line revenue can expand rapidly while operating losses persist. Management has tied division breakeven to reaching ₹10,000 crore in annual sales, an operating target now deferred to FY28.22 If that revenue threshold slips further or arrives without meaningful margin expansion, the paints division risks turning into a structural drag on standalone cash flows. The earliest indicator of trouble would be market share gains plateauing as introductory price discounts close against legacy leaders.
Risk two: commodity cycles turn against the cash engines
Grasim's standalone operations are underwriting its consumer expansion at a moment when both core commodity divisions have enjoyed cyclical strength. In the first quarter of FY27, viscose staple fibre realizations rose 19% year over year.6 Yet on earnings calls, management acknowledged that these margins remain cyclical, while pointing to an influx of new domestic chlor-alkali capacity entering the market.22 If Chinese viscose exports increase or domestic caustic soda prices soften, standalone EBITDA could contract precisely when Birla Opus requires continued balance-sheet support. Trade policy adds another layer of vulnerability: import tariffs, anti-dumping duties, and Bureau of Indian Standards quality control orders govern the flow of cheap Chinese product into the domestic market, and any regulatory easing would immediately compress domestic realizations.
Risk three: the discount widens
A holding-company discount is not a permanent constant; it expands and contracts based on capital allocation discipline. If public equity markets conclude that standalone industrial cash will continue to be recycled into cash-absorbing ventures—including Birla Pivot, renewable energy platforms, and decorative paints—investors may demand an even wider discount to net asset value. Management's stated commitment to maintain equity stakes above 50% in both UltraTech Cement and Aditya Birla Capital means further capital calls from those subsidiaries remain an ongoing possibility.5 Meanwhile, the brand royalty of 0.25% introduced in mid-2026 introduces a small but symbolically sensitive governance headwind, funnelling cash from a listed operating company to a promoter entity.22
Risk four: energy and input costs
The chlor-alkali process is inherently power-intensive, meaning state grid tariff hikes or rising thermal coal costs directly erode electrochemical unit margins. On the consumer side, paint manufacturing depends heavily on crude-oil derivatives, titanium dioxide, and packaging materials—a cost structure that management noted suffered an unprecedented raw-material cost shock in the first quarter of FY27.22 Geopolitical tensions in the Persian Gulf, which leadership explicitly cited as a driver of chemical feedstock volatility, amplify cost pressures across both manufacturing divisions simultaneously.22
Risk five: stranded overseas assets
The idled Terrace Bay mill in Ontario and the scheduled idling of the Nackawic facility in New Brunswick expose Grasim to continuing holding costs, environmental liabilities, potential balance-sheet impairments, and fraught capital restart decisions.[^27]25 Outside investors should scrutinize the carrying value of these assets within the joint-venture and associate accounts for future write-downs, as well as monitor whether management moves toward permanent site closures or outright divestments.
Myth versus reality
Myth: Grasim is fundamentally a textile fibre company. Reality: Cellulosic fibre is merely one operating segment within a standalone company whose revenue expansion is increasingly propelled by paints and Birla Pivot, and whose consolidated valuation is overwhelmingly dominated by its listed holding in UltraTech Cement.69
Myth: UltraTech's cement dealership network automatically handed Birla Opus ready-made distribution. Reality: The cement footprint assisted primarily in institutional sales and specialized building-solutions outlets. The vast majority of Birla Opus's retail penetration had to be built and financed from scratch through free tinting machines, enriched dealer commissions, and painter loyalty programmes.18
Myth: Captive ownership of raw materials inherently protects profit margins. Reality: Backward integration succeeds only under specific structural conditions. Captive chlor-alkali has anchored domestic viscose production for five decades, but captive Canadian pulp mills became uncompetitive burdens that management chose to idle when global open-market pulp proved cheaper.[^27]25
Myth: The decorative paints war has already been won because Asian Paints lost market share. Reality: Birla Opus disrupted the category's market share rankings, but the insurgent has yet to demonstrate sustainable operating profitability, and its initial price discount to incumbents narrowed significantly after necessary price hikes.122
The activist's memo
A skeptical institutional activist evaluating Grasim would raise four pointed questions. First, why must Grasim maintain a controlling stake of more than 50% in Aditya Birla Capital, and what risk-adjusted return does that recurring equity infusion deliver to Grasim's standalone shareholders? Second, why not pass through a substantially larger portion of UltraTech's dividend distributions directly to parent-company investors? Third, what is management's explicit operational contingency if Birla Opus fails to achieve breakeven by FY28? And fourth, why implement a new promoter brand royalty when the stock already trades at a steep holding-company discount? None of these inquiries implies bad faith; rather, they address the structural reasons why public markets discount the corporate portfolio.
An activist would also challenge the company's financial disclosure. While Grasim provides comprehensive operational metrics and top-line revenue for Birla Opus, it does not disclose a separate segment EBITDA for paints, leaving outside investors unable to track the exact trajectory of quarterly operating losses.64 For a consumer venture that has absorbed ₹10,000 crore in capital, granular visibility into segment profitability, dealer receivables, and working capital is essential to verify management's path to breakeven. That same disclosure gap applies to Birla Pivot, where the sole published milestone is targeted EBITDA breakeven by the exit of FY27.4
Finally, leadership continuity presents an operational question mark. Birla Opus lost its founding chief executive in late 2025, prompting Grasim's group managing director to assume direct oversight of the business.41 While that executive intervention provides interim stability, consolidating operational control of an insurgent consumer brand under the parent company's chief executive is an imperfect long-term governance arrangement for a vertical management expects to become one of Grasim's primary growth engines.
XI. Playbook: Durable Conglomerate & Investing Lessons
Integration is a survival tool with an expiry date
Backward integration begins as an operational necessity, but its strategic utility can expire. In the 1950s and 1970s, Grasim's captive caustic soda capacity and in-house pulp innovations at Harihar protected manufacturing operations in an import-constrained economy where merchant supply was erratic and scarce.3 That integration generated enduring value because the raw materials were difficult to procure domestically and could be produced economically on site. The experience of the group's overseas pulp mills illustrates the inverse: when a commodity input is plentiful and traded globally, maintaining high-cost captive assets in distant jurisdictions transforms an intended supply moat into a fixed-cost drag.[^27]25 Vertical integration is not an absolute virtue; its value shifts as trade flows and cost structures evolve.
Counter-cyclical consolidation works when you understand the asset
UltraTech's ascent demonstrated that counter-cyclical consolidation generates substantial enterprise value when executed in an industrial sector management thoroughly understands. Grasim systematically expanded its cement footprint by acquiring kilns from distressed or exiting sellers—beginning with the demerged cement operations of Larsen & Toubro, followed by large-scale additions from Jaiprakash Associates and Kesoram Industries.13[^17]17 The broader lesson is that acquisitions create durable value not simply through balance-sheet scale, but when an acquirer possesses operational mastery and purchases during cyclical downturns when sellers are compelled to negotiate. Conversely, the capital losses sustained through Idea Cellular underscore the hazards of deploying that same conglomerate balance sheet into a capital-intensive consumer sector governed by fundamentally different regulatory and competitive rules.32
Disrupting an oligopoly requires scale and patience
Birla Opus demonstrates that a well-capitalized challenger can breach an established consumer oligopoly and secure meaningful market share within two years by combining overwhelming upfront manufacturing capacity with aggressive dealer incentives.15 Yet initial volume gains reflect the deployment of corporate capital rather than accumulated brand equity. The more demanding phase of disruption arrives once promotional channel subsidies and introductory pricing discounts normalize, requiring the insurgent to prove that acquired volume can generate sustainable operating returns without ongoing balance-sheet support.
Holding company discounts respond to behaviour, not rhetoric
Public equity markets evaluate holding companies on capital allocation discipline rather than corporate narratives. Grasim's persistent discount to net asset value has remained wide for years despite UltraTech's compounding scale and cash generation.9 Holding company discounts typically contract only when parent boards establish predictable pass-through dividend policies or simplify corporate structures. Grasim has chosen the opposite course, using cash flows from mature commodity assets to maintain controlling stakes in listed subsidiaries and incubate capital-intensive new platforms. While active capital recycling represents a deliberate conglomerate strategy, equity markets consistently price the redeployment risk into the parent stock.
XII. Bull vs. Bear Case & What to Watch (1–3 Key KPIs)
The bull case
In the bullish scenario, Birla Opus scales to ₹10,000 crore in revenue by FY28 and transitions into profitability, establishing itself as the undisputed number-two decorative paints brand behind Asian Paints. Operating momentum provides early backing for that path, underscored by a 10% revenue market share by March 2026 and 64% year-over-year revenue expansion in the first quarter of FY27.46 UltraTech executes its roadmap beyond 240 million tonnes of annual capacity by March 2028 while sustaining industry-leading EBITDA per tonne, distributing higher dividend streams back to Grasim.8 Meanwhile, specialty fibres and downstream chlorine derivatives—including lyocell, CPVC, and epichlorohydrin—cushion the standalone manufacturing portfolio against broad commodity price swings.23 Concurrently, Birla Pivot achieves operational breakeven, and Grasim's holding-company discount narrows as standalone free cash flow turns sustainably positive and balance-sheet leverage recedes.
The core of the bull thesis is that peak capital expenditure has passed. If operating losses in decorative paints diminish while chemical realizations and viscose earnings remain steady, parent-level cash generation would expand significantly, compelling public equity markets to ascribe genuine standalone value to the non-UltraTech assets.
The bear case
In the bearish scenario, incumbent paint manufacturers mount a protracted defence through promotional spending, dealer perks, and price competition, causing Birla Opus's top-line expansion to decelerate as its introductory price discount erodes. The channel stocking and cumulative 8.8% price increases observed in the first quarter of FY27 serve as early indicators of that operational friction.22 Simultaneously, cyclical realizations in cellulosic fibres and chlor-alkali soften from recent highs, curtailing the standalone operating cash flow required to subsidize paints. Standalone net debt climbs past the roughly ₹9,900 crore recorded in June 2026, forcing Grasim to rely on another outside equity call or seek higher cash distributions from UltraTech.22 Overseas, the idled Canadian pulp mills incur balance-sheet write-downs, while lingering governance sensitivities, including the promoter brand royalty, entrench a wide holding-company discount.
The most potent bear argument is grounded in corporate precedent. Grasim's history demonstrates strong returns when acquiring and consolidating heavy industrial assets it operates directly, and poor capital outcomes when its balance sheet is enlisted to finance consumer or telecom ventures governed by unfamiliar unit economics. Decorative paints aligns more closely with the second category, and evidence of sustainable operating profitability has yet to materialize.
What the holding structure means for each case
A defining structural feature complicates both investment theses. Because listed holdings—predominantly UltraTech Cement—account for the overwhelming majority of Grasim's enterprise value, even an exceptional commercial outcome in decorative paints may move the parent company's share price less than a modest cyclical shift in national cement realizations. Market analyses have consistently observed that Grasim's equity valuation tracks UltraTech's stock price closely.9
In operational reality, the paints venture affects parent equity primarily through the holding-company discount. A profitable, cash-generative Birla Opus would provide institutional investors with a tangible reason to value the standalone operating portfolio rather than writing it off as a drain on cement cash flows. Conversely, persistent operating deficits in consumer paints furnish the market with continued justification to widen that discount.
Weighing the two
Neither case can be dismissed lightly. Birla Opus has disproved the conventional assumption that an insurgent could not take meaningful market share from an entrenched market leader like Asian Paints. It has yet to disprove the more critical financial assertion that a capital-intensive challenger cannot generate attractive economic returns in the process. The ultimate verdict will emerge over the next two to three years, as introductory price discounts close and sales approach the revenue threshold management has established as the benchmark for corporate breakeven.
The three KPIs to track
First, Birla Opus quarterly revenue and revenue market share. This metric provides the most immediate signal of whether consumer demand and channel distribution hold as cumulative price increases narrow the pricing discount against established incumbents. Management has explicitly linked division breakeven to reaching ₹10,000 crore in annual revenue by FY28.22
Second, chlor-alkali electrochemical unit realizations alongside cellulosic staple fibre selling prices. Together, these figures dictate the volume of operating cash flow the mature standalone commodity businesses generate to fund ongoing incubation expenses. Grasim discloses its net ECU realization each quarter.6
Third, standalone net debt relative to standalone EBITDA. This leverage ratio indicates whether the capital requirements of Birla Opus and Birla Pivot are being absorbed by parent-level cash flows or are elevating corporate indebtedness. Management has stated that it expects to maintain standalone leverage below two times EBITDA.22
XIII. Epilogue: The Conglomerate's Ultimate Dilemma
When Kumar Mangalam Birla assumed leadership of the group in 1995, Grasim was a commodity fibre and cement producer defined by an engineering culture that built what international suppliers would not sell. Three decades later, it controls India's largest cement manufacturer, a major listed financial services group, the country's leading chlor-alkali chemical operations, and a consumer paints challenger that has unsettled one of the most profitable retail franchises in modern corporate India.
The unresolved question is whether an organization shaped by heavy industrial manufacturing can build an insurgent consumer brand that earns sustainable returns above its cost of capital. The early operational record is mixed. Birla Opus achieved national scale and retail distribution faster than industry incumbents anticipated. Yet that rapid ascent has exacted a visible financial price: persistent operating losses, rising standalone leverage, and leadership turnover. The ultimate test will not be the market share Birla Opus captures during its aggressive rollout, but the operating margins it can sustain once introductory dealer terms and volume subsidies normalize.
There is a striking symmetry in that corporate arc. G.D. Birla's enterprise began by addressing an acute supply challenge: a newly independent nation short on raw cotton. Seventy-nine years later, the company is confronting a complex demand hurdle: persuading homeowners, contractors, and retail dealers to embrace an unfamiliar brand over incumbents they have trusted for generations. The swadeshi breakthrough rewarded chemical engineering and capital patience. The consumer offensive requires brand affinity, channel discipline, and a willingness to absorb sustained cash burn.
Grasim has repeatedly demonstrated balance-sheet resilience and long-term patience. In cement, it proved it could outlast rivals across multi-year consolidation cycles to create an industry champion. What it has yet to prove is that a consumer brand assembled through aggressive introductory pricing and subsidized retail equipment can convert into an enterprise that earns its cost of capital without ongoing parent-company support. That ambiguity sits at the heart of how public markets price the company every day.
For equity investors, Grasim remains a definitive case study in how conglomerates create and erode shareholder value. UltraTech illustrates the compounding power of patient, counter-cyclical industrial roll-ups. Vodafone Idea demonstrates the severe balance-sheet damage that occurs when conglomerate cash is enlisted to back an embattled venture facing a brutal price war. Birla Opus sits squarely between those two precedents. Grasim's persistent 40%-plus holding-company discount is effectively the market's ongoing skepticism over which of those precedents the paints venture will ultimately mirror—and the operational trajectory over the next few years will settle the debate.
References
-
How Birla Opus Broke into India's Paints Industry with Scale, Capital and 45,000 Tinting Machines — Outlook Business ↩↩↩↩↩↩↩↩↩↩↩↩
-
Aditya Birla Group set to disrupt Paint industry with 40% addition to Industry Capacity; Birla Opus targets Rs 10,000 Cr revenue within 3 years — Grasim Industries, 2024-02-22 ↩↩↩↩↩↩↩↩
-
75 glorious years of Grasim — Aditya Birla Group ↩↩↩↩↩↩↩↩↩↩↩
-
Grasim Q4 FY26: record numbers, but the real story is the new engines — Multibagg, 2026-05-21 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Grasim Q4 FY26 Earnings Call: Paints Market Share Crosses 10%, UltraTech Hits Record EBITDA per Ton — Cofacto, 2026-05 ↩↩↩↩↩↩↩
-
Grasim Q1 FY27 Financial Results — Grasim Industries, 2026-08-12 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Grasim Industries Ltd Share Price Today – Live Price & Market Trends — StockGro, 2026-09-24 ↩
-
Q4FY2026 – Creating and Scaling Growth Engines for 'Viksit Bharat' — Grasim Industries, 2026-05-20 ↩↩↩↩↩↩↩↩↩↩
-
Grasim Industries: Paying for Cement, Getting the Rest Free — Wealthspark, 2026-01-02 ↩↩↩↩↩
-
Grasim: 75 years of breaking barriers and forging new paths — Aditya Birla Group ↩↩↩↩↩↩↩
-
SEBI seeks details of Grasim's L&T stake buy — Business Standard, 2001-12-27 ↩
-
Grasim to get control of L&T cement business on July 1 — Business Standard, 2004-05-28 ↩↩
-
Grasim offers to acquire 30% stake — CemNet, 2004-06-14 ↩↩↩↩
-
Overwhelming response to Grasim's open offer to the shareholders of UltraTech CemCo Ltd. — UltraTech Cement, 2004-06-01 ↩
-
Samruddhi Cement Limited to merge with UltraTech — UltraTech Cement, 2009-11-15 ↩↩↩
-
Update on Scheme of Demerger (Century Textiles cement business) — UltraTech Cement, 2019 ↩
-
Demerger of Cement Business of Kesoram Industries Limited into UltraTech Cement Limited — UltraTech Cement, 2023-11-30 ↩↩
-
UltraTech completes acquisition of cement business of Kesoram Industries Limited — UltraTech Cement, 2025-03 ↩
-
UltraTech Acquires 32.72% Stake in India Cements — Reuters, 2024-07-28 ↩
-
Adani Becomes India's Second Largest Cement Player — Adani Group, 2022-09-16 ↩↩
-
Grasim's Rs 3,970 Cr Dividend Boosts Paint Growth Amid Debt — Whalesbook, 2026-05-14 ↩↩
-
Grasim Industries Ltd (Q1 2027) Earnings Call Highlights — Yahoo Finance, 2026-08-12 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Grasim Q1 FY27: Record EBITDA, fast-growing new engines, and clear project milestones — Multibagg, 2026-08-13 ↩↩↩↩↩
-
Terrace Bay Pulp – More details on the deal with Aditya Birla Group — NetNewsLedger, 2012-07-13 ↩
-
AV Group NB Announces Temporary Idling of Nackawic Dissolving Pulp Mill — PaperAge, 2026-09-18 ↩↩↩↩↩↩
-
Grasim's Canadian JV AVNB to temporarily idle Nackawic pulp mill — ScanX, 2026-09 ↩
-
Aditya Birla Nuvo to merge with Grasim in mega-restructuring — Forbes India, 2016-08-11 ↩↩
-
Nuvo merger with Grasim starts debate — Business Standard, 2016-08-11 ↩↩
-
IiAS Recommends Voting Against Grasim and Aditya Birla Nuvo Merger — Business Standard, 2016-09-05 ↩
-
Why the Grasim-Nuvo Merger Left Minority Shareholders Unhappy — Forbes India, 2016-08-25 ↩
-
Scrutinizer Report and Voting Results: Amalgamation of Aditya Birla Nuvo with Grasim — National Stock Exchange of India, 2017-04-10 ↩
-
Grasim Industries reports Q2 consolidated loss of Rs 1,299.86 cr — Business Standard, 2018-11-14 ↩↩↩
-
Grasim's small shareholders may not be keen to invest more in Vodafone Idea — Business Standard, 2020-09-09 ↩↩↩
-
CCI finds prima facie abuse of dominance by Asian Paints in Grasim Paints case — Storyboard18, 2025-07 ↩↩↩↩
-
Protecting 'competitor' at the cost of 'competition'? Asian Paints vs. Birla Opus — The Antitrust Attorney Blog (MM Sharma) ↩
-
Grasim becomes net debt-free on standalone basis after fertiliser arm sale — Business Standard, 2022-02-14 ↩
-
Grasim to issue rights shares at Rs1,812 each to raise Rs4,000 cr — Domain-b, 2024-01 ↩↩↩
-
Grasim Industries appoints H K Agarwal as MD — Grasim Industries, 2021 ↩
-
Himanshu Kapania to replace Harikrishna Agarwal as Grasim Industries MD — Indian Chemical News, 2025-02-11 ↩↩
-
Birla Opus CEO Rakshit Hargave Resigns to Head Britannia — Angel One, 2025-11 ↩↩↩
-
Britannia names ex-Birla Opus head Rakshit Hargave as CEO — afaqs!, 2025 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube