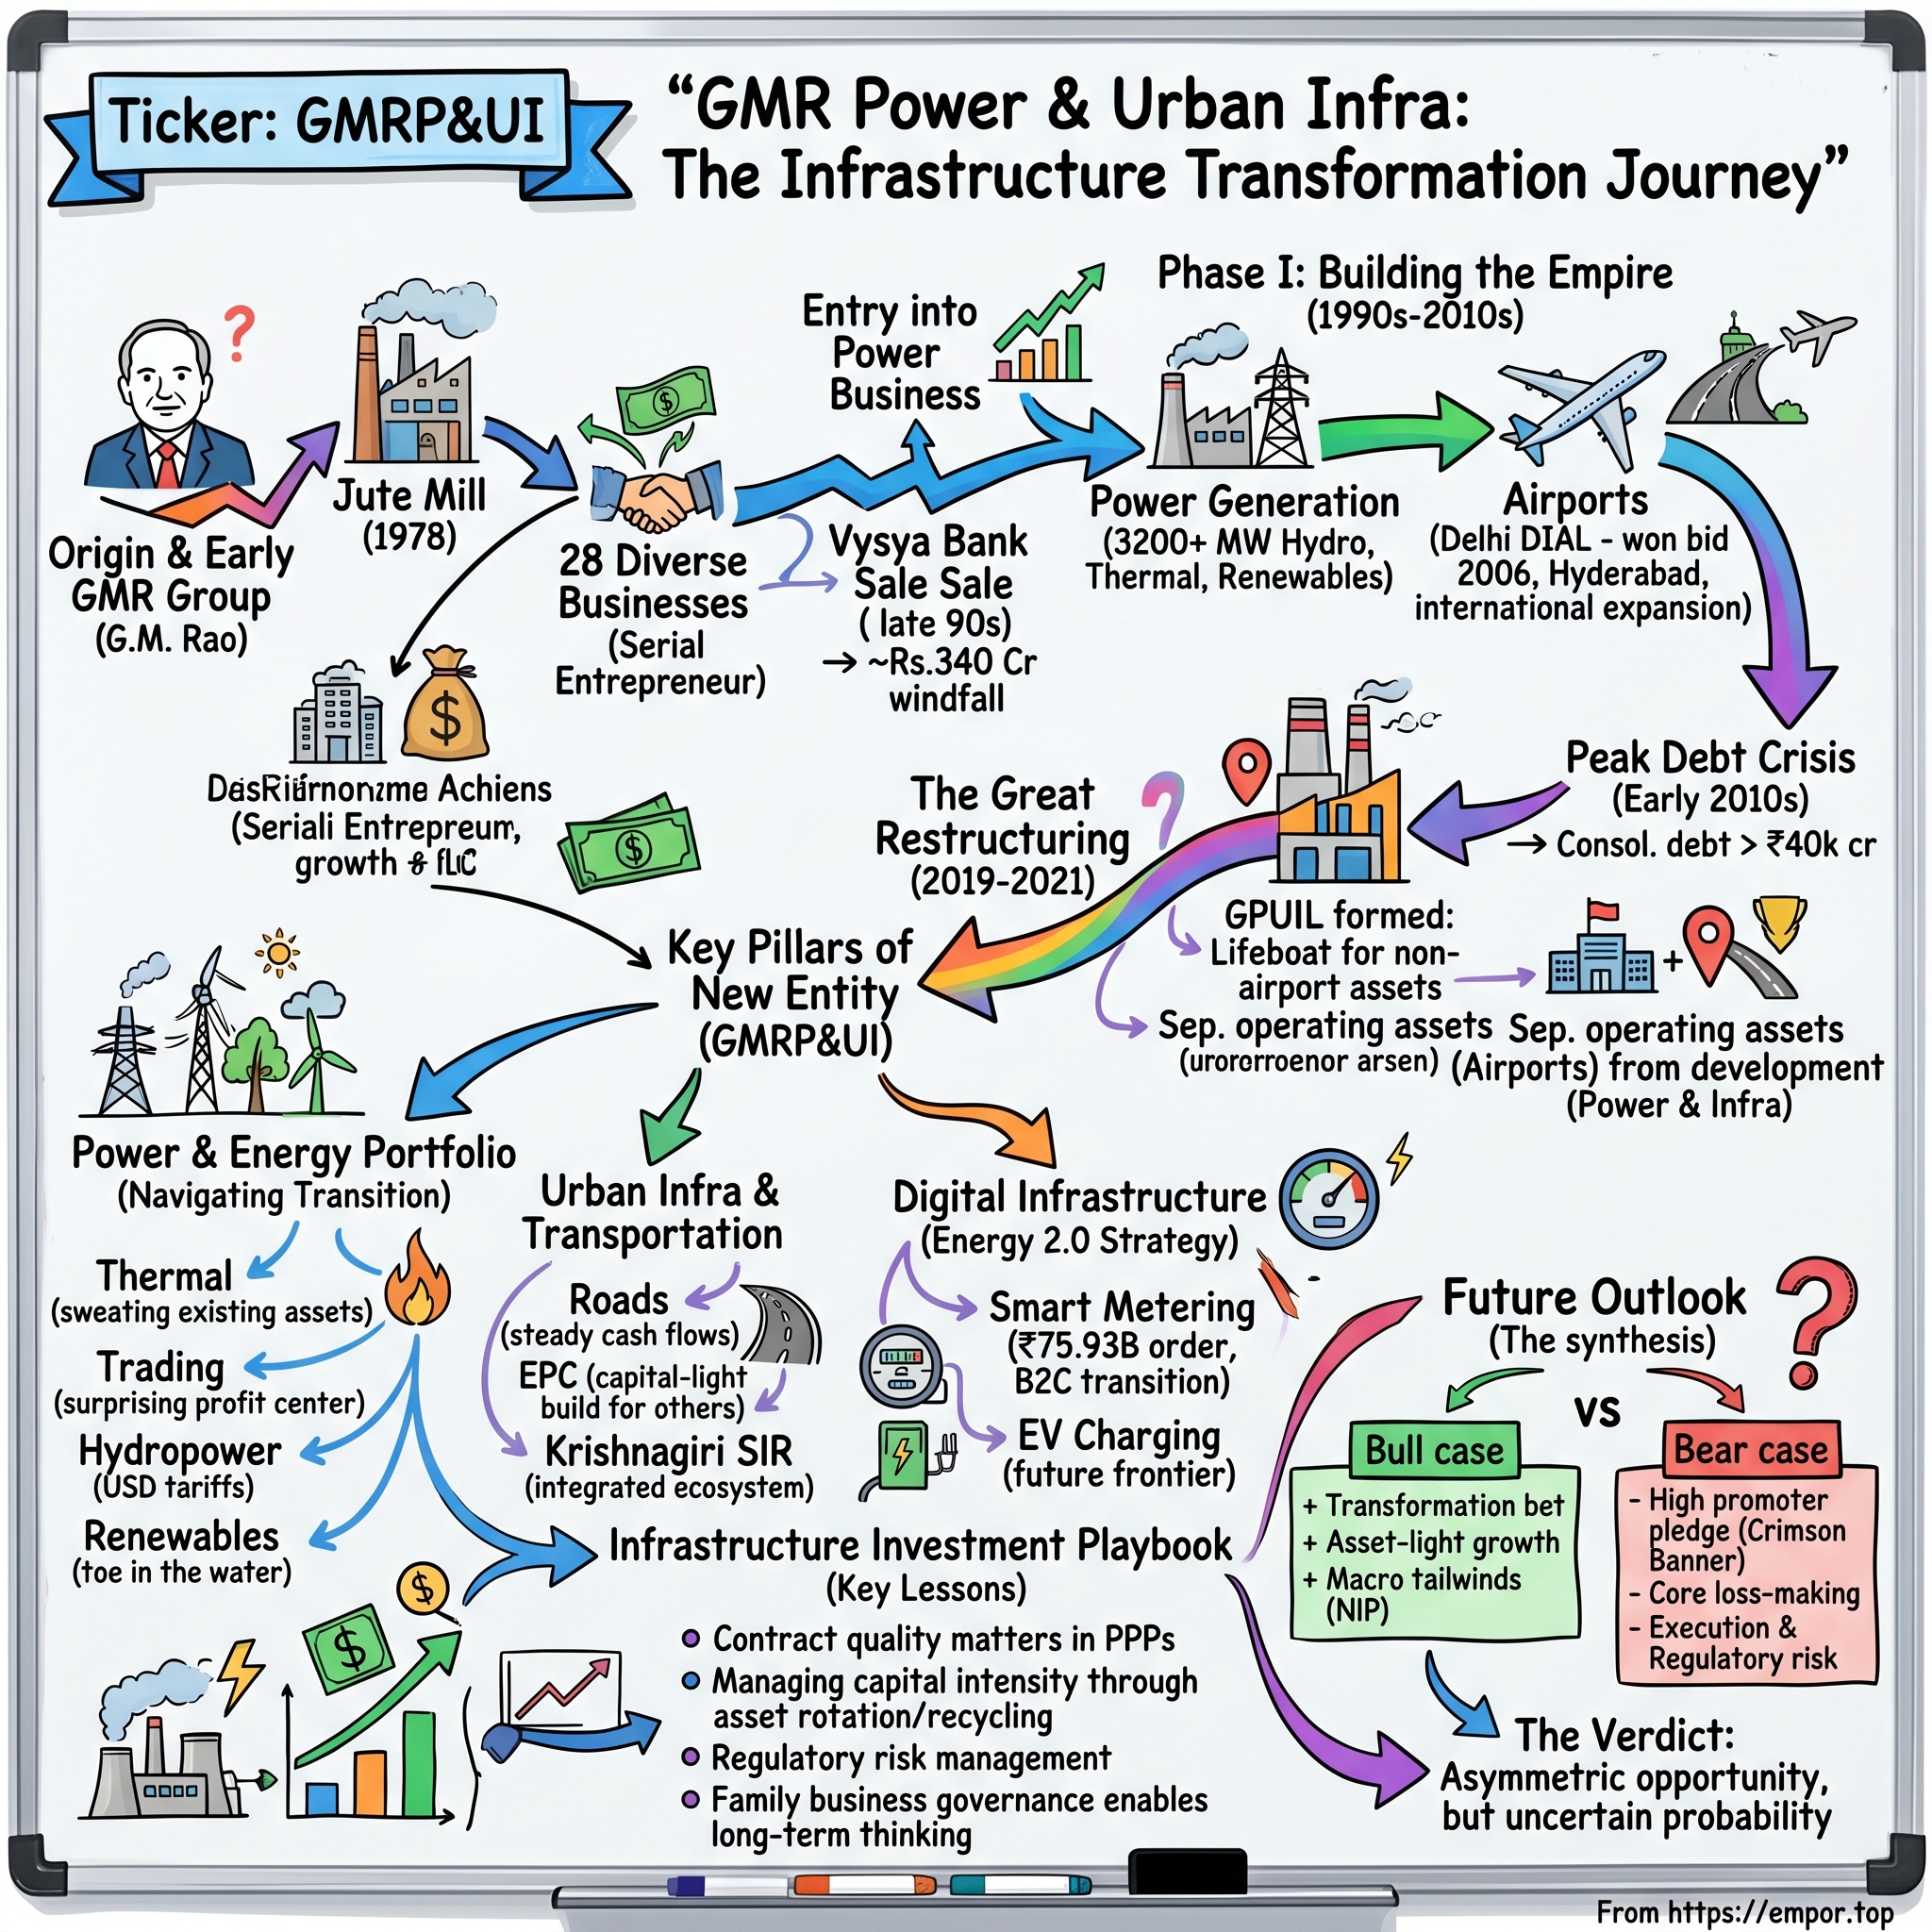
GMR Power & Urban Infra: The Phoenix of Indian Infrastructure
I. Introduction & The Resurrection Blueprint
The Hook: A Stock Nobody Asked For
On March 23, 2022, a new ticker called GMRP&UI started trading on India's two main stock exchanges1. Nobody had applied for its shares, and there had been no initial public offering roadshow or anchor book. Instead, the shares simply appeared in the demat accounts of anyone who had held GMR Infrastructure on the record date of January 12, 2022, distributed at a ratio of one new share for every ten existing shares2. In effect, it was the GMR Group's corporate attic: the collection of legacy assets the family had spent a decade struggling to sell, restructure, or explain.
That attic was crowded. It contained two coal-fired power plants locked in years of courtroom battles with state electricity distribution boards. It held two gas-fired turbines in Andhra Pradesh that had sat idle or under-run since 2016 because domestic gas never arrived. There were toll roads entangled in traffic claims, a dedicated freight corridor railway contract with multi-thousand-crore claims still in litigation, a Himalayan hydropower project, a stalled dam project in Nepal that existed only on paper, and a large industrial land parcel near Hosur. Above all, it carried the debt burden tied to every one of those projects.
The other side of the demerger kept the crown jewels. GMR Infrastructure, subsequently renamed GMR Airports, retained the flagship Delhi and Hyderabad airports in partnership with France's Groupe ADP, establishing itself as India's first listed pure-play airport company in January 20221. The market's initial diagnosis of the non-airport spin-off was unsparing: it looked like a classic corporate "stub"—a workout vehicle whose only purpose was to be slowly liquidated for whatever residual value lenders might leave behind.
Four and a half years later, that skeptical reading has been only partly vindicated. The company's consolidated proforma net debt, which it tracks including joint ventures, dropped from roughly ₹17,500 crore in FY23 to about ₹9,300 crore by June 20263. Its two operating coal plants have run at plant load factors well above the national private-sector average. And in July 2023, a GMR subsidiary secured a ₹7,593-crore contract to install and operate 75.69 lakh prepaid smart electricity meters across 22 districts of Uttar Pradesh4. For a period, public markets bought into the turnaround, sending the stock to a record high in September 20245.
Yet the resurrection remains unfinished. By September 18, 2026, the share was trading around ₹926, well below the ₹120.88 at which the company sold new shares to institutional investors only nine months earlier7. Around its August 2026 board meeting, market capitalisation stood at roughly ₹7,700 crore8. Meanwhile, regulatory uncertainty re-emerged: in May 2026, the Uttar Pradesh government abruptly switched every prepaid smart meter in the state to postpaid billing after consumer protests9. And about 61% of the promoter family's shares are pledged10.
The Demerger Crucible
Under the court-approved scheme of arrangement, the non-airport businesses were carved out into GMR Power and Urban Infra Limited (GPUIL) as a going concern, bundling energy, urban infrastructure, engineering procurement and construction (EPC), and special investment regions. The National Company Law Tribunal's Mumbai bench sanctioned the composite scheme in December 202111. Because the resulting shareholding mirrored that of the parent, every GMR Infrastructure owner woke up holding two companies with very different futures2.
Management countered skepticism by pledging a shift to an "Asset Light Asset Right" posture. Under this strategy, the company aimed to monetize or restructure stranded assets, stop building concrete on its own balance sheet, and grow in services-style infrastructure12. Dalal Street's assessment was considerably blunter: investors treated the airport business as the asset worth owning, while GPUIL was the baggage required to acquire it.
The Core Thesis of This Story
The central question framing this investigation is whether GPUIL has built anything durable, or whether its revival has been primarily propelled by three external tailwinds. The first was an intense thermal power demand boom that pushed Indian coal plants to elevated utilisation rates. The second was a run of court verdicts that finally released years of withheld discom payments. The third was a national smart-metering programme funded by the central government.
Management frames the smart meter contract as the foundation of a predictable, utility-like annuity. This analysis evaluates that claim against the company's operating record, and against a counterparty—the Uttar Pradesh power distribution utilities—that has already altered core contractual terms midway through execution.
The Roadmap
This account traces the group's trajectory from a jute mill in Rajam to Delhi's airport. It follows the debt-driven buildout of 2006 to 2012, the subsequent decade of asset fire sales, and the legal engineering of the demerger. From there, it examines the operational realities of the coal plants, the rollout of the smart meter franchise, the monetization prospects of the Krishnagiri landbank, and the contested railway claims. Finally, it addresses the governance questions—promoter share pledges, equity dilution, and a recurring cast of counterparties—that any long-term investor must weigh before trusting the turnaround.
Before any of that, though, the story begins with the founder whose sheer appetite for scale built this empire and nearly broke it.
 Subscribe on LinkedIn
II. The Founder's Odyssey: G.M. Rao & The Conglomerate Machine (1978–2005)
The Rajam Origins
Rajam sits on the Andhra–Odisha border, a small trading town of agricultural markets and commodity mills. Grandhi Mallikarjuna Rao grew up there, earned a mechanical engineering degree from Andhra University, and in 1972 went to work as a shift engineer at a paper mill in Rajahmundry13. He did not stay salaried for long. A family profile in Business Today recorded a brief stint working for a Public Works Department executive engineer, followed by the venture that defined the next four decades: in 1978, Rao set up a jute mill in his hometown14.
What followed was a serial-entrepreneurial phase that reads, in hindsight, like an apprenticeship for building a conglomerate. Rao tried his hand at roughly 28 businesses13, spanning steel rolling, ferroalloys, sugar, and alcohol distillation14. Few of these operations were glamorous, but they taught him how to navigate Licence-Raj India: securing bureaucratic approvals, managing unionised labour, assembling bank credit, and keeping factories running through chronic grid shortages. That final lesson proved critical.
The Vysya Bank Catalyst
The pivotal breakthrough was financial rather than industrial. Rao had accumulated a substantial equity stake in Vysya Bank, a mid-sized private lender deeply embedded in Andhra Pradesh's trading communities. When the Dutch financial group ING sought an entry point into Indian banking, GMR became the natural seller. In June 2002, ING agreed to acquire a 23.99% block from the GMR Group at ₹626.92 per share, or roughly ₹340.8 crore, raising ING's total ownership to 43.99% of the bank15. Forbes India later estimated Rao's cumulative proceeds from exiting the lender at about ₹560 crore13.
The absolute figure mattered less than the liquidity it unlocked. In the early 2000s, government tenders for Indian infrastructure concessions required bidders to commit unencumbered equity. Rao suddenly held clean, unpledged capital just as New Delhi opened the power, highway, and airport sectors to private investment.
Pioneering Indian PPP
GMR's first power project, a 200 MW diesel plant in Chennai, began operating in 199913. A 220 MW barge-mounted power station followed at Tanir Bavi near Mangalore16. The group then developed the 388.5 MW Vemagiri combined-cycle gas plant in Andhra Pradesh, commissioned in September 200617. Vemagiri's early history provided an ominous precedent: according to rating agency ICRA, the plant sat idle for lack of gas until January 200817. It was an early preview of the domestic fuel shortages that would strand the group's entire gas fleet a decade later.
Highway concessions during the Golden Quadrilateral buildout followed the same template: win a government concession, raise project debt against future cash flows, construct the asset, and collect tolls or state-guaranteed annuities. The group's executive culture was forged around public procurement, where competitive bidding prized winning tenders above long-term operational resilience.
The Family Constitution
Rao's most unusual institutional initiative was not an industrial asset. According to Forbes India, the family council convened for the first time on July 27–28, 2002, and the formal family constitution took "almost nine years to frame"13. The pact granted equal rights to women in the family and provided a structured voice to the next generation13. Business Today detailed a succession protocol in which the family council planned to rotate the group chairmanship after Rao stepped back14. That forum brought together son-in-law Srinivas Bommidala, sons G.B.S. Raju and Grandhi Kiran Kumar, and the founder himself to deliberate on conglomerate direction14.
Corporate observers often credit the constitution with helping GMR avoid the acrimonious succession disputes that fractured rival Indian business houses. On that narrow claim, the public record is supportive: no open family ruptures comparable to those at several peer conglomerates have surfaced.
Myth vs. Reality: Did Governance Discipline Capital?
The broader assertion—that this governance framework instilled institutional discipline over capital allocation—warrants a much more skeptical audit. The constitution was being drafted during the exact decade in which the group committed its costliest capital allocation blunders. A legal charter governing board representation, executive succession, and family dispute resolution is fundamentally distinct from an internal risk framework capable of restraining a founder from overbidding for global utilities at the peak of a credit bubble.
The historical record indicates that the family governance apparatus fulfilled its core mandate: keeping the family united. It was never engineered to shield minority shareholders from the promoter group's collective appetite for debt-fuelled expansion, and it failed to do so. The historical evidence thus narrows the governance narrative: the constitution established succession discipline, not capital discipline. For investors assessing GPUIL today, the critical test is not the existence of the family charter, but whether that same family council now allocates capital with greater restraint. Section VIII returns to that question with fresh evidence from 2025 and 2026.
With unencumbered equity from the Vysya exit, operating credentials from its initial power plants, and an organisational machine built for bidding, GMR stood fully primed by 2005. What followed was the most aggressive bidding spree in the group's history.
III. The Infrastructure Supercycle & The Near-Death Spiral (2006–2018)
The Golden Era of Megaprojects
On January 31, 2006, the Government of India selected the GMR-led consortium to modernise and operate Indira Gandhi International Airport in Delhi, formally signing the Operations, Management and Development Agreement on April 4, 200618. The group had already secured the greenfield Hyderabad airport concession in December 200418. For an enterprise that had started with a single jute mill, winning India's premier aviation gateways was a transformative leap. It gave GMR a halo of execution capability that made commercial lenders eager to finance its grandest ambitions.
Management leveraged that market standing aggressively across the power sector. It planned two large thermal stations: the 600 MW Warora plant in Maharashtra and the 1,050 MW Kamalanga plant in Odisha1920. Both were engineered around the promise of cheap domestic fuel from captive coal blocks and Coal India linkages. Beside its operating Vemagiri asset in Andhra Pradesh, GMR also broke ground on an adjacent 768 MW gas-fired station at Rajahmundry21.
The InterGen Debacle
The group's most audacious gamble arrived in October 2008, weeks after the collapse of Lehman Brothers. GMR agreed to acquire a 50% stake in InterGen, a global power producer with operating plants across the United Kingdom, Australia, and Mexico, for approximately $1.1 billion22. The strategic rationale was global scale and technical expertise, but the timing was disastrous. Worldwide credit markets were freezing just as GMR's domestic capital expenditure cycle required massive cash injections.
Barely two years later, GMR reversed course. On November 28, 2010, China Huaneng Group agreed to acquire the 50% holding for $1.23 billion, with the transaction scheduled to close in the first half of 20112223. At a headline level, GMR recouped its capital with a nominal profit of roughly $130 million. Yet against the high cost of acquisition debt and the immense management bandwidth consumed, the trade yielded negligible real return. InterGen was not a fatal error, but a costly round trip. More importantly, it established a recurring conglomerate pattern: acquiring assets at market peaks with borrowed funds, then selling under pressure when the balance sheet needed liquidity.
PT GEMS and the Coal Hedge That Wasn't
In 2011, GMR acquired a 30% stake in PT Golden Energy Mines, an Indonesian thermal coal producer. It purchased an 18% interest from the Dian Swastatika group and picked up the remaining 12% through the miner's initial public offering24, with reported consideration ranging between $500 million and $550 million in cash[^25]. Management presented the purchase as an operational hedge: owning overseas coal reserves would protect fuel margins for its domestic coastal plants.
In practice, the hedge failed to function as planned. The Indonesian government overhauled its export pricing framework to match international benchmarks, while Indian electricity regulators refused to grant automatic pass-throughs for escalating imported fuel prices. That mismatch triggered a decade of regulatory battles and commercial litigation. When GMR finally divested the stake in 2022, it received $420 million upfront alongside deferred milestone payments25. The total cash recovered fell short of the original outlay, even before accounting for more than a decade of financing and holding costs.
Male: When a Sovereign Changes Its Mind
GMR's international airport concession in the Maldives revealed an entirely different vulnerability: sovereign counterparty risk. On November 29, 2012, an incoming Maldivian administration abruptly repudiated GMR's concession contract to modernise and operate Malé's international airport. An arbitral tribunal ruled the repudiation wrongful in June 2014 and awarded GMR approximately $270 million in damages in October 201626.
The Maldives disbursed $271 million on November 15, 2016. However, $185 million went immediately to Axis Bank to extinguish the project loan, leaving GMR with a net recovery of about $86 million27. The episode demonstrated that while contracts with sovereign counterparties can eventually be enforced in court, "eventually" can take four years—and secured lenders invariably collect their share first. That hard-earned lesson would echo years later in Uttar Pradesh.
The Twin Balance Sheet Crisis Strikes
Back home, GMR's domestic energy portfolio was struck by two structural shocks at the same time.
The first was the collapse of the domestic gas market. The Rajahmundry plant, comprising two 384 MW units, was completed around 2012. But output from Reliance Industries' KG-D6 basin plummeted, leaving the turbines completely stranded21. The plant operated only briefly starting in August 2015 under a subsidized government scheme that auctioned imported liquefied natural gas to idled facilities21. By May 2016, lenders invoked strategic debt restructuring, converting defaulted debt into a 55% equity stake in the project subsidiary21. A subsequent resolution plan in 2019 split the plant's ₹2,353 crore debt burden, classifying ₹1,412 crore as sustainable debt and converting ₹941 crore into cumulative redeemable preference shares21. In an April 2025 interview, managing director Srinivas Bommidala confirmed that the group's gas-fired stations had been non-operational since 201612.
The second shock crippled thermal coal. On September 24, 2014, the Supreme Court of India cancelled 214 coal block allocations, invalidating GMR's captive mining rights28. The 1,050 MW Kamalanga plant had been designed specifically to burn captive coal. Stripped of that supply, it had to buy expensive fuel through spot auctions, the government's SHAKTI linkage windows, and overseas imports. When GMR sought to pass those higher fuel expenses on to state power distribution companies, the utilities refused and withheld payments20.
Group debt escalated sharply. Business Standard reported consolidated debt of around ₹37,000 crore in early 201329, and by fiscal 2016, gross debt stood at ₹37,480 crore30. GMR became a prime exhibit in what the Reserve Bank of India described as the "twin balance sheet" crisis: overleveraged infrastructure conglomerates on one side, and state-owned banks burdened with rising bad debts on the other31.
The Great Selling
To avert insolvency, management executed a classic survival playbook: liquidating premier assets to preserve the parent group. In March 2019, a consortium of Tata Group, Singapore's sovereign fund GIC, and SSG Capital Management agreed to invest ₹8,000 crore in GMR Airports at an equity valuation of ₹18,000 crore32. In February 2020, France's Groupe ADP agreed to purchase a 49% stake in GMR Airports for ₹10,780 crore, valuing the airport holding company at ₹22,000 crore33.
Divesting distressed thermal generation proved far more challenging. In October 2019, JSW Energy agreed to acquire the Kamalanga plant at an enterprise value of ₹5,321 crore34. But that deal fell apart on July 31, 2020, when JSW walked away, citing pandemic-related disruptions and unmet conditions35.
Myth vs. Reality: Did Management Hedge Fuel Risk?
The central premise of GMR's energy strategy was that long-term fuel linkages and power purchase agreements would insulate equity returns from commodity cycles and regulatory shifts. The operating record between 2008 and 2018 refutes that assumption.
The gas turbines were built on feedstock promises that evaporated, leaving neither Vemagiri nor Rajahmundry with contractual recourse to compensate lenders or shareholders when KG-D6 reserves declined. The coal stations operated under power purchase agreements that assumed fuel price increases could be passed through automatically, but state discoms disputed every tariff petition. Kamalanga's dispute with Haryana and Odisha over fuel cost pass-through was settled only when the Supreme Court ruled on September 8, 202520—more than a decade after the coal block cancellations triggered the initial claim.
The financial toll was severe. In March 2025, Rajahmundry's lender consortium accepted a one-time settlement of ₹657 crore against its total exposure across term loans, debentures, preference shares, unpaid interest, and corporate guarantees36. That recovery represented a steep loss against the ₹2,353 crore of debt the facility carried before its 2019 debt restructuring21, while original project equity had long since been wiped out. The narrower, defensible reality is that GMR's contracts provided protection only after years of litigation while cash was withheld. For an equity investor, relying on court decrees years down the road is closer to holding a speculative, long-dated claim than operating behind an economic moat.
By 2020, the group's survival depended on severing its profitable airport franchise from its legacy industrial debt. That corporate partitioning set the stage for the demerger.
IV. The Great Demerger & The Clean-Up Playbook (2019–2022)
The Architecture of a Split
Consider the dilemma confronting Groupe ADP's investment committee in Paris in 2020. They had just agreed to pay ₹10,780 crore for 49% of an airport platform33. Yet the listed entity through which public investors held that business, GMR Infrastructure, was also burdened by stranded gas turbines, coal plants entangled in litigation, toll roads, and an EPC contracting division. Every rupee of cash generated by Delhi and Hyderabad risked being called on—directly or via corporate guarantees—to keep the non-airport ventures afloat. For the airport portfolio to trade at an unencumbered valuation, the legacy liabilities had to be quarantined elsewhere.
The solution was a composite scheme of arrangement among GMR Power Infra Limited, GMR Infrastructure, and a newly incorporated entity, GMR Power and Urban Infra Limited. The Mumbai bench of the National Company Law Tribunal sanctioned the scheme in December 202111. Energy, urban infrastructure, EPC, and special investment regions were transferred to GPUIL as an operating going concern11. Shareholders received one GPUIL share with a face value of ₹5 for every ten GMR Infrastructure shares of ₹1 face value they owned2.
In financial engineering terms, this was a textbook split between a "good company" and a "workout vehicle." Its economic rationale lay less in building new operations than in dismantling a conglomerate discount. Investors seeking pure-play airport exposure could now hold it cleanly, while those willing to wager on a distressed operational workout could price that risk independently.
Balance Sheet Surgery: PT GEMS
The first major balance-sheet surgery arrived six months after listing. On August 31, 2022, GPUIL subsidiary GMR Coal Resources signed a definitive agreement to sell its 30% stake in PT GEMS to PT Radhika Jananta Raya, an arm of Indonesian mining services group PT ABM Investama, for $420 million upfront alongside deferred consideration tied to agreed milestones25. The group received the $420 million by mid-September 202237. Management funnelled the proceeds directly into retiring the expensive offshore debt that had financed the original acquisition. That transaction effectively closed the loop on the overseas coal hedge: roughly a decade of ownership, an ultimate exit below the initial cash outlay, and a considerably leaner balance sheet as the principal prize.
The Listing Reality Check
GPUIL began trading on March 23, 20221. The company spent its initial years as a standalone listed entity working to persuade skeptical investors that it was something more than a slow-motion liquidation vehicle. Disclosures focused single-mindedly on deleveraging. The company's own proforma reporting, which incorporated the debt of joint ventures such as Bajoli Holi and Rajahmundry, showed net debt peaking at roughly ₹17,500 crore in FY23. At that peak, net debt stood at more than six times EBITDA3.
The Clean-Up Continued Past the Listing
The demerger proved to be merely the opening act of the balance-sheet overhaul. Three subsequent transactions played just as large a role in reshaping GPUIL.
Buying out Tenaga. Malaysia's Tenaga Nasional had long held a substantial minority interest in GMR Energy, the intermediate holding company for the Kamalanga and Warora coal plants. On November 22, 2023, GPUIL bought out Tenaga's 29.14% stake for just $28.5 million. The purchase lifted GPUIL's holding from roughly 57.76% to 86.90% and terminated the shareholders' agreement38. The modest price tag reflected the reality of the asset: an overseas strategic partner accepted a nominal sum to walk away. The accounting shift was equally consequential. GMR Energy moved from equity-method accounting to full balance-sheet consolidation, which explained why GPUIL's reported revenue, EBITDA, and debt escalated sharply across FY24 and FY25383. Investors comparing year-on-year headline growth across that period were largely observing an accounting reclassification rather than sudden organic expansion. The final 2.37% interest in Kamalanga was acquired from IDFC First Bank for ₹60 crore on March 30, 2026, bringing project ownership to about 100%39.
The Kuwait bonds and the arrival of Synergy. In December 2015, GMR Infrastructure had raised $300 million by issuing foreign currency convertible bonds to the Kuwait Investment Authority40. Following the demerger, $275 million of those obligations sat on GPUIL's balance sheet. In July 2024, a consortium led by Synergy Capital, a special-situations investment firm founded by Sudhir Maheshwari, acquired the bond portfolio from KIA41. Synergy described the transaction as its largest investment to date41. On July 10, 2024, the $275 million of 7.5% bonds were converted into 11.12 crore newly issued GPUIL shares. The bondholders simultaneously waived ₹1,175.75 crore of accrued interest, an obligation GPUIL booked as an exceptional gain in FY2542. That single accounting waiver formed a substantial portion of why reported FY25 net profit of approximately ₹1,738 crore appeared far stronger than the underlying operational earnings43.
Spinning off the gas plants and Bajoli Holi. On April 13, 2025, GPUIL announced a framework agreement to divest a 79.86% stake in the Bajoli Holi hydro facility, alongside 51% equity interests in both Vemagiri and Rajahmundry, to Synergy Investments Holding for a combined ₹653 crore12. Management indicated that proceeds would fund the Rajahmundry lender settlement, remove roughly ₹4,400 crore of debt from the consolidated balance sheet, and formally carve out non-operating and stressed assets12. The company's announcement emphasised that Synergy was neither part of the promoter group nor a related party12. Legal counsel publicly characterized the divestment as completed by August 202544. By June 2026, GPUIL's corporate structure continued to reflect residual holdings: 49% of Vemagiri and Rajahmundry, and a remaining 9.86% second tranche of Bajoli Holi3.
What the Clean-Up Reveals
It is worth pausing on the recurring presence of a single counterparty across this restructuring: Synergy appeared in three distinct roles within two years. First, it acquired the Kuwaiti convertible bonds and swapped them into equity. Second, it stepped in to take the stranded gas assets and the capital-intensive hydropower project off the company's books. And, as Section VIII details, an entity controlled by the same founder emerged as the lead investor in the company's December 2025 preferential share issue.
Nothing on the public record suggests that these transactions violated corporate regulations; each was formally disclosed, approved, and priced. Yet they concentrated an extraordinary degree of the group's turnaround execution within a single, repeat counterparty. That relationship warrants closer scrutiny than a standard non-related-party disclosure conveys.
The balance-sheet surgery ultimately left GPUIL with a smaller, significantly simplified power portfolio. That streamlined thermal fleet is where the vast majority of the company's cash is generated today.
V. The Power & Energy Portfolio Deep Dive
Two Plants, One Business
Inside the control room at Warora, roughly 100 kilometres from Nagpur, two 300 MW units operated near full output through the summer of 2026, burning coal railed in from nearby Western Coalfields mines. In the first quarter of fiscal 2027, Warora recorded a 90% plant load factor (PLF), while Kamalanga reached 87%. By comparison, the all-India private generator average hovered around 77%3.
Plant load factor measures the proportion of theoretical maximum output a generating station actually delivers—the power-sector equivalent of an airline's load factor or a hotel's occupancy rate. In thermal coal generation, anything consistently above 85% indicates heavy utilisation. Operating stations that once stood as symbols of GMR's balance-sheet distress have turned into some of the most productive private coal assets in the country.
Energy continues to anchor GPUIL's financial profile. In FY26, the energy division generated ₹5,407 crore of the company's ₹7,332 crore consolidated revenue—nearly three-quarters of the top line—and produced ₹1,692 crore of its ₹2,021 crore consolidated EBITDA3. Every other asset in the portfolio, from smart electricity meters to highways and industrial land, remains secondary to the economics of these two thermal stations.
Kamalanga: The Plant the Supreme Court Rescued
The 1,050 MW Kamalanga plant in Odisha serves four primary off-takers. Under long-term power purchase agreements (PPAs), it supplies 263 MW to Odisha's GRIDCO on a regulated cost-plus basis, 335 MW to Haryana, and 288 MW to Bihar. It also maintains a five-year contract to deliver 102 MW to Tamil Nadu's TANGEDCO20. With approximately 93% of its capacity tied up under firm contracts, its uncommitted merchant generation has at times fetched more than ₹6 per kilowatt-hour on wholesale power exchanges20.
The decisive turnaround unfolded in the courtroom. On September 8, 2025, the Supreme Court ruled in Kamalanga's favour in its protracted fuel cost pass-through dispute. The court directed that state discoms share the financial burden of domestic coal shortfalls rather than claiming cheaper linkage supplies exclusively for themselves. In November 2025, Kamalanga received roughly ₹1,083 crore in overdue arrears from Haryana utilities20. Just eighteen days later, on September 26, 2025, another Supreme Court ruling dismissed approximately ₹1,287 crore in claims brought by its Chinese EPC contractor, SEPCO20. Bolstered by these legal victories, CARE Ratings upgraded Kamalanga's long-term bank facilities from BBB to A- on December 11, 202520. The project company subsequently refinanced roughly ₹2,700 crore of debt, reducing its borrowing rate from 12.15% to 9.50%45.
Two qualifications temper this operational recovery. First, the cash injection from Haryana was largely a one-off settlement. Once historical arrears were cleared, the lucrative late-payment surcharge income those overdue balances had generated came to a halt. Kamalanga's FY26 EBITDA fell 18% to ₹943 crore, a decline management attributed in part to the reduction in surcharge receipts3. Second, CARE noted that surplus cash generated by Kamalanga "will be upstreamed to promoters" following the refinancing, subject to lender approval20. For minority shareholders of the listed parent, this serves as a reminder that operating cash flows face senior claims before filtering down to equity.
Warora: Steady, Leveraged, Renewal-Dependent
Warora's 600 MW capacity is underpinned by long-term PPAs for 200 MW with Maharashtra's MSEDCL and 150 MW with TANGEDCO, alongside a medium-term 150 MW agreement with Haryana expiring in March 2029, leaving roughly 91% of capacity contracted19. In October 2025, CARE reaffirmed Warora's credit rating at BBB- with a stable outlook19. That lower rating relative to Kamalanga reflects legacy liabilities: Warora operates under a debt restructuring executed within the Reserve Bank of India's stressed-asset framework, where covenant terms permit lenders to sweep surplus operating cash to accelerate repayment of unsustainable debt tranches19.
Warora delivered ₹570 crore of EBITDA on total income of ₹1,871 crore in FY26, holding its PLF steady at 85% for a second consecutive year3. However, its contracted revenue profile faces renewal hurdles. CARE highlighted that both the TANGEDCO and Haryana agreements expire in September 2028 and March 2029 respectively, designating these renewals as "a key credit monitorable"19. Substantial regulatory receivables from the Dadra and Nagar Haveli distribution licensee also remain tied up on its balance sheet19.
The asset also received an unearned policy reprieve: on July 11, 2025, a Ministry of Environment, Forest and Climate Change notification exempted Warora from mandated capital expenditure for installing flue-gas desulphurisation equipment19. That regulatory relief spared the plant a round of debt-funded environmental upgrades, though such exemptions remain subject to administrative and judicial revision.
The Stranded Gas Fleet and the Hydro Pipeline
Following the asset sales outlined earlier, the stranded gas assets—Vemagiri (388 MW) and Rajahmundry (768 MW)—now sit primarily under Synergy's operational control, with GPUIL retaining a residual 49% stake in each3. Bajoli Holi, the 180 MW run-of-river hydroelectric facility on Himachal Pradesh's Ravi River that synchronized with the grid in March 202246, has also been largely divested. In practical terms, the group monetised its sole operational greenfield hydro project to fund the resolution of its idle gas plants.
That leaves a capital-intensive hydro development pipeline. GPUIL lists 1,425 MW of hydro capacity under development, led by projects such as Talong and Alaknanda3. The largest asset on the drawing board is Nepal's 900 MW Upper Karnali project. Following 18 years of procedural delays, and after Bangladesh scrapped a proposed 500 MW cross-border offtake arrangement, The Kathmandu Post reported in July 2025 that the project structure had been overhauled: India's state-owned SJVN and GMR each took a 34% equity stake, and initial tenders were floated for preliminary site works47. An eighteen-year gap between concession award and initial site works offers an instructive baseline for assessing the real-world timeline of every asset in this development registry.
Myth vs. Reality: "Long-Term PPAs Mean Utility-Style Cash Flows"
On paper, long-term PPAs promise utility-like stability: off-taking distribution companies pay a capacity charge ensuring fixed-cost recovery alongside an energy charge passing through fuel expenses. In practice, GPUIL's commercial history contradicts that theoretical certainty. Kamalanga's state discom counterparties withheld disputed fuel costs for years until the Supreme Court intervened. At the end of the first half of FY26, Kamalanga's total receivables, including contested regulatory claims, stood at approximately ₹2,245 crore—a figure larger than its annual EBITDA20. Similarly, Warora recovered roughly ₹230 crore of historical regulatory dues from MSEDCL and TANGEDCO only after securing favorable court orders in 202319.
The mechanism that improved cash collection was not contract enforcement by the generator, but statutory discipline imposed from above. CARE noted that discom receivables normalised only after the Ministry of Power introduced the Late Payment Surcharge Rules in June 202219. The plants' improved cash conversion stems from an administrative enforcement backstop rather than a proprietary corporate moat.
What survives is a narrower operational reality: GPUIL operates competitive thermal assets with secured fuel arrangements and high grid-dispatch priority, backed by an institutional payment-security regime far more stringent than that of the prior decade. Validating that reality requires maintaining PLFs above 80% and receivable cycles below 90 days without ongoing judicial intervention. The true operational test will arrive in 2028 and 2029, when Warora must recontract half its generating capacity.
For now, these two thermal stations generate the cash that sustains the corporate structure. Yet the investment thesis driving the stock's re-rating hinges on an entirely different asset: a small digital meter mounted outside a residence in Varanasi.
VI. The ₹7,600-Crore Dark Horse: The Smart Metering Pivot & RDSS Economics
The Scene: A Meter That Talks
In a narrow lane in Varanasi, a technician in a GMR-branded jacket unscrews an old electromechanical meter—the kind with a spinning aluminium disc—and bolts in a white box fitted with a cellular communication module. The legacy meter required a meter reader to visit in person once a month, leaving ample room for unrecorded consumption or tampering. The digital replacement transmits consumption data every few minutes directly to a central server. In prepaid mode, it can disconnect supply automatically once a household’s credit balance is exhausted and restore power remotely the moment the customer recharges via mobile phone.
India historically loses a substantial portion of the power it generates between the distribution substation and consumer billing, an operational shortfall known as aggregate technical and commercial (AT&C) losses. For state electricity distribution companies (discoms), those chronic distribution leakages have long formed the bedrock of structural insolvency. Smart metering emerged as New Delhi’s technological remedy, and GMR moved aggressively to position itself as one of the primary infrastructure providers deploying and managing the hardware.
RDSS: The Mandate
The flagship policy driving this shift was the central government’s Revamped Distribution Sector Scheme (RDSS), backed by an outlay of just over ₹3 lakh crore[^49]. The programme established an ambitious initial target: installing 25 crore smart meters across the country by March 202648. Deployment on the ground, however, lagged far behind that timetable. By December 31, 2025, only about 3.9 crore meters had been installed nationwide under the scheme, prompting policymakers to push the target completion deadline to March 202849.
The underlying commercial structure represents the critical economic departure from prior public utility contracts. Under RDSS, cash-strapped state discoms do not purchase the meters. Instead, private Advanced Metering Infrastructure Service Providers (AMISPs) finance, deploy, and operate the entire system on a build-own-operate basis. In return, the AMISP collects a fixed monthly service fee per operational meter over a concession running up to ten years48. In operational terms, the arrangement mirrors a mobile-network handset contract: the vendor absorbs the capital expenditure upfront and recoups its investment through long-term service fees.
GMR's Mega-Win in Uttar Pradesh
On July 24, 2023, GMR Smart Electricity Distribution Private Limited (GSEDPL) secured an order valued at ₹7,593 crore to install 75.69 lakh prepaid smart meters across Uttar Pradesh. Awarded under a design-build-finance-own-operate-transfer (DBFOOT) model with a ten-year concession term, the mandate covered 22 districts—including Varanasi, Prayagraj, Agra, Mathura, and Aligarh—serving two state-owned distribution utilities: Purvanchal Vidyut Vitran Nigam (PuVVNL) and Dakshinanchal Vidyut Vitran Nigam (DVVNL)4. Srinivas Bommidala, then serving as Chairman – Energy, framed the win as a major step in the group's transition "into green and technology-based energy business"4.
Execution was organized across three special-purpose vehicles (SPVs): Kashi (2.73 million meters covering Varanasi and Azamgarh), Triveni (2.29 million meters across Prayagraj and Mirzapur), and Agra (2.55 million meters in Agra and Aligarh)3. GSEDPL holds a 90% equity stake in each project vehicle, while Bosch Global Software Technologies owns the remaining 10% and delivers the core IT architecture under a bundled software integration contract350.
This division of labour highlights the essential operational profile of the business. GMR is neither a meter manufacturer nor an enterprise software developer; it acts as an infrastructure project integrator. It procures physical meters from third-party manufacturers, integrates proprietary software licensed from Bosch, and mobilizes contracted field teams for street-level deployment. In this respect, GMR mirrored its competitors: none of the major corporate bidders that captured Uttar Pradesh's smart-metering packages—a cohort that included Adani, Larsen & Toubro, IntelliSmart, and GMR—manufactured metering hardware in-house51.
The Numbers, and Why the Accounting Matters
The financial trajectory of this new division accelerated rapidly. Smart meter revenue expanded from roughly ₹321 crore in FY25 to ₹1,418 crore in FY2643. Yet statutory reporting painted a subdued operational picture: under Indian Accounting Standards (Ind AS), the segment generated an EBITDA margin of only about 12% in FY26. Performance deteriorated further in the first quarter of fiscal 2027, when the business recorded a slightly negative EBITDA alongside a pre-tax loss of approximately ₹47 crore3.
Alongside its statutory filings, management presents an alternative "proforma" presentation, which it describes as operating asset accounting. This framework capitalizes installed meters as fixed balance-sheet assets and treats incoming utility payments as recurring rental revenue. Under this proforma methodology, the segment's FY26 EBITDA margin stood at an eye-catching 72%3.
The stark difference between 12% and 72% does not point to accounting impropriety; rather, it reflects two distinct accounting representations of the same underlying capital cycle. Statutory Ind AS rules treat the active rollout phase much like an EPC construction contract: procurement and installation costs are recognized immediately alongside project revenue at thin procurement margins, building a financial asset receivable that unwinds across the concession. Management’s proforma lens models the post-commissioning steady state: an operational asset base collecting recurring service fees against modest incremental maintenance outlays.
For public market investors, however, the 72% margin remains a proforma calculation rather than realizable operating cash flow today. Converting that theoretical margin into sustained returns requires state discoms to disburse every contractual monthly fee on schedule for a full decade. Meanwhile, the borrowing required to install the meters has already arrived on the books: net debt allocated to the smart metering division surged from ₹860 crore in March 2026 to ₹1,440 crore by June 20263.
The Installation Curve
Field deployment mirrored that accounting deceleration, recording a burst of initial momentum followed by an abrupt slowdown. GPUIL disclosed approximately 30 lakh cumulative installations by January 26, 202645, climbing to roughly 39 lakh by April 30, 202650, but reaching only around 41 lakh by July 31, 20263. In practical terms, after installing nearly 9 lakh units during the three months leading up to April, field crews deployed barely 2 lakh over the subsequent quarter. Reflecting the drop in installation activity, smart meter revenue fell sharply in the first quarter of fiscal 2027 to ₹225 crore, down from ₹512 crore in the preceding quarter3.
The deceleration was not an operational bottleneck of GMR’s making. In May 2026, state energy policy shifted abruptly.
The Uttar Pradesh Climbdown
On May 6, 2026, the Uttar Pradesh Power Corporation Limited (UPPCL) directed all state discoms to immediately convert every smart prepaid meter across the state to conventional postpaid billing via the central backend platform9. At the time of the directive, approximately 85 lakh smart meters had been installed throughout Uttar Pradesh, roughly 83 lakh of which were operating under prepaid protocols52. Going forward, the state utility mandated that all new metering connections be configured as postpaid52.
The policy reversal followed widespread consumer protests over alleged billing spikes and faulty automated deductions. In several districts, public backlash escalated to the point where residents dismantled digital meters from residential walls and deposited them outside local administrative offices9. Investigative reporting by Swarajya revealed that over 11 lakh deployed units statewide relied on obsolete 2G and 3G communication modems that suffered chronic connectivity failures on modern telecom networks51. Disclosed public records do not tie those connectivity failures to any individual contractor or project vehicle. Regulatory support from the top had already softened: a month before the state decree, Union Power Minister Manohar Lal clarified before the Lok Sabha that prepaid functionality had never been compulsory under federal guidelines53.
For GMR’s underlying concession, the pivot from prepaid to postpaid did not void the project agreements. The installed units retain digital metering capabilities and continue transmitting consumption intervals to utility servers. Where cellular transmission fails, concessionaires remain obligated to deploy staff for physical manual meter reading52. Reporting by Swarajya indicated that monthly per-meter service fees continued to accrue despite the operational shift, though specific fee structures and penalty thresholds remain commercially confidential51.
GPUIL’s August 2026 investor presentation offered no detailed assessment of how the operational transition would affect net collections or penalty deductions. Instead, management disclosed that PuVVNL and DVVNL had officially granted an extension of the milestone completion deadlines for all three project clusters to March 31, 20283.
Myth vs. Reality: "Pristine, Annuity-Style Cash Flows With No Discom Risk"
The investment narrative driving the stock's multi-year re-rating rested on the premise that smart metering represents a high-margin, utility-like annuity entirely shielded from the discom balance-sheet dysfunction that crippled GMR's thermal fleet. A critical audit of the operating record refutes that absolute claim, leaving behind a narrower proposition that remains unproven.
Execution delays are now structural reality. A project originally designed for swift, front-loaded deployment required a multi-year administrative deadline extension to 2028. Three years into the concession, GMR had installed approximately 41 lakh meters, representing roughly 54% of its 75.7-lakh-unit commitment3. This shortfall reflects a nationwide trend under RDSS, which has achieved only a modest fraction of its original deployment ambitions49. While the execution friction is industry-wide, the capital carrying costs and deferred cash flows rest directly on GMR's balance sheet.
Counterparty and regulatory risk remains immediate. The Uttar Pradesh distribution utilities tasked with servicing GMR's monthly billing for the next decade altered a core operating parameter of the entire installed fleet with a single administrative order, responding to consumer discontent9. Prepaid billing was the central technological mechanism intended to restore discom liquidity by eliminating payment defaults before power was consumed. Reverting to postpaid billing reinstates the collection risk that has historically driven state utilities into arrears. While project agreements incorporate payment-security escrows, the group’s prior experiences in Malé and Kamalanga demonstrate that enforcing legal rights against state-backed entities can consume years of litigation while project debt service continues unabated.
Technological and integration risks rest with the concessionaire. As an integrator reliant on external meter suppliers, third-party software vendors, and commercial telecom networks, GMR carries the integration risk between field hardware and utility billing engines. The controversy surrounding legacy 2G and 3G modem connectivity across Uttar Pradesh highlights how technological obsolescence can rapidly translate into political vulnerability.
What survives is a far more qualified business case. If the deployed meter base achieves full system integration and state discoms consistently disburse monthly per-meter fees without punitive SLA deductions, GSEDPL holds a decade-long portfolio of recurring service revenue with significant barriers to vendor replacement. Yet the critical operational metric validating that financial return is not the gross count of meters mounted on walls, but the number of active, integrated meters generating verified, unencumbered monthly fee receipts. Management disclosures have not broken out recurring fee collections from ongoing installation billing. Until that cash generation is verified across successive quarters, equity investors are projecting an annuity from an installation curve that has already experienced its first major policy disruption.
Smart metering represents GMR’s bid to build an asset-light operational future. Realizing value from its legacy footprint, however, depends on monetizing its physical landbank and settling protracted claims from the past.
VII. Urban Infrastructure & Land Monetization: Krishnagiri SIR & Transportation EPC
The Land by State Highway 85
Drive south-east out of Bengaluru, cross the state border into Tamil Nadu at Hosur, and follow State Highway 85. The landscape shifts from congested technology suburbs into the sprawling factory belt that has transformed Hosur into one of southern India’s premier manufacturing nodes. Here, GMR and the Tamil Nadu Industrial Development Corporation (TIDCO) assembled the GMR Krishnagiri Special Investment Region (SIR). TIDCO has described the joint venture as covering 2,101 acres, featuring a 640-acre first phase developed with industrial plots, internal arterial roads, power, water, and sewage treatment infrastructure54. The industrial park targeted manufacturers in automotive, auto components, general engineering, electronics, precision engineering, and defence and aerospace54.
For years, the investment narrative surrounding this asset has rested on the promise of "hidden value." Hosur has emerged as a critical hub for electronics assembly and electric-vehicle production, positioned directly along the Chennai–Bengaluru Industrial Corridor. For multinational corporations seeking to diversify supply chains beyond China, industrial land with pre-approved clearances, existing power infrastructure, and reliable water access offers undeniable strategic appeal.
What Is Actually Left
The critical reality of Krishnagiri in 2026 is how sharply the operational landbank differs from that headline acreage. GPUIL's June 2026 investor presentation recorded an available landbank of approximately 366 acres, edging up slightly from about 347 acres in March 2026350. Within that total, roughly 56 acres remained under discussion for sale to a Tamil Nadu government agency, about 60 acres was planned for the next development phase, and 20 acres had been leased to an industrial client3. The widely cited 2,100-acre figure defines the broader regional development boundary, not the unencumbered land currently ready for monetisation on GPUIL's balance sheet. To date, that single 20-acre lease stands as the only disclosed commercial transaction completed on the property.
Myth vs. Reality: "A Liquid Cash Windfall"
GMR has held this land for well over a decade. The group broke ground on the Special Investment Region in 201855, and the underlying land parcels were assembled years before that56. Yet the operational monetisation record remains modest: one active industrial lease and a single pending sale to a state agency across land carried directly on the company's books. The claim that Krishnagiri represents an imminent, liquid cash windfall is contradicted by the company's own historical pace of execution.
The more defensible framing is long-dated option value. Krishnagiri is a well-positioned industrial asset capable of generating sporadic, lumpy cash inflows over an extended multi-year horizon. For equity investors, the key operational performance indicators to track are closed commercial transactions—measured in acres sold or leased annually and the net rupee value realised per acre—rather than non-binding discussions or preliminary memorandum disclosures.
Transportation and Rail EPC
GPUIL's engineering, procurement, and construction (EPC) division, working alongside a joint-venture partner, constructed a major segment of the World Bank-funded Eastern Dedicated Freight Corridor for the Dedicated Freight Corridor Corporation of India (DFCCIL): packages 201 (Mughalsarai to New Karchana) and 202 (New Karchana to New Bhaupur), spanning roughly 450 kilometres of heavy freight track3. The underlying rail packages have been fully completed and handed over to the client3. What remains on the balance sheet is unresolved compensation. GPUIL has an unbilled prolongation claim of approximately ₹2,829 crore tied up in arbitration and litigation, of which roughly ₹506 crore had been recognised under internal accounting policies as of June 30, 2026, alongside about ₹500 crore of overdue, accounted DFCC receivables3.
This distinction requires analytical precision: a ₹2,829-crore prolongation claim is not a ₹2,829-crore asset. The company's own financial statements have recognised only about 18% of that total. In Indian infrastructure contracting, delay and prolongation claims against state entities routinely face years of contentious dispute resolution and settle at steep discounts to their headline values. For valuation purposes, the DFCC claim is best treated as a long-duration, probability-weighted recovery rather than near-term balance-sheet cash.
The road concession portfolio follows a similar pattern of contested recoveries. GPUIL retains interests in two annuity projects spanning 133 kilometres—Pochanpalli and the Chennai Outer Ring Road—alongside one 35-kilometre toll concession on the Ambala–Chandigarh highway3. At Ambala–Chandigarh, traffic fell 16% in FY26 as commercial traffic diverted onto competing bypass routes. The concessionaire's compensation claim for that traffic loss has shuttled between the Delhi High Court and a special leave petition filed before the Supreme Court by the National Highways Authority of India (NHAI)503. In total, the highway segment generated a net loss of approximately ₹106 crore at the profit-after-tax level in FY263. While market observers have frequently anticipated a clean portfolio exit via an infrastructure investment trust (InvIT), no such divestment surfaced across the company's FY26 or first-quarter FY27 reporting. The primary operational resolution arrived at Pochanpalli, where an amicable settlement of all outstanding project disputes with NHAI delivered a modest one-time gain43.
Across Krishnagiri, the dedicated freight corridor, and the legacy highway portfolio, the underlying pattern remains consistent: expansive headline numbers, sluggish cash conversion, and protracted judicial or administrative timelines. These holdings are not without economic value, but they represent claims and long-dated options rather than immediate liquidity. They should be valued just as the company's own accounting approaches them: conservatively, partially, and late.
That reality leads to the central governance question confronting the turnaround: who decides how any cash these assets produce gets allocated?
VIII. Management, Governance & Capital Allocation: The Family Constitution Under Fire
The People in the Room
G.M. Rao, now in his mid-seventies, remains the founding figure and chairs the family council14. The operating leadership of GPUIL rests with his son-in-law, Srinivas Bommidala, the company's managing director. Bommidala has served on the boards of GMR group entities since 1996 and directed group bids and project development from 1995. In 2006, he became the first managing director of Delhi International Airport, and from 2012 to 2017 he chaired the airports business57. Rao's younger son, Grandhi Kiran Kumar, serves as the GMR Group's corporate chairman57.
Bommidala's tenure at GPUIL carries a clear operational signature. Rather than launching new megaprojects, he has managed a patient workout of legacy liabilities through the courts, lender consortiums, and commercial counterparties. The favorable Kamalanga verdicts, the Rajahmundry debt settlement, the Synergy divestment, and the Tenaga buyout all took place on his watch. That represents tangible execution, but it is execution focused on the balance-sheet cleanup rather than long-term growth. The smart meter contract, the group's only major new commercial bet, is the first real test of whether this leadership team can build a profitable business rather than simply repair an old one.
The December 2025 Preferential Issue
On December 17, 2025, GPUIL's board approved raising up to ₹1,200 crore at an issue price of ₹120.88 per security7. The transaction was split into two parts. Approximately 6.62 crore newly issued equity shares went to two non-promoter institutional investors to raise ₹800 crore: Synergy Industrial and Power Metals Limited committed ₹450 crore, while Credit Solutions India Trust invested ₹350 crore. Alongside the equity shares, 3.31 crore convertible warrants were allocated to Hyderabad Jabilli Properties, a promoter group entity, for ₹400 crore58. According to the postal ballot notice, the company earmarked ₹1,000 crore to repay borrowings and ₹200 crore for general corporate purposes58.
The disclosure tables reveal the ownership structure behind the raise. Synergy Industrial and Power Metals named Sudhir and Sangeeta Maheshwari as its ultimate beneficial owners. The entity already held 8.71% of GPUIL before the issue and was positioned to reach roughly 12.22% after allotment58. This was the same Sudhir Maheshwari whose investment firm had acquired the Kuwaiti foreign currency convertible bonds and taken over the group's stranded gas assets and capital-heavy hydro facility4112. Meanwhile, Hyderabad Jabilli Properties listed its beneficial owners as the founder, his wife, both sons, Srinivas Bommidala, and other family members58.
The shares and warrants were formally allotted on January 28, 202650. The institutional equity investors paid for their shares in full. The promoter entity, by contrast, paid only the mandatory 25% upfront—roughly ₹100 crore—securing an 18-month window to pay the remaining ₹300 crore and convert the warrants into equity50. By June 30, 2026, the company had received ₹900 crore of the total ₹1,200 crore issue, and its monitoring agency reported no deviation from the stated use of proceeds59.
The Warrant Problem
The core governance issue lies in the pricing gap. The warrant conversion price was fixed at ₹120.88 per share. By mid-September 2026, the stock was trading around ₹926. If that discount persists into mid-2027, the promoter group has little financial incentive to pay the remaining ₹300 crore to exercise its conversion rights; in that scenario, the company would forfeit the initial deposit but lose the anticipated equity capital. In practical terms, the warrant structure gave the promoter family an inexpensive call option on market upside. The two non-promoter investors, by contrast, bought shares outright at a premium and remain underwater. For minority shareholders, the message is straightforward: the structure aligned the promoters with equity gains without exposing them to the downside.
The Pledge Overhang
The warrant structure takes on added significance against the backdrop of how the family finances its holdings across the wider group. In June 2026, GMR Enterprises pledged 2.2 crore GPUIL shares, representing 2.82% of the company, to a debenture trustee. The pledge secured ₹300 crore of unlisted debentures issued by another group company, GMR Infra Projects, with a disclosed security cover ratio of just 0.7760. Days later, GMR Business and Consultancy LLP pledged an additional 5.1 crore shares—equivalent to 6.53% of the company—against ₹1,400 crore of debentures issued by GMR Estate Management10. Regulatory disclosures noted that the borrowed funds were earmarked for "personal use by promoters and PACs"10. Following those transactions, approximately 61% of the promoter shareholding stood encumbered10. Over the same period, overall promoter ownership fell to around 46% by June 20268, while an inter-se transfer consolidated roughly a quarter of the company under GMR Estate Management61.
Any assumption that the promoters were reducing pledges in mid-2026 is contradicted by the exchange filings. The June 2026 disclosures confirmed fresh encumbrances. Security cover ratios below 1.0 indicate that the pledged GPUIL shares alone do not cover the underlying debt obligations, suggesting these borrowings rely on collateral or guarantees outside the listed entity's disclosures. For minority shareholders, the transmission mechanism is direct: if the equity price drops sharply, lenders to promoter entities can demand additional margin or liquidate pledged shares, putting mechanical downward pressure on the market price. This encumbrance overhang remains an active vulnerability rather than a historical issue.
The Next Raise
On August 14, 2026, GPUIL's board approved an enabling resolution to raise up to ₹3,000 crore through a qualified institutions placement, foreign currency convertible bonds, or other eligible instruments8. The proposal was put to a shareholder vote at the company's 7th annual general meeting on September 21, 202662, and the voting results alongside the scrutinizer's report were filed with the stock exchanges the following day[^65]. While an enabling resolution does not obligate management to launch an immediate issue, the potential scale is substantial: against a late-August market capitalisation of roughly ₹7,700 crore8, raising the full ₹3,000 crore would involve issuing securities worth nearly 40% of the company's prevailing market value, resulting in significant dilution for existing equity holders.
Myth vs. Reality: "Disciplined Capital Allocation"
Management frames its operating strategy around an "Asset Light Asset Right" posture12. Testing that narrative against recent corporate actions produces a divided verdict.
On the positive side, GPUIL divested its stranded gas assets rather than sinking fresh capital into idle turbines, settled Rajahmundry's debt obligations at a steep discount to book value, refinanced high-cost project debt, and used the majority of its preferential issue proceeds to repay borrowings. Consolidated proforma net debt has fallen by nearly half from its peak in fiscal 20233.
On the negative side, the smart meter rollout remains capital-intensive during its active deployment phase, driving up segment debt. The board sought an expansive ₹3,000 crore fundraising mandate barely six months after raising ₹1,200 crore. The promoter group continues to pledge listed shares to finance unlisted entities outside the public company. And the group's most critical restructuring transactions continue to rely on the same repeat external counterparty.
The aggressive, debt-fueled expansion chronicled in earlier decades has not resurfaced in its original form. Yet the underlying governance framework is largely unchanged. The fairest conclusion is that capital discipline has been enforced by balance-sheet distress rather than institutional self-restraint. Whether that discipline endures once liquidity loosens remains an open question. The key milestones that will show whether capital allocation has genuinely transformed are clear: a sustained decline in promoter share pledges, full promoter warrant conversion into equity, and the strict deployment of any new institutional equity proceeds toward debt reduction rather than speculative expansion.
With the management incentives and corporate governance mapped, the next step is to put the underlying businesses through a formal competitive stress test.
IX. Strategic Frameworks: Porter's 5 Forces & Hamilton Helmer's 7 Powers
War-Gaming the Portfolio
A rigorous way to stress-test GPUIL is to examine how vulnerable its operating divisions are to competitive attack. Which counterparty holds genuine pricing power? What recourse would a state utility or infrastructure agency have if GMR walked away tomorrow? The answers diverge sharply between baseload thermal power and smart metering, illustrating why conventional corporate shorthand—such as labeling the turnaround a "utility moat"—fails to capture the economic reality of the enterprise.
Porter's Five Forces
Bargaining power of buyers: extremely high. GPUIL’s principal customers are state electricity distribution companies, the Dedicated Freight Corridor Corporation of India, and the National Highways Authority of India. These are state-backed monopsonies. They possess the statutory and administrative leverage to delay payments, dispute tariffs before regulatory commissions and appellate tribunals, renegotiate operating terms, or, as Uttar Pradesh demonstrated in May 2026, alter a core technological mode by administrative decree9. Kamalanga’s fuel-cost dispute required a Supreme Court ruling to compel payment20. The dedicated freight corridor prolongation claim remains tied up in protracted litigation3. Across every operating segment, the sovereign or quasi-sovereign counterparty commands overwhelming leverage.
Bargaining power of suppliers: moderate to high. In thermal power, Coal India subsidiaries provide the vast majority of fuel under long-term linkage agreements. At Kamalanga, contracted linkages cover roughly 80% of fuel requirements, forcing the plant to procure the remaining balance through competitive auctions or spot purchases20. In smart metering, GMR procures physical hardware and cellular communication modules from manufacturers such as Genus Power Infrastructures48 while relying on Bosch Global Software Technologies for the central software architecture3. As a pure-play infrastructure integrator, GMR sits directly between an assertive state off-taker and specialized hardware and software vendors. Without proprietary intellectual property or captive component manufacturing, that structural positioning leaves operating margins vulnerable to cost pressures on either side.
Threat of new entrants: low to moderate. Concession tenders under the Revamped Distribution Sector Scheme impose stringent pre-qualification thresholds on net worth, turnover, and balance-sheet capacity, successfully filtering out smaller EPC contractors. However, well-capitalized conglomerates and public-sector platforms face few barriers to entry. In Uttar Pradesh alone, bidding consortiums featured corporate heavyweights including Adani, Larsen & Toubro, and IntelliSmart—a joint venture between the National Investment and Infrastructure Fund and Energy Efficiency Services Limited—with IntelliSmart securing the state's largest single award of 67 lakh meters across western districts51. Capital-intensive qualification criteria keep out startups, but they offer little defense against well-funded domestic giants.
Threat of substitutes: high in power, lower but not zero in metering. Conventional coal generation faces intensifying long-term competition from utility-scale solar, wind, and battery storage systems competing for incremental state utility procurement. That structural shift underscores why Warora’s power purchase agreement renewals in 2028 and 2029 represent an existential commercial hurdle19. In smart metering, measuring electricity consumption is technically unavoidable, leaving the core meter without a direct technological substitute. Yet the policy reversal in Uttar Pradesh proved that prepaid billing—the exact functionality that provided the strongest economic justification for state discoms—remains politically discretionary953.
Rivalry: high. Competitive bidding across highway concessions, rail EPC, and power generation has historically driven project returns toward the developer's cost of capital. In smart metering, contracts are awarded strictly to the lowest qualified bidder on a monthly per-meter service fee. That dynamic concentrates commercial competition into a zero-sum bidding battle upfront, leaving the winning concessionaire locked into that fixed price across a ten-year operating horizon.
Hamilton Helmer's 7 Powers
Switching costs: meaningful in smart metering, but contractual rather than earned. Once an advanced metering infrastructure provider has installed hardware, head-end systems, and meter data management software across millions of households, replacing the concessionaire mid-contract would create severe operational chaos for a state discom. That systemic friction provides genuine inertia across the ten-year concession. Yet this switching cost protects the concession contract, not the contract price. In tariff arbitrations, penalty negotiations, or regulatory disputes, the state off-taker retains the upper hand.
Scale economies: moderate. Grouping 7.57 million meters across 22 contiguous districts delivers tangible operating efficiencies, lowering street-level field-service costs, telecommunications network overhead, and data-centre expenses per active meter3. However, GMR's scale remains regional and considerably smaller than that of national platforms. It functions as a localized field-efficiency advantage within assigned project clusters rather than a structural, industry-wide cost moat.
Cornered resource: weak. The Krishnagiri industrial landbank occupies a favorable corridor outside Hosur, but the developable acreage carried on the balance sheet is modest and faces ample regional competition. The thermal stations operate on standard Coal India linkages accessible to any qualified domestic generator. GPUIL owns no proprietary patents, custom silicon, or exclusive software codebases.
Process power: emerging, and unproven outside litigation. GMR’s clearest institutional capability lies in its three decades of navigating the Indian regulatory labyrinth: managing complex right-of-way disputes, land acquisition, lender consortium negotiations, and multi-tier judicial appeals. The landmark Supreme Court and appellate tribunal victories securing recovery for Kamalanga and Warora demonstrate real institutional persistence in the courtroom2019. Yet the organizational ability to win high-stakes commercial disputes is also a byproduct of operating within concession models that chronically generate them.
Network economies, counter-positioning, and brand: negligible. While the GMR brand carries significant prestige in civil aviation and airport concessions, there is no evidence that public utilities or distribution companies pay a brand premium for electricity generation or smart metering. Management presentations frequently emphasize potential "group synergies," such as utilizing airport real estate as charging hubs for electric vehicle fleets. That concept represents a speculative commercial option rather than a demonstrable economic power3.
What the Frameworks Say Together
Taken together, Hamilton Helmer's and Michael Porter's diagnostic frameworks reveal an enterprise defined by a single weak-to-moderate competitive advantage (contractual switching costs in smart metering), an emerging operational capability (institutional resilience in administrative and legal disputes), and an asset portfolio exposed to state counterparties with overwhelming commercial leverage.
This is not the structural profile of a compounding economic franchise. Rather, it describes a capable, battle-tested infrastructure contractor-operator whose financial returns are dictated by street-level execution, cash-collection cycles, and the blended cost of debt capital. That operating profile carries legitimate investment merit. But equity markets must evaluate and price GPUIL for what it actually is: an infrastructure workout and contracting business, rather than a recession-proof utility or a high-margin technology platform.
That strategic reality sets up the final valuation challenge: what must an investor believe to justify the bull case, and what operating tests would a prudent skeptic demand?
X. The Investment Thesis: Bull vs. Bear & The Historical Falsification Radar
The Activist's Memo
Imagine a deep-value credit fund acquiring a significant stake and presenting its agenda to the board. Its engagement letter would not begin with smart meters. It would focus squarely on corporate architecture, demanding four specific commitments.
First, ring-fence smart-meter cash flows. The metering special-purpose vehicles house the only asset in the portfolio with long-duration contracted revenues. A credit-minded investor would insist that those operational cash flows remain quarantined inside bankruptcy-remote project vehicles, dedicated exclusively to servicing project-level debt and funding shareholder distributions rather than backstopping holding-company liabilities or promoter borrowings.
Second, cap promoter share pledges. With roughly three-fifths of the promoter shareholding encumbered—portions of which secure debentures issued by affiliated group entities for the disclosed "personal use" of promoters10—the fund would require the family council to adopt a binding, downward-sloping pledge ceiling. It would also demand that every rupee of equity proceeds received from warrant conversions be matched by proportionate pledge de-encumbrances.
Third, comprehensively disclose repeat counterparty arrangements. Synergy has acted as distressed bond buyer, asset acquirer, and equity co-investor across an eighteen-month restructuring window411258. The fund would call for an exhaustive, consolidated disclosure of every commercial, deferred, or contingent agreement between GMR entities and Synergy-affiliated platforms, including earn-out mechanisms and the uncompleted Bajoli Holi tranches.
Fourth, report auditable operating performance indicators. Instead of cumulative meters bolted to walls, quarterly reporting should disclose the number of meters active, integrated into utility billing engines, and generating realized service fees, alongside an ageing schedule of receivables due from PuVVNL and DVVNL. Gross installation numbers alone offer little insight into cash generation.
None of these requests is unusual. Each addresses a vulnerability where the investment narrative currently relies on institutional trust, and each provides an observable operational benchmark.
The Bull Case
Cash-flow inflection from smart metering. If the extended project milestone of March 2028 is achieved and Uttar Pradesh distribution utilities disburse monthly service fees on schedule, upfront installation capital expenditure will fall away. At that stage, the operating-asset economics reflected in management's proforma disclosures—which highlighted a 72% EBITDA margin in FY26—would begin translating into realized free cash flow3. The division could then re-rate from an EPC project contractor into an infrastructure yield platform.
Balance-sheet normalisation. Proforma consolidated net debt has already contracted from roughly ₹17,500 crore to approximately ₹9,300 crore3. Kamalanga's project debt refinancing reduced its borrowing costs from 12.15% to 9.50%45, while Warora successfully exited the specified restructuring monitoring period under its stressed-asset framework19. If the outstanding promoter warrants convert into equity and proceeds from future institutional placements are directed to debt repayment, balance-sheet leverage could decline further.
Unrecognised claims and latent assets. The unbilled Dedicated Freight Corridor prolongation claim, the Ambala–Chandigarh highway traffic arbitration, lingering GRIDCO receivables at Kamalanga, unpaid Dadra and Nagar Haveli regulatory dues at Warora, the second monetization tranche of Bajoli Holi, and industrial land sales at Krishnagiri all represent potential liquidity outside the current recurring earnings base32019.
Baseload coal assets in a supply-constrained power market. Both thermal power stations continue to operate at plant load factors well above the national private-sector average3. Kamalanga has also fortified its forward revenue profile by securing a 25-year, 100 MW power purchase agreement with Karnataka at a levelised tariff of ₹5.78 per unit, scheduled to begin in April 202720.
The Bear Case
Discom payment gridlock and counterparty friction. Uttar Pradesh's abrupt policy pivot from prepaid to postpaid smart metering underscored that state distribution utilities can unilaterally reshape operating models overnight9. If recurring service-fee disbursements face administrative disputes or penalty deductions, GSEDPL would carry escalating balance-sheet leverage—having reached ₹1,440 crore in net borrowing by June 2026—against deferred receivables3. That working-capital strain mirrors the precise liquidity trap that paralyzed the group's thermal generation assets for a decade.
Operating profits remain thin beneath one-off gains. While reported profit after tax from continuing operations stood at roughly ₹587 crore in FY26, that figure included ₹964 crore of exceptional income; before exceptional credits, the company incurred a consolidated pre-tax loss of approximately ₹304 crore3. FY25 profitability was similarly buoyed by an exceptional ₹1,176-crore interest waiver on converted foreign currency bonds42. In the first quarter of fiscal 2027, continuing operations posted a net loss of around ₹35 crore3. Stripped of debt forgiveness and non-recurring items, the operating business remains near accounting breakeven.
Equity dilution and pledge overhang. A shareholder-approved enabling resolution to raise up to ₹3,000 crore in fresh equity overhangs a company with an August 2026 market capitalisation of approximately ₹7,700 crore8, while roughly 61% of the promoter family's shares remain encumbered10. These twin conditions create meaningful structural supply risk for public market equity holders under both orderly share issuance and abrupt market corrections.
Thermal contract expiration risk. Warora's power purchase agreements with TANGEDCO and Haryana expire between September 2028 and March 202919. Recontracting that capacity at profitable tariffs within a national grid expanding utility-scale renewable generation backed by battery storage represents an acute commercial test.
The Historical Falsification Radar
Across four decades of conglomerate expansion, corporate distress, and subsequent restructuring, the operating record provides a rigorous baseline to audit core investment assumptions.
The assertion that the family constitution enforces disciplined capital allocation was narrowed. The charter effectively prevented internal succession disputes, but it coexisted with the peak-cycle acquisitions of InterGen and PT GEMS alongside an unsustainable debt spiral.
The assertion that long-term power purchase agreements yield predictable, utility-like cash flows was narrowed. Counterparties eventually settled outstanding balances, but receipts materialized only after years of multi-tiered litigation and an administrative payment-security overhaul that GMR did not initiate.
The assertion that smart-metering concessions provide pristine, low-risk annuities was rejected in its strong form. Concession execution timetables were extended to 2028, and state administrators overhauled the operational mode by administrative fiat. A narrower claim remains unverified by historical cash conversion: if paid on schedule, these contracts deliver sticky, long-duration service fees.
The assertion that legacy landholdings and arbitral claims represent imminent cash windfalls was rejected on timing. Disclosed corporate filings confirm only a 20-acre industrial lease at Krishnagiri and an internally recognized ₹506-crore portion of an unresolved ₹2,829-crore railway prolongation claim3.
The assertion of an institutionalized transition to asset-light capital discipline remains intact but unproven. The balance-sheet workout is genuine, but mounting debt within the smart meter rollout, an enabling resolution to raise ₹3,000 crore, and elevated promoter share encumbrances indicate that the capital allocation test is still running.
The KPIs That Matter Most
Three primary metrics determine whether the corporate turnaround is compounding durable economic value or merely recycling balance-sheet obligations.
-
Smart meters live, integrated, and collected. The critical operational metric is not physical installation volume, but meters connected to utility backend platforms that generate verified, unencumbered monthly service-fee collections. This cash realization is the only mechanism that converts management's 72% proforma EBITDA margin into actual balance-sheet liquidity.
-
Consolidated net debt to EBITDA. The company reports a proforma version of this leverage metric, tracking a reduction from above 6x in FY23 toward approximately 4.5x by June 20263. Whether that multiple continues to compress as smart-meter capital expenditure unfolds provides the definitive measure of balance-sheet normalisation.
-
Promoter share pledge percentage. Encumbrances stood at approximately 61% of total promoter holdings following transactions in June 202610. The quarterly trajectory of this metric offers the most transparent indicator of whether borrowing demands across unlisted promoter entities are diminishing or expanding.
The final evaluation belongs to what this corporate evolution illustrates about the broader landscape of Indian infrastructure development.
XI. Epilogue & Playbook Lessons for Emerging Market Infrastructure
The Lessons
Capital-heavy public-private partnerships rarely compound equity when both the buyer and the fuel supplier are state monopolies. GMR's coal plants became viable operations only after a decade in which state distribution utilities withheld contracted payments and fuel allocations were rewritten from above. Equity investors who financed those plants in 2010 endured years of courtroom battles and lender debt restructurings before seeing an operational return. The primary lesson for investors in any Indian infrastructure developer is to scrutinize fuel pass-through clauses and statutory payment-security mechanisms before examining power purchase agreement tenors. The contract tenor indicates how long the concession lasts; the clauses determine whether it actually pays.
Corporate unbundling can unlock value, but it does not create it. Separating the airport portfolio from legacy industrial operations allowed two fundamentally distinct businesses to be valued on their own terms. The airport division secured an experienced international strategic partner, while GPUIL received a dedicated mandate to resolve stranded assets. Yet what gave the workout vehicle value was not the financial engineering of the demerger itself, but a sequence of subsequent external catalysts: favorable Supreme Court decrees, national late-payment surcharge reforms, a specialized counterparty willing to acquire stressed assets, and a nationwide surge in thermal power demand.
Asset-light is a strategic direction, not a completed destination. GPUIL describes its operating posture as "Asset Light Asset Right"12, and its primary commercial bet is a long-duration utility service concession. Yet delivering that service requires substantial debt-funded capital expenditure during the installation phase, its ultimate payer is a state-owned monopsony, and its underlying economics depend on regulatory policies that the counterparty has already altered by administrative decree. While emerging-market infrastructure may increasingly tilt toward service providers rather than concrete-pourers, the policy reversal in Uttar Pradesh offers a sober reminder: service contractors ultimately inherit the exact same sovereign counterparty risk that challenged asset builders before them.
Final Reflections
Viewed from a distance, GMR Power and Urban Infra presents a compelling corporate survival case. A company that public markets initially treated as a liquidation stub has reduced its proforma net debt by nearly half, turned two once-stranded thermal plants into heavily dispatched baseload generators, secured the largest commercial contract in its history, and negotiated an exit from capital-draining assets that few market buyers wanted.
Look closer, however, and the structural vulnerabilities remain acute. Milestone completion for the smart-metering concession has been deferred to 2028 after state authorities abruptly switched operating protocols in response to consumer protests. Headline accounting profitability remains heavily buoyed by non-recurring credits and debt waivers rather than core operating cash flows. The promoter family encumbered additional shares in 2026 rather than reducing pledges. And an enabling resolution authorizing up to ₹3,000 crore in fresh equity capital leaves existing shareholders facing meaningful potential dilution.
Whether GPUIL is ultimately remembered as a durable turnaround in Indian infrastructure, or merely as a skillfully managed, ongoing high-wire act of emerging-market leverage, will not be determined by management presentations. It will be decided by a concise set of verifiable operating numbers reported across the coming quarters: active meters generating verified monthly fee collections, debt steadily compressing, and promoter share pledges being permanently released.
References
-
GMR Power and Urban Infra starts trading in bourses — Business Standard, 2022-03-23 ↩↩↩
-
GMR Infrastructure Limited Demerger: Record date, share allotment, what should investors do? — Zee Business, 2022-01 ↩↩↩
-
GMR Power and Urban Infra Investor Presentation – Q1FY27 — BSE Filing, 2026-08-14 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
GMR Smart Electricity Distribution Company bags Rs 7593 crore contract for smart meter installations in UP — Business Today, 2023-07-24 ↩↩↩
-
GMR Power freezes in 5% upper circuit, hits record high — Business Standard, 2024-09-24 ↩
-
GMR Power and Urban Infra Ltd stock quote (18/09/2026) — Mirae Asset Sharekhan, 2026-09-18 ↩↩
-
GMR Power Board Approves Preferential Issue to Raise Up to ₹1,200 Crore — India Infoline, 2025-12-17 ↩↩
-
GMR Power & Urban board meet Aug 14 for ₹3,000 cr fundraise — Multibagg Market Pulse, 2026-08 ↩↩↩↩↩
-
UP govt rolls back smart prepaid electricity meter system, all users shifted to postpaid — Upstox News, 2026-05 ↩↩↩↩↩↩↩
-
GMR Power and Urban Infra: Promoter pledges 5.1 crore shares for ₹1,400 crore debt — Whalesbook, 2026-06-16 ↩↩↩↩↩↩↩
-
GMR Infrastructure gets NCLT nod for demerger of non-airport business — Business Standard, 2021-12-23 ↩↩↩
-
Media Release: Divestment of stake in non-operating and stressed assets — GMR Power and Urban Infra (NSE Filing), 2025-04-13 ↩↩↩↩↩↩↩↩↩
-
For GM Rao, family legacy matters — Forbes India, 2015-11-26 ↩↩↩↩↩↩
-
India's new business families: GM Rao cements — Business Today, 2011-04-17 ↩↩↩↩↩
-
ING to buy 24% Vysya stake for Rs 340.8 crore — Business Standard, 2002-06-21 ↩
-
GMR Vemagiri Power Generation Limited Rating Rationale — ICRA, 2016-01-18 ↩↩
-
Press Release: GMR Warora Energy Limited — CARE Ratings, 2025-10-13 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Press Release: GMR Kamalanga Energy Limited — CARE Ratings, 2025-12-11 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Finding a Resolution: GMR Rajahmundry Energy — Power Line, 2019-05-20 ↩↩↩↩↩↩
-
China Huaneng to Pay $1.23 Billion for InterGen Stake — Bloomberg, 2010-11-28 ↩↩
-
GMR to divest its 50% share in InterGen — Business Standard, 2010-11-29 ↩
-
India's GMR Energy buys into Indonesia's Golden Energy Mines — The Asset, 2011-08-15 ↩
-
GMR Group to divest 30% stake in Indonesia's PT GEMS for $420 mn — Business Standard, 2022-08-31 ↩↩
-
GMR wins $270 million arbitration award in Maldives airport dispute — Business Standard, 2016-10-27 ↩
-
Maldives pays US$271m in damages to India's GMR — Maldives Independent, 2016-11-17 ↩
-
Coal blocks: Supreme Court cancellation and its fallout — Business Today, 2014-11-20 ↩
-
GMR Infra set to sell more assets to offload debt — Business Standard, 2013-03-05 ↩
-
GMR Infra shares zoom nearly 20% on reduction in FY17 debt — Business Standard, 2017-06-02 ↩
-
Financial Stability Report Archives — Reserve Bank of India ↩
-
Tata, GIC, SSG to pick up Rs 80 billion stakes in GMR's airport unit — Business Standard, 2019-03-27 ↩
-
France's Groupe ADP to buy 49% stake in GMR Airports for Rs 10,780 crore — Business Today, 2020-02-21 ↩↩
-
JSW Energy to acquire 100% stake in GMR Kamalanga Energy for Rs 5,321 crore — Business Today, 2019-10 ↩
-
JSW Energy terminates Rs 5,321 crore acquisition of GMR Kamalanga power plant — Business Today, 2020-07-31 ↩
-
GMR Rajahmundry Energy Ltd updates on OTS — EquityBulls, 2025-03 ↩
-
GMR Coal Resources receives USD 420 mn for divestment of 30% stake in PT GEMS — Business Standard, 2022-09-16 ↩
-
GMR Power and Urban Infra acquires 29.14% stake in GMR Energy — MoneyWorks4Me, 2023-11-22 ↩↩
-
GMR Energy Nears Full Control of Kamalanga Power Plant with Rs 60 Crore Stake Buy — TipRanks, 2026-03-30 ↩
-
GMR Infrastructure raises $300 mn from Kuwait Investment Authority — Business Standard, 2015-12-04 ↩
-
Synergy Capital Acquires GMR Group Convertible Bond Portfolio from Kuwait Investment Authority — Synergy Capital, 2024-07-11 ↩↩↩↩
-
GMR Power & Urban Infra Ltd Management Discussions — India Infoline ↩↩
-
GMR Power and Urban Infra: Smart meters surge, energy stays resilient in FY26 — Multibagg Market Pulse, 2026-05-23 ↩↩↩
-
SAM Advises GMR Energy on Divestment of Stake in SPVs Operating Power Plants to Synergy Investments — SCC Times, 2025-08-14 ↩
-
GMR Power and Urban Infra Limited Releases Q3FY26 Investor Presentation — ScanX, 2026-02 ↩↩↩
-
GE commissions 180 MW Bajoli Holi hydro project in Himachal Pradesh — GE Vernova, 2022-07-06 ↩
-
After 18 years, GMR proceeds with Upper Karnali hydropower works — The Kathmandu Post, 2025-07-18 ↩
-
India's huge bet on smart electricity meters — The Daily Brief by Zerodha, 2025-10 ↩↩↩
-
Progress on Smart Meter Installation under RDSS — Press Information Bureau, 2026 ↩↩
-
GMR Power and Urban Infra Investor Presentation – Q4FY26 — NSE Filing, 2026-05-22 ↩↩↩↩↩↩
-
UP's Smart Meter Climbdown: Yogi Might Manage Political Costs, But Governance Damage Is Harder to Undo — Swarajya, 2026-05 ↩↩↩↩
-
UP Govt scraps smart prepaid meter system, shifts all consumers to postpaid mode — PSU Watch, 2026-05-08 ↩↩↩
-
Union Power Minister says prepaid smart meters not mandatory for consumers — All India Radio News, 2026-04-02 ↩↩
-
GMR Krishnagiri SIR — Tamil Nadu Industrial Development Corporation (TIDCO) ↩↩
-
GMR Infrastructure lays foundation stone of proposed GMR Krishnagiri Special Investment Region — Business Standard, 2018-08-27 ↩
-
GMR Infra procures 280 acres of land in Tamil Nadu — Business Standard, 2013-05-07 ↩
-
Srinivas Bommidala — GMR Varalakshmi Foundation Board, GMR Group ↩↩
-
Postal Ballot Notice: Preferential Issue of Equity Shares and Warrants — GMR Power and Urban Infra (NSE Filing), 2025-12-17 ↩↩↩↩↩
-
GMR Power and Urban Infra Files SEBI Monitoring Report on Rs 1,200 Crore Preferential Issue — TipRanks, 2026-08-14 ↩
-
GMR promoter pledges 22 million shares, representing 61.07% of holding — ScanX, 2026-06 ↩
-
GMR Power inter-se transfer lifts stake to 24.91% — Multibagg Market Pulse, 2026-06-23 ↩
-
Notice of the 7th Annual General Meeting — GMR Power and Urban Infra (BSE Filing), 2026-08-27 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube