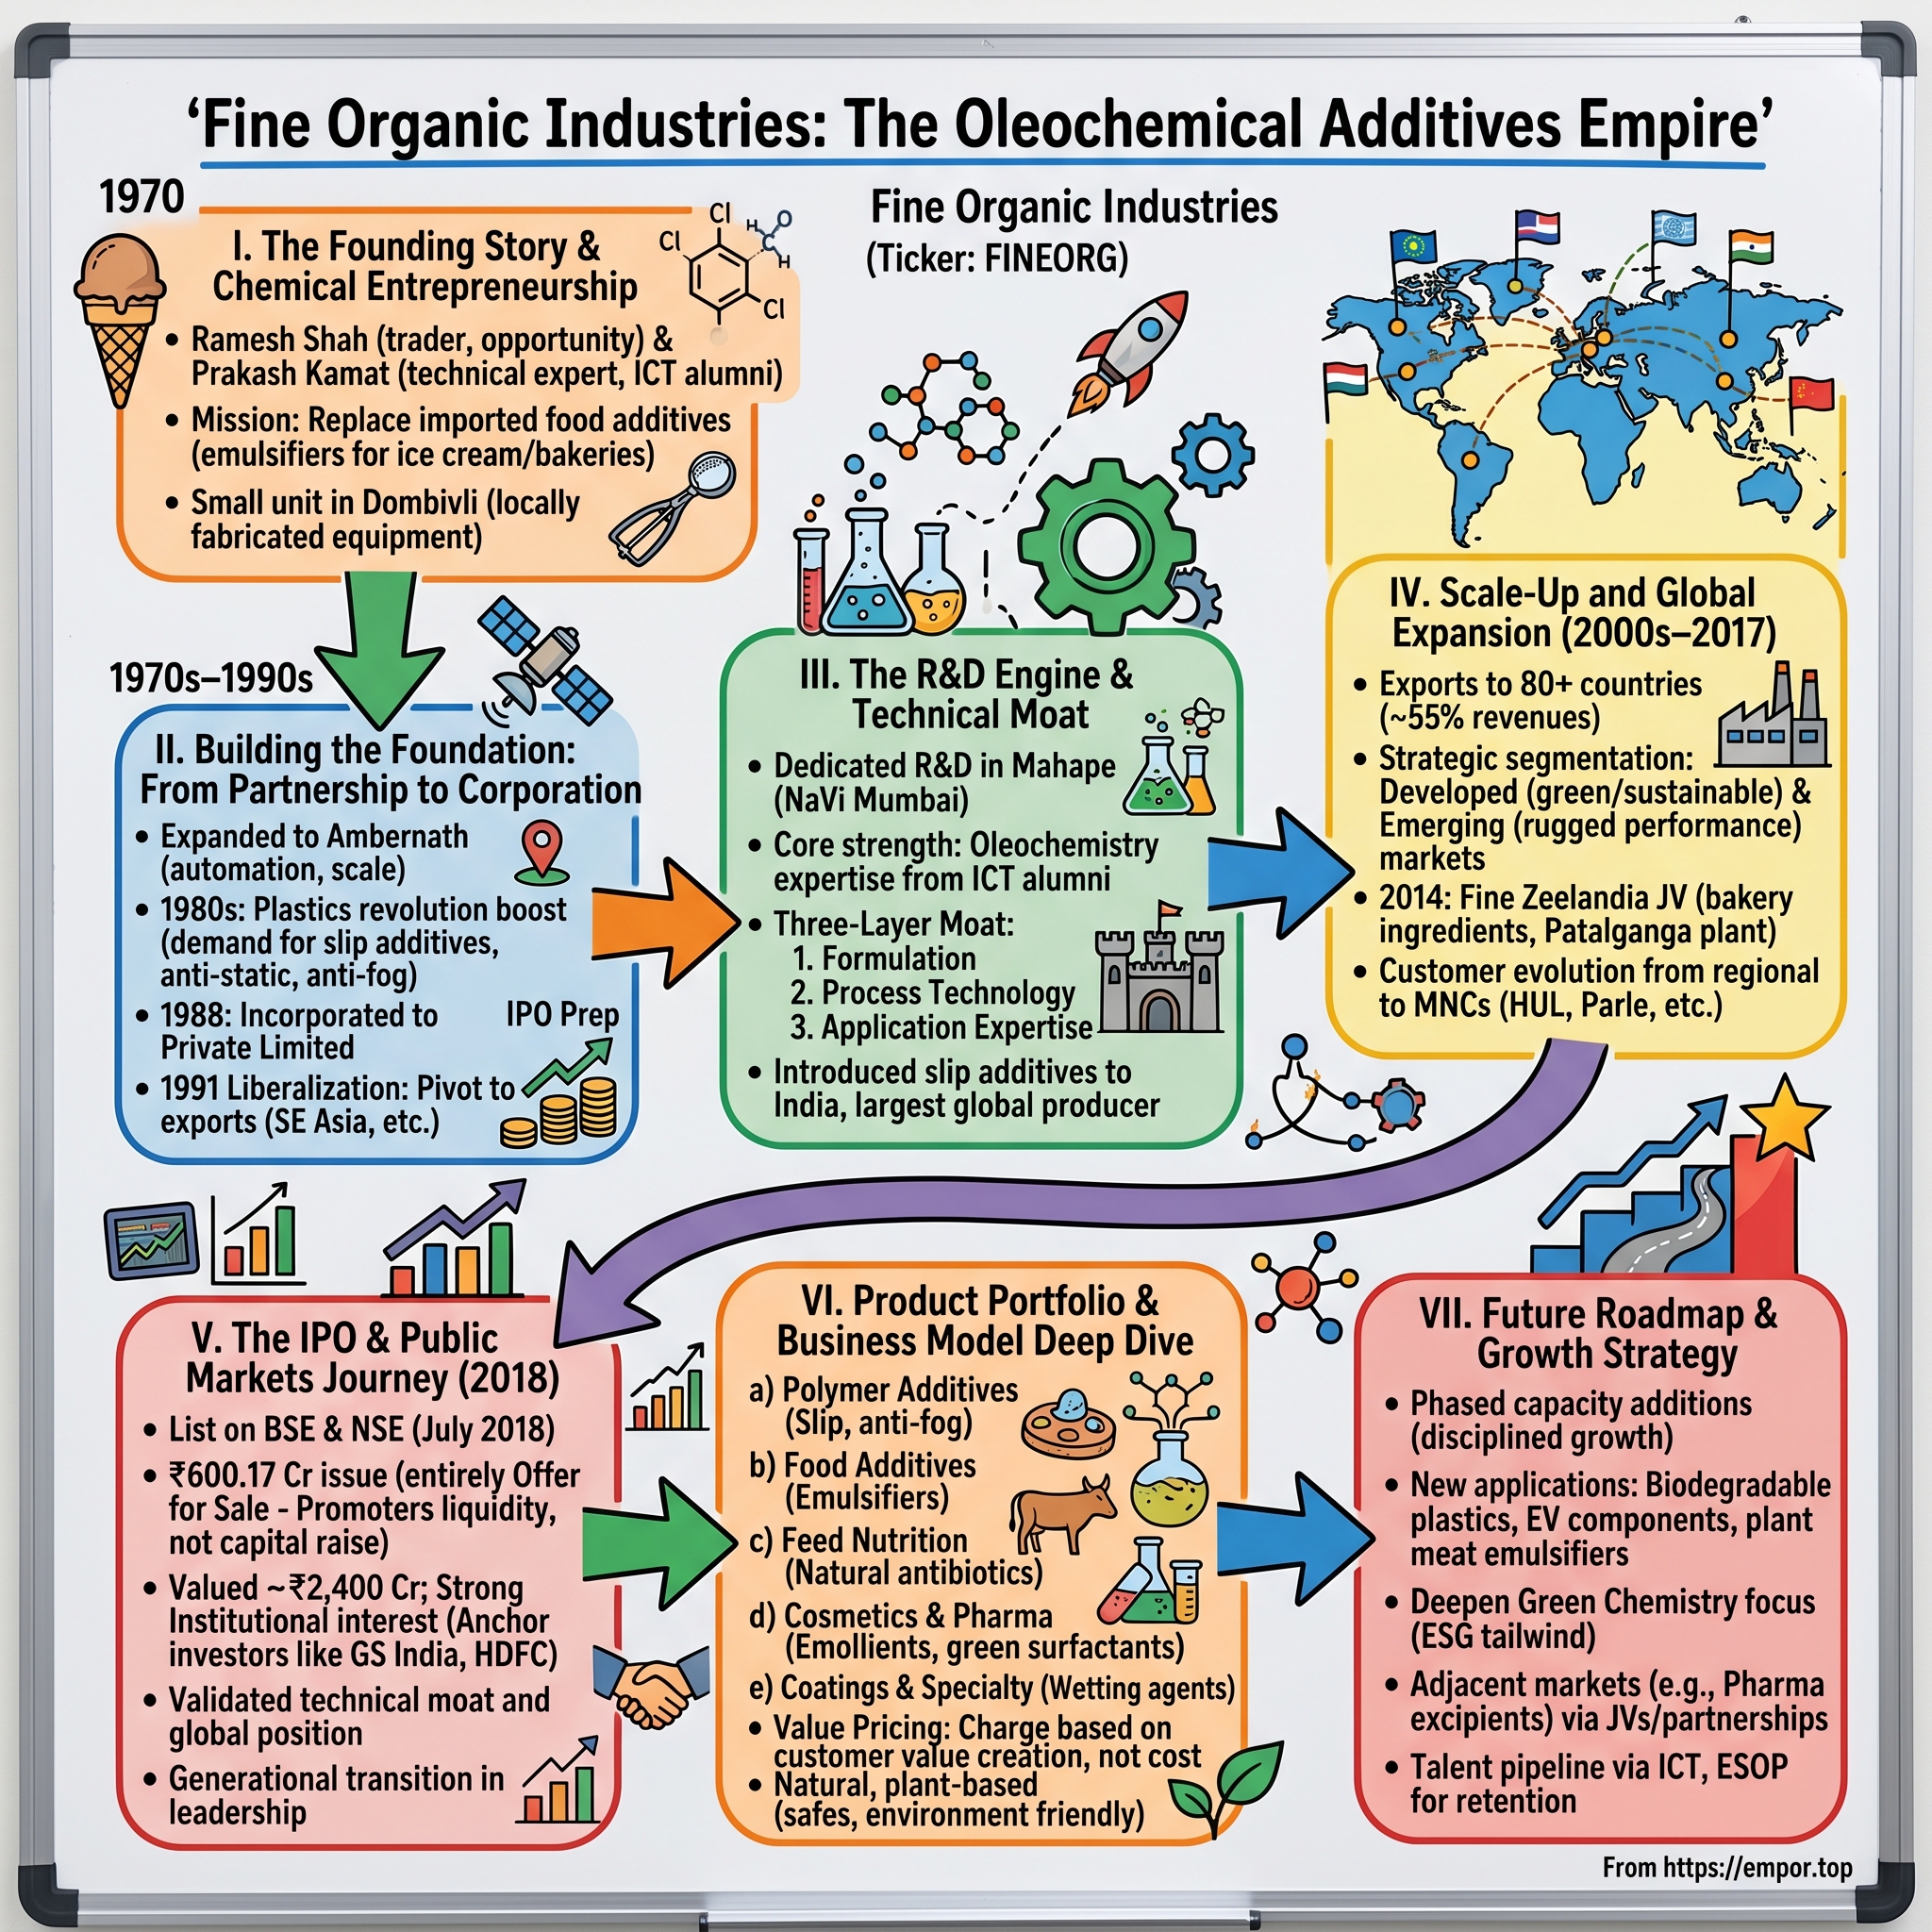
Fine Organic Industries: The Oleochemical Additives Empire
I. Introduction & Episode Roadmap
There is a distinct category of industrial supplier that remains unfamiliar to general observers yet essential to its customer base. Across polypropylene film operations in Gujarat, masterbatch compounding facilities in Sharjah, or automated bakery lines in Indonesia, plant chemists rely on specialized additives to prevent plastic film from adhering to itself or to stop dough from tearing during high-speed processing. In many cases, these additives consist of white flakes or beads produced in Ambernath, Maharashtra, by a manufacturer that attracted little public market attention until its listing in the summer of 2018.
That company is Fine Organic Industries, listed on the National Stock Exchange of India as FINEORG.9 The company manufactures oleochemical additives—such as slip agents, anti-blocks, anti-fogs, anti-statics, emulsifiers, anti-crystallizers, and bio-based surfactants—derived from vegetable fats rather than petrochemical inputs. It sells roughly 450 products into more than 80 countries.3 It maintains this operating model with no long-term debt, a cash balance that has at times exceeded ₹1,000 crore, and a board governed by the founding family alongside the technocrat who co-founded the business in 1970.3
The investment thesis centers on a debt-free market leader holding a strong position in Indian polymer slip additives, an established global role in a niche sector often bypassed by major chemical conglomerates, and a five-decade operating history in oleochemistry—a branch of chemistry increasingly supported by global environmental regulations.
While established within its sector, the company's overall scale remains modest by global chemical industry standards. Fine Organics has operated in a revenue band around ₹2,200 crore to ₹2,400 crore in recent years, with net profit in the ₹400 crore range and EBITDA margins that management has described as normalizing into a low-twenties corridor after a post-COVID spike.34 Return on equity has run in the mid-twenties on an unleveraged balance sheet—a metric achieved entirely through operational earnings rather than debt leverage.2
This financial profile highlights a central analytical question: in an industry where raw material costs track Sumatran palm oil prices and shipping economics depend on global maritime routes, how much of Fine Organics' performance reflects durable manufacturing capabilities, and how much stems from cyclical commodity and shipping movements? Promoters of the stock point to specialized process knowledge and high customer switching costs, while critics attribute peak earnings to temporary inventory gains and freight cost pass-throughs.
Both arguments present empirical support, requiring a systematic review of the company's operating history and financial structure.
The business trajectory follows several clear developments: the initial 1970s venture in Mumbai producing vegetable-fat emulsifiers to replace constrained imports; the strategic shift from bakery ingredients to higher-margin plastic additives; the technical foundation built on esterification processes and close ties with the Institute of Chemical Technology; and the structural protection provided by three-to-five-year customer qualification cycles. The evaluation also covers the 2018 public listing, the financial mechanics of the post-pandemic demand surge, a critical assessment of the primary bullish assumptions, and corporate governance dynamics—including management's statement that internal execution bandwidth represents its primary growth constraint.
The story begins with the market conditions of 1970s India, when import restrictions forced domestic manufacturers to develop local chemical capabilities.
 Subscribe on LinkedIn
II. The Post-Independence Chemical Landscape & The Founding Bet (1970–1988)
In 1970, a bakery owner in Bombay seeking a cake emulsifier—such as glyceryl monostearate, which keeps fat and water from separating in batter—faced severe supply barriers. Producing it domestically was rare; the primary suppliers were located in Denmark, Germany, and the United States. Obtaining imported additives required an import license, tightly rationed Reserve Bank foreign exchange, and months of waiting.
This supply constraint reflected the broader landscape of India's post-independence License Raj. The domestic chemical industry focused primarily on bulk commodities like fertilizers, caustic soda, and basic acids. Specialty inputs—additives used in fractions of a percent to ensure product performance and stability—arrived irregularly from abroad. For entrepreneurs capable of solving the underlying technical challenges, this structural gap presented a clear commercial opportunity.
Ramesh Shah, a chemical trader, understood the market's acute friction points through daily interaction with local buyers struggling to secure emulsifiers, stabilizers, and related additives. Prakash Kamat brought technical execution from the University Department of Chemical Technology (UDCT, later the Institute of Chemical Technology), an institution responsible for training a substantial share of India's chemical process engineers and entrepreneurs.
In 1970, the two formed a partnership firm.[^2] The division of labor paired market intelligence with chemical synthesis: one partner identified specific customer shortages, while the other developed the corresponding reaction processes. This arrangement created a direct feedback loop between buyer complaints and process adjustments.
The initial commercial focus was straightforward: replace imported food emulsifiers for local bakeries and ice cream manufacturers with locally synthesized plant-based derivatives.[^2] The venture did not invent new molecules; it synthesized established additives domestically to provide local customers with shorter lead times.
The accidental fifty-year bet
The founders chose vegetable fats—such as palm, sunflower, and rapeseed oils—rather than petrochemical feedstocks. This choice stemmed from practical availability rather than environmental foresight, as India possessed domestic fat sources but lacked a reliable petrochemical feedstock chain in 1970.
However, this decision committed the company to oleochemistry. Oleochemistry splits triglycerides from vegetable oils into fatty acids and glycerine, synthesizing them into esters, amides, and specialized derivatives. Petrochemistry, by contrast, builds molecules up from cracked hydrocarbons. The two disciplines rely on different processing equipment, impurity controls, and technical skill sets.
Decades later, regulatory shifts in Europe and North America accelerated restrictions on petrochemical inputs—including per- and polyfluoroalkyl substances (PFAS) and phthalates—while consumer demand pushed clean-label formulations in food and cosmetics. Consequently, a manufacturing approach adopted out of raw material necessity aligned with a growing global regulatory preference for bio-based inputs. This outcome demonstrates how long-term technical specialization can yield strategic advantages when external market conditions shift, rather than a master strategy planned in 1970.
To scale production, the founders established their first dedicated manufacturing facility in Dombivli, northeast of Mumbai.[^2] The primary value of the Dombivli plant lay less in volume than in operational discipline. Synthesizing food-grade emulsifiers required running esterification reactions to precise endpoints and purifying the output to meet strict food-industry standards. Mastering reaction engineering, distillation, and quality control established an institutional baseline that the company later leveraged when expanding into polymer additives.
This technical foundation set the stage for the strategic pivot that ultimately transformed the company's growth profile.
III. From Domestic Import Substituter to Polymer Additive Champion (1988–2010)
The moment a chemist realizes that the molecule sold to a bakery can also solve a friction problem in a plastics plant is the moment a niche supplier finds a scalable path.
In 1988, the partnership restructured into Fine Organic Industries (Mumbai) Private Limited.[^2] Incorporation reflected expanding commercial ambitions, but the more consequential evolution was in the product mix.
Why plastic film needs fat
The underlying technical challenge in flexible packaging is straightforward. Polyethylene and polypropylene film—used in packaging, wrappers, bags, and agricultural mulch—emerges from an extruder hot and sticky. When layers stack together, they adhere. Run through high-speed packaging equipment, the film jams, stretches, or tears. Plant engineers refer to this as a coefficient-of-friction problem: the film is simply too adhesive against itself.
The solution lies in slip agents. Erucamide and oleamide are fatty acid amides synthesized by combining plant-derived fatty acids with an amide group. Blended into the polymer melt in minute quantities, the additive migrates to the surface as the film cools, forming a microscopically thin, lubricating layer. The film slides smoothly, enabling machinery to operate at full speed.
Achieving this outcome requires precise chemical execution. If the additive migrates too slowly, the film remains sticky at conversion; if it migrates too quickly, the chemical blooms on the surface, hazing the film and impairing printing ink. Migration rates depend on chemical purity, melting behavior, particle morphology, and resin compatibility. Rather than a basic commodity, the additive acts as a precise performance specification sold in flake or bead form.
Fine Organics expanded into this category systematically, developing slip agents first, followed by anti-fogging agents to prevent moisture condensation on food wrappers and greenhouse films, anti-static agents to prevent dust accumulation and static cling, and specialized processing aids.3
Why this was better business than bakeries
While food emulsifiers offered steady demand, polymer additives provided three structural advantages for the company's growth trajectory.
First, favorable customer cost economics. Because an additive represents a fraction of a percent of a film's total weight but determines whether production lines function, buyers face asymmetrical risk: the operational loss from a failed additive far outweighs any modest savings from a cheaper alternative.
Second, volume scalability. Global demand for flexible plastic packaging expanded rapidly, with every ton of resin requiring additive dosing. While food emulsifiers grew alongside domestic bakery consumption, slip agents scaled with global packaging output.
Third, high switching barriers created by qualification cycles. Replacing an emulsifier in a food formulation requires testing and recipe adjustments. Replacing an additive in food-contact packaging requires the film converter to re-validate the material, while end-brand owners must re-qualify their packaged products. This multi-tiered regulatory and technical approval process creates durable customer retention.
Manufacturing infrastructure expanded alongside demand. Fine Organics developed facilities at Ambernath and Badlapur within the Maharashtra industrial corridor, incorporating multi-stage purification, distillation, and flaking and beading equipment required to produce uniform additives for automated resin dosing.[^2]3
Displacing the giants at home
During the 1990s and 2000s, Fine Organics steadily displaced multinational chemical suppliers across the domestic market. This competitive gain relied on localized technical support rather than pure price discounting.
Indian plastic converters operated diverse machinery across varied resin grades, frequently dealing with variable feedstock quality. Rather than standard global grades shipped from Europe with long lead times, local plant managers required custom formulation tweaks and rapid troubleshooting. Operating within Maharashtra allowed Fine Organics to deliver within days and dispatch application engineers directly to customer facilities.
This responsive model produced a dominant domestic footprint in key polymer additive segments, with industry analysts estimating its market share in core slip additive categories at approximately 90%.[^10] While this figure represents an estimate across un-censored niche categories rather than the entire chemical sector, it underscores Fine Organics' position as the primary supplier for Indian film converters.
International expansion followed through rigorous qualification processes. Global masterbatch manufacturers and resin producers across the Middle East, Europe, and Asia began qualifying the company's additives during the 2000s.[^2] Each approval required years of testing, but once established, these credentials proved resilient against competing suppliers.
By the end of the 2000s, the company had established its modern operating framework: a concentrated manufacturing base in Maharashtra, a revenue mix weighted toward polymer additives, a stable food-ingredients division, and an expanding export footprint.
IV. Technical Moat, The ICT R&D Engine & Oleochemical Esterification Chemistry
Evaluating Fine Organics' competitive protection requires examining the chemical engineering within its reactors.
What the company actually does
The manufacturing process begins with vegetable oil, such as palm kernel oil. Chemically, vegetable oils consist of triglycerides—three fatty acid chains attached to a glycerine backbone. Splitting the oil yields free fatty acids and glycerine.
Synthesizing derivatives requires rebuilding these molecules. Attaching a fatty acid to an alcohol produces an ester. Combining a fatty acid with glycerine in controlled ratios creates mono- or di-glycerides, such as glyceryl monostearate. Reacting a fatty acid with ammonia generates an amide, such as the slip agent erucamide. Adding ethylene oxide units to a fatty alcohol forms an ethoxylate, which serves as the backbone for mild surfactants. Fine Organics' portfolio is essentially the systematic exploration of this space: esters, amides, and derivatives built from fatty acids and glycerine.3
The primary commercial barrier lies not in basic synthesis, but in operational consistency. Competent chemical engineers can produce basic glyceryl monostearate; the difficulty comes from manufacturing high-purity batches consistently at commercial yields over decades.
Esterification is an equilibrium reaction that yields a broad product distribution—containing mono-, di-, and tri-substituted molecules alongside unreacted raw materials, color impurities, and odor compounds. Because customers typically require a narrow product specification, plant operators must drive reactions to precise endpoints before separating components using multi-stage high-vacuum distillation, often near temperatures where molecules risk thermal degradation.
The operation resembles distilling perfume rather than spirits: process parameters are highly temperature-sensitive, mixtures discolor if overheated, and the distinction between a premium batch and off-spec inventory depends on minor variations in degrees and residence times. Proprietary operational parameters for hundreds of product variants reside in internal process sheets and institutional memory rather than standard textbooks.
The talent pipeline
This technical complexity relies directly on the company's relationship with the Institute of Chemical Technology (ICT) in Mumbai, reflected in a deep, multi-decade recruiting and collaboration relationship with India's premier chemical engineering school.[^10]
While many specialty chemical companies claim strong internal research capabilities, the structural mechanism here is unusually focused: a specialized oleochemical manufacturer located near the country's primary chemical engineering institution, continuously recruiting graduates for decades and offering career paths dedicated to a single chemical discipline rather than rotating talent across diverse divisions.
In strategy frameworks, such an advantage resembles a cornered resource, though it remains incomplete. Competitors can also recruit ICT graduates. The core advantage lies in retention: process chemists who spend fifteen years refining fatty amide crystallization develop specialized institutional knowledge that is difficult to replace or replicate elsewhere.
The approval cycle
Commercial protection is further reinforced by regulatory and customer validation timelines. Polymer additives used in food-contact packaging films must satisfy regional food-contact standards, including U.S. Food and Drug Administration (FDA) rules and European Food Safety Authority (EFSA) frameworks. Film converters must validate additive performance on specific machinery, while consumer brand owners conduct separate product-qualification trials. Combined, qualification at a top-tier global customer runs roughly three to five years.[^10]
Customer economics reinforce this inertia. Because an additive accounts for less than one percent of total film manufacturing costs, switching suppliers to achieve a modest price discount yields minimal savings relative to the operational risk. Changing additives requires years of engineering validation, regulatory re-filings, and potential disruption to continuous production lines.
This dynamic creates substantial switching costs for established accounts. However, this protection functions symmetrically: while high switching barriers protect Fine Organics from displacement at existing customers, they equally delay the company when attempting to win accounts from incumbent suppliers.
Portfolio and IP
The resulting product portfolio spans polymer additives, food ingredients, the CosPha personal care line of bio-based surfactants, feed nutrition, and specialty coatings, encompassing roughly 450 products and 80-plus countries.3
Intellectual property protection relies primarily on trade secrets rather than patents. Because core oleochemical ester molecules are widely known, the primary defensible assets reside in process design: catalyst selection, reaction endpoint management, distillation train configuration, crystallization parameters, and custom formulation libraries developed for specific customer applications. Patenting these techniques would require public disclosure, whereas maintaining operational secrecy protects proprietary methods.
For investors, trade secret protection carries distinct trade-offs. While trade secrets do not expire, they offer no legal recourse against independent rediscovery and rely entirely on workforce retention. The durability of this moat depends on maintaining low turnover and expanding the process library faster than competitors can replicate it.
That expanding operational library set the stage for scaling manufacturing capacity.
V. Global Scale-Up, Joint Ventures & The Pre-IPO Inflection (2010–2018)
During the 2010s, Fine Organics transitioned from a domestic manufacturer exporting surplus volume into an integrated global supplier operating out of India.
Manufacturing capacity expanded first. Throughout this period, the company expanded its facilities in Ambernath and Patalganga, raising total installed capacity from tens of thousands of tonnes per annum into six-figure territory across its integrated plants.[^2]3 This expansion pattern set a template for future capital expenditure: brownfield and greenfield projects funded entirely through internal cash generation, engineered in-house, and designed for low capital cost per tonne. In an industry selling performance-based additives with commodity-linked raw materials, minimizing capital expenditure per unit of capacity remains critical to maintaining high return metrics.
The Zeelandia JV: moving downstream
In 2015, the company formed a 50:50 joint venture with Netherlands-based Zeelandia International to manufacture bakery ingredients—including premixes, release agents, and related specialty formulations—for the Indian market.12
Strategically, this represented a shift downstream into formulated products. While supplying standalone emulsifiers to bakeries functions as an ingredient sales model, selling finished premixes moves closer to the end user, capturing higher value and establishing direct insight into customer technical requirements rather than competing solely on procurement specifications.
The partnership structure reflected management's risk preference. Zeelandia brought downstream bakery application expertise that Fine Organics lacked as a chemical manufacturer. Structuring the venture as an equal partnership—rather than pursuing an acquisition or licensing agreement—allowed management to expand application capabilities while preserving balance-sheet discipline.
Operationally, the Fine Zeelandia joint venture has remained a modest financial contributor relative to Fine Organics' overall revenue. Rather than serving as a major earnings driver, the venture illustrates management's operating template: pursuing incremental, low-risk downstream expansion through joint ventures with established category specialists.
Thailand: going to the feedstock
A second joint venture focused on upstream supply security rather than downstream formulation. Fine Organics established a joint venture operation in Thailand to position polymer additive production closer to Southeast Asian palm feedstock sources and regional conversion hubs.3
The economic logic addressed freight inefficiency and regulatory friction. Palm kernel derivatives originate in Indonesia, Malaysia, and Thailand. Importing raw materials to Maharashtra for synthesis and subsequently re-exporting finished additives to Southeast Asia incurred double shipping legs and transit delays. Operating in Thailand reduced logistics costs, provided a hedge against shifting Malaysian and Indonesian export duties on palm oil, and placed production directly within a major regional packaging market.
However, translating this supply-chain logic into operational scale encountered execution delays, with progress moving significantly slower than initial project timelines suggested.
The distribution machine
Parallel to its manufacturing joint ventures, Fine Organics expanded a global distribution network comprising roughly 180 distributors across more than 80 countries, driving export sales toward a majority of total revenue.3[^10]
In specialty additives, distribution requires ongoing technical support rather than routine order fulfillment. Channel partners serve as front-line application engineers, troubleshooting issues such as film clarity or migration speed directly at converter facilities. Developing this global network through multi-year customer qualifications created an uncapitalized commercial asset that fortified the company's international reach.
By 2017, Fine Organics exhibited a distinct financial profile: a dominant position in domestic polymer additives, growing export sales, high return metrics, a debt-free balance sheet, and a founding leadership team evaluating long-term liquidity and governance. Preparing for an initial public offering represented the next phase in its corporate structure—offered in a format that reflected management's view of its internal capital requirements.
VI. The 2018 IPO, Promoter OFS & Public Market Valuation Economics
Unlike most public offerings in India designed to raise fresh capital, Fine Organic Industries' initial public offering was structured entirely as an Offer for Sale.
The company filed its draft prospectus with the Securities and Exchange Board of India (SEBI) in February 2018 and completed the public transaction in June 2018.[^2]1 The business raised no primary equity, adding no proceeds to its balance sheet. Instead, existing shareholders sold 76.6 lakh shares at an upper price band of ₹783 per share, generating approximately ₹600 crore that went entirely to the selling promoters and early investors.17
Reading the structure
An entirely secondary offering highlighted three structural attributes of the business.
First, the company did not require external equity. Operating with zero debt, self-funded capital expenditures, and strong return metrics, the business generated sufficient internal cash flow to fund its expansion without diluting existing equity holders.
Second, the transaction provided liquidity for the founding family. After nearly five decades of private operation, the promoter group held the vast majority of its net worth in an unlisted entity. The sale enabled partial monetization for estate planning, generational ownership transitions, and portfolio diversification.
Third, the public listing served as a formal governance mechanism. Subjecting the family-governed firm to continuous reporting disclosures, quarterly financial reporting, and minimum public shareholding requirements established an institutional framework designed to endure beyond the founding generation.
The listing and the argument
The stock listed in early July 2018 at ₹815 per share, representing a modest 4% premium over the issue price and valuing the company at approximately ₹2,400 crore, or roughly 30 times trailing earnings.7
This measured market debut reflected a core analytical debate over the nature of Fine Organics' earnings model.
Skeptics viewed the company primarily as a chemical processor operating between volatile palm feedstock prices and competitive downstream markets. From this perspective, gross margins depended heavily on the spread between agricultural raw material costs and finished additive prices. Assigning a 30-times earnings multiple to a processor vulnerable to Malaysian palm oil price swings, critics argued, exposed investors to cyclical risk.
Proponents, by contrast, emphasized the company's financial metrics and product complexity. They noted that commodity processors rarely maintain mid-twenties returns on equity without leverage across multiple operating cycles. Furthermore, managing roughly 450 product variants requiring customer-specific formulations signaled an application-focused business selling tailored technical solutions rather than high-volume commodity tonnage, allowing capital to compound efficiently without debt.
What the market concluded
Over the next five years, public market valuations leaned heavily toward the bullish thesis. Continuous operational execution, internal capital compounding, and a sharp earnings surge in fiscal years 2022 and 2023 propelled the stock above ₹7,000 per share during the broader chemical sector rally.8
However, this valuation expansion carried subtle risks. A significant portion of the re-rating coincided with an extraordinary earnings peak that management later acknowledged reflected unsustainable post-pandemic market conditions rather than a permanent step-change in underlying earning power. Expanding valuation multiples during peak cyclical earnings created a compounding effect on the stock price, leaving valuations vulnerable when market conditions normalized.
VII. Business Model & Segment Deep-Dive: Polymer, Food, CosPha & Specialty Additives
A useful way to understand this business is to ask what happens if the product fails.
If a bulk chemical supplier delivers slightly off-spec caustic soda, the customer adjusts the dosage. If Fine Organics delivers an erucamide batch whose migration rate is off, a film converter runs twenty tonnes of unsellable film before anyone notices, and a customer's automated packaging line comes to a halt. The additive represents a tiny fraction of total manufacturing cost, but its operational failure carries immense financial downside.
This asymmetry underpins the entire commercial model.
The segments
Polymer additives form the core of the business, generating between 60% and 65% of total revenue by supplying resin manufacturers, masterbatch compounders, and packaging film converters worldwide.3 This segment represents the company's strongest global market position and deepest qualification moat, driven by the strict regulatory compliance required for food-contact packaging.
Food additives account for 20% to 25% of revenue, encompassing emulsifiers such as glyceryl monostearate and polyglycerol esters, anti-crystallizers that maintain texture in spreads and confectionery, and dough conditioners for automated bakeries.3 Demand in this division is inherently defensive, anchored by customer relationships that in several cases span multiple decades.
The remaining 10% to 15% of sales consists of specialty lines, including CosPha bio-based surfactants for personal care, feed nutrition additives, industrial coatings, and agricultural anti-fog solutions.3 While management frames these emerging categories as growth vectors, they remain small relative to core operations. In each niche, Fine Organics operates as a challenger attempting to displace established incumbents, subjecting its expansion to the same multi-year qualification lags that protect its mature product lines.
Pricing power and its limits
The asymmetric dynamic of a low-cost, high-impact additive provides Fine Organics with notable pricing resilience. When raw material costs rise, customers typically accept price increases rather than risk re-qualifying an alternative supplier to save a fraction of a percent in total production cost.
However, this resilience does not translate into unconstrained pricing power. Fine Organics cannot unilaterally expand margins at will. Its primary institutional buyers—global resin producers and multinational food conglomerates—are sophisticated procurement organizations with full visibility into oleochemical feedstock benchmarks. Consequently, high customer switching costs protect operating spreads rather than enabling arbitrary price expansion. The company can defend its margins against cost inflation, but it cannot dictate terms to the market.
The palm oil pass-through machine
The company's principal feedstocks include palm kernel oil derivatives, stearic acid, rapeseed-derived erucic acid, and vegetable glycerine.3 These agricultural commodities are traded globally, with prices dictated by plantation yields, Southeast Asian export policies, biofuel mandates, and currency fluctuations.
Fine Organics passes these raw material cost fluctuations through to customers, though adjustments operate with a lag of one to two quarters before appearing in realized selling prices.5 This delay reflects contract reset schedules, existing inventory turnover, and formal price negotiations.
This pass-through lag fundamentally shapes reported operating margins, creating distinct cyclical distortions:
When feedstock costs rise, the company sells finished products derived from lower-cost inventory into a market adjusting to higher price levels. This dynamic expands reported margins, creating the appearance of enhanced pricing power through temporary inventory gains.
Conversely, when raw material prices decline, the company processes higher-cost inventory while customers demand immediate price reductions. The resulting margin compression mimics competitive pressure, though it stems primarily from temporary inventory losses.
Over a complete commodity cycle, these opposing swings tend to normalize. Within shorter two-to-three-year windows, however, the pass-through lag can significantly distort reported profitability—a dynamic clearly demonstrated in the company's financial performance between fiscal 2022 and fiscal 2026.
VIII. Financial Economics, Margin Supercycle Anatomy & The Post-COVID Normalization (FY21–FY26)
In the financial year ended March 2023, Fine Organic Industries reported consolidated revenue of roughly ₹3,023 crore and net profit of approximately ₹618 crore, with operating EBITDA margins reaching about 28.5%.23 Compared to the company's historical operating margin baseline in the low twenties, this performance represented an extraordinary surge rather than a sustainable step-change in baseline profitability.
Anatomy of a windfall
Three distinct factors drove this temporary expansion, none of which reflected core process chemistry improvements:
First, raw material price trajectories provided a sharp tailwind. Palm-derived feedstocks increased sharply through 2021 and 2022. Under Fine Organics' lag-pass-through mechanics, selling finished products based on prevailing market prices while processing inventory acquired at earlier, lower costs produced substantial temporary inventory gains.
Second, freight cost dynamics created revenue inflation. Container rates on global export routes spiked during post-pandemic supply chain disruptions. Because Fine Organics passed shipping costs directly through to customers, these elevated freight charges expanded top-line revenue without adding meaningful absolute profit. Moreover, with global shipping delayed, Fine Organics' ability to fulfill deliveries allowed it to command temporary pricing premiums. Consequently, a portion of the fiscal 2023 revenue peak reflected passed-through freight costs rather than expanded sales volumes.
Third, global supply chain dislocations created acute scarcity value. Persistent shipping bottlenecks in 2021 and 2022 made reliable delivery from an integrated manufacturer unusually valuable to international buyers seeking supply security.
Management's own read
During this period, executive guidance diverged from prevailing market sentiment.
Throughout fiscal 2023, while equity markets extrapolated peak profitability into permanent earning power, management explicitly cautioned analysts during earnings calls that elevated margins were temporary and expected to return to a normalized corridor in the low twenties.56 Executives maintained this stance on subsequent calls as margins contracted, characterizing the margin compression as anticipated normalization rather than competitive erosion or operational failure.5
This communication discipline signaled management's focus on long-term operating realities over short-term equity market valuations. By actively discouraging analysts from treating peak cyclical spreads as structural, executive commentary aligned closely with subsequent economic outcomes, establishing a track record of transparent financial reporting.
The mean reversion
Operating metrics subsequently normalized as management anticipated. Consolidated revenue declined to roughly ₹2,205 crore in fiscal 2024 and ₹2,269 crore in fiscal 2025, before recovering toward ₹2,365 crore in fiscal 2026.234 Operating EBITDA margins compressed back into a range of 20.4% to 22.6% as freight rates normalized and palm feedstock prices stabilized.24
This mean reversion highlights two analytical conclusions:
First, the top-line contraction of roughly 27% from fiscal 2023 to fiscal 2024 reflected price and freight deflation rather than volume collapse. Because top-line revenue incorporates volatile feedstock prices and passed-through freight, reported revenue serves as an imperfect indicator of underlying demand compared to physical volume shipped.
Second, operating margins maintained a resilient floor above 20%. Standard commodity chemical processors typically experience margin collapse into single digits following commodity downcycles. Maintaining EBITDA margins above 20% throughout complete input-price and logistics normalizations confirms that high switching costs and specialized process knowledge protect core manufacturing spreads. While peak margins reflected temporary market conditions, the post-cycle margin floor demonstrates the structural quality of Fine Organics' economic moat.
The balance sheet
Financial solvency has remained a structural constant. Fine Organics maintains a zero-long-term-debt balance sheet and holds accumulated cash and liquid investments exceeding ₹1,000 crore.23 Independent credit rating assessments consistently reflect this conservative financial structure.2
Working capital management has similarly demonstrated operational control, maintaining a cash conversion cycle within a two-to-three-month band despite severe global logistics delays—a notable operational outcome for an enterprise exporting across 80 countries.2
However, this capital allocation strategy presents clear financial trade-offs. Holding substantial low-yielding treasury reserves alongside an operating business generating mid-twenties returns on equity mechanically depresses overall return on equity. While management maintains a conservative dividend payout to preserve internal capital for future capacity expansion,3 the accumulation of idle cash drags down overall compounding metrics unless deployed into productive capital expenditure.
This balance sheet posture points directly to a central operational question: with ample capital available and identified market demand, why has capital deployment proceeded slowly? Management's explanation highlights internal execution constraints—a theme that forms the central focus of the analysis that follows.
IX. Industry Structure, Global Competitive Landscape & 7 Powers / Porter's 5 Forces Analysis
Placing Fine Organics alongside its global competitors immediately highlights a stark contrast in scale: nearly every major peer is significantly larger.
The field
In polymer additives, key international competitors include Croda International in the United Kingdom, Emery Oleochemicals with operations in Malaysia and Germany, Japan's KAO Corporation, and Riken Vitamin.1011 In food emulsifiers, the competitive field features Danisco (a unit of IFF), Kerry Group, Denmark's Palsgaard, and BASF.10
Several of these rivals operate at revenue levels many times that of Fine Organics. Croda alone operates at a revenue scale well above it and across a far broader portfolio,11 while BASF operates on an entirely different order of magnitude.
This structural disparity shapes the primary competitive dynamic in a counterintuitive way: in this niche, size does not automatically confer an advantage.
For a diversified chemical conglomerate, oleochemical slip additives represent a minor product line within a vast portfolio. Capital allocation committees at multinational firms evaluating whether to defend a global niche worth a few hundred million dollars against a focused, low-cost Indian supplier often decide that resources are better deployed elsewhere. For Fine Organics, by contrast, this niche constitutes its core business. This asymmetry of strategic focus allows small, dedicated specialists to maintain defensible positions alongside global giants.
Cost position
Fine Organics' cost structure relies on integrated Maharashtra facilities built through capital-efficient in-house engineering, competitive Indian labor and overhead costs, and reaction yields refined over decades across core chemistries.[^10] Consequently, the company maintains a low cost position globally in its key product categories.
However, low operational costs do not equate to an unassailable moat. Southeast Asian producers sit closer to raw feedstock sources and enjoy their own structural cost benefits. The Indian cost advantage is a matter of degree rather than a structural monopoly, remaining partially subject to currency movements and domestic wage dynamics.
Seven Powers, honestly applied
Evaluating the business through Hamilton Helmer's 7 Powers framework highlights distinct structural strengths and limitations:
Process Power represents the company's strongest strategic advantage. Decades of proprietary expertise in esterification control, high-vacuum molecular distillation, and particle morphology—embedded in internal process sheets and experienced personnel—align directly with Helmer's definition of process power: operational knowledge built through extended organizational learning that cannot be easily purchased. This advantage is evidenced by the resilient margin floor maintained throughout input-cost normalizations and the inability of resource-rich multinationals to displace Fine Organics in its core market.
Switching Costs are substantial and mechanically verified by the multi-year customer qualification cycles required in food-contact packaging. This represents the second-strongest power. Its primary constraint, however, is symmetry: high switching costs protect existing accounts from competitors but equally slow Fine Organics when attempting to capture market share from incumbent suppliers.
Counter-Positioning is moderate and partial. The company's bio-based oleochemical portfolio positions it favorably as global regulations tighten on petrochemical derivatives. However, strict counter-positioning requires that incumbent competitors cannot adopt the newcomer's model without cannibalizing their own core business. Because major chemical producers can and do build oleochemical capabilities, the regulatory tailwind provides an industry tailwind rather than a structural barrier preventing incumbent response.
Cornered Resource is modest. As noted in the analysis of its academic ties, the company benefits from a strong recruiting and retention pipeline rather than exclusive access to talent or proprietary raw material deposits.
Scale Economies, Network Economies, and Branding offer minimal structural protection. Fine Organics remains subscale globally; additives feature no network effects; and brand equity matters to plant chemists but carries no consumer pull.
Overall, two strong powers and two moderate ones yield a respectable, if bounded, competitive posture.
Porter's five forces
A complementary Porter's Five Forces analysis reveals a clear divide across product lines:
New entrants: low threat. The combination of specialized process know-how, global regulatory registrations, and multi-year customer qualification cycles means a well-capitalized new entrant would require roughly half a decade before achieving meaningful commercial revenue.
Buyer power: moderate, and rising at the top end. While smaller converters possess minimal leverage, global resin manufacturers and consumer packaging conglomerates command significant bargaining power, maintain full visibility into oleochemical feedstock benchmarks, and increasingly enforce dual-sourcing mandates.
Supplier power: moderate to high, and the most underappreciated force. Raw palm-chain feedstocks are concentrated geographically and remain subject to export levy and tariff policies in Indonesia and Malaysia, which have shifted abruptly in recent years.10 As a price taker on raw materials, Fine Organics relies primarily on its lag-pass-through pricing mechanics, which offset cost inflation over several quarters rather than immediately.
Substitutes: low in the near term. Within oleochemistry, no direct functional substitute exists for established slip additives. The primary long-term substitution risk involves macro shifts: if bio-based regulatory preferences stall or petrochemical inputs become significantly cheaper, the relative value of green positioning could diminish.
Rivalry: disciplined at the top, competitive at the bottom. In high-end, qualification-intensive polymer additives, competitive rivalry remains muted due to high customer retention. In basic emulsifiers and standard product grades, however, competition is price-sensitive, particularly against Southeast Asian volume producers.
This analysis presents an attractive industry structure in specialized, qualified categories and a more competitive environment in standard lines. The durability of Fine Organics' earnings ultimately depends on preserving a product mix weighted toward the specialty end of that spectrum.
X. Historical Falsification Layer & Skeptical Investor Stress Test
Every bullish thesis for Fine Organic Industries rests on four primary claims, each of which can be tested against the empirical record to determine how the underlying business mechanism actually functions.
Pass 1: Does the qualification moat cut both ways?
The claim: Three-to-five-year customer approval cycles create near-impenetrable customer lock-in.
The test: If customer switching barriers are an industry-wide structural property rather than a company-specific advantage, they should equally obstruct Fine Organics when it operates as a challenger.
The evidence: The company's geographic expansion record confirms this symmetry. Although Fine Organics has built an international presence over more than two decades, its market share among top-tier North American and European polymer converters expanded incrementally account by account rather than through sudden market gains. During the 2021–2022 global supply chain dislocations, when Western converters actively sought alternative suppliers, Fine Organics was unable to convert shipping disruptions into a rapid step-change in Western tier-one market share. Even when supply chains failed, prospective buyers were still required to complete multi-year technical and regulatory validation cycles before changing suppliers.
A similar dynamic affects the CosPha bio-based surfactant line. Personal care and cosmetic brand owners require extended ingredient qualification, placing Fine Organics in the role of an incumbent challenger subject to the same multi-year timeline.
Verdict: The claim holds defensively but fails as an engine for rapid expansion. The qualification moat protects existing accounts but retards new market capture during favorable demand shifts. Consequently, financial models assuming rapid market share gains misinterpret the underlying friction. The primary metric to monitor is the multi-year trajectory of export volume in North America and Europe rather than short-term quarterly spikes.
Pass 2: Is disciplined capital allocation actually an execution constraint?
The claim: Management exercises strict capital discipline, deploying cash prudently into international expansion.
The test: On financial statements, capital discipline and operational execution bottlenecks can produce identical low-leverage cash balances. The key test is whether management completes identified and funded capital projects on schedule.
The evidence: Executive disclosures highlight an internal execution bottleneck. Through fiscal 2024 and fiscal 2025, management deferred second-phase expansion work in Thailand and additional production lines in Malaysia, attributing the delays during analyst calls to limited internal project management bandwidth—not capital constraint, not demand weakness, not regulatory obstruction.5
This bottleneck reflects the trade-offs of a centralized, family-led decision structure. While Fine Organics holds ample cash reserves and has established the strategic rationale for international capacity—including raw material proximity and logistics efficiency—project execution remains funneled through a limited group of senior technical managers. Consequently, major projects must proceed serially rather than concurrently across sites in Gujarat, Thailand, Malaysia, and potential overseas locations.
Verdict: The claim survives in a modified form. Capital allocation has successfully avoided value-destroying acquisitions or major project write-offs. However, concentrating execution within a narrow leadership group has led to cash accumulating on the balance sheet while capacity expansions proceed sequentially. This structure lowers asset turnover and places a drag on return metrics. The critical key performance indicator to track is the actual commissioning schedule of the Gujarat SEZ facility relative to initial guidance.
Pass 3: Was the margin expansion structural?
The claim: The surge to a 28.5% operating EBITDA margin in fiscal 2023 demonstrated a permanent step-change in pricing power.
The test: A structural expansion in pricing power requires operating margins to remain elevated after temporary supply chain disruptions and raw material spikes subside.
The evidence: Operating margins did not hold at peak levels. As global freight rates normalized and palm feedstock prices stabilized, EBITDA margins reverted to the low-twenties range, aligning with explicit prior guidance from management.245
Verdict: The claim of a permanent margin step-change is invalid. The fiscal 2023 profitability peak resulted from temporary inventory gains and passed-through freight spikes. However, the post-normalization margin floor in the 20% to 23% range confirms the ongoing protection provided by high customer switching costs and specialized process knowledge. The key metric remains whether EBITDA margins hold within this 20% to 23% corridor across a full raw material cost cycle.
Pass 4: Is pass-through seamless?
The claim: The company seamlessly passes all raw material cost changes on to customers.
The test: The efficacy of price pass-through mechanisms is tested during periods of raw material price deflation rather than inflation.
The evidence: Contractual reset lags create operational margin compression when input costs fall. When palm kernel oil and fatty acid prices drop sharply, buyers demand immediate price reductions while Fine Organics continues processing higher-cost raw material inventory, compressing margin until the two align.5
Verdict: Pass-through mechanisms function effectively over full multi-quarter commodity cycles but introduce volatility across individual quarters. Single-quarter gross margin fluctuations reflect raw material price trends as much as competitive strength, making short-term margin shifts an unreliable indicator of structural market position.
A fifth test worth adding: customer concentration and multi-sourcing
The test: The primary long-term risk to market position is dual-sourcing strategies by major global packaging converters.
The evidence: Rather than replacing Fine Organics directly, major international converters seeking to mitigate single-region supply risks may qualify secondary Southeast Asian suppliers alongside their primary accounts. Because customer switching costs prevent total supplier displacement, competitive erosion manifests through reduced volume growth within existing accounts rather than sudden customer churn.
Verdict: Dual-sourcing risks represent the most direct threat to market share expansion. Monitoring volume growth relative to broader end-market packaging demand provides the clearest test of whether dual-sourcing is eroding sales within key global accounts.
XI. Current Management, Family Governance & Capital Allocation Execution
The board of Fine Organic Industries functions largely as an extended family managing a specialized chemical manufacturing operation built over more than five decades.
Mukesh Shah serves as Chairman and Managing Director, leading global sales, commercial strategy, and quality control—functions closely aligned in a business where customer retention depends directly on product reliability.3 Jayen Shah serves as Chief Executive Officer and Whole-time Director, overseeing operational execution and manufacturing expansion.3 Tushar Shah and Bimal Shah serve as executive directors managing specific business verticals and supply chain operations.3 Prakash Kamat, who co-founded the original 1970 partnership from the UDCT side, remains associated with the company in a technical and advisory capacity.3
Reading the structure
The practical advantage of this organizational structure lies in its continuity. In a business where competitive differentiation stems from cumulative process know-how, retaining the founding leadership maintains valuable institutional memory. Operational knowledge within chemical manufacturing represents a tangible asset, allowing long-serving technical leaders to resolve complex synthesis challenges using established historical precedents.
The structural limitation, however, centers on executive centralization: strategic decisions remain funneled through a compact leadership group, making management bandwidth a binding operational constraint.
Alignment and governance hygiene
Promoter shareholding has remained at approximately 75%, matching the statutory ceiling permitted under Indian minimum public shareholding regulations.89 This high ownership stake aligns promoter interests directly with public shareholders, as financial returns for the founding family depend on the broader commercial trajectory of the business.
On standard corporate governance metrics, executive remuneration has remained aligned with company profitability, while promoter shares are held without pledging.38 The absence of pledged promoter stock eliminates a common source of balance-sheet stress among Indian mid-cap companies, removing incentives to prioritize short-term share price movements over underlying operational performance.
Related-party disclosures primarily involve commercial arrangements with joint venture entities, with recent annual reports featuring clean audit opinions and unreserved auditor annexures.3
While a clean audit opinion reflects baseline regulatory compliance rather than exceptional governance, management's operational conduct provides secondary confirmation. Management's early warning on normalizing fiscal 2023 margins, its decision to forego unnecessary primary equity dilution during the initial public offering, and its reliance on self-funded growth demonstrate a disciplined approach to balance-sheet management.
The capital allocation record
The company's historical capital deployment reflects a consistent reinvestment strategy. Capital expenditure has focused primarily on expanding brownfield and greenfield capacity across existing manufacturing sites in Ambernath, Patalganga, and Dombivli, funded entirely through internal cash generation.3 Expanding facilities at established locations—where site infrastructure, regulatory approvals, and trained personnel are already present—has delivered higher return on invested capital than pursuing unproven greenfield developments elsewhere.
Dividend distributions have remained conservative, with retained earnings directed toward funding self-financed expansion projects.3
In corporate development, the company has consistently favored organic expansion and targeted joint ventures over strategic acquisitions.312 The public record shows no large corporate acquisitions and, consequently, no goodwill write-offs. While avoiding value-destroying M&A represents sound capital preservation, it demonstrates risk mitigation rather than proactive external capital deployment.
Overall, Fine Organics presents a governance and capital allocation model characterized by strong downside protection alongside unproven upside execution at scale. Management has protected capital effectively; whether leadership can accelerate reinvestment while navigating internal bandwidth constraints remains the primary question for long-term compounding.
XII. Growth Strategy, SEZ Priority & Current Risk Radar
Evaluating Fine Organics' operational priorities in late 2026 reveals an execution pipeline significantly narrower than its range of theoretical growth options—a deliberate focus driven by management bandwidth constraints.
The Gujarat SEZ as the chosen priority
The company has directed its primary engineering and project bandwidth toward a Special Economic Zone (SEZ) project in Gujarat, aimed at serving long-term export demand.34
Selecting an SEZ location over conventional domestic capacity aligns directly with the company's operating model. An SEZ facility allows duty-free raw material imports and tax-advantaged finished exports—a critical structural benefit for an enterprise that imports palm feedstocks and exports a majority of its production. Furthermore, a Gujarat site provides direct port access, cutting inland transportation costs from Maharashtra plants to export terminals, alongside streamlined state chemical permitting processes.
For investors, the SEZ project serves as the primary benchmark for evaluating whether internal execution bottlenecks are being managed or merely renamed. Fully funded and prioritized ahead of deferred joint venture projects in Thailand and Malaysia, the project offers observable milestones: land acquisition, environmental clearances, construction progress, and final commissioning dates can all be measured against management's prior guidance.
The US option
Management has also evaluated localized manufacturing in North America.4 The economic logic reflects market realities: ocean freight represents a meaningful component of delivered additive costs, while North American packaging converters increasingly favor near-shored suppliers to insulate their supply chains against global disruptions.
However, this initiative remains an evaluation rather than a firm capital commitment. Given management's centralized execution bandwidth and the priority assigned to the Gujarat SEZ, North American manufacturing is unlikely to materialize as a near-term operational asset.
Optionality worth separating from noise
CosPha green surfactants represents the more strategically aligned growth option. The commercial premise relies on substituting oleochemical-derived surfactants for synthetic sulfates such as SLS and SLES in shampoos, cleansers, and personal care products, driven by European clean-label preferences and formulator demand.3 The line utilizes the same palm feedstocks, esterification chemistries, and processing equipment as core operations.
Nevertheless, commercial expansion faces structural hurdles. Ingredient qualification in personal care is protracted, incumbent mild surfactant producers are large and entrenched, and the segment currently contributes a modest share of total revenue. Consequently, CosPha serves as a logical product extension with an unproven revenue conversion rate.
Bio-plastic additives—specifically slip and anti-static packages formulated for polylactic acid (PLA) and polyhydroxyalkanoates (PHA) biodegradable films—offer distinct long-term optionality. Biodegradable polymers exhibit different melting behavior, surface chemistry, and migration dynamics than conventional polyethylene, preventing standard additive packages from transferring directly. Fine Organics holds a structural advantage because its additives are vegetable-derived, ensuring that compostable packaging maintains its environmental compliance. However, commercial scaling remains constrained by the adoption rate of bio-plastics, which has historically lagged industry forecasts.
The risk radar, mechanism by mechanism
Raw material and policy volatility. Abrupt shifts in export duties, levies, and domestic market obligation rules in Indonesia and Malaysia directly impact the landed cost of palm-chain feedstock.10 This policy unpredictability represents the company's most immediate operational risk, driving the multi-quarter margin compression and expansion cycles created by raw material pricing lags.
Freight and geopolitics. Red Sea shipping disruptions have extended routing and elevated spot container rates on Asia-Europe trade lanes, lengthening transit times and tying up working capital in inventory at sea.10 For an enterprise exporting across more than 80 countries, maritime freight logistics directly dictate export competitiveness and cash conversion efficiency.
Customer multi-sourcing. Rather than sudden account losses, the primary market share risk involves major international packaging converters adopting dual-sourcing strategies. As outlined in Section X, this dynamic results in gradual volume erosion within key accounts rather than visible customer churn.
Regulatory risk on single-use plastics. Expanding restrictions on single-use plastic packaging across India and global markets present potential headwinds for select packaging applications. However, two offsetting factors soften this impact: a significant share of polymer additive volume goes into food packaging, which typically receives regulatory exemptions to preserve food safety, while trends toward thinner, higher-performance films require higher additive loading per tonne of resin. Consequently, the net commercial impact of plastic regulations remains balanced.
Execution risk. Permitting timelines, land acquisition, and environmental approvals for the Gujarat facility depend on external regulatory bodies. Given the company's historical pattern of deferring capacity expansions, project schedule slippage represents a realistic baseline expectation for investors rather than an unexpected disruption.
XIII. Playbook: Business & Investing Lessons
1. A niche specialty advantage is built by subtraction, not addition. Fine Organics' position stems not from broad diversification, but from fifty-six years of focused execution in a single discipline—synthesizing functional molecules from vegetable fats. In doing so, it has accumulated far more operational experience in oleochemistry than a diversified generalist can justify. A chemical conglomerate typically assigns its top process engineers to its largest business lines, whereas a specialized firm directs all technical talent toward its primary focus. Over decades, that concentration creates a capability gap that capital alone cannot quickly close.
2. Small-dosage economics provides a reliable pricing defense, but not unconstrained pricing power. When an additive accounts for a fraction of a percent of a customer's total bill of materials yet determines whether an automated production line functions, the buyer's incentive to switch suppliers drops sharply. This dynamic recurs across industrial sectors, including specialty catalysts, industrial enzymes, and critical fasteners. However, as the company's operating history demonstrates, this economic structure protects operating spreads rather than expanding them. Analysts must distinguish margin resilience against cost inflation from unilateral price-setting power.
3. An institutional pipeline to a technical university functions as a structural asset. The company's multi-decade relationship with the Institute of Chemical Technology is not a corporate social responsibility initiative; it is a recruitment pipeline for critical process engineering talent. Companies that establish deep, multi-decade links with premier technical institutions in their specific discipline secure an intellectual asset that rarely appears on balance sheets or stock screeners.
4. Family governance involves structural trade-offs that require balanced evaluation. Analysis of promoter-led firms often frames family control in binary terms. The operating history at Fine Organics indicates a more nuanced reality. Family leadership has provided substantial downside protection: a debt-free balance sheet, conservative capital allocation without high-risk acquisitions, clean financial reporting, and executive willingness to publicly temper unsustainable margin expectations. Simultaneously, executive centralization has created a binding execution constraint that delays project delivery. Investors evaluating this governance profile trade rapid capacity expansion for operational stability and downside protection.
5. Distinguishing temporary windfalls from durable franchise earning power is critical. The fiscal 2023 margin surge provides a clear case study in evaluating cyclical specialty chemical earnings. When operating margins spiked seven to eight percentage points above the historical baseline, equity markets extrapolated peak profitability into structural growth. Management explicitly warned that the margin expansion was temporary, and subsequent results confirmed that normalization. The broader analytical lesson remains clear: when a manufacturer's margins widen alongside rising raw material prices and freight spikes, the margin expansion typically reflects lag-pass-through mechanics and inventory timing rather than enhanced competitive power. Valuations must account for how earnings will behave once those transitory factors reverse.
XIV. Analysis, Bull vs. Bear Case & Key KPIs to Watch
The bull case
The strongest version of the bull argument does not rest on rapid expansion. It rests on the durability of an unusually profitable, defensible market position.
Fine Organics holds a commanding domestic position in key polymer slip additive categories and a credible global tier-two seat in a niche that major chemical conglomerates have limited incentive to contest properly.[^10] Customer relationships are protected by qualification cycles whose economics make switching irrational for buyers. Furthermore, its post-normalization operating margin floor—revealed after input prices and freight rates settled—sits above 20%, serving as empirical evidence that its process advantage is operational rather than narrative.4
The balance sheet carries no long-term debt and maintains a cash balance that fully funds its identified expansion pipeline without equity dilution.23 For an enterprise whose earnings are cyclically exposed to agricultural commodities, zero leverage is not merely financial conservatism; it provides the structural resilience required to navigate raw material cycles.
Finally, the global regulatory trend shifting away from petrochemical-derived additives in food-contact packaging and personal care toward bio-based alternatives directly favors the oleochemical processing capabilities the company has developed over five decades.
The bear case
The core bear case does not dispute the quality of the franchise, but questions whether its growth rate justifies a premium valuation multiple.
Growth remains constrained by management bandwidth—as executive commentary has explicitly acknowledged—evidenced by project deferrals in Thailand and Malaysia while engineering resources are focused on the Gujarat facility.5 A specialized manufacturer that can execute only one major capital project at a time risks ceding incremental volume growth to competitors capable of managing concurrent expansion projects.
Operating margins remain vulnerable to palm kernel oil price movements and ocean container rates—neither of which the company can control—ensuring that quarterly earnings will exhibit cyclical noise unrelated to underlying market position.
Consolidated revenue has remained largely flat between fiscal 2024 and fiscal 2026, fluctuating in a range of ₹2,200 crore to ₹2,400 crore.34 While part of this top-line stagnation reflects price and freight deflation rather than volume contraction, investors paying a growth multiple require clear evidence of volume growth, which has remained modest.
Moreover, the qualification moat functions symmetrically. Because switching barriers protect incumbent suppliers as effectively as they shield Fine Organics, the company faces inherent friction when attempting to gain share in new accounts, preventing rapid top-line acceleration.
Finally, product concentration in polymer additives ties a substantial portion of overall operating profit to global plastic packaging demand and its evolving regulatory oversight.
Where the evidence lands
Weighing these opposing arguments, empirical evidence clarifies the thesis: the qualification moat holds as a defensive barrier rather than an engine for aggressive market capture; the management quality thesis holds regarding capital preservation and downside protection rather than rapid project execution; the structural margin expansion claim fails and is replaced by a verified high-margin floor; and the balance-sheet strength remains intact, albeit partly as a byproduct of capital under-deployment.
This assessment yields a high-quality, low-variance industrial franchise whose primary strategic question is not whether it can sustain attractive returns on invested capital, but whether leadership can systematically deploy additional capital at scale.
The forces, applied to the investment question
Applying Porter's Five Forces to the investment thesis highlights that supplier power presents the greatest short-term earnings volatility, buyer power poses the primary threat of gradual margin erosion at top-tier accounts, and high entry barriers provide ongoing franchise protection. Under Hamilton Helmer's 7 Powers framework, process power and customer switching costs drive core economic returns, while counter-positioning and cornered resources play supporting roles.
Relative to global peers, Fine Organics remains significantly smaller than Croda International, KAO Corporation, BASF, and Danisco owner IFF, and is unlikely to close that scale gap.1011 Consequently, the relevant evaluation metric is not aggregate scale, but return on capital employed within its specialized niche, where zero leverage and low capital intensity per unit of capacity create a distinct financial profile.
The three KPIs that matter
1. EBITDA margin stability within the normalized corridor. Whether operating EBITDA margins remain within the 20% to 23% range across complete raw material and freight cycles serves as the direct test of whether process know-how and switching costs provide durable protection. Sustained margin compression below this corridor would undermine the moat thesis far more decisively than a single quarter's top-line miss.
2. Gujarat SEZ commissioning milestones against project timelines. This metric provides an empirical test of management's execution bottleneck. Land acquisition, environmental clearances, construction progress, and commercial commissioning dates offer clear progress indicators. Executing the project on schedule would demonstrate improved operational bandwidth, whereas schedule slippage akin to prior overseas deferrals would confirm structural execution constraints.
3. Export volume growth across North American and European markets. Tracking underlying physical volume rather than freight-inflated export revenue into Western growth markets tests the symmetric-moat thesis. Securing regulatory and technical approvals at Western tier-one packaging converters and converting them into sustained volume growth would demonstrate that the qualification moat can support market share gains over time.
XV. Epilogue & Final Reflections
Fifty-six years separate the 1970 partnership synthesizing emulsifiers for local Bombay bakeries from an enterprise whose additives are blended into packaging films across four continents. Little about that evolution was dramatic: the company underwent no high-stakes pivots, no debt-fueled acquisitions, no corporate restructuring, and produced no high-profile media figureheads. Instead, the business expanded through continuous focus on oleochemical processing, customer qualification, and incremental process refinements.
This operating trajectory offers a distinct contrast to broader corporate narratives in India, which often highlight debt-funded conglomerate expansion or rapid tech-driven disruption. Fine Organics represents a different archetype: a manufacturing business that grew at a pace funded entirely by internal cash generation, maintained narrow technical specialization, and systematically avoided balance-sheet leverage. Whether market observers view that approach as disciplined capital stewardship or risk-averse conservatism depends largely on execution over the coming five-year cycle.
The company now sits at a critical strategic transition. The founding generation's operating framework—centralized executive decision-making, self-funded capital deployment, and serial project execution—built a high-return business operating in a revenue band of ₹2,200 crore to ₹2,400 crore. However, management has acknowledged to analysts that this centralized structure now represents its primary growth constraint. The key question for the coming decade is whether a family-governed firm can build the institutional depth required to execute concurrent international projects without compromising the operational discipline that established its economic moat. Many promoter-led mid-cap enterprises in India have attempted that organizational shift, but relatively few have successfully executed it at scale.
For investors, the core analytical conclusion is clear. The company's competitive moat—anchored by specialized process knowledge and high customer switching costs—is real and measurable, though narrower and slower to scale than bullish narratives suggest. Management has maintained a conservative, debt-free balance sheet, yet executive bandwidth limitations have left substantial treasury reserves under-deployed. Ultimately, converting proven technical capabilities into a larger revenue base will be determined not by strategic guidance or corporate projections, but by the physical commissioning dates of its expansion facilities.
References
-
Fine Organic Industries Limited — Red Herring Prospectus (RHP) — BSE India, 2018-06-12 ↩↩
-
Fine Organic Industries Limited — ICRA Credit Rating Rationale, 2025-11-20 ↩↩↩↩↩↩↩↩↩
-
Fine Organic Industries Limited — Annual Report FY 2024-25 — Fine Organics Investor Relations ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Fine Organic Industries Limited — Q1 FY 2026-27 Financial Results & Investor Presentation, 2026-08-12 ↩↩↩↩↩↩↩↩
-
Fine Organic Industries Limited — Earnings Call Transcript, Q4 FY24 & FY24 Results — Trendlyne ↩↩↩↩↩↩↩
-
Fine Organic Industries Limited — Earnings Call Transcript, Q3 FY24 — Trendlyne ↩
-
Fine Organic Industries IPO Bidding Details & Listing Performance — Moneycontrol, 2018-07-02 ↩↩
-
Fine Organic Industries Quarterly Financials and Shareholding Pattern — BSE India ↩↩↩
-
Fine Organic Industries Shareholding Pattern & Corporate Governance Disclosures — NSE India ↩↩
-
Global Polymer & Food Additives Market Dynamics — ICIS Chemical Business ↩↩↩↩↩↩
-
Croda International Plc — Annual Report & Investor Disclosures, 2024-03-01 ↩↩↩
-
Fine Zeelandia Private Limited — Joint Venture Filing & Corporate Profile — Ministry of Corporate Affairs, India ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube