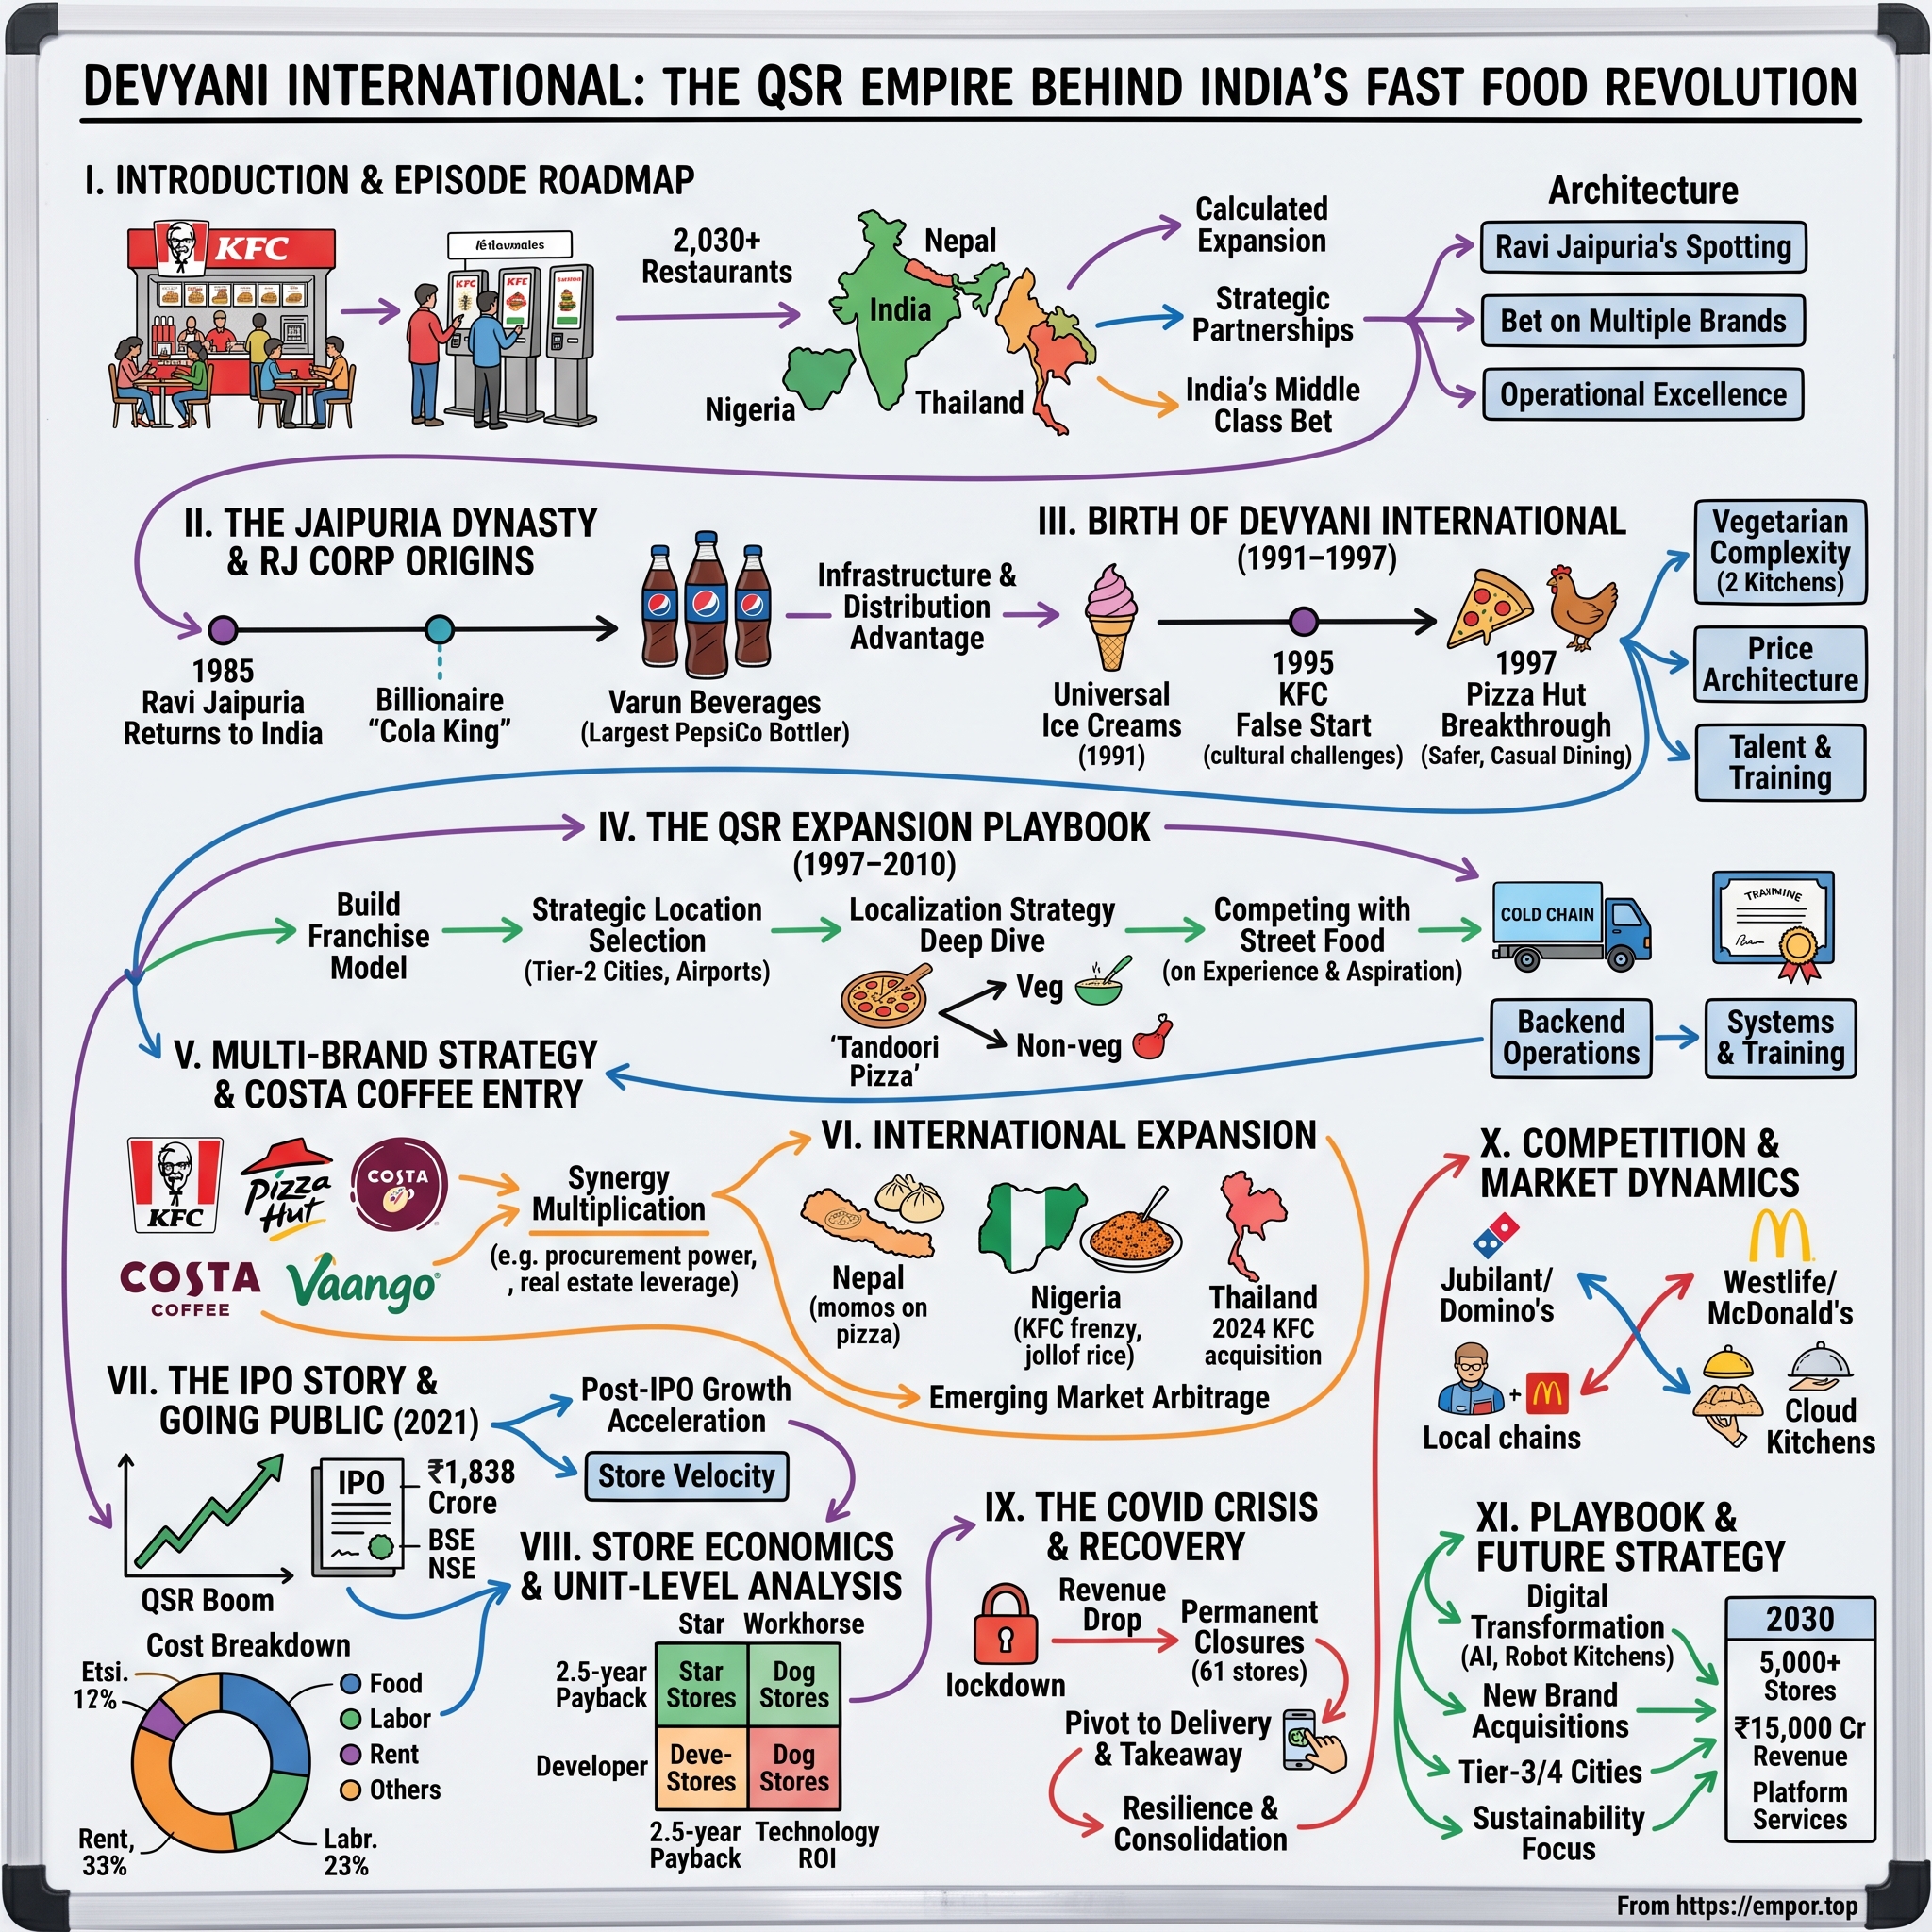
Devyani International: The QSR Empire Behind India's Fast Food Revolution
I. Introduction & Episode Roadmap
On a Tuesday afternoon in late July 2026, Devyani International's management team dialled into an earnings call and delivered a number the company had been chasing for two years: its highest reported EBITDA on record, ₹254.8 crore, on quarterly revenue of ₹1,580.5 crore.1 Operating EBITDA rose nearly 38% year on year, while profit before tax reached its highest level in eight quarters.2 After a fiscal year in which the company had lost money, the tone on the call was noticeably lighter.
And yet, buried inside the same slide deck was a metric that explains why this business remains one of the most argued-over names in Indian consumer equities. Pizza Hut India—a 626-store network Devyani has operated since 1997—generated a negative brand contribution margin of 1.9% in that same quarter.1 This was not merely a compressed margin, but a direct loss at the store level, before allocating corporate overhead, depreciation, or interest expenses.
That contrast defines the tension at the center of this story. Devyani International Limited, listed on the NSE under the ticker DEVYANI, is the largest franchisee of Yum! Brands in India and one of the largest globally. As of June 30, 2026, it operated 2,255 restaurants across India, Thailand, Nepal, and Nigeria—794 KFCs in India alone, plus a Thai KFC network of 323 stores, a Costa Coffee chain, and a portfolio of home-grown Indian brands acquired over the past eighteen months.1 For the year ended March 31, 2026, consolidated revenue reached ₹5,611.5 crore, up 13.3%.3
The company also lost ₹42.5 crore that year, a loss that widened from ₹6.9 crore the year before.4 Its three-year average return on equity sits at roughly negative 3.5%, and return on capital employed at about 5%—figures that would be unremarkable for an early-stage company, but are striking for a 35-year-old enterprise operating over 2,000 outlets with ₹3,833 crore of gross debt on its balance sheet.5
The central question of this episode: Ravi Kant Jaipuria built one of the world's most profitable PepsiCo bottling franchises. Did that playbook—territorial density, supply-chain scale, relentless distribution—actually transfer to running restaurants? Or has Devyani spent a decade proving that owning the rights to a global brand in a huge market is a license to grow revenue, not a license to earn returns?
The story unfolds across five acts. Origins: an ice-cream company incorporated in 1991 that became a Pizza Hut franchisee in Jaipur in 1997.[^6] Segment economics: why KFC works, why Pizza Hut broke, and why the difference is not about management effort. The deal machine: a $128.9 million Thai acquisition, a ₹419.6 crore Indian biryani chain, and a $934 million all-stock merger with the only other listed company that does exactly what Devyani does.678 The falsification layer: testing each promoter claim against Devyani's own record over the longest span that bears on it. And the forward case: what would have to be true, and what single data point would break it.
One more shift altered the landscape while this story was being written. On September 1, 2026—four days ago—Yum! Brands completed the sale of Pizza Hut outside mainland China to private equity firm LongRange Capital for approximately $1.5 billion.9 Devyani's second-largest brand no longer has the same franchisor it did when this narrative began. To understand what that means, start with the man whose name is not on the company, but whose daughter's is.
 Subscribe on LinkedIn
II. The Jaipuria Dynasty & The RJ Corp Playbook
The Jaipuria family did not start in restaurants. They started in glass bottles, sugar syrup, and the unglamorous logistics of getting a cold drink to a village in Uttar Pradesh before it went warm.
Ravi Kant Jaipuria returned to India in the mid-1980s to join a family bottling operation, and over the following three decades assembled RJ Corp into PepsiCo's largest bottling franchise outside the United States—the business eventually listed as Varun Beverages. The economics of that model are worth understanding precisely, because they are the source of both the operational strength and the strategic illusion running through Devyani's story.
Bottling is a business of exclusive territory. PepsiCo grants a franchisee the right to manufacture and distribute across defined geographies. Within those borders, the franchisee is the sole distributor for that brand. Success is almost entirely a function of two variables: how many outlets a network can reach, and how cheaply it can reach them. Add a plant, densify the route, cut the cost per case, repeat. Labour is concentrated in factories and delivery trucks rather than spread across thousands of customer-facing sites. There is no real estate rent on a high street, nor a host to seat guests. Demand is largely driven by availability—put the product within arm's reach of desire, as the old Coca-Cola adage went, and volume follows.
Devyani was built by leaders who internalised that logic completely. That mindset shows up in the language management uses: store additions, network density, cluster economics, supply-chain leverage, and procurement scale. The instinct is to expand the footprint aggressively, then let volume absorb fixed overhead. It is a powerful instinct that explains why Devyani expanded faster than nearly any other Indian quick-service restaurant operator during the post-COVID window—growing from roughly 1,300 outlets to over 2,250 in four years.
The promoter group has explicitly and repeatedly claimed that this beverage distribution DNA translates to restaurants. Shared procurement across RJ Corp entities, a common understanding of Indian consumer behaviour, and a management culture built around volume throughput are presented as inherited competitive advantages rather than mere financial backing.
Here is where the operational record refuses to cooperate.
Testing the claim. A restaurant is not a distribution route. In bottling, incremental volume flows through existing capital assets. In the quick-service restaurant industry, incremental volume requires a new lease, a new kitchen, a crew of 20 to 30 employees, and enough footfall on that specific corner to cover a rent that escalates every few years. Labour is the second-largest expense and does not automatically shrink when a store underperforms. In India, a critical intermediary also sits between Devyani and its end customer: food delivery aggregators, whose commissions and co-funded promotions compress store-level profit margins.
The evidence against seamless capability transfer appears in the return metrics over an extended period. Over the trailing three years, Devyani's average return on equity has been negative.5 The company reported a net loss in FY26 and earned virtually no profit in FY25.4 It closed 61 core stores in FY21.[^11] In FY26, it closed 22 Costa Coffee outlets—the first contraction in that chain's Indian store count in more than five years.10 In FY27 to date, management has cut the Pizza Hut store count.1 These contractions reflect an operator discovering, site by site, that a portion of its network expansion was misplaced.
The calibrated conclusion. Historical performance does not completely invalidate the Jaipuria playbook. Devyani's procurement scale, its capacity to open more than 100 outlets annually, and its gross margin of roughly 69% demonstrate structural advantages over subscale competitors.1 What the record rejects is the stronger claim that beverage distribution capabilities insulate restaurant returns. Scale protects gross margins at the top of the income statement, but leaves bottom-line returns vulnerable to real estate leases, store labour, aggregator commissions, and shifting menu preferences—four cost variables a bottling operator never has to price. The durable advantage is limited to procurement efficiency and rollout velocity rather than superior capital returns. The benchmark required to validate the broader claim is consolidated return on capital employed moving sustainably into the mid-teens; at roughly 5%, it has not reached that threshold.5
That establishes the family background. Now to the enterprise itself—which began, improbably, with ice cream.
III. The Genesis of Devyani & The Yum! Brands Marriage (1991–1997)
In December 1991, India was six months past the balance-of-payments crisis that forced it to pledge gold reserves to the Bank of England. Economic liberalisation was just beginning, foreign brands remained abstract to most Indian consumers, and the idea that an American fried-chicken chain would one day serve as the profit engine of an Indian listed company seemed improbable.
That same month, Universal Ice Creams Private Limited was incorporated in New Delhi.[^6] It was an entry into cold-chain food—which in India at the time required keeping products frozen across a distribution network that largely lacked refrigeration infrastructure. The business was later renamed Devyani International Private Limited in June 2000, after Ravi Jaipuria's daughter, and converted into a public company in May 2005.[^6]
The strategic shift occurred in 1997, when Devyani signed a development agreement with PepsiCo Restaurants International (India) Private Limited to open Pizza Hut outlets in North India, launching its first store in Jaipur.[^6] Two details of that entry shaped the company's trajectory for the next three decades.
First, the counterparty. In 1997, PepsiCo still owned Pizza Hut, KFC, and Taco Bell before spinning off its restaurant division later that year into Tricon Global Restaurants, which eventually became Yum! Brands. Devyani's relationship with the franchisor originated as an extension of the Jaipuria family's existing PepsiCo bottling partnership. Devyani did not secure these territorial rights through a competitive auction against global bidders; it obtained them through established corporate access. That provided a meaningful head start, but it represented a relationship-based advantage rather than an exclusive contractual monopoly—a distinction with critical implications for the company's long-term corporate rights.
Second, the location. Opening the first Pizza Hut in Jaipur rather than Delhi or Mumbai signaled an expansion strategy focused on regional market penetration from the outset rather than metropolitan flagship placement.
The initial phase demonstrated how poorly Western fast-food economics mapped onto Indian market realities. Roughly a third of India's population is vegetarian, and in North India—Devyani's core territory—the proportion is higher. Building a quick-service restaurant concept in a price-sensitive market dominated by established street-food alternatives presented severe operational hurdles. Specialized kitchen equipment had to be imported. Poultry supply chains meeting international food-safety standards had to be constructed without an existing third-party cold-chain logistics industry, while commercial dairy standards for pizza cheese had to be established alongside local processors.
KFC's market entry ran in parallel. Yum! opened its first KFC outlet in Bangalore in 1995 and operated the brand directly for years before dividing India into distinct franchise territories: Devyani secured the North and East, while Sapphire Foods took the West and South. Establishing two major franchisees under one franchisor was a deliberate strategy by Yum! to maintain competitive tension and avoid reliance on a single partner. Decades later, that geographic bifurcation created the structural friction that both franchisees are attempting to resolve through consolidation.
What this history tells investors. Devyani's corporate origin reflects a distribution family securing an option on Western brand equity in a nascent market, then spending two decades constructing the supply infrastructure needed to exercise it. The resulting moat is real but narrowly defined: it consists of territorial incumbency under license, rather than brand ownership, proprietary culinary intellectual property, or structural customer lock-in. Ultimately, Devyani's long-term economics depend on franchise contracts controlled by a third party—and on that franchisor's continued reinvestment in the brand.
By 2015, that foundational infrastructure was established. How Devyani deployed it over the subsequent decade determined whether network scale could translate into sustainable economic returns.
IV. Building the Indian QSR Playbook & Franchise Moats (1997–2015)
There is a spreadsheet that governs every decision in this business, and it has four inputs: rent, royalties, food costs, and footfall.
Start with the royalty, because it is the input Devyani cannot negotiate away. Under its franchise arrangements, Devyani pays Yum! a royalty running at roughly 6% to 6.5% of gross revenue, plus an upfront fee for each new store—reported in franchise disclosures at around $53,400 for a new KFC and $26,700 for a new Pizza Hut.11 Before Devyani pays for a single piece of chicken, it surrenders roughly 6% of top-line revenue to a licensor in Louisville. On a store generating ₹100,000 a day, that translates to approximately ₹6,000 daily—or roughly ₹22 lakh annually—paid in perpetuity and indexed directly to the store's sales.
This is the central bargain of master-franchise economics: the franchisee rents brand equity and funds it out of the operating margin. In exchange, it receives a proven format, national advertising, franchisor-funded product development, and established brand recognition. What it does not receive is pricing power over its licensor. When the franchisor mandates a store refresh, a new kitchen layout, or a digital ordering standard, that capital expenditure lands entirely on the franchisee's balance sheet.
The second input, rent, reflects where Devyani's strategy visibly evolved. The early Pizza Huts were destination restaurants—spanning more than 2,000 square feet with table service and family dining. That format aligned with the market in 2003, when dining out at Pizza Hut was an event. It became economically unviable once smartphone delivery services proliferated. Devyani's newer KFC outlets are substantially smaller, engineered for rapid throughput and delivery pickup rather than dwell time, and located in Tier 2 and Tier 3 cities, highway plazas, and airports where rent per square foot is a fraction of a metropolitan high street.
The third input, food cost, is where the Jaipuria procurement network operates. Devyani's consolidated gross margin reached 69.1% in the June 2026 quarter, up 90 basis points year on year, while Pizza Hut India specifically operated at a 76.3% gross margin.1 Pizza Hut's raw material economics are strong—flour, cheese, and vegetables cost relatively little compared to menu prices—yet the brand generates losses at the store level. That contrast demonstrates that Devyani's primary challenge is store-level overhead and volume, not sourcing efficiency.
The fourth input—footfall, expressed operationally as Average Daily Sales (ADS)—is the decisive metric. A QSR store's costs are overwhelmingly fixed in the short run: leases are signed, store crews are scheduled, and kitchen equipment depreciates regardless of order volume. Above a specific daily sales threshold, incremental orders drop through to contribution margins close to the gross margin level. Below that threshold, the store operates at a loss. On the June 2026 call, management stated that once KFC's ADS crosses roughly ₹105,000 to ₹110,000, brand contribution margins reach approximately 20%.2 Current KFC ADS stands at ₹98,000.1
This reframes the operating narrative. Devyani is not primarily managing a cost problem; it is managing a volume-per-store challenge in a business where rapid network expansion regularly adds new outlets that start below the profitability threshold, temporarily depressing average store metrics.
A fifth input, missing from standard financial models, is menu relevance. The localization strategy executed by Devyani and Yum! through the 2000s required substantial operational adaptation. Operating a chicken chain in a market where a large minority of consumers abstain from meat required building a vegetarian menu without diluting the core brand—leading to items like the Paneer Zinger, which adopted the architecture of the flagship burger while replacing the protein. Spice profiles were adjusted for local palates, and entry price points were engineered downward so that a standardized, air-conditioned meal could compete against street-side options.
That localization enabled KFC to scale into a mass-market brand in India rather than remaining a niche concept. However, it also introduced a long-term structural constraint: training consumers on low entry price points built an expectation of continuous value. Promotional combos, ₹99 offers, and festival bundles anchored consumer price perceptions. Consequently, raising menu prices remains difficult for Indian QSR operators, as customers respond strongly to promotions and penalize menu-price increases.
The investor takeaway from this period. Devyani constructed substantial operating capabilities between 1997 and 2015: standardized kitchen operations, trained staff, localized menu offerings like the Paneer Zinger, and a supply chain delivering strong gross margins. What it could not construct—because no franchisee can—is control over the two variables that determine long-term return on capital: contractual royalty rates and the franchisor's brand relevance. The former is fixed by contract; the latter depends on the licensor's strategy. As subsequent events demonstrate, the two core global brands in Devyani's portfolio have followed sharply divergent paths on brand relevance.
V. Segment Deep-Dive I: KFC India — The Engine of the Empire
To understand why Devyani remains a compelling business case despite its mixed financial record, consider the scene inside a KFC outlet in a Tier 2 Indian city on a Saturday evening.
Unlike the sit-down dining demographic of traditional Pizza Huts, the customer base consists largely of young consumers dining in, picking up delivery orders, or queuing at self-order kiosks. More importantly, direct competition remains sparse. While the Indian market is saturated with local burger joints and pizza chains, organized, standardized, nationally branded fried chicken is effectively a single-player category.
That structural dominance represents Devyani's single most critical asset, and its financial impact is evident in the operating figures. In the quarter ended June 30, 2026, KFC India generated ₹684.2 crore in revenue—an 11.7% year-on-year increase across 794 stores—delivering positive same-store sales growth of 3.3% and a brand contribution margin of 16.9%.1 Devyani added 11 net new KFC outlets during the quarter.12 For the full fiscal year 2026, KFC India generated ₹2,373.7 crore in revenue, up 8.9%, with a brand contribution margin of 15.8%.3
Within those quarterly metrics, channel mix highlights a key operational shift: dine-in sales reached 57% in the June 2026 quarter, up from 54% a year earlier.1 Following several years dominated by food delivery expansion, customer footfall has shifted back toward in-store dining. Commercially, this shift provides a meaningful structural advantage, as dine-in orders avoid third-party delivery aggregator commissions, expanding margins without requiring additional promotional spending.
Now the falsification. The central bullish thesis for KFC has long rested on the premise that fried chicken commands genuine pricing power in India. That claim can be tested against the empirical record.
Fiscal year 2026 provided a clear test, and the strong version of the pricing-power thesis did not hold. Full-year same-store sales growth for KFC India stood at negative 0.8%.3 In the September 2025 quarter, KFC's same-store sales declined 4.2%, Devyani reported a net loss of ₹21.9 crore, and consolidated brand contribution margin compressed from 13.6% a year earlier to 11.7%.13 On an earnings call, management attributed the slump to the convergence of Shraavana and Navaratri—two major religious periods marked by vegetarian observance—within the same quarter, alongside unseasonal rainfall in eastern India.13
While valid, that explanation highlights a structural vulnerability: a brand with true pricing power does not surrender 4% of same-store volume to predictable calendar events. Devyani's core growth engine remains structurally exposed to recurring seasonal lulls in non-meat consumption, particularly in its primary markets across North and East India. This is not an unexpected macroeconomic headwind, but a predictable, annual operating constraint.
Nor was fiscal 2026 an isolated occurrence. KFC's brand contribution margin compressed from roughly 19% in FY24 down to 15.8% for full-year FY26 as raw material inflation, aggregator commissions, and real estate rents escalated, forcing the company to rely on value combos to protect footfall.3 Increased promotional bundling demonstrates that input inflation could not simply be passed along to consumers through menu price increases.
The calibrated verdict. The evidence supports a narrower, yet still valuable, conclusion: KFC India possesses strong category power—backed by limited direct competition in organized chicken QSR, high customer repeat rates, and strong brand recall—but lacks true price power. Because it cannot fully absorb or pass through input inflation without sacrificing footfall, store-level margins remain a function of store volume and channel mix rather than pricing discretion.
This dynamic places critical weight on management's explicitly stated performance targets. Management has informed investors that reaching an Average Daily Sales (ADS) threshold of ₹105,000 to ₹110,000 yields a 20% brand contribution margin, projecting to reach that target within 18 to 24 months alongside long-term same-store sales growth of 5% to 6%.2 This represents a clear, measurable commitment. If KFC India's ADS remains stagnant near ₹98,000 into FY29 with brand contribution staying in the mid-teens, the operating-leverage thesis will be disproved—not from a collapse in chicken demand, but because store network additions outpaced store-level traffic growth.
In support of management's projection, the March 2026 quarter delivered KFC's highest same-store sales growth in fourteen quarters at 4.9%, followed by 3.3% growth in the June 2026 quarter.141 While two quarters signal an operational rebound rather than a definitive trend, the core engine of Devyani's business shows renewed momentum. Its secondary brand, however, faces a fundamental challenge.
VI. Segment Deep-Dive II: Pizza Hut's Restructuring & The SSSG Trap
In April 2026, Devyani made a decision that no franchisee makes lightly: it stopped building.
Speaking after the March 2026 financial results, Chief Financial Officer Manish Dawar told investors that Devyani would open no new Pizza Hut stores in the coming year, opting instead to return to basics by addressing portfolio gaps, product quality, and staff retraining.14 Marketing oversight was also consolidated under corporate leadership, with Chief Marketing Officer Sandeep Anand taking direct charge.14
To appreciate how sharply the brand's trajectory shifted, track its opening cadence. In FY25, Devyani opened 63 net new Pizza Hut outlets; in FY26, it opened just 9.4 By the June 2026 quarter, the company closed 13 stores on a net basis, shrinking the network from 639 at fiscal year-end to 626.31 An aggressive expansion drive had turned into an operational retreat.
The financial results explain the halt. In FY26, Pizza Hut India's revenue fell 1.6% to approximately ₹720.6 crore as full-year same-store sales contracted by 5.3%.15 The slowdown intensified in the March 2026 quarter, with revenue dropping 3.5% to ₹169.2 crore, same-store sales falling 3.7%, average daily sales settling at roughly ₹30,000, and brand contribution sliding into negative territory.14 The June 2026 quarter brought slight operational relief—same-store sales contracted by a softer 2.2% and average daily sales rose to ₹32,000—yet brand contribution remained negative at minus 1.9%, representing a store-level operating loss of roughly ₹4 crore.12
Stack the two core brands side by side, and the diagnostic contrast is stark. KFC generates roughly ₹98,000 in average daily sales per store, whereas Pizza Hut generates ₹32,000.1 Both operate under the same parent corporate structure, benefit from identical procurement channels, and share executive oversight. Pizza Hut even boasts a superior gross margin. The underlying problem is not supply-chain execution; it is consumer demand.
What actually happened to Pizza Hut in India. Three distinct forces squeezed the brand. First, Domino’s, operated by Jubilant FoodWorks, dominated delivery operations through superior store density, faster turnaround times, and an early-mover advantage in mobile ordering. Second, below Domino’s, budget-focused regional chains and cloud kitchens undercut entry price points. Third, above it, artisanal and gourmet pizzerias captured the high-end dining occasion. Pizza Hut was left marooned in the mid-market dine-in space—a format that consumer preferences had largely abandoned.
This outcome directly challenges the promoter group's portfolio diversification thesis.
Testing the claim. Management argues that a multi-brand portfolio hedges category risk, allowing stronger segments to carry weaker ones. In a master-franchise structure, however, that risk-mitigation mechanism is fundamentally constrained: a franchisee does not own brand equity, direct global marketing, or control product innovation. When consumer mindshare slips, the franchisee remains locked into long-term real estate leases and brand-specific kitchen infrastructure with minimal strategic pivot room. It can update store designs, trim overhead, and run local promotions, but it cannot re-architect the core brand.
That dynamic ties up capital that could otherwise fund higher-return opportunities. Every rupee bound to a 2,000-square-foot mall lease for a struggling Pizza Hut is a rupee unavailable for a KFC store earning a 17% brand contribution margin. Meanwhile, operational turnarounds move slowly: on the June 2026 call, management framed its recovery strategy around product revamps, pricing adjustments, and quality fixes, promising completion within a couple of months before rollout—messaging that had already been repeated across multiple earnings calls.142
Then came a major structural shift. On June 16, 2026, Yum! Brands announced the sale of its global Pizza Hut business—divesting the mainland China network to Yum China for $1.2 billion and selling the remaining international operations to private equity firm LongRange Capital for approximately $1.5 billion.169 The non-China transaction closed on September 1, 2026.9 Following the initial announcement, Indian franchisee shares dipped, with Devyani falling 1.4% and Sapphire Foods easing 1.05% in early trading.17
That market reaction was surprisingly muted. Devyani’s Pizza Hut operations are now licensed from a private equity firm operating under fixed fund lifespans and specific return targets, rather than a strategic parent managing both KFC and Pizza Hut. While Devyani has reported no changes to its contractual terms, the governance reality has shifted: a franchisee’s moat relies heavily on its licensor’s long-term strategic commitments, and Devyani's key licensor was sold.
The verdict. The multi-brand diversification thesis is unpersuasive in its strong form. Rather than hedging operational risk, a multi-brand franchise model can concentrate capital risk across assets the operator cannot independently steer. The benchmark for evaluating Pizza Hut's recovery is clear and trackable: brand contribution margin must return to positive territory and remain positive for at least two consecutive quarters. Until that milestone is reached, the division will continue to absorb capital and leadership bandwidth while weighing on group returns.
VII. Segment Deep-Dive III: Costa Coffee & Premium Beverage Optionality
India is fundamentally a tea-drinking market. Anyone selling coffee in the country must reckon with that baseline, which explains why out-of-home coffee has remained one of India's most promoted yet challenging consumer opportunities for two decades.
Devyani holds the master franchise for Costa Coffee in India. For years, management and analysts framed the brand as a capital-light optionality play on urban premiumisation. Coffee carries attractive product economics: gross margins on espresso beverages are among the highest in the food and beverage industry. The strategic thesis assumed that if Indian consumers adopted café habits at even a fraction of the pace seen across East Asia, Costa could compound steadily alongside the group's fast-food core.
Fiscal year 2026 delivered a reality check. Costa Coffee's Indian store count contracted to 198 from 220—the first net decline in more than five years—as Devyani closed 22 underperforming outlets.10 Revenue for the brand nevertheless expanded by roughly 7%, indicating that management pruned unproductive real estate rather than suffering a broad top-line decay.10 Within Devyani's disclosures, the franchisee-brands segment containing Costa generated ₹54.9 crore in revenue during the June 2026 quarter with a brand contribution margin of 15.1%, while Costa reported positive same-store sales growth of 10.2% on Average Daily Sales of ₹29,000.1
The operational picture is mixed but stabilizing: a chain that over-expanded, retrenched, and is now generating top-line growth from a smaller footprint, delivering the strongest same-store sales performance in Devyani's portfolio.
The competitive environment remains intense. Tata Starbucks dominates as the scale incumbent in Indian premium coffee, while Tim Hortons has expanded aggressively. Meanwhile, domestic specialty operators—such as Blue Tokai, Third Wave Coffee, and Subko—have reshaped the market by centering their brand identity on Indian coffee origins rather than relying solely on imported Western café templates.18 That landscape creates friction with global brand ambitions: in May 2025, Costa's global Chief Executive Philippe Schaillee stated that India should rank among the chain's top five global markets by 2030—a target that sits uncomfortably alongside a year of net store closures in India.10
Devyani also faces internal capital competition. The group has been preparing to launch Kwench, KFC's beverage-focused sub-brand offering iced coffees, shakes, and sparkling lemonades.18 Adding high-margin beverages to an established 794-store KFC network requires far less capital than opening standalone coffee shops, signaling where management expects higher incremental returns.
The economics of café operations clarify why store footprint adjustments occur so abruptly. While coffee inputs represent a minor fraction of menu pricing, the customer is effectively paying for dwell time—occupying space, seating, power outlets, and air conditioning. Consequently, café profitability is primarily a real estate challenge rather than a beverage sourcing issue. If a site carries high rent without generating sufficient dwell-oriented footfall, a gross margin exceeding 75% quickly dissolves into fixed occupancy costs; if the location is well-chosen, unit-level margins expand rapidly. That structural dynamic explains why Costa's Indian footprint reached 220 outlets before requiring the removal of 22 locations in a single year: aggregate averages masked significant variance across individual site performances.10
What this means for the investment case. Costa is currently too small to drive Devyani's consolidated performance, with the entire franchisee-brands segment accounting for roughly 3.5% of quarterly revenue.1 Its significance is diagnostic: it provides a clear case study of management's capital allocation discipline. Devyani over-expanded the network, acknowledged the misstep, and disciplined the estate. Rationalizing unproductive locations demonstrates operational responsiveness, though not strategic foresight. Costa remains a modest, improving asset supported by category tailwinds, yet it has not demonstrated a clear competitive moat against larger incumbents or culturally attuned specialty chains. The key metric for investors will be whether store additions resume sustainably on improved unit economics, proving that the retrenchment successfully re-anchored the brand.
While domestic coffee optionality remains modest, Devyani took a far larger strategic gamble 3,000 kilometers to the east.
VIII. International Expansion & The Thailand Acquisition (RD Thailand)
In December 2023, Devyani did something no Indian QSR operator had done: it bought a bigger restaurant business in a foreign country than most of its domestic peers owned at home.
The target was Restaurants Development Co. Ltd., a Thai company running 274 KFC outlets and employing more than 4,500 people. The price was $128.9 million.6 The structure was deliberately unusual: Devyani acquired the business through a Dubai vehicle, Devyani International DMCC, in which it held 51%, with Singapore's Temasek Holdings holding the balance alongside a local Thai partner. Devyani contributed ₹341 crore, Temasek ₹328 crore, and the Thai partner ₹11 crore.6 The transaction completed in early 2024.[^21]
Strategically, the logic was clear. Devyani already had small international operations in Nepal and Nigeria, but Thailand offered something different: a mature, high-frequency chicken-consuming market — Thailand eats fried chicken the way India eats street snacks — with an established 274-store network available in a single transaction. It also diversified away from the Indian religious calendar that periodically punctures KFC's domestic volumes.
Operationally, it worked. Thailand became Devyani's largest international contributor. As of March 31, 2026, the group operated 321 stores in Thailand, 40 in Nigeria and 38 in Nepal.3 The international division generated ₹1,859.4 crore of FY26 revenue, up 13.8%, at a brand contribution margin of 17.1% — a higher brand contribution than KFC India managed that year.3 In the June 2026 quarter, international revenue rose 20.7% to ₹523 crore with brand contribution improving to 18.2% from 16.7%, and Thai KFC ADS running at THB 55,000 across 323 stores.1
Nigeria deserves a footnote of its own. ADS there ran at 1,046,000 naira in the June quarter — a number that grows impressively in local currency and requires careful interpretation given the naira's depreciation.1 Nepal improved to NPR 159,000 from NPR 145,000.1 Small businesses, but genuinely growing.
Now the falsification, and this one is more nuanced than the bull or bear caricature.
The thesis claim was that Thailand would accelerate growth and hedge Indian cyclicality. On growth, it plainly did — FY25 consolidated revenue jumped 39.2% to ₹4,951 crore, overwhelmingly because Thailand consolidated.19 On margin, the initial concern that Thai gross margins were structurally lower than India's has been superseded by the actual reported numbers: international gross margin ran at 64.9% in FY26, below India's, but brand contribution at 17.1% ran above it, because Thai stores carry lower occupancy and delivery costs.3 The margin worry was directionally wrong at the line that matters.
The capital structure is a different matter, and here the concern is real. In March 2026, Devyani announced a fresh ₹347 crore into the Thai business — ₹232 crore to repay debt the Thai operator owed to the Dubai entity, and ₹114.8 crore for working capital and capex.7 The funding was itself borrowed: DID took a ₹232 crore short-term loan from Axis Bank's Dubai branch, secured by a corporate guarantee from Devyani International, plus a ₹114.8 crore convertible loan from the parent.7 The transaction was expected to complete by June 30, 2026, after which DID would hold 49% of Restaurants Development with a group entity, Yellow Palm Co. Ltd., holding 51%.7
Read that structure carefully. Two years after acquiring the business, Devyani was injecting fresh capital, funded by offshore short-term bank debt, guaranteed by the listed Indian parent, into a foreign subsidiary in which the listed entity's direct vehicle now holds a minority 49%. The acquisition did not become self-funding on the original timetable. And the parent's balance sheet — ₹3,833 crore of gross debt — carries a contingent obligation for foreign-currency borrowing on an asset it does not wholly own.5
Calibrated conclusion. Thailand is the strongest evidence in Devyani's record that management can buy an asset and operate it competently — international brand contribution above the Indian core is a genuine result, not a talking point. The claim survives on operations. What it does not survive on is financing discipline: the deal required incremental parent-guaranteed leverage well after closing, at a time when consolidated returns were already negative. The forward test is whether international operations generate enough free cash to service and retire the Dubai facility without further injections from India. If a second capital call arrives, the accretion argument is finished.
Which brings us to the arithmetic underneath every one of these decisions.
IX. Store Economics, Unit-Level Math, & Capital Allocation
At its core, every quick-service restaurant business reduces to a single equation repeated across thousands of locations—an equation that clarifies much of Devyani's financial performance.
The unit-level arithmetic is straightforward. Building a new KFC location requires between ₹1 crore and ₹1.5 crore in capital, while a Pizza Hut or Costa Coffee outlet requires progressively less, though format-specific capital expenditures are not consistently disclosed. That upfront investment secures the lease, kitchen equipment, interior fit-out, and exterior signage. Once open, the location generates daily sales, from which Devyani retains roughly 69% after accounting for direct food costs.1 Out of that remaining 69%, the store pays rent, labor, utilities, aggregator commissions, royalties, and local marketing. What remains is the store-level operating profit—termed brand contribution—measured before allocating corporate overhead, depreciation, interest, and taxes.
Those store-level margins vary sharply across Devyani's portfolio: KFC India generates a brand contribution of 16.9%, Pizza Hut stands at negative 1.9%, and international operations deliver 18.2%.1 This metric represents the core indicator of store profitability and serves as the single most critical line for evaluating the company's operating performance.
This store-level structure interacts directly with Devyani's rapid expansion, explaining years of subdued consolidated returns. The company added 257 net new outlets in FY25 to reach a network of 2,039 stores, followed by 217 net new additions in FY26 to expand the footprint to 2,256 outlets.193 A newly opened store typically operates well below mature sales thresholds, requiring 18 to 36 months to ramp up to full earnings potential. The fixed overhead, however—including lease liabilities, store staffing, depreciation, and financing costs for the underlying capital—accumulates on the income statement immediately upon launch.
For an operator adding more than 200 locations annually across a 2,000-store estate, roughly 10% of the entire network remains in an unseasoned, sub-scale, or unprofitable ramp phase at any given point. This structural drag is an inherent feature of rapid unit expansion rather than an operational failure. Consequently, headline consolidated profitability systematically understates the underlying earning power of the mature store base—though it equally implies that if mature store returns remain inadequate, rapid expansion consumes capital rather than compounding long-term value.
Determining which dynamic dominates Devyani's performance remains the central debate for investors. In FY26, the company reported a net loss of ₹42.5 crore alongside 217 net store additions, the integration of an acquired loss-making brand portfolio, and negative same-store sales growth across its two largest Indian brands.43 Adjusting for the dilution of unseasoned store openings reveals a modestly profitable core, whereas unadjusted results reflect net cash consumption. Evaluating the stock ultimately depends on how one interprets this operational split.
The lease accounting problem. Accounting standards introduce an additional layer of financial distortion that affects key operating ratios. Under Ind AS 116, leased restaurant properties must be recorded on the balance sheet by capitalizing the present value of future lease commitments as a debt-like liability matched against a right-of-use asset. Operating lease expenses are consequently replaced by depreciation and interest charges. For an enterprise operating 2,255 leased sites, this accounting treatment inflates reported EBITDA by removing rental expenses, while simultaneously expanding reported debt liabilities and depressing interest coverage ratios.
Devyani's reporting explicitly separates these accounting effects. For the June 2026 quarter, the company reported headline EBITDA of ₹254.8 crore alongside an operating EBITDA of ₹151.1 crore.1 The ₹104 crore spread represents the non-cash lease accounting adjustment. While headline commentary highlighted a 16.1% EBITDA margin, the cash-relevant operating EBITDA margin stood at 9.6%.1 Management's transparent disclosure of both figures provides essential clarity, yet evaluating performance against historical results prior to 2019 or against peers using alternative accounting treatments requires explicit adjustment for these lease obligations.
The capital allocation audit. Beyond core store expansion, Devyani has directed capital toward three principal areas: the Thai acquisition, the Sky Gate transaction, and home-grown brand initiatives such as Vaango and Food Street. The execution record across these investments is mixed. Vaango has developed into a functional asset—generating average daily sales of ₹26,000 with same-store sales growth of 7.1% in the June 2026 quarter—yet it remains immaterial relative to group earnings after years of operation.1 Costa Coffee underwent aggressive expansion before management retrenched and closed underperforming outlets.10 Meanwhile, the Thailand acquisition delivered strong operational results, though it required additional capital injections beyond original projections.7
This track record points neither to reckless capital destruction nor to strict capital discipline. Instead, it reveals a promoter group willing to deploy leverage for large-scale expansion and slow to prune underperforming assets, while equity returns remain below the cost of capital. Reflecting these capital constraints, the board opted not to recommend a dividend for FY26 due to standalone losses.3 Fifteen years into expanding its store network, the enterprise has yet to generate sustainable free cash flow for shareholder distributions.
This represents the financial standing of the business today. To understand how this balance sheet profile took shape, the narrative moves to the critical operational disruption that tested the entire sector.
X. COVID-19 Crisis, Delivery Aggregator Pivot, & The 2021 IPO
In March 2020, India announced a nationwide lockdown with roughly four hours of notice. For an enterprise whose entire operational model depended on welcoming customers into dining rooms, the shutdown presented an immediate existential shock.
The financial data from that period capture the disruption precisely. Dine-in, which accounted for 48.85% of Devyani's revenue in FY20, collapsed to 29.80% in FY21.[^11] Nearly twenty percentage points of revenue mix vanished in twelve months. The company permanently shuttered 61 core-brand locations that year—sites whose unit-level economics could not survive the loss of footfall.[^11]
What followed was the most consequential operational restructuring in Devyani's history, executed under severe pressure. Management accelerated integration with Zomato and Swiggy, built out proprietary digital ordering channels, renegotiated leases with landlords facing sudden vacancy risks, and streamlined store staffing. The dine-in-optimized Pizza Hut estate—large-format locations designed for sit-down family dining—became the portfolio's most vulnerable asset, creating an operational drag that was never fully reversed.
The pivot also introduced a permanent structural cost. Aggregator commissions and promotional co-funding—which typically range from the high teens to mid-twenties as a percentage of order value in India—shifted from a minor channel expense into a permanent feature of the income statement. Devyani resolved a short-term survival crisis by surrendering a portion of store-level unit economics to two platform aggregators. Every QSR operator made a similar compromise, and none has fully unwound it—which is why KFC India's dine-in channel mix recovering to 57% carries notable operational significance.1
That structural compromise fundamentally altered the competitive landscape. An aggregator commission is far more than a service fee. When a customer places an order through Zomato or Swiggy, the platform controls the user interface, search ranking, promotional visibility, payment processing, and consumer data. The restaurant is effectively converted from an independent retailer into a food supplier, while the platform displays competing offerings side by side.
For a brand with weak differentiation, that intermediation is damaging because platforms make product substitution effortless. For a brand with strong consumer pull, the impact is manageable because customers actively search for the brand rather than browsing the category. This operational distinction explains why KFC and Pizza Hut diverged sharply under the same corporate management: one brand generates direct search volume, while the other is routinely browsed past.
Then, with remarkable timing, came the initial public offering.
Devyani's public offering opened in August 2021, raising ₹1,838 crore in a price band of ₹86 to ₹90 per share—comprising a ₹440 crore fresh issue alongside a ₹1,398 crore offer for sale by existing shareholders.20 Allotment was completed on August 11, and the stock listed on August 16, 2021, at ₹140.90 per share, delivering a listing gain of roughly 56% over the issue price.20
Several aspects of that transaction warrant analytical scrutiny rather than simple celebration.
First, Devyani was loss-making at the time of listing, a point highlighted publicly by equity research analysts during the subscription window.21 The company went public on an investment thesis centered on post-pandemic consumption recovery and footprint expansion runway, rather than established profitability.
Second, the majority of the proceeds did not fund enterprise growth. Roughly 76% of the capital raised represented an offer for sale by existing investors, while the fresh issue portion was allocated toward debt repayment rather than new store rollouts.20 While standard corporate practice, this structure prioritized liquidity for pre-IPO shareholders over balance-sheet expansion.
Third, and most tellingly: five years after listing, the equity raised has been absorbed by network expansion, gross debt stands at ₹3,833 crore, no dividends have been declared, and subsequent growth has required additional borrowings, a preferential equity issuance for the Sky Gate transaction, and offshore bank facilities.53 The IPO temporarily deleveraged the balance sheet, but the underlying business model re-leveraged it.
The takeaway. The pandemic demonstrated Devyani's operational adaptability under extreme distress—the enterprise survived, preserved the majority of its footprint, and rebuilt its delivery capabilities. The IPO revealed a different reality: public market equity in this business model gets consumed by store expansion rather than accumulating as free cash flow. Together, these two events established the operating pattern that governs the business today: growth funded by continuous capital deployment, with sustainable equity returns still pending.
XI. Management Governance, Related-Party Dynamics, & Trust Stress Test
On April 1, 2026, Devyani changed the person running the company for the first time in its modern history—and the choice revealed much about what the board views as the primary strategic priority.
Virag Joshi, who had driven the Yum! relationship and the operating build-out for decades, superannuated as Whole-time Director on March 31, 2026, remaining on the board as a Non-Executive Director providing strategic advice.22 His replacement as President and Group CEO was Manish Dawar—until that moment the company's Chief Financial Officer, who joined Devyani in 2021 after stints at Hindustan Unilever and Reebok India.22 Anupam Kumar, previously Executive Vice President of Finance, stepped up as CFO, while Neeraj Tiwari joined as Chief Technology Officer.22
Promoting the CFO to CEO ahead of a complex all-stock merger in a year of losses is a specific corporate signal. Boards make this move when they believe the binding constraint is capital discipline, integration, and cost control, rather than operating flair or brand-building. Whether that is the correct diagnosis remains open to debate—Pizza Hut's challenge is arguably a marketing and product issue—but the signal itself is unambiguous.
Above the executive layer sits a governance structure that a sceptical investor should examine carefully. Ravi Kant Jaipuria serves as Non-Executive Chairman and Founder, with Varun Jaipuria as Non-Executive Director. The board comprises 10 directors, of whom five are independent.3 The promoter group holds roughly 62.5% of the equity, with RJ Corp Limited alone holding 57.98% as of March 31, 2026.233
The bull reading of that ownership structure is alignment: the family's wealth rises and falls with the stock, minimizing the risk of a professional manager optimizing for an annual bonus. The sceptical reading is that a 62.5% holder controls every ordinary resolution outright, leaving minority shareholders with influence primarily through the market price. Both perspectives are valid simultaneously. What matters is observable corporate behavior.
On that front, the record contains a genuine positive worth stating precisely: Devyani's promoters and persons acting in concert declared no encumbrance on their shares for the financial year ended March 31, 2026, with the declaration filed to the exchanges on April 3, 2026.23 Share pledging by promoters is one of the most reliable early-warning indicators in Indian mid-caps, and its absence here—for that named period, on that named filing—is meaningful. It is not a general assurance about the group's overall leverage, and it should not be read as one.
Related-party transactions are unavoidable in this structure and warrant ongoing scrutiny. Devyani operates inside an ecosystem that includes Varun Beverages, the PepsiCo bottler—and Devyani's restaurants serve PepsiCo beverages. Group entities share office premises, administrative infrastructure, and logistics. The Thailand structure now involves Yellow Palm Co. Ltd., a group entity holding 51% of the Thai operating company while the listed entity's Dubai subsidiary holds 49%.7 The Sky Gate acquisition was funded through a preferential equity issuance.3
None of these arrangements is improper on its face, and all remain subject to standard regulatory frameworks, audit committee approvals, and shareholder ratifications for material transactions. But the aggregate effect is a corporate structure of real complexity: a listed Indian parent, a Dubai subsidiary co-owned with Temasek, a Thai operating company majority-held by a group entity, an offshore bank facility guaranteed by the parent, and a pending merger. An activist investor's first question would be simple: how much of the group's underlying economics can a minority shareholder in the listed entity actually see, and how much sits in vehicles where the listed company holds less than half?
Management credibility, judged by behavior over time. The pattern across recent earnings calls cuts both ways. When financial results disappoint, management's explanations are external and specific: religious calendar seasonality, unseasonal rains in eastern India, crude and LPG cost inflation, wage and utility increases, and exchange-rate pressure.132 These factors are real, but they are also recurring features of operating restaurants in India rather than unexpected shocks.
To management's credit, they have paired these explanations with concrete, falsifiable commitments: the ₹105,000 to ₹110,000 Average Daily Sales threshold, the 20% KFC brand contribution target, the 5% to 6% long-run same-store sales expectation, and the decision to freeze Pizza Hut store openings rather than merely discuss operational fixes.214 Halting expansion in a struggling brand is a visible, costly act of capital discipline that provides more signal than earnings-call commentary. Similarly, following the September 2025 Goods and Services Tax rationalization, the chairman publicly stated that the impact on the category was minimal and that input-cost benefits had been passed to consumers—a measured assessment at a time when industry peers were claiming a broader demand windfall.24
The verdict on credibility is neither uncritical trust nor outright skepticism. This leadership team makes specific, dated, checkable commitments, and execution over the next two years will determine whether those targets are met. That level of accountability is more than many Indian promoter groups provide.
XII. Competitive Landscape & Industry Structure (7 Powers & Porter's 5 Forces)
Strip away the brand logos and ask a harder question: in the value chain running from a chicken farm to a consumer's hand, where does the profit actually pool? Devyani sits in the middle of that chain, and structural business frameworks make its position uncomfortably clear.
Hamilton Helmer's 7 Powers, applied honestly.
Cornered resource is the power Devyani is usually credited with, but the claim requires qualification. The company holds exclusive KFC development rights in defined Indian territories as well as Nepal, Nigeria, and Thailand. That creates a genuine barrier, as a new entrant cannot open a KFC in Devyani's licensed regions. Yet it remains a licensed resource, held under agreements with a franchisor that can be sold—as Pizza Hut's non-China business was in September 2026—and that extracts roughly 6% of gross revenue for the privilege.11 Devyani does not own the resource; it rents it. The distinction is the difference between a true moat and a lease on a moat.
Scale economies are real and demonstrably working. A network of 2,255 stores purchases poultry, cheese, packaging, and media at prices a 200-store operator cannot match, helping drive gross margins near 69%.1 This represents Devyani's most defensible advantage and the clearest operational inheritance from the Jaipuria bottling business.
Process power—accumulated operating know-how built across 29 years—is plausible, but empirical evidence is mixed. Strong process power should manifest as superior store-level margins relative to peers. While Devyani's KFC brand contribution of roughly 17% is respectable, its Pizza Hut contribution is negative.1 Process power that fails to generate store-level profits on a product with a 76% gross margin is doing limited work.
Branding power does not belong to Devyani at all. Yum! Brands built it, and LongRange Capital acquired a share of it through Pizza Hut. Devyani remains purely the operational franchisee.
Switching costs and network economies are essentially non-existent. A consumer deciding between a KFC meal and a street-side chicken roll faces zero switching cost.
Counter-positioning is absent. Devyani operates as the scale incumbent rather than an insurgent disruptor.
Porter's Five Forces, and the fifth force that Porter did not name.
Rivalry: extreme. Devyani competes with Sapphire Foods—its Yum! franchisee counterpart and pending merger partner—alongside Jubilant FoodWorks in pizza, Westlife Foodworld and Restaurant Brands Asia in burgers, and a fragmented market of regional chains.
Threat of substitutes: very high and structurally underrated. India possesses one of the deepest, lowest-cost, and most culturally embedded street-food ecosystems in the world. Every organized fast-food meal represents a discretionary trade-up from local alternatives available at a fraction of the price.
Buyer power: high. Indian fast-food consumers are exceptionally price-sensitive. Devyani's inability to pass through full input cost inflation without losing customer footfall demonstrates this constraint.
Supplier power: high and dual-sided. On one side sit commodity suppliers for poultry, dairy, and edible oil, whose price cycles Devyani cannot fully hedge. On the other sit the franchisors, who dictate royalty rates, mandate store formats, and control brand strategy.
Channel power: the decisive force. Zomato and Swiggy maintain a functional duopoly over Indian food delivery. When an operator's primary growth channel is controlled by two platforms that own both the customer relationship and ordering data, those aggregators capture a structural share of industry economics. Devyani's strategic emphasis on expanding dine-in sales and building proprietary digital channels serves as an implicit acknowledgment of how expensive third-party platforms have become.
A comparison with peers clarifies these industry dynamics. Jubilant FoodWorks built Domino's around a delivery-first model years before food aggregators emerged, allowing it to retain customer relationships and protect pizza margins while Pizza Hut struggled. Westlife Foodworld and Restaurant Brands Asia operate burger formats in western and southern India under different real-estate profiles and competitive conditions. Sapphire Foods, prior to its pending merger, offered the closest direct benchmark—operating identical brands under the same franchisor across different territories. Sapphire's Pizza Hut same-store sales contracted by 9% in FY26, a steeper decline than Devyani's 5.3% drop.15 When two independent operators running the same brand in different regions of the country report sharp same-store sales declines, the underlying issue lies with the brand rather than store management.
The synthesis. Devyani occupies a squeezed position: paying royalties to its franchisor above, surrendering margin to delivery aggregators beside it, serving a price-sensitive consumer base below, and competing against abundant local substitutes all around. Its principal defense remains operational scale—maintaining a network large enough to keep unit costs below those of smaller competitors.
That structural reality forms the underlying logic of the transaction about to reshape the enterprise.
XIII. Historical Falsification & Critical Risk Radar
Evaluating Devyani's investment case requires placing management's key strategic claims alongside the empirical record to establish definitive verdicts.
Claim one: multi-brand ownership diversifies risk. Rejected. Pizza Hut delivered negative same-store sales of 5.3% across FY26, with brand contribution turning negative and store count contracting.151 The failure mechanism is specific to master franchising: Devyani controls local execution but not overall brand strategy, leaving capital stranded in format-specific leases when consumer preferences shift. The revised, defensible claim is that multi-brand ownership diversifies revenue rather than returns. Falsification metric going forward: Pizza Hut India brand contribution margin. Two consecutive positive quarters would validate the narrower revenue-diversification claim, whereas continued negative contribution through FY27 confirms full rejection.
Claim two: the Varun Beverages playbook transfers to QSR. Narrowed sharply. The Jaipuria distribution model transfers to procurement scale and rollout velocity, but fails to protect capital returns. Three-year average return on equity has been negative, while return on capital employed sits near 5%.5 Falsification metric: consolidated ROCE. Sustained movement into the low teens would validate the broader claim; another three years in mid-single digits closes the argument.
Claim three: the Thailand acquisition was accretive. Intact on operations, unproven on capital. International brand contribution of 17.1% in FY26 exceeded KFC India's 15.8%, refuting initial concerns that Thai margins would dilute group performance.3 However, the business required a ₹347 crore capital injection in March 2026—funded by parent-guaranteed offshore debt—two years after the initial transaction.7 Falsification metric: whether the Dubai debt facility is retired entirely from international operating cash flow without additional calls on the Indian parent.
Claim four: capital allocation is disciplined. Unproven, with a mixed record. The case against strict discipline is clear: Costa Coffee expanded to 220 locations before management shuttered 22 outlets in a single year.10 Similarly, Pizza Hut store additions ran at 63 in FY25 before slowing sharply to just 9 in FY26.4 Home-grown brand ventures have operated for years without generating material earnings. The counter-evidence for emerging discipline is recent: management halted Pizza Hut construction rather than adding unprofitable footprint, and pruned underperforming Costa locations while growing overall brand revenue.1410 The fair verdict is that Devyani corrects operational missteps visibly and at significant expense, but repeats them frequently enough that retrenchment remains a regular feature of its strategy. Falsification metric: whether the Sky Gate portfolio scales to justify its price tag of more than ₹419.6 crore, or joins Vaango as a permanently sub-material line item.25
Claim five: Sky Gate was a smart entry into Indian cuisine. Too early to judge, with accounting that warrants close monitoring. Devyani acquired 80.72% of Sky Gate Hospitality—owner of Biryani By Kilo, Goila Butter Chicken, and The Bhojan—for ₹419.6 crore on June 10, 2025, reaching full ownership by March 7, 2026, through a follow-on purchase comprising ₹27.5 crore in cash and ₹30 crore in non-convertible redeemable preference shares.25263 Early operational performance is positive: Biryani By Kilo posted average daily sales of ₹76,000 with 7.2% same-store sales growth in the June 2026 quarter, while own-brands brand contribution rose to 10.2% from 7.9%.1 Management has described BBK as a future ₹1,000 crore brand.2 However, the acquisition widened consolidated losses in FY26, and own-brand store count expanded rapidly from 96 to 217 in twelve months—representing a fast integration of an acquired network while management simultaneously executes a major merger and a core brand turnaround.43
The current risk radar, restricted to mechanisms directly impacting the income statement:
Channel economics. Aggregator commissions and promotional co-funding reduce store contribution directly. Any increase in platform take-rates flows straight to the bottom line without an operational offset.
Input inflation. Commodity costs for poultry feed, dairy, and edible oil cannot be hedged at Devyani's scale, while management flagged crude, LPG, utility, and wage inflation as active operational headwinds as recently as July 2026.2
Franchisor transition risk. Pizza Hut's global ownership transferred to private equity firm LongRange Capital on September 1, 2026.9 While contract terms remain unchanged, a private equity franchisor operates under different strategic horizons and return expectations than a corporate brand parent, introducing an open governance variable.
Integration and execution risk. Devyani is concurrently merging with a listed competitor, integrating an acquired multi-brand enterprise, restructuring Pizza Hut, and refinancing a foreign subsidiary—four major corporate transformations under a CEO who assumed leadership five months ago.
Currency and offshore leverage. Operational exposures across the naira, baht, and dirham, combined with a parent corporate guarantee on a dollar-linked borrowing facility, create ongoing balance-sheet friction against an Indian rupee under pressure.27
Accounting judgment to monitor. Two balance-sheet areas carry significant estimation risk. The first is asset impairment across store equipment and right-of-use assets for underperforming outlets, where persistent store-level losses raise questions regarding asset carrying values. The second is goodwill and intangible assets from the Sky Gate and Thailand acquisitions, which require annual impairment testing. Neither area has triggered adverse auditor comments, and the board maintains ten directors—including five independent members—overseeing reporting.3 These remain operational variables to monitor in future disclosures.
Predictable seasonality. The impact of Shraavana and Navaratri on non-vegetarian consumption is an annual, structural reality in core northern and eastern markets that must be built into operating baselines rather than treated as an unexpected quarterly shock.
XIV. Bear vs. Bull Thesis & Future Growth Vectors
Every debate about this stock eventually reduces to a single disagreement: is Devyani a good business having a bad few years, or a mediocre business having a good few quarters?
The bull case, stated at its strongest.
Start with the merger, which represents the most significant strategic catalyst for the company since the Thailand transaction. On January 1, 2026, Devyani and Sapphire Foods announced an all-stock merger valued at approximately $934 million, consolidating India's two largest Yum! franchisees into a single entity.827 Under the agreed terms, Sapphire shareholders receive 177 Devyani shares for every 100 held, with an appointed date of April 1, 2026.27 The combined group would operate more than 3,000 restaurants generating roughly $1 billion in annual revenue, creating one of Yum!'s largest franchise partners worldwide.3 Management guides to annual synergies of ₹210 crore to ₹225 crore starting from the second full year post-integration, driven by unified brand strategy, procurement scale, shared technology infrastructure, and leaner corporate overheads.27 As part of the transaction framework, Arctic International, a Devyani group entity, agreed to acquire an 18.5% equity stake in Sapphire from existing promoters, retaining an option to assign that holding to a financial investor.27 Yum! approved the consolidation, and Devyani additionally agreed to acquire 19 KFC restaurants in Hyderabad operated directly by Yum! India.27 Stock exchanges issued their observation letters on June 16, 2026, and the scheme was subsequently revised in August 2026, with completion targeted by the end of FY27, subject to regulatory, tribunal, shareholder, and creditor approvals.28292
Set against ₹210 crore to ₹225 crore of projected synergies, Devyani's entire FY26 net loss was ₹42.5 crore.4 If management realizes even half of those cost savings, the company's baseline profitability changes fundamentally. That is the bull thesis in its simplest form.
Beyond the merger, the secular growth runway remains intact. India's organized fast-food market penetration stays at a fraction of North American or Chinese per-capita levels. KFC India, operating 794 stores with recovering same-store sales, maintains clear headroom to expand beyond 1,000 locations in a category with no comparable organized rival.1 Internationally, the Thai operations continue to outperform the domestic core on brand contribution margins.3 Meanwhile, home-grown brands are scaling faster than anticipated, with both Biryani By Kilo and Goila Butter Chicken reaching operational break-even ahead of schedule.3 Digital ordering channels, self-service kiosks, and drive-thrus continue to expand average order values. Finally, the operating leverage mechanism is straightforward: management needs an estimated 7% to 12% increase in sales per KFC outlet to unlock a 300-basis-point expansion in brand contribution margin—a substantial profit unlock on a ₹2,400 crore brand.2
The bear case, stated at its strongest.
The bear case does not contest top-line expansion; it questions whether that revenue translates into durable equity returns.
Devyani has expanded revenue at a compound annual rate of roughly 19% over the past decade, yet its three-year average return on equity remains negative, return on capital employed sits near 5%, gross debt totals ₹3,833 crore, dividends remain absent, and the company reported a net loss for the most recent fiscal year.543 Skeptics argue that these depressed returns are not a temporary byproduct of growth investment, but an inherent output of the master-franchise model. A franchisee surrenders 6% of gross sales to its licensor, pays high-teens to mid-twenties commissions to food delivery aggregators, absorbs escalating lease liabilities across 2,255 locations, and absorbs rising labor costs within a price-sensitive market that resists menu price increases. The residual earnings are thin, cyclical, and capital-intensive.
On the Sapphire merger, skeptics emphasize that combining two franchisees alters none of the underlying industry forces. Consolidation yields procurement scale, but it eliminates a competitor that operated in non-overlapping territories. It confers no added bargaining power over Yum!, LongRange Capital, food delivery platforms, or end consumers. Both companies operated at a loss in the first half of FY26—Devyani losing ₹22 crore and Sapphire losing ₹15 crore—and combining two unprofitable franchisees yields a larger unprofitable franchisee unless synergies prove durable and execution remains clean.27 Furthermore, Sapphire's Pizza Hut estate faces even steeper operational headwinds than Devyani's, with full-year FY26 same-store sales contracting 9% and revenue falling 7% to approximately ₹506.5 crore.15
The bear case also highlights structural complexity as a permanent drag on valuation multiples. Offshore corporate vehicles in Dubai, a minority equity position in Thailand, parent guarantees on foreign-currency debt, promoter-affiliated stake purchases through Arctic International, and ongoing transactions with the group's bottling arm create administrative opacity that pure-play peers do not carry.
The activist's letter, if one were written.
An activist investor would argue that Devyani's asset portfolio requires active rationalization: exit the Pizza Hut franchise rather than funding another operational restructuring; consolidate the international corporate structure into wholly owned entities or monetize it; freeze store additions for 18 months to allow the 2,255-store network to mature; and disclose granular per-format capital expenditure and store payback timelines so shareholders can verify capital returns independently. The counter-argument from management is that master-franchise agreements carry contractual store-opening mandates and exit restrictions—an explanation that underscores the fundamental capital constraints of the master-franchise model.
Where the evidence leaves it.
The empirical record presents an enterprise defined by sharp internal contrasts: a scaled operator with high-performing assets in KFC India and Thailand, a troubled Pizza Hut franchise, a high-stakes merger in progress, and a ten-year record of converting top-line growth into minimal equity return. The bull case requires merger synergies to materialize on schedule and KFC store sales to cross management's target threshold. The bear case does not require a dramatic failure of either—merely that their benefits arrive late.
XV. Business & Investing Playbook
What generalisable lessons does 35 years of Devyani teach an investor evaluating a franchised consumer business?
One: a master franchise is a leveraged bet on someone else's brand decisions. The franchisee controls site selection, service speed, cost structures, and local menu adaptation. The franchisor controls consumer pull: brand positioning, global product pipelines, marketing investment, and, in Pizza Hut's case, the identity of the brand owner itself. Devyani's two primary brands, managed by the same team within the same market, generate a 16.9% store margin and a negative 1.9% store margin respectively.1 Operational discipline alone cannot overcome structural weakness in brand equity. In assessing any franchisee, the primary question is not management competence, but brand health.
Two: in retail, store expansion is a vanity metric; sales per store determines economic viability. Adding locations drives top-line expansion, but store additions operating below their leverage thresholds consume capital and dilute returns. Devyani's financial disclosures illustrate this dynamic: increasing KFC's average daily sales from ₹98,000 to ₹110,000 expands brand contribution from 17% to 20%—a 300-basis-point margin improvement across the group's primary asset, achieved without deploying additional capital.12 Incremental revenue from an existing unit generates far higher operating leverage than top-line growth driven by new openings. A retailer expanding store count while same-store sales remain flat or negative is effectively buying revenue at the expense of return on capital.
Three: evaluate lease accounting before comparing valuation multiples. Standard Ind AS 116 lease capitalisation inflates reported EBITDA and balance-sheet leverage relative to underlying cash flows. Devyani's ₹254.8 crore reported EBITDA and ₹151.1 crore operating EBITDA in a single quarter reflect distinct financial metrics: the former includes lease accounting adjustments, while the latter reflects actual operational cash flow.1 Evaluating a lease-heavy QSR operator against an asset-light peer without adjusting for lease liabilities distorts valuation comparisons.
Four: evaluate management by variables within their direct control. Operational leadership cannot alter a franchisor's global brand strategy, but it controls capital allocation. Devyani's leadership demonstrated discipline by halting Pizza Hut store expansion to protect unit economics, even at the cost of short-term network growth.14 Conversely, management controls corporate leverage, offshore balance-sheet guarantees, and inorganic acquisitions—areas where capital deployment has remained consistently expansionary. Capital allocation decisions provide a clearer signal of corporate direction than forward guidance.
The three key performance indicators to monitor. The investment case can be evaluated through three quarterly metrics:
First, KFC India Average Daily Sales and brand contribution margin. This represents the primary earnings engine. Management has tied its operating thesis to average daily sales crossing ₹105,000 to ₹110,000 to unlock a 20% brand contribution margin.2 Key monitorables include whether daily sales bridge the gap from ₹98,000 and whether incremental revenue flows through to margins or is absorbed by occupancy, labor, and platform commission costs.
Second, Pizza Hut India brand contribution margin. The critical indicator for Pizza Hut is not store count or top-line revenue, but store-level contribution, which identifies whether the network is generating or consuming cash. Following a negative 1.9% brand contribution in the June 2026 quarter, a sustained return to positive contribution represents the principal benchmark for operational recovery.1
Third, consolidated return on capital employed relative to net debt. At approximately 5% ROCE against ₹3,833 crore of gross debt, and with a pending merger expanding the equity base, this metric provides the ultimate test of long-term value creation.5 It will determine whether three decades of network expansion—from a regional ice-cream enterprise to a 3,000-restaurant multinational footprint—has generated returns above the company's cost of capital.
References
-
Devyani Q1 FY27 slides: record EBITDA amid brand turnaround — Investing.com, 2026-07-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Devyani International Ltd (BOM:543330) Q1 2027 Earnings Call Highlights — Yahoo Finance, 2026-07-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Devyani International Annual Report FY 2025-26: Revenue at ₹56,115 Million, Merger with Sapphire Foods Announced — ScanX, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Devyani International reports Rs 42.5 crore FY26 loss; Pizza Hut store openings drop from 63 to 9 — Storyboard18, 2026-05 ↩↩↩↩↩↩↩↩
-
Devyani International Ltd — consolidated financials, ratios and balance sheet — Screener.in ↩↩↩↩↩↩↩↩
-
India KFC operator Devyani International enters Thailand with $129 million deal — ThePrint, 2023-12-18 ↩↩↩
-
Devyani International to invest ₹347 crore in Thailand's KFC operator — Business Standard, 2026-03-20 ↩↩↩↩↩↩↩↩
-
Shares of KFC and Pizza Hut Indian operator Devyani jump on merger with rival franchisee Sapphire — CNBC, 2026-01-02 ↩↩
-
Yum Brands completes $2.7 billion sale of Pizza Hut business — Investing.com, 2026-09-01 ↩↩↩↩
-
Costa Coffee store count shrinks to 198 in India in FY26, revenue up 7% — Business Standard, 2026-07-26 ↩↩↩↩↩↩↩↩
-
Devyani International — Franchisee of Yum! Brands: franchise terms and royalty structure — PA Wealth ↩↩
-
Devyani International posts nearly four-fold Q1FY27 profit; adds 11 KFC stores, trims 13 Pizza Hut outlets — Storyboard18, 2026-07-29 ↩
-
KFC, Pizza Hut operator Devyani International stock slips 3% after muted Q2 results — Business Standard, 2025-11-07 ↩↩↩
-
Devyani International freezes new Pizza Hut stores in FY27 as loss-making brand undergoes marketing reset — Storyboard18, 2026-05 ↩↩↩↩↩↩↩↩
-
Pizza Hut's India partners go back to basics on products and pricing — Business Standard, 2026-06-17 ↩↩↩↩
-
Yum! Brands, Inc. Enters into Agreements to Sell Pizza Hut for $2.7 Billion — Yum! Brands, 2026-06-16 ↩
-
Sapphire Foods down 1%, Devyani International sheds 1.4% after Yum Brands announces Pizza Hut sale — Moneycontrol via TradingView, 2026-06-17 ↩
-
From burgers to brews: Why QSR brands are betting big on coffee — Storyboard18, 2026 ↩↩
-
Devyani International FY25 Earnings Results: Revenue Soars 39%, Adds 257 New Stores — Angel One, 2025-05 ↩↩
-
Devyani International IPO Date, Price, Issue Size and Listing Details — Chittorgarh, 2021-08 ↩↩↩
-
Should you bid for loss-making Devyani International's Rs 1,800 crore IPO? — Business Standard, 2021-08-03 ↩
-
KFC India operator Devyani International promotes CFO Manish Dawar to CEO — Business Standard, 2026-02-04 ↩↩↩
-
Devyani International promoters declare no encumbrance on shares in FY26 — ScanX, 2026-04-03 ↩↩
-
India's KFC, Pizza Hut operator Devyani hails historic GST move, sees minimal impact — A2Z Taxcorp, 2025-11 ↩
-
Devyani to acquire 80.72% stake in Sky Gate Hospitality for ₹419.6 crore — Business Standard, 2025-04-24 ↩↩
-
KFC operator Devyani International to acquire majority 81% stake in 'Biryani by Kilo' parent for ₹420 crore — Devyani International Limited, 2025-04-24 ↩
-
Devyani–Sapphire Merger Explained: Share Swap, Timeline, Synergies — PL Capital, 2026-01 ↩↩↩↩↩↩
-
Devyani International, Sapphire Foods rally up to 9% on merger approval — Business Standard, 2026-06-16 ↩
-
Devyani, Sapphire Foods shares rise 3% after revision of merger scheme — Business Standard, 2026-08-27 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube