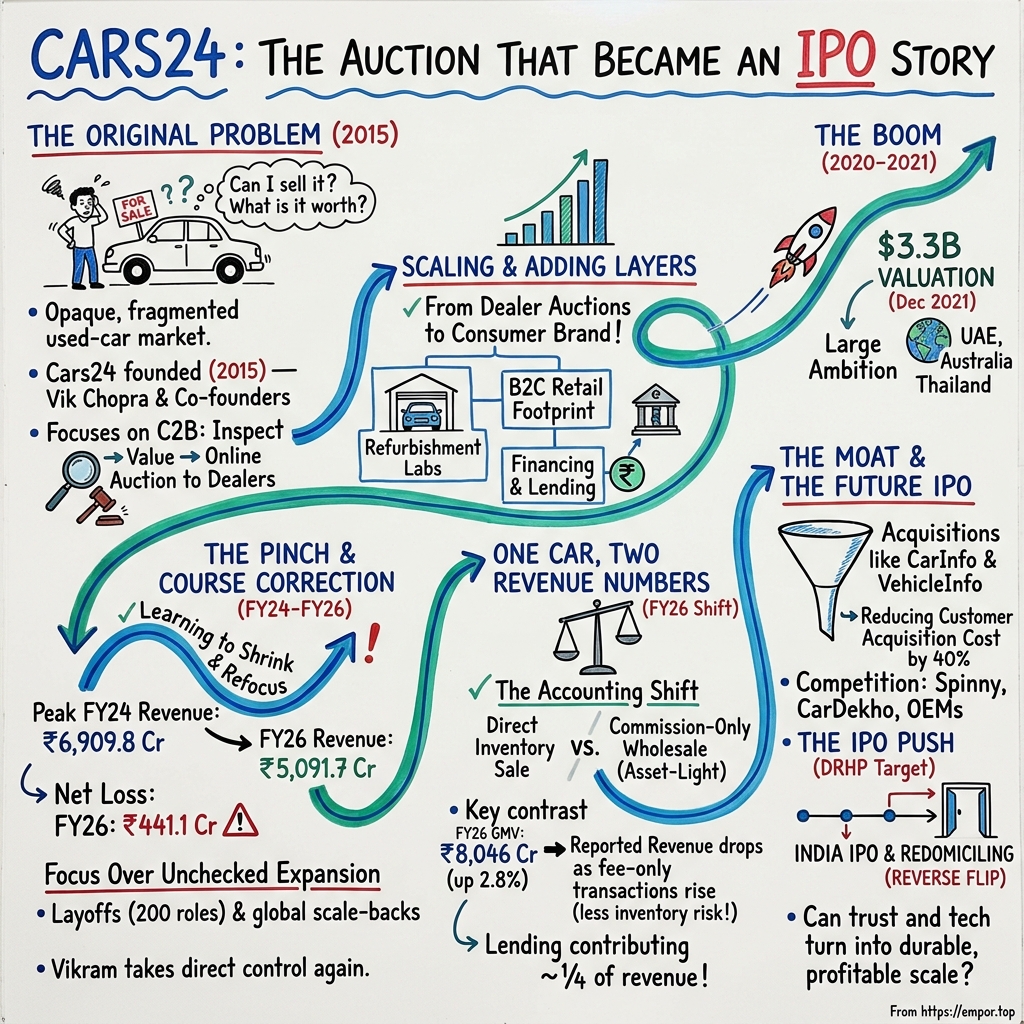
Cars24: The Auction That Became an IPO Story
I. The car no one could sell
Picture a man standing beside a hatchback in a Gurugram parking lot with a phone in his hand. He has called three dealers. One offered a number that felt insulting, one promised to come by and never did, and the third wanted to haggle over a scratch on the rear bumper that the seller had never noticed. Somewhere across the city, a young couple is looking for exactly this kind of car. They have the opposite problem. They cannot tell whether the odometer has been wound back, whether the car has been in a flood, or whether the registration papers will survive a visit to the transport office. Each side holds half the information the other needs, and neither trusts the other with it.
That imbalance sits at the centre of India's used-car market, and it is the problem Cars24 was built to solve. Strip away the refurbishment labs, the lending arm, the AI tools and the IPO plans, and the company still rests on one idea: a stranger will pay more for a car, and pay faster, if someone credible has inspected it, priced it and taken responsibility for the paperwork.
Cars24 was founded in Gurugram in 2015 by four men: Vikram Chopra, Mehul Agrawal, Gajendra Jangid and Ruchit Agarwal.1 Chopra became chief executive. Agrawal took operations. Jangid ran marketing. Agarwal, a chartered accountant who had worked at Infosys and spent four years as a vice-president at BofA Securities after a Cornell MBA, met the other three after returning to India in 2014 and became the finance chief.2 Chopra and Agrawal had been here before. They had co-founded FabFurnish, an online furniture business.3 It never became the large company its founders hoped for, but it taught an expensive lesson about e-commerce. Selling goods online is mostly a problem of finding enough supply at the right price, and the company that controls supply has a structural edge over the one that only rents traffic.
The four founders turned that lesson around. They did not start by building a showroom for buyers. They started with sellers. Cars24 would give a car owner an estimated price online, inspect the car at a branch or at home, and then sell it to dealers through an online auction, earning a commission when the car sold.2 Chopra later described the core engine as "fair price discovery of a used car through a dealer side auction engine."4 The seller got a quick, firm price and someone else to handle the transfer. The dealer got a steady flow of inspected stock without driving around the city to find it. Cars24 got the fee and, with every car, more data on what a 2014 Swift with 70,000 kilometres was actually worth in Pune in February.
It was a clever wager because it attacked the scarce side first. In used cars, buyers are plentiful and good cars are not. Organise the supply and the buyers will follow.
Eleven years later, that wager has become one of India's best-known consumer brands, a multi-country group and an IPO candidate. It has also become a far more complicated business than a dealer auction. Cars24 now buys cars outright, refurbishes them, sells them to retail customers, lends them the money to buy them and offers warranties and services around them. Each layer was meant to deepen the relationship with the customer. Each also added labour, inventory and capital to a business that began by charging a fee.
That complexity shows up in the numbers. The India group's revenue from operations peaked at about ₹6,910 crore in FY24, then fell to about ₹6,233 crore in FY25 and about ₹5,092 crore in FY26, which ended in March 2026.1 That is a fall of more than a quarter in two years. Net losses were about ₹498 crore, ₹543 crore and ₹441 crore over the same three years.1 The latest year was the best of the three on the bottom line, and the worst on the top line.
Then comes the number that makes the story worth telling. In the same year that statutory revenue fell 18%, Cars24 said the gross value of the cars transacted on its India platform rose almost 3%, to about ₹8,046 crore, and that its adjusted net revenue rose 27%.1 The company's explanation is that it changed how part of the business works. In the middle of FY26, it moved a chunk of its wholesale trade from buying and reselling cars, where the full price of each car counts as revenue, to arranging the deal for a commission, where only the fee does.1
That explanation may be largely right. It may also be a convenient way to describe a business whose core car sales are shrinking. The core segment that sells cars through auctions and retail still made up about 87% of India operating revenue, and it fell almost 23% in FY26 after an 11% fall the year before.5
So the questions this story has to answer are practical ones. Is the falling revenue mostly accounting presentation, or a weakening core? Can better economics coexist with renewed growth, or has Cars24 bought its narrower loss by shrinking? And in a market where Spinny, CarDekho, local dealers and carmakers' own used-car networks all compete for the same seller and buyer, does Cars24 have an edge that lasts? The company is preparing to ask public investors to answer those questions with their money. The auction solved the seller's problem. Whether it can be made to pay at scale is still being decided.
 Subscribe on LinkedIn
II. Cars24 made the auction the product
The early Cars24 branch was a modest thing: a covered bay, a few inspectors with checklists, a desk for paperwork and a screen. A seller would drive in, an inspector would walk around the car, pop the bonnet, check the chassis number against the registration certificate, test the electricals and photograph the scratches. Within the hour, the car's report would go live to a network of dealers who bid for it online. If the price cleared, the seller could leave with a commitment and Cars24 would handle the transfer of ownership, the part of a private sale that can drag on for weeks if a buyer forgets to re-register the car in his own name.
The inspection and auction loop put that idea into practice. The dealers did not need much persuasion. Chopra later said the company's dealer onboarding was "so organic, that it's not even funny."4 For a dealer, a pre-inspected car arriving on a phone screen was simply a cheaper way to buy inventory.
It is worth being precise about what kind of business this was, because the distinction matters for everything that follows. A classifieds site such as an online listings portal makes money by selling leads: it shows a car to buyers and charges dealers or sellers for visibility, but it does not touch the car. Cars24's auction was a step beyond that. It took physical custody of the transaction for a short time, set the price through bidding and took a commission on the sale. That is more work than a listing, but it is still a fee business. It does not require the company to own cars.
Over the next six years, Cars24 kept moving down the chain. It started buying cars itself, so that it could sell them not only to dealers but directly to retail customers. Owning a car means owning its risk. If a car sits on the lot for three months, its value falls. If the inspection missed a problem, the company eats the repair. So Cars24 built refurbishment centres, which it called "Mega Refurbishment Labs", to recondition cars to a standard it could sell with confidence. By December 2021, it had seven of these in India and had opened its first abroad, in Dubai.6 It also built retail hubs where buyers could see and test cars, and a logistics network to move vehicles between them.
Each step was a rational answer to a real problem. Buyers of used cars care far more about the car's condition than about the platform's interface, and the only way to promise condition is to control the car. Owning inventory also lets a company set the retail price instead of taking a slice of someone else's. But each step turned a fee business into something closer to a retailer, with its fixed costs, inventory exposure and need for working capital.
The next layer was money. Most Indian car buyers borrow, and a buyer who can arrange a loan at the point of sale is much more likely to complete the purchase. Cars24 set up a lending business in 2019; when it raised its Series D that October, it said part of the money would go into its newly launched consumer-lending arm.7 By late 2021, the company said more than half of its customers financed their purchases through Cars24.6
Lending is a second way to earn from the same car, and it is attractive because interest income recurs month after month while a car sale happens once. It also brings underwriting, collections and credit losses into a business that had started as a matchmaker. Cars24 Financial Services, the lending arm, now funds itself partly by packaging loans into pools and selling notes backed by them, which brings a set of ratings and asset-quality measures that a car marketplace never had to worry about.8
By the time Cars24 announced its December 2021 funding, it described itself in heroic numbers. It said it had sold more than 400,000 vehicles, attracted about 13 million monthly visitors to its website and was operating in roughly 200 Indian cities.6 Those are historical company claims made at the peak of a funding cycle, not current operating measures, and they cannot be compared with today's figures on a like-for-like basis. They do show how far the business had travelled from a single inspection bay.
The ambition had always been large. When Cars24 raised its $100 million Series D in October 2019, it said it handled about 150,000 transactions a year and set a target of one million a year by the end of 2021, with a presence in 75 Indian cities by the end of 2019.7 Around the same time, Business Insider reported that Cars24 expected to break even by December 2019.[^9] Neither happened.
In the first half of FY26, Cars24 said it completed about 85,000 car transactions across India, the UAE and Australia combined, and it was on track for more than 180,000 in the full year.9 More than four years after the target date, annual transactions across three countries were less than a fifth of the million once promised for India by 2021, and the company was still loss-making. Missed targets are common for young companies, and the market changed sharply in between. But the record matters for how a public investor should read the targets Cars24 is setting now.
Here is the first unanswered tension. Every service Cars24 added made the customer relationship deeper: the seller gets a price, the buyer gets an inspected car, the borrower gets a loan, and the company touches every step. The question is whether each layer earns more than it costs. An auction commission requires few assets. A refurbished car on a retail lot requires many. The pandemic boom was about to give Cars24 the money to build all of it at once, before anyone could know the answer.
III. The boom made the model look exportable
In the autumn of 2021, the used-car business looked like one of the best trades in global consumer technology. Semiconductor shortages had throttled new-car production around the world, waiting lists at dealerships stretched for months, and families who had avoided public transport during the pandemic wanted a car of their own. Used-car prices rose. In the United States, online car retailers were valued like technology companies. In India, venture investors were looking for the local version, and Cars24 was the largest candidate.
The money came fast. In November 2020, a $200 million Series E led by DST Global took Cars24 to a valuation of about $1 billion.10 In September 2021, it announced a $450 million round, of which $340 million was Series F equity and $110 million debt, at a valuation of about $1.84 billion.6 Three months later, on 19 December 2021, it announced another $400 million: $300 million of Series G equity led by Alpha Wave Global, formerly Falcon Edge, and $100 million of debt. The valuation was $3.3 billion.6 The investor list included DST Global, SoftBank Vision Fund 2, Alibaba, Tencent and Exor Seeds.6 In about a year, Cars24 had raised roughly $840 million in equity and its valuation had more than tripled.6 In total, it has raised more than $1.3 billion from investors including SoftBank, Alpha Wave Global and Peak XV.1
That $3.3 billion figure is still the last widely reported priced valuation of the company. It is worth looking at it the way a public investor would, as a price observed in one market on one day, not as a measure of what the business is worth.
Three features of the round make it a weak anchor. The first is timing. December 2021 was the peak of a global boom in growth-company valuations; within months, interest rates rose, and the listed online car retailers that served as reference points lost most of their market value. The second is size. A $300 million equity cheque bought roughly 9% of a company priced at $3.3 billion, so the round set a price for a small slice and extrapolated it to the whole. The third is the security.
Late-stage venture investors almost always buy preference shares, which typically carry rights to get their money back ahead of ordinary shareholders if the company is sold below expectations. Global Car Group, the Singapore parent, has not published the terms of its share classes, so the precise protections attached to the Series G are not public. But a share with downside protection is worth more than an ordinary share in the same company, which means the headline valuation overstates what the same business would fetch as common equity. A public investor in an IPO buys ordinary shares.
Since then, the record has been quiet. Multiples records a $30 million strategic investment in July 2024 and retains the $3.3 billion valuation from December 2021;10 that later transaction was not a fresh priced round and does not refresh the mark. The company's CFO, Shivanshu Makkar, said in 2026 that Cars24 had not raised an external funding round since 2022.11 Nearly five years have passed without a new external price, which can mean the company did not need one, or that it did not want to set one below the last.
What did the money build? The first answer was geography. Cars24 launched in the UAE in July 2021 and in Australia and Thailand in October 2021, with Southeast Asia named as the next frontier.6 The second was capacity at home: refurbishment labs, retail hubs and the lending book. The third was claims. In 2021, Cars24 said it had a 90% share of India's used-car market.6 That figure needs careful handling. A year earlier, describing its Series E, the company had framed its position as more than 90% of online used-car transactions and about 5–6% of the total pre-owned market.10
The two definitions describe very different businesses. The 90% figure applied to a narrow slice of a market dominated by local dealers and private sales; it was never a measure of Cars24's share of all used cars sold in India. Even in early 2026, Makkar described Cars24 as "already the largest player in India" while setting a target of about 10% market share within three to four years.9 A company that already held 90% of its market would not need to aim for 10%.
The market itself is large and still disorganised, which is the bull case's foundation. Redseer estimates that India's used-car market could reach about $70 billion by FY31, with nine to ten million cars sold a year, and that about 80% of transactions are still unorganised.12 Makkar has said the industry is growing at 10–12% a year and that Cars24 aims to grow at nearly twice that pace.9 Those numbers describe the broad category. The market Cars24 can actually reach with its current model is narrower: cars good enough to refurbish and resell with a warranty, in the cities where it has retail hubs, to buyers who will pay for that assurance rather than buy from a neighbour. That reachable market is still large, but it is a fraction of the headline.
The expansion abroad tested whether the playbook could travel. The record is mixed. Global Car Group still counts subsidiaries in Thailand among its twelve,1 but when Makkar described the business in September 2026, he spoke of operations across India, the UAE and Australia; Thailand, one of the three 2021 launches, had dropped out of the story management tells.11 The UAE appears to have worked best. Makkar said Cars24 had about 7% of the UAE used-car market and was growing at nearly 30% there, and that it had expanded to three cities in Australia.13 These markets are part of Global Car Group, not the India company, and their results sit outside the India numbers that dominate this story.
The boom gave Cars24 a bigger footprint, a bigger organisation and a famous valuation. It did not prove that the expanded model earned a return on the money. That test came later, and it arrived as a restructuring.
IV. The bigger company had to learn to shrink
In late April 2025, Cars24 employees in product and technology learned that their roles no longer existed. About 200 people were laid off.5 The timing was awkward: the cuts came days after Cars24 announced that it had bought Team-BHP, one of India's best-known car-enthusiast forums.[^15] Chopra explained the decision in unusually direct terms. Some projects and roles, he said, had been added prematurely.5
That admission is the most useful single piece of evidence about how Cars24's management thinks, and it cuts both ways. It was candid. Many founders blame macroeconomics or the market. Chopra blamed the company's own sequencing, which suggests a leader willing to name his mistakes. But it was also a confession that the organisation built on the 2021 capital had got ahead of the business that was supposed to pay for it.
The numbers show why the reset was needed. India revenue grew about 25% in FY24 to its peak of roughly ₹6,910 crore, then fell for two years in a row, to about ₹5,092 crore in FY26.1 Over the same period, the net loss widened slightly, then narrowed: roughly ₹498 crore, ₹543 crore and ₹441 crore.1 Put simply, Cars24 lost about ₹9 for every ₹100 of revenue in FY26, versus about ₹7 in FY24, so the narrower loss came with a shrinking business, not a more profitable one on that measure.
These are India figures, and the boundary matters. The India operating company, CARS24 Services Private Limited, is wholly owned by Global Car Group Limited, a Singapore holding company that also owns the UAE and Australian businesses.14 Global Car Group reported FY26 operating revenue of $810.4 million, about ₹7,658 crore, down 13.3% from $934 million, and a net loss of $56.3 million, about ₹532 crore.1 The India company is the largest part of the group, but it is not the whole of it, and the entity that eventually lists will be the group, reorganised in India. Investors will be buying the whole perimeter.
The leadership changes that followed the layoffs were more significant than the layoffs themselves. In March 2026, Himanshu Ratnoo, the chief executive of the India used-car business, stepped down, and Chopra took direct oversight of it.5 On 29 April 2026, Gajendra Jangid, the co-founder and marketing chief, moved from his executive role to an advisory one.15 The next day, Mehul Agrawal, co-founder and chief operating officer, stepped back from his operating role after 11 years, while staying on the board.3 In about six weeks, the company lost the head of its largest business and two of its four founders from day-to-day management, months before a planned IPO.
Agrawal's farewell post was upbeat. He wrote that Cars24 had "just closed our first globally profitable quarter," described the company as a $3 billion business across three geographies, and said it had "a genuine shot at building something worth $100 Bn."3 The profitable quarter he described was profitable on an adjusted basis, a distinction this story returns to below. The exits themselves are not proof of trouble; founders move on before IPOs for many reasons, and the company has not disclosed any reason beyond personal choice. But they concentrate operational responsibility in Chopra at the moment when the India core is shrinking, which makes his record on that core the central management question.
That record has two parts. On the positive side, Chopra has been candid about mistakes, cut costs, cut roles and restructured how wholesale works, and the FY26 loss is smaller. On the negative side, the targets he and the company set in earlier years were missed by wide margins, the business he now runs directly has shrunk for two years, and the timeline for the IPO has moved more than once. The evidence supports the description of a course correction. It does not yet support a record of restored growth.
Ownership and incentives are harder to assess, because Cars24 is still private. The India company's shares are all held by Global Car Group and its nominees.16 The parent's investors include SoftBank, Alpha Wave Global and Peak XV, among others,10 but Global Car Group has not published a full schedule of who owns what, how much the founders hold or what preference rights the investors carry. Those disclosures will come only with an offer document.
What is visible is the cost of paying people in equity. India employee-benefit expense rose from about ₹524 crore in FY24 to ₹604 crore in FY25 and ₹806 crore in FY26, a 33% jump in the latest year even as revenue fell 18%.116 Much of that increase came from share-based pay. The India company's ESOP charge rose from ₹36.5 crore to ₹212.3 crore, which Makkar attributed to equity granted to the founders of acquired businesses: Team-BHP, VehicleInfo and CarInfo.1 At group level, the ESOP charge was reported at about ₹239 crore.5 The two figures cover different perimeters and should not be added together.
Share-based pay deserves attention because it is easy to treat as an accounting nuisance. It does not consume cash, so it is excluded from adjusted earnings. But it transfers ownership from existing shareholders to employees and sellers of acquired companies, and in Cars24's case it was equal to almost half of the India net loss in FY26. The India statements disclose key-management salaries in their related-party schedules but not individual chief-executive or CFO pay over several years, so the link between executive rewards and results cannot yet be judged.
The reset, in other words, has cut costs and narrowed the loss while the organisation shrank, the founders stepped back and the equity bill grew. Management's answer to the shrinking revenue is that it is not really shrinking at all, which leads to the most important accounting question in the story.
V. One car, two revenue numbers
Under the wholesale model introduced in FY26, Cars24 records only the commission when it matches a seller and dealer, rather than the full sale price it recorded when it bought and resold a car. The company says much of the decline in statutory revenue reflects that change, not a fall in the number of cars changing hands.1
Three numbers capture the argument. Gross merchandise value, the total value of cars transacted through the India platform, rose about 2.8% in FY26, to roughly ₹8,046 crore. Adjusted net revenue, the company's own measure of what it keeps from transactions, rose 27% to about ₹1,411 crore. Statutory revenue from operations, the number in the audited accounts, fell 18.3% to about ₹5,092 crore.1
The relationship between the first two is the most revealing. In FY25, adjusted net revenue was about ₹1,108 crore on GMV of about ₹7,827 crore, so Cars24 kept about ₹14 of every ₹100 of car value flowing through its platform.1 In FY26, it kept about ₹17.5. If that number is calculated consistently, it is genuinely good news: more of each transaction is staying with Cars24, through commissions, financing, warranties and services, without the platform having to hold more cars.
Now look at what the audited accounts show beneath the headline. Revenue from selling products, mostly cars, fell 22.7% to about ₹4,439 crore. Revenue from services more than doubled, from about ₹90 crore to about ₹206 crore. Other operating revenue, which includes financing income, rose 12.5% to about ₹447 crore.1 The service line is the commission business and similar fees, and its doubling is consistent with the wholesale shift. But it added only about ₹116 crore while product revenue fell by about ₹1,307 crore. Part of that gap is the full value of cars no longer recorded as revenue. Part of it may be fewer cars sold at retail. The accounts do not separate the two.
That is the missing piece. Cars24 has not published a reconciliation that shows, for the same set of years, how much GMV went through the inventory-led model and how much through the commission model, how much net revenue each produced, and what margin each earned. Without that bridge, GMV, adjusted net revenue and statutory revenue are three different measures pointing in different directions, and the reader is asked to trust that the most flattering one is the right one.
There are reasons for caution. GMV grew less than 3%, roughly in line with inflation and well below the 10–12% industry growth rate Makkar has cited.9 In the first half of FY26, the company said GMV was largely flat.9 So even on the company's preferred measure of activity, Cars24 grew more slowly than its market. And the core segment that sells cars through auctions and retail, which still made up about 87% of India revenue, fell for a second straight year.5 The accounting change explains why revenue fell faster than activity. It does not explain why activity barely grew.
Management's own messaging illustrates the problem. In May 2026, Moneycontrol reported Makkar's FY26 figures under a headline saying that Cars24 had narrowed its adjusted EBITDA loss to ₹200 crore and that revenue had grown 27%.17 The 27% referred to adjusted net revenue. Four months later, the audited filings showed statutory revenue down 18%. Both statements were accurate on their own terms. A public investor will need to know which definition the company is using every time it says "revenue."
The economic logic of the wholesale shift is sound. Some categories, such as old or damaged cars sold for scrap or to small dealers, earn thin margins when bought and resold, and they tie up cash and carry the risk of price falls. Converting them to a fee model reduces inventory exposure and capital needs. The cost is lower revenue per transaction and, potentially, less control over the quality of what is sold. That trade-off can be right, but it should show up in better contribution per car and better cash flow, not only in a better ratio of net revenue to GMV.
Lending is becoming a larger part of the mix. Makkar said lending contributed about a quarter of revenue in FY26 on his measure, up from about a fifth the year before, and that disbursals grew in the second half.17 In the first half of FY26, loans disbursed rose 38% to about ₹1,637 crore.9 Cars24 Financial Services' revenue rose to about ₹299 crore in FY26 from about ₹265 crore, and its profit after tax more than tripled, to about ₹21 crore.1 That makes lending financially relevant and, unusually for this company, profitable. It remains smaller than the car-transaction engine on which it depends for customers.
The loss is narrowing on the company's preferred measure, too. Adjusted EBITDA loss fell from about ₹475 crore in FY25 to about ₹200 crore in FY26, and management reported its first positive adjusted EBITDA quarter, about ₹20 crore, in the March quarter.11 Makkar attributed part of that improvement to AI, which he said cut inspection time from about an hour to about 15 minutes and contributed about 300 basis points of adjusted EBITDA improvement.17 He also attributed it to lending and to cheaper customer acquisition.
These are adjusted, management-reported measures. Adjusted EBITDA excludes share-based pay, depreciation, interest and other items; on the audited basis, the India group still lost about ₹441 crore. The gap between the two is largely the ₹212 crore ESOP charge, depreciation on refurbishment and retail assets, and financing costs, partly offset by about ₹128 crore of other income, mostly interest on deposits.1 The ESOP charge does not consume cash, but it is paid in the shares that public investors would own.
Cash is a separate test again. In FY25, the most recent year with full audited cash flows, the India group's pre-tax loss was about ₹541 crore, but its operating cash outflow was only about ₹92 crore.16 That looks like a business close to cash breakeven, but the reasons matter. About ₹450 crore of non-cash charges were added back, including about ₹147 crore of depreciation. Working capital released cash: lower inventory contributed about ₹150 crore and lower receivables about ₹54 crore.16 Shrinking inventory is a one-time source of cash; a business cannot keep releasing it forever. In FY24, by contrast, the operating outflow was about ₹447 crore.16 The FY25 improvement was real, but it came partly from shrinking, and it did not establish that the model generates cash.
In September 2026, Makkar said Cars24 was "not burning any cash right now."13 If true at group level and sustained, that would be the most important development in the story. The audited FY26 cash-flow statements will test it.
So the revenue puzzle has a partial answer. The shift to commission recognition explains a large part of the gap between activity and statutory revenue, and the company is keeping more of each transaction. But activity itself is barely growing, the core car-sales segment has declined for two years, and the profit improvement depends on adjusted measures that exclude a large and growing equity bill. The figure that would settle the debate is a three-year, like-for-like bridge from GMV to net revenue to statutory revenue, split between inventory-led and commission-led transactions, with contribution margin for each. Until Cars24 publishes it, the bull and bear cases can each claim the same numbers.
VI. A larger funnel is not yet a moat
A buyer in Bengaluru looking for a five-year-old Hyundai Creta in late 2026 has more choice than ever. Cars24's app shows her a refurbished car with an inspection report and a warranty. Spinny shows her a similar car with its own inspection and return policy. CarDekho shows her listings from dealers across the city. A Maruti Suzuki True Value outlet down the road sells certified cars backed by India's largest carmaker, and a Mahindra First Choice dealer offers another. A local dealer will sell her one for less if she is willing to take a chance. And a colleague may sell her one privately for less still.
That is the competitive reality Cars24 faces. Local dealers and private sales remain the default for most transactions.12 The organised players compete on trust, inspection, selection, financing and convenience. None of these advantages is unique.
The closest rival is Spinny. Like Cars24's retail business, Spinny buys cars from consumers, refurbishes them and sells them directly, and car sales account for nearly 98% of its revenue.12 Its trajectory has diverged from Cars24's. Spinny's revenue reached about ₹4,656 crore in FY25, nearly doubling in two years, and was estimated to have grown about 29% to roughly ₹6,000 crore in FY26; its FY25 net loss was about ₹424 crore.12 Entrackr reported that Spinny's FY26 revenue grew more than 28% and passed ₹6,000 crore, while Cars24's India revenue fell 18%.5 Spinny bought GoMechanic for about ₹450 crore in cash and stock and confidentially pre-filed IPO papers to raise about ₹2,500–3,000 crore.12 CarDekho's parent, Girnar, is also preparing an IPO of up to ₹3,500 crore.13
The topline comparison is imperfect. Spinny remains almost entirely inventory-led, so its revenue includes the full price of each car, while Cars24 has moved part of its business to commissions. A rupee of Spinny revenue is not equivalent to a rupee of Cars24 revenue. But the direction is hard to dismiss. Spinny's FY26 revenue grew, while Cars24's core car-sales revenue fell. Some of that is the accounting change. Some of it, on the evidence of Cars24's flat GMV, is market share moving to a competitor in the business both companies consider most important.
CarTrade, the closest listed comparison, is a different kind of business. It runs classifieds platforms such as CarWale and BikeWale and an auction business, earning mostly fees rather than vehicle sale prices. In FY26, it reported revenue of about ₹779 crore, up about 22%, and net profit of about ₹244 crore.18 It is smaller, asset-light and profitable, and it is useful as a reminder of what a fee-based car platform can earn, not as a direct comparison for a business that refurbishes and sells cars.
The carmakers bring a different threat. Maruti Suzuki True Value and Mahindra First Choice sit inside dealer networks that already see a large share of used cars through trade-ins when customers buy new ones. Spinny launched a product to help new-car dealers manage their exchange vehicles,12 which shows how valuable that supply source has become. Cars24 has to buy many of its cars from individual sellers, which costs more to acquire.
Does Cars24 have something rivals cannot copy? The company's case rests on network effects and data. More inspections and transactions should produce better price estimates, which should attract more sellers and buyers, which should produce more data. There is some truth in that. A pricing model trained on millions of inspections is an asset, and the transaction history makes it harder for a new entrant to price cars as accurately.
But the structure of the market limits how much that edge is worth. Used cars are infrequent purchases: a family buys one every five to seven years. That means low customer frequency and little opportunity for habit or switching costs to form. A buyer who used Cars24 in 2021 has no particular reason to return in 2027 instead of checking Spinny or a local dealer. Cars24 has not disclosed repeat-purchase rates, customer retention or the share of sales coming from returning customers. Without that evidence, the network effect remains a plausible mechanism, not a demonstrated one.
On the supply side, sellers are fragmented, which means no single seller can dictate terms. That reduces dependence on any one supplier, but it does not give Cars24 bargaining power: a seller who gets a low quote can walk to Spinny, a dealer or a carmaker's exchange desk. The largest procurement line in FY25 was purchases of used cars, about ₹5,384 crore,16 and Cars24 has to compete for every one. The India statements do not identify any customer accounting for 10% or more of revenue.16
The concentration that matters is not in any customer but in the business model itself: almost all revenue depends on used-car transactions, whose volume depends on supply, affordability, credit and consumer confidence. When India cut GST on new cars, Makkar called it "short-term pain" because Cars24 was holding inventory bought at higher prices.9 That is what inventory risk looks like in practice.
Viewed through Michael Porter's five forces, the picture is crowded. Rivalry among organised players is intense and rising as several head to public markets. Substitutes in the form of local dealers and private sales are everywhere. Buyers and sellers both have options. Barriers to entry are moderate: building a refurbishment network takes capital, but Spinny and the carmakers have already done it. Hamilton Helmer's seven powers offer a few possible sources of advantage: scale economies in refurbishment and logistics, a brand that signals trust, and process power in inspection and pricing. The evidence that any of them is producing durable advantage, such as superior margins per car, lower acquisition cost per buyer than rivals or higher price realisation for the same car, has not been published.
The most interesting current claim is about process. Cars24 says AI-assisted inspections cut inspection time from about 60 minutes to about 15 and contributed about 300 basis points of adjusted EBITDA improvement in FY26.17 The company says it uses AI to audit retail hubs and to handle more than 1.5 million minutes of calls a month across seven languages, and that it committed about $20 million to an initiative called Cars24 Labs to build AI-first products.111
If those claims hold, they matter: inspection is the core cost of the seller-side business, and a four-fold reduction in inspector time changes the economics of each car. But inspection technology is not proprietary to any one company. Spinny, CarDekho and carmakers can buy or build similar tools. A cost advantage from AI will last only if Cars24 compounds it faster than rivals copy it, and the evidence for that is a management claim, not a disclosed per-car cost comparison.
Cars24 has a credible operating proposition. It does inspection, inventory, transactions and financing under one roof, and few competitors can match that range. What it has not shown is that the range produces pricing power, loyalty or a cost position that rivals cannot match. That is why the next question matters: if the moat is not yet proven, has Cars24 at least bought a wider funnel at a price the economics can repay?
VII. Buying the funnel before the IPO
Cars24 says more than 12 million people open CarInfo each month, an app that lets car owners check their vehicle's registration details, insurance status, traffic fines and service history.19 In January 2026, Cars24 bought it.19 The logic was obvious. Those 12 million people own cars. Some of them will sell one soon, and some will buy one. If Cars24 can reach them at the moment they check their insurance or pay a fine, it can acquire sellers and buyers more cheaply than by buying ads.
CarInfo was part of a burst of acquisitions. In April 2025, Cars24 bought Team-BHP, the enthusiast forum.[^15] In January 2026, it bought CarInfo and its sister app BikeInfo, which continue to run as standalone apps with their existing teams.19 In March 2026, it bought VehicleInfo.10 And on 3 November 2026, Cars24 and Alba Cars, a Dubai premium used-car retailer that sells about 300 vehicles a month, announced that Alba's operating businesses had become part of the Cars24 group; together, the two businesses retail more than 1,000 vehicles a month in the UAE.20 Alba kept its brand and leadership. No price was disclosed.
The prices of the Indian deals are not consistent across public sources, which is itself a sign of how little Cars24 has disclosed. For CarInfo, MediaNama reported consideration of about ₹118 crore, citing a regulatory filing; Cars24 did not officially disclose the deal value.19 Multiples records the CarInfo deal at $47 million and VehicleInfo at $5 million.10 The difference may reflect the split between cash and stock or the timing of payments, but the company has not published a reconciliation. The founders of acquired businesses also received equity, Makkar said, contributing to the FY26 ESOP charge.1 Paying in shares conserves cash but dilutes existing shareholders, and it makes the true price of a deal harder to see.
The measurable outcome Cars24 points to is cheaper customer acquisition. Makkar said retail customer-acquisition cost fell by more than 40% year on year in FY26, partly because of traffic from acquired platforms.17 Advertising and promotion spending was roughly flat, at about ₹105 crore in FY26 versus about ₹106 crore the year before.1 If customer-acquisition cost really fell by 40% while marketing spending held steady, the number of retail customers acquired should have risen sharply, which is hard to reconcile with a fall in car-sales revenue. The likely answer is that the company's definition of acquisition cost differs from a simple ratio of marketing spending to sales, but Cars24 has not published the calculation.
That is the evidence limit. Without the revenue of the acquired companies, their user retention, integration costs and the rate at which their users convert into Cars24 sellers or buyers, there is no way to judge whether Cars24 paid a fair price or earned a return. Spinny's acquisition of GoMechanic, at about ₹450 crore for a business with about ₹145 crore of FY25 revenue, gives one rough benchmark for what an adjacent car-services asset can cost in this market,12 but a mechanic network and a vehicle-information app are not the same kind of asset. Purchase multiples cannot be compared with industry deals until Cars24 discloses more.
The acquisitions sit alongside a pattern of internal capital flows. In FY25, the India company issued about 923,000 new shares to its parent and received about ₹1,045 crore, after about ₹749 crore the year before.16 That was intra-group support from Global Car Group, which owns 100% of the India company, not a public-market raise. It does show that the India business has depended on its parent's capital to fund its losses and investments, and that the parent's own funding came from the venture rounds of 2020 and 2021.
The record of capital allocation is the counterweight to the acquisition thesis. Cars24's post-2021 expansion was followed by a retreat from Thailand, layoffs because projects had been added prematurely and two consecutive years of declining India revenue. That sequence does not prove the expansion caused the decline; the post-pandemic normalisation of used-car demand and rising competition both played a part. But it makes management's current claims about return on spending central to the IPO case, because public investors will be giving the same management team new money to spend.
What will that money be for? In September 2026, Makkar said the IPO was mainly about expansion and liquidity rather than an immediate need for cash. He said Cars24 had sufficient cash and did not need to burn it, and that the IPO would give liquidity to shareholders and employees and strengthen governance.13 Primary capital, he said, would fund a "war chest to go deeper into India."11 He then described what that might mean: "Maybe I go to 200 cities and about 50,000 cars," compared with retail operations in 25 cities today.13
That ambition deserves a careful reading. In 2019, Cars24 targeted 75 cities by year-end.7 In 2021, it said it was active in about 200 cities.6 In 2026, its retail business operates in 25. The earlier city counts may have included inspection branches and franchise points rather than retail hubs, so the figures are not directly comparable. But the pattern is a company that expanded its physical footprint quickly, then contracted it, and now proposes to expand it again with public money. Makkar's framing was tentative, a "maybe" rather than a commitment, and he said there was no valuation target for the IPO.13
There is also a difference in emphasis between his statements. In May 2026, his focus was on the narrowing adjusted EBITDA loss and the first profitable quarter on that measure.17 In September, it was on the reverse flip, the war chest and possible expansion. Both are consistent with a company that has stabilised and is now looking for growth. The question is whether the growth plan follows demonstrated economics or precedes them. The credibility test is simple. If Cars24 can show that its retail operations in the existing 25 cities earn a positive contribution per car after acquisition, refurbishment and logistics costs, and that newer cities reach that point within a defined period, a move toward 200 cities is a reasonable use of capital. If it cannot, the plan repeats the pattern of 2021.
VIII. The balance sheet behind the “growth engine”
A young couple in Jaipur find a six-year-old Maruti Baleno on the Cars24 app for about ₹5.5 lakh. They cannot pay cash. The app offers a loan, approved in minutes, with a monthly instalment they can manage. They buy the car. Behind that transaction sits a different business: a lender that has assessed their income and credit history, a loan that will be repaid over four or five years, and a collection process that will kick in if they miss a payment. For Cars24, the loan is both a sales tool and a second business. For a public investor, it is a reason to look at the balance sheet as well as the income statement.
The appeal of lending is easy to see. A financed sale is more likely to close, so lending raises conversion. The interest income is recurring, unlike the one-off car sale. And because Cars24 originates loans through its own platform, it has information about the car and the buyer that a bank would not. In FY26, Cars24 Financial Services earned about ₹21 crore of profit.1
But lending changes the risk profile of the group, so the entities need to be kept separate. Cars24 Financial Services Private Limited is the lending company. It funds part of its book by securitisation: it bundles car loans into pools and sells notes backed by their repayments. CARE Ratings rated two classes of notes from one such pool in June 2026 at CARE A+ (SO) and CARE BBB+ (SO).8 The "SO" stands for structured obligation. These ratings apply to the notes, which are protected by credit enhancement such as cash collateral and subordination. They are not ratings of Cars24 Financial Services as a company, let alone of the India operating group or Global Car Group.
CARE's rationale does give a useful look at the lending book. Cars24 Financial Services had assets under management of about ₹2,380 crore at the end of FY25 and earned about ₹6.8 crore of profit that year.8 Its gross non-performing assets, loans on which repayments were overdue by 90 days or more, rose to 3.99% in FY25, then improved to 0.98% by December 2025.8 Its capital adequacy ratio, a measure of how much equity backs its loans, was about 41% at FY25 and 44% at December 2025, high for a lender of its size.8 CARE noted that the lender sources its loans captively through Cars24 and depends on the collection performance of the underlying pools, and it flagged the earlier rise in bad loans as a constraint.8
The improvement in asset quality is encouraging. A fall in gross bad loans from about 4% to about 1% in nine months is large. But a fall that fast can reflect a growing book, where new loans have not yet had time to go bad, write-offs, or the sale of weak loans, as well as better underwriting. The test is how loans made in a given period perform over time, which lenders call vintage analysis, and Cars24 has not published it. Until audited FY26 and FY27 data show that the improvement has held through a full cycle of loan maturities, it should be treated as provisional.
The operating company's balance sheet carries risks of its own. At March 2025, the India group had borrowings of about ₹874 crore, of which about ₹414 crore were due within a year.16 During FY25, it borrowed about ₹961 crore and repaid about ₹1,276 crore, a large churn that shows how dependent the business is on continued access to lenders.16 The audited statements disclosed no covenant breach or refinancing warning.16 Leases on refurbishment and retail sites are recorded separately and should not be counted as borrowed money, though they are a real fixed commitment.
Receivables are small relative to revenue, as one would expect in a business where most customers pay before taking the car. Net trade receivables fell to about ₹90 crore at March 2025 from about ₹143 crore a year earlier.16 Of the March 2025 balance, about ₹26 crore was not yet due and about ₹63 crore was less than six months overdue; impairments rose to about ₹2.4 crore from about ₹0.4 crore.16 Most balances were recent, but the rise in impairments is worth watching, especially as the commission model grows and dealers rather than consumers become a larger share of counterparties. The India company's general trade terms run from 30 to 180 days.16
Interest on deposits remained a significant support to earnings.161 That income is real, but it comes from cash raised in the venture rounds, not from selling cars. It made the loss smaller without making the operating business profitable, and it will shrink as the cash is spent.
The group said it faced "various cases" and that management, after consulting legal advisers, believed it had a strong chance of success and had made no provision; the summary table listed no quantified contingent liabilities.16 The auditor gave an unqualified opinion.16 The absence of a quantified total is a limit of the company's disclosure, not evidence that the claims are immaterial. An offer document will have to list material litigation, and that list will be an important diligence item.
The related-party picture is modest. In FY25, the India company sold used cars worth about ₹17 crore, about 0.3% of revenue, to Cariot Auto, a related party, and paid a small support-service fee to the parent.16 The company says these transactions were on arm's-length terms. They are small relative to the business, but the cross-border structure, with a Singapore parent and Indian, UAE and Australian operating companies, means intra-group flows will need full disclosure when the group reorganises.
The watch list for the balance sheet is therefore specific. Investors should follow loan vintages and collection rates in the lending book, the ageing of trade receivables, operating cash flow at both India and group level, and the maturity profile of borrowings. Lending can be the growth engine Cars24 describes. It can also turn a marketplace into a credit business, whose losses tend to arrive all at once, in the downturn, when car sales are also falling.
IX. Analysis & Bear vs. Bull Case
Cars24 is preparing to go public with a valuation mark that is almost five years old and an India business that is a quarter smaller, on its statutory revenue line, than it was at its peak. The last priced round valued the company at $3.3 billion in December 2021.10 In FY26, the India group reported revenue of about ₹5,092 crore, a net loss of about ₹441 crore, GMV of about ₹8,046 crore and adjusted net revenue of about ₹1,411 crore.1 The group as a whole reported revenue of about $810 million and a net loss of about $56 million.1 The question for a public investor is whether Cars24 is a scaled transaction platform approaching profitable growth, or an inventory-heavy retailer still trying to prove its economics.
The bull case has a real mechanism. India's used-car market is large, fragmented and still mostly unorganised, and Redseer expects it to grow strongly through the end of the decade.12 The friction points that Cars24 was built to solve, price discovery, inspection, paperwork and financing, have not gone away. Cars24 already operates across most of the transaction and is the largest organised player by the company's account.9
Its shift to commissions in wholesale reduces inventory risk, its net revenue is growing faster than its GMV, its lending arm is profitable, and AI may be cutting the cost of the most labour-intensive step. If all of that holds, the FY26 figures look like the low point of a reset: a smaller but better business, now positive on adjusted EBITDA and, on the CFO's account, not burning cash. Add a successful reverse flip and fresh capital, and Cars24 could grow into the profitable, data-rich car platform its investors bought in 2021.
The bear case starts from the same numbers. The core car-sales segment fell for the second year in a row and still accounts for the large majority of India revenue.5 GMV grew less than 3%, below the industry's growth rate, while Spinny's revenue grew more than 28%.5 The revenue bridge between models has not been published. The profit improvement is on an adjusted basis that excludes a ₹212 crore equity bill that grew almost six-fold in a year.
The leaders of the largest business and two co-founders stepped back within weeks of each other. The acquisitions have not been shown to earn a return. And the company's history includes a missed breakeven target in 2019, a million-transaction target for 2021 that it never approached, an international expansion that management now describes in three countries rather than four and an IPO timeline that has slipped more than once.
The strategy's stress points are clear. If more of wholesale moves to commissions while GMV and customer acquisition slow, lower inventory risk may not make up for lower revenue per transaction, and the business could become smaller and more profitable per car without becoming large enough to justify its valuation. If lending grows faster than car sales, Cars24's results will increasingly depend on collections and credit losses, and the asset-quality improvement will face its real test in a downturn.
Valuation brings the problem into focus. The $3.3 billion mark is not a current equity value and not a public-market multiple. It was set for preference shares, at the top of a cycle, for a small slice of the company. At a rough exchange rate of about ₹94.5 to the dollar, the rate implied by the reported FY26 group figures, $3.3 billion is about ₹31,000 crore.1 Against the group's FY26 revenue of about ₹7,658 crore, that is about four times statutory revenue. Against India adjusted net revenue of about ₹1,411 crore, it is about 22 times, although that compares a group value with an India-only measure, which overstates the multiple. With statutory losses, price-to-earnings and EV-to-EBITDA multiples are not meaningful.
An enterprise value cannot be reliably calculated. The India group had about ₹874 crore of borrowings at March 2025 and cash and short-term investments whose FY26 breakdown has not been published,16 but there is no current group balance sheet, no current equity value and no disclosed amount of planned IPO proceeds. Nor can a fully diluted share count be built. Global Car Group has not published its share classes, its option pool, outstanding warrants or convertibles, or the shares owed to acquired-company founders. Any headline market value at listing will therefore be an equity value on an uncertain share count, and the free float, the shares actually available to trade, will be a fraction of it.
Peers help only with care. The closest operating peer is Spinny, which is unlisted, loss-making and has not set an IPO valuation. CarTrade is listed and profitable. At its mid-November 2026 share price, its market value was about ₹12,900 crore,21 which is about 16–17 times its FY26 revenue of about ₹779 crore and a little over 50 times its net profit of about ₹244 crore, all on an equity-value basis.18 But CarTrade is a classifieds and auction business with high margins and no inventory; applying its revenue multiple to Cars24's statutory revenue would be like valuing a supermarket at the multiple of a listings website.
A more defensible comparison is between CarTrade's revenue and Cars24's adjusted net revenue, which both represent the fees and margin a platform keeps. Even then, Cars24's net revenue includes the margin on cars it owns and refurbishes, with the capital needs that implies, while CarTrade's does not. The listed online car retailers in the United States, whose valuations collapsed after 2021 and then partly recovered, are aspirational comparisons, not direct ones, because their market, their credit markets and their scale differ.
An intrinsic view can be framed as scenarios rather than a target. Suppose the reset works and India adjusted net revenue grows from about ₹1,400 crore to about ₹3,000 crore over five years, roughly 16% a year, close to the twice-the-market growth Makkar has targeted.9 If the business then earns an EBITDA margin of 15–20% on net revenue, which would require keeping refurbishment and logistics costs under control as it expands, it would produce roughly ₹450–600 crore of EBITDA.
Apply a multiple of 15–20 times, plausible for a profitable, growing Indian consumer platform, and the India operating business would be worth somewhere around ₹7,000–12,000 crore before net debt and dilution. In a stronger case, net revenue reaches ₹4,500 crore with a 25% margin, and the value rises toward ₹17,000–23,000 crore. In a weaker case, net revenue stalls around today's level and the business hovers near breakeven, and the value falls to a few thousand crore. These are illustrations of the arithmetic, not forecasts. They exclude the UAE and Australian businesses, which would add value if they are profitable, and they do not account for the cost of capital needed to reach scale.
The exercise shows what the 2021 valuation embeds. To justify about ₹31,000 crore on India alone, Cars24 would need something close to the strong case: a tripling of net revenue, durable profitability at margins few inventory-led retailers have achieved, and a valuation multiple that assumes continued growth. That is possible, but it is a lot to assume about a business whose activity grew less than 3% last year. The IPO price, when it comes, may land above the intrinsic range for reasons that have nothing to do with value: few listed used-car platforms in India, a narrative of formalisation, a small free float and strong demand for consumer-technology listings. It may land below it if Spinny lists first and sets a lower benchmark, or if markets turn. Those are price forces, not business value.
Management credibility is the last piece. Makkar said in January 2026 that the IPO would be announced within 12–18 months.9 Chopra gave a six-to-twelve-month window the same month.13 By September, the DRHP itself was not expected before April 2027.13 The May interview headlined revenue growth of 27%; the September filings showed a statutory decline of 18%. Each statement was defensible. Taken together, they show a company that chooses its measures carefully. Adjusted EBITDA profitability and the contribution of AI should be treated as management-reported claims until reconciled with audited accounts.
Three measures will decide the next chapter. The first is like-for-like India net revenue, split between the inventory and commission models, which will show how net revenue tracks activity. The second is gross profit or contribution per vehicle after acquisition, refurbishment and logistics costs, which will show whether each car earns money. The third is operating cash flow, which will show whether the business funds itself. Two financial checks sit behind them: the ageing of trade receivables and the vintage performance of the lending book. And for capital allocation, investors should track how many CarInfo, Team-BHP and VehicleInfo users become Cars24 customers, and at what cost.
X. Playbook: Business & Investing Lessons
The first lesson is that in a market built on uncertainty, trust has to be an operating process. Cars24's early insight was that a seller would accept a lower price for certainty and a buyer would pay a higher price for assurance, and that the gap between those prices was the business. But the trust did not come from a logo or a marketing campaign. It came from the inspection and transaction process.
Cars24's effort to speed inspections was not just about cutting costs; it was trying to industrialise the thing that made the brand worth something. Founders building marketplaces in messy categories should notice that the moat, if there is one, lives in the process, and a process can be copied unless it keeps improving faster than rivals can imitate it.
The second lesson is that a bigger transaction is not always a better business. When Cars24 moved part of wholesale to commissions, revenue fell by billions of rupees and the business arguably got better. That is the paradox of the ₹3 lakh sedan that becomes ₹15,000 of revenue. The topline measures how much money passes through a company's hands, not how much it keeps. Investors who compare platforms on revenue are comparing different things, and founders who chase gross revenue for its headline value may be choosing the worse business. The number to watch is what the company keeps after paying for the car.
The third lesson is that expansion is an option only when the old city works. Cars24's post-2021 expansion and retreat show the risk. A new city should be a bet placed on the evidence of the last one, and a company that cannot show the unit economics of its existing footprint is asking investors to fund hope.
The fourth lesson is that an acquisition earns its price after the customer arrives. CarInfo's audience makes it a plausible source of future sellers and buyers. But users of a vehicle-information app are not customers of a used-car business until they sell or buy a car. Cars24 paid for those users partly in shares and says customer-acquisition costs fell, but it has not shown how many CarInfo users became Cars24 customers or what each one cost. A funnel is only as valuable as the share of people who come out of the bottom of it.
The fifth lesson is that a narrower loss is progress, but cash pays the bills. Cars24's narrower FY26 loss and the company's reported positive adjusted EBITDA in the final quarter were meaningful achievements after a painful reset. But audited accounts still showed a loss, and the last audited cash-flow year benefited partly from selling down inventory, which can happen only once. Adjusted profit is a measure of what a business could earn if some costs were not counted. Cash flow is a measure of whether it can survive without its investors. Cars24 says it is no longer burning cash. Its next audited accounts will show whether that is a new condition or a good quarter.
XI. Epilogue
Tonight, Cars24 is a company in the middle of a legal migration. Its parent, Global Car Group, is moving its domicile from Singapore to India, a process the CFO said had been approved in Singapore and would take six to nine months.13 Only when the group becomes an Indian company can it file a draft red herring prospectus with SEBI, and Makkar said in September 2026 that Cars24 expected to be eligible to do so by April 2027.13 After filing, SEBI review, pricing and book-building could take another three to four months.13 No Cars24 offer document appears among SEBI's public-issue filings.22 The company has not disclosed the size of the IPO, its price band, or the split between new shares and shares sold by existing investors.11 The earliest realistic listing is therefore the second half of 2027.
Several events will come before then, and each will answer part of the story.
The first is the reverse flip itself. When Global Car Group becomes an Indian company, its investors' share classes will have to convert into a structure that can be listed, and the terms on which that happens will show who owns Cars24 and on what rights. If the conversion gives preference holders more shares than their headline ownership suggests, existing ordinary shareholders and future public investors will own less. That is the first thing to read in the DRHP.
The second is the DRHP. It will contain three years of restated, audited consolidated accounts for the whole group, a subsidiary chart, intercompany eliminations, a list of material litigation, related-party transactions, executive pay, the share capital history and the intended use of proceeds. Many of the questions this story cannot answer, about the revenue bridge, the cap table, the acquisitions and the legal exposure, will be answered there or will be visibly avoided. If the use of proceeds is mostly retail expansion toward 200 cities, investors will need to see city-level economics for the existing 25 to judge whether the plan is grounded.
The third is the audited FY27 result for the India company, which should arrive around September 2027 if the usual filing calendar holds. If India revenue returns to growth on a comparable basis, with GMV and net revenue reconciled to statutory revenue, the reset will have worked. If revenue falls for a third year, the commission-model explanation will be harder to sustain.
The fourth is the lending book. If gross bad loans stay near the 1% reported in late 2025 as the loans written in FY26 mature, Cars24's financing arm will look like a real asset. If they drift back toward 4%, the growth engine will have become a source of risk.
The fifth is Spinny's IPO. If Spinny lists first, it will set the public-market benchmark for an inventory-led Indian used-car platform, and Cars24 will be priced against it. A strong reception would help Cars24's valuation; a weak one would force a harder conversation about the 2021 mark.
And then there is the acquired funnel. The test is conversion: how many users of CarInfo, Team-BHP and VehicleInfo become sellers and buyers, at what cost and with what margin.
Each of these events bears on the same question. Cars24 has narrowed its loss, kept more of each transaction and stabilised after a painful reset. It has not yet shown that it can grow again on a capital-efficient basis, or that the group investors will own matches the India story they have been told. The added services and technology could make the original auction business more defensible. They could also simply make it more complicated. The next twelve months will show which.
XII. Outro
Go back to the man in the Gurugram parking lot, phone in hand, trying to find out what his car is worth. Eleven years ago, Cars24 answered him with an inspection, an auction and a promise to deal with the paperwork. It worked. Sellers and buyers came, investors followed, and in December 2021 they put a price of $3.3 billion on the idea. Since then, the business has grown more complex, shrunk at home, lost founders from its operating ranks and found new ways to measure itself.
That price remains a historical marker. The current evidence is a smaller India business, a narrower loss and management's claim that the real business is growing underneath. Cars24 solved the seller's first problem, how to get a fair price. The problem it still has to solve is its own: how to make that transaction grow again without buying growth at any price. The public market, when it finally gets to set its own price, will not ask what the car was worth in 2021. It will ask what it is worth now.
References
-
Cars24's India Entity Trims FY26 Net Loss By 19% YoY To ₹441 Cr — Inc42, 2026-09-04 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
CFOs In Tech: Cars24's Ruchit Agarwal On A Startup's Financial Vision, The Principle Of Frugality And More — Inc42, 2021-05-06 ↩↩
-
Another Exit At IPO-Bound Cars24 As Cofounder Mehul Agarwal Steps Down — Inc42, 2026-04-30 ↩↩↩
-
Slingshot interview #3: Building a 3 way marketplace the Cars24 way with Vikram Chopra — Slingshot by Arkam Ventures, 2021-01-25 ↩↩
-
Cars24 India posts Rs 5,092 Cr revenue in FY26; revenue declines for second year — Entrackr, 2026-09-04 ↩↩↩↩↩↩↩↩↩
-
India's Cars24, a used-vehicle sales platform, raises $400M, now at a $3.3B valuation, to double down on growth — TechCrunch, 2021-12-19 ↩↩↩↩↩↩↩↩↩↩
-
CARS24 raises $100 million in Series D funding, targets presence in 75 cities by end-2019 — Autocar Professional, 2019-10-18 ↩↩↩
-
Cars24 Financial Services Private Limited securitisation rating rationale — CARE Ratings, 2026-06 ↩↩↩↩↩↩
-
IPO in 12-18 months; GST cut caused short-term pain but used-car disruption has begun: CARS24 CFO — Business Today, 2026-01-15 ↩↩↩↩↩↩↩↩↩↩
-
CARS24 revenue, valuation, funding and investors — Multiples ↩↩↩↩↩↩↩
-
Cars24 IPO plans advance as CFO Shivanshu Makkar targets April 2027 eligibility to file DRHP in India — Kotak Neo, 2026-09-28 ↩↩↩↩↩↩
-
Spinny's IPO Ride, But What's Under The Hood? — Inc42, 2026-09-27 ↩↩↩↩↩↩↩↩
-
Cars24 Eyes April 2027 Reverse Flip Ahead Of IPO Filing — Inc42, 2026-09-28 ↩↩↩↩↩↩↩↩↩↩↩
-
Global Car Group Limited and subsidiaries, FY25 annual return and audited financial statements — Cars24 ↩
-
Cars24 co-founder Gajendra Jangid steps back from executive role ahead of IPO — Moneycontrol, 2026-04-29 ↩
-
CARS24 Services Private Limited consolidated financial statements and auditor's report, FY25 — filed statements ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Cars24 narrows FY26 adjusted EBITDA loss to Rs 200 crore, revenue grows 27%: CFO Shivanshu Makkar — Moneycontrol, 2026-05-07 ↩↩↩↩↩↩
-
CarTrade Tech Q4 results: stock jumps 17%; check earnings summary — Business Today, 2026-05-07 ↩↩
-
CARS24 acquires CarInfo to expand into vehicle information services — Entrackr, 2026-01-05 ↩↩↩↩
-
Cars24 and Alba Cars join forces to accelerate growth in the UAE automotive market — Khaleej Times, 2026-11-03 ↩
-
CarTrade Tech Limited (CARTRADE.NS) stock quote — Financial Modeling Prep, 2026-11-16 ↩
-
Public issues filings — Securities and Exchange Board of India ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube