Carborundum Universal: The Grinding-Wheel Empire That Bet on Germany and Russia — and Is Now Cleaning Up After Itself
I. Introduction & Episode Setup
On 30 March 2026, in a board meeting held not in Chennai but in Cyprus, the directors of a holding company most Indian investors have never heard of voted to kill a 120-year-old German brand.
The company was CUMI AWUKO Abrasives GmbH. The holding company was CUMI International Limited, registered in Nicosia. And the decision — a voluntary winding-up under German law — closed the book on an acquisition that had been announced barely four years earlier as a landmark European expansion.1 Six weeks later, on 13 May 2026, a second board, this one in South Africa, concluded that a zirconia business CUMI had bought in 2008 was not in a position to continue operating and that there was no realistic alternative.1 Both decisions landed in the same set of accounts. Together they cost ₹135 crore before tax.2
That is not the whole story of Carborundum Universal Limited. But it is the part that changed most in the last twenty-four months, and it is the part that any honest account has to start with.
CUMI is a seventy-two-year-old Chennai company that makes things almost nobody outside industry thinks about: grinding wheels, cutting discs, refractory bricks that line the inside of furnaces, and the abrasive grains — fused alumina and silicon carbide — that go into all of it. It is the flagship materials business of the Murugappa Group, a Chennai conglomerate now in its second century. As of early September 2026, the market capitalised it at roughly ₹20,400 crore.3 Its products reach steel mills, foundries, auto plants, glass furnaces, shipyards and — increasingly, and this is the interesting part — semiconductor wafer-fabrication equipment makers.
Here is the tension that makes this a story rather than a filing summary. In the very same financial year that CUMI wound down one German subsidiary, wrote down a South African one, and absorbed the aftermath of a Russian subsidiary being placed on the United States sanctions list, it also formally launched "Aspiration 2030" — a strategic programme aimed squarely at semiconductors, defence ceramics, and clean-energy materials.1 A cleanup narrative and a growth narrative, delivered on the same earnings call, by the same person, in the same hour.
Which one is the company?
The honest answer, which this article will try to earn rather than assert, is that both are — but they belong to different geographies and different capabilities, and conflating them is the single most common error in how CUMI gets described. The Indian core is a genuinely strong, backward-integrated, cash-generative industrial franchise that grew standalone profit by nearly a third in a difficult year. The overseas portfolio is a nearly two-decade record of expensive lessons. The question for anyone holding the stock is whether those are two independent facts or two symptoms of the same underlying capability — and whether the new bets, which are technologically ambitious and largely pre-revenue, look more like the first story or the second.
There is a further complication. The market is not pricing CUMI as a company in the middle of a cleanup. It is pricing it at a trailing price-to-earnings multiple somewhere between the low eighties and the high nineties depending on which earnings base you use — against a return on equity that fell to under 7% in the most recent year, from a three-year average closer to 11%.34 That is an expensive multiple on depressed earnings, which is either a market correctly looking through one-off charges to a normalised earnings power, or a market that has not yet finished repricing. The sell-side consensus, for what it is worth, has drifted toward the cautious end.4
Here is the route. First, the origin — compressed, because a company founded in 1954 has a lot of history and only some of it bears on the present. Then the business as it exists today: three segments, wildly different economics, and a competitive structure that is much better understood than it is documented. Then the moat claim, tested against the place it demonstrably failed. Then the reckoning — the 2020s acquisition wave and what happened to it, which is the analytical heart of this piece. Then Aspiration 2030, sized to its actual economic weight rather than its narrative appeal. Then management and incentives. Then the numbers. Then the industry, the risks, and the arguments on both sides.
One framing note before we begin. CUMI describes itself, accurately, as a "mines to market" company with a net-debt-free balance sheet and an investment-grade credit rating. Every word of that is true. It is also true that a company can be conservatively financed and still deploy capital badly, and the two claims need to be tested separately rather than allowed to vouch for each other. Hold that thought.
 Subscribe on LinkedIn
II. Origins, Compressed: From Chettiar Banking to Industrial Materials (1900–1990s)
The Murugappa story does not begin in a factory. It begins in a counting house.
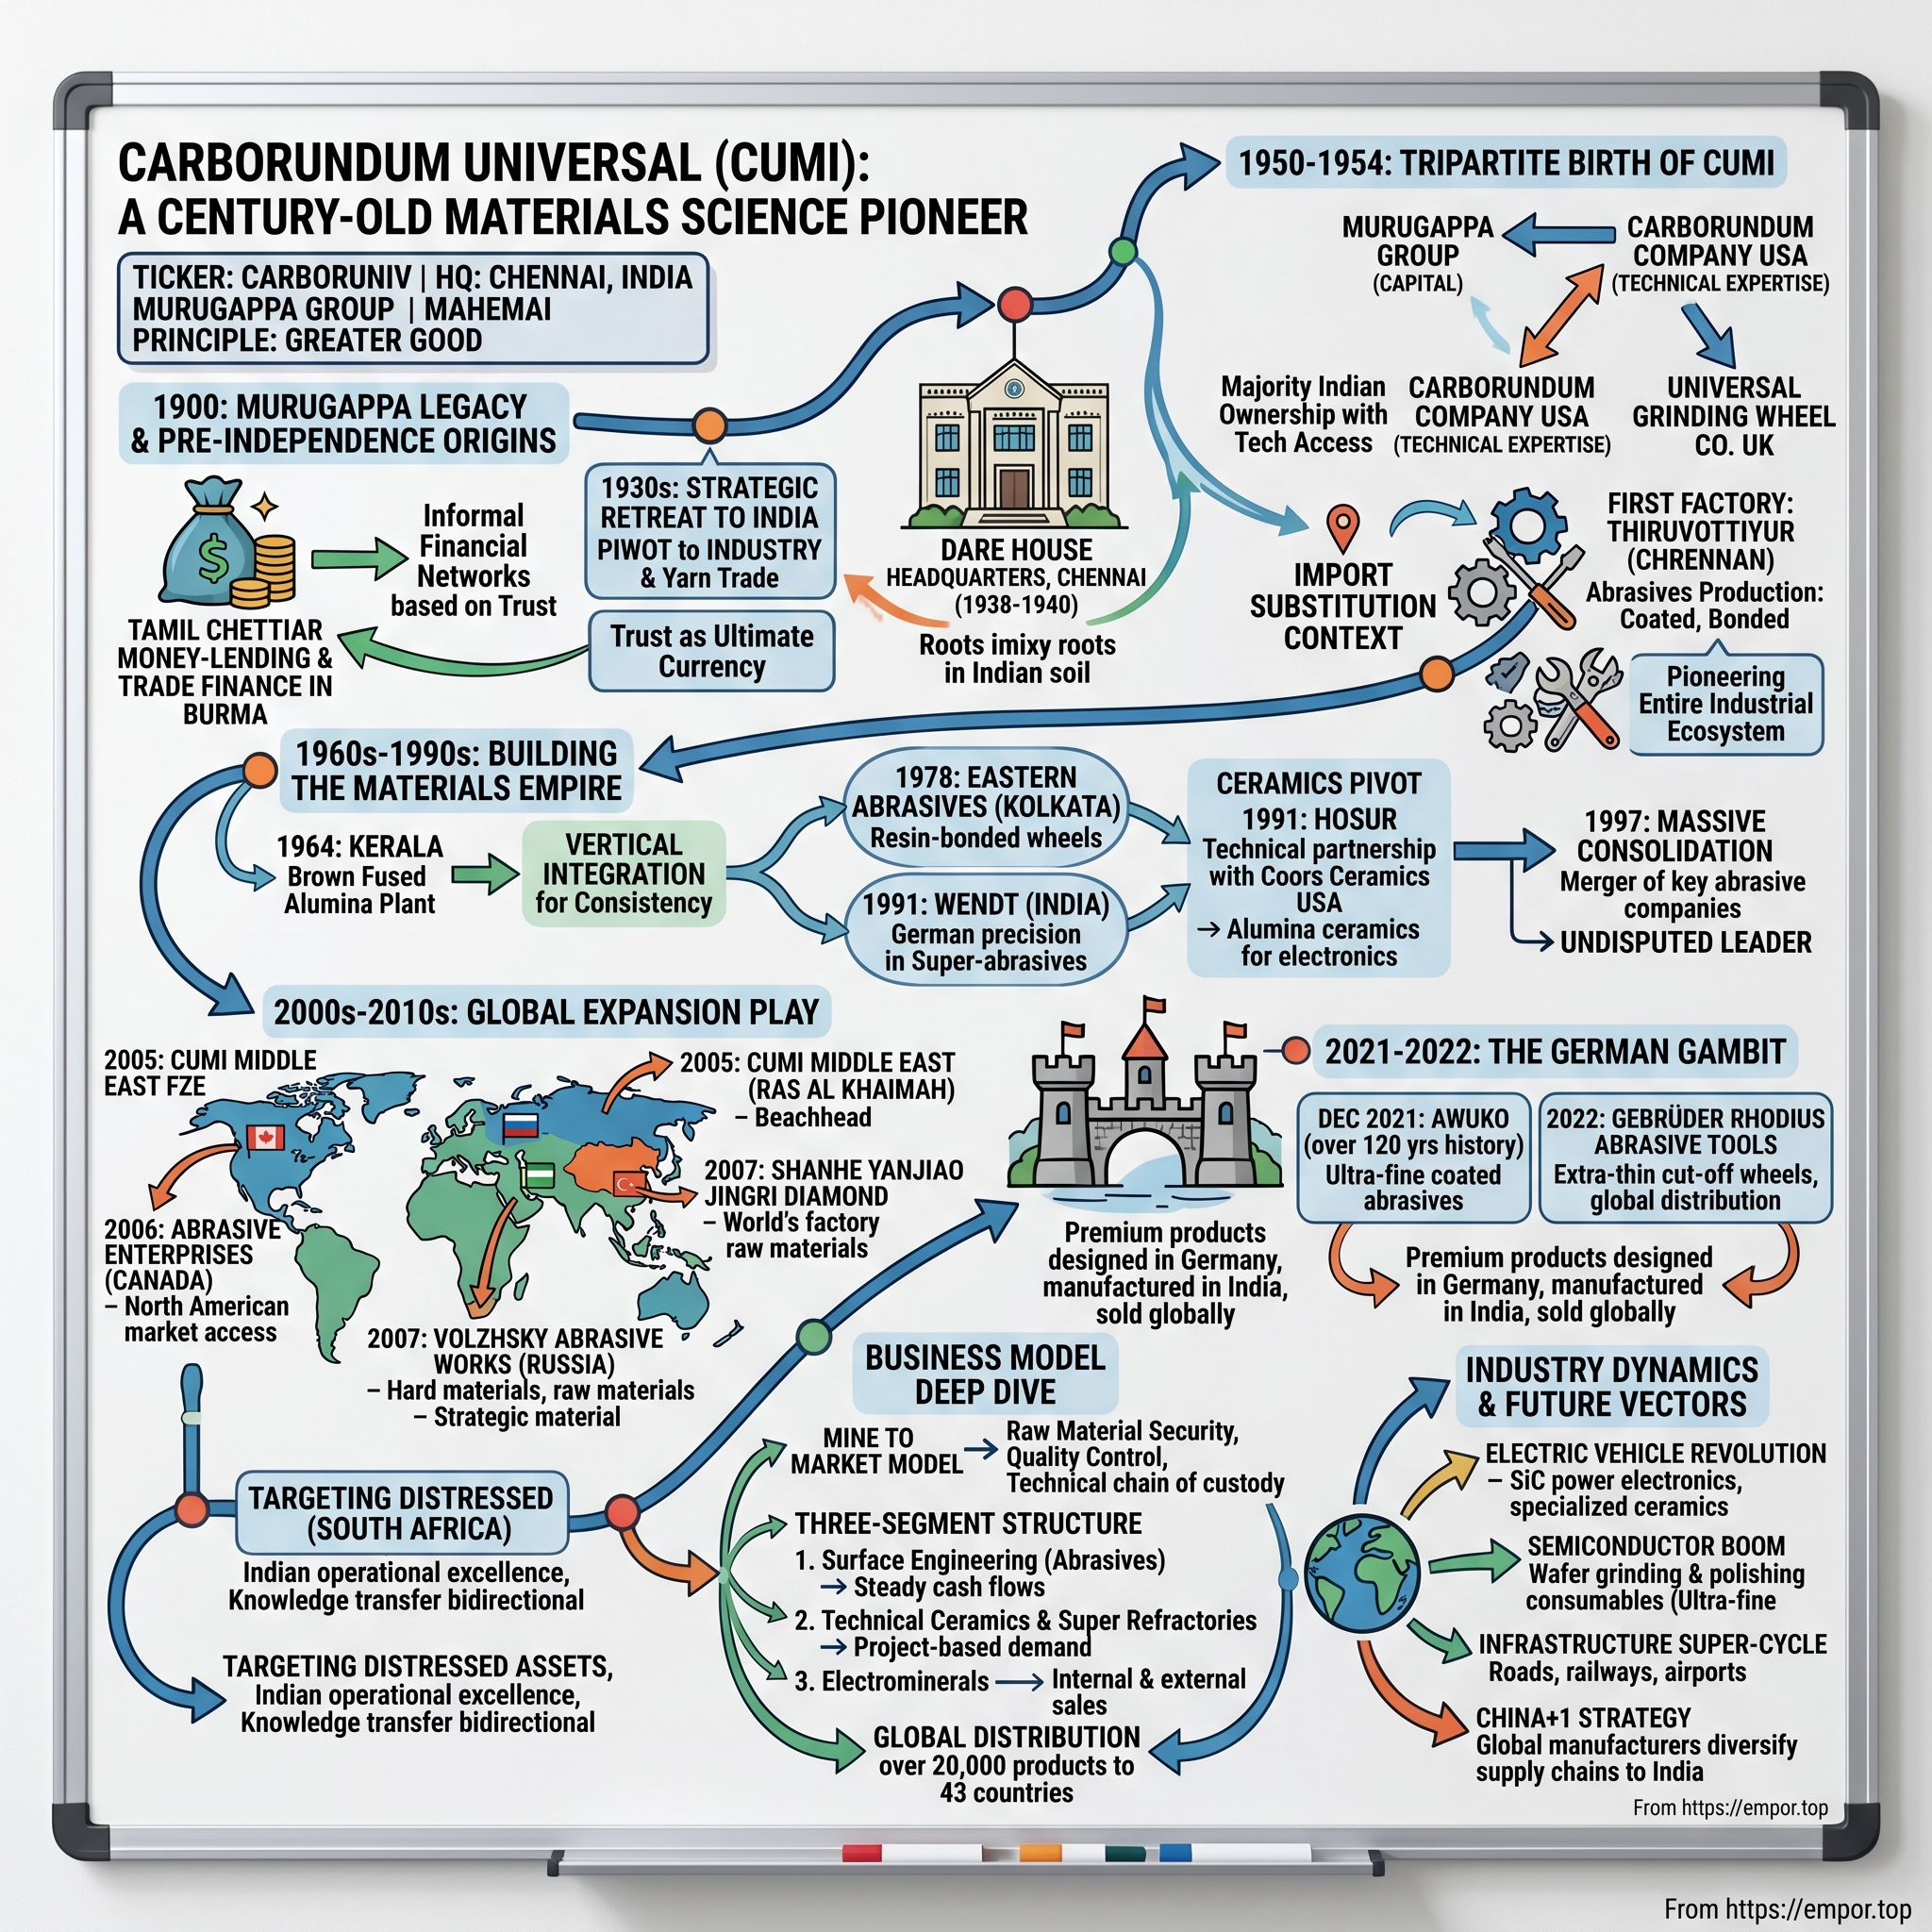
In 1900, A.M. Murugappa Chettiar established a money-lending and banking operation in Burma — part of the Nattukottai Chettiar commercial diaspora that ran credit networks across Burma, Malaya and Ceylon in the late colonial period. These were not casual traders. The Chettiar system was a sophisticated, family-underwritten financial network with its own accounting conventions, its own inter-firm credit discipline, and a reputation for standing behind obligations that functioned as collateral in itself. When the Second World War and the subsequent political upheavals in Southeast Asia made those positions untenable, the capital came home to Madras.
What arrived in India, then, was not just money. It was an institutional habit: long horizons, family control, reputational capital treated as a balance-sheet asset. Murugappa still markets itself on that inheritance — the group's "five lights" of integrity, passion, quality, respect and responsibility appear in every CUMI press release to this day.2 Investors should treat that as a genuine cultural fact and simultaneously refuse to let it stand in for evidence about capital allocation. Patient capital and well-deployed capital are different things, and the second half of this article is largely about the gap between them.
The industrial pivot came in the 1930s and accelerated after Independence. India in the early 1950s was a country that could not make its own grinding wheels. That sounds trivial until you think about what a grinding wheel does: it is the tool that finishes every other tool. Machine parts, bearings, engine components, cutting dies — nothing gets to final tolerance without abrasives. A country trying to build a machine-tool industry without a domestic abrasives industry is a country importing its own ability to manufacture.
So in 1954, CUMI was founded as a tripartite joint venture between The Carborundum Company of the United States, Universal Grinding Wheel of the United Kingdom, and the Murugappa Group of India.5 The name is a portmanteau of the two foreign partners. The structure was pure import-substitution logic: foreign technology, Indian ownership and market access, domestic production of a strategically necessary input.
What happened next is the part that actually matters to the modern thesis, and it took forty years.
Rather than remaining a wheel-maker buying grain from someone else, CUMI walked backwards down its own supply chain. In 1964 it commissioned a Brown Fused Alumina plant at Kalamassery, near Cochin — the abrasive grain itself, made by fusing bauxite in an electric arc furnace at temperatures above 2,000°C.5 The following year it began mining bauxite at Bhatia in Gujarat and built a calcination plant at Okha.5 In 1984 it commissioned a silicon carbide plant at Koratty in Kerala, followed by a micro-grit plant in 1988.5 White Fused Alumina came at Edappally in 1992. A mini-hydel power station at Maniyar in 1994 addressed the least glamorous and most decisive input of all: electricity, because fusing minerals is an enormously power-hungry business and power cost is the difference between a profitable furnace and a stranded asset.5
Read that sequence again and notice what it is. Bauxite mine → calcination → electric furnace → grain → micro-grit → wheel. CUMI did not buy a supply chain; it built one, node by node, over three decades. By the 1990s it was, in its own description, the largest producer of fused alumina in India and among the largest global producers of silicon carbide grains.1
Alongside integration came technology partnerships. Wendt, a German precision-abrasives specialist, and a ceramics tie-up with Coors of the United States in the early 1990s seeded what became the Industrial Ceramics business — the highest-margin part of CUMI today, and the part carrying almost all of the forward optionality. Those partnerships have not been static: in a notable structural change, the German joint-venture partner sold its entire 37.5% holding in Wendt (India) on the floor of the stock exchanges, and effective 14 May 2025 Wendt India ceased to be a joint venture, remaining an associate of CUMI.1
The reason to compress a century into a few hundred words is that the history is not the moat. Age is not an advantage; plenty of seventy-year-old industrial companies have been comprehensively destroyed. What the history produced that might be an advantage is specific and testable: raw-material self-sufficiency in a business where raw material is 40-plus per cent of cost, decades of accumulated furnace and formulation know-how, and a distribution network into Indian industrial buyers built one dealer at a time.
Whether those things constitute a durable competitive advantage — and crucially, where they constitute one — is the question the rest of this story answers, and the answer is more geographically bounded than the company's global-ambition language implies.
III. The Business Today: Three Segments, One Dominant
Walk into a CUMI plant and the first thing that strikes you is heat. Not the metaphorical kind — the literal, furnace-radiating, stand-back kind. Fusing alumina means running an electric arc furnace hot enough to melt bauxite into a solid ingot, which is then cooled, broken, crushed and graded into particles measured in microns. The company operates a wet silicon carbide rod mill at its Russian plant whose output gets oven-dried before the next stage; the photographs in the annual report look like something from a 1960s industrial documentary.1
That is one end of the business. At the other end, in a clean room at Hosur, technicians handle ceramic components destined for semiconductor wafer-fabrication equipment, where a contaminant measured in parts per billion is a defect. Same company. Same reporting segment structure. Radically different economics.
The segment map
For the year ended 31 March 2026, CUMI reported consolidated sales of ₹5,149 crore, up 6.5%.2 The split:
Abrasives — ₹2,271 crore, roughly 44% of revenue, up 5.1%.2 Bonded wheels, coated abrasives (think sandpaper, industrially), thin cutting wheels, superabrasives. This is the historic core and the largest revenue line.
Ceramics and Refractories — ₹1,268 crore, about 25%, up 9.3%.2 Industrial ceramics, wear-protection tiles, metallised cylinders for vacuum interrupters, refractory bricks, anti-corrosive linings, and the newer ballistic and electronic ceramics.
Electrominerals — ₹1,632 crore, about 32%, up 3.7%.2 The grain business: brown and white fused alumina, silicon carbide, treated grains, specialty zirconia products. It sells to CUMI's own downstream segments and to third parties, including CUMI's competitors.
Now the part that revenue share conceals. Segment profit before interest and tax tells a completely different story: Ceramics earned ₹256 crore, Abrasives ₹97 crore, Electrominerals ₹91 crore.2 Read that again. The segment producing a quarter of revenue produced more than half of segment profit. Ceramics ran a consolidated margin of about 20.2%; Abrasives, the largest revenue line, ran at 4.3%; Electrominerals at 5.6%.6
Those consolidated margins are, however, deeply misleading about the underlying Indian business — and the divergence is the single most important structural fact in CUMI's accounts. At the standalone (India-only) level, Abrasives earned a PBIT of ₹195 crore on sales of ₹1,270 crore, a margin above 15%.26 The consolidated Abrasives margin collapsed to 4.3% because the overseas abrasives subsidiaries lost money: RHODIUS lost ₹45 crore and AWUKO ₹75 crore in FY26 alone.6
Sit with that arithmetic for a second, because it reframes everything. CUMI's Indian abrasives business is a mid-teens-margin franchise. Its consolidated abrasives business is a low-single-digit-margin franchise. The difference is entirely the foreign assets. Total standalone PBIT rose 23.4% to ₹525 crore in FY26 while consolidated profit before exceptional items fell 27.2% to ₹416 crore.6 The India business was not the problem. The India business was quietly having a good year while the consolidated numbers deteriorated.
Management itself decomposed the consolidated profit decline on the Q4 FY26 call with unusual specificity: VAW in Russia accounted for roughly ₹87 crore of it, RHODIUS ₹46 crore, Foskor ₹22 crore, AWUKO ₹19 crore.6 Four foreign subsidiaries, ₹174 crore of profit erosion, in a year when the domestic engine improved. The pattern was visible at the half-year mark too: on the Q2 FY26 call, management attributed the first-half PBIT decline of ₹192 crore against ₹304 crore to VAW at about ₹51 crore, RHODIUS at ₹26 crore and the standalone business at ₹34 crore — foreign losses doing roughly two-thirds of the damage.7
Competitive structure — and a number worth distrusting
The received wisdom on Indian abrasives is that CUMI and Grindwell Norton — the listed Indian subsidiary of France's Saint-Gobain — form a duopoly. That much is well supported: two large integrated players with full product ranges, quality certification, and national distribution, facing a long tail of small unorganised producers who compete mainly in low-end coated abrasives on price.
The market-share figure attached to that duopoly, however, deserves scepticism. Trade press has variously put the combined CUMI–Grindwell share at around 70% of the market with roughly equal splits,8 and at closer to 51% with each around a quarter. CUMI does not disclose a market share figure. Neither number is a company-reported KPI, they differ by nearly forty per cent in relative terms, and they may be measuring different denominators — organised versus total, abrasives-only versus abrasives-plus-adjacent. Any investment case that rests on "CUMI has 30% share" is resting on a trade estimate, not a disclosure. The structure — two integrated incumbents, high qualification barriers, fragmented low-end competition — is well evidenced. The magnitude is not.
Globally, the picture inverts. In coated abrasives and cutting discs — the markets RHODIUS and AWUKO played in — the field includes Klingspor, Tyrolit, 3M, a long list of European regional producers, and a very large volume of Chinese supply. Nobody has a duopoly there. That structural difference is not incidental; it is the explanation for almost everything that went wrong in Germany, and we will return to it.
Scale, footprint, and what it actually buys
CUMI operates manufacturing across India, Russia, Australia, China, Thailand, Canada and, until the wind-downs, Germany and South Africa, with a global workforce exceeding 10,000 including contractors.1 Export intensity varies enormously by segment, and management was refreshingly precise about this on the Q4 call: over 80% of the Industrial Ceramics business is export, roughly 33% of standalone Electrominerals is export, and less than 10% of Abrasives is export.6
That distribution is analytically useful. It means the Abrasives franchise is fundamentally a domestic business protected by domestic structure, while the Ceramics franchise is a global business competing on technical qualification, and Electrominerals is a globally-traded commodity-to-specialty business exposed to whatever China is doing with capacity and export policy in any given quarter.
Three businesses, three completely different competitive games. Which brings us to the question of what CUMI's advantage actually is — and where the evidence for it runs out.
IV. What "Moat" Actually Means Here — and Where the Evidence Is Thin
Every industrial company claims process know-how. Most of them are describing the ordinary competence required to stay in business rather than an advantage over rivals. So it is worth being precise about what CUMI's claimed edge is, what supports it, and what the record says about its limits.
The claim has three parts. First, backward integration: CUMI mines, calcines, fuses and grades its own raw material, which few pure-play abrasives makers do. Second, technical and process know-how accumulated over seven decades of furnace operation and formulation. Third, switching costs — an abrasive wheel is a consumable qualified into a customer's production process, and requalifying is disruptive enough that buyers do not switch on small price differences.
What supports it
The integration claim is straightforwardly true and economically meaningful. Fused alumina and silicon carbide are power-intensive to make and the input cost is a large share of a finished wheel's cost. Owning the grain means owning the margin at two stages instead of one, and it means supply security when Chinese export policy shifts. CUMI is by its own account the largest producer of fused alumina in India and among the largest global producers of silicon carbide grains.1 Grindwell Norton is also backward-integrated in silicon carbide, so this is not unique — but relative to the unorganised tail and to most global coated-abrasives specialists, it is a real structural difference.
The switching-cost claim is plausible and partly evidenced. CUMI holds a thicket of qualifications — IATF 16949 for automotive, AS9100 and EN9100 for aerospace, oSa for bonded and thin wheels, EN12413.1 In the newer businesses the qualification evidence is more concrete still: STANAG Level 4 qualification for vehicle armour and BIS Threat Level 5 and 6 for personnel protection in the defence ceramics line.6 Qualifications like these take years and create genuine friction.
The durability claim has one strong piece of support: CUMI has coexisted with Grindwell Norton for the better part of seventy years without either driving the other out, which in a two-player market is itself informative. Duopolies that persist for seventy years usually persist for structural reasons.
What does not support it
Here the evidence thins considerably, and it is worth naming the gaps explicitly rather than assuming the moat.
CUMI discloses no customer-retention data, no win/loss rates, no price realisation versus peers, and no market-share figure of its own. On the Q4 FY26 call, an analyst from Aditya Birla Mutual Fund asked directly what CUMI's wallet share was with its largest solid-oxide-fuel-cell customer. The answer: "We wouldn't like to share such details at this call. As I said, we feel that we are an important supplier to the customer."6 That is a perfectly normal corporate response and also a data gap. An investor cannot verify a switching-cost moat from "we feel that we are an important supplier."
More usefully, management itself has repeatedly characterised its domestic growth as volume-driven rather than price-driven. Asked on the Q4 call what split of standalone Electrominerals growth came from volume versus price, the answer was unambiguous: "The predominant growth has come from volume. Price is probably you can treat it as flat, some small percentage."6 The same framing recurred at Q1 FY27 on abrasives: "The sum and substance of the answer is it's predominantly volume driven growth."9
That matters. Pricing power is the cleanest observable signature of a moat. A business growing on volume at flat prices, in a market management concedes is under continuing pressure from Chinese imports — "the Chinese intensity continues to be there, there is no kind of coming down of it"6 — is a business with market position but not demonstrated pricing power. It may still be an excellent business. It is not the same claim.
Where the moat demonstrably broke
And then there is the falsification test that CUMI ran on itself, at a cost of ₹135 crore.
If technical and process know-how in abrasives were a portable, general-purpose advantage, then acquiring a German coated-abrasives maker and applying CUMI's expertise should have worked. CUMI said so at the time, explicitly. In December 2021, announcing the AWUKO asset purchase, the executive who is now CUMI's Managing Director said the deal was "in line with CUMI's aggressive inorganic growth plans" and that "with our expertise and experience in turning around the performance of stressed assets we intend to enhance our international offerings in Coated Abrasive products."10 The then-MD added that "significant cross learning is possible as CUMI also operates two Coated Abrasive makers in India."10
Four years later, the same company's own explanation for why it was shutting the business down cited "a combination of structural and external factors viz. product and market conditions, global overcapacity & pricing pressure, geopolitical and macroeconomic pressures, increasing energy costs."1
Notice what is on that list and what is not. Nothing about failed technology transfer. Nothing about manufacturing execution. The failure was in market structure and cost position — a fragmented, overcapacitised European market where nobody had pricing power, and a German cost base with energy and wage costs CUMI could not offset.
That is a specific and useful finding, not a generic one. It says the moat is real but geographically bounded. CUMI's advantage in India is a joint product of process capability and a favourable market structure — two integrated incumbents, a qualification barrier, and a customer base that values reliability. Transplant the process capability into a market without the favourable structure and it does not generate returns. The know-how travelled. The pricing environment did not, and the pricing environment was doing more of the work than the "expertise in turning around stressed assets" language implied.
Verdict, and how to falsify it. The domestic moat claim survives, narrowed: CUMI has a defensible position in Indian abrasives and a genuinely differentiated technical position in industrial ceramics, but the evidence supports market position and cost advantage rather than pricing power, and it does not travel to structurally different markets. The claim that CUMI's capability is a globally portable asset is rejected by its own record in Germany. The cleanest forward test is not a share statistic — it is whether standalone Abrasives PBIT margin, which slipped from 16.1% to 15.3% in FY26 on weak first-half volumes,6 recovers and holds in the mid-to-high teens while volumes grow. Margin held through a volume cycle is what a moat looks like in the accounts. Volume bought with price is what its absence looks like.
Which raises the obvious question: if the German assets were structurally disadvantaged, why did CUMI buy them?
V. The 2020s Global M&A Wave — And the Reckoning (2021–2026)
Consider the position CUMI found itself in during late 2021.
The company had just come through the pandemic with its balance sheet intact — consolidated revenue of ₹2,631 crore and profit after tax of ₹284 crore in FY21, essentially no net debt, and a parent group with deep pockets and a long horizon.10 Europe, meanwhile, was full of distressed industrial assets: family-owned German Mittelstand manufacturers with strong brands, real technology and broken balance sheets, being sold cheap by insolvency administrators.
To a management team with cash, a stated ambition to globalise, and genuine expertise in the product category, this looked like an obvious opportunity. It is worth stating plainly that the logic was not stupid. It was the kind of logic that persuades good boards.
The German gambit
On 22 December 2021, CUMI GmbH signed an asset purchase agreement with the insolvency administrator of AWUKO ABRASIVES Wandmacher GmbH & Co. KG, having won a competitive bidding process. The estimated purchase price was €6.01 million for land, buildings, plant, machinery, brands, trademarks, patents and technical know-how — cash and receivables excluded.10 It bought coated-abrasives capacity of 10 million square metres and a 120-year-old brand with a leadership position in leather and wood applications.10
Six weeks later, on 2 February 2022, came the larger deal: 100% of RHODIUS Abrasives GmbH at an enterprise value of €55 million, roughly ₹464 crore.11 RHODIUS had 2021 sales of €62.5 million, meaning CUMI paid about 0.9 times revenue — not, on its face, an expensive multiple. RHODIUS made high-performance grinding and cutting consumables, exported more than 70% of revenue to over 100 countries, and claimed the world's thinnest cutting wheel.11
Two deals, roughly €61 million of enterprise value, giving CUMI a European manufacturing and distribution platform in a stroke. The Surface Engineering revenue line duly jumped, largely on acquisition.
What actually happened
AWUKO never scaled. Its sales went from €10.1 million in FY25 to €10.5 million in FY26 — growth of 4.6%, but on a base so small it barely registered against a group doing over ₹5,000 crore.6 Meanwhile its loss before exceptional items and tax widened from €6.6 million to €7.7 million.6 Set those two numbers side by side: a business losing roughly three-quarters of its revenue every year, for four consecutive years. The loss after tax including closure costs reached €18.6 million in FY26.1
By the time the Cyprus board voted on 30 March 2026, the language in the accounts was final: continued underperformance, mounting losses, "inability to achieve a turnaround given the prevailing market conditions."1 Financial information for the entity was restated on a realisable-value, non-going-concern basis, generating a ₹119 crore exceptional charge for write-downs and restructuring.1 Management had earlier estimated the impact at ₹110–130 crore.1213 Notably, the accounts state that AWUKO "is not a material subsidiary of the Group" — technically accurate, and a reminder that a business can be immaterial to revenue while being highly material to the credibility of an acquisition strategy.1
RHODIUS is the more interesting case, because it is the one being kept.
FY26 was bad. Net revenue fell from €66.7 million to €60.8 million, a decline of 8.8%, and the loss after tax widened from €0.2 million to €2.6 million.1 Management's explanation was partly self-inflicted and partly market: in Q1 FY26 RHODIUS transitioned to a new third-party logistics provider, which cost roughly €5 million of sales that were never recovered over the balance of the year, on top of raw material and energy inflation and "severe pricing pressure."6
An investor should weigh that carefully. A logistics transition that destroys €5 million of sales is an execution failure, not a market failure — but it is also a one-time, identifiable, fixable one. And the early evidence is that it is being fixed: in Q1 FY27, RHODIUS posted sales of €15.6 million, up 18% year on year, with the loss narrowing to €0.7 million from €1.6 million in the prior-year quarter.9 Management guided to roughly 5% FY27 sales growth and "a very small loss."6 The candour is worth noting: on the same call where he announced the Aspiration 2030 growth programme, the MD guided one of his own subsidiaries to a loss.
The unavoidable point, though, is chronology. RHODIUS was acquired in early 2022. Four full financial years later it has yet to make money, and management's own framing has been that the full financial turnaround has taken longer than initially projected. That is not a disaster. It is not a success either.
The Russia problem
CUMI acquired Volzhsky Abrasive Works in 2007 — the world's largest single-site silicon carbide manufacturer, with capacity of 90,000 tonnes per annum.15 For fifteen years it was one of the better deals in the portfolio, contributing meaningful profit and cheap grain.
On 10 January 2025, the US Department of State announced that a set of Russian manufacturing companies including VAW had been added to the Treasury Department's Office of Foreign Assets Control Specially Designated Nationals and Blocked Persons list, for operating in the manufacturing sector of the Russian economy.14 The consequence was immediate and mechanical: VAW's property and interests in property in the United States or under US control were blocked, and most transactions involving US currency or US persons became impossible without a licence.1
The FY25 accounts recognised an impairment of ₹104.13 crore, representing foreign-currency balances held with a clearing agency and export receivables sitting outside the group.1 No additional impairment was required in FY26 — an important detail, because it means the write-off was bounded to trapped receivables rather than a wholesale impairment of the plant.1
The operating damage, however, has continued. VAW's revenue fell from RUB 9,403 million to RUB 6,084 million, a decline of 35.3%, as exports were choked off and the business refocused on the Russian domestic market.16 Profit before exceptional items and tax fell from RUB 1,777 million to RUB 671 million.6 And ₹297.1 crore of VAW's cash sits on the consolidated balance sheet unavailable to any other group entity because of repatriation restrictions.1
That last number deserves emphasis. When CUMI describes itself as net-debt-free, roughly ₹297 crore of the cash supporting that description is trapped in Russia. The business remains profitable at reduced scale, and CUMI has not divested it. Asked about it at Q1 FY27, management's position was essentially defensive: comply, stay put, serve the domestic market.9
There is a fair defence here and it should be stated: nobody in 2007 could have forecast the specific sanctions of 2025. But "Russia carries political risk" was not an exotic insight in 2007 either, and the exposure was never hedged or reduced across eighteen years of ownership.
South Africa: the thirteen-year problem
Foskor Zirconia (Pty) Ltd was acquired in 2008 — a 51% stake held indirectly through CUMI International.65 The company's own disclosure is the most damning sentence in the FY26 accounts: Foskor Zirconia "has not been able to achieve sustainable profits since 2013, despite several strategic and operational restructuring initiatives undertaken in the past."6
Thirteen years. Multiple restructurings. FY26 revenue of ZAR 461 million, up 11.2%, with the loss before exceptional items and tax widening from ZAR 37 million to ZAR 77 million on zircon sand price volatility, rand appreciation and South African electricity costs.6 The board concluded on 13 May 2026 — one day before CUMI announced its annual results — that there was no realistic alternative to ceasing operations, and a ₹16 crore write-down followed.1
The write-down is small. The elapsed time is not.
Historical falsification: testing the "disciplined acquirer" claim
Now put the four episodes together, because individually each has an excuse and collectively they have a pattern.
Russia, 2007. South Africa, 2008. Germany, 2021 and 2022. Three separate cross-border platforms, acquired across three different decades, by at least two different management generations. All four assets required exceptional charges, wind-downs or write-downs within the same twenty-four-month window, FY25 to FY26. Cumulative exceptional items across the two years: ₹239 crore.1
Against that, the counterevidence for the defence: the balance sheet never broke. Consolidated net cash stood at ₹392.9 crore at 31 March 2026, up from ₹257.7 crore a year earlier.1 The debt-equity ratio was 0.08.2 CRISIL reaffirmed CUMI at AA+/Stable and A1+ on 25 March 2026, five days before the AWUKO wind-down vote, citing strong market position, integrated operations and robust debt protection metrics.15 There has been no equity dilution beyond routine employee stock option exercises — paid-up capital rose by just ₹0.07 million during FY26 on option exercises.1 The dividend was maintained at ₹4.00 per share for a second consecutive year despite profits falling by a third.2 Not one of these ventures threatened the enterprise.
So how should this be resolved? Not by putting the two lists side by side and shrugging.
The verdict. The "conservatively financed" claim is confirmed and robust — tested through two years of severe profit decline, an unexpected sanctions event, and two simultaneous business closures, and the balance sheet strengthened. The "disciplined capital allocator" claim, however, must be narrowed sharply. CUMI's domestic deployment record is good: the standalone business generated ₹525 crore of PBIT in FY26, up 23.4%, on capital deployed in Indian furnaces, kilns and grinding lines.6 Its cross-border deployment record over nineteen years is poor, and the pattern is recurrent rather than episodic. The recurrence is what makes it a pattern rather than bad luck: different decades, different geographies, different management, same outcome.
Importantly, the failures share a common shape. Each was a bet that CUMI could take a structurally disadvantaged foreign asset — a distressed insolvency estate, a marginal minority-controlled minerals operation, a mid-scale player in an overcapacitised market — and fix it. That is a turnaround thesis, not a synergy thesis, and turnarounds in commoditised markets are the hardest thing in industrials.
What would falsify or confirm the revised view. Two specific tests. First, whether RHODIUS — the one German asset retained — reaches profitability in FY27 as guided, and holds it in FY28. Second, whether Silicon Carbide Products, the newest bolt-on, behaves differently.
The newest bolt-on, and why it is different
On 16 September 2024, CUMI agreed to acquire 100% of Silicon Carbide Products, Inc. of Horseheads, New York, at an enterprise value of $6.66 million, roughly ₹56 crore.16 SCP makes nitride-bonded silicon carbide — a ceramic with high wear and thermal-shock resistance, used in power generation, mining, material handling, molten non-ferrous metal transfer and petrochemical refineries. Founded in 1994, it closed 2023 with sales of $4.2 million "with a healthy profit and return profile."16
Three things distinguish this from the German deals. It was small enough to be genuinely low-risk. It was already profitable — CUMI was buying a working business, not a turnaround. And the stated logic was capability and channel access rather than scale: leveraging SCP's nitriding furnace design and tooling for the Indian market while using its American customer network to sell CUMI's products.16
Early results support the thesis, modestly. In FY26, its first full year under CUMI, SCP recorded revenue of $4.7 million and profit after tax of $0.3 million.1 It grew, it stayed profitable, and it required no exceptional charge. That is exactly three data points on a nineteen-year pattern, which is not enough to overturn anything — but the design of the deal is different in the ways that matter, and that is worth crediting even before the outcome is known.
Which brings us to the far larger bet CUMI is now making — one that cannot be bolted on for ₹56 crore.
VI. Aspiration 2030: The Forward Bet, and What It's Actually Made Of
Roughly fifty minutes into the Q4 FY26 earnings call, having walked analysts through two subsidiary closures, a Russian sanctions overhang and a 27% decline in pre-exceptional profit, the Managing Director changed register. "Now, I would quickly cover our Aspiration 2030," he said — and then delivered a strategy presentation long enough that he apologised for it: "I know it is a long opening remark, but I thought it is needed."6
It was needed, because Aspiration 2030 is the frame through which CUMI is asking investors to interpret everything else.
What it actually is
Aspiration 2030 is not, formally, a revenue target. It is a seven-block operating programme: building a high-performance organisation, ambitious growth in current businesses, innovation, exploring new growth frontiers, manufacturing excellence, sales and marketing excellence, and cross-organisational digital and ESG initiatives.16
The commercially interesting content sits in the "new frontiers" block, and it is genuinely specific. Consider what CUMI actually built in FY26, and what each piece cost.
Semiconductors. In the first half of FY26, CUMI commissioned the first module of a dedicated facility making advanced ceramic components for semiconductor wafer-fabrication equipment, at a capital outlay of ₹66 crore.6 The line runs end to end — high-purity powder preparation, precision machining, cleaning — aimed at global OEMs. Products have been approved by a key customer for serial production, which begins in FY27 with utilisation ramping gradually.6 Management expects the investment could eventually scale "3x to 4x."6
It is worth being clear about what this is and is not. CUMI is not making chips, and it is not making wafer-fab equipment. Asked about this directly at Q1 FY27, the MD was blunt: "We are not getting into semiconductor fab equipment manufacturing... We have been manufacturing ceramics over 40, 50 years."9 What CUMI makes is the ceramic parts inside the machines that make chips — components that must survive plasma, extreme thermal cycling and aggressive chemistry without shedding a single contaminating particle. It is a real, high-barrier niche. It is also a components-supplier position in someone else's supply chain, with all the customer-concentration implications that carries.
Defence and aerospace. A new facility at ₹49 crore outlay produces advanced ceramics for ballistic protection of vehicles and personnel.6 CUMI has secured STANAG Level 4 qualification for vehicle armour and BIS Threat Levels 5 and 6 for personnel protection, and is awaiting SCOMET approval, which would enable export.6 Management expects the business to scale "gradually" toward 2030.6
Clean energy. CUMI commissioned a pilot-scale facility using spray pyrolysis to make ceramic powders for solid-oxide fuel cell and electrolyser cathodes, based on a technology transfer from CGCRI, the government's Central Glass and Ceramic Research Institute.6 Separately — and this is the one piece already producing revenue — CUMI's existing Engineering Ceramics business, which supplies components to an SOFC customer, grew 30% in FY26 on what management described as strong demand from the AI-driven data-centre segment.6
Advanced materials. Silicon nitride and aluminium nitride powders via a technology transfer agreement; high-purity silicon carbide, where CUMI has achieved 5N purity and initiated the route to 6N; graphene applications in bioplastics, coatings, concrete and rubber.6
For those unfamiliar with the notation: "5N" means 99.999% pure, "6N" means 99.9999%. Each additional nine is roughly an order of magnitude harder and is the difference between an industrial-grade material and one usable in electronics. CUMI has reached 5N and is "currently working on a pilot scale manufacturing facility" for 6N.6
Sizing it honestly
Now the discipline. Every one of these initiatives sits inside the existing Ceramics or Electrominerals segments. None has disclosed standalone revenue. Management was explicit about the trajectory of the transformational-products basket: it expects them to contribute around 10% of the Electrominerals business by 2030, "compared to the current level, practically very little."6
Practically very little. That is management's own characterisation, and it should govern how the story is told. The more mundane Electrominerals reshaping is actually the bigger economic event: core fused alumina and silicon carbide falling from 85% of that segment to 55–60% by 2030, treated grains rising from 5–6% to around 20%, and zirconia-based specialty products from 8% to 18–20%.6 That is a mix shift toward higher-value product, and it is far more likely to move the P&L this decade than graphene.
The historical test: does CUMI convert technology into revenue?
There is a directly relevant precedent, and it cuts in a more nuanced direction than the sceptical case assumes.
In August 2021, CUMI acquired a controlling stake in Pluss Advanced Technologies, a materials-science company specialising in phase-change materials and specialty polymers — positioned at the time as optionality in cold-chain logistics and, eventually, EV battery thermal management.17 It was exactly the kind of adjacent, technically interesting, narrative-rich bet that Aspiration 2030 is full of.
Five years on, the record is mediocre but improving. Pluss recorded consolidated revenue of ₹98.1 crore in FY26, up 21.8% from ₹80.6 crore, and — for the first time in this reporting series — turned a profit after tax of ₹1.8 crore against a loss of ₹3.6 crore the year before.1 At the group profit-before-tax level, after acquisition accounting, Pluss still detracted ₹9 crore in FY26 versus ₹17.1 crore in FY25.1 Note also that CUMI granted Pluss's erstwhile promoters a put option over their residual stake, with a reciprocal call option — a structure that limits the seller's downside and is worth knowing about.1
So the fair reading is: five years after acquisition, a materials-optionality bet reached roughly 2% of group revenue and marginal profitability, on an improving trend. Not a failure. Not a needle-mover. Conversion happened, slowly.
Verdict on the optionality claim. Aspiration 2030's technical building blocks are real and verifiable — commissioned facilities, achieved purity grades, named qualifications, an approved serial-production programme with a semiconductor customer. That is materially better evidence than most companies offer when they invoke semiconductors. But certification is not commercialisation, and CUMI's own conversion record — Pluss at roughly 2% of revenue after five years — argues for a slow ramp rather than a step change. The honest framing is that these are real options with real strike prices already paid, sized today at essentially zero of group profit, and management has declined to attach revenue or margin targets to them. Asked directly at Q4 FY26 whether Aspiration 2030 carried a revenue or margin target, the answer was that CUMI shares only one-year guidance.6 Investors are being asked to fund a 2030 programme against annual disclosure.
The KPI to watch is narrow and specific: whether semiconductor components and metallised substrates produce disclosed, separately identified revenue. Management said at Q1 FY27 that wafer-equipment components would begin contributing in FY27 and accelerate in FY28, with metallised substrate revenue starting FY28.9 Those are dated, falsifiable claims. Hold them to it.
VII. Management, Incentives, and Credibility Since 2023
There is an uncomfortable symmetry at the centre of CUMI's current leadership, and it is worth stating plainly because it cuts in both directions.
Sridharan Rangarajan, a chartered accountant with four decades of experience across manufacturing, banking, contracting and distribution, joined the Murugappa Group in 2011 as Chief Financial Officer of Carborundum Universal, serving in that role until 2018, after which he became President and Group Chief Financial Officer of the Murugappa Group.1 He joined the CUMI board in July 2021.1 He now runs the company as Managing Director.
He was also the executive who, in December 2021, described the AWUKO acquisition as being "in line with CUMI's aggressive inorganic growth plans" and invoked "our expertise and experience in turning around the performance of stressed assets."10
So the person explaining the wind-down is, to a significant degree, the person who authored the acquisition. That is not a scandal — it is common in industrial companies with deep internal benches, and it comes with a genuine benefit: institutional memory, and no incentive to blame a predecessor. But it does mean investors should read the AWUKO post-mortem knowing the author is grading his own work.
How the explanation actually read
On the evidence, he graded it fairly harshly. The Q4 FY26 disclosure did not hide behind macro language. It named the causes with specificity — product and market limitations, global overcapacity and pricing pressure, energy costs, the thirteen-year unprofitability run at Foskor — and it stated the accounting consequence rather than deferring it.16 An analyst opened the Q&A by congratulating management "on taking a timely decision on the divestiture of an Awuko."6
That word — timely — deserves scrutiny. AWUKO was acquired in December 2021 and wound down in March 2026: four years and three months. Foskor was acquired in 2008 and, by the company's own account, stopped being sustainably profitable in 2013; it was closed thirteen years later.6 These are not fast decisions. The willingness to close a losing position and say why is a real credibility asset. The elapsed time before doing so is a real fact about decision speed, and it is the more informative of the two.
Guidance discipline: an actual scorecard
Here is where CUMI's management scores better than the headline numbers suggest, and it is checkable because Rangarajan does something unusual: he explicitly compares each result against the guidance he gave on the prior call, out loud, including the misses.
The FY26 scorecard, from his own Q4 FY26 remarks:6
- Consolidated sales: guided 5.5–6.5%, delivered 6.5%. Met.
- Consolidated Electrominerals sales: guided 1–2%, delivered 3.7%. Beat.
- Electrominerals PBIT margin: guided 4.5–5.5%, delivered 5.6%. Beat.
- Consolidated Abrasives PBIT margin: guided 4–4.5%, delivered 4.3%. Met.
- Consolidated Ceramics sales: guided 13–14%, delivered 9.3%. Missed, materially.
- Capital expenditure: guided ₹350 crore, spent ₹309 crore. Under.
Four met or beaten, one clear miss, one underspend. And crucially, he stated the Ceramics miss himself rather than letting an analyst find it: "During the last call, we gave a sales growth of 13% to 14% in Ceramics. We achieved 9.3% growth in Ceramics."6
That is genuine guidance discipline — specific, segment-level, and self-scored. It is a meaningfully higher standard of disclosure than most Indian mid-caps offer, and it is the strongest single argument for management credibility here.
The FY27 guidance is equally specific.6 Consolidated sales growth of 4–4.5% headline, or 11–12% excluding the ₹343 crore of FY26 revenue that came from Foskor and AWUKO. Abrasives 5.5–6% headline, 11–12% excluding AWUKO's ₹108 crore. Ceramics 15–15.5%. Electrominerals declining 6.5–7% headline on the Foskor closure, or growing 8–9% on a comparable basis. Margin targets: Abrasives 9.5–10%, Ceramics 20.5–21%, Electrominerals 9–9.5%. Capex ₹400 crore.
One yellow flag. Per the Q1 FY27 call, management raised its Ceramics growth guidance sharply — to a range of 23–25% from the 15–15.5% given three months earlier — after a single quarter in which consolidated Ceramics grew 16.5%.918 Raising a full-year target by roughly eight percentage points on one quarter's data is aggressive, particularly from a team that missed its Ceramics number the prior year by nearly five points in the other direction. Whether that reflects genuine order-book visibility or momentum-chasing is exactly the kind of thing the next two quarterly prints will settle.
Incentives and ownership
The Managing Director's gross remuneration for FY26 was ₹4.17 crore, up 9.28% year on year, at 57.78 times the median employee's pay.1 Median employee remuneration rose 3.02%, and average salaries rose 8.48% against managerial remuneration up 13.72%.1 By Indian large-cap standards these are unremarkable figures; a 57.78x ratio is on the moderate side.
Ownership is where alignment actually lives, and the structure is worth understanding. The promoter and promoter group held 38.89% at 31 March 2026.1 That has drifted down over time — screener data shows it at 41.28% as recently as September 2023.3 This is gradual drift, not a dramatic exit, and no promoter-pledge or governance dispute has surfaced in the FY26 filings.
What is more striking is who owns the rest. Mutual funds held 27.75% and foreign institutional investors 10.73%, with individuals at 15.92%.1 Domestic institutions holding nearly 28% of a mid-cap industrial is a substantial, sticky, but also demanding shareholder base — and it explains the unusually analyst-heavy, segment-level disclosure culture on the calls.
Chairman M.M. Murugappan, a non-executive promoter-family director, has been on the board since October 1996, drawing 14.71 times the median employee's remuneration.1 The board added Ambassador D.B. Venkatesh Varma, a career diplomat, as an independent director effective 4 March 2026 — a notable appointment for a company simultaneously navigating Russia sanctions, defence-ceramics SCOMET approvals and Western trade policy.1
The structural point on incentives: the Managing Director's personal equity stake is modest, so alignment runs primarily through the promoter family's own 38.89% rather than through management's shareholding. That is the standard Indian family-conglomerate arrangement. It generally produces long horizons and conservative balance sheets — both visibly present here — and it does not particularly reward aggressive value creation or punish slow exits from losing positions. Which is roughly what the record shows.
VIII. Financial Trajectory: A Two-Year Margin Story
If you looked only at CUMI's consolidated profit line for the last three years, you would conclude the business was collapsing.
Consolidated profit after tax attributable to owners went ₹461 crore in FY24, ₹293 crore in FY25, ₹195 crore in FY26.216 Two consecutive years of declines, roughly 36% and then 33%. On that trajectory alone, a reasonable observer would assume structural deterioration.
They would be wrong, and the reason matters more than the numbers.
Separating the one-off from the ongoing
Revenue never stopped growing. Consolidated sales rose 6.5% in FY26 and standalone sales rose 8.6% to ₹3,024 crore.2 Standalone profit after tax actually increased to ₹416 crore from ₹322 crore.2 Standalone total PBIT rose 23.4%.6 The Indian business, which is the majority of the enterprise value by any reasonable reckoning, had a good year.
The consolidated profit decline decomposes into two distinct things that should never be added together. First, ₹239 crore of exceptional items across FY25 and FY26 — the VAW receivable impairment, the AWUKO closure, the Foskor write-down.1 These are non-recurring by construction; the assets are being closed. Second, genuine ongoing operating deterioration at the foreign subsidiaries, worth roughly ₹174 crore of pre-exceptional profit decline in FY26 alone.6 The second category is the one that matters for normalised earnings, and it too largely disappears with the closures — except for the VAW component, which does not, because VAW is not being sold.
Consolidated profit before exceptional items and tax was ₹416 crore in FY26 against ₹572 crore in FY25.6 That is the number to normalise from, not ₹195 crore.
The balance sheet
Consolidated net cash improved to ₹392.9 crore from ₹257.7 crore.1 Gross borrowings did rise — to roughly ₹413 crore, from a very low base of about ₹70 crore in FY20 — but against equity of a different order of magnitude entirely, producing a debt-equity ratio of 0.08.23
More telling than the stock is the flow. Free cash flow was 56.6% of PAT at consolidated level in FY26, against 16.1% the prior year; standalone, 46.5% against 13.9%.2 That is a dramatic improvement in cash conversion, and it is the kind of operational signal that rarely lies — working capital was released and capital expenditure came in under guidance.
The credit rating tells the same story from the outside. CRISIL's March 2026 reaffirmation at AA+/Stable and A1+ explicitly cited strong market position, revenue diversity, integrated operations, comfortable capital structure and robust debt protection metrics, while flagging "volatility in operating profitability across business segments" as the offsetting weakness.15 A rating agency, reading the same files, arrived at the same split verdict this article has: strong balance sheet, volatile earnings.
The one asterisk, already noted: ₹297.1 crore of the group's cash is VAW's and cannot be moved.1 "Net debt-free" is true. It is slightly less liquid than it sounds.
The valuation problem
Here is where the story gets genuinely uncomfortable for a bull.
As of 2 September 2026, CUMI traded around ₹1,072 per share for a market capitalisation of roughly ₹20,400–21,000 crore.34 The trailing price-to-earnings multiple sat between roughly 81 and 99 times depending on the earnings base used.34 Return on equity was 6.92% in the latest year against a three-year average nearer 11%, with return on capital employed at 10.5%.3 Five-year profit growth was negative 3% compounded, against five-year sales growth of 15%.3 The shares have traded between ₹735 and ₹1,307 over the past year.4 Sell-side consensus, thin at six covering analysts, has skewed toward the bearish end.4
Some of that multiple is arithmetic artefact — a P/E on exceptional-item-depressed earnings is not a meaningful number, and the forward multiple compresses substantially on normalised earnings.4 But even normalising, this is not a stock priced as a cyclical industrial in the middle of a cleanup. It is priced for the recovery to happen and for Aspiration 2030 to work. The gap between a mid-single-digit ROE and a multiple in that range is the entire investment debate.
The pivot quarter
Which brings us to Q1 FY27, reported in August 2026, and the single most important recent data point.
Consolidated sales rose 16.9% to ₹1,411 crore. Consolidated profit after tax rose 23.4% to ₹76 crore. Consolidated PBIT rose 40.9% to ₹114 crore.918 Standalone sales rose 21.2% to ₹846 crore.9
The segment detail is what makes it interesting. Abrasives sales grew 20.1% to ₹610 crore with PBIT of ₹40 crore against ₹11 crore a year earlier. Electrominerals grew 16.8% to ₹473 crore with PBIT of ₹22 crore against ₹4 crore. Ceramics grew 16.5% to ₹349 crore with PBIT of ₹74 crore.18 Standalone Electrominerals PBIT went from ₹7 crore to ₹39 crore.9
Three segments growing in the mid-to-high teens, with the two low-margin segments showing PBIT expanding several-fold off depressed bases — and no exceptional item dragging the headline. It is the first genuinely clean quarter in over a year, and it followed a Q4 FY26 in which consolidated PAT was actually negative at a loss of ₹18 crore because of the exceptional charges.
The honest caveat is severe, though. Q1 FY26 was a weak base — standalone Abrasives volumes were soft in the first half of FY26, and management said so repeatedly, noting H2 FY26 grew about 31% sequentially over H1.6 Comparing a recovering quarter against a depressed one flatters growth in both revenue and, through operating leverage, profit. A PBIT that goes from ₹11 crore to ₹40 crore is impressive; it is also what happens when a fixed-cost manufacturing base moves from under-absorption to normal absorption.
So the single most important open question for a reader to carry forward is this: is Q1 FY27 a genuine inflection or a base effect? Two more quarters of mid-teens growth against normalising comparisons would settle it. One quarter does not.
IX. Industry Dynamics and Risk Radar
For twenty years, the central competitive fact in global abrasives and electrominerals was straightforward: China built enormous capacity in fused alumina, silicon carbide and abrasive grains, and exported it at prices Western and Indian producers struggled to match. That single force explains a great deal — including, by CUMI's own account, why AWUKO's economics never worked.
In 2025 and 2026, that force met organised resistance for the first time in a while, and the mechanism is concrete enough to be worth tracing.
The trade-policy tailwind
In the United States, the International Trade Commission determined in September 2025 that the domestic industry was materially injured by imports of sol-gel alumina-based ceramic abrasive grains from China,19 and antidumping and countervailing duty orders followed, applicable from 29 September 2025.20
In the European Union, the sequence ran through 2025 into 2026. Provisional anti-dumping duties on Chinese fused alumina were imposed in July 2025 at rates ranging from roughly 111% to 136%. The Commission then moved to definitive duties, announced 16 January 2026, at rates between roughly 88.7% and 110.6%, running for an initial five years, with a duty-free tariff-rate quota permitting a limited volume of Chinese imports before duties bite.21
Separately, China removed the export rebate on abrasive products, cutting it from 9% to zero effective April 2026 — a self-inflicted reduction in Chinese export competitiveness that an Equirus analyst raised on the Q4 FY26 call.6
This is not generic "China+1" narrative. It is a dated, mechanism-level change in relative cost — and unusually, there is already evidence in CUMI's numbers that it is working. Standalone Electrominerals exports doubled in FY26, rising from 11% of that business to a little over 33%, more than ₹300 crore.6 Management attributed the surge to existing global OEM relationships, the introduction of treated grains, and explicitly, "anti-dumping duties against Chinese grains by EU."6
That is a rare thing in equity analysis: a policy change, a stated transmission mechanism, and a measurable revenue response, all within twelve months. It deserves to be treated as evidence rather than narrative.
But note what it is not. Anti-dumping duties are jurisdiction-specific and product-specific. They apply to fused alumina in the EU and sol-gel ceramic grains in the US. They do not remove global overcapacity; they redirect it. Volumes shut out of Europe and America go somewhere, and one of the places they go is India, where management confirmed Chinese import intensity has not diminished.6 Duties also expire, get litigated, and get circumvented through third countries. A tailwind with a five-year initial clock is not a moat.
The risks that actually bite
Russia remains structurally embedded. VAW was impaired, not divested. Its cash is trapped, its exports are curtailed, and its future depends on geopolitical developments over which CUMI has no influence. The business remains profitable at reduced scale, but a second-order sanctions escalation — secondary sanctions on entities dealing with SDN-listed companies, for instance — is a live tail risk that management can only manage defensively.
Cyclicality. Abrasives and refractories are consumables sold into steel, auto, foundry, glass and construction. They are geared to industrial output, which is geared to the capex cycle. The FY26 first half is a clean illustration: standalone Abrasives volumes were weak, cost absorption suffered, and full-year standalone PBIT margin slipped from 16.1% to 15.3% despite an H2 recovery of roughly 31% sequentially.6 Nothing structural broke; a demand air-pocket simply passed through the fixed cost base.
Input costs. Electricity and raw materials — bauxite, alumina, zircon sand, petroleum coke — are the dominant cost lines in fusion. The annual report flags aluminium price volatility as a specific risk.1 At Q1 FY27, analysts pressed on a ₹15–16 crore abrasives PBIT decline linked to oil-based input costs.9 These are recurring, not exceptional.
Execution risk on the new bets. FY27 capex is guided at ₹400 crore, up roughly 30% from ₹309 crore.6 A meaningful share goes into advanced ceramics for power electronics, substrates, brazed assemblies, thermal spray powder furnaces and zirconia capacity.6 The company is spending more, on more technically demanding products, in adjacent markets, immediately after a two-year run of overseas execution misses. That sequencing deserves scrutiny even if each individual project is sensible.
Customer concentration in the growth vectors. The semiconductor programme depends on qualification with a "key customer," singular in management's phrasing.6 The SOFC business depends on a customer whose order visibility management describes as running to roughly 2028, and whose wallet share CUMI declined to disclose.6 These are the classic economics of a specialised component supplier: high barriers to entry, and a single buyer on the other side of the table holding most of the negotiating leverage. That is not a reason to dismiss the opportunity, but it is a reason not to model it as a cornered resource.
The absence of a governance overhang. No activist campaign, promoter pledge issue, auditor qualification or public governance dispute appears in the FY26 filings. The statutory audit is performed by Price Waterhouse, with PricewaterhouseCoopers GmbH auditing RHODIUS.1 The more relevant sceptical lens here is not governance — it is valuation and the cross-border capital allocation record, both of which the next section takes head-on.
X. Bull vs. Bear Case
Strip away the narrative and the disagreement about CUMI reduces to one question: is the Indian core a compounding franchise temporarily obscured by foreign write-offs, or is it a good-but-cyclical industrial business carrying a growth multiple it has not earned?
Both readings use the same facts.
The bull case
A defensible domestic position in a two-player market. Seventy years of coexistence with Grindwell Norton, in a market where qualification cycles, capital intensity and distribution depth keep out serious new entrants. The unorganised tail competes on price at the low end and cannot follow into precision or industrial applications.
The cleanup is genuinely finished for two of three problem assets. AWUKO is being wound down; management said at Q1 FY27 it was "trying our best to complete the process in a quarter or so."9 Foskor is in exit evaluation with a solution expected within a quarter.9 Together they represented ₹343 crore of FY26 revenue at negative margins.6 Removing them mechanically improves consolidated margin without any operational improvement whatsoever.
A dated, mechanism-level trade tailwind with measurable early evidence — the doubling of standalone Electrominerals exports being the cleanest proof point available.
Q1 FY27 as the first clean quarter, with all three segments growing in the mid-to-high teens and no exceptional item.
Balance-sheet optionality. Net cash, AA+/A1+, and a controlling family with a multi-generational horizon means CUMI can fund ₹400 crore of capex and further bolt-ons from internal accruals without dilution.
Real, already-paid-for optionality in ceramics. The semiconductor and defence facilities exist, the qualifications are secured, and serial supply has begun. This is further along than "we are exploring."
The bear case
A nineteen-year cross-border pattern. Russia 2007, South Africa 2008, Germany 2021–22 — three platforms, three decades, all requiring write-offs or wind-downs in the same two-year window. Until proven otherwise, the base rate on CUMI's foreign deployment is poor, and management has signalled continued M&A ambition (PMO/M&A capability is literally one of the Aspiration 2030 building blocks).1
Valuation prices the recovery, not the risk. A trailing multiple in the eighties-to-nineties against a 6.92% ROE, with negative five-year profit growth, and one clean quarter of evidence.34 The market is not offering a margin of safety on the turn.
The growth vectors are pre-revenue and management will not target them. Transformational products are "practically very little" today and guided to about 10% of Electrominerals by 2030.6 Pluss took five years to reach roughly 2% of group revenue and marginal profit.1 The refusal to attach revenue or margin targets to Aspiration 20306 means investors cannot mark progress against a stated plan.
Capital efficiency has genuinely deteriorated, and not only because of exceptionals. ROCE at 10.5% on a rising capital base, with capex guided up 30%, is a combination that requires the new capital to earn considerably better than the old.3
Global overcapacity has not gone away. The force that broke AWUKO's economics was redirected by anti-dumping duties, not eliminated, and CUMI's own management confirms Chinese intensity in India is undiminished.6
Russia is unresolved. Not divested, not written off in full, cash trapped, and outside management's control.
Seven Powers and Five Forces, applied honestly
Running Hamilton Helmer's framework across CUMI produces a short list, which is itself informative.
Scale economies — present in Electrominerals, where furnace and power economics reward volume, and CUMI is the largest Indian producer of fused alumina. Genuine but shared with Grindwell Norton domestically and dwarfed by Chinese scale globally.
Switching costs — present in bonded and precision abrasives and stronger still in qualified ceramics, where STANAG, BIS and semiconductor OEM approvals take years. This is CUMI's most credible power, and it is concentrated in Ceramics, the smallest-revenue and highest-margin segment. That is not a coincidence.
Cornered resource — arguably present in backward integration plus the CGCRI technology transfer for SOFC powders and the nitride technology licence.6 Weak form: these are licensed and replicable, not owned and unique.
Process power — the claim CUMI leans on hardest, and the one Germany falsified as a portable asset. It appears to be process power conditional on a favourable market structure, which is a much weaker power than process power simpliciter.
Counter-positioning, network economies, branding — essentially absent. RHODIUS and AWUKO carry brand heritage; neither converted it into pricing power.
On Porter, the picture is a genuinely mixed industry. Rivalry is moderate domestically and brutal globally. Buyer power is high in commodity grain and in the new growth vectors where CUMI faces a single dominant customer, but lower in qualified bonded abrasives sold through a dealer network. Supplier power is mitigated by CUMI's own mines and furnaces — the clearest structural payoff of the 1960s integration strategy. Entry barriers are high in India and low-to-nil globally, where the entrant already exists at scale in China. Substitution is a slow-burn risk: superabrasives and improved cutting technologies can displace conventional wheels, though CUMI plays in superabrasives too.
The summary judgment is that CUMI has a real but narrow set of powers, concentrated in switching costs in ceramics and integration-driven cost position in India, and that the powers do not extend to the geographies where it has spent the most acquisition capital.
The KPIs that matter
Three, and only three.
1. Standalone Abrasives and Ceramics PBIT margin. This is the domestic moat, measured directly. Standalone Abrasives ran 15.3% in FY26, down from 16.1%.6 If the moat is real, margin holds or expands through the volume recovery. If growth is being bought with price, margin will not follow volume.
2. Consolidated segment growth against management's own FY27 guidance. Management gives segment-level numbers and self-scores against them. Abrasives 11–12% and Electrominerals 8–9% on a comparable basis, and Ceramics — where guidance was raised sharply at Q1 FY27 — are checkable every ninety days.69 This is simultaneously a growth KPI and a management-credibility KPI, which is what makes it efficient.
3. Disclosed revenue from the emerging vectors. Not capex, not qualifications, not pilot facilities. Revenue. Management has committed to wafer-fab equipment components contributing in FY27 and accelerating in FY28, with metallised substrates starting FY28.9 If FY28 arrives with these still buried inside segment totals and no separate disclosure, that is an answer in itself.
XI. Durable Lessons for Investors
The most transferable thing about CUMI's last five years is not a fact about abrasives. It is a set of analytical habits that this particular company happens to illustrate unusually cleanly.
A domestic moat does not travel with the acquisition. CUMI's Indian advantage is the joint product of capability and market structure — two integrated incumbents, qualification barriers, a customer base that values reliability over the last five per cent of price. Take the capability to Germany, where the structure is fragmented and overcapacitised, and it produces nothing. The general lesson: when a company proposes to export its competitive advantage, ask which part of that advantage is the company and which part is the market it happens to operate in. Geography-specific moat claims need geography-specific evidence, and the burden of proof sits with the acquirer.
Balance-sheet discipline and deployment discipline are different claims. CUMI is genuinely conservatively financed — net cash, AA+ rated, no dilution, dividend maintained through a 33% profit decline. It has also lost money on three of its last four cross-border platforms. Neither fact contradicts the other, and neither should be allowed to vouch for the other. When a company's capital-allocation reputation rests mostly on what it has not done — not levered up, not diluted — check separately what it has actually done with the capital it deployed.
Admitting a loss is a credibility asset; the lag before admitting it is the more informative number. CUMI's disclosure on AWUKO and Foskor was specific, causal and unflinching, which is better than most. But Foskor stopped being sustainably profitable in 2013 and closed in 2026. Thirteen years of restructuring initiatives is not patience; it is a decision-making speed. When a company tells you candidly why something failed, note the candour — then measure the interval between when the failure became visible and when it was acted on. That interval is a governance metric.
Size optionality to its economic weight, not its narrative appeal. Semiconductors, defence ceramics and solid-oxide fuel cells make for a far better story than treated abrasive grains. But it is treated grains going from 5–6% to 20% of Electrominerals that will move CUMI's P&L this decade, while transformational products are guided to roughly 10% of one segment by 2030 from a base management itself calls "practically very little." Certifications, pilot facilities and qualified prototypes are the price of admission to a market, not evidence of a position in it. The company's own history — a materials-science acquisition reaching about 2% of group revenue after five years — is the best available prior for how fast the conversion actually runs.
Finally: read the entity-wise disclosure, not the consolidated headline. CUMI's most valuable disclosure is a table almost nobody reads — the subsidiary-by-subsidiary breakdown of profit before tax. That table showed the Indian business earning ₹525 crore while foreign subsidiaries collectively contributed a loss, in a year when the consolidated headline suggested a company in decline. The consolidated number was accurate and almost entirely uninformative. In any group with meaningful overseas operations, the segment and entity tables tell you where the business actually is, and the headline tells you only what happened to be aggregated.
References
-
CUMI 72nd Annual Report FY2025-26 — Carborundum Universal Limited ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Carborundum Universal's Full Year 2025-26 and Q4 2025-26 Press Release — Murugappa Group, 2026-05-14 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Carborundum Universal Ltd — consolidated financials, ratios and shareholding — Screener.in ↩↩↩↩↩↩↩↩↩↩
-
Carborundum Universal (NSE:CARBORUNIV) — quote, valuation and analyst consensus — StockAnalysis.com ↩↩↩↩↩↩↩↩
-
About CUMI — History and Milestones — Carborundum Universal Limited ↩↩↩↩↩↩↩
-
Carborundum Universal Limited Q4 FY26 Earnings Conference Call Transcript — CUMI, 2026-05-15 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Carborundum Universal Limited Q2 FY26 Earnings Conference Call Transcript — CUMI, 2025-10-31 ↩
-
Earnings call transcript: Carborundum Universal Q1 FY27 results — Investing.com, 2026-08-10 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
CUMI to acquire assets of AWUKO Abrasives, Germany — Press Release, CUMI, 2021-12-23 ↩↩↩↩↩↩
-
Carborundum Universal-led Germany arm to acquire 100% stake in RHODIUS Abrasives at Rs464cr — IndiaInfoline, 2022-02-02 ↩↩
-
CUMI International to wind down German arm amid mounting losses — Industrial Economist ↩
-
Carborundum Universal to wind down German subsidiary, estimated impact Rs 110-130 crore — Business Upturn ↩
-
Sanctions to Degrade Russia's Energy Sector — U.S. Department of State, 2025-01-10 ↩
-
Rating Rationale — Carborundum Universal Limited — CRISIL Ratings, 2026-03-25 ↩↩
-
CUMI to acquire 100% stake in Silicon Carbide Products, Inc., New York — Press Release, Murugappa Group, 2024-09-16 ↩↩↩↩
-
Carborundum Universal to acquire controlling stake in PLUSS Advanced Technologies — Business Standard, 2021-08-26 ↩
-
Carborundum Universal: Q1 FY27 Consolidated Sales Rise 16.9% to ₹1,411 Cr — InvestyWise, 2026 ↩↩↩
-
Sol Gel Alumina-Based Ceramic Abrasive Grains from China Injure U.S. Industry, Says USITC — U.S. International Trade Commission, 2025-09-03 ↩
-
Sol Gel Alumina-Based Ceramic Abrasive Grains From the People's Republic of China: Antidumping Duty Order and Countervailing Duty Order — Federal Register, 2025-09-29 ↩
-
Commission acts against unfairly traded imports of fused alumina — European Commission DG Trade, 2026-01-16 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube