Accelya Solutions India: Who Owns the Airline Industry's Plumbing?
I. Introduction & Episode Roadmap
Picture a travel agent in Nairobi, Lisbon or Lucknow pressing "issue" on an airline ticket. The traveller sees a confirmation email. The agent sees a commission. Nobody sees what happens next. The ticket has to be reported, reconciled and settled. Money moves from the agency to the airline, and every one of the hundreds of airlines selling through the travel trade has to be paid correctly for tickets sold by tens of thousands of agents. In a large share of the world, that process runs through the International Air Transport Association's Billing and Settlement Plan (BSP). The software window that airlines and agents use to see those settlements, BSPLink, is operated by the Accelya group.12
Part of the engineering, processing and back-office work behind that system is done from Pune, by a company listed on India's National Stock Exchange under the ticker ACCELYA. Accelya Solutions India Limited earns roughly ₹530 crore a year in revenue, has returned around 40% on equity in recent years, carries almost no debt, and is about three-quarters owned by a holding-company chain that leads up to Vista Equity Partners, the US private equity firm.34 Most Indian retail investors have never heard of it.
That combination raises the question this story is built around. Is ACCELYA a wonderful annuity business that trades cheaply because it is obscure and controlled? Or is it a cash-dispensing subsidiary whose growth, strategy and upside now sit above it, in a private group that happens to own 74.66% of its shares?
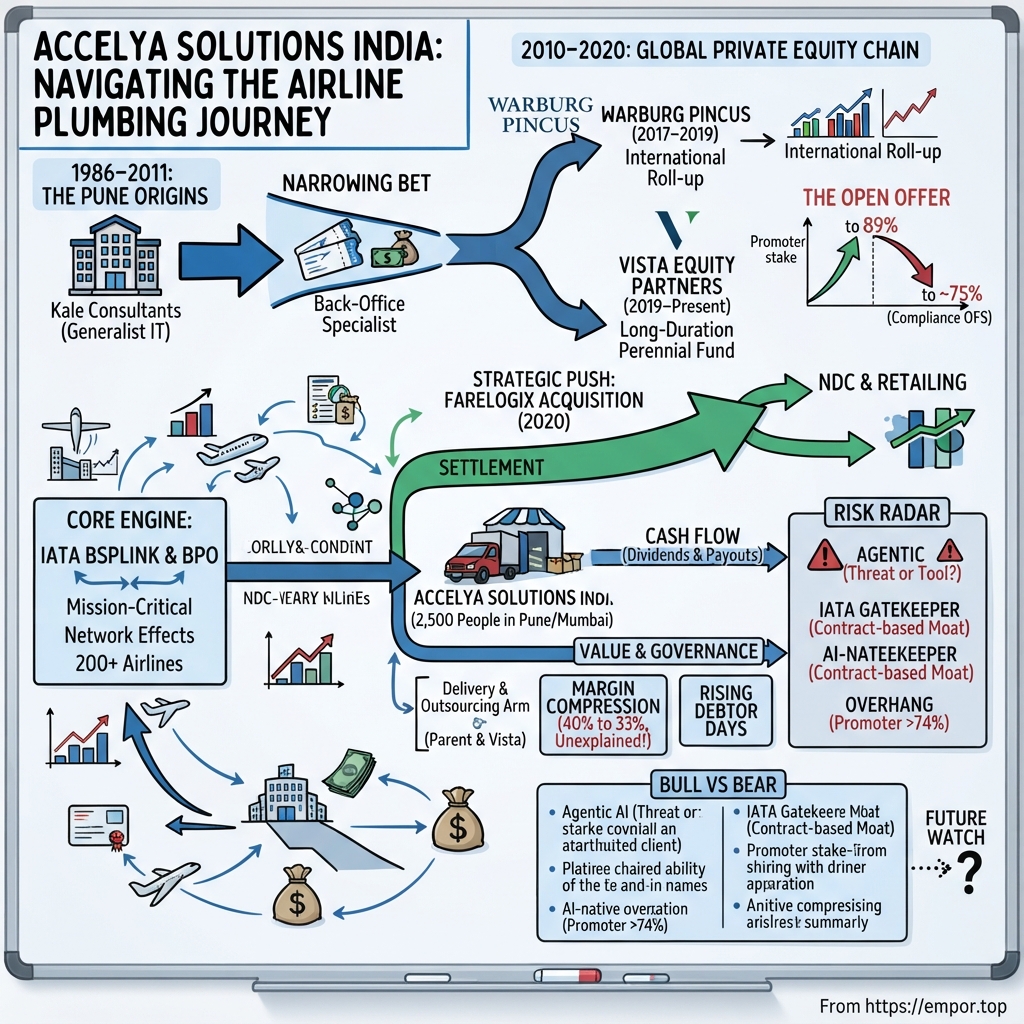
The story moves through four parts. It starts with the origin: an Indian IT services company that bet everything on one unusual vertical. Then comes a sequence of private equity owners that turned that company into the delivery arm of a global airline software roll-up. After that, the story looks at how this "subsidiary of a subsidiary of a subsidiary" produces returns on capital most software companies would envy. Finally, it asks what all of this means for the minority shareholder, who owns a slice of the cash flow but none of the steering wheel.
 Subscribe on LinkedIn
II. Origins: From Kale Consultants to Airline-Only Specialist (1986–2011)
Pune in the mid-1980s was a city of engineering colleges, auto-component plants and defence establishments, not yet the IT hub it would become. Kale Consultants Limited was founded there in 1986 as a general enterprise IT services firm, one of many small Indian software houses trying to sell programming talent to anyone who would buy it.5 It had no obvious edge. Generalist IT services is a business in which a firm's main asset walks out of the door every evening and a competitor can hire it away the next morning.
The narrowing bet
What made Kale different was a decision to stop being a generalist. Around the turn of the millennium, the company moved almost entirely into technology and services for airline "back office" functions: revenue accounting, the processing of BSP settlement data, fare proration between carriers on interline tickets, and commission management for agents.56
In plain English, revenue accounting answers a surprisingly hard question: when a passenger flies Mumbai–Frankfurt–Toronto on one ticket across two airlines, who earned how much? Fares are sold in one currency, flown in segments, discounted by agents, refunded in part, and taxed at several borders. Each airline has to recognise its revenue correctly, bill its partners, and audit agents who may have under-collected. This is tedious, rules-heavy, high-volume work, the kind that is worth outsourcing to a specialist and very expensive to get wrong.
Why airlines, of all things
Airlines are one of the few industries where a neutral, shared processor makes more structural sense than every company building its own system. Hundreds of airlines and many thousands of agents all have to settle with one another, and bilateral arrangements between every pair would be chaos. That is why IATA created the BSP clearinghouse in the first place. A vendor that sits inside that shared plumbing is plugged into a network, rather than selling a standalone tool.
Absorbed into a global roll-up
The founders' company did not stay independent. Around 2010–2011, Spain-headquartered Accelya Group acquired control of Kale Consultants, which triggered the first of several open offers to Indian public shareholders.7 The company was renamed Accelya Kale Solutions and later Accelya Solutions India Limited.5
Here the Indian company's identity changed. It stopped being the headquarters of its own strategy and became one important node in a global group. That shift explains almost everything that follows, because from this point on the most important decisions about the business were made by whoever owned the parent.
III. The Private Equity Chain of Custody: Warburg Pincus to Vista Equity Partners (2017–2020)
A private equity deal in a boardroom in New York or Madrid seldom makes headlines in Pune. For ACCELYA's public shareholders, though, each change of ownership at the top of the group set off a legal chain reaction that reached all the way down to their holdings.
Warburg, then Vista
In 2017, Warburg Pincus took control of the global Accelya Group and pushed international expansion and platform investment.6 Two years later came the transaction that defines the company today. In November 2019, Vista Equity Partners agreed to acquire Accelya from Warburg Pincus.8 The deal was reported at roughly $1.5 billion, and it was made through Vista's Perennial fund, a long-duration vehicle designed to hold businesses for longer than a typical five-year buyout cycle.89
That detail matters. A traditional buyout fund needs an exit, and an exit might mean selling the Indian listed stake or taking it private. A perennial fund can simply keep collecting cash. Minority shareholders were no longer dealing with a temporary owner. They were dealing with a patient one.
The open offer, explained
Under India's SEBI takeover regulations, anyone who acquires control of a listed company, even indirectly by buying its foreign parent, must make an open offer to the public shareholders. Think of it as a fairness rule: if control changes hands, minority holders get a chance to leave at a regulated price instead of being stuck with an owner they did not choose.
Vista's acquisition of the parent triggered that obligation for ACCELYA. The offer to public shareholders was executed in early 2020, at a price reported between roughly ₹956 and ₹1,043 per share including interest for the time since the underlying deal.710
The stake that went up, then came down
This is the part minority investors should read twice. Following the open offer and further acquisitions, the promoter's shareholding rose to as high as about 89% by late 2020.104 India requires listed companies to have at least 25% public shareholding. At 89%, the promoter was well above the cap. Market participants on investor forums read the spike as a possible prelude to a full delisting.10
What actually happened can be checked in the record. In June 2021, the promoter sold shares through an offer for sale (OFS) on the exchange. Business Standard reported that the stock rebounded 16% from the day's low on strong demand for that OFS.11 By early 2022, promoter holding had fallen back to about 75%. It has stayed at 74.66% since then, including through mid-2026.4
The outline for this story raised a historical question: was there a formal, abandoned delisting attempt through reverse book-building, or just a required sell-down? In the sources available here, the observable record is an open offer that took the promoter above the public-float ceiling, followed by an OFS that brought it back down to comply. A formal delisting offer that failed is not visible in the documents reviewed for this article. The accurate verdict is that the mechanics look like a compliance sell-down, and the delisting interpretation was market speculation rather than a documented attempt.
That distinction matters for governance, but it does not change the lesson for a minority holder. The controlling shareholder has once held nearly nine-tenths of the company, and it still owns more than 74%. Taking the company private remains an open option. That option caps the upside of any re-rating argument and hangs over price discovery. This is the first place where the stock might disappoint a public investor, even if the underlying business does fine.
IV. The Farelogix Bet: Buying What Sabre Was Blocked From Buying (2020)
In a US federal courtroom in Delaware in early 2020, and in the offices of the UK's Competition and Markets Authority, regulators were fighting over a small Miami software company that most travellers had never heard of. Farelogix built technology based on NDC (New Distribution Capability), IATA's newer standard that lets airlines sell fares, seats and extras directly with rich content, rather than through the rigid, decades-old formats used by the global distribution systems.
The deal that couldn't happen
Sabre, one of the big GDS operators, had agreed in 2018 to buy Farelogix for about $360 million.12 The US Department of Justice challenged the merger on the theory that Sabre would be buying a nascent competitor that could otherwise erode its distribution toll. The UK CMA blocked it outright in April 2020, and Sabre and Farelogix abandoned the deal.12 (In a twist, the US court actually ruled against the DOJ, but the UK prohibition was enough to kill the transaction.)
The sponsor that could
Within weeks, on June 16, 2020, Accelya announced that it would acquire Farelogix itself, and it later completed the deal.1314 Kirkland & Ellis advised Vista and Accelya.15 The episode made a live experiment of a strategic question. A dominant strategic buyer could not own this asset for competition reasons, but a financial sponsor's portfolio company, which was not a GDS, could.
The purchase price for the Accelya–Farelogix deal was not disclosed in the sources reviewed.1316 That means there is no reliable way to say whether Accelya bought cheaper than Sabre's $360 million. Buying in the middle of the pandemic, in the spring of 2020, with the only obvious strategic bidder legally barred, points toward a buyer's market, but that is inference, not evidence.
Strategic logic and a scoping warning
Strategically, Farelogix pushed the Accelya group out of pure back-office settlement and into front-end airline retailing and order management.16 That diversified the group, but it also moved it into territory held by Sabre, Amadeus and IBS Software, where competition is much tougher than in settlement processing.
The most important point for ACCELYA shareholders is structural: this acquisition was made at the level of the global Accelya Group, not by the Indian listed company. The listed entity does not do its own M&A. It delivers work for the group. So when an investor asks about "management's capital allocation", the real capital deployment decisions (buying Farelogix, funding platform investment) are made above the listed company, by Vista. The Indian company's role is to execute and to pay dividends.
V. The Core Engine: Airline Financial & Commercial BPO — Industry, Competitors, Economics
Walk into an Accelya delivery floor in Pune or Mumbai on a Monday morning and it looks nothing like a romantic picture of the airline business. There are no aircraft and no uniforms. There are screens full of ticket coupons, agency sales reports, exception queues and reconciliation files. An airline in Latin America has a proration dispute with a European partner. An agency sales report has not balanced. A cargo waybill has been billed at the wrong weight. Each of these is small, but there are millions of them, and they carry real money.
What the listed company actually does
Accelya Solutions India works as a delivery and outsourcing hub for the global group, with roughly 2,500 people.3 Its work runs through transaction processing, hosted software and managed business process services for the group's airline customers. That includes revenue accounting and proration, BSP-related processing, invoicing and commission management, cargo revenue management tools and, after Farelogix, some delivery work on NDC order management.36
The group describes itself as serving more than 200 airlines and says its platforms process large volumes of airline revenue, often cited at over $100 billion a year.16 These are company-disclosed figures and have not been independently audited. They indicate scale, not a verified market share.
The IATA relationship: the closest thing to a moat
The most valuable single asset in this story is Accelya's role as operator of BSPLink, IATA's platform for distributing and viewing BSP settlement data.12 In 2024–2025 Accelya and IATA described a deeper collaboration on the future of airline settlement.2
Consider an analogy. If BSP is a stock exchange's clearinghouse, BSPLink is the terminal every broker uses to see their settlements. Tens of thousands of agents and hundreds of airlines have processes, reports and staff training built around it. Replacing it would mean retraining an industry. That is a real switching cost and a real network effect, and it means that the group's name is stamped on the pipes that carry the airline industry's money.
The honest Helmer test: cornered resource or renewable contract?
Hamilton Helmer's "cornered resource" is an asset a company controls on attractive terms that competitors cannot get. BSPLink does not fully meet that bar. The mandate belongs to IATA, and Accelya operates it under a contract. A single, highly informed buyer can re-tender, split the work, or bring it in-house at renewal.
History cuts both ways here. The relationship has lasted a long time and has deepened rather than weakened, which is evidence of incumbency power.12 Yet the mechanism that would break the moat, an IATA re-bid, has not been tested in public in the materials reviewed, so the moat's strength against it is unproven rather than confirmed. The calibrated conclusion: this is a strong incumbent position with high switching costs, sitting on top of a single counterparty that holds the ultimate bargaining power. Structurally, it resembles a dominant-customer relationship more than a permanent franchise. The event that would confirm or falsify it is simple: the next renewal of the BSPLink mandate, and on what terms.
A further scoping caveat is needed. The IATA contract belongs to the group. The Indian listed company earns from it through the delivery and services work it performs under intercompany arrangements. The moat is therefore one step removed from the minority shareholder, as Section VI shows.
The competitive map
The market is not empty.
SITA, the airline-industry-owned IT and communications cooperative, has a much wider scope (connectivity, baggage, border systems) and overlaps with Accelya around the edges of settlement and data.
IBS Software, which originated in Kerala, is larger and centred on passenger service systems and full-service airline operations. It is an adjacent threat rather than a head-on rival in revenue accounting.
Amadeus and Sabre are the GDS giants. Industry estimates put global GDS share at roughly 40% for Amadeus, 30% for Sabre and 20% for Travelport. These companies have vastly greater scale than Accelya, and after the Farelogix block they both showed renewed appetite for NDC and retailing technology. They compete with the Accelya group specifically in the layer Farelogix brought in.
Mercator, Hitit and Comarch are smaller specialists in adjacent revenue accounting, passenger service system and loyalty niches. Their existence is evidence that airlines have credible alternatives, which undermines any claim of an absolute moat. Airlines can and do use several vendors.
Economics: the annuity claim
In theory, the model is attractive. Revenue is recurring, largely driven by transactions and usage, and tied to multi-year contracts. Costs are mostly people and infrastructure. That should produce a stable annuity that rises with air traffic. Section VI tests that theory against the reported numbers, and the numbers only partly cooperate.
A foreshadowing: AI as tool and threat
The group has started calling itself an AI-forward vendor. It has announced agentic AI work with AWS in airline workflows, Vista's portfolio-wide "Agentic Factory" programme, and AI features in sales audit.17 That is a credible move. It is also a quiet admission that the labour-heavy processing model behind today's margins is exactly what automation compresses. Section VIII takes up that tension.
VI. Who Actually Owns This Cash Flow: Captive Subsidiary Economics and the Dividend Machine
Every spring, ACCELYA's board meets and recommends a dividend. For FY26 the final dividend recommended was ₹35 per share.4 Most of that money goes to Madrid, to Accelya Holding World S.L.U., and from there up a chain of holding companies to Vista.34 Minority shareholders get their proportionate share of the same cheque. It is a clean, generous arrangement, and it tells an investor more about what this company is than any strategy slide.
The structural fact
ACCELYA is 74.66% owned by Accelya Holding World S.L.U., which sits within the "Canary Topco" ownership chain controlled by Vista.34 The right mental model is not "Indian airline software company." It is "outsourcing and delivery arm of a global private company, with a public minority attached."
Related-party dependence
The company's revenue and costs run heavily through intercompany agreements with Accelya Group entities. Related-party filings have disclosed arrangements covering distribution of group IP, collection-management services and shared amenities and expenses.183 The exact share of revenue that comes from related parties is set out in the related-party note of the annual report. This article has not independently extracted that percentage, so it is treated here as a key figure to be checked rather than a number to be stated.
The reason it matters is transfer pricing. When a big share of revenue is priced between a parent and its subsidiary, the "market" setting margins is partly the controlling shareholder's own policy, within tax and arm's-length limits. Margin changes may therefore reflect decisions in Madrid as much as competition in the market.
The numbers that tell the story
Revenue has crept up rather than compounded. Consolidated sales were about ₹469 crore in FY23, about ₹511 crore in FY24, about ₹529 crore in FY25 and about ₹532 crore in FY26.4 The last two years amounted to growth in the low single digits, below the growth rate of global air travel volumes after the pandemic recovery.
Profit swung much more. Net profit was about ₹127 crore in FY23, dropped roughly a quarter to about ₹94 crore in FY24, recovered to about ₹129 crore in FY25, and fell back to about ₹95 crore in FY26.4 A business sold as a recurring annuity has had two drops of about 25% in three years.
Operating margin fell from about 40% to about 33% over the same period, while revenue rose.4 This is the most important number to question. There are three possible explanations, and they have very different implications:
- Wage and delivery cost inflation in Indian tech talent. This is real and industry-wide, but a firm with pricing power passes it on.
- A change in intercompany pricing set by the parent. This is a governance question, not an operating one.
- Real pricing pressure in the core processing business. This would weaken the moat thesis.
In the September 2024 analysts' meet, management discussed the business mainly in terms of group strategy, product transition and investment in technology.19 The sources reviewed do not contain a clean decomposition that divides the margin decline among these three causes. An honest reading is that the "cost pressure" explanation remains unquantified in public, and the burden of proof lies with management. Until a call or filing separates wages, transfer pricing and customer pricing, the margin decline should be seen as unexplained rather than explained.
Occasional one-off items, such as tax matters and exceptional charges, also affect some years' profits, which is part of why the profit line swings more than revenue. Investors should read the notes to the accounts before extrapolating any single year.
Working capital: debtor days drifting out
Receivable days increased from about 67 to about 84.4 For a company whose largest counterparties include its own group, that raises a governance-relevant question. Is the parent taking longer to settle intercompany balances, or are airlines paying more slowly? The first would amount to a quiet transfer of working capital from minority shareholders to the controller. The second would be ordinary credit stress. The sources reviewed do not answer the question, so it stays open, and it is worth tracking.
The dividend machine
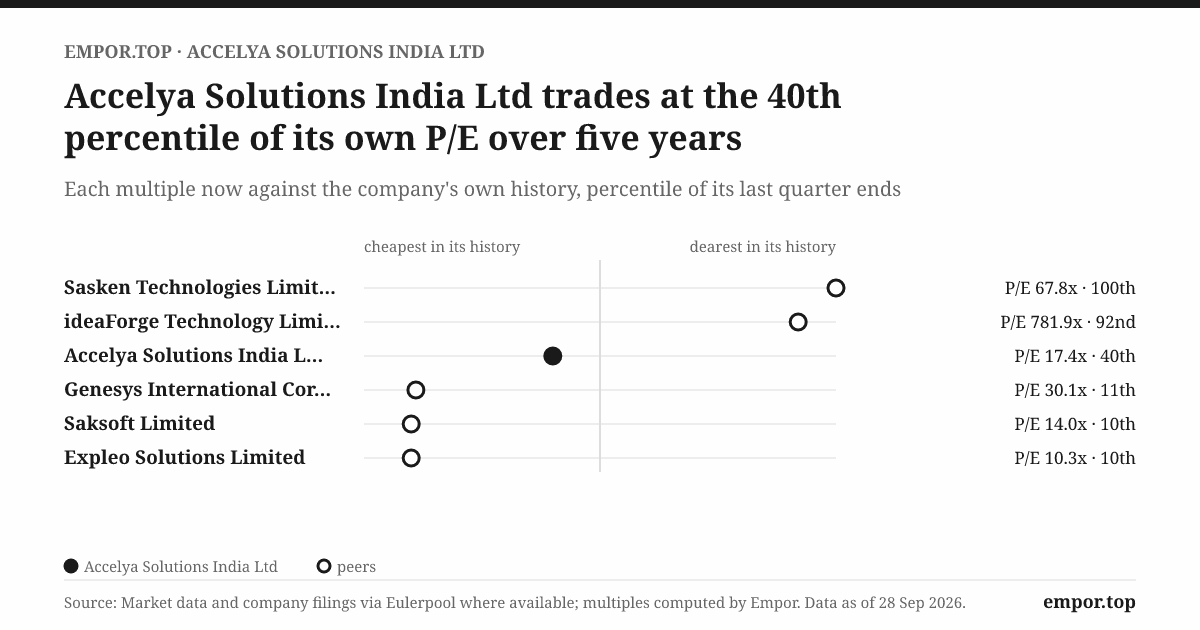
Historically, the payout ratio has ranged very widely, from about 17% to about 184% of profit. Recently it has been around 55%, and the yield is about 4%.4 The company is almost debt-free, with ROE of 39–42% and ROCE of about 49%.4
There are two readings.
The discipline reading: a mature, capital-light delivery business does not need much reinvestment, so returning cash is the right choice. Hoarding cash in India would earn low returns and invite pressure from the controller.
The extraction reading: growth investment happens above the listed company. Farelogix was bought with group and Vista capital, not ACCELYA's retained earnings. The Indian subsidiary therefore acts as a cash source whose job is to send money up the chain. The high ROE is partly a sign that equity is kept lean because retained capital has nowhere of its own to go.
These two readings are not mutually exclusive. The evidence fits both: the high payout is rational given where growth capital actually goes, but it confirms that ACCELYA is not the vehicle through which the group compounds. A minority holder is buying a yield stream with limited growth, not a stake in the group's growth.
The market's verdict
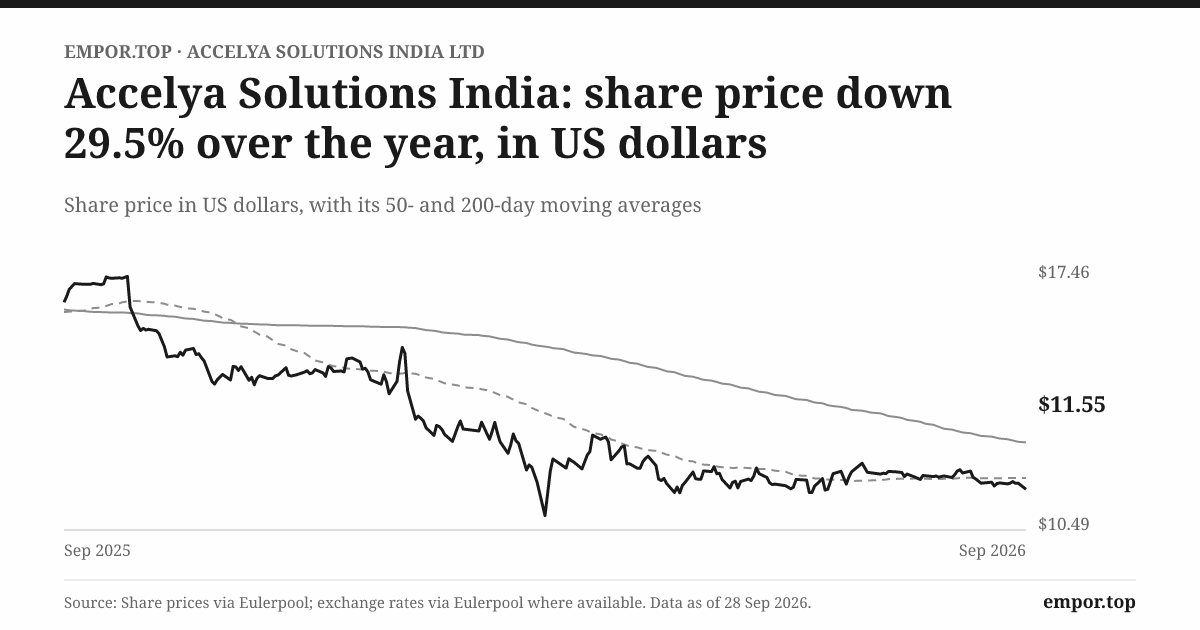
Foreign institutional holding fell from 4.99% in 2017 to 0.11% in 2026.4 That is a clear and measurable vote. Specific public explanations for these exits were not found in the sources reviewed. The plausible causes include a small free float, limited liquidity, the ownership overhang and slow growth, but these are inferences. The fact itself stands: sophisticated foreign capital has almost completely left.
VII. Management Today: Gurudas Shenoy and the Post-Founder Era
In July 2022 the managing director's chair at the Pune company went to someone whose career had been built reading ledgers rather than writing code.
The finance-track insider
Gurudas Shenoy became Managing Director in July 2022.3 He had spent about seventeen years within the Accelya group. He was CFO of the Indian listed entity until February 2021, then moved to the group, where he served as regional CFO for the Americas, with responsibilities that included Farelogix.3 He was not a founder, not an outside turnaround executive and not a product visionary. He is a finance professional promoted from within a system that he knows inside out.
That background fits the role. The listed company does not need a dealmaker, because the deals happen above it. It needs someone who can manage delivery costs, renew contracts, keep intercompany arrangements clean and satisfy auditors. It is reasonable to judge him as an operator of a captive delivery business, not as a capital allocator.
Incentives and skin in the game
In the past, investor-forum scrutiny has noted that executives' personal shareholdings in the listed entity are small next to the ~75% promoter block.10 Current-year remuneration and executive shareholding details are in the annual report's corporate governance and remuneration disclosures.3 The structural point does not depend on the exact numbers: the incentives of senior management, who are group employees, are primarily aligned with the group, and only secondarily with the listed company's minority float.
The credibility test
With a finance insider in charge, three questions matter most.
Guidance discipline. The company does not give formal numerical guidance in the way that Indian IT majors do. That shields it from missing targets, but it also leaves investors fewer promises against which to measure delivery.
Explaining the margin decline. As Section VI noted, the public materials reviewed do not break down the 40%-to-33% margin slide by cause.19 A finance-track leader is well placed to give that breakdown. Its absence is a data point in itself.
Consistency on payouts. The swing in payout ratios over time, from far below profit to far above it, shows a dividend policy shaped by the group's cash needs and one-off events rather than a fixed formula.4 The AGM proceedings record routine resolutions passing with the promoter's vote dominating, as would be expected with a 74.66% holder.20
The overall judgment is that Shenoy's record as MD is still short and made mostly of stable delivery, with no stumbles recorded in the sources reviewed, but also with no clear explanation of the most important trend in the numbers. The case for his credibility is intact but unproven. The event that would change that is a quarter in which management explains the margin mix in concrete terms.
VIII. Risk Radar: The AI Question, the IATA Gatekeeper, and Working Capital Strain
Consider a revenue accountant in 2016, matching coupons to sales reports line by line. By 2026, much of that matching is automated. Now picture an AI agent that can read a proration dispute, apply the interline agreement, draft a correction and flag only the true exceptions to a person. That is the tool Accelya says it is building.17 It is also a description of fewer billable hours of work.
AI: the mechanism, not the buzzword
Industry surveys, including SITA's 2025 airline IT research, show a majority of airline IT leaders now ranking generative AI as a top investment priority. Accelya's announced work with AWS on agentic AI in airline workflows, and its participation in Vista's Agentic Factory, suggest a management team that sees this coming.17
The mechanism of the risk is straightforward. If a meaningful part of revenue scales with processing effort (people and hours per transaction), automation reduces the effort per transaction. If pricing is per transaction and the vendor keeps the savings, margins rise. If customers demand that savings be shared, or a competitor offers AI-native processing more cheaply, revenue per transaction falls. Who captures the productivity gain comes down to the bargaining power discussed in Section V. It is worth noting that announcements of pilots are not revenue. The test is whether AI shows up in reported margin or contract wins, not in blog posts.
The IATA gatekeeper
Section V described the BSPLink relationship as a strong but contract-based incumbency. The risk to monitor is concrete: any IATA tender activity, public IATA comments on vendor strategy, or a competitor's win in adjacent settlement infrastructure.
Governance and minority risk
Three elements together create governance risk that is separate from operating risk: ownership of more than 74% by a financial sponsor, a documented episode in which the promoter's stake rose to about 89%, and heavy dependence on related-party revenue.41118 The practical safeguards are Indian rules requiring certain material related-party transactions to be approved by non-related shareholders, AGM voting patterns, and auditor reporting (including CARO annexures).203 No auditor qualifications were identified in the documents reviewed, which does not mean none will ever arise.
Working-capital strain
The increase in debtor days from about 67 to about 84 is the most tangible early-warning indicator here.4 If receivables continue to lengthen, the question of whether the parent is slow-paying will become more pressing.
Demand cyclicality
The revenue depends on airline transaction volumes. Fuel shocks, pandemics and airline failures flow straight into it. The 2020 pandemic, when global air traffic collapsed, is the clearest recent test of that. For all its "utility" language, this business is exposed to the cycle.
Cyber and data
The company processes airline financial settlement data at global scale, so a breach or major outage would be serious both reputationally and contractually. No specific incident was identified in the sources reviewed. This remains a standing structural risk rather than an active event.
IX. Bull vs Bear — The Investment Case Stress-Tested
Imagine two investors meeting in a café in Pune's Koregaon Park. One holds a printout of return ratios, the other a printout of the shareholding pattern. Both are right about their printouts.
The bull case
The business sits inside mission-critical, IATA-linked airline infrastructure, in a niche that few competitors are eager to enter. ROE is around 40% and ROCE around 49%, and there is almost no debt.4 Revenue is recurring and contract-backed. The dividend yield is about 4%.4 Management is moving early on AI rather than waiting.17 And a patient controller (a perennial fund) is less likely to force a disruptive sale.9
The bear case
Revenue growth has slowed to low single digits while operating margins fell from roughly 40% to 33%, without a clear public explanation.4 Profit has dropped by roughly a quarter twice in three years. The group's growth investments, such as Farelogix, take place above the listed company.13 The FII base has almost vanished.4 The promoter once held about 89% of the company and still owns 74.66%, which leaves a permanent overhang on float and price discovery.411 Debtor days are rising, and the related-party explanation has not been ruled out.
Porter's five forces, briefly
Buyer power: high. IATA is a single, sophisticated gatekeeper, and large airlines use several vendors. Supplier power: moderate. Skilled Indian tech labour is the main input, and wage inflation is real. Threat of substitutes: rising. Airline in-house automation and AI-native processing could substitute for outsourced labour. Threat of new entrants: low in settlement, higher in retailing. Few want to rebuild BSP plumbing, but NDC is contested. Rivalry: moderate in back office, intense in front office, where Amadeus, Sabre and IBS operate.
Helmer's 7 Powers, applied
Switching costs: present and real at the group level (BSPLink, embedded revenue-accounting workflows). Network economies: partial, because they belong to IATA's BSP network rather than to Accelya itself. Cornered resource: not established, since the mandate is contracted. Scale economies: moderate within the niche, minor next to Amadeus. Process power: plausible, given decades of rules-heavy processing know-how, but AI threatens to make that know-how easier to copy. Brand and counter-positioning: weak. Most importantly, all of these powers belong mainly to the group. The listed entity reaches them through transfer-priced agreements.
The activist lens
A skeptical investor or activist would focus on four questions. What share of revenue is related-party, and how is it priced? Why did margins fall seven points while revenue rose? Are group entities paying invoices more slowly? And, given that the group funds its growth elsewhere, would minorities be better served by a fair buyout? The practical difficulty is leverage. With 74.66% promoter ownership and almost no institutional float, minorities have little ability to force answers beyond votes on related-party transactions and questions at the AGM.20
Weighing it
The record does not reject the moat claim. It narrows it. The group's position in airline settlement looks durable, but the listed company's share of that value is determined by the controller, and it has not recently translated into margin expansion or growth. The fairest summary is that the moat is intact but its economics are not currently showing up in margins or growth, and management has yet to show why. What would change that view is a margin that stabilises or recovers along with a transparent account of related-party pricing.
X. Durable Lessons: Investing in Captive Subsidiaries of Global Private Equity
There is a particular kind of listed Indian company that looks like a gift on a stock screener: high ROE, no debt, a fat dividend, a modest valuation. Accelya belongs to that category, alongside a number of other captive subsidiaries of multinational parents. The lessons generalise.
The moat may belong to someone else. When a listed company is the delivery arm of a globally controlled parent, the durable assets (the IATA mandate, the major airline contracts, the product IP) may sit with the group. The subsidiary earns a return set by intercompany agreements, not by its own pricing power.
High ROE with little reinvestment is a recognisable signature. It often indicates a cash-generation vehicle for the parent rather than an independent compounder. That can be a perfectly good investment, but it should be underwritten like a bond with some equity features, not as a growth story.
Antitrust can set the price. The Farelogix episode shows that sometimes the best acquisition opportunity comes from a blocked deal elsewhere in the industry, when the natural buyer is legally barred.1213
Indian takeover rules create observable signals. Open offers, jumps in promoter stake above the 75% ceiling, and forced sell-downs through OFS are public, dated events.711 Careful investors can track them as leading indicators of what a controller intends.
XI. Epilogue & What to Watch
The next ticket issued in Nairobi, Lisbon or Lucknow will still be settled through plumbing in which Accelya plays a central part. That is unlikely to change soon. What is less certain is how much of the value of that plumbing reaches a minority shareholder in Pune.
The KPIs that matter
Three measures carry most of the signal:
- Operating margin trend. Does it stabilise around 33%, recover, or keep compressing? This is the single best test of pricing power and of intercompany pricing.
- Debtor days. Do receivables go back toward 67 days or keep lengthening? This is the clearest indicator for related-party working capital.
- Promoter shareholding percentage. Any move away from 74.66%, up or down, is the key governance signal.
Events to monitor
Quarterly results and analysts' meets, for any concrete breakdown of the margin decline. News of any IATA BSPLink renewal or tender. Any new open offer, OFS or delisting proposal from the promoter group. Evidence that the agentic AI initiatives are turning into revenue or measurable cost savings, as distinct from pilots. And the trends in FII and DII ownership.
This is ultimately a story less about a product or a founder than about what it means to own a minority stake in the cash-generating engine of someone else's global strategy. The infrastructure is durable, the growth is uncertain, and the controlling shareholder's interests may not always run parallel to those of the public float.
References
-
Accelya & IATA Strengthen Partnership for Airline Settlement — Accelya press release ↩↩↩↩
-
39th Annual Report FY2024-25 — Accelya Solutions India Limited (NSE filing), 2025-10-13 ↩↩↩↩↩↩↩↩↩↩
-
Accelya Solutions India Ltd. — company financials, shareholding pattern, ratios — Screener ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Accelya Solutions India Limited — Investor Relations — Accelya ↩↩↩
-
Annual Report 2020-21 — Accelya Solutions India Limited ↩↩↩↩
-
Public announcement / open offer document, Accelya Kale Solutions — SEBI ↩↩↩
-
Accelya Announces Acquisition by Vista Equity Partners — Accelya press release, 2019 ↩↩
-
Accelya Kale Solutions — Niche & Sticky Business — ValuePickr Forum ↩↩↩↩
-
Accelya rebounds 16% from day's low on strong response for OFS — Business Standard, 2021-06-10 ↩↩↩↩
-
M&A deal of the month: After Sabre-Farelogix, the Accelya-Farelogix saga — Edgar, Dunn & Company ↩↩↩
-
Accelya to Acquire Farelogix — BusinessWire, 2020-06-16 ↩↩↩↩
-
Accelya Completes Acquisition of Farelogix — Accelya press release, 2020 ↩
-
Kirkland Represents Vista Equity Partners and Accelya on Acquisition of Farelogix — Kirkland & Ellis, 2020-06 ↩
-
After Sabre-Farelogix: deal analysis — Edgar, Dunn & Company ↩↩
-
Accelya and AWS bring Agentic AI into Airline Workflows — Accelya ↩↩↩↩
-
Covering Letter — Related Party Transactions, 30 June 2021 — Accelya (BSE filing) ↩↩
-
Transcript of Analysts Meet, 12 Sep 2024 — Accelya Solutions India Limited, 2024-09-12 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube