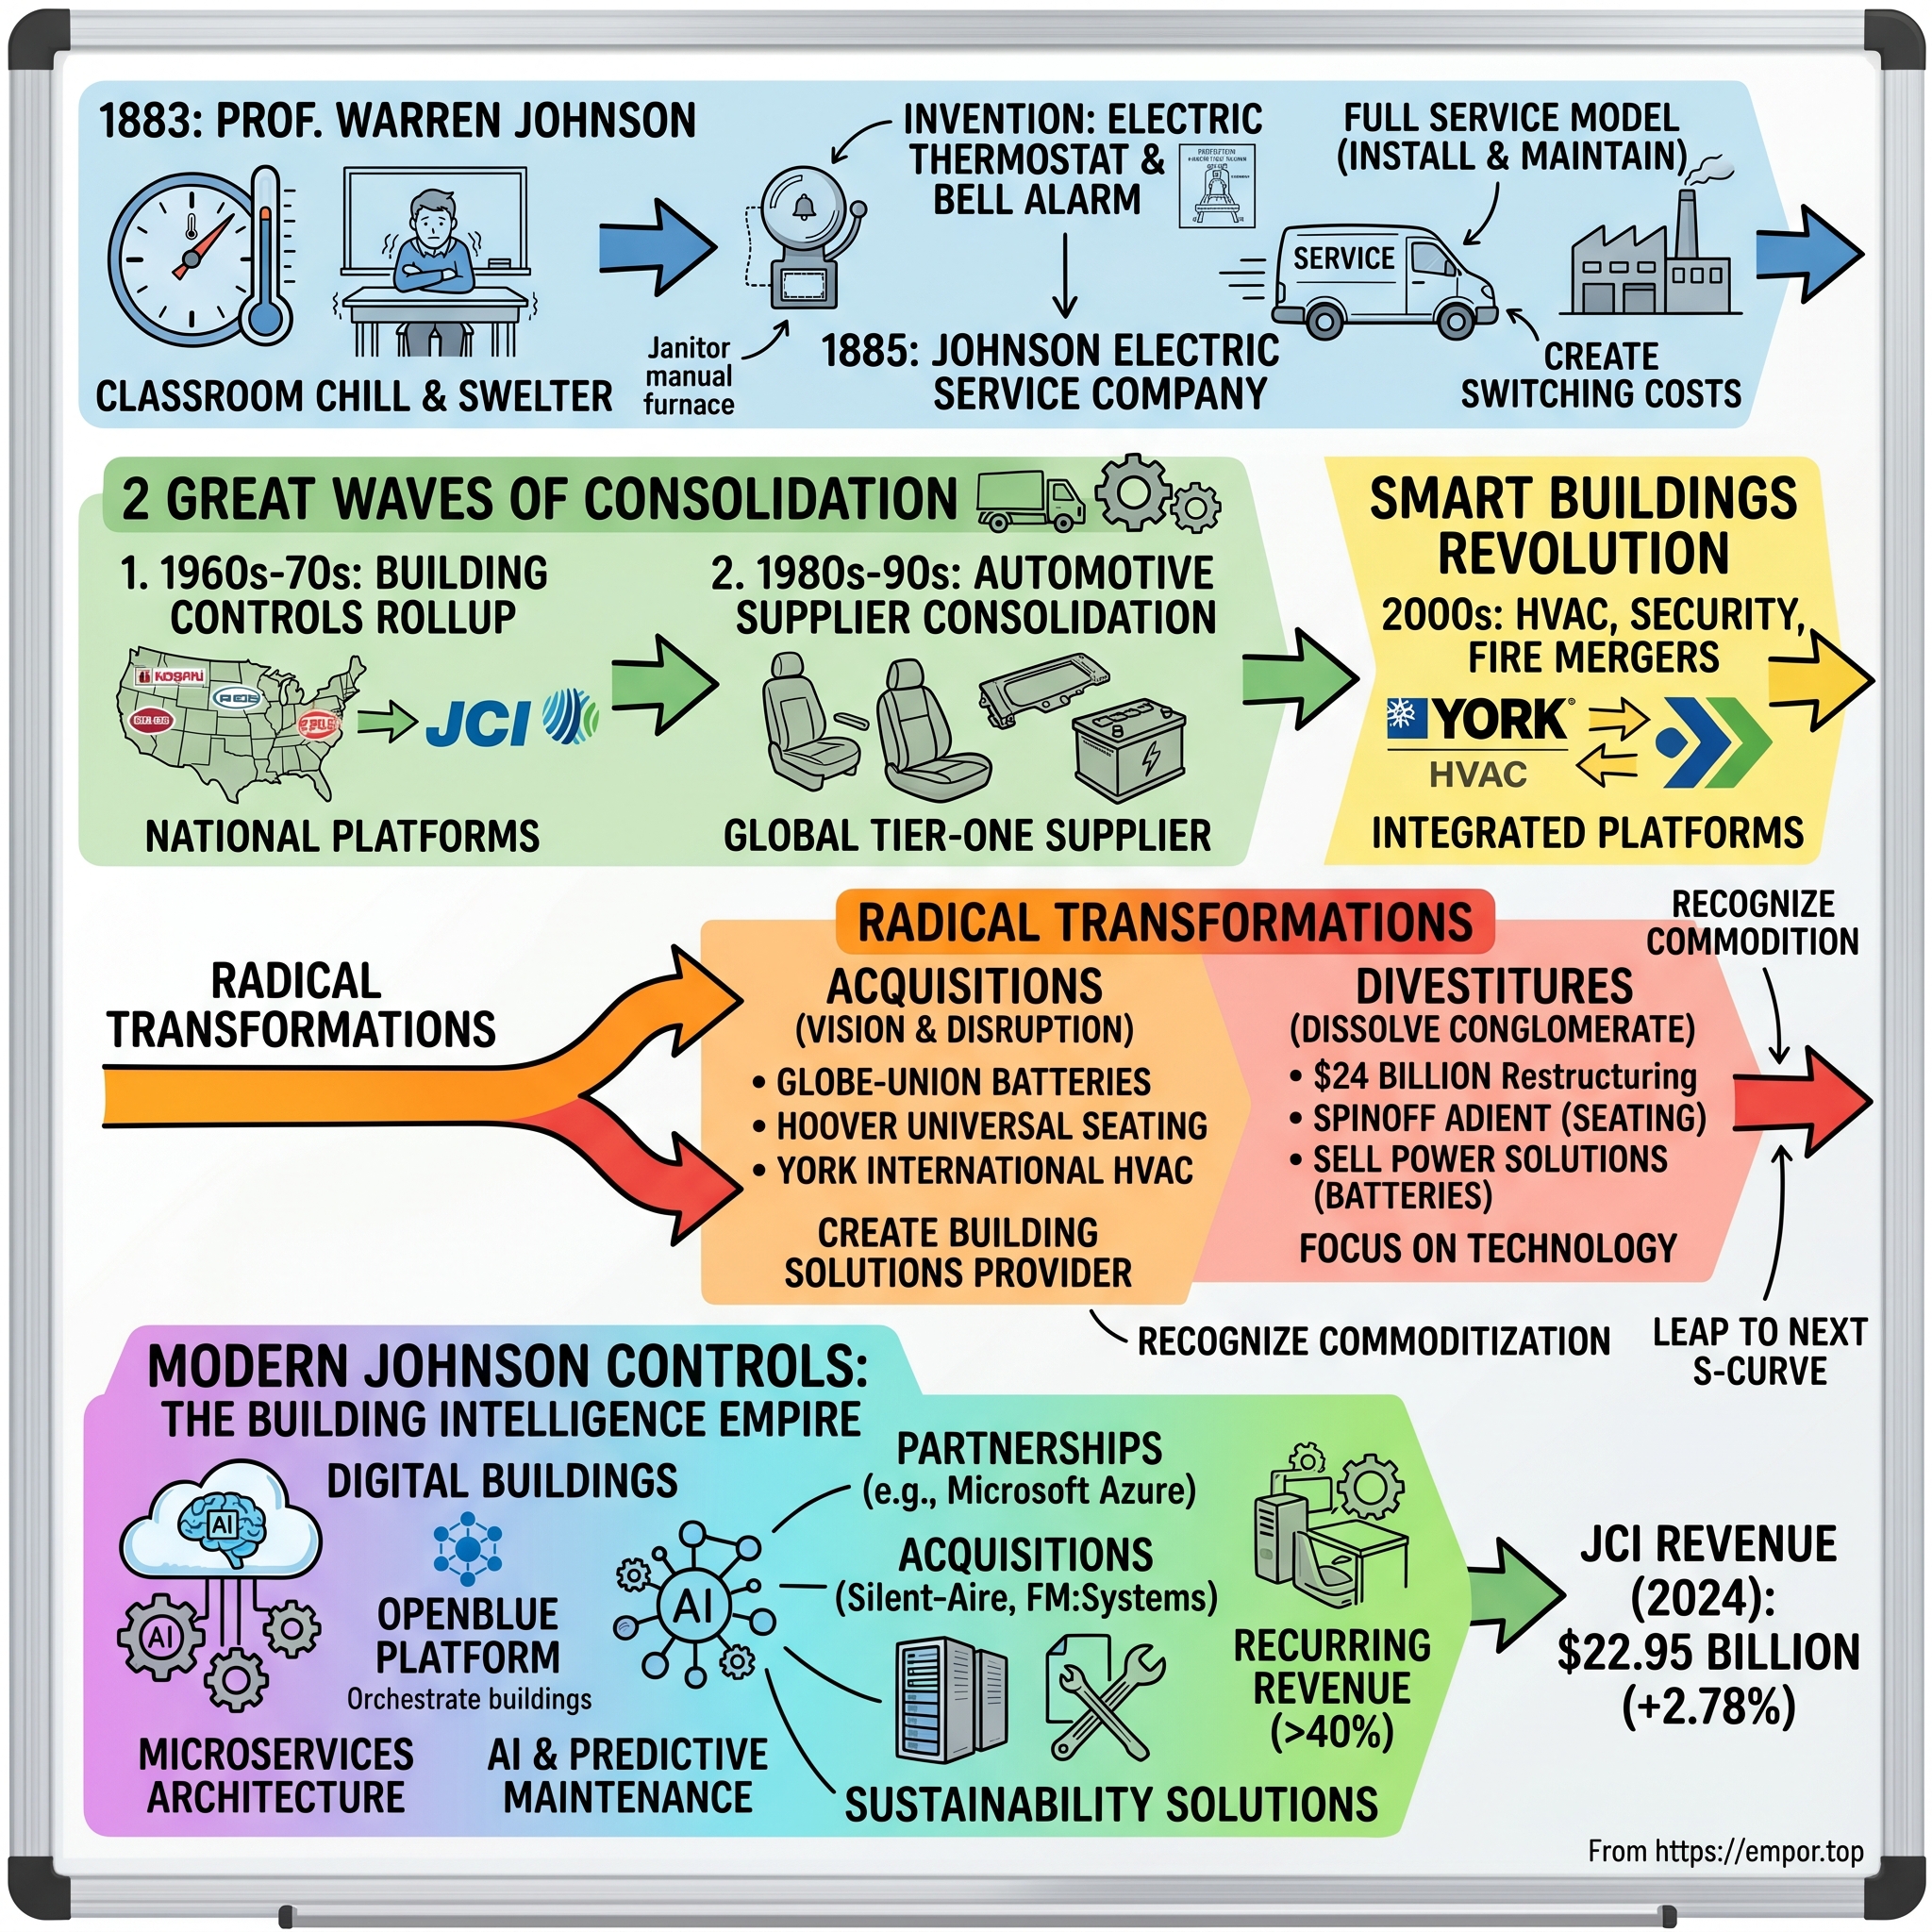
Johnson Controls: The 140-Year Reinvention of Building Intelligence
I. Introduction, Thesis & The $100 Billion Building Question (15–20 min)
The Machine Inside the Building
Stand on the roof of a hyperscale data center in northern Virginia on an August afternoon, and the first thing you notice is the noise. It is not the servers; those are sealed away below. It is the cooling plant: rows of chillers, air handlers the size of shipping containers, and pumps pushing chilled water through continuous loops. If that cooling fails for more than a few minutes, processors overheat, and a facility worth billions of dollars becomes an inoperable oven. Hospitals, semiconductor fabs, research labs, and airports operate on the same principle. Every modern commercial building is essentially a machine for moving heat, air, and water, monitored by sensors, valves, fire alarms, and access controls.
Johnson Controls International plc (JCI, listed on the NYSE) sells, installs, and services much of that critical machinery. In fiscal 2025, which ended September 30, 2025, continuing operations generated $23.6 billion of sales, up 3% on a reported basis and 6% organically.1 That revenue is spread across three regional segments—Americas, EMEA, and APAC—and a product lineup that includes York chillers, Metasys building controls, Simplex fire alarms, Tyco fire suppression, and a portfolio of security brands.2 The company is legally incorporated and headquartered in Cork, Ireland, while its North American operations remain rooted in the Milwaukee area, where the whole story began.23
The Central Question
The central question is how an enterprise founded in 1885 around a Wisconsin professor's thermostat spent the next 140 years drifting away from that core invention before fighting its way back. Over that span, Johnson Controls evolved from a pioneer in pneumatic temperature regulation into the country's largest automotive battery manufacturer, a major supplier of automotive seating, the vehicle for a politically contentious Irish tax inversion, and ultimately, under activist pressure, a focused commercial buildings company. Each pivot possessed its own strategic rationale at the time. Yet the cumulative outcome was a business that owned premier brands in building technology while persistently trailing its purest rivals in operating margins and market valuation.
The Core Paradox
The paradox is straightforward. Johnson Controls possesses marquee brands, an expansive installed base, and what management describes as a field sales and technician organization "roughly twice the scale of our nearest competitor."4 Yet throughout most of the 2016–2024 period, the company lagged behind Trane Technologies (TT) in operating profitability. In calendar 2025, Trane reported an adjusted operating margin of 18.5% on $21.3 billion of revenue.5 Johnson Controls, by contrast, routinely posted GAAP earnings well below its adjusted figures, weighed down by serial restructuring charges, a major ransomware attack, a costly PFAS environmental settlement, and the overhead of managing businesses it would ultimately divest.
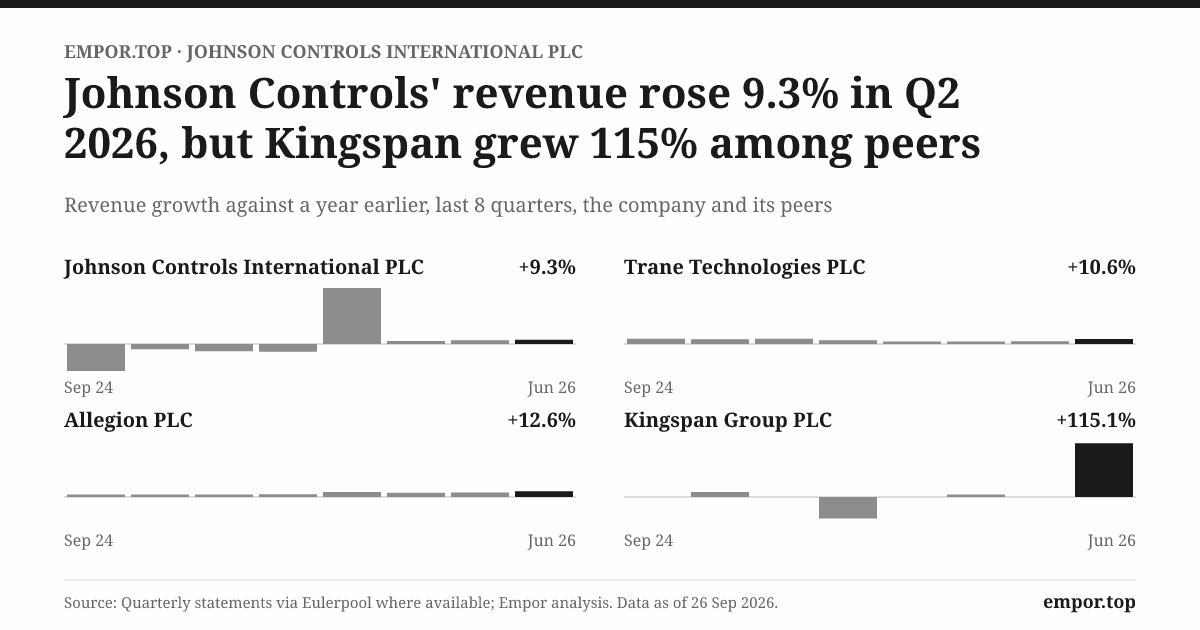
That track record frames the central dilemma of 2026. In July 2026, management raised its fiscal 2026 outlook for the third time, guiding to roughly 8% organic growth and adjusted earnings per share of about $5.05, representing roughly 35% growth over the prior year.6 Accelerations of that magnitude are rare for a 140-year-old industrial manufacturer. They raise an essential question for investors: is this the long-promised operational turnaround finally taking hold, or is Johnson Controls simply riding a cyclical wave of demand for cooling equipment at the peak of an AI data center construction boom? The evidence indicates that both forces are at work, and determining their relative contribution is critical to evaluating what the business is actually worth.
The Roadmap
Four themes run through this story. First, while HVAC and building controls appear to be equipment-manufacturing operations, they function economically like local service businesses, where route density, labor productivity, and technician retention determine operating margins. Second, the multi-decade detour into automotive batteries and seating created an unwieldy conglomerate that required decades of divestitures to undo. Third, a persistent gap developed between top-down financial engineering—exemplified by the 2016 Tyco tax inversion—and the field-level execution required to generate sustained cash flow. Fourth, an operational reckoning culminated in 2024, when Elliott Investment Management accumulated a stake exceeding $1 billion, the company agreed to sell its residential HVAC business to Bosch for $8.1 billion, and the board appointed Danaher veteran Joakim Weidemanis as chief executive officer.789
For investors, the issue is not whether Johnson Controls owns quality assets; its market positions are well established. The question is whether the company can finally translate those assets into consistent, peer-level financial performance, and whether the operational improvements recorded since 2025 reflect structural organizational discipline or merely the tailwind of an unprecedented data center investment cycle. Exploring that balance requires returning to the beginning: a cold classroom in Whitewater, Wisconsin.
 Subscribe on LinkedIn
II. Warren Johnson & The Pneumatic Age (1883–1960s) (20–25 min)
A Professor, a Janitor, and a Bell
In the early 1880s, Warren S. Johnson taught at the State Normal School in Whitewater, Wisconsin. He had worked as a printer, surveyor, schoolteacher, and school superintendent before joining the faculty in 1876.10 The school was heated by steam, and temperature was managed the way it was in most facilities at the time: a janitor walked the hallways, judged whether a classroom was too hot or too cold, and walked down to the basement to adjust the boiler dampers. The process was slow, imprecise, and continually uncomfortable for students and staff.
Johnson's insight was to allow the room to register its own needs. In 1883, he patented the "electric tele-thermoscope," a bimetallic device that sensed ambient room temperature and rang a bell in the basement to alert the janitor when adjustments were required. The Encyclopedia of Milwaukee describes it as the first room-situated thermostat.3 Though mechanically simple, it established a foundational architectural principle: a building could monitor its internal state and signal its operational requirements. Modern building management systems, from Metasys controllers to hyperscale data center chilled-water plants, remain direct descendants of that concept.
Money from Milwaukee
Commercializing that technology required external capital. Johnson secured backing from William Plankinton, a prominent Milwaukee businessman who served as the first president of the Johnson Electric Service Company, established in 1885.11 The enterprise was later renamed the Johnson Service Company in 1902.3 Plankinton led the organization until 1901, when Johnson assumed the presidency himself.11
The decisive product innovation was not the electric bell, but the automated mechanism that succeeded it. Johnson developed pneumatic control systems that used compressed air to actuate valves and dampers directly, removing manual labor from the operating loop.10 The installation functioned as a building's primitive nervous system: a wall thermostat sensed temperature shifts, minute variations in air pressure routed signals through narrow copper tubing embedded in the walls, and a mechanical actuator in the basement modulated steam valves. It operated entirely on mechanical physics, without microprocessors or electrical wiring.
The durability of that architecture proved remarkable. Pneumatic systems were mechanically robust, inexpensive to maintain, and exceptionally reliable; thousands of commercial and civic buildings continued operating on compressed-air lines decades after solid-state electronic controls reached the market. Yet that longevity cut both ways. While it secured an enduring, annuity-like maintenance base, it also meant that each major industry platform transition—first from pneumatics to analog electronics, and later to networked digital building automation—forced property owners to reevaluate their vendor relationships. Every hardware replacement cycle opened the door to competing equipment makers.
The Pneumatic Moat
That dynamic established the commercial model for commercial building technology. Once pneumatic tubing was routed behind plaster walls and through floor slabs, the original installer held a structural advantage whenever the facility required maintenance, recalibration, or system expansion. Removing functional infrastructure to replace an incumbent vendor was economically impractical. This dynamic established a recurring economic reality of the industry: initial equipment installations operate largely as customer-acquisition vehicles, while the compounding profitability of the business resides in decades of downstream aftermarket service.
A Restless Inventor
Warren Johnson was an inveterate tinkerer who resisted remaining confined to temperature controls. Over his career, he secured more than 50 patents, investing capital into pneumatic tower clocks, gasoline engines, and early horseless carriages. He reportedly became the first person to receive a U.S. government contract to deliver mail via motor vehicle.10 The Encyclopedia of Milwaukee notes that he operated "a successful steam and gasoline automobile business" prior to his death in 1911.3
Following Johnson's death, his executive successors enacted an operational retrenchment that prefigured the modern company's challenges. They dismantled the peripheral automotive and mechanical ventures, focusing capital exclusively on commercial temperature regulation.3 That early portfolio rationalization took place prior to World War I. Harry Ellis served as president from 1912 to 1938, followed by Joseph Cutler from 1938 to 1960—a period of executive continuity that steered the core controls enterprise intact through the Great Depression and the Second World War.11
Why This Matters Today
This foundational era was more than an industrial prelude. It established three enduring structural pillars: control of the core sensing and actuation layer, sticky customer relationships where service revenues dwarf initial equipment sales, and deep technical authority among the specifying engineers who design commercial facilities. Crucially, it also revealed a recurring vulnerability: an executive inclination toward adjacent hardware markets that absorbed capital and executive focus away from the core controls enterprise. Managing that friction would define the next century of corporate evolution.
III. The Minicomputer Breakthrough & The Conglomerate Detour (1970s–1990s) (25–30 min)
From Air Tubes to Silicon
By the late 1960s, the company was prepared to expand beyond its legacy niche in pneumatic regulation. In 1968, it merged with Penn Controls, a transaction that added electrical components, expanded international manufacturing facilities, and elevated the business into the Fortune 500.310 Penn provided internal access to specialized components previously purchased from third-party suppliers, marking an early phase of vertical integration.
The decisive technological shift arrived four years later. In 1972, Johnson introduced the JC/80, which management described as the commercial building industry's first minicomputer-based automation system, capable of reducing customer fuel requirements by up to 30%.10 Where pneumatic installations operated like localized reflexes—reacting mechanically at the zone level—the JC/80 served as a building's centralized brain. By monitoring temperatures, pressures, and mechanical equipment across an entire property from a single console, it automated supervisory decisions regarding when to stage heating, initiate cooling, or shut down idle equipment.
The Oil Shock Turns a Luxury into an Investment
Macroeconomic conditions soon accelerated adoption. When the 1973 oil embargo drove energy prices sharply higher, commercial property owners faced urgent economic incentives to modernize mechanical operations. An automated control system capable of generating double-digit fuel savings ceased to be an optional building convenience; it offered a measurable return on investment. This inflection altered the industry's sales proposition, transforming building controls from an amenity focused on occupant comfort into a capital expenditure justified by operating payback. That economic logic remains central to commercial retrofits and facility decarbonization projects today. Reflecting its expanded technological scope, the enterprise formally adopted the name Johnson Controls, Inc., in 1974.10
The Fateful Merger with Globe-Union
In 1978, Johnson Controls completed a transaction that redirected its strategic focus for the next four decades: a merger with Globe-Union, a neighboring Milwaukee manufacturer and the largest producer of automotive batteries in the United States. The combination roughly doubled Johnson Controls' total revenues overnight.103 Globe-Union possessed an established industrial franchise, having developed the thin-wall polypropylene battery container in the late 1950s and grown into the leading domestic manufacturer of replacement automotive batteries by 1971.12
The strategic rationale presented for an environmental controls enterprise acquiring an automotive battery maker centered on portfolio diversification. Commercial construction followed pronounced cyclical swings, whereas aftermarket automotive replacement batteries offered a steady, nondiscretionary consumer revenue stream. In retrospective capital-allocation terms, however, the merger exemplified the conglomerate-building strategy common across corporate America during the 1970s, prioritizing top-line scale over operational synergy. Moving the corporate headquarters from downtown Milwaukee north to suburban Glendale following the transaction provided a tangible indicator of this shifting organizational identity.3
Seats, Speed, and Just-in-Time
Johnson Controls expanded its automotive commitments further during the 1980s. In 1985, the company acquired Hoover Universal for approximately $219 million in cash and stock, securing a major seating franchise alongside sophisticated just-in-time manufacturing capabilities, and subsequently integrated Ferro Manufacturing.10 Under the just-in-time operational framework, Johnson Controls established dedicated assembly plants adjacent to automaker facilities, sequencing and delivering finished seating assemblies directly to vehicle production lines within hours of installation. The delivery model demanded exacting manufacturing precision and tight supply-chain synchronization.
Two chief executives orchestrated this industrial expansion: Fred Brengel, who led the enterprise from 1967 to 1988, and his successor James Keyes, who served from 1988 to 2002.11 Under their leadership, automotive manufacturing became the dominant growth driver. By the 1990s, automotive components generated nearly three-quarters of total corporate revenues.10 For all practical purposes, Johnson Controls had transformed into a Tier-1 automotive supplier with an embedded commercial building controls division.
The Economic Mismatch
The strategic friction inherent in this structure was not that automotive manufacturing lacked operational competence, but that its fundamental unit economics diverged sharply from commercial building systems. Automotive seating and lead-acid batteries operated as capital-intensive, high-volume manufacturing businesses with pricing dictated by a concentrated group of original equipment manufacturers exercising substantial procurement leverage. Commercial building systems, by contrast, functioned as specialized field-engineering operations characterized by decentralized customer relationships, proprietary technical architectures, and high-margin recurring service agreements. Because the automotive division commanded greater aggregate revenue, it consistently absorbed the larger share of capital expenditure and senior executive focus.
For investors evaluating this era, the central lesson concerns the penalty of strategic dispersion. Conglomerates combining disparate business models frequently trade at multiples anchored to their lowest-margin, most capital-intensive segment, while finite managerial bandwidth slows reinvestment in high-return assets. Over the subsequent twenty-five years, Johnson Controls confronted the consequences of that diversion, discovering that its building automation business had conceded competitive ground to focused peers. Crucially, the most acute strategic deficiency lay not in controls software, but in the primary mechanical equipment those controllers were designed to govern.
IV. York International & The Applied HVAC Transformation (2005) (30–35 min)
The Gap in the Mechanical Room
Consider a hospital basement mechanical room in the early 2000s. A Johnson Controls Metasys panel mounted on the wall blinked with operational data. Yet the massive chillers generating chilled water for the entire facility—the primary consumers of mechanical energy—invariably carried nameplates from Trane or Carrier. Johnson Controls governed the building's brain, but not its heart.
That imbalance created an acute strategic vulnerability. Competitors manufacturing applied chillers could bundle proprietary controls directly with their equipment, presenting facility owners with a single point of operational accountability. Whenever that bundled proposition succeeded, Metasys risked being displaced from new construction projects entirely.
The mechanics of commercial construction amplified this risk. When commissioning a complex facility, a building owner retains a consulting mechanical engineer to draft detailed specifications detailing equipment requirements and naming approved manufacturers. Mechanical contractors subsequently bid against those specifications. If an engineer specifies a particular chiller, and that equipment maker packages proprietary controls alongside the heavy machinery, the controls platform frequently rides along. Securing an approved position at that initial engineering specification stage represents a quiet but decisive distribution channel. To protect its market standing, Johnson Controls needed an engineering footprint in the most capital-intensive equipment in the building, rather than relying solely on the controls panel mounted to the wall.
The York Deal
On August 24, 2005, Johnson Controls agreed to acquire York International for approximately $3.2 billion in cash, paying $56.50 per share and assuming roughly $800 million of York's debt. York's shareholders approved the transaction on December 9, 2005.13 York generated estimated annual sales of nearly $5 billion, and the combination effectively doubled Johnson Controls' commercial building footprint, folding York into an expanded Controls Group with nearly $6 billion in sales.13
York brought an established industrial pedigree; management describes its York engineering center as home to roughly 150 years of HVAC and thermal-management leadership.4 Its industrial centrifugal chillers were deeply entrenched with the mechanical engineering firms that design large-scale institutional facilities. Chief executive John Barth, who led Johnson Controls from 2002 to 2007, oversaw the transaction.11
The Strategic Case
The industrial logic was compelling. By integrating York, Johnson Controls could provide an end-to-end mechanical package spanning chillers, air handlers, automated controls, and ongoing maintenance. That integrated offering resonated across large, complex institutional projects—including hospitals, university campuses, and airports—where facility directors favored reduced vendor complexity and unified operational accountability. Crucially, York brought an extensive installed base of applied chillers requiring decades of periodic maintenance, retrofits, and overhauls, directly feeding the recurring service network that generated the segment's highest margins.
What York Also Brought
The less examined dimension of the York acquisition was its residential and light commercial portfolio: residential furnaces, split-system air conditioners, and heat pumps marketed primarily through independent wholesale distributors and regional dealer networks. This division operated under fundamentally different commercial dynamics, customer procurement habits, and cyclical risks than the large applied systems business. It remained directly exposed to residential construction cycles and discretionary consumer spending, competing in a commoditized market where equipment brand differentiation was minimal and local dealer distribution channels determined market share.
A decade later, Johnson Controls expanded its commitment to unitary heating and cooling. In October 2015, the company established Johnson Controls-Hitachi Air Conditioning alongside 株式会社日立製作所 Hitachi, acquiring a 60% controlling interest in a joint venture generating more than ¥350 billion (approximately $2.8 billion) in annual sales, supported by 14,000 employees and 24 design and manufacturing facilities spanning Asia, Europe, and Latin America.14 The venture focused on ductless mini-splits and variable-refrigerant-flow systems, the compact, decentralized architectures prevalent across Asian and European commercial and multi-family residential structures.
The Verdict on York
Evaluating the York acquisition against its original rationale yields a divided verdict. The commercial applied business, particularly heavy-duty centrifugal chillers, proved to be one of the most durable assets Johnson Controls ever secured, ultimately serving as the thermal backbone for modern AI data center infrastructure. The residential business, by contrast, persisted as a source of cyclical earnings volatility and lower operating margins, culminating in the company's agreement to divest its residential and light commercial HVAC operations—including the Hitachi joint venture—to Bosch for $8.1 billion in a transaction completed in 2025. In practice, Johnson Controls spent two decades managing a residential heating and cooling business that equity markets never rewarded before fully exiting the category.
The outcome of the York acquisition presents a nuanced verdict on Johnson Controls' capital allocation. The company acquired a strategically indispensable applied cooling franchise, but it simultaneously absorbed an ill-fitting residential business that it retained for twenty years before divesting. That structural pattern—an exceptional industrial core burdened by noncore corporate appendages—would recur on an even larger scale a decade later in an acquisition that introduced intense public and political scrutiny alongside strategic scale.
V. The $16.5B Tyco Merger & Tax Inversion: Financial Engineering vs. Field Reality (2016) (35–40 min)
A Merger in the Middle of a Campaign
On January 25, 2016, Johnson Controls and Tyco International announced a combination structured through an unusual corporate inversion. Legally, Irish-domiciled Tyco served as the acquirer. Legacy Johnson Controls shareholders received approximately 56% of the equity alongside roughly $3.9 billion in cash, while Tyco shareholders retained 44%.1516 Under the merger terms, each Johnson Controls share could be exchanged for one share of the combined entity or $34.88 in cash, subject to proration.16
Tyco arrived with its own complex history as an acquisitive conglomerate that had spent years breaking itself apart; by 2016, its remaining operations centered on commercial fire protection and electronic security. The transaction closed on September 2, 2016, with Tyco adopting the name Johnson Controls International plc and shifting the enterprise's legal domicile from the United States to Cork, Ireland.17
The Tax Math and the Political Firestorm
Management projected $650 million in operational and tax synergies across the first three years.17 Contemporaneous reporting estimated the ongoing tax savings alone at roughly $150 million annually.18 For an industrial enterprise generating tens of billions of dollars in revenue, that tax reduction was meaningful but hardly transformative—making the subsequent political reaction all the more intense.
Evaluated strictly on unit economics, the trade-off was stark. An annual tax reduction of $150 million, while welcome, was modest alongside the combined top line; a single percentage point of operating margin expansion across the commercial buildings portfolio would have delivered greater financial value. In exchange for that incremental tax benefit, the enterprise absorbed substantial organizational friction: acute political scrutiny, an overseas legal headquarters detached from its operational center in Milwaukee, and a corporate identity rooted more in financial engineering than field engineering. While those liabilities did not appear directly on an income statement, they influenced how institutional clients, public-sector procurement officers, and investors perceived the business for years.
The political fallout arrived swiftly. Hillary Clinton, then campaigning in the Democratic presidential primary, condemned the transaction as "outrageous" and pledged to pursue an exit tax targeting inverted corporations.19 During a February 2016 debate, she asserted that federal taxpayers had effectively bailed out Johnson Controls when rescuing the domestic auto industry. PolitiFact rated the claim "Mostly True," noting that while the company had not received direct bailout funds, it had benefited substantially as a major component supplier to General Motors and Chrysler.18 For an enterprise whose customer roster relied heavily on municipal school districts, local governments, and federal agencies, carrying the public label of a corporate deserter imposed a tangible reputational cost.
The Strategic Pitch
Beyond balance-sheet optimization, leadership presented an expansive strategic thesis: pairing HVAC and automation controls with commercial fire safety and electronic security would establish an end-to-end digital building platform. In theory, a single vendor could furnish, network, and maintain every critical system—orchestrating heating, ventilation, lighting, fire suppression, and access control through a unified technological architecture.
What Actually Happened
Field execution proved far more challenging than the integration blueprint. Under the original leadership structure, Alex Molinaroli, the legacy Johnson Controls chairman and chief executive, led the combined enterprise, while George Oliver, Tyco's former CEO, served as president and chief operating officer. In August 2017, the board abruptly accelerated executive succession: Molinaroli departed the company and its board effective September 1, 2017—eighteen months ahead of schedule—clearing the path for Oliver to assume the roles of chairman and chief executive.20 While the board characterized the move as recognition of Oliver's integration stewardship, the sudden transition signaled that the dual-executive arrangement had strained operational cohesion.
Oliver, who had steered Tyco prior to the combination, would guide Johnson Controls from 2017 into 2025.11 His tenure would encompass sweeping portfolio divestitures, an aggressive push into proprietary digital platforms, and a persistent run of restructuring charges.
Testing the Inversion Thesis
The hypothesis that combining Tyco with Johnson Controls would unlock a uniquely integrated buildings platform warrants rigorous examination against subsequent operating results. Over the following eight years, recurring financial friction told a different story. In fiscal 2024, Johnson Controls recognized $544 million in restructuring charges, reporting GAAP diluted earnings per share of $2.52 against adjusted earnings per share of $3.71.21 That divergence of more than a dollar per share represented costs management routinely asked shareholders to exclude from core operating performance. When restructuring expenses recur annually over an extended cycle, they cease to function as one-time events and reflect the ongoing cost of running the business.
Strategic decisions made in 2026 further eroded the original platform narrative. Bloomberg reported that Johnson Controls was exploring a sale of its access control and intrusion detection product lines, operations that could command up to $4.5 billion in a transaction.22 Moreover, management conceded to analysts in 2026 that security products are "less differentiated" than applied HVAC systems.4 Placing the security lines acquired through Tyco on the auction block effectively conceded that the initial ambition of an all-inclusive building systems platform had been fundamentally narrowed.
A balanced appraisal indicates that while Tyco contributed highly lucrative assets—particularly in fire detection and suppression, where statutory life-safety building codes mandate regular inspections and generate sticky service revenues—the thesis of a fully integrated digital hardware ecosystem failed to materialize as envisioned. What ultimately emerged was a more modest, practical configuration: fire protection operating as a resilient, code-mandated service line alongside mechanical HVAC, rather than an all-encompassing software architecture. Yet the immediate imperative following the merger was far more pressing: dismantling the sprawling non-building franchises that still burdened the corporate perimeter.
VI. The Great Conglomerate Unwind (2016–2020) (30–35 min)
Two Months After the Merger
The Tyco merger had barely closed when Johnson Controls began dismantling its automotive empire. On October 31, 2016, the company completed the spin-off of its seating and interiors business as Adient plc, distributing one Adient share for every ten Johnson Controls shares.23 Adient was expected to carry about $3.5 billion of debt at separation, and the proceeds of that debt were intended to fund about $3.0 billion in cash transfers to Johnson Controls.24
The transaction structure reflected the stark divergence in financial quality between the two businesses. Johnson Controls extracted billions in cash, while saddling Adient with substantial debt alongside the structural handicaps of automotive seating: intensive capital expenditure cycles, high customer concentration, and structurally thin operating margins. For Johnson Controls, the separation removed a capital-intensive division at the precise moment it needed balance-sheet flexibility to navigate the integration of Tyco.
Selling the Battery Business at the Right Time
The larger prize remained the battery division, the direct descendant of Globe-Union. On April 30, 2019, Johnson Controls completed the sale of its Power Solutions business to an entity controlled by Brookfield Business Partners, with institutional partners including Caisse de dépôt et placement du Québec (CDPQ), for $13.2 billion.25 Net cash proceeds after tax and transaction costs were approximately $11.6 billion.25 The divested business was subsequently rebranded as Clarios.
The timing proved advantageous. Lead-acid batteries represented a mature, cash-generative industrial franchise facing medium-term technological uncertainty as global automakers accelerated their investments in electric vehicle architectures. By monetizing the asset before battery chemistry transitions could impair terminal multiples, Johnson Controls captured a premium valuation for a legacy manufacturing operation.
What Happened to the Money
How leadership deployed that capital revealed the company's shifting corporate posture. Management said it planned to use the net proceeds to reduce about $3.4 billion of debt and fund repurchases of up to $8.2 billion of shares.25 Shortly after closing, the company launched a modified Dutch auction tender offer for up to $4.0 billion of shares at $36 to $40 a share.26
Returning the bulk of the proceeds to shareholders repaired the post-merger balance sheet and supported near-term earnings per share, but it carried an enduring strategic consequence: it stripped away the company's financial shock absorbers. There was no longer an automotive battery division to generate baseline cash flow or cushion execution missteps in commercial building projects. From 2019 onward, Johnson Controls had to stand entirely on the operational merits of its buildings portfolio, evaluated directly against pure-play competitors like Trane Technologies and Carrier Global (CARR), which gained independence from United Technologies in 2020.
Scoring the Unwind
Evaluated in isolation, the unwind accomplished its explicit goals: two ill-fitting manufacturing operations were divested at favorable valuations, and the balance sheet was substantially deleveraged. Yet the transaction sequence warrants broader historical context. Johnson Controls spent four decades assembling those automotive operations, committing generations of capital expenditure and managerial attention to high-volume manufacturing that shared no operational or engineering synergies with environmental controls. Dispersing those proceeds through share repurchases and debt reduction liquidated a conglomerate structure rather than funding a new compounding engine. The unwind corrected a multi-decade strategic detour rather than demonstrating unusual capital-allocation foresight.
With the automotive operations dismantled, Johnson Controls was finally reduced to its commercial buildings core. Proving what that core could deliver required examining the mechanical reality inside the machine.
VII. Inside the Machine: Segment Economics, Installed Base, & Field Services (40–45 min)
A Day in the Life of a Branch
Entering a Johnson Controls branch office in Baltimore on a weekday morning reveals a scene that looks less like a technology vendor and more like a regional mechanical contractor. Service technicians load vans with replacement parts, sales engineers review mechanical blueprints for a hospital expansion, and project managers coordinate equipment delivery schedules for air handlers. Management hosted investors at that Baltimore branch in June 2026, highlighting relationships with local building owners, general contractors, and engineering consultants that spanned roughly a century.4 This distributed field network is where the company's operating profits are ultimately generated or lost.
Understanding those economics requires clarifying how leadership reports operating performance. Johnson Controls measures divisional profitability using "segment EBITA"—earnings before interest, taxes, and amortization of acquired intangibles, calculated prior to corporate overhead allocations. While segment EBITA reflects the earnings generated by field operations before central administrative charges, it sits well above the net earnings received by shareholders. That persistent spread between segment EBITA and GAAP net income—driven by recurring restructuring charges and integration expenses—remains one of the defining characteristics of the company's financial reporting.
Where the Money Came From Before the Split
Fiscal 2024, the final full fiscal year before the residential divestiture and subsequent segment reorganization, provides an instructive baseline of the legacy organizational structure. The company reported $27.4 billion of consolidated sales across four operating segments.21 Building Solutions North America delivered $11.3 billion of sales and $1,663 million of segment EBITA, generating an operating margin of 14.7%. Building Solutions EMEA/LA produced $4.3 billion in revenue at a 9.1% margin, while Building Solutions Asia Pacific generated $2.2 billion at an 11.7% margin. Meanwhile, Global Products—the centralized manufacturing division encompassing York chillers, controls, fire safety hardware, and the residential lines—generated $9.5 billion of sales and $2,123 million of EBITA, delivering a 22.3% margin.21
That margin profile highlighted a persistent structural disparity across the enterprise. Centralized equipment manufacturing delivered premium profitability, whereas international field operations generated thin margins. Field branches across Europe, Latin America, and Asia lagged behind North American profitability, burdened by fragmented branch networks, lower local service density, and softer regional commercial construction activity.
The New Structure
In April 2025, Johnson Controls dismantled the separate Global Products division and realigned into three direct regional segments: Americas, EMEA, and APAC.2 Under this revised structure, manufacturing earnings were integrated directly into the geographic territories where equipment was sold. In the third quarter of fiscal 2026, the Americas generated $4.5 billion of sales with an adjusted segment EBITA margin of 21.1%, EMEA produced $1.3 billion at a 14.3% margin, and APAC delivered $0.8 billion at 21.2%.6 Recurring field services accounted for roughly 32% of continuing operations revenue in fiscal 2025, with equipment products and installed systems generating the remaining 68%.2
While folding manufacturing profits into geographic segments precludes a direct comparison with historical branch margins, the directional shift is evident. Divesting the lower-margin residential operations structurally elevated reported segment profitability, lifting EMEA segment margins from historical single digits into the mid-teens and underscoring the higher baseline margin profile of commercial applied equipment.
Why Direct Service Is the Real Business
The economic logic underpinning this direct branch infrastructure mirrors the commercial aviation aftermarket. A commercial applied chiller operates effectively like a building's jet engine: an initial installation can cost hundreds of thousands of dollars and remain operational for thirty to forty years. While upfront equipment bidding is intensely competitive, the mechanical plant requires ongoing preventive maintenance, factory parts, software recalibrations, and major periodic overhauls throughout its operational life. The original manufacturer holds an inherent advantage in securing those recurring, high-margin service contracts.
Johnson Controls, much like Trane Technologies, distributes and maintains the vast majority of its applied equipment through direct company-owned branches rather than independent third-party distributors. Leadership contends that direct distribution provides tighter ownership of the customer relationship and expands aftermarket service capture. On the third-quarter fiscal 2026 earnings call, management emphasized that Johnson Controls maintained more "feet on the ground" than direct peers because of its deliberate historical commitment to direct customer service.4
Testing the Installed-Base Moat
The proposition that an expansive installed base guarantees insurmountable customer switching costs warrants critical examination, as field evidence reveals marked disparities across product categories.
In building controls, the historical moat has been significantly eroded by the industry-wide adoption of open communication protocols. Industry standards such as BACnet, LonWorks, and Modbus enable controllers and sensors from rival manufacturers to interoperate seamlessly. Furthermore, Honeywell's Tridium subsidiary, which introduced the Niagara Framework in 1999, established an open software integration layer that allows independent system integrators to normalize and manage multi-vendor building automation platforms from a unified console.27 Consequently, a facility executive overseeing a Metasys installation is no longer tethered to Johnson Controls technicians in the manner of the legacy pneumatic era; third-party integrators can service, program, and expand hybrid networks. Switching costs remain, but customer lock-in has diminished substantially.
Aftermarket service retention exhibits similar differentiation under pricing scrutiny. On the third-quarter fiscal 2026 earnings call, management acknowledged a decline in Americas security service backlog, attributing the contraction to a strategic rebalancing between contract pricing and service volume in an operational domain characterized as less proprietary than applied HVAC.4 Earlier in 2026, the chief executive similarly noted that the company was "rebalancing in the security service business between price and volume."28 In operational terms, when the company attempted to push aggressive price realization in commercial security monitoring and maintenance, customers defected to local or regional competitors—a classic indicator of limited pricing power rather than an unassailable commercial moat.
By contrast, fire protection and life-safety systems maintain significantly higher commercial resilience. Municipal building and life-safety codes mandate periodic certified inspections, testing, and compliance documentation, ensuring that certified installers like Simplex routinely retain recurring inspection contracts. Complex applied HVAC service exhibits comparable durability: management reported that HVAC and fire service revenues were expanding at mid- to high-single-digit rates, supported by the technical specialization required to maintain large-scale central chiller plants.4
The Fixed-Price Trap
The direct branch model also entails substantial balance-sheet and execution risks that differentiate it from pure software or equipment manufacturing. When Johnson Controls executes large installations under fixed-price construction contracts, it assumes full project execution risk. Unanticipated site delays, skilled labor shortages, or sub-contractor cost inflation directly compress realized contract margins. Managing project slippage demands relentless operational discipline at the branch level, explaining why executive leadership repeatedly stresses installation governance.
A related operational liability resides within energy performance contracting. Under these long-term agreements—predominantly executed with public school districts, municipal entities, and federal facilities—Johnson Controls modernizes building infrastructure and provides contractual guarantees that utility savings will offset the project's capital financing costs over ten to twenty years. While performance contracting serves as a compelling vehicle to originate major retrofit projects without requiring upfront municipal capital, the underlying performance guarantees leave the company exposed to multi-year engineering assumptions. If mechanical efficiencies fall short of projections or utility baselines shift unpredictably, Johnson Controls remains liable for the shortfall.
Ultimately, the competitive moat derived from Johnson Controls' installed base is genuine but unevenly distributed. It remains formidable in heavy applied chillers and code-mandated fire life-safety systems, moderate in building controls due to open interoperability protocols, and fragile in electronic security, where customer churn follows attempted price increases. The operational indicator that separates structural competitive advantage from cyclical volume remains sustained, organic service contract growth and customer retention over multiple seasons. Yet in 2026, the most demanding technical and commercial test of that installed base is unfolding in an operating environment far removed from commercial office buildings: the hyperscale AI data center.
VIII. The Data Center Boom, Silent-Aire, & The OpenBlue Software Reality Check (35–40 min)
Heat Is the New Constraint
From a thermal perspective, an artificial intelligence data center functions as an industrial furnace that must be continuously cooled. As high-performance computing silicon grows more power-dense, rack-level heat generation surges, transforming thermal dissipation into the primary physical bottleneck governing how much compute capacity a facility can support. Joakim Weidemanis crystallized the inflection on the third-quarter fiscal 2026 earnings call: "this is the age of thermal management."4
The operational order book reflects the scale of that transformation. Johnson Controls recorded organic order growth of 39% in the first quarter of fiscal 2026, 30% in the second quarter, and 27% in the third.29306 Total company backlog expanded 32% organically to reach a record $21.0 billion by the close of the third quarter, with the Americas accounting for $15.9 billion of that commitment.6 On that earnings call, the chief financial officer projected that data center equipment and services would generate a high-teens percentage of total fiscal 2026 revenue and could expand to roughly one-third of corporate sales within three to five years.4 Underscoring that momentum, applied HVAC revenue in the Americas expanded in the high teens during the third quarter.4
Silent-Aire: The Well-Timed Bet
Johnson Controls' competitive positioning in data centers rests heavily on an acquisition completed before the generative AI expansion gained broad visibility. In April 2021, the company agreed to acquire Silent-Aire, a specialist in hyperscale data center cooling and modular critical infrastructure, for up to $870 million, structured as approximately $630 million in upfront cash alongside contingent earnout milestone payments.31 The transaction closed on May 12, 2021.32
Silent-Aire manufactured large custom air handlers and modular thermal systems assembled in off-site factories rather than erected on location, matching the operational demands of cloud platforms building facilities at rapid speed. In retrospect, the purchase stands out as one of the most effective capital-allocation decisions of the Oliver era, embedding Johnson Controls directly into the design blueprints and procurement pipelines of the largest cloud builders immediately before demand surged.
The post-deal accounting reveals an illuminating detail regarding management's initial expectations. When the transaction closed, Johnson Controls recorded the estimated fair value of the contingent earnout liability at approximately $90 million, measured against a maximum potential payout of about $250 million.32 In effect, leadership initially anticipated that Silent-Aire would achieve only a modest portion of its stretch targets. The subsequent data center construction wave converted a sensible, mid-sized bolt-on into a central corporate pillar. That commercial outcome represents a clear operational success, but its historical nature warrants precision: it was an intelligent strategic bet that became transformative because external market demand shifted massively in its favor, rather than an explicit forecast of the AI infrastructure boom made by leadership at the time.
How Hyperscalers Buy
The third-quarter fiscal 2026 earnings call provided a clear window into how hyperscale developers manage equipment procurement. Weidemanis explained that hyperscale operators typically engineer their data center cooling architectures alongside a restricted roster of one, two, or at most three approved suppliers, occasionally embedding customer engineering personnel alongside Johnson Controls' technical staff for a week to ten days. Once designed into a reference architecture, a vendor competes for ongoing equipment allocations across multiple facilities, where faster manufacturing lead times and dependable delivery execution can win volume beyond initial baseline allocations.4
That commercial dynamic presents an essential operational nuance for investors. Securing an approved design-in status is vital, yet hyperscalers routinely split contract awards across their approved vendors to diversify operational risk. The sector operates not as a proprietary monopoly, but as an intensely competitive oligopoly where factory execution and supply-chain responsiveness dictate market share. When asked directly whether Johnson Controls was winning market share from peers, Weidemanis responded, "We think we are for the categories that we focus on."4 That perspective reflects executive conviction rather than an independently verified market-share calculation.
A further operational nuance touches profitability. The chief financial officer noted that rapid data center expansion is currently tilting corporate sales toward equipment systems, which carry lower operating margins than field services.4 Leadership argues that this expanding mechanical footprint will reliably feed decades of high-margin aftermarket maintenance agreements. While that lifecycle thesis is logically sound, it represents an expectation for future years rather than an operational result visible today. The definitive test for investors will be whether service attachment rates on newly commissioned data centers translate into sustained organic service revenue growth across subsequent cycles.
Moving Up the Value Chain
Concurrently, Johnson Controls is moving to capture more revenue per megawatt of data center power capacity. In February 2026, the company agreed to acquire Alloy Enterprises, a Boston-based company developing a thermal-management platform centered on advanced direct liquid cooling components.33 On the third-quarter call, management stated that its commercial pipeline for coolant distribution units had expanded to approximately $1 billion, that initial customer shipments were scheduled for the fourth quarter, and that the platform had secured an NVIDIA certification.4 The company also introduced an absorption chiller reference design intended to convert operational waste heat into supplemental cooling, reducing net electricity consumption.4
These product initiatives demonstrate technical momentum, but they warrant analytical caution. A qualified sales pipeline does not represent recognized revenue, a technical certification does not constitute a purchase contract, and a reference design is not a firm equipment order. Johnson Controls has an uneven historical record of converting early engineering concepts into sustained high-margin cash flow, and the direct liquid cooling arena is populated by capable competitors, including Vertiv Holdings (VRT), which the company cites as a key rival.2
The OpenBlue Reality Check
That analytical skepticism applies with even greater justification to the company's enterprise software ambitions. On July 31, 2020, Johnson Controls introduced OpenBlue, positioned as a comprehensive suite of connected building technologies combining domain engineering expertise with artificial intelligence, digital twins, and cloud analytics.34 At its September 2021 investor day, executive leadership placed OpenBlue at the center of corporate strategy, linking the platform to facility decarbonization and smart building management.35
The underlying investment thesis was that Johnson Controls could evolve into a software-enabled enterprise commanding recurring, high-margin revenue streams and a corresponding software valuation multiple. Five years later, disclosed financial performance does not support that narrative. Johnson Controls provides no standalone disclosure of OpenBlue revenue or recurring software sales in its regular segment reporting, leaving the scale of commercial adoption impossible for investors to verify independently. In 2026, the company's core growth story is overwhelmingly about physical chillers, air handlers, coolant distribution units, and branch services—not software subscriptions. On the third-quarter fiscal 2026 call, OpenBlue was not the focal point of the presentation; physical thermal management was.4
Structural commercial barriers explain that divergence. Many commercial facilities operate under triple-net lease agreements where tenants absorb utility expenses, weakening the property owner's economic incentive to license energy-optimization software. Furthermore, commercial building customers frequently consume digital monitoring through integrated field-service contracts rather than unbundled software subscriptions. The most measured conclusion is that OpenBlue serves primarily as a digital tool enabling branches to win and retain field-service relationships, while the ambition of transforming Johnson Controls into a software business remains unsupported by disclosed financial data. The evidence that would alter that assessment is straightforward: regular, audited disclosures detailing recurring software revenue, margins, and growth.
The data center expansion is undeniably genuine, and it has reinvigorated the company's order book. Yet that secular wave arrived only after an extended stretch in which legacy execution faltered—an operational drift that ultimately brought an activist investor straight to the boardroom.
IX. The Activist Reckoning: Elliott Management, The $8.1B Bosch Sale, & Danaher Succession (2024–2025) (35–40 min)
The Weekend the Systems Went Dark
On the weekend of September 23, 2023, Johnson Controls began receiving reports of system outages. It was a ransomware attack. The company later disclosed that the incident involved unauthorized access, data exfiltration, and the deployment of ransomware across portions of its internal IT infrastructure, noting that the impact on net income for the fiscal first quarter ended December 31, 2023, was approximately $27 million.36 The Dark Angels ransomware group claimed responsibility and reportedly demanded a $51 million ransom.36
While the direct financial expense was modest for a corporation of its scale, the reputational symbolism was severe. Johnson Controls sells commercial building security and cyber-secure facility controls. A network breach that paralyzed internal operations offered an uncomfortable reminder that the company's back-office architecture remained a complex patchwork of legacy Johnson Controls and Tyco systems.
Promises Versus Delivery
The security breach punctuated an extended cycle of investor frustration. At its September 2021 investor day, management set three-year targets running through fiscal 2024: annual organic revenue growth of 6% to 7%, segment EBITA margin expansion of 250 to 300 basis points, and compound annual growth in adjusted earnings per share of 18% to 21%.35 Adjusted EPS had stood at $2.65 in fiscal 2021.37 By fiscal 2024, adjusted EPS reached $3.71.21 That performance represented approximately 12% annualized earnings growth—respectable in historical terms, but well below the committed range. While top-line expansion held closer to plan, the earnings shortfall represented a substantial gap on the metric investors prioritized most.
That persistent spread between executive targets and realized financial results established an ideal operational opening for an activist shareholder.
Elliott Arrives
In May 2024, Bloomberg reported that Elliott Investment Management had built an equity position exceeding $1 billion in Johnson Controls, ranking the activist among the company's top ten shareholders.7 Elliott's operational thesis followed a tested playbook: target an established industrial enterprise with attractive core assets, lagging segment margins, and an overly complex corporate perimeter, and then push for strategic simplification, cost discipline, and leadership renewal.
Johnson Controls responded rapidly. On July 23, 2024, the company announced an agreement to sell its residential and light commercial HVAC operations to Bosch.8 A week later, on July 31, 2024, the company announced that George Oliver planned to retire as chief executive once a successor was appointed, confirming that the board had initiated a formal executive search while appointing Patrick Decker, the former CEO of Xylem and a former Tyco executive, as an independent director.938 Elliott partner Marc Steinberg stated that the firm appreciated its "productive discussions" with leadership and believed the announced initiatives positioned the business to realize the benefits of its ongoing transformation. Shares rose approximately 8% following the announcement.38
The Bosch Deal
The transaction with Bosch carried a total enterprise value of $8.1 billion, encompassing Johnson Controls' North American ducted residential business alongside the global residential joint venture with Hitachi, with Hitachi retaining select ductless assets in Shimizu, Japan.39 Johnson Controls' portion of the consideration totaled approximately $6.7 billion, generating net cash proceeds of roughly $5.0 billion after taxes and transaction expenses.39 The company completed the sale on August 1, 2025, and announced plans to return capital to shareholders through a $5.0 billion accelerated share repurchase program.39
The divestiture effectively dismantled the lower-margin residential holdings acquired through the York and Hitachi combinations. By exiting residential HVAC, Johnson Controls eliminated its exposure to cyclical single-family housing construction and volatile consumer replacement cycles, transforming into a pure-play commercial building technology and solutions provider. Earlier in 2024, the enterprise had also completed the sale of its Air Distribution Technologies division—including commercial air-distribution brands Titus and Ruskin—to Truelink Capital, without publicly disclosing financial terms.40
That portfolio rationalization carried an important caveat for equity investors. While divesting residential heating and cooling sharpened the commercial focus, it represented a structural admission of past capital misallocation: Johnson Controls had retained those residential assets for two decades and expanded its commitment through the Hitachi joint venture in 2015, only to reverse course under activist pressure. Furthermore, allocating the vast majority of the transaction windfall to share repurchases meant that future earnings growth would have to stem from organic execution within the remaining commercial operations, rather than reinvestment into new operating assets.
A Danaher Veteran Takes Over
On February 5, 2025, Johnson Controls appointed Joakim Weidemanis as chief executive officer, effective March 12, 2025. Oliver continued as non-executive chairman through July 31, 2025, when he was succeeded as chairman by Mark Vergnano, a board director since 2016.41 Weidemanis joined after a 13-year career at Danaher, where he most recently served as executive vice president for Diagnostics and China, overseeing an operating group generating approximately $15 billion in annual revenue across eight distinct businesses.41
The leadership transition sent an unmistakable operational signal. Rather than elevating an executive steeped strictly in HVAC manufacturing, the board selected an operator trained in the Danaher Business System, an operational framework centered on continuous improvement, standardized work routines, and quantitative measurement. Weidemanis now refers to Johnson Controls' adaptation as its "proprietary business system," and executive leadership characterizes it as "how we run the company."4
That choice introduces an essential operational test. The Danaher methodology was established and refined within automated factories and life-sciences businesses characterized by highly repeatable, standardized manufacturing workflows. Johnson Controls, by contrast, relies heavily on distributed branch networks, regional project execution, and decentralized service routes where operating margins depend on local technician productivity and variable site conditions. Whether lean industrial practices can be effectively transposed into that people-intensive, field-service environment represents the central strategic question facing the executive team.
Early indications of Weidemanis's operational style emerge through his management vocabulary and public cadence: reviewing sales funnels, shortening order-to-delivery lead times, expanding manufacturing throughput, and frequently referencing the "gemba"—the lean-manufacturing principle denoting the factory floor or physical setting where work takes place. For the June 2026 investor event, he steered Wall Street analysts through an active manufacturing plant and a regional branch office rather than delivering a traditional slide deck.42 When questioned about component supply bottlenecks, he noted that very occasionally he must get involved personally.4 Asked about the multi-year durability of AI infrastructure investments, he drew on his diagnostic background, observing that researchers are only beginning to apply advanced AI models to unlock biological datasets.4 It reflects an exacting, process-oriented leadership posture that aligns directly with board expectations. Whether that operational discipline can be institutionalized across roughly 40 manufacturing sites and hundreds of local branch offices remains the definitive milestone for the coming years.4
Capital allocation under the reconstituted leadership team has likewise adopted a disciplined posture. During the first nine months of fiscal 2026, Johnson Controls generated $2.3 billion in free cash flow, repurchased $850 million of common shares, and distributed $734 million in dividends, on top of the $5.0 billion accelerated share repurchase program launched following the Bosch transaction.61 The figures point toward an emphasis on shareholder capital returns over conglomerate building. The prospective divestiture of the electronic security product lines will serve as the next benchmark of whether asset proceeds continue to be channeled back to shareholders or are redeployed toward adjacent hardware acquisitions.
X. Competitive Dynamics, Porter's 5 Forces, & Hamilton Helmer's 7 Powers (30–35 min)
The Battlefield
Johnson Controls operates across several overlapping competitive arenas. In applied commercial HVAC and heavy centrifugal chillers, its primary rivals are Trane, Carrier, ダイキン工業 Daikin Industries, and 三菱電機 Mitsubishi Electric. In building automation and controls, it contends with Honeywell International (HON), Siemens (SIE.DE), Schneider Electric (SU.PA), and Carrier's automated solutions. In data center thermal management, Vertiv stands as a formidable competitor. In its regulatory filings, Johnson Controls identifies Honeywell, Siemens Smart Infrastructure, Schneider Electric, Carrier, Trane, Vertiv, API Group, and Daikin among its principal competitors.2
The broader competitive landscape has also been reshaped by aggressive portfolio restructuring across the sector. Peers have executed major asset realignments: Carrier completed its roughly $14.2 billion acquisition of Viessmann Climate Solutions in January 2024 and sold its Access Solutions security division to Honeywell for approximately $5.0 billion in cash proceeds in June 2024.43 Across the industry, diversified equipment makers have systematically divested peripheral holdings, channeling capital toward focused climate and building-intelligence pure plays.
Porter's Five Forces
The threat of new entrants remains structurally low. Manufacturing industrial applied chillers demands decades of specialized thermodynamic engineering, compliance with stringent pressure vessel certifications, adherence to evolving low-global-warming-potential refrigerant regulations, heavy capital manufacturing assets, and deep relationships with the mechanical specifying engineers who author commercial blueprints. A venture-backed startup cannot easily replicate that manufacturing scale or distribution network. New entrants can, however, penetrate specialized technological niches such as direct liquid cooling components—a dynamic that led Johnson Controls to acquire Alloy.
Supplier power is moderate but exhibits sharp cyclical pinch points. Johnson Controls procures basic raw commodities including copper and steel, alongside electronic components, specialized compressors, and next-generation refrigerants. During accelerated demand surges, supply-chain bottlenecks inevitably emerge. On the third-quarter fiscal 2026 earnings call, Weidemanis noted that supply-chain constraints are "always an issue" in a high-growth operating environment, while arguing that Johnson Controls controls more of its supply chain than certain competitors because it manufactures critical chiller subsystems in-house.4
Buyer power varies dramatically across project lifecycles. During the design and construction phase of a new facility, specifying engineers and general contractors command substantial leverage, routinely playing equipment manufacturers against one another to negotiate pricing. In the hyperscale data center market, buyer leverage is even more pronounced: cloud developers engineer facilities alongside a restricted roster of two or three qualified suppliers and deliberately split order volumes among them to limit vendor lock-in, as management detailed to analysts.4 Once a building is occupied, however, buyer leverage recedes sharply. The property owner faces steep switching barriers, particularly for complex central chiller plants and code-mandated life-safety systems where third-party maintenance alternatives are limited.
The threat of substitutes is practically nonexistent for thermal management. Commercial structures and dense computing environments must reject thermodynamic heat to operate; no digital alternative can bypass the physical laws of heat dissipation. In building controls and monitoring software, by contrast, the substitution threat is meaningfully higher: open communication protocols and platform-agnostic supervisory software allow building operators to integrate rival equipment without relying on proprietary vendor controls.
Competitive rivalry is intense yet economically rational. The primary incumbents—Johnson Controls, Trane, and Carrier—compete vigorously on energy efficiency, equipment reliability, delivery lead times, and branch service coverage, while largely avoiding destructive price wars. In the generative AI infrastructure expansion, manufacturing throughput, factory capacity, and delivery speed have become critical competitive weapons.
Hamilton Helmer's 7 Powers
Scale economies provide a meaningful operational advantage across both centralized manufacturing and distributed field services. In branch operations, greater geographic density yields more efficient technician dispatch routes, shorter response times, and higher labor utilization. Management's claim that Johnson Controls commands roughly twice the field presence of its nearest competitor represents a genuine operational asset, provided route density translates into superior labor productivity.4
Switching costs represent a durable but unevenly distributed moat across the portfolio. Switching barriers are exceptionally high in life-safety fire protection and applied chiller maintenance, where specialized tooling, proprietary parts, and regulatory compliance create persistent customer inertia. In building automation, switching costs are moderate, constrained by open protocol standards. In electronic security, however, switching barriers are structurally weak: the company's acknowledged experience of losing contract volume when attempting to enforce higher service pricing demonstrates limited customer lock-in.4
Network effects are negligible. Telemetry and operational data harvested from one commercial facility provide no compounding utility or direct network benefit to occupants in another building.
Counter-positioning has historically hindered Johnson Controls rather than protected it. Incumbents anchored to high-margin, billable technician hours and branch labor models faced internal organizational friction when contemplating automated digital monitoring platforms or open software architectures that threatened to cannibalize on-site maintenance revenue.
Cornered resource advantages remain modest. A skilled mechanical field workforce is increasingly scarce, making the company's base of more than 90,000 employees an important operational reserve during industry expansions.4 Yet licensed technicians and sales engineers can be recruited away by competitors and independent contractors, rendering labor scale an operational capability rather than an unassailable proprietary asset.
Process power represents the central competitive battleground. Historically, peers like Trane established reputations for superior operational consistency, while Johnson Controls struggled with restructuring expenses and execution slippage. The rollout of a Danaher-inspired operating framework represents a direct effort to cultivate durable process power across the enterprise. During the June 2026 "Going to Gemba Day," leadership presented operational proof points, highlighting a computer room air handler line where branch and factory teams more than quadrupled production capacity without major capital investment, halved manufacturing lead times, and cut inventory by half.442 While these showcases indicate measurable lean improvements on specific factory floors, they represent company-selected case studies rather than audited, system-wide transformations.
The competitive contrast with Trane illustrates the challenge of distinguishing internal operational progress from broad macro tailwinds. Trane spent years operating as a focused climate pure play, establishing the financial and operational benchmark against which Johnson Controls is evaluated. In calendar 2025, Trane delivered record bookings of $22.6 billion, organic bookings growth of 11%, and a 22% surge in Americas commercial HVAC bookings.5 Those performance metrics demonstrate that unprecedented demand for hyperscale data center cooling and high-efficiency mechanical infrastructure has propelled the entire sector. A significant portion of Johnson Controls' recent financial acceleration reflects industry-wide cyclical momentum that its primary rival has captured with equal or greater vigor.
Branding remains a durable asset within institutional procurement channels. In commercial building design, legacy brands such as York, Simplex, and Metasys command deep familiarity and technical credibility among specifying engineers, providing Johnson Controls with a structural advantage when commercial blueprints are initially drafted.
The Competitive Verdict
Evaluated through structural frameworks, Johnson Controls possesses authentic competitive advantages: immense field scale, resilient switching barriers across complex HVAC and code-mandated fire safety, and respected brand equity among mechanical engineers. Its historical vulnerability has been process power—the organizational discipline required to convert an expansive installed base into consistent, peer-leading operating margins. The executive adoption of a Danaher-derived management system directly targets that structural deficiency. Whether those lean operational principles can overcome decades of conglomerate inertia is the question that will determine the company's long-term valuation. The next section tests whether the investment thesis driving Johnson Controls in 2026 can withstand rigorous scrutiny against its own corporate record.
XI. The Historical Falsification Layer: Testing Core Investment Claims (25–30 min)
Claim One: A Durable Moat in Controls and Equipment
The bullish investment thesis contends that Johnson Controls' massive installed base—particularly its Metasys building automation systems and embedded branch service relationships—creates an unassailable customer lock-in moat.
The primary mechanism that would falsify that claim is customer multi-sourcing, made possible by open communication protocols and third-party system integrators. Operating evidence confirms that this competitive erosion is real. The widespread adoption of open industry standards and supervisory software platforms like Tridium Niagara has made it straightforward for facility owners to mix hardware vendors and contract independent system integrators rather than relying on proprietary branch labor.27 In commercial security, management's acknowledgment that the business surrendered service volume after pushing aggressive price increases provides direct proof that customers will defect when pricing discipline is tested.428
Conversely, field evidence confirms that the switching moat remains durable in complex applied HVAC and life safety. Management reported that HVAC and fire service revenues continued expanding within their mid- to high-single-digit target ranges, while the company's surging installed base of hyperscale data center chillers and air handlers is positioned to expand that recurring maintenance pool over time.4
The historical record therefore narrows the original claim. Johnson Controls does not possess a universal customer lock-in moat across commercial building technology. It commands an exceptionally sticky position in heavy thermal machinery and code-mandated fire inspections, counterbalanced by a far more contestable posture in digital controls and electronic security. The operational milestone that would validate this narrowed claim is sustained mid- to high-single-digit organic service growth as newly commissioned data center cooling plants mature into long-term service agreements.
Claim Two: Scale and Portfolio Breadth Created Resilience
A second enduring defense of the legacy conglomerate model held that diversification across products, end markets, and geographies insulated Johnson Controls from macroeconomic shocks. Four decades of corporate capital allocation largely refute that thesis. The company spent generations accumulating capital-intensive automotive battery and seating operations before expensively spinning them off. It absorbed a residential heating and cooling business through York, doubled down through the Hitachi joint venture, and ultimately divested both to Bosch for $8.1 billion after years of margin drag.39 It merged with Tyco partly to integrate electronic security into a unified digital building platform, only to find itself in 2026 exploring a sale of those core security product lines for up to $4.5 billion.22 Portfolio trimming followed the same pattern across international territories: Johnson Controls divested ADT Mexico in October 2025 for net proceeds of $207 million, completed the sale of ADT Spain in April 2026 for $98 million, and agreed to divest its United Kingdom residential security business.44
The pattern is unmistakable: substantial capital deployed in pursuit of portfolio scale was later systematically unwound. Historically, broad operational breadth diluted executive focus and depressed return on invested capital rather than providing downside protection. Johnson Controls has generated its highest-quality returns when operating as a focused commercial building systems and solutions provider. For investors, the question is whether executive leadership has permanently absorbed that lesson. On the third-quarter fiscal 2026 earnings call, Weidemanis noted that the company might make "surgical" moves into electrical distribution capabilities through partnerships or targeted acquisitions.4 Given the enterprise's corporate history, any capital allocation straying beyond the core thermal and life-safety perimeter warrants rigorous investor scrutiny.
Claim Three: Margin Expansion Is Locked In
The argument that Johnson Controls has permanently structuralized higher operating margins faces the most direct historical test. At its September 2021 investor day, prior management targeted compound annual adjusted earnings per share growth of 18% to 21% through fiscal 2024, but delivered roughly 12%.353721 Compounding that shortfall, reported GAAP results persistently trailed adjusted figures by a wide margin. In fiscal 2025, GAAP diluted earnings of $2.63 per share fell well short of adjusted earnings of $3.76, weighed down by $546 million in restructuring and impairment costs, $180 million in transformation expenses, and $102 million in accelerated depreciation on enterprise resource planning assets.1
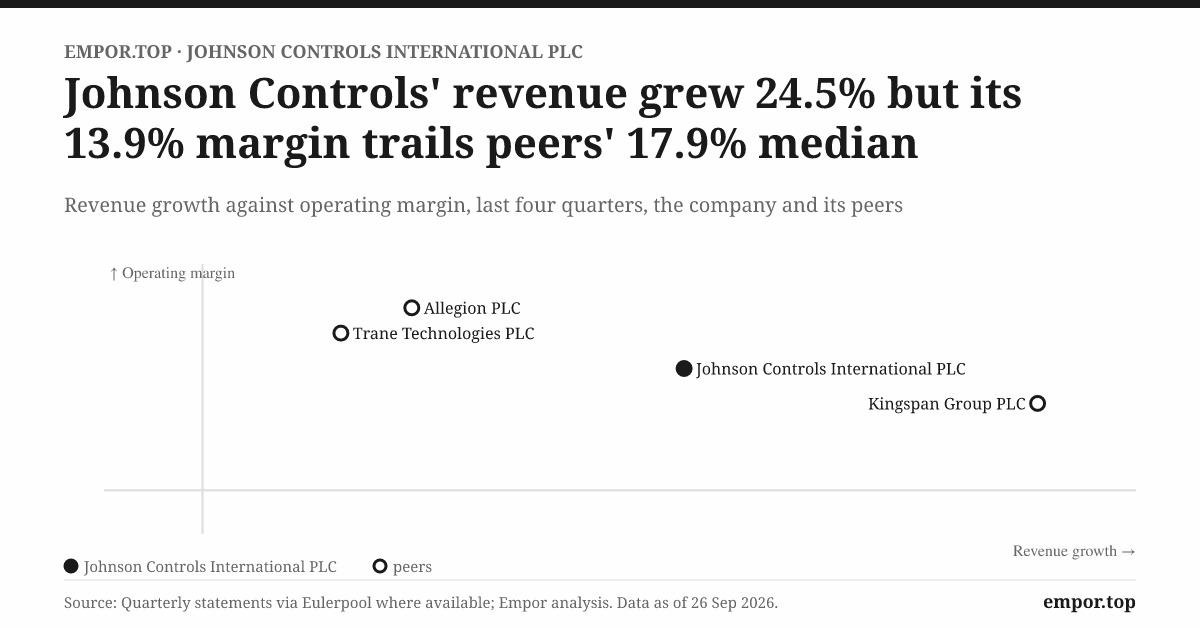
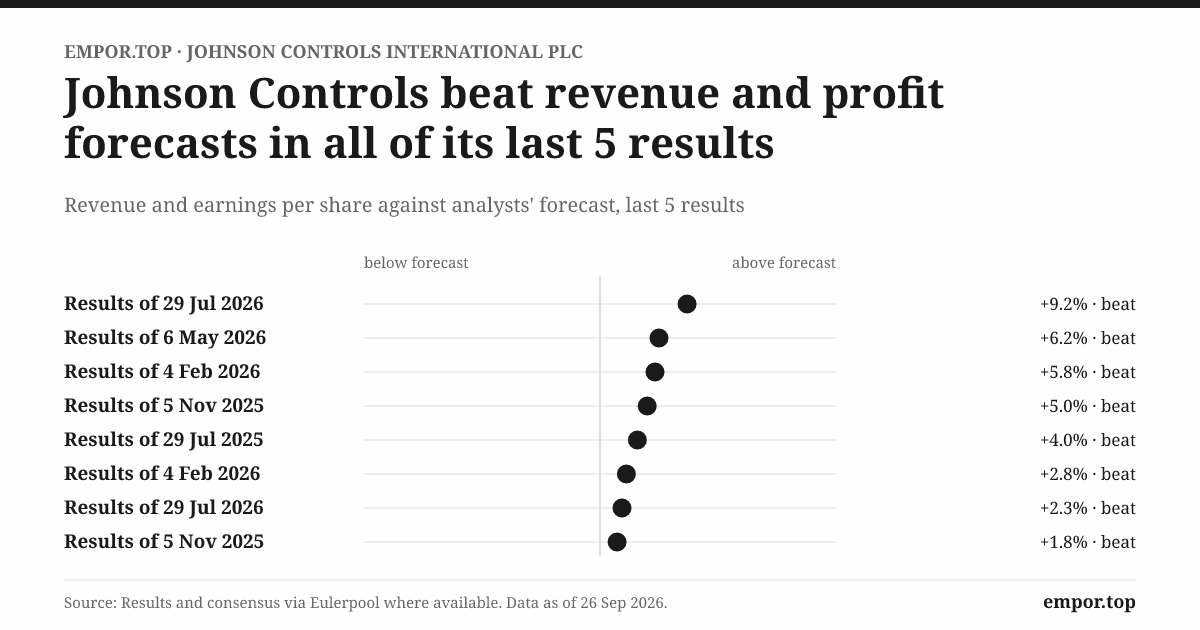
The reconstituted leadership team under Weidemanis has established a more dependable forecasting rhythm. Management initiated fiscal 2026 adjusted earnings guidance at roughly $4.55 per share in November 2025, lifting that outlook to about $4.70 in February, $4.85 in May, and $5.05 in July.129306 In the third quarter of fiscal 2026, adjusted segment EBIT margin expanded 260 basis points year-over-year to 17.0%.4 That performance narrowed the historical gap with Trane Technologies, which delivered a full-year 2025 adjusted operating margin of 18.5%, though an isolated fiscal quarter cannot be equated directly with a complete operating year.5
Meanwhile, the legacy divergence between GAAP and non-GAAP results has not fully disappeared. Restructuring expenses totaled $224 million during the first nine months of fiscal 2026, leaving nine-month GAAP earnings of $3.12 per share trailing adjusted earnings of $3.50 per share.45 The balanced verdict is that while current margin expansion is tangible, its structural durability remains unproven. The present margin surge coincides with an extraordinary data center construction wave that provides substantial pricing leverage and factory absorption across the applied cooling industry. The definitive operational test will arrive when secular demand normalizes: if operating margins remain resilient in the high teens and restructuring adjustments finally fade, the thesis of permanent operational reform will be confirmed.
A Note on Legal Overhangs
One material risk sits outside everyday manufacturing and branch service operations. In April 2024, company subsidiary Tyco Fire Products agreed to a $750 million settlement to resolve class-action claims brought by nationwide public water systems concerning per- and polyfluoroalkyl substances, or PFAS, allegedly linked to aqueous film-forming firefighting foams.46 Johnson Controls recognized a pre-tax charge of $750 million in fiscal 2024, partially offset by $367 million in expected insurance recoveries, and continued to record insurance proceeds across fiscal 2026.2145 However, because the settlement covered only public water systems that had detected PFAS contamination as of May 15, 2024, it did not resolve potential future exposure from other municipal water authorities or private tort claims.46 Environmental indemnification remains an unresolved legacy from the Tyco acquisition that warrants ongoing monitoring.
Subjecting Johnson Controls' core claims to historical falsification leaves the investment case at an inflection point. The enterprise is more focused, better capitalized, and operationally tighter than at any point since the 2016 Tyco inversion. Yet validating the thesis requires proving that recent margin acceleration stems from institutionalized operational discipline rather than the transient tailwind of an unprecedented data center capital expenditure cycle. That unresolved tension sets the stage for the competing bull and bear cases.
XII. The Investment Spine: Bull vs. Bear Case & What to Watch (20–25 min)
The Neutral Thesis
In the autumn of 2026, Johnson Controls stands as a streamlined commercial building systems provider anchored by applied HVAC, life-safety fire protection, and recurring branch services, with expanding exposure to hyperscale data center cooling. Its operational results have reached multi-year highs. The central dilemma for investors is whether that acceleration marks a lasting internal operational transformation or the crest of a cyclical demand wave that temporarily flatters its product line.
The Bull Case
The bull case rests on three distinct pillars.
The first is structural data center demand. A record order backlog of $21.0 billion and executive projections that data centers will expand to roughly one-third of total corporate revenue within three to five years provide the business with rare revenue visibility.64 If leadership executes against that backlog, commissioning thousands of chillers and air handlers today establishes an expanded installed base that should generate high-margin aftermarket maintenance contracts for decades to come.
The second pillar centers on portfolio simplification. Divesting the residential heating and cooling business to Bosch removed an erratic, lower-margin consumer segment and sharply reduced corporate complexity, while leadership continues to prune regional security assets.3944 That balance-sheet discipline left net debt at $8.8 billion at the end of the fiscal third quarter of 2026, or 1.9 times adjusted EBITDA—comfortably below management's long-term target leverage range.6
The third pillar is internal operational execution. The Danaher-inspired management system has begun delivering measurable efficiency gains in targeted manufacturing cells, and the long-term financial algorithm introduced in June 2026 targets high-single-digit organic revenue growth, operating leverage exceeding 30%, double-digit adjusted earnings growth, and 95% to 100% free cash flow conversion.4 If the executive team delivers on those commitments, operating margins could continue to close the historical gap with top-tier industrial peers.
The Bear Case
The bear case highlights four corresponding operational vulnerabilities.
The primary risk is the cyclicality of AI infrastructure spending. On the third-quarter fiscal 2026 earnings call, analyst Jeffrey Sprague questioned whether hyperscale customers could earn acceptable economic returns on their massive artificial intelligence capital investments. Weidemanis expressed optimism grounded in the early stage of enterprise AI adoption, yet openly acknowledged that his assessment was "an opinion."4 Should cloud platforms decelerate their construction tempo or reevaluate capital expenditures, equipment order growth could contract rapidly just as Johnson Controls brings expanded factory capacity online.
The second risk is customer concentration and procurement leverage. A small cohort of hyperscale technology platforms accounts for an outsized portion of incremental demand, and these buyers systematically split contract awards across a restricted roster of approved manufacturers to limit pricing power.4 Furthermore, this surge in data center installations tilts corporate revenue toward upfront mechanical equipment, which the chief financial officer acknowledged creates a modest margin headwind relative to higher-margin field services.4
The third risk lies in field execution. The lean operating framework originated in standardized, repetitive manufacturing environments. Adapting those principles across a decentralized network of local branch offices handling bespoke installation projects, fixed-price contracts, and unionized trade labor presents far steeper organizational friction than factory showcases suggest. Underscoring that friction, organic service orders expanded just 4% in the third quarter of fiscal 2026, while commercial security services remained under margin pressure.4
The fourth risk encompasses regional volatility and environmental liability. The Middle East accounts for approximately 10% of EMEA segment revenue and has experienced operational disruptions from regional conflict, contributing to muted EMEA revenue growth of just 1% in the third quarter.46 Concurrently, lingering liabilities from municipal and tort litigation over PFAS firefighting foam represent an unresolved long-term financial drag.46
An Activist's Stress Test
A rigorous activist appraisal raises four foundational questions. Why do restructuring and transformation expenses continue to absorb hundreds of millions of dollars annually after a full decade of portfolio overhauls? Why has leadership declined to disclose standalone software revenue after years of marketing OpenBlue as a strategic platform? Will proceeds from potential security divestitures be returned to shareholders, or redeployed into adjacent industrial hardware? And how much of recent operating margin expansion stems from factory absorption during a cyclical volume surge rather than permanent labor productivity? These inquiries do not dismiss the turnaround, but they establish the burden of proof facing executive leadership.
Three second-layer diligence considerations reinforce that skepticism. First, the corporate balance sheet is functional but carries limited idle liquidity: net debt of $8.8 billion and cash reserves of roughly $641 million at the end of the third quarter of fiscal 2026 reflect an enterprise that has prioritized aggressive share repurchases over building cash reserves.6 While that strategy maximizes capital returns during an industry upcycle, it narrows financial flexibility if demand cools while capital commitments for factory expansion remain active. Second, the recurring presence of insurance recoveries and portfolio gains in the non-GAAP reconciliation bridge requires investors to scrutinize quarterly earnings quality with exceptional care.6 Third, reported deliberations regarding a potential sale of the security products division present a double-edged dynamic: a lucrative transaction would finalize portfolio purification, yet a discounted valuation would serve as a tangible reminder of the shareholder capital stranded in the 2016 Tyco combination.22
The Three KPIs That Matter
To evaluate which narrative unfolds, investors should monitor three key performance indicators:
First, applied HVAC and data center order momentum alongside backlog conversion. The vital metric is whether quarterly equipment bookings continue to outpace recognized revenues, and whether record backlog converts into billings without project delivery delays or cost overruns.
Second, organic field-service revenue growth. High-margin branch service represents the compounding economic core of the enterprise and the primary measure of its installed-base switching moat. Management has set an objective to sustain organic service expansion in the mid- to high-single-digit range; verifying that newly installed data center chillers convert into recurring maintenance agreements will confirm the health of that engine.4
Third, the spread between GAAP and adjusted net earnings. If the proprietary business system delivers sustainable operational discipline, restructuring charges, facility realignment costs, and non-operating adjustments should systematically taper, allowing reported GAAP results to converge steadily with adjusted earnings per share.
The concluding question confronting shareholders is as much historical as financial: after 140 years of conglomerate expansion, corporate inversions, and strategic divestitures, has Johnson Controls finally returned to the disciplined mechanical core where its story began?
XIII. Epilogue: What Would Warren Johnson Think? (15–20 min)
From a Bell to a Brain
In 1883, Warren Johnson sought to eliminate the manual labor of a janitor walking hallways to adjust boiler dampers in a cold Wisconsin classroom. His device sensed ambient temperature and rang a bell in the basement—an innovation grounded in a straightforward premise: allow the building to communicate its own operational requirements.3
Nearly a century and a half later, in 2026, the enterprise he established engineers thermal management architectures for hyperscale data centers, developing absorption chillers designed to convert waste heat into cooling alongside liquid cooling distribution units certified for NVIDIA hardware.4 The basement bell has evolved into supervisory digital control algorithms, the classroom into an expansive data hall, and the dampers into motorized valves modulating chilled-water loops to protect billions of dollars in high-performance computing silicon. The underlying thermodynamic reality, however, remains unchanged: commercial facilities remain machines designed to move air, heat, and water.
The Lesson of the Detour
The central lesson of Johnson Controls' 140-year trajectory is that its most resilient economic value has always resided in the mechanical room: engineering, controlling, and maintaining the critical physical infrastructure that keeps complex facilities functional. Over four decades, automotive batteries, vehicle seating, residential furnaces, and an expansive electronic security portfolio were each accumulated under the strategic banner of portfolio diversification and scale. Yet each addition introduced capital dispersion and managerial friction, and each was ultimately spun off, divested, or placed on the auction block.
That historical unwind does not guarantee that the modern enterprise will automatically match top-tier industrial peers. Rather, it clarifies where the burden of operational proof resides. Johnson Controls enters late 2026 with a degree of portfolio clarity it lacked for generations, a substantial order backlog tied to the secular expansion of artificial intelligence infrastructure, and an executive leadership team applying standardized lean manufacturing discipline. What it has yet to demonstrate is a sustained record of peer-level operating profitability and GAAP cash generation across an entire macroeconomic cycle.
Warren Johnson's enterprise began by designing a building that could monitor its internal state and signal when mechanical adjustments were required. The company's long-term future rests on its ability to apply that same feedback loop to its own operations: measuring performance with GAAP transparency, responding rapidly to field-level execution bottlenecks, and resisting the historical temptation to wander far from its mechanical core.
References
-
Johnson Controls Reports Q4 and FY25 Results; Initiates FY26 Guidance (Form 8-K Exhibit 99.1) — Johnson Controls International plc, SEC EDGAR, 2025-11-05 ↩↩↩↩
-
Johnson Controls International plc Form 10-K for Fiscal Year Ended September 30, 2025 — SEC EDGAR, 2025 ↩↩↩↩↩↩
-
Johnson Controls — Encyclopedia of Milwaukee, University of Wisconsin–Milwaukee ↩↩↩↩↩↩↩↩↩
-
JCI Q3 FY2026 Earnings Call — BigGo Finance, 2026-07-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Trane Technologies Reports Strong Fourth-Quarter and Full-Year 2025 Results — Trane Technologies, 2026-01-29 ↩↩↩
-
Johnson Controls Reports Strong Q3 Results; Raises FY26 Guidance (Form 8-K Exhibit 99.1) — Johnson Controls International plc, SEC EDGAR, 2026-07-29 ↩↩↩↩↩↩↩↩↩↩↩
-
Activist Hedge Fund Elliott Builds $1 Billion-Plus Stake in Johnson Controls — Bloomberg, 2024-05-20 ↩↩
-
Johnson Controls to Sell Residential and Light Commercial HVAC Businesses — Johnson Controls, 2024-07-23 ↩↩
-
Johnson Controls Announces Initiation of CEO Succession Following Significant Milestones in Portfolio Transformation — Johnson Controls, 2024-07-31 ↩↩
-
Aug. 25, 2005: Johnson Controls To Acquire York — ACHR News ↩↩
-
Johnson Controls and Hitachi Complete Global Air Conditioning Joint Venture — Hitachi, 2015-10-01 ↩
-
Johnson Controls and Tyco to Merge — SDM Magazine, 2016-01-25 ↩
-
Tyco International plc Form 424B3 Joint Proxy Statement/Prospectus — SEC EDGAR, 2016 ↩↩
-
Johnson Controls and Tyco Complete Merger — SDM Magazine, 2016-09-06 ↩↩
-
Hillary Clinton Says Johnson Controls Got Federal Bailout — PolitiFact, 2016-02-11 ↩↩
-
Hillary Clinton Statement on Johnson Controls-Tyco Inversion Deal — The American Presidency Project, 2016-01-25 ↩
-
Johnson Controls CEO Succession Press Release (Form 8-K Exhibit 99.1) — Johnson Controls International plc, SEC EDGAR, 2017-08-21 ↩
-
Johnson Controls Reports Q4 and FY24 Results (Form 8-K Exhibit 99.1) — Johnson Controls International plc, SEC EDGAR, 2024-11-06 ↩↩↩↩↩↩
-
Johnson Controls Said to Weigh $4.5 Billion in Divestitures — Bloomberg, 2026-04-15 ↩↩↩
-
Johnson Controls International plc Form 10-Q for Quarter Ended December 31, 2016 — SEC EDGAR, 2017 ↩
-
Adient Ltd Form 10 Information Statement (Exhibit 99.1) — SEC EDGAR, 2016 ↩
-
Johnson Controls Reports Strong Organic Revenue and Earnings Growth in Fiscal Q2; Closes Sale of Power Solutions Business — PR Newswire, 2019-05-01 ↩↩↩
-
Johnson Controls International plc Announces Cash Tender Offer for up to $4,000,000,000 of Its Ordinary Shares — PR Newswire, 2019-05-03 ↩
-
Johnson Controls Flags Security Services Reset in Q2 2026 — Security Systems News, 2026-05 ↩↩
-
Johnson Controls Q1 FY26 Earnings Release (Form 8-K Exhibit 99.1) — Johnson Controls International plc, SEC EDGAR, 2026-02-04 ↩↩
-
Johnson Controls Revised Q2 FY26 Earnings Release (Form 8-K/A Exhibit 99.1) — Johnson Controls International plc, SEC EDGAR, 2026-05-06 ↩↩
-
Johnson Controls Agrees to Acquire Silent-Aire to Accelerate Growth in Hyperscale Data Center Vertical — Johnson Controls, 2021-04-09 ↩
-
Johnson Controls International plc Form 10-Q for Quarter Ended June 30, 2021 — SEC EDGAR, 2021 ↩↩
-
Johnson Controls Signs Agreement to Acquire Alloy Enterprises, Strengthening Data Center Thermal Management Leadership — Johnson Controls, 2026-02-18 ↩
-
Johnson Controls Launches OpenBlue — Johnson Controls, 2020-07-31 ↩
-
Johnson Controls Hosts Virtual Investor Day; Reaffirms 2021 Guidance and Announces Three-Year Financial Targets — Johnson Controls, 2021-09-08 ↩↩↩
-
Johnson Controls Says Ransomware Attack Cost $27 Million, Data Stolen — BleepingComputer, 2024 ↩↩
-
Johnson Controls Reports Solid Fourth Quarter and Full Year Results; Initiates FY22 Guidance — PR Newswire, 2021-11-05 ↩↩
-
Johnson Controls CEO to Retire After 'Constructive' Conversations with Activist Elliott; Shares Surge — CNBC, 2024-07-31 ↩↩
-
Johnson Controls Completes Sale of Residential and Light Commercial HVAC Business — Johnson Controls, 2025-08-01 ↩↩↩↩↩
-
Johnson Controls to Sell Air Distribution Technologies Business to Truelink Capital — Johnson Controls, 2024-06-18 ↩
-
Johnson Controls Announces Joakim Weidemanis as Next CEO (Form 8-K Exhibit 99.2) — Johnson Controls International plc, SEC EDGAR, 2025-02-05 ↩↩
-
Johnson Controls to Host "Going to Gemba Day" on June 1 — Johnson Controls, 2026-05-22 ↩↩
-
Carrier Completes Acquisition of Viessmann Climate Solutions — Carrier Global, 2024-01-02 ↩
-
Johnson Controls International plc Form 10-Q for Quarter Ended June 30, 2026 — SEC EDGAR, 2026 ↩↩
-
Johnson Controls Reports Strong Q3 Results; Raises FY26 Guidance — Johnson Controls Investor Relations, 2026-07-29 ↩↩
-
PFAS-Affected Water Systems to Receive $750M in Settlement with Tyco Fire Products — WPR ↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube