Sony Group Corporation: From Post-War Transistor Pioneer to Entertainment & Sensing Colossus
I. Introduction & The Transformation Thesis
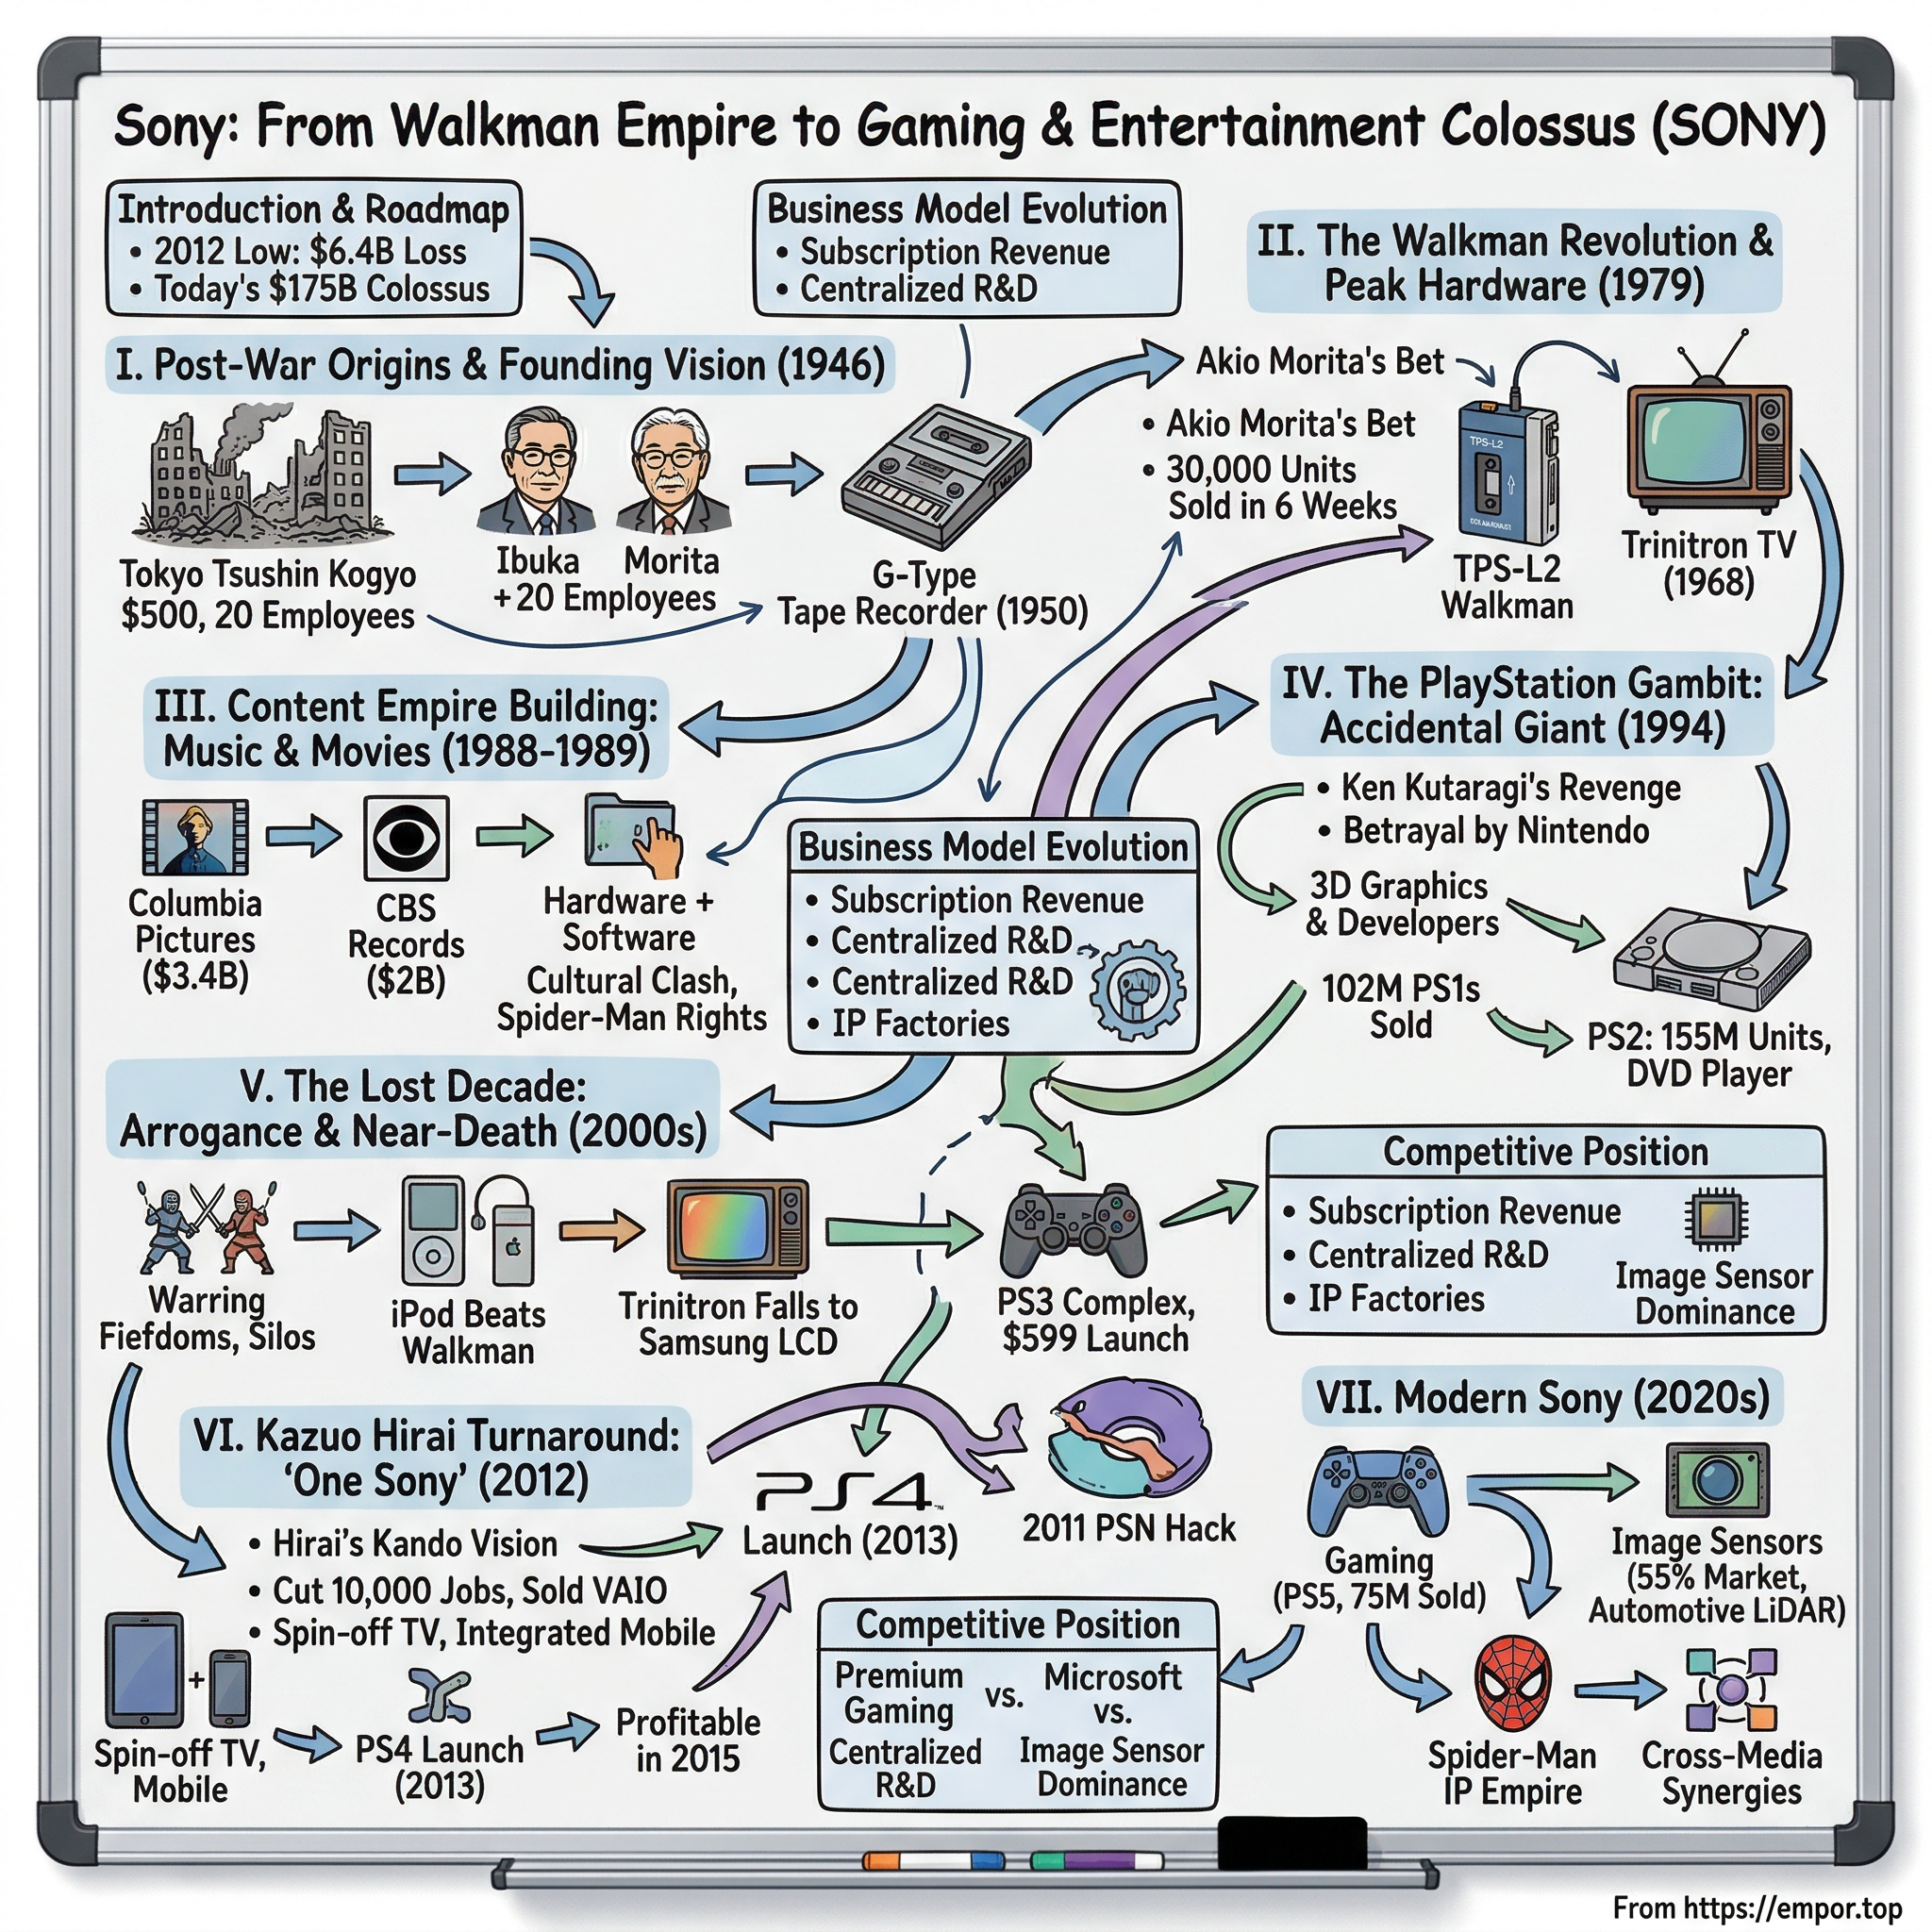
Picture two very different rooms, separated by eight decades. The first was a burned-out floor of a Tokyo department store in the months after Japan's surrender, where a handful of engineers repaired radios on salvaged benches and dreamed about building things nobody else could make. The second was a Tokyo conference hall on May 8, 2026, where Hiroki Totoki (十時 裕樹), a finance-trained chief executive, walked investors through a fiscal year of record sales of ¥12.48 trillion and record operating income of ¥1.45 trillion1 — and spent much of the Q&A discussing not consumer gadgets, but memory-chip prices, anime franchises, music catalogs, and a new joint venture with TSMC2.
The distance between those two rooms is the story of Sony Group Corporation (ソニーグループ株式会社; NYSE: SONY, TSE: 6758). It is the narrative of an enterprise that invented a defining consumer category roughly once a decade, lost its bearings so severely that its debt rating slid to speculative grade3, and then rebuilt its foundation around businesses its founders would barely recognize.
The central paradox is simple to state but difficult to explain. Sony was once the quintessential Japanese hardware powerhouse — the creator of the pocket transistor radio, the Trinitron television, the Walkman, and the PlayStation. Its peers in that tradition, the storied electronics conglomerates of Osaka and Tokyo, spent the 2000s and 2010s being hollowed out by Korean and Chinese competitors. Sony appeared destined for the same fate. Instead, in the fiscal year ended March 2026, the segments driving the majority of its operating profit were a gaming platform, a music publishing and recorded-music empire, and an image-sensor business1. Meanwhile, the legacy television operation, the last major pillar of the old Sony, is being transferred to a joint venture controlled by China's TCL4.
The financial results illustrate this shift in compressed form. In FY2023 (the fiscal year ended March 2024), Sony reported ¥13.02 trillion in revenue and ¥1.21 trillion in operating income; one year later, operating profit reached ¥1.41 trillion5. Then, in October 2025, Sony distributed 83.6% of its financial-services arm to shareholders6, shrinking its top-line revenue base while enhancing its consolidated operating margins. Following a strong first quarter in FY2026, management raised its full-year operating-income guidance to ¥1.72 trillion7.
The contemporary company operates through five engines. Game & Network Services (PlayStation) generates the largest share of revenue. Music — comprising Sony Music Entertainment, Sony Music Publishing, and Japan's Aniplex — serves as the steadiest compounder of earnings. Pictures, which includes the anime streaming platform Crunchyroll, operates as a content studio that deliberately avoided building a costly mass-market streaming service. Imaging & Sensing Solutions manufactures the CMOS image sensors found in a substantial share of the world's premium smartphones. Finally, Entertainment, Technology & Services (ET&S) encompasses what remains of the historic consumer-electronics empire: cameras, audio gear, and — until 2027 — televisions.
That architecture raises the core question of this analysis: is Sony an inherently advantaged owner of proprietary platforms and intellectual property, or a well-managed conglomerate whose revival has been magnified by a weak yen, a fortunate sensor customer relationship, and a single, exceptionally successful console cycle? The evidence suggests that while key components of the transformation thesis have proved durable, others have narrowed, and some remain management aspirations rather than confirmed structural moats.
The spine of the argument
Evaluating the investment case requires weighing three distinct competitive advantages against four structural vulnerabilities. The bull thesis rests on clear foundations. First, substantial switching costs and network effects protecting PlayStation: hundreds of millions of dollars of digital purchases sit inside player accounts, and game publishers invariably gravitate to where active players congregate. Second, cornered intellectual property: irreplaceable music copyrights, the Spider-Man film and merchandising rights, and an expanding anime library that competitors cannot easily duplicate. Third, proprietary process engineering in image sensors that global rivals have chased for more than a decade without eliminating the performance gap at the high end.
The counterarguments are equally concrete. Development budgets for flagship games are expanding faster than the addressable player base; cyclical console hardware dynamics continue to govern a significant portion of PlayStation's unit economics; the image-sensor business remains heavily exposed to a single dominant smartphone customer and concentrated fabrication facilities in an active earthquake zone; and Sony's corporate ledger includes some of the costliest acquisition write-downs in entertainment history. Layered over all these fundamentals is foreign exchange: reporting in yen while earning heavily in US dollars and euros inflates reported earnings when the Japanese currency weakens — and the yen has been historically depressed.
Neither narrative is conclusive in isolation. The task here is to measure each proposition against Sony's demonstrated operational record and determine which claims hold up under scrutiny.
The road ahead
The story unfolds across eight decades: from the charred floor of a Tokyo department store; through the global phenomenon of the Walkman and the flawed assumption that controlling hardware and content together would guarantee victory; through a humiliating rupture with Nintendo that inadvertently created PlayStation; through the lost decade marked by the iPod, the troubled PlayStation 3 rollout, and record corporate losses; through the turnaround executed by Kazuo Hirai and Kenichiro Yoshida; and ultimately to today's critical tests of capital allocation — including the acquisition of Bungie, the global monetization of anime, customer concentration in sensors, and the carve-out of the financial-services division. Each chapter offers vital context for evaluating Sony today, tracing back to the founders' founding conviction: to build what others could not.
 Subscribe on LinkedIn
II. Post-War Crucible & The Transistor Breakthrough (1946–1970s)
Two men and a department store
In the autumn of 1945, Tokyo was a city of ash and rubble. In the Nihonbashi district, inside the damaged Shirokiya department store, an engineer named Masaru Ibuka (井深 大) set up a modest radio-repair workshop. He was an inventive engineer with restless technical curiosity, determined to build civilian products that would restore purpose to Japan's post-war technical community.
His partner arrived from a very different background. Akio Morita (盛田 昭夫), the eldest son of a family of sake brewers spanning fourteen generations, was trained in physics but possessed a commercial instinct Ibuka lacked. Where Ibuka asked whether a device could be engineered, Morita asked who would buy it and how to reach them. That division of labor — the technical purist and the market dealmaker — defined Sony's executive dynamic for four decades.
The enterprise they established in May 1946 was Tokyo Tsushin Kogyo (東京通信工業, or Tokyo Telecommunications Engineering Corporation)8. Ibuka's founding prospectus outlined an unusual mandate for a cash-strapped startup: establish an ideal factory where engineers could exercise technical creativity with autonomy, avoid superficial commercial compromises, and develop products competitors could not match. The document read less like a conventional business plan than a design manifesto — establishing a stubborn engineering pride that would repeatedly define, and occasionally imperil, the business.
Early failures
The company's initial years were precarious. The young team experimented with an electric rice cooker that produced inconsistent batches and a heated cushion — stopgap consumer novelties improvised to meet payroll. Their first ambitious product, a magnetic tape recorder, was cumbersome and expensive: technically sophisticated, yet commercial deadweight. The lesson Morita extracted became an enduring theme in consumer hardware: engineering distinction does not automatically generate commercial demand. By repositioning the machine as an instructional and institutional tool for schools and courtrooms, he secured buyers who valued functional utility rather than novel hardware for its own sake.
The transistor bet
The decisive breakthrough stemmed from a calculated bet on a component its own creators had largely pigeonholed. In the early 1950s, the company licensed transistor patents from Western Electric, the manufacturing arm of AT&T whose Bell Laboratories had invented the semiconductor device9. Prevailing industry consensus held that early transistors lacked the frequency range for complex consumer electronics, relegating them to hearing aids. Ibuka, however, was determined to build mass-market radios.
Sony introduced the TR-55 in 1955, followed in 1957 by the TR-63, promoted as the world's smallest transistor radio and serving as the company's first major export to North America9. When the device proved marginally too large for a standard dress shirt pocket, management coined the descriptor "pocketable" and outfitted sales representatives with custom shirts featuring slightly enlarged pockets9. The maneuver illustrated early Sony commercial methodology: legitimate miniaturization engineering bolstered by theatrical merchandising. Despite carrying a retail price equivalent to roughly a month's wages for an average Japanese worker, the TR-63 sold briskly9.
A name built for the world
In January 1958, the enterprise officially renamed itself Sony Corporation8. The name combined the Latin sonus (sound) with the mid-century American colloquialism "sonny," deliberately discarding traditional Japanese corporate nomenclature in favor of a short, phonetically universal trademark that consumers in New York, London, or Hamburg could easily pronounce. Morita recognized that post-war Japanese exporters faced pervasive international skepticism regarding manufacturing quality. Establishing a distinctive, borderless brand identity was not a marketing vanity, but a strategic imperative to escape the low-margin commodity trap.
The Trinitron gamble
Sony entered color television late, and its initial technical choice nearly ruined the company. In 1965, management licensed a cathode-ray technology called Chromatron, but the design proved exceedingly difficult to mass-produce, yielding production costs that far exceeded retail pricing — an operational drain that, in IEEE Spectrum's account, was threatening to sink the company10. Ibuka personally supervised a dedicated four-engineer team to abandon Chromatron and develop an alternative architecture using a single electron gun and a vertical "aperture grille" rather than the industry-standard shadow mask10.
To understand the mechanism: a conventional color television screen functioned like a barrier punctured by thousands of tiny holes, filtering electron beams onto red, green, and blue phosphor dots. Because this shadow mask absorbed and blocked substantial electron energy, picture brightness suffered. Sony's aperture grille used fine, vertically tensioned slits instead, allowing far more electron energy through to produce a noticeably brighter and sharper image. The Trinitron, unveiled in 1968, became an immediate commercial success; Sony eventually sold 280 million Trinitron televisions and computer monitors, and in 1973 it became the first consumer electronics device to receive an Emmy Award10.
The Trinitron delivered an advantage that extended beyond direct operational profits. It established a durable premium pricing umbrella — consumers routinely paid a substantial markup for Sony displays because the visual contrast was immediately apparent — and helped alter the international reputation of Japanese manufacturing10. For investors, the enduring takeaway from this formative era is a recurring operating pattern: Sony proved most formidable when commercializing proprietary technologies it controlled end-to-end and could market as categorically superior. The subsequent era would test whether that engineering-led formula could extend from standalone hardware into global consumer culture.
III. The Walkman Era & Peak Hardware Hegemony (1979–1990s)
An old man's opera request
In early 1979, Masaru Ibuka — by then Sony's honorary chairman and a frequent international traveler — asked company engineers for a way to listen to opera on long flights without disturbing fellow passengers11. The engineering team adapted the Pressman, a portable cassette recorder built for journalists, by removing the recording circuitry and built-in speaker, incorporating stereo playback components, and pairing the device with lightweight headphones. Whereas conventional headphones at the time weighed nearly as much as the player itself, Sony's redesigned set weighed approximately 50 grams11.
Akio Morita recognized that the device possessed commercial potential far beyond senior executives, identifying younger consumers as the primary market. Inside Sony, the proposal met initial resistance: marketing and engineering staff argued that a tape player lacking recording capability represented a functional step backward. Morita overruled internal skepticism and mandated commercial production. The TPS-L2 debuted in Japan in 1979 and reached the United States in 1980, initially branded as the "Soundabout," with a retail price of approximately $15011.
Why the Walkman mattered
Initial sales were modest, but the fitness and outdoor recreation boom of the early 1980s accelerated adoption, transforming the Walkman from a niche electronic novelty into a global cultural phenomenon11. By the end of March 1999, cumulative sales of cassette-based Walkman devices reached 186 million units11. Yet unit volume captured only part of the commercial disruption: the product detached recorded audio from static home stereo systems and automobiles, establishing personal, mobile listening as a permanent consumer habit. Contemporary digital audio formats and wireless listening hardware trace their behavioral blueprint directly to that shift.
The device also solidified Sony's corporate self-conception as the arbiter of global media consumption hardware. That institutional confidence later provided the ambition needed to launch PlayStation as a proprietary gaming platform, but it also fostered an insularity that left the company vulnerable when software-driven competitors, led by Apple, redefined portable digital music two decades later.
The compact disc and the standards game
In the early 1980s, Sony collaborated with the Dutch electronics group Philips to establish the Compact Disc standard. Sony contributed key technical architecture, notably the cross-interleave Reed-Solomon code for digital error correction and the physical optical format specifications, which together established the CD as the world's dominant audio format for the next two decades. Executive Norio Ohga (大賀 典雄) — a former opera student who would later serve as Sony's president and chief executive — championed a disc capacity long enough to accommodate a full performance of Beethoven's Ninth Symphony, according to company lore. The CD became an enduring standards triumph because Sony and Philips licensed the specifications broadly across the electronics and recording industries, turning open adoption into an industry-wide platform victory.
Betamax: the lesson that shaped thirty years
The collaborative success of the Compact Disc stood in sharp contrast to a costly setback Sony had suffered just years earlier. In 1975, Sony introduced Betamax, a videocassette recorder engineered with high-fidelity video reproduction. However, JVC's competing VHS format offered longer recording capacity — two hours initially, allowing users to tape full sporting events and movies — and JVC licensed the technology broadly to competing equipment makers. As the home video rental market expanded, VHS became the de facto industry standard, turning Betamax into a classic business-school case study of technical superiority defeated by network distribution and licensing scale.
From the Betamax defeat, Sony's executive leadership drew an influential, yet fundamentally skewed, strategic conclusion: that controlling content was the decisive prerequisite for format supremacy. If Sony owned major Hollywood studios and music catalogs, management reasoned, it could guarantee studio backing for proprietary physical media formats and avoid being marginalized again. That conviction — treating hardware and entertainment software as an interdependent fortress — would justify the largest capital deployments and acquisitions in the company's history.
For investors evaluating Sony's corporate evolution, the Walkman era represented the zenith of the company as an uncontested hardware powerhouse, but it also sowed the seeds of its most value-destructive strategic error. The operational lesson of Betamax centered on the commercial power of open licensing and ecosystem breadth. The lesson Sony's leadership internalized, by contrast, was that physical format security required content ownership. The subsequent era demonstrated the immense financial cost of that miscalculation.
IV. Content Empire Gambit: CBS Records, Columbia Pictures, and the Synergy Illusion (1988–2000s)
The opera singer in the corner office
Norio Ohga was not a conventional Japanese electronics executive. A trained opera singer whom Akio Morita had recruited directly from the music world, Ohga rose through the corporate ranks to lead the enterprise, bringing an artist's temperament to an engineering culture and an unshakeable conviction that Sony's future lay in owning the content that played on its devices.
Buying the content
In November 1987, Sony agreed to acquire CBS Records for approximately $2 billion, completing the transaction in January 198812. CBS Records was then widely recognized as the world's largest record producer, boasting a roster that included Michael Jackson, Bruce Springsteen, Barbra Streisand, and Billy Joel12. The two companies were already well acquainted: they had operated a successful Japanese joint venture, CBS/Sony, since 196812. That institutional familiarity proved decisive; of the era's two marquee acquisitions, the music transaction would endure as the far superior capital deployment.
Then came Hollywood. In November 1989, Sony finalized the acquisition of Columbia Pictures Entertainment for $3.4 billion in cash — $27 per share — while assuming $1.4 billion in debt, marking the largest Japanese corporate takeover in the United States up to that point13. The purchase delivered an archive of roughly 2,700 feature films and 23,000 television episodes, driven by the explicit rationale of securing proprietary "software" to feed future Sony hardware launches13.
The synergy thesis meets reality
On paper, the synergy thesis appeared airtight: an integrated conglomerate controlling film studios, record labels, and consumer hardware could dictate new industry formats, preempt another Betamax defeat, and extract profits across every layer of the value chain. Operational reality proved far more unforgiving. Sony installed film producers Peter Guber and Jon Peters to manage the studio, corporate overhead expanded rapidly, and high-budget productions such as Last Action Hero fell flat at the box office.
The financial reckoning followed. In November 1994, Sony wrote off approximately $2.7 billion in goodwill tied to the studio — a tacit admission that it had substantially overpaid. The episode also left an enduring regulatory mark: in 1998, the U.S. Securities and Exchange Commission determined that Sony had provided inadequate disclosure regarding mounting operating losses at Sony Pictures prior to the write-down, partly by blending the unprofitable film division with the lucrative music business into a single reporting segment, resulting in a $1 million civil penalty for the company14. The studio's balance-sheet drag lingered across corporate cycles: more than two decades later, in January 2017, Sony booked another $962 million impairment on its film business15.
Myth vs. reality: did hardware–content synergy work?
A recurring corporate narrative suggests that Sony's content acquisitions were a visionary masterstroke that laid the foundation for today's entertainment-led powerhouse. The historical record refutes the strong version of that claim. The precise synergy Sony paid a premium to achieve — using captive content to mandate proprietary hardware formats — largely failed to materialize. Proprietary formats such as the MiniDisc never achieved ubiquitous global adoption, and the impulse to protect hardware through content restrictions later crippled Sony during the dawn of digital music. Along the way, the film studio absorbed two massive write-downs and a federal regulatory penalty over reporting transparency.
What ultimately survived was a narrower, far more disciplined strategic reality: deep catalogs of intellectual property generate substantial cash flows only when licensed agnostically to any distributor willing to pay market rates. Sony's music and film operations matured into dependable, highly profitable divisions only after management discarded the fortress model and operated them as independent rights-holders licensing to Apple, Spotify, Netflix, and other third-party platforms.
The hidden jewel
One comparatively modest transaction from this era proved to be the most consequential entertainment investment Sony ever executed. In 1999, following years of complex litigation, Sony acquired the film rights to Spider-Man from Marvel for a reported $7 million16. The inaugural 2002 film alone grossed $821 million worldwide16. More than twenty-five years later, Spider-Man remains an indispensable commercial anchor across Sony Pictures, a premier exclusive franchise for PlayStation's first-party game development, and a pillar of the group's broader transmedia strategy — an enduring demonstration that in media investing, asymmetric returns typically stem from low-cost options on iconic characters rather than multi-billion-dollar buyouts of legacy studios.
For investors, this era establishes a vital baseline: whenever management promotes cross-divisional "synergy," the historical base rate for forced hardware-and-software integration is poor, whereas the structural returns on independent, platform-agnostic intellectual property ownership have proved exceptional. Yet even as the corporate center struggled to digest its Hollywood studio, an engineer deep within the company was preparing to prove that Sony could still build a revolutionary computing platform from scratch — provided an external partner humiliated it into action.
V. Ken Kutaragi’s Guerilla War: The PlayStation Platform Engine (1991–2006)
The betrayal in Chicago
On June 1, 1991, Sony arrived at the Summer Consumer Electronics Show in Chicago to unveil a joint project it had spent two years developing with Nintendo: a CD-ROM peripheral for the Super Nintendo, internally designated the "Play Station"17. The following morning, Nintendo of America chairman Howard Lincoln took the stage to announce that Nintendo had partnered with Philips instead to construct its CD system. Sony executives learned of the reversal alongside the rest of the audience17.
Nintendo had grown wary that Sony intended to leverage the partnership as a commercial beachhead in video games — a suspicion that proved entirely accurate. Ken Kutaragi (久多良木 健), the Sony engineer spearheading the project, had viewed the collaboration as the critical first step toward his true objective: entering the console business outright17. Kutaragi operated as an internal insurgent. A hardware engineer who had earlier developed the sound processor for Nintendo's Super Famicom, he was regarded by many traditionalist Sony executives as an eccentric tinkering with children's toys.
"Keep going"
Inside Sony's executive committee, senior leaders mounted a strong case for abandoning video games altogether. Many viewed interactive software as a low-margin toy business, beneath an enterprise that manufactured premium Trinitron televisions and owned Columbia Pictures. Norio Ohga, however, was incensed by Nintendo's public repudiation. According to accounts compiled by Video Games Chronicle for PlayStation's 30th anniversary, Ohga resolved that Sony would never withdraw from the sector and instructed Kutaragi's team to keep going17. Sony Computer Entertainment was forged out of that corporate defiance.
Architecting the platform
Kutaragi's architectural choices were fundamentally commercial strategies disguised as engineering decisions. Most crucially, he selected CD-ROMs rather than proprietary silicon cartridges. Cartridges carried steep fabrication costs and long production lead times, forcing third-party publishers to commit substantial working capital to large manufacturing runs months ahead of release. By contrast, optical discs were inexpensive to press and could be manufactured within days, allowing publishers to limit inventory risk with smaller initial batches and rapidly reorder inventory on breakout hits.
Furthermore, Sony drew directly on the disc-pressing and logistics infrastructure of its music division, granting game developers greater supply-chain flexibility, a software certification window compressed from months to roughly two weeks, and royalty terms noticeably more attractive than those enforced by Nintendo or Sega17. In operational terms, Sony positioned itself as the most publisher-friendly platform in the industry — an ecosystem advantage far more decisive than raw silicon performance.
The PlayStation launched in Japan on December 3, 1994, immediately exhausting its initial shipment of 100,000 units, before arriving in North America on September 9, 199517. Landmark titles such as Gran Turismo, Metal Gear Solid, and Final Fantasy VII defined the era, powering the console past 100 million cumulative lifetime sales17.
PlayStation 2: the Trojan horse
The PlayStation 2, introduced in 2000, executed an elegant convergence strategy: it incorporated a built-in DVD player at a moment when standalone players carried prohibitive consumer price tags. For millions of households, the device doubled as their first DVD player — a gaming machine that subsidized its own adoption into the living room as a family entertainment hub. Sony subsequently confirmed that the PlayStation 2 surpassed 160 million lifetime unit sales, establishing it as the best-selling home console in gaming history18.
Why this matters now
For investors assessing the modern enterprise, the initial PlayStation era provides the clearest historical proof of Sony's capacity to build a self-reinforcing two-sided platform: an ecosystem where an expanding player base attracts software developers, whose titles in turn pull in more consumers. It also illustrates Sony's most effective operational formula in interactive entertainment: winning not through closed hardware lock-in or forced proprietary integration, but by establishing the most commercially advantageous distribution network for independent third-party creators. That distinction remains vital in evaluating subsequent capital allocation, particularly when management later pursued costly acquisitions to build live-service capabilities rather than relying on external partnerships.
Yet that triumph introduced a profound structural vulnerability. By the early 2000s, PlayStation was generating an outsized share of Sony's consolidated operating earnings while legacy consumer electronics divisions deteriorated under intense foreign competition. That runaway success fostered institutional hubris — embodied by Kutaragi — and a belief that Sony possessed the pricing power to unilaterally dictate technical standards to consumers and developers alike. The subsequent console cycle would ruthlessly test that assumption, arriving precisely as an entirely different computing revolution emerged from Cupertino.
VI. The Lost Decade: Digital Arrogance, The iPod Humiliation, and the 2012 Near-Death (2000–2012)
Everything needed to win, except the will
In October 2001, Steve Jobs introduced the iPod with the proposition of "1,000 songs in your pocket." On paper, Sony should have dominated the digital audio market. It possessed the world's preeminent portable audio brand in the Walkman, decades of engineering mastery in miniaturization and battery chemistry, and one of the globe's largest recorded-music catalogs. Yet that organizational integration proved to be an operational trap.
While Sony's hardware divisions recognized consumer demand for open MP3 playback, Sony Music — acutely vulnerable to digital piracy — insisted on rigorous digital rights management and copy-protection protocols. The resulting compromise was ATRAC, a proprietary compression format wrapped in cumbersome software that prioritized copyright defense over user experience. Apple, unencumbered by a legacy record label, negotiated licensing agreements across the music majors and paired an open ecosystem with intuitive software. The hardware-and-content fortress Sony had assembled across the 1980s had turned into a corporate cage.
Silos and an outsider CEO
Under Nobuyuki Idei (出井 伸之) in the late 1990s and early 2000s, Sony fragmented into semi-autonomous divisional silos that competed for capital and rarely coordinated product roadmaps. In 2005, the Welsh-born Howard Stringer, a former CBS executive who had managed Sony's American operations, became the first non-Japanese executive appointed to lead the company19. Stringer initiated restructuring programs and sought to dismantle divisional rivalries under a "Sony United" banner, yet he struggled to assert authority over entrenched engineering fiefdoms in Tokyo, while the structural economics of the core consumer-electronics operations continued to erode.
The PS3: when a platform forgets its partners
The PlayStation 3 launched in November 2006 carrying aggressive premium price tags of $499 and $59920. Ken Kutaragi had engineered the console around an exotic, multicore Cell Broadband Engine processor and an integrated Blu-ray optical drive. The architecture proved ruinously expensive: the research firm iSuppli estimated that the 60-gigabyte model cost approximately $840 to manufacture, creating a cash loss exceeding $240 on every unit sold at the $599 retail price20. By contrast, iSuppli estimated that Microsoft was already generating a modest hardware profit on each Xbox 360 console20.
Beyond the negative hardware margins, the Cell architecture was notoriously complex to program, alienating the third-party game developers whose support had secured PlayStation's initial dominance. The PlayStation 3 represented a wholesale inversion of the original PlayStation strategy: it was expensive for consumers, hostile to software developers, and optimized around Sony's proprietary corporate format ambitions — winning the high-definition optical disc battle for Blu-ray — rather than ecosystem utility. Nintendo's accessible, low-cost Wii and Microsoft's developer-friendly Xbox 360 swiftly captured market share and industry momentum.
The hack
In April 2011, intruders compromised the PlayStation Network between April 17 and 19, exposing personal data associated with approximately 77 million registered user accounts; Sony did not publicly disclose the intrusion until April 2621. The network remained completely offline for more than three weeks. For an enterprise staking its future on subscription services and digital ecosystem distribution, the outage inflicted severe reputational damage — serving as an enduring lesson that modern platform operators bear cybersecurity and infrastructure resilience as first-order operating exposures.
The abyss
The corporate nadir arrived in the fiscal year ended March 2012. Sony posted a record annual net loss of ¥456.7 billion (roughly $5.7 billion) alongside a consolidated operating loss of ¥67.3 billion22. The television manufacturing business was hemorrhaging capital under intense pricing pressure from South Korean competitors Samsung and LG, pushing Sony into its fourth consecutive year of net losses19. At the time, Engadget observed that Sony's total market valuation had collapsed to approximately one-tenth of Samsung's and roughly 3% of Apple's22. Two years later, in 2014, the company's credit rating was downgraded to speculative grade3.
What investors should take from it
The lost decade was not merely a corporate case study in organizational hubris; it established the critical baseline for evaluating Sony's structural risk profile. Within a single decade, the company surrendered category dominance in portable audio, severely impaired a leading gaming franchise, experienced a massive platform security breach, and absorbed relentless losses in a commoditizing television operation. Any investment thesis celebrating Sony's modern competitive moats must account for how rapidly those advantages evaporated when divisional politics and proprietary formats took precedence over customer value and third-party developer economics. Entering 2012, the decisive operational question was whether incoming leadership could execute the deep structural surgery required — and whether the company would survive the procedure.
VII. The Kazuo Hirai Turnaround & The "One Sony" Surgery (2012–2018)
The PlayStation kid takes over
On February 1, 2012, Sony announced that Kazuo Hirai (平井 一夫), then 51, would become president and chief executive effective April 123. Hirai was an unusual choice to lead an established Japanese conglomerate. Rather than rising through Tokyo's traditional hardware and engineering ranks, he had built his career within Sony's entertainment divisions and played a central role expanding PlayStation and its networked services23. Howard Stringer, the outgoing chairman, praised his "unique capacity to inspire people, to build teams, to make the tough decisions"23.
Hirai framed his turnaround strategy around "One Sony," invoking the cultural touchstone of kando — the sensation of being deeply moved. While the phrase sounded like corporate sentimentality, the operational execution proved unsentimental.
The executioner
Hirai's most consequential managerial move was recruiting Kenichiro Yoshida (吉田 憲一郎), a Sony veteran who had departed to run the group's internet subsidiary So-net and returned to the parent enterprise in December 201324. Yoshida was appointed chief strategy officer and subsequently chief financial officer. Where Hirai provided institutional diplomacy and an engaging public face, Yoshida brought financial rigor and an unsparing willingness to say no to entrenched divisional leaders. Hirai later credited him with combining "a deeply strategic mindset with a relentless determination to achieve defined targets"24.
The surgery
In February 2014, Sony announced it would sell its VAIO personal-computer business to the investment fund Japan Industrial Partners, split its struggling television division into a standalone operating subsidiary, and eliminate 5,000 jobs3. Divesting VAIO carried acute symbolic weight — it had been one of the consumer industry's most admired PC brands — but the unit had long failed to generate adequate returns and sat outside Hirai's core pillars3. Carving out television forced that business to survive on its own standalone economics rather than absorb cross-subsidies from healthier operations. Meanwhile, management curtailed smartphone production from a global volume race down to a specialized niche, while liquidating prime corporate real estate and non-core equity holdings.
The governing rule was straightforward: withdraw capital from operations incapable of earning their cost of capital, regardless of historical prestige.
That discipline ran directly against traditional Japanese corporate conventions. Domestic electronics conglomerates routinely treated operating divisions as lifetime stakeholders, subsidizing chronically unprofitable units with earnings from healthy ones and viewing divestitures as a failure of duty to workers and suppliers. Sony did not abandon that relationship overnight — the buyer of VAIO, for instance, retained former Sony personnel to keep supporting existing customers3 — but management established an internal benchmark: every business had to justify its capital allocation through its own numbers.
Executing that restructuring under severe financial distress magnified the operational friction. When management announced the VAIO divestment, Sony was projecting an annual net loss of roughly ¥110 billion and had just seen its debt rating downgraded to speculative grade3. Retrenching from a distressed posture forced the company to sell assets at depressed valuations, fund severance packages from strained cash reserves, and ask employees to trust leadership amid deep workforce reductions. Pushing the portfolio overhaul through that liquidity squeeze, rather than deferring action, demonstrated the executive team's resolve during the company's most fragile modern period.
The PS4 redemption
Concurrently, PlayStation systematically dismantled the strategic errors of the previous console cycle. Led by lead system architect Mark Cerny and Sony Computer Entertainment chief Andrew House, the PlayStation 4, launched in late 2013, abandoned exotic custom silicon in favor of a standard PC-style architecture that external studios could easily program. Sony introduced the console at $399 — a full $100 below Microsoft's Xbox One, which had been burdened with a costly bundled camera peripheral and a confusing early messaging strategy surrounding game ownership. PlayStation's positioning was unadorned: an accessible machine engineered explicitly for players. The PlayStation 4 became one of the best-selling consoles in gaming history, generating the robust operating cash flows that funded the rest of Sony's corporate recovery.
Finding the real moats
The more durable strategic evolution lay in identifying which business lines possessed genuine structural advantages. Two divisions stood out. The first was Imaging & Sensing Solutions: Sony had pioneered stacked CMOS image-sensor architecture and was becoming the indispensable supplier to the world's premier smartphone manufacturers. The second was high-margin, recurring intellectual property: music publishing royalties, streaming catalog licensing, and PlayStation's rapidly expanding base of network subscriptions.
The financial inflection arrived swiftly. In the fiscal year ended March 2018, Sony reported operating income of ¥734.9 billion — more than doubling the ¥288.7 billion recorded the prior year and establishing a new corporate earnings record8. With the turnaround firmly demonstrated, Sony announced in February 2018 that Yoshida would succeed Hirai as chief executive from April 1, 2018, with Hirai becoming chairman24.
A calibrated verdict
The Hirai turnaround is frequently celebrated as an unvarnished triumph of management willpower. The historical evidence warrants a more measured assessment. Hirai and Yoshida executed necessary portfolio rationalizations with exceptional discipline. Yet that recovery was also powerfully accelerated by an unusually favorable cyclical alignment: Microsoft's missteps during the PlayStation 4 rollout, alongside a multi-year boom in multi-lens smartphone cameras that flooded the sensor division with high-margin demand. The true test of whether capital discipline had become permanent institutional muscle memory, or merely a temporary survival mechanism born of crisis, would arrive under Yoshida and Totoki — when Sony once again had substantial capital to spend.
VIII. The Yoshida-Totoki Era: Architecting an IP & Sensor Giant (2018–Present)
Two financial minds
Kenichiro Yoshida and Hiroki Totoki represent the antithesis of Ken Kutaragi's engineering-first swagger. Neither is a product inventor; both operate as disciplined capital allocators. As chief executive from 2018, Yoshida reorganized the enterprise around what management described as "getting closer to people" — creators and consumers — deploying capital heavily into entertainment intellectual property. Totoki, who rose through Sony's corporate finance ranks, became president, chief operating officer, and chief financial officer in April 202325.
When PlayStation chief Jim Ryan retired, Totoki stepped in directly as interim head of Sony Interactive Entertainment. Effective June 1, 2024, he assumed the role of SIE chairman, establishing a joint leadership structure with Hideaki Nishino overseeing platform business and Hermen Hulst managing game studios, both reporting directly to him26. On January 29, 2025, Sony announced that Totoki would succeed Yoshida as Group CEO effective April 1, 2025, with Yoshida remaining as chairman and Lin Tao appointed as Sony's first female CFO25. In announcing the transition, Yoshida credited Totoki with spearheading the group's aggressive capital deployment into content intellectual property and semiconductor manufacturing25.
Sony Group Corporation
On April 1, 2021, the parent company formally renamed itself Sony Group Corporation, while its electronics operating subsidiaries were consolidated into a separate operating entity that inherited the historic Sony Corporation name27. The corporate reclassification carried operational significance beyond nomenclature: it formally recast the parent enterprise as an overarching portfolio manager allocating capital across diverse operating subsidiaries, rather than a legacy consumer-electronics manufacturer managing entertainment side ventures. While management framed the corporate purpose around an expansive mission to "fill the world with emotion, through the power of creativity and technology," that mandate is elastic enough to encompass virtually any commercial enterprise — reinforcing why capital allocation discipline, rather than corporate rhetoric, serves as the primary metric for investors.
The financial services spin-off
For decades, Sony's domestic life insurance, casualty insurance, and banking operations functioned as a dependable cash engine, generating the domestic liquidity that helped sustain the group through the consumer-electronics crises of the 2000s. Yet housing a regulated life insurer alongside entertainment assets and semiconductor fabrication facilities generated a classic conglomerate discount: divergent capital requirements, acute interest-rate sensitivity, and an equity investor base that struggled to value the combined enterprise.
Sony announced a partial spin-off in May 2023. Following regulatory approvals, Sony Financial Group shares listed on the Tokyo Stock Exchange's Prime Market on September 29, 2025. On October 1, 2025, Sony distributed 83.6% of the shares to its shareholders as a dividend in kind — one SFGI share for each Sony share — while retaining an equity stake of approximately 16.4%6.
The transaction carried a significant accounting consequence for reported earnings. Because the spin-off required Sony to reclassify accumulated other comprehensive income associated with the financial business, the company booked a loss from discontinued operations of ¥1.36 trillion, translating an underlying year of record operating income into a reported consolidated net loss attributable to shareholders of ¥326.9 billion for FY202528. Although this balance-sheet adjustment represented a non-cash accounting effect of deconsolidation rather than an operational deterioration, it rendered headline consolidated net income for FY2025 non-comparable with prior reporting periods.
The anime machine
In anime, Sony assembled an integrated production and distribution apparatus that differs sharply from Western streaming models. The domestic Japanese foundation rests on Aniplex, an operating unit of Sony Music Entertainment Japan, and its affiliated animation studios. The international distribution engine is Crunchyroll, which Sony acquired from AT&T for $1.175 billion, completing the purchase on August 9, 2021, when the platform counted approximately 5 million paid subscribers29. By 2026, Crunchyroll reported 21 million paid subscribers, expanding from 17 million a year earlier30.
Concurrently, Sony deployed balance-sheet capital to build strategic footholds across Japan's broader intellectual property landscape. In January 2025, it became the largest shareholder in publishing and media house Kadokawa with an approximately 10% equity stake acquired for roughly ¥50 billion31. In July 2025, it took a 2.5% stake in Bandai Namco for about ¥68 billion32. Broadening its character portfolio beyond anime, Sony agreed in December 2025 to acquire WildBrain's 41% interest in Peanuts Holdings for 630 million Canadian dollars, raising Sony's combined ownership of the Peanuts franchise to 80%33.
Crunchyroll's expansion highlights a fundamental shift in international entertainment consumption. Long treated as a niche subculture in Western markets, anime evolved into mainstream entertainment for younger global demographics — with Sony establishing the premier specialized destination rather than ceding the category to general-entertainment platforms like Netflix or Disney. Crunchyroll's competitive advantage does not rest on securing complete exclusivity over every premier title; rather, it stems from deep back-catalogs, rapid same-day simulcasting from Japanese broadcast networks, and community features that foster higher user engagement. That dynamic resembles a platform switching-cost advantage more than a traditional content-windowing moat.
The overarching commercial model is a vertically integrated pipeline spanning original light-novel or manga source material, animation production, soundtrack publishing, global direct-to-consumer streaming, theatrical event distribution, consumer merchandising, and video games. Unlike the failed hardware-content synergy experiments of the 1980s and 1990s, Sony operates this media pipeline agnostically, licensing finished content widely across external platforms and theaters. Nonetheless, minority holdings such as Kadokawa and Bandai Namco confer strategic influence rather than operational control, functioning as strategic call options whose ultimate investment return hinges on executed co-productions rather than initial equity announcements.
Management credibility: promises versus outcomes
How dependable has executive execution proved under Yoshida and Totoki? While their operating track record surpasses Sony's historical conglomerate baseline, it reveals notable strategic miscalculations alongside financial discipline.
On financial forecasting and restructuring, management established strong execution credibility. Corporate earnings guidance has leaned conservative: Sony introduced its initial FY2026 operating-income forecast at ¥1.60 trillion in May 202628, raising it to ¥1.72 trillion after a single quarter of results7. Similarly, leadership expanded its three-year cumulative operating cash flow target from ¥4.8 trillion to ¥5.7 trillion2. The carve-out of Sony Financial Group, announced in 2023, closed precisely within the schedule management originally committed to shareholders6.
Conversely, PlayStation's high-profile pivot toward live-service gaming exposed the limits of corporate strategy. Management's marquee operational objective — releasing twelve live-service multiplayer titles from PlayStation Studios within approximately three years following the Bungie acquisition34 — faltered, resulting in project cancellations and restructuring driven by market headwinds rather than disciplined preemption.
Nevertheless, managerial accountability evolved constructively compared to earlier eras. Totoki's public critique of PlayStation's operating profit margins and studio cost structures in February 202435, coupled with his frank admission in May 2026 that "some investments went well, some did not"2, provided transparency that is historically rare among senior Japanese corporate executives. While managerial candor cannot substitute for sound capital allocation, it provides the prerequisite feedback loop for correcting capital deployment errors before they compound into systemic balance-sheet write-downs.
Automotive optionality — tested and closed
For much of the current decade, Sony's broader technology narrative incorporated an automotive initiative: Sony Honda Mobility, an electric-vehicle joint venture formed with Honda to produce and market the Afeela electric sedan. Leadership originally framed the venture as an asset-light commercial showcase for Sony's CMOS sensors, in-cabin entertainment software, and spatial computing interfaces. That strategic option ultimately reached a definitive close. Following Honda's broader retrenchment in electric-vehicle production, the partners discontinued the Afeela program, announcing on April 21, 2026, that they would downsize the joint venture and reabsorb personnel into the respective parent corporations36. For FY2025, Sony recognized ¥44.9 billion in additional losses associated with the vehicle program's discontinuation and operational wind-down1.
For equity investors, the financial outcome is illustrative rather than debilitating. The financial losses remained ring-fenced, adhering to management's commitment to avoid capital-intensive industrial manufacturing commitments. Yet the episode reinforces an enduring pattern across Sony's corporate history: speculative hardware showcases and consumer partnerships have translated into durable operating cash flows far less reliably than proprietary platform ecosystems and specialized component manufacturing. That operating reality offers vital perspective as management turns to promote next-generation physical AI initiatives — setting the stage for a detailed examination of the group's divisional economics.
IX. Segment Engine Room: Economics, Competition, and Financial Dissection
The shape of the profit pool
An examination of Sony's FY2025 financial results illustrates the transformed architecture of the enterprise. On sales of ¥12.48 trillion from continuing operations, operating income reached ¥1.45 trillion1. Game & Network Services led the contribution with ¥463.3 billion of operating income, followed closely by Music at ¥447.0 billion and Imaging & Sensing Solutions at ¥357.3 billion, while Entertainment, Technology & Services generated ¥158.6 billion and Pictures delivered ¥104.9 billion28. In aggregate, gaming, music, and sensors generated roughly four-fifths of total segment operating profit, leaving the heritage consumer-electronics division responsible for barely a tenth.
Following a robust first quarter in FY2026, management raised full-year guidance to ¥12.5 trillion in sales and ¥1.72 trillion in operating income, representing an operating margin of approximately 13.8%7. The earnings profile marks a structural departure from the conglomerate that spent years absorbing persistent losses across consumer display hardware.
1. Game & Network Services: the scale platform
PlayStation functions primarily as a digital platform tollbooth. Sony collects high-margin commissions on third-party digital game downloads, downloadable add-ons, and in-game microtransactions through the PlayStation Store, layers recurring cash flows through PlayStation Plus network subscriptions, and publishes its own portfolio of first-party titles. In the first quarter of FY2026, monthly active users on the network reached a June record of 125 million, even as total user playtime softened by 4%7.
The hardware trajectory, however, has diverged from the expanding network base. While cumulative PlayStation 5 shipments surpassed 93 million units, annual volume decelerated: Sony shipped 16 million consoles in FY2025 compared with 18.5 million the prior year, with shipments falling to 1.5 million units in the January–March quarter of 2026 from 2.8 million twelve months earlier37. To defend unit economics against escalating component costs, Sony increased console prices in the United States in August 2025 and introduced further increases across the U.S., Europe, Japan, and Southeast Asia in March 2026, responding to a sharp memory-semiconductor squeeze fueled by artificial intelligence data-center expansion37. During the May 2026 earnings conference, management acknowledged that both the release schedule and pricing strategy for next-generation hardware remained undecided, cautioning that elevated memory procurement costs would persist into FY20272.
Operational profitability, by contrast, demonstrated notable resilience. Segment operating income increased 12% to a record ¥463.3 billion in FY2025 on roughly flat sales of ¥4.69 trillion37 — absorbing substantial balance-sheet write-downs on Bungie along the way. In the opening quarter of FY2026, segment operating profit surged 37% to ¥202 billion, bolstered by U.S. tariff refunds and favorable foreign exchange movements, prompting leadership to raise its full-year divisional earnings forecast to ¥660 billion7. A significant portion of this near-term expansion, however, reflects non-operational tailwinds: Sony projected approximately ¥80 billion in total tariff refunds for FY2026, roughly 70% of which was recognized in the first quarter alone7.
Alongside these cyclical factors, management initiated a subtle structural shift. In February 2024, Totoki informed investors that multiplatform releases of first-party titles on personal computers represented a crucial lever for expanding operating profit margins35. Distributing PlayStation titles on PC broadens the monetization pool for games whose massive development expenses are already fully sunk, though it incrementally dilutes hardware exclusivity. For a publisher navigating escalating studio budgets, expanding addressable audiences across external hardware is a pragmatic defense of capital returns — yet it also concedes that proprietary console ecosystems alone can no longer shoulder the full financial weight of blockbuster software development.
Historical falsification: the live-service pivot
The live-service expansion began with aggressive operational targets. When Sony completed the $3.6 billion acquisition of Bungie in July 2022, leadership planned to leverage the studio's technical expertise to overhaul PlayStation Studios, committing to allocate 49% of first-party development budgets toward live-service multiplayer experiences and launch twelve internal live-service titles within roughly three years34.
Subsequent operating results dismantled that hypothesis. Concord, developed by Firewalk Studios following its 2023 acquisition, debuted in late August 2024 and was pulled offline approximately two weeks later; on October 29, 2024, Sony shuttered both Firewalk and mobile developer Neon Koi, eliminating 210 positions38. Hermen Hulst acknowledged the operational failure directly, conceding that "we did not hit our targets with this title"38. The financial repercussions culminated in FY2025, when Sony recognized ¥120.1 billion — approximately $766 million — in impairment charges against Bungie's assets, citing both Destiny 2's underperformance and the launch of Marathon139.
Underlying this setback was an unsustainable industry-wide cost trajectory. Internal studio documents disclosed during a December 2023 breach at Insomniac Games revealed that Marvel's Spider-Man 2 absorbed a production budget of $315 million, more than double the $156 million spent on Marvel's Spider-Man: Miles Morales, which had reached 10.2 million unit sales40. Studio budgets doubling across a single sequel cycle crystallized the financial hazard of the premium development cost spiral.
Executive commentary reflected this harsher operational reality. During the February 2024 earnings call — after holiday-quarter divisional operating margins compressed to approximately 6% and management reduced its full-year PS5 shipment projection from 25 million to 21 million units — Totoki cautioned that the division lacked a "deep understanding of how their work is being translated to growth, generation of sustainable profits and higher margin"35. Equity markets reacted immediately, erasing approximately $10 billion from Sony's market capitalization following the presentation35.
The empirical record is clear: while PlayStation's core platform moat — its digital store, network lock-in, and dominant third-party software share — remains exceptionally strong, the hypothesis that Sony could rapidly acquire and scale an internal live-service software empire has been thoroughly falsified. Management has since recalibrated toward a more disciplined operational posture: extracting earnings from network subscriptions, hardware price increases, selective PC ports, and overhead control. While reported FY2026 divisional margins will appear inflated by temporary tariff recoveries and currency weakness, the durable test of segment health will be whether double-digit margins persist once those non-operational tailwinds recede.
2. Music: the high-margin oligopoly
Global recorded music operates as a disciplined triopoly. In 2025, Universal Music Group commanded approximately 32.5% of the worldwide market, followed by Sony Music Entertainment at 22.7% and Warner Music Group at 14.8%41. In music publishing — which controls the underlying composition and lyrical copyrights rather than master sound recordings — Sony Music Publishing holds the global leadership position with a 25.9% market share, surpassing Universal's 23.6%41.
The underlying unit economics are straightforward and lucrative. Digital streaming platforms distribute the majority of their revenue directly to rights holders under statutory and negotiated royalties, while legacy catalog assets require virtually zero incremental capital expenditure to generate cash flow. Sony cemented its publishing scale in November 2018 by acquiring the 60% equity interest in EMI Music Publishing it did not already own for $2.3 billion, valuing the business at an enterprise value of $4.75 billion42.
In FY2025, divisional operating income climbed 25% to ¥447.0 billion on a 15% revenue gain, though reported earnings benefited from a ¥34.7 billion remeasurement gain associated with consolidating Peanuts Holdings1. Underlying demand remained steady into FY2026: during the first quarter, streaming revenue expanded by approximately 10% in recorded music and 8% in publishing in constant-currency dollar terms7.
The principal structural risks facing the division center on subscriber saturation across mature Western streaming markets, increasing leverage among marquee recording artists seeking ownership of their master tapes, and the proliferation of synthetic, algorithmically generated tracks on streaming platforms. During the May 2026 earnings call, when analysts questioned catalog durability against generative artificial intelligence, Totoki characterized AI as "an amplifier of human imagination," not a replacement for artists2. While rhetorically reassuring, that perspective represents corporate optimism rather than verified protection. For investors, the decisive benchmark will be streaming revenue growth relative to aggregate industry expansion: sustained underperformance against broader global royalty growth would signal structural erosion in catalog pricing power.
3. Pictures: the disciplined "arms dealer"
Unlike its Hollywood peers, Sony Pictures deliberately avoided launching a proprietary direct-to-consumer streaming platform to compete with Netflix or Disney+. Instead, management adopted an agnostic "arms dealer" distribution strategy, licensing its theatrical film slate and television catalog across premium bidding partners, including lucrative multi-year output agreements with Netflix and Disney. This strategic restraint insulated Sony from the multi-billion-dollar operating losses that battered rival entertainment conglomerates during the peak streaming wars.
The trade-off for avoiding subscriber acquisition wars is earnings volatility. In FY2025, Pictures operating income declined 11% to ¥104.9 billion, burdened by ¥27.1 billion in asset impairment charges at visual-effects studio Pixomondo1. Theatrical receipts contracted sharply during the year, even as Crunchyroll and the broader Media Networks division posted steady expansion30. The theatrical upside increasingly relies on specialized franchises: international box-office receipts for anime releases, led by Demon Slayer: Infinity Castle, reached approximately $490 million outside Japan30. Stripped of corporate packaging, the studio has become predominantly dependent on anime and Spider-Man intellectual property, while its secondary live-action comic adaptations have generated inconsistent returns.
4. Imaging & Sensing Solutions: the semiconductor moat
At its physical foundation, a complementary metal-oxide-semiconductor (CMOS) image sensor converts incoming photons into digital electrical signals. Sony's decisive technical breakthrough was stacked sensor architecture: fabricating the photodiode pixel layer and the logic processing circuitry on distinct semiconductor wafers before bonding them together vertically. Separating the layers allows the sensing area to maximize light capture while the underlying silicon processes complex signal calculations at high speed without compromising pixel surface area.
This manufacturing advantage translated into commercial dominance. Semiconductor research firm Yole Group estimated Sony's global CMOS image-sensor market share at approximately 45% in 2023, up from 42% in 202243. In FY2025, divisional revenue increased 20% to ¥2.15 trillion while operating income jumped 37% to a record ¥357.3 billion, driven by increased average selling prices and higher unit shipments of premium mobile sensors to a key customer2. That momentum accelerated into the first quarter of FY2026, with segment operating profit surging 125% year-over-year7.
Historical falsification: customer concentration and capital intensity
While Sony's silicon engineering remains formidable, the commercial moat is constrained by customer concentration. Although Sony refrains from identifying individual clients in regulatory filings, management disclosures consistently highlight the outsized role of a "major customer," universally recognized across the supply chain as Apple. Concentrated purchasing volume grants a buyer immense commercial leverage: it can qualify dual-source suppliers, mandate engineering redesigns, or exert aggressive pricing pressure. Simultaneously, Chinese smartphone original equipment manufacturers have systematically diversified component orders toward domestic semiconductor fabricators, including OmniVision, SmartSens, and GalaxyCore43. These commercial shifts represent viable threats to segment profitability that do not require Sony's technical supremacy to falter.
Sustaining that technical edge also demands intense capital expenditures. In April 2025, Bloomberg reported that Sony was exploring a potential carve-out or partial spin-off of its semiconductor division, a report management dismissed by stating it had no concrete plans for such a divestment44. By May 2026, leadership adopted an alternative structural solution: signing a non-binding memorandum of understanding with TSMC to establish a joint venture at Sony's Kumamoto fabrication facility, under which Sony retains majority equity control while TSMC provides advanced process technology — a "fab-lite" partnership structured to ease Sony's capital-expenditure obligations2. The arrangement expanded an existing industrial relationship, building on Sony's 6% equity investment in TSMC's Japanese manufacturing subsidiary, JASM, in Kumamoto Prefecture45.
Geographic concentration materialized as an acute operating vulnerability in mid-2026. On July 28, 2026, an earthquake disrupted operations at Sony's primary fabrication hub, the Kumamoto Technology Center; clean-room lines resumed in phased increments beginning August 4, with output targeted to return to pre-quake baselines by mid-August46. Management noted that the ultimate financial impact could not yet be reliably estimated and excluded earthquake recovery costs from updated earnings guidance7.
The operational reality is clear: Sony's process-engineering moat in high-end imaging remains undisputed, yet the business is more vulnerable than promotional conglomerate narratives suggest. Its medium-term margins remain tethered to Apple's product cycles, persistent consumer demand for multi-lens smartphone arrays, and the smooth execution of its fab-sharing alliance with TSMC. For investors, the decisive metric will be diversification into automotive and industrial machine-vision applications — an expansion management has pledged for years, but which has yet to contribute a substantial share of segment profits.
5. ET&S: a business being handed off
The Entertainment, Technology & Services segment reflects the managed twilight of Sony's traditional electronics footprint. In FY2025, divisional revenue contracted 6% and operating income declined 17%, driven primarily by weakening global television sales1. In March 2026, Sony executed definitive agreements to transfer its home-entertainment operations — including televisions, home audio systems, and projectors — into BRAVIA Inc., a newly formed joint venture controlled 51% by China's TCL and 49% by Sony, scheduled to begin operations in April 2027 for a transaction value of approximately ¥75.4 billion4. The agreement marks the definitive conclusion of Sony's era as an independent television manufacturer, acknowledging that premium brand equity could no longer offset the manufacturing scale of Chinese panel producers. Adding to near-term margin pressure, escalating semiconductor memory costs posed an immediate operational headwind, with management working to limit the net impact on ET&S operating expenses to roughly ¥30 billion in FY20262.
X. Capital Allocation, M&A Track Record, and the Activist Crucible
The scorecard
The most reliable measure of a conglomerate's strategic coherence is how its capital deployments perform over time. Evaluated across corporate cycles, Sony's acquisition record reveals a stark dichotomy between durable intellectual property rights and speculative production capacity.
Its most value-accretive transactions secured established copyrights, catalog scale, and specialized distribution networks at measured multiples. Consolidating full ownership of EMI Music Publishing in 2018 secured the world's largest publishing catalog just as streaming platforms drove an industry-wide revaluation of music royalties42. Crunchyroll scaled from roughly 5 million paid subscribers at acquisition to 21 million2930, turning Sony into the premier international gateway for Japanese animation. In gaming, the 2019 acquisition of Insomniac Games for $229 million47 delivered marquee Marvel's Spider-Man titles that generated tens of millions of unit sales. And Marvel's licensing of the Spider-Man film rights for a reported $7 million in 199916 remains the most asymmetric intellectual property investment in the company's modern history.
The value-destructive transactions, by contrast, share a consistent architecture: paying peak valuations for operational turnaround bets, transient studio talent, or speculative hardware ventures. Columbia Pictures historically absorbed a $2.7 billion write-down and an SEC disclosure penalty14, followed decades later by an additional $962 million impairment15. The $3.6 billion purchase of Bungie34 has already triggered ¥120.1 billion in asset impairments1, with its initial strategic mandate — spearheading PlayStation's live-service transformation — largely unfulfilled. Firewalk Studios was acquired and shuttered in roughly eighteen months38. The Afeela electric-vehicle program was formally discontinued36, and visual-effects studio Pixomondo required substantial impairment charges1.
The underlying pattern is structurally consistent. Sony generated exceptional capital returns when acquiring durable, platform-agnostic intellectual property catalogs and established franchises at reasonable entry valuations. It destroyed capital when attempting to buy creative hit-making capability or live-service development speed at premium multiples. During the May 2026 earnings conference, Totoki acknowledged that historical divergence directly, conceding that "some investments went well, some did not," while pledging that management would enforce "rational prices" on future acquisitions and return higher proportions of free cash flow to shareholders2. While rhetorically disciplined, that commitment will face its true test whenever premier entertainment assets or studio properties next become available on the open market.
What the market is paying for
Public equity markets have treated Sony's record operating earnings with persistent caution rather than an uncritical re-rating. Adjusted for its five-for-one stock split, Sony's American Depositary Receipt (ADR) traded near $23.50 following the release of its first-quarter results in late July 20267. That valuation multiple reflects a structural conglomerate discount. Public investors are tasked with appraising an enterprise that blends a cyclical video-game hardware cycle, a high-margin music publishing oligopoly, an unpredictable theatrical film studio, and a capital-intensive semiconductor fabrication business — with the consolidated results translated through a volatile Japanese yen.
Operating independently, each segment would command a distinct investor base with contrasting hurdle rates and valuation methodologies. Bundled together, they expose consolidated earnings to cross-segment volatility. Dismantling that valuation penalty is precisely why executive leadership spent years rationalizing non-core assets — and why the next phase of portfolio restructuring will determine Sony's terminal valuation far more than individual quarterly earnings beats.
The activist stress test
The strategic durability of Sony's corporate architecture has faced external pressure through two high-profile activist campaigns waged by Daniel Loeb's hedge fund, Third Point. Both interventions provide valuable benchmarks for assessing management's portfolio logic.
In 2013, Third Point proposed that Sony execute an initial public offering for up to 20% of its entertainment assets to unlock shareholder value and force operational transparency. Sony's board of directors rejected the proposal unanimously, with Kazuo Hirai responding that "continuing to own 100 per cent of our entertainment business is the best path forward"48. Subsequent operating history validated that resistance: entertainment intellectual property, streaming distribution, and catalog licensing expanded into the group's most dependable compounder of free cash flow.
In June 2019, Third Point launched a second campaign backed by a $1.5 billion equity position, urging Sony to spin off its semiconductor imaging division into a publicly traded pure play and monetize non-core minority holdings in companies such as Spotify and Olympus49. In September 2019, Sony's board once again unanimously rejected the semiconductor separation, with Yoshida defending the business as "a crucial growth driver for Sony"49.
The longer-term outcome, however, reveals a more nuanced reality. While management repeatedly rebuffed Loeb's explicit proposals, leadership spent the subsequent six years executing a structural overhaul that closely mirrored his core diagnosis. Sony systematically monetized non-core equity holdings, carved out and distributed 83.6% of its financial-services division to shareholders in 20256, explored options surrounding its semiconductor footprint in early 202544, and subsequently entered a manufacturing joint venture with TSMC to curb the capital intensity of its sensor operations2. In effect, corporate leadership resisted activist governance pressure while pragmatically adopting its underlying imperatives: narrowing corporate sprawl, mitigating balance-sheet capital intensity, and eliminating the conglomerate discount.
What a skeptical activist would ask today
A contemporary activist or institutional shareholder evaluating Sony would challenge executive management on four unresolved strategic questions:
- Capital efficiency of minority holdings: What measurable return on invested capital justifies deploying balance-sheet reserves into minority equity stakes in Japanese media and publishing conglomerates — such as Kadokawa and Bandai Namco — rather than returning that capital directly to shareholders through buybacks?
- Governance of creative acquisitions: Why did the retention-heavy earnout structure negotiated in the $3.6 billion Bungie transaction fail to insulate the business from severe post-acquisition asset impairments and studio talent attrition?
- Quality of near-term earnings: What portion of projected FY2026 operating earnings represents durable operational improvement across core business lines, as opposed to transient foreign-exchange windfalls and non-recurring U.S. tariff refunds?
- Terminal structure of the semiconductor division: Will Imaging & Sensing Solutions remain a permanent internal segment, or does the capital-sharing joint venture with TSMC represent the initial phase of an eventual equity carve-out or structural spin-off?
Returning capital
Concurrently, Sony's capital return framework has expanded in both scale and structure. In October 2024, the company executed a five-for-one stock split to broaden its retail shareholder base and enhance market liquidity5. In May 2026, the board of directors authorized a share repurchase program of up to ¥500 billion, announced plans to cancel approximately 184 million shares of treasury stock, and increased its annual dividend projection from ¥25 to ¥35 per share28.
Underpinning these distributions is a reinforced balance sheet. Sony concluded the fiscal year on March 31, 2026, with net cash of ¥539.2 billion1, while executive leadership raised its cumulative three-year operating cash flow projection from ¥4.8 trillion to ¥5.7 trillion2.
The enterprise commands substantial balance-sheet liquidity, yet its long-term equity compounding rate hinges on capital allocation discipline. When the next major consolidation wave emerges across global entertainment and gaming, the central question for investors is whether management will deploy that balance sheet to secure enduring, cash-generative catalog rights akin to EMI Music Publishing, or pursue high-multiple studio buyouts that mirror the miscalculations of Bungie. The answer to that question will be shaped by the broader competitive terrain Sony navigates across interactive media, streaming distribution, and advanced semiconductor manufacturing.
XI. Strategy Analysis: Hamilton Helmer’s 7 Powers & Porter’s 5 Forces
Seven Powers: where Sony's advantage really lives
Hamilton Helmer’s strategy framework asks a fundamental question: what structural conditions allow a business to earn persistently higher economic returns than its competitors? For Sony, the answers vary sharply across operating units — a divergence that serves as both the primary justification for, and the persistent critique of, the modern conglomerate.
Network economies. PlayStation’s digital platform represents the clearest two-sided network in the portfolio: an expanding pool of active players attracts software developers, whose titles in turn bring in more consumers. With monthly active users reaching 125 million7, the gravitational pull of that ecosystem is formidable. Yet unlike pure software marketplaces, console networks are not winner-take-all; platform loyalty faces a structural reset with every hardware transition, rendering this network power potent but cyclical.
Scale economies. Both advanced semiconductor fabrication and blockbuster game development demand immense capital commitments that smaller rivals cannot match. However, scale cuts in both directions. The $315 million production budget for Marvel's Spider-Man 240 illustrates how scale functions simultaneously as an imposing barrier to entry for challengers and an acute financial vulnerability for the studio when project returns falter.
Switching costs. Digital game purchases, accumulated trophy collections, and established friend networks create substantial friction for consumers considering a platform defection. In a digital distribution era, every software license tied to a user's account raises the financial and psychological hurdle of defecting to Xbox or Nintendo.
Cornered resources. The exclusive film rights to Spider-Man and Sony's music publishing catalog represent authentic cornered resources: irreplaceable cultural assets that competitors cannot duplicate, circumvent, or license away. Across the group's broader asset base, these catalog and character rights represent its purest and most durable economic moats.
Counter-positioning. When legacy entertainment peers committed tens of billions of dollars to build captive direct-to-consumer streaming services, Sony Pictures deliberately refrained, positioning itself instead as an agnostic content supplier licensing films and television libraries across competing bidders. While this counter-positioning insulated Sony from the destructive operating losses that battered rival studios, it entailed a structural concession: relinquishing direct subscriber billing relationships and user behavioral data to third-party distributors.
Process power. Proprietary stacked CMOS sensor architectures and fine-pitch wafer bonding represent classic process power: decades of specialized manufacturing and packaging know-how that rivals have struggled to reverse-engineer. Yet the fab-sharing joint venture with TSMC introduces a subtle strategic question: if advanced fabrication processes are shared with or offloaded to an external foundry, does proprietary process power gradually diffuse? While Totoki maintained that pixel design and process technology remain "separate things"2, that operational boundary will remain a critical dynamic for investors to monitor.
Branding. PlayStation and Sony’s Alpha mirrorless cameras command premium pricing power and strong brand affinity. Sony’s ability to implement mid-cycle price hikes across multiple regions on the PlayStation 537 demonstrated genuine brand strength — yet decelerating annual hardware shipments also highlighted the outer elasticity limits of that pricing flexibility.
Porter's Five Forces
Threat of new entrants: low in hardware and sensors, moderate in creative content. Building a competitive console ecosystem requires billions of dollars in upfront capital, established developer networks, and multi-year catalog development. The costly retreat of well-funded initiatives, such as Google’s Stadia, underscores how steep that platform barrier remains. In semiconductors, the most credible new challengers are Chinese image-sensor fabricators targeting domestic smartphone tiers43, though matching Sony's yield efficiency in flagship silicon remains technically demanding.
Bargaining power of buyers: high in sensing, moderate in gaming. Heavy customer concentration in image sensors — dominated by Apple — grants the primary buyer immense commercial leverage over unit pricing, design revisions, and multi-sourcing decisions. In interactive entertainment, individual consumers possess negligible day-to-day bargaining power once locked inside an ecosystem, but exercise decisive collective choice at generational hardware resets.
Bargaining power of suppliers: elevated and expanding. The 2026 semiconductor memory squeeze turned dynamic random-access memory (DRAM) producers into powerful gatekeepers, forcing mid-cycle hardware price increases and complicating roadmaps for next-generation systems237. In recorded music, superstar recording artists command increasing leverage over royalties and catalog ownership. In interactive gaming, premier third-party publishers and elite development talent negotiate aggressively over store commission terms and exclusivity windows.
Threat of substitutes: substantial and pervasive. Premium console gaming competes not merely against rival hardware platforms, but against mobile games, short-form video, and generative media for aggregate consumer leisure hours. Softening engagement hours across the PlayStation Network7 provide an early reminder that the broader attention economy presents mounting substitution pressures.
Competitive rivalry: intense across all core divisions. In gaming, Microsoft pairs an expansive balance sheet with Activision Blizzard's cross-platform catalog, while Nintendo commands unmatched first-party loyalty. In recorded music, Universal Music Group maintains an industry-leading global market share41. In semiconductor imaging, Samsung continues to challenge premium tiers while domestic Chinese fabricators expand across mid-range volume.
The strategic synthesis is clear: Sony’s most dependable economic moats reside in cornered intellectual property resources (music publishing and film copyrights) and platform switching costs (digital PlayStation libraries). Its acute structural vulnerabilities concentrate in semiconductor imaging, where customer concentration, fabrication capital intensity, and geopolitical supply-chain risks converge. That tension sets the stage for the competing investment cases that follow.
XII. The Bull vs. Bear Case & Critical KPIs
The bull case
1. A vertically integrated cross-media intellectual property pipeline. Sony can adapt an original manga or light novel, produce the animation through Aniplex, release the soundtrack through Sony Music, stream episodes globally on Crunchyroll, distribute feature films to theaters, and develop video game adaptations. The theatrical performance of Demon Slayer and Chainsaw Man releases across 2025 and 2026 demonstrated this multi-window distribution apparatus operating at commercial scale30. Strategic equity stakes in Peanuts Holdings33, Kadokawa31, and Bandai Namco32 broaden the upstream creative funnel. While Walt Disney represents the closest corporate peer in franchise monetization, Sony's specialized anime pipeline commands unique demographic reach among younger international audiences.
2. Portfolio simplification to narrow the conglomerate discount. Distributing the financial-services business to shareholders6 and transferring majority control of television manufacturing to a joint venture with TCL4 leave Sony structured predominantly around higher-margin entertainment and sensing assets. Proponents of the bull thesis maintain that shedding regulated financial operations and diluting exposure to commoditized display hardware should steadily narrow Sony's historical conglomerate discount.
3. Sensor diversification into automotive and industrial machine vision. The manufacturing joint venture with TSMC is explicitly structured to support advanced silicon for emerging "physical AI" applications — including autonomous vehicles, industrial robotics, and spatial machines requiring high-precision optical sensing2. If these industrial and mobility use cases expand, aggregate demand for CMOS image sensors would diversify beyond the replacement cycles of premium smartphones.
4. Durable compounding in music publishing and recorded music. Holding the global leadership position in music publishing41 alongside steady streaming revenue expansion7, Sony Music operates as a high-margin, capital-light cash generator with multi-year compounding potential backed by irreplaceable catalog rights.
The bear case
1. Escalating production budgets in blockbuster game development. First-party production costs have roughly doubled across a single sequel cycle40, even as annual PlayStation 5 console shipments decelerate37. With flagship budgets exceeding $300 million, a single high-profile creative misfire can erase an entire year of divisional margin expansion.
2. Live-service setbacks and structural exposure to console cycles. Substantial balance-sheet impairments against Bungie39 alongside the swift cancellation and shutdown of Concord and its studio38 demonstrate that Sony has struggled to acquire its way into recurring live-service gaming revenue. Failing to build a durable live-service software portfolio leaves interactive entertainment earnings closely tethered to traditional hardware upgrade cycles.
3. Customer concentration and operational fragility in imaging. Segment profitability remains heavily exposed to a single dominant smartphone customer, rising component substitution by domestic Chinese sensor fabricators43, the geographic concentration of fabrication lines in an active earthquake zone46, and continuous capital-expenditure requirements that threaten to compress divisional operating margins.
4. Vulnerability to cybersecurity breaches and supply-chain disruptions. Sony's operational track record includes the 2011 PlayStation Network intrusion that compromised 77 million user accounts21 and the December 2023 ransomware attack on Insomniac Games that leaked confidential budgets and studio files40. Operating a digital platform anchored by user profiles and stored payment credentials carries permanent cybersecurity exposure. Compounding those digital risks are physical and supply-chain vulnerabilities: the July 2026 earthquake disrupting clean-room operations at the Kumamoto fabrication facility46, escalating memory-chip prices driven by artificial intelligence infrastructure demand2, and shifting U.S. trade policy — which imposed operational costs before generating substantial tariff refunds in FY20267.
5. Foreign exchange tailwinds and non-recurring earnings lifts. Consolidated reported earnings have been significantly flattered by a historically weak Japanese yen; during the first quarter of FY2026, the U.S. dollar averaged ¥159.3 compared to ¥144.6 in the prior-year period7. Simultaneously, non-recurring U.S. tariff refunds provided an immediate boost to Game & Network Services operating profit7. A sustained strengthening of the yen or the exhaustion of one-off recoveries would compress reported operating earnings, even if underlying operations remained stable.
Myth vs. reality
Myth: Sony is now a pure-play entertainment company. Reality: Semiconductors remain a substantial driver of operating profit28, and leadership's decision to pursue a manufacturing joint venture rather than an equity spin-off keeps the group exposed to capital-intensive hardware cycles.
Myth: PlayStation margins are structurally solved. Reality: FY2026 profit forecasts rely significantly on non-recurring tariff refunds and foreign exchange tailwinds7; annual hardware shipments are falling37; and next-generation console production costs remain uncertain amid rising memory component prices2.
Myth: Sony's capital allocation is uniformly disciplined. Reality: While acquisitions such as EMI Music Publishing and Crunchyroll generated strong returns, the broader corporate ledger includes costly asset impairments and project cancellations across Bungie, Firewalk, Pixomondo, and Afeela13836.
The KPIs that matter most
1. Game & Network Services operating margin, excluding one-offs. Tracking normalized divisional margins clarifies whether PlayStation's profit expansion reflects permanent operational efficiencies or transient tailwinds. The critical analytical benchmark is the segment's underlying operating margin once non-recurring U.S. tariff refunds, currency swings, and studio impairments are stripped out.
2. Imaging & Sensing Solutions non-mobile revenue mix. The proportion of sensor sales derived from automotive, industrial robotics, and machine-vision deployments will indicate whether the semiconductor division can successfully diversify beyond its dependence on mature smartphone upgrade cycles and a single dominant client.
3. PlayStation monthly active users and total playtime engagement. Monitoring active account volumes alongside aggregate gameplay hours will reveal whether the platform's digital network is expanding independently of aging console hardware, or gradually losing consumer leisure time to mobile gaming, social video, and competing entertainment platforms.
XIII. Epilogue: Lessons for Founders, Operators, and Conglomerates
In 1979, Masaru Ibuka boarded an international flight with a modified portable cassette player and a pair of custom 50-gram headphones, wanting only to listen to opera without disturbing his seatmates. Nearly half a century later, the enterprise he co-founded generates the vast majority of its operating profit from assets that bear little resemblance to standalone audio hardware: anime streaming subscriptions, music publishing royalties, a digital gaming network, and CMOS image sensors embedded inside competitors' smartphones. Distilled across eight decades of engineering breakthroughs, strategic miscalculations, and balance-sheet restructuring, Sony's trajectory offers four enduring lessons for founders, corporate operators, and modern conglomerates.
Do not force captive synergy. Sony's recurring impulse to make proprietary entertainment content serve captive hardware — from the synergy rationale behind the acquisition of Columbia Pictures to the restrictive digital rights management protocols that hobbled the Walkman's digital successors — consistently destroyed capital. Sony's content divisions compounded value only after management discarded the fortress model and operated them agnostically, licensing catalog rights, film slates, and software libraries to third-party distributors and direct platform rivals alike.
Portfolio pruning is an active strategy. Kazuo Hirai and Kenichiro Yoshida did not revive Sony by inventing new product categories; they stabilized the enterprise by refusing to cross-subsidize operations incapable of earning their cost of capital. Divesting VAIO, carving out television manufacturing into a standalone subsidiary, and ultimately transferring majority control of consumer displays to a joint venture with TCL reflect the same operational discipline applied over twelve years. Withdrawing capital from legacy prestige businesses is often the essential prerequisite for funding genuine economic moats.
Cross-boundary leadership preserves conglomerates. Sony’s most constructive corporate eras were guided by executives comfortable operating across distinct worlds: Akio Morita bridging post-war Japanese engineering and Western consumer marketing; Norio Ohga bridging artistic temperament and industrial manufacturing; Kazuo Hirai bridging Tokyo executive headquarters and California entertainment studios; and Hiroki Totoki bridging corporate finance and creative studio economics. Conglomerates decay when divisional fiefdoms insulate leadership from commercial reality; they endure when executive leadership can evaluate engineering, creative output, and capital allocation through a unified financial lens.
Asymmetric partnership outperforms closed dominance. Sony rarely prevailed by being the lowest-cost manufacturer or maintaining a completely closed proprietary standard. Instead, its most durable competitive positions emerged when it functioned as an indispensable platform partner — offering game publishers an efficient distribution marketplace, providing streaming platforms with premium licensed film and television content, and supplying global smartphone manufacturers with critical imaging silicon. As escalating memory component costs complicate console hardware roadmaps and generative artificial intelligence challenges traditional creative workflows, Sony's primary test is whether it can preserve that partner leverage. Ultimately, the company's modern evolution demonstrates that long-term enterprise resilience depends less on defending legacy machines than on exercising the discipline to discern which platforms, components, and intellectual property are worth owning.
References
-
Sony Group FY2025 Consolidated Financial Results (Form 6-K) — Sony Group Corporation / SEC EDGAR, 2026-05-08 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Sony FY2025 Earnings Call: Record Sales and Operating Income, TSMC Joint Venture, Memory Crunch — BigGo Finance, 2026-05-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Sony To Exit PC Business By Selling VAIO — TechCrunch, 2014-02-06 ↩↩↩↩↩↩
-
Sony and TCL Definitive Agreements on Home Entertainment Business Joint Venture (Form 6-K) — Sony Group Corporation / SEC EDGAR, 2026-03-31 ↩↩↩
-
Sony Group FY2024 Consolidated Financial Results (Form 6-K) — Sony Group Corporation / SEC EDGAR, 2025-05-14 ↩↩
-
Sony Group Corporation Completed the Spin-Off of 83.6% of Sony Financial Group Inc. — MarketScreener, 2025-10-01 ↩↩↩↩↩
-
Sony Q1 FY2026 Slides: Operating Income Surges 40% on Gaming, Sensors — Investing.com, 2026-07-31 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Sony Corporation Form 20-F for the Fiscal Year Ended March 31, 2018 — SEC EDGAR, 2018-06 ↩↩↩
-
Transistor Radio, Model TR-63 — Victoria and Albert Museum Collections ↩↩↩↩
-
The Consumer Electronics Hall of Fame: Sony Trinitron — IEEE Spectrum ↩↩↩↩
-
The Consumer Electronics Hall of Fame: Sony Walkman — IEEE Spectrum ↩↩↩↩↩
-
Sony Completes $2 Billion Purchase of CBS Records — UPI Archives, 1988-01-05 ↩↩↩
-
Sony Completes Columbia Takeover — UPI Archives, 1989-11-07 ↩↩
-
SEC v. Sony Corporation and Sumio Sano, Litigation Release No. 15832 — U.S. Securities and Exchange Commission, 1998-08-05 ↩↩
-
Sony Pictures Takes $962 Million Impairment Charge on Film Business — The Hollywood Reporter, 2017-01-30 ↩↩
-
Why Sony Teamed Up With Marvel Studios for Another Spider-Man Movie — TIME, 2015-02-10 ↩↩↩
-
PlayStation at 30: The Betrayal and Revenge Story of the PS1 — Video Games Chronicle, 2024-12 ↩↩↩↩↩↩↩
-
As the Switch Closes In, Sony Confirms PS2 Sold 160 Million Units — Push Square, 2024-11 ↩
-
Sony's Stringer Steps Down as President, CEO — IndustryWeek, 2012-02-01 ↩↩
-
Sony's Loss Is at Least $240 on Every PS3 — Fortune, 2006-11-16 ↩↩↩
-
Sony's PlayStation Network Breach Risks Explode — IEEE Spectrum, 2011-04 ↩↩
-
Sony's Final 2011 Report Shows a Record Net Loss, Optimism for 2012 — Engadget, 2012-05-10 ↩↩
-
Sony Confirms Kazuo Hirai as New President and CEO — Engadget, 2012-02-01 ↩↩↩
-
Sony Announces Management Changes: Kenichiro Yoshida Appointed President and CEO (Form 6-K) — Sony Corporation / SEC EDGAR, 2018-02-02 ↩↩↩
-
Hiroki Totoki Named New CEO of Sony Group; Kenichiro Yoshida to Remain as Chairman — Music Business Worldwide, 2025-01-29 ↩↩↩
-
New Leadership Structure Formed at Sony Interactive Entertainment — Sony Interactive Entertainment, 2024-05-13 ↩
-
Change of the Sony Entity for License Agreements, etc. — Sony Corporation, 2021-04-01 ↩
-
Sony Group FY2025 Results, Spin-Off Loss and Buyback (Form 6-K Summary) — Stock Titan, 2026-05-08 ↩↩↩↩↩
-
Sony Closes $1.175 Billion Deal to Buy Crunchyroll From AT&T — Engadget, 2021-08-09 ↩↩
-
Crunchyroll Gains 21M Subscribers Backing Sony's Anime Strategy — Outlook Respawn, 2026-05 ↩↩↩↩↩
-
Sony Becomes Largest Shareholder in Kadokawa in January — Anime News Network, 2024-12-19 ↩↩
-
Bandai Namco, Sony Sign Strategic Business Partnership — Anime News Network, 2025-07-24 ↩↩
-
Signing of Definitive Agreement for the Acquisition of a Stake in Peanuts Holdings LLC (Form 6-K) — Sony Group Corporation / SEC EDGAR, 2025-12-19 ↩↩
-
Sony Officially Owns Bungie Now — TechCrunch, 2022-07-15 ↩↩↩
-
PlayStation Operating Margins Plunge to Decade-Lows, Wiping $10 Billion off Sony's Market Value — Game World Observer, 2024-02-19 ↩↩↩↩
-
Sony, Honda to Scale Down Sony Honda Mobility Following AFEELA Cancellation — CollisionWeek, 2026-04-21 ↩↩↩
-
PlayStation 5 Hardware Sales Plunge Amid Price Hikes — Game Developer, 2026-05 ↩↩↩↩↩↩↩
-
Sony Shuts Down Concord Dev Firewalk and Mobile Studio Neon Koi — Game Developer, 2024-10-29 ↩↩↩↩↩
-
Sony Records a $766 Million Impairment Loss Against Bungie for the 2025 Financial Year — PC Gamer, 2026-05 ↩↩
-
Insomniac Leak Reveals Sales of PlayStation Games on PC, Spider-Man 2 Budget of $315 Million — Game World Observer, 2023-12-19 ↩↩↩↩
-
Annual Market Share Survey Reveals the Recorded-Music and Music Publishing Winners and Losers — Music & Copyright (Omdia), 2026-04-27 ↩↩↩↩
-
Sony Completes $2.3bn Acquisition of EMI Music Publishing — Music Business Worldwide, 2018-11-14 ↩↩
-
CMOS Image Sensors: Sony Heads Towards 50% Market Share — eeNews Europe, 2024 ↩↩↩↩
-
Sony Mulls Spin-Off of Chip Business, Says Report — eeNews Europe, 2025-04-29 ↩↩
-
JASM Set to Expand in Kumamoto Japan — Sony Semiconductor Solutions Group, 2024-02-06 ↩
-
Status of Sony Semiconductor Solutions Group Manufacturing Operations Affected by 2026 Kumamoto Earthquakes (Second Update) — Sony Semiconductor Solutions Group, 2026-07-31 ↩↩↩
-
Sony Paid $229M for Insomniac Games — Game World Observer, 2020-02-11 ↩
-
Sony Rejects Entertainment Unit Spin-Off Proposal — Gulf News, 2013-08-06 ↩
-
Sony Rejects Dan Loeb's Pitch to Spin Off Semiconductor Business and Focus on Entertainment — TheWrap, 2019-09-17 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube